With Micron’s recent pullback, a lot of people are fixated on its 5x forward P/E and calling it cheap.
Honestly, memory is a cyclical business. In a low-base year, earnings growth and valuation can both look unusually attractive, so you can’t take that apparent cheapness at face value.
When I look at $MU , I start by asking three things: How long can this memory shortage last? Is free cash flow keeping pace with earnings? And roughly where would a safe entry price be after the drop?
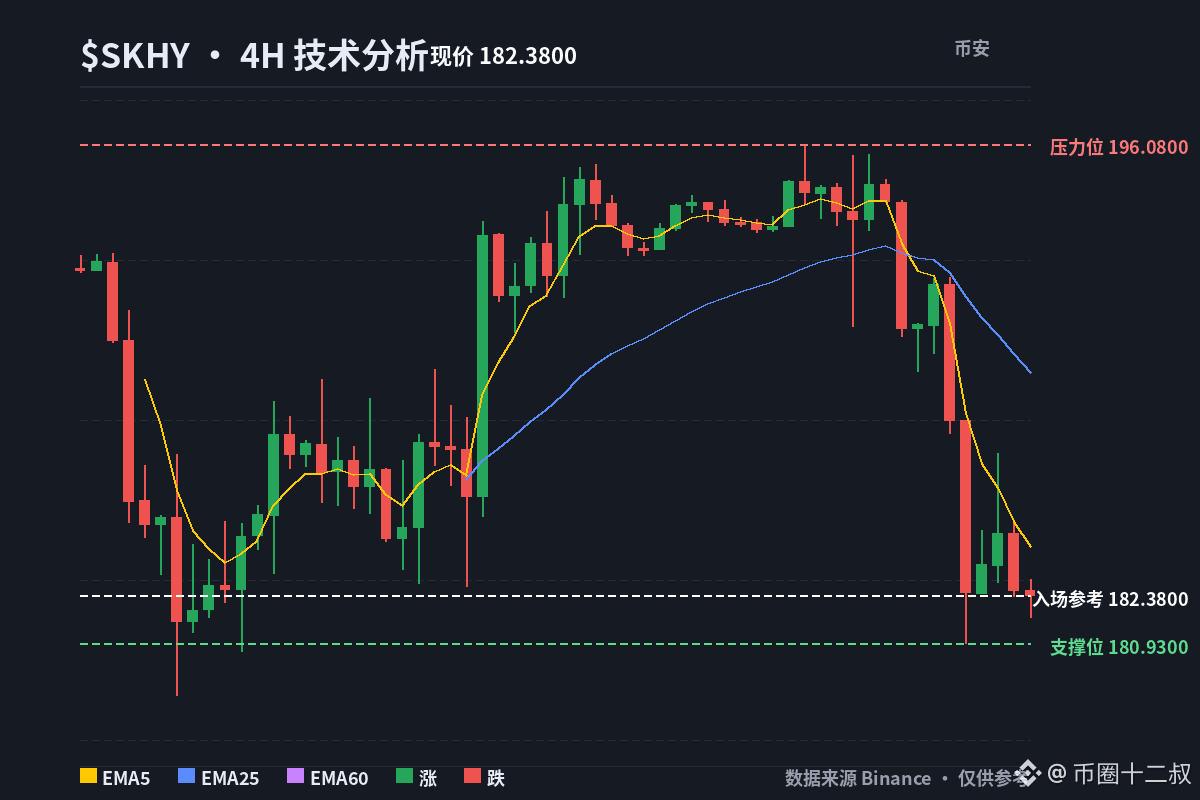
Personally, I still lean toward buying the leader, $SKHY .