


During the week of October 5–11, global markets entered a macro data vacuum. Beneath the calm surface, however, a battle over “who sets the price of bonds” is rapidly intensifying. Downward revisions to U.S. August PCE data and a sharp weakening in nonfarm payrolls pushed the probability of an October rate hike down to around 22%. Yet the 10-year Treasury yield remained near 5.3%, while the 30-year yield touched a multi-decade high above 5.6%—a rare “decoupling” between the bond market and the Fed’s near-term policy signals. Meanwhile, U.S.-Iran talks over the Strait of Hormuz have stalled, and the recovery in energy supplies has failed to bring Brent crude prices down significantly, suggesting that markets are pricing in a pessimistic outlook for geopolitical risks in the Middle East. Globally, the Bank of Japan has raised rates to a 31-year high, and expectations of a rate hike by the Reserve Bank of India are mounting. The synchronized rate-hike story is no longer just about the United States; it is now global. Bitcoin has climbed above $86,000, but weakening on-chain momentum is locked in a tug-of-war with liquidity pressures from a high-yield environment. This week, watch closely for divergence between 2-year and 10-/30-year Treasury yields, and whether gold rises in tandem with yields—this will be a key signal of bond-market risks spilling over into risk assets.
I. Delayed Rate Hikes: From the “October suspense” to “December pricing”
Last week, two key data releases completely reshaped market expectations for the Fed’s near-term path. August PCE was revised down, while September nonfarm payrolls rose by only 29,000, far below the expected 84,000; the unemployment rate climbed to 4.2%, and wage growth slowed to 3%, the lowest since May 2021. This combination of data caused the probability of a second rate hike in October to plunge from a high level to about 22%, and the market at one point interpreted this as a “dovish victory.”
But this interpretation is overly optimistic. No hike in October does not mean the rate-hike cycle is over; it simply shifts the timing window. CME data show that the probability of a December hike has been pushed up to around 67%, right at the upper edge of the “uncertainty zone.” Once subsequent CPI or PCE data prove sticky, or energy prices rise again, a probability break above 70% would force many institutions to begin pricing in a December hike earlier than planned. This means the current market “breathing room” is essentially a time-mismatch illusion of easing: marginal improvement in short-end rate expectations masks a fundamental shift in the pricing logic of long-end rates.
The release of the Fed’s September meeting minutes at 2 a.m. on October 7 is the most important information event this week. In September, the Fed unanimously voted 12-0 to raise rates by 25 basis points to 3.75%-4.00%, the first hike since July 2023. The market needs three key answers from the minutes: was the September hike an “insurance-style precaution” or a formal restart of the hiking cycle? How concerned was the committee about energy inflation and underlying inflation? How many members believed financial conditions were still not tight enough? If the minutes’ wording is more hawkish than Waller’s September speech, the probabilities of hikes in both October and December could be pushed up again.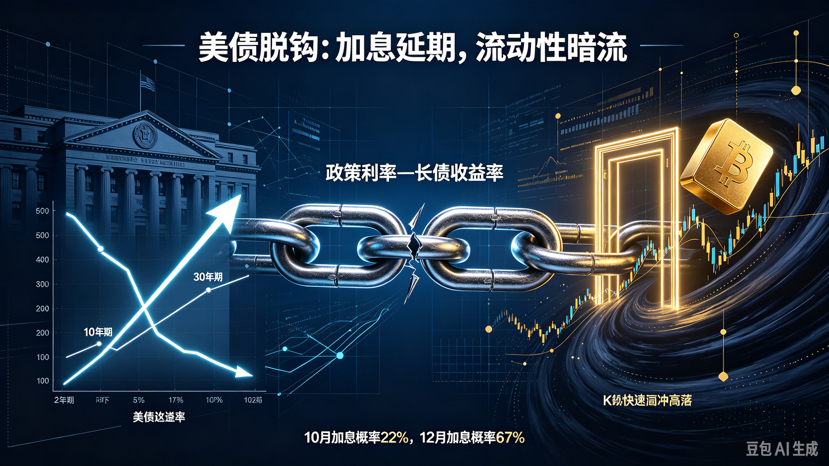
II. Bond Market Decoupling: When Risk-Free Rates Stop “Obeying”
The market signal this week worth the most caution does not come from any economic data release, but from the increasingly obvious divergence between bond markets and policy signals. Under conventional logic, a lower probability of rate hikes and weakening employment data should push long-term yields lower. Yet the reality is exactly the opposite: the 10-year U.S. Treasury yield briefly touched 5.34% intraday on October 1, the highest since 2002, while the 30-year yield broke above 5.65%, also setting a 24-year record.
The core meaning of this divergence is: the drivers of bond yields have already switched from the “Fed policy path” to “sovereign credit and fiscal supply.” Government bond yields in the U.S., Germany, and France have all hit multi-year highs, while 30-year UK gilt yields even broke above 6%. France has become Europe’s new source of risk due to fiscal problems and political risk, and the euro has fallen to a 17-month low. When multiple sovereign bond markets come under pressure at the same time, rising yields are no longer simply a matter of “pricing in rate hikes,” but a collective revaluation of government debt sustainability, excess fiscal supply, and long-term inflation persistence.
For risk assets, the key is not whether yields are “high” or not, but the relationship between 2-year yields and 10-year/30-year yields. If 2-year yields fall while 10-year and 30-year yields fall in tandem, it means the market is pricing in “the end of hikes + controllable inflation,” which is favorable for risk assets. But if 2-year yields fall while 10-year and 30-year yields rise instead—as happened last week—it means that even with the Fed not hiking, the bond market is “automatically tightening” financial conditions through rising long-end rates. That is the most unfavorable scenario for risk assets: liquidity is being drained silently, with no clear policy signal to trade against.
III. Energy Pricing Power Shift: Why can’t recovering supply bring oil prices down?
Brent crude is still holding near $101 per barrel. Notably, energy supply through the Strait of Hormuz is recovering and even gradually catching up to pre-conflict output levels, yet oil prices have not fallen effectively as Trump had previously optimistically expected.
Behind this anomaly lies a structural shift in energy pricing logic. Previously, the market broadly believed that as long as supply recovered, oil prices would naturally fall. But reality shows that among the three key factors affecting energy prices—supply conditions, capital pricing, and geopolitical influence—capital’s pessimistic pricing of Middle East geopolitical risk has already overtaken the improvement in supply.
The deadlock in U.S.-Iran relations is the direct source of this pessimistic pricing. On October 4, Iranian Parliament Speaker Mohammad Bagher Ghalibaf stated clearly that the Strait of Hormuz “will never be opened” until the seven conditions under the Islamabad memorandum of understanding are met. Iran’s conditions include the U.S. lifting the naval blockade, immediately returning frozen funds, lifting sanctions on Iranian oil exports, and ending hostilities on all fronts. Trump rejected Iran’s proposal of “reopening the strait in seven days in exchange for lifting sanctions,” but left room for indirect talks while not ruling out renewed military action.
In the short term, the probability of another attack on Iran before the U.S. midterm elections in November is low, but that does not mean the risk has disappeared. If the U.S. continues to substitute economic sanctions and diplomatic pressure for military action, Brent crude will find solid geopolitical premium support in the $95-$105 range. This week, the key focus is whether Brent can effectively break below $95—if supply recovery combined with progress in geopolitical talks still cannot push oil below that level, it means the “ratchet effect” of energy inflation is becoming entrenched, which will directly squeeze the Fed’s policy space.
IV. Global Rate-Hike Resonance: High rates are turning from an “American story” into a “global story”
The delay of U.S. rate hikes does not mean the global interest-rate environment is easing. On the contrary, rate-hike pressure in multiple economies is rising in parallel.
The Bank of Japan raised its policy rate to 1.25% in September, the highest level in 31 years, and markets expect another 25-basis-point hike to 1.5% in December. The risk of a yen rate hike lies in its linkage with U.S. Treasury yields: when expectations for U.S. rate hikes are delayed, downward pressure on the yen instead increases, forcing the BOJ to tighten monetary policy more aggressively.
The Reserve Bank of India is also under pressure to raise rates. A weaker rupee, persistent capital outflows, and widening interest-rate differentials are pushing the RBI toward a rate hike in October or December. If India confirms a hike, the global rate-hike resonance will expand from G7 countries to major emerging-market economies, and the “story radius” of high rates will widen significantly.
In Europe, France is becoming a new source of risk. The combination of widening fiscal deficits and political uncertainty has pushed French government bond yields close to 5%, while the euro has fallen to a 17-month low. This not only increases the overall risk premium in the European bond market, but also exports inflation pressure globally through euro depreciation.
V. The liquidity undercurrent in the cryptocurrency market
Bitcoin is currently trading near $86,000. Intraday on October 5, it briefly touched $86,995, and more than $1 billion in short positions were forcibly liquidated within 24 hours. On the surface, weak employment data provided support for risk assets—Bitcoin rose about 1.1% that day, seemingly “ignoring” elevated Treasury yields.
But this “ignoring” should be viewed cautiously. The impact of a high-yield environment on the crypto market is not expressed through a sharp price collapse, but through liquidity contraction and suppressed volatility. Last week, Bitcoin repeatedly showed a “round-trip” pattern—sharp spikes followed by equally sharp pullbacks—which is a classic sign of weakening liquidity. U.S. spot Bitcoin ETFs recorded about $134 million in net inflows in the first two days of October, but the prior nine-day cumulative inflow streak of $3.1 billion ended on September 30 with $149 million in net outflows. The weakening pace of inflows is highly correlated with the shift in institutional allocation preferences caused by elevated long-end yields.
Even more worth watching is the transmission chain between Bitcoin and U.S. Treasury yields. When 2-year yields fall while 10-year and 30-year yields remain elevated or continue to rise, the denominator in risk-asset valuations does not truly improve—the marginal easing of short-end rate expectations is offset by the expansion of the long-end rate’s “term premium.” In such an environment, Bitcoin prices are driven more by marginal buying and leveraged positions than by sustained institutional allocation demand. QCP Group’s market report also points out that BTC needs to rise above $87,200 to confirm the sustainability of the rally.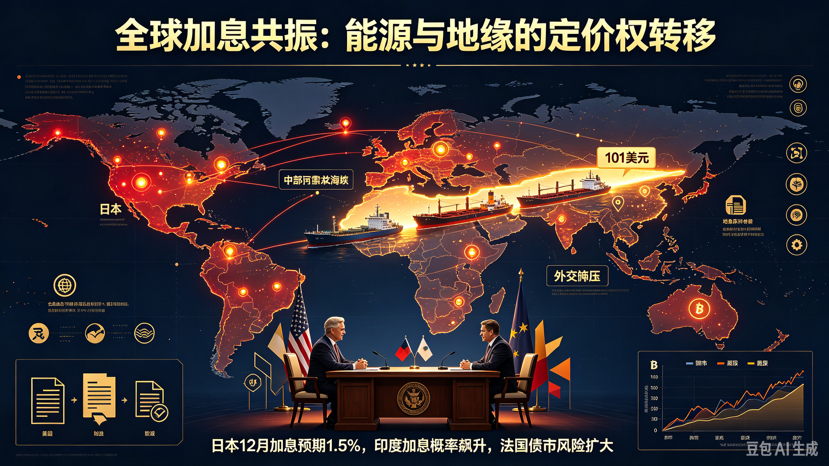
Six, the repricing of Chinese assets and this week’s key watch points
On October 8, China’s A-share and Hong Kong markets resumed trading after the National Day holiday, and Southbound Stock Connect also reopened simultaneously. Before the holiday, Chinese assets had partially priced in optimistic expectations for the China-U.S. summit, but the global macro environment changed significantly during the holiday: U.S. Treasury yields remained elevated, tensions between the U.S. and Iran showed no easing, and Brent crude held above $100. This means that when Chinese risk assets resume trading on October 8, they will face a “catch-down repricing” from the external liquidity environment. The RMB exchange rate, Hong Kong-listed Chinese equities, and commodities highly linked to Chinese demand could all see compensatory adjustments.
This week’s core observation framework:
First, the shape of U.S. Treasury yield curves matters more than their absolute level. If 2Y yields fall while 10Y/30Y yields continue to rise, the liquidity squeeze on risk assets will intensify; if all three decline together, short-term pressure will ease.
Second, the synchronization between gold and U.S. Treasury yields. Gold is currently fluctuating in the $4,150-$4,200 range, pressured by elevated yields and a strong dollar. But if gold rises against the trend while yields continue to climb, it would mean the market is beginning to materially price sovereign debt risk, and global risk appetite would face a systemic reassessment.
Third, whether Brent crude can effectively break below $95. This not only concerns the inflation path, but also whether the market’s pricing of Middle East geopolitical risk will begin to ease.
Fourth, the result of Bitcoin’s test of the $87,200 resistance level. In a tight-liquidity environment, whether this level is broken will determine the short-term direction. If Bitcoin can hold above this level even as long-end U.S. Treasury yields continue to climb, it would suggest the crypto market is forming a pricing logic independent of the traditional interest-rate environment; otherwise, it would confirm that the high-yield environment’s suppression of risk appetite remains effective.
There are no major economic data releases this week, but “no data” does not mean “no risk.” The interaction among bonds, energy, and geopolitics may determine the short-term direction of risk assets more than any single economic report. Liquidity is being silently reallocated, and markets often complete pricing before they even realize it.#Drift黑客受害者启动索赔 #Solana代币化股票9月交易量破44亿美元 #比特币现货ETF三季度净流入63.4亿美元 #以太坊验证者退出队列增392% #IMF拨款萨尔瓦多并豁免超额购BTC $BTC


