During this cycle, I feel that exchange platform tokens are indispensable. As long as centralized exchanges exist, platform tokens will exist too. However, for long-term regulatory compliance, they will gradually add a new label to platform tokens—chain tokens.
Every platform token is like your own child. I believe no platform would dislike its own child doing well. When the child does well, it gains better presentation and greater price credibility, allowing it to better survive the bull and bear cycles.
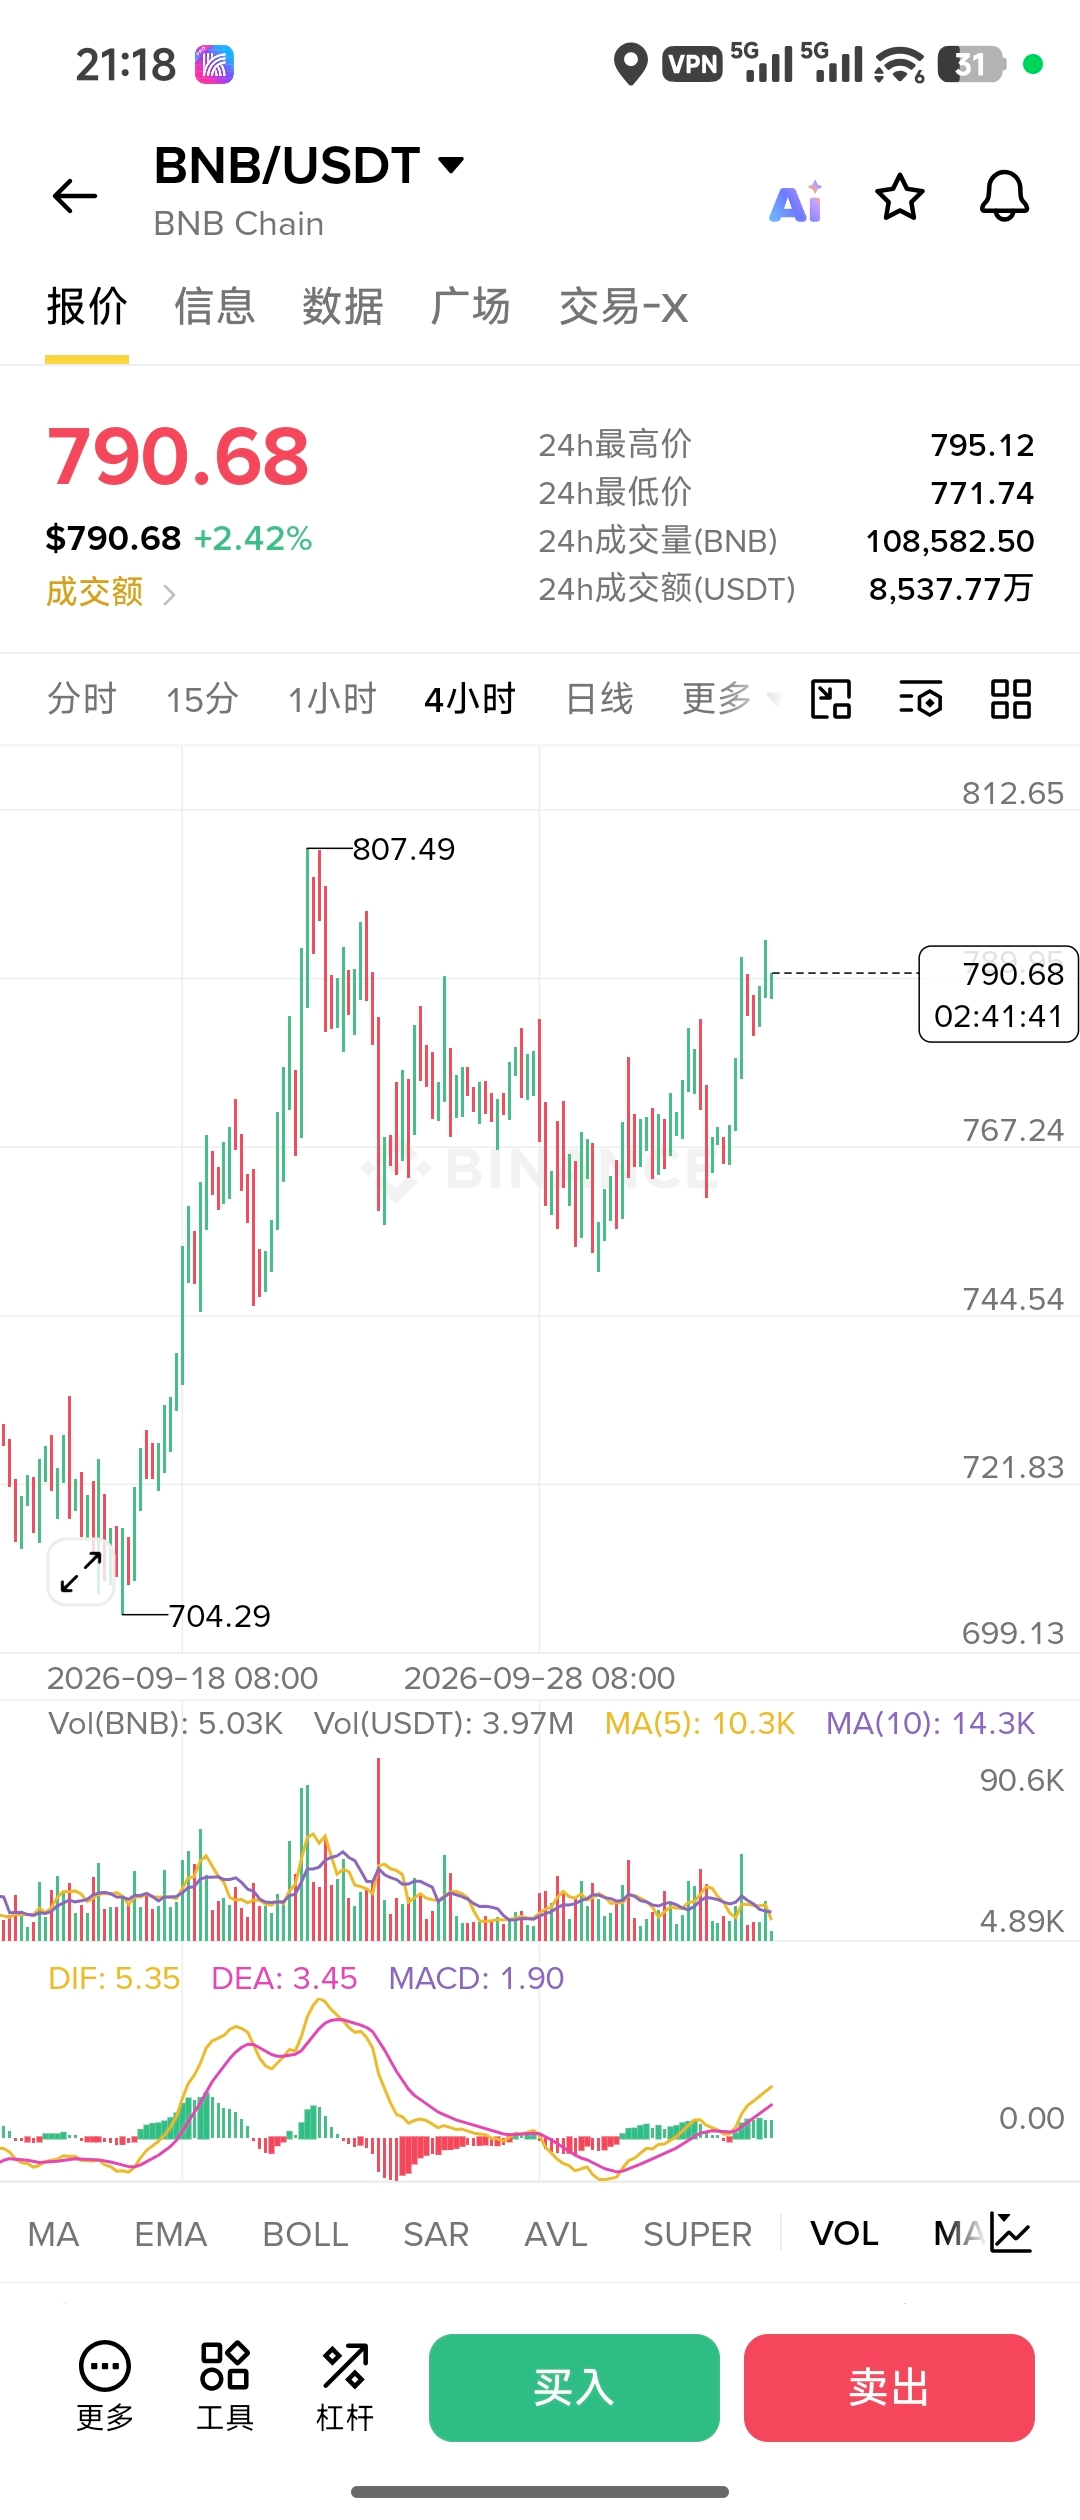
Actually, in this cycle, my main outlook is BGB and OKB. But later I found that in every investment strategy, you inevitably need part of the capital to serve as a capital-protection/backup buffer. That’s what $BNB can do. With sufficient size and stable enough pricing, it fits as an asset for long-term, steady returns.
I’m bullish on it mainly because:
① Quarterly burn continues to reduce supply. In July, about 1.62 million were burned, bringing the total supply down to about 133 million, with a target of 100 million. Annualized burn is roughly 5%.
② Demand is tied to Binance and the chain. Fee discounts, Launchpad, and staking all consume BNB. In September, Binance BTC reserves are about 693,000 coins—near a two-year high. BNB Chain tokenized stocks/ETFs have exceeded $1 billion, and RWA holders are about 1.9 million, roughly 40% of the total tracked amount.
③ Phantom integration, the 0 Gas campaign extended to the end of October, and VanEck has already submitted the BNB ETF prospectus. Also, the corporate library BNC was renamed BNB Standard.
So, in the platform token sector, my staged allocation is: 50% to invest in BNB, and the remaining 50% to invest in BNB and BGB to pursue higher returns.
As long as BNB doubles this cycle, I’ll get my principal back, so I won’t need to worry about later changes in returns. Besides, I believe BNB could reach around 2500 this cycle.