


The U.S. nonfarm payrolls for September came in far below expectations, and expectations for Fed rate hikes in October cooled quickly. However, yields on 10-year U.S. Treasuries and the U.S. dollar index rose against the trend, creating a typical market divergence. Short-end interest-rate pricing has eased, while long-end yields have remained stubbornly high due to constraints from fiscal supply and energy inflation. This contradictory macro environment is becoming a new pricing backdrop for crypto assets. Next week, the Fed meeting minutes, long-end Treasury auctions, the release of G7 oil reserves, and the ISM non-manufacturing PMI will be key variables determining the near-term direction of risk assets. The crypto market will no longer focus only on a single employment report; changes in long-end Treasury yields will become the most important “steering wheel” for the行情.
First, the abnormal market reaction to the NFP: the good news is realized, but long-end yields refuse to fall
U.S. September nonfarm payrolls added only 29,000 jobs, far below the market expectation of 90,000. At the same time, August employment data was revised down, and the unemployment rate rose to 4.2%. This data clearly shows that the U.S. labor market is starting to cool down. CME FedWatch immediately priced: the probability of keeping rates unchanged in October rose to 83.9%, and the market largely ruled out the possibility of a hike this month. However, the probability of a December hike remains high at 66.1%—it hasn’t disappeared despite weaker employment.
Most worth watching is the abnormal market behavior after this data release. In the initial phase after the NFP was released, the market quickly traded the logic of “employment weakening—yields falling.” Treasury yields briefly pulled back, but the price action soon turned sharply into a V-shaped reversal. At one point, the 10-year Treasury yield surged to 5.36%, the U.S. dollar index refreshed a 17-month high, and even gold—often viewed as a safe-haven—failed to deliver a sustained rebound. Over the whole week, gold prices fell by nearly 2%.
The core logic behind this is that short-end rates are determined more by Fed policy, while long-end U.S. Treasury yields are increasingly constrained by three major factors: U.S. fiscal deficits, Treasury supply, and energy inflation risks.
The NFP data only changes the market’s view of the October FOMC meeting, but it cannot solve the massive issue of long-term Treasury supply. The G7’s release of strategic oil reserves is only a stopgap. Geopolitical conflicts in the Middle East still exist, and inflation risks from high oil price volatility cannot be eliminated in a single step. This creates the special macro backdrop today: hikes will likely be paused in October, but the high long-end rate environment will persist, making it difficult for risk assets to enjoy a broad, liquidity-friendly loosening.
For cryptocurrencies, the implication of this bifurcated setup is very clear: near-term bad news has been partially digested, but the medium-term macro headwind has not fully disappeared. Liquidity-sensitive assets such as Bitcoin and Ethereum can hardly start a new one-way surge driven solely by a single weaker-than-expected NFP report. The next move will largely depend on whether long-end Treasury yields can fall back from their more-than-20-year highs.
Second,整理 the core macro events for next week: four key threads that determine the crypto market’s tempo
Over the coming week, the market’s focus has already shifted from “whether there will be a hike in October” to “whether there will be another hike in December.” Various data releases and officials’ speeches will keep adjusting how the market prices the year-end rate path.
First and most important is the Fed’s September meeting minutes, released at 2:00 a.m. Beijing time on Thursday. The key focus of these minutes is not whether the meeting discussed October policy, but rather internal disagreement among Fed officials: how many still worry about a rebound in inflation and support further rate hikes, and how many believe that cooling employment is already sufficient and tightening should be paused. If the overall wording of the minutes is hawkish—emphasizing inflation risks and not ruling out additional hikes—it will likely suppress crypto risk assets again. If more officials inside the Fed lean toward stopping hikes, it will likely bring emotional sentiment back to repair. Besides the minutes, you also need to closely track public remarks from Fed Governor Bowman and St. Louis Fed President Musalem—hawkish comments can easily jolt market expectations.
The second major variable comes from the Treasury market. The U.S. Department of the Treasury is about to publish the repurchase operation size for 20–30-year Treasuries and will conduct auctions for 10-year and 30-year Treasuries. Right now, the entire market is focused on the Treasury’s repurchase plan—one of the few policy tools that can help ease long-end yields. If the repurchase size is larger than market expectations, it could relieve Treasury supply pressure, and the 10-year yield could decline, benefiting crypto and growth risk assets. If the repurchase size falls short of expectations, Treasury yields would likely remain elevated, continuing to suppress market valuations. Bidding and subscription results at Treasury auctions will also directly reflect how willing overseas capital is to absorb the U.S.’s long-term debt.
Third is the energy front. The G7 has agreed to release a total of 100 million barrels of oil and diesel strategic reserves, coordinated through the International Energy Agency, with the goal of smoothing out energy prices. On the other hand, the market widely expects OPEC+ to keep its November production target unchanged, and shipping risks through the Strait of Hormuz have not been eliminated. Oil prices are the biggest source of uncertainty for inflation right now. If strategic reserve releases can effectively push down oil prices, inflation expectations would cool and the Fed’s motivation to hike further would weaken. But if geopolitical conflicts continue to drive oil prices higher, even if employment data weakens, the Fed would still retain the option of a hike in December, putting renewed pressure on the crypto market.
Fourth are key economic data releases and overseas central bank actions. On Monday night, the U.S. ISM Non-Manufacturing PMI will be released. The services sector is the last source of resilience in the U.S. economy; if services data drops sharply, it can further confirm economic cooling. On Friday, the initial University of Michigan Consumer Sentiment Index can be used to observe households’ psychological inflation expectations. In addition, the ECB will publish its September meeting minutes, the Bank of Japan’s governor Ueda Kazuo will speak, and the RBA/central bank (as applicable) and India’s central bank rate decision will land. Changes in policy “resonance” across major global central banks will also indirectly affect risk appetite in the crypto market. U.S. equities are currently in the gap before the third-quarter earnings season, which further increases the weight of macro pricing. Risk assets overall will likely keep oscillating with rate-expectation swings.
Third, the transmission logic to the crypto market: two scenario analyses
Currently, crypto assets are being pulled by two forces at the same time. On one hand, weaker U.S. employment data makes the market rule out a hike in October, which is a marginal positive. On the other hand, long-end Treasury yields remain elevated and energy inflation risks are still present, meaning the valuation pressure in the medium term has not been lifted. Next, you can simply divide into two benchmark scenarios.
First scenario: a more optimistic case. The Fed meeting minutes release a dovish signal; the Treasury’s bond repo program size comes in above expectations; and the 10-year Treasury yield shows a clear pullback. In this case, risk appetite can recover, Bitcoin and Ethereum are likely to sustain the rebound, and ETF inflows would be easier to maintain. But note: as long as the probability of a December hike has not fallen significantly, the rally is more likely to be defined as a “range-bound uptrend,” making it difficult to turn into an unconstrained, super one-way bull market.
Second scenario: a more cautious case. The meeting minutes use hawkish wording; Treasury auction subscriptions come in weak; combined with geopolitical risks, oil prices stay elevated and long-end yields keep probing upward. Even if October eventually confirms a pause in hikes, tighter financial conditions caused by high long-end yields would still suppress crypto assets. The market would easily see a rally followed by a pullback, and profit-taking is more likely to be concentrated.
A common misconception needs to be clarified here: many investors believe that as long as the Fed pauses hikes, the crypto market will enter a bull market. But the contradiction right now is that it’s long-end U.S. Treasury yields that truly constrain risk assets—not the short-term policy rate. Even if the federal benchmark rate is no longer raised, if long-term Treasury yields keep climbing, the financial environment is still effectively tightening passively, and it will be hard for crypto asset valuations to open upside space.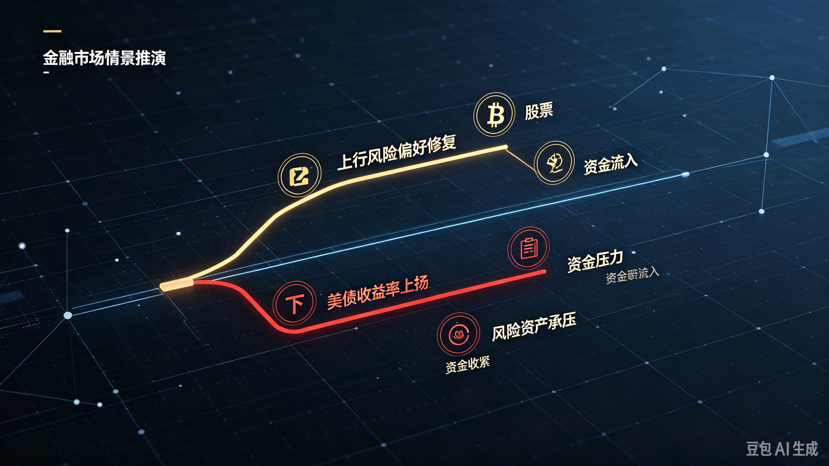
Fourth, the monitoring framework and practical takeaways for ordinary investors
For participants in the crypto market, you don’t need to over-focus on a single month’s NFP data. Instead, build a new macro monitoring checklist.
First, focus on the 10-year U.S. Treasury yield. This is the most important leading indicator at this stage, even more important than day-to-day price fluctuations. If yields continue to rise, it’s a clear macro headwind signal; only when yields show a sustained decline can we say the macro pressure is truly easing.
Second, closely watch changes in the wording of the Fed meeting minutes and officials’ speeches. Focus on the internal stance on whether to hike in December—not on the October FOMC meeting, which has largely been predetermined in expectations.
Third, track oil prices and inflation expectations. Energy prices are currently a key variable determining the Fed’s policy at year-end. If oil prices rebound sharply, the risk of a December hike will come back into focus.
Fourth, also observe the daily capital flows of the Bitcoin spot ETFs. Ultimately, changes in macro expectations will show up in whether capital flows into or out of the ETFs. If macro news is positive but ETF flows continue to be net outflows, it means institutions do not recognize this rebound, and the sustainability of the move will be called into question.
In terms of position management, we are currently in a period of macro contradictions. All kinds of data can easily trigger violent swings in the market, so it’s not suitable to add heavy exposure all at once chasing a rally. At this stage, it’s more appropriate to think of the market as range-bound: focus on verifying whether long-end rates have turned materially, rather than using a single NFP release to directly declare a bull market.
The unexpectedly weak September NFP improved expectations at the margin, but the Treasury market’s response has already clearly told the market that just weaker employment is not enough to immediately flip the broader environment of high long-end yields. Next week is a concentrated window for validating macro data. The Fed minutes, Treasury repo auctions, and energy prices together will define the tone for global risk assets over the coming period.
The crypto market has entered a brand-new pricing stage. It no longer simply follows near-term policy rate expectations. Instead, the weight of longer-term factors—such as U.S. fiscal debt supply and energy inflation risks—is steadily increasing. For traders, more than chasing day-to-day price action, the key is confirming whether long-end yields have truly reached a turning point. That is the underlying core that determines how far this rebound can go.
Risk warning: The information above is for macro market analysis only and does not constitute any investment advice. Trading in virtual currencies involves extremely high risk—please participate with caution. #SEC因拨款中断暂停加密ETF审查 #Zcash现货ETF首现周度净流出9360万美元 #比特币冲击8.7万美元遇阻回落 #美联储10月加息概率降至17% #英伟达股价创历史新高涨2.4% $BTC


