What is happening to Long positions on trading platforms and its impact on the crypto market? Are we facing organized quasi-fraud?
Every time the market drops suddenly, you see the same scene repeat: hundreds of millions of dollars liquidated in minutes, most of them Long positions. During 2026 alone, the market recorded more than 15 mass liquidation events exceeding $300 million in 24 hours, reaching more than $600 million on some days, and even approaching $1 billion on extremely volatile days.
The last of these waves occurred at the end of September 2026, when around $309 million in Longs were liquidated in a single day, with the largest share on Binance, OKX, Bybit, and Hyperliquid. A few days earlier, on September 16, $571 million in Long positions were wiped out after the failure to pass the CLARITY Act in the US Senate, with $190 million for Bitcoin alone and $190 million for Ethereum.
How does the liquidation mechanism work and why does it hit Longs more?
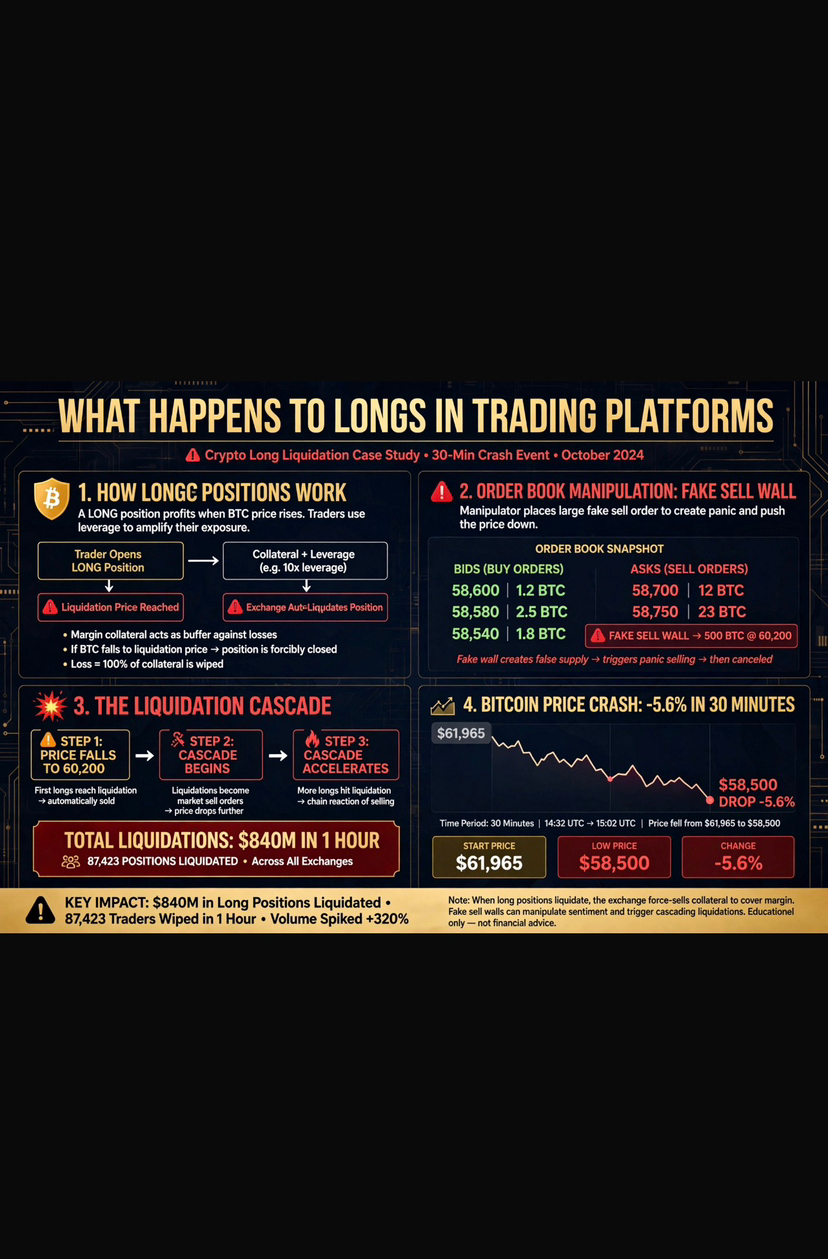
When you open a Long position with 10x leverage worth $10,000, you actually control $100,000. If the price drops just 10% against your expectation, you lose your entire margin and the platform closes your position forcibly.
The problem is that these closures are executed via immediate market sell orders, and this selling pushes the price down further, so other positions are liquidated, and thus the market enters a vicious cycle called Liquidation Cascade. Data indicates that 70-80% of liquidation in a downtrend is for Long positions, because the majority tends to be optimistic and enters Long, making the market completely exposed under the blows of market makers.
In one event documented in 2026, liquidity in order books dropped by 98% and bid-ask spreads widened by more than 1,300 times within just one hour, and more than $500 million was liquidated.
Are platforms manipulating? And what is the fraud suspicion?
Here the market is divided into two opinions, and both have evidence:
1. The technical view: The market works as designed
There is no single entity responsible. Platforms apply the automatic liquidation system to protect themselves from losses. The rise in Open Interest to between $48 and $51 billion, while spot trading volume is much lower, means that a large part of the price is artificial and built on leverage, and any small shake blows it up. This is not fraud, but a structural fragility in the Perpetual futures system that never expires.
2. The view that sees manipulation: Hunting Liquidity
Here suspicions begin. Numerous reports from traders on OKX and Binance talk about the same pattern:
- Freezing the platform and suspending login and canceling orders at critical moments, and only small traders with Long positions are affected, while institutional accounts and Short accounts work normally, leaving them until their positions are blown up.
- Inserting a fake Wick candle: Suddenly a very sharp bearish candle appears on only one platform, different from the global price, accurately hitting the stop-loss of Longs and then the price immediately returns to normal. This process is described by traders as precise harvesting by controlling the fake market depth.
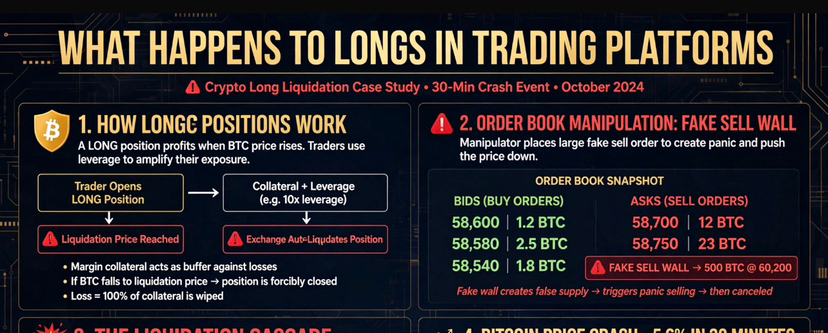
- The phenomenon of adding fake liquidity: As happened this week when Bitcoin fell below $83,000 after more than $30 million in sell orders suddenly appeared at $85,700 to stop the price rise and push it to liquidate $70 million of Longs.
Even Kris Marszalek, CEO of http://Crypto.com, called for an urgent regulatory investigation after a record liquidation of $20 billion following Bitcoin's 15% drop from $124,000 to $98,500, talking about manipulation in order books and printing abnormal prices during the sell-off, and called on the SEC and CFTC to investigate pricing, lag, and margin systems.
Impact on the market
As a result of this system, the crypto market moves not based on project news, but based on where liquidity pools. Market makers know where high-leverage Long positions accumulate below the price of $83,000 to $78,000, and it becomes very low-cost to insert a dip to liquidate $2 billion at once. And when ETF buying slowed from $1 billion per day in September to just $15 million, the market lost its biggest supporter, and the liquidation of Longs became inevitable.
It is not direct fraud like fake platforms that confiscate users' money, but it is a system that allows major platforms to profit from liquidation fees, and from the ADL system that punishes winning traders to cover the losses of insolvent ones, a system that does not exist in traditional markets and raises serious questions about market integrity.