#micronbeatsearningsliftsguidance
Micron’s Earnings Beat Expectations as AI Memory Demand Stays Strong
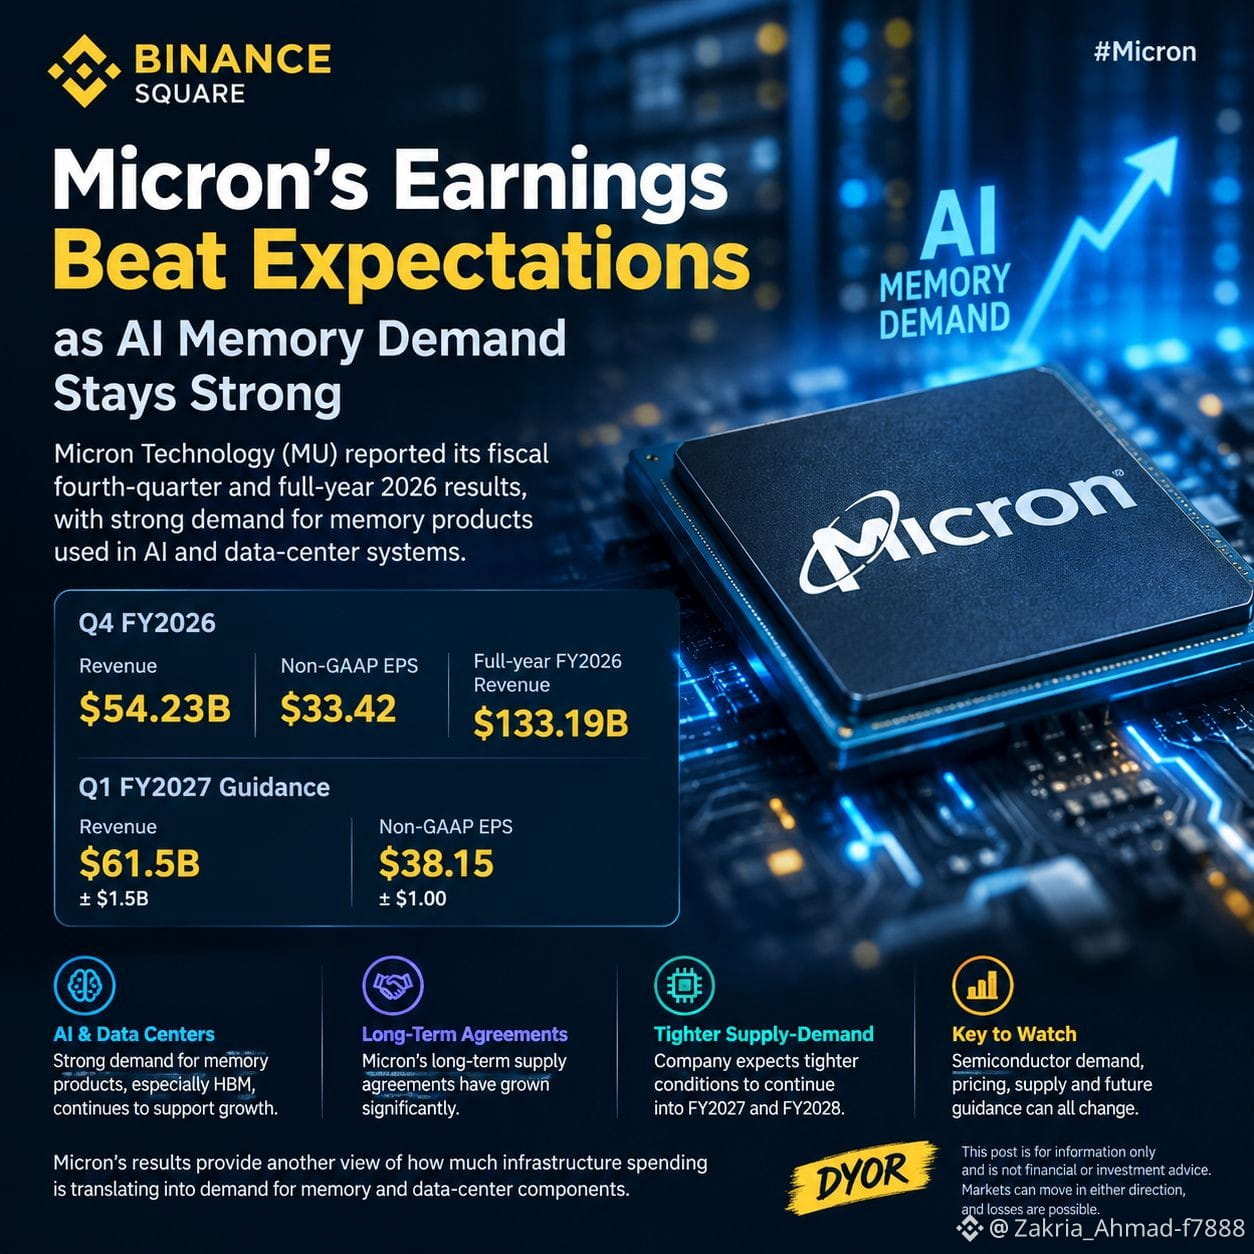
Micron Technology has reported its fiscal fourth-quarter and full-year 2026 results, with the company pointing to strong demand for memory products used in AI and data-center systems.
Micron reported:
• Q4 revenue: $54.23 billion
• Q4 non-GAAP EPS: $33.42
• Full-year FY2026 revenue: $133.19 billion
• Q1 FY2027 revenue guidance: $61.5 billion ± $1.5 billion
• Q1 non-GAAP EPS guidance: $38.15 ± $1.00
The company’s latest outlook is above the guidance it gave for the previous quarter. Micron had previously expected about $50 billion in Q4 revenue, while actual revenue came in at $54.23 billion.
One of the main areas to watch is AI-related memory demand. Micron said its long-term supply agreements have grown significantly, while demand for high-bandwidth memory (HBM) remains an important part of its business outlook. Reuters reported that Micron expects tighter supply-demand conditions to continue into fiscal 2027 and 2028.
This makes Micron an interesting company to follow alongside the broader AI semiconductor market. Its results also provide another view of how much infrastructure spending is translating into demand for memory and data-center components.
Still, strong earnings do not automatically mean the stock will continue in the same direction. Semiconductor demand, pricing, supply, capital spending and future guidance can all change.
I’ll be watching how Micron’s outlook develops through fiscal 2027.
DYOR. This post is for information only and is not financial or investment advice. Markets can move in either direction, and losses are possible.
#micron #MU #earnings #Aİ #Semiconductors #stocks