Finally know why $CRCL dropped! Because it’s here
Stablecoins are the holy-grail-level track in crypto circles! As one of the most profitable businesses in the crypto world, a company that issues stablecoins receives users’ dollars, then turns around to buy U.S. Treasuries—keeping all the interest for itself. Tether’s annual profit exceeds ten billion dollars, making it even more profitable than BlackRock.
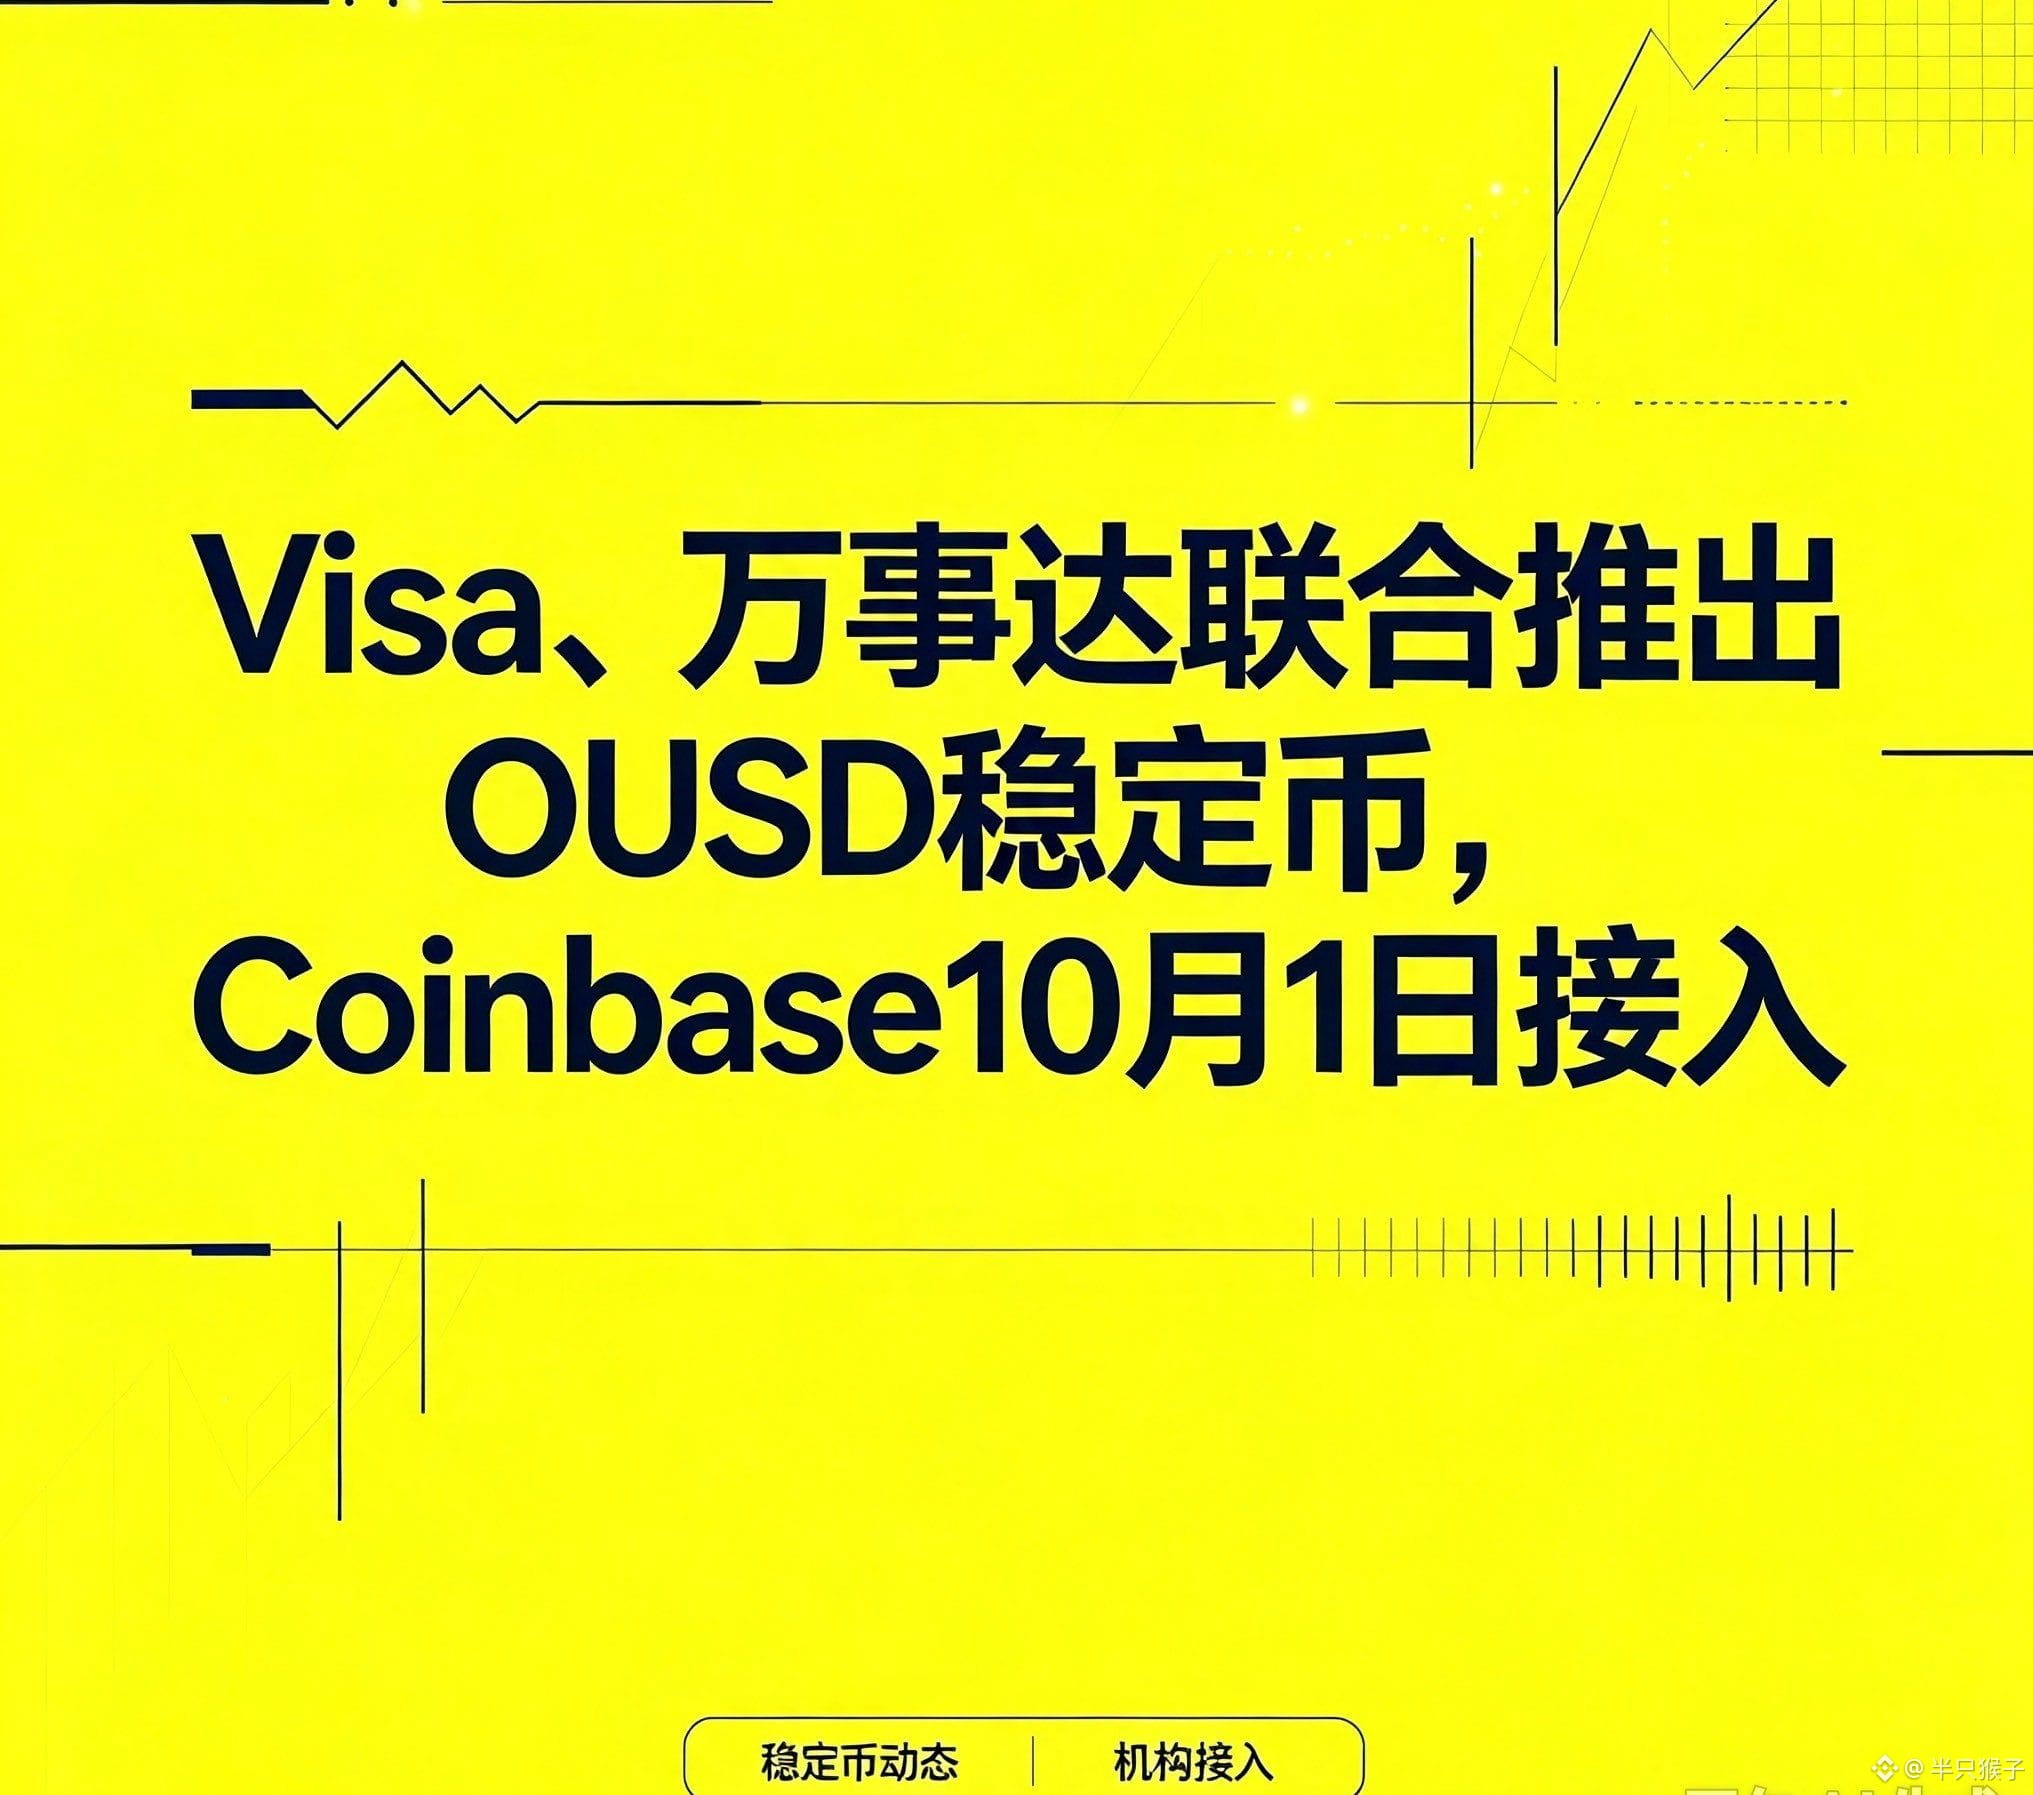
Yesterday, five institutions including Visa jointly launched OUSD, with initial liquidity of over $1 billion.
Now, today’s stablecoins have an overlooked problem
Total supply has surpassed $304 billion, with USDT and USDC accounting for 85%.
But look at efficiency: the USDC supply is only half that of USDT, yet its on-chain transfer volume is nearly 5 times higher. Most of these transfers come from internal DeFi loops—on the Base chain, 69% of USDC transfers come from DEX liquidity, and 23% come from flash loans.
Now, what stablecoins want to earn is interest; what OUSD wants to do is embed itself into commercial settlement processes.
What it means for crypto
First, the competition logic changes. Previously it was about who had the biggest pool; now it’s about who is truly embedded into commercial settlement.
Second, the DeFi landscape may be shaken. If OUSD works in real-world business scenarios, it could in turn affect its standing in DeFi.
Third, USDC faces the most pressure—because in terms of “real demand,” the two will compete directly.
In summary
OUSD isn’t stealing market share—it’s going after the position of the “commercial settlement layer.”
If it succeeds in running that system, the competition among stablecoins will shift from “who has the biggest pool” to “whose rails are more useful.” $CRCL