
#美光业绩超预期并上调指引 Micron’s performance—has AI trading come back for another round?
First the conclusion: it’s not just above expectations, it’s crushingly above expectations.
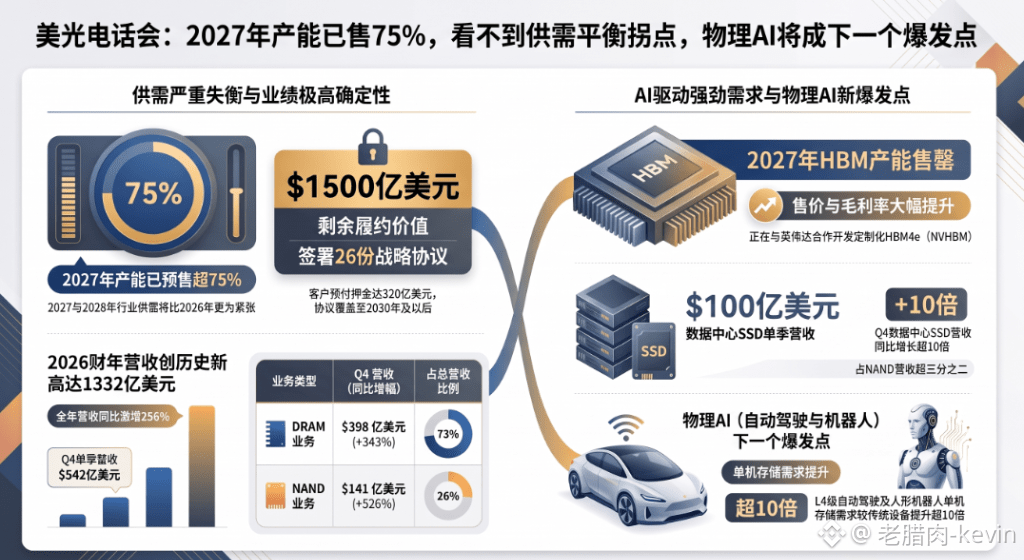
Q4 revenue was $54.2B versus the market’s $51.5B—$2.7B higher. Adjusted EPS was $33.42 versus the expected $31.61, also above. The most impressive part is the data center business: up from $1.58B in the same period last year to $18B, a 11x jump.
There were plenty of highlights on the earnings call. CEO Sanjay Mehrotra’s exact words: “AI is becoming super-intelligent; memory-enhanced like this is the intelligence.” Put simply: the more intense AI gets, the more memory is in short supply—and Micron profits.
More tangible still, management said supply and demand in 2027 and 2028 will be tighter than in 2026. Right now, they “don’t see when it could rebalance.” They’ve already signed 26 strategic customer agreements, locking in that by 2030 the company will get more than 35% of revenue from these deals.
So has the money returned to AI trading? After-hours price action was a bit complicated. It rose and then slipped, because next quarter’s gross margin guidance is 86.25%, slightly lower than this quarter’s 87%, mainly due to higher employee bonuses.
But the bottom line is: revenue and guidance both beat hard, and gross margin fluctuations are just a detour. On Wall Street, there’s already commentary saying they “see no negative signals that the cycle is about to turn.”
This AI story isn’t over yet. $MU $SOXL $DRAM