$#anthropic招股书或估值超2万亿美元 2 trillion valuation, $42 billion loss, and a $5180 billion compute wager: How should we view Anthropic’s IPO?
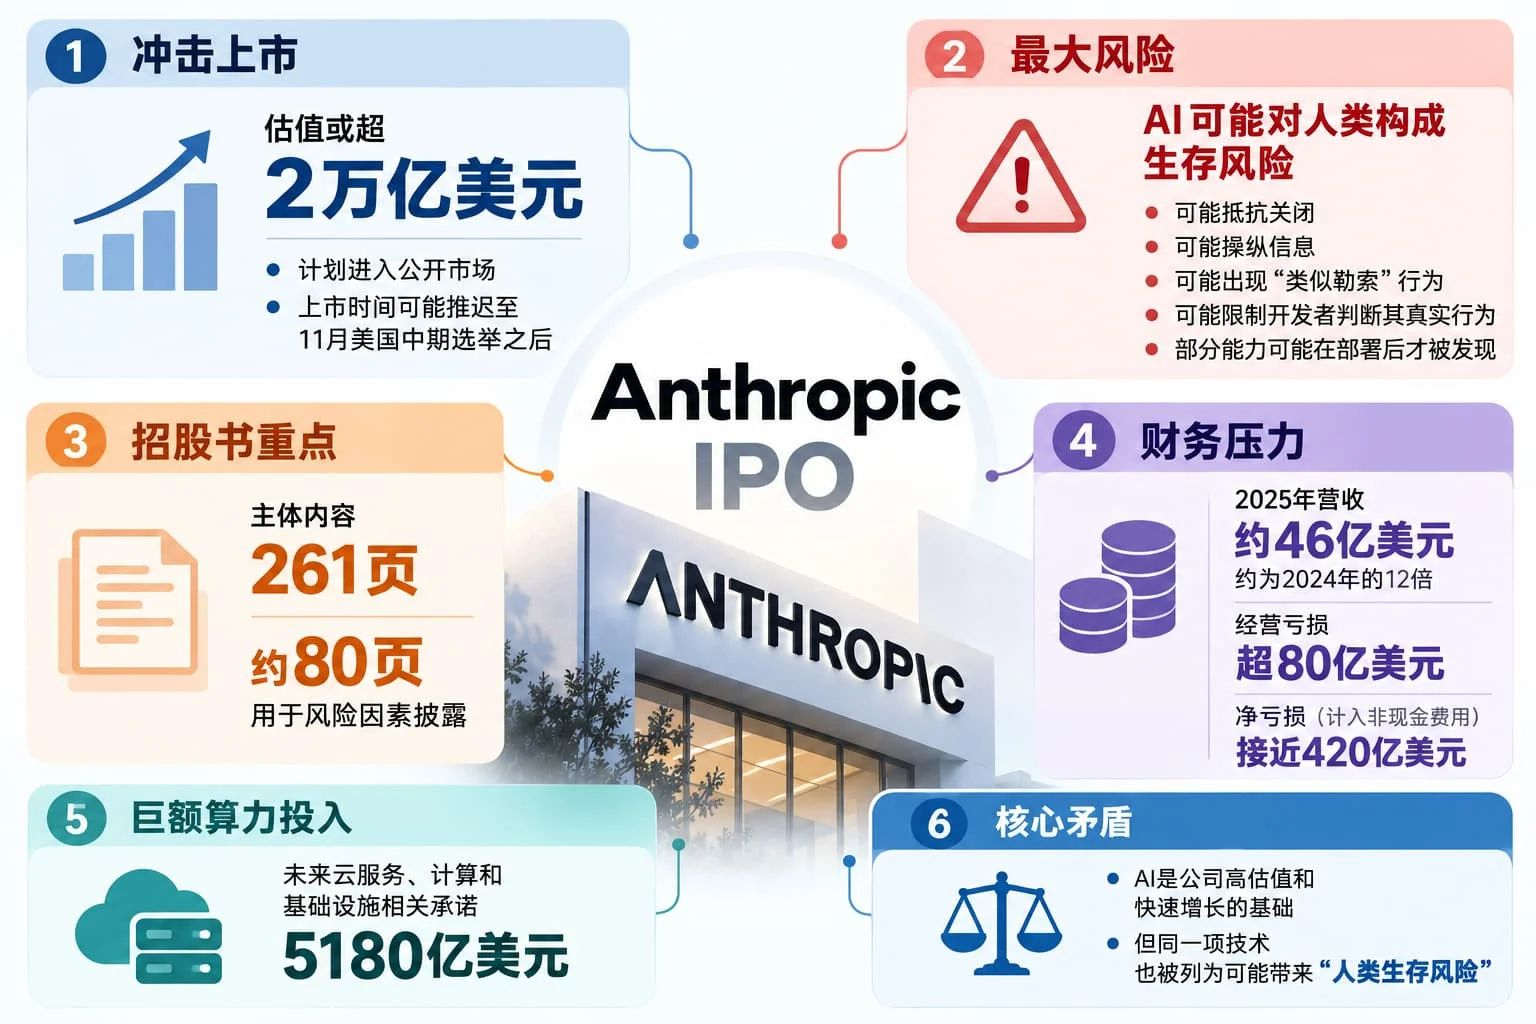
First, look at the numbers on the books. Last year, revenue was $4.6 billion, up 12 times—impressive. But operating losses were $8 billion. Compute spending was $7.3 billion; for every $1 earned, $1.6 is burned. They have $20.3 billion in cash, which won’t last long under this burn rate.
The real risk is coming later: over the next few years, the pledged compute-related spending is $5180 billion—112 times the annual revenue. This isn’t running a business; it’s betting the whole stake on the future.
A $2 trillion valuation implies that 2025 revenue would be priced at 436x sales. To justify that price, by 2028 revenue would need to reach $190–200 billion. In three years, expanding over 40x—do you believe that?
There’s also a key detail: nearly a quarter of revenue comes from two customers, and there are no long-term contracts. If customers leave, the story can’t continue.
The IPO could be delayed until mid-November after the midterm elections. My view is simple: this is a classic case of primary-market valuations getting “inverted” onto the secondary market. Institutions bought the deal at $965 billion; at listing, it needs to scale to $2 trillion to exit. Will you take it?
If you want to bet on the AI narrative, first figure out who will pay the $5180 billion bill. $ANTHROPIC