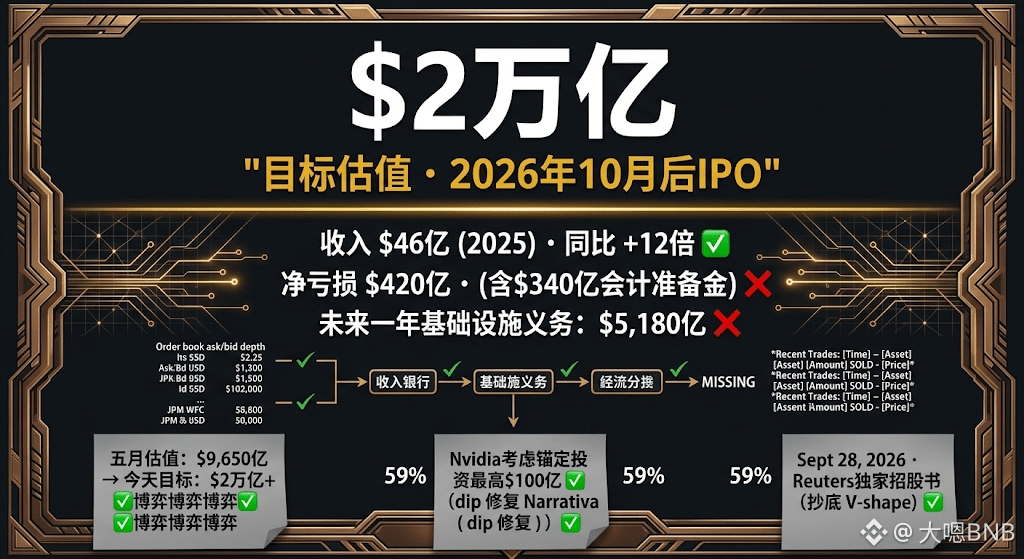

Today, Reuters has seen Anthropic’s IPO filing.
A few figures:
2025 revenue is $4.6 billion, up 12x year over year.
Net loss of $42 billion — but $34 billion is an accounting provision, not the same as real cash burn. Real operating loss is $8.06 billion.
Plans to spend $518 billion over the next year on cloud computing and infrastructure.
Target valuation: above $2 trillion.
In May, the valuation was still $965 billion; in less than four months, the target doubled.
I dug into the logic behind these numbers: In July 2026, annualized revenue is projected to exceed $65 billion, with Q2 single-quarter revenue at $11.6 billion. If this growth rate can hold, the forecast for 2028 revenue of $190 billion to $200 billion would be real — and the $2 trillion valuation is roughly 10x expected 2028 revenue.
Whether it can be sustained depends on one thing: whether the growth rate can be maintained.
The company is currently the 7th-largest by market cap (if the IPO succeeds), surpassing Tesla and Berkshire Hathaway. But it has only one product — AI coding tool and Claude.
SpaceX priced to list in June at $1.77 trillion; shares jumped 19% on the first day and are now around $147 (IPO price $135).
Anthropic is 12% more expensive than SpaceX, but its monetization path is clearer than SpaceX’s — enterprise and developer subscriptions are more predictable than satellite launches.
The IPO is expected after mid-term elections. Nvidia is considering joining as an anchor investor.
For BTC: Anthropic’s successful IPO is the strongest institutional endorsement of this year’s AI narrative — it should lift risk appetite across the entire AI supply chain, benefiting BTC as a supporting asset for the AI economy.
Would you subscribe at a $2 trillion valuation?
$BTC
$NVDAB
#anthropic招股书或估值超2万亿美元