Little chives · Global macro market dashboard intelligence (09-26 Special Issue)
Benchmark period: 09-25 08:35 to 09-26 08:35 | Global macro vertical-track firsthand analysis
【In-depth intelligence from the Large Model · Strategic Answers】
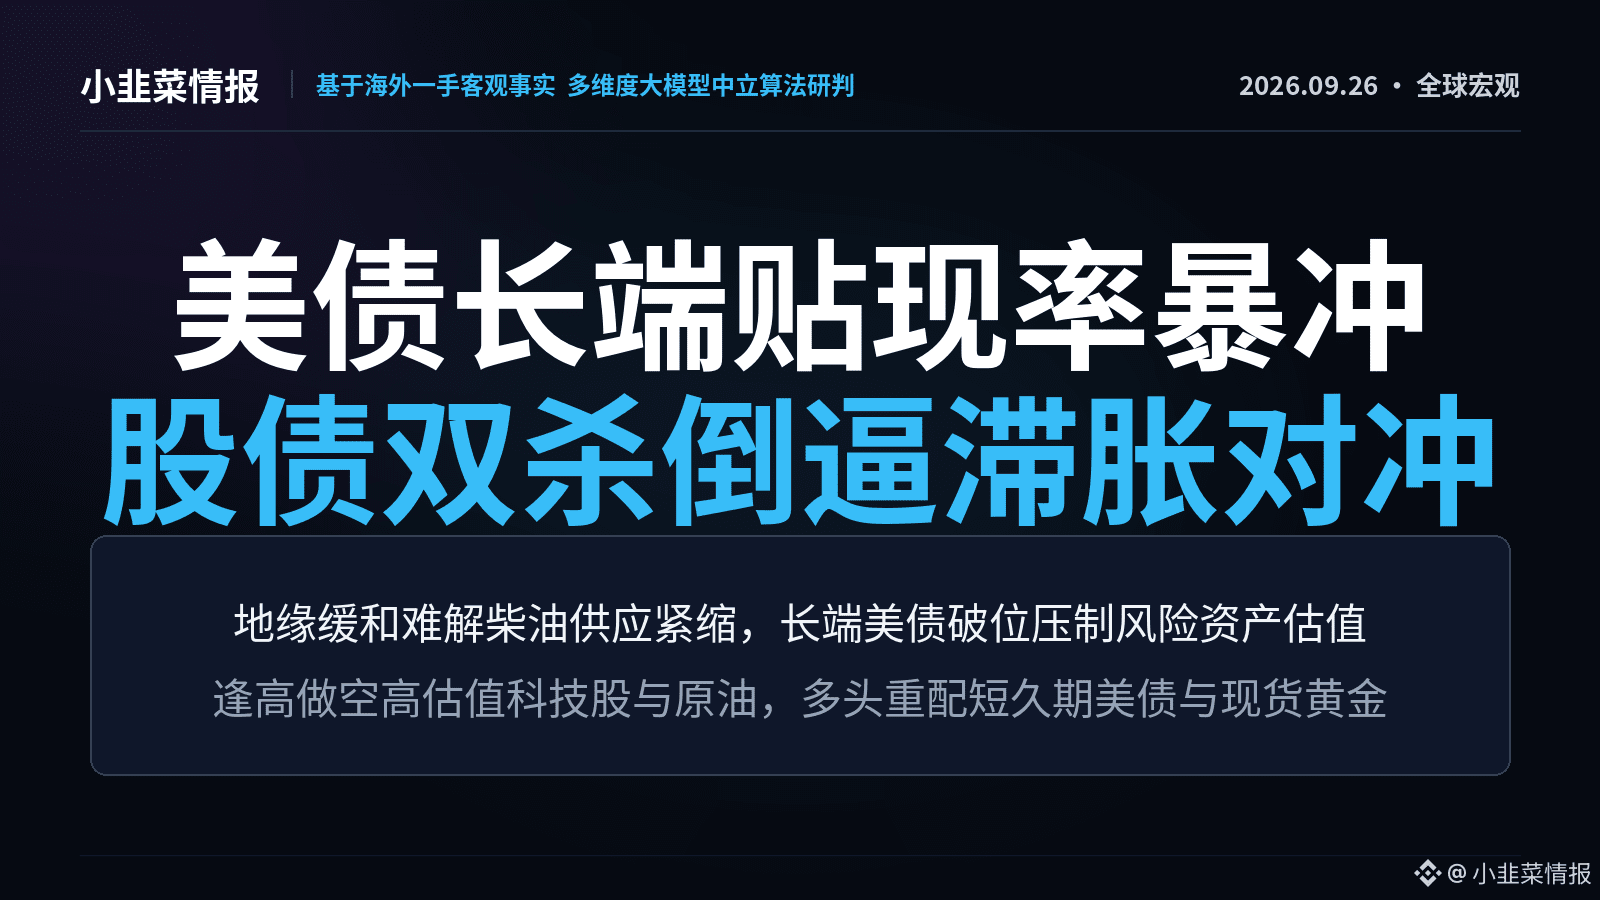
Over the past 24 hours, global macro has shown a clear stagflation pattern alongside a reshaping of discount rates: the 10-year U.S. Treasury yield surged to 5.23%, and the 30-year moved above 5.5%. Sovereign bond yields worldwide have entered decades-long high territory; the equity-and-bond risk premium has fallen to historical lows, and U.S. stock valuations are approaching a critical turning point. Although U.S.-Iran discussions related to the Strait of Hormuz triggered a technical negotiation, causing crude oil to tumble intraday by 4%, real logistics bottlenecks remain unresolved—super-large oil tanker freight rates hit a record of $1.27 million per day, and diesel supply remains tight. Meanwhile, the one-year Michigan inflation expectation climbed to 4.6%, forcing markets to price in a Fed rate-hike probability of around 70%. Joint official action by the U.S. and Japan targeting undervaluation of the yen further amplifies the risk of unwinds in global carry trades and FX volatility.
The strategic conclusion is extremely clear: the macro cycle has shifted from being driven primarily by liquidity premia to a comprehensive anti-stagflation defense and valuation-clearing phase. Asset allocation will firmly implement both long/short hedging strategies: short high-valuation tech growth stocks that are sensitive to duration, and go long crude oil for the decline in the geopolitical premium; meanwhile, go long spot gold with characteristics that hedge against both fiscal deficit risk and inflation. Also, rebalance into short-term cash-management tools and high-yield assets in the short end of U.S. Treasuries to lock in near risk-free high discounted returns, and ride through the storm of tightening global liquidity.
【24H Core Firsthand Dynamic Checklist】
• Nigeria joins the International Energy Agency; crude oil production hits a six-year high: Nigeria is set to formulate ambitious energy plans over the coming decades, including expanding its oil industry and accelerating development of the renewables sector.
• As oil prices fall and stocks rise, the U.S. dollar declines: the U.S. Dollar Index (DXY00) fell by -0.32% on Friday.
• Oil prices drop sharply; hopes to reach an agreement to reopen the Strait of Hormuz: November WTI crude (CLX26) closed down -2.20 (-2.33%); November RBOB gasoline (RBX26) closed down -0.1455 (-4.37%).
————————————
Firsthand long-form facts and AI deep-dive analysis across the internet have been synced to the official website:
The full network firsthand facts and multi-dimensional AI deep-dive analysis have been synced to the official board—see the homepage for the dedicated channel pinned at the top.