

只会呐喊的尖刀手
272 Posts
只会呐喊的尖刀手
Report
Block User
乘风破浪会有时 直挂云帆济沧海

BNB Holder
Frequent Trader
9 Years
434 Following
29.1K+ Followers
15.8K+ Liked
Posts
PINNED
·
--
The wind blew the clouds apart.
The sky has a patch of blue—
just enough for me
to put on
an unbothered, carefree smile.
The wind blew the clouds apart.
The sky has a patch of blue—
just enough for me
to put on
an unbothered, carefree smile.
The sky has a patch of blue—
just enough for me
to put on
an unbothered, carefree smile.
2.7k
27
134
2.7k
·
--
Article
Don’t just watch Nvidia—AI’s “landlords” are quietly collecting rentEveryone’s watching the AI market, their eyes glued to Nvidia, Microsoft, and OpenAI: the moment Jensen Huang shows up in a leather jacket, the U.S. stocks act like they’ve been injected with adrenaline; when Sam Altman says, “Next year will be even more intense,” analysts change their earnings forecasts overnight.
But if you really think the future of AI is just “a few big players in California closing the door to make chips, training models, and conveniently ruling the world,” then it’s a bit like thinking you only need to buy a pot to open a hotpot restaurant—yes, the pot matters, but without electricity, without gas, without a shop, without drainage pipes, what you cook isn’t hotpot; it’s a fire-drill.
Don’t just watch Nvidia—AI’s “landlords” are quietly collecting rent
Everyone’s watching the AI market, their eyes glued to Nvidia, Microsoft, and OpenAI: the moment Jensen Huang shows up in a leather jacket, the U.S. stocks act like they’ve been injected with adrenaline; when Sam Altman says, “Next year will be even more intense,” analysts change their earnings forecasts overnight.
But if you really think the future of AI is just “a few big players in California closing the door to make chips, training models, and conveniently ruling the world,” then it’s a bit like thinking you only need to buy a pot to open a hotpot restaurant—yes, the pot matters, but without electricity, without gas, without a shop, without drainage pipes, what you cook isn’t hotpot; it’s a fire-drill.
But if you really think the future of AI is just “a few big players in California closing the door to make chips, training models, and conveniently ruling the world,” then it’s a bit like thinking you only need to buy a pot to open a hotpot restaurant—yes, the pot matters, but without electricity, without gas, without a shop, without drainage pipes, what you cook isn’t hotpot; it’s a fire-drill.
12
5
18
384
·
--
Fell down
Then, naturally, kissed the earth
And, as a bonus, picked up
That candy
that had just fallen
Fell down
Then, naturally, kissed the earth
And, as a bonus, picked up
That candy
that had just fallen
Then, naturally, kissed the earth
And, as a bonus, picked up
That candy
that had just fallen
612
7
51
612
·
--
The next major opportunity may initially seem unremarkable.
Until a small innovation changes the entire industry.
—CZ BNB
#比特币突破8.5万美元
The next major opportunity may initially seem unremarkable.
Until a small innovation changes the entire industry.
—CZ BNB
#比特币突破8.5万美元
Until a small innovation changes the entire industry.
—CZ BNB
#比特币突破8.5万美元
473
5
35
648
·
--
A painful truth:
Many people don’t have the patience to spend 3 years building their own career
but they do have the patience to work for someone else for 40 years
A painful truth:
Many people don’t have the patience to spend 3 years building their own career
but they do have the patience to work for someone else for 40 years
Many people don’t have the patience to spend 3 years building their own career
but they do have the patience to work for someone else for 40 years
2.7k
24
156
2.7k
·
--
Article
BTC Reclaims $80,000: Bad News Didn’t Hit, But I Don’t Recommend You Chase It NowThis week, the macro environment and regulation are actually not very friendly:
• The Federal Reserve hiked rates by 25bp, bringing interest rates to 3.75%–4.00%;
• In the U.S., the (CLARITY Act) advanced in the Senate but was blocked;
• In the first half of the week, BTC once dipped back toward around 77,000.
But on September 18, BTC not only reclaimed 80,000, it also briefly surged to between $81.2k and $81.4k. ETH rose in tandem by about 7%–8%, and SOL, XRP, and others also followed. At the same time, the US spot BTC ETF ended its streak of outflows and recorded roughly $160 million in net inflows.
My judgment is straightforward:
This isn’t a “full return of the bull market,” but a rebound driven by the combined effects of “bad news being digested + short-covering + ETF capital returning.”
BTC Reclaims $80,000: Bad News Didn’t Hit, But I Don’t Recommend You Chase It Now
This week, the macro environment and regulation are actually not very friendly:
• The Federal Reserve hiked rates by 25bp, bringing interest rates to 3.75%–4.00%;
• In the U.S., the (CLARITY Act) advanced in the Senate but was blocked;
• In the first half of the week, BTC once dipped back toward around 77,000.
But on September 18, BTC not only reclaimed 80,000, it also briefly surged to between $81.2k and $81.4k. ETH rose in tandem by about 7%–8%, and SOL, XRP, and others also followed. At the same time, the US spot BTC ETF ended its streak of outflows and recorded roughly $160 million in net inflows.
My judgment is straightforward:
This isn’t a “full return of the bull market,” but a rebound driven by the combined effects of “bad news being digested + short-covering + ETF capital returning.”
• The Federal Reserve hiked rates by 25bp, bringing interest rates to 3.75%–4.00%;
• In the U.S., the (CLARITY Act) advanced in the Senate but was blocked;
• In the first half of the week, BTC once dipped back toward around 77,000.
But on September 18, BTC not only reclaimed 80,000, it also briefly surged to between $81.2k and $81.4k. ETH rose in tandem by about 7%–8%, and SOL, XRP, and others also followed. At the same time, the US spot BTC ETF ended its streak of outflows and recorded roughly $160 million in net inflows.
My judgment is straightforward:
This isn’t a “full return of the bull market,” but a rebound driven by the combined effects of “bad news being digested + short-covering + ETF capital returning.”
1.9k
9
106
1.9k
·
--
Don’t be afraid to go slow
Even snails have a springtime
Carrying a heavy shell on their back
Step by step
Turning the road into poetry
Don’t be afraid to go slow
Even snails have a springtime
Carrying a heavy shell on their back
Step by step
Turning the road into poetry
Even snails have a springtime
Carrying a heavy shell on their back
Step by step
Turning the road into poetry
1.8k
4
81
1.8k
·
--
The rain stopped.
The sky forgot to turn off the faucet.
It’s okay.
A rainbow is its apology.
The best apology
The rain stopped.
The sky forgot to turn off the faucet.
It’s okay.
A rainbow is its apology.
The best apology
The sky forgot to turn off the faucet.
It’s okay.
A rainbow is its apology.
The best apology
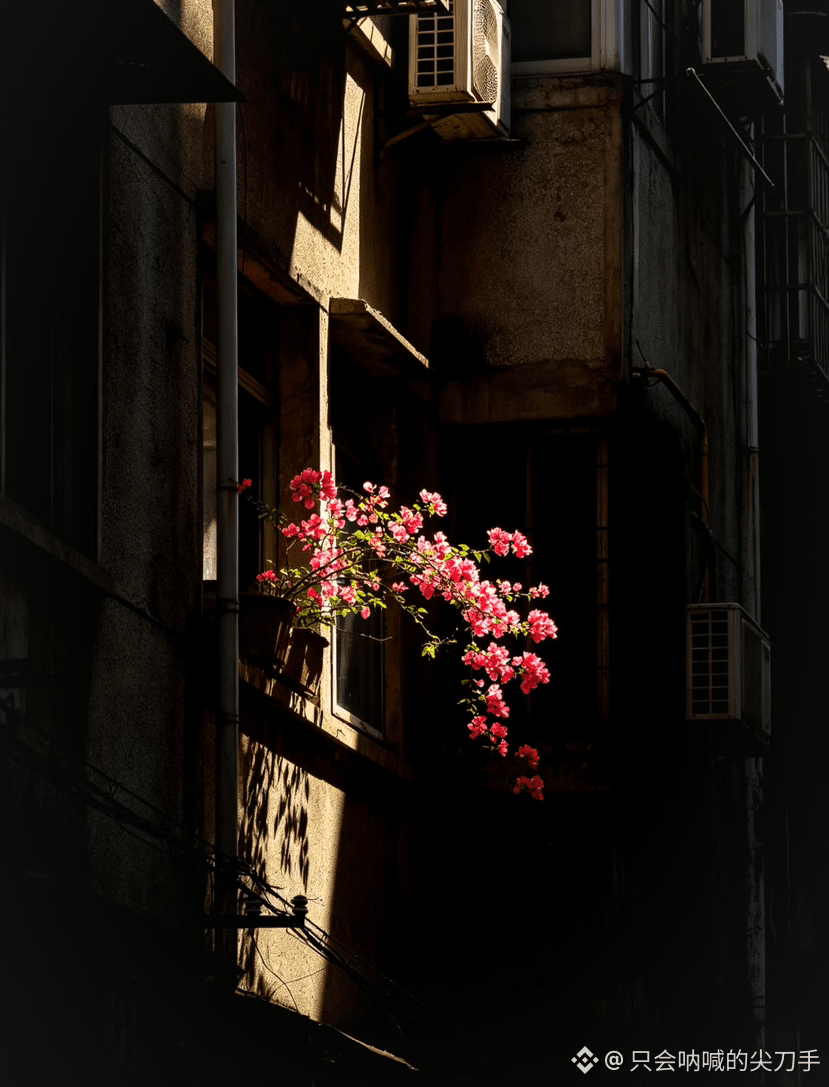
2k
5
114
2k
·
--
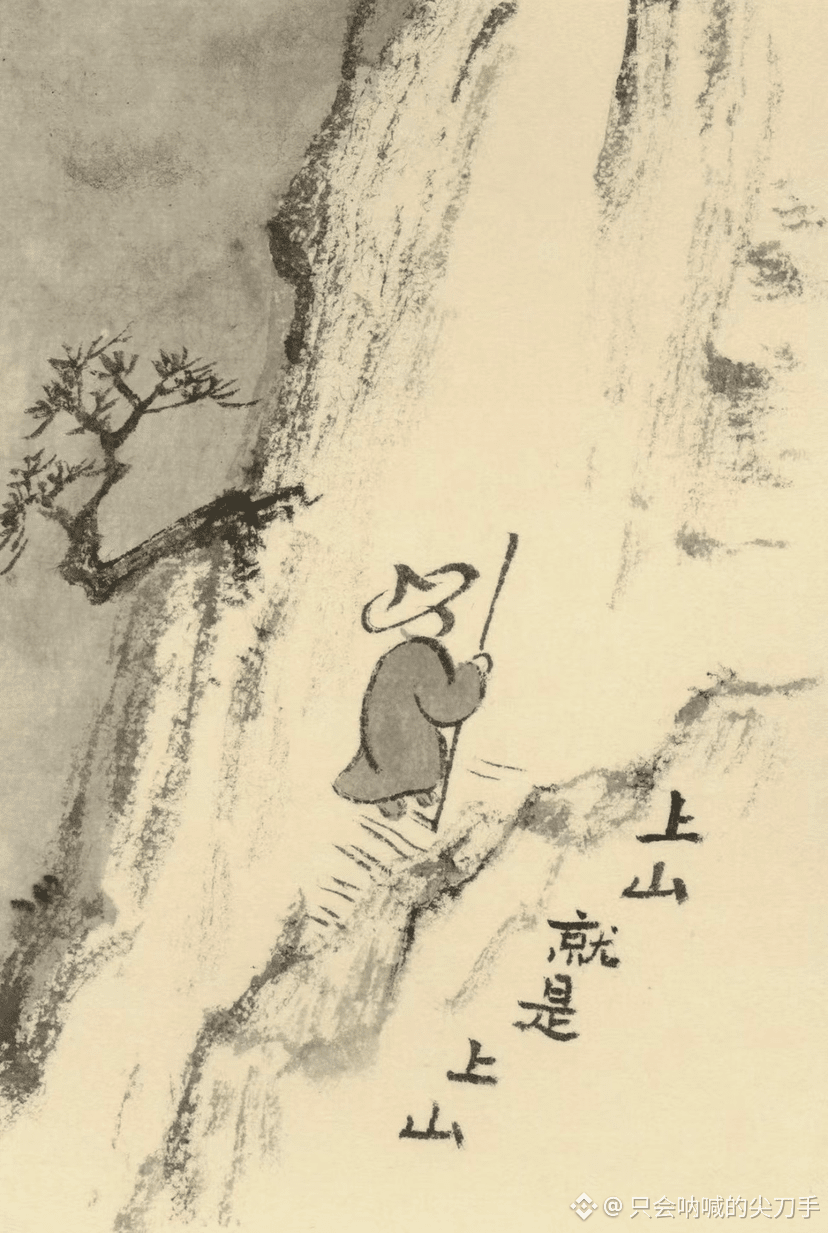
Fell over
So naturally I kissed the earth
And, while I was at it, picked up
That candy that had just dropped
A moment ago
Fell over
So naturally I kissed the earth
And, while I was at it, picked up
That candy that had just dropped
A moment ago
So naturally I kissed the earth
And, while I was at it, picked up
That candy that had just dropped
A moment ago
2.6k
10
143
2.6k
·
--
【Product Name】Today’s Limited Edition·You
【Production Date】The moment you wake up this morning
【Ingredients】Sunlight, a gentle breeze, and a little stubbornness
【Indications】Specifically treats being unhappy, having no spirit, and wanting to just lie down and do nothing
【Directions】Use anytime, all day long—refill your “good mood” whenever you need it
【Precautions】Avoid using it together with “negative energy.” Do not suppress your frustrations on an empty stomach
【Shelf Life】Only valid for today. Please switch to the new version tomorrow
—Please store it properly; you are the limited edition.🏷️💖
【Product Name】Today’s Limited Edition·You
【Production Date】The moment you wake up this morning
【Ingredients】Sunlight, a gentle breeze, and a little stubbornness
【Indications】Specifically treats being unhappy, having no spirit, and wanting to just lie down and do nothing
【Directions】Use anytime, all day long—refill your “good mood” whenever you need it
【Precautions】Avoid using it together with “negative energy.” Do not suppress your frustrations on an empty stomach
【Shelf Life】Only valid for today. Please switch to the new version tomorrow
—Please store it properly; you are the limited edition.🏷️💖
【Production Date】The moment you wake up this morning
【Ingredients】Sunlight, a gentle breeze, and a little stubbornness
【Indications】Specifically treats being unhappy, having no spirit, and wanting to just lie down and do nothing
【Directions】Use anytime, all day long—refill your “good mood” whenever you need it
【Precautions】Avoid using it together with “negative energy.” Do not suppress your frustrations on an empty stomach
【Shelf Life】Only valid for today. Please switch to the new version tomorrow
—Please store it properly; you are the limited edition.🏷️💖
3.1k
25
206
3.1k
·
--
👀 Wherever your eyes reach, there is scenery.
👂 Whatever your ears hear, there is lovely music.
👐 Whatever your hands touch, there is warmth.
💖 Whatever your heart yearns for, there is an open road.
👀 Wherever your eyes reach, there is scenery.
👂 Whatever your ears hear, there is lovely music.
👐 Whatever your hands touch, there is warmth.
💖 Whatever your heart yearns for, there is an open road.
👂 Whatever your ears hear, there is lovely music.
👐 Whatever your hands touch, there is warmth.
💖 Whatever your heart yearns for, there is an open road.
2.8k
10
164
2.8k
·
--
Allow anything to happen.
Allow plans to be thrown off.
Allow yourself to be imperfect.
Allow today to be just an “ordinary day.”
You don’t have to shine all the time.
You can also be a quiet shadow.
That, too, is proof that you exist.
Allow anything to happen.
Allow plans to be thrown off.
Allow yourself to be imperfect.
Allow today to be just an “ordinary day.”
You don’t have to shine all the time.
You can also be a quiet shadow.
That, too, is proof that you exist.
Allow plans to be thrown off.
Allow yourself to be imperfect.
Allow today to be just an “ordinary day.”
You don’t have to shine all the time.
You can also be a quiet shadow.
That, too, is proof that you exist.
3.6k
8
208
3.6k
·
--
“Today, the protagonist decides to take a break.
Not to save the world, nor to conquer the stars.
Just sits by the window, sipping a cup of warm milk,
watching pedestrians hurry past, and then tells himself:
‘Hey, you’ve worked hard today.’”
“Today, the protagonist decides to take a break.
Not to save the world, nor to conquer the stars.
Just sits by the window, sipping a cup of warm milk,
watching pedestrians hurry past, and then tells himself:
‘Hey, you’ve worked hard today.’”
Not to save the world, nor to conquer the stars.
Just sits by the window, sipping a cup of warm milk,
watching pedestrians hurry past, and then tells himself:
‘Hey, you’ve worked hard today.’”

2.8k
18
160
2.8k
·
--
Bullish
Verified
Not exactly quiet lately for NVIDIA: China is investigating whether it actually kept the promise of “fair treatment” made back when it acquired Micrelax; meanwhile, the U.S. Department of Justice is also scrutinizing NVIDIA and Groq’s $17 billion “technology licensing + core personnel joining” deal, suspecting it may be a “backdoor acquisition” meant to sidestep antitrust review.
It sounds scary, but translated into plain language it means this: regulators worry that NVIDIA is getting too strong—don’t let it swallow up all its rivals. These investigations may rattle sentiment in the short term, but most likely the outcome is fines or process improvements. It’s unlikely NVIDIA gets broken up, and it definitely won’t make AI data centers start returning GPUs.
What really drives the stock price is still: “Are there buyers? Can they supply enough?” The answer is straightforward: buyers are lining up. In the latest quarter, revenue hit $96.2 billion—up 100% year over year. The next-quarter guidance is $108 billion. Huang Renxun says NVIDIA can still grow another 70% in the coming fiscal year, with roughly $2 trillion in orders on hand. Blackwell is already in short supply; Rubin will take over. CUDA, network cards, full machine racks, and the ecosystem of cloud providers are all tightly integrated—competitors may rise, but replacing NVIDIA is not something that will happen in just two or three years.
Of course there are risks: China revenue is not steady; HBM and packaging capacity are bottlenecks; gross margins could slide a bit from 75%; and Amazon/Google’s in-house chips may take some share of inference scenarios. But those are more like “earn less / longer lead times,” not “demand is gone.”
So NVIDIA recently is like the top student in class getting checked for homework—not because the grades are bad, but because the fame and power are too big, so regulators want to verify the rules. As long as the world is still building AI factories, NVIDIA is selling “shovels + engines + an operating system.”
My take is simple: short term there can be regulatory and valuation swings, but in the long run I still look favorably on NVIDIA stock. Don’t treat it like a risk-free deposit, but don’t declare the AI compute-cycle over too early either—chances are you’ll be wrong.$NVDA.US
Not exactly quiet lately for NVIDIA: China is investigating whether it actually kept the promise of “fair treatment” made back when it acquired Micrelax; meanwhile, the U.S. Department of Justice is also scrutinizing NVIDIA and Groq’s $17 billion “technology licensing + core personnel joining” deal, suspecting it may be a “backdoor acquisition” meant to sidestep antitrust review.
It sounds scary, but translated into plain language it means this: regulators worry that NVIDIA is getting too strong—don’t let it swallow up all its rivals. These investigations may rattle sentiment in the short term, but most likely the outcome is fines or process improvements. It’s unlikely NVIDIA gets broken up, and it definitely won’t make AI data centers start returning GPUs.
What really drives the stock price is still: “Are there buyers? Can they supply enough?” The answer is straightforward: buyers are lining up. In the latest quarter, revenue hit $96.2 billion—up 100% year over year. The next-quarter guidance is $108 billion. Huang Renxun says NVIDIA can still grow another 70% in the coming fiscal year, with roughly $2 trillion in orders on hand. Blackwell is already in short supply; Rubin will take over. CUDA, network cards, full machine racks, and the ecosystem of cloud providers are all tightly integrated—competitors may rise, but replacing NVIDIA is not something that will happen in just two or three years.
Of course there are risks: China revenue is not steady; HBM and packaging capacity are bottlenecks; gross margins could slide a bit from 75%; and Amazon/Google’s in-house chips may take some share of inference scenarios. But those are more like “earn less / longer lead times,” not “demand is gone.”
So NVIDIA recently is like the top student in class getting checked for homework—not because the grades are bad, but because the fame and power are too big, so regulators want to verify the rules. As long as the world is still building AI factories, NVIDIA is selling “shovels + engines + an operating system.”
My take is simple: short term there can be regulatory and valuation swings, but in the long run I still look favorably on NVIDIA stock. Don’t treat it like a risk-free deposit, but don’t declare the AI compute-cycle over too early either—chances are you’ll be wrong.$NVDA.US
It sounds scary, but translated into plain language it means this: regulators worry that NVIDIA is getting too strong—don’t let it swallow up all its rivals. These investigations may rattle sentiment in the short term, but most likely the outcome is fines or process improvements. It’s unlikely NVIDIA gets broken up, and it definitely won’t make AI data centers start returning GPUs.
What really drives the stock price is still: “Are there buyers? Can they supply enough?” The answer is straightforward: buyers are lining up. In the latest quarter, revenue hit $96.2 billion—up 100% year over year. The next-quarter guidance is $108 billion. Huang Renxun says NVIDIA can still grow another 70% in the coming fiscal year, with roughly $2 trillion in orders on hand. Blackwell is already in short supply; Rubin will take over. CUDA, network cards, full machine racks, and the ecosystem of cloud providers are all tightly integrated—competitors may rise, but replacing NVIDIA is not something that will happen in just two or three years.
Of course there are risks: China revenue is not steady; HBM and packaging capacity are bottlenecks; gross margins could slide a bit from 75%; and Amazon/Google’s in-house chips may take some share of inference scenarios. But those are more like “earn less / longer lead times,” not “demand is gone.”
So NVIDIA recently is like the top student in class getting checked for homework—not because the grades are bad, but because the fame and power are too big, so regulators want to verify the rules. As long as the world is still building AI factories, NVIDIA is selling “shovels + engines + an operating system.”
My take is simple: short term there can be regulatory and valuation swings, but in the long run I still look favorably on NVIDIA stock. Don’t treat it like a risk-free deposit, but don’t declare the AI compute-cycle over too early either—chances are you’ll be wrong.$NVDA.US

NVDAUS+0.22%
2
4
838
·
--
Bearish
ZEC’s sudden surge—put simply, it’s “ETF buy pressure + short liquidations + the privacy narrative” all blowing in the same direction. It’s not that there are really that many people using ZEC for transfers. The price went from 50 to 1200, but the pool’s share only rose by 5 percentage points—showing that the money is trading the story, not the product.
The shorts have already been liquidated in a first round. Anyone who was going to get cut has already been cut. After that, there are no fresh shorts left to squeeze. Bulls now have to hold the bag themselves. Futures positions are about $2 billion, roughly half the entire equity value on top—so when it drops, it becomes a ruthless cascade of liquidations, even worse than the rally.
Grayscale’s ZCASH is currently being pulled up by big institutions, but ETFs aren’t a money-printing machine. The day net inflows turn negative, the market will instantly flip from “institutional bull” to “good news already priced in.” Add the EU’s 2027 ban on privacy coins, and the fact that in the US the moment regulation changes, exchanges can delist this stuff—so it’s inherently policy-sensitive.
On the macro side, no one takes a side: oil is heading toward $100, the 10-year Treasury is at 4.8, and the Fed is set to keep hiking. Even gold’s safe-haven hedge isn’t working. If that’s the environment, who would still treat a high-leverage alt as a treasure? BTC hasn’t even returned to $80k, yet ZEC jumps 24x first—that’s liquidity illusion.
Don’t learn from the big shots and stubbornly hold short positions to lose tens of millions. Smart people aren’t in a rush to short right now—wait for three signals: ZCASH inflows turn negative, a 4-hour long upper wick appears, and BTC breaks above $78k. Once it hits, place your sell orders. Targets first at 800, then 500. Going long ZEC is chasing the story; shorting ZEC is waiting for the story to run out of oxygen: the wind stops, the pigs fall first—and privacy coins fall the hardest.
This isn’t a bargain-hunting moment—it’s a hunter waiting for prey. $ZEC
{future}(ZECUSDT)
ZEC’s sudden surge—put simply, it’s “ETF buy pressure + short liquidations + the privacy narrative” all blowing in the same direction. It’s not that there are really that many people using ZEC for transfers. The price went from 50 to 1200, but the pool’s share only rose by 5 percentage points—showing that the money is trading the story, not the product.
The shorts have already been liquidated in a first round. Anyone who was going to get cut has already been cut. After that, there are no fresh shorts left to squeeze. Bulls now have to hold the bag themselves. Futures positions are about $2 billion, roughly half the entire equity value on top—so when it drops, it becomes a ruthless cascade of liquidations, even worse than the rally.
Grayscale’s ZCASH is currently being pulled up by big institutions, but ETFs aren’t a money-printing machine. The day net inflows turn negative, the market will instantly flip from “institutional bull” to “good news already priced in.” Add the EU’s 2027 ban on privacy coins, and the fact that in the US the moment regulation changes, exchanges can delist this stuff—so it’s inherently policy-sensitive.
On the macro side, no one takes a side: oil is heading toward $100, the 10-year Treasury is at 4.8, and the Fed is set to keep hiking. Even gold’s safe-haven hedge isn’t working. If that’s the environment, who would still treat a high-leverage alt as a treasure? BTC hasn’t even returned to $80k, yet ZEC jumps 24x first—that’s liquidity illusion.
Don’t learn from the big shots and stubbornly hold short positions to lose tens of millions. Smart people aren’t in a rush to short right now—wait for three signals: ZCASH inflows turn negative, a 4-hour long upper wick appears, and BTC breaks above $78k. Once it hits, place your sell orders. Targets first at 800, then 500. Going long ZEC is chasing the story; shorting ZEC is waiting for the story to run out of oxygen: the wind stops, the pigs fall first—and privacy coins fall the hardest.
This isn’t a bargain-hunting moment—it’s a hunter waiting for prey. $ZEC
The shorts have already been liquidated in a first round. Anyone who was going to get cut has already been cut. After that, there are no fresh shorts left to squeeze. Bulls now have to hold the bag themselves. Futures positions are about $2 billion, roughly half the entire equity value on top—so when it drops, it becomes a ruthless cascade of liquidations, even worse than the rally.
Grayscale’s ZCASH is currently being pulled up by big institutions, but ETFs aren’t a money-printing machine. The day net inflows turn negative, the market will instantly flip from “institutional bull” to “good news already priced in.” Add the EU’s 2027 ban on privacy coins, and the fact that in the US the moment regulation changes, exchanges can delist this stuff—so it’s inherently policy-sensitive.
On the macro side, no one takes a side: oil is heading toward $100, the 10-year Treasury is at 4.8, and the Fed is set to keep hiking. Even gold’s safe-haven hedge isn’t working. If that’s the environment, who would still treat a high-leverage alt as a treasure? BTC hasn’t even returned to $80k, yet ZEC jumps 24x first—that’s liquidity illusion.
Don’t learn from the big shots and stubbornly hold short positions to lose tens of millions. Smart people aren’t in a rush to short right now—wait for three signals: ZCASH inflows turn negative, a 4-hour long upper wick appears, and BTC breaks above $78k. Once it hits, place your sell orders. Targets first at 800, then 500. Going long ZEC is chasing the story; shorting ZEC is waiting for the story to run out of oxygen: the wind stops, the pigs fall first—and privacy coins fall the hardest.
This isn’t a bargain-hunting moment—it’s a hunter waiting for prey. $ZEC
2
6
1.3k
·
--
1. BTC is ranging between 77,800–79,200 (RMB), and has not yet reclaimed the 790,000 level. The market is waiting for Thursday’s PPI and Friday’s CPI.
2. ETH is hovering around 2,490; SOL is around 103. Altcoins are diverging: ZEC is strong, while WLD/MORPHO are weak.
3. Brent is edging toward $100 intraday. Attacks by Iran/Iranian-linked forces + the Houthis on Saudi facilities have heightened geopolitical risk, weighing on risk assets.
4. The probability of a Fed rate hike in September is about 60%. 10Y U.S. Treasuries are near 4.8%. A stronger dollar is bearish for crypto and gold in the short term.
5. Spot BTC ETFs saw net outflows of about $47 million yesterday. IBIT/BITB/ARKB had inflows, while GBTC is lagging.
6. ETH ETFs posted small net outflows as well. XRP ETFs bucked the trend, attracting about $2 million; capital is selecting specific targets to buy.
7. Zcash (ZEC): Grayscale’s ZCSH assets broke through $500 million. Privacy coins remain one of the strongest narratives in a weak market.
8. RWA/stablecoins continue to outperform: bank-backed euro stablecoins, an Uzbekistan pilot, and Circle’s cross-border payments expansion.
9. Block has applied to the OCC for a national trust bank charter, aiming to provide BTC + stablecoin custody—an additional step for institutional infrastructure.
10. Robinhood is betting on prediction markets, connecting with Crypto.com/OG.com. Exchanges are looking for incremental growth in “non-crypto” business.
11. The Liquid Network security incident is unfolding. BTC L2 security audits and custody trust are back in focus.
12. HYPE’s unlock selling pressure hasn’t fully cleared. Multicoin is accused of selling about 1.725M HYPE since the end of July, netting $77 million in profit.
13. Derivatives longs hold a slight edge (BTC long/short ratio about 1.11), but a break above 81,000 could trigger liquidation of nearly $860 million in short positions.
14. Copper on the LME hit a record high of $14,779 per ton intraday. AI + power grids + EVs + Chile disruptions are drawing commodities to absorb some speculative capital.
15. Gold first sold off then rallied: spot gold has returned to 4,400. The narrative has shifted from “safe-haven” to “rate-hike pressure vs central bank gold buying.”
16. Supply disruptions in rare earths/antimony/tungsten plus Middle East oil prices. Capital preference: crude oil, copper, rare earths, and precious/rare metals > high-FDV altcoins.
17. Total crypto market cap is about $2.7–2.8 trillion. The Altcoin Season Index is 47/100—still not at a full altcoin season.
This isn’t a “bull-market pullback”—it’s a “macros tied-up period.” As long as oil prices/CPI/Fed don’t clear, BTC is hard to trade directionally.
1. BTC is ranging between 77,800–79,200 (RMB), and has not yet reclaimed the 790,000 level. The market is waiting for Thursday’s PPI and Friday’s CPI.
2. ETH is hovering around 2,490; SOL is around 103. Altcoins are diverging: ZEC is strong, while WLD/MORPHO are weak.
3. Brent is edging toward $100 intraday. Attacks by Iran/Iranian-linked forces + the Houthis on Saudi facilities have heightened geopolitical risk, weighing on risk assets.
4. The probability of a Fed rate hike in September is about 60%. 10Y U.S. Treasuries are near 4.8%. A stronger dollar is bearish for crypto and gold in the short term.
5. Spot BTC ETFs saw net outflows of about $47 million yesterday. IBIT/BITB/ARKB had inflows, while GBTC is lagging.
6. ETH ETFs posted small net outflows as well. XRP ETFs bucked the trend, attracting about $2 million; capital is selecting specific targets to buy.
7. Zcash (ZEC): Grayscale’s ZCSH assets broke through $500 million. Privacy coins remain one of the strongest narratives in a weak market.
8. RWA/stablecoins continue to outperform: bank-backed euro stablecoins, an Uzbekistan pilot, and Circle’s cross-border payments expansion.
9. Block has applied to the OCC for a national trust bank charter, aiming to provide BTC + stablecoin custody—an additional step for institutional infrastructure.
10. Robinhood is betting on prediction markets, connecting with Crypto.com/OG.com. Exchanges are looking for incremental growth in “non-crypto” business.
11. The Liquid Network security incident is unfolding. BTC L2 security audits and custody trust are back in focus.
12. HYPE’s unlock selling pressure hasn’t fully cleared. Multicoin is accused of selling about 1.725M HYPE since the end of July, netting $77 million in profit.
13. Derivatives longs hold a slight edge (BTC long/short ratio about 1.11), but a break above 81,000 could trigger liquidation of nearly $860 million in short positions.
14. Copper on the LME hit a record high of $14,779 per ton intraday. AI + power grids + EVs + Chile disruptions are drawing commodities to absorb some speculative capital.
15. Gold first sold off then rallied: spot gold has returned to 4,400. The narrative has shifted from “safe-haven” to “rate-hike pressure vs central bank gold buying.”
16. Supply disruptions in rare earths/antimony/tungsten plus Middle East oil prices. Capital preference: crude oil, copper, rare earths, and precious/rare metals > high-FDV altcoins.
17. Total crypto market cap is about $2.7–2.8 trillion. The Altcoin Season Index is 47/100—still not at a full altcoin season.
This isn’t a “bull-market pullback”—it’s a “macros tied-up period.” As long as oil prices/CPI/Fed don’t clear, BTC is hard to trade directionally.
2. ETH is hovering around 2,490; SOL is around 103. Altcoins are diverging: ZEC is strong, while WLD/MORPHO are weak.
3. Brent is edging toward $100 intraday. Attacks by Iran/Iranian-linked forces + the Houthis on Saudi facilities have heightened geopolitical risk, weighing on risk assets.
4. The probability of a Fed rate hike in September is about 60%. 10Y U.S. Treasuries are near 4.8%. A stronger dollar is bearish for crypto and gold in the short term.
5. Spot BTC ETFs saw net outflows of about $47 million yesterday. IBIT/BITB/ARKB had inflows, while GBTC is lagging.
6. ETH ETFs posted small net outflows as well. XRP ETFs bucked the trend, attracting about $2 million; capital is selecting specific targets to buy.
7. Zcash (ZEC): Grayscale’s ZCSH assets broke through $500 million. Privacy coins remain one of the strongest narratives in a weak market.
8. RWA/stablecoins continue to outperform: bank-backed euro stablecoins, an Uzbekistan pilot, and Circle’s cross-border payments expansion.
9. Block has applied to the OCC for a national trust bank charter, aiming to provide BTC + stablecoin custody—an additional step for institutional infrastructure.
10. Robinhood is betting on prediction markets, connecting with Crypto.com/OG.com. Exchanges are looking for incremental growth in “non-crypto” business.
11. The Liquid Network security incident is unfolding. BTC L2 security audits and custody trust are back in focus.
12. HYPE’s unlock selling pressure hasn’t fully cleared. Multicoin is accused of selling about 1.725M HYPE since the end of July, netting $77 million in profit.
13. Derivatives longs hold a slight edge (BTC long/short ratio about 1.11), but a break above 81,000 could trigger liquidation of nearly $860 million in short positions.
14. Copper on the LME hit a record high of $14,779 per ton intraday. AI + power grids + EVs + Chile disruptions are drawing commodities to absorb some speculative capital.
15. Gold first sold off then rallied: spot gold has returned to 4,400. The narrative has shifted from “safe-haven” to “rate-hike pressure vs central bank gold buying.”
16. Supply disruptions in rare earths/antimony/tungsten plus Middle East oil prices. Capital preference: crude oil, copper, rare earths, and precious/rare metals > high-FDV altcoins.
17. Total crypto market cap is about $2.7–2.8 trillion. The Altcoin Season Index is 47/100—still not at a full altcoin season.
This isn’t a “bull-market pullback”—it’s a “macros tied-up period.” As long as oil prices/CPI/Fed don’t clear, BTC is hard to trade directionally.

3.3k
7
189
3.3k
·
--
Fold up the anxiety and put it into yesterday's pocket.
Spread out your hopes, until they cover today's tabletop.
The rest—leave it to the wind.
Fold up the anxiety and put it into yesterday's pocket.
Spread out your hopes, until they cover today's tabletop.
The rest—leave it to the wind.
Spread out your hopes, until they cover today's tabletop.
The rest—leave it to the wind.
1.6k
16
126
1.6k
·
--
• Allow yourself to make mistakes, and refuse mental exhaustion.
• Completion is more important than perfection, and starting is more crucial than planning.
• Goal: stay calm and get off work on time.
• Status: battery full, signal full.
• Allow yourself to make mistakes, and refuse mental exhaustion.
• Completion is more important than perfection, and starting is more crucial than planning.
• Goal: stay calm and get off work on time.
• Status: battery full, signal full.
• Completion is more important than perfection, and starting is more crucial than planning.
• Goal: stay calm and get off work on time.
• Status: battery full, signal full.

1.4k
10
89
1.4k
·
--
Life is not about rushing along the road, but about feeling the road.
May you today:
When you look down, have steadfast steps,
when you look up, have a clear distant horizon.
Do not chase time, only walk beside it.
Turn your days into poetry, even if only in line breaks
Life is not about rushing along the road, but about feeling the road.
May you today:
When you look down, have steadfast steps,
when you look up, have a clear distant horizon.
Do not chase time, only walk beside it.
Turn your days into poetry, even if only in line breaks
May you today:
When you look down, have steadfast steps,
when you look up, have a clear distant horizon.
Do not chase time, only walk beside it.
Turn your days into poetry, even if only in line breaks

3.1k
15
196
3.1k
·
--
May you today:
Travel on your path, not dwelling on the past;
Be at home, not thinking of disturbances.
Let your heart hold mountains and seas—quiet, yet uncontentious.
Pause, then forget, and let it ride the wind; walk on, then look ahead, and move with ease.
May you today:
Travel on your path, not dwelling on the past;
Be at home, not thinking of disturbances.
Let your heart hold mountains and seas—quiet, yet uncontentious.
Pause, then forget, and let it ride the wind; walk on, then look ahead, and move with ease.
Travel on your path, not dwelling on the past;
Be at home, not thinking of disturbances.
Let your heart hold mountains and seas—quiet, yet uncontentious.
Pause, then forget, and let it ride the wind; walk on, then look ahead, and move with ease.
3.4k
26
209
3.4k
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number