The 30-year mortgage rate just hit 7.45% — highest since 2023 when inflation was running at 6.4%+.
That's a 150 basis point spike in just six months.
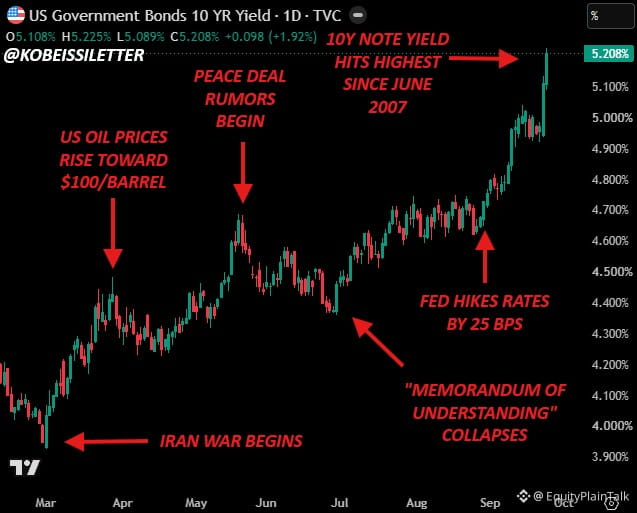
Bond market's under serious pressure. Yields climbing fast. Mortgage rates following right behind.
This isn't just noise. Housing affordability was already stretched. Now? Even tougher for buyers.
Context matters: back in 2023, inflation was the obvious culprit. Now inflation's cooled off, but rates are still climbing. Why?
Bond vigilantes are back. Deficit concerns, supply/demand imbalance in Treasuries, and sticky inflation expectations are all playing a role.
For everyday people: higher mortgage rates mean fewer home sales, slower housing turnover, and pressure on homebuilders.
For markets: this is a real constraint on economic activity. Housing is a massive part of GDP.
Watch the 10-year Treasury yield closely. It's the real driver here. If it keeps climbing, mortgage rates follow — and the housing market stays frozen.
That's a 150 basis point spike in just six months.
Bond market's under serious pressure. Yields climbing fast. Mortgage rates following right behind.
This isn't just noise. Housing affordability was already stretched. Now? Even tougher for buyers.
Context matters: back in 2023, inflation was the obvious culprit. Now inflation's cooled off, but rates are still climbing. Why?
Bond vigilantes are back. Deficit concerns, supply/demand imbalance in Treasuries, and sticky inflation expectations are all playing a role.
For everyday people: higher mortgage rates mean fewer home sales, slower housing turnover, and pressure on homebuilders.
For markets: this is a real constraint on economic activity. Housing is a massive part of GDP.
Watch the 10-year Treasury yield closely. It's the real driver here. If it keeps climbing, mortgage rates follow — and the housing market stays frozen.