Just aligned the positions with two parties: not “repeat-lesson custody/managed services” OMB, and not “tokenized venue for next quarter” — this is the proposal letter from a16z and the DeFi Education Fund to the SEC.
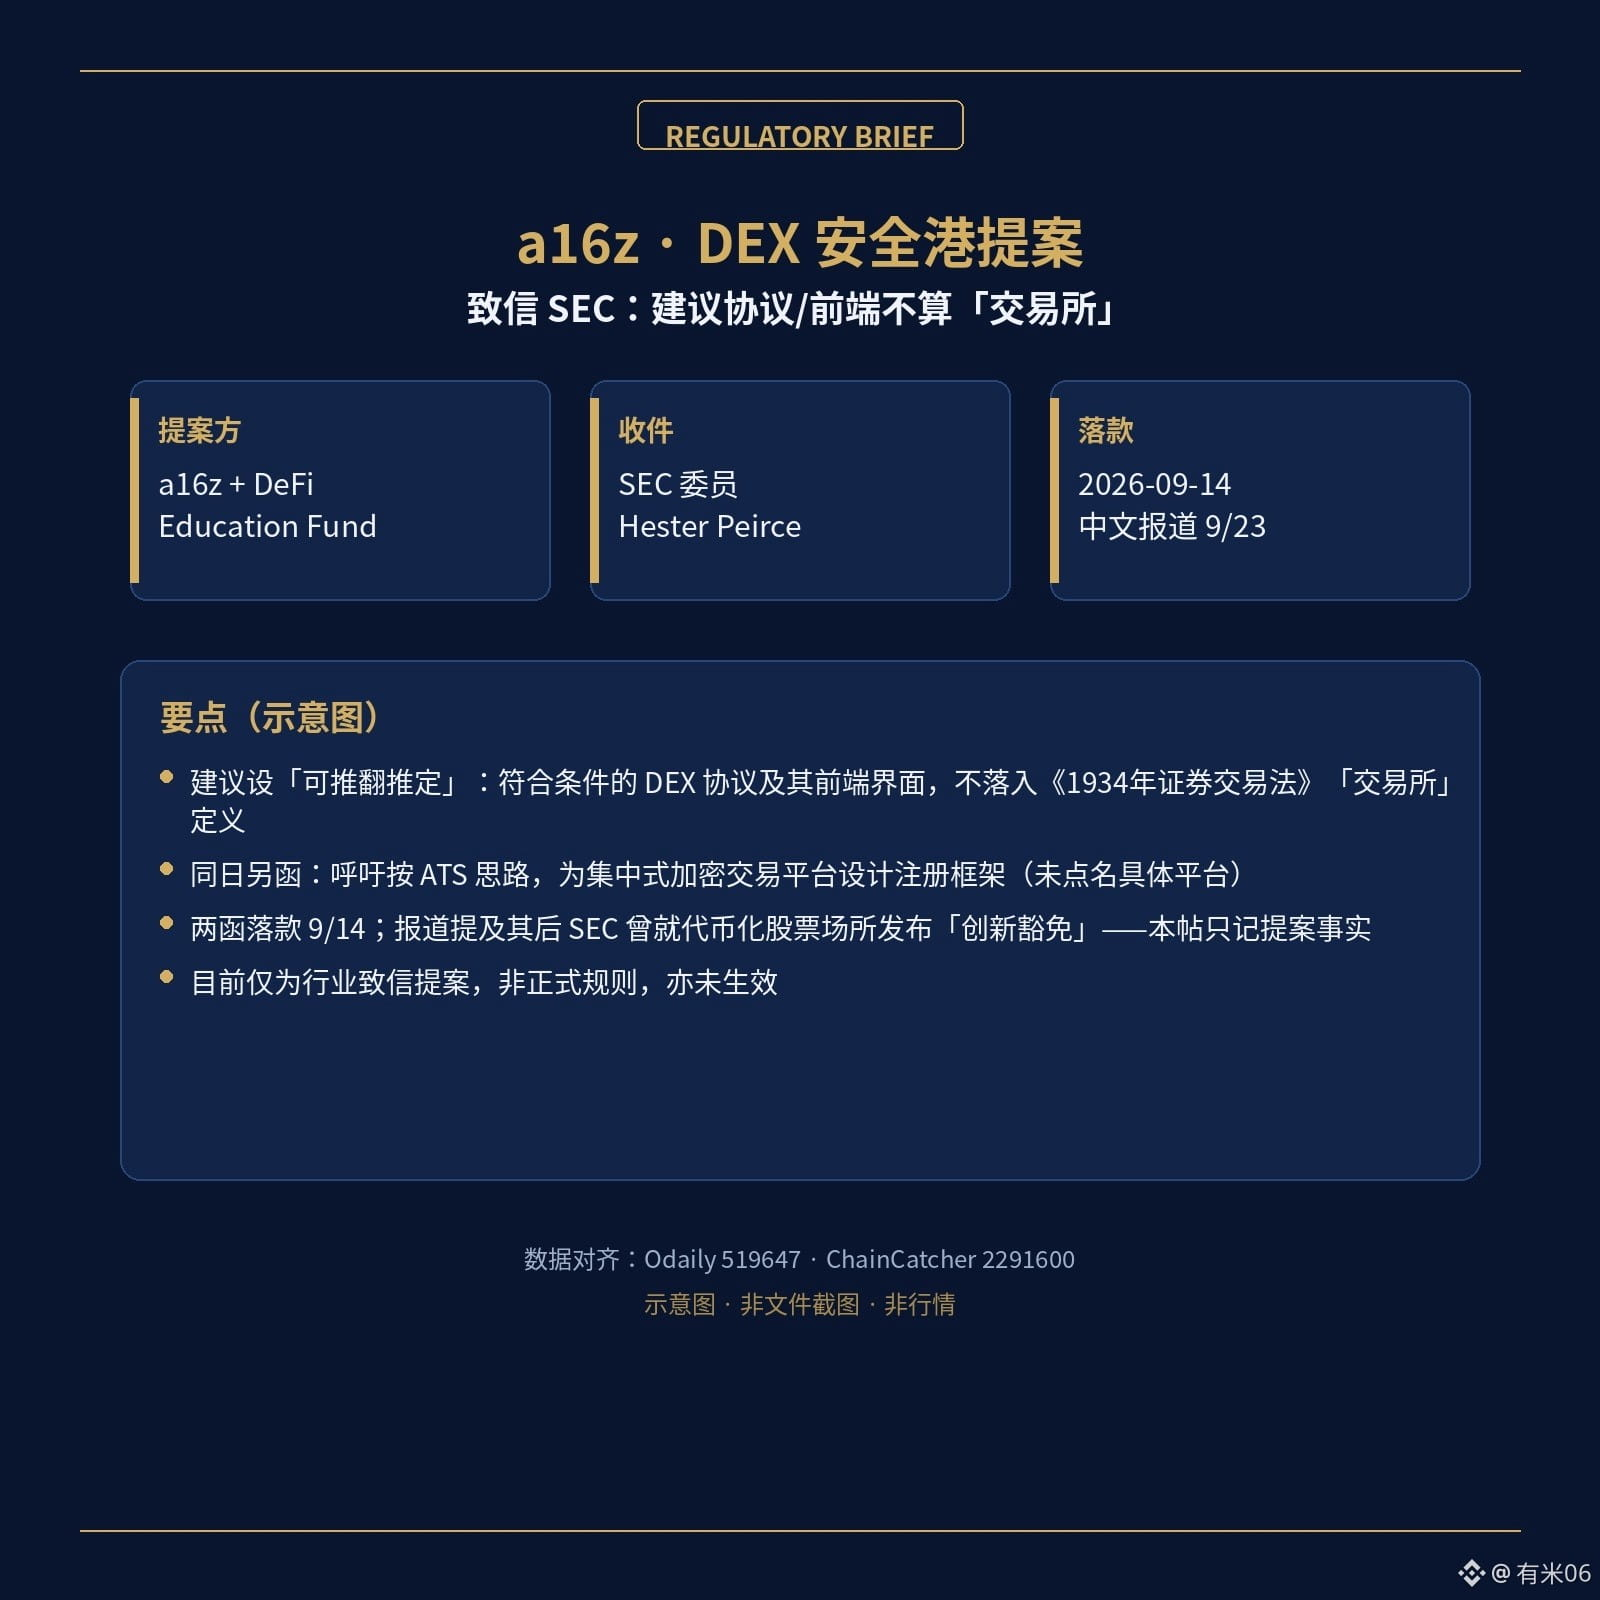
According to Odaily Flash News 519647 and ChainCatcher 2291600: a16z and the DeFi Education Fund jointly submitted a proposal to U.S. Securities and Exchange Commission (SEC) Commissioner Hester Peirce, recommending the establishment of a safe-harbor rule and the creation of a “rebuttable presumption”—that decentralized exchange (DEX) protocols meeting certain conditions, along with their front-end interfaces, would not be considered an “exchange” as defined in the Securities Exchange Act of 1934.
On the same day, a16z also submitted another letter calling on the SEC to adopt the conceptual approach of the 1998 alternative trading system (ATS) rules to design a registration regime for centralized crypto trading platforms; the signature dates of both letters are 2026-09-14. The report also mentioned that three days after the letters were signed, the SEC issued an “innovative exemption” regarding tokenized stock trading venues—here only as timeline background; the earlier post is not expanded.
Need to distinguish: this is an industry letter and rule proposal, not an official rule that has been approved by the SEC, and certainly not something taking effect immediately. The image is an illustration of regulatory key points, not a screenshot of documents, and not market data.
Data as of: 2026-09-23 (Odaily 519647 05:26 / ChainCatcher 2291600 04:22, Asia/Shanghai)
For information sharing only; does not constitute investment advice.
#SEC #Regulatory
According to Odaily Flash News 519647 and ChainCatcher 2291600: a16z and the DeFi Education Fund jointly submitted a proposal to U.S. Securities and Exchange Commission (SEC) Commissioner Hester Peirce, recommending the establishment of a safe-harbor rule and the creation of a “rebuttable presumption”—that decentralized exchange (DEX) protocols meeting certain conditions, along with their front-end interfaces, would not be considered an “exchange” as defined in the Securities Exchange Act of 1934.
On the same day, a16z also submitted another letter calling on the SEC to adopt the conceptual approach of the 1998 alternative trading system (ATS) rules to design a registration regime for centralized crypto trading platforms; the signature dates of both letters are 2026-09-14. The report also mentioned that three days after the letters were signed, the SEC issued an “innovative exemption” regarding tokenized stock trading venues—here only as timeline background; the earlier post is not expanded.
Need to distinguish: this is an industry letter and rule proposal, not an official rule that has been approved by the SEC, and certainly not something taking effect immediately. The image is an illustration of regulatory key points, not a screenshot of documents, and not market data.
Data as of: 2026-09-23 (Odaily 519647 05:26 / ChainCatcher 2291600 04:22, Asia/Shanghai)
For information sharing only; does not constitute investment advice.
#SEC #Regulatory