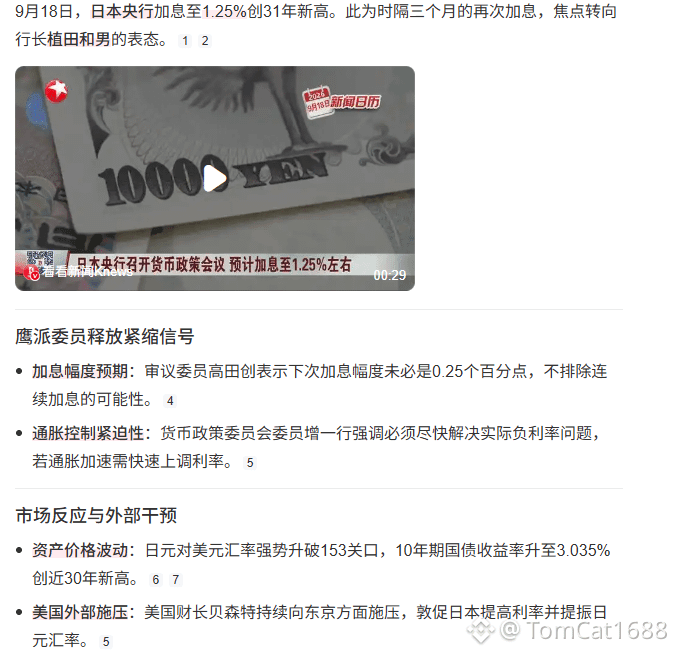
#日本央行加息至31年高位
With a 7-2 vote, the Bank of Japan raised its policy rate from 1.00% to 1.25% in a drastic move—this is the highest interest rate in exactly 31 years since 1995! The hike came just 3 months after the previous increase, setting the shortest interval between rate hikes since 1990!
But the most explosive part is this: once the rate hike was implemented, the Japanese yen actually plunged! The USD/JPY surged by more than 70 points in the short term, at one point piercing the 157 level. Why? Because two members voted against it—Ueda and Oritake were even more direct: “No plan for a pace of rate hikes, and no predetermined endpoint for interest rates.” The market instantly understood: this is nothing more than a “hawkish-sounding but dovish” rate hike!
Now look at the brutal truth of the fundamentals: Japan’s core CPI has been rising year-on-year for 60 consecutive months. In August, core CPI was 1.7%, but once energy subsidies are withdrawn, core CPI could directly break 2% in October. By March 2027, it may even reach 3%!
The fatal contradiction is this: Japan’s government debt ratio has already exceeded 230% of GDP. Meanwhile, the Kishida Cabinet is pushing a record-breaking fiscal expansion with a historic budget of 122 trillion yen, yet the central bank is forced to tighten monetary policy. Fiscal and monetary policy directions are severely torn apart!
You can’t create prosperity with rate hikes; you can’t rein in the debt with tightening. The Bank of Japan’s boldest gamble in 31 years doesn’t bet on inflation—it bets on a country being consumed by structural problems. How long can it hold out?
With a 7-2 vote, the Bank of Japan raised its policy rate from 1.00% to 1.25% in a drastic move—this is the highest interest rate in exactly 31 years since 1995! The hike came just 3 months after the previous increase, setting the shortest interval between rate hikes since 1990!
But the most explosive part is this: once the rate hike was implemented, the Japanese yen actually plunged! The USD/JPY surged by more than 70 points in the short term, at one point piercing the 157 level. Why? Because two members voted against it—Ueda and Oritake were even more direct: “No plan for a pace of rate hikes, and no predetermined endpoint for interest rates.” The market instantly understood: this is nothing more than a “hawkish-sounding but dovish” rate hike!
Now look at the brutal truth of the fundamentals: Japan’s core CPI has been rising year-on-year for 60 consecutive months. In August, core CPI was 1.7%, but once energy subsidies are withdrawn, core CPI could directly break 2% in October. By March 2027, it may even reach 3%!
The fatal contradiction is this: Japan’s government debt ratio has already exceeded 230% of GDP. Meanwhile, the Kishida Cabinet is pushing a record-breaking fiscal expansion with a historic budget of 122 trillion yen, yet the central bank is forced to tighten monetary policy. Fiscal and monetary policy directions are severely torn apart!
You can’t create prosperity with rate hikes; you can’t rein in the debt with tightening. The Bank of Japan’s boldest gamble in 31 years doesn’t bet on inflation—it bets on a country being consumed by structural problems. How long can it hold out?