Ciena’s rebound is interesting. But I don’t think the 4% move proves much yet.
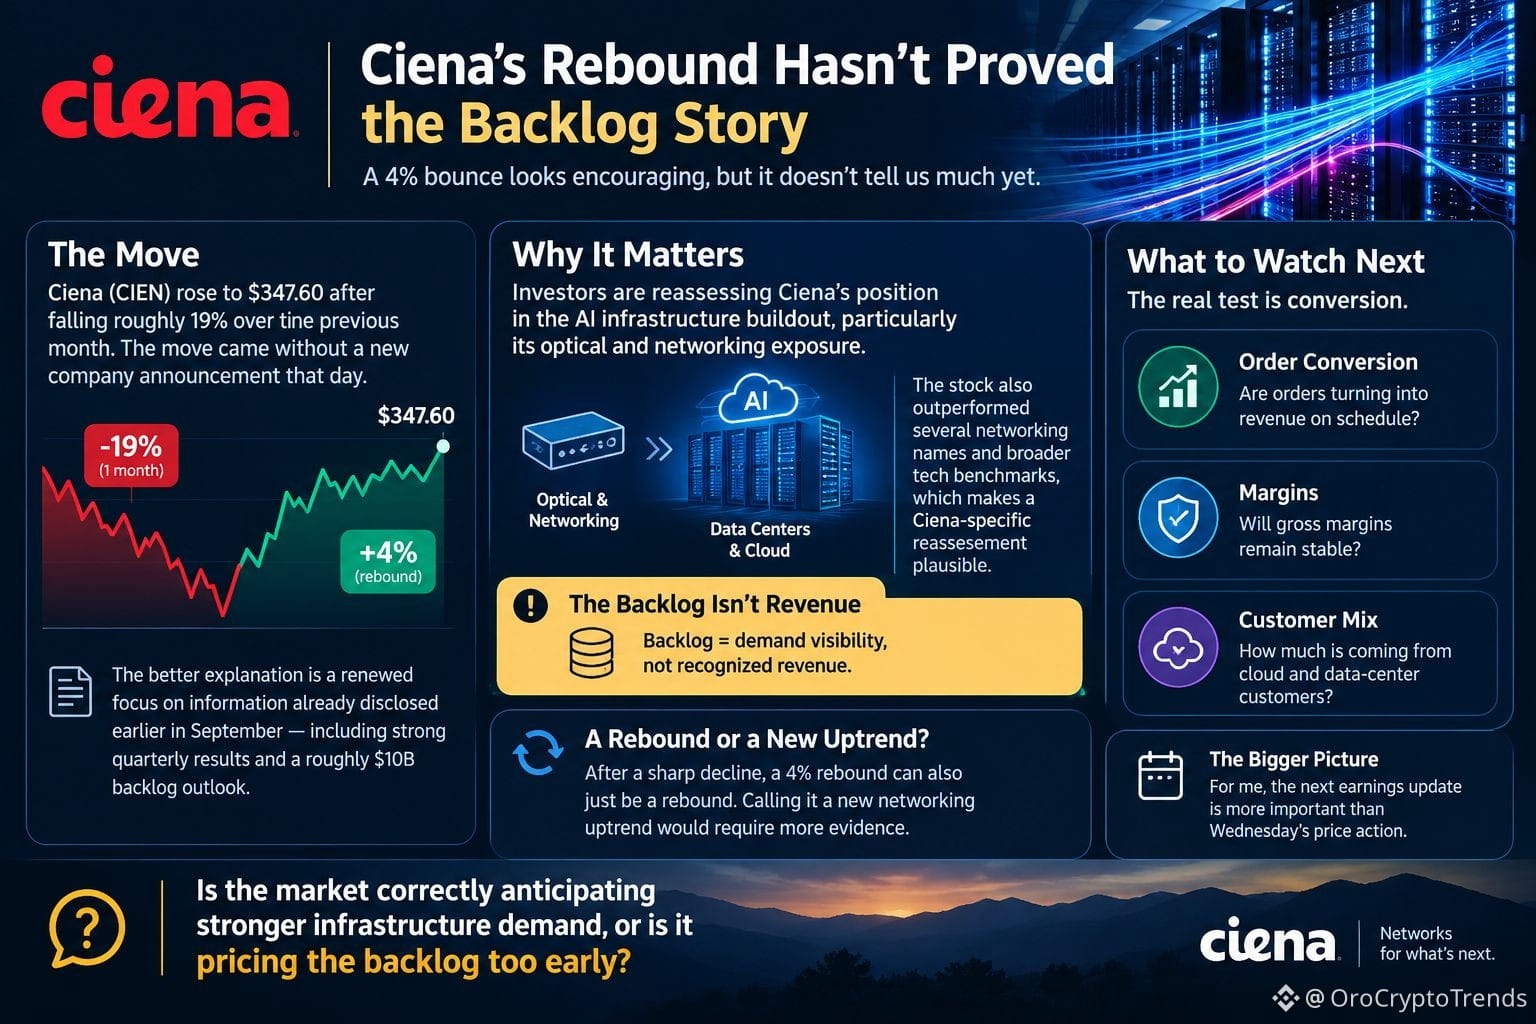
Ciena (CIEN) rose to $347.60 after falling roughly 19% over the previous month. The move came without a new company announcement that day, so the better explanation is a renewed focus on information management had already disclosed earlier in September, including strong quarterly results and its roughly $10B backlog outlook.
That distinction matters.
My read is that investors are reassessing Ciena’s position in the AI infrastructure buildout, particularly its optical and networking exposure. The stock also moved more strongly than several nearby networking names and broader technology benchmarks, which makes a Ciena-specific reassessment plausible.
But there’s a problem with treating the backlog as an immediate growth signal.
Backlog is demand visibility, not recognized revenue.
The real test is conversion. Future results should tell us whether orders are turning into revenue on schedule, whether gross margins remain stable, and how strongly cloud and data-center customers are contributing.
After a sharp decline, a 4% rebound can also be just that — a rebound. Calling it a new networking uptrend would require more evidence.
For me, the next earnings update is more important than Wednesday’s price action.
Is the market correctly anticipating stronger infrastructure demand, or is it pricing the backlog too early?
#Ciena
Ciena (CIEN) rose to $347.60 after falling roughly 19% over the previous month. The move came without a new company announcement that day, so the better explanation is a renewed focus on information management had already disclosed earlier in September, including strong quarterly results and its roughly $10B backlog outlook.
That distinction matters.
My read is that investors are reassessing Ciena’s position in the AI infrastructure buildout, particularly its optical and networking exposure. The stock also moved more strongly than several nearby networking names and broader technology benchmarks, which makes a Ciena-specific reassessment plausible.
But there’s a problem with treating the backlog as an immediate growth signal.
Backlog is demand visibility, not recognized revenue.
The real test is conversion. Future results should tell us whether orders are turning into revenue on schedule, whether gross margins remain stable, and how strongly cloud and data-center customers are contributing.
After a sharp decline, a 4% rebound can also be just that — a rebound. Calling it a new networking uptrend would require more evidence.
For me, the next earnings update is more important than Wednesday’s price action.
Is the market correctly anticipating stronger infrastructure demand, or is it pricing the backlog too early?
#Ciena