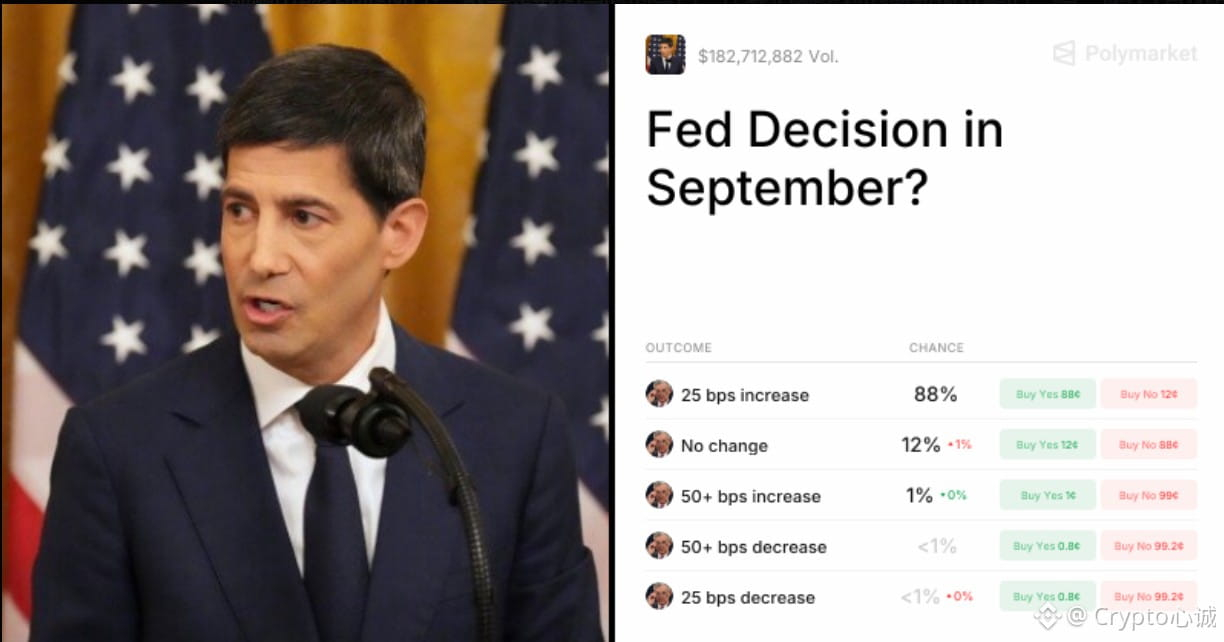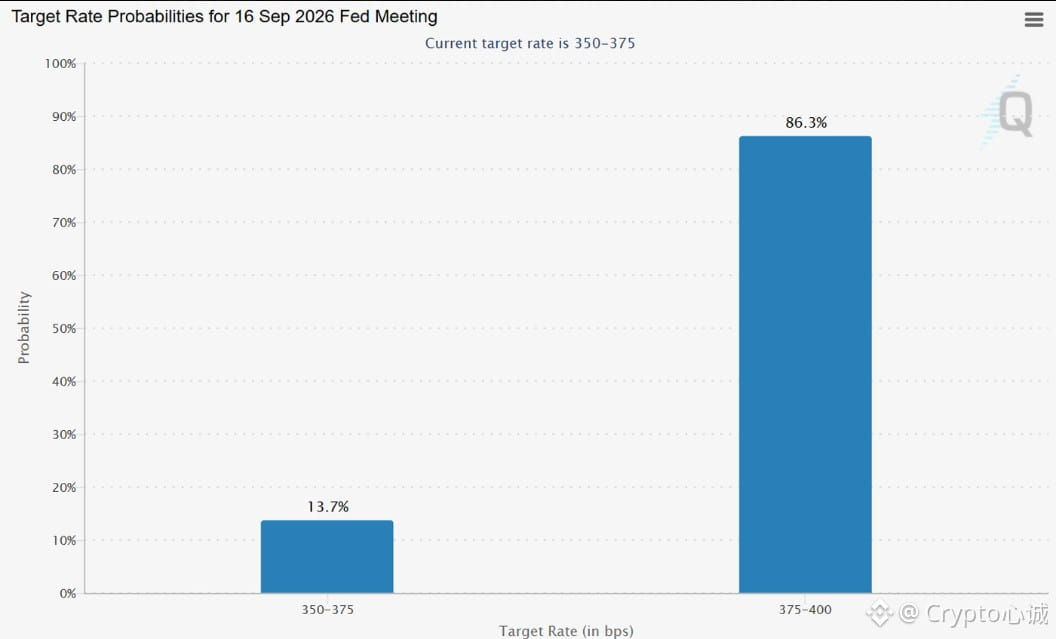
At 2:00 AM Beijing time on September 17, the interest rate decision will be released. The market has priced a September rate hike at 90%, but I still don’t think there will be a hike.
This isn’t denying the CPI is on the hot side: headline is 0.4% and core is 0.3% month-on-month, with both gasoline and housing at the highs. The issue is that it’s energy that’s heating up. Core year-over-year has already returned to 2.4%, the post-pandemic low. Hitting the oil price with a 25 bp move treats the symptom, not the cause, and it would also fold the next round of tightening into the dot-plot meeting.
In July, the September (9-3) meeting held steady with no change. Just adding one more index reading that meets expectations would mean turning around at the SEP meeting—like getting cornered by futures. The dot plot and the statement can become hawkish enough to replace an immediate rate hike. The October and December options are still there.
After a rate hike gets fully bought up, the real shock would be if there is no hike. My baseline is to keep rates at 3.50%–3.75%. Refuting this is simple—have the statement add 25 bp, or show in the dot plot that there are still two more hikes to come this year. Otherwise, don’t chase hawkishness further when it’s already priced at 90%.
$BTC
#美联储加息是否已成定局
This isn’t denying the CPI is on the hot side: headline is 0.4% and core is 0.3% month-on-month, with both gasoline and housing at the highs. The issue is that it’s energy that’s heating up. Core year-over-year has already returned to 2.4%, the post-pandemic low. Hitting the oil price with a 25 bp move treats the symptom, not the cause, and it would also fold the next round of tightening into the dot-plot meeting.
In July, the September (9-3) meeting held steady with no change. Just adding one more index reading that meets expectations would mean turning around at the SEP meeting—like getting cornered by futures. The dot plot and the statement can become hawkish enough to replace an immediate rate hike. The October and December options are still there.
After a rate hike gets fully bought up, the real shock would be if there is no hike. My baseline is to keep rates at 3.50%–3.75%. Refuting this is simple—have the statement add 25 bp, or show in the dot plot that there are still two more hikes to come this year. Otherwise, don’t chase hawkishness further when it’s already priced at 90%.
$BTC
#美联储加息是否已成定局