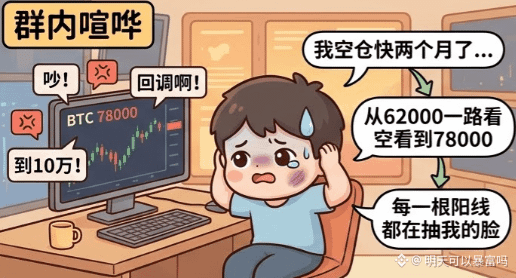
Today BTC wobbled around 78,000 all day, and people in my group are arguing again. Those with no position shout “wait for a pullback.” Those fully in shout “I’m seeing 100,000.” I said nothing in between. Because I’ve been out of the market for almost two months—starting from 62,000 all the way down/up to 78,000 as I’ve been bearish. Every bullish candle has been slapping my face.
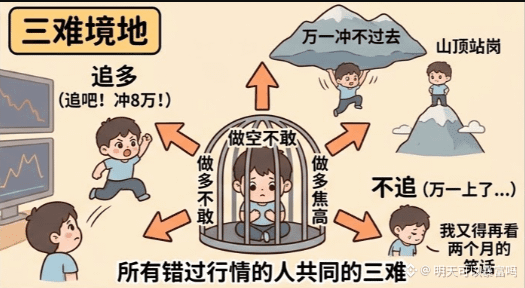
This feeling is way too familiar. If I chase it and it breaks 79,000, above that is the 80,000 level. What if it can’t push through and gets hammered back? Then I’ll be the one guarding the top of the mountain. If I don’t chase it and this wave really runs up to 80,000, then I’ll have to watch another two months of jokes. Shorting gives me no nerve; going long makes me fear heights. That anxiety of being in cash—that’s probably the “three difficulties” shared by everyone who’s missed the move.
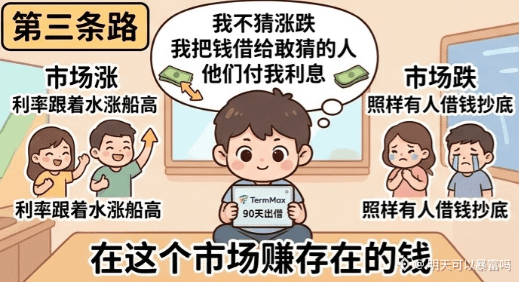
Recently, I couldn’t take this anymore, so I changed my thinking. If I’m afraid to bet on direction, can I still participate in the market without betting on direction? Later, I put part of my U into TermMax to lend it out for 90 days. The logic is simple: I don’t guess whether prices will rise or fall. I lend money to the people who do, and they pay me interest. When the market rises, more borrowers come in, and my rate goes up with the tide. When the market falls, people still borrow to buy the dip, and I still collect my interest. Direction is their business—I earn money from the market’s existence itself.
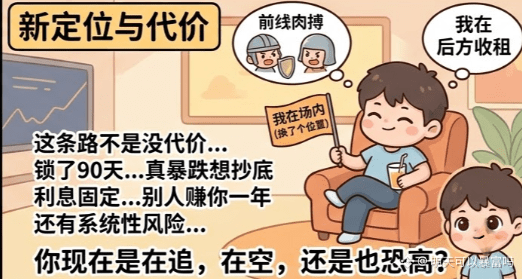
Once I got this positioning clear in my head, the stone in my heart finally dropped. I no longer obsess every day about whether to chase, because I’m already in the market—just in a different position. While others are in the frontline fighting hand-to-hand, I’m in the back collecting rent. Of course the returns can’t compare to those who correctly call it, but it’s still better than sitting in cash and staring blankly. More importantly, I’m back in the game: my mindset shifted from spectator to player.
But let’s be clear: there’s a cost to this path. When you lend your money out, you lock it for 90 days. If you truly encounter a brutal drop mid-way and want to buy the dip, the money isn’t in your hands—you’re just anxious. The interest rate is fixed. When the market goes wild, watching others make in a day what you’d earn in a year is impossible to feel nothing. And also, if the borrowers truly run into systemic risk, both interest and principal can hang in the balance—no matter how many safeguards the mechanism has, it’s not absolutely risk-free.
So this isn’t a perfect solution—it’s a compromise that lets people with fear of heights sleep at night. You don’t necessarily have to choose between chasing and going short. There’s a third way: become a creditor of the market.
Are you currently chasing, or going short—or are you also fear-height like me?
#termmax @TermMax
This feeling is way too familiar. If I chase it and it breaks 79,000, above that is the 80,000 level. What if it can’t push through and gets hammered back? Then I’ll be the one guarding the top of the mountain. If I don’t chase it and this wave really runs up to 80,000, then I’ll have to watch another two months of jokes. Shorting gives me no nerve; going long makes me fear heights. That anxiety of being in cash—that’s probably the “three difficulties” shared by everyone who’s missed the move.
Recently, I couldn’t take this anymore, so I changed my thinking. If I’m afraid to bet on direction, can I still participate in the market without betting on direction? Later, I put part of my U into TermMax to lend it out for 90 days. The logic is simple: I don’t guess whether prices will rise or fall. I lend money to the people who do, and they pay me interest. When the market rises, more borrowers come in, and my rate goes up with the tide. When the market falls, people still borrow to buy the dip, and I still collect my interest. Direction is their business—I earn money from the market’s existence itself.
Once I got this positioning clear in my head, the stone in my heart finally dropped. I no longer obsess every day about whether to chase, because I’m already in the market—just in a different position. While others are in the frontline fighting hand-to-hand, I’m in the back collecting rent. Of course the returns can’t compare to those who correctly call it, but it’s still better than sitting in cash and staring blankly. More importantly, I’m back in the game: my mindset shifted from spectator to player.
But let’s be clear: there’s a cost to this path. When you lend your money out, you lock it for 90 days. If you truly encounter a brutal drop mid-way and want to buy the dip, the money isn’t in your hands—you’re just anxious. The interest rate is fixed. When the market goes wild, watching others make in a day what you’d earn in a year is impossible to feel nothing. And also, if the borrowers truly run into systemic risk, both interest and principal can hang in the balance—no matter how many safeguards the mechanism has, it’s not absolutely risk-free.
So this isn’t a perfect solution—it’s a compromise that lets people with fear of heights sleep at night. You don’t necessarily have to choose between chasing and going short. There’s a third way: become a creditor of the market.
Are you currently chasing, or going short—or are you also fear-height like me?
#termmax @TermMax