#termmax @TermMax
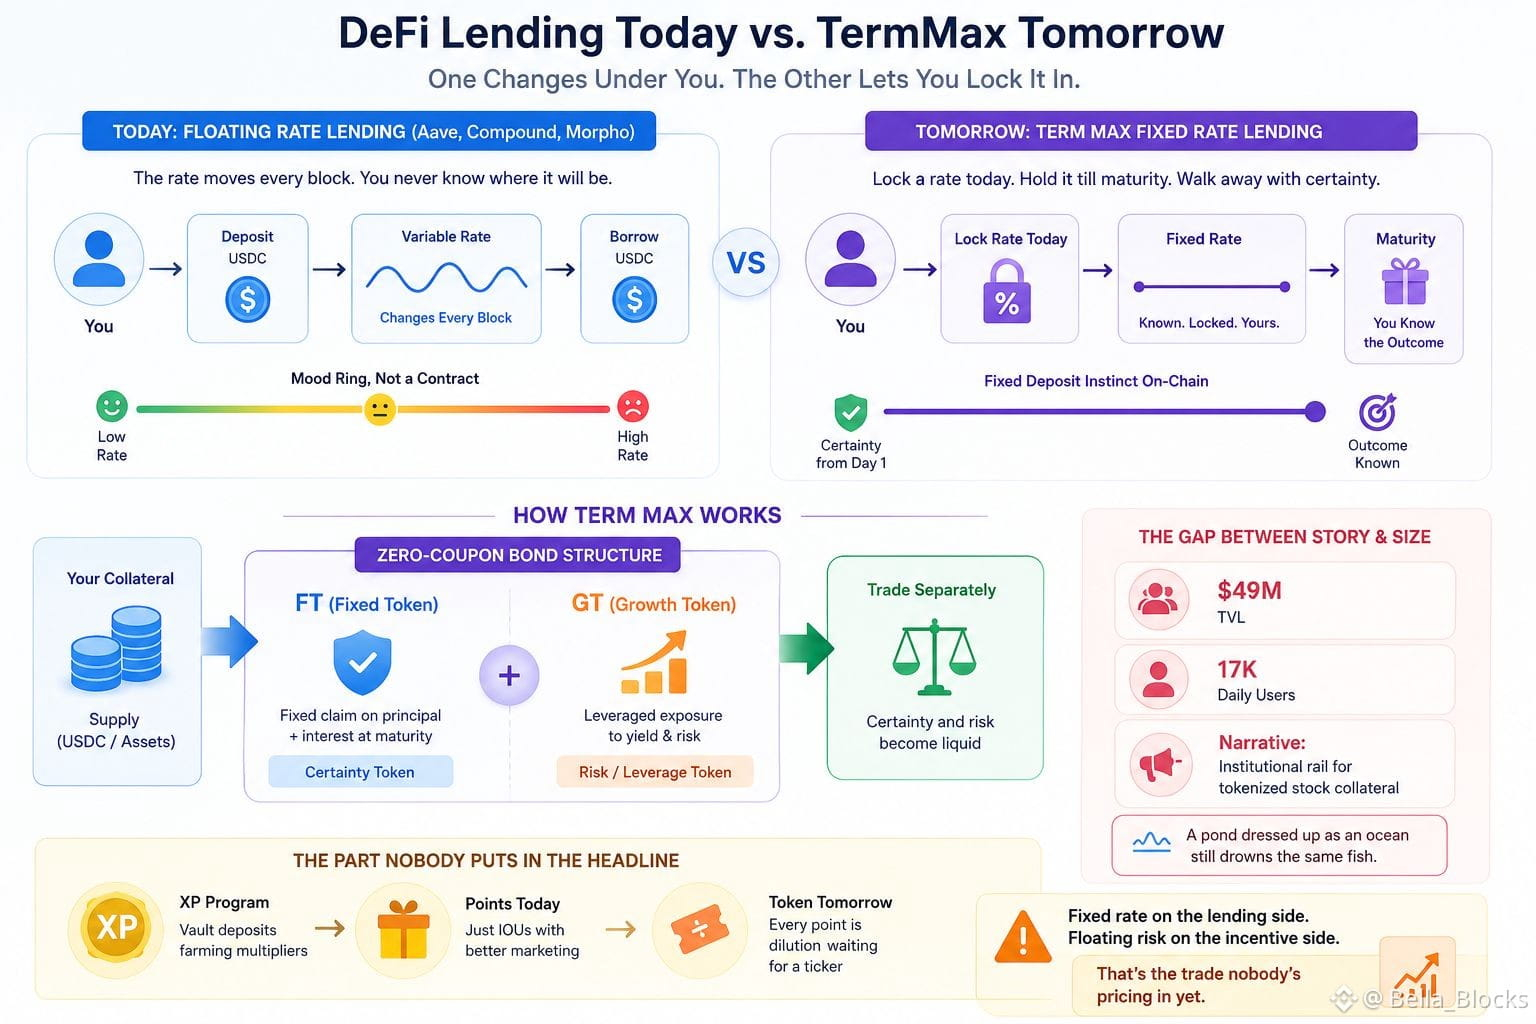
I keep coming back to how every DeFi lending rate acts like a mood ring, not a contract. Aave, Compound, Morpho Blue — you deposit, you borrow, and the rate moves under your feet every single block. It's a fixed deposit that changes its own interest rate while you're still holding the receipt. Nobody signs up for a savings account like that in real life, but somehow we all normalized it on-chain.
TermMax is selling the opposite pitch. Lock a rate today, hold it till maturity, walk away with a number you already knew going in. That's the bank FD instinct wrapped in a zero-coupon bond structure — you're not chasing yield, you're pricing time. Split principal and interest into two tokens, an FT for the fixed claim and a GT for the leveraged, collateral-heavy side, and suddenly you can trade the certainty separately from the risk. Clean mechanism on paper.
But I keep staring at the size of this thing next to the size of the story. Forty-nine million in TVL, seventeen thousand daily users, and a press release talking like it's already the institutional rail for tokenized stock collateral. That gap between the narrative and the balance sheet is the tell. A pond dressed up as an ocean still drowns the same fish if the tide goes wrong.
And the part nobody puts in the headline — there's an XP program running right now, vault deposits farming multipliers ahead of a token that doesn't exist yet. Points programs are just IOUs with better marketing. Every point earned today is dilution waiting for a ticker. Fixed rate on the lending side, floating risk on the incentive side — that's the trade nobody's pricing in yet.
$HEMI
$TREE
$RE
I keep coming back to how every DeFi lending rate acts like a mood ring, not a contract. Aave, Compound, Morpho Blue — you deposit, you borrow, and the rate moves under your feet every single block. It's a fixed deposit that changes its own interest rate while you're still holding the receipt. Nobody signs up for a savings account like that in real life, but somehow we all normalized it on-chain.
TermMax is selling the opposite pitch. Lock a rate today, hold it till maturity, walk away with a number you already knew going in. That's the bank FD instinct wrapped in a zero-coupon bond structure — you're not chasing yield, you're pricing time. Split principal and interest into two tokens, an FT for the fixed claim and a GT for the leveraged, collateral-heavy side, and suddenly you can trade the certainty separately from the risk. Clean mechanism on paper.
But I keep staring at the size of this thing next to the size of the story. Forty-nine million in TVL, seventeen thousand daily users, and a press release talking like it's already the institutional rail for tokenized stock collateral. That gap between the narrative and the balance sheet is the tell. A pond dressed up as an ocean still drowns the same fish if the tide goes wrong.
And the part nobody puts in the headline — there's an XP program running right now, vault deposits farming multipliers ahead of a token that doesn't exist yet. Points programs are just IOUs with better marketing. Every point earned today is dilution waiting for a ticker. Fixed rate on the lending side, floating risk on the incentive side — that's the trade nobody's pricing in yet.
$HEMI
$TREE
$RE