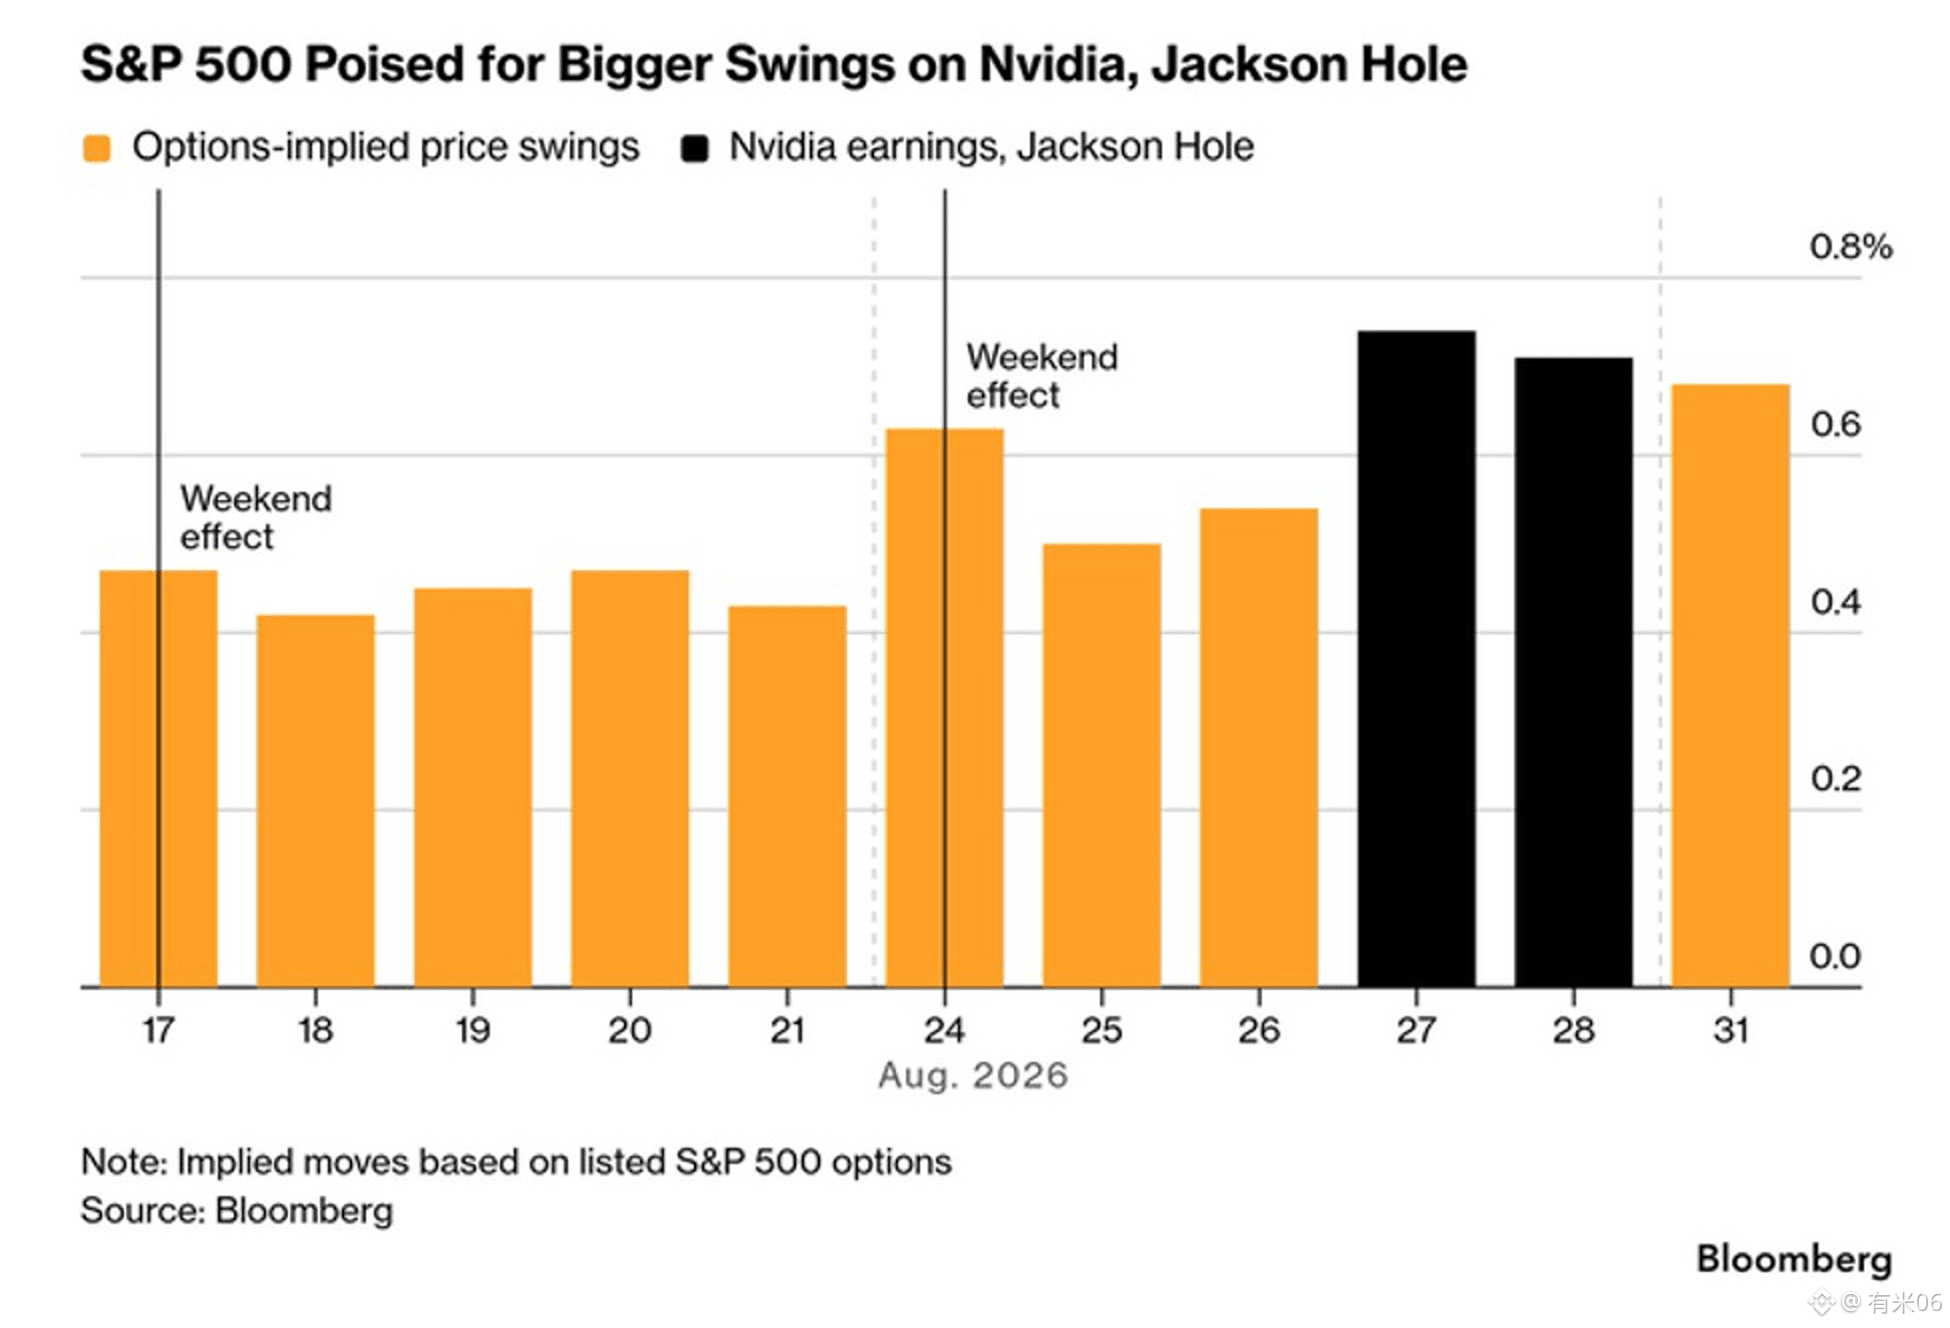
Saw the Kobeissi chart of S&P 500 options—August 27 and August 28 were separately labeled as NVIDIA earnings and the Jackson Hole (event) for those two days. This is the implied volatility used by exchange-traded options to price the index each day; it’s not the intraday rise/fall that already happened, and it’s not the VIX points.
In another post on Twitter, he wrote that on the 27th it was about 0.75% and on the 28th about 0.70%; those numbers were not printed on the chart. NVIDIA earnings were after the market close on August 26; the official Jackson Hole schedule is August 27 to 29—so it’s not the same statement as what he wrote on Twitter, calling the 28th the opening day.
In another post on Twitter, he wrote that on the 27th it was about 0.75% and on the 28th about 0.70%; those numbers were not printed on the chart. NVIDIA earnings were after the market close on August 26; the official Jackson Hole schedule is August 27 to 29—so it’s not the same statement as what he wrote on Twitter, calling the 28th the opening day.