


Original title: Robinhood Chain: Can It Move Robinhood's Bottom Line?
Original author: ACJ, Blockworks
Original compilation: Azuma, Odaily Planet Daily
Key Takeaways
· Even though Robinhood’s overall business hit a historic high, its crypto business is in decline. In Q2 2026, Robinhood’s crypto revenue fell 38% year over year to $100 million, accounting for only 8% of the company’s total revenue. Retail crypto trading volume was down 36% year over year, and the share of crypto assets in customers’ total assets under custody (AUC) also dropped to a record low of just 7%.
· Robinhood Chain is one of the strongest Layer 2 (L2) network launch cases in recent performance. In July, the chain generated $3.6 million in Real Economic Value (REV), accounting for 38% of all L2 network revenues tracked by growthepie—surpassing even established networks including Polygon and Base.
· The driver of early activity on Robinhood Chain was not real-world assets (RWA), but Meme coins. In July, Meme coins accounted for 51% of Robinhood Chain spot trading volume, while RWA accounted for only 5%. In addition, 48% of RWA trading volume came from liquidity pools pairing RWA with Meme coins.
· Robinhood’s clearest monetization opportunity is not at the infrastructure layer, but at the application layer. At present, USDG stablecoins can generate about $10.5 million in annualized interest revenue; the Morpho example also proves the value of Robinhood’s main-app distribution capability. By contrast, Lighter’s trading volume via Robinhood Wallet integration accounts for only 0.2% of its total perpetual contract volume.
· At present, Robinhood Chain cannot meaningfully impact Robinhood’s profits. The combined annualized scale of known Robinhood Chain revenue sources is only about $54.8 million, equivalent to 14% of Robinhood’s annualized crypto business revenue. If Robinhood Chain wants to become a significant business line, the company needs to scale up USDG, commercialize the main-app traffic, or use the chain as an entry point into higher-value products.
Introduction: Robinhood’s crypto business is at a crossroads
Perhaps no company better represents the rise of retail investors than Robinhood—it has become synonymous with retail investing, and its underlying business has therefore grown quickly.
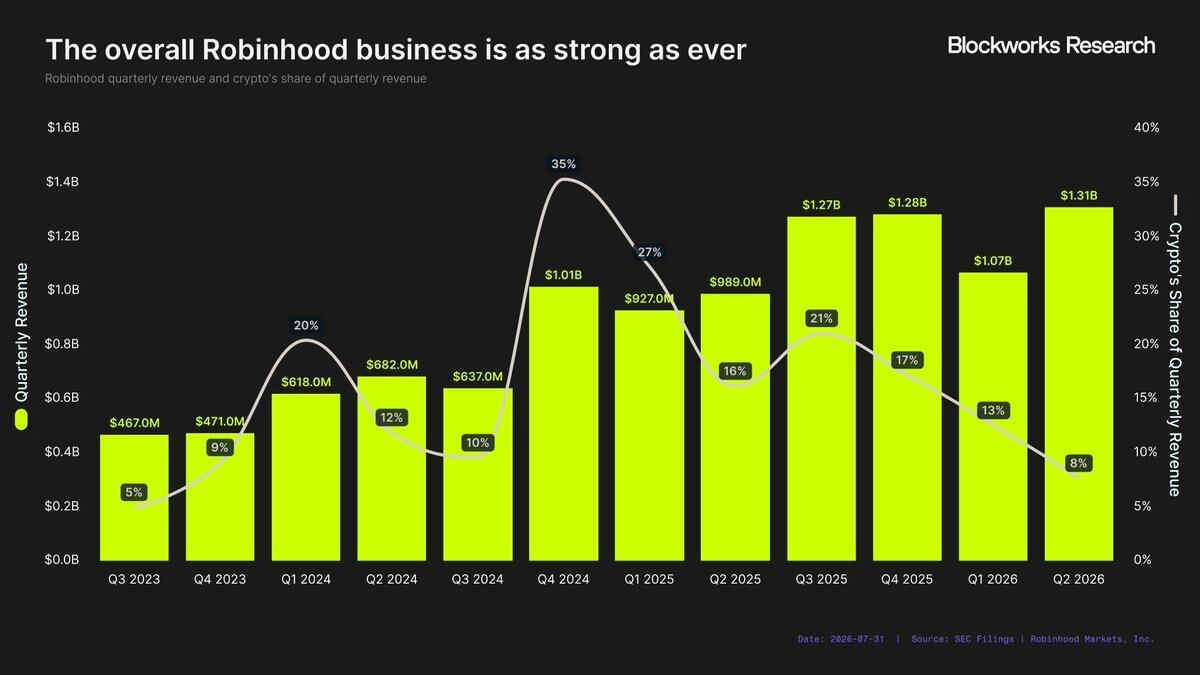
In Q2 2026, Robinhood’s quarterly revenue reached $1.31 billion, a record high, up 32% year over year and up 92% compared with Q2 2024. This growth comes not only from its core stock and options trading business, but also from its continuously expanding product ecosystem. Today, Robinhood has 13 business lines with more than $100 million in annualized revenue. In fact, in Q2 2026, all of Robinhood’s transaction-based revenue business lines achieved double-digit year-over-year growth…
Except for one—crypto.
The crypto business, which once contributed more than one-third of Robinhood’s revenue, has now shrunk to a nearly negligible part. In Q2 2026, only 8% of Robinhood’s total revenue came from crypto, the lowest level since Q3 2023.
The importance of crypto in Robinhood’s revenue structure has declined dramatically—even event contracts (prediction markets), which were only introduced last year, generated more revenue in the second quarter than the crypto business:
· Event contract revenue: $156 million;
· Crypto business revenue: $100 million;
This weakness shows up not only in the falling share of revenue, but also in the fact that Robinhood’s core users are losing interest in crypto assets. While this trend is not unique to Robinhood, the magnitude of the decline is still striking.
The clearest sign comes from trading activity. In Q2 2026, retail cryptocurrency trading volume on the Robinhood App was only $18.2 billion, down 36% year over year—the lowest quarterly level since Q3 2024.
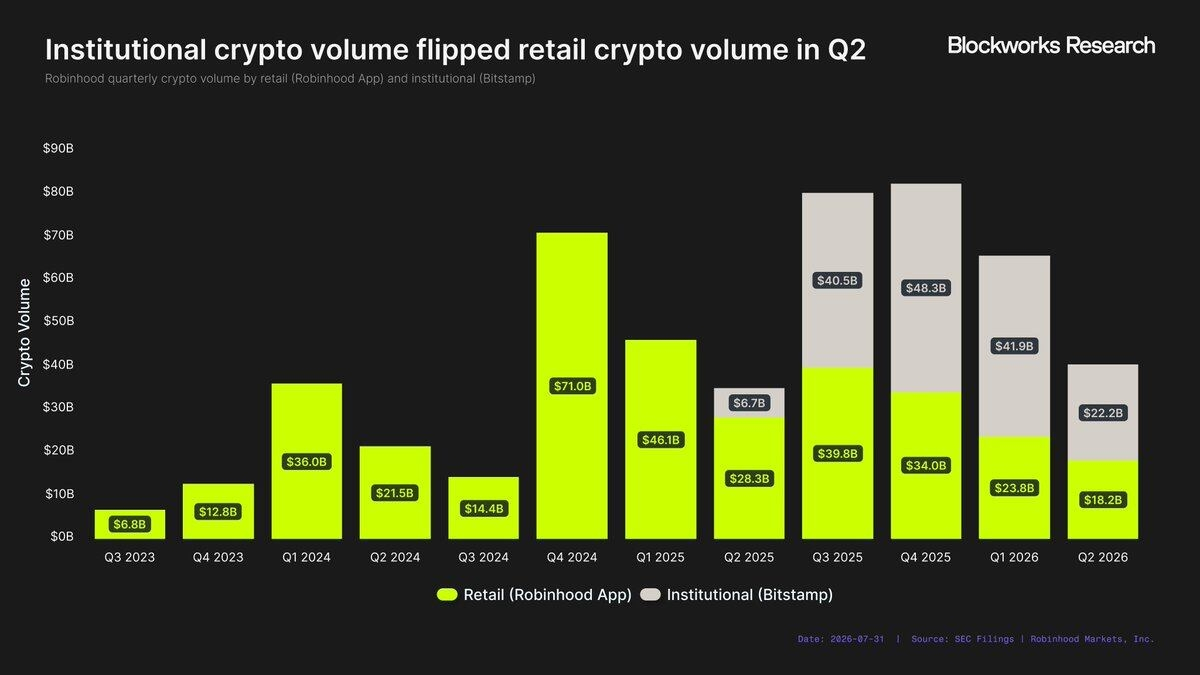
The decline is so large that institutional trading volume on Bitstamp first exceeded retail trading volume on Robinhood during this period. Moreover, the institutional activity trading volume itself was not particularly strong—Bitstamp’s Q2 trading volume was $22.2 billion, its second-lowest quarterly performance in history.
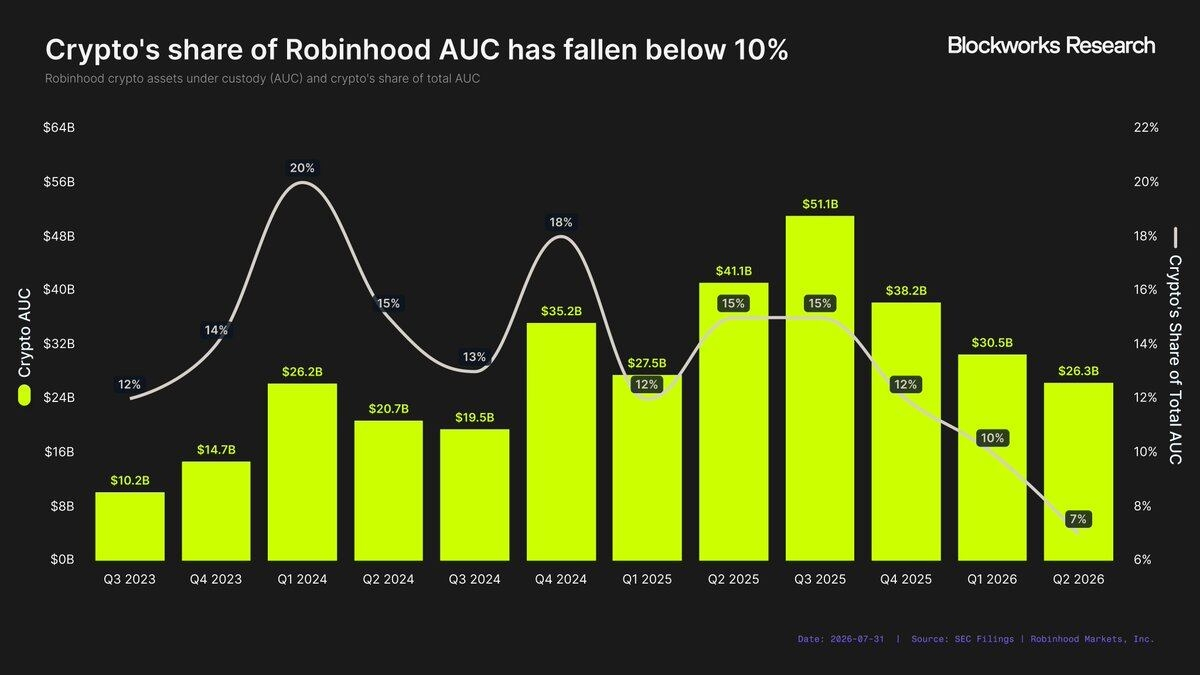
Trading volume is not the only metric that can demonstrate a contraction in crypto-related business. In the first quarter of 2024, crypto custody assets (AUC) were $26.2 billion, accounting for 20% of Robinhood’s total AUC. More than two years later, crypto AUC is roughly flat at $26.3 billion, but its share of total AUC has fallen to just 7%, the lowest quarterly percentage on record.
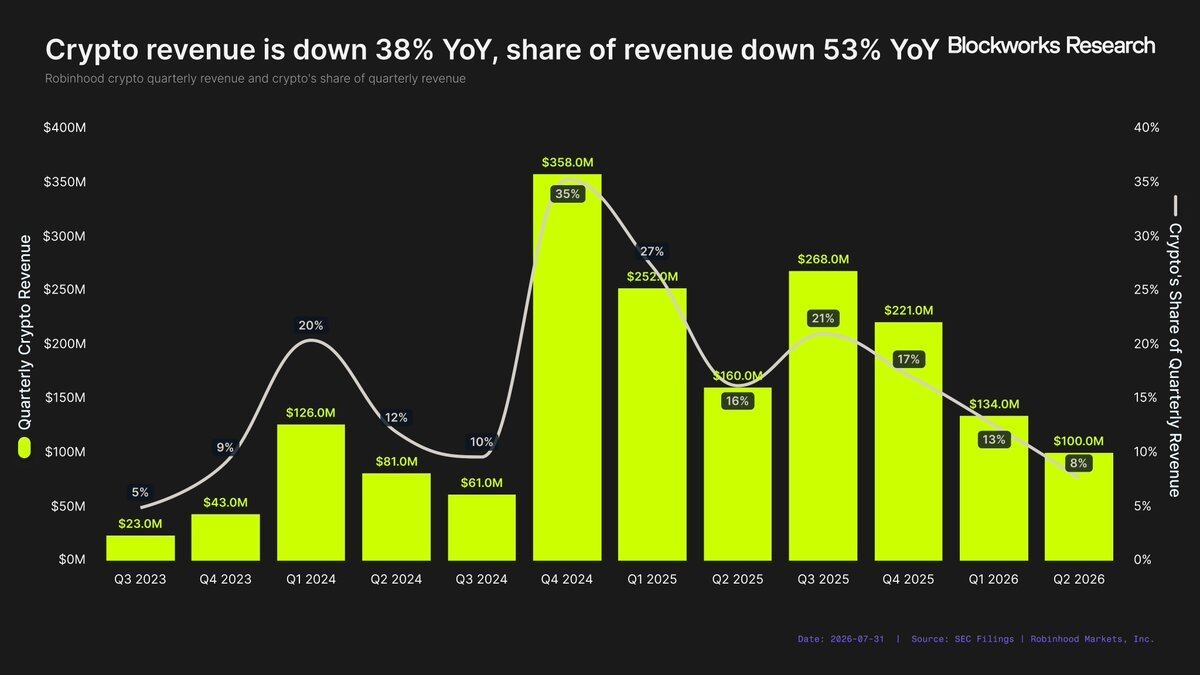
Against this backdrop, Robinhood’s crypto revenue has taken a major hit. In Q2, crypto revenue fell 38% year over year, and its share of total revenue dropped by 53%. In short, the overall company is growing, but the crypto business is not.
However, Robinhood has not backed out of crypto. Instead, it launched Robinhood Chain—its biggest crypto bet to date. Robinhood is no longer trying to rely almost entirely on trading revenue; it is attempting to build a broader, more durable crypto business. The key question is whether Robinhood Chain can make crypto a meaningful driver of Robinhood’s growth again.
How much monetization potential does Robinhood Chain have?
On July 1, 2026, Robinhood officially announced the mainnet launch of Robinhood Chain at The World Is Flat event. This is a Layer-2 (L2) blockchain developed by Robinhood itself, designed to power the company’s continuously growing on-chain ecosystem. Since its launch, Robinhood Chain has become one of the fastest-starting blockchains in the recent period.
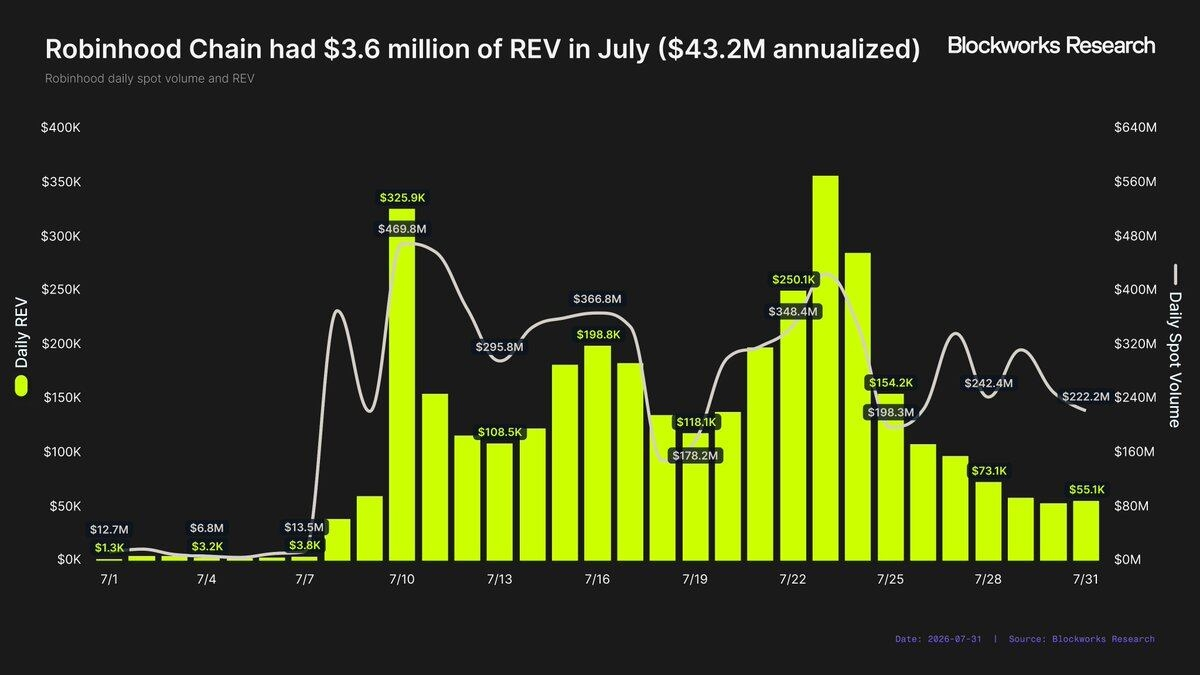
In its first month after launch, Robinhood Chain generated $3.6 million in Real Economic Value (REV). It’s still too early to judge whether this level of activity is sustainable, but if we simply annualize based on the first-month data, Robinhood Chain’s annualized REV is approximately $43.2 million.
That’s a good starting point, but at only this scale it is still far from enough to reverse the trend of falling crypto revenue at Robinhood.
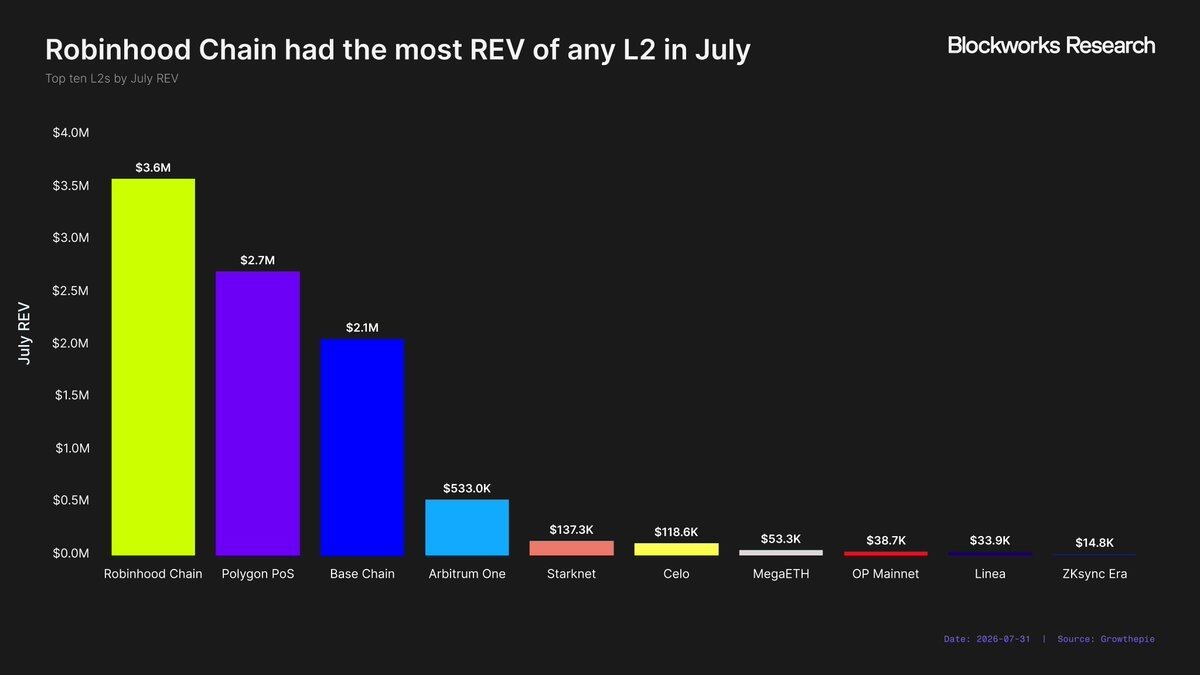
Even so, Robinhood Chain’s launch performance remains impressive. In July, Robinhood Chain ranked first in revenue across all L2 networks, surpassing many more established networks that have been live for years, such as Polygon ($2.7 million) and Base ($2.1 million).
According to data tracked by growthepie, Robinhood Chain currently accounts for 38% of chain revenue across all L2 networks. In other words, Robinhood Chain is already the largest L2 by chain revenue, but 62% of market share still belongs to other networks. Even if total L2 chain revenue stagnates, Robinhood Chain can still achieve significant growth by capturing a larger share of the market.
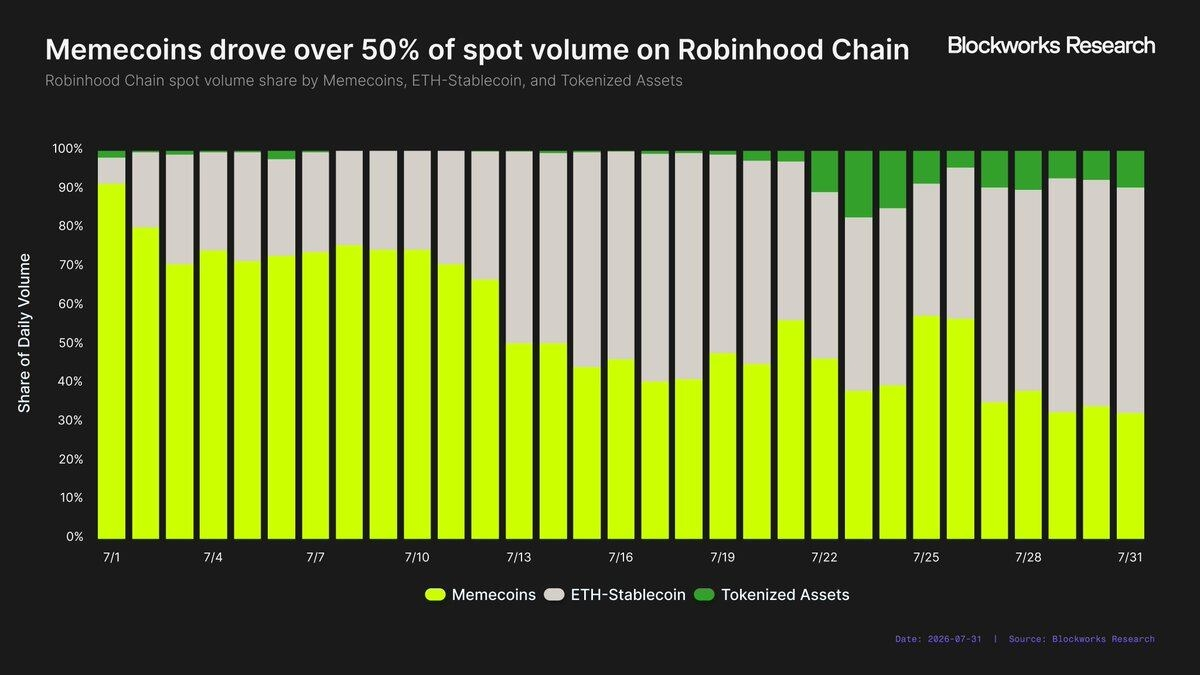
However, there was an important prerequisite for Robinhood Chain’s early success: most of the activity is currently attributed to Meme coins, and Meme coins have historically been one of the biggest drivers of blockchain REV. Robinhood appears to accept this quietly; founder Vlad Tenev has repeatedly expressed support for Meme coins.
Even so, the extent to which Meme coins are driving activity on Robinhood Chain is still quite striking. In July, the chain facilitated $6.93 billion in spot trading volume, with $3.55 billion (51%) coming from Meme coins. By comparison, RWA—what Robinhood claims as the core use case—accounted for only $313.2 million, or 5% of total volume.
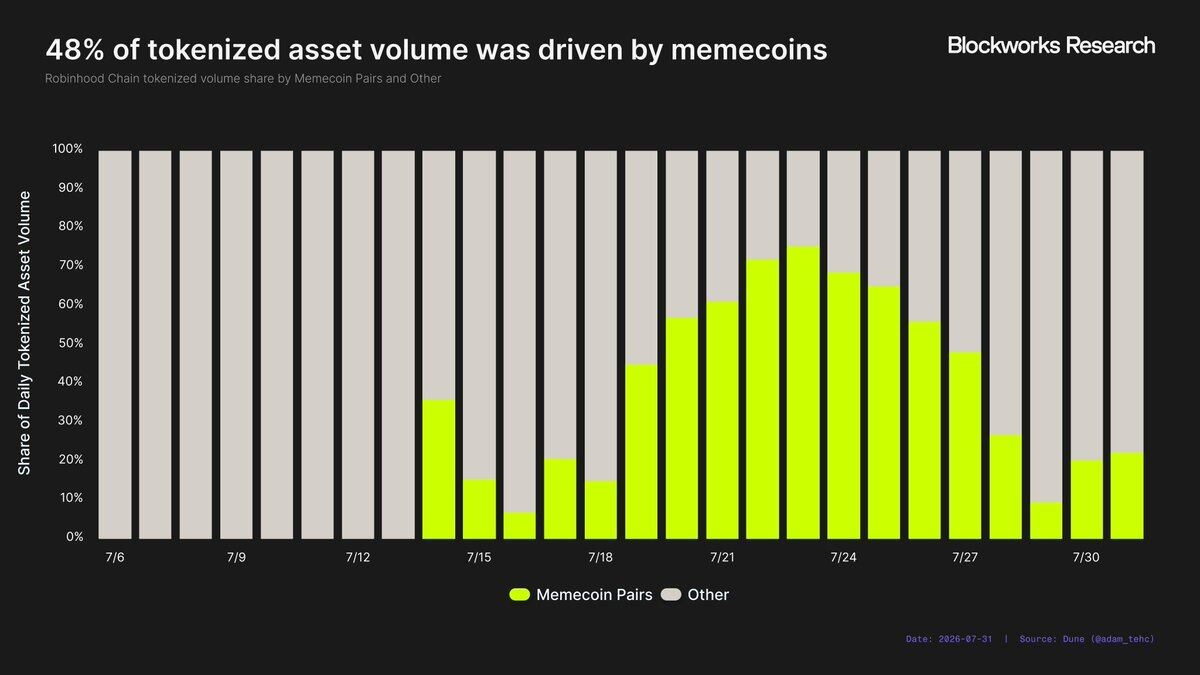
Moreover, the direct share of Meme coins in trading volume on Robinhood Chain may still underestimate their true impact on network activity. Take RWA as an example. One strategy promoted by the Meme coin launching platform L()ng is to pair Meme coins with tokenized stocks or ETFs inside liquidity pools, linking Meme coin price action to the underlying RWA. If the underlying RWA rises—say by 5%—the Meme coin price also rises by 5% (assuming no buying or selling). As a result, a substantial portion of what looks like RWA trading volume is actually driven by Meme coins. From July 6 to July 31, 48% of RWA trading volume occurred in liquidity pools pairing RWA with Meme coins.
While Meme coins can effectively drive growth in chain revenue, historically they rarely become a long-term stable source of income. Meme coin activity is highly rotational; Ethereum, Avalanche, TRON, and Base have all experienced their own speculative hype cycles, but eventually funds and users move to other networks again. Whether Robinhood Chain can retain these activities in the future remains unclear. One month of data is not enough to prove that Meme coins will become a sustainable REV source for Robinhood Chain, or whether they’re just another temporary stop in the rotation of capital—eventually returning to Solana.
From a more macro perspective, REV driven solely by Robinhood Chain is unlikely to revive Robinhood’s crypto business. Across the entire industry, network revenue is in a structural decline. First-generation smart contract platforms used to rely on the scarcity of block space to generate substantial fee income, but as block space gradually becomes commoditized, it becomes increasingly difficult for new chains to create significant revenue purely through infrastructure itself.
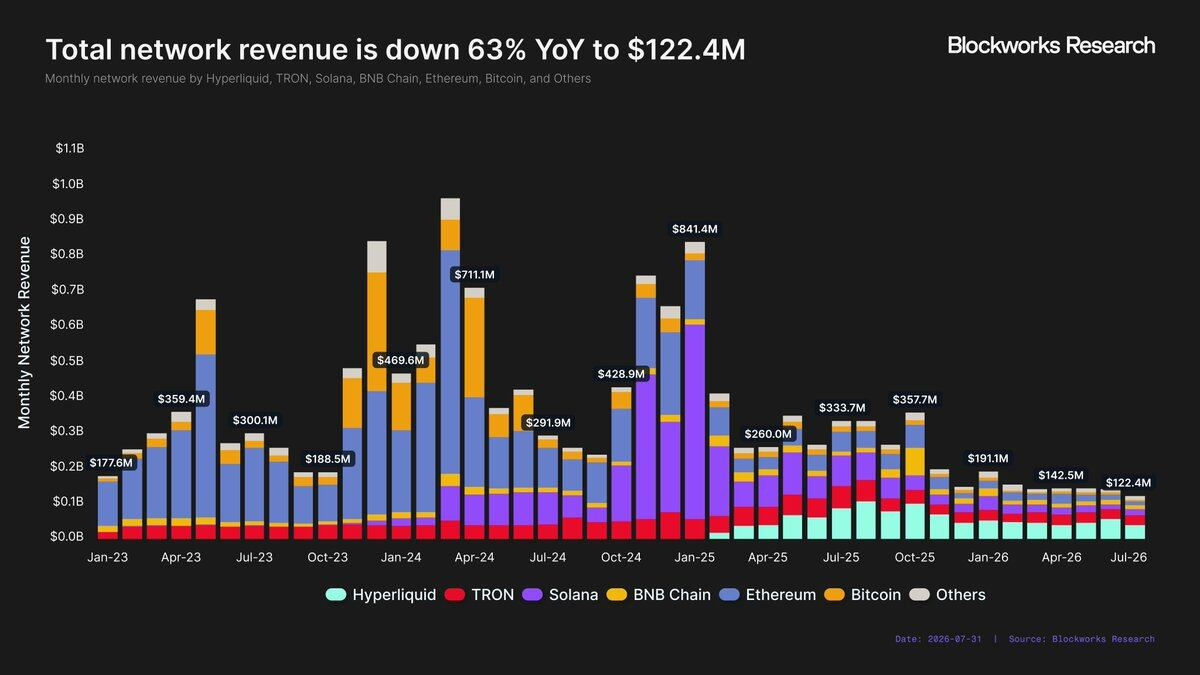
In July, the blockchains tracked by Blockworks generated $122.4 million in network revenue, the lowest monthly total in more than three and a half years. By contrast, network revenue in July 2025 was $333.7 million, down 63% year over year. This deterioration cannot be simply attributed to market cycles. In July 2023, during the previous bear market, the chains still generated $300.1 million in network revenue.
As noted earlier, Robinhood already has 13 business lines with at least $100 million in annualized revenue. Relying on network revenue alone, it’s hard to imagine how Robinhood Chain could join that group. Even if Robinhood Chain continues to capture a larger share of L2 activity, its chain revenue would ultimately run into a market ceiling around $100 million in annualized terms.
Breaking through this ceiling requires Robinhood to bring its existing user base on-chain. However, since Robinhood’s users are mainly located in the United States, under the current regulatory environment most of them cannot access Robinhood Chain via the Robinhood app, and this process may take time.
If Robinhood wants Robinhood Chain to become, in the short term, the next $100 million business line, the company needs to go beyond a network revenue-only model.
Monetization of the application layer
Value capture in the crypto industry is gradually shifting from the infrastructure layer to the application layer. Solana is a great example.
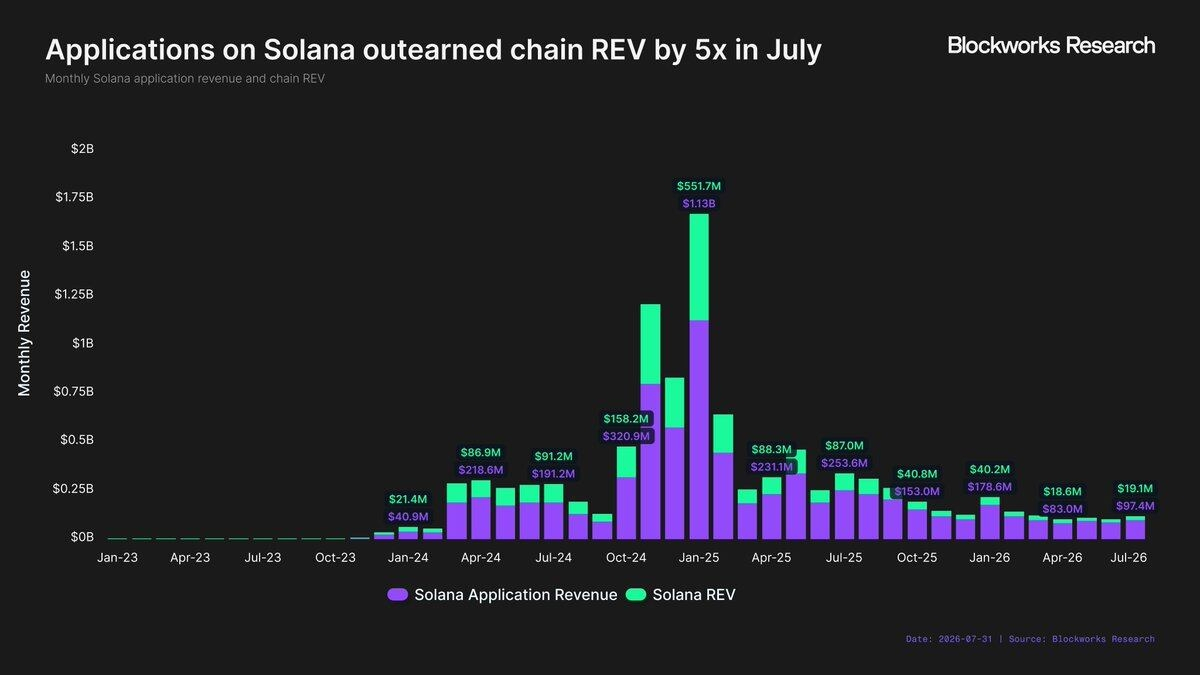
In early January 2024, shortly after Solana’s recovery, Solana applications generated $40.9 million in revenue, while the Solana network could generate $21.4 million in REV—application revenue was about 1.9x network revenue. In January 2025, at the peak of Solana’s bull market, application revenue reached $1.13 billion, while Solana REV was $551.7 million, keeping the ratio at roughly 2x. But since then, this gap has widened further. In July 2026, for every $1 of revenue created by Solana ecosystem applications, the network itself captures only about $0.20.
In other words, the application layer is capturing more and more value, while the proportion of value captured by the underlying blockchain is declining. If Robinhood wants Robinhood Chain to become the next $100 million business line, it must directly participate in monetizing on-chain applications. Although Robinhood hasn’t officially announced this strategy yet, its early moves point in that direction.
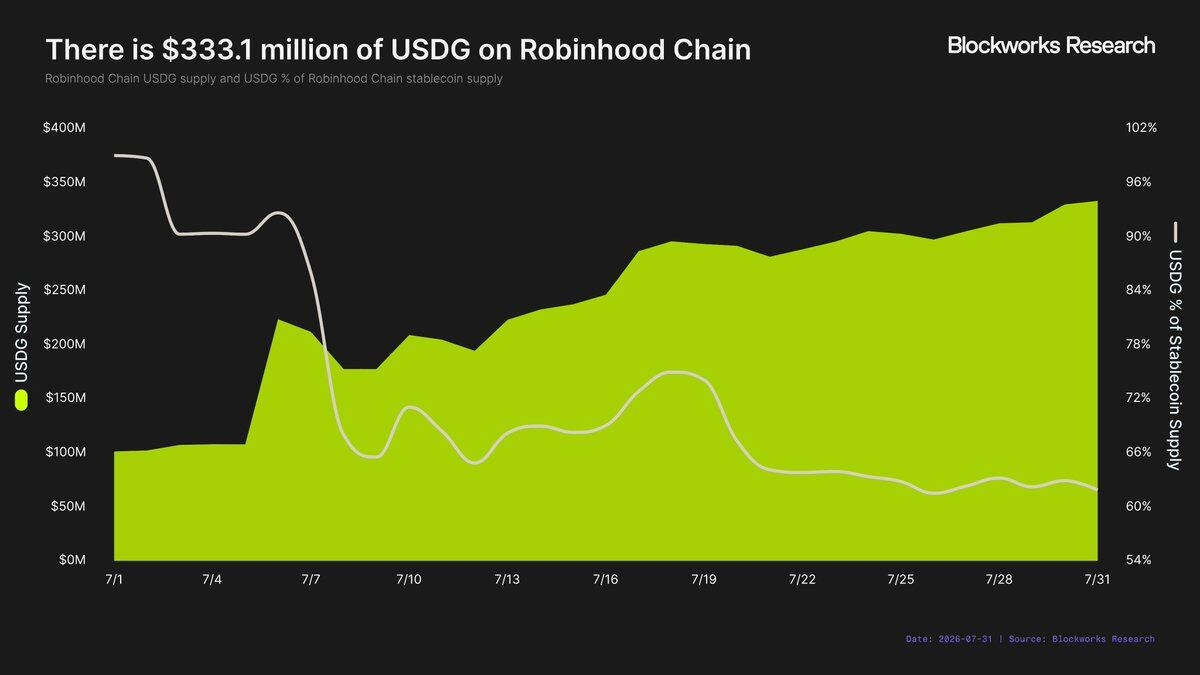
The most standout case so far is Robinhood’s stablecoin strategy. Unlike most blockchains that mainly rely on Circle’s USDC or Tether’s USDT, Robinhood defines USDG as the native stablecoin of Robinhood Chain. This creates an additional revenue stream for Robinhood—interest income generated from the underlying reserve assets of USDG. As of the end of July, the market capitalization of USDG on Robinhood Chain was $333.1 million. Assuming a 3.5% yield on the underlying reserves and that Robinhood keeps 90% of the related interest income, USDG would generate approximately $10.5 million in additional annualized revenue.
Robinhood should have no trouble further increasing the supply of USDG, thereby creating a durable stream of income. If USDG supply reaches $1 billion (a reasonable target since 11 other blockchains already have stablecoin supplies of at least $1 billion), it would generate $31.5 million in annualized revenue—nearly matching Robinhood Chain’s current chain revenue.
Robinhood Chain also appears to be expanding beyond stablecoins into the application layer. Lighter has launched a customized deployment of its Perp DEX on Robinhood Chain and will share trading fees on a 50/50 basis with Robinhood. As part of the partnership, Robinhood Wallet—a self-custody wallet separate from the main Robinhood app—will display Lighter’s perpetual contracts directly within the app.
In addition, it’s also rumored that Morpho paid fees to Robinhood for integration within the Robinhood app. If true, this would be a business model that is clearly different from the traditional blockchain ecosystem—where incentives usually flow from the blockchain to the application to attract deployments. Robinhood, instead, is trying the reverse: applications pay to obtain Robinhood’s user distribution channel.
How much is Robinhood’s distribution capability worth?
The feasibility of the entire application-layer strategy ultimately depends on the value of Robinhood’s distribution channels. If protocol teams are willing to pay for access to Robinhood users, then Robinhood can commercialize this flow of traffic as a business asset.
Based on current case studies, protocols on Robinhood Chain can primarily obtain users through two channels:
· Robinhood’s main app, for example Morpho;
· Independent Robinhood Wallet, for example Lighter.
Although the distribution value of Robinhood’s main app is well known to the market, the value distributed via Robinhood Wallet remains far less clear.
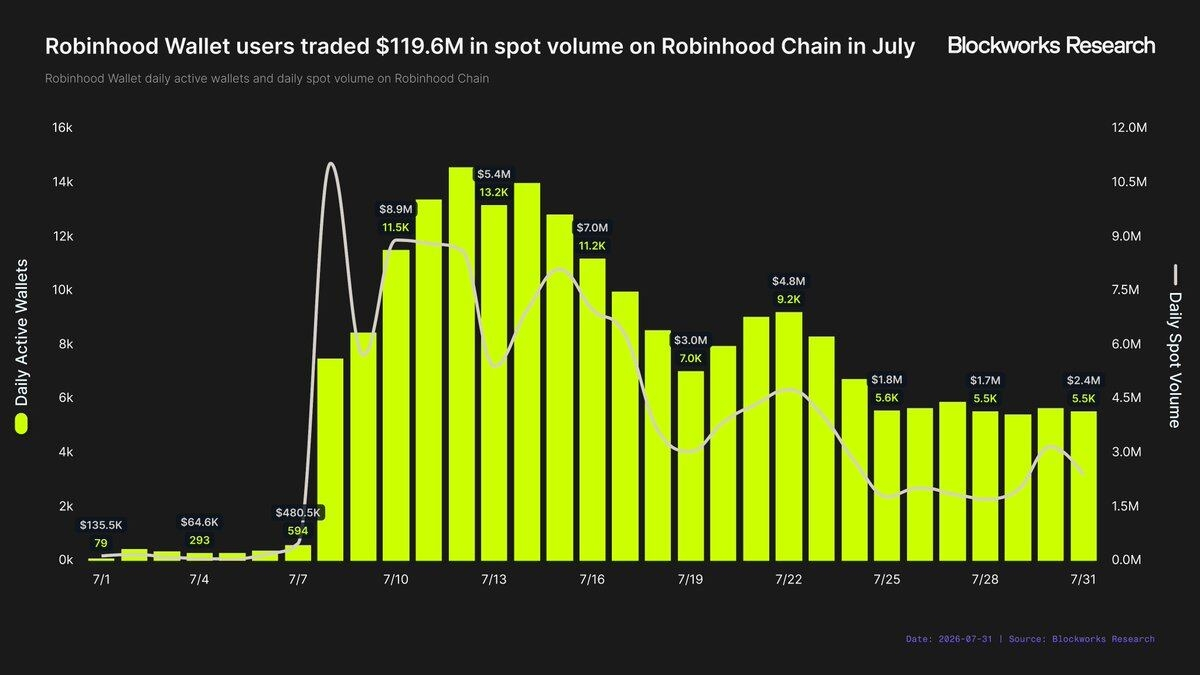
Looking only at active usage on Robinhood Chain, Robinhood Wallet users generated $119.6 million in trading volume in July. Daily trading volume peaked at $11 million on July 8, then fell to an average of $2.1 million per day in the last week of the month. Robinhood Wallet’s average daily active wallets in July were also only slightly below 7,000. This analysis does not apply bot (Sybil) attack filtering, so the actual number of independent users may be lower.
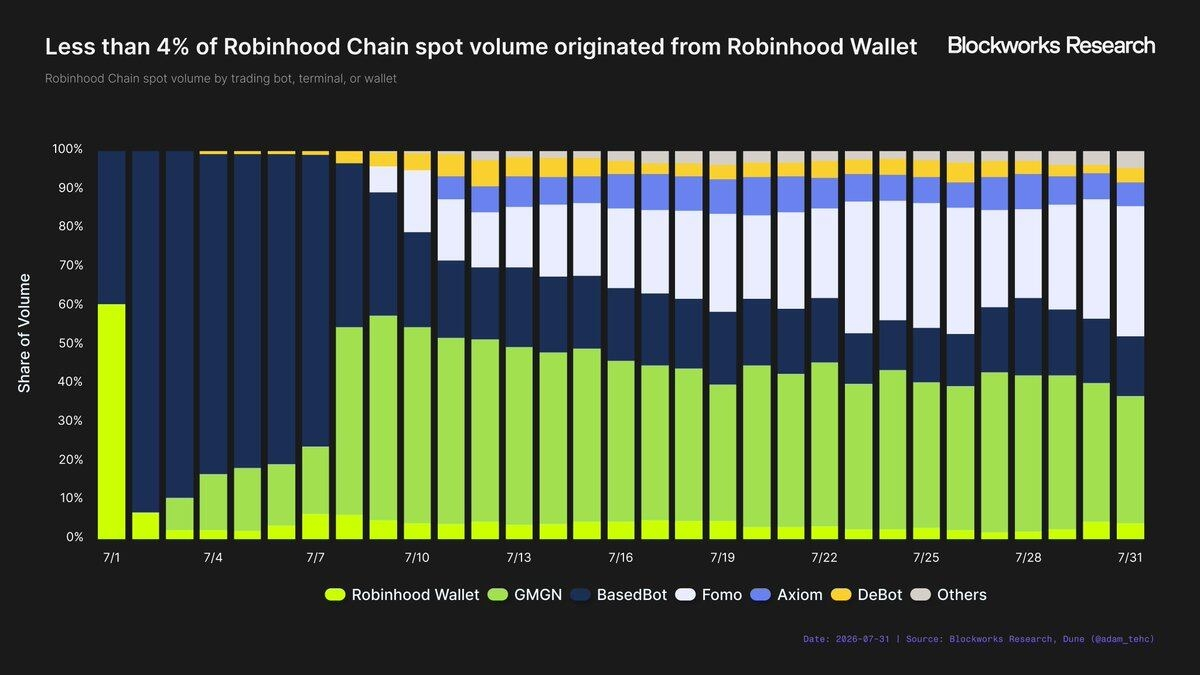
Compared with the broader wallet and trading-app ecosystem on Robinhood Chain, Robinhood Wallet is still a relatively small participant. Tracked wallets and trading apps generated $3.08 billion in trading volume in July, of which Robinhood Wallet accounted for $119.6 million—less than 4% market share. However, the trading volume of these apps is primarily driven by heavy users. In terms of average daily active wallet counts, Robinhood Wallet ranks fourth, even though it ranks sixth by trading volume.
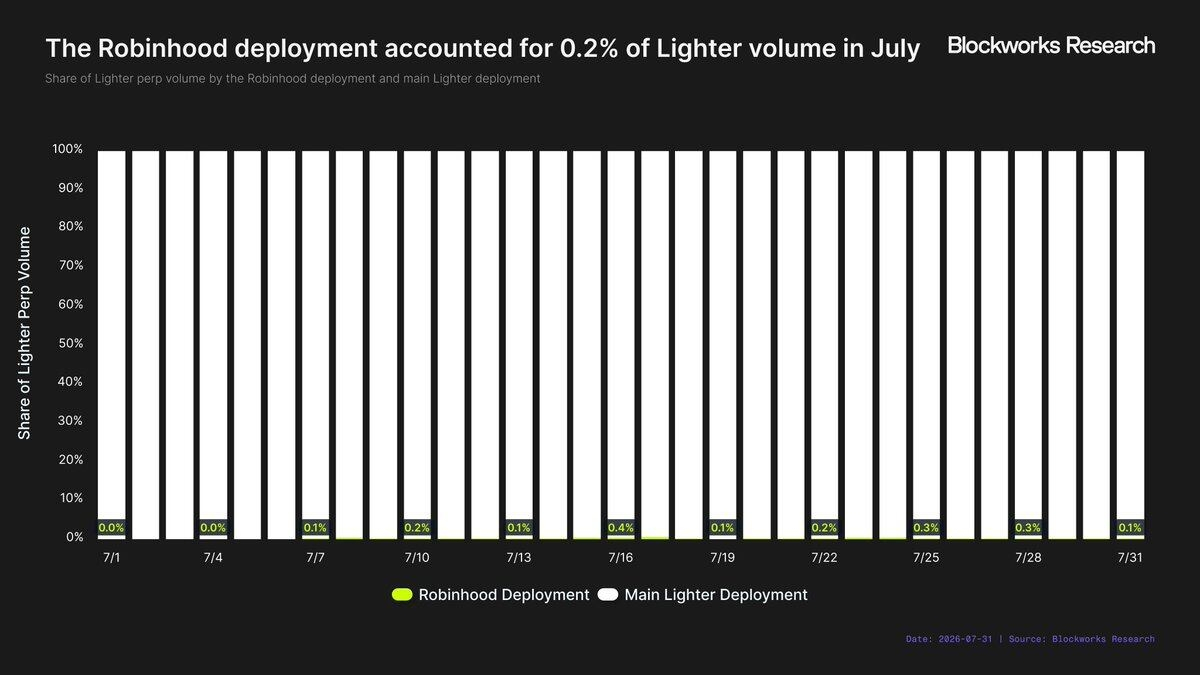
Lighter’s integration further demonstrates the limited value of Robinhood Wallet distribution. Since integrating into Robinhood Wallet, Lighter’s Robinhood deployment has accounted for only 0.2% of its total perpetual contract trading volume. In July, this figure was $86.8 million, below the spot trading volume generated during the same month via Robinhood Wallet.
What’s arguably even more concerning is that Lighter is directly incentivizing perpetual contract trading via Robinhood Wallet, allocating 11 million LIT tokens for this purpose—currently worth roughly $25 million. Even if current trading volume is still reward-driven, without these incentives it would likely be even lower. As of now, it’s hard to draw conclusions about how much value distribution via Robinhood Wallet alone can realistically generate.
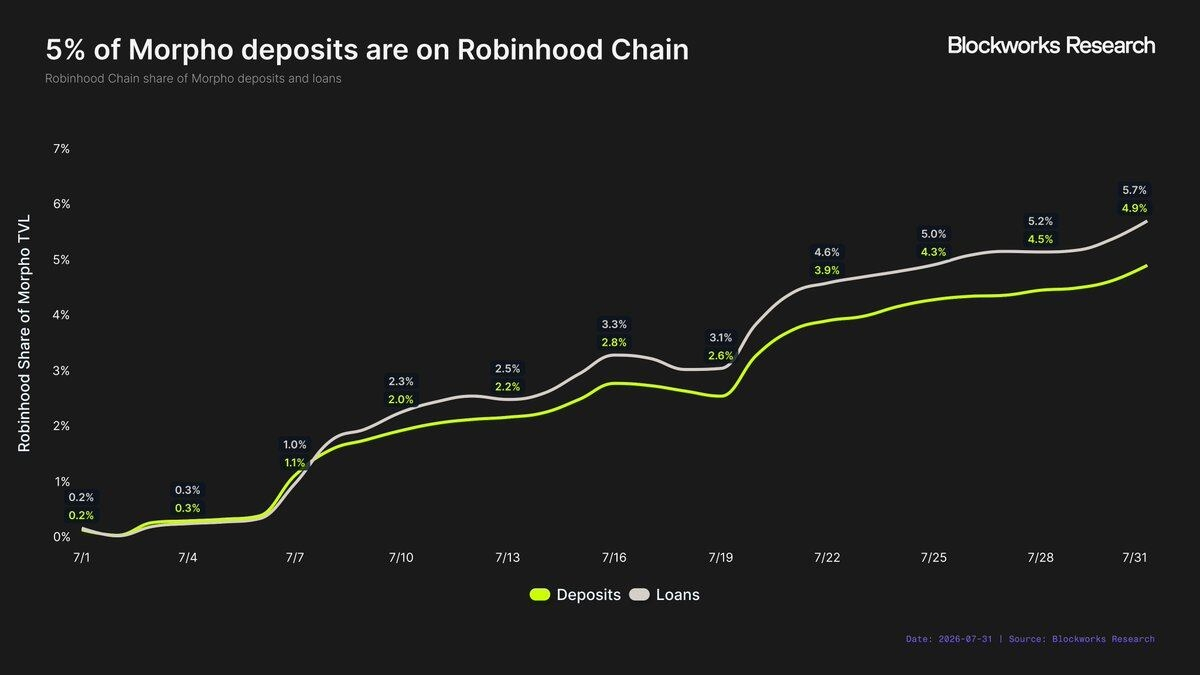
Although the distribution value provided by Robinhood Wallet may be limited, Robinhood’s main app is very different. Morpho offers the clearest example: Robinhood users can deposit stablecoins into Morpho directly through the main app to earn incentivized 7% annualized returns. As of the end of July, the market deployed by Morpho on Robinhood Chain accounted for 5% of Morpho’s total deposits and nearly 6% of all loans. After launching for just one month, Robinhood Chain had already become Morpho’s third-largest TVL market.
It’s important to acknowledge that this part of TVL is also incentivized. Even so, the difference between Robinhood main-app distribution and Robinhood Wallet distribution remains substantial. While not a perfect like-for-like comparison, Robinhood Chain’s market share of Morpho’s total deposits is 25x Robinhood’s deployed market share of Lighter’s total perpetual contract trading volume.
Therefore, the early conclusion about Robinhood’s distribution value is split. For protocols that can secure direct integration into Robinhood’s main app, the distribution value appears extremely high; but distribution via Robinhood Wallet alone is far less compelling. Unless Wallet integration can act as a stepping stone to reach the main app ultimately, it’s hard to understand why a protocol would sacrifice meaningful economic value for this purpose.
Admittedly, this conclusion is based only on two early case studies. Robinhood has not formally confirmed application-layer distribution trading as a broader strategy, nor is it clear how far the company plans to pursue these kinds of partnerships. Still, the differences observed so far are significant. The real value of Robinhood’s distribution capability does not come from “being associated with the Robinhood brand” or “being deployed on Robinhood Chain,” but from being able to directly reach users inside Robinhood’s main app.
Can Robinhood Chain revive the crypto business?
This report begins with a core question: can Robinhood Chain make crypto a meaningful driver of Robinhood’s growth again?
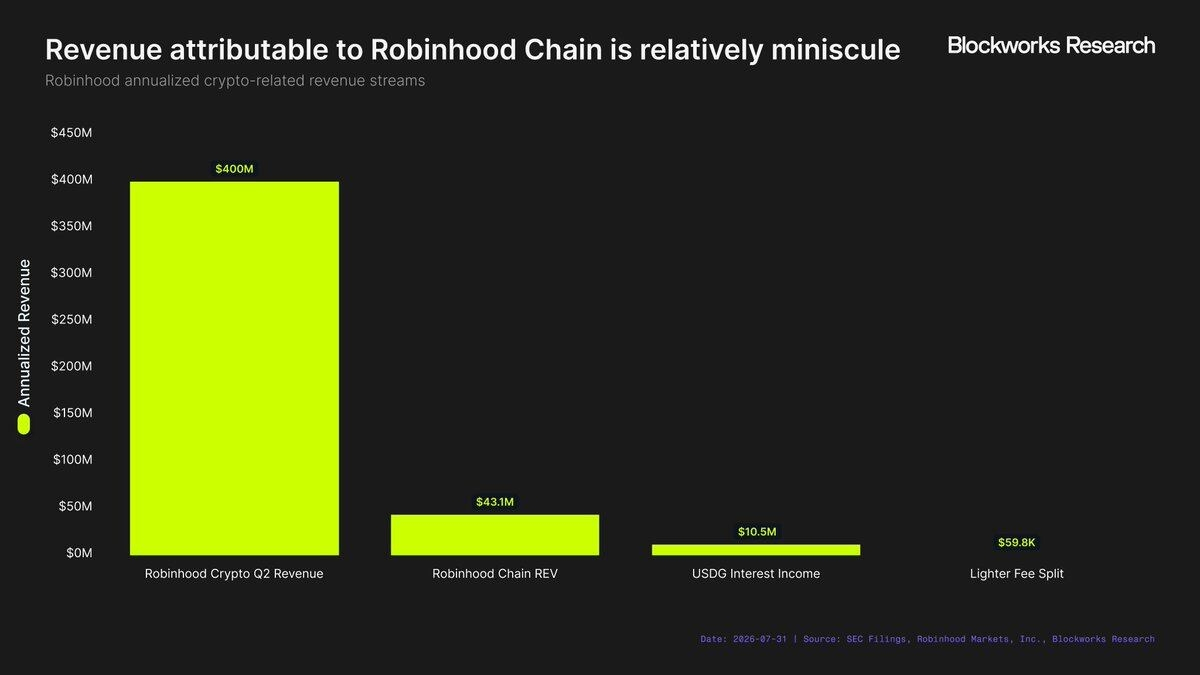
Early data paints a fairly clear picture. Robinhood Chain has achieved notable success as a blockchain, but it has not yet become a meaningful contributor to Robinhood’s business. In Robinhood’s second quarter, crypto revenue was $100 million, roughly annualized to $400 million. By comparison, the known and quantifiable revenue streams associated with Robinhood Chain (chain REV, USDG interest revenue, and the Lighter fees shared by Robinhood) total only $54.8 million annualized—about 14% of Robinhood’s annualized crypto revenue. To be fair, this comparison annualizes only the first-month data for Robinhood Chain, and should not be mistaken for its long-term revenue potential.
Honestly, Robinhood Chain will never have a material impact on Robinhood relying on network revenue alone. Block space is already too commoditized, and the overall L2 revenue market is too small. If Robinhood Chain is to make crypto a meaningful growth driver again, the company needs to monetize economic activity above the infrastructure layer.
Stablecoins offer the clearest path. Tether and Circle have already proven how lucrative interest income from stablecoin reserves can be. At a 3.5% yield, every $1 billion of USDG supply would generate $35 million in annualized revenue for Robinhood (assuming it retains all relevant interest income). If supply reaches $10 billion, that figure rises to $350 million per year—almost matching Robinhood’s current annualized crypto revenue. This won’t happen overnight, but given the scale and volume of Robinhood’s business, achieving this goal is not unthinkable.
App distribution is another compelling opportunity. Robinhood has something that almost all other blockchains lack—direct access to a massive retail investor base. If on-chain protocols are willing to pay for access to these users, or share revenue with Robinhood, Robinhood can monetize its distribution capability rather than relying solely on fees generated by the chain itself. Early results suggest this strategy works: when protocols integrate into Robinhood’s main app, it does drive results, even if the value of the Robinhood Wallet distribution itself is minimal.
There is another possibility: Robinhood may not view Robinhood Chain as a standalone business that earns money. Instead, it may see the chain as a user entry point and conversion channel. Robinhood Chain could serve as a lead-generation tool—exposing users to tokenized assets (and enabling trading of stocks, options, crypto, etc.) before bringing them into the broader Robinhood ecosystem. In this model, the chain’s value may not show up in network revenue, but rather through higher engagement and revenue in other parts of the Robinhood business.
At this point, the question posed at the start of this report still has an answer of “no.” Robinhood Chain has not become a meaningful driver of Robinhood’s growth, and network revenue alone will never make it so. For the answer to eventually become “yes,” Robinhood would need to scale USDG, or commercialize the user distribution capabilities of its main Robinhood app. Otherwise, Robinhood Chain is likely to have only indirect financial value, serving as a lead-generation tool for higher-value products that are already driving Robinhood’s business.
Original text link