


Original title: If you don't understand AI by the end of this, the next decade will confuse you Original author: Anish Moonka Translated by: Peggy, BlockBeats
Editor's note: When people talk about AI, the focus often centers on the most visible aspects: chatbots, AI assistants, and various new applications. However, behind these products, a deeper industrial restructuring is taking place. From electricity, chips to data centers, and then to models and applications, AI is actually a technology stack composed of multiple layers of infrastructure, and the flow of capital and profits is much more complex than what is seen on the surface.
This article systematically outlines the value chain from the perspective of the "AI five-layer structure": why hundreds of billions of dollars are flowing into energy, chips, and cloud infrastructure; why model companies are still burning through cash while growing rapidly; and in which links the real value may be concentrated first in this technological revolution.
By comparing AI with historical cycles such as the electricity revolution and the construction of internet infrastructure, the author attempts to answer a key question: In this technological wave that may reshape the global industrial structure, where is capital flowing, and how can ordinary people participate in this round of AI wealth opportunities?
The following is the original text:
Most people think that AI is just a chatbot.
I understand that thought. You open ChatGPT, let it edit an email for you, and it does it instantly. It feels like magic. So you close the page, thinking you understand how AI works. But that's like swiping your Visa credit card at a restaurant and thinking you understand how Visa makes money. You've only used the product, without seeing the system behind it.
For most of last year, I was trying to figure out where the real profits in AI were going. And the somewhat embarrassing truth is: it took me a long time to realize I was looking at the wrong level. I was focused on ChatGPT, Claude, Gemini—the things you could directly access.
Meanwhile, $700 billion is quietly flowing into another infrastructure I can't even name: chips I've never heard of, packaging technology abbreviations that sound like they've been made up, cooling systems, and power plants. In Texas, Iowa, and Hyderabad, massive amounts of concrete are being poured to build data centers.
A year ago, almost no one around me talked about these things. Now, everyone is talking about them.
This article is quite long. If you don't have time to read it now, you can save it for later.
I want to take you on a complete journey through the AI value chain: from the electricity that powers data centers all the way to the apps on your phone.
Furthermore, I will explain things in a way that you can understand even if you've never read a listed company's annual report before. I will explain all the terminology; I will provide real data for every judgment; and I will frankly explain any areas where I am still uncertain, because there are indeed some.
Let's begin.
1. A five-tiered cake (why is no one discussing the bottom four tiers?)
AI is infrastructure. Just like the internet, just like electricity, it needs factories. —Jensen Huang
Most people understand AI as a smart computer answering questions.
This is like saying the internet is "a place to watch videos." Technically correct, but it completely misses the point.
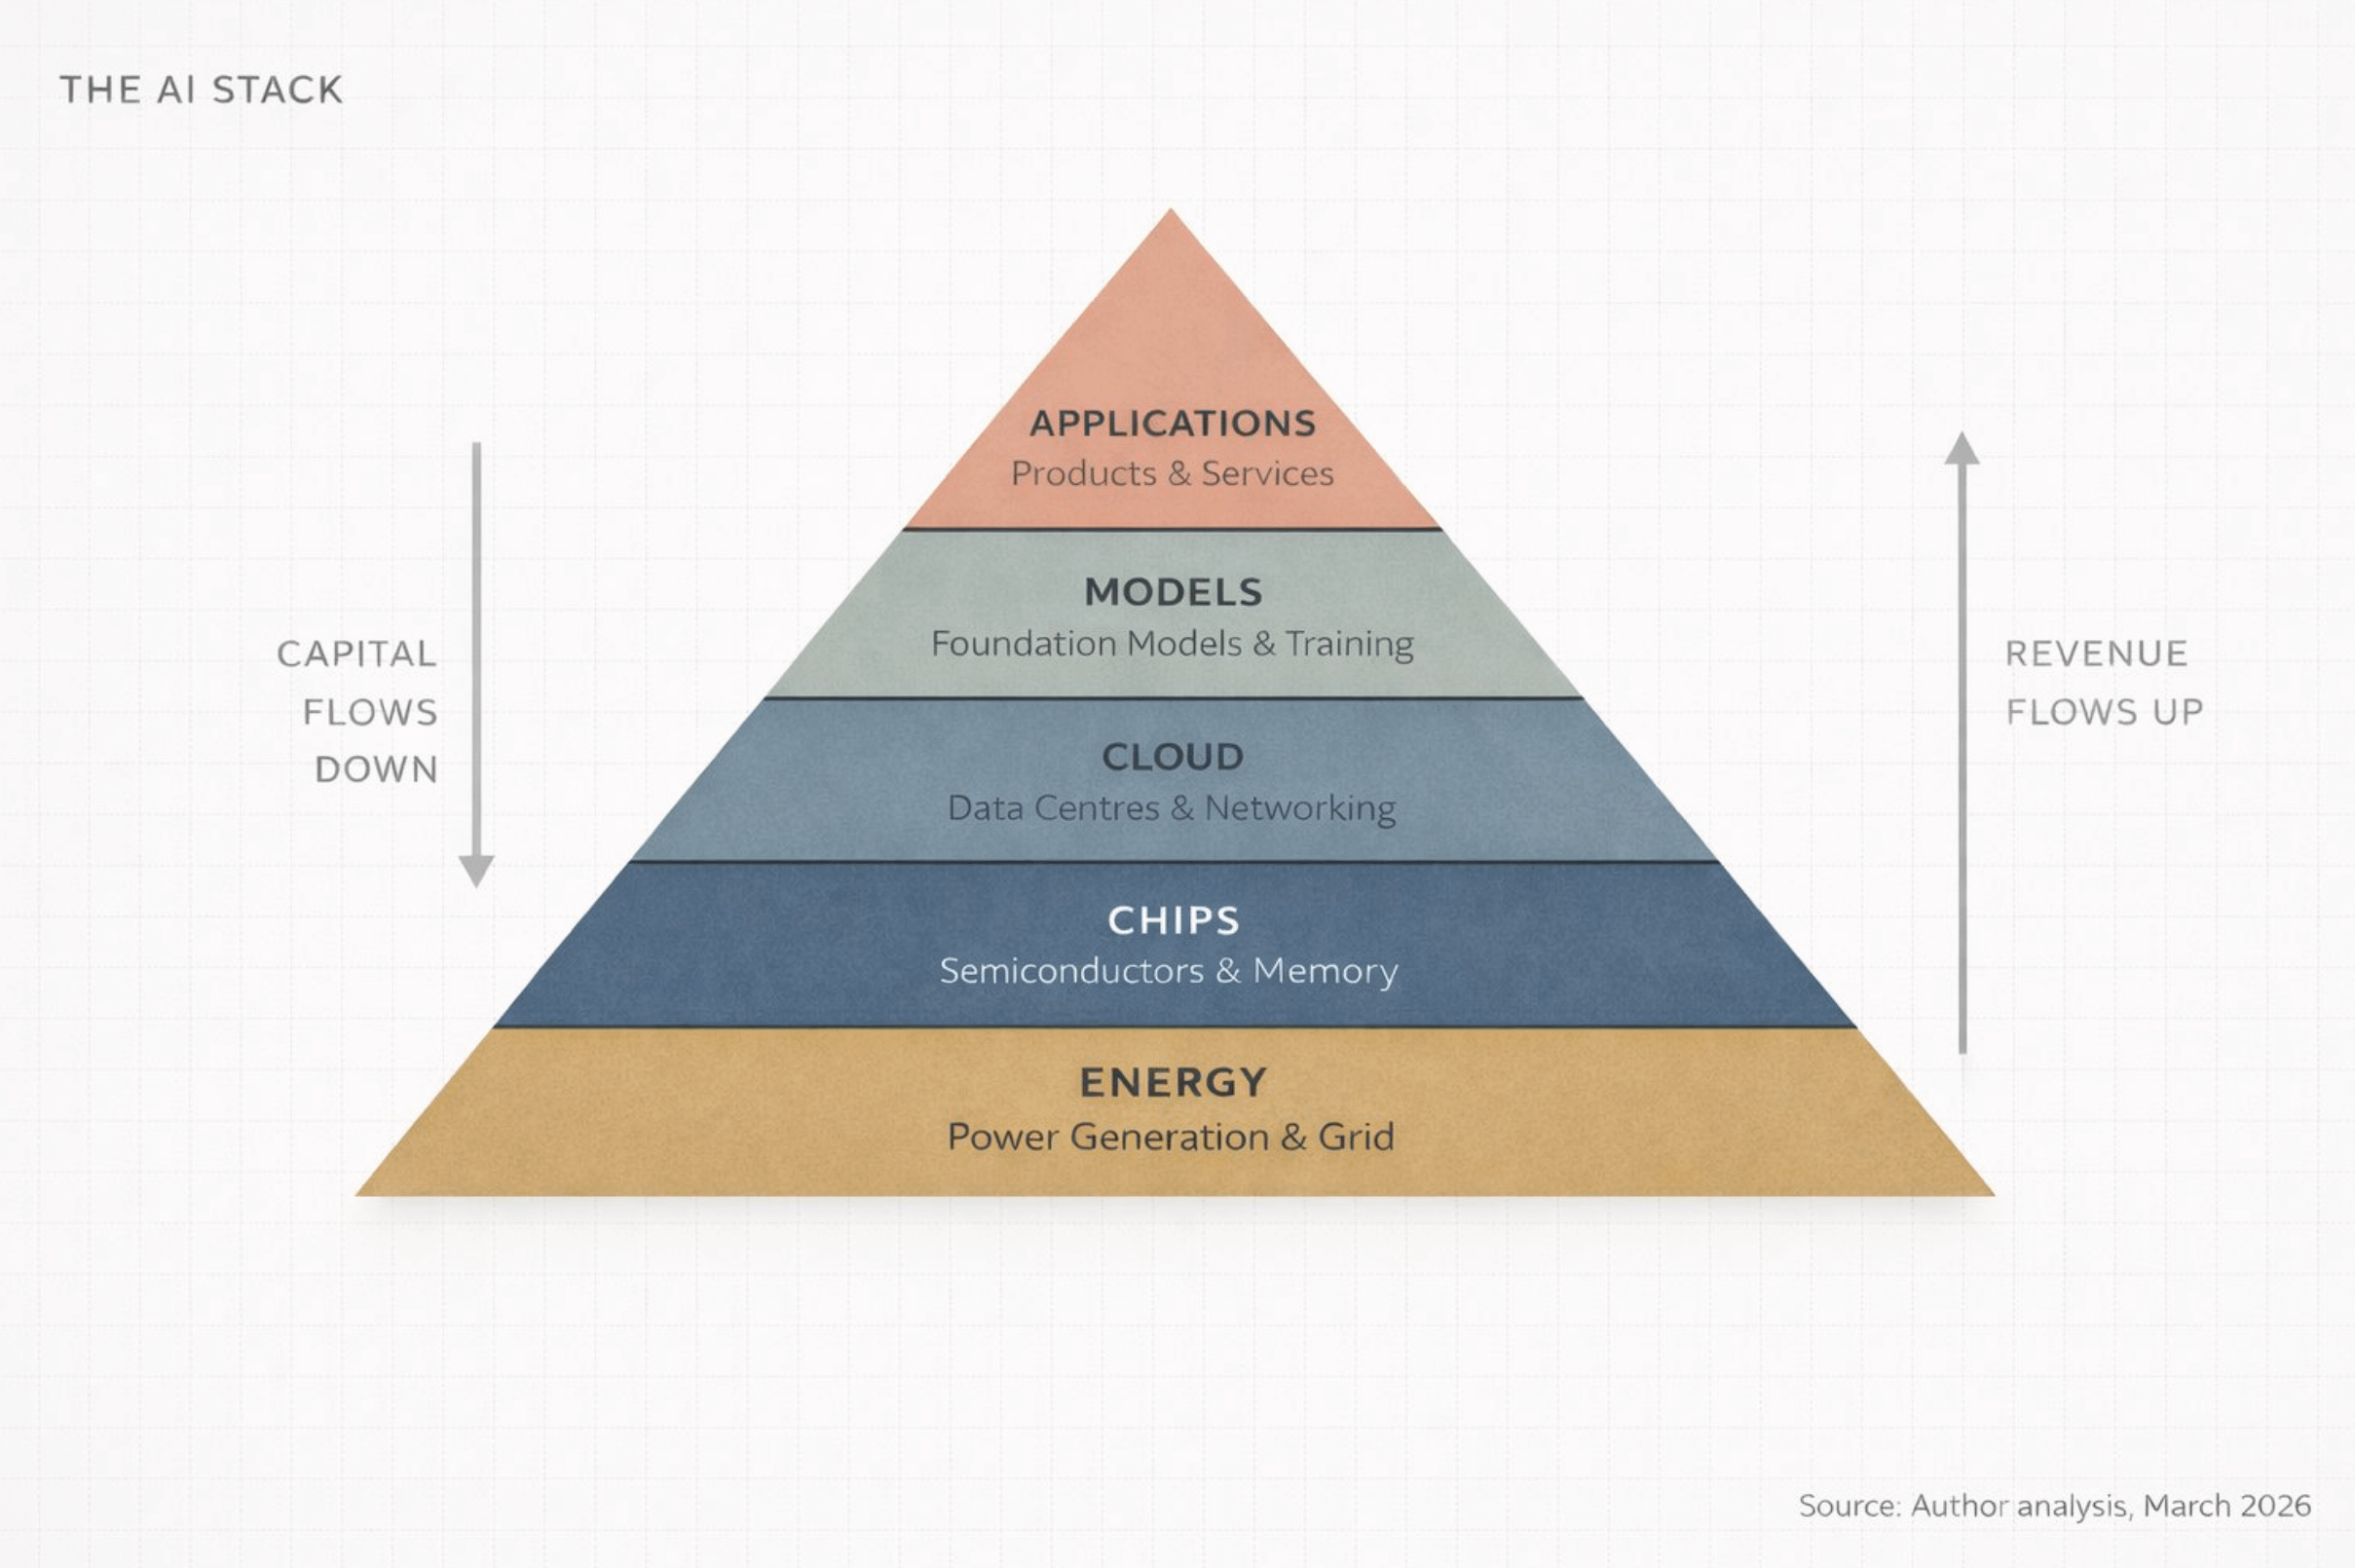
At the World Economic Forum in January 2026, Jensen Huang described AI as a five-layer system:
Energy
Chips
Cloud computing
Models
Applications
He called this entire system "the largest infrastructure project in human history."
First, think about this word: infrastructure.
Highways. Power grids. Water supply systems. These things make modern civilization run, but people usually only notice them when they malfunction.
AI is becoming the same thing: invisible, indispensable, and extremely expensive to build. I call this entire structure the AI Stack. It consists of five layers, stacked on top of each other, with each layer supporting the layer above it, and funding flowing bidirectionally between these layers.
The simplest version I can give is this:
Energy – you need electricity to run a computer, and a lot of electricity at that.
Chips are processors specifically designed for computing. This is not the CPU in your laptop.
For the cloud, you need huge warehouse-style data centers filled with these chips and connected by extremely high-speed networks.
For models, you need real AI software—an "intelligent brain" that learns patterns from data.
Applications are products that people actually use, such as ChatGPT, Google Search, or a bank's anti-fraud system.
Any discussion of AI that only focuses on the fifth layer (the application layer) ignores a full 80% of reality. And if you're an investor, entrepreneur, or simply someone trying to understand the future direction of the world, the truly important point is that money isn't evenly distributed across these five layers. It concentrates, grows exponentially, and flows to a very few key nodes.
Today, these funds are being concentrated in places that most people are completely unaware of.
II. Tracking Fund Flows (The answer isn't where you expect it)
People's attention is almost always focused on the application layer. ChatGPT, GitHub Copilot, Claude, Perplexity.
These are all products that you can use directly, so it's easy to think that the story of AI is probably just about these applications.
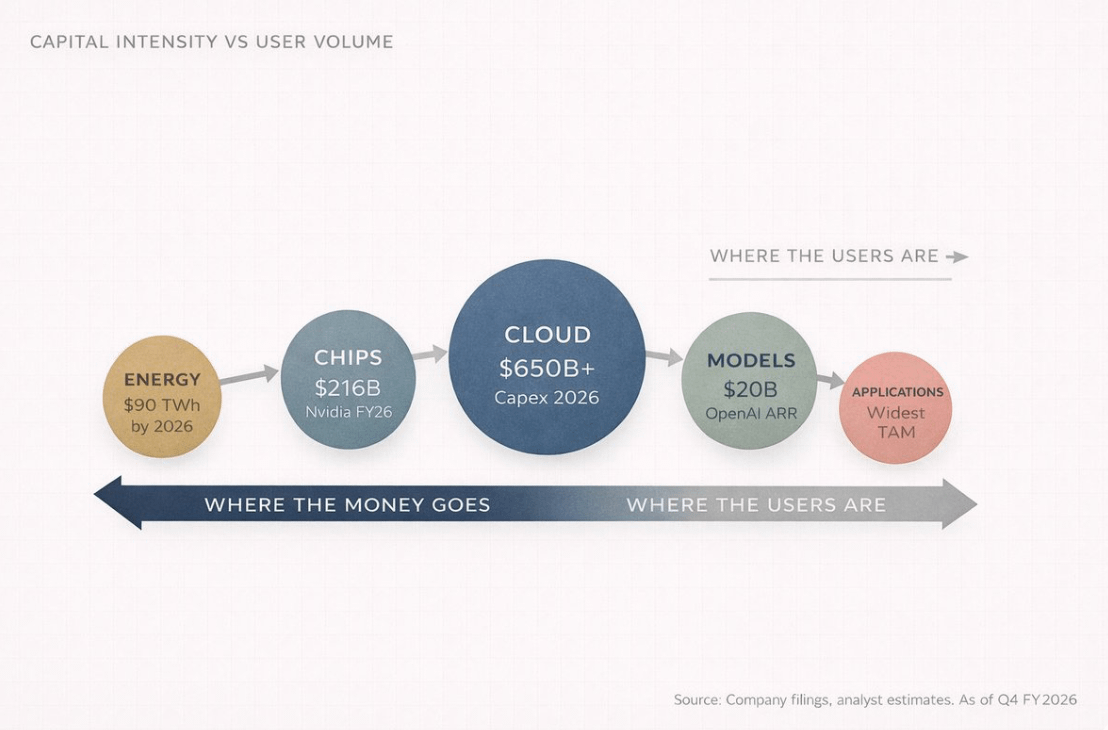
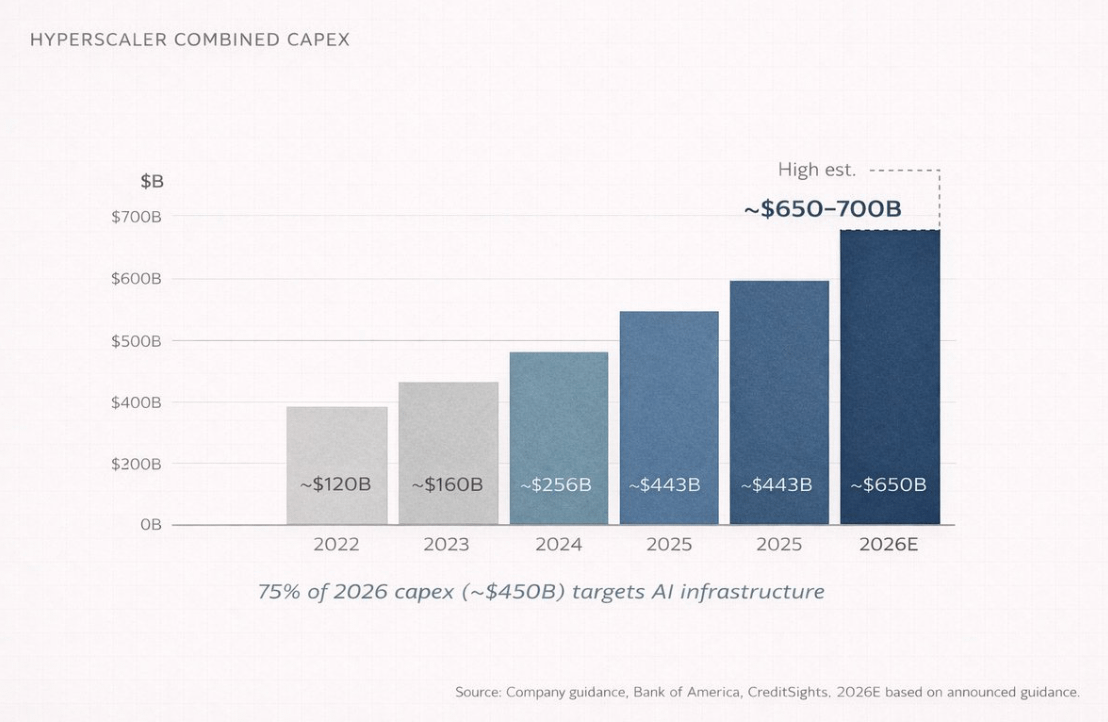
But most people overlook one thing. By 2026, the world's four largest cloud computing companies (Amazon, Microsoft, Google, and Meta) are expected to have a total annual capital expenditure (CapEx) of $650 billion to $700 billion.
This is a year, totaling four companies.
This figure is roughly equivalent to Switzerland's entire annual GDP. Of that, approximately 75%, or about $450 billion, will be directly invested in AI infrastructure.
It's not chatbots, it's not apps. It's architecture, chips, fiber optics and networks, cooling systems—things nobody talks about at cocktail parties. That just goes to show the money's there.
Because if you think about it carefully, before anyone can use ChatGPT, someone has to do one thing first: build a data center the size of a shopping mall, install tens of thousands of dedicated processors inside, connect them with network equipment worth far more than the market value of most companies, and then provide the entire system with enough power to power a small city. And this has to be done every single day.
These are the first to third layers: energy, chips, and cloud infrastructure. These are the invisible layers, and also where huge amounts of capital are actually deployed.
Some might ask, "What about OpenAI? Haven't they already made billions of dollars?"
That's true.
By the end of 2025, OpenAI's annualized recurring revenue (ARR) will have reached $20 billion. Just a year ago it was $6 billion, and the year before that it was only $2 billion.
A tenfold increase in two years—few companies in human business history have achieved such rapid revenue growth on this scale.
However, the problem is that the cost is equally staggering.
By 2025: OpenAI will have burned through approximately $9 billion in cash.
2026: Projected to burn through $17 billion
This only refers to the inference cost, which is the actual cost of the system running the model when you ask an AI a question:
2025: $8.4 billion
Projected value for 2026: US$14.1 billion
According to current projections, OpenAI is not expected to achieve positive cash flow until 2029 or 2030.
So here's the question: where did all that money go?
The answer is: flow down the AI technology stack.
Flow direction:
Microsoft Azure (OpenAI is required to pay Microsoft 20% of its revenue by 2032 under the agreement)
Nvidia GPUs
Engineering companies that build data centers
and energy companies that provide electricity
If you stare at this system for a while, you'll notice an almost cyclical structure:
Microsoft invests in OpenAI
OpenAI used this money to purchase Azure cloud services.
Azure uses revenue to buy Nvidia chips
Nvidia reports record profits
Everyone applauded
Then, the funds continued to flow downwards.
There is a very important structural fact in the AI technology stack:
The vast majority of users are at the top layer (application layer).
The vast majority of profits are at the lowest level (infrastructure layer).
This misalignment between user position and profit position is the core of the entire AI investment logic.
This is the first rule of the AI value chain: income flows upwards, while capital sinks downwards.
III. You've actually seen this scene before.
All human problems are essentially engineering problems, and engineering problems can ultimately be solved. —Buckminster Fuller
If you want to truly understand what is happening with AI, you can look back at the history of the electrical revolution between 1880 and 1920.
In 1882, Thomas Edison built the first commercial power station on Pearl Street in Manhattan, New York. At the time, most people considered electricity nothing more than a novelty, a more "advanced" way of lighting. After all, gas lamps already worked perfectly well. Who really needed something like this?
But in just 40 years, electricity has completely reshaped almost every industry: manufacturing, transportation, communications, healthcare, and entertainment.
The real winners of this revolution were not the inventors of the light bulb, but those who built the infrastructure: General Electric, Westinghouse Electric, power companies, copper mining companies, and engineering and construction companies.
Today, AI is repeating the same pattern, only the speed has been compressed to a few years instead of decades.
Compare the two chains:
AI System: AI → Data Center → Chip → Raw Materials → Energy
Electricity system: Electricity → Factory → Machinery → Raw materials → Coal/Hydropower
The two paths are almost identical. And once again, the winner is not primarily at the application layer, but at the infrastructure layer.
I call this phenomenon Infrastructure Gravity. Whenever a new computing platform emerges, the people who create wealth first are always the "shovel sellers".
The app will eventually surpass the competition and receive all the media attention. But the infrastructure will take away most of the profits.
For example, Nvidia's revenue for fiscal year 2026 (ending January 2026) was $215.9 billion, a 65% year-over-year increase. Of that, the data center business alone generated $62.3 billion in revenue in the last quarter, a 75% year-over-year increase. This business now accounts for 91% of Nvidia's total revenue.
In other words, a company with $68 billion in revenue in a single quarter, 90% of which comes from the same business line.
Let's look at chip manufacturing. TSMC will hold approximately 70% of the global wafer foundry market share in 2025, with sales of $122.5 billion. Second place, Samsung Electronics, will only have 7.2%. This level of monopoly even makes the once-dominant Standard Oil seem less impressive.
Infrastructure always wins first. The real question is, how long will this window of opportunity last?
Ask anyone what the internet revolution is, and they'll say Google, Amazon, and Facebook.
But if you ask where the earliest money was made, the answer is actually Cisco Systems and Corning, the companies that laid fiber optic networks.
The same story, just in a different era.
IV. The part no one wants to listen to
The stock market is a machine that moves money from the impatient to the patient. —Charlie Munger
I have to be honest. When I first started looking at AI as an investor, I made the same mistake as most people: I focused on the application layer. I saw ChatGPT grow. I saw Anthropic raise billions of dollars. So I thought, AI companies will win, so I'll invest in AI companies.
Later, three things changed my perspective, and they happened in sequence.
First thing: The hottest companies are burning money.
I've noticed that almost all "AI companies" are burning through cash like crazy. OpenAI, Anthropic, Mistral AI, xAI—they're all spending money far faster than they're making it. The reason isn't a poor business model, but rather that computing power costs are structural.
Every time you ask an AI question, the system must perform actual calculations. Calculations require GPUs, and GPUs require electricity. The more powerful the model, the higher the computing power required, so the operating costs only increase.
In other words, the AI winners that people think they are are actually the ones who spend the most money.
The second thing: The most profitable jobs are at the bottom.
I've noticed that infrastructure companies are printing money. Nvidia's gross margin is close to 75%, and TSMC is expanding production while raising prices because demand far exceeds supply.
These companies don't have the "when will they make a profit" question. Their problem is that we simply can't build faster. These are two completely different problems.
The third thing: Don't think like a "consumer" (which is also the most uncomfortable one).
I realized that I've been thinking about AI like a consumer.
Consumers see the application. Engineers see the technology stack. Once you see the entire technology stack, you can no longer ignore it.
Every AI release becomes a Capital Expenditure (CapEx) announcement. Every model upgrade becomes a new chip order. Every new feature becomes a new data center lease.
The entire industry began to resemble concentric circles: the closer to the center, the more concentrated the profits.
Perhaps you are: a software engineer focusing on AI models, a retail investor who bought Nvidia shares at $300, or someone observing this revolution from afar in India (or perhaps you are all three at the same time—that would be the most interesting position).
Regardless of your position, the principle remains the same. Consumers see the product, investors see the supply chain. And the best investors see the supply chain that is already in place before the product launch.
V. Investor Map: A Layer-by-Layer Breakdown of the AI Technology Stack
The article is already quite long, so I will speed up the pace.
Below is the structure of each layer of the AI Stack, the main players, and the potential opportunities.
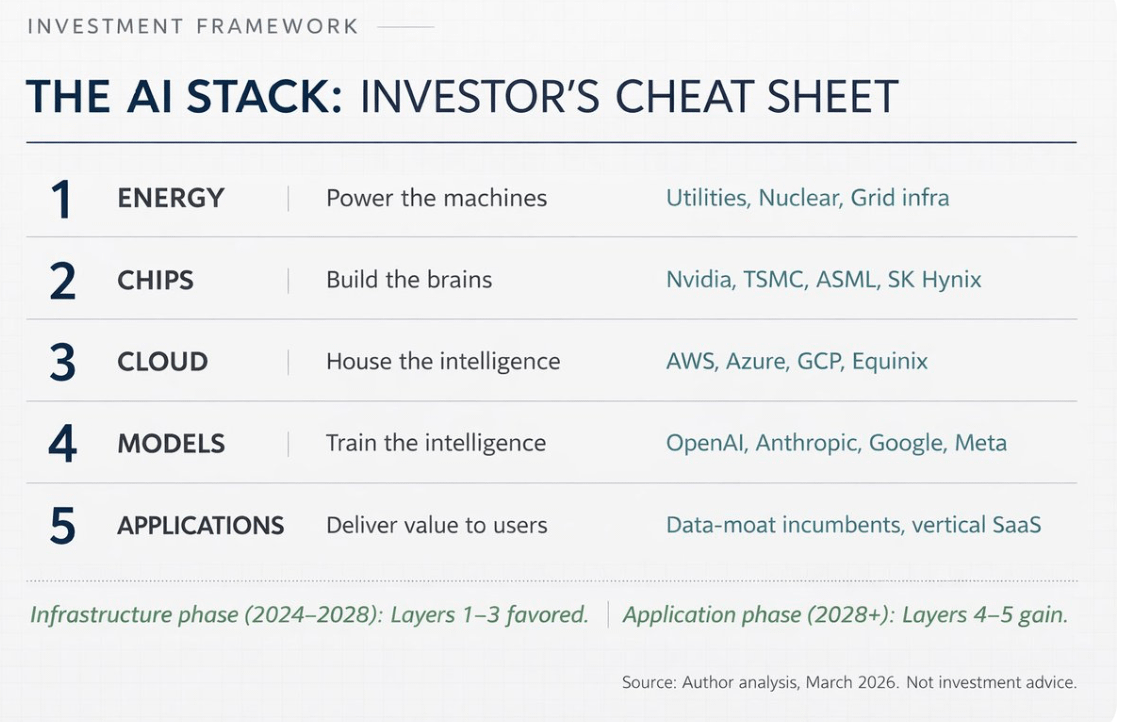
Layer 1: Energy
AI data centers are extremely power-intensive. A single large-scale model training session can consume the electricity of a small town for a year. By 2026, global AI data centers are projected to consume approximately 90 terawatt-hours of electricity annually, a roughly tenfold increase compared to 2022.
This leads to a very simple investment logic: whoever can provide a stable power supply to data centers will benefit. This includes nuclear power companies, natural gas companies, renewable energy companies, power grid companies, and especially energy companies located near data center clusters.
Jensen Huang stated in October 2025 that data centers could potentially build their own power sources faster than connecting to the grid. In fact, many tech companies are already building power generation facilities directly next to their data centers, bypassing the power grid.
This shocks me. These tech companies are turning into their own power companies.
Beneficiaries include utility companies, independent power producers, and power equipment manufacturers (transformers, switchgear, etc.). In Asia, such as India, power equipment and transmission companies will also benefit as hyperscaler data centers expand.
Layer 2: Chip
This is the layer most familiar to the public because of Nvidia. But in reality, this layer is far more complex than a single company.
The chip layer can be further subdivided into several sub-layers:
Design company
Nvidia(GPU)、AMD、Broadcom、Qualcomm
And an increasing number of cloud vendors are developing their own chips: Google TPU, Amazon Trainium, Microsoft Maia
Manufacturing Company
The market is almost entirely dominated by TSMC, with a market share of approximately 70%, followed by Samsung Electronics (7.2%). Intel is attempting to rebuild its foundry business, but this will take many years.
Equipment Company
The machines used to manufacture the chips come from ASML (the only company that produces EUV lithography machines), as well as Applied Materials, Lam Research, and Tokyo Electron.
Memory company
AI models require large amounts of high-bandwidth memory (HBM). Major players include SK Hynix, Samsung, and Micron Technology.
Packaging technology
Advanced packaging technologies (such as TSMC's CoWoS) have become a new bottleneck.
The most striking thing about this layer is actually the concentration:
Nvidia: Approximately 92% AI GPU market share
TSMC: Manufactures almost all AI chips
ASML: The sole EUV equipment supplier
One company designs. One company manufactures. One company produces the manufacturing machines. This concentration presents both an investment opportunity and a geopolitical risk.
Layer 3: Cloud and Data Center
This is where the chip actually operates.
Huge warehouse-style facilities:
Thousands of servers
High-speed network connection
Liquid cooling system (now standard, instead of optional)
The market is dominated by three major cloud vendors:
Amazon Web Services(31%)
Microsoft Azure(24%)
Google Cloud(11%)
Oracle is also expanding rapidly, with plans for $50 billion in capital expenditures by 2026. But this layer goes far beyond the hyperscaler.
For example:
Foxconn assembles 40% AI servers
Arista Networks provides network equipment.
Credo Technology (stock price increased by 117% in 2025)
Vertiv provides liquid cooling
Data center real estate companies:
Equinix
Digital Realty
Even concrete suppliers are involved; each floor has a complete supply chain.
According to estimates from Bank of America, by 2026, hyperscalers will allocate 90% of their operating cash flow to capital expenditures. This figure will remain at 65% in 2025.
Morgan Stanley predicts that these companies will issue more than $400 billion in debt this year to build data centers. This figure is projected to reach $165 billion by 2025.
When I first read this number, I stopped. $400 billion in debt a year, just to build more warehouses filled with computers.
Layer 4: Model
This layer is the "brain layer," the company responsible for training and building real AI models.
The main players include:
OpenAI (GPT series, annualized revenue of over $20 billion)
Anthropic (Claude, reportedly with annualized revenue of approximately $19 billion by early 2026)
Google DeepMind(Gemini)
Meta AI (Llama, an open-source model)
Mistral AI
xAI (Developed by Grok)
This floor fascinates me because it is both the most sought-after and the least profitable.
For example:
OpenAI's revenue growth is unprecedented, but it is still projected to burn through $17 billion in cash by 2026.
Anthropic is also growing rapidly, but it is highly dependent on funding—a $5 billion funding round in early 2026 valued at approximately $170 billion.
The problem is that there is a structural contradiction in the business model at this level. As the model becomes more powerful, it requires more computing power, but the cost of computing power often grows faster than revenue.
It's a bit like running a restaurant where every new dish requires more expensive ingredients, but customers want the prices to stay the same.
As a result, profit margins have been consistently squeezed.
When will things change? I'm not sure, maybe not in the short term.
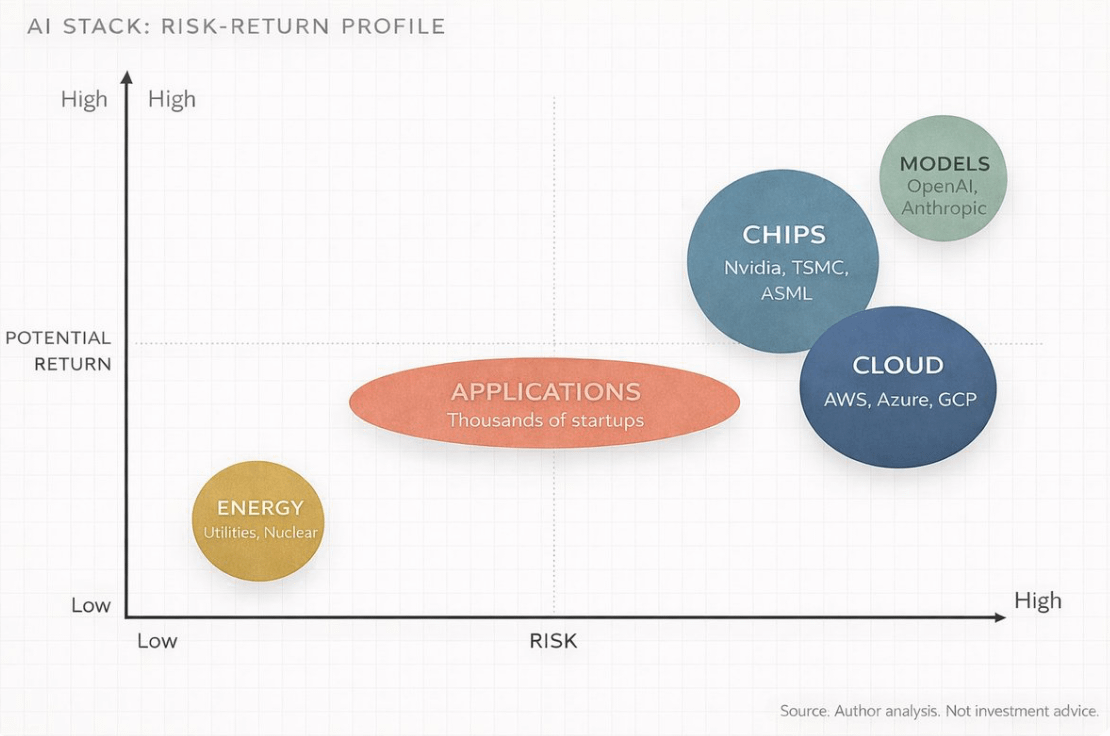
For investors, this layer represents high risk and high return. The problem is that most of these companies are still privately held.
Therefore, investment exposure in the public market mainly comes from two channels:
Cloud computing companies
For example, Microsoft holds a significant stake in OpenAI and provides it with computing power through Microsoft Azure.
chip company
Because the training process of models consumes a lot of their hardware.
Layer 5: Applications
This is the layer you see every day. Examples include ChatGPT, Google Search powered by Gemini, Microsoft Copilot's functionality in Office, banks' AI-powered anti-fraud systems, Netflix's recommendation algorithm, and AI image enhancement on mobile phones.
The application layer is the widest and most crowded layer. Thousands of startups and large enterprises compete here. In the long run, it is likely to become the largest layer in terms of market size. Some forecasts suggest that the application layer market could exceed $2 trillion by the early 2030s.
However, at this stage, this layer also has the lowest profit margin and the most uncertain competition.
At this level, the real differentiation comes from data. Companies that possess unique, proprietary data will build a lasting advantage.
For example:
Salesforce – Enterprise CRM Data
Bloomberg – Financial Market Data
Epic Systems – Medical Records Data
Companies that possess this data moat can perform deep fine-tuning of AI models, something that general chatbots cannot do.
For investors, the application layer may ultimately offer the greatest potential for returns, but it can also destroy the most capital.
Most AI startups fail, and only a few survivors achieve exponential compound growth.
The most likely investment logic for the next 3 to 5 years is to bet on infrastructure now and on applications later. And the smartest money has already positioned itself in this way.
The companies that will truly win in Layer 5 are likely to be those that possess data that others cannot obtain.
Interestingly, many of these companies don't even call themselves AI companies.
VI. AI Risks: "Isn't this just a bubble?"
The investor's greatest enemy may very well be himself. —Benjamin Graham
Let's face the most common question directly: "What about the dot-com bubble? Isn't it the same thing? Huge infrastructure investments, no profits, and everyone was hyped up."
This is a very good question, and it deserves a serious answer.
The key difference is that during the dot-com bubble, when companies were building infrastructure, the demand hadn't actually materialized yet. Back then, businesses were frantically laying fiber optic networks and building server rooms, but real internet users were still using dial-up connections.
The result was that the infrastructure was built, but the demand didn't actually materialize for 5 to 7 years. During that period, a large number of companies went bankrupt and were liquidated.
By 2026, the demand for AI will already exist. Nvidia's chips will be in short supply, TSMC's advanced packaging capacity will be completely sold out, and cloud computing leasing prices will be rising rather than falling. Meanwhile, OpenAI will add 400 million weekly active users between March and October 2025. Models will be used.
Computing power is being consumed. Customers are paying. This doesn't mean there's no risk. In fact, the risk is enormous, and I probably think about this issue more often than I'd like to admit it.
There are three points that deserve particular attention.
Capital mismatch risk
By 2026, technology companies will spend more than $650 billion on data centers.
If AI service revenue growth is insufficient to support these investments, many companies will face severe profit margin compression. Even Amazon's free cash flow may turn negative this year.
This is Amazon, the company that practically invented the cloud computing business model.
Supply chain concentration risk
The AI supply chain is highly concentrated.
TSMC produces approximately 70% of the world's chips.
ASML is the sole supplier of EUV lithography machines.
Nvidia designs 92% of AI data center GPUs
Any major shock, such as geopolitical events, natural disasters, or changes in the competitive landscape, could affect the entire AI industry chain.
For example, a major earthquake in Hsinchu, Taiwan, could potentially set back global AI development by several years. This idea should be unsettling.
DeepSeek variables
In January 2025, the Chinese AI lab DeepSeek released a model. Its performance was close to that of state-of-the-art models, but the training cost was only a small fraction of the original.
This challenges a core assumption: that investing more computing power will necessarily lead to better AI.
If the gap between open-source models and high-efficiency models continues to narrow in the future, then the logic of infrastructure investment will be weakened.
I don't think DeepSeek overturned the entire logic of AI investment. But it did introduce a variable that didn't exist before. And once this variable appears, it won't disappear.
But I will always return to a larger framework.
Consulting firms have provided long-term forecasts: McKinsey & Company predicts that global data center investment will reach a cumulative $6.7 trillion by 2030; PwC predicts that AI will contribute $15.7 trillion to global GDP by 2030; and International Data Corporation (IDC) predicts that AI-related solutions will have a cumulative economic impact of $22.3 trillion.
Even if these figures are overstated by 50%, we are still facing the largest technology-driven economic transformation since the internet. The issue is not direction, but scale.
I often hear people say, "I'm skeptical of AI."
sure.
You can question the model's capabilities and the development timeline, but don't ignore the supply chain structure.
These are two completely different things. One is healthy, rational skepticism; the other will make you miss opportunities.
Five years from now, the winners of this cycle will be very clear.
History always follows this pattern. And the key to this game now is: understand the structure before others do.
VII. Participate in the game at the correct level
Imagine AI as a five-layer video game. Each layer is a different level.
Level 1: Energy
This is the beginner tutorial level. It's important, simple, and you'll almost never lose if you play it correctly. Low risk, stable returns.
Just like NPCs in a game: they don't die, but they keep giving rewards.
Level 2: Chip
This is a boss battle. Power is most concentrated, and profits are highest. But at the same time, the technological and geopolitical risks are also the greatest.
The rewards are huge, but the difficulty is on Hard mode.
Level 3: Cloud Computing
This is a multiplayer server where all players are active. Hyperscalers act like server administrators, taking a cut from all transactions.
Level 4: Model
This is the PVP arena. The competition is extremely fierce, and innovation happens at an incredibly fast pace.
Most players will be eliminated; only those with the best equipment will survive.
Level 5: Application
This is an open-world map. The possibilities are endless, but there are no fixed rewards. You have to find the quests yourself.
The real Meta Strategy is simple. You don't need to play through all the levels.
Most people will go for Level 5 because it's the most visible. But right now, the smartest money is grinding for experience in Levels 2 and 3 because that's where the highest returns are at this stage.
Your position in the technology stack determines what you should focus on.
For non-technical people
You don't need to understand how GPUs work. You just need to know that someone has to manufacture GPUs, someone has to build data centers for them, and someone has to power them. And these companies are all publicly traded companies; you can read their financial statements.
For technicians
You already know that models are getting stronger. But you may be underestimating one thing: the real bottlenecks are becoming the physical world: electricity, cooling, and chip packaging. The AI competition of the next decade may be more of an engineering problem than a problem of model architecture in academic papers.
For investors
The AI value chain is actually five different transactions. They differ in risk, timeframe, and winners. Treating AI as an industry is like treating "technology" as an industry in 1998. The internal differences are enormous.
This situation won't last forever. One day, the infrastructure will mature, the application layer will be integrated, and value will shift upwards again.
The same applies to the internet age. Ultimately, the companies that make the most money are Amazon, Google, and Facebook, not fiber optic companies and server manufacturers.
But AI hasn't reached that stage yet. We're still in the infrastructure stage, the stage of selling shovels.
Right now, shovels are making a fortune. Those who understand the complete technology stack will see the signs before the turning point occurs.
Others will be surprised time and time again at where the money went.
Ten years from now, understanding the AI technology stack will be as fundamental as understanding a balance sheet.
Remember three things: Understand the technology stack. Draw the hierarchical structure. Track capital flows.
This is the game.
[Original Link]