【Chinese Concept Stocks Q3 Earnings Series—PDD】
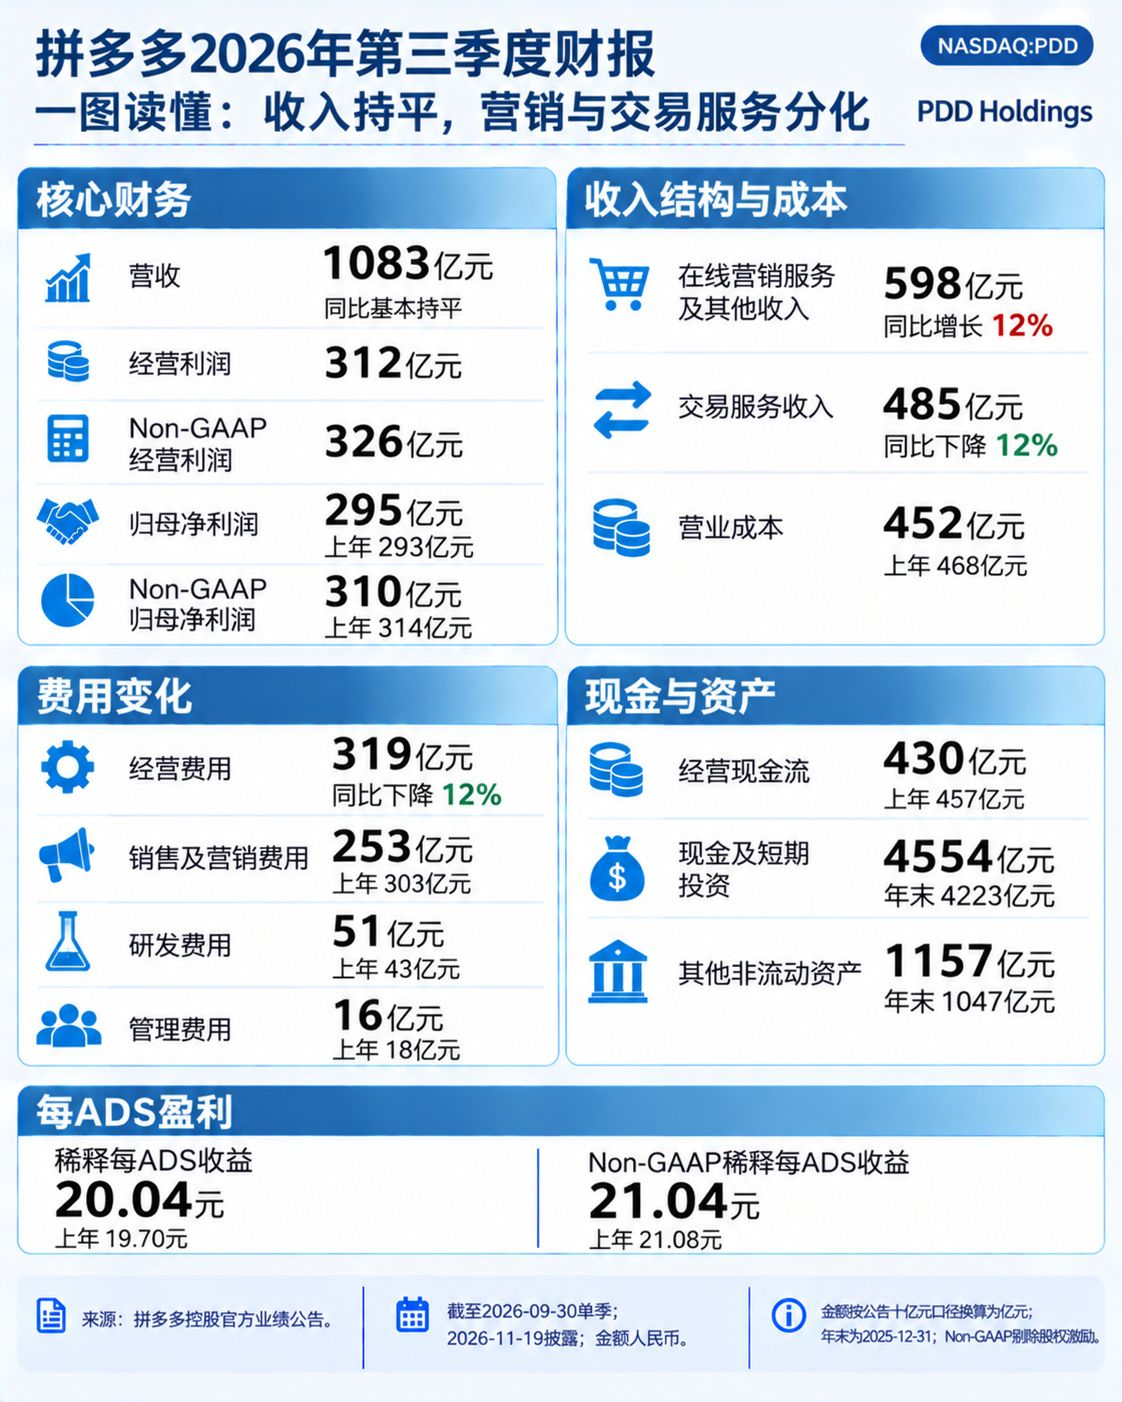
PDD $PDDB reported third-quarter revenue of RMB 108.3 billion, essentially flat year over year. Online marketing revenue was RMB 59.8 billion, up 12%, while transaction services revenue was RMB 48.5 billion, down 12%. A year ago, the figures were RMB 53.3 billion and RMB 54.9 billion, respectively—the increase in one offsetting the decline in the other almost exactly, with revenue shifting further toward merchant advertising. Profit held up on cost cuts: operating costs fell from RMB 46.8 billion to RMB 45.2 billion, marketing expenses were slashed from RMB 30.3 billion to RMB 25.3 billion, and R&D spending rose from RMB 4.3 billion to RMB 5.1 billion. Adjusted net income attributable to shareholders of the parent company was still below last year’s, at RMB 31.0 billion versus RMB 31.4 billion.
The profit saved wasn’t earned. Marketing expenses were cut by RMB 5.0 billion in one go, but while the savings are real, revenue hasn’t picked up. Adjusted net income is already trending down, and operating cash flow also fell from RMB 45.7 billion to RMB 43.0 billion. There’s only one thing to watch going forward: whether the decline in transaction services revenue, at RMB 48.5 billion, narrows. That will determine whether revenue can return to growth; advertising can no longer carry the whole business. The market gave it a thumbs-up.
On earnings day, the stock closed at $86.00, up 11.04%. It was still 31.4% below its 52-week high, and had rebounded 19.5% from its year-to-date low of $71.94. The market is betting that cost cuts will deliver, and that profits can be squeezed out even without revenue growth. That optimism has gone too far: cost savings alone can’t support an 11% re-rating. If the decline in transaction services revenue doesn’t stop in the fourth quarter, the stock won’t hold at this level.
This is only a summary of publicly available earnings information and does not constitute investment advice.
#拼多多 #BStocks #股票财报季
PDD $PDDB reported third-quarter revenue of RMB 108.3 billion, essentially flat year over year. Online marketing revenue was RMB 59.8 billion, up 12%, while transaction services revenue was RMB 48.5 billion, down 12%. A year ago, the figures were RMB 53.3 billion and RMB 54.9 billion, respectively—the increase in one offsetting the decline in the other almost exactly, with revenue shifting further toward merchant advertising. Profit held up on cost cuts: operating costs fell from RMB 46.8 billion to RMB 45.2 billion, marketing expenses were slashed from RMB 30.3 billion to RMB 25.3 billion, and R&D spending rose from RMB 4.3 billion to RMB 5.1 billion. Adjusted net income attributable to shareholders of the parent company was still below last year’s, at RMB 31.0 billion versus RMB 31.4 billion.
The profit saved wasn’t earned. Marketing expenses were cut by RMB 5.0 billion in one go, but while the savings are real, revenue hasn’t picked up. Adjusted net income is already trending down, and operating cash flow also fell from RMB 45.7 billion to RMB 43.0 billion. There’s only one thing to watch going forward: whether the decline in transaction services revenue, at RMB 48.5 billion, narrows. That will determine whether revenue can return to growth; advertising can no longer carry the whole business. The market gave it a thumbs-up.
On earnings day, the stock closed at $86.00, up 11.04%. It was still 31.4% below its 52-week high, and had rebounded 19.5% from its year-to-date low of $71.94. The market is betting that cost cuts will deliver, and that profits can be squeezed out even without revenue growth. That optimism has gone too far: cost savings alone can’t support an 11% re-rating. If the decline in transaction services revenue doesn’t stop in the fourth quarter, the stock won’t hold at this level.
This is only a summary of publicly available earnings information and does not constitute investment advice.
#拼多多 #BStocks #股票财报季