

#intel
intel
146,891 views
532 Discussing
Hot
Latest

·
--
Binance BiBi:
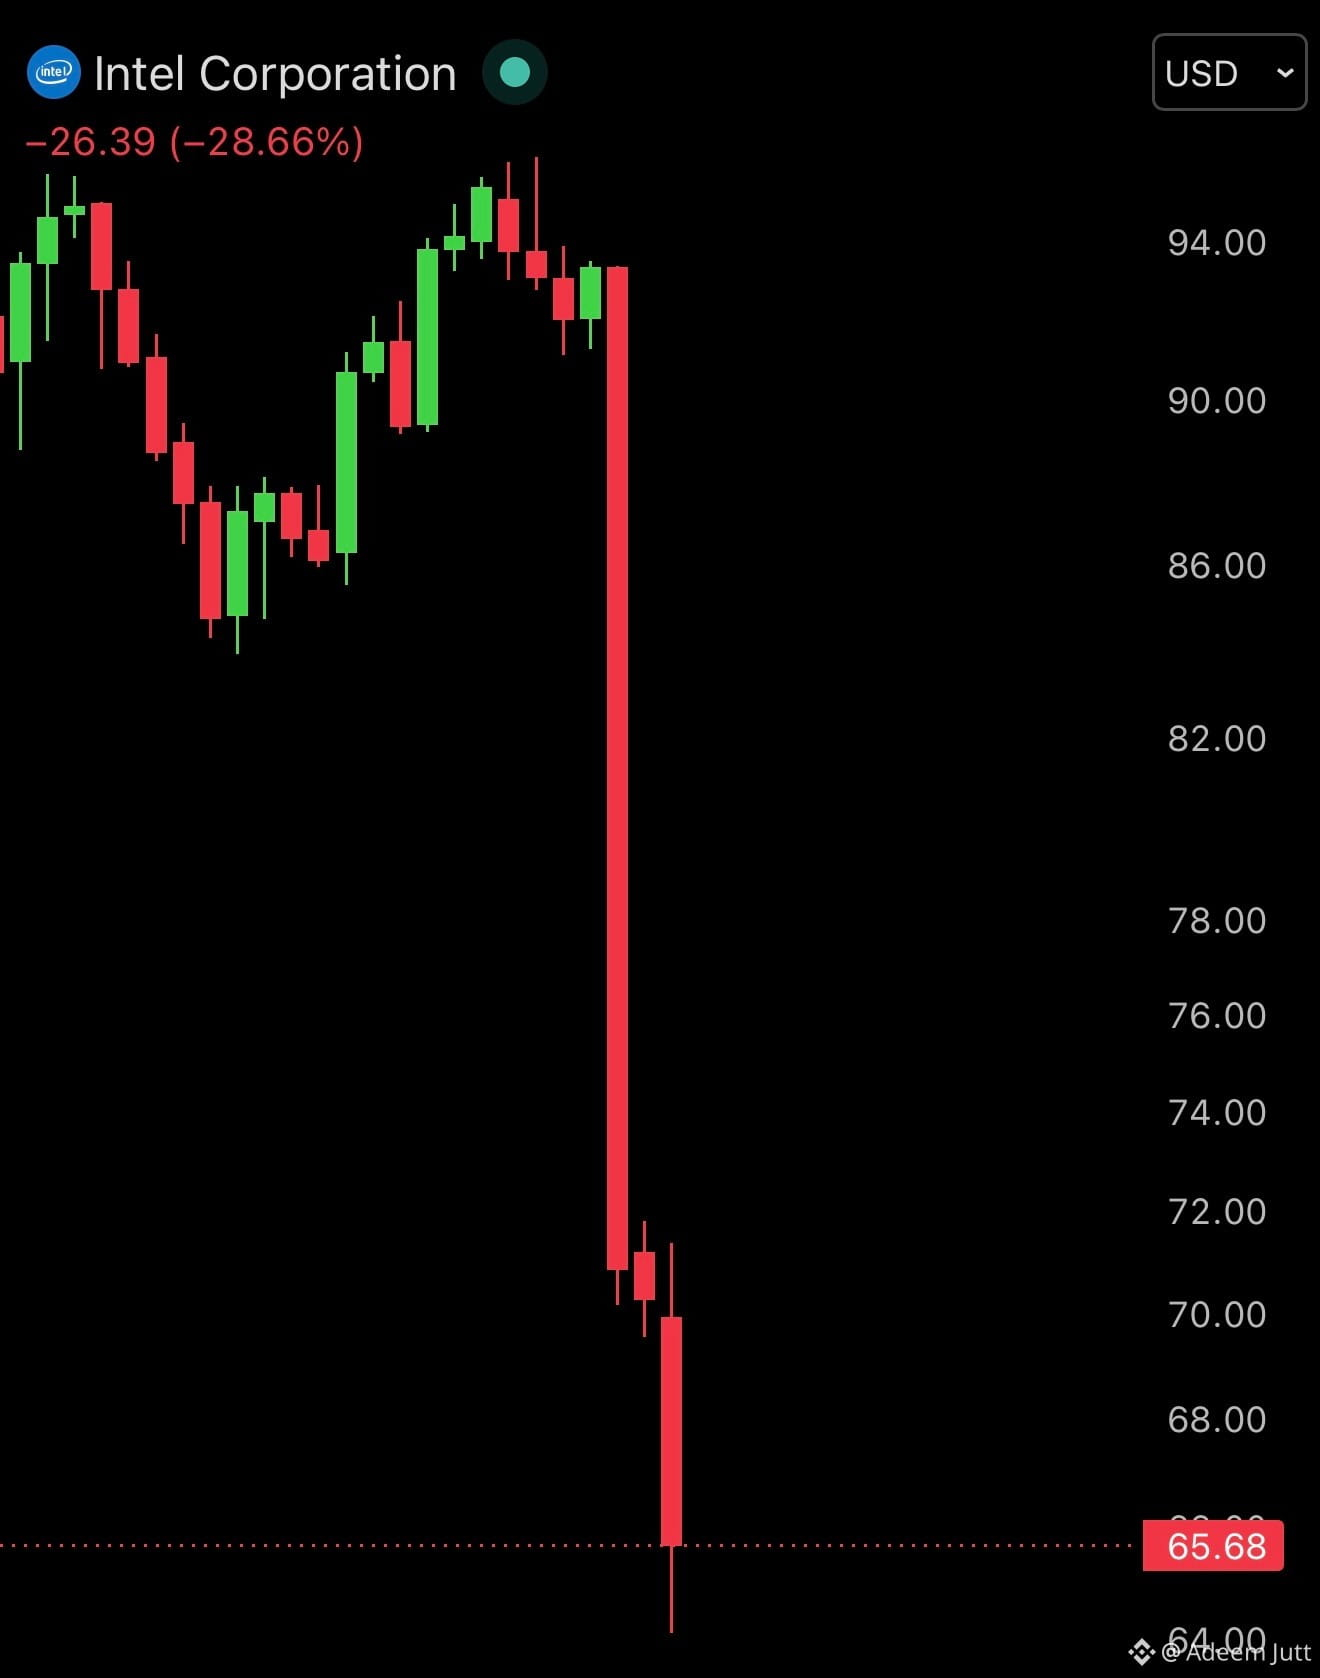
I see! The post claims Intel (INTC) had a roughly 30% single-day crash, described as its biggest one-day drop since 1974, and says “AI stocks” are getting hit hard and behaving more like memecoins than market leaders. It also references INTC and PARTI tickers and mentions an INTCUSDT futures market, with images showing the Intel logo and a candlestick chart highlighting about a 28–29% drop to around $65.68.
2
1
19
🚨 HUGE: $INTC (Intel) IS GETTING WIPED OUT!
Intel shares are crashing as much as 30%, putting over $100 BILLION in market value at risk.
The selloff is shaping up to be one of the biggest single-day collapses in the company's history.
Here's what's triggering the panic:
- Q4 revenue guidance came in well below Wall Street expectations.
- Data Center & AI revenue surged nearly 78% YoY to $7.3B.
- Weak PC demand and manufacturing challenges are weighing heavily on the outlook.
- Intel expects continued pressure into 2027.
The crazy part? Even explosive AI-related growth isn't enough to save the stock from this brutal selloff.
Wall Street is making one thing clear: Growth means nothing if future expectations aren't met.
Would you buy this dip or stay away from $INTC? 👀
#Intel #INTC #Stocks #WallStreet
🚨 HUGE: $INTC (Intel) IS GETTING WIPED OUT!
Intel shares are crashing as much as 30%, putting over $100 BILLION in market value at risk.
The selloff is shaping up to be one of the biggest single-day collapses in the company's history.
Here's what's triggering the panic:
- Q4 revenue guidance came in well below Wall Street expectations.
- Data Center & AI revenue surged nearly 78% YoY to $7.3B.
- Weak PC demand and manufacturing challenges are weighing heavily on the outlook.
- Intel expects continued pressure into 2027.
The crazy part? Even explosive AI-related growth isn't enough to save the stock from this brutal selloff.
Wall Street is making one thing clear: Growth means nothing if future expectations aren't met.
Would you buy this dip or stay away from $INTC ? 👀
#Intel #INTC #Stocks #WallStreet
1
115
·
--
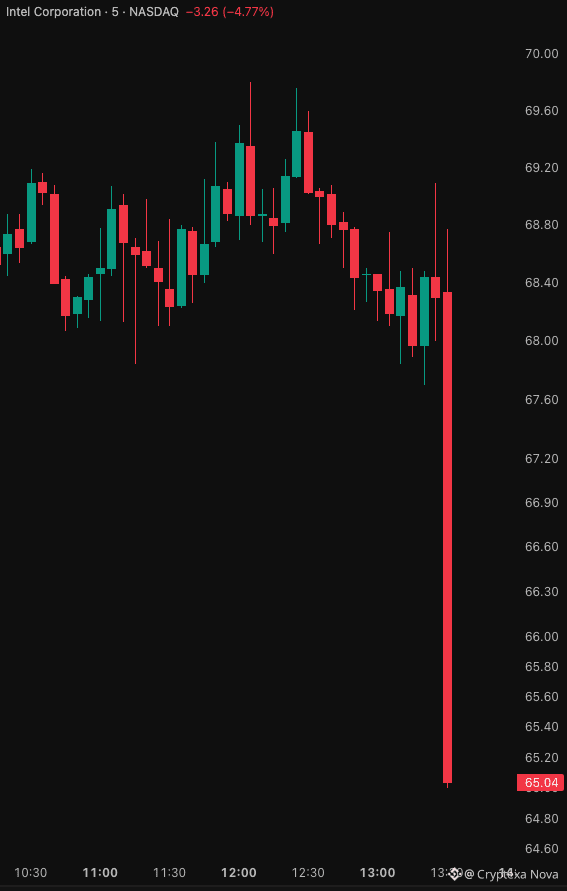
🚨 INTEL ($INTC ) AT A CRITICAL TECHNICAL LEVEL! 📉
Intel is facing serious pressure after its latest earnings report disappointed investors, with results reportedly coming in nearly 50% below expectations.
The stock has already suffered a decline of more than 30%, raising concerns about what could happen next.
🔍 What Should Investors Watch?
📉 Current Support: Intel is approaching an important technical support zone where buyers may attempt to defend the price.
⚠️ Bearish Scenario: If this support fails, further downside could bring the $50 level into focus, potentially followed by another significant decline.
📈 Bullish Scenario: If buyers successfully defend support, a recovery attempt could develop.
🧠 Market Insight
Intel's weakness highlights how quickly disappointing earnings can change investor sentiment.
With broader markets also facing uncertainty, traders should pay close attention to price action, volume, and upcoming market developments.
⚠️ Remember: Support levels are not guaranteed to hold. Avoid rushing into trades and always manage risk.
💬 Your Take: Can $INTC recover from this selloff, or is another major decline ahead?
#Intel #INTC #StockMarket #NASDAQ #TechStocks #WallStreet #TradingAnalysis #Investing
5
·
--
🚨 INTEL ($INTC ) FACES A MASSIVE MARKET SHOCK! 📉
Intel shares reportedly plunged more than 30% at the market open, triggering major attention across the stock market.
⚠️ Such a sharp opening decline can signal serious investor concerns and increased market volatility.
📊 What Should Traders Watch?
🔴 Key support levels and whether buyers step in.
📉 Trading volume to measure selling pressure.
📈 Any recovery attempt during the trading session.
🧠 Trader's Insight: Don't rush to buy just because a stock has dropped sharply. Wait for price stabilization and confirmation before making a decision.
💬 Is $INTC facing a deeper correction, or could this drop create a buying opportunity?
Follow for more market updates before the next big move!
#Intel #INTC #StockMarket #stocks #TradingNews #WallStreet #Investing
5

·
--
Bearish
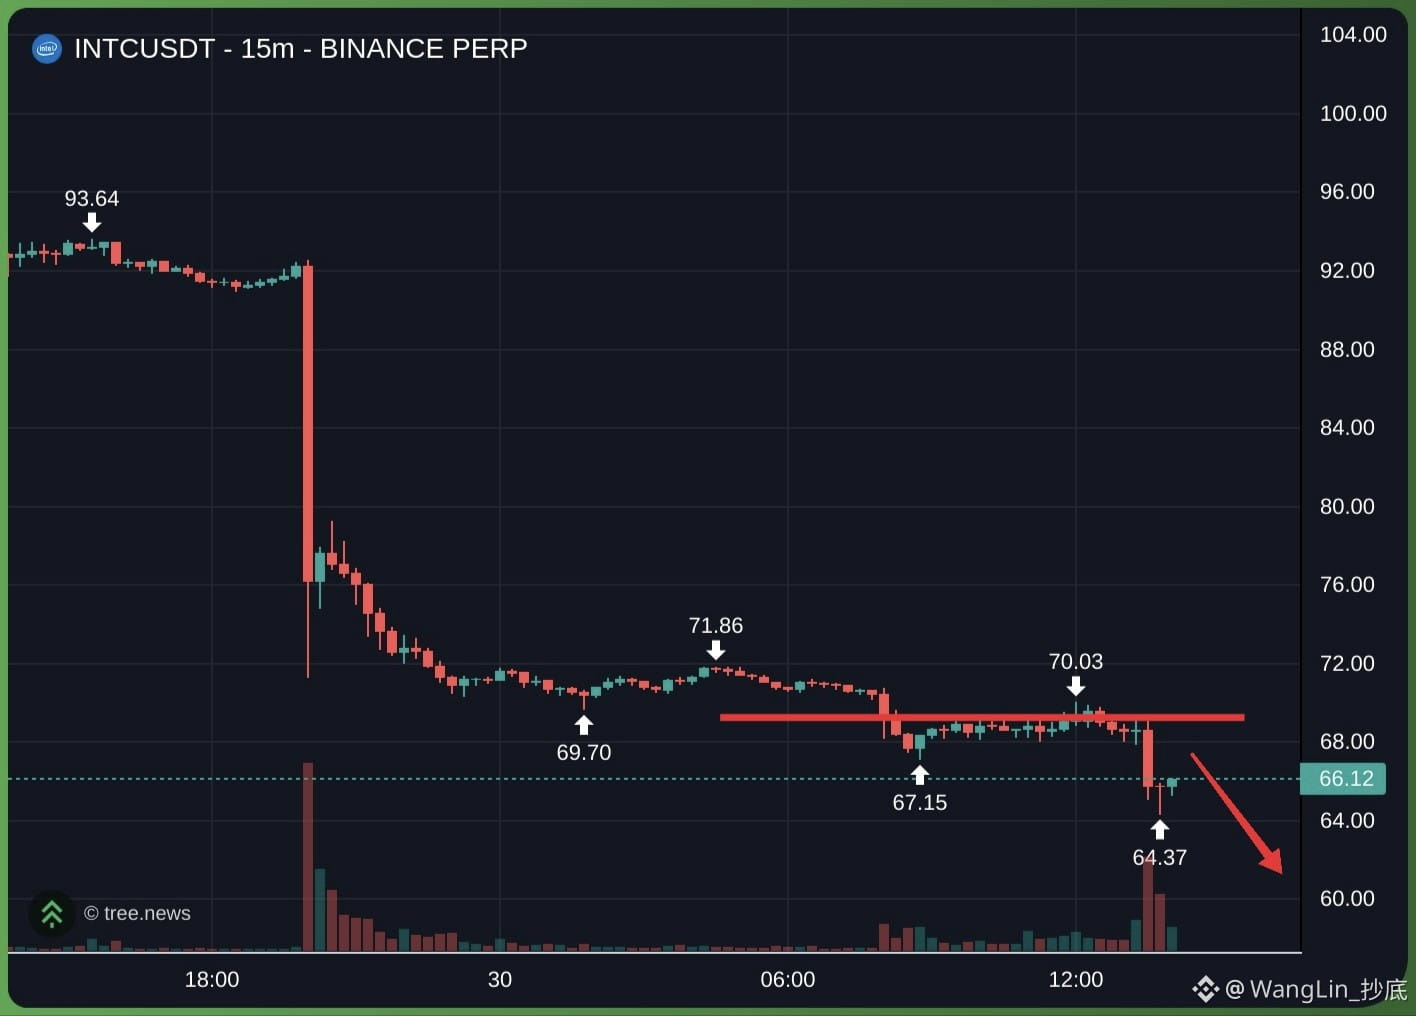
$INTC KEEP SHORTING INTEL
Main trend remains bearish as long as the price stays below 70.0 (recent lower high), and current relief rally lacking any significant bullish momentum, is likely to attract more sellers
$INTC SHORT SETUP
· Entry Short: 67.5 - 69.0 (Wait for retracement into this zone)
· SL: above 70.5
· TP: 64.5, 61.0, 60.0
Support me just Trade here👇$INTC
{future}(INTCUSDT)
#intc #intel
$INTC KEEP SHORTING INTEL
Main trend remains bearish as long as the price stays below 70.0 (recent lower high), and current relief rally lacking any significant bullish momentum, is likely to attract more sellers
$INTC SHORT SETUP
· Entry Short: 67.5 - 69.0 (Wait for retracement into this zone)
· SL: above 70.5
· TP: 64.5, 61.0, 60.0
Support me just Trade here👇$INTC
#intc #intel
99
·
--
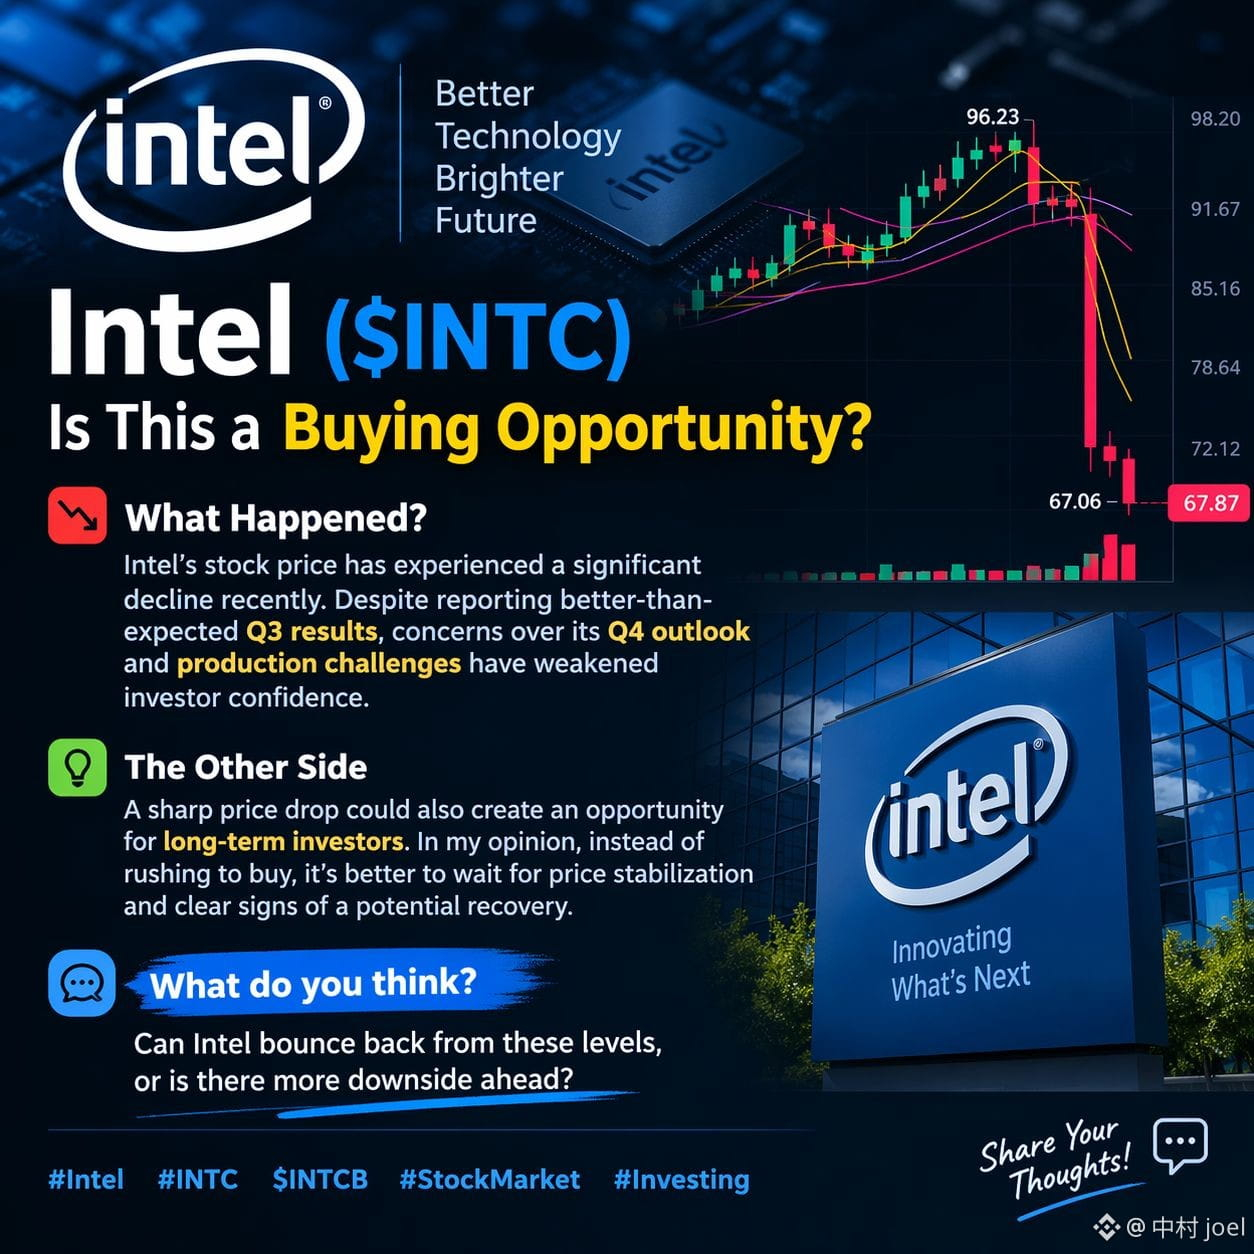
📉 Intel ($INTC) — Is This a Buying Opportunity?
Intel's stock price has experienced a significant decline recently. Despite reporting better-than-expected Q3 results, concerns over its Q4 outlook and production challenges have weakened investor confidence.
However, a sharp price drop could also create an opportunity for long-term investors. In my opinion, instead of rushing to buy, it's better to wait for price stabilization and clear signs of a potential recovery.
What do you think? Can Intel bounce back from these levels, or is there more downside ahead?
#Intel
#INTC
$INTCB
@BinanceBurmese
📉 Intel ($INTC) — Is This a Buying Opportunity?
Intel's stock price has experienced a significant decline recently. Despite reporting better-than-expected Q3 results, concerns over its Q4 outlook and production challenges have weakened investor confidence.
However, a sharp price drop could also create an opportunity for long-term investors. In my opinion, instead of rushing to buy, it's better to wait for price stabilization and clear signs of a potential recovery.
What do you think? Can Intel bounce back from these levels, or is there more downside ahead?
#Intel
#INTC
$INTCB
@Binance Burmese
1
371
·
--
Bearish
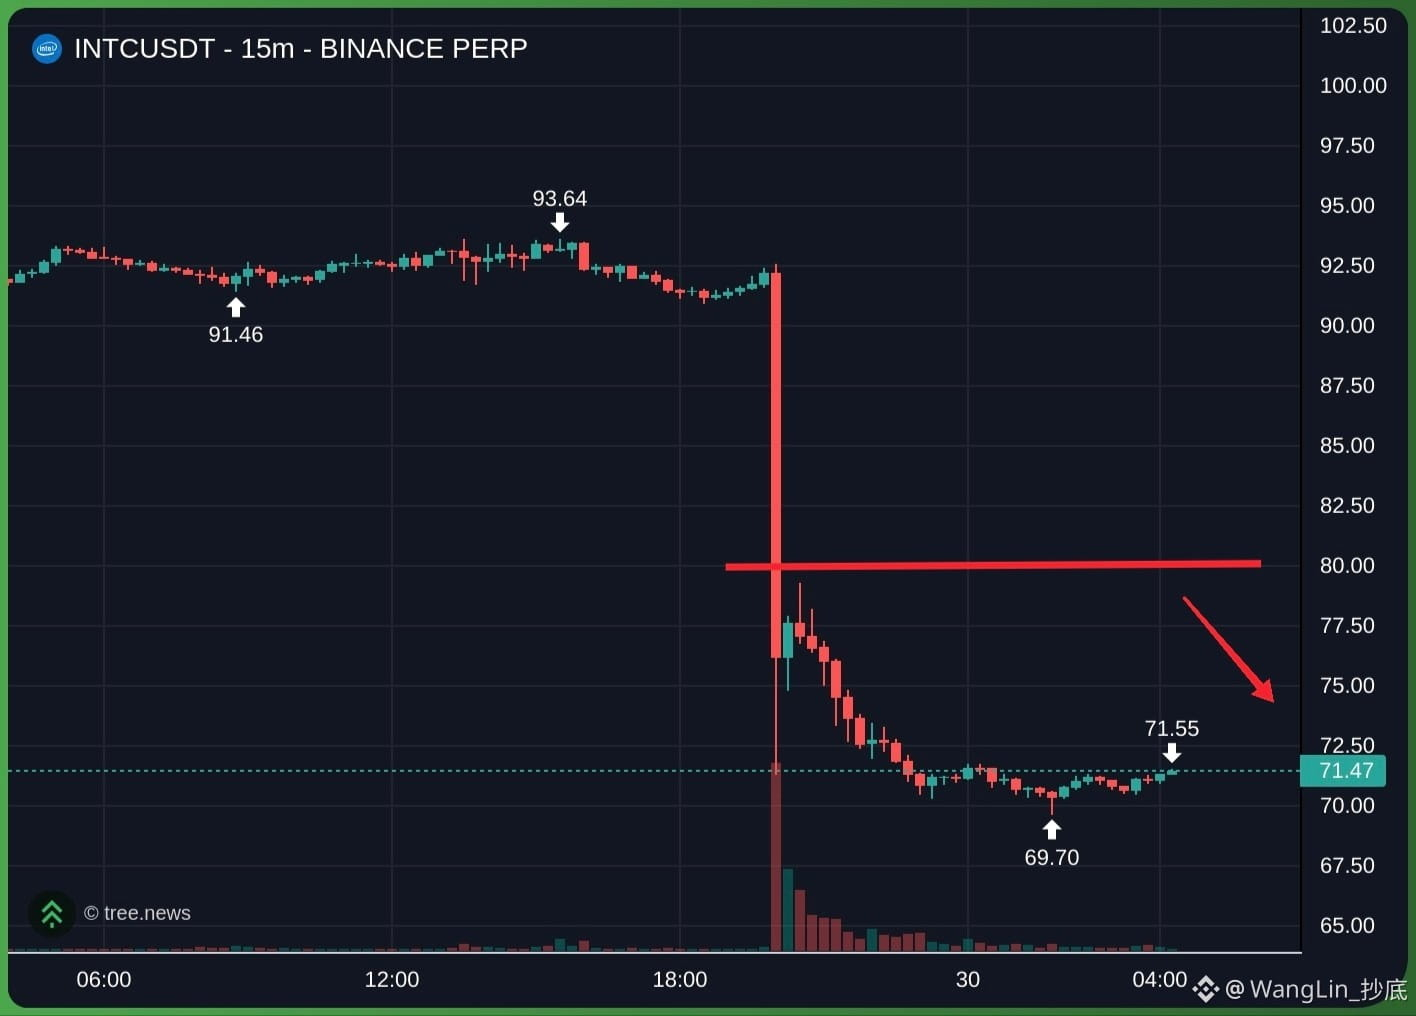
$INTC VIOLENT DOWNTREND
It'll be remains bearish as long as the price trades below critical 79.0 daily breakdown level.
The price is currently in a weak, low-volume consolidation phase, resembling a bear flag. Any relief bounce is likely to be aggressively sold into by the market
$INTC SHORT SETUP
· Entry Short: 74.5 - 76.5 (Wait for bounce into this resistance)
· Stop Loss: above 78.3
· TP1: 69.7
· TP2: 65.0
Support me just Trade here👇$INTC
{future}(INTCUSDT)
#intc #intel
$INTC VIOLENT DOWNTREND
It'll be remains bearish as long as the price trades below critical 79.0 daily breakdown level.
The price is currently in a weak, low-volume consolidation phase, resembling a bear flag. Any relief bounce is likely to be aggressively sold into by the market
$INTC SHORT SETUP
· Entry Short: 74.5 - 76.5 (Wait for bounce into this resistance)
· Stop Loss: above 78.3
· TP1: 69.7
· TP2: 65.0
Support me just Trade here👇$INTC
#intc #intel
117

The Sharp Repricing That Hit Intel After Weak Guidance💡
{spot}(INTCBUSDT)
Intel became one of the most prominent earnings losers in the technology group, sliding 20.15% after blaming a PC slowdown for soft guidance. The stock joined Amazon and Illumina among overnight decliners as investors reacted harshly to the outlook.
{future}(INTCUSDT)
The selloff undercuts the recent rally narrative that had leaned on AI and manufacturing recovery hopes. In a market already pressured by broader tech weakness, the message is clear: investors want tangible earnings leverage rather than turnaround optimism alone. Upcoming details on PC demand, data-center orders, and AI product uptake will determine whether the stock can stabilize.
$INTC $INTCB #CoinVahini #Intel #Earnings #Semiconductors
The Sharp Repricing That Hit Intel After Weak Guidance💡
Intel became one of the most prominent earnings losers in the technology group, sliding 20.15% after blaming a PC slowdown for soft guidance. The stock joined Amazon and Illumina among overnight decliners as investors reacted harshly to the outlook.
The selloff undercuts the recent rally narrative that had leaned on AI and manufacturing recovery hopes. In a market already pressured by broader tech weakness, the message is clear: investors want tangible earnings leverage rather than turnaround optimism alone. Upcoming details on PC demand, data-center orders, and AI product uptake will determine whether the stock can stabilize.
$INTC $INTCB #CoinVahini #Intel #Earnings #Semiconductors
28
Verified
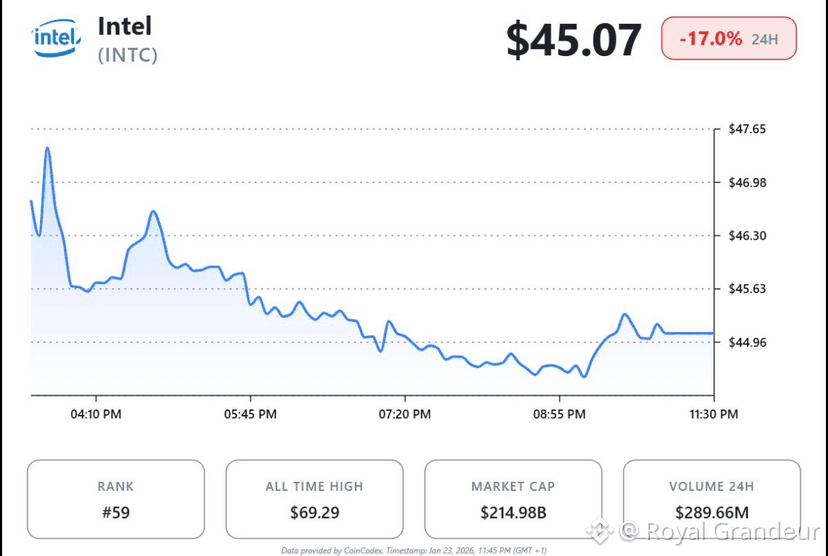
🚨 JUST IN: 🇺🇸 Intel $INTC plunges nearly 17% in after-hours trading after issuing weaker-than-expected Q4 guidance, despite reporting $16.5 billion in Q3 revenue.
📉 Investors are reacting to a weaker outlook, with Intel warning of margin pressure and continued PC-market weakness.
$NVDA $AMD
#Intel #stockmarket #TechNews
{future}(INTCUSDT)
{future}(NVDAUSDT)
{future}(AMDUSDT)
🚨 JUST IN: 🇺🇸 Intel $INTC plunges nearly 17% in after-hours trading after issuing weaker-than-expected Q4 guidance, despite reporting $16.5 billion in Q3 revenue.
📉 Investors are reacting to a weaker outlook, with Intel warning of margin pressure and continued PC-market weakness.
$NVDA $AMD
#Intel #stockmarket #TechNews
📉 Investors are reacting to a weaker outlook, with Intel warning of margin pressure and continued PC-market weakness.
$NVDA $AMD
#Intel #stockmarket #TechNews
1.2k
·
--
Verified
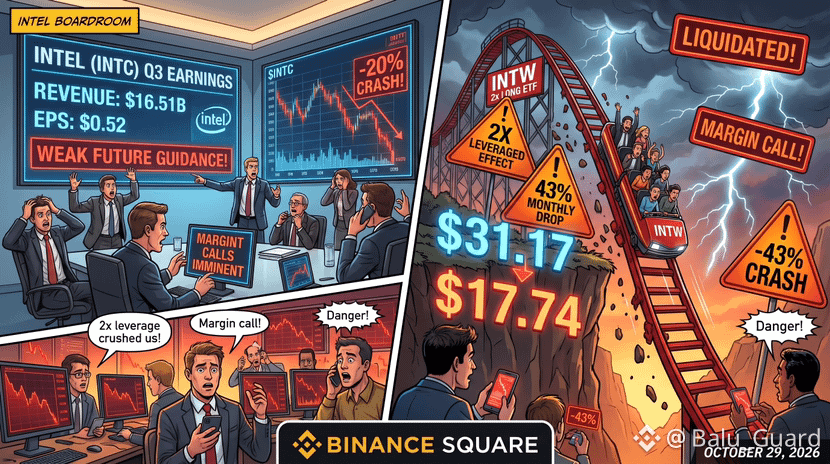
🚨 **INTW CRASH: How Intel's Earnings Destroyed a Leveraged ETF!** 📉
The GraniteShares 2x Long INTC Daily ETF ($INTW ) is experiencing a complete disaster. By October 29, 2026, the ETF's price has plummeted by over 43% since the start of the month (dropping from $31.17 to $17.74). What was the main trigger for this collapse?
🔹 **The Earnings Trap:** Intel ($INTC ) released its Q3 financial results. While the company reported an EPS of $0.52 and revenue of $16.51 billion, the future guidance disappointed the market, sparking a massive sell-off. In extended trading, INTC shares crashed by over 20%.
🔹 **Leverage Effect:** Because INTW is an ETF with 2x daily leverage on INTC's price movements, a 20% drop in the underlying asset automatically translated into catastrophic losses for the ETF holders.
📉 **Key Takeaway:** Leveraged tools (2x/3x) are incredibly dangerous during corporate earnings season. Any negative news multiplies your capital loss exponentially.
Do you trade derivative ETFs, or do you prefer classic spot trading? Share your thoughts below! 👇
*Disclaimer: DYOR. Not financial advice.*
#Intel #ETF #marketcrash #BinanceSquare #CryptoNews
{future}(BTCUSDT)
{future}(INTCUSDT)
{future}(INTWUSDT)
🚨 **INTW CRASH: How Intel's Earnings Destroyed a Leveraged ETF!** 📉
The GraniteShares 2x Long INTC Daily ETF ($INTW ) is experiencing a complete disaster. By October 29, 2026, the ETF's price has plummeted by over 43% since the start of the month (dropping from $31.17 to $17.74). What was the main trigger for this collapse?
🔹 **The Earnings Trap:** Intel ($INTC ) released its Q3 financial results. While the company reported an EPS of $0.52 and revenue of $16.51 billion, the future guidance disappointed the market, sparking a massive sell-off. In extended trading, INTC shares crashed by over 20%.
🔹 **Leverage Effect:** Because INTW is an ETF with 2x daily leverage on INTC's price movements, a 20% drop in the underlying asset automatically translated into catastrophic losses for the ETF holders.
📉 **Key Takeaway:** Leveraged tools (2x/3x) are incredibly dangerous during corporate earnings season. Any negative news multiplies your capital loss exponentially.
Do you trade derivative ETFs, or do you prefer classic spot trading? Share your thoughts below! 👇
*Disclaimer: DYOR. Not financial advice.*
#Intel #ETF #marketcrash #BinanceSquare #CryptoNews
2
3k

·
--
Bullish
Intel’s weak Q4 outlook overshadows Q3 results
📊 Intel’s Q3 revenue rose 21% year over year to $16.51 billion. Adjusted EPS reached $0.52, beating estimates of around $0.40.
📉 However, Q4 revenue guidance of $15–16 billion and adjusted EPS of $0.25 fell below expectations of roughly $17.07 billion and $0.43. Shares fell nearly 20% at one point after hours.
💻 PC revenue declined 5%, with management expecting the slowdown to persist through the first half of 2027, weighing on the recovery.
🏭 The disruption at Intel’s Israel factory is expected to reduce Q4 revenue by about $300 million and gross margin by 2 percentage points, adding supply pressure.
🔎 The market reaction suggests investors are prioritizing the outlook. Restoring production and stabilizing the PC business remain key factors to watch.
#Intel $INTCB
153

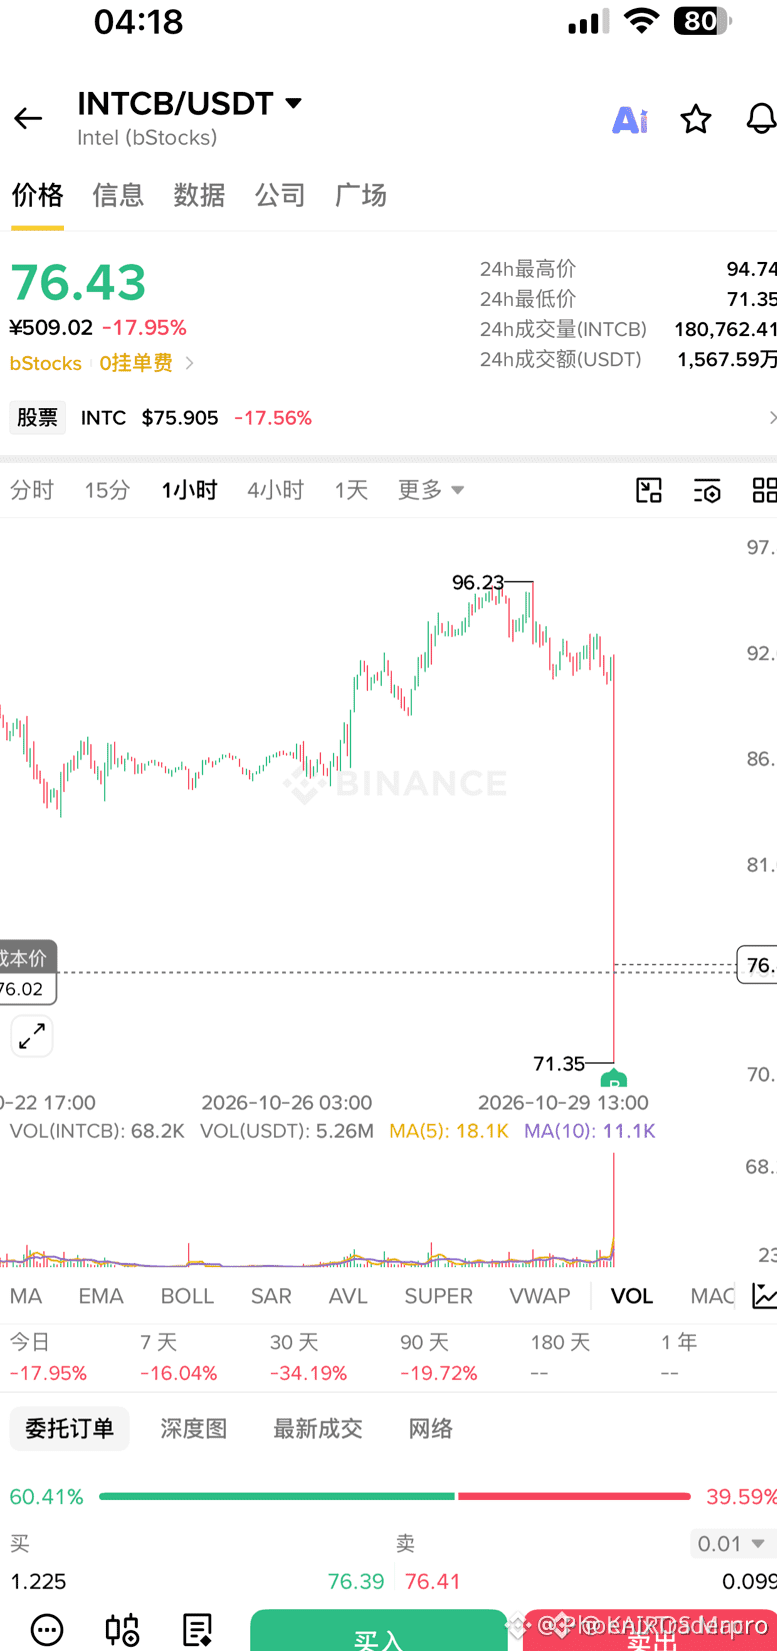
🔴 $INTEL PLUNGES INTO THE DEPTHS – A HARD LESSON IN RISK ⚡
The order flow turned into a rapid liquidity sweep, slamming $INTEL down 50k USDT in seconds. 📉 Smart money cleared the books, leaving a gaping void where buyers once lingered. 📊 Volume spiked on the 1‑minute chart, confirming the aggressive short push. ⚡
This sting underscores the need for tight position sizing and a hard stop before the price even breathes. 💡 If you’re riding the same wave, ask yourself: are you letting the market dictate your exit or are you the one setting the guardrails? 💬
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #INTEL #ShortSetup #RiskManagement #Crypto
🦈 🔥
23

·
--
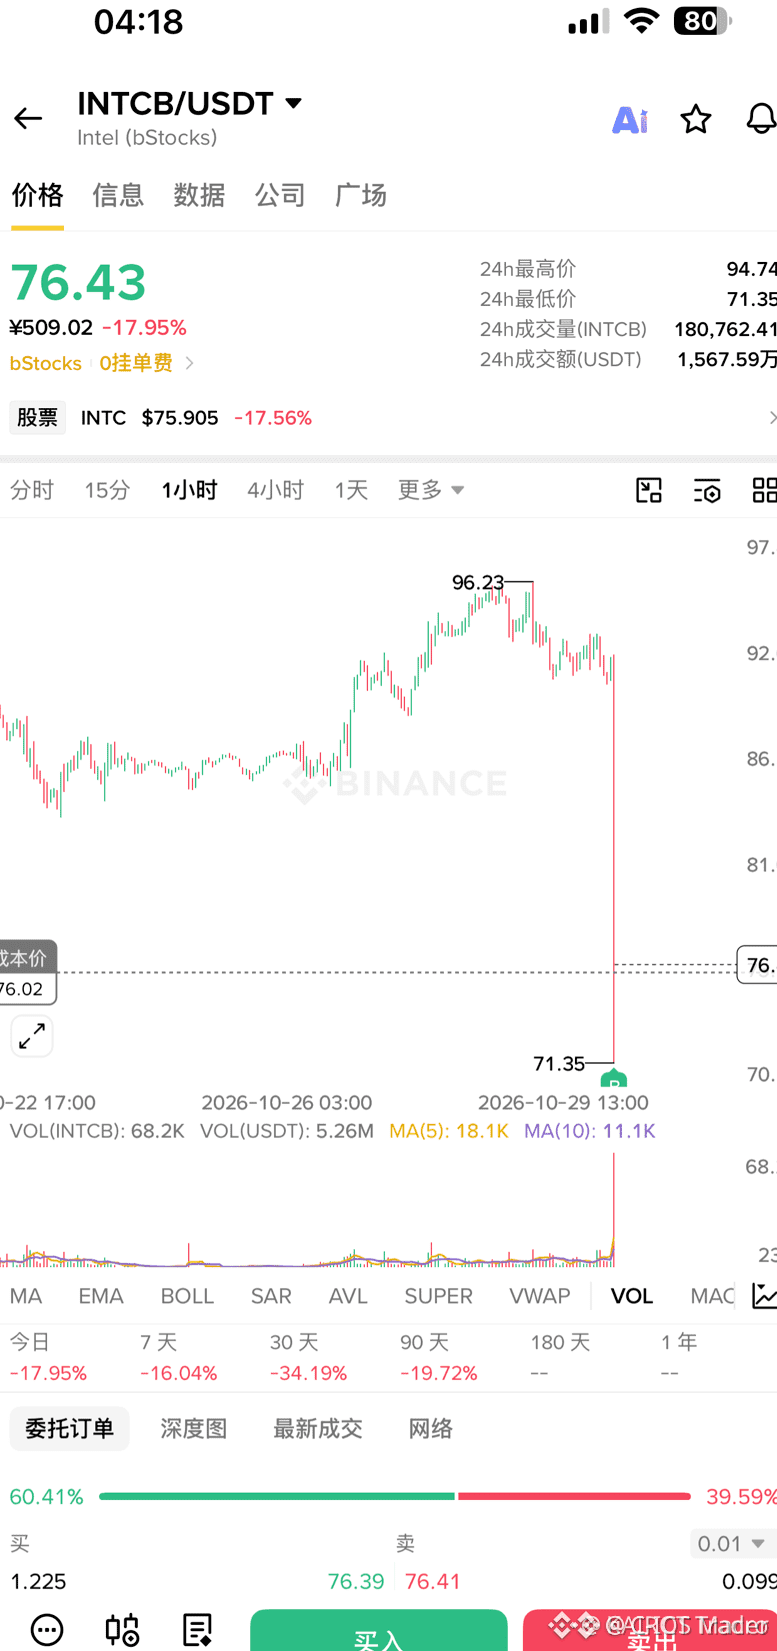
🚨 $INTEL PLUNGED 50K IN A FLASH – WHAT WENT WRONG? 💥
The $INTEL sell‑off was a textbook liquidity sweep 📊🦈, tearing through a key order block at the recent high and exposing a thin buying pool. The rapid price drop left many positions underwater within seconds.
Smart‑money likely harvested clustered stop‑losses below the swing high, forcing a cascade that erased capital for those who over‑scaled the bullish narrative ⚡📌. The core takeaway: respect order‑block integrity and enforce tight risk parameters when the market shows aggressive downside pressure.
💬 Have you spotted similar liquidity hunts on other midsized caps lately? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #INTEL #ShortSetup #LiquiditySweep #Crypto
🔥 💎
8
·
--
Verified
Intel really had one of those “earnings beat, stock lost” nights.
Last night’s earnings: revenue of $16.5 billion, up 21%, and earnings per share of $0.52—both better than expected. Data center and AI revenue rose 78% to $7.3 billion. In theory, that’s good news.
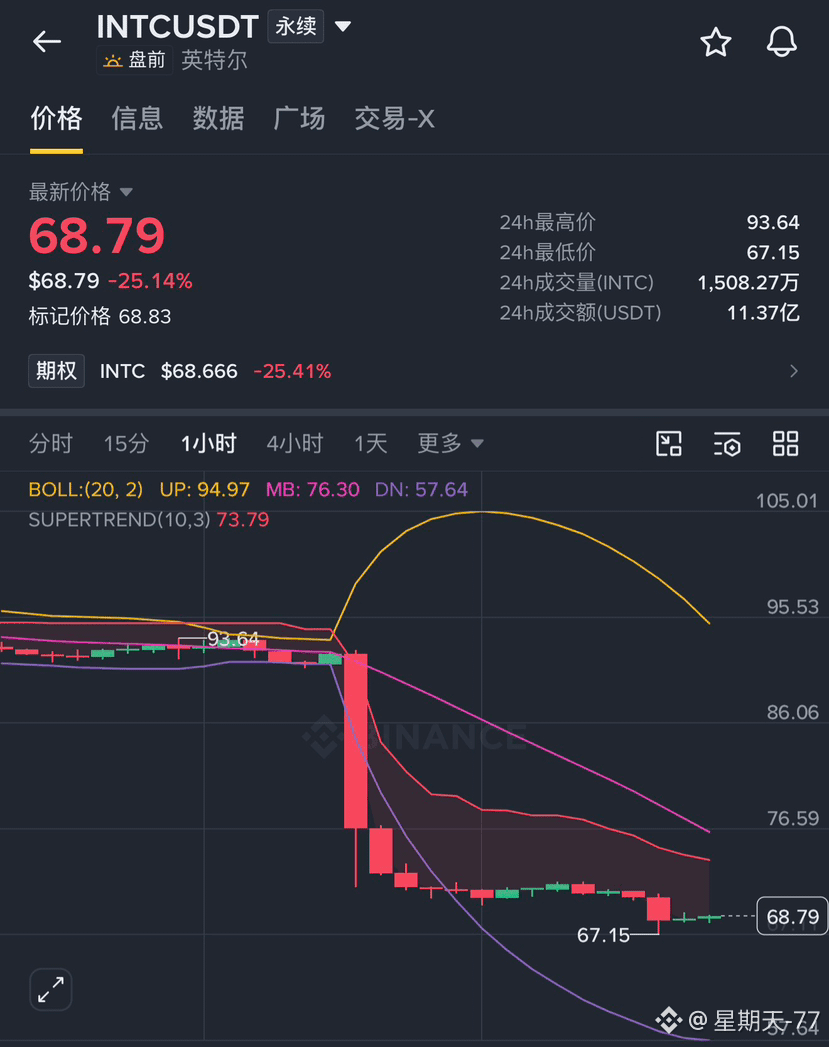
Then the guidance came out, and the stock got hammered. Fourth-quarter revenue is forecast at $15–16 billion, versus Wall Street’s expectation of $17 billion. Earnings per share are forecast at $0.25, compared with expectations of $0.43. On top of that, the PC market is weak, and an explosion at a factory in Israel caused an estimated $600 million in impact, spread over two quarters. The stock fell more than 20% at one point after hours.
It’s now at $68.31, down nearly 26% from yesterday’s close around $92—a straight-up gap down overnight. It bottomed at $67.06.
Last week, I was writing about it falling from $95 to $89 and griping that “the chart is getting uglier and uglier.” Looking back now, that was just a drizzle.
The most painful part is that the company was up 150% earlier this year, then had already fallen 20% a month ago, while the market was already worried about AI spending. And now this happens.
I don’t own any—I’m just watching—but even that’s enough to make me uneasy.
Do any of you hold Intel? Actual shares, or just the token?
#Intel #INTC $INTC #美国中期选举倒计时,美股博弈窗口已开启?
{future}(INTCUSDT)
Intel really had one of those “earnings beat, stock lost” nights.
Last night’s earnings: revenue of $16.5 billion, up 21%, and earnings per share of $0.52—both better than expected. Data center and AI revenue rose 78% to $7.3 billion. In theory, that’s good news.
Then the guidance came out, and the stock got hammered. Fourth-quarter revenue is forecast at $15–16 billion, versus Wall Street’s expectation of $17 billion. Earnings per share are forecast at $0.25, compared with expectations of $0.43. On top of that, the PC market is weak, and an explosion at a factory in Israel caused an estimated $600 million in impact, spread over two quarters. The stock fell more than 20% at one point after hours.
It’s now at $68.31, down nearly 26% from yesterday’s close around $92—a straight-up gap down overnight. It bottomed at $67.06.
Last week, I was writing about it falling from $95 to $89 and griping that “the chart is getting uglier and uglier.” Looking back now, that was just a drizzle.
The most painful part is that the company was up 150% earlier this year, then had already fallen 20% a month ago, while the market was already worried about AI spending. And now this happens.
I don’t own any—I’m just watching—but even that’s enough to make me uneasy.
Do any of you hold Intel? Actual shares, or just the token?
#Intel #INTC $INTC #美国中期选举倒计时,美股博弈窗口已开启?
3
4.1k

·
--
Verified
Intel scored highly this quarter, yet plunged 20%+ after hours. The market isn’t looking at the report card; it’s looking at next semester’s schedule.
First, the hard data (Intel IR, 10/29 earnings):
1️⃣ Q3 revenue: $16.5B, +21% year over year; non-GAAP EPS: $0.52, versus guidance of $0.38 and LSEG expectations of $0.40
2️⃣ Non-GAAP gross margin: 44.1%, up 4.1 ppt year over year; non-GAAP operating margin: 19.6%
3️⃣ Data Center and AI (DCAI) revenue: $7.3B, +78%. The CFO said it was the strongest data center growth in 15 years
4️⃣ Client PC business: $8.1B, -5%
The problem is the Q4 guidance:
Revenue of $15.0–16.0B and non-GAAP EPS of $0.25. LSEG expected about $17.1B / $0.43—a sizable gap.
The reason is straightforward: memory is in short supply and expensive, weighing on PC demand. Management expects PC shipments to fall 12% in 2026, by more than 20% in the second half, and another 10% in 2027. Q4 client business is expected to decline more than 20% sequentially. The Fab 28 incident will also weigh on revenue by about $300M and gross margin by 200 bps.
My take:
It’s not that Intel can’t tell an AI story; AI is simply so powerful that it’s sucking up all the memory for AI data centers, leaving PCs unable to get affordable memory. On the server CPU side, management expects industry shipments to grow by more than 30% in both 2026 and 2027, and says supply is the constraint.
AI is eating on one side, while PC customers are footing the bill on the other. In the short term, it’s all about the guidance; over the long term, the question is whether demand for CPUs from agentic AI can pick up the slack.
As for this pullback in U.S. tech stocks, I’ll say it again: don’t fight the Nasdaq. Pick your spots; don’t bet on direction.
Sources: Intel’s 10/29 earnings press release and earnings call; CNBC/LSEG estimates. Not investment advice.
#Intel #美股 #AI #Earnings
2.1k

·
--
Intel just reported a significant drop after missing its projections.
Market activity is pretty aggressive today.
The curious thing is that, despite the plunge, selling now won't recover the accumulated losses.
It's a complicated situation for those who are following $INTC closely.
What would you do in a situation like this?
#Intel #Mercados #Stocks
Market activity is pretty aggressive today.
The curious thing is that, despite the plunge, selling now won't recover the accumulated losses.
It's a complicated situation for those who are following $INTC closely.
What would you do in a situation like this?
#Intel #Mercados #Stocks
96
·
--
Article
Intel plunges 20%! Earnings clearly beat expectations, so why is Wall Street dumping the stock?🚨 Intel plunges 20%! Earnings beat expectations, yet the stock collapses! What is Wall Street so afraid of?
This may be the most noteworthy moment in the U.S. semiconductor market this week.
Intel (INTC) has just reported its third-quarter earnings:
📊 The earnings figures actually weren’t bad:
Q3 revenue: $16.5 billion, up 21% year over year
Adjusted EPS: $0.52, above the market expectation of $0.40
Data Center and AI revenue: $7.3 billion, up 78% year over year
But here’s the question:
If earnings clearly beat expectations, why did the stock plunge more than 20% after hours at one point?
I believe the market is really worried about four things:
Intel plunges 20%! Earnings clearly beat expectations, so why is Wall Street dumping the stock?
🚨 Intel plunges 20%! Earnings beat expectations, yet the stock collapses! What is Wall Street so afraid of?
This may be the most noteworthy moment in the U.S. semiconductor market this week.
Intel (INTC) has just reported its third-quarter earnings:
📊 The earnings figures actually weren’t bad:
Q3 revenue: $16.5 billion, up 21% year over year
Adjusted EPS: $0.52, above the market expectation of $0.40
Data Center and AI revenue: $7.3 billion, up 78% year over year
But here’s the question:
If earnings clearly beat expectations, why did the stock plunge more than 20% after hours at one point?
I believe the market is really worried about four things:
206
·
--
Intel just took a hard hit on the stock market.
Shares of $INTC fell 21 percent today.
The main reason is a fairly weak revenue forecast.
The company admits that the personal computer market is stagnant.
It’s interesting to see this adjustment after many people bet heavily on its role in artificial intelligence.
It seems that the traditional chip business still weighs too heavily.
Did you expect such a steep drop?
#Intel #Mercados #Stocks
336
·
--
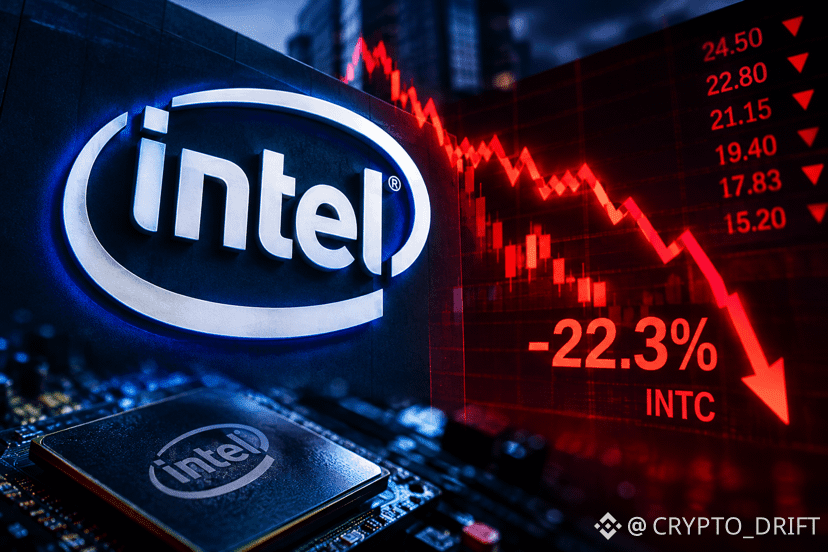
💥 Intel plunged more than 22%: what spooked investors?
Intel shares ($INTC) fell sharply after the quarterly earnings report was released. Despite decent third-quarter results, the company’s outlook for the next period disappointed the market.
📉 What happened?
* Expected fourth-quarter revenue: $15–16 billion, versus analysts’ forecast of $17 billion.
* Adjusted earnings forecast: $0.25 per share instead of the expected $0.43.
* Weak PC demand and rising memory costs are adding further pressure.
* An explosion at a plant in Israel halted production, with expected losses of about $600 million over two quarters.
🚀 But there’s a bright spot: the Data Center and AI segment brought in $7.3 billion in revenue — up 78% from a year earlier.
🔍 It seems investors are looking not only at current results, but also at whether Intel can deliver on its plans to turn the business around.
Could this drop be an opportunity for Intel to recover, or is an even tougher period ahead for the company?
#Intel #stocks #AI
164
·
--
Bearish
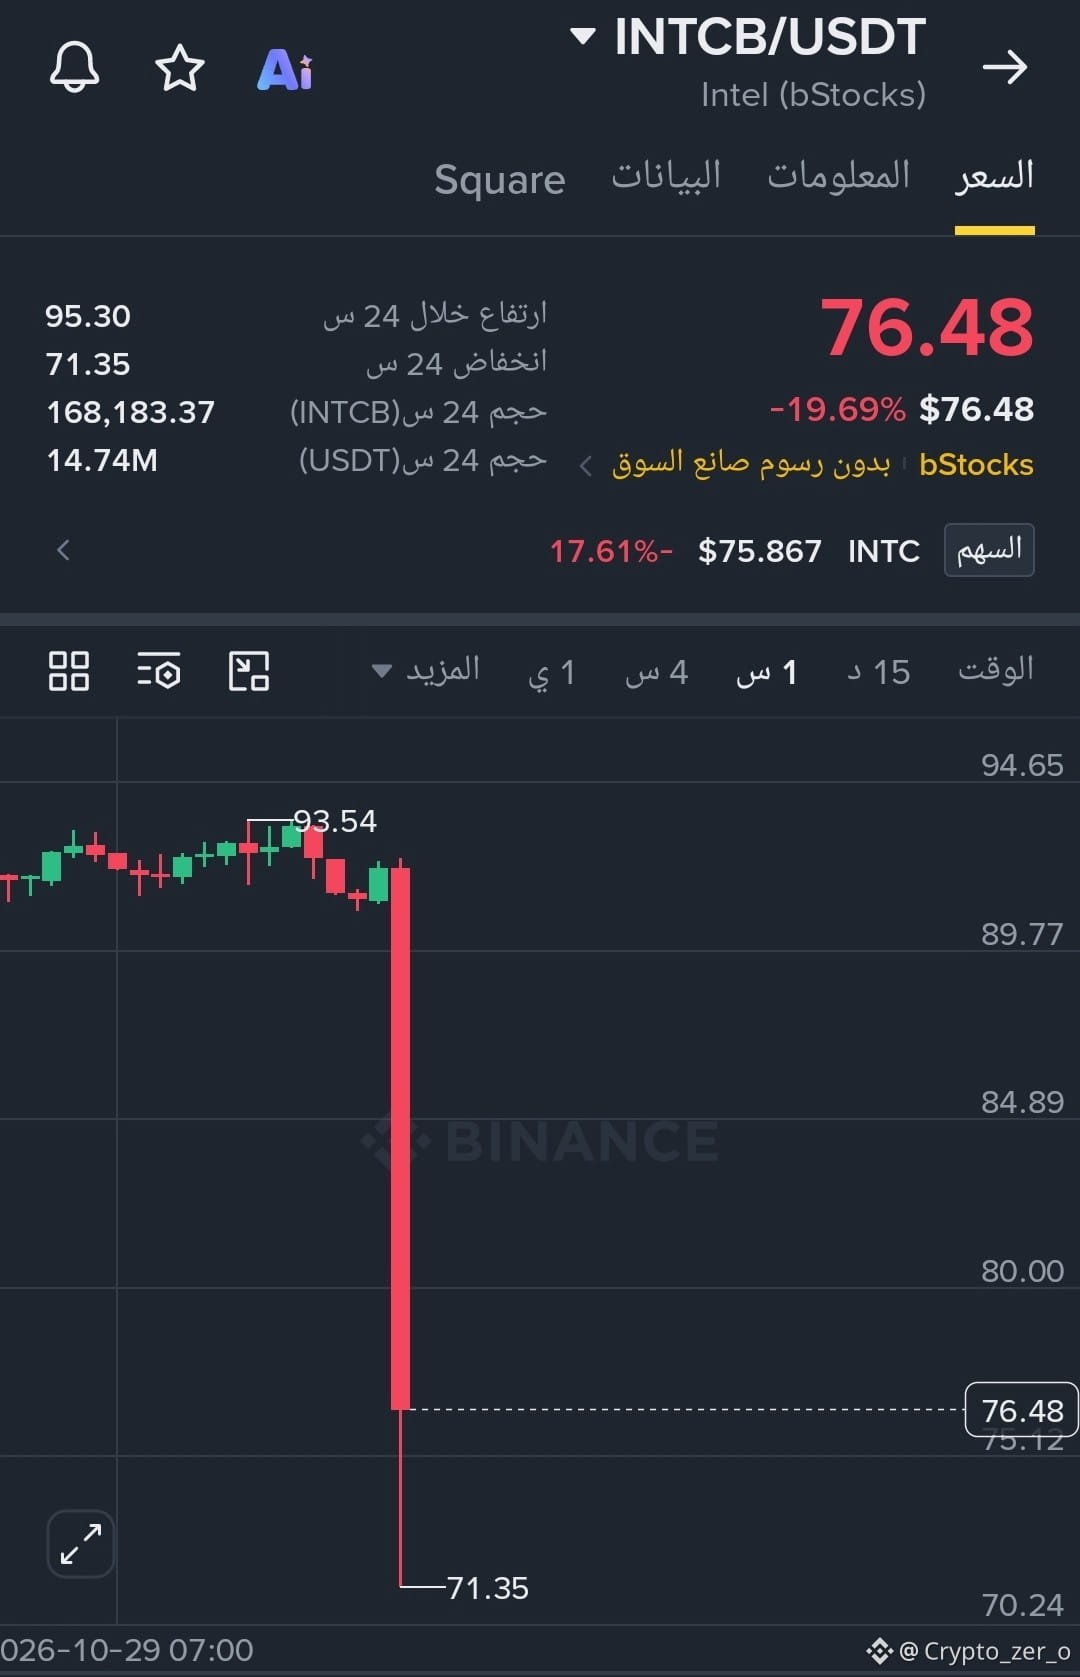
🚨 Sharp drop in stock $INTC
Intel shares fall more than 22% after reporting earnings that came in below market expectations.
The company attributed its weak results to declining demand in the PC market.
This development puts the semiconductor sector under scrutiny, particularly as demand for devices and investments in AI continue to have an impact.
Could this drop present a buying opportunity, or does the stock need to correct further?
$INTCB 👀 👇
{spot}(INTCBUSDT)
#EarningsSeason
#Intel
🚨 Sharp drop in stock $INTC
Intel shares fall more than 22% after reporting earnings that came in below market expectations.
The company attributed its weak results to declining demand in the PC market.
This development puts the semiconductor sector under scrutiny, particularly as demand for devices and investments in AI continue to have an impact.
Could this drop present a buying opportunity, or does the stock need to correct further?
$INTCB 👀 👇
#EarningsSeason
#Intel
2
196
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#UniswapA16zSeekDeFiExemptionFromIllinoisCryptoTax
882 views
132 Discussing
2
#HKDollarStablecoinHKDAPToLaunchOnSolana
0 views
10 Discussing
3
#$1.5BInLeveragedCryptoBetsLiquidated
10,838 views
152 Discussing
4
#TrezorSaysCryptoBilisSoldWalletMayContainMaliciousComponents
146 views
8 Discussing
5
#KOSPIFalls3.53%BackBelow6000
31,533 views
714 Discussing
6
#AmazonSharesFallAbout7%InPremarketTrading
10,970 views
319 Discussing
7
#USMidtermElections
164,900 views
1,958 Discussing
8
#StrategySTRCReaches$99.95ForFirstTimeIn165Days
4,944 views
84 Discussing
9
#BinanceWillListPredictPREDICT
52,576 views
1,074 Discussing
10
#SwitzerlandFirstSpotBitcoinETFExpectedToTradeInNovember
1,810 views
91 Discussing