

Powerpei
1.3k Posts
Powerpei
 Square Verified+
Report
Block User
独立开发者
DeFi基础设施 & AI交易工具深度分析
自研Web3资产监控软件
美股港股实战洞见
X:@PWenzhen76938 没有任何小号,请勿上当!
Open Trade

BNB Holder
Occasional Trader
3.2 Years
1.2K+ Following
42.0K+ Followers
34.7K+ Liked
Posts
Portfolio
All
Quotes
Videos
Live
PINNED
·
--
I joined Binance Square in November last year.
Back then, I saw Yingge promoting the Creator Platform, so I hopped on.
I have to say, Yingge is kind of my benefactor.
I should say she’s a benefactor for a lot of small retail investors. Everyone who knows her knows she’s very capable and also easygoing (and the key is, she’s also beautiful).
The deepest impression I have is when I ran into some small problems and went to ask Yingge for advice—I was afraid I wouldn’t do it well. Yingge told me: Just be yourself.
After that, I met Cy, who also gave me a lot of help and guidance.
I didn’t think too much. I just adjusted the content I usually posted to align more with the task direction.
Bit by bit, I managed to get a few first-place rankings; in total, I think it added up to nearly $10,000.
To be honest, that number isn’t that big, but the advantage is the low barrier to entry.
You don’t need 100,000 followers. You don’t need to grind data every day. If your writing is good, you still have a chance to get on the leaderboard.
Even now, I still update posts every day. Occasionally, when I see creator tasks that fit, I’ll join in.
Not grinding, but it’s pretty interesting.
Compared to writing on X for half a day just to get a few likes, Square at least gives you positive feedback—you write something and you can actually earn money.
#币安广场
35
2
50
23.3k
·
--
Verified
Anyone who trades on-chain knows how frustrating this can be: you place a stop-loss order, and before it even gets triggered, someone has already spotted it. Pull up a liquidation map and you’ll see the stop-loss levels of thousands of traders laid out in plain sight. Stop hunts work precisely because all this information is transparent. It’s not that someone leaked anything—that’s simply the cost of transparency on a blockchain...
So is it possible to make your trading intentions completely unreadable until they’re executed? That’s what I found most interesting while researching @nillionnetwork recently. After reading about it, I went ahead and bought 500U worth of $NIL spot to start building a position.
Most privacy projects focus on hiding the transactions themselves—the amounts, senders, assets, and so on. But Nillion takes a different approach: it focuses on the intent behind a transaction. Your orders, the conditions you’re waiting for, your strategy—all of this is normally transparent on-chain. Nillion’s core product, Covenants, is designed to solve this problem.
A Covenant is an encrypted instruction. You specify an action—such as selling at a certain price, placing a bid in an auction, or releasing a payment at a certain time—then seal it and bind it to a condition before sending it on-chain. While it remains encrypted, nobody can see its contents. Once the condition is met, it automatically opens and executes. There’s no need to run a bot, use a keeper service, or rely on a third party to hold it for you and promise not to peek.
There are already plenty of potential use cases: stop-loss orders that nobody can hunt, bids that stay sealed until an auction ends, proof that you made a prediction before an event happened, and payments that are automatically released at a set time. These are all essential for large-scale operations and protecting strategies.
Dusk is already live on Ethereum mainnet. This is a real mainnet launch, not a testnet—you can create Covenants, run nodes, and build with the SDK right now. Dusk is only the first of the seven eras in Nillion’s roadmap. More releases are expected before the end of the year, and the next six eras will continue to expand what the platform can do. What we’re seeing now is still just the earliest version.
500U isn’t much, but I wanted to get involved early and see how things develop. I’ll keep an eye on the roadmap and share more as things progress.
#NIL $NIL @nillionnetwork
Anyone who trades on-chain knows how frustrating this can be: you place a stop-loss order, and before it even gets triggered, someone has already spotted it. Pull up a liquidation map and you’ll see the stop-loss levels of thousands of traders laid out in plain sight. Stop hunts work precisely because all this information is transparent. It’s not that someone leaked anything—that’s simply the cost of transparency on a blockchain...
So is it possible to make your trading intentions completely unreadable until they’re executed? That’s what I found most interesting while researching @Nillion recently. After reading about it, I went ahead and bought 500U worth of $NIL spot to start building a position.
Most privacy projects focus on hiding the transactions themselves—the amounts, senders, assets, and so on. But Nillion takes a different approach: it focuses on the intent behind a transaction. Your orders, the conditions you’re waiting for, your strategy—all of this is normally transparent on-chain. Nillion’s core product, Covenants, is designed to solve this problem.
A Covenant is an encrypted instruction. You specify an action—such as selling at a certain price, placing a bid in an auction, or releasing a payment at a certain time—then seal it and bind it to a condition before sending it on-chain. While it remains encrypted, nobody can see its contents. Once the condition is met, it automatically opens and executes. There’s no need to run a bot, use a keeper service, or rely on a third party to hold it for you and promise not to peek.
There are already plenty of potential use cases: stop-loss orders that nobody can hunt, bids that stay sealed until an auction ends, proof that you made a prediction before an event happened, and payments that are automatically released at a set time. These are all essential for large-scale operations and protecting strategies.
Dusk is already live on Ethereum mainnet. This is a real mainnet launch, not a testnet—you can create Covenants, run nodes, and build with the SDK right now. Dusk is only the first of the seven eras in Nillion’s roadmap. More releases are expected before the end of the year, and the next six eras will continue to expand what the platform can do. What we’re seeing now is still just the earliest version.
500U isn’t much, but I wanted to get involved early and see how things develop. I’ll keep an eye on the roadmap and share more as things progress.
#NIL $NIL @Nillion
1
5
2.2k
·
--
CoreWeave fell 15.5% in a single day on Wednesday, closing at $65.78. The yield on its debt due in 2032 surged past 15%, and its CDS spread jumped above 1,000 basis points. Based on market pricing, the probability of default within five years is around 63%. Chamath posted a chart, Musk replied “Yikes,” and timelines were flooded with claims that leveraged AI infrastructure was about to collapse.
But the same company has around $129 billion in contracted revenue backlog, with Meta accounting for 27% and OpenAI for 17%. BofA has a Buy rating and a $140 price target, implying 105% upside. The CEO himself says the market is “irrational.” The bond market thinks it’s about to die; equity analysts think it could double—and they’re looking at the same financial statements...
What CoreWeave does is different from traditional hardware sales. It borrows money up front to stock up on GPUs, packages them as computing services, and rents them to customers through long-term contracts. Its balance sheet is full of debt, but the revenue side is supposed to turn into stable, recurring cash flow. Why are customers willing to sign long-term contracts? Because building their own clusters is too slow, too expensive, and too uncertain. In effect, CoreWeave takes on that uncertainty first by leveraging its own balance sheet, then sells the locked-in computing capacity. The more leverage it takes on, the more certainty it can offer—but the more fragile it becomes.
A few details are worth noting. Gartner says around 80% of neocloud providers could shut down by 2030. Nvidia and CoreWeave have a backstop agreement: Nvidia will take over any computing capacity that remains unsold by April 2032. This has barely been discussed, but it may be the most important safety net in the whole story. There have also been reports that OpenAI’s actual revenue is $20 billion lower than previously estimated. If expectations for demand from the largest customer are weakening, then the $129 billion contracted backlog deserves a discount.
The fear-driven narrative is certainly alarming, but it’s also overly simplistic. If the contracted backlog converts on schedule, then interest coverage is just a matter of timing. The key word is “if.” Whoever can survive this surge in the cost of capital will have the strongest moat in those long-term contracts. For now, let’s keep watching.
Data is based on public disclosures from the respective parties and does not constitute investment advice.
341
·
--
The broader market is still seeing weak, choppy trading today, with major coins under pressure. But a few small- and mid-cap coins have been moving independently, which is pretty interesting.
The clearest example is $WAL (Walrus), a decentralized storage project in the Sui ecosystem. Both its 24-hour trading volume and price gains have been strong, with obvious signs of concentrated inflows. The move has been driven mainly by the narrative around AI data infrastructure. However, there is still unlock pressure ahead. For now, the rally seems largely driven by the narrative and concentrated trading, while real demand has yet to be proven. A sharp price rise and a proven investment thesis are two different things...
There’s also been activity in a few other areas. AI Agent-related tokens like Quack AI (Q) continue to attract attention, while Bitway (BTW), with its relatively large market cap, has also appeared on the trending list. In areas like storage, AI, and privacy, ZEC and STRK have also put in decent weekly performances, so there’s some interest in pockets of the market.
Overall, today’s action is driven by selective themes rather than a broad-based rally. When the wider market is weak, capital tends to concentrate in assets with a compelling narrative and strong trading volume. But when sentiment fades, prices can fall just as quickly. For WAL, the key things to watch are whether trading volume can hold up and whether product development can keep pace—don’t focus only on its one-day gain.
The above is purely market commentary and my personal opinion, not investment advice. Markets move quickly, so please do your own research.
11
6.4k
·
--
Today I came across a pretty wild meme coin, Doge Pepe (DOPE), which combines two classic meme characters, Doge and Pepe. The craziest part is how it supposedly came about: someone apparently used the wrong API while generating images with AI and accidentally created it, spending around $1,900 in the process. And just like that, it became a meme coin...
It’s up around 100% in 24 hours, with a price of around $0.025 and a market cap of about $25M. It’s pure meme with no real utility—the kind that’s exciting on the way up, but won’t warn you before it drops.
One more reminder, folks: there are several tokens with the same name on the market, especially on Solana. Be sure to verify the contract address before getting involved, or you might end up buying the wrong one and have nowhere to turn when things go south.$DOGE
{future}(DOGEUSDT)
Today I came across a pretty wild meme coin, Doge Pepe (DOPE), which combines two classic meme characters, Doge and Pepe. The craziest part is how it supposedly came about: someone apparently used the wrong API while generating images with AI and accidentally created it, spending around $1,900 in the process. And just like that, it became a meme coin...
It’s up around 100% in 24 hours, with a price of around $0.025 and a market cap of about $25M. It’s pure meme with no real utility—the kind that’s exciting on the way up, but won’t warn you before it drops.
One more reminder, folks: there are several tokens with the same name on the market, especially on Solana. Be sure to verify the contract address before getting involved, or you might end up buying the wrong one and have nowhere to turn when things go south.$DOGE
1
1.7k
·
--
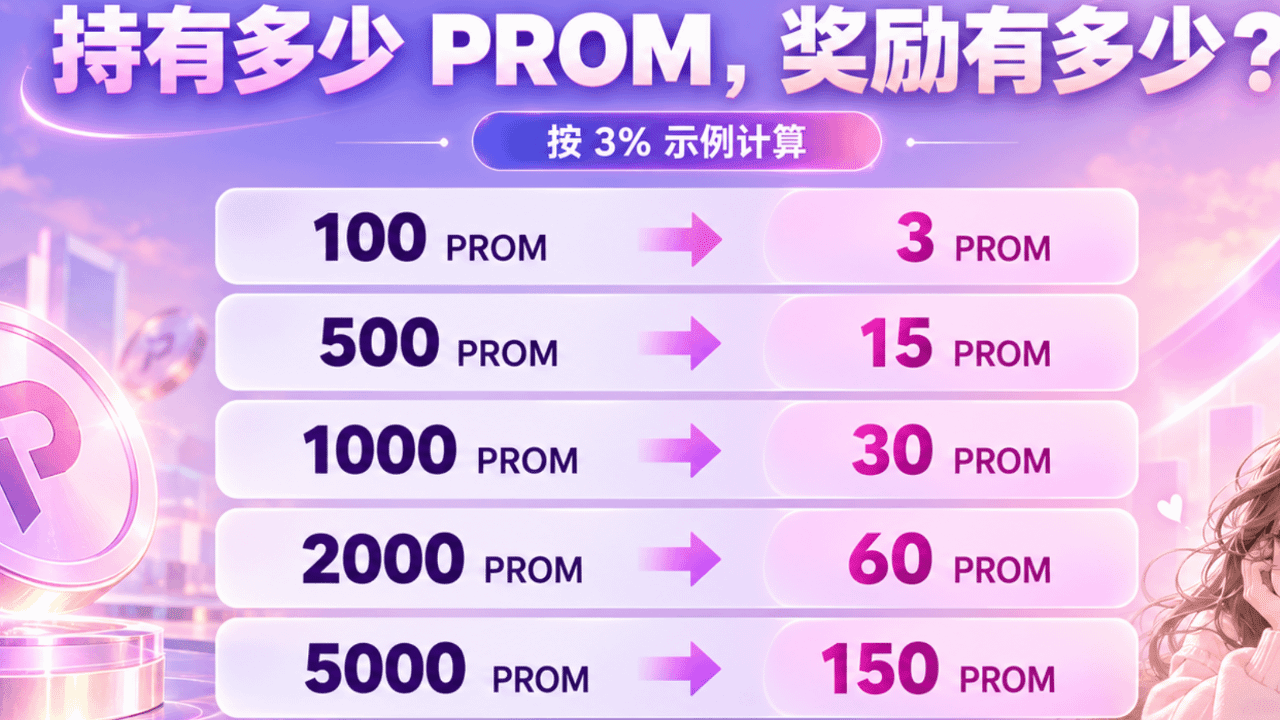
🎙️ Holding PROM? Don’t miss out! HiiT 7-day holding event and guild benefits
End
01 h 15 m 52 s
2.1k
0
0
·
--
XDP is definitely the hottest token on Base today. Its trading volume has topped $100 million, while its market cap is only a little over $20 million—that ratio looks pretty wild.
From what I can tell, it’s basically a project built around XRP yields. After the token launched on Base, it got caught up in the hype.
Trading is very active, with buying and selling roughly balanced, but liquidity in the pool is only around $2 million. At this volume, the price could get hammered at any moment.
In my view, this looks more like short-term capital chasing a hot trend on Base than something backed by deep fundamentals.
The hype is real, but if you’re thinking of getting in, weigh the risks for yourself. Don’t get carried away just by the trading volume.
1
748
·
--
A hundred billion in market cap evaporated in a day. On Friday, every headline screamed “SpaceX declares war on telecom.”
T-Mobile fell 13%, and the comments section was already writing the telecom operators’ obituaries.
But I noticed one detail while watching the market: tower companies were up.
Crown Castle and American Tower—both rose that same day.
If satellites were really going to wipe out cell towers, tower companies should have fallen too.
The fact that they rose suggests investors are betting that ground infrastructure won’t disappear—but the people collecting rent on it might be replaced.
//
Starlink Mobile has secured low-band spectrum, giving it the ability to reach indoors.
But its bandwidth is narrow and latency is high; it’s still a long way from replacing the everyday mobile experience.
But it doesn’t actually need to replace it. It only needs to convince the market that “replacement is possible” for telecom operators’ valuations to collapse. You can’t defend against an opponent that doesn’t need cell towers by simply building more cell towers.
Friday was the teaser. But that teaser was already worth a hundred billion.
#SPCX $SPCX
{future}(SPCXUSDT)
A hundred billion in market cap evaporated in a day. On Friday, every headline screamed “SpaceX declares war on telecom.”
T-Mobile fell 13%, and the comments section was already writing the telecom operators’ obituaries.
But I noticed one detail while watching the market: tower companies were up.
Crown Castle and American Tower—both rose that same day.
If satellites were really going to wipe out cell towers, tower companies should have fallen too.
The fact that they rose suggests investors are betting that ground infrastructure won’t disappear—but the people collecting rent on it might be replaced.
//
Starlink Mobile has secured low-band spectrum, giving it the ability to reach indoors.
But its bandwidth is narrow and latency is high; it’s still a long way from replacing the everyday mobile experience.
But it doesn’t actually need to replace it. It only needs to convince the market that “replacement is possible” for telecom operators’ valuations to collapse. You can’t defend against an opponent that doesn’t need cell towers by simply building more cell towers.
Friday was the teaser. But that teaser was already worth a hundred billion.
#SPCX $SPCX
1
1
1.4k
·
--
Verified
STRK just surged more than 50% today, trading around $0.11–0.12, with trading volume in the hundreds of millions. It’s the biggest mover among altcoins.
The catalyst was a comment from StarkWare’s CEO that they’re considering making Starknet independent of Ethereum L2 and turning it into a standalone Layer 1. The goal is to make it the first quantum-resistant network by 2027—earlier than Ethereum’s own plans. The market immediately priced in the new narrative, shifting its view from “an Ethereum add-on” to “a sovereign, quantum-resistant public blockchain.”
But honestly, it’s still only “under active consideration.” There’s been no governance vote and no proposal yet. Historically, stories about considering a pivot can cool off quickly after a rally… And after digging into the data, actual daily active users and on-chain revenue don’t really match the size of this move. Futures volume is far higher than spot volume, and there’s a lot of leverage piled up.
It’s fine to keep an eye on it in the short term, but don’t treat it as a long-term thesis. If the plan doesn’t materialize, or Ethereum accelerates its own quantum-resistance efforts, the premium could disappear just as quickly. Do your own research, everyone.
$STRK
{future}(STRKUSDT)
STRK just surged more than 50% today, trading around $0.11–0.12, with trading volume in the hundreds of millions. It’s the biggest mover among altcoins.
The catalyst was a comment from StarkWare’s CEO that they’re considering making Starknet independent of Ethereum L2 and turning it into a standalone Layer 1. The goal is to make it the first quantum-resistant network by 2027—earlier than Ethereum’s own plans. The market immediately priced in the new narrative, shifting its view from “an Ethereum add-on” to “a sovereign, quantum-resistant public blockchain.”
But honestly, it’s still only “under active consideration.” There’s been no governance vote and no proposal yet. Historically, stories about considering a pivot can cool off quickly after a rally… And after digging into the data, actual daily active users and on-chain revenue don’t really match the size of this move. Futures volume is far higher than spot volume, and there’s a lot of leverage piled up.
It’s fine to keep an eye on it in the short term, but don’t treat it as a long-term thesis. If the plan doesn’t materialize, or Ethereum accelerates its own quantum-resistance efforts, the premium could disappear just as quickly. Do your own research, everyone.
$STRK
2.6k
·
--
MAGIC doubled today
It gained 110% to 140% in 24 hours, with the price briefly nearing $0.16.
Trading volume exceeded its market cap, reaching several times the market cap during some periods.
I looked around but couldn't find any major news.
No big partnerships, no mainnet upgrades, and no signs of institutional money coming in.
Funds have already been rotating through the gaming and NFT sectors lately. With its small market cap and high turnover, it's no surprise that MAGIC got pushed up.
My take on this kind of market is simple: watch, but don't chase.
When volume is there, everything looks like a trend. Once it dries up, you can tell it was just sentiment.
The hottest token today could be the quietest tomorrow.
$MAGIC
{future}(MAGICUSDT)
MAGIC doubled today
It gained 110% to 140% in 24 hours, with the price briefly nearing $0.16.
Trading volume exceeded its market cap, reaching several times the market cap during some periods.
I looked around but couldn't find any major news.
No big partnerships, no mainnet upgrades, and no signs of institutional money coming in.
Funds have already been rotating through the gaming and NFT sectors lately. With its small market cap and high turnover, it's no surprise that MAGIC got pushed up.
My take on this kind of market is simple: watch, but don't chase.
When volume is there, everything looks like a trend. Once it dries up, you can tell it was just sentiment.
The hottest token today could be the quietest tomorrow.
$MAGIC
2
1
1.3k
·
--
There’s one thing I most want to know this earnings season: after the giants have poured so much money into AI, can their balance sheets actually handle it?
For more than a year, cloud providers and AI labs have kept ramping up capital spending.
GPUs, HBM, advanced packaging, optical modules, data center power—the whole supply chain has been lifted by this spending.
It no longer matters how compelling the story sounds.
Now we need to see how much of that money comes back after it’s spent.
Earnings reports start coming thick and fast in the second half of October.
➢ Around the 21st and 22nd: IBM, Tesla, and Intel
➢ On the 28th: Microsoft, Google, and Meta all report on the same day
➢ On the 29th: Apple and Amazon
I’m most interested in the group reporting on the 28th.
If Microsoft, Google, and Meta keep raising their capex guidance without squeezing cloud margins, the case for the hardware and power supply chains will remain solid.
On the other hand, if spending growth slows, or free cash flow comes under significant pressure,
the first to be sold will be the high-valuation stocks propped up by a narrative.
//
As it happens, FOMC is also that same week, on the 27th and 28th.
Long-term yields are already at multi-year highs.
Oil prices have climbed back toward $100 on geopolitical concerns.
If the meeting minutes or dot plot remain hawkish, and oil prices stay elevated, real interest rates will be hard to bring down.
Tech stocks are already stretched on valuation; add this on top and volatility will be high.
━━━━━ • ━━━━━
The direction of money has actually become clear lately:
it’s moving toward areas with real supply-and-demand bottlenecks.
Memory, especially HBM and scarce DRAM; data center power; independent power producers and nuclear power; optical modules; advanced packaging. These areas have long order visibility and strong pricing power. They won’t be afraid of questions about where the money went this earnings season.
Companies relying purely on the AI story, but without capacity or locked-in customers, will be most vulnerable to repricing when earnings pressure and interest-rate pressure hit at the same time.
——
My view is this:
this earnings season will separate the winners from the rest.
Companies that can deliver orders and cash flow will keep attracting capital.
Those that can’t will give back some of the gains they made in recent months on the back of a narrative.
Tech stocks as a whole will be more volatile in the short term, especially with FOMC and earnings landing in the same week.
But volatility doesn’t mean the trend has reversed.
The long-term AI capex cycle isn’t over; we’ve just entered the phase where companies have to show me the numbers. Three reports come out on the 28th.
The amount of information that night could determine where things go over the next month.$IBMB
{spot}(IBMBUSDT)
There’s one thing I most want to know this earnings season: after the giants have poured so much money into AI, can their balance sheets actually handle it?
For more than a year, cloud providers and AI labs have kept ramping up capital spending.
GPUs, HBM, advanced packaging, optical modules, data center power—the whole supply chain has been lifted by this spending.
It no longer matters how compelling the story sounds.
Now we need to see how much of that money comes back after it’s spent.
Earnings reports start coming thick and fast in the second half of October.
➢ Around the 21st and 22nd: IBM, Tesla, and Intel
➢ On the 28th: Microsoft, Google, and Meta all report on the same day
➢ On the 29th: Apple and Amazon
I’m most interested in the group reporting on the 28th.
If Microsoft, Google, and Meta keep raising their capex guidance without squeezing cloud margins, the case for the hardware and power supply chains will remain solid.
On the other hand, if spending growth slows, or free cash flow comes under significant pressure,
the first to be sold will be the high-valuation stocks propped up by a narrative.
//
As it happens, FOMC is also that same week, on the 27th and 28th.
Long-term yields are already at multi-year highs.
Oil prices have climbed back toward $100 on geopolitical concerns.
If the meeting minutes or dot plot remain hawkish, and oil prices stay elevated, real interest rates will be hard to bring down.
Tech stocks are already stretched on valuation; add this on top and volatility will be high.
━━━━━ • ━━━━━
The direction of money has actually become clear lately:
it’s moving toward areas with real supply-and-demand bottlenecks.
Memory, especially HBM and scarce DRAM; data center power; independent power producers and nuclear power; optical modules; advanced packaging. These areas have long order visibility and strong pricing power. They won’t be afraid of questions about where the money went this earnings season.
Companies relying purely on the AI story, but without capacity or locked-in customers, will be most vulnerable to repricing when earnings pressure and interest-rate pressure hit at the same time.
——
My view is this:
this earnings season will separate the winners from the rest.
Companies that can deliver orders and cash flow will keep attracting capital.
Those that can’t will give back some of the gains they made in recent months on the back of a narrative.
Tech stocks as a whole will be more volatile in the short term, especially with FOMC and earnings landing in the same week.
But volatility doesn’t mean the trend has reversed.
The long-term AI capex cycle isn’t over; we’ve just entered the phase where companies have to show me the numbers. Three reports come out on the 28th.
The amount of information that night could determine where things go over the next month.$IBMB
1
566
·
--
Tomorrow, 10.10
On this day last year, Bitcoin plunged from around $122,000 in a single sharp drop.
It never reclaimed its high of $126,000.
A year has passed.
Now look at this week:
On October 7, U.S. spot Bitcoin ETFs saw $487 million in net outflows in a single day—the most since June.
BlackRock’s IBIT alone saw $208 million flow out....
October opened with net outflows overall, eating into some of September’s strong inflows.
Ethereum ETFs have also seen consecutive outflows.
The Fed’s September meeting minutes were released. Most officials thought another rate hike this year was still possible.
The 10-year Treasury yield is hovering around 5.3%, a multi-year high.
Tensions in the Middle East and around the Strait of Hormuz haven’t eased, and oil prices continue to weigh on risk assets.
In the 24 hours around the 8th, liquidations topped $1 billion, with longs making up the vast majority.
And one more thing:
An address linked to the U.S. government moved more than 10,000 bitcoins, worth about $1 billion.
They came from the batch of coins seized from Bitfinex.
The receiving address isn’t labeled.
There’s no confirmation they were sold, but as soon as news like this surfaces, the uncertainty gets priced in.
//
How I see it
ETF outflows, macro tightening, liquidations—
Taken together, they’re really different facets of the same thing: rates staying high for too long, and leverage being the first to exit.
That’s how the market is interpreting it for now: “deleveraging,” not a trend reversal.
The government wallet is a separate issue to watch.
There have been similar moves before: some coins were transferred and not sold, while others were sold off gradually.
The address not being labeled doesn’t mean anything one way or the other. It’s just another unknown on the market’s radar.
As for tomorrow’s date:
Markets don’t trade by the calendar, but traders remember dates.
An anniversary effect doesn’t change the fundamentals, but it can amplify sentiment—
especially when the previous high still hasn’t been reclaimed.
There have been a lot of signals this week.
Taken one by one, none is enough on its own to reverse the direction.
The key variable is still Treasury yields.
If 5.3% moves higher, risk assets won’t be very comfortable.
BTC-0.86%
IBITETF+0.00%
8
1.5k
·
--
TOKEN2049 Singapore, October 7–8. A few unlocks—just so happen to get stuck right around here
The days when institutions, market makers, and the most concentrated attendee funds are present are also when supply is the most concentrated
On October 1, $SUI unlocks about 13.26 million tokens; the circulating ratio is roughly 0.32%, worth about $16.7 million
On the same day, $EIGEN unlocks about 36.82 million tokens; circulating ratio 5.19%, about $10.3 million
On October 2, $ENA releases about 40.63 million tokens following a monthly rhythm; circulating ratio 0.45%, about $11 million
The amounts aren’t particularly extreme
But when a few happen to overlap and coincide with a major event, time itself becomes an amplifier
—
ENA, one more thing to add
After the tokenomics was adjusted in August, the remaining investor allocation that was originally scheduled for March 2028 was moved up and released all at once on October 5
The market’s figures are roughly 1.41 billion tokens; plus the total of regular allocations for core contributors, it brings the number to about 1.5 billion tokens. The headline numbers are really scary
But StablecoinX’s roughly 3.03 billion tokens are locked up and, although they reach maturity in the same period, selling is still constrained by the foundation’s approval rights and preferential purchase rights
The actual amount that can enter the market is much smaller than the headline suggests
EIGEN’s next unlock is about 38 million tokens around October 11, still at the tail end of the conference week
//
“Unlocking doesn’t mean dumping”—we’ve said this many times, but you also can’t treat it like a get-out-of-jail-free card
The circulating share of SUI and ENA’s regular allocations is already not high; some early holdings may have been repurchased by the foundation or pre-hedged
What really matters is whether wallets send tokens to exchanges, how the funding rate moves, and whether the distribution of orders on the order book changes. Those expectations should first show up there
If the conference news is heavily positive, it won’t be hard for buy-side demand to eat through sell pressure. If the narrative is bland, then the same supply turns into a distribution window
Time overlap amplifies sentiment—not the tokens themselves.
1
2.1k
·
--
DEX tokens on Solana have been taking turns getting attention lately.
RAY moved, ORCA moved, and today it’s MET’s turn—it surged nearly 40% in a day.
Around 0.44, with a market cap of 250 million and 24-hour trading volume of 160 to 200 million.
Nearly the entire market cap changed hands in a day.
On-chain trading has picked up, and liquidity protocols are among the first to benefit from the volume. It’s a bit like what happened with UNI back then.
But that 40% is already reflected in the price.
Money flows into this kind of sector fast—and leaves just as quickly. What we’re talking about today may be forgotten by tomorrow.
I didn’t chase it, and I’m not planning to.
Figures vary across sources, so check them yourself.
$MET
{future}(METUSDT)
DEX tokens on Solana have been taking turns getting attention lately.
RAY moved, ORCA moved, and today it’s MET’s turn—it surged nearly 40% in a day.
Around 0.44, with a market cap of 250 million and 24-hour trading volume of 160 to 200 million.
Nearly the entire market cap changed hands in a day.
On-chain trading has picked up, and liquidity protocols are among the first to benefit from the volume. It’s a bit like what happened with UNI back then.
But that 40% is already reflected in the price.
Money flows into this kind of sector fast—and leaves just as quickly. What we’re talking about today may be forgotten by tomorrow.
I didn’t chase it, and I’m not planning to.
Figures vary across sources, so check them yourself.
$MET
2
957
·
--
Verified
Pudgy Penguins’ parent company, Igloo, announced it’s shutting down Abstract, a consumer-focused L2 on Ethereum. Its mainnet will shut down on December 15, just over a year after launch.
The numbers don’t look too bad:
400,000 users, more than 140 apps, and partnerships with Disney and Red Bull Racing.
Hundreds of millions of transactions.
But Luca Netz himself said they burned tens of millions of dollars over the past 18 months.
Growth stalled, liquidity was thin, and the DeFi ecosystem never took off. Subsidies couldn’t keep things going.
No token, no ICO.
Just a straightforward shutdown.
There’s still around $47–48 million sitting on-chain.
Users need to bridge their assets out before December 15. After that, they won’t be able to access them.
If you have assets there, don’t wait.
All resources are being redirected to the Pudgy Penguins brand and PENGU.
On the day the news broke, PENGU fell around 5.6%, to about $0.009.
In the short term, this narrows the narrative. The “own chain” premium is gone, and PENGU has one less part of its story.
In the medium term, it’s about where the savings go:
Will they really be invested in the brand and token utility, or is this just a way to stop the bleeding?
Honestly, I don’t think shutting down the chain itself is anything to criticize.
If you can’t afford to keep it running, shutting it down is better than keeping up appearances.
But what will support PENGU’s valuation now that the chain is gone? That’s the question that’s finally on the table.
$PENGU
{future}(PENGUUSDT)
Pudgy Penguins’ parent company, Igloo, announced it’s shutting down Abstract, a consumer-focused L2 on Ethereum. Its mainnet will shut down on December 15, just over a year after launch.
The numbers don’t look too bad:
400,000 users, more than 140 apps, and partnerships with Disney and Red Bull Racing.
Hundreds of millions of transactions.
But Luca Netz himself said they burned tens of millions of dollars over the past 18 months.
Growth stalled, liquidity was thin, and the DeFi ecosystem never took off. Subsidies couldn’t keep things going.
No token, no ICO.
Just a straightforward shutdown.
There’s still around $47–48 million sitting on-chain.
Users need to bridge their assets out before December 15. After that, they won’t be able to access them.
If you have assets there, don’t wait.
All resources are being redirected to the Pudgy Penguins brand and PENGU.
On the day the news broke, PENGU fell around 5.6%, to about $0.009.
In the short term, this narrows the narrative. The “own chain” premium is gone, and PENGU has one less part of its story.
In the medium term, it’s about where the savings go:
Will they really be invested in the brand and token utility, or is this just a way to stop the bleeding?
Honestly, I don’t think shutting down the chain itself is anything to criticize.
If you can’t afford to keep it running, shutting it down is better than keeping up appearances.
But what will support PENGU’s valuation now that the chain is gone? That’s the question that’s finally on the table.
$PENGU
1.2k
·
--
Verified
The Nasdaq hit another record
The forces behind it are clear
AI and computing power are leading the charge
Investors’ stance is direct:
Set high interest rates aside for now, and put oil-price jitters aside too. It’s all in on one theme: computing power, models, and infrastructure.
Nvidia rose about 2.1%, bringing its market cap to $5.76 trillion
The market has been talking about the $6 trillion mark for a long time. Now it’s visibly getting closer
It was still the S&P 500’s biggest single driver of gains on the day. The narratives around chip demand and capital spending remain intact
Microsoft, Meta, and Tesla were generally up more than 1%–2%, with the Magnificent Seven broadly strong
Expectations for AI orders and applications are still sustaining valuations
//
Three threads made me stop and take notice today
SpaceX rose more than 7%
Morgan Stanley reiterated its Overweight rating and $300 price target, saying the valuation looks low ahead of Starship’s 15th test flight
The pricing logic is changing
The market is starting to assign it three labels at once: launch services, satellite communications, and AI computing infrastructure
When one stock carries three narratives, investors are willing to chase it
TSMC strengthened, amid discussions about a partnership with Elon Musk’s Terafab chip factory
Advanced-process capacity meets a hyperscaler’s self-built wafer fab
If a deal really comes together, it would directly address the bottleneck in AI computing supply. Cerebras attracted buyers
Altman called it a
close partner
With OpenAI’s endorsement, attention shifted from general-purpose GPUs to specialized chips and alternative architectures.
//
With all three threads converging, today’s market action wasn’t about the gains. It was about
a shift in pricing logic
Nvidia’s market cap is nearing $6 trillion, and consensus is solidifying
SpaceX is being repriced as an AI infrastructure asset, with its set of labels expanding
Terafab and Cerebras have moved self-built fabs + specialized chips
from narrative to concrete partnership discussions
A new variable on the computing-power supply side is starting to take shape. From models to chips to wafer fabs, investors are buying further and further down the stack
The ability to build computing power at the physical layer is now just as valuable as the models themselves.
$SPCXB
{spot}(SPCXBUSDT)
The Nasdaq hit another record
The forces behind it are clear
AI and computing power are leading the charge
Investors’ stance is direct:
Set high interest rates aside for now, and put oil-price jitters aside too. It’s all in on one theme: computing power, models, and infrastructure.
Nvidia rose about 2.1%, bringing its market cap to $5.76 trillion
The market has been talking about the $6 trillion mark for a long time. Now it’s visibly getting closer
It was still the S&P 500’s biggest single driver of gains on the day. The narratives around chip demand and capital spending remain intact
Microsoft, Meta, and Tesla were generally up more than 1%–2%, with the Magnificent Seven broadly strong
Expectations for AI orders and applications are still sustaining valuations
//
Three threads made me stop and take notice today
SpaceX rose more than 7%
Morgan Stanley reiterated its Overweight rating and $300 price target, saying the valuation looks low ahead of Starship’s 15th test flight
The pricing logic is changing
The market is starting to assign it three labels at once: launch services, satellite communications, and AI computing infrastructure
When one stock carries three narratives, investors are willing to chase it
TSMC strengthened, amid discussions about a partnership with Elon Musk’s Terafab chip factory
Advanced-process capacity meets a hyperscaler’s self-built wafer fab
If a deal really comes together, it would directly address the bottleneck in AI computing supply. Cerebras attracted buyers
Altman called it a
close partner
With OpenAI’s endorsement, attention shifted from general-purpose GPUs to specialized chips and alternative architectures.
//
With all three threads converging, today’s market action wasn’t about the gains. It was about
a shift in pricing logic
Nvidia’s market cap is nearing $6 trillion, and consensus is solidifying
SpaceX is being repriced as an AI infrastructure asset, with its set of labels expanding
Terafab and Cerebras have moved self-built fabs + specialized chips
from narrative to concrete partnership discussions
A new variable on the computing-power supply side is starting to take shape. From models to chips to wafer fabs, investors are buying further and further down the stack
The ability to build computing power at the physical layer is now just as valuable as the models themselves.
$SPCXB
1
813
·
--
Partly True
The most notable move among major-cap coins today is $ADA
Up roughly 10% to 11% in 24 hours, with the price near 0.27. That’s a 90-day high and one of its strongest daily performances since May.
Trading volume was about $1.09 billion, nearly twice the 30-day median. This wasn’t a thin-market pump.
Two catalysts came together:
RealFi launched on mainnet on October 1, bringing tokenized real-world assets and the USDr stablecoin to Cardano. They’re available on Lace, Liqwid, and SundaeSwap.
That same day, Hoskinson brought scaling back into the spotlight with #LeiosIsComing.
Linear Leios testnet throughput is roughly six times the mainnet’s current capacity, while the mainnet target remains the Dijkstra hard fork at the end of the year.
The price broke out where these two narratives converged—not simply because it was following the broader market.
$ADA
1
2.2k
·
--
Verified
Today I’m focusing on just one thing
ENA
Not because it’s been surging
It’s because the investors’ vesting line was cut off early today
The original plan was to release roughly 78 million-plus tokens each month, gradually through March 2028
By the end of August, the rules changed. The remaining batches for about 17 months were consolidated and released all at once today
Working backward, that’s about 1.41 billion tokens—around 14% of the circulating supply
The foundation hasn’t officially stamped and confirmed this figure
Another calendar used on the market only shows 170 million tokens for regular monthly releases
But what the market is trading today is the previous expectation.
//
On the same day, there’s also a second layer
StablecoinX holds about 3.03 billion tokens, accounting for 20% of the total supply. The contract lock-up was also lifted today
But this is not a dump that can be done casually
Selling and transferring require the foundation’s written approval, and operational needs must be notified five business days in advance. The foundation also has the right of first purchase
What can actually be put on the market immediately is mainly the investors’ portion whose vesting ended early, plus the team’s monthly batches released as usual.
——
The idea is simple
They want to release it all at once, to replace the supply uncertainty hovering over each month for more than a year into the future
But the shadow hasn’t disappeared
It’s gone from a slow drip to concentrated delivery landing today
Unlocking doesn’t automatically mean a sell-off
What I’m looking at is whether wallets are moving toward exchanges, and whether there’s actual trading
The team and foundation’s monthly releases still need to continue until 2028
Today is the endpoint of the investors’ line—not the endpoint of supply.
$ENA
{future}(ENAUSDT)
Today I’m focusing on just one thing
ENA
Not because it’s been surging
It’s because the investors’ vesting line was cut off early today
The original plan was to release roughly 78 million-plus tokens each month, gradually through March 2028
By the end of August, the rules changed. The remaining batches for about 17 months were consolidated and released all at once today
Working backward, that’s about 1.41 billion tokens—around 14% of the circulating supply
The foundation hasn’t officially stamped and confirmed this figure
Another calendar used on the market only shows 170 million tokens for regular monthly releases
But what the market is trading today is the previous expectation.
//
On the same day, there’s also a second layer
StablecoinX holds about 3.03 billion tokens, accounting for 20% of the total supply. The contract lock-up was also lifted today
But this is not a dump that can be done casually
Selling and transferring require the foundation’s written approval, and operational needs must be notified five business days in advance. The foundation also has the right of first purchase
What can actually be put on the market immediately is mainly the investors’ portion whose vesting ended early, plus the team’s monthly batches released as usual.
——
The idea is simple
They want to release it all at once, to replace the supply uncertainty hovering over each month for more than a year into the future
But the shadow hasn’t disappeared
It’s gone from a slow drip to concentrated delivery landing today
Unlocking doesn’t automatically mean a sell-off
What I’m looking at is whether wallets are moving toward exchanges, and whether there’s actual trading
The team and foundation’s monthly releases still need to continue until 2028
Today is the endpoint of the investors’ line—not the endpoint of supply.
$ENA
1
5
10k
·
--
The futures aren’t reopening until Sunday 6:00 PM (ET) — Monday hasn’t opened yet
Meanwhile, I’ll scan the news from the weekend first
Let’s sort out the clues for the open
//
The tone set at Friday’s close is very important, because Monday’s early session will most likely follow that pricing
The September Non-Farm Payrolls added only 29,000 jobs, versus expectations of around 90,000
That’s a big gap
Unemployment rate: 4.2%
The market reaction is:
The odds of a rate hike in October were pushed sharply lower. The guidance moved from nearly 70% previously down to about 24%
But the stock market didn’t fall
Dow +0.49%, S&P +0.73%, Nasdaq +1.19%, and the Nasdaq 100 closed at a new high
The logic is simple:
Weak employment → lower odds of rate hikes → growth stocks benefit
A textbook “weak NFP” trade
//
On Friday, I kept three lines/threads for individual stocks. On Monday at the open, I’ll first watch these
Nvidia closed at 233.95, and during the day it touched 237.88, marking a new intraday high in its market debut/new high since May
Semiconductors overall were on the stronger side, but memory was going the other way
Toshiba said it plans to expand hard-disk production, and Seagate and Western Digital each fell by about 10%
Expansion news is a negative for memory stocks—once capacity ramps up, prices get pressured down
Tesla +4.65%
Q3 deliveries were 486,532 units, well above the forecast of 464,000
SpaceX also rose 7.35%
Nike was one of the worst performers in the Dow, down about 3.6%
The issue is demand from China, plus a full-year revenue outlook guidance cut
━━━━━
On Monday daytime, there’s only one thing that can truly change the pricing: the 9:00 AM 9月 ISM Services PMI for September. The expectation is around 55.1, prior value 55.4
The headline number doesn’t matter
What matters are the sub-components inside
If new orders are still expanding, and the prices component is still high, then Friday’s “pause rate hikes” trade logic will be reversed
But if the employment sub-component also turns weaker like the Non-Farm payrolls, then growth stocks and small/mid caps will likely keep running
In plain terms: there are two storylines. Before the ISM prints, it’s all guessing
At 9:45 there’s also the S&P Global Services PMI final estimate. There are no major earnings reports that day
China’s National Day holiday runs until Oct 7, so liquidity in Asia-Pacific is thin
The Fed minutes are on Wednesday, and have nothing to do with Monday
On Monday, just watch that one number—not investment advice. DYOR
$TESL.ETF
3
3k
·
--
Verified
There’s only one hot search today: SAND
But the reason it’s rising has nothing to do with the Metaverse
On Oct 2 in the afternoon, Korea’s three major exchanges—Up, Humb, and Coin1—lifted the six-week trading warning, and deposits and withdrawals resumed
Previously, on Aug 22, the SAND cross-chain bridge had an incident: on Base and BSC, a batch of unbacked tokens was minted. The three exchanges immediately put up trading warning notices
Once the warning was removed, Korea’s liquidity gate opened
The price jumped from around 0.044 straight to 0.084; in 24 hours it rose 50% to 80%, with trading volume of roughly $900 million
But the market cap is only 230 million
—
I looked at the structure: this isn’t spot being repriced
Contract trading volume is far higher than spot; open interest has surged significantly, and a round of liquidations has cleared out the shorts
The breakout from 0.065 to 0.068 is sitting on positions that have been capped for months—but the main fuel was leverage squeeze, not because someone is suddenly re-backing their view of Sandbox’s business
One more thing
The cross-chain bridge issue hasn’t gone away just because the warning was lifted. The abnormal minting alerts on Base and BSC are still there
It’s the release of liquidity and a short squeeze driving the move—not fundamentals. Don’t mix them up.
$SAND
{future}(SANDUSDT)
There’s only one hot search today: SAND
But the reason it’s rising has nothing to do with the Metaverse
On Oct 2 in the afternoon, Korea’s three major exchanges—Up, Humb, and Coin1—lifted the six-week trading warning, and deposits and withdrawals resumed
Previously, on Aug 22, the SAND cross-chain bridge had an incident: on Base and BSC, a batch of unbacked tokens was minted. The three exchanges immediately put up trading warning notices
Once the warning was removed, Korea’s liquidity gate opened
The price jumped from around 0.044 straight to 0.084; in 24 hours it rose 50% to 80%, with trading volume of roughly $900 million
But the market cap is only 230 million
—
I looked at the structure: this isn’t spot being repriced
Contract trading volume is far higher than spot; open interest has surged significantly, and a round of liquidations has cleared out the shorts
The breakout from 0.065 to 0.068 is sitting on positions that have been capped for months—but the main fuel was leverage squeeze, not because someone is suddenly re-backing their view of Sandbox’s business
One more thing
The cross-chain bridge issue hasn’t gone away just because the warning was lifted. The abnormal minting alerts on Base and BSC are still there
It’s the release of liquidity and a short squeeze driving the move—not fundamentals. Don’t mix them up.
$SAND
3
3.6k
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
BitcoinShortTermHoldersReach4.08MBTC
128,067 views
1,103 Discussing
#BitcoinShortTermHoldersReach4.08MBTC 🚨 4.08M BTC — IS SELLING PRESSURE BUILDING?
Hey guys, Bitcoin short-term holders reportedly hold 4.08M BTC, the highest level since June. 📊
Here's what caught my attention:
BTC price: ~$81.9K
STH cost basis: ~$74.9K
Entry zone: $82K–$86K
Stablecoin supply: ~$302B, showing little growth.
⚠️ My take: The market looks slightly fragile, but this isn't a confirmed sell signal. Watch the $74.9K level closely.
Will fresh demand absorb the supply, or will panic selling kick in?
Let's watch the data, guys. 👀
— Dwarix .
DWARIX 策
·1 Likes
·1.1k views
BitcoinRecoversTo$82K
105,039 views
202 Discussing
OctoberFedHikeOddsFallToAround17%
35,285 views
632 Discussing