
CryptoLite_247
934 Posts
CryptoLite_247
Report
Block User
Free Stock Market News ACCURATE, CONSISTENT, & RELIABLE || https://x.com/Yusty121 || Crypto first commentary with Marco Market Context
Open Trade
Occasional Trader
5.4 Years
6 Following
351 Followers
1.3K+ Liked
Posts
Portfolio
All
Quotes
PINNED
Verified
Cathie Wood says each Starship launch could generate roughly $1B in revenue with Elon Musk targeting as many as 10K flights per year by 2030.
She says that would put Starship at $10T in annual revenue and make $SPCX $1.8T IPO valuation look very different in hindsight.
Cathie Wood says each Starship launch could generate roughly $1B in revenue with Elon Musk targeting as many as 10K flights per year by 2030.
She says that would put Starship at $10T in annual revenue and make $SPCX $1.8T IPO valuation look very different in hindsight.
She says that would put Starship at $10T in annual revenue and make $SPCX $1.8T IPO valuation look very different in hindsight.
21
3
69
84.7k
PINNED
19
1
52
81.9k
·
--
Bullish
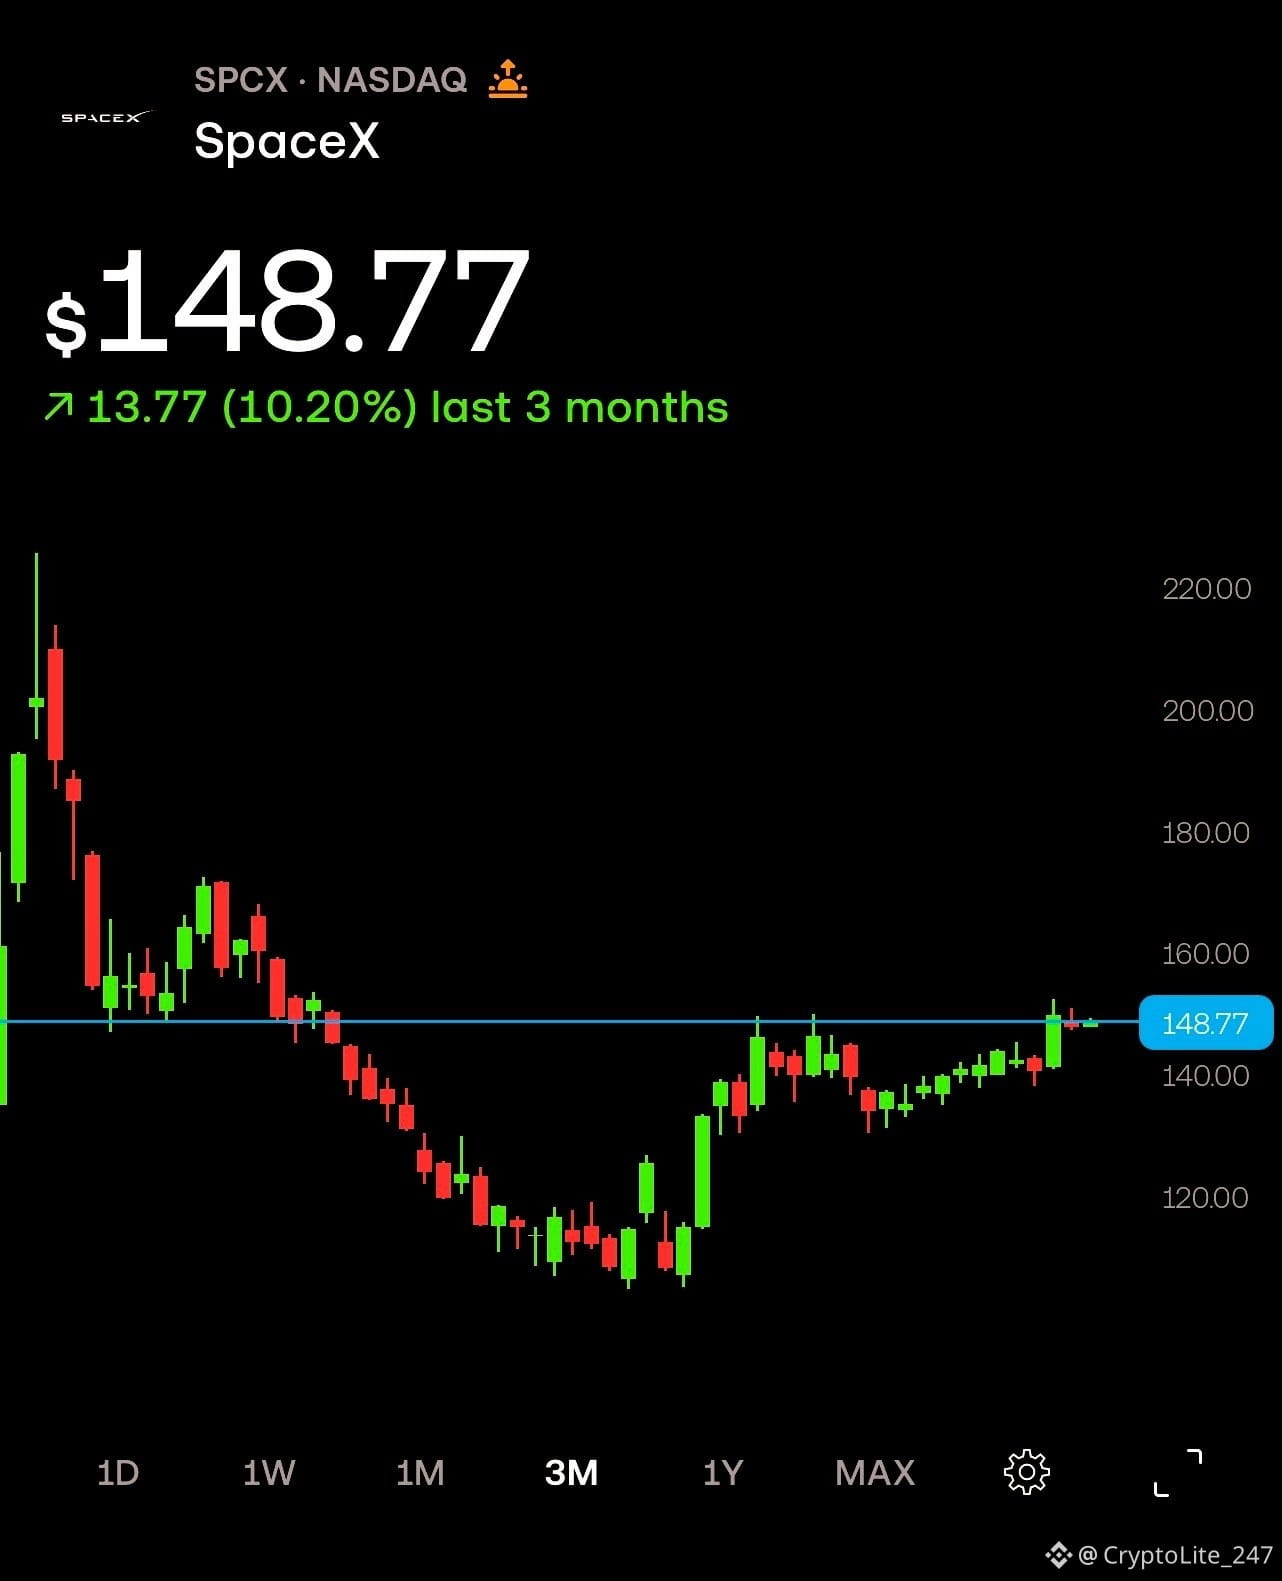
$SPCX could be one of the biggest long-term bets in the market but the valuation leaves very little room for mistakes.
SpaceX already dominates orbital launches, with Falcon 9 reportedly carrying roughly 80% of global payload mass last year. But the bigger opportunity could be what happens if Starship achieves reliable, rapid reusability.
Raymond James analyst Brian Gesuale has a $800 price target, while VY Capital believes SpaceX could exceed a $10T valuation within 5–7 years. Cathie Wood has also argued that each Starship launch could eventually generate around $1B, creating a theoretical path toward $10T in annual Starship revenue if Musk's 10,000-flight target were achieved.
Starlink is already generating recurring revenue from satellite broadband, including aviation connectivity, while SpaceX continues using its launch and Starlink ecosystem to fund the next layer of growth.
The challenge is execution. 10,000 Starship flights per year by 2030 would require an extraordinary increase in launch cadence, reliability, infrastructure and demand. Even if Starship succeeds, timelines could slip and costs could remain higher than expected.
And valuation matters. At roughly 20x next year's expected sales and 83x projected earnings, investors are already paying heavily for future growth.
$SPCX could be one of the biggest long-term bets in the market but the valuation leaves very little room for mistakes.
SpaceX already dominates orbital launches, with Falcon 9 reportedly carrying roughly 80% of global payload mass last year. But the bigger opportunity could be what happens if Starship achieves reliable, rapid reusability.
Raymond James analyst Brian Gesuale has a $800 price target, while VY Capital believes SpaceX could exceed a $10T valuation within 5–7 years. Cathie Wood has also argued that each Starship launch could eventually generate around $1B, creating a theoretical path toward $10T in annual Starship revenue if Musk's 10,000-flight target were achieved.
Starlink is already generating recurring revenue from satellite broadband, including aviation connectivity, while SpaceX continues using its launch and Starlink ecosystem to fund the next layer of growth.
The challenge is execution. 10,000 Starship flights per year by 2030 would require an extraordinary increase in launch cadence, reliability, infrastructure and demand. Even if Starship succeeds, timelines could slip and costs could remain higher than expected.
And valuation matters. At roughly 20x next year's expected sales and 83x projected earnings, investors are already paying heavily for future growth.
SpaceX already dominates orbital launches, with Falcon 9 reportedly carrying roughly 80% of global payload mass last year. But the bigger opportunity could be what happens if Starship achieves reliable, rapid reusability.
Raymond James analyst Brian Gesuale has a $800 price target, while VY Capital believes SpaceX could exceed a $10T valuation within 5–7 years. Cathie Wood has also argued that each Starship launch could eventually generate around $1B, creating a theoretical path toward $10T in annual Starship revenue if Musk's 10,000-flight target were achieved.
Starlink is already generating recurring revenue from satellite broadband, including aviation connectivity, while SpaceX continues using its launch and Starlink ecosystem to fund the next layer of growth.
The challenge is execution. 10,000 Starship flights per year by 2030 would require an extraordinary increase in launch cadence, reliability, infrastructure and demand. Even if Starship succeeds, timelines could slip and costs could remain higher than expected.
And valuation matters. At roughly 20x next year's expected sales and 83x projected earnings, investors are already paying heavily for future growth.
1
455
·
--
Bullish
$CRDO is showing that AI infrastructure isn’t just about GPUs connectivity is becoming a major bottleneck.
Credo Technology jumped 4.5% to $175.89 after posting a huge fiscal Q1 2027 quarter. Revenue hit $479M, up 114.7% YoY, while adjusted EPS came in at $1.20, beating the $1.17 consensus.
The momentum is carrying into the next quarter too. Management guided for $525M–$535M in Q2 revenue, with the midpoint implying roughly 10.6% sequential growth.
non-GAAP net income surged 140% YoY to $236.3M. FY2026 revenue had already reached nearly $1.3B, up about 206% YoY.
The bigger thesis is bandwidth. As AI clusters scale, high-speed optical connectivity becomes increasingly critical for moving data between GPUs, servers and networking infrastructure.
$CRDO is becoming a serious AI connectivity play, but the valuation and expectations are rising alongside the growth.
$CRDO is showing that AI infrastructure isn’t just about GPUs connectivity is becoming a major bottleneck.
Credo Technology jumped 4.5% to $175.89 after posting a huge fiscal Q1 2027 quarter. Revenue hit $479M, up 114.7% YoY, while adjusted EPS came in at $1.20, beating the $1.17 consensus.
The momentum is carrying into the next quarter too. Management guided for $525M–$535M in Q2 revenue, with the midpoint implying roughly 10.6% sequential growth.
non-GAAP net income surged 140% YoY to $236.3M. FY2026 revenue had already reached nearly $1.3B, up about 206% YoY.
The bigger thesis is bandwidth. As AI clusters scale, high-speed optical connectivity becomes increasingly critical for moving data between GPUs, servers and networking infrastructure.
$CRDO is becoming a serious AI connectivity play, but the valuation and expectations are rising alongside the growth.
Credo Technology jumped 4.5% to $175.89 after posting a huge fiscal Q1 2027 quarter. Revenue hit $479M, up 114.7% YoY, while adjusted EPS came in at $1.20, beating the $1.17 consensus.
The momentum is carrying into the next quarter too. Management guided for $525M–$535M in Q2 revenue, with the midpoint implying roughly 10.6% sequential growth.
non-GAAP net income surged 140% YoY to $236.3M. FY2026 revenue had already reached nearly $1.3B, up about 206% YoY.
The bigger thesis is bandwidth. As AI clusters scale, high-speed optical connectivity becomes increasingly critical for moving data between GPUs, servers and networking infrastructure.
$CRDO is becoming a serious AI connectivity play, but the valuation and expectations are rising alongside the growth.
417
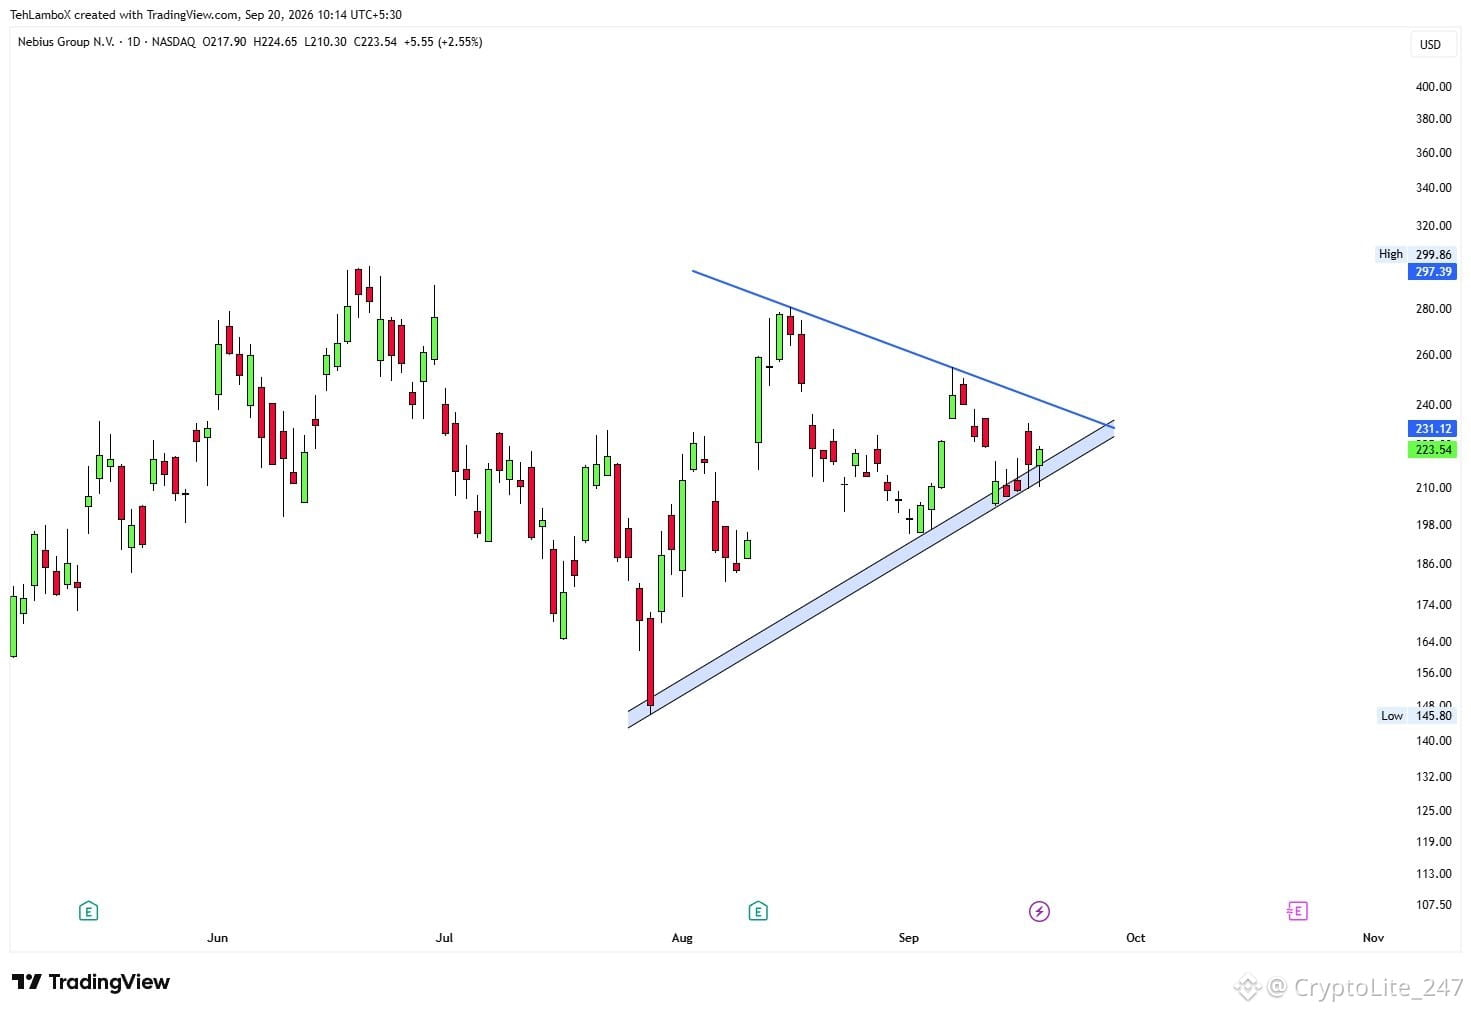
🚨UPDATE: $NBIS Triangle ready to break next week?
I readjusted the lower trendline and made it a zone since we saw some kind of reaction every time we tested it.
Now my breakdown level is 210, below which I will be bearish and I dont have a bullish level but it should be somewhere between 240-245 depending on the time of the breakout.
🚨UPDATE: $NBIS Triangle ready to break next week?
I readjusted the lower trendline and made it a zone since we saw some kind of reaction every time we tested it.
Now my breakdown level is 210, below which I will be bearish and I dont have a bullish level but it should be somewhere between 240-245 depending on the time of the breakout.
I readjusted the lower trendline and made it a zone since we saw some kind of reaction every time we tested it.
Now my breakdown level is 210, below which I will be bearish and I dont have a bullish level but it should be somewhere between 240-245 depending on the time of the breakout.
2
672
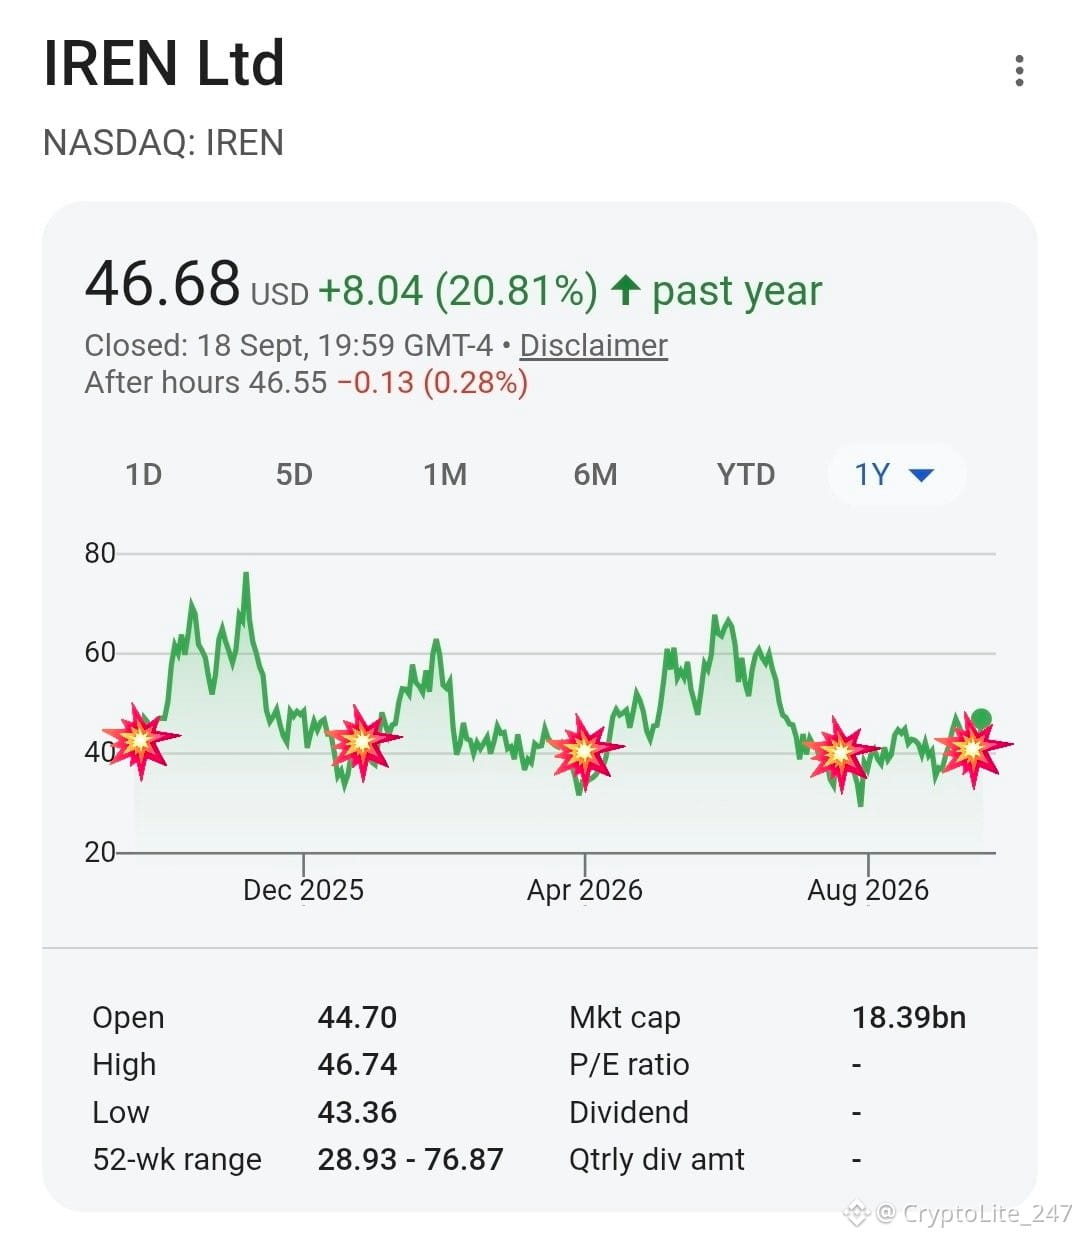
$IREN - I think the consolidation period is coming to an end.
Look at the pattern over the last year. Every time IREN has fallen back into the $35-$40 range and consolidated, it has eventually made another major run higher.
This is now the fourth time we’ve seen something similar.
I think the stock wants to make another major run from here.
$IREN - I think the consolidation period is coming to an end.
Look at the pattern over the last year. Every time IREN has fallen back into the $35-$40 range and consolidated, it has eventually made another major run higher.
This is now the fourth time we’ve seen something similar.
I think the stock wants to make another major run from here.
Look at the pattern over the last year. Every time IREN has fallen back into the $35-$40 range and consolidated, it has eventually made another major run higher.
This is now the fourth time we’ve seen something similar.
I think the stock wants to make another major run from here.
1
325
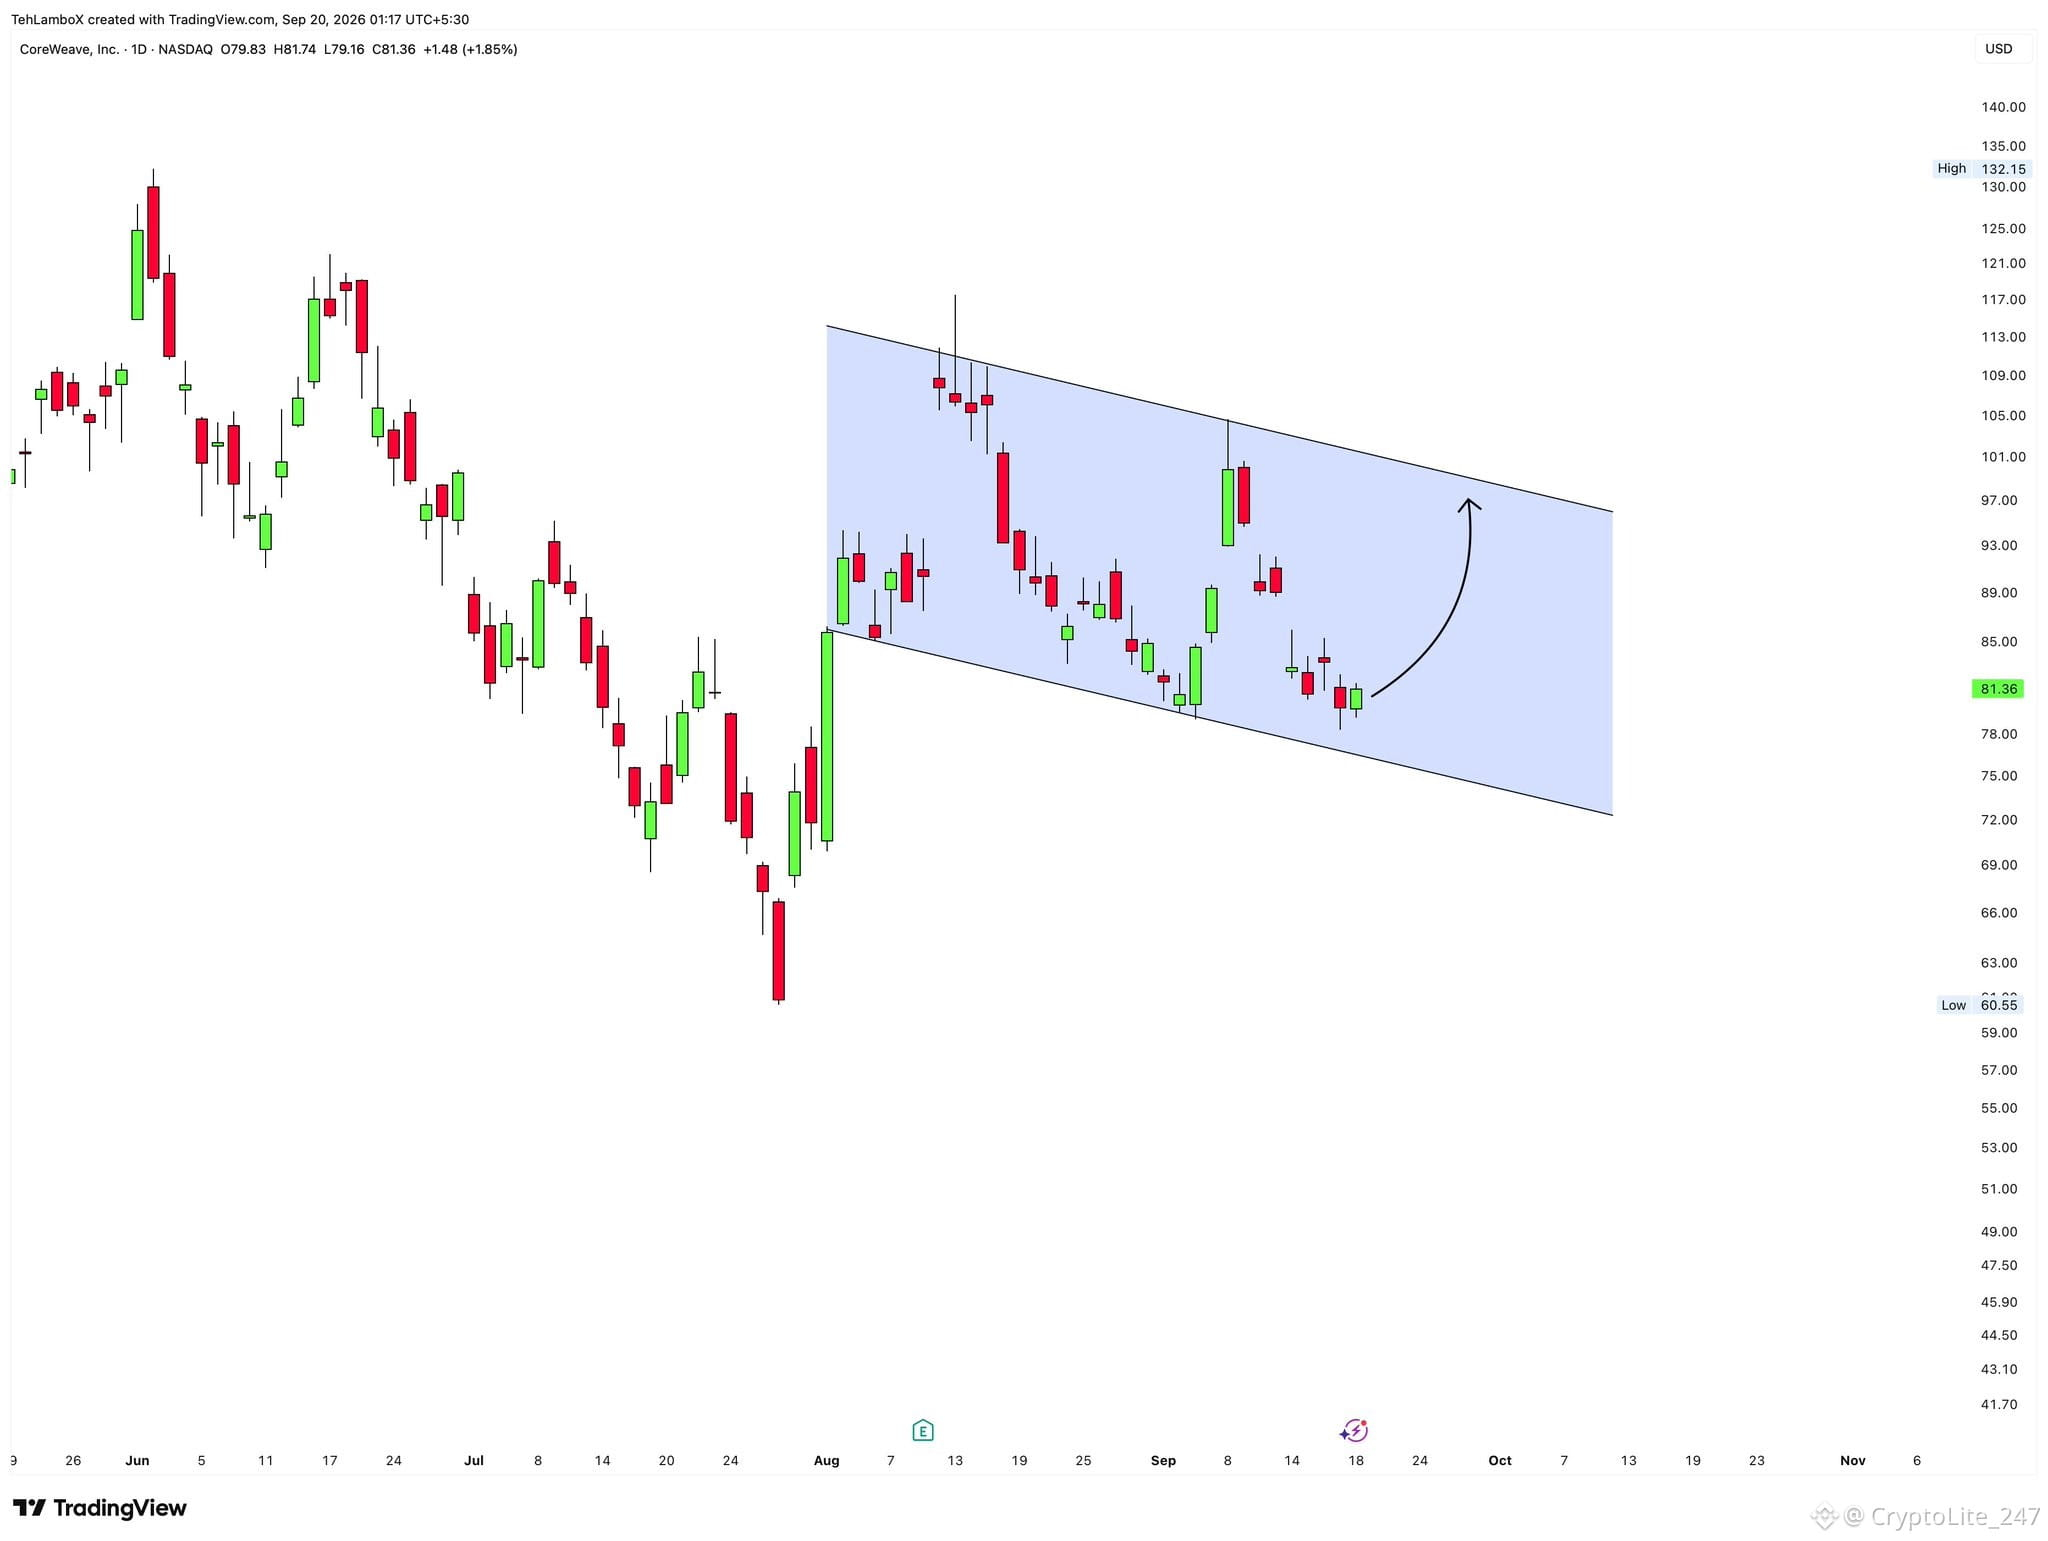
🚨ALERT: $CRWV is in a potential bull flag.
This should look to bounce off this zone from 76-80 zone towards 95 - 100 zone, a solid bounce only to the upper trendline, once the flag breaks we talk big money
🚨ALERT: $CRWV is in a potential bull flag.
This should look to bounce off this zone from 76-80 zone towards 95 - 100 zone, a solid bounce only to the upper trendline, once the flag breaks we talk big money
This should look to bounce off this zone from 76-80 zone towards 95 - 100 zone, a solid bounce only to the upper trendline, once the flag breaks we talk big money
1
330
·
--
Bullish
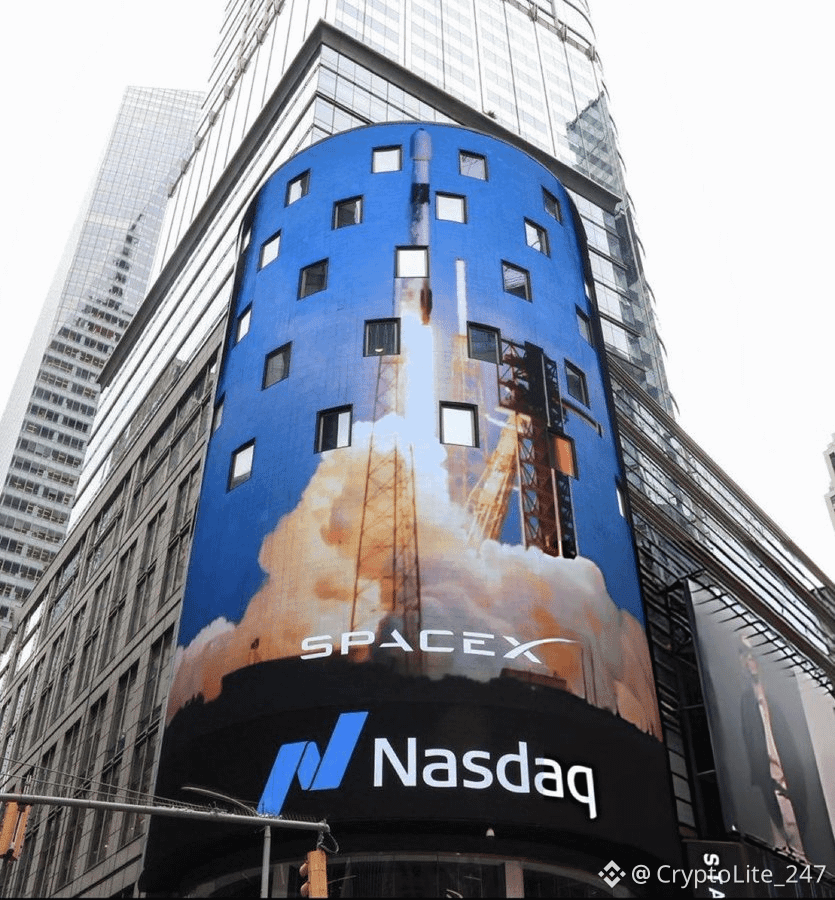
BREAKING: $SPCX ’s Nasdaq-100 weight has been confirmed at 2.82% in the latest rebalance, more than double its initial 1.34% weight.
SpaceX will make up 2.82% of the Nasdaq 100 when the index's quarterly rebalance takes effect this Monday.
BREAKING: $SPCX ’s Nasdaq-100 weight has been confirmed at 2.82% in the latest rebalance, more than double its initial 1.34% weight.
SpaceX will make up 2.82% of the Nasdaq 100 when the index's quarterly rebalance takes effect this Monday.
SpaceX will make up 2.82% of the Nasdaq 100 when the index's quarterly rebalance takes effect this Monday.
2
179
·
--
Bullish
$IREN
{future}(IRENUSDT)
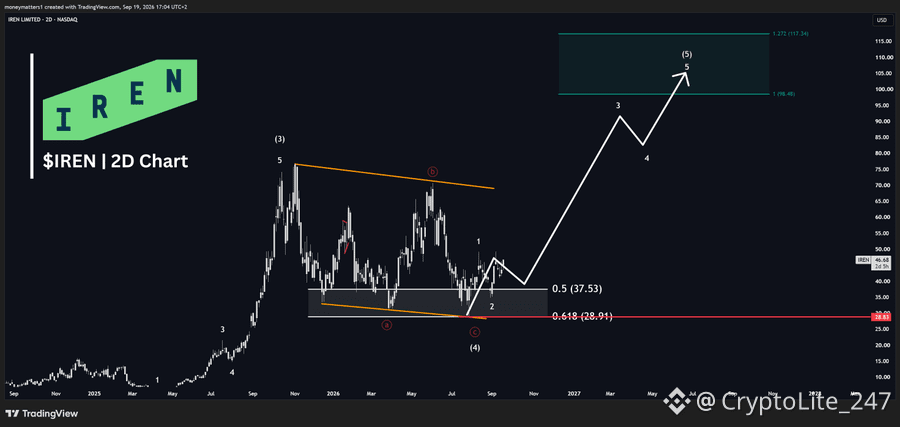
is one of the most overlooked setups in the entire market right now.
Fundamentals have significantly improved over the last months, while price has struggled to find support.
But this phase is probably over now.
We've already seen the first move to build a strong impulse towards $100+.
If momentum and volume can follow up now, this will probably be one of the best performing stocks over the next months.
Save this and thank me in 3 months.
$IREN
is one of the most overlooked setups in the entire market right now.
Fundamentals have significantly improved over the last months, while price has struggled to find support.
But this phase is probably over now.
We've already seen the first move to build a strong impulse towards $100+.
If momentum and volume can follow up now, this will probably be one of the best performing stocks over the next months.
Save this and thank me in 3 months.
is one of the most overlooked setups in the entire market right now.
Fundamentals have significantly improved over the last months, while price has struggled to find support.
But this phase is probably over now.
We've already seen the first move to build a strong impulse towards $100+.
If momentum and volume can follow up now, this will probably be one of the best performing stocks over the next months.
Save this and thank me in 3 months.
2
191
The $NBIS ATM is still technically alive, but the numbers make me far less worried about it.
Nebius sold 12.73M of the 25M authorized shares through June 30 at an average $223.60, raising $2.85B gross. that leaves 12.27M shares or ~49% of the program.
Here’s what matters: the late-July share count barely moved, suggesting they weren’t blindly dumping stock after Q2.
Even assuming every remaining share gets sold, we’re talking roughly $2.7B of additional capital at ~$218 for only ~4–5% incremental dilution.
And I suspect 9–12M shares may still remain.
So yes, there’s an overhang. But I’m not losing sleep over 4–5% dilution if Nebius can recycle that capital into AI capacity generating today’s contract economics.
Dilution without adequate returns destroys value.
Dilution funding high-return capacity can create it.
The $NBIS ATM is still technically alive, but the numbers make me far less worried about it.
Nebius sold 12.73M of the 25M authorized shares through June 30 at an average $223.60, raising $2.85B gross. that leaves 12.27M shares or ~49% of the program.
Here’s what matters: the late-July share count barely moved, suggesting they weren’t blindly dumping stock after Q2.
Even assuming every remaining share gets sold, we’re talking roughly $2.7B of additional capital at ~$218 for only ~4–5% incremental dilution.
And I suspect 9–12M shares may still remain.
So yes, there’s an overhang. But I’m not losing sleep over 4–5% dilution if Nebius can recycle that capital into AI capacity generating today’s contract economics.
Dilution without adequate returns destroys value.
Dilution funding high-return capacity can create it.
Nebius sold 12.73M of the 25M authorized shares through June 30 at an average $223.60, raising $2.85B gross. that leaves 12.27M shares or ~49% of the program.
Here’s what matters: the late-July share count barely moved, suggesting they weren’t blindly dumping stock after Q2.
Even assuming every remaining share gets sold, we’re talking roughly $2.7B of additional capital at ~$218 for only ~4–5% incremental dilution.
And I suspect 9–12M shares may still remain.
So yes, there’s an overhang. But I’m not losing sleep over 4–5% dilution if Nebius can recycle that capital into AI capacity generating today’s contract economics.
Dilution without adequate returns destroys value.
Dilution funding high-return capacity can create it.
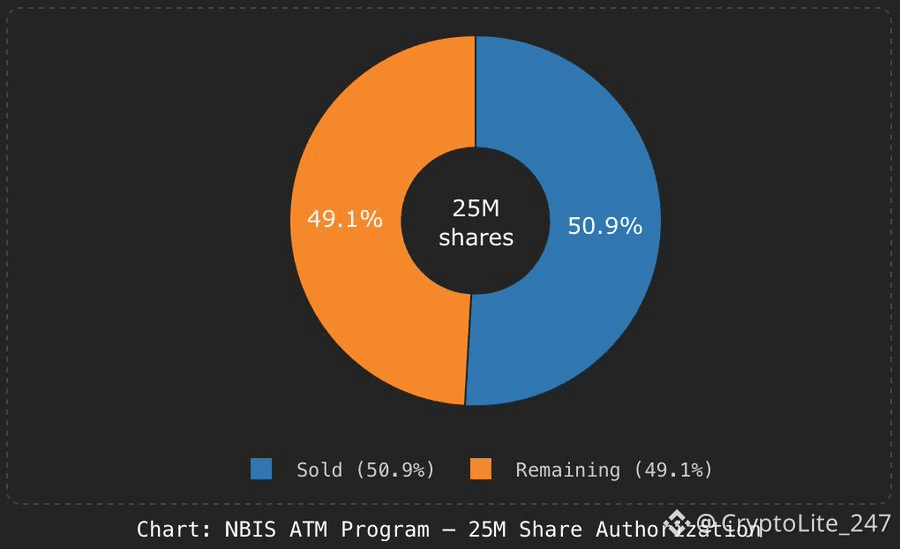
2
297
·
--
Bullish
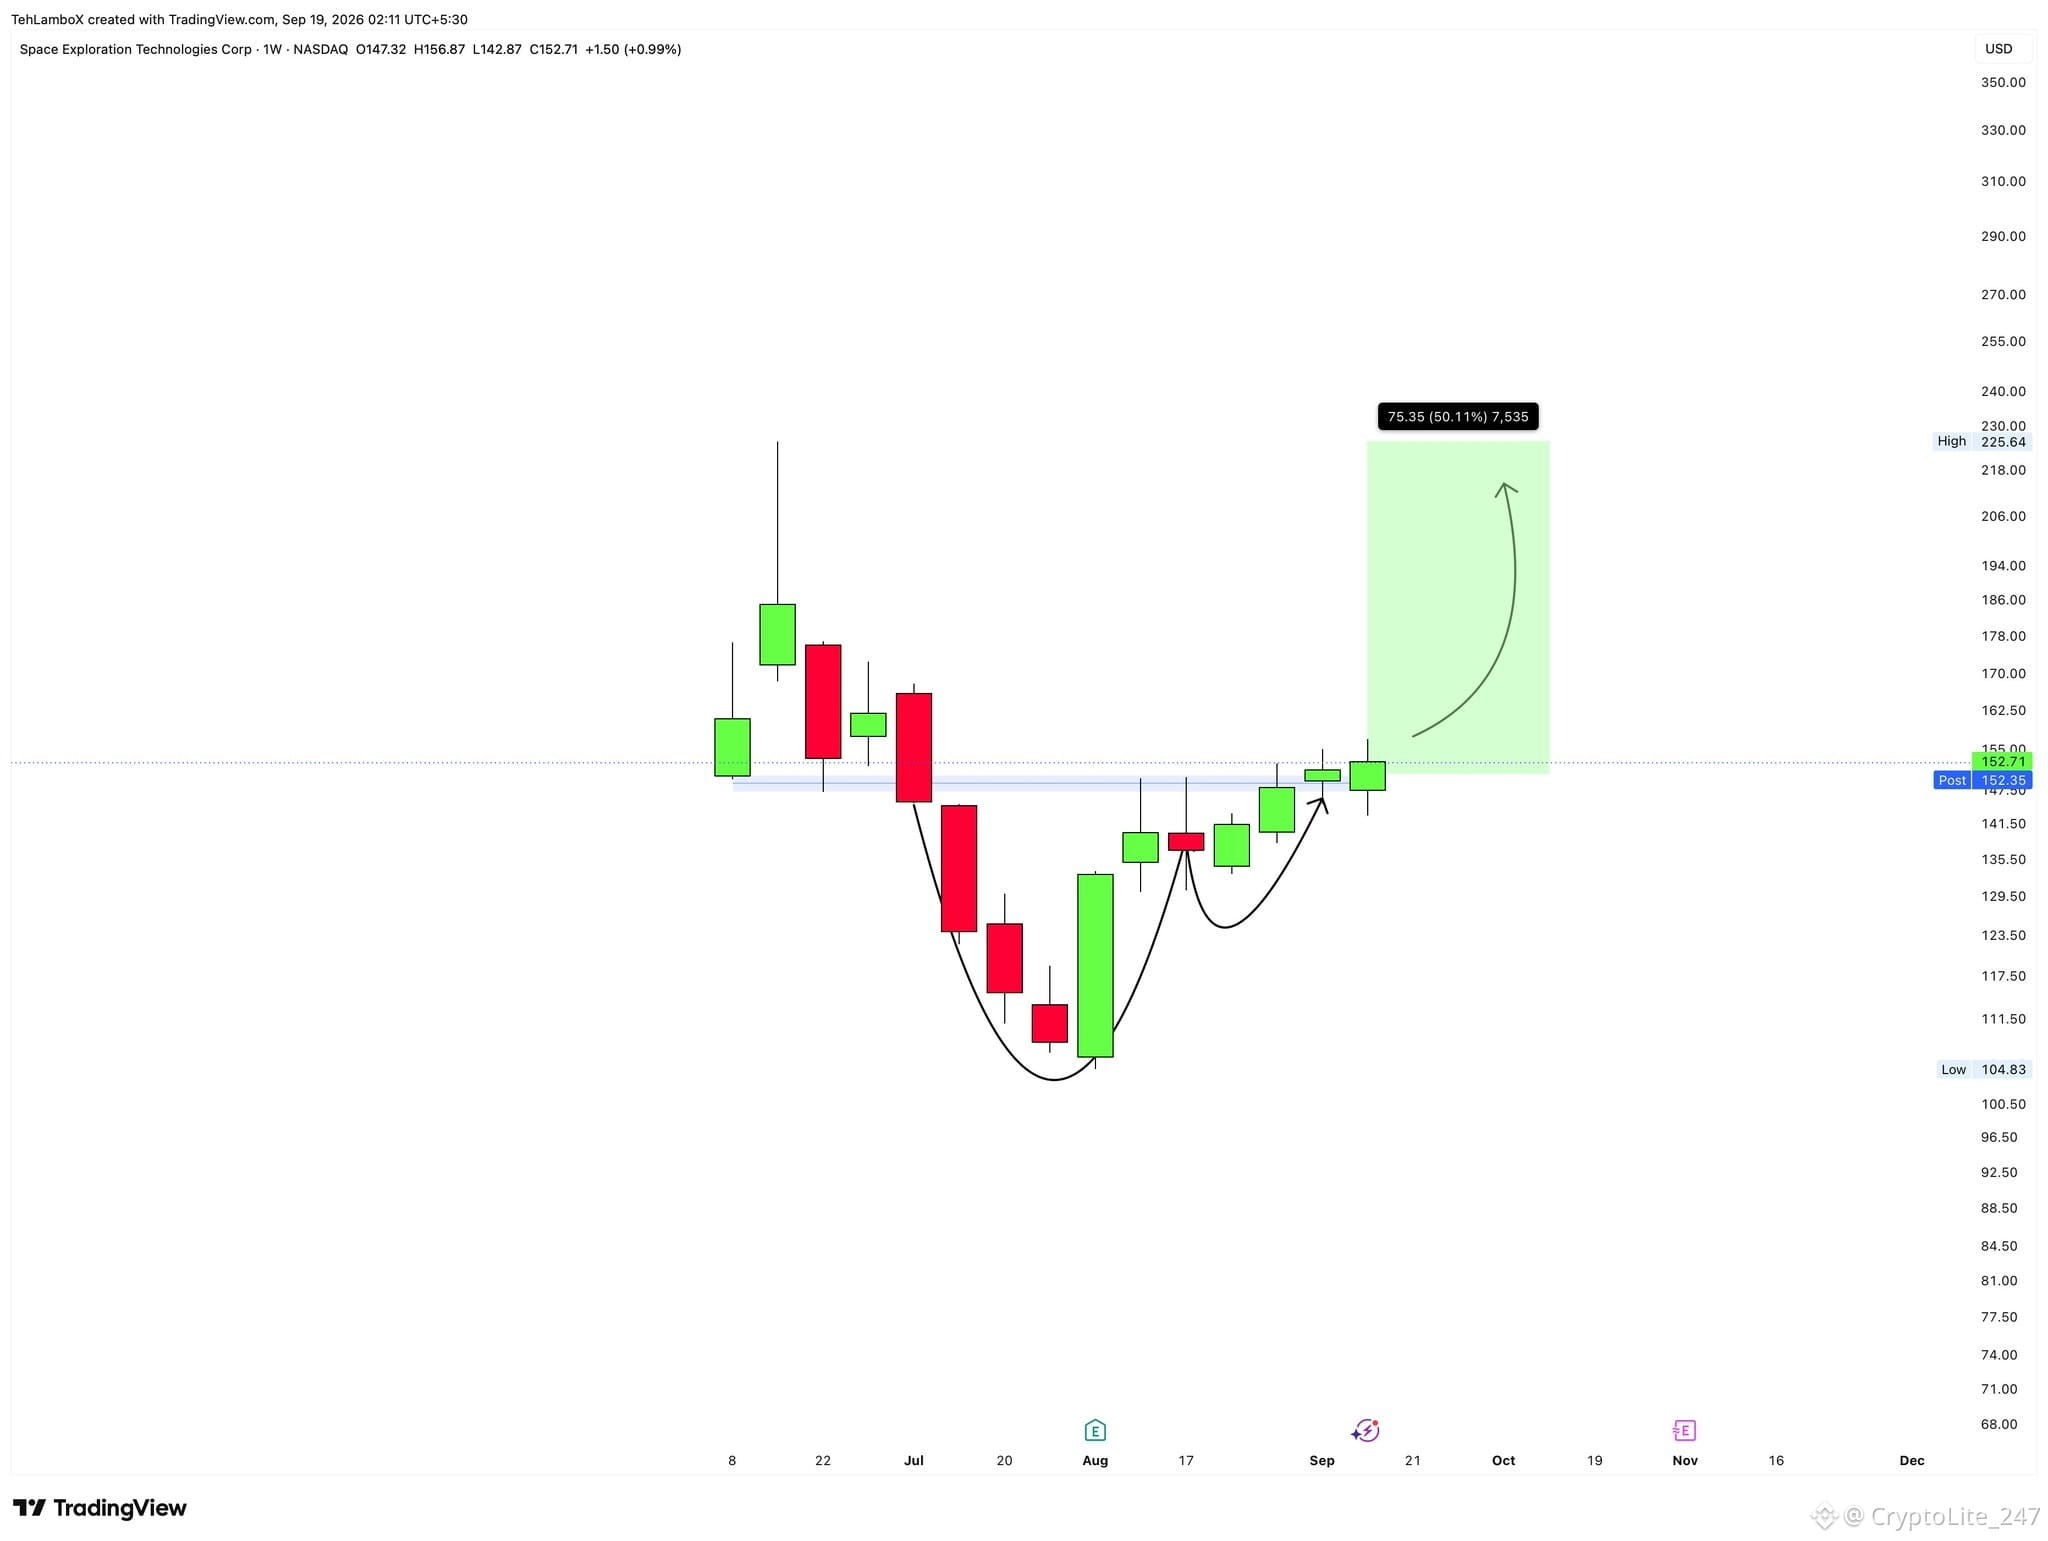
🚨BULLISH: $SPCX Closed second weekly candle above the resistance back to back.
Are we ready for the moon shot next week?
🚨BULLISH: $SPCX Closed second weekly candle above the resistance back to back.
Are we ready for the moon shot next week?
Are we ready for the moon shot next week?
1
521
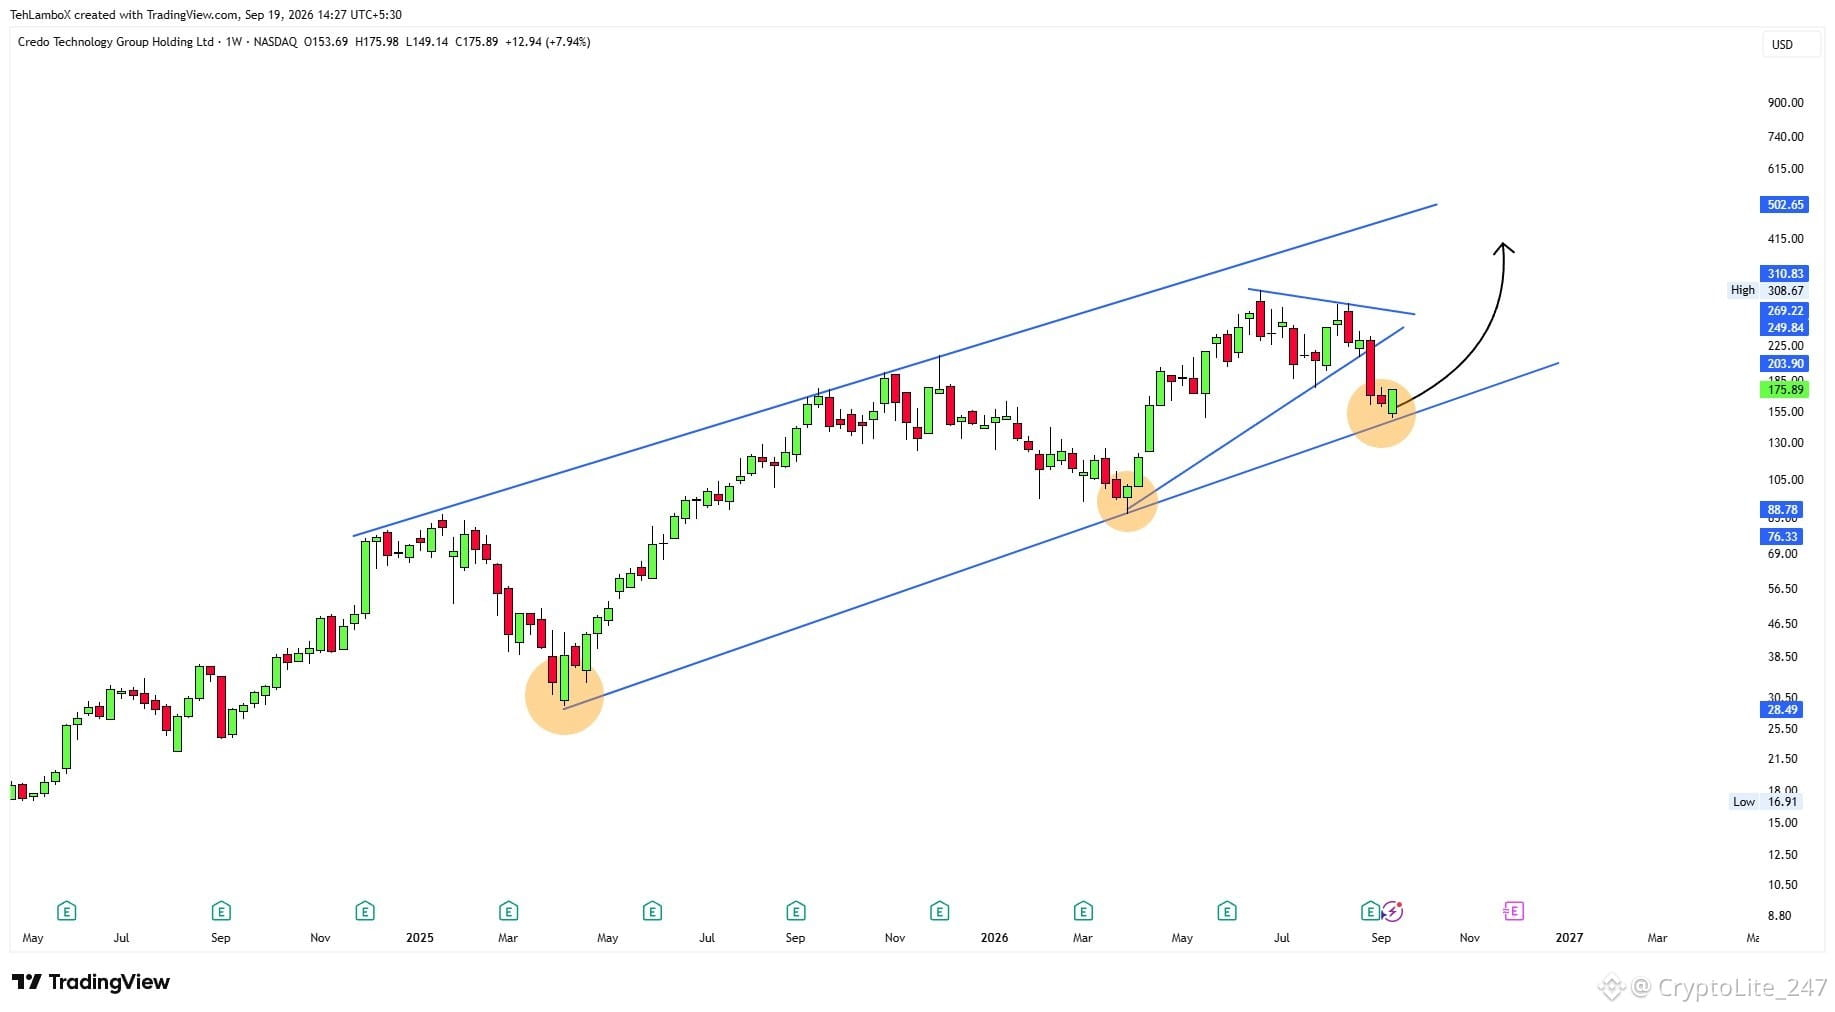
🚨 $CRDO : 17% bounce captured
But wait? This has potential for a lot more, I would put the targets towards 200 and then 225 atleast here.
Longer term, I see 400 or even 500. YES, this is the kind of support we bounced off, last time almost did a 4x off this support only so yes I am Bullish.
🚨 $CRDO : 17% bounce captured
But wait? This has potential for a lot more, I would put the targets towards 200 and then 225 atleast here.
Longer term, I see 400 or even 500. YES, this is the kind of support we bounced off, last time almost did a 4x off this support only so yes I am Bullish.
But wait? This has potential for a lot more, I would put the targets towards 200 and then 225 atleast here.
Longer term, I see 400 or even 500. YES, this is the kind of support we bounced off, last time almost did a 4x off this support only so yes I am Bullish.
1
581
Anthropic, OpenAI, $SPCX and $GOOGL were SUED in federal court over allegations they illegally coordinated to slow AI development.
The lawsuit argues Dario Amodei’s call for “industry-wide coordination” to “pace the frontier,” later supported by $TSLA CEO Elon Musk, Sam Altman and Demis Hassabis, amounted to an antitrust violation between competitors.
The companies had not responded to Politico’s requests for comment as of publication.
Anthropic, OpenAI, $SPCX and $GOOGL were SUED in federal court over allegations they illegally coordinated to slow AI development.
The lawsuit argues Dario Amodei’s call for “industry-wide coordination” to “pace the frontier,” later supported by $TSLA CEO Elon Musk, Sam Altman and Demis Hassabis, amounted to an antitrust violation between competitors.
The companies had not responded to Politico’s requests for comment as of publication.
The lawsuit argues Dario Amodei’s call for “industry-wide coordination” to “pace the frontier,” later supported by $TSLA CEO Elon Musk, Sam Altman and Demis Hassabis, amounted to an antitrust violation between competitors.
The companies had not responded to Politico’s requests for comment as of publication.
5
3.6k
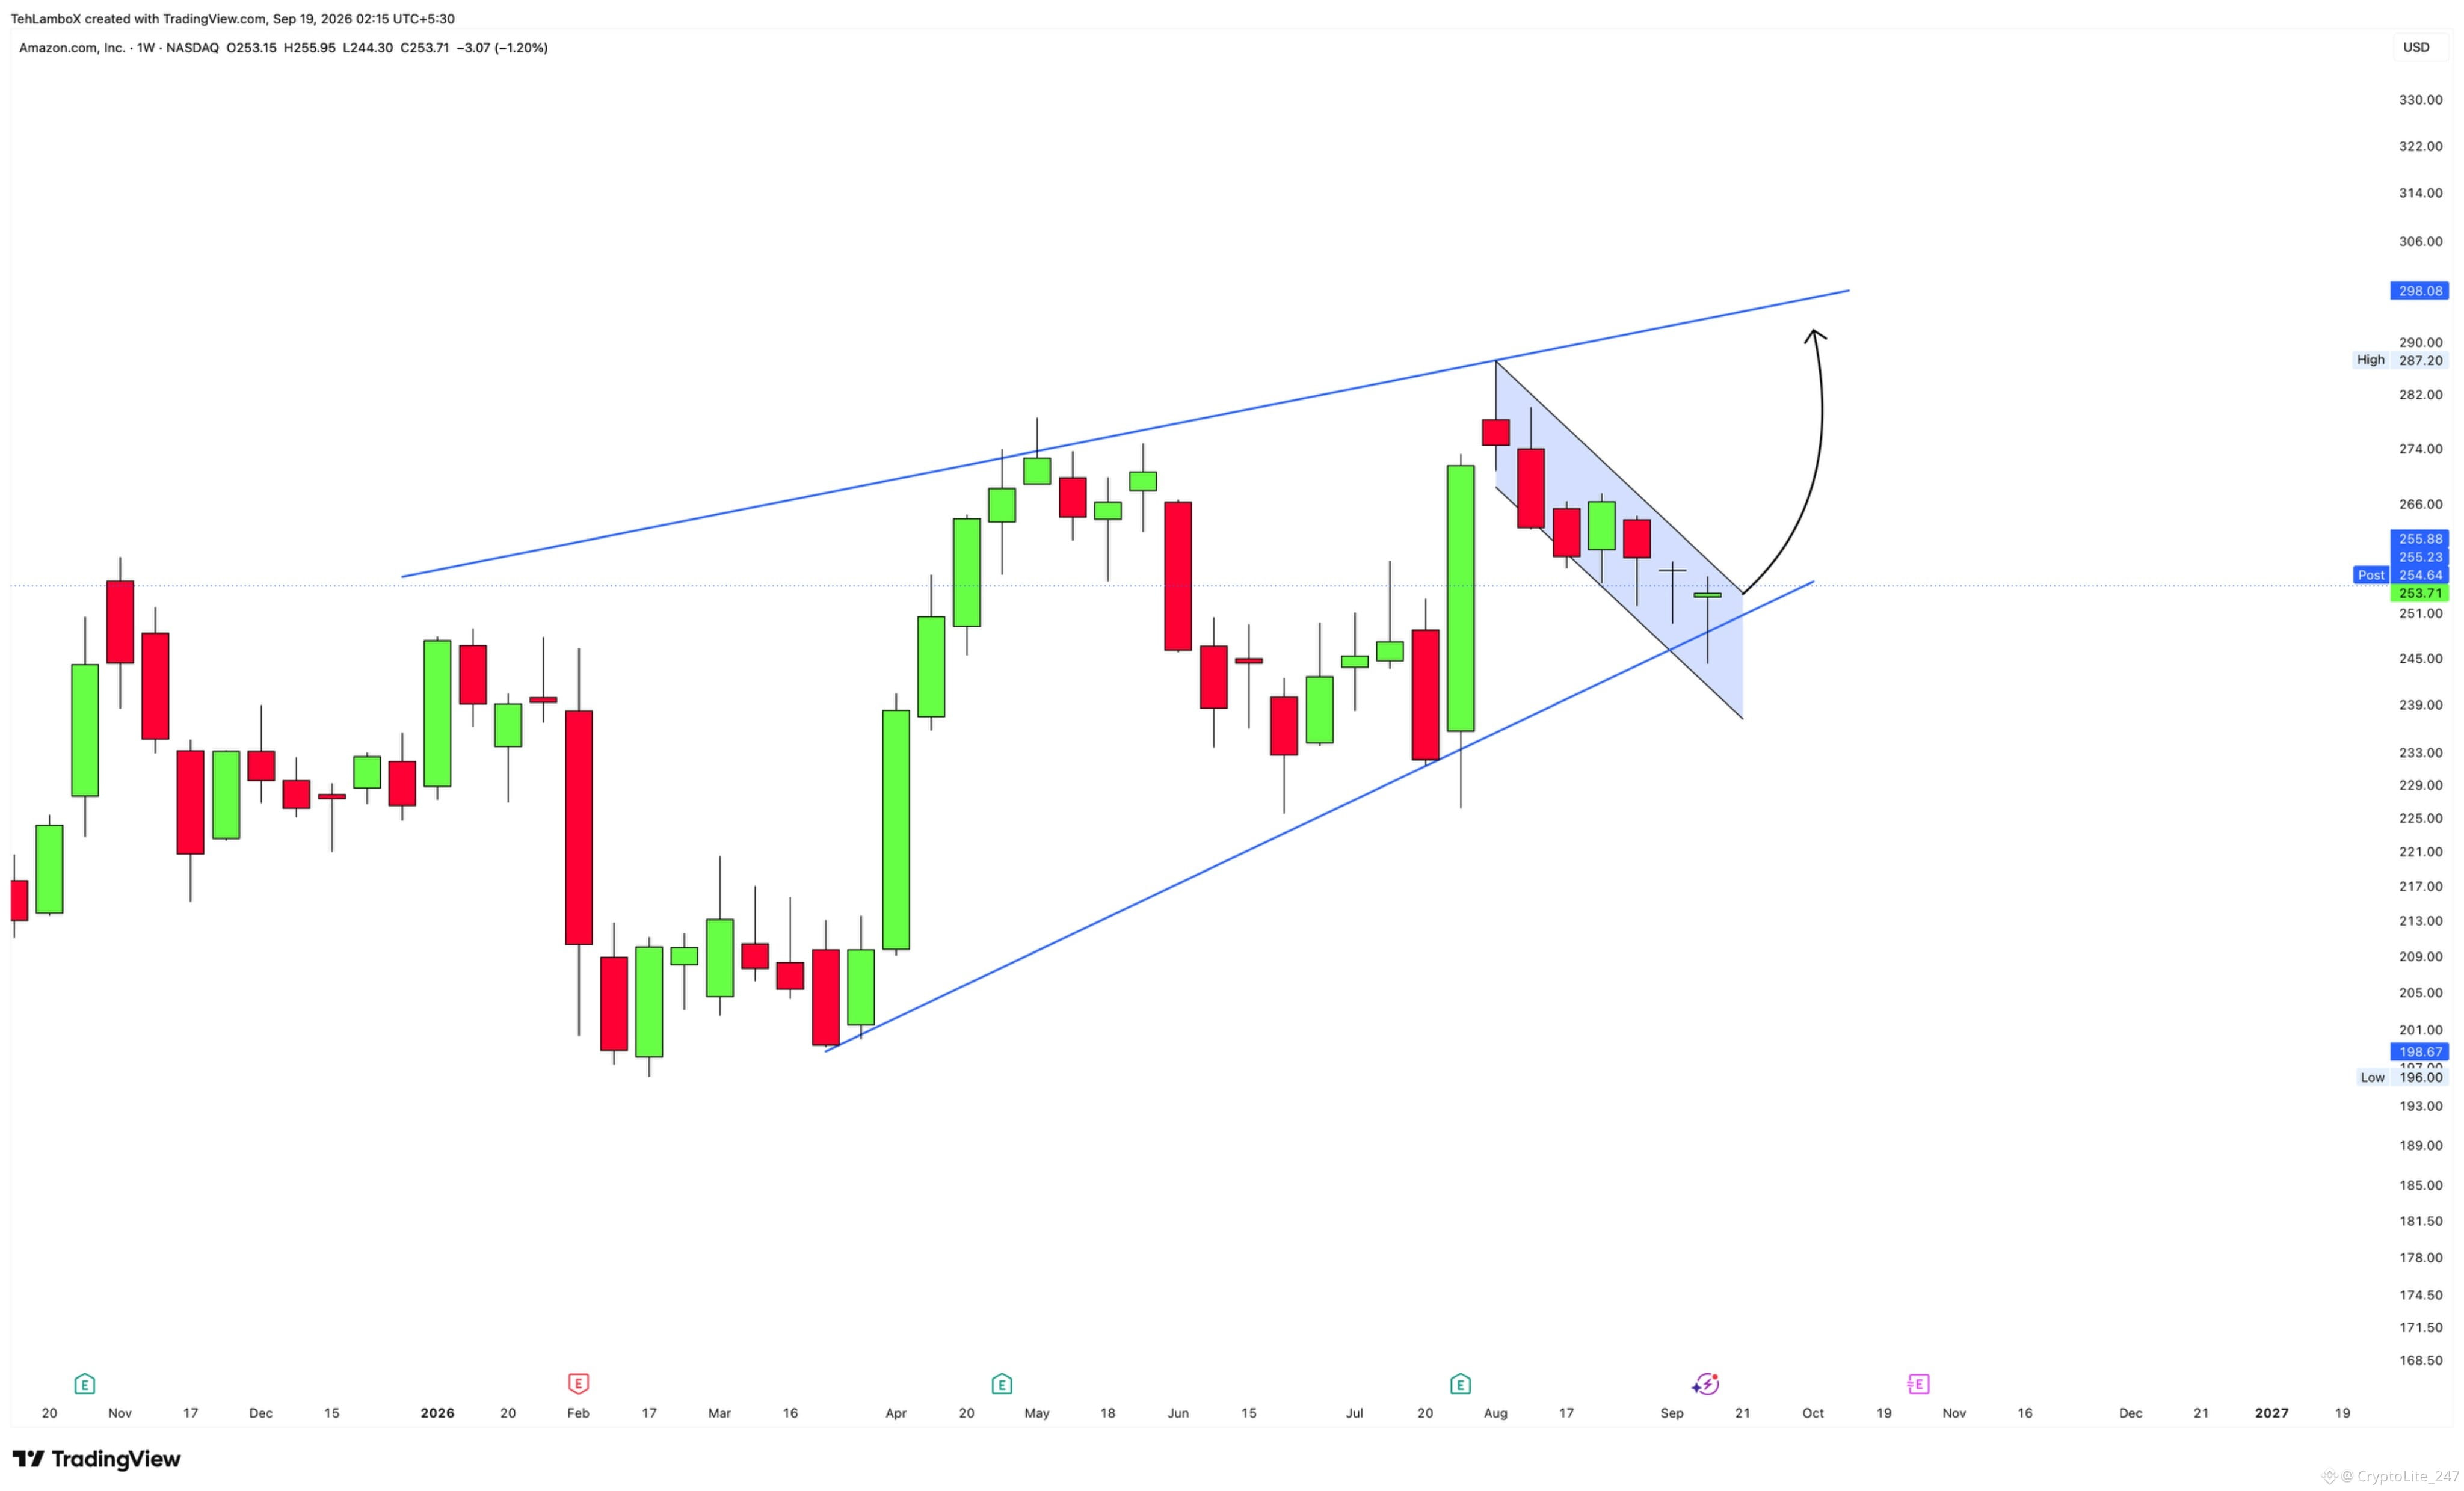
🚨UPDATE: $AMZN is now ready to bounce?
This looks like it has bounced off the lower trendline, ready to breakout above 260 and then target 295-300 in the near future.
I called this to fall from 266 and it for almost 8% towards 245. Follow me if you don't want to miss the next post.
🚨UPDATE: $AMZN is now ready to bounce?
This looks like it has bounced off the lower trendline, ready to breakout above 260 and then target 295-300 in the near future.
I called this to fall from 266 and it for almost 8% towards 245. Follow me if you don't want to miss the next post.
This looks like it has bounced off the lower trendline, ready to breakout above 260 and then target 295-300 in the near future.
I called this to fall from 266 and it for almost 8% towards 245. Follow me if you don't want to miss the next post.
1
475
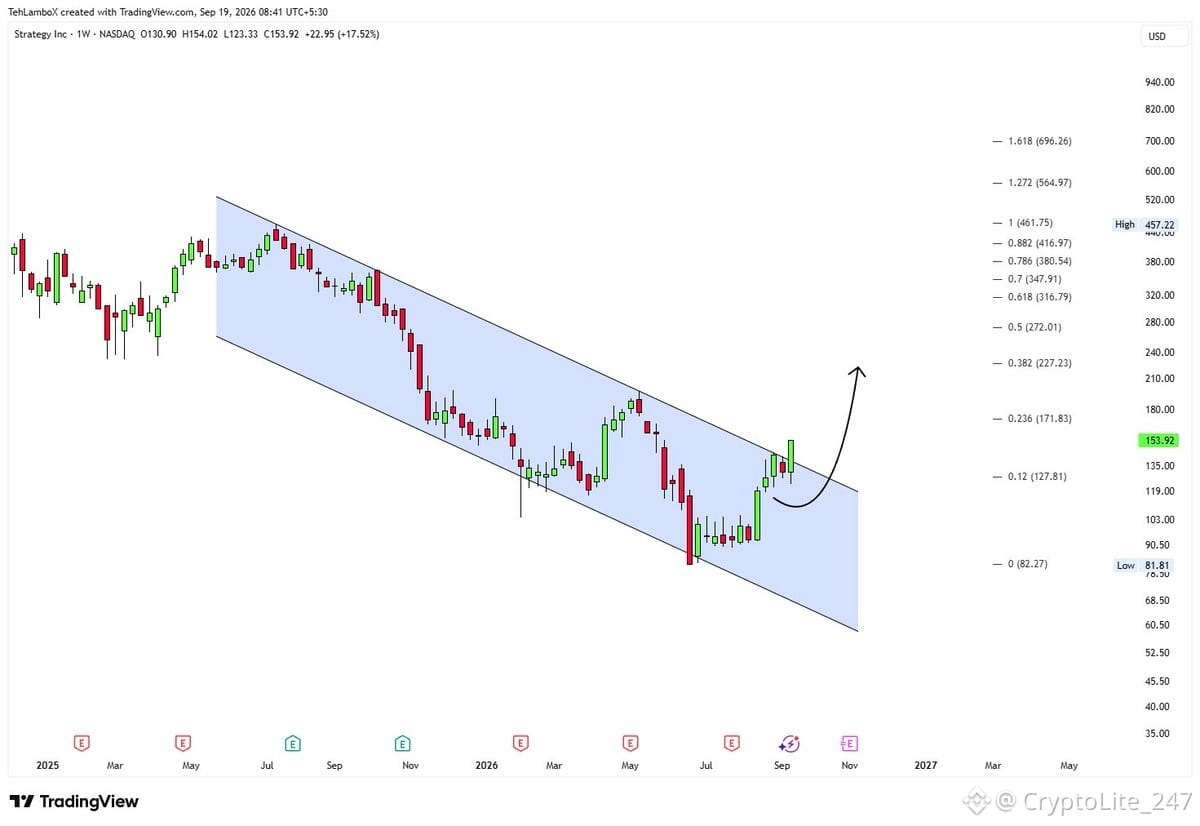
🚨UPDATE: $MSTR Has broken out on the weekly here.
This looks likely to test 171 next week as $BTC is looking hot and ready to run past 82k over the weekend. An interesting one to add to the watchlist.
🚨UPDATE: $MSTR Has broken out on the weekly here.
This looks likely to test 171 next week as $BTC is looking hot and ready to run past 82k over the weekend. An interesting one to add to the watchlist.
This looks likely to test 171 next week as $BTC is looking hot and ready to run past 82k over the weekend. An interesting one to add to the watchlist.
1
599
·
--
Bullish
Verified
BREAKING: NASA awards $SPCX
{future}(SPCXUSDT)
SpaceX $946 million for three more crew flights to the ISS.
SpaceX will fly Crew-15, Crew-16 and Crew-17, bringing its total NASA crew missions to 17. This deal covers launch, orbit, return, recovery, cargo and lifeboat services through 2030.
BREAKING: NASA awards $SPCX
SpaceX $946 million for three more crew flights to the ISS.
SpaceX will fly Crew-15, Crew-16 and Crew-17, bringing its total NASA crew missions to 17. This deal covers launch, orbit, return, recovery, cargo and lifeboat services through 2030.
SpaceX $946 million for three more crew flights to the ISS.
SpaceX will fly Crew-15, Crew-16 and Crew-17, bringing its total NASA crew missions to 17. This deal covers launch, orbit, return, recovery, cargo and lifeboat services through 2030.
1
1
871
·
--
Bullish
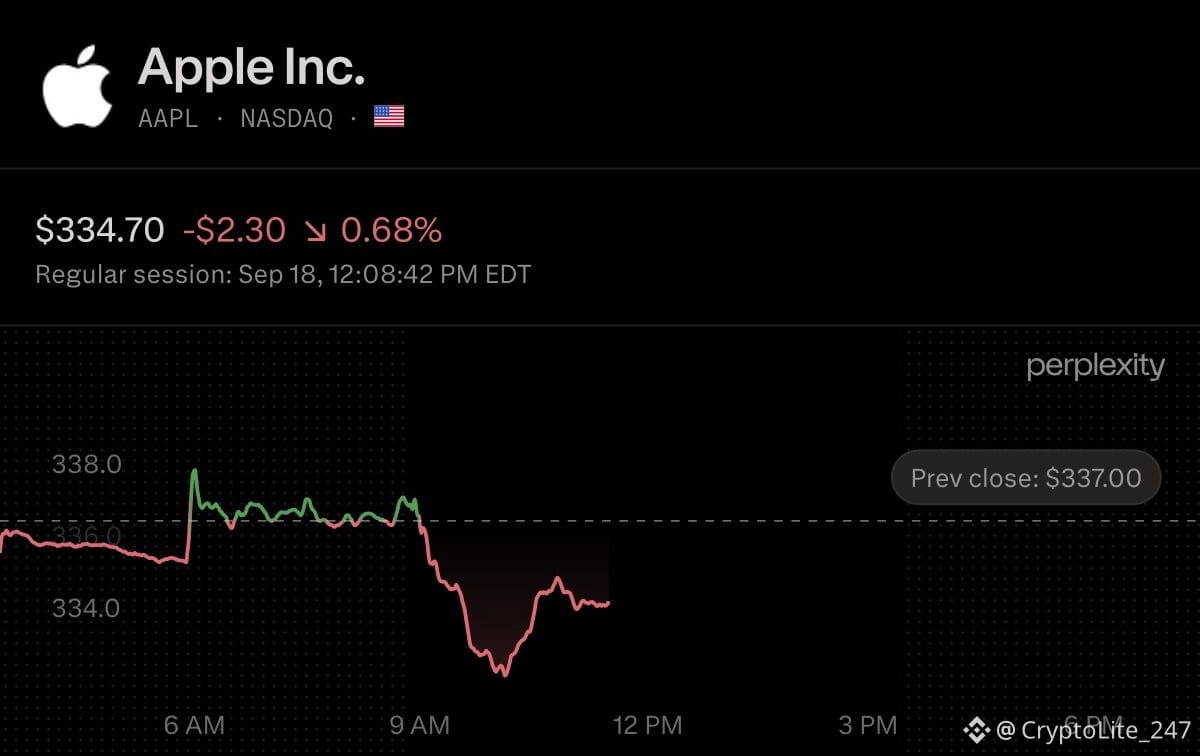
Jefferies says early iPhone 18 Pro/Pro Max demand is showing weakness and expects $AAPL could cut orders in October.
U.S. lead times remain at zero, while 18 Pro Max resale premiums are just 1%-8% versus 15%-29% for the 17 Pro Max last year.
Jefferies also expects the upcoming Duo to cannibalize 18 Pro/Pro Max sales, especially the Pro Max, making Apple’s planned ~15% YoY production increase harder to achieve.
Jefferies says early iPhone 18 Pro/Pro Max demand is showing weakness and expects $AAPL could cut orders in October.
U.S. lead times remain at zero, while 18 Pro Max resale premiums are just 1%-8% versus 15%-29% for the 17 Pro Max last year.
Jefferies also expects the upcoming Duo to cannibalize 18 Pro/Pro Max sales, especially the Pro Max, making Apple’s planned ~15% YoY production increase harder to achieve.
U.S. lead times remain at zero, while 18 Pro Max resale premiums are just 1%-8% versus 15%-29% for the 17 Pro Max last year.
Jefferies also expects the upcoming Duo to cannibalize 18 Pro/Pro Max sales, especially the Pro Max, making Apple’s planned ~15% YoY production increase harder to achieve.
1
166
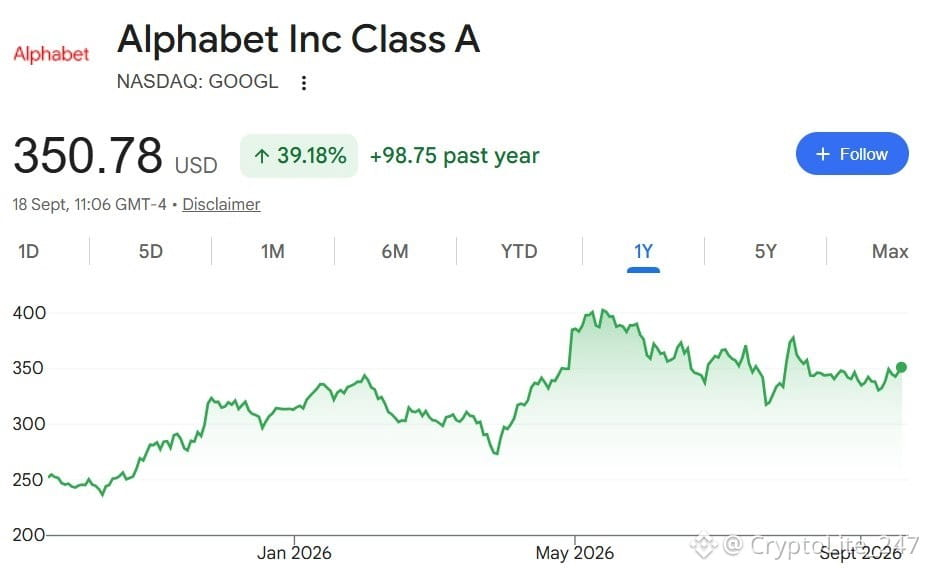
There was a big analyst upgrade for $GOOGL today from Tigress Financial, who kept their strong buy recommendation, but upped their price target from $415 to $485.
Meanwhile it was announced that Waymo, one of Alphabet's subsidiary companies, will be introducing a fully autonomous EV ride-hailing service in Singapore in 2028.
This follows on from the news earlier this week that they will be launching a driverless commercial taxi service in Tokyo in 2027.
So this is more evidence that Waymo will be expanding rapidly in the next few years, and is obviously positive news for anyone who is indirectly invested in them through Alphabet.
There was a big analyst upgrade for $GOOGL today from Tigress Financial, who kept their strong buy recommendation, but upped their price target from $415 to $485.
Meanwhile it was announced that Waymo, one of Alphabet's subsidiary companies, will be introducing a fully autonomous EV ride-hailing service in Singapore in 2028.
This follows on from the news earlier this week that they will be launching a driverless commercial taxi service in Tokyo in 2027.
So this is more evidence that Waymo will be expanding rapidly in the next few years, and is obviously positive news for anyone who is indirectly invested in them through Alphabet.
Meanwhile it was announced that Waymo, one of Alphabet's subsidiary companies, will be introducing a fully autonomous EV ride-hailing service in Singapore in 2028.
This follows on from the news earlier this week that they will be launching a driverless commercial taxi service in Tokyo in 2027.
So this is more evidence that Waymo will be expanding rapidly in the next few years, and is obviously positive news for anyone who is indirectly invested in them through Alphabet.
1
311
$AMZN AWS and $SAP.US signed a 5-year partnership to bring SAP Business AI to seven more regions including India, Japan, the UK and Brazil.
That puts SAP’s AI stack closer to more enterprise customers while AWS captures the infrastructure underneath it.
$AMZN AWS and $SAP.US signed a 5-year partnership to bring SAP Business AI to seven more regions including India, Japan, the UK and Brazil.
That puts SAP’s AI stack closer to more enterprise customers while AWS captures the infrastructure underneath it.
That puts SAP’s AI stack closer to more enterprise customers while AWS captures the infrastructure underneath it.
AMZN-0.35%
SAPUS-1.95%
1
1
366
·
--
Bullish
Verified
BREAKING: $SPCX could see up to $22 billion in passive buying today.
SpaceX’s Nasdaq-100 weighting is expected to more than double from 1.28% to 2.82% after more shares became available for public trading.
Passive funds are expected to increase their SpaceX holdings at today’s closing auction before the new weight takes effect Monday.
BREAKING: $SPCX could see up to $22 billion in passive buying today.
SpaceX’s Nasdaq-100 weighting is expected to more than double from 1.28% to 2.82% after more shares became available for public trading.
Passive funds are expected to increase their SpaceX holdings at today’s closing auction before the new weight takes effect Monday.
SpaceX’s Nasdaq-100 weighting is expected to more than double from 1.28% to 2.82% after more shares became available for public trading.
Passive funds are expected to increase their SpaceX holdings at today’s closing auction before the new weight takes effect Monday.
1
5
12.4k
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
BOJRaisesRatesTo31YearHigh
133,208 views
2,066 Discussing
#BOJRaisesRatesTo31YearHigh
#BOJRaisesRatesTo31YearHigh 🇯🇵📈
The Bank of Japan has taken another major step by raising interest rates to their highest level in 31 years, putting global markets on alert. The move signals a continued shift away from Japan’s long-standing ultra-loose monetary policy. Higher Japanese rates could strengthen the yen, influence global bond yields, and potentially impact capital flows across financial markets. Crypto and risk assets may also react as investors reassess liquidity and risk exposure. Traders are now watching the BOJ’s next statements closely for clues about future rate decisions. Volatility could increase as markets digest the policy change and its potential global impact. #BOJ #Japan #Crypto #Markets #InterestRates $NVDAB
maqsoodahmed1
·1 Likes
·148 views
BuffettStepsDownAsBerkshireChairman
63,290 views
1,027 Discussing
XRPExchangeReservesHitSevenYearLow
68,116 views
953 Discussing