

PIZZA看加密
960 Posts
PIZZA看加密
 Square Verified
Report
Block User
我瞎说我的,您随意看

Macro KOL
21 Following
337 Followers
468 Liked
1 Badges
Posts
·
--
Verified
2Z is down nearly 19%, and I’m still bearish on the coming week
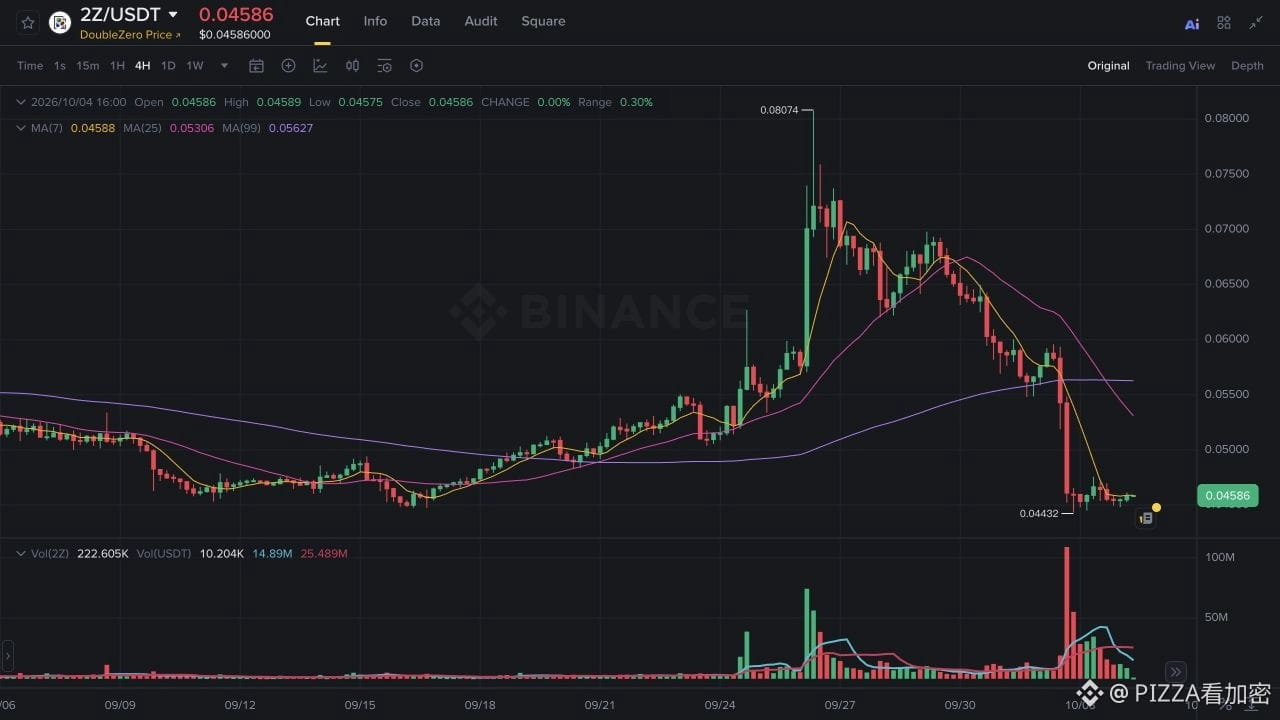
Over the next 3 to 7 days, I’m bearish on $2Z. In October, we enter the first-year unlock window that was originally disclosed. The amount of potential sellable supply increases, but the price is still stuck near the lows after the sharp selloff. What I’m more worried about is that any rebound may run into sell orders and then get pushed back down again.
I care more about how much the supply is actually going to increase. In the monthly circulation plan published by Upbit, at the end of September there are about 3.47 billion tokens, and at the end of October about 5.11 billion—an increase of roughly 47%. This is the month-end arrangement from the original disclosure; it may be adjusted, and it can’t be used to prove how many tokens are entering exchanges today or how many are being sold. But as restrictions are lifted, holders who previously couldn’t sell can now choose to sell as well. That means we’ll need more buy-side demand to absorb the selling.
The price also hasn’t given me confidence to catch a bottom. Using Binance UTC daily candles: on October 2, the drop from open to close was about 18.8%. As of today at 16:05 Beijing time, 2Z/USDT is around 0.04585, still near the low of that down day’s daily candle. The decline isn’t small—but how cheap it is versus how much selling pressure has been digested are two different things.
The bullish side has one reason worth taking seriously: the unlock schedule was disclosed long ago, so this selloff may have already priced in the concern in advance—and it may not drop again in another leg. I agree with that: you shouldn’t assume it will keep falling just because there’s an unlock. The issue now is that the rebound hasn’t yet reclaimed the range that was lost during the drop. For that reason, I’m more inclined to think the selling pressure is still being digested, and a short-term rebound is likely to be pushed back down again.
I’ll be watching the 0.055 to 0.057 USDT area—close to the low and the closing price around October 1. If the price returns to that zone and then continues with two consecutive UTC daily candles closing above 0.057, I’ll withdraw my bearish view for this week. Until then, just moving sideways near the lows isn’t enough for me to treat it as a reversal.
#2Z #代币解锁 #cryptocurrency
234
·
--
Verified
BTC to watch ISM tomorrow night. I’m bearish on this rebound.
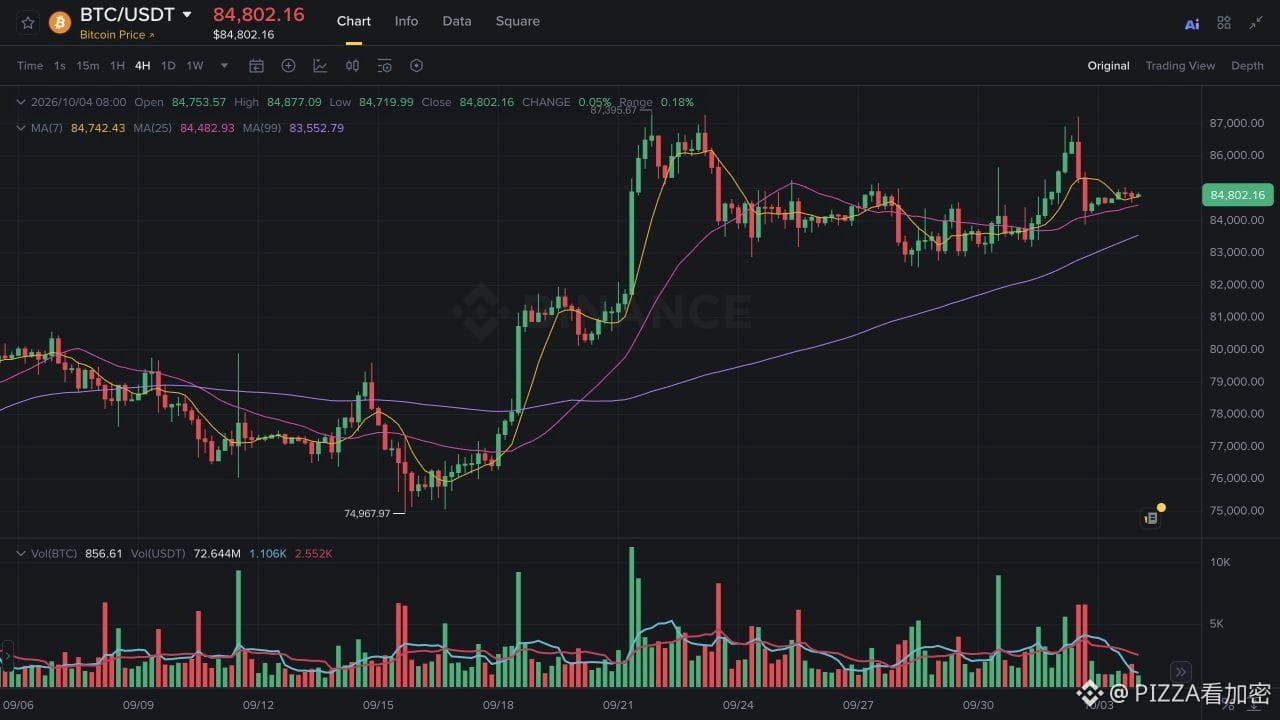
Over the next two days, I’m bearish on $BTC . This weekend’s rebound hasn’t yet recovered to the position it was before Friday’s drop. Tomorrow night, the U.S. services sector data will answer another question: has the wage/price pressure from firms easing or not? If price pressure is still worsening, I think this rebound is more likely to come under pressure again.
At 22:00 Beijing time on October 5, ISM will release its September services report. I’ll first look at the price components. In the previous August report, the employment index was only 47.8, yet the prices index rose from 70.3 to 72.6. When hiring weakness and rising procurement costs happen at the same time, relying on employment weakening to expect rate cuts isn’t a sufficient rationale.
The Federal Reserve just raised rates by 25 basis points in September, and its statement also clearly said inflation is still too high. If service businesses continue to face price pressure, it will be even harder for the Fed to ease. It would also be more difficult for BTC to attract buy-side demand just through rate cuts. This is my main reason for being bearish.
The coin price hasn’t given me enough bullish reasons either. On October 4 at 11:06, Binance BTC/USDT spot was around 84.8k; the four-hour candle that closed before 20:00 Beijing time on Friday was around 86.4k. This drawdown hasn’t been fully recovered yet—I take it as evidence that the rebound is weak. As for what exactly is behind the sell-off, you can’t tell from the candlesticks alone.
Tomorrow night could also give bulls an opportunity. If the price components clearly decline, and new orders don’t show obvious deterioration, then there would be grounds to believe cost pressures are easing, and the market would have more reason to expect rates to move lower. If I only see employment continuing to weaken, I’ll remain bearish. But if price pressure does truly ease, and BTC recovers and holds around 86.4k, then I will retract this call.
#BTC #加密货币 #ISM
1.9k
·
--
Verified
The jobs report is weak, and I'm not in a hurry to go long QQQ yet.
The September jobs report was on the weak side, so I remain cautious about QQQ continuing to rise next week. If employment slows, the Fed may have one fewer rate hike to consider—but if consumption and orders also weaken, then we’d have to reassess how much companies can actually earn.
In the 9/ employment report released on October 2, September added only 29,000 jobs. July and August were also revised downward by a combined 60,000. Such job growth could provide slightly less justification for the Fed to keep hiking rates. However, the Fed only raised rates by 0.25 percentage points in September. Skipping one hike is still far from starting rate cuts.
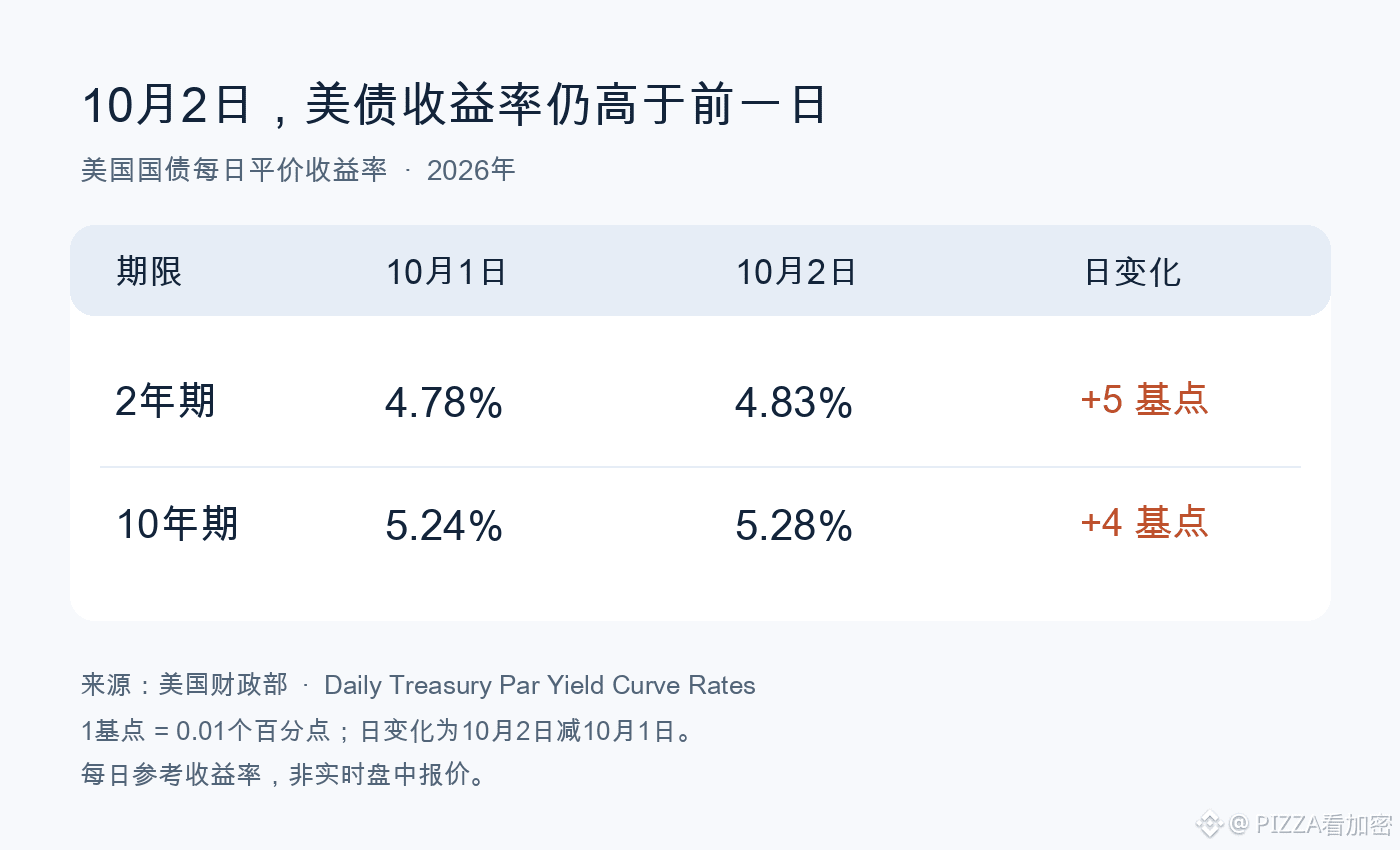
In the U.S. Treasury’s reference yields on October 2, the 2-year was 4.83% and the 10-year was 5.28%—up by 5 and 4 basis points respectively versus the previous day. There isn’t much change, so you can’t conclude that QQQ is going to fall. But there’s also no clear support for the idea that rate pressure has eased.
If employment continues to weaken, consumption and corporate orders may also be affected. Companies in QQQ could then earn less than originally expected. Employment that’s just a bit weak may ease rate-hike pressure, but if it’s too weak, the stock market may become worried.
If U.S. Treasury yields can pull back, companies’ expectations for future business won’t get worse, and I’d be more willing to look favorably on QQQ. Based on this jobs report alone, I’m still not ready to change my view.
#QQQ #美股 #JobsReport
1
1.6k
·
--
Verified
BTC surged to 87,000 again and then fell back. This non-farm report still can’t sustain a continued rally
In the next 24 to 48 hours, I’m more inclined to believe $BTC will keep chopping lower under pressure. The non-farm employment data is relatively weak and may ease concerns about further rate hikes, but Bitcoin has already given back the gains after the data release. BTC hasn’t reclaimed the pre-release price. This weekend, I’m expecting it to move higher steadily—but for now, I don’t agree with that.
On the evening of October 2 at 20:30, the US September non-farm payrolls added 290,000 jobs, below Reuters’ survey expectation of 90,000. The combined figures for July and August were also revised down by 60,000, indicating that job growth in the first two months was even lower than originally seen. Private non-farm average hourly earnings rose only 0.1% month over month, and the unemployment rate was 4.2%. This set of data provides slightly less justification for continued rate hikes.
Weaker employment could lead the Fed to hike less times, reducing one layer of interest-rate pressure on BTC. If the cost of capital doesn’t keep rising, investors may also be more willing to tolerate the volatility of holding BTC. Whether this buying interest will actually show up remains to be seen in the subsequent market.
The Fed only raised rates by 25 bps on September 16, lifting the target range for the federal funds rate to 3.75%–4.00%. The statement still says inflation is too high. This non-farm report can support the view that there may be one fewer hike, but it’s still too early to treat rate cuts as already certain.
BTC did surge briefly, then pulled back again. Binance BTC/USDT spot was around 86,616 USDT before the release, and within the first 15 minutes after the release it hit a high of 87,220. After that, it failed to hold. As of 11:02 Beijing time on October 3, it was quoted at 84,614—about 2.31% lower than the level before the release. Here, we compare before vs. after the release, not the 24-hour move.
Price can’t tell us who is selling, but this time the upside push wasn’t sustained. Even if the non-farm report gives a reason for fewer hikes, the current data still isn’t enough to interpret this weekend’s rebound as a sustained rally.
The bullish case is still there. Wage growth is slow, and the prior two months were revised down again—so employment data could indeed make the Fed more cautious about continuing rate hikes. An unemployment rate of 4.2% also isn’t enough on its own to prove that the US has already entered a recession. Writing weak non-farm data as “BTC must fall” is equally over the top.
For now, I’ll use the area around 86,600 USDT to test the rebound. This is the actual price before the release, used to compare the走势 before and after the news. If BTC reclaims this zone and holds it, I’ll withdraw my view that the weekend is relatively weak; if it only bounces briefly and then falls back again, the explanation that it remains under pressure to consolidate will have more support. You can open the BTC chart to cross-check this condition.
#BTC #非农 #Federal Reserve
1
1.6k
·
--
Verified
Nike wants to save $2.5 billion—so why is the stock still under pressure?
After this earnings report from Nike, I’m more inclined to think the stock price will remain under pressure for the next two to four weeks. The company expects to earn less this fiscal year than analysts currently estimate, and its $2.5 billion cost-cutting plan will keep accumulating into fiscal 2031. To reverse the stock price in the short term, evidence that sales are recovering matters more than the scale of the money saved. This discussion is about NYSE-listed shares of NKE.
In the first quarter of fiscal 2027, announced on October 1, Nike earned $0.48 per share, beating the $0.43 quarterly consensus expectation listed by Nasdaq. The quarter alone looks fine, but full-year guidance is only $1.15 to $1.35. Nasdaq’s current full-year consensus is $1.61.
The company’s midpoint of $1.25 is about 22% below that expectation, and it has already excluded roughly $0.15 per share in restructuring costs. Even if you temporarily ignore the costs from restructuring, Nike still expects to fall short of analysts’ earnings estimates. A better single quarter isn’t enough to support a judgment that the full-year outlook has already turned positive.
If investors are willing to pay the same price for each dollar of profit, then with lower expected profits the stock price will be pressured as well. But that 22% gap in profit expectations can’t simply be translated into the stock falling 22%.
The stock has already dropped ahead of this. Nasdaq’s premarket quote at 8:13 a.m. ET on October 2 was about $32.50, down 7.54% from the prior session’s close. This earnings report has already caused some of the worries to be reflected in the price. Whether the stock keeps falling next will depend on how earnings forecasts and valuation change. This quote is a premarket snapshot, and it could rebound later.
The benefit from Nike’s cost savings can be seen in the numbers, but the recovery in sales hasn’t caught up. This quarter’s revenue fell 4% year over year, direct-to-consumer revenue declined 8%, and online business fell 13%. Gross margin moved from 42.2% back to 42.8%, mainly driven by lower warehousing and logistics costs. The company can keep a bit more per dollar of sales, but total sales are down—so the gross profit for the whole quarter is still $145 million less than last year.
The $2.5 billion in the Pace plan also takes time. The company says the accumulated savings through fiscal 2031 haven’t yet deducted approximately $1 billion in pre-tax restructuring costs, nor the subsequent reinvestments. For fiscal 2027, it expects about $300 million in related costs to be recognized. You can’t treat the $2.5 billion as profit earned in a single fiscal year.
There are also reasons to be bullish: North America revenue is up 2% year over year, and gross margin has already rebounded. If North America continues to grow and the declines in direct-to-consumer sales narrow, cost savings and selling more product could work together to improve profits—and the market may even be willing to pay ahead for the next phase of recovery.
For now, I’m not treating this earnings report as the starting point for a rise. If over the next two to four weeks the stock price recovers the decline after the report and continues to strengthen, then the view that it will face short-term pressure should be withdrawn. Subsequent disclosures—if they can show that sales are recovering and that profit guidance has room to be raised—would also change my view on how quickly this company is on track to recover.
#耐克 #美股 #Earnings report
209
·
--
Verified
Merchants can integrate stablecoin payments reliably and continue accepting fiat as usual.
Citi and Coinbase’s disclosed payment setup allows merchants that don’t want to hold coins to also accept stablecoin payments. Stablecoins are automatically converted into fiat before settlement, eliminating the merchants’ work of directly managing the coins. Whether merchants actually use this service depends on how many orders truly pay with stablecoins; whether merchants choose to keep the coins can be assessed separately.
On September 28, both parties disclosed an expanded cooperation. Under the merchants’ payment arrangement, customers pay stablecoins through Spring by Citi. Coinbase’s payment system automatically converts the stablecoins into fiat, and Citi handles settlement.
For merchants who simply want to add another payment option, this arrangement removes the need to directly manage coins. They don’t have to decide separately how to hold the coins or when to convert them for this revenue. The service provider handles the related operations, and merchants can decide independently whether to accept stablecoin payments versus holding coins long-term.
In the same announcement, Coinbase Virtual Accounts will automatically convert the received fiat into stablecoins to serve a different kind of need. The two directions of business cannot be mixed together and treated as evidence that merchants are starting to stockpile coins.
Even if, in the future, more and more payments are completed through this arrangement, you still can’t infer merchants’ stablecoin balances from payment amounts alone. Just because a merchant is willing to accept coins from customers doesn’t mean they want to keep sales revenue in coins; conversely, receiving fiat doesn’t prevent stablecoins from playing a role in that payment.
Eliminating operational steps can only explain why merchants might be willing to integrate; it still can’t prove that customers will choose it. The parties’ announcements do not disclose the actual payment volume under this cooperation, nor do they provide a complete fee schedule. Whether it’s more cost-effective than the original payment method, and whether settlement and refunds meet everyday business needs, still requires real-world usage to answer.
At present, the arrangements disclosed by both parties start in the United States, and you shouldn’t interpret it as global integration of payment options across Citi’s worldwide business scope. Only after the participating merchants continuously receive this kind of order can it be confirmed that the arrangement has been put into everyday business.
285
·
--
Micron can pay current-quarter investments from operating cash flows, and customer deposits must be accounted for separately
Micron’s operating cash flow for fiscal year $MU 2026 fourth quarter already covers the company’s current-quarter spending on plant and equipment. Customer deposits received additionally increase available funds, but they come with repayment conditions attached. To judge how much more Micron has for capacity expansion or share repurchases, you need to separate cash generated from operations from deposits that are temporarily available.
On September 30, Micron disclosed that for the fourth quarter ended September 3, it generated about $43.97 billion in operating cash flow, while spending $11.11 billion to construct plants and buy equipment. Subtracting the two directly leaves roughly $32.86 billion. This does not add back government subsidies or proceeds from equipment sales, so it differs from the company’s adjusted free cash flow definition.
This quarter, Micron also received $12.3 billion in cash deposits from strategic customer agreements. In the prepared remarks for the earnings call, management made it explicit that these deposits are recorded in financing activities and do not affect free cash flow. The money had not originally flowed into operating cash flow, so deducting it again would underestimate operating performance; including it as “extra money made from selling chips” would overestimate it.
When customers place deposits in advance and agree to multi-year supply arrangements, Micron can receive part of the funds earlier to plan capacity. In the previously disclosed 10-Q for the third quarter, these contract terms set binding purchase quantities, with most using fixed prices or price bands with floors and ceilings. Having purchase volumes written into the contracts provides a higher degree of certainty in arranging capacity than merely relying on forecasts based on customer demand.
This time, management explained that cash deposits under strategic customer agreements are not subject to usage restrictions. After customers meet minimum purchase requirements, they gradually get their deposits back during the latter portion of each agreement. When assessing room for repurchases, dividends, or continued capacity expansion, this obligation must be included as well.
Long-term agreements also cannot guarantee the same amount of operating cash flow every quarter. Even with a price floor, production costs still need to be controlled, deliveries must be completed as agreed, and the timing of cash collections versus accounts payable can all affect cash flow in the quarter. While deposit receipts can ease funding pressure, they cannot replace cash generated by ongoing operations.
If the current-quarter investments are supported by operating cash flow, you still need to calculate how much cash will be left in the future. After the company increases investment, whether operating cash flow remains sufficient and whether deposit repayments clash with other spending will both change the amounts available for repurchases or dividends. Ignoring the deposit repayment obligation would overestimate the funds available for shareholder returns.
327
·
--
This Ethereum scaling upgrade can’t be simply understood as a blanket reduction in fees
Glamsterdam’s proposal increases Ethereum’s processing capacity while also adjusting gas charges for certain newly added on-chain data operations. Whether this scaling will make a particular application cheaper depends on which operations it uses and the gas price at that time—not on a vague assumption that fees are uniformly discounted.
As of October 1, the official plan is to activate on October 6 on the Sepolia testnet. The dates for Hoodi and the mainnet have not been determined yet. This announcement has not changed the existing mainnet fee rules for $ETH .
Besides executing transactions, nodes must also store account information, contract code, and storage data. With more things allowed per block, the new data may also occupy disk space faster and slow down nodes. Simply improving execution speed doesn’t solve the ongoing problem of accumulating data.
The upgraded block access lists will list the accounts and storage locations involved in executing transactions, enabling clients to read and verify in parallel. If clients can process more work at once, that creates the conditions to increase throughput. But reading faster doesn’t mean storing less—the long-term burden of additional data still needs to be handled.
The included EIP-8037 increases gas charges for operations such as creating new accounts, writing to new storage locations, and deploying code, and measures the newly added state separately. This fee structure is intended to control the data growth rate after scaling. If an application frequently creates new data, it needs to重点算 (pay particular attention to) and estimate the extra cost of these operations. There is also another fee adjustment for accessing existing data, so you can’t simply categorize applications into “fees increase” and “fees don’t increase.”
An increase in the gas consumed by the same kind of operation doesn’t necessarily mean the ETH-denominated bill will rise. If congestion eases after scaling, the decrease in unit price may offset the increase in usage; and even if demand grows along with it, you still can’t guarantee that transaction fees will go down.
Developers also have to deal with compatibility issues. After the Ethereum Foundation replayed historical transactions, they found that most transactions can still be executed unchanged, while a small number of contracts rely on hard-coded gas assumptions. Some failures can be resolved by raising the transaction gas limit, while others require modifying the contract or how it is called. Increasing the limit only allows a transaction to use more gas—it does not automatically make every transaction spend the full amount.
Testnet fees also can’t be used to predict mainnet bills, because test traffic and the prices users are willing to pay are different. For application teams, a more useful approach is to test the new rules with their own transactions and compare the old and new usage under the same gas unit price. First determine how much more or less the business itself will consume, then observe congestion and gas prices after the upgrade goes live on mainnet. Only by combining these two parts can you tell whether this scaling upgrade will save money for your users—or cost them more.
273
·
--
Investors in Europe can now buy a physically backed Zcash product on regulated exchanges, with a custodian holding the real coins. Meanwhile, another EU regulation that has already taken effect sets a timeline for licensed platforms—after the deadline, they must draw a clear line separating from this kind of asset. In the same jurisdiction, opening and clearing happen at the same time.
In the Chinese community, when people talk about an EU privacy-coin ban, it’s basically second-hand accounts, and then second-hand accounts of those accounts. Article 79 of Regulation 2024/1624 actually targets accounts: credit institutions, financial institutions, and crypto-asset service providers may not hold anonymous accounts, nor may they hold any accounts that can conceal the identity of holders, or make transactions anonymous and further obscure them. In that one sentence, the provision points to coins that enhance anonymity. The application date is stated in Article 90—July 10, 2027. Nowhere in the entire regulation does it name #Zcash, and it doesn’t name any specific token.
This kind of drafting leaves room for securitized wrappers. The law bans the form of accounts and service behavior, but does not put the assets themselves onto a list. An ETP listed in Europe is a security. The people who buy it open accounts in their own names at brokers, and the trades and settlements go through the security pipeline—no one holds a shielded address for the customer. When 21Shares launched at this point in time, the bet was that this reading would hold. The product is packaged to look like a conventional security, with an annual management fee of 2.50%—which is higher than most crypto ETPs. The issuer itself knows it’s a niche shelf. Buyers of this layer of shell get only the price exposure; they don’t get privacy itself, and Zcash’s utility is entirely on the privacy side. This mismatch ultimately determines how big the securitization channel can grow.
That the interpretation is plausible doesn’t mean the business will work. This so-called Europe’s first ZEC physical product launched with an asset size of a bit over $100,000, and the issuer’s website shows exactly that number. Around the same time, the U.S. spot ZEC ETF traded on NYSE Arca—according to the materials it filed with regulators—after it listed at the end of August, its assets exceeded $500 million within two weeks. That’s a difference of three orders of magnitude. The European product looks more like an option pre-purchased in advance: it bets that the 2027 timeline will ultimately not sweep the security shell into the prohibited category.
That $500 million in the U.S. also needs to be viewed carefully. In the same set of materials, it states that an investment vehicle under DCG took 85,705 ZEC to receive a $100 million share allocation—settling via physical transfers. DCG is the parent company of Grayscale. Its founder has publicly said that part of Bitcoin’s market value would be moved into privacy assets, and also that ZEC has room for hundreds of multiples. This is a genuine faith vote, different from the influx of unknown buy orders in the secondary market. After stripping out that related-party transfer, remaining external inflows look much more modest.
On September 23, during intraday trading the high reached $1,679.83, and by the close it fell back to $1,498.26—within a day it吐出了 everything it had pushed up. Binance perpetual positions dropped from 498,867 coins that day to the current 449,367 coins. On the day the news landed, positions were decreasing, with no new money pouring in. The spot price on $ZEC is currently $1,512.39, down 6.04% over the past 24 hours; at the start of the year it was still around $500.
Talking about ZEC alongside Monero is the most common lazy approach in this topic. Monero’s privacy is enabled by default and can’t be turned off; Zcash’s shielding is optional. On-chain, 4.91 million ZEC are currently sitting in the shield pool, accounting for 29.0% of total supply; the remaining more than 70% is still sitting in transparent addresses. Due diligence for these two kinds of assets by compliance teams is completely different. The platforms have already handled them separately as well: on Binance, XMRUSDT is in the BREAK state and has long stopped trading; ZEC and DASH are still on the shelf. Europe has precedents for enforcement—previously, a large exchange directly converted Monero balances of European users into Bitcoin at market prices and liquidated them, without leaving a grace period to sell gradually.
21Shares likely read the law correctly on the legal-text side, but is still wrong on the business side. The security wrapper can solve the hurdle for compliance entities, but it can’t solve whether European distribution channels are willing to put a controversial 2027 target onto their shelf. The asset size of this Europe product will answer that question first. If the size is still sitting in the tens of hundreds of thousands through Q4, it suggests the channel side hasn’t accepted that reading, and that timeline will keep sitting on ZEC’s valuation. If it truly starts compounding week over week, that would indicate licensed distributors have already finished their legal opinions internally, and that discount should be recovered. There’s also a third path: if a regulator in any member state—or an EBA technical standard—counts the exposure from holding shielded assets as “confusing transactions,” then the first thing that would go wrong would be that security shell, and the spot market would be unaffected.
Beyond the regulatory line, there’s another dated item on-chain. The NU7 plan activates on the mainnet on November 5. The block interval is compressed from 75 seconds to 25 seconds, and v4 trading is retired at the same time. The testnet runs first on October 6, and the final decision on what remains is set for October 20. Holders have a specific action to take: in the old Sprout pool there are still 22,430 ZEC left. After the upgrade, this portion may be permanently locked. If you have shielded addresses from earlier years, go check them yourself—faster than asking someone else.
This market narrative is already quite crowded. Many people are spreading the idea that compliance domestication and compliance expulsion are the same good thing. You can check once a week the asset size of that European ETP—how the channels interpret this regulation will show itself in that number sooner than any interpretation.
1
403
·
--
Verified
On the Binance trading interface from four years ago, BUSD was placed in the most convenient spot, while USDC was merely a tolerated outsider. After the whole BUSD episode, Binance stepped away from the stablecoin issuance end, and that territory was ceded. Now this exchange has turned around and is paying money to become a shareholder of Circle—and it has also tied itself into a five-year promotional agreement. With roles reversed, whose pocket the money ultimately lands in is the balance sheet that should be clarified.
The terms are all laid out in the 8-K. Binance will subscribe to Circle’s Class A common shares at $80.84 per share for a total of roughly $100 million. The deal will be settled on September 17, and disclosed before trading on September 22. The stock cannot be sold, transferred, or hedged within two years. Voting rights remain with Binance. The commercial agreement runs for five years, replacing two older arrangements signed in November 2024 and August 2025, with a focus on emerging markets.
Circle doesn’t really lack this extra $100 million. This equity is more like a block of collateral welded between the interests of both sides: the two-year lock-in keeps Binance pinned in place and promotional fees keep getting collected, but the stock can’t be pushed out. What’s being exchanged for in this transaction is distribution rights—and distribution rights are the priciest cost item in Circle’s business.
The Q2 report lays out this cost structure. Almost all of Circle’s revenue comes from interest on reserve assets. The year-over-year growth in total revenue relative to reserve earnings is 7%. In the same quarter, distribution, trading, and other costs were $412 million, up only 1% year over year. Subtract those growth rates, and the portion the company keeps after distribution has a 15% year-over-year increase. With more partners, money paid out didn’t inflate in a linear way—there are signs that Circle has been able to claw back some pricing power in channel negotiations.
To judge whether this Binance deal is expensive, you first need to use the Coinbase deal as the benchmark. The profit-sharing terms set in 2023 were renewed as-is in August this year through 2029. Coinbase receives all of the yield on its own USDC reserve on its platform, and the remaining portion outside the platform is split in half. In 2024, Circle paid about $908 million for this. With the terms unchanged and the term even longer, Circle can’t move it in the short term.
Binance’s paid structure here is narrower. Circle pays incentive fees monthly. The billing base includes only the portion of USDC held through the Modular Smart Contract Wallet service—that is, the wallet infrastructure Circle provides itself. The other USDC that circulates within the platform doesn’t go into this pool. The downside Circle suffered under the prior agreement is written into this definition.
There’s another layer of accounting that’s easy to overlook. Under the Coinbase deal’s definitions, the USDC on Binance is considered “outside the platform,” and Coinbase still takes half of the remaining residual earnings. For every additional dollar of USDC Circle puts on Binance, it first pays Binance’s monthly fee, then splits the remaining amount with Coinbase, and only then does it eventually reach its own shareholders. Before the marginal profit from the new channel shows up on Circle’s books, it has to pass through two gates.
On the cost side, things are still relatively decent. The USDC circulation volume at quarter-end was $73.3 billion—still up year over year—but it dropped from the end of March, and the in-year peak wasn’t maintained. In the same period, the reserve yield fell by 66 basis points year over year. As unit yield declines and quarter-end balances shrink sequentially, growth in scale turns from a bonus into a necessity. What Binance needs to supply is precisely that gap. Its emerging-market customer base has a rigid demand for dollar accounts—it just previously couldn’t access them.
Market disagreement about this company is a bit exaggerated. On August 3, Morgan Stanley cut CRCL from Neutral to Underweight and slashed the target price to $38, arguing that tokenized cash products and new stablecoin models would likely squeeze its profitability over the long term. The first half of that case holds up: revenue is almost entirely tied to reserve interest, and when the interest-rate environment moves, the entire income statement moves with it. The second half, though, I disagree with. Treating channel expansion as profit leakage doesn’t match the trajectory suggested by the Q2 report. The $412 million figure is right there—it hasn’t risen proportionally with the number of partners. The stock’s later path has moved farther and farther away from that target price.
I’ll rank the three layers of value in this transaction. Equity financing comes last, and the five-year channel lockup sits in the middle. The top value is that Circle has turned a competitor it faced head-on in earlier days into a distribution partner it now binds with equity. A long-term variable hanging outside the balance sheet is pulled inside.
There’s only one condition for the arrangement to fail: the share of distribution, trading, and other costs as a portion of revenue. In the next two quarters, that ratio needs to rise again; meanwhile, if USDC circulation volume at quarter-end drops again quarter over quarter, then it’s essentially “buy scale with profit,” and all the statements above become moot.
The case for the bears is also defensible. Binance’s user base is primarily trading-focused: stablecoins in trading accounts turn over quickly and are thinly “deposited,” unlike the long-term balances at custody-style platforms, which are a different type of asset. Demand in emerging markets is real, but ticket size is low—by the time it’s allocated to reserve earnings, it only becomes evident over several quarters. The agreement is written for five years, but in practice it’s just an upper limit, and early termination clauses remain dangling.
On the market front, $CRCLB spot is quoted at $92.55, down 3.38% over the past 24 hours. The day after the news landed, the price moved back—this extra $100 million wasn’t treated by the market as a reason for revaluation. Binance’s cost basis at 80.84 is still in unrealized profit, and the two-year lockup keeps it temporarily sitting on the books.
What’s worth watching next isn’t the stock price. The on-chain balance structure of #USDC is publicly verifiable, and the line item for distribution costs in Circle’s Q3 report will be disclosed as usual. If you’re interested in this business, you can add these two items to your watchlist and check back on them once per quarter.
1
1
1.2k
·
--
Verified
This week’s copycats outperformed the mainstream. The simplest explanation is that Bitcoin money flowed out. Take the leading coins, line them up against the timeline—then you’ll see the order doesn’t match. The ones that surged the most moved first, while Bitcoin moved afterward. Anything that runs ahead of beta can’t be explained again with beta.
Over seven days, NEAR rose 65.8%, and ARB and INJ also climbed by more than 40%; meanwhile Bitcoin during the same period rose only 13.6%. Bitcoin’s gap-up happened on the 21st, while NEAR and ARB had already been pulling upward since the 15th and 16th—about five or six days earlier than the broader market.
Each of the three coins has its own story. $NEAR : around mid-month there was a milestone incentive reward-claiming window, and immediately after, Hyperliquid launched its privacy perpetuals—then the AI agent narrative got reignited in the same momentum. $ARB is driven by the Robinhood Chain. This chain is built using Arbitrum Orbit, and on-chain revenue flows back to Arbitrum through the expansion program. Standard Chartered also provided coverage during this period. Only $INJ was pushed up purely by a one-paper filing. On September 18, 21Shares submitted an S-1 amendment for an Injective spot ETF to regulators, planning to list it on Nasdaq under the ticker code TINJ. Custody is handled by Coinbase Custody and BitGo, and the pricing benchmark is based on the FTSE Injective Index. That day and the next day brought two back-to-back big bullish candles, with the timing perfectly aligned.
Among the three catalysts, the ETF story looks the most like a traditional “big positive” in the conventional sense, yet the realized upside turned out to be the smallest.
My view is that the act of submitting the application itself is no longer worth much. Once the generic listing standards were in place, copycat ETFs didn’t need to go through approval step-by-step for each one anymore—scarcity disappeared, and so did the premium. Bloomberg’s James Seyffart counted early this year: there were 126 crypto ETP applications waiting in line for approval. He described issuers as throwing a large number of products at the wall. He also expected that by late 2026 into 2027, a batch of products would have to be liquidated for failing to raise enough money. Injective falls right into the “long tail” he described. In its own prospectus, 21Shares states that as of September 1, INJ’s total market cap was about $488 million. On the same underlying there’s also Canary’s staked version queuing up—both teams watching roughly the same sub-$500 million pile.
Making the filing “cheaper” doesn’t mean it will be “faster” to launch. What the generic listing standard removes is the exchange’s approval process—while the registration documents still have to become effective when they’re supposed to. In this amendment, the clause delaying effectiveness is still left exactly as it was.
Crossing out the ETF doesn’t work either, because one existing fund is a ready counterexample. Bitwise’s Solana ETF, ticker BSOL: since listing, its shares have been steadily trending downward, yet cumulative inflows still reached $1 billion. What kept it afloat was a 5.80% net staking yield—something denominated in SOL, accruing upward regardless of SOL price swings. Getting approval is just your ticket to enter; yield is the reason holders are willing to stay.
If you go back to this 21Shares filing by this standard, two blank spots jump out. In the staking section, it says the founders have discretion and they’ll only stake a portion of INJ if there are no material legal or regulatory risks. In the management fee section, it’s still just a bracket—no number filled in. Whether this fund ends up looking like BSOL or not will depend on how these two places are finally filled in.
Putting the ETF aside, Injective’s own “board” has a line that’s rare elsewhere. Its deflation comes from the application layer. Different applications running on the network aggregate transaction fees to do community buybacks; the INJ bought is directly burned, and base-layer gas doesn’t play a major role there. The more on-chain business, the faster the burn. This line has nothing to do with whether the filing and approvals land, but it more directly determines whether people will still be willing to hold it long-term.
Market structure is saying the same thing. As price climbed so much, open interest fell rather than rose, and funding rates hovered nearly at zero. The buy side came from spot, and leverage barely participated. The upside is there’s no crowded long positioning up top waiting to get squeezed. The downside is there’s also no leverage helping push prices higher.
The bearish case is also solid. Ben Slavin from Mellon Asset Servicing believes the market’s absorption capacity is good so far; he hasn’t seen structural constraints that would overwhelm the current issuance pace. There’s also an asymmetry you have to admit: with a pool of this size, one single dump into Bitcoin—money so large that you can’t even see ripples—placed into Injective would constitute a sizable position. People who are betting on the ETF effect shouldn’t pretend this isn’t real.
INJ is now $7.95. Next, we can look at 21Shares’ next amendment—whether the management fee is filled in, and whether staking shifts from “discretionary” to a standard arrangement. Once those two spots are locked in, you’ll have the answer to how much the ETF line in this #山寨ETF 行情 is actually worth. If after becoming effective the inflows end up stuck long-term at the level of hundreds of millions of dollars, the liquidations Seyffart mentioned will likely start first with this kind of underlying.
2
3.7k
·
--
Wells Fargo analyst Ken Gawrelski said on Monday that when Meta raised its price target, the company finally now has a story to tell. Put that line in the context of the past few months, and it feels a bit ironic. Wall Street’s biggest gripe with Meta is exactly that the money is being spent ever more aggressively, yet it can’t explain which products—ones that would actually get users to pay—will ultimately come out of it. This week, an AI agent called Muse has filled in that blank at least for now, and the stock price has done the “filling in” first.
Meta surged 11.43% in a single day on Monday. On Binance, the $METAB mark is currently around $734, up a bit over 8% over the past 24 hours. Over the weekend and the past few days, the price basically moved sideways—most of the action was concentrated in the U.S. stock market open. This rally was driven by Muse. It launched on September 8 and can help users send emails, schedule appointments, fill out forms, and place orders directly. According to reports from overseas media, in its first few days after launch, Muse’s download count exceeded 730,000, ahead of ChatGPT and Claude. On September 18, it also climbed to No. 1 on the free app chart in the U.S. #Meta #AI agent
To understand this bullish candle, you need to flip back to Meta’s second-quarter earnings report from late July. In that quarter, Meta revenue was $60.8 billion, up 28% year over year—the ad machine kept rolling. The lower half of the income statement looked ugly: net profit was down 14% year over year. Even more striking was the cash flow: capital expenditures nearly wiped out operating cash flow, leaving quarterly free cash flow at under $800 million. Management also raised its full-year capital expenditure guidance to $130 billion to $145 billion, citing rising component prices and the need to build data centers in advance to support future years’ computing capacity. After the earnings were released, the stock fell sharply after-hours.
So for the past two months, the market has been asking the same question: with so much money poured into GPUs and data centers, what exactly do they get back in return? Muse is Meta’s first answer to show a user-driven download decision—something users are willing to go out and install. Earlier, JPMorgan’s Doug Anmuth moved first: on September 10, he upgraded the rating from Neutral to Overweight and raised the price target to $820. His reasoning was that Meta’s self-developed model has already caught up to the first tier, and Muse plus externally open model interfaces could open another revenue line beyond ads. Wells Fargo raised its target to $796 this time, with essentially the same logic.
There are also credible dissenting voices. Oppenheimer’s Jason Helfstein ran the numbers. At a subscription price of $20 per month, Meta would need to accumulate roughly 115 million paid users for Muse to generate about $28 billion in annual revenue. He doesn’t think it will happen in the near term, for three reasons: the paid conversion rate is already low, ChatGPT and Gemini have already taken up space, and users may not necessarily be comfortable handing over all their various account usernames and passwords to Meta.
On Monday, another development also occurred—one that may matter even more than the download chart. Starting Sunday night, Amazon began blocking Muse from outside its own marketplace. Amazon cited several reasons, including that Meta didn’t give advance notice, that Muse doesn’t indicate it is a robot when browsing webpages, and that it appears to capture and save users’ login information. In the past year, Amazon has taken similar actions against shopping agents from Google and OpenAI, and it has even sued Perplexity over similar issues.
My take on this rally has two halves. In the first half, I agree with JPMorgan and Wells Fargo. In July, the market punished Meta for a core reason: capital expenditures didn’t seem to translate into product outcomes. Now the “outcomes” are showing up—users really are downloading—and the biggest hole in the valuation has been filled to some extent. There’s a reason the stock is revising back.
In the second half, I side with Helfstein, and I also think his math is a bit optimistic. The fact that Muse tops the download charts proves curiosity. But curiosity is still separated from revenue by two hurdles: retention and then paid conversion. There are too many examples of AI apps that surge on ranking lists and then quickly cool off. I even think the subscription fee itself isn’t the most crucial thing. The truly valuable position for Meta is the “entry point” that determines what users decide to buy before they buy it. Once that entry point is firmly established, the advertising and shopping-guidance businesses can grow alongside it. Unfortunately, what Amazon blocked is exactly that entry point. An agent can place orders for you, but only if merchants are willing to let it into the door. America’s largest e-commerce platform has already stated it won’t allow it—so Muse’s shopping scenario is missing the biggest piece for now.
There’s also another risk on the ledger. The more popular Muse becomes, the more inference compute must be burned. The situation in the second quarter—where capital expenditures ate up all cash flow—likely will continue through this year as well. This rally is buying the story, but the bill will only line up in later quarters. If Muse’s daily active users clearly drop over the next few weeks, or if free cash flow in the third-quarter earnings report continues to hover around zero, then this upward move won’t be sustainable.
On Thursday morning Beijing time, Zuckerberg will deliver a keynote at the Connect conference. The agenda already includes a dedicated session for Muse Spark, as well as an open-source model called Muse Glimmer aimed at local AI agents. The Information reported that Meta may release an AI glasses product without cameras, but Meta has not confirmed it.
You can look at whether Meta at Connect is willing to disclose Muse retention or daily active usage, and then compare that with the gap between capital expenditures and operating cash flow shown in the third-quarter earnings report at the end of October. The former indicates whether users stick around; the latter indicates how long this “accounting” can hold up.
205
·
--
Bitcoin took three bearish hits last week. The Federal Reserve, after years, raised rates again; the Bank of Japan followed suit, pushing interest rates to levels not seen in many years. In the Senate, the crypto market structure bill, CLARITY, failed to pass even the procedural vote. Based on experience from the past few years, a week like this is when bulls should usually stay away—yet on Monday, a big bullish candle appeared.
On Monday, $BTC pushed through 85,000 and even touched above 87,000 intraday—first time returning to that level since the end of January. This morning it pulled back to around 85,000. What the market is arguing about now is what this move actually represents: is it fuel from shorts being squeezed out, or is actual spot money really back? The two answers lead to completely different paths from here, so I broke down the data that could be pulled.
The squeeze part is real. According to liquidation data compiled by Crypto Briefing, roughly $648 million worth of short positions were wiped out across the whole network in a single day, with the most concentrated clean-up happening during the single hour when the rally was strongest. Glassnode had already warned before the market even took off that a large pile of short positions sat not far above the current price. Once price enters that range, liquidation orders turn into market buy orders, and the market essentially pushes itself higher. This fuel can only burn once—once it’s burned, it’s gone.
But squeeze alone can’t explain the change in open interest on Binance perpetual futures. If it were only a squeeze—shorts getting liquidated and positions being closed passively—open interest should trend downward. From daytime into late night on Monday, BTCUSDT perpetual open interest rose from about 108,000 BTC to above 111,000 BTC. While price was being driven up, open interest was also increasing, which suggests that while some shorts were being liquidated, others were simultaneously opening new long positions.
Funding rates didn’t run out of control. During the entire push, the rate hovered around roughly 0.01% (one basis point). Even the batch settled at 8 a.m. this morning was below that level, and the long/short account ratio also still showed slightly more shorts. Quite a few long positions were newly opened, but not many were willing to chase at high prices. This mix is more like someone built positions on the breakout, while retail leveraged longs haven’t poured in at scale yet.
On the spot side, U.S. spot Bitcoin ETFs saw a V-shaped week. In the two days around the policy decision, total outflows were about $746 million. Starting Thursday, flows flipped to inflows, and on Friday a single day saw $433 million in inflows—its biggest day since early September. On Monday, Strategy disclosed that last week it bought another 950 BTC with cash, totaling $75.7 million. That amount isn’t huge relative to today’s trading volume, but its significance is that Saylor is still willing to pull out cash at these prices.
Why didn’t the three bearish hits knock the market down? The reasons aren’t mysterious. The rate hike was already fully priced into the market. When the “boot” finally dropped, there was one less uncertainty. After the Bank of Japan’s hike, the yen didn’t strengthen; Japan’s rates remain far below the U.S., so the feared unwinding of carry trades didn’t happen. CLARITY failing was a bad sign, but in the same week the SEC granted new exemptions for tokenized securities trading venues, and regulation wasn’t tightening in a one-directional way.
On the debate, both sides have plenty of heavyweight supporters. Galaxy Research’s head Alex Thorn is the most optimistic. Last week Bitcoin’s weekly close was above the 50-week moving average—first time since 45 weeks ago. He tracked the 13 times in the past that had similar recoveries: 11 of them did not go on to set new lows afterward, leading him to believe the bear-market bottom has likely already arrived. But he also said this bottom is still provisional. The other camp’s worries have justification too. During the rebound in August, some analysts had already warned that after the squeeze burns out, if spot doesn’t step in, the reversal back often comes quickly and violently—and the market did, in fact, churn up and down for several more weeks afterward.
My take is that this move is more solid than August’s, but it still isn’t solid enough to treat 85,000 as a newly confirmed step. Short squeeze fuel, ETF inflows, and new long openings in futures all showed up together, and funding rates stayed moderate. In the past six months, many rebounds only had the first ingredient—once the squeeze was done, the market turned around. I agree with Thorn’s direction: reclaiming the 50-week moving average does show up often statistically near the end of bear markets. But even he says it’s provisional, so I won’t treat a statistical pattern as a completed conclusion.
What would make me change my mind is the divergence between ETF flows and futures open interest. If this week’s ETFs start seeing net outflows again for several consecutive days, while futures open interest continues to stack higher, it would suggest spot buyers are stepping away and only leverage remains. That kind of structure is easiest to get knocked back by a single long lower shadow, and in this case, the longs that got squeezed would be the same ones who chase in on Monday.
There are also many external variables. This Thursday, Trump is scheduled to meet with Xi Jinping. In market sentiment, some risk is implicitly being bet on a smooth meeting; if talks break down, risk assets would face pressure together, and Bitcoin would likely not be able to avoid it. The Federal Reserve also hinted last week that there could be another hike later in the year. The PCE inflation data at the end of the month will directly affect that expectation.
In the next few days, you can compare Farside’s daily updated ETF flow data side by side with Binance perpetual open interest. If both move upward together, then 85,000 can be considered to hold; if only open interest is rising, then that move is still being propped up by leverage. #BTC
43
·
--
This Thursday night, the White House will host a state banquet, and the guest list has drawn even more attention than the menu. The main guest will be Xi Jinping, who is visiting Washington for a state visit. Huang Renxun, Altman, Cook, and the Qualcomm executive Amon will all sit in the same banquet hall. After the news broke, discussion in the Chinese online community almost all moved in one direction: Nvidia is about to return to China. I read through Nvidia’s latest quarterly report and coverage from several media outlets line by line. On this table, the value of $NVDAB is not located where most people think it is.
First, let’s lay out what actually happened. The banquet is scheduled for September 24. This will be Xi Jinping’s first entry into the White House in more than ten years. The report that Huang Renxun would attend was first released by Bloomberg on September 15. Artificial intelligence and semiconductors are issues that cannot be avoided in the talks. A similar scene has already happened once this year: in May, when Trump visited China, Huang Renxun was added to the delegation at the last minute. Back then, the H200 issue didn’t land, and after the fact, U.S. trade officials even said that chip export controls were never put on the negotiation table at all.
To judge whether this time can be different, you have to first see what Nvidia itself says in its regulatory filings. In Nvidia’s quarterly report filed on August 26, there is a dedicated section discussing China’s H200. Starting in February this year, the U.S. government issued licenses allowing Nvidia to sell small quantities of H200 to specified Chinese customers. After that, the Chinese government restricted these purchases, and Nvidia wasn’t able to sell through its licensed quotas. In the first half of the fiscal year, Nvidia recorded a loss of $400 million for H200 due to demand dropping. After the provision, actual shipments accounted for only a small fraction of the licensed quota. In the last quarter’s data center revenue, the share was less than 1%. The H200 exports also had to be shipped back to the United States for inspection before entering. Then, upon entry, a 25% tariff is paid. Nvidia couldn’t pass this cost onto customers.
This passage clarifies where the problem’s core really lies. The door in Washington has been opened just a crack; what blocks Nvidia is Beijing. Another section of the quarterly report puts it even more directly: the Chinese government encourages customers to buy products from domestic competitors, discourages the procurement, import, and use of Nvidia data center products, and even includes China-specific versions of products designed for compliance. Huang Renxun himself said in a CNBC interview in May that Nvidia has essentially given up the market for high-end AI chips in China to Huawei, and the company’s guidance has been set with China at zero.
So how much is this “dinner table” really worth? You can work backward from Nvidia’s current books. In the quarter through the end of July, Nvidia revenue was $96.2 billion. Based on the location of customers’ headquarters, China (including Hong Kong) contributed $7.88 billion, less than one tenth. This metric looks at where the customer’s headquarters is, and the portion actually tied to H200 licenses is so small it can be ignored. Management’s revenue guidance for the current quarter is $108 billion, and it is explicitly stated that the guidance excludes any data center compute power revenue from China.
A few years ago, China once accounted for at least one-fifth of Nvidia’s data center revenue. Now, in the guidance, that piece is zero. In August last year, Huang Renxun said the Chinese AI chip market could reach roughly $50 billion per year. The gap between “zero” and that number is what’s being discussed at the dinner table on Thursday night. Since the company counts China as zero, market expectations basically don’t include that piece either. Nothing was “negotiated” at the banquet—Nvidia’s existing business will not earn a single extra dollar; only if results are achieved would there be additional revenue. The market also doesn’t show anyone racing ahead: $NVDAB is currently around $224, still well below the early-September high.
External viewpoints mostly diverge on one question: after the licenses are allowed, how big can this business become? The more optimistic camp is represented by Wedbush’s Dan Ives. During Trump’s visit to China in May, he viewed that summit as a turning point for the AI industry, believing that U.S.-China easing would bring fresh momentum to tech stocks. Another Wedbush semiconductor analyst, Matt Bryson, offered a much colder assessment at the end of August. He believes that in the foreseeable future, this H200 route can only add a little to Nvidia’s China revenue. Each procurement requires individual approval, and the data centers and power capacity that can actually take delivery are also limited. In Washington, Senators Warren and Hawley have continued to warn that selling Nvidia chips to China would threaten national security.
I’m more inclined to agree with Bryson—mainly because of the timing. H200 is no longer Nvidia’s strongest product. Newer Blackwell has already produced two generations of chips in the United States. The more quarters Huawei and other domestic chip companies add to their output, the less Chinese large-scale customers need H200. Even if Beijing loosens up, it’s more likely to treat this as a bargaining chip and allow it in a limited way, with both volume and pace controlled by Beijing. In a plate where single-quarter revenue is heading toward $100 billion, this incremental amount would be almost invisible in the earnings report. What could make the numbers clearly change is Beijing allowing domestic data centers to purchase at scale and Washington simultaneously greenlighting products newer than H200—and those two things would need to happen together. Right now, there’s no sign of either one.
The practical benefit Nvidia could get from this dinner table might even be mostly inside the United States. In a CNBC report dated September 20, it said that debates over AI safety regulation have been getting louder in Washington, and Huang Renxun has become Trump’s most important ally on this issue. Several of Nvidia’s key customers are calling for slowing model iteration. In a moment like this, being able to speak in the White House could be worth more than selling tens of thousands more units of H200.
My judgment also has the possibility of being overturned. The most direct signal comes from Beijing. After the meeting, if China’s regulators loosen up on H200 or newer compliant products—allowing major firms to buy them and install them in domestic data centers—then the bargaining chip would be cashed in. The second signal will be in Nvidia’s next quarterly report: whether management still writes China data center compute power as zero. Risks also exist in the opposite direction. Opposition in Congress to selling chips to China has been persistent, and around the summit there was also a debate on AI safety. Whichever side tightens further, this already narrow channel could get narrowed again.
If you want to follow this, you can check whether semiconductors are mentioned in the list of outcomes released by both sides after Thursday’s meeting, and also pay attention to whether Beijing’s wording on procurement of foreign AI chips by domestic companies has changed. The movements in these two areas can explain more than who sits next to whom at the banquet. #英伟达 #美中峰会 #US stocks
1
122
·
--
Verified
NEAR The most lively place this week is actually not on NEAR’s own chain. near.com has made perpetual trading default to “private,” and both matching and depth are entirely routed to Hyperliquid’s order book. The coin price has been climbing steadily, and in the Chinese news updates, most of the headlines only mention a sudden surge. What I want to figure out is this: what exactly does “private” hide, and how much of this rally comes from the product itself.
Let me lay it out first. Starting September 17, all perpetual positions opened on near.com go through a “private” sharded path to route funds; the source of deposits and account ownership are not visible to the outside world. This shard is maintained by seven validator nodes, and it connects to the mainnet via a TEE bridge. The trading instruments and leverage use Hyperliquid’s existing setup—on the front end it lists more than 50 markets and up to 40x leverage. near.com connecting to Hyperliquid for perpetuals began as early as June; this time, the only addition is making “private” the default. $NEAR in Binance spot jumped from the $2.30 close on September 13 to around $4.3—up nearly 90% in a bit over a week, and daily trading volume expanded to about ten times its usual level.
The most common misunderstanding in Chinese retellings is “on-chain invisibility.” What the privacy layer breaks is the linkage between wallets and positions: others can’t trace from the deposit path to find who owns that position. But the position itself is still posted on Hyperliquid’s public order book—direction, size, and liquidation all occur there. Big players can use it to hide identity, but they can’t hide the position; a 40x trade that can be seen and watched will still get hit—risk doesn’t disappear. Also, privacy is built on trust in seven nodes plus a TEE, which is more centralized than NEAR mainnet verification, so people watching should have that in mind.
The second question is how much of the rally is subsidized demand. On September 17, the privacy TVL surpassed $70 million and triggered the first batch of snapshots for the NEAR@3.33 incentive program. The rules are to allocate 333,333 milestone tokens to qualifying users: the privacy balance must exceed $100, and users must have had at least one privacy exchange. For any single wallet, the maximum allocation is 2%. The tokens are locked first. Only after NEAR’s three consecutive days’成交量-weighted average price is not below $3.33 will the tokens be converted 1:1 into NEAR. I calculated using Binance daily data myself: starting September 18, the three consecutive days’ volume-weighted average prices were all above $3.33. If the official threshold is close to that, the barrier has already been crossed.
At current prices, this incentive is worth roughly $1.4 million. Compared with daily trades in the billions of dollars, it’s almost negligible—it can’t prop up a rally of nearly 90%. The $3.33 level looks more like a price everyone is watching, concentrating attention on NEAR. The main driver of buy pressure is largely the launch of a usable product with trackable data. On September 19, the official said privacy TVL had already reached $90 million—up by more than $20 million in just over two days.
Now, consider what this really is: is it NEAR’s product advantage, or just Hyperliquid adding another front end? Hyperliquid has onboarded several front ends in these months. The perpetuals on Base App are supplied by Hyperliquid, and even the African exchange VALR has integrated its engine. To Hyperliquid, near.com is just one traffic entry point; most trading fees flow toward the matching side. What NEAR itself retains is the deposit leg: users can open positions directly with any assets from more than 30 chains—no manual cross-chain steps, and no need to create another account. The official says the total value routed via NEAR Intents over cross-chain has already exceeded $30 billion. According to co-founder Illia Polosukhin, it’s “AI does the front end, the blockchain does the back end.” Dragonfly partner Haseeb Qureshi publicly praised this product as doing extremely well right now, and he also noted that they hold NEAR.
I agree the product is getting better, but I don’t agree that the entire rally should be credited to NEAR’s moat. Whether the routing and privacy layer can actually keep money there depends on whether TVL is still present after the incentives end. Most perpetual trading fees go to Hyperliquid; how the NEAR token will capture that portion of revenue currently has no clear answer.
On the contract side, the structure looks healthier than I expected. The notional open interest for Binance NEAR contracts rose from about $90 million on September 16 to $220 million, leverage clearly came in—but over the past few days, the funding rate has basically stayed around the 0.01% baseline, and longs haven’t been paying a premium just to secure positions. This rally has mainly been driven by spot.
And don’t ignore tailwinds in other segments. Zcash has also been moving up over the past month: from September 16 to 17 it expanded volume in sync with NEAR, and the privacy track overall has had momentum. NEAR has one extra “checkable” element beyond a pure privacy narrative—its product and TVL numbers. But once the segment sentiment ebbs, it can’t hold on either.
Risks should be made clear too. Privacy derivatives are not available in the U.S. and Canada, and regulators’ views on how these products will be handled are still unsettled. After incentives end, capital may withdraw. Once it’s already risen by nearly 90%, any negative catalyst will be amplified.
My view is: this market has real product support, but part of it is attention premium. You can watch two signals: whether privacy TVL can stay near $90 million after the first batch of rewards are claimed, and whether near.com will publish perpetual trading volume. If the former drops back below $70 million, I’ll conclude that most of the demand was drawn out primarily by incentives. #NEAR #Hyperliquid
4
1.7k
·
--
The finance head of Alibaba said during last month’s call that, based on the current average gross margin, it would take roughly how many years to recoup the money invested in AI. And if the internally developed chips get used more and the gross margin is lifted further, the payback period could be pushed even earlier. What bulls and bears are arguing about now is whether that one sentence holds up—everything else is just side issues.
At present, $BABAB is quoting at $114.06. It’s still about 40% below this year’s peak, and the market clearly doesn’t believe the payback promise.
In the quarter ended at the end of June, Alibaba’s capital expenditures were RMB 67.7 billion, up 75% year over year. The money spent in a single quarter is more than six times the net profit for the same period. Net cash outflow for free cash flow expanded to RMB 44.7 billion—more than double that of the same period last year. On the day the August earnings report came out, the stock price plunged, and that drop was exactly tied to these figures.
In February 2025, Alibaba announced it would invest at least RMB 380 billion over three years to build AI and cloud infrastructure. By the end of June, management said it had already spent RMB 190 billion—exactly half, with a little more than a year left in the plan. At the pace of the most recent quarter, RMB 380 billion looks more like a floor line; the wording the company used at the time was also at least in that sense. In August, the company raised HKD 80 billion via a Hong Kong placement, and the use-of-proceeds announcement locked the purpose in completely: 100% for AI infrastructure.
For cloud and AI computing power, revenue in the June quarter was RMB 48.4 billion, up 45% year over year—its fastest growth in more than five years. Annualized, that’s roughly over RMB 190 billion. The RMB 190 billion already invested is almost one-for-one with that annualized revenue. To recoup the principal in three years purely through gross profit, the gross margin would need to stay consistently stable year after year, and the new machines also need to have work lined up immediately.
The hole is right there. That annualized figure of over RMB 190 billion is not earned by new machines alone; the underlying base of the legacy cloud business makes up a substantial portion. What should be asked is how much incremental revenue those incremental capital expenditures generated, and Alibaba has not disclosed that separately. Spreading the cost of the newly purchased assets using the company-wide average gross margin naturally produces a payback period that is overly optimistic. The cloud business’s profit margin is already at 12%—the direction is correct—but it still has a long way to go before covering the depreciation of RMB 67.7 billion bought in a quarter. Depreciation also has a lag: the money spent this year will gradually appear in the profit and loss statements over the coming years, and the most ugly part of the reporting won’t be here yet.
Alibaba has no real exit. Total revenue rose by only low single digits in the June quarter. The e-commerce side basically moved sideways; the only story it can tell now is cloud and AI. Earlier, CEO Eddie Wu Yongming had laid out the ranking on a previous call: the company’s top priority is to beat the market’s average growth rate and gain a larger share, with profit margins coming later. With that ranking in place, capital expenditures won’t be halted just because cash flows look ugly.
Internally developed chips are the trump card behind this narrative. Pangu PPU from T-head uses its own computing architecture and chip-to-chip interconnect. Overall performance is benchmarked against NVIDIA’s H20 tier. By early August, there were already 650 external customers using Alibaba Cloud’s chips. Replacing outsourced chips with its own can indeed lift gross margin. If this step is genuinely executed, the shortened payback period can be calculated. The bottleneck is supply. These chips rely on high-bandwidth memory and advanced packaging capacity, and neither of these capabilities is currently abundant in China. Alibaba has also not publicly disclosed what proportion internally developed chips represent in its own computing capacity, which is the most opaque piece in the whole accounting.
On September 18, JPMorgan set Alibaba’s target price at $210, arguing that after next-generation multimodal model APIs significantly lowered API pricing, cloud competitiveness strengthened. On the other hand, in August, Michael Burry said on X that Alibaba would need to fall by half more before he would consider buying back. He had already rotated his position away months earlier to JD.com, and he also described the endless rounds of equity issuance as Alibaba’s new paradigm.
I’m positioned somewhat on the bullish side. Cloud revenue growth is real, profit margins are improving, and there’s no need to doubt the demand side. Burry reads the equity issuance as proof that the model can’t be sustained, but I think that’s reading too much into it. The funds in the financing announcement are clearly meant to seize the production capacity window. But I don’t accept the ‘pay back in three years’ framing either. It assumes that new machines are fully utilized immediately, and it assumes gross margin won’t be dragged down by depreciation and competition—both assumptions currently lack data to support them.
On the tape, after the August earnings report, $BABAB kept sliding. In mid-September it tested the low of this leg. Over the past two days, it has bounced back somewhat thanks to a broad rebound in U.S.-listed China concept stocks. On Friday, the primary shares in New York closed at $113.24, up more than four percentage points that day. The U.S. market was closed over the weekend, and the quotes basically tracked along the closing line. At this current level, the valuation simply leaves no room for a payback story.
Alibaba’s November quarterly report will be able to tell us this. If cloud revenue growth clearly slows and capital expenditures keep rising, the payback assumption will have to be recalculated entirely. If the company discloses the share of internally developed chips for the first time, and gross margin also lifts accordingly, then the ‘two and a half years’ claim would have support. You can watch the line represented by #阿里巴巴 for what comes next—those two numbers can explain whether this bill will actually balance better than focusing on the daily quotes.
1
198
·
--
Verified
At the end of last month, after that Solana governance vote passed, the Chinese community that same day quickly settled on a single line: SOL should print less. I’ve followed that line for most of the past half month. This week, I wanted to write it into my notes, so I went and queried the parameters on the mainnet as a quick check.
The answer on-chain hasn’t changed.
Solana mainnet’s getInflationGovernor is a public interface—anyone can call it. Today I read it out, and the taper field that controls the rate at which inflation decreases is still 0.15, exactly the same as before the vote. SGP-0002 is supposed to change that number to 0.30, and so far it hasn’t been executed on-chain.
The sticking point is public. Anza’s condition is that before adjusting the issuance rate, they must first land SIMD-0607—switch the calculation of staking rewards from floating-point numbers to integer fixed-point—otherwise different clients will produce slightly different results, and the chain will split. The version carrying this change is Agave v4.4. I checked the release page: up to September 18, what it has put out is still an alpha version. On the mainnet, only a handful of nodes are running this build; there’s no release date even for the official version.
So this is the current situation: a supply contraction that has already passed, but has no effective date. The SIMD-0607 change is still waiting for Anza and Firedancer to each provide a representative to sign off, and both client teams need to cut over together at the same epoch boundary—whoever is slower has to wait. SOL has outperformed the broader market this month, and the money is likely getting in through this gap.
First, let’s make the “outperformed” part clear. Over the past thirty days, SOL’s exchange rate versus Bitcoin and Ethereum both rose 12.6%, while during the same period those two big coins basically stayed in place on their own.
Looking only at one month, yes—it’s clearly leading.
If you stretch the window to ninety days, SOL’s exchange rate versus Ethereum is only up 0.7%, meaning it’s essentially flat. The recent period of SOL’s lead over Ethereum looks more like making up the missing chunk from earlier in the summer—it’s not really a brand-new valuation uplift. Bitcoin’s lead, on the other hand, has continued for three straight months. That line looks more solid.
Most explanations point to spot ETFs. The numbers don’t quite cooperate. The last time SOL spot ETFs saw a large inflow was in the week of August 28, with a net inflow of $153.87 million in that single week. By the week of September 18, it was down to just $13.2 million—cut down to about a small fraction of August’s level. Records of continuous net inflows are still technically hanging around, but in this same time, the coin price rose by 15%. Clearly, the buy orders didn’t come through that channel. The “existing holdings” explanation also can’t hold: the share of these funds’ holdings is only a bit over two percent of SOL’s circulating market value, and that position size can’t determine the relative strength over one month.
The technical picture also needs to be broken down. Alpenglow is this year’s biggest protocol change for Solana—it replaces the voting part in consensus with Votor. According to Anza’s schedule, starting September 28 the mainnet will enter functional activation; the effect will roll out step by step across epoch boundaries until October. The official “150 ms final confirmation” is given as a target value, but there’s no mainnet empirical validation. This build only has Votor; Rotor, which is responsible for block propagation, has been pushed into the later proposals. Eight days later, we’ll likely see headlines saying Solana has entered the millisecond era. It will be more reliable to verify again once the real-world data comes out. #Alpenglow
Back to that vote: the disagreement actually isn’t technical. Accelerating the decaying rate benefits people who hold their coins without moving them, while institutions living off staking yield pay the cost. Solana Company publicly opposed it: in its second-quarter revenue, 99.4% came from staking its own SOL holdings—this is a bill it can’t avoid.
Kraken initially voted against, but near the deadline it changed most votes to in favor; Galaxy switched from abstaining to being just over half in favor. In the end, the “yes” votes barely cleared the two-thirds threshold. It was only short of passing by a single large-holder changing their mind. That vote structure itself signals that within Solana, there still isn’t consensus on reducing issuance. It looks more like a time-line-driven tradeoff—shifting some cash flow from staking participants to long-term coin holders. #Solana
For this month’s excess returns: the ETF-related portion can be written off directly. The high-beta rebound explains part of it. The biggest remaining piece is that the market paid in advance for a supply contraction that hasn’t gone into effect yet. There’s nothing necessarily wrong with pricing early—markets have been doing this all along. But the time value of that money is entirely staked on when Agave v4.4 finally turns into the official version. And right now there’s no date for that—only a sentence that says the technical work must be done first.
There are two scenarios that would overturn my claim. One is if weekly ETF inflows return to the August-level magnitude, and the price keeps leading at the same time—then it would indicate the buy orders really are coming from that channel, and I simply underweighted it. The other is if v4.4 becomes the official version and the taper on-chain flips to 0.30—then that expectation would be fulfilled, and the time mismatch I’m worried about would no longer hold.
Today’s market action is conveniently putting this story through a stress test. $SOL fell 5.2% over 24 hours, with Bitcoin dropping much less over the same period. When the high-beta looked so good during the upswing, it would be just as painful when it reverses. September has been passing through two things that were already weighing on the market: rate hikes and disappointment around crypto legislation. People holding high-beta positions and staying close to the trend in such days don’t have it easy.
If you want to follow this thesis, rather than staring at price every day, a more efficient method is to query the mainnet getInflationGovernor yourself once every few days to see whether taper has moved from 0.15 to 0.30. It’s a public interface—you don’t need to trust anyone’s retelling. If it actually changes, then the logic of reduced issuance finally lands on-chain. If it stays the same, then this price today is still just paying for a promise.
2
1.6k
·
--
Verified
On Wednesday, the U.S. SEC gave the green light to tokenized U.S. stocks, and on Friday, the share prices of both Coinbase and Robinhood surged together. After reading the terms line by line, I can’t quite understand one thing: Robinhood’s stock tokens were sold in Europe for over a year, and yet—right by chance—this exemption excludes them. The applause the market gave both companies sounded almost equally loud.
First, let’s talk about what this exemption covers. The SEC newly created a category called “a tokenized securities trading venue.” Once a platform gets this status, it doesn’t need to register as an exchange; it can use a licensed AMM pool on a public blockchain to match tokenized U.S. stocks. The market makers supplying liquidity to the pool also don’t need to register as broker-dealers. The conditions are laid out one by one: the platform must be a U.S. company; both traders and liquidity providers must pass review; token holders must receive the same dividend rights and voting rights as ordinary shares—synthetic products with only price exposure don’t qualify. Before a platform lists a particular stock, it must notify the issuing company. The issuer has 30 days to formally object in writing; if they don’t speak up, it’s considered approval. The exemption lasts for five years, and before it expires, the SEC will decide how to write the formal rules.
What most affects business scale is the quota. For tiers like the S&P 500 and Russell 1000, a platform can list at most 75 stocks. For each stock, the trading volume on-chain can’t exceed 0.25% of that stock’s average daily share volume from the previous month. If trading volume exceeds the limit, trading in that stock must be paused; if the number of listed stocks exceeds the quota, the platform simply loses the exemption. Compared with the daily trading volume of large-cap stocks, these quotas are just a small fraction.
The stock-price reaction was far more generous than the terms suggest. On Monday, the Senate voted down a market structure bill, and Coinbase dropped by about 10% that same day. After the exemption came out, it surged for two straight days; on Friday, it jumped 11.66% in a single day, closing at $194.25—more than fully reversing Monday’s drop. Robinhood also rose significantly on Friday, while Charles Schwab fell slightly on the day the exemption was announced. On the same day, Bitcoin reclaimed the $80,000 level. Of the gains over these two days, it’s hard to say how much belongs to the SEC, really.
Back to the question at the start. When CoinDesk tallied the beneficiaries, it named them: Robinhood’s stock tokens, Kraken’s xStocks, and Ondo’s offshore products all fell outside the framework. These products offer only price exposure and don’t come with shareholder rights. That day, Robinhood CEO Tenev still posted in praise, saying tokenization is coming to the U.S. He’s right—but if Robinhood wants to do it in the U.S., it has to rebuild everything to meet standards that include full shareholder rights; the overseas version can’t simply be carried back.
Coinbase didn’t have this business in the U.S. in the first place, so effectively the two companies are starting from the same line. Baird analyst Robert Bamberger said on Friday that the exemption brings Coinbase closer to Robinhood in this business. With the CLARITY Act endlessly delayed, this is a clear positive for Coinbase. Still, his rating remains “Hold,” and his price target is $130—far below the current price. Securitize CEO Carlos Domingo is more optimistic; he thinks there’s finally a pathway to trade truly tokenized stocks. Meanwhile, Thomas Cowan, who’s bullish, reminded everyone that this is only the first controlled step, and the market won’t immediately open up.
I agree with Cowan and Bamberger on this. Coinbase’s trading revenue in Q2 came in below market expectations. Subscription and services revenue accounted for 48% of net revenue, and the company has spent these past two years searching for growth points beyond trading. Tokenized U.S. stocks can be folded into its “everything exchange” story, but based on the current quotas, it’s almost invisible on the income statement over the next one to two years. The stock jumped nearly 20% in two days—what the market is buying is an option whose outcome won’t be known until five years from now.
There are two other things I think will stall this business. One is the issuing company’s right to veto. A 30-day silence counts as consent, which sounds lenient—until a few top issuers publicly object, and then the list of the first 75 stocks will be missing a chunk. The other is the stance of traditional exchanges. The World Federation of Exchanges previously said publicly that it opposes “speeding up” tokenized-stock trading with broad exemptions, and it criticized some products being packaged as stocks when they are not. Nasdaq and the Chicago Options Exchange are members of that organization. These exchanges have enough incentive to lobby issuers to say no. The exemption itself is an executive order; the legislative path in Congress has already been blocked, the regulatory landscape has changed, and this order can also be withdrawn.
I tend to believe the exemption gives Coinbase relatively more benefit than it gives Robinhood. Robinhood already has products, but it can’t use them here, so both companies in the U.S. have to start over from scratch. How much more either company can make from this is short-term locked down by the quota. If, after the first batch of platforms goes live, the quota is quickly used up—and then the SEC relaxes the cap, and top issuers largely stay silent and allow it—that would mean I’m underestimating the business. In that case, it wouldn’t be surprising if Robinhood catches up on the strength of user scale.
$COINB on the weekend around $195, basically tracking Friday’s closing price; $HOODB is about the same. You can look at line #代币化股票 to see the list of platforms that applied for trading-venue status in the first batch, and whether anyone from top issuers came out to object during the 30-day window—this tells you how big the business can get more than that one big bullish candle on Friday.
2
1.3k
·
--
On Tuesday afternoon’s vote in Washington, the crypto industry waited for an entire year, and the CLARITY market structure bill—along with its debate procedure—didn’t even make it onto the agenda. This Congress basically has no chance. The awkward part is what happened in the charts over the following days: the bill died, yet crypto prices bounced back instead. What exactly did the industry lose when the bill failed? And is the market not caring because it has seen through it—or because it missed something? It’s worth going through these together.
A procedural vote required 60 votes, and this time it fell far short. All Democrats voted “no,” and several Republicans—including Collins, Hawley, Moran, and others—also defected. The most striking were Democrats like Gillibrand, Warner, Booker, and Gallego, who had spent months scrubbing the bill’s language with the Republicans; in the end, not a single one of them cast a “yes” vote.
Where the talks broke down has little to do with how the SEC and CFTC would split responsibilities. What truly got stuck were the moral/ethics clauses. Democrats wanted the provisions banning officials and their family members from profiting from the crypto industry to be written broader and tougher, aimed squarely at the president’s family’s crypto businesses. Republicans revised the wording in a version over the weekend, but Democrats still wouldn’t accept it. Senate Majority Leader Thune later said the final proposal already addressed the other side’s concerns, and that the other side walked away on its own.
Another shadow thread is stablecoin yield. Hawley and Moran sided with community banks, worrying that if stablecoins were allowed to pay rewards similar to interest, deposits would leave small-town banks, making it harder for local farms and small businesses to borrow. Crypto firms say it’s basically the same as credit card cashback, but the banking industry doesn’t buy that.
Now look at the prices. On the day of the vote, BTC’s daily candle closed down more than three percentage points; ETH fell even harder, nearing five points. If you only look at that one day, you’d think the market cared. The turning point came over the next two days. On Wednesday, the Fed raised rates by 25 basis points—the first time in three years. By Friday, U.S. Treasury yields and oil prices both retreated from their highs, and fears of inflation after the rate hike eased, sending risk assets back up. As of this morning, BTC is back above $81,000 and ETH is back above $2,600—already not only recouped the losses from the vote day but also gained some extra.
Another thing pushing prices happened on Thursday. SEC Chair Atkins released an innovative exemption allowing tokenized U.S. stocks to be traded in AMM pools on-chain, with a five-year term. It requires tokens to have the same rights to dividends and voting as the underlying stock. In her statement, Atkins directly mentioned that Congress failed to move forward on CLARITY. The SEC, she said, is moving ahead using existing authority first, while acknowledging this is only a transitional measure—formal rules must follow.
Friday’s leaders were Layer 2 and DeFi—$ARB is the most representative. Its momentum started well before the vote, and the current price is already up to about three times what it was a month ago. The driver is Robinhood Chain. This chain is built on Arbitrum technology, and according to its expansion plan, it will share 10% of net revenue with Arbitrum. Robinhood built this chain to focus on tokenized stocks; with the SEC exemption coming out, that theme got another push forward.
In the original text of the exemption, there’s a requirement: trading venues must set admission standards and only allow certain participants to trade. The on-chain market the SEC opened now has gatekeeping: what’s allowed in are licensed institutions and users who have passed identity verification, and the pools also run under a permission model. A few of the coins that surged the most this week are telling exactly the story of licensed institutions getting on-chain.
After the bill died, what was lost was half the picture. CLARITY left many provisions for open DeFi. Software that doesn’t touch user funds is separately protected: verification of transactions, publishing code, building wallets, running front-ends—all are included. It doesn’t regulate developers who don’t control the chain, nor does it treat things as if they were remittance businesses. Native tokens like ETH, after passing maturity tests, can be categorized as “digital commodities” under the CFTC. These provisions have to be written into law to count. Asset classification and developer protection are things the SEC can’t provide with exemptions and guidance alone; even if it does now, a future administration can change it back.
Coinbase CEO Brian Armstrong said the bill’s failure is disappointing, but fortunately there’s another path: going through the SEC and the CFTC. The worry from Enso co-founder Connor Howe is almost the opposite: a new chair wouldn’t need a Senate confirmation vote to rewrite an institutional rule. Strategy was even more blunt, saying BTC’s regulatory status in the U.S. has been clear for years.
I partly agree with all three perspectives. The three sides are really talking about different assets. On BTC, Strategy is right. Coinbase and Robinhood, like licensed companies, are covered—Armstrong is also right: the administrative route is enough, and arguably faster. But once you get to layer $ETH , things get complicated. ETH itself is most likely treated as a commodity; the people affected are the open protocols running on ETH and the developers who write code for them. They were waiting for a law to carve out a safe, unified zone—now they can only hope the regulator’s attitude stays consistent. Howe’s concern lands here most accurately.
So my judgment is: this week’s price action doesn’t care, and that’s correct in the short term. The market is calming after the rate hike in macro terms, and the SEC’s ability to quickly push exemptions/approvals is also real—both are true. But the market is likely underestimating the impact of legislative failure on open DeFi. For now, regulatory benefits are concentrated on the side with gatekeeping, and that side’s rules themselves are temporary. After mid-year elections, if the political landscape and regulatory approach change, exemptions can be given—and taken back.
If the Senate were to retake the vote before this year’s recess and pass it, or if the SEC and CFTC include non-custodial developers in protection within formal rules, then the cost of legislative failure would be smaller than I estimate. Conversely, if over the next few months we only see permissioned pools and licensed channels, and open DeFi keeps getting no further movement, then the risk will keep hanging there.
Next, you can look at the SEC and CFTC’s follow-up rules to see whether they explicitly mention developers who don’t have custody of users’ funds. If they do, the gap left by #CLARITY法案 can be filled. If it’s only permissioned pools, then this week’s rally will only be on the licensed-institution side.
5
2.4k
·
--
For the past two years, people in the compute-power space have gotten used to a familiar script: more and more cards keep coming out from Nvidia, so rents will inevitably drift downward. This week, Nebius went the other way. It increased prices for on-demand GPUs, moving from the previous-generation cards straight to the latest Blackwell lineup—prices that have already risen once earlier this year. When the news broke, the stock jumped that night; peers moved along with it. But by the time U.S. markets opened, the gain had been largely given back—more than half of it.
What the price increase signals is that Neocloud truly has pricing power. The question is why investors only gave it a half-day good reaction. That’s what I’ve been trying to figure out. $NBISB is currently around $216, still far below the mid-August peak.
According to Reuters, the new pricing schedule takes effect on October 1, with Nvidia GPUs across all generations raised by 17% to 21%. For H100, the per-card price goes from $3.85 to $4.50. The latest B300 saw the biggest increase, and CPU instances and memory also rose. The previous round was in May; this time, they added another layer at a higher level. CoreWeave previously hinted at price increases too, and in recent days capacity has basically been sold out.
What I care about most is the H100 segment. This card has been shipping for more than three years; by logic, prices should have fallen to clear inventory by now, yet rents are still moving upward. In its Q2 shareholder letter, Nebius also noted that the prices for new contracts signed for older-generation cards were more than 30% higher than in Q1. This ties into the largest controversy in AI infrastructure: depreciation. Starting this year, Nebius extended the depreciation life of servers and networking equipment from 4 years to 5 years. Michael Burry publicly criticized tech companies last year for lengthening server depreciation and making profits look better. Older cards become more expensive to lease, which is exactly the strongest rebuttal in the hands of the bulls: if cards can still be rented out at higher prices, adding another year of depreciation still holds up.
So why didn’t the stock win investors over. After reading the shareholder letters, I believe the direct contribution of the price increase to this year’s revenue isn’t as big as the headline suggests. Nebius relies on mid-term contracts of one to three years to make its living, and long-term customers already get discounted pricing. This time, the changes target on-demand listed prices, covering only part of the revenue base. The large orders signed in Q2 mostly correspond to capacity that won’t come online until the end of this year, contributing mainly in 2027. What the price increase changes is expectations for renewals and new contracts; the quarterly books basically don’t move.
Nebius is also testing more aggressive pricing. The shareholder letter says that in Q3 it ran the first pilot of a capacity auction, securing the highest Blackwell deal price the company has achieved so far, and it also signed its first short-term “urgent” orders for three to six months at prices clearly higher than standard contracts. If you view the on-demand price increase as part of this package, it looks more like it’s setting a price anchor for next year’s new contracts.
The pressure on the other side of the ledger is even bigger. In Q2, Nebius revenue was $582 million, while capital expenditures were about $5.7 billion in the same period—its spending pace is close to ten times its cash-in. How is the gap funded? The shareholder letter lists three options: customer prepayments, asset-backed loans, and a share issuance. By the end of June, the company sold more than 10 million shares via market-priced issuance, with an average price of $223.6. Then in August it issued a sizable batch of convertible bonds. Now the stock trades below the average price of that issuance; in the past month it’s fallen by more than 20%. Dilution concerns are a major driver. The benefits of the price increase have to first offset the dilution from each round of financing before they finally flow back to existing shareholders.
Wall Street is clearly divided on this. Goldman analyst Alexander Duval raised his price target to $328 by late August, arguing that it’s getting power faster than expected and that prepayments make expansion easier to finance. Truist initiated coverage with a Buy at the beginning of September, also emphasizing the pricing power created by scarcity. The cautious camp is watching execution; DA Davidson previously cut its target price due to delays at the New Jersey Vineland data center. On the day of the price increase, CoreWeave didn’t rise—it fell instead. Some media analysis suggests investors worry about how much of its capacity has already been locked in at the old prices, and how much debt is being carried behind that.
My take is that the shift of bargaining power toward the supply side is real. The H100 pricing is hard evidence—that part is where I stand with Goldman and Truist. But I don’t agree that price increases can solve Nebius’s balance-sheet problems within one or two quarters. The company’s own model shortens the payback period for new contracts to 1 year and 10 months; previously it was two to three years. This holds only if prices can stay firm next year. When the next-generation Rubin ships at scale and new capacity floods the market, if older-card rents reverse downward, both assumptions—5 years of depreciation and payback in under two years—will be challenged at the same time. Then, looking back, today’s price increase may end up being evidence of a peak.
There’s another line in the shareholder letter that shows just how much confidence management has. Nebius said that by today’s terms, the 2027 capacity could already be sold out. The company intentionally reserved part of it for urgent orders, hoping to sell at even higher prices. That’s a bet on the rising-price trend: if they’re right, next year’s profits come out higher by a good margin; if they’re wrong, it means empty cabinets paired with interest that can’t be paid back.
So my view on this price increase is fairly neutral: it proves demand, but it doesn’t prove the financial model. #AI算力 can next look at the three-quarter report in November—whether the prices on newly signed contracts for older cards can still hold, and whether the cadence of share issuance and convertible bonds slows down. If both of these move in a good direction, then there will be a reason to reclaim the gains the stock has given back this time.
1
213
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
SECHaltsCryptoETFReviewsAmidFundingLapse
108,807 views
933 Discussing
🚨 SEC FREEZES CRYPTO ETF REVIEWS!
A major development is shaking the crypto market!
Due to the U.S. government funding crisis, the SEC has reportedly paused reviews of more than 90 crypto ETF applications. #SECHaltsCryptoETFReviewsAmidFundingLapse
This could have a serious impact on the market.
$SOL , $DOGE and other altcoins waiting for ETF approvals may face significant delays.
ETF approvals are one of the biggest potential catalysts for institutional money entering crypto. Any delay could weaken short-term expectations and increase market uncertainty.
However, this is not a rejection. Once the funding situation is resolved, reviews could resume.
Personally, I think this is a development worth watching closely. The longer the uncertainty continues, the greater the potential impact on altcoin sentiment.
DYOR.
Kripto Kurdu
·9 Likes
·4k views
ZcashETFPostsFirstWeeklyOutflow$93.6M
69,498 views
219 Discussing
GreekPoliceBustCryptoScamRingArrest17
247,560 views
1,712 Discussing