
CryptoLite_247
874 Posts
CryptoLite_247
Report
Block User
Free Stock Market News that is FAST, ACCURATE, CONSISTENT, and RELIABLE || Not Just Stock News || Crypto first commentary with Marco Market Context
Open Trade
Frequent Trader
5.4 Years
6 Following
309 Followers
1.2K+ Liked
Posts
Portfolio
All
Quotes
PINNED
See translation
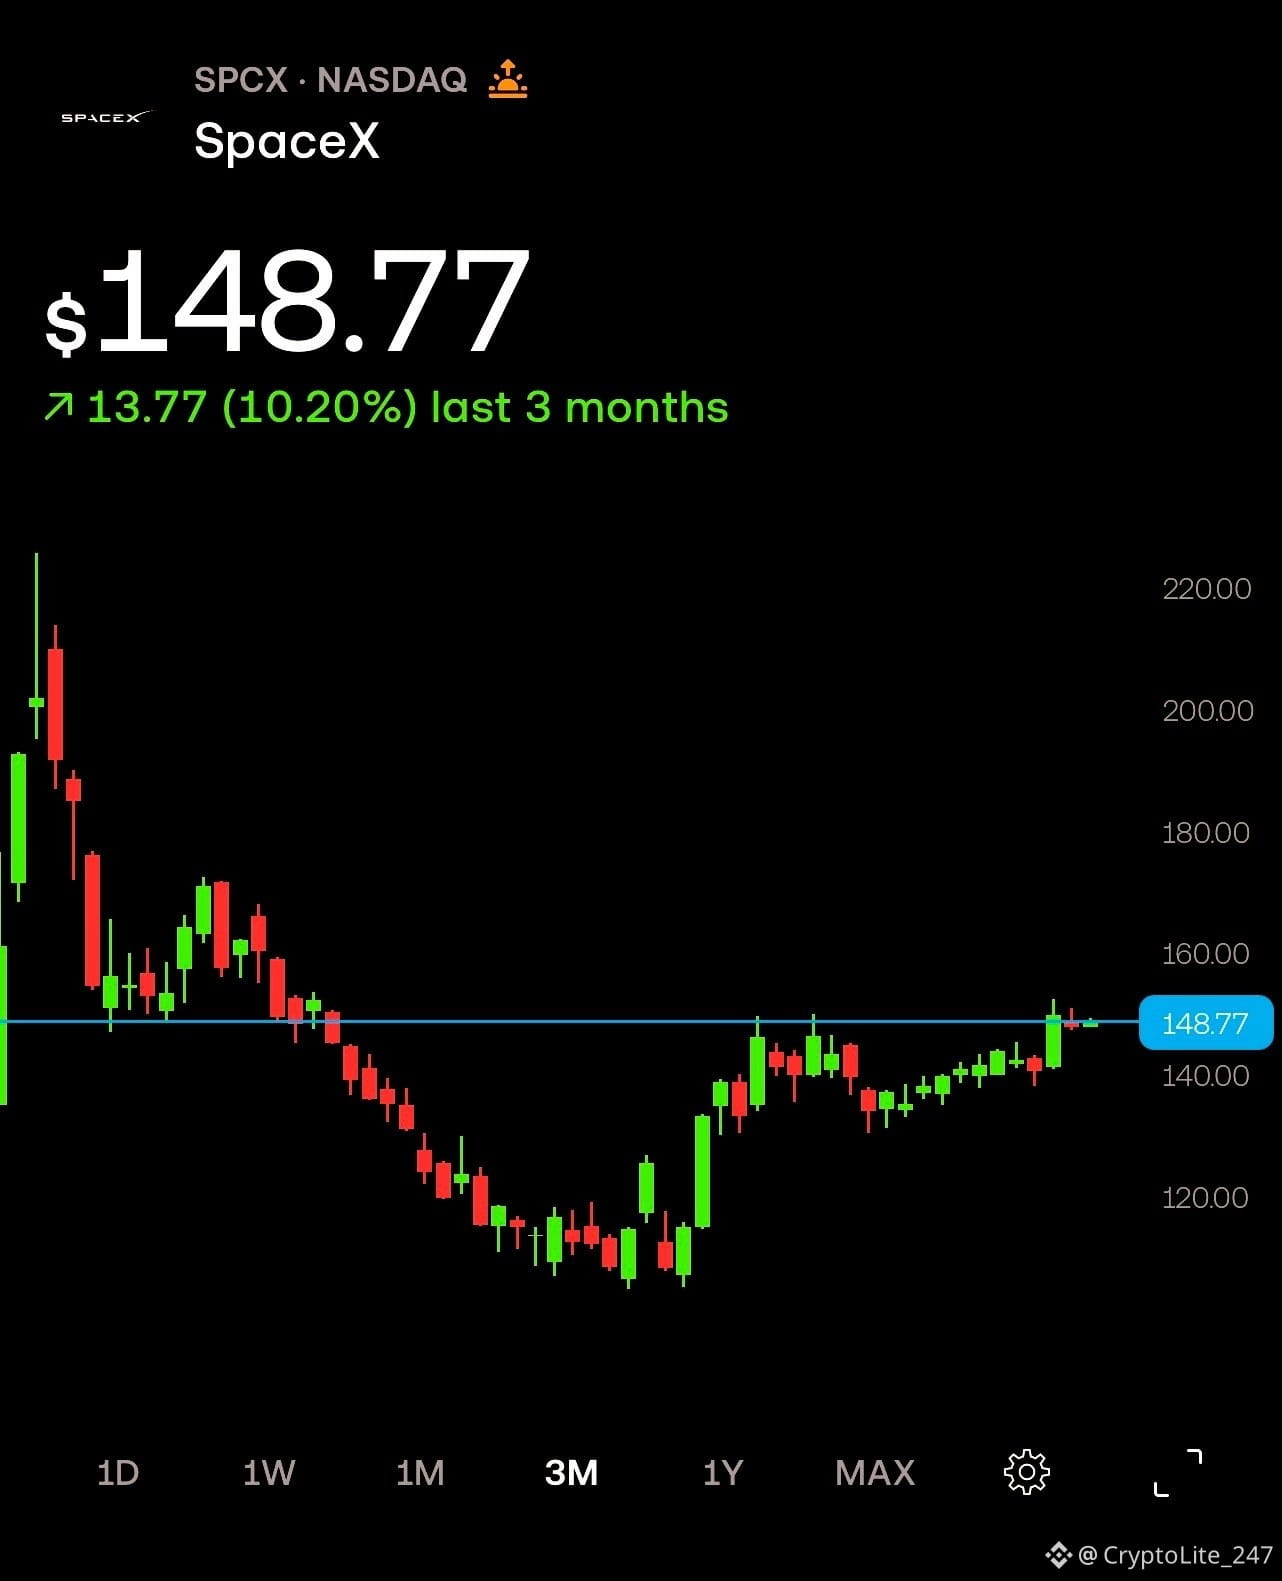
We’re never seeing $SPCX below $100 are we?
We’re never seeing $SPCX below $100 are we?
17
1
49
81.8k
See translation
$MU appointed Deirdre Hanford president of Micron Research Labs, its Boise-based research hub backed by $10B over the next decade and expected to break ground in 2027.
The lab will host hundreds of researchers focused on future memory, compute, advanced packaging and semiconductor manufacturing, while Micron’s broader $250B+ U.S. investment plan is expected to create 90,000 jobs.
$MU appointed Deirdre Hanford president of Micron Research Labs, its Boise-based research hub backed by $10B over the next decade and expected to break ground in 2027.
The lab will host hundreds of researchers focused on future memory, compute, advanced packaging and semiconductor manufacturing, while Micron’s broader $250B+ U.S. investment plan is expected to create 90,000 jobs.
The lab will host hundreds of researchers focused on future memory, compute, advanced packaging and semiconductor manufacturing, while Micron’s broader $250B+ U.S. investment plan is expected to create 90,000 jobs.
1
96
See translation
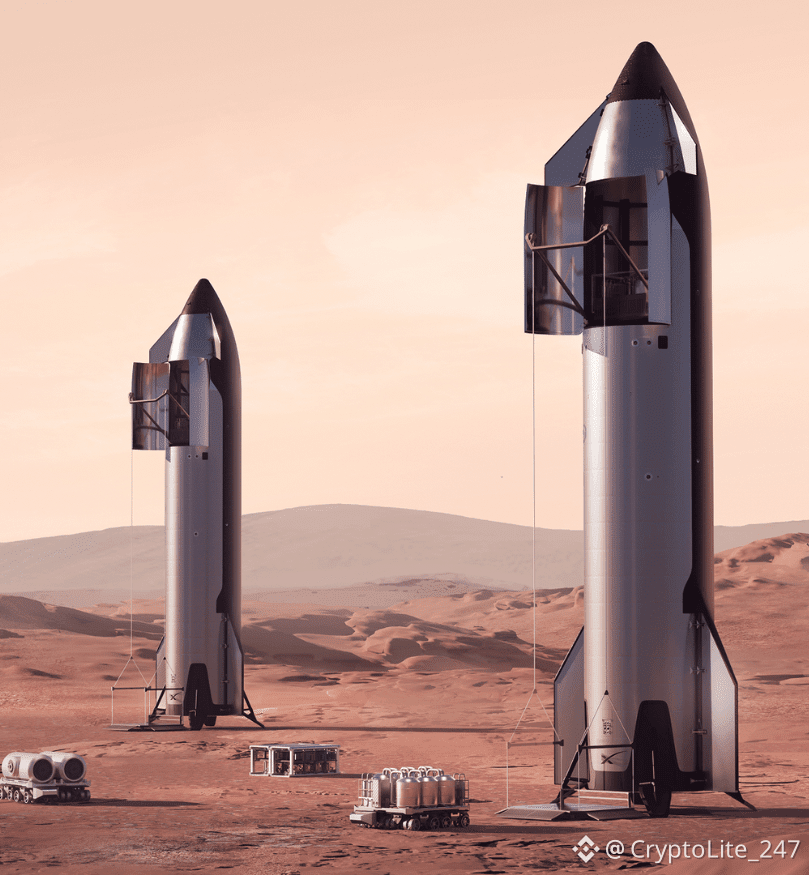
$SPCX is targeting September 22 for Starship Flight 14 which is planned to be its first mission into orbit around Earth.
The flight would also deploy Starlink V3 satellites for the first time as Starship starts moving from testing toward real payload deployment.
$SPCX is targeting September 22 for Starship Flight 14 which is planned to be its first mission into orbit around Earth.
The flight would also deploy Starlink V3 satellites for the first time as Starship starts moving from testing toward real payload deployment.
The flight would also deploy Starlink V3 satellites for the first time as Starship starts moving from testing toward real payload deployment.
1
321
See translation
$META CEO Mark Zuckerberg says “I don’t think the industry needs a coordinated pause” and believes labs should slow down individually when safety requires it.
Meta already delayed Muse for months which is why Zuck sees trust becoming a competitive advantage in AI.
$META CEO Mark Zuckerberg says “I don’t think the industry needs a coordinated pause” and believes labs should slow down individually when safety requires it.
Meta already delayed Muse for months which is why Zuck sees trust becoming a competitive advantage in AI.
Meta already delayed Muse for months which is why Zuck sees trust becoming a competitive advantage in AI.
1
332
Verified
See translation
Cathie Wood says each Starship launch could generate roughly $1B in revenue with Elon Musk targeting as many as 10K flights per year by 2030.
She says that would put Starship at $10T in annual revenue and make $SPCX $1.8T IPO valuation look very different in hindsight.
Cathie Wood says each Starship launch could generate roughly $1B in revenue with Elon Musk targeting as many as 10K flights per year by 2030.
She says that would put Starship at $10T in annual revenue and make $SPCX $1.8T IPO valuation look very different in hindsight.
She says that would put Starship at $10T in annual revenue and make $SPCX $1.8T IPO valuation look very different in hindsight.
2
7
4.7k
See translation
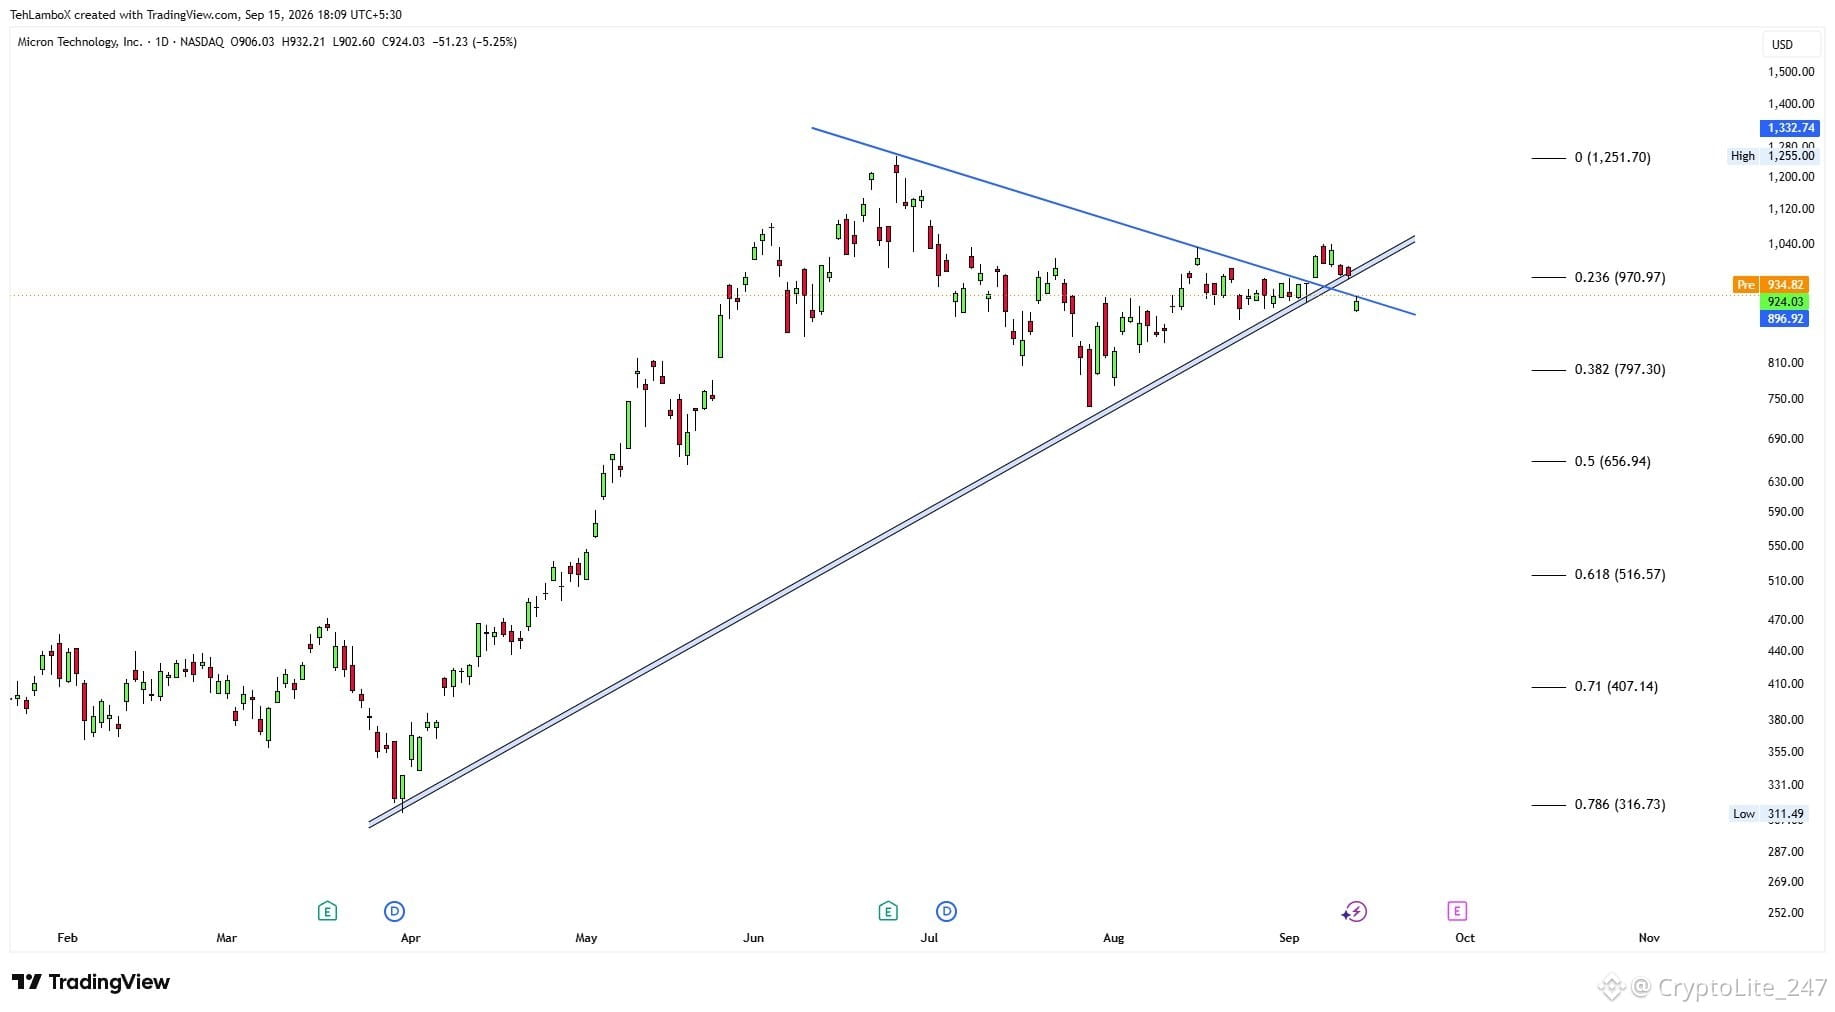
🚨UPDATE: I AM SCARED FOR $MU HERE!!
If this breaks 902, this will be ready for a bigger fall. This needs to recover 1000 this week otherwise next weeks might be bearish for MICRON!
Keep an eye on this one.
🚨UPDATE: I AM SCARED FOR $MU HERE!!
If this breaks 902, this will be ready for a bigger fall. This needs to recover 1000 this week otherwise next weeks might be bearish for MICRON!
Keep an eye on this one.
If this breaks 902, this will be ready for a bigger fall. This needs to recover 1000 this week otherwise next weeks might be bearish for MICRON!
Keep an eye on this one.
1
412
See translation
This is starting to get interesting.
$INTC is in exploratory talks with $SKHY SK Hynix on a potential deal that could bring SK Hynix memory-chip manufacturing to the U.S. for the first time, including possibly leasing part of Intel’s Ohio fab.
Another structure under discussion is a venture involving Intel, SK Hynix and major cloud companies seeking to secure memory supply, but no decision has been made and South Korean approval could be a hurdle for advanced DRAM or HBM production.
This is starting to get interesting.
$INTC is in exploratory talks with $SKHY SK Hynix on a potential deal that could bring SK Hynix memory-chip manufacturing to the U.S. for the first time, including possibly leasing part of Intel’s Ohio fab.
Another structure under discussion is a venture involving Intel, SK Hynix and major cloud companies seeking to secure memory supply, but no decision has been made and South Korean approval could be a hurdle for advanced DRAM or HBM production.
$INTC is in exploratory talks with $SKHY SK Hynix on a potential deal that could bring SK Hynix memory-chip manufacturing to the U.S. for the first time, including possibly leasing part of Intel’s Ohio fab.
Another structure under discussion is a venture involving Intel, SK Hynix and major cloud companies seeking to secure memory supply, but no decision has been made and South Korean approval could be a hurdle for advanced DRAM or HBM production.
1
344
See translation
BREAKING: $SPCX has signed a Starfall mission deal with Luxembourg-based Space Cargo for Starship’s first commercial mission, planned for 2028
Space Cargo plans to fly the BentoBox system aboard Starfall, carrying and safely returning up to 1 ton of customer payloads from orbit
BREAKING: $SPCX has signed a Starfall mission deal with Luxembourg-based Space Cargo for Starship’s first commercial mission, planned for 2028
Space Cargo plans to fly the BentoBox system aboard Starfall, carrying and safely returning up to 1 ton of customer payloads from orbit
Space Cargo plans to fly the BentoBox system aboard Starfall, carrying and safely returning up to 1 ton of customer payloads from orbit
1
18
Partly True
See translation
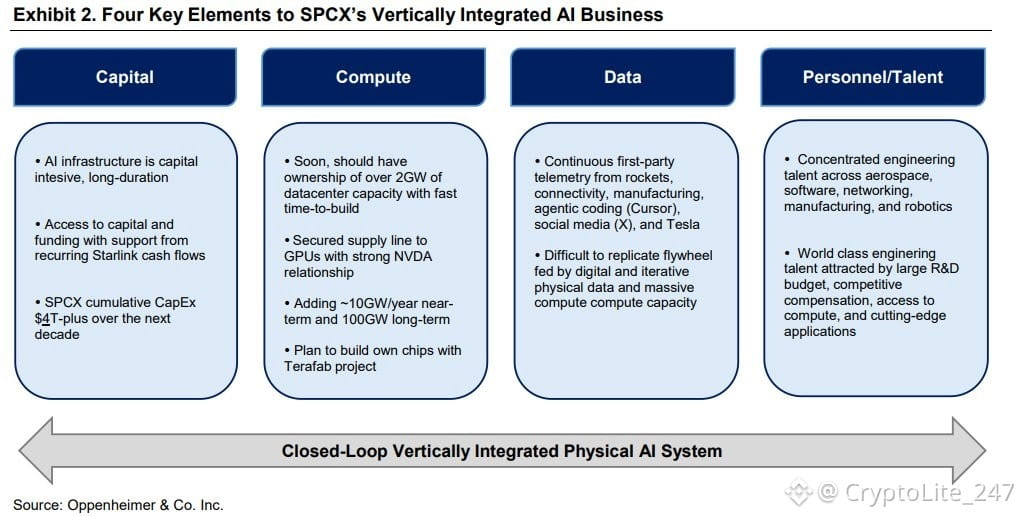
Here's a great visual of how $SPCX is building a vertically integrated AI business across capital, compute, data and talent.
That advantage becomes a lot more valuable as AI usage explodes with agentic workloads now driving ~70% of OpenRouter tokens while token consumption grows far faster than efficiency can offset.
You can already see it in compute pricing with $GOOGL paying ~$11 per GPU hour and an implied 9 month GPU payback as SpaceX scales toward 8 GW by the end of 2027.
Here's a great visual of how $SPCX is building a vertically integrated AI business across capital, compute, data and talent.
That advantage becomes a lot more valuable as AI usage explodes with agentic workloads now driving ~70% of OpenRouter tokens while token consumption grows far faster than efficiency can offset.
You can already see it in compute pricing with $GOOGL paying ~$11 per GPU hour and an implied 9 month GPU payback as SpaceX scales toward 8 GW by the end of 2027.
That advantage becomes a lot more valuable as AI usage explodes with agentic workloads now driving ~70% of OpenRouter tokens while token consumption grows far faster than efficiency can offset.
You can already see it in compute pricing with $GOOGL paying ~$11 per GPU hour and an implied 9 month GPU payback as SpaceX scales toward 8 GW by the end of 2027.
1
2
1.1k
Partly True
See translation
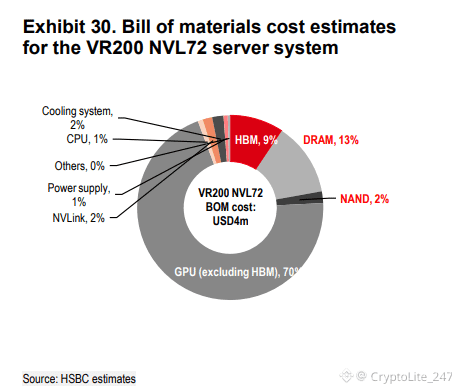
$NVDA Rubin BoM shows where the AI dollar is moving as memory now represents 24% of system cost and DRAM alone is larger than HBM:
• GPU excluding HBM 70%
• DRAM 13%
• HBM 9%
• NAND 2%
• NVLink 2%
• Cooling 2%
• Power supply 1%
• CPU 1%
That fits the architecture too because Rubin increases memory bandwidth 2.8x versus 2.3x more compute which broadens opportunity across HBM DRAM and NAND for $MU and $SKHY while Nvidia still captures most of the value inside each rack.
$NVDA Rubin BoM shows where the AI dollar is moving as memory now represents 24% of system cost and DRAM alone is larger than HBM:
• GPU excluding HBM 70%
• DRAM 13%
• HBM 9%
• NAND 2%
• NVLink 2%
• Cooling 2%
• Power supply 1%
• CPU 1%
That fits the architecture too because Rubin increases memory bandwidth 2.8x versus 2.3x more compute which broadens opportunity across HBM DRAM and NAND for $MU and $SKHY while Nvidia still captures most of the value inside each rack.
• GPU excluding HBM 70%
• DRAM 13%
• HBM 9%
• NAND 2%
• NVLink 2%
• Cooling 2%
• Power supply 1%
• CPU 1%
That fits the architecture too because Rubin increases memory bandwidth 2.8x versus 2.3x more compute which broadens opportunity across HBM DRAM and NAND for $MU and $SKHY while Nvidia still captures most of the value inside each rack.
2
2
959
See translation
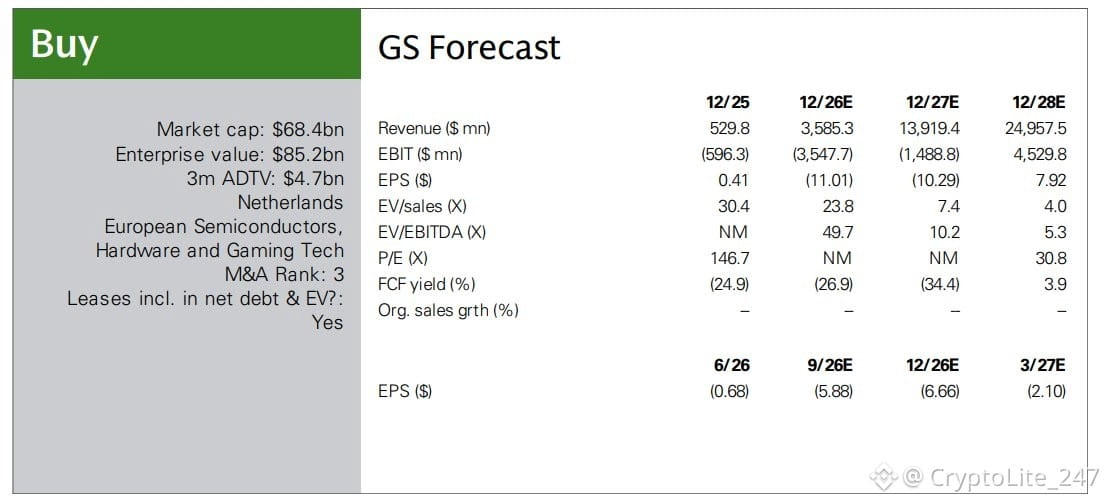
Goldman Sachs expects 2028 to be the inflection year for $NBIS with revenue nearly doubling to $25B while EPS flips from loss to nearly $8 of earnings (30x earnings).
You can see how its already moving that way with demand visible 24 months out and management saying it could sell all planned 2027 capacity today while keeping room for higher value customers as pricing and contract terms improve.
Nebius is also moving beyond raw infrastructure through $PLTR enterprise distribution while customer prepayments help fund growth which sets up 2028 as the year the capacity build starts translating into real earnings power.
Goldman Sachs expects 2028 to be the inflection year for $NBIS with revenue nearly doubling to $25B while EPS flips from loss to nearly $8 of earnings (30x earnings).
You can see how its already moving that way with demand visible 24 months out and management saying it could sell all planned 2027 capacity today while keeping room for higher value customers as pricing and contract terms improve.
Nebius is also moving beyond raw infrastructure through $PLTR enterprise distribution while customer prepayments help fund growth which sets up 2028 as the year the capacity build starts translating into real earnings power.
You can see how its already moving that way with demand visible 24 months out and management saying it could sell all planned 2027 capacity today while keeping room for higher value customers as pricing and contract terms improve.
Nebius is also moving beyond raw infrastructure through $PLTR enterprise distribution while customer prepayments help fund growth which sets up 2028 as the year the capacity build starts translating into real earnings power.
1
1
458
·
--
Bullish
See translation
JUST IN: $NBIS Nebius contract value per megawatt jumped to over $40M this year as Chamath Palihapitiya says “they’re superb, but we need 50 of these guys, 100 of them, 1,000 of them.”
JUST IN: $NBIS Nebius contract value per megawatt jumped to over $40M this year as Chamath Palihapitiya says “they’re superb, but we need 50 of these guys, 100 of them, 1,000 of them.”
1
202
·
--
Bullish
See translation
$FPS.US Q4 FY26
Revenue: $462M, +94% YoY (record) GAAP EPS: $0.21 Adjusted EPS: $0.25 Bookings: $1.5B, +375% YoY (record) Book-to-bill: 3.3x Backlog: $3.0B, +256% YoY (record) Net income: $66M, 14.3% margin Adjusted EBITDA: $113M, +163% YoY, 24.4% margin Operating cash flow: $74M
FY26 full year: Revenue: $1.42B, +89% YoY Adjusted EBITDA: $323M, +91% YoY Adjusted EPS: $0.68
FY27 Guide: Revenue: $2.4B-$2.6B, +76% at midpoint Adjusted EBITDA: $575M-$625M, +86% at midpoint Adjusted EPS: $1.26-$1.40, +95% at midpoint
Notes: Revenue, EBITDA, and adjusted net income all beat the high end of May guidance. Q4 guide topped out at $432M and they did $462M.
They booked more orders in the fourth quarter than they generated in revenue for the entire fiscal year. That is the number that matters.
Backlog grew 53% in a single quarter. Book-to-bill went from 2.3x to 3.3x. Demand is accelerating, not plateauing.
Margins expanded 200 bps sequentially for the second straight quarter while new campuses are still ramping. Net income margin up 800 bps QoQ.
Powertrain Solutions grew 259% for the year and is now a third of revenue. Putting $35M into Tijuana to expand that capacity by more than 50%. Total revenue capacity goes to $5.8B.
FY27 guide is significantly above the IPO forecast and management expects revenue and EBITDA to step up every quarter. Stock closed at $31 going into this.
$FPS.US Q4 FY26
Revenue: $462M, +94% YoY (record) GAAP EPS: $0.21 Adjusted EPS: $0.25 Bookings: $1.5B, +375% YoY (record) Book-to-bill: 3.3x Backlog: $3.0B, +256% YoY (record) Net income: $66M, 14.3% margin Adjusted EBITDA: $113M, +163% YoY, 24.4% margin Operating cash flow: $74M
FY26 full year: Revenue: $1.42B, +89% YoY Adjusted EBITDA: $323M, +91% YoY Adjusted EPS: $0.68
FY27 Guide: Revenue: $2.4B-$2.6B, +76% at midpoint Adjusted EBITDA: $575M-$625M, +86% at midpoint Adjusted EPS: $1.26-$1.40, +95% at midpoint
Notes: Revenue, EBITDA, and adjusted net income all beat the high end of May guidance. Q4 guide topped out at $432M and they did $462M.
They booked more orders in the fourth quarter than they generated in revenue for the entire fiscal year. That is the number that matters.
Backlog grew 53% in a single quarter. Book-to-bill went from 2.3x to 3.3x. Demand is accelerating, not plateauing.
Margins expanded 200 bps sequentially for the second straight quarter while new campuses are still ramping. Net income margin up 800 bps QoQ.
Powertrain Solutions grew 259% for the year and is now a third of revenue. Putting $35M into Tijuana to expand that capacity by more than 50%. Total revenue capacity goes to $5.8B.
FY27 guide is significantly above the IPO forecast and management expects revenue and EBITDA to step up every quarter. Stock closed at $31 going into this.
Revenue: $462M, +94% YoY (record) GAAP EPS: $0.21 Adjusted EPS: $0.25 Bookings: $1.5B, +375% YoY (record) Book-to-bill: 3.3x Backlog: $3.0B, +256% YoY (record) Net income: $66M, 14.3% margin Adjusted EBITDA: $113M, +163% YoY, 24.4% margin Operating cash flow: $74M
FY26 full year: Revenue: $1.42B, +89% YoY Adjusted EBITDA: $323M, +91% YoY Adjusted EPS: $0.68
FY27 Guide: Revenue: $2.4B-$2.6B, +76% at midpoint Adjusted EBITDA: $575M-$625M, +86% at midpoint Adjusted EPS: $1.26-$1.40, +95% at midpoint
Notes: Revenue, EBITDA, and adjusted net income all beat the high end of May guidance. Q4 guide topped out at $432M and they did $462M.
They booked more orders in the fourth quarter than they generated in revenue for the entire fiscal year. That is the number that matters.
Backlog grew 53% in a single quarter. Book-to-bill went from 2.3x to 3.3x. Demand is accelerating, not plateauing.
Margins expanded 200 bps sequentially for the second straight quarter while new campuses are still ramping. Net income margin up 800 bps QoQ.
Powertrain Solutions grew 259% for the year and is now a third of revenue. Putting $35M into Tijuana to expand that capacity by more than 50%. Total revenue capacity goes to $5.8B.
FY27 guide is significantly above the IPO forecast and management expects revenue and EBITDA to step up every quarter. Stock closed at $31 going into this.
FPSUS+1.25%
1
2
420
·
--
Bullish
Verified
See translation
BREAKING: $SPCX President Gwynne Shotwell says demand for AI compute remains extremely strong and hints at an upcoming announcement:
“Compute rental is a heck of a business. We see no drop in demand at all. It’s a lot. I think we’ll probably do some announcement quickly.”
BREAKING: $SPCX President Gwynne Shotwell says demand for AI compute remains extremely strong and hints at an upcoming announcement:
“Compute rental is a heck of a business. We see no drop in demand at all. It’s a lot. I think we’ll probably do some announcement quickly.”
“Compute rental is a heck of a business. We see no drop in demand at all. It’s a lot. I think we’ll probably do some announcement quickly.”
3
6
5.4k
Partly True
See translation
Cathie Wood bought the rip with $7.3M worth of $META . She also bought $4.2M of $AVAV.US .
Cathie Wood bought the rip with $7.3M worth of $META . She also bought $4.2M of $AVAV.US .
META+1.48%
AVAVUS-0.81%
2
1
1.9k
·
--
Bullish
See translation
$AAPL has reportedly accepted Samsung’s Q1 2027 memory pricing with DRAM and NAND roughly 30% to 40% above Q3 levels.
Apple accepting those increases is another sign that memory suppliers still have the upper hand on pricing heading into 2027 especially for $MU and $SKHY
$AAPL has reportedly accepted Samsung’s Q1 2027 memory pricing with DRAM and NAND roughly 30% to 40% above Q3 levels.
Apple accepting those increases is another sign that memory suppliers still have the upper hand on pricing heading into 2027 especially for $MU and $SKHY
Apple accepting those increases is another sign that memory suppliers still have the upper hand on pricing heading into 2027 especially for $MU and $SKHY
1
1
1.2k
See translation
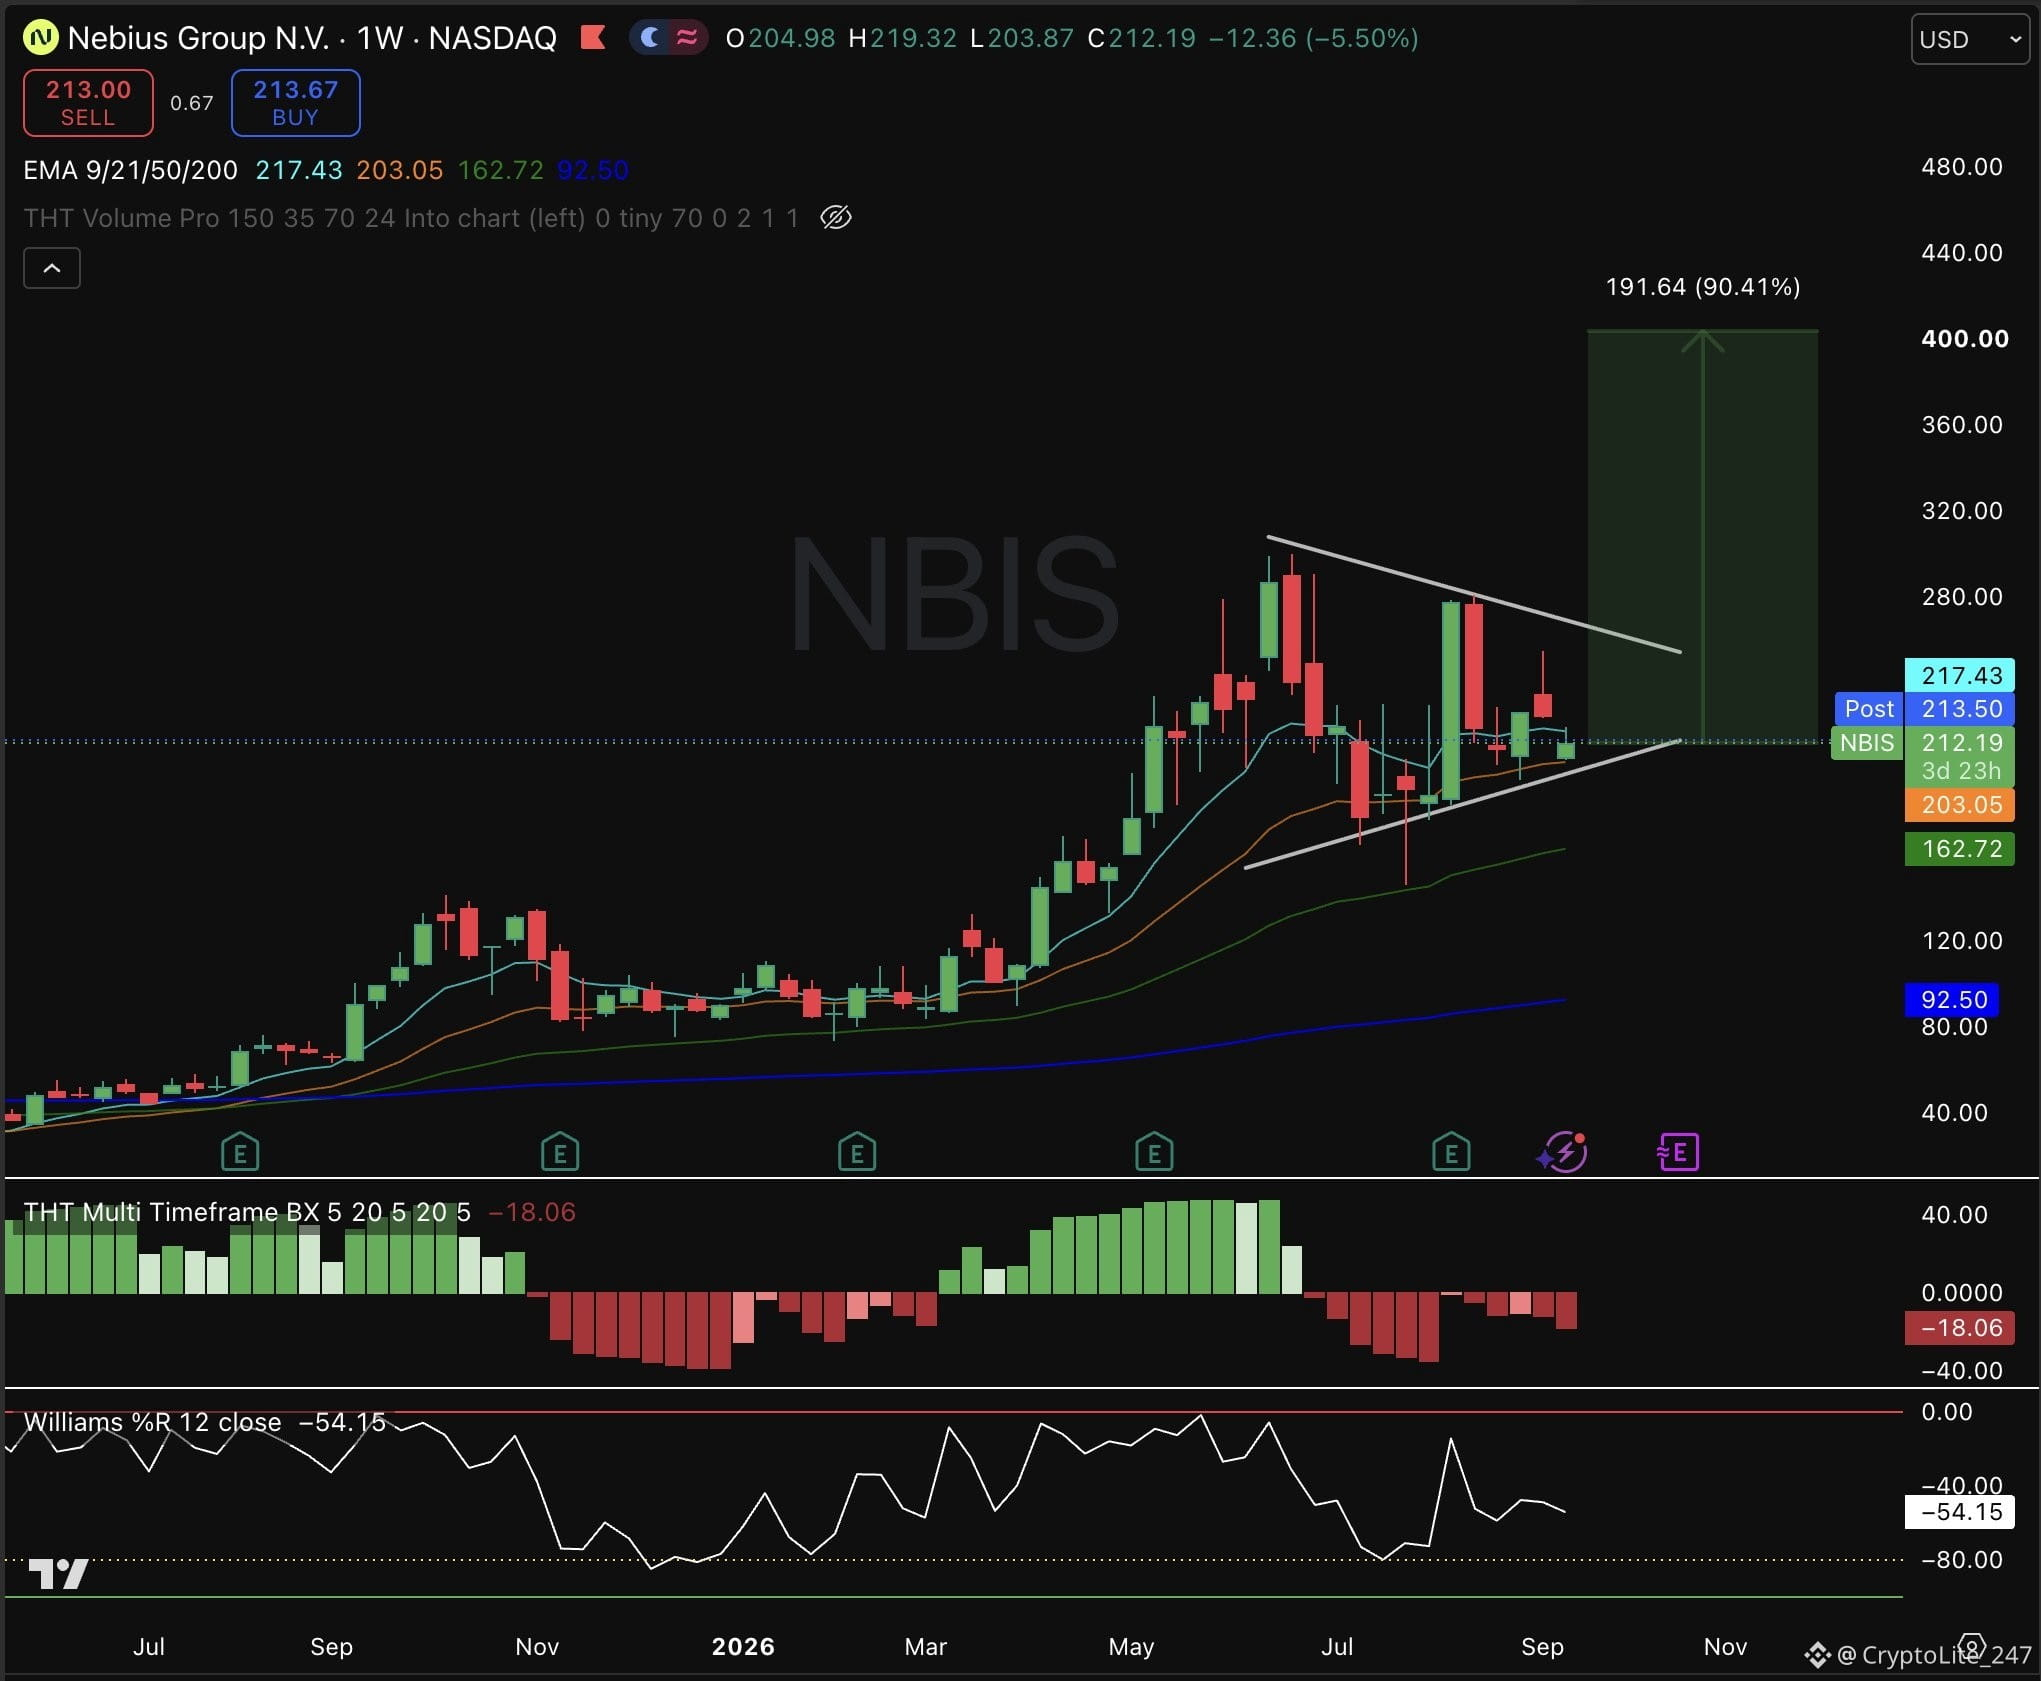
$NBIS currently retesting the 21 weekly EMA which it has bounced off every single time over the past year
It's also been consolidating in this range from $200-$280 for 3+ months now, last time we got this large of consolidation it led to the stock breaking out 200%+
Some catalysts which can help us break out again towards $400+ could be 2027 ARR guidance, another deal, or just more quarters of them reporting insane 500%+ YoY revenue growth.
$NBIS currently retesting the 21 weekly EMA which it has bounced off every single time over the past year
It's also been consolidating in this range from $200-$280 for 3+ months now, last time we got this large of consolidation it led to the stock breaking out 200%+
Some catalysts which can help us break out again towards $400+ could be 2027 ARR guidance, another deal, or just more quarters of them reporting insane 500%+ YoY revenue growth.
It's also been consolidating in this range from $200-$280 for 3+ months now, last time we got this large of consolidation it led to the stock breaking out 200%+
Some catalysts which can help us break out again towards $400+ could be 2027 ARR guidance, another deal, or just more quarters of them reporting insane 500%+ YoY revenue growth.
1
1
416
See translation
JPMorgan just upgraded $IREN to overweight with a $65 price target.
Sees them as “formidable” or top-tier neocloud/AI infrastructure provider.
I think $IREN remains one of the most interesting AI-Infra plays here, with asymmetric upside.
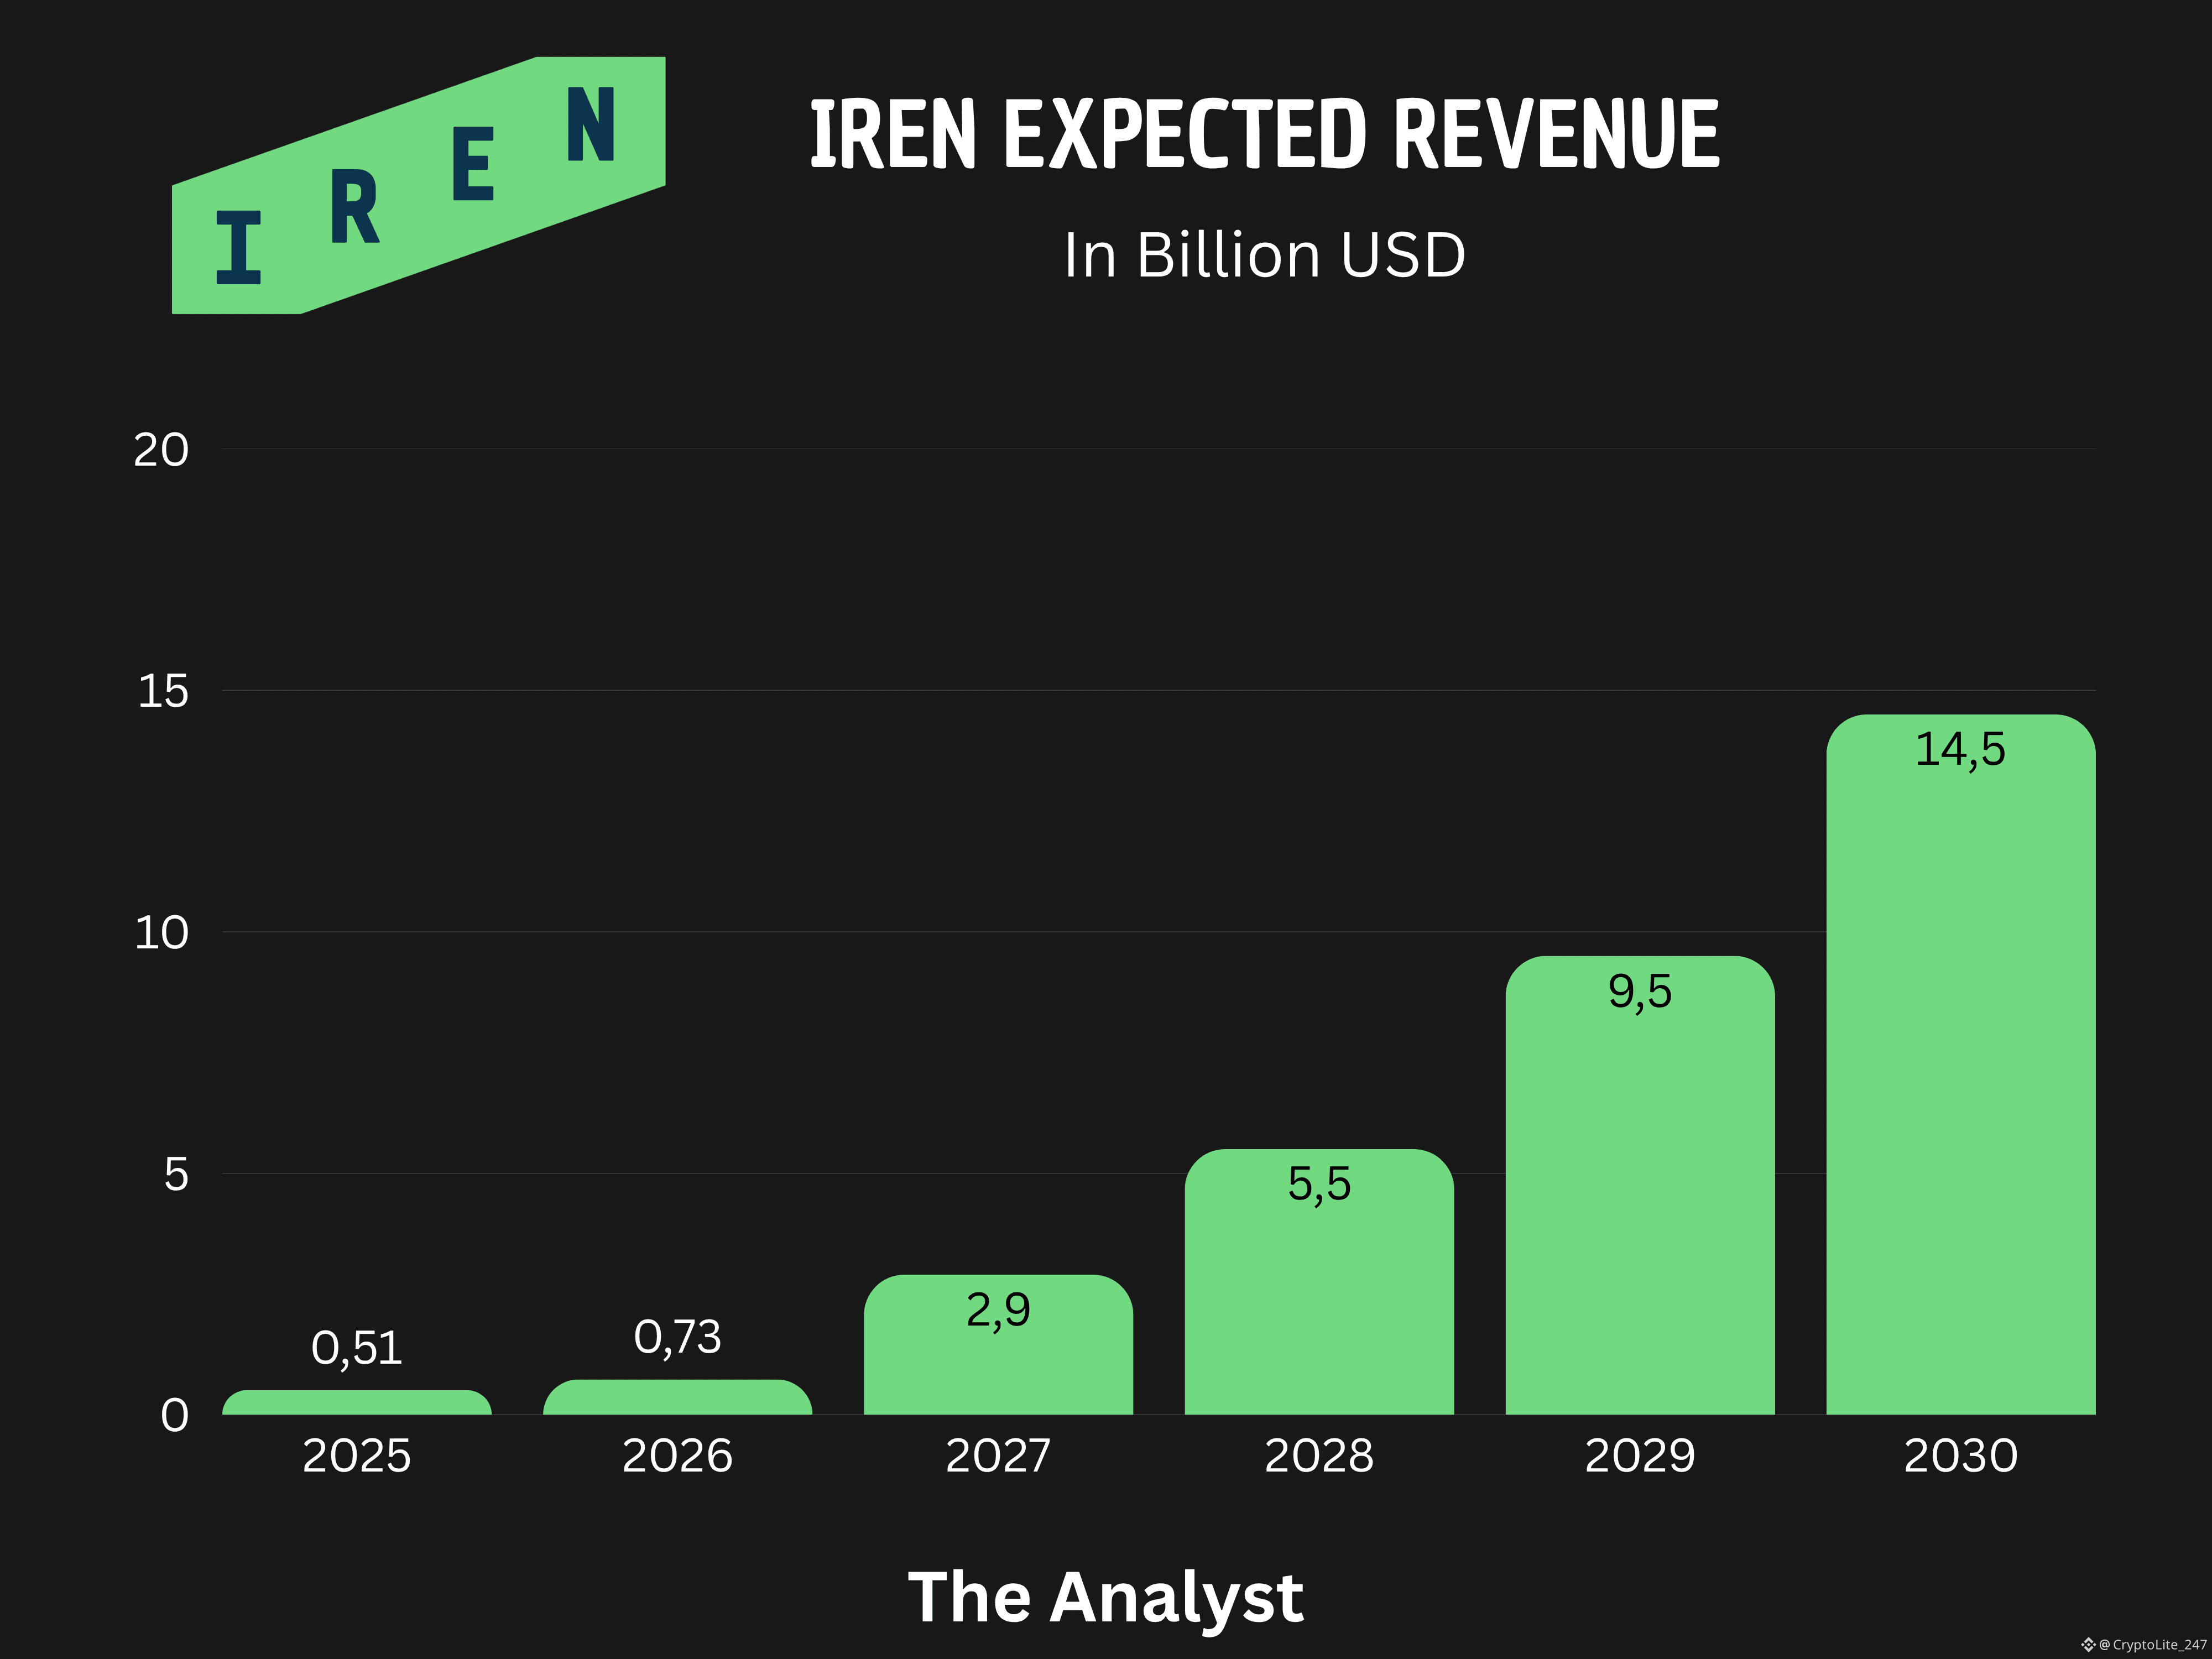
Annual revenue is expected to 20x until 2030.
Exit ARR guidance for 2026 is at $4B.
85% of this revenue is already under contract.
If $IREN proves that they can actually execute on their guidance now, the upside potential for a rerating is huge.
JPMorgan just upgraded $IREN to overweight with a $65 price target.
Sees them as “formidable” or top-tier neocloud/AI infrastructure provider.
I think $IREN remains one of the most interesting AI-Infra plays here, with asymmetric upside.
Annual revenue is expected to 20x until 2030.
Exit ARR guidance for 2026 is at $4B.
85% of this revenue is already under contract.
If $IREN proves that they can actually execute on their guidance now, the upside potential for a rerating is huge.
Sees them as “formidable” or top-tier neocloud/AI infrastructure provider.
I think $IREN remains one of the most interesting AI-Infra plays here, with asymmetric upside.
Annual revenue is expected to 20x until 2030.
Exit ARR guidance for 2026 is at $4B.
85% of this revenue is already under contract.
If $IREN proves that they can actually execute on their guidance now, the upside potential for a rerating is huge.
129
Partly True
See translation
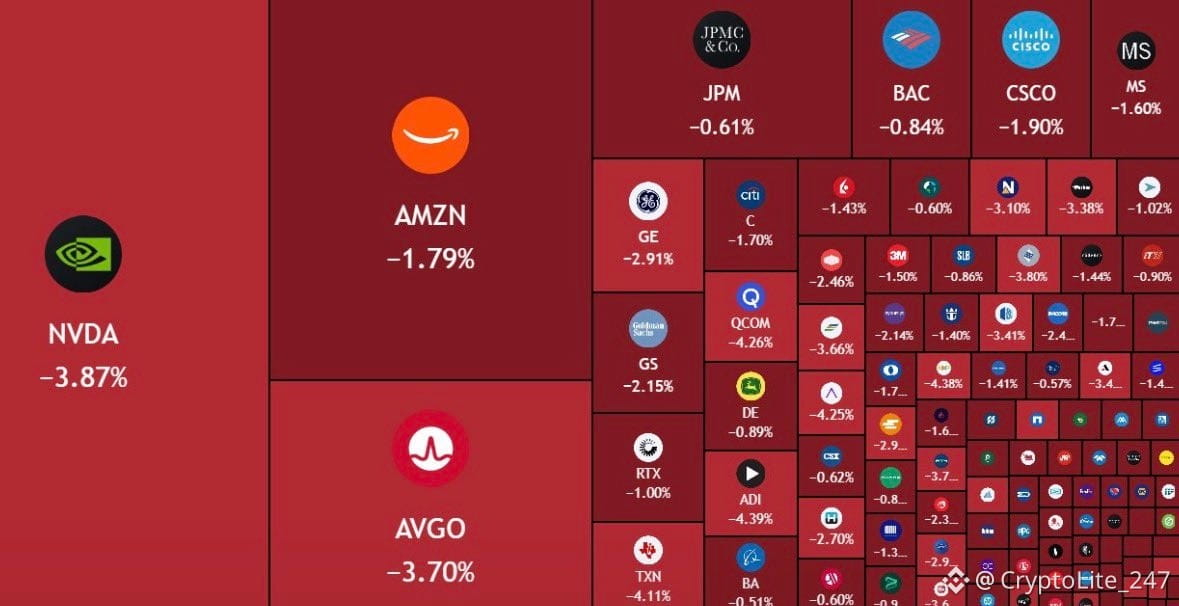
JUST IN: Over $500,000,000,000 erased from the US stock at market open
$NVDA
$AVGO
JUST IN: Over $500,000,000,000 erased from the US stock at market open
$NVDA
$AVGO
$NVDA
$AVGO
1
536
See translation
$NVDA is making quantum computing easier to build with CUDA Q Logical which is a new platform that helps researchers design systems that can correct their own errors and run useful applications.
Fermilab already cut development from 5 months to 3 weeks while another team modeled 1,000 logical qubits with ~10x less hardware.
$NVDA is making quantum computing easier to build with CUDA Q Logical which is a new platform that helps researchers design systems that can correct their own errors and run useful applications.
Fermilab already cut development from 5 months to 3 weeks while another team modeled 1,000 logical qubits with ~10x less hardware.
Fermilab already cut development from 5 months to 3 weeks while another team modeled 1,000 logical qubits with ~10x less hardware.
1
198
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
FedRateWatch
905,700 views
4,339 Discussing
Share & Win Traffic Reward in our Trending Hashtag Campaign
✨Topic: FOMC September, What's The Fed's Next Move?
👉How to Join:
Publish a short post or article with hashtag #FedRateWatch
Create content based on the below angles:
- August core CPI rose 0.3% month-over-month, and the odds of a 25bp hike this week are now close to 90%. Do you anticipate a rate hike this week? Is it a one-off, or the start of a longer hiking cycle?
- If the hike lands, how does it play out for BTC, tech stocks, and gold? Bullish or bearish?
- How are you planning to trade next? Share your BTC, stocks or gold trade/holdings with our trade sharing widget.
⏰Campaign Period:
- 2026-09-15 11:00 - 2026-09-17 3:00 UTC
🎁Reward:
- Qualified posts that comply with the above guidelines and contain more than 100 words will be reviewed and may receive a random traffic boost of 500 to 3,000 views. You will receive a notification from your feed secretary if your post is selected.
- Get a chance to have your article featured on Binance Square Official
Need ideas for your post? Visit the topic page #FedRateWatch or the Square Guide on How to Post for Better Reach.
Binance Square Official
·523 Likes
·1.2M views
MSTRTradingVolumeSurpassesMorganStanley
1,355 views
84 Discussing
BitcoinFalls4%
8,727 views
329 Discussing