

Insight Lab CH
1.2k Posts

Insight Lab CH
Report
Block User
2 Following
32 Followers
57 Liked
Posts
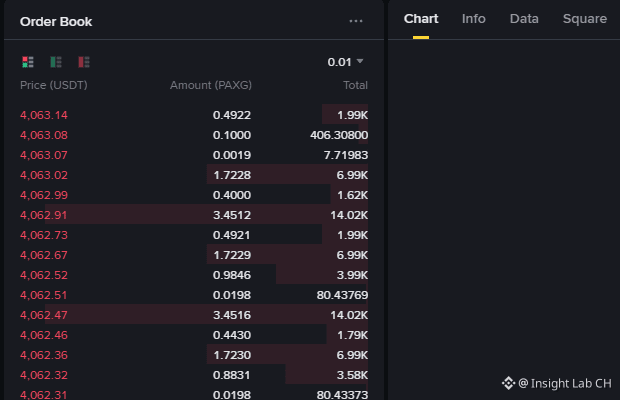
Spot gold prices surged sharply in a one-way rally during today's trading session, climbing more than 1.00% on the day and touching an intraday high of $4,056.94 per ounce. This sharp move came at a sensitive juncture, with geopolitical tensions remaining elevated and major central banks divided over the direction of monetary policy.
Gold broke through a key resistance level and topped the $4,050 mark, signaling that institutional safe-haven funds are flowing back into traditional defensive assets at an accelerating pace. With inflationary pressures persisting and macroeconomic uncertainty rising, investors are growing significantly more skeptical of credit assets and the purchasing power of fiat currencies, while market concern about downside risks has clearly intensified.
The large-scale influx of safe-haven buying quickly boosted liquidity across the precious metals sector. In broader financial markets, however, such a strong defensive allocation often drains capital from risk assets. The simultaneous rise in commodities and safe-haven assets could further stoke inflation expectations and weigh on fixed-income assets, keeping U.S. Treasury yields and the dollar locked in a tug-of-war at elevated levels.
For crypto markets, the heavy flow of capital into traditional safe-haven assets such as gold highlights investors' caution amid the current high-volatility environment. Although the digital-gold narrative remains intact over the long term, in the short term $BTC may face the dual challenges of macro liquidity being diverted elsewhere and speculative positions being reduced for safety. Investors should be alert to the pullback pressure that could arise as risk appetite contracts. #Gold #MacroEconomics #SafeHaven
Spot gold prices surged sharply in a one-way rally during today's trading session, climbing more than 1.00% on the day and touching an intraday high of $4,056.94 per ounce. This sharp move came at a sensitive juncture, with geopolitical tensions remaining elevated and major central banks divided over the direction of monetary policy.
Gold broke through a key resistance level and topped the $4,050 mark, signaling that institutional safe-haven funds are flowing back into traditional defensive assets at an accelerating pace. With inflationary pressures persisting and macroeconomic uncertainty rising, investors are growing significantly more skeptical of credit assets and the purchasing power of fiat currencies, while market concern about downside risks has clearly intensified.
The large-scale influx of safe-haven buying quickly boosted liquidity across the precious metals sector. In broader financial markets, however, such a strong defensive allocation often drains capital from risk assets. The simultaneous rise in commodities and safe-haven assets could further stoke inflation expectations and weigh on fixed-income assets, keeping U.S. Treasury yields and the dollar locked in a tug-of-war at elevated levels.
For crypto markets, the heavy flow of capital into traditional safe-haven assets such as gold highlights investors' caution amid the current high-volatility environment. Although the digital-gold narrative remains intact over the long term, in the short term $BTC may face the dual challenges of macro liquidity being diverted elsewhere and speculative positions being reduced for safety. Investors should be alert to the pullback pressure that could arise as risk appetite contracts. #Gold #MacroEconomics #SafeHaven
Gold broke through a key resistance level and topped the $4,050 mark, signaling that institutional safe-haven funds are flowing back into traditional defensive assets at an accelerating pace. With inflationary pressures persisting and macroeconomic uncertainty rising, investors are growing significantly more skeptical of credit assets and the purchasing power of fiat currencies, while market concern about downside risks has clearly intensified.
The large-scale influx of safe-haven buying quickly boosted liquidity across the precious metals sector. In broader financial markets, however, such a strong defensive allocation often drains capital from risk assets. The simultaneous rise in commodities and safe-haven assets could further stoke inflation expectations and weigh on fixed-income assets, keeping U.S. Treasury yields and the dollar locked in a tug-of-war at elevated levels.
For crypto markets, the heavy flow of capital into traditional safe-haven assets such as gold highlights investors' caution amid the current high-volatility environment. Although the digital-gold narrative remains intact over the long term, in the short term $BTC may face the dual challenges of macro liquidity being diverted elsewhere and speculative positions being reduced for safety. Investors should be alert to the pullback pressure that could arise as risk appetite contracts. #Gold #MacroEconomics #SafeHaven
183
Wall Street Journal reporter Nick Timiraos, often called the “Fed whisperer,” recently wrote that under current Fed Chair Kevin Warsh, the Federal Reserve has officially shifted into a tightening cycle. Looking back at history, he stressed that this is precisely when “forward guidance” plays a pivotal role, as it did in 1999, when the Fed used clear communication to guide market expectations before adjusting interest rates and avoid a repeat of severe turbulence.
This revisiting of past tightening cycles is no coincidence. It suggests that, after restarting rate hikes in September, the Fed’s policy communications are at an extremely sensitive turning point. Contrary to the wishful thinking of some market participants that “one rate hike and then it’s over,” stronger forward guidance during a tightening cycle often signals that a higher and more prolonged rate path is taking shape, as policymakers seek to prepare markets for the impact of further tightening.
At the macro level, this hawkish tightening signal is putting substantial pressure on risk assets. With expectations for policy rates remaining firm, U.S. Treasury yields and the dollar index will continue to receive support, while the marginal tightening of overall financial conditions will inevitably raise global borrowing costs and weigh on the real economy and the valuation resilience of capital markets.
For crypto assets, it will be difficult for the market to stage a major rally of its own amid the twin headwinds of tighter liquidity and high interest rates. Investors’ risk appetite for assets such as $BTC may cool further, with capital flows favoring a defensive stance. In the short term, investors should be highly alert to the risk of valuation declines if macro policy guidance turns more hawkish. 📉
#Fed #InterestRates #MacroEconomics
Wall Street Journal reporter Nick Timiraos, often called the “Fed whisperer,” recently wrote that under current Fed Chair Kevin Warsh, the Federal Reserve has officially shifted into a tightening cycle. Looking back at history, he stressed that this is precisely when “forward guidance” plays a pivotal role, as it did in 1999, when the Fed used clear communication to guide market expectations before adjusting interest rates and avoid a repeat of severe turbulence.
This revisiting of past tightening cycles is no coincidence. It suggests that, after restarting rate hikes in September, the Fed’s policy communications are at an extremely sensitive turning point. Contrary to the wishful thinking of some market participants that “one rate hike and then it’s over,” stronger forward guidance during a tightening cycle often signals that a higher and more prolonged rate path is taking shape, as policymakers seek to prepare markets for the impact of further tightening.
At the macro level, this hawkish tightening signal is putting substantial pressure on risk assets. With expectations for policy rates remaining firm, U.S. Treasury yields and the dollar index will continue to receive support, while the marginal tightening of overall financial conditions will inevitably raise global borrowing costs and weigh on the real economy and the valuation resilience of capital markets.
For crypto assets, it will be difficult for the market to stage a major rally of its own amid the twin headwinds of tighter liquidity and high interest rates. Investors’ risk appetite for assets such as $BTC may cool further, with capital flows favoring a defensive stance. In the short term, investors should be highly alert to the risk of valuation declines if macro policy guidance turns more hawkish. 📉
#Fed #InterestRates #MacroEconomics
This revisiting of past tightening cycles is no coincidence. It suggests that, after restarting rate hikes in September, the Fed’s policy communications are at an extremely sensitive turning point. Contrary to the wishful thinking of some market participants that “one rate hike and then it’s over,” stronger forward guidance during a tightening cycle often signals that a higher and more prolonged rate path is taking shape, as policymakers seek to prepare markets for the impact of further tightening.
At the macro level, this hawkish tightening signal is putting substantial pressure on risk assets. With expectations for policy rates remaining firm, U.S. Treasury yields and the dollar index will continue to receive support, while the marginal tightening of overall financial conditions will inevitably raise global borrowing costs and weigh on the real economy and the valuation resilience of capital markets.
For crypto assets, it will be difficult for the market to stage a major rally of its own amid the twin headwinds of tighter liquidity and high interest rates. Investors’ risk appetite for assets such as $BTC may cool further, with capital flows favoring a defensive stance. In the short term, investors should be highly alert to the risk of valuation declines if macro policy guidance turns more hawkish. 📉
#Fed #InterestRates #MacroEconomics
23
The U.S. Department of Commerce released durable goods orders data for September on Tuesday. Overall orders rose 1.8% month over month, above the previously expected 1.7%, while the prior figure was also revised up from -0.10% to 0.1%. However, core durable goods orders, which reflect companies' long-term investment appetite and exclude aircraft and defense, fell 0.5% month over month, far below the market's expected increase of 0.70%.
This combination of data exposes a structural divergence in the current economic fundamentals. While the overall indicator was strong, boosted by military equipment and large transportation orders, the sharp contraction in core capital goods orders suggests that companies are significantly slowing capital expenditure in the face of high interest rates and macro uncertainty.
After the data release, traditional financial markets reacted sharply, with the U.S. 30-year Treasury yield quickly rising and remaining at a high level of 5.304%. Persistently elevated long-term borrowing costs have intensified concerns that the medium- to long-term growth momentum of the real economy is being constrained, and the yield premium on dollar assets is directly weighing on risk appetite.
For crypto assets, elevated long-term U.S. Treasury yields will continue to drain liquidity from high-risk speculative markets, limiting the short-term valuation recovery room for digital assets represented by $BTC . If macro tightening pressures continue to build, investors should remain alert to downside volatility caused by a further decline in risk appetite. 📉
#DurableGoods #USEconomy #BondYields
The U.S. Department of Commerce released durable goods orders data for September on Tuesday. Overall orders rose 1.8% month over month, above the previously expected 1.7%, while the prior figure was also revised up from -0.10% to 0.1%. However, core durable goods orders, which reflect companies' long-term investment appetite and exclude aircraft and defense, fell 0.5% month over month, far below the market's expected increase of 0.70%.
This combination of data exposes a structural divergence in the current economic fundamentals. While the overall indicator was strong, boosted by military equipment and large transportation orders, the sharp contraction in core capital goods orders suggests that companies are significantly slowing capital expenditure in the face of high interest rates and macro uncertainty.
After the data release, traditional financial markets reacted sharply, with the U.S. 30-year Treasury yield quickly rising and remaining at a high level of 5.304%. Persistently elevated long-term borrowing costs have intensified concerns that the medium- to long-term growth momentum of the real economy is being constrained, and the yield premium on dollar assets is directly weighing on risk appetite.
For crypto assets, elevated long-term U.S. Treasury yields will continue to drain liquidity from high-risk speculative markets, limiting the short-term valuation recovery room for digital assets represented by $BTC . If macro tightening pressures continue to build, investors should remain alert to downside volatility caused by a further decline in risk appetite. 📉
#DurableGoods #USEconomy #BondYields
This combination of data exposes a structural divergence in the current economic fundamentals. While the overall indicator was strong, boosted by military equipment and large transportation orders, the sharp contraction in core capital goods orders suggests that companies are significantly slowing capital expenditure in the face of high interest rates and macro uncertainty.
After the data release, traditional financial markets reacted sharply, with the U.S. 30-year Treasury yield quickly rising and remaining at a high level of 5.304%. Persistently elevated long-term borrowing costs have intensified concerns that the medium- to long-term growth momentum of the real economy is being constrained, and the yield premium on dollar assets is directly weighing on risk appetite.
For crypto assets, elevated long-term U.S. Treasury yields will continue to drain liquidity from high-risk speculative markets, limiting the short-term valuation recovery room for digital assets represented by $BTC . If macro tightening pressures continue to build, investors should remain alert to downside volatility caused by a further decline in risk appetite. 📉
#DurableGoods #USEconomy #BondYields
34
A Saudi-led multinational coalition issued an official statement saying that coalition air defense forces had recently intercepted and destroyed two ballistic missiles launched by Yemen’s Houthi forces over Riyadh, the Saudi capital. The attack, aimed directly at the political and economic center of a key Gulf energy power, marks a new phase of substantial military escalation in the Middle East’s geopolitical confrontation. It has not only shattered the region’s fragile recent balance but also put the stability of a vital Gulf security corridor to a severe test once again.
The significance of this incident lies in the direct security threat it poses to global energy supply chains. Markets had broadly expected the conflict in the Middle East to remain a localized war of attrition, but the direct strike on Saudi Arabia’s heartland and major cities has overturned that optimistic outlook. At this sensitive juncture, when inflation remains stubbornly high across the world’s major economies, any weakening of the defenses of a key oil-producing nation could easily trigger a concentrated release of risk premiums on the crude oil supply side.
In terms of how the crisis is transmitted through macro financial markets, a sudden escalation in geopolitical tensions will quickly drive up oil prices and directly slow the pace of disinflation. Rising oil costs will limit major central banks’ room to cut interest rates, prompting risk-free U.S. Treasury yields to rebound and expanding safe-haven demand for the dollar. Against this backdrop, global equity markets and cross-asset valuation frameworks will come under broad pressure, as stagflation concerns once again begin to dominate the macroeconomic outlook.
For cryptocurrency markets, the worsening situation in the Middle East will bring significant liquidity withdrawal pressure in the short term. Amid extreme uncertainty and rising risk aversion, investors are more inclined to exit high-risk positions and move back into traditional defensive assets such as the U.S. dollar and gold. If expectations of tighter macroeconomic conditions become further entrenched alongside geopolitical risks, crypto assets, including $BTC , will face even heavier valuation correction and deleveraging pressures.
#Geopolitics #CrudeOil #MacroEconomy
A Saudi-led multinational coalition issued an official statement saying that coalition air defense forces had recently intercepted and destroyed two ballistic missiles launched by Yemen’s Houthi forces over Riyadh, the Saudi capital. The attack, aimed directly at the political and economic center of a key Gulf energy power, marks a new phase of substantial military escalation in the Middle East’s geopolitical confrontation. It has not only shattered the region’s fragile recent balance but also put the stability of a vital Gulf security corridor to a severe test once again.
The significance of this incident lies in the direct security threat it poses to global energy supply chains. Markets had broadly expected the conflict in the Middle East to remain a localized war of attrition, but the direct strike on Saudi Arabia’s heartland and major cities has overturned that optimistic outlook. At this sensitive juncture, when inflation remains stubbornly high across the world’s major economies, any weakening of the defenses of a key oil-producing nation could easily trigger a concentrated release of risk premiums on the crude oil supply side.
In terms of how the crisis is transmitted through macro financial markets, a sudden escalation in geopolitical tensions will quickly drive up oil prices and directly slow the pace of disinflation. Rising oil costs will limit major central banks’ room to cut interest rates, prompting risk-free U.S. Treasury yields to rebound and expanding safe-haven demand for the dollar. Against this backdrop, global equity markets and cross-asset valuation frameworks will come under broad pressure, as stagflation concerns once again begin to dominate the macroeconomic outlook.
For cryptocurrency markets, the worsening situation in the Middle East will bring significant liquidity withdrawal pressure in the short term. Amid extreme uncertainty and rising risk aversion, investors are more inclined to exit high-risk positions and move back into traditional defensive assets such as the U.S. dollar and gold. If expectations of tighter macroeconomic conditions become further entrenched alongside geopolitical risks, crypto assets, including $BTC , will face even heavier valuation correction and deleveraging pressures.
#Geopolitics #CrudeOil #MacroEconomy
The significance of this incident lies in the direct security threat it poses to global energy supply chains. Markets had broadly expected the conflict in the Middle East to remain a localized war of attrition, but the direct strike on Saudi Arabia’s heartland and major cities has overturned that optimistic outlook. At this sensitive juncture, when inflation remains stubbornly high across the world’s major economies, any weakening of the defenses of a key oil-producing nation could easily trigger a concentrated release of risk premiums on the crude oil supply side.
In terms of how the crisis is transmitted through macro financial markets, a sudden escalation in geopolitical tensions will quickly drive up oil prices and directly slow the pace of disinflation. Rising oil costs will limit major central banks’ room to cut interest rates, prompting risk-free U.S. Treasury yields to rebound and expanding safe-haven demand for the dollar. Against this backdrop, global equity markets and cross-asset valuation frameworks will come under broad pressure, as stagflation concerns once again begin to dominate the macroeconomic outlook.
For cryptocurrency markets, the worsening situation in the Middle East will bring significant liquidity withdrawal pressure in the short term. Amid extreme uncertainty and rising risk aversion, investors are more inclined to exit high-risk positions and move back into traditional defensive assets such as the U.S. dollar and gold. If expectations of tighter macroeconomic conditions become further entrenched alongside geopolitical risks, crypto assets, including $BTC , will face even heavier valuation correction and deleveraging pressures.
#Geopolitics #CrudeOil #MacroEconomy
394
Ukrainian President Zelenskyy said in his latest update that Russian forces fired 16 ballistic missiles into Ukraine and deployed more than 280 drones over the past night. At the same time, Zelenskyy publicly criticized delays in the delivery of air-defense interceptor missiles, saying they directly weakened frontline defenses and advanced the other side’s strategic objectives.
The ongoing escalation of large-scale airstrikes and disruptions in the supply chain for Western military aid highlight that the geopolitical conflict in Eastern Europe is entering a dangerous new phase of attrition warfare. Markets’ previous complacency about the conflict becoming normalized may be forced to shift, putting safe-haven premiums under renewed pressure to reprice.
A substantial rise in geopolitical risks is pushing up global stagflation expectations and increasing volatility in commodity and crude oil prices. The U.S. dollar index and Treasury yields are gaining safe-haven support, while valuations of high-risk assets will continue to face the dual pressures of tightening liquidity and risk aversion.
For crypto markets, liquidity outflows triggered by geopolitical crises often take effect before safe-haven narratives do. Against a backdrop of sharply rising macroeconomic uncertainty, risk assets such as $BTC are particularly vulnerable to near-term pressure, and investors should beware of sharp deleveraging risks.
#Geopolitics #UkraineCrisis #MacroRisk
Ukrainian President Zelenskyy said in his latest update that Russian forces fired 16 ballistic missiles into Ukraine and deployed more than 280 drones over the past night. At the same time, Zelenskyy publicly criticized delays in the delivery of air-defense interceptor missiles, saying they directly weakened frontline defenses and advanced the other side’s strategic objectives.
The ongoing escalation of large-scale airstrikes and disruptions in the supply chain for Western military aid highlight that the geopolitical conflict in Eastern Europe is entering a dangerous new phase of attrition warfare. Markets’ previous complacency about the conflict becoming normalized may be forced to shift, putting safe-haven premiums under renewed pressure to reprice.
A substantial rise in geopolitical risks is pushing up global stagflation expectations and increasing volatility in commodity and crude oil prices. The U.S. dollar index and Treasury yields are gaining safe-haven support, while valuations of high-risk assets will continue to face the dual pressures of tightening liquidity and risk aversion.
For crypto markets, liquidity outflows triggered by geopolitical crises often take effect before safe-haven narratives do. Against a backdrop of sharply rising macroeconomic uncertainty, risk assets such as $BTC are particularly vulnerable to near-term pressure, and investors should beware of sharp deleveraging risks.
#Geopolitics #UkraineCrisis #MacroRisk
The ongoing escalation of large-scale airstrikes and disruptions in the supply chain for Western military aid highlight that the geopolitical conflict in Eastern Europe is entering a dangerous new phase of attrition warfare. Markets’ previous complacency about the conflict becoming normalized may be forced to shift, putting safe-haven premiums under renewed pressure to reprice.
A substantial rise in geopolitical risks is pushing up global stagflation expectations and increasing volatility in commodity and crude oil prices. The U.S. dollar index and Treasury yields are gaining safe-haven support, while valuations of high-risk assets will continue to face the dual pressures of tightening liquidity and risk aversion.
For crypto markets, liquidity outflows triggered by geopolitical crises often take effect before safe-haven narratives do. Against a backdrop of sharply rising macroeconomic uncertainty, risk assets such as $BTC are particularly vulnerable to near-term pressure, and investors should beware of sharp deleveraging risks.
#Geopolitics #UkraineCrisis #MacroRisk
734
The Bank of Japan (BOJ) officially released its latest report on price trends on Tuesday. The data showed that in September, the underlying inflation indicator, which excludes fresh food and special factors, surged year over year to 3.2%, accelerating sharply from 2.6% the previous month and reaching its highest level in three years. The BOJ had already raised its benchmark interest rate to 1.25% in September, marking its largest rate hike since 1990. This strong set of figures directly confirms that inflationary pressures have spread throughout Japan.
The data’s significance lies in its unequivocal indication that Japan’s core inflation has become firmly established and moved well above the long-term target of 2%. Although markets broadly expect the BOJ to hold off on action at its monetary policy meeting this Friday, rising producer prices in the services sector amid tensions in the Middle East add to the picture. An official declaration that underlying inflation has reached its target now appears imminent, sharply increasing the likelihood of another rate hike in the coming months.
At the level of traditional macro finance, the BOJ’s continued hawkish shift is having a profound impact on global capital flows. The substantial rise in the cost of yen funding will continue to accelerate the unwinding of the global “yen carry trade.” The large-scale withdrawal of low-cost, yen-funded leveraged capital could easily push up global sovereign bond yields and heighten liquidity vulnerabilities in international financial markets.
For cryptoasset markets, rising global risk-free rates and the retreat of carry-trade capital are undoubtedly major headwinds. As the macro liquidity environment tightens, risk assets, including $BTC , face the dual pressures of valuation declines and liquidity outflows. Amid the current confluence of geopolitical complexity and monetary tightening, investors should remain highly cautious and watch for the potential risk of a deep downturn.📉
#BOJ #Inflation #InterestRates #MacroEconomics
The Bank of Japan (BOJ) officially released its latest report on price trends on Tuesday. The data showed that in September, the underlying inflation indicator, which excludes fresh food and special factors, surged year over year to 3.2%, accelerating sharply from 2.6% the previous month and reaching its highest level in three years. The BOJ had already raised its benchmark interest rate to 1.25% in September, marking its largest rate hike since 1990. This strong set of figures directly confirms that inflationary pressures have spread throughout Japan.
The data’s significance lies in its unequivocal indication that Japan’s core inflation has become firmly established and moved well above the long-term target of 2%. Although markets broadly expect the BOJ to hold off on action at its monetary policy meeting this Friday, rising producer prices in the services sector amid tensions in the Middle East add to the picture. An official declaration that underlying inflation has reached its target now appears imminent, sharply increasing the likelihood of another rate hike in the coming months.
At the level of traditional macro finance, the BOJ’s continued hawkish shift is having a profound impact on global capital flows. The substantial rise in the cost of yen funding will continue to accelerate the unwinding of the global “yen carry trade.” The large-scale withdrawal of low-cost, yen-funded leveraged capital could easily push up global sovereign bond yields and heighten liquidity vulnerabilities in international financial markets.
For cryptoasset markets, rising global risk-free rates and the retreat of carry-trade capital are undoubtedly major headwinds. As the macro liquidity environment tightens, risk assets, including $BTC , face the dual pressures of valuation declines and liquidity outflows. Amid the current confluence of geopolitical complexity and monetary tightening, investors should remain highly cautious and watch for the potential risk of a deep downturn.📉
#BOJ #Inflation #InterestRates #MacroEconomics
The data’s significance lies in its unequivocal indication that Japan’s core inflation has become firmly established and moved well above the long-term target of 2%. Although markets broadly expect the BOJ to hold off on action at its monetary policy meeting this Friday, rising producer prices in the services sector amid tensions in the Middle East add to the picture. An official declaration that underlying inflation has reached its target now appears imminent, sharply increasing the likelihood of another rate hike in the coming months.
At the level of traditional macro finance, the BOJ’s continued hawkish shift is having a profound impact on global capital flows. The substantial rise in the cost of yen funding will continue to accelerate the unwinding of the global “yen carry trade.” The large-scale withdrawal of low-cost, yen-funded leveraged capital could easily push up global sovereign bond yields and heighten liquidity vulnerabilities in international financial markets.
For cryptoasset markets, rising global risk-free rates and the retreat of carry-trade capital are undoubtedly major headwinds. As the macro liquidity environment tightens, risk assets, including $BTC , face the dual pressures of valuation declines and liquidity outflows. Amid the current confluence of geopolitical complexity and monetary tightening, investors should remain highly cautious and watch for the potential risk of a deep downturn.📉
#BOJ #Inflation #InterestRates #MacroEconomics
136
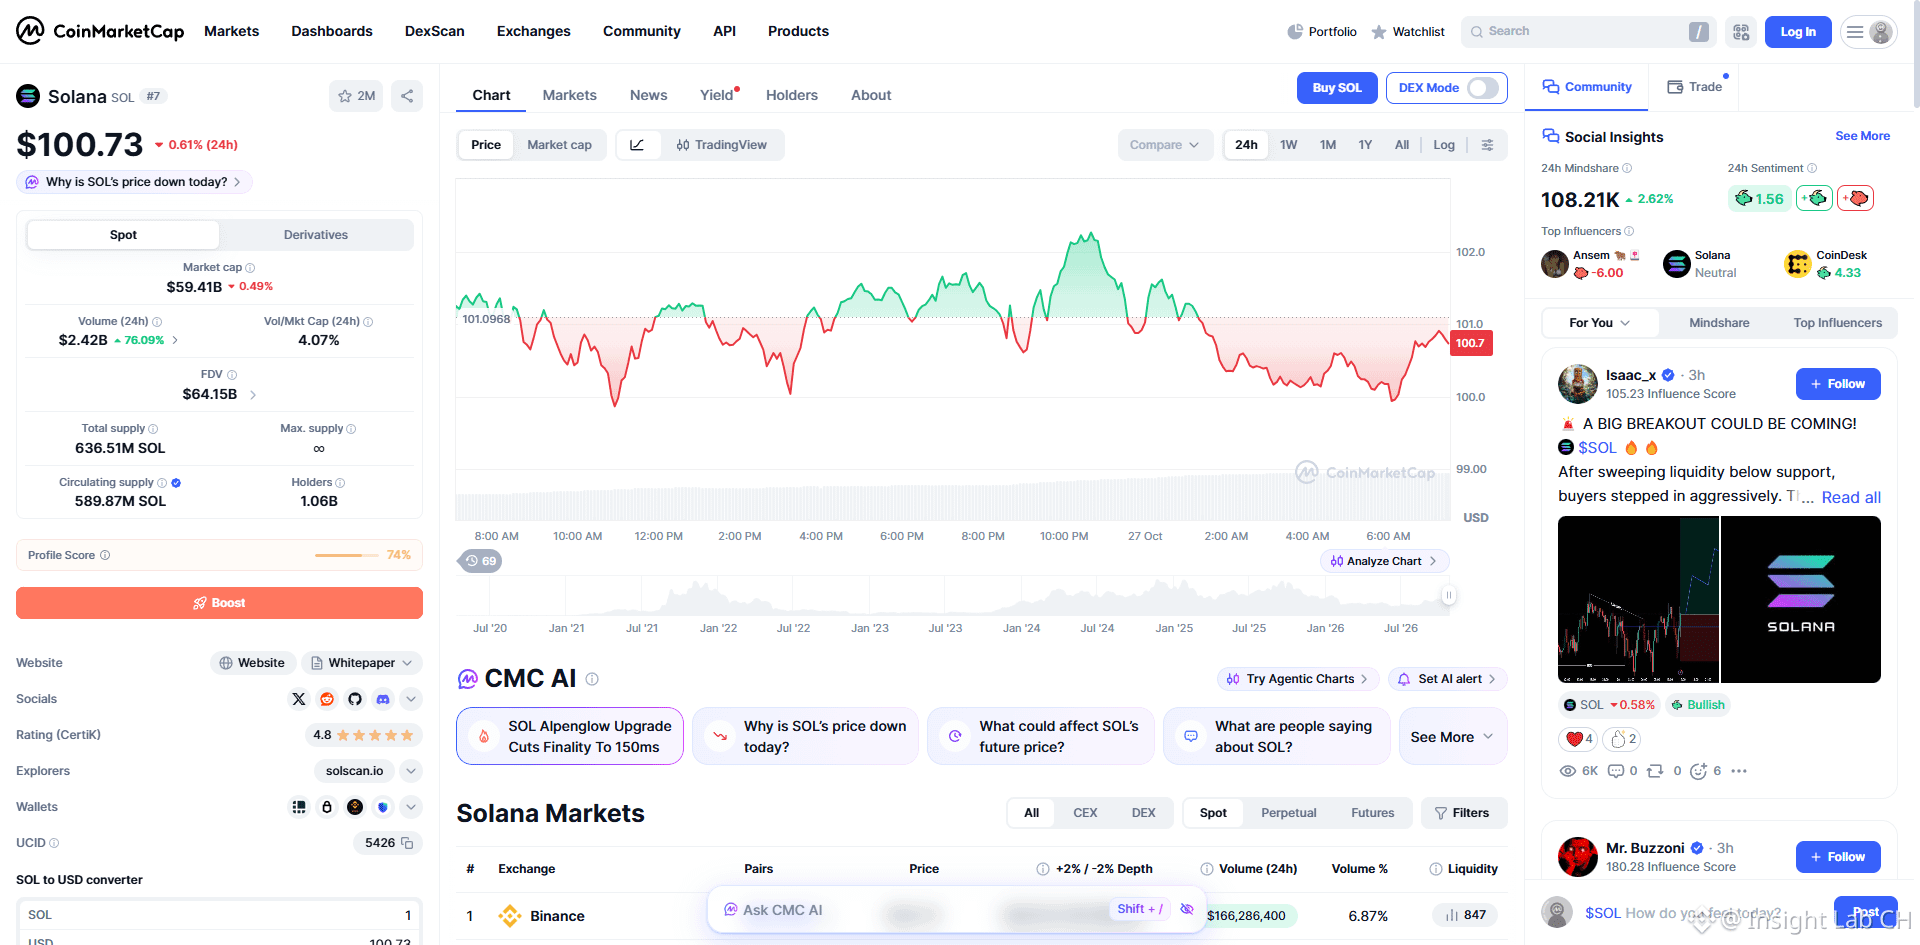
$SOL is currently ranked 4th on CoinMarketCap's trending list. Against the backdrop of high interest rates and tightening macro liquidity, rising interest in high-beta risk assets often signals a risk of overheated sentiment. Short-term capital speculation is intensifying, so be highly alert to potential liquidity-squeeze-driven pullbacks. ⚠️ #Solana #Layer1
$SOL is currently ranked 4th on CoinMarketCap's trending list. Against the backdrop of high interest rates and tightening macro liquidity, rising interest in high-beta risk assets often signals a risk of overheated sentiment. Short-term capital speculation is intensifying, so be highly alert to potential liquidity-squeeze-driven pullbacks. ⚠️ #Solana #Layer1
106
The Bank of Korea released preliminary economic growth data for the third quarter on Tuesday, showing that gross domestic product (GDP) grew 1.0% quarter on quarter, significantly exceeding the market’s prior expectation of 0.7%. Growth was driven primarily by the global artificial intelligence (AI) boom, which boosted exports of semiconductors and related electrical equipment by 2.3%, while investment in chipmaking equipment surged 4.1%. However, behind the strong headline figures was a highly uneven recovery: private consumption actually contracted by 0.2% quarter on quarter.
From a macroeconomic perspective, this is not a broad-based, healthy, internally driven boom, but a structural rebound heavily reliant on a single external technology cycle. Although a 1.9% increase in public spending provided some support for growth, households’ reduced spending on goods and services reflects weak domestic demand amid high interest rates. More concerningly, soaring home prices in the Seoul area and high household debt pose a dual risk to financial stability, severely limiting the central bank’s room for further monetary easing.
In traditional financial markets, this disconnect between strong exports and weak domestic demand could force the Bank of Korea to maintain a relatively tight monetary stance to curb asset bubbles, thereby pushing up domestic bond yields and weighing on risk premiums. If global capital expenditure on AI infrastructure cools temporarily in the future, economies highly dependent on semiconductor exports will face significant pressure to reprice their valuations.
For cryptocurrency markets, growth driven by a strong external cycle does not translate effectively into ample retail liquidity. South Korea’s robust domestic speculative capital is unlikely to keep expanding amid contracting domestic demand and mounting debt pressures. Investors should be alert to the knock-on effects of fragile macroeconomic fundamentals. In particular, when global risk appetite tightens, risk assets such as $BTC may struggle to gain lasting support from localized industry tailwinds.
#SouthKorea #MacroEconomics #GlobalEconomy
The Bank of Korea released preliminary economic growth data for the third quarter on Tuesday, showing that gross domestic product (GDP) grew 1.0% quarter on quarter, significantly exceeding the market’s prior expectation of 0.7%. Growth was driven primarily by the global artificial intelligence (AI) boom, which boosted exports of semiconductors and related electrical equipment by 2.3%, while investment in chipmaking equipment surged 4.1%. However, behind the strong headline figures was a highly uneven recovery: private consumption actually contracted by 0.2% quarter on quarter.
From a macroeconomic perspective, this is not a broad-based, healthy, internally driven boom, but a structural rebound heavily reliant on a single external technology cycle. Although a 1.9% increase in public spending provided some support for growth, households’ reduced spending on goods and services reflects weak domestic demand amid high interest rates. More concerningly, soaring home prices in the Seoul area and high household debt pose a dual risk to financial stability, severely limiting the central bank’s room for further monetary easing.
In traditional financial markets, this disconnect between strong exports and weak domestic demand could force the Bank of Korea to maintain a relatively tight monetary stance to curb asset bubbles, thereby pushing up domestic bond yields and weighing on risk premiums. If global capital expenditure on AI infrastructure cools temporarily in the future, economies highly dependent on semiconductor exports will face significant pressure to reprice their valuations.
For cryptocurrency markets, growth driven by a strong external cycle does not translate effectively into ample retail liquidity. South Korea’s robust domestic speculative capital is unlikely to keep expanding amid contracting domestic demand and mounting debt pressures. Investors should be alert to the knock-on effects of fragile macroeconomic fundamentals. In particular, when global risk appetite tightens, risk assets such as $BTC may struggle to gain lasting support from localized industry tailwinds.
#SouthKorea #MacroEconomics #GlobalEconomy
From a macroeconomic perspective, this is not a broad-based, healthy, internally driven boom, but a structural rebound heavily reliant on a single external technology cycle. Although a 1.9% increase in public spending provided some support for growth, households’ reduced spending on goods and services reflects weak domestic demand amid high interest rates. More concerningly, soaring home prices in the Seoul area and high household debt pose a dual risk to financial stability, severely limiting the central bank’s room for further monetary easing.
In traditional financial markets, this disconnect between strong exports and weak domestic demand could force the Bank of Korea to maintain a relatively tight monetary stance to curb asset bubbles, thereby pushing up domestic bond yields and weighing on risk premiums. If global capital expenditure on AI infrastructure cools temporarily in the future, economies highly dependent on semiconductor exports will face significant pressure to reprice their valuations.
For cryptocurrency markets, growth driven by a strong external cycle does not translate effectively into ample retail liquidity. South Korea’s robust domestic speculative capital is unlikely to keep expanding amid contracting domestic demand and mounting debt pressures. Investors should be alert to the knock-on effects of fragile macroeconomic fundamentals. In particular, when global risk appetite tightens, risk assets such as $BTC may struggle to gain lasting support from localized industry tailwinds.
#SouthKorea #MacroEconomics #GlobalEconomy
According to the latest data from the CME FedWatch Tool, markets currently see an 89.5% chance that the Federal Reserve will hold rates steady at this week’s meeting, and just a 10.5% chance of a 25-basis-point rate hike. However, expectations for the policy path in December have shifted significantly: the probability of a cumulative 25-basis-point hike has risen to 73.9%, the probability of a 50-basis-point hike stands at 8.4%, and the chance of rates remaining unchanged has fallen to just 17.7%.
These figures reflect growing disagreement over a near-term policy pause followed by a resumption of tightening toward year-end. Although rates are all but certain to remain unchanged in the short term, rising expectations of a year-end hike suggest that persistent inflation and economic resilience are keeping policymakers on alert. This divergence in expectations has tempered the excessive optimism about an imminent shift toward easing, adding further uncertainty to future asset pricing.
In macro-financial markets, renewed expectations of year-end rate hikes will provide strong support for U.S. Treasury yields and the dollar index. As markets gradually price in a higher-for-longer terminal rate, the scope for valuation expansion in global risk assets will come under direct pressure. The prospect of tighter liquidity conditions also leaves traditional capital markets facing greater volatility and correction risks before year-end.
For crypto assets, a resurgence in expectations of tighter policy often means rising risk premiums and slower inflows of new capital. If expectations of year-end rate hikes become further entrenched, major assets such as $BTC may struggle to attract sufficient liquidity in the near term, and market sentiment could shift from blind optimism to a defensive wait-and-see stance. Investors should be alert to the risk of liquidity squeezes caused by swings in macro policy expectations.🏛️
#Fed #InterestRates #MacroEconomics
According to the latest data from the CME FedWatch Tool, markets currently see an 89.5% chance that the Federal Reserve will hold rates steady at this week’s meeting, and just a 10.5% chance of a 25-basis-point rate hike. However, expectations for the policy path in December have shifted significantly: the probability of a cumulative 25-basis-point hike has risen to 73.9%, the probability of a 50-basis-point hike stands at 8.4%, and the chance of rates remaining unchanged has fallen to just 17.7%.
These figures reflect growing disagreement over a near-term policy pause followed by a resumption of tightening toward year-end. Although rates are all but certain to remain unchanged in the short term, rising expectations of a year-end hike suggest that persistent inflation and economic resilience are keeping policymakers on alert. This divergence in expectations has tempered the excessive optimism about an imminent shift toward easing, adding further uncertainty to future asset pricing.
In macro-financial markets, renewed expectations of year-end rate hikes will provide strong support for U.S. Treasury yields and the dollar index. As markets gradually price in a higher-for-longer terminal rate, the scope for valuation expansion in global risk assets will come under direct pressure. The prospect of tighter liquidity conditions also leaves traditional capital markets facing greater volatility and correction risks before year-end.
For crypto assets, a resurgence in expectations of tighter policy often means rising risk premiums and slower inflows of new capital. If expectations of year-end rate hikes become further entrenched, major assets such as $BTC may struggle to attract sufficient liquidity in the near term, and market sentiment could shift from blind optimism to a defensive wait-and-see stance. Investors should be alert to the risk of liquidity squeezes caused by swings in macro policy expectations.🏛️
#Fed #InterestRates #MacroEconomics
These figures reflect growing disagreement over a near-term policy pause followed by a resumption of tightening toward year-end. Although rates are all but certain to remain unchanged in the short term, rising expectations of a year-end hike suggest that persistent inflation and economic resilience are keeping policymakers on alert. This divergence in expectations has tempered the excessive optimism about an imminent shift toward easing, adding further uncertainty to future asset pricing.
In macro-financial markets, renewed expectations of year-end rate hikes will provide strong support for U.S. Treasury yields and the dollar index. As markets gradually price in a higher-for-longer terminal rate, the scope for valuation expansion in global risk assets will come under direct pressure. The prospect of tighter liquidity conditions also leaves traditional capital markets facing greater volatility and correction risks before year-end.
For crypto assets, a resurgence in expectations of tighter policy often means rising risk premiums and slower inflows of new capital. If expectations of year-end rate hikes become further entrenched, major assets such as $BTC may struggle to attract sufficient liquidity in the near term, and market sentiment could shift from blind optimism to a defensive wait-and-see stance. Investors should be alert to the risk of liquidity squeezes caused by swings in macro policy expectations.🏛️
#Fed #InterestRates #MacroEconomics
Iran’s semi-official Fars News Agency recently reported that an Iranian security official had publicly stated that Iran was fully prepared and on high alert for possible Israeli actions. The official stressed that even the slightest attack would prompt Iran to retaliate in kind with unprecedented speed and scale, and issued a direct warning to the Israeli public.
The renewed escalation of geopolitical tensions in the Middle East has completely dashed market optimism that the situation might ease. The two sides’ hardline statements are more than a mere war of words: they signal a tangible risk of disruption to Middle Eastern energy transport routes and supply chains, casting a shadow over the global inflation outlook.
Risk aversion has risen sharply as a result. In the short term, traditional safe-haven assets such as the U.S. Dollar Index and gold are receiving strong support, while oil prices face upward pressure from a risk premium. Against a backdrop of already-tight macro liquidity, rising commodity costs could force major central banks to maintain high interest rates for longer, further weighing on global risk appetite.
For crypto assets, the downside pressure from the current situation should not be underestimated. In a market dominated by risk aversion, $BTC and major altcoins are often seen as high-volatility risk assets and face selling pressure. In the near term, capital is more likely to flow back into cash as a safe haven, and investors should be highly alert to the risk of a deep correction triggered by tightening liquidity.📉
#Geopolitics #OilMarket #RiskOff
Iran’s semi-official Fars News Agency recently reported that an Iranian security official had publicly stated that Iran was fully prepared and on high alert for possible Israeli actions. The official stressed that even the slightest attack would prompt Iran to retaliate in kind with unprecedented speed and scale, and issued a direct warning to the Israeli public.
The renewed escalation of geopolitical tensions in the Middle East has completely dashed market optimism that the situation might ease. The two sides’ hardline statements are more than a mere war of words: they signal a tangible risk of disruption to Middle Eastern energy transport routes and supply chains, casting a shadow over the global inflation outlook.
Risk aversion has risen sharply as a result. In the short term, traditional safe-haven assets such as the U.S. Dollar Index and gold are receiving strong support, while oil prices face upward pressure from a risk premium. Against a backdrop of already-tight macro liquidity, rising commodity costs could force major central banks to maintain high interest rates for longer, further weighing on global risk appetite.
For crypto assets, the downside pressure from the current situation should not be underestimated. In a market dominated by risk aversion, $BTC and major altcoins are often seen as high-volatility risk assets and face selling pressure. In the near term, capital is more likely to flow back into cash as a safe haven, and investors should be highly alert to the risk of a deep correction triggered by tightening liquidity.📉
#Geopolitics #OilMarket #RiskOff
The renewed escalation of geopolitical tensions in the Middle East has completely dashed market optimism that the situation might ease. The two sides’ hardline statements are more than a mere war of words: they signal a tangible risk of disruption to Middle Eastern energy transport routes and supply chains, casting a shadow over the global inflation outlook.
Risk aversion has risen sharply as a result. In the short term, traditional safe-haven assets such as the U.S. Dollar Index and gold are receiving strong support, while oil prices face upward pressure from a risk premium. Against a backdrop of already-tight macro liquidity, rising commodity costs could force major central banks to maintain high interest rates for longer, further weighing on global risk appetite.
For crypto assets, the downside pressure from the current situation should not be underestimated. In a market dominated by risk aversion, $BTC and major altcoins are often seen as high-volatility risk assets and face selling pressure. In the near term, capital is more likely to flow back into cash as a safe haven, and investors should be highly alert to the risk of a deep correction triggered by tightening liquidity.📉
#Geopolitics #OilMarket #RiskOff
420
Latin American financial markets were rocked by sharp volatility on Monday. After the results of Brazil’s election were announced, left-wing candidate Lula defeated right-wing senator Bolsonaro to win the presidency. Bovespa stock index futures plunged nearly 15% at one point in early trading, the Brazilian real fell 12.2% against the U.S. dollar in spot trading, and interest rate futures surged in tandem, with rates on contracts expiring in January 2031 jumping 182 basis points.
The election results exceeded some pollsters’ expectations, stoking market concerns about future fiscal expansion and a policy shift in Brazil. The surge in sovereign risk premiums directly reflected investors’ defensive stance toward an expansion of sovereign debt, as emerging-market sovereign assets faced a fresh crisis of confidence.
The sharp volatility quickly drove up risk discounts on regional currencies and bonds, prompting cross-border capital to flow back into dollar-denominated safe-haven assets at an accelerated pace. The steep drop in commodity-exporting countries’ currencies also cast a shadow over global liquidity expectations, worsening volatility across markets.
For crypto markets, although steep depreciation in sovereign fiat currencies may spur passive demand for inflation protection and asset preservation in some regions, in a global macro environment dominated by risk aversion, risk assets such as $BTC are more vulnerable to liquidity outflows. Investors should be alert to the risk of systemic sell-offs.📉
#Brazil #EmergingMarkets #MacroEconomics
Latin American financial markets were rocked by sharp volatility on Monday. After the results of Brazil’s election were announced, left-wing candidate Lula defeated right-wing senator Bolsonaro to win the presidency. Bovespa stock index futures plunged nearly 15% at one point in early trading, the Brazilian real fell 12.2% against the U.S. dollar in spot trading, and interest rate futures surged in tandem, with rates on contracts expiring in January 2031 jumping 182 basis points.
The election results exceeded some pollsters’ expectations, stoking market concerns about future fiscal expansion and a policy shift in Brazil. The surge in sovereign risk premiums directly reflected investors’ defensive stance toward an expansion of sovereign debt, as emerging-market sovereign assets faced a fresh crisis of confidence.
The sharp volatility quickly drove up risk discounts on regional currencies and bonds, prompting cross-border capital to flow back into dollar-denominated safe-haven assets at an accelerated pace. The steep drop in commodity-exporting countries’ currencies also cast a shadow over global liquidity expectations, worsening volatility across markets.
For crypto markets, although steep depreciation in sovereign fiat currencies may spur passive demand for inflation protection and asset preservation in some regions, in a global macro environment dominated by risk aversion, risk assets such as $BTC are more vulnerable to liquidity outflows. Investors should be alert to the risk of systemic sell-offs.📉
#Brazil #EmergingMarkets #MacroEconomics
The election results exceeded some pollsters’ expectations, stoking market concerns about future fiscal expansion and a policy shift in Brazil. The surge in sovereign risk premiums directly reflected investors’ defensive stance toward an expansion of sovereign debt, as emerging-market sovereign assets faced a fresh crisis of confidence.
The sharp volatility quickly drove up risk discounts on regional currencies and bonds, prompting cross-border capital to flow back into dollar-denominated safe-haven assets at an accelerated pace. The steep drop in commodity-exporting countries’ currencies also cast a shadow over global liquidity expectations, worsening volatility across markets.
For crypto markets, although steep depreciation in sovereign fiat currencies may spur passive demand for inflation protection and asset preservation in some regions, in a global macro environment dominated by risk aversion, risk assets such as $BTC are more vulnerable to liquidity outflows. Investors should be alert to the risk of systemic sell-offs.📉
#Brazil #EmergingMarkets #MacroEconomics
55
Binance Futures is about to launch the $STMUSDT perpetual contract. Against the backdrop of currently tight macro liquidity, investors should be highly alert to the potential volatility and downside risks that the launch of new derivatives may trigger. #BinanceFutures #STM
Binance Futures is about to launch the $STMUSDT perpetual contract. Against the backdrop of currently tight macro liquidity, investors should be highly alert to the potential volatility and downside risks that the launch of new derivatives may trigger. #BinanceFutures #STM
87
Observed $SOL is currently ranked #18 on the CoinMarketCap trending list. In the current environment of a tightening cycle and macro liquidity pressure, the short-term hype of high-beta assets can easily mask deeper downside risks. Chasing gains blindly requires caution against valuation corrections brought by a retreating tide of liquidity. #Solana #Layer1
Observed $SOL is currently ranked #18 on the CoinMarketCap trending list. In the current environment of a tightening cycle and macro liquidity pressure, the short-term hype of high-beta assets can easily mask deeper downside risks. Chasing gains blindly requires caution against valuation corrections brought by a retreating tide of liquidity. #Solana #Layer1
26
Binance Futures is about to list the $EQTUSDT perpetual contract. Amid the current macro environment of tight liquidity, the expansion of derivatives markets is often accompanied by sharp volatility. Be wary of downside and liquidity risks. ⚠️ #BinanceFutures #EQT
Binance Futures is about to list the $EQTUSDT perpetual contract. Amid the current macro environment of tight liquidity, the expansion of derivatives markets is often accompanied by sharp volatility. Be wary of downside and liquidity risks. ⚠️ #BinanceFutures #EQT
100
Binance Futures is about to list the $EIDOUSDT perpetual contract. Amid the current liquidity crunch, new derivative listings are often accompanied by sharp volatility, so beware of downside risks. #Binance #FuturesListing
Binance Futures is about to list the $EIDOUSDT perpetual contract. Amid the current liquidity crunch, new derivative listings are often accompanied by sharp volatility, so beware of downside risks. #Binance #FuturesListing
88
According to two U.S. officials, U.S. forces deployed in the Middle East have completed preparations for a large-scale military operation and could launch a new round of high-intensity strikes against Iran within 96 hours of receiving an order from U.S. President Donald Trump. Unlike previous conventional defensive operations, which were limited to suppressing radar systems and missile launch sites, the scope of the current operational plan would be significantly broader, aiming to strike key strategic targets in depth.
This potential military escalation has completely upended market expectations that the fragile balance in the Middle East would hold. If the U.S. military formally launches a full-scale attack, energy supply chains and vital shipping lanes in the Persian Gulf would face a direct risk of disruption, sharply increasing the likelihood that geopolitical tensions could escalate from localized friction into systemic confrontation.
Macroeconomic markets have rapidly priced in the risk. Oil prices face significant upward pressure, as tighter energy supplies would directly raise inflation expectations and limit central banks’ room to cut interest rates. Surging demand for safe-haven assets is strengthening the U.S. dollar and gold, while valuations of global risk assets are likely to come under severe pressure.
For crypto assets, tightening liquidity and spreading risk aversion are significant headwinds. As macro-geopolitical crises intensify, risk assets such as $BTC are often among the first to face deleveraging-driven sell-offs. Investors should be highly alert to the risk of short-term liquidity cascades and market declines.⚠️
#Geopolitics #MiddleEastCrisis #MacroRisk
According to two U.S. officials, U.S. forces deployed in the Middle East have completed preparations for a large-scale military operation and could launch a new round of high-intensity strikes against Iran within 96 hours of receiving an order from U.S. President Donald Trump. Unlike previous conventional defensive operations, which were limited to suppressing radar systems and missile launch sites, the scope of the current operational plan would be significantly broader, aiming to strike key strategic targets in depth.
This potential military escalation has completely upended market expectations that the fragile balance in the Middle East would hold. If the U.S. military formally launches a full-scale attack, energy supply chains and vital shipping lanes in the Persian Gulf would face a direct risk of disruption, sharply increasing the likelihood that geopolitical tensions could escalate from localized friction into systemic confrontation.
Macroeconomic markets have rapidly priced in the risk. Oil prices face significant upward pressure, as tighter energy supplies would directly raise inflation expectations and limit central banks’ room to cut interest rates. Surging demand for safe-haven assets is strengthening the U.S. dollar and gold, while valuations of global risk assets are likely to come under severe pressure.
For crypto assets, tightening liquidity and spreading risk aversion are significant headwinds. As macro-geopolitical crises intensify, risk assets such as $BTC are often among the first to face deleveraging-driven sell-offs. Investors should be highly alert to the risk of short-term liquidity cascades and market declines.⚠️
#Geopolitics #MiddleEastCrisis #MacroRisk
This potential military escalation has completely upended market expectations that the fragile balance in the Middle East would hold. If the U.S. military formally launches a full-scale attack, energy supply chains and vital shipping lanes in the Persian Gulf would face a direct risk of disruption, sharply increasing the likelihood that geopolitical tensions could escalate from localized friction into systemic confrontation.
Macroeconomic markets have rapidly priced in the risk. Oil prices face significant upward pressure, as tighter energy supplies would directly raise inflation expectations and limit central banks’ room to cut interest rates. Surging demand for safe-haven assets is strengthening the U.S. dollar and gold, while valuations of global risk assets are likely to come under severe pressure.
For crypto assets, tightening liquidity and spreading risk aversion are significant headwinds. As macro-geopolitical crises intensify, risk assets such as $BTC are often among the first to face deleveraging-driven sell-offs. Investors should be highly alert to the risk of short-term liquidity cascades and market declines.⚠️
#Geopolitics #MiddleEastCrisis #MacroRisk
43
French President Emmanuel Macron has recently moved forward with the “forward nuclear early-warning” plan, joining 10 European allies, including the United Kingdom, Germany, and Poland, to expand the forward deterrence and early-warning deployment of French nuclear forces. The plan proposes deploying nuclear-capable Rafale fighter jets in several parts of Europe and establishing a new intelligence-sharing and early-warning communications network. However, Italy has explicitly refused to join, and the three Baltic states have also been left out, highlighting the serious divisions that persist within Europe over defense.
This strategic move shows that Europe is seeking to break free from its traditional security umbrella’s sole reliance on the United States, as the geopolitical landscape enters a high-risk phase of independent deterrence. Yet the disconnect among countries’ positions on nuclear strategy makes it difficult to establish a truly unified line of defense and could instead heighten the risk of direct confrontation with Russia, increasing the likelihood of miscalculation and friction across the continent.
The escalation of geopolitical nuclear deterrence directly weighs on risk appetite in traditional financial markets. A sustained rise in Europe’s geopolitical risk premium will dampen expectations for an economic recovery in Europe and drive more safe-haven capital toward hard-currency assets such as the U.S. dollar and gold. The volatility baseline in global capital markets may rise significantly.
For crypto assets, prolonged and increasingly complex geopolitical tensions tend to squeeze speculative liquidity in the market. In an environment dominated by safe-haven sentiment, risk assets such as $BTC are more vulnerable to pressure from liquidity flowing back into traditional safe havens. Investors should be alert to the risk of episodic liquidity cascades triggered by geopolitical black swan events.
#Geopolitics #NuclearDeterrence #MacroEconomy
French President Emmanuel Macron has recently moved forward with the “forward nuclear early-warning” plan, joining 10 European allies, including the United Kingdom, Germany, and Poland, to expand the forward deterrence and early-warning deployment of French nuclear forces. The plan proposes deploying nuclear-capable Rafale fighter jets in several parts of Europe and establishing a new intelligence-sharing and early-warning communications network. However, Italy has explicitly refused to join, and the three Baltic states have also been left out, highlighting the serious divisions that persist within Europe over defense.
This strategic move shows that Europe is seeking to break free from its traditional security umbrella’s sole reliance on the United States, as the geopolitical landscape enters a high-risk phase of independent deterrence. Yet the disconnect among countries’ positions on nuclear strategy makes it difficult to establish a truly unified line of defense and could instead heighten the risk of direct confrontation with Russia, increasing the likelihood of miscalculation and friction across the continent.
The escalation of geopolitical nuclear deterrence directly weighs on risk appetite in traditional financial markets. A sustained rise in Europe’s geopolitical risk premium will dampen expectations for an economic recovery in Europe and drive more safe-haven capital toward hard-currency assets such as the U.S. dollar and gold. The volatility baseline in global capital markets may rise significantly.
For crypto assets, prolonged and increasingly complex geopolitical tensions tend to squeeze speculative liquidity in the market. In an environment dominated by safe-haven sentiment, risk assets such as $BTC are more vulnerable to pressure from liquidity flowing back into traditional safe havens. Investors should be alert to the risk of episodic liquidity cascades triggered by geopolitical black swan events.
#Geopolitics #NuclearDeterrence #MacroEconomy
This strategic move shows that Europe is seeking to break free from its traditional security umbrella’s sole reliance on the United States, as the geopolitical landscape enters a high-risk phase of independent deterrence. Yet the disconnect among countries’ positions on nuclear strategy makes it difficult to establish a truly unified line of defense and could instead heighten the risk of direct confrontation with Russia, increasing the likelihood of miscalculation and friction across the continent.
The escalation of geopolitical nuclear deterrence directly weighs on risk appetite in traditional financial markets. A sustained rise in Europe’s geopolitical risk premium will dampen expectations for an economic recovery in Europe and drive more safe-haven capital toward hard-currency assets such as the U.S. dollar and gold. The volatility baseline in global capital markets may rise significantly.
For crypto assets, prolonged and increasingly complex geopolitical tensions tend to squeeze speculative liquidity in the market. In an environment dominated by safe-haven sentiment, risk assets such as $BTC are more vulnerable to pressure from liquidity flowing back into traditional safe havens. Investors should be alert to the risk of episodic liquidity cascades triggered by geopolitical black swan events.
#Geopolitics #NuclearDeterrence #MacroEconomy
258
📅 Key Macroeconomic Events and Outlook for This Week
🇺🇸 27/10 22:00 (UTC+8) - CB Consumer Confidence (Forecast: 80.5, Previous: 81.9)
🇺🇸 29/10 02:00 (UTC+8) - Federal Funds Rate (Forecast: 4.00%, Previous: 4.00%)
🇺🇸 29/10 02:00 (UTC+8) - FOMC Statement
🇺🇸 29/10 02:30 (UTC+8) - FOMC Press Conference
🇺🇸 29/10 20:30 (UTC+8) - Advance GDP q/q (Forecast: 3.2%, Previous: 1.5%)
🇺🇸 29/10 20:30 (UTC+8) - Core PCE Price Index m/m (Forecast: 0.3%, Previous: 0.2%)
Based on macroeconomic data expectations, the monthly core PCE rate is expected to rebound, while the GDP growth forecast has accelerated significantly. This indicates that underlying inflation stickiness and the risk of an overheating economy have not been eliminated. Under the current monetary policy framework, should inflationary pressures re-emerge, the Federal Reserve may maintain a more hawkish stance. Risk assets could face dual pressures from liquidity and valuations in the short term, so market volatility risks warrant close attention.
#FOMC #Fed
📅 Key Macroeconomic Events and Outlook for This Week
🇺🇸 27/10 22:00 (UTC+8) - CB Consumer Confidence (Forecast: 80.5, Previous: 81.9)
🇺🇸 29/10 02:00 (UTC+8) - Federal Funds Rate (Forecast: 4.00%, Previous: 4.00%)
🇺🇸 29/10 02:00 (UTC+8) - FOMC Statement
🇺🇸 29/10 02:30 (UTC+8) - FOMC Press Conference
🇺🇸 29/10 20:30 (UTC+8) - Advance GDP q/q (Forecast: 3.2%, Previous: 1.5%)
🇺🇸 29/10 20:30 (UTC+8) - Core PCE Price Index m/m (Forecast: 0.3%, Previous: 0.2%)
Based on macroeconomic data expectations, the monthly core PCE rate is expected to rebound, while the GDP growth forecast has accelerated significantly. This indicates that underlying inflation stickiness and the risk of an overheating economy have not been eliminated. Under the current monetary policy framework, should inflationary pressures re-emerge, the Federal Reserve may maintain a more hawkish stance. Risk assets could face dual pressures from liquidity and valuations in the short term, so market volatility risks warrant close attention.
#FOMC #Fed
🇺🇸 27/10 22:00 (UTC+8) - CB Consumer Confidence (Forecast: 80.5, Previous: 81.9)
🇺🇸 29/10 02:00 (UTC+8) - Federal Funds Rate (Forecast: 4.00%, Previous: 4.00%)
🇺🇸 29/10 02:00 (UTC+8) - FOMC Statement
🇺🇸 29/10 02:30 (UTC+8) - FOMC Press Conference
🇺🇸 29/10 20:30 (UTC+8) - Advance GDP q/q (Forecast: 3.2%, Previous: 1.5%)
🇺🇸 29/10 20:30 (UTC+8) - Core PCE Price Index m/m (Forecast: 0.3%, Previous: 0.2%)
Based on macroeconomic data expectations, the monthly core PCE rate is expected to rebound, while the GDP growth forecast has accelerated significantly. This indicates that underlying inflation stickiness and the risk of an overheating economy have not been eliminated. Under the current monetary policy framework, should inflationary pressures re-emerge, the Federal Reserve may maintain a more hawkish stance. Risk assets could face dual pressures from liquidity and valuations in the short term, so market volatility risks warrant close attention.
#FOMC #Fed
65
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number