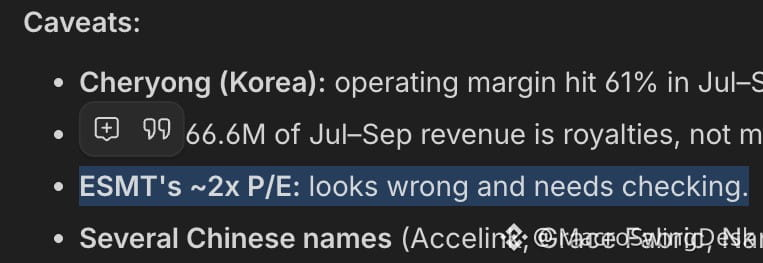
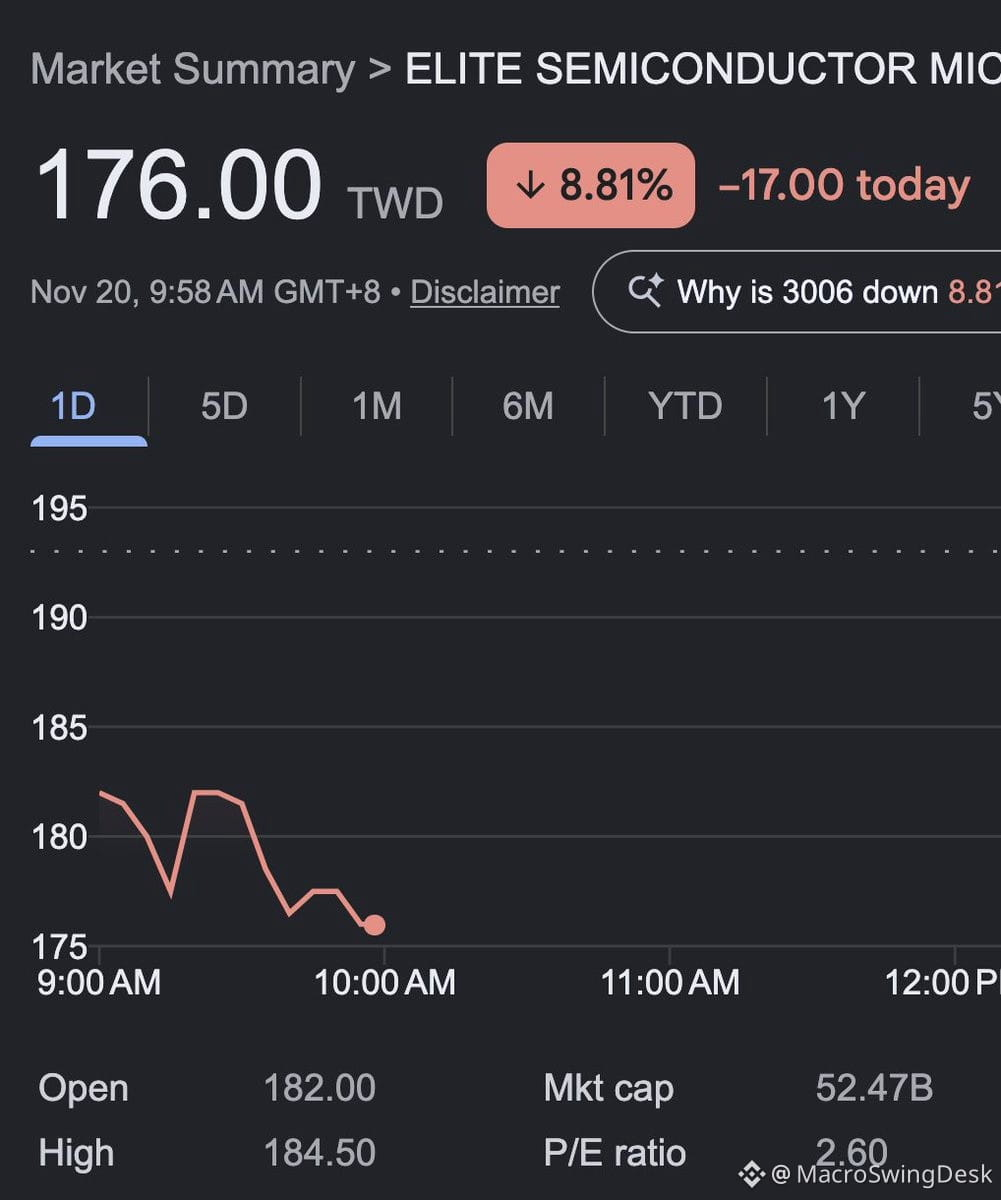
Market is pricing $ESMT like it's about to implode, but the numbers tell a completely different story.
Let's break it down:
• $1.58B market cap
• $747M net cash + $274.7M inventory = $1.02B in liquid value
• Adjusted EV sits at just $559M
• Q3 free cash flow: $349.5M
• Q3 net income: $327M
So the operating business is being valued at ~$559M while printing $300M+ per quarter in net income. That's a 1.2x annualized P/E if you believe Q3 wasn't a fluke.
And here's the kicker:
• DDR2/DDR3 supply stays tight through 2027
• ASPs rising into Q4 despite consumer demand softening
• Management talking 30–50% dividend payout ratios by 2027
• October likely added another ~$96M to the balance sheet
This isn't some speculative growth story or AI hype play. This is a legacy memory chip company generating absurd cash flow, sitting on a fortress balance sheet, and trading like it's going out of business.
Either the market knows something catastrophic is coming, or this is one of the most mispriced stocks in the small-cap space right now. Even AI models I ran the numbers through flagged this as statistically bizarre.
If earnings hold and cash keeps piling up, this thing either gets acquired, starts buying back stock aggressively, or the market wakes up. Risk/reward here looks asymmetric.
Let's break it down:
• $1.58B market cap
• $747M net cash + $274.7M inventory = $1.02B in liquid value
• Adjusted EV sits at just $559M
• Q3 free cash flow: $349.5M
• Q3 net income: $327M
So the operating business is being valued at ~$559M while printing $300M+ per quarter in net income. That's a 1.2x annualized P/E if you believe Q3 wasn't a fluke.
And here's the kicker:
• DDR2/DDR3 supply stays tight through 2027
• ASPs rising into Q4 despite consumer demand softening
• Management talking 30–50% dividend payout ratios by 2027
• October likely added another ~$96M to the balance sheet
This isn't some speculative growth story or AI hype play. This is a legacy memory chip company generating absurd cash flow, sitting on a fortress balance sheet, and trading like it's going out of business.
Either the market knows something catastrophic is coming, or this is one of the most mispriced stocks in the small-cap space right now. Even AI models I ran the numbers through flagged this as statistically bizarre.
If earnings hold and cash keeps piling up, this thing either gets acquired, starts buying back stock aggressively, or the market wakes up. Risk/reward here looks asymmetric.