Global chemicals diverge as oil keeps costs elevated while production margins remain under pressure
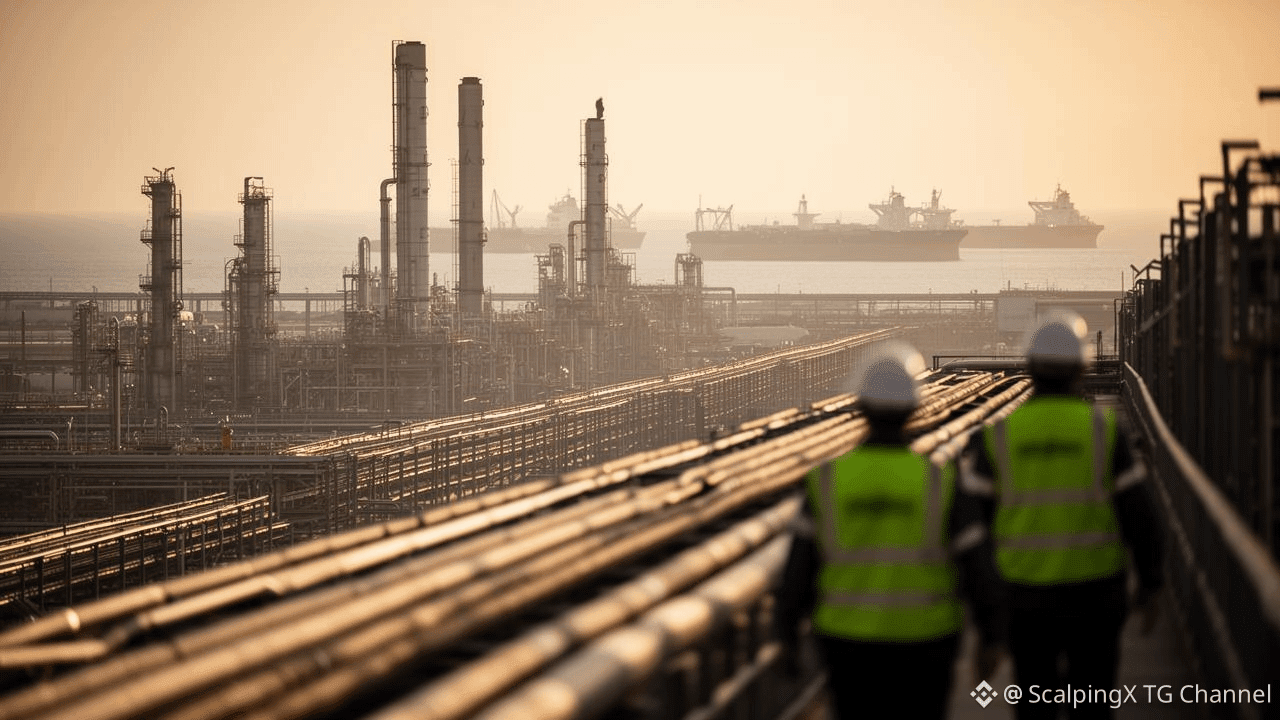
🛢 Brent around $102/bbl continues to keep feedstock costs elevated, particularly for naphtha and oil-dependent crackers. However, finished-product prices have not risen fast enough to fully offset higher input costs, leaving margins across several chains under pressure.
🇪🇺 Europe is entering October with a clearer upward pricing trend. Olefin contracts are expected to rise by around EUR 60–80/ton, while styrene could increase by roughly EUR 100–150/ton. Polyolefins, polystyrene and PET had already moved higher beforehand. Even so, ethylene, PE and PP spreads remain below year-ago levels, suggesting much of the increase still reflects feedstock cost pass-through rather than stronger pricing power.
🇨🇳 China has effectively frozen price indications during Golden Week, but unchanged quotations do not mean supply and demand are balanced. PP and PE inventories at Sinopec and CNPC remain above seasonal averages, while suppliers avoided aggressive price cuts ahead of the holiday.
📉 Pressure may become more visible after China reopens on October 8. If inventories fail to decline sufficiently in the first week and new PE–PP capacity starts as scheduled in the second half of the month, polyolefin prices could face stronger downside pressure by the third week after the holiday.
🌍 The US is following a different path from Europe, with most major-volume resins expected to trade flat to lower in October. The broader picture is therefore not a synchronized global chemical upcycle, but a widening divergence between feedstock costs, demand conditions and the ability of producers to defend margins across regions.
#ChemicalMarkets $CL