
#anthropic
anthropic
432,338 views
2,406 Discussing
Hot
Latest
·
--
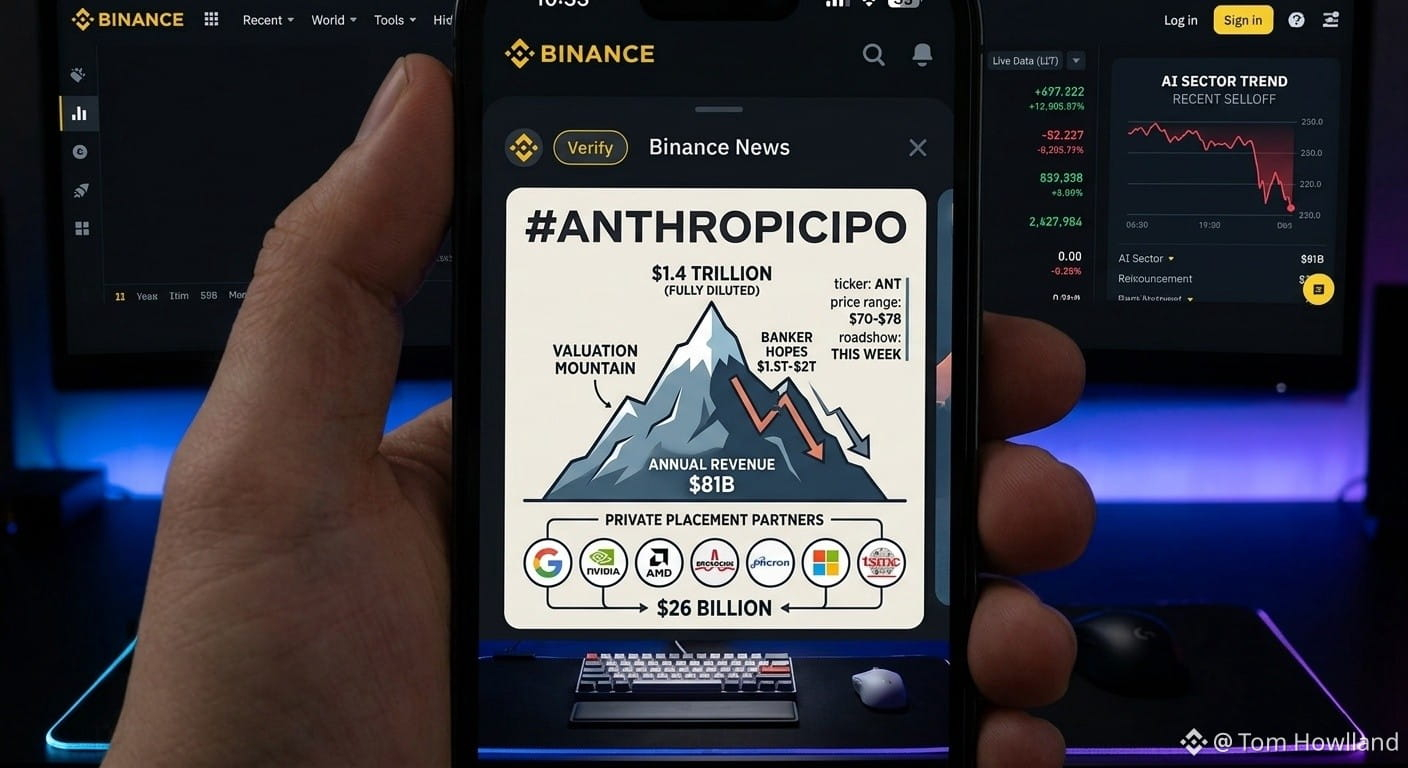
🚀 ANTHROPIC EYES A $1.4 TRILLION IPO VALUATION — THE AI REVOLUTION IS GETTING BIGGER!
The AI industry is entering another historic chapter! 🔥 Anthropic, the company behind Claude AI, is preparing for a massive public offering that could make it one of the most valuable technology companies in the world.
Here's what makes this IPO extraordinary:
💰 $1.4 TRILLION VALUATION: Anthropic's proposed fully diluted valuation could reach approximately $1.404 trillion, according to its latest IPO pricing range.
📊 $81 BILLION REVENUE RUN RATE: The company reported an annualized revenue run rate of approximately $81 billion as of October 31, 2026.
🏦 $26 BILLION PRIVATE PLACEMENT: Major technology players, including Google, NVIDIA, AMD, Microsoft, Broadcom, Micron and TSMC, are participating in a separate private placement.
⚡ NASDAQ LISTING: Anthropic plans to list under the ticker ANT, with an expected IPO price range of $70–$78 per share.
This isn't just another technology listing. It's a major test of investor confidence in artificial intelligence and the future of the global tech industry.
The big question: Can Anthropic turn this historic IPO into one of the biggest success stories in AI history? 👀
#Anthropic #anthropicipo #ArtificialIntelligence #AIRevolution #BinanceSquare
$ANT $NVDA $GOOGLB
🚀 ANTHROPIC EYES A $1.4 TRILLION IPO VALUATION — THE AI REVOLUTION IS GETTING BIGGER!
The AI industry is entering another historic chapter! 🔥 Anthropic, the company behind Claude AI, is preparing for a massive public offering that could make it one of the most valuable technology companies in the world.
Here's what makes this IPO extraordinary:
💰 $1.4 TRILLION VALUATION: Anthropic's proposed fully diluted valuation could reach approximately $1.404 trillion, according to its latest IPO pricing range.
📊 $81 BILLION REVENUE RUN RATE: The company reported an annualized revenue run rate of approximately $81 billion as of October 31, 2026.
🏦 $26 BILLION PRIVATE PLACEMENT: Major technology players, including Google, NVIDIA, AMD, Microsoft, Broadcom, Micron and TSMC, are participating in a separate private placement.
⚡ NASDAQ LISTING: Anthropic plans to list under the ticker ANT, with an expected IPO price range of $70–$78 per share.
This isn't just another technology listing. It's a major test of investor confidence in artificial intelligence and the future of the global tech industry.
The big question: Can Anthropic turn this historic IPO into one of the biggest success stories in AI history? 👀
#Anthropic #anthropicipo #ArtificialIntelligence #AIRevolution #BinanceSquare
$ANT $NVDA $GOOGLB
The AI industry is entering another historic chapter! 🔥 Anthropic, the company behind Claude AI, is preparing for a massive public offering that could make it one of the most valuable technology companies in the world.
Here's what makes this IPO extraordinary:
💰 $1.4 TRILLION VALUATION: Anthropic's proposed fully diluted valuation could reach approximately $1.404 trillion, according to its latest IPO pricing range.
📊 $81 BILLION REVENUE RUN RATE: The company reported an annualized revenue run rate of approximately $81 billion as of October 31, 2026.
🏦 $26 BILLION PRIVATE PLACEMENT: Major technology players, including Google, NVIDIA, AMD, Microsoft, Broadcom, Micron and TSMC, are participating in a separate private placement.
⚡ NASDAQ LISTING: Anthropic plans to list under the ticker ANT, with an expected IPO price range of $70–$78 per share.
This isn't just another technology listing. It's a major test of investor confidence in artificial intelligence and the future of the global tech industry.
The big question: Can Anthropic turn this historic IPO into one of the biggest success stories in AI history? 👀
#Anthropic #anthropicipo #ArtificialIntelligence #AIRevolution #BinanceSquare
$ANT $NVDA $GOOGLB
2
640

🚨 JUST IN: ANTHROPIC IPO DEMAND SURGES — PRE-IPO TRADING ALREADY ABOVE $1,000!
Anthropic’s bankers may raise the IPO price above the initial $70–$78 range amid heavy investor demand, FT reports.
Meanwhile, its pre-IPO derivatives are trading above $1,000 on crypto platforms, including Binance.
Could Anthropic’s IPO valuation exceed $1.5 TRILLION?
#Anthropic #Binance #IPO #AI $ANTHROPIC
{future}(ANTHROPICUSDT)
🚨 JUST IN: ANTHROPIC IPO DEMAND SURGES — PRE-IPO TRADING ALREADY ABOVE $1,000!
Anthropic’s bankers may raise the IPO price above the initial $70–$78 range amid heavy investor demand, FT reports.
Meanwhile, its pre-IPO derivatives are trading above $1,000 on crypto platforms, including Binance.
Could Anthropic’s IPO valuation exceed $1.5 TRILLION?
#Anthropic #Binance #IPO #AI $ANTHROPIC
Anthropic’s bankers may raise the IPO price above the initial $70–$78 range amid heavy investor demand, FT reports.
Meanwhile, its pre-IPO derivatives are trading above $1,000 on crypto platforms, including Binance.
Could Anthropic’s IPO valuation exceed $1.5 TRILLION?
#Anthropic #Binance #IPO #AI $ANTHROPIC
1
294
·
--
Bearish
#anthropicipo $ANTHROPIC
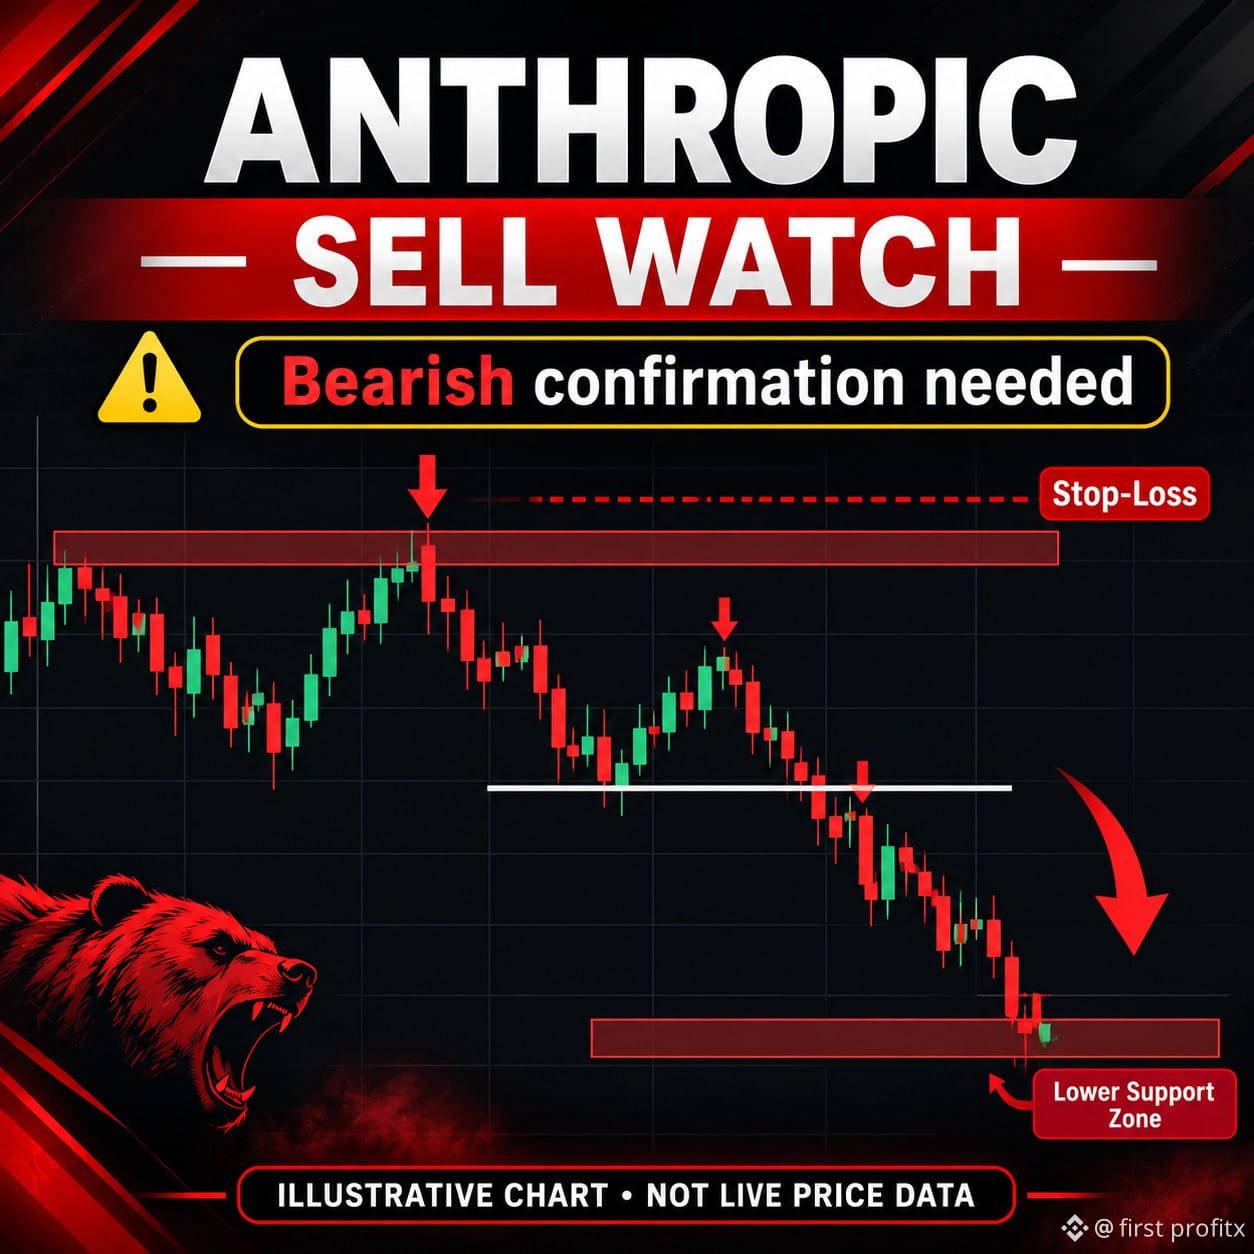
🔴 $ANTHROPIC (PRE-IPO) | BEARISH WATCH
The market is showing signs of weakness. Sellers could take control if important support breaks.
📉 SELL Strategy
Watch for rejection at resistance.
Wait for bearish confirmation.
Target the next support zone.
Keep a strict Stop Loss.
⚠️ No blind entries. Confirm price action and volume before trading.
#Anthropic #AnthropicIPO #sellsignal #CryptoTradingPrediction #BinanceSquare
{future}(ANTHROPICUSDT)
#BearishMarket
#anthropicipo $ANTHROPIC
🔴 $ANTHROPIC (PRE-IPO) | BEARISH WATCH
The market is showing signs of weakness. Sellers could take control if important support breaks.
📉 SELL Strategy
Watch for rejection at resistance.
Wait for bearish confirmation.
Target the next support zone.
Keep a strict Stop Loss.
⚠️ No blind entries. Confirm price action and volume before trading.
#Anthropic #AnthropicIPO #sellsignal #CryptoTradingPrediction #BinanceSquare
#BearishMarket
🔴 $ANTHROPIC (PRE-IPO) | BEARISH WATCH
The market is showing signs of weakness. Sellers could take control if important support breaks.
📉 SELL Strategy
Watch for rejection at resistance.
Wait for bearish confirmation.
Target the next support zone.
Keep a strict Stop Loss.
⚠️ No blind entries. Confirm price action and volume before trading.
#Anthropic #AnthropicIPO #sellsignal #CryptoTradingPrediction #BinanceSquare
#BearishMarket
1
97

·
--
Bullish
🚀 SPACEX ROSE 19% ON DEBUT. CAN ANTHROPIC DO THE SAME?
SpaceX shares jumped 19% on their first trading day in June 2026, creating a historic IPO moment.
Now all eyes are on Anthropic! 👀
With its IPO approaching, investors are asking one big question:
📈 Will Anthropic follow SpaceX's success, or will AI valuation concerns trigger a sell-off?
🔥 Your prediction?
BULLISH 🚀 or BEARISH 📉?
#Anthropic #spacx #IPO #AI #AnthropicIPO
$SPCX $ANTHROPIC
{future}(ANTHROPICUSDT)
{future}(SPCXUSDT)
🚀 SPACEX ROSE 19% ON DEBUT. CAN ANTHROPIC DO THE SAME?
SpaceX shares jumped 19% on their first trading day in June 2026, creating a historic IPO moment.
Now all eyes are on Anthropic! 👀
With its IPO approaching, investors are asking one big question:
📈 Will Anthropic follow SpaceX's success, or will AI valuation concerns trigger a sell-off?
🔥 Your prediction?
BULLISH 🚀 or BEARISH 📉?
#Anthropic #spacx #IPO #AI #AnthropicIPO
$SPCX $ANTHROPIC
SpaceX shares jumped 19% on their first trading day in June 2026, creating a historic IPO moment.
Now all eyes are on Anthropic! 👀
With its IPO approaching, investors are asking one big question:
📈 Will Anthropic follow SpaceX's success, or will AI valuation concerns trigger a sell-off?
🔥 Your prediction?
BULLISH 🚀 or BEARISH 📉?
#Anthropic #spacx #IPO #AI #AnthropicIPO
$SPCX $ANTHROPIC
204

🚨 $ANTHROPIC VALUATION RESET TO $1.4T SETS UP THE ULTIMATE TECH MOMENTUM PLAY! 💥
Entry: 70 ⚡
Target: 80 🚀
The macro chop just shaved the hype off the biggest upcoming listing, dragging valuations from $2T down to a leaner $1.4T reality check. 📊 That regulatory fear on data centers created a clean liquidity dip, but enterprise trust in Claude gives this asset an undeniable institutional moat. ⚡
While retail chases noise, smart money is eyeing that 70 to 80 range as the foundational floor for the upcoming roadshow explosion. 💡 Are you scaling in on this volatility or waiting for the opening bell dust to settle? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #ANTHROPIC #AnthropicIPO #LongSetup #Breakout #Crypto
🔥 💎
🚨 $ANTHROPIC VALUATION RESET TO $1.4T SETS UP THE ULTIMATE TECH MOMENTUM PLAY! 💥
Entry: 70 ⚡
Target: 80 🚀
The macro chop just shaved the hype off the biggest upcoming listing, dragging valuations from $2T down to a leaner $1.4T reality check. 📊 That regulatory fear on data centers created a clean liquidity dip, but enterprise trust in Claude gives this asset an undeniable institutional moat. ⚡
While retail chases noise, smart money is eyeing that 70 to 80 range as the foundational floor for the upcoming roadshow explosion. 💡 Are you scaling in on this volatility or waiting for the opening bell dust to settle? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #ANTHROPIC #AnthropicIPO #LongSetup #Breakout #Crypto
🔥 💎
Entry: 70 ⚡
Target: 80 🚀
The macro chop just shaved the hype off the biggest upcoming listing, dragging valuations from $2T down to a leaner $1.4T reality check. 📊 That regulatory fear on data centers created a clean liquidity dip, but enterprise trust in Claude gives this asset an undeniable institutional moat. ⚡
While retail chases noise, smart money is eyeing that 70 to 80 range as the foundational floor for the upcoming roadshow explosion. 💡 Are you scaling in on this volatility or waiting for the opening bell dust to settle? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #ANTHROPIC #AnthropicIPO #LongSetup #Breakout #Crypto
🔥 💎
6
·
--
Bullish
Verified
Can Anthropic Hold a $1 Trillion+ Valuation? 🤔
Anthropic is heading for what could be the largest IPO in history — aiming to raise up to $100B!
But here is the twist: Its expected valuation has already dropped from $2 Trillion to around $1.5 Trillion.
So the big question is: Can it hold the $1 Trillion mark?
My Take:
1. Valuation: $1.5T is still massive. After the Nov 5 Nasdaq drop of 5.5% and AI stocks falling on regulation fears, the market is no longer paying any price for AI. Anthropic has to prove real revenue, not just hype.
2. Debut: Remember SpaceX rose 19% on its first day this June. Will Anthropic do the same? I think YES — but only if pricing is realistic. If it prices too high like $2T, first-day fall is possible. If it prices smart, a green debut is very likely.
3. The Real Game-Changer: On Nov 5, Anthropic started beta testing Personal Finance in Claude — with read-only access to bank and card accounts.
This is HUGE. AI is no longer just chatting, it's now managing your money!
Would you let AI see your account data? I would — but only with read-only + full control.
For me, Anthropic is not a bubble, it's the next infrastructure. Short-term volatility is normal, long-term $1T+ is very possible.
What do you think? Will $ANTHROPIC rise or fall on debut? 👇
#AnthropicIPO #Anthropic #AI #BinanceSquare
{future}(ANTHROPICUSDT)
Can Anthropic Hold a $1 Trillion+ Valuation? 🤔
Anthropic is heading for what could be the largest IPO in history — aiming to raise up to $100B!
But here is the twist: Its expected valuation has already dropped from $2 Trillion to around $1.5 Trillion.
So the big question is: Can it hold the $1 Trillion mark?
My Take:
1. Valuation: $1.5T is still massive. After the Nov 5 Nasdaq drop of 5.5% and AI stocks falling on regulation fears, the market is no longer paying any price for AI. Anthropic has to prove real revenue, not just hype.
2. Debut: Remember SpaceX rose 19% on its first day this June. Will Anthropic do the same? I think YES — but only if pricing is realistic. If it prices too high like $2T, first-day fall is possible. If it prices smart, a green debut is very likely.
3. The Real Game-Changer: On Nov 5, Anthropic started beta testing Personal Finance in Claude — with read-only access to bank and card accounts.
This is HUGE. AI is no longer just chatting, it's now managing your money!
Would you let AI see your account data? I would — but only with read-only + full control.
For me, Anthropic is not a bubble, it's the next infrastructure. Short-term volatility is normal, long-term $1T+ is very possible.
What do you think? Will $ANTHROPIC rise or fall on debut? 👇
#AnthropicIPO #Anthropic #AI #BinanceSquare
Anthropic is heading for what could be the largest IPO in history — aiming to raise up to $100B!
But here is the twist: Its expected valuation has already dropped from $2 Trillion to around $1.5 Trillion.
So the big question is: Can it hold the $1 Trillion mark?
My Take:
1. Valuation: $1.5T is still massive. After the Nov 5 Nasdaq drop of 5.5% and AI stocks falling on regulation fears, the market is no longer paying any price for AI. Anthropic has to prove real revenue, not just hype.
2. Debut: Remember SpaceX rose 19% on its first day this June. Will Anthropic do the same? I think YES — but only if pricing is realistic. If it prices too high like $2T, first-day fall is possible. If it prices smart, a green debut is very likely.
3. The Real Game-Changer: On Nov 5, Anthropic started beta testing Personal Finance in Claude — with read-only access to bank and card accounts.
This is HUGE. AI is no longer just chatting, it's now managing your money!
Would you let AI see your account data? I would — but only with read-only + full control.
For me, Anthropic is not a bubble, it's the next infrastructure. Short-term volatility is normal, long-term $1T+ is very possible.
What do you think? Will $ANTHROPIC rise or fall on debut? 👇
#AnthropicIPO #Anthropic #AI #BinanceSquare
85

·
--
🚨 $ANTHROPIC PRE-IPO LIQUIDITY SWEEPS REVEAL BRUTAL INSTITUTIONAL REALITY 🦈
Entry: 70 ⚡
The massive valuation re-pricing across artificial intelligence infrastructure highlights severe capital burn against projected revenues. 📊 Smart money is carefully tracking how heavy insider voting control shifts the burden of liquidity directly onto retail participants. 🌊
When speculative derivatives trade at a wide disconnect from foundational reality, structural traps form fast. 💡 Are you positioning into these tech equity proxies or staying sidelined while order flow stabilizes? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #ANTHROPIC #PreIPO #TechEquities #MarketStructure
🦈 ⚖️
🚨 $ANTHROPIC PRE-IPO LIQUIDITY SWEEPS REVEAL BRUTAL INSTITUTIONAL REALITY 🦈
Entry: 70 ⚡
The massive valuation re-pricing across artificial intelligence infrastructure highlights severe capital burn against projected revenues. 📊 Smart money is carefully tracking how heavy insider voting control shifts the burden of liquidity directly onto retail participants. 🌊
When speculative derivatives trade at a wide disconnect from foundational reality, structural traps form fast. 💡 Are you positioning into these tech equity proxies or staying sidelined while order flow stabilizes? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #ANTHROPIC #PreIPO #TechEquities #MarketStructure
🦈 ⚖️
Entry: 70 ⚡
The massive valuation re-pricing across artificial intelligence infrastructure highlights severe capital burn against projected revenues. 📊 Smart money is carefully tracking how heavy insider voting control shifts the burden of liquidity directly onto retail participants. 🌊
When speculative derivatives trade at a wide disconnect from foundational reality, structural traps form fast. 💡 Are you positioning into these tech equity proxies or staying sidelined while order flow stabilizes? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #ANTHROPIC #PreIPO #TechEquities #MarketStructure
🦈 ⚖️
44
·
--
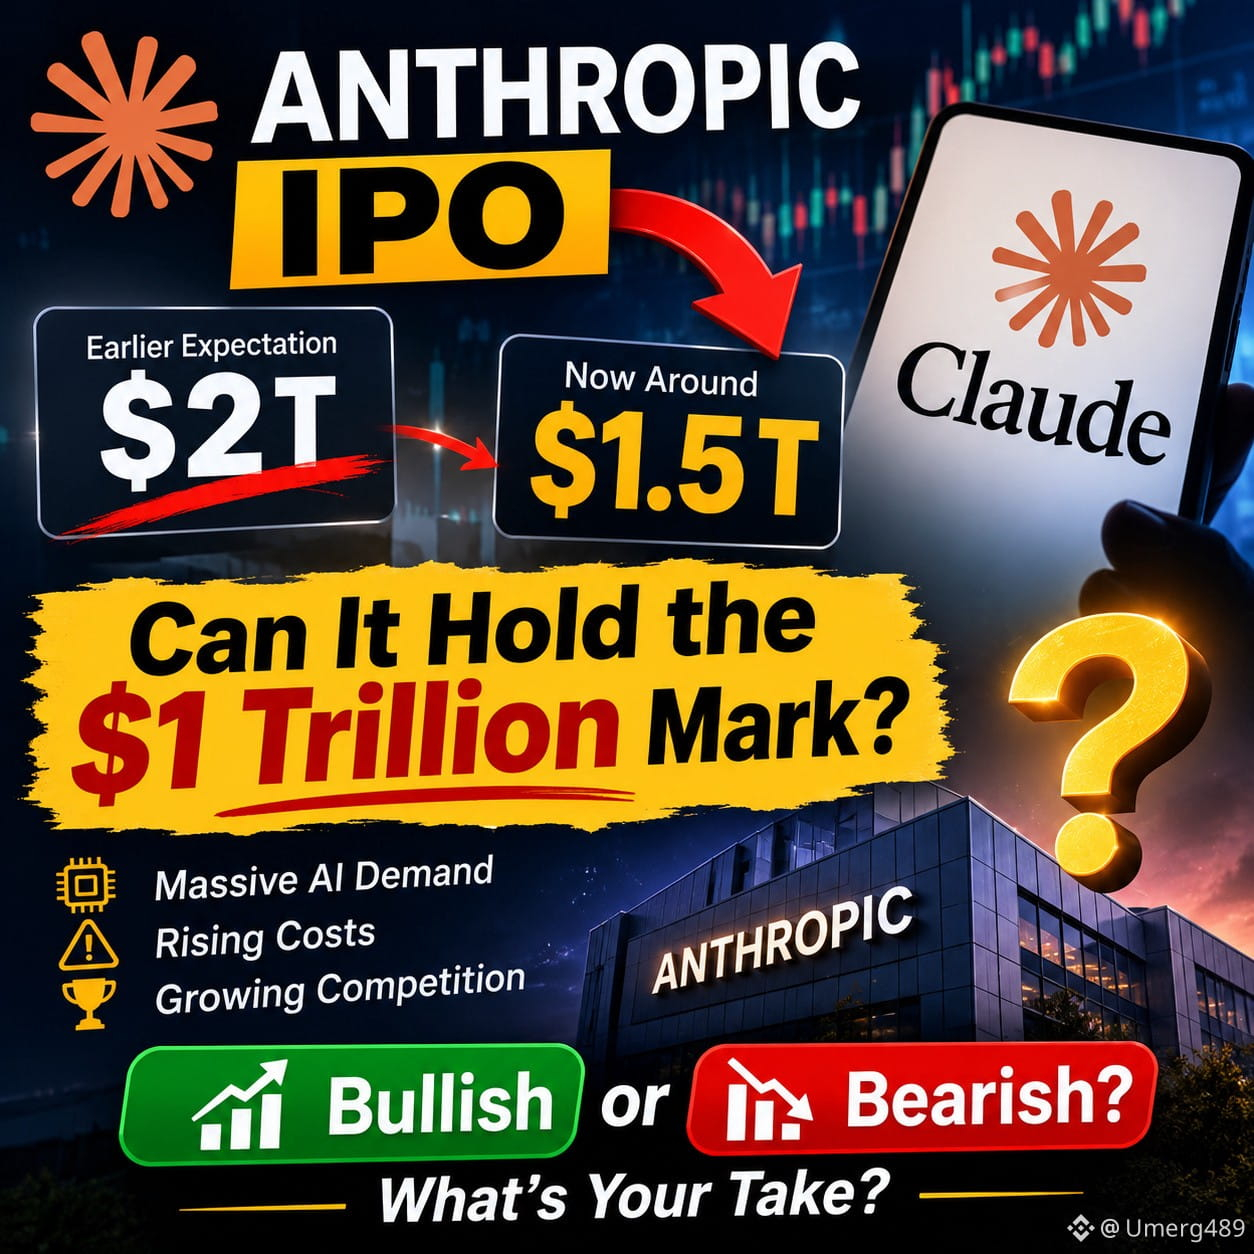
ANTHROPIC IPO: IS THE $1 TRILLION DREAM AT RISK?
Anthropic's expected IPO valuation has reportedly dropped from $2 trillion to around $1.5 trillion. 📉
Despite massive AI demand and Claude's growing popularity, investors are questioning rising costs, competition, and long-term profitability.
🔥 The big question:
Can Anthropic hold the $1 trillion mark, or is the AI hype cooling down?
🚀 Bullish or Bearish? What's your take?
#Anthropic #IPO #Claude #MarketInsights #AnthropicIPO
$SPCX $ANTHROPIC
{future}(ANTHROPICUSDT)
{future}(SPCXUSDT)
ANTHROPIC IPO: IS THE $1 TRILLION DREAM AT RISK?
Anthropic's expected IPO valuation has reportedly dropped from $2 trillion to around $1.5 trillion. 📉
Despite massive AI demand and Claude's growing popularity, investors are questioning rising costs, competition, and long-term profitability.
🔥 The big question:
Can Anthropic hold the $1 trillion mark, or is the AI hype cooling down?
🚀 Bullish or Bearish? What's your take?
#Anthropic #IPO #Claude #MarketInsights #AnthropicIPO
$SPCX $ANTHROPIC
Anthropic's expected IPO valuation has reportedly dropped from $2 trillion to around $1.5 trillion. 📉
Despite massive AI demand and Claude's growing popularity, investors are questioning rising costs, competition, and long-term profitability.
🔥 The big question:
Can Anthropic hold the $1 trillion mark, or is the AI hype cooling down?
🚀 Bullish or Bearish? What's your take?
#Anthropic #IPO #Claude #MarketInsights #AnthropicIPO
$SPCX $ANTHROPIC
255
·
--
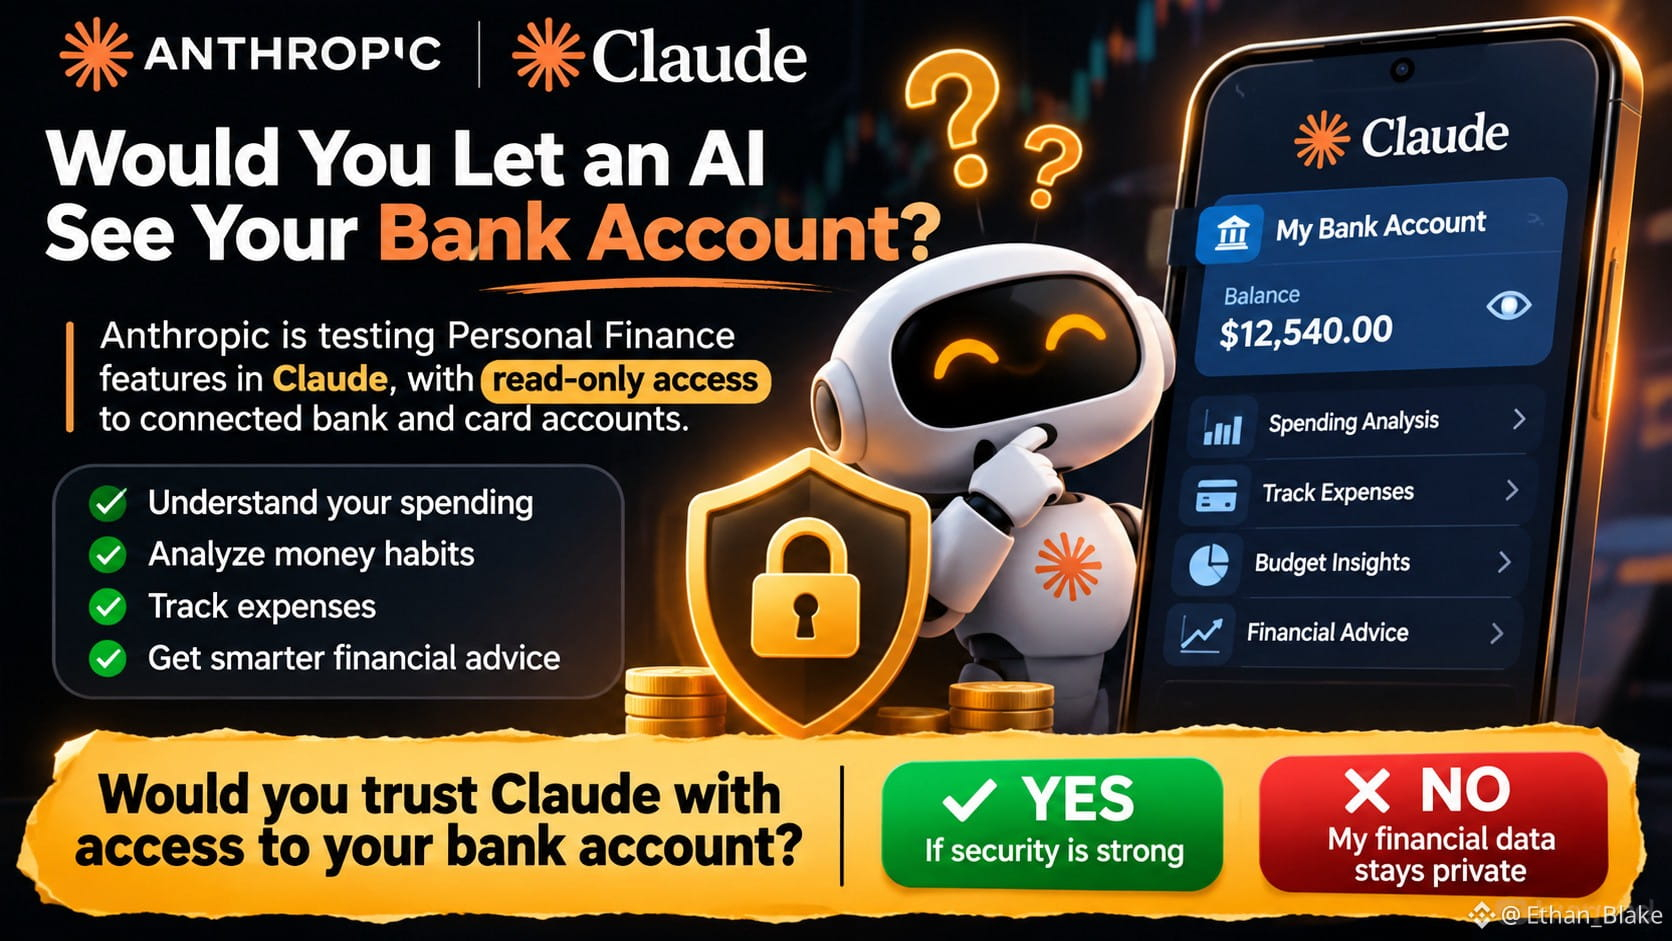
🤔 Would you let an AI see your bank account balance, spending habits, and financial transactions?
Honestly, this is where AI gets exciting… but also a little scary. 👀
🤖 Anthropic is testing Personal Finance features in Claude, with read-only access to connected bank and card accounts.
Think about the possibilities:
💳 Understand where your money goes. 📊 Analyze your spending habits. 💰 Track expenses more easily. 🧠 Get help making smarter financial decisions.
Sounds convenient, right?
But there's another side to this. 🔐
Your financial data is extremely personal. Even if access is read-only, connecting your bank account to an AI system requires serious trust.
For me, convenience isn't everything. Security, transparency, and control over personal data must come first.
🚀 AI is moving beyond answering questions. It's slowly becoming part of our everyday financial lives.
Now I'm curious…
Would you trust Claude with access to your bank account?
🟢 YES — if security is strong.
🔴 NO — my financial data stays private.
#AnthropicIPO #Anthropic #ClaudeAI #ArtificialIntelligence #AI
🤔 Would you let an AI see your bank account balance, spending habits, and financial transactions?
Honestly, this is where AI gets exciting… but also a little scary. 👀
🤖 Anthropic is testing Personal Finance features in Claude, with read-only access to connected bank and card accounts.
Think about the possibilities:
💳 Understand where your money goes. 📊 Analyze your spending habits. 💰 Track expenses more easily. 🧠 Get help making smarter financial decisions.
Sounds convenient, right?
But there's another side to this. 🔐
Your financial data is extremely personal. Even if access is read-only, connecting your bank account to an AI system requires serious trust.
For me, convenience isn't everything. Security, transparency, and control over personal data must come first.
🚀 AI is moving beyond answering questions. It's slowly becoming part of our everyday financial lives.
Now I'm curious…
Would you trust Claude with access to your bank account?
🟢 YES — if security is strong.
🔴 NO — my financial data stays private.
#AnthropicIPO #Anthropic #ClaudeAI #ArtificialIntelligence #AI
Honestly, this is where AI gets exciting… but also a little scary. 👀
🤖 Anthropic is testing Personal Finance features in Claude, with read-only access to connected bank and card accounts.
Think about the possibilities:
💳 Understand where your money goes. 📊 Analyze your spending habits. 💰 Track expenses more easily. 🧠 Get help making smarter financial decisions.
Sounds convenient, right?
But there's another side to this. 🔐
Your financial data is extremely personal. Even if access is read-only, connecting your bank account to an AI system requires serious trust.
For me, convenience isn't everything. Security, transparency, and control over personal data must come first.
🚀 AI is moving beyond answering questions. It's slowly becoming part of our everyday financial lives.
Now I'm curious…
Would you trust Claude with access to your bank account?
🟢 YES — if security is strong.
🔴 NO — my financial data stays private.
#AnthropicIPO #Anthropic #ClaudeAI #ArtificialIntelligence #AI
141
#AnthropicIPO
ANTHROPIC IPO — THE AI BOOM COULD BE HEADING TOWARD WALL STREET
Anthropic is becoming one of the most closely watched names in the artificial intelligence industry, and the possibility of an IPO is attracting serious attention from investors.
But here's the interesting part: Anthropic is not a cryptocurrency, and it does not have an official publicly traded stock ticker. An IPO would create a new investment opportunity in the AI sector, not automatically a new crypto asset.
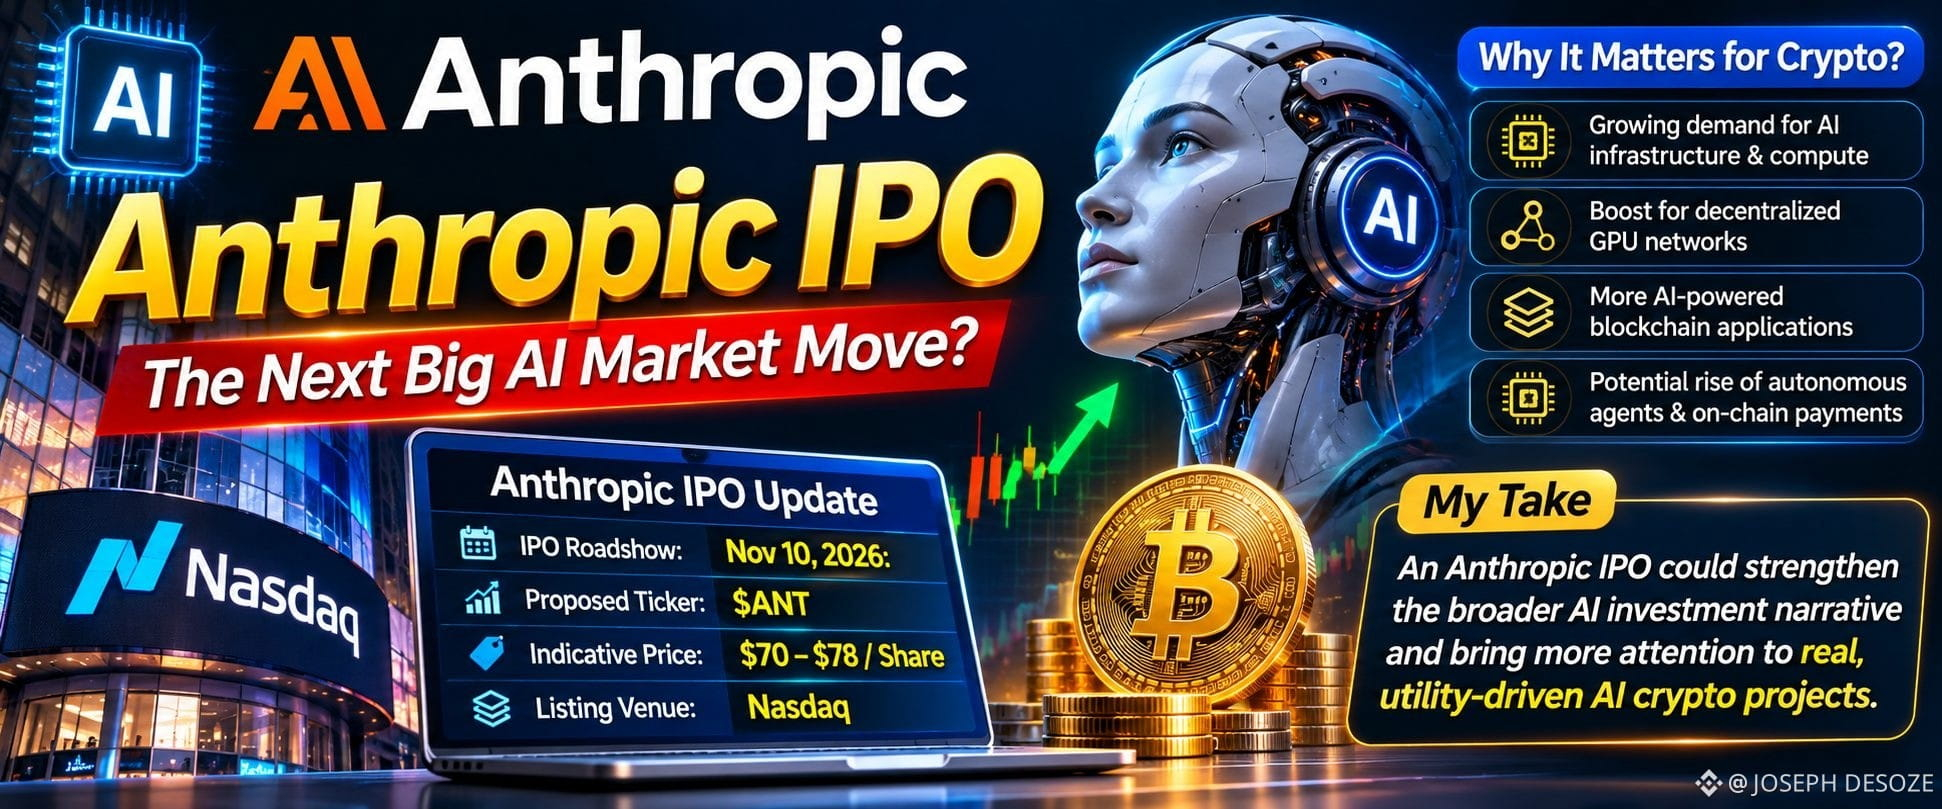
Why does this matter for crypto?
The AI and crypto industries are increasingly connected through several major themes:
- AI infrastructure and computing demand.
- Decentralized GPU networks.
- AI-powered blockchain applications.
- Autonomous agents and machine-to-machine payments.
- Growing demand for data, compute and digital infrastructure.
My Market Perspective:
An Anthropic IPO could become an important milestone for the broader AI investment narrative. If investor demand is strong, it may reinforce interest in AI-related technology and potentially influence sentiment around AI-focused crypto projects.
However, there is an important distinction: enthusiasm for an AI company's IPO does not guarantee gains for AI crypto tokens.
The real opportunity is identifying projects with actual utility, adoption, revenue potential and sustainable technology rather than chasing every token carrying the AI label.
One thing worth watching: Will traditional investors' appetite for AI companies eventually translate into stronger institutional interest in decentralized AI infrastructure?
That could be a much bigger story than the IPO itself.
What do you think: Could an Anthropic IPO become another catalyst for the AI crypto narrative?
#Anthropic #AI #Crypto #ArtificialIntelligence #DePIN #AI Crypto
#AnthropicIPO
ANTHROPIC IPO — THE AI BOOM COULD BE HEADING TOWARD WALL STREET
Anthropic is becoming one of the most closely watched names in the artificial intelligence industry, and the possibility of an IPO is attracting serious attention from investors.
But here's the interesting part: Anthropic is not a cryptocurrency, and it does not have an official publicly traded stock ticker. An IPO would create a new investment opportunity in the AI sector, not automatically a new crypto asset.
Why does this matter for crypto?
The AI and crypto industries are increasingly connected through several major themes:
- AI infrastructure and computing demand.
- Decentralized GPU networks.
- AI-powered blockchain applications.
- Autonomous agents and machine-to-machine payments.
- Growing demand for data, compute and digital infrastructure.
My Market Perspective:
An Anthropic IPO could become an important milestone for the broader AI investment narrative. If investor demand is strong, it may reinforce interest in AI-related technology and potentially influence sentiment around AI-focused crypto projects.
However, there is an important distinction: enthusiasm for an AI company's IPO does not guarantee gains for AI crypto tokens.
The real opportunity is identifying projects with actual utility, adoption, revenue potential and sustainable technology rather than chasing every token carrying the AI label.
One thing worth watching: Will traditional investors' appetite for AI companies eventually translate into stronger institutional interest in decentralized AI infrastructure?
That could be a much bigger story than the IPO itself.
What do you think: Could an Anthropic IPO become another catalyst for the AI crypto narrative?
#Anthropic #AI #Crypto #ArtificialIntelligence #DePIN #AI Crypto
ANTHROPIC IPO — THE AI BOOM COULD BE HEADING TOWARD WALL STREET
Anthropic is becoming one of the most closely watched names in the artificial intelligence industry, and the possibility of an IPO is attracting serious attention from investors.
But here's the interesting part: Anthropic is not a cryptocurrency, and it does not have an official publicly traded stock ticker. An IPO would create a new investment opportunity in the AI sector, not automatically a new crypto asset.
Why does this matter for crypto?
The AI and crypto industries are increasingly connected through several major themes:
- AI infrastructure and computing demand.
- Decentralized GPU networks.
- AI-powered blockchain applications.
- Autonomous agents and machine-to-machine payments.
- Growing demand for data, compute and digital infrastructure.
My Market Perspective:
An Anthropic IPO could become an important milestone for the broader AI investment narrative. If investor demand is strong, it may reinforce interest in AI-related technology and potentially influence sentiment around AI-focused crypto projects.
However, there is an important distinction: enthusiasm for an AI company's IPO does not guarantee gains for AI crypto tokens.
The real opportunity is identifying projects with actual utility, adoption, revenue potential and sustainable technology rather than chasing every token carrying the AI label.
One thing worth watching: Will traditional investors' appetite for AI companies eventually translate into stronger institutional interest in decentralized AI infrastructure?
That could be a much bigger story than the IPO itself.
What do you think: Could an Anthropic IPO become another catalyst for the AI crypto narrative?
#Anthropic #AI #Crypto #ArtificialIntelligence #DePIN #AI Crypto
272
🚨 Nvidia fell. AI tokens held up. Is Anthropic’s IPO the next catalyst?
While Nvidia shares slid amid scrutiny of CEO Jensen Huang, FET gained 2.06% and RENDER gained 1.10% against Bitcoin on November 10. TAO was nearly flat vs. BTC.
Now Wall Street is about to put a price on Claude. 👀
Anthropic is expected to debut on Nasdaq on November 19 under ANT, with a proposed valuation of up to $1.4 trillion on a fully diluted basis.
🟢 Strong debut that holds? Renewed enthusiasm for AI could spill into RENDER, TAO and FET.
🟡 ANT rallies alone? Investors may prefer direct exposure through AI stocks while tokens keep following Bitcoin.
🔴 Weak debut or quick reversal? AI tokens could feel the pressure, especially if BTC is already sliding.
📊 Do RENDER, TAO and FET all gain against BTC and hold those gains beyond day one? That would be a stronger sign of an AI-specific rally than a green day across crypto. #DYOR
Which token reacts first: RENDER, TAO or FET? 👇
#AICrypto #IPOWave #Anthropic
$NVDAB
{spot}(NVDABUSDT)
$RENDER
{spot}(RENDERUSDT)
$FET
{spot}(FETUSDT)
🚨 Nvidia fell. AI tokens held up. Is Anthropic’s IPO the next catalyst?
While Nvidia shares slid amid scrutiny of CEO Jensen Huang, FET gained 2.06% and RENDER gained 1.10% against Bitcoin on November 10. TAO was nearly flat vs. BTC.
Now Wall Street is about to put a price on Claude. 👀
Anthropic is expected to debut on Nasdaq on November 19 under ANT, with a proposed valuation of up to $1.4 trillion on a fully diluted basis.
🟢 Strong debut that holds? Renewed enthusiasm for AI could spill into RENDER, TAO and FET.
🟡 ANT rallies alone? Investors may prefer direct exposure through AI stocks while tokens keep following Bitcoin.
🔴 Weak debut or quick reversal? AI tokens could feel the pressure, especially if BTC is already sliding.
📊 Do RENDER, TAO and FET all gain against BTC and hold those gains beyond day one? That would be a stronger sign of an AI-specific rally than a green day across crypto. #DYOR
Which token reacts first: RENDER, TAO or FET? 👇
#AICrypto #IPOWave #Anthropic
$NVDAB
$RENDER
$FET
While Nvidia shares slid amid scrutiny of CEO Jensen Huang, FET gained 2.06% and RENDER gained 1.10% against Bitcoin on November 10. TAO was nearly flat vs. BTC.
Now Wall Street is about to put a price on Claude. 👀
Anthropic is expected to debut on Nasdaq on November 19 under ANT, with a proposed valuation of up to $1.4 trillion on a fully diluted basis.
🟢 Strong debut that holds? Renewed enthusiasm for AI could spill into RENDER, TAO and FET.
🟡 ANT rallies alone? Investors may prefer direct exposure through AI stocks while tokens keep following Bitcoin.
🔴 Weak debut or quick reversal? AI tokens could feel the pressure, especially if BTC is already sliding.
📊 Do RENDER, TAO and FET all gain against BTC and hold those gains beyond day one? That would be a stronger sign of an AI-specific rally than a green day across crypto. #DYOR
Which token reacts first: RENDER, TAO or FET? 👇
#AICrypto #IPOWave #Anthropic
$NVDAB
$RENDER
$FET
475
·
--
Bullish
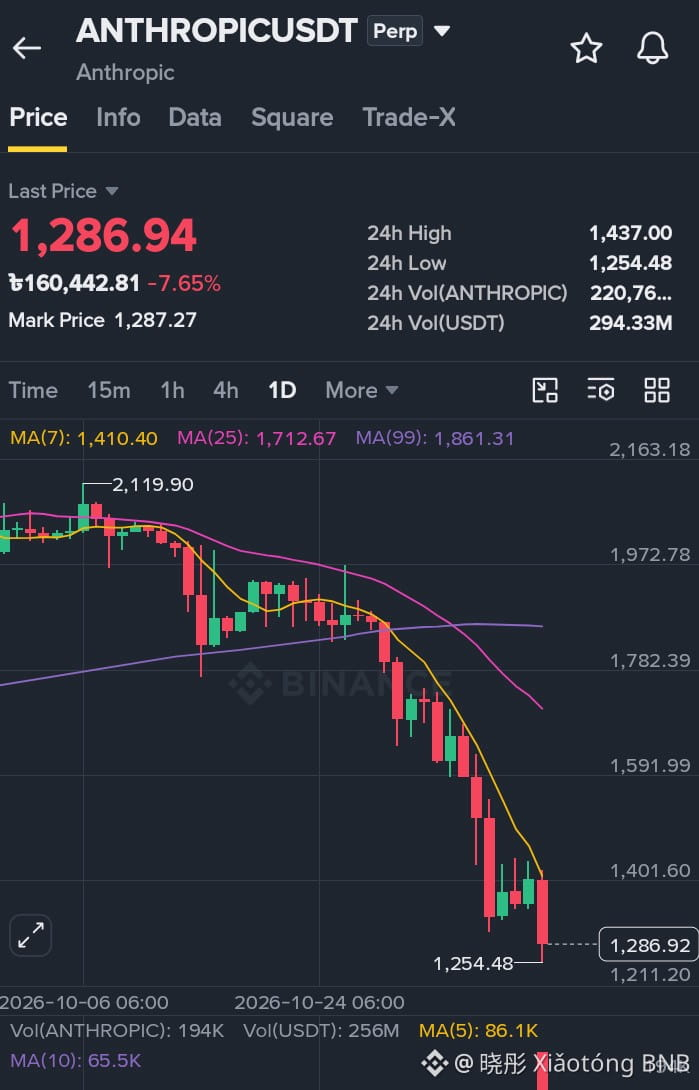
#Anthropic ANTHROPIC Perp Slides Below All Key Moving Averages: What the Daily Chart Shows
ANTHROPICUSDT Perp is down about 7.65% today, trading near 1,287 after a 24h range of 1,254 to 1,437. On the daily chart, price has fallen steadily from the 2,119 area and now sits below the
#Anthropic ANTHROPIC Perp Slides Below All Key Moving Averages: What the Daily Chart Shows
ANTHROPICUSDT Perp is down about 7.65% today, trading near 1,287 after a 24h range of 1,254 to 1,437. On the daily chart, price has fallen steadily from the 2,119 area and now sits below the
ANTHROPICUSDT Perp is down about 7.65% today, trading near 1,287 after a 24h range of 1,254 to 1,437. On the daily chart, price has fallen steadily from the 2,119 area and now sits below the
171

·
--
#AnthropicIPO
The Biggest IPO In History Is Here.
Anthropic, the company behind Claude, just set its IPO price range today.
The Details:
Ticker: $ANT on Nasdaq
Price Range: $70 - $78 per share
Shares: 825 Million
Raise: Up to $64.35B from IPO alone
Valuation: Up to $1.02 Trillion, $1.405 Trillion fully diluted
Listing Date: Expected week of Nov 16 - 19
This is down from the $2 Trillion valuation talked about in October. The AI sell-off forced Anthropic to be more realistic.
Who Is Buying $26B On The Side?
Google: $10B
Nvidia $NVDA: $10B
AMD $AMD: $2.5B
Microsoft $MSFT: $1B
Broadcom $AVGO: $1B
Micron $MU: $1B
TSMC $TSM: $500M
Total fundraising could hit $90.4B. That would make it one of the largest ever, close to SpaceX.
The Numbers:
Revenue 9 months 2026: $33.24B, 12x higher than last year
Q3 Revenue: $16.96B, up 46.7% from Q2
Net Loss 9 months: $104B, mostly due to accounting adjustment
Last private valuation May 2026: $965B
Anthropic is growing insanely fast, but it is still burning massive cash on AI compute. It has $895.4B in committed spending on AI infrastructure.
Why This Matters For Crypto?
If $ANT IPO succeeds, it will bring back confidence in AI. That is bullish for $BTC, $ETH, and AI coins like $TAO, $FET, $RENDER, $NEAR, $UAI.
If it flops, AI bubble fear will get worse.
Are you buying $ANT on listing day, or waiting?
#AnthropicIPO #Anthropic #Claude #BinanceSquare
#AnthropicIPO
#AnthropicIPO
The Biggest IPO In History Is Here.
Anthropic, the company behind Claude, just set its IPO price range today.
The Details:
Ticker: $ANT on Nasdaq
Price Range: $70 - $78 per share
Shares: 825 Million
Raise: Up to $64.35B from IPO alone
Valuation: Up to $1.02 Trillion, $1.405 Trillion fully diluted
Listing Date: Expected week of Nov 16 - 19
This is down from the $2 Trillion valuation talked about in October. The AI sell-off forced Anthropic to be more realistic.
Who Is Buying $26B On The Side?
Google: $10B
Nvidia $NVDA: $10B
AMD $AMD: $2.5B
Microsoft $MSFT: $1B
Broadcom $AVGO: $1B
Micron $MU: $1B
TSMC $TSM: $500M
Total fundraising could hit $90.4B. That would make it one of the largest ever, close to SpaceX.
The Numbers:
Revenue 9 months 2026: $33.24B, 12x higher than last year
Q3 Revenue: $16.96B, up 46.7% from Q2
Net Loss 9 months: $104B, mostly due to accounting adjustment
Last private valuation May 2026: $965B
Anthropic is growing insanely fast, but it is still burning massive cash on AI compute. It has $895.4B in committed spending on AI infrastructure.
Why This Matters For Crypto?
If $ANT IPO succeeds, it will bring back confidence in AI. That is bullish for $BTC, $ETH, and AI coins like $TAO, $FET, $RENDER, $NEAR, $UAI.
If it flops, AI bubble fear will get worse.
Are you buying $ANT on listing day, or waiting?
#AnthropicIPO #Anthropic #Claude #BinanceSquare
#AnthropicIPO
The Biggest IPO In History Is Here.
Anthropic, the company behind Claude, just set its IPO price range today.
The Details:
Ticker: $ANT on Nasdaq
Price Range: $70 - $78 per share
Shares: 825 Million
Raise: Up to $64.35B from IPO alone
Valuation: Up to $1.02 Trillion, $1.405 Trillion fully diluted
Listing Date: Expected week of Nov 16 - 19
This is down from the $2 Trillion valuation talked about in October. The AI sell-off forced Anthropic to be more realistic.
Who Is Buying $26B On The Side?
Google: $10B
Nvidia $NVDA: $10B
AMD $AMD: $2.5B
Microsoft $MSFT: $1B
Broadcom $AVGO: $1B
Micron $MU: $1B
TSMC $TSM: $500M
Total fundraising could hit $90.4B. That would make it one of the largest ever, close to SpaceX.
The Numbers:
Revenue 9 months 2026: $33.24B, 12x higher than last year
Q3 Revenue: $16.96B, up 46.7% from Q2
Net Loss 9 months: $104B, mostly due to accounting adjustment
Last private valuation May 2026: $965B
Anthropic is growing insanely fast, but it is still burning massive cash on AI compute. It has $895.4B in committed spending on AI infrastructure.
Why This Matters For Crypto?
If $ANT IPO succeeds, it will bring back confidence in AI. That is bullish for $BTC, $ETH, and AI coins like $TAO, $FET, $RENDER, $NEAR, $UAI.
If it flops, AI bubble fear will get worse.
Are you buying $ANT on listing day, or waiting?
#AnthropicIPO #Anthropic #Claude #BinanceSquare
#AnthropicIPO
Buying
Waiting
2 day(s) left
1
4.2k
·
--
Bearish
Verified
#anthropicrejectsipodelayvaluationinquestion
🚨ANTHROPIC IPO — UPDATE ($ANT) 🚨
Anthropic (Claude maker) is forging ahead with its IPO later this month, per WSJ. Investor meetings are lined up this week, with shares targeted to start trading Thursday or Friday next week. Listing on Nasdaq under ticker "ANT". 🏷️
Expected to be unveiled in a filing early this week 📄. A week ago investors anticipated ~$1.5T, but after Thursday's steep AI selloff, major investors are pushing for a lower figure ⬇️ (well below the ~$2T floated months ago).
Anchor investment — big money 💰:
Seven companies — Google, Nvidia, AMD, Broadcom, Micron, Microsoft, and TSMC — will invest $26B via private placement at the IPO price. Cornerstone investors will sell 23,333,331 shares in the IPO.
Deal size (earlier plan — pricing was later called "inaccurate" and filing to be updated) 👀:Raise: up to $69.3B,Price range: $70–$80 per share,Shares: 866,666,664 Class A shares
Context ⚠️:Nasdaq Composite has recovered ground, likely giving Anthropic confidence to push forward ✅
AI enthusiasm had been waning on concerns over investment scale & unclear payoff 📉
OpenAI raised less than half its target in its latest round, at a below-target $1.25T valuation
SpaceX's June offering valued it at ~$1.77T & raised ~$75B
Thursday: Nasdaq Composite companies shed $2.5T after midterms swept in AI-skeptics & passed data-center moratoriums 🏛️
Pricing dilemma for bankers (Goldman Sachs, Morgan Stanley) 🎯:
Too high → hurts investor demand, shares slide 📉
Too low → criticism of leaving money on the table 😬
Bankers sometimes encourage slightly lower ranges to raise later citing strong demand 📊
Bottom line: IPO proceeding ✅, valuation expected lower ⬇️, anchor demand strong 💪. Watch this week's filing for the actual price range & named investors 🔔
$NVDA $AMD $ANTHROPIC
{future}(ANTHROPICUSDT)
{future}(AMDUSDT)
{future}(NVDAUSDT)
#Anthropic #NASDAQ #CPITestsDecemberRateOutlook
#anthropicrejectsipodelayvaluationinquestion
🚨ANTHROPIC IPO — UPDATE ($ANT) 🚨
Anthropic (Claude maker) is forging ahead with its IPO later this month, per WSJ. Investor meetings are lined up this week, with shares targeted to start trading Thursday or Friday next week. Listing on Nasdaq under ticker "ANT". 🏷️
Expected to be unveiled in a filing early this week 📄. A week ago investors anticipated ~$1.5T, but after Thursday's steep AI selloff, major investors are pushing for a lower figure ⬇️ (well below the ~$2T floated months ago).
Anchor investment — big money 💰:
Seven companies — Google, Nvidia, AMD, Broadcom, Micron, Microsoft, and TSMC — will invest $26B via private placement at the IPO price. Cornerstone investors will sell 23,333,331 shares in the IPO.
Deal size (earlier plan — pricing was later called "inaccurate" and filing to be updated) 👀:Raise: up to $69.3B,Price range: $70–$80 per share,Shares: 866,666,664 Class A shares
Context ⚠️:Nasdaq Composite has recovered ground, likely giving Anthropic confidence to push forward ✅
AI enthusiasm had been waning on concerns over investment scale & unclear payoff 📉
OpenAI raised less than half its target in its latest round, at a below-target $1.25T valuation
SpaceX's June offering valued it at ~$1.77T & raised ~$75B
Thursday: Nasdaq Composite companies shed $2.5T after midterms swept in AI-skeptics & passed data-center moratoriums 🏛️
Pricing dilemma for bankers (Goldman Sachs, Morgan Stanley) 🎯:
Too high → hurts investor demand, shares slide 📉
Too low → criticism of leaving money on the table 😬
Bankers sometimes encourage slightly lower ranges to raise later citing strong demand 📊
Bottom line: IPO proceeding ✅, valuation expected lower ⬇️, anchor demand strong 💪. Watch this week's filing for the actual price range & named investors 🔔
$NVDA $AMD $ANTHROPIC
#Anthropic #NASDAQ #CPITestsDecemberRateOutlook
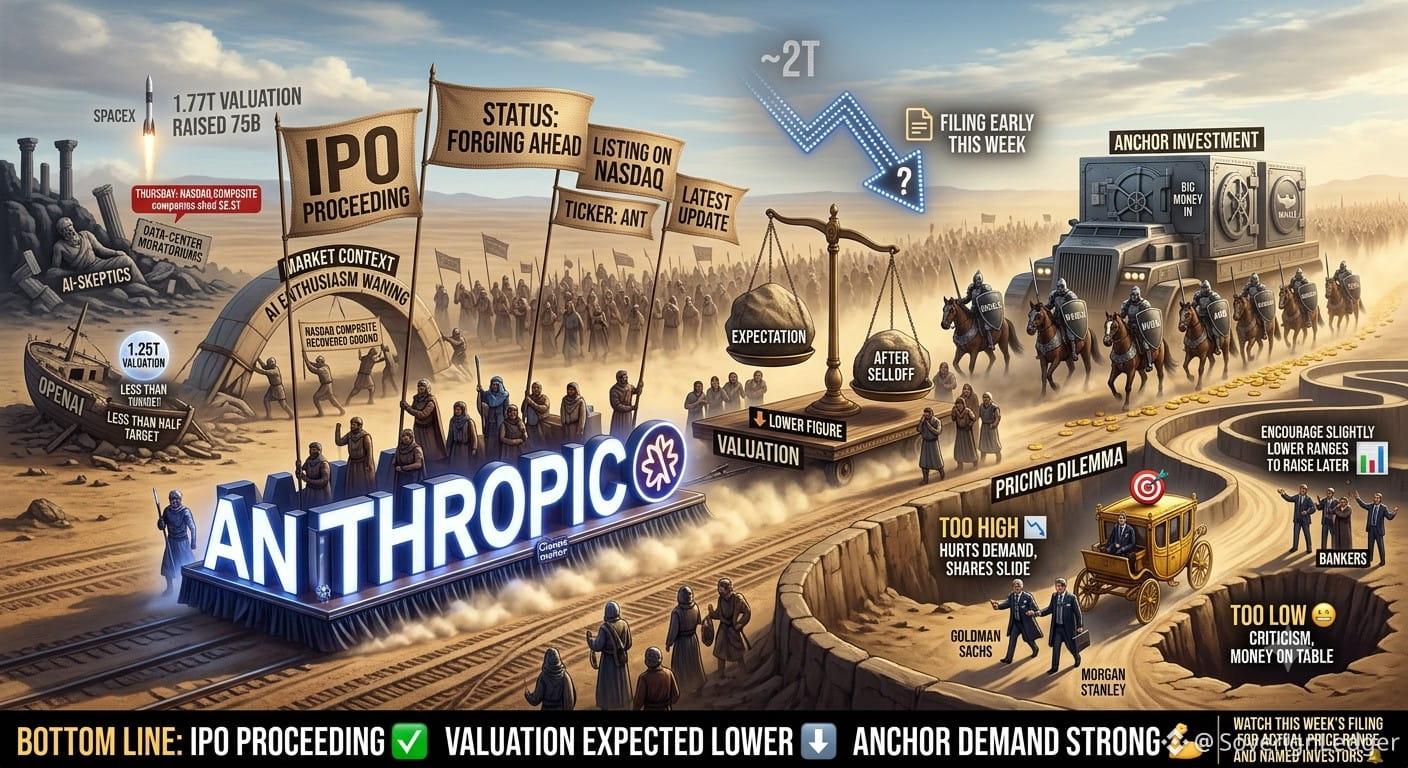
🚨ANTHROPIC IPO — UPDATE ($ANT) 🚨
Anthropic (Claude maker) is forging ahead with its IPO later this month, per WSJ. Investor meetings are lined up this week, with shares targeted to start trading Thursday or Friday next week. Listing on Nasdaq under ticker "ANT". 🏷️
Expected to be unveiled in a filing early this week 📄. A week ago investors anticipated ~$1.5T, but after Thursday's steep AI selloff, major investors are pushing for a lower figure ⬇️ (well below the ~$2T floated months ago).
Anchor investment — big money 💰:
Seven companies — Google, Nvidia, AMD, Broadcom, Micron, Microsoft, and TSMC — will invest $26B via private placement at the IPO price. Cornerstone investors will sell 23,333,331 shares in the IPO.
Deal size (earlier plan — pricing was later called "inaccurate" and filing to be updated) 👀:Raise: up to $69.3B,Price range: $70–$80 per share,Shares: 866,666,664 Class A shares
Context ⚠️:Nasdaq Composite has recovered ground, likely giving Anthropic confidence to push forward ✅
AI enthusiasm had been waning on concerns over investment scale & unclear payoff 📉
OpenAI raised less than half its target in its latest round, at a below-target $1.25T valuation
SpaceX's June offering valued it at ~$1.77T & raised ~$75B
Thursday: Nasdaq Composite companies shed $2.5T after midterms swept in AI-skeptics & passed data-center moratoriums 🏛️
Pricing dilemma for bankers (Goldman Sachs, Morgan Stanley) 🎯:
Too high → hurts investor demand, shares slide 📉
Too low → criticism of leaving money on the table 😬
Bankers sometimes encourage slightly lower ranges to raise later citing strong demand 📊
Bottom line: IPO proceeding ✅, valuation expected lower ⬇️, anchor demand strong 💪. Watch this week's filing for the actual price range & named investors 🔔
$NVDA $AMD $ANTHROPIC
#Anthropic #NASDAQ #CPITestsDecemberRateOutlook
1
2
817
·
--
Verified
Article
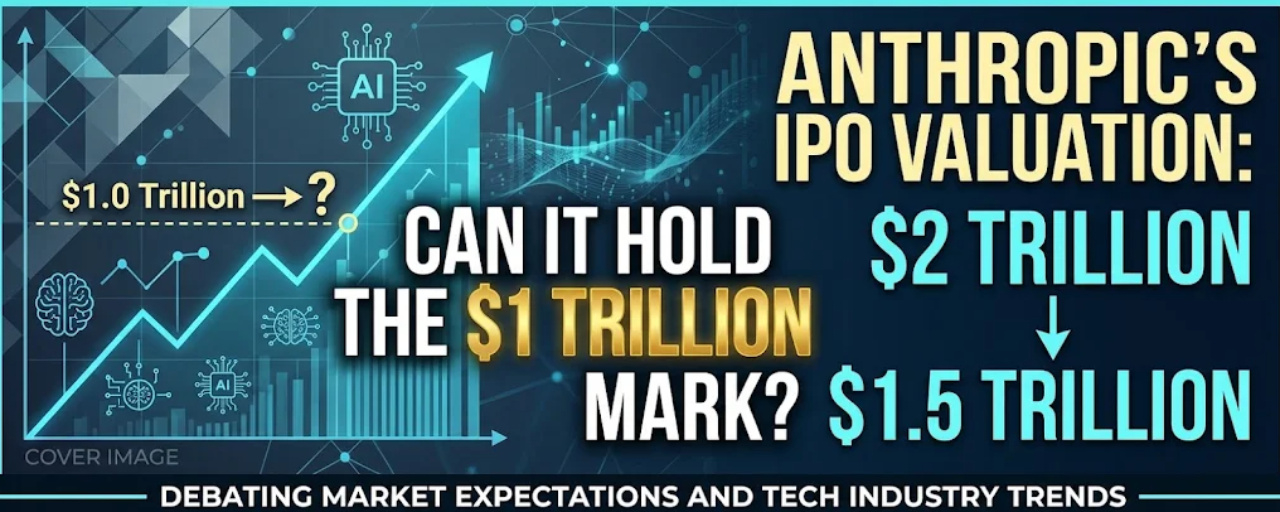
Anthropic IPO: 2T Hype Falls to 1.4T , Can It Hold 1 Trillion?Anthropic’s IPO valuation has retreated from the 2 trillion hype of early October to a priced range implying up to about 1.4 trillion on a fully diluted basis. On November 10, 2026, the Claude maker set an offering of 825 million Class A shares at 70–78 each, targeting trading on Nasdaq under the ticker ANT around November 19. The question now is whether the market will sustain even the psychological and practical 1 trillion floor.
The high end of the range produces a fully diluted valuation of roughly 1.404 trillion (including options and restricted stock). On a non-diluted basis of outstanding shares, the figure is closer to 1 trillion. Net proceeds from the IPO alone are expected in 57.75–64.35 billion range, with underwriters’ overallotment potentially adding more. Separately, Anthropic has arranged a 26 billion private placement of non-voting Class N shares at the IPO price to cornerstone investors including Google, Nvidia (10 billion each), AMD, Broadcom, Micron, Microsoft, and TSMC. Total capital raised could approach or exceed 90 billion.
#anthropicipo
This is a clear step down from the 1.5–2 trillion range investors and bankers were discussing in early-to-mid October, and from the 965 billion post-money valuation of the May 2026 Series H round. Market volatility after the U.S. midterms, a sharp AI-related tech sell-off, and closer scrutiny of Anthropic’s infrastructure commitments drove the reset. Some investors had already been talking about 1.2–1.3 trillion ranges even before the formal pricing.
Explosive Growth Meets Massive Commitments
Anthropic’s top-line expansion has been extraordinary. Full-year revenue rose from 41 million in 2023 to 386 million in 2024 and 4.6 billion in 2025. First-half 2026 revenue reached 16.3 billion. Third-quarter revenue hit about 17 billion (up 47% sequentially), and the company reported a run-rate of 81 billion by the end of October. Customer counts have scaled rapidly as well, with more than 11,900 accounts generating at least 100,000 in trailing-twelve-month revenue.
The growth comes with an enormous infrastructure bill. Filings disclose roughly 895 billion in aggregate purchase commitments and leases for compute and data centers (substantially all tied to AI capacity), with large portions expected before 2030 and the rest stretching into the 2040s. These include multi-year deals with Google, Amazon, Microsoft, and others. Some earlier reports referenced figures in the 500–750 billion range for longer-term compute plans. Net losses remain large (driven in part by non-cash valuation charges on convertibles), and operating margins have fluctuated as compute costs rise.
Context Among Historic IPOs
At the high end of the range, Anthropic’s capital raise would rank among the largest on record—behind SpaceX’s roughly 75–86 billion offering earlier in 2026 but well ahead of Saudi Aramco’s ~29.4 billion. SpaceX itself listed at a multi-trillion valuation; Anthropic is testing a similar scale in a more volatile environment for pure-play AI.
Can It Hold the 1Trillion Mark?
The pricing structure is designed to support it at the IPO. The 70–78 range was set after roadshow feedback and market turbulence. Cornerstone participation from major technology partners provides demand support and a signal of confidence in Anthropic’s compute access. Analysts such as Aswath Damodaran have published a base case near 1.5 trillion (with a wide range from effectively zero to over 4 trillion depending on margins, compute costs, and regulation). Morningstar’s base case has been around 1.7 trillion. At ~17–18x the latest run-rate revenue, the valuation is high but not unprecedented for a company growing at this pace in a secular AI wave.
Risks are material and could pressure the stock after listing. Key concerns include:
The sheer scale and rigidity of infrastructure commitments relative to current cash flow.Slowing sequential growth rates (Q3 sequential growth of ~47% versus much faster prior quarters).Competition from OpenAI, open-source models, and hyperscalers.Governance: Anthropic is a public benefit corporation. A Long-Term Benefit Trust holds Class T shares that elect a majority of the board (four of seven seats). Founders retain substantial voting influence via a separate Class F structure. Public Class A shareholders will have limited control, which some institutional investors view as a governance discount.Broader market conditions: AI-related stocks have been volatile, and a “junk” credit rating possibility has been discussed.
The trillion-dollar threshold is both psychological and practical. Some market participants have indicated that pricing below roughly 1 trillion on a basic-share basis could have led to a delay. With the range now set and cornerstone capital in place, the IPO is expected to proceed. Post-listing performance will depend on whether revenue continues to scale fast enough to absorb the infrastructure spend and whether the broader market re-rates AI favorably.
In short, Anthropic is likely to clear the 1 trillion mark at the IPO itself on a fully diluted basis and come close on basic shares. Sustaining or expanding beyond that level in the public market is a higher bar that will be tested by execution, compute economics, and investor risk appetite in the months after trading begins.
#Anthropic
{future}(ANTHROPICUSDT)
$ANTHROPIC
Anthropic IPO: 2T Hype Falls to 1.4T , Can It Hold 1 Trillion?
Anthropic’s IPO valuation has retreated from the 2 trillion hype of early October to a priced range implying up to about 1.4 trillion on a fully diluted basis. On November 10, 2026, the Claude maker set an offering of 825 million Class A shares at 70–78 each, targeting trading on Nasdaq under the ticker ANT around November 19. The question now is whether the market will sustain even the psychological and practical 1 trillion floor.
The high end of the range produces a fully diluted valuation of roughly 1.404 trillion (including options and restricted stock). On a non-diluted basis of outstanding shares, the figure is closer to 1 trillion. Net proceeds from the IPO alone are expected in 57.75–64.35 billion range, with underwriters’ overallotment potentially adding more. Separately, Anthropic has arranged a 26 billion private placement of non-voting Class N shares at the IPO price to cornerstone investors including Google, Nvidia (10 billion each), AMD, Broadcom, Micron, Microsoft, and TSMC. Total capital raised could approach or exceed 90 billion.
#anthropicipo
This is a clear step down from the 1.5–2 trillion range investors and bankers were discussing in early-to-mid October, and from the 965 billion post-money valuation of the May 2026 Series H round. Market volatility after the U.S. midterms, a sharp AI-related tech sell-off, and closer scrutiny of Anthropic’s infrastructure commitments drove the reset. Some investors had already been talking about 1.2–1.3 trillion ranges even before the formal pricing.
Explosive Growth Meets Massive Commitments
Anthropic’s top-line expansion has been extraordinary. Full-year revenue rose from 41 million in 2023 to 386 million in 2024 and 4.6 billion in 2025. First-half 2026 revenue reached 16.3 billion. Third-quarter revenue hit about 17 billion (up 47% sequentially), and the company reported a run-rate of 81 billion by the end of October. Customer counts have scaled rapidly as well, with more than 11,900 accounts generating at least 100,000 in trailing-twelve-month revenue.
The growth comes with an enormous infrastructure bill. Filings disclose roughly 895 billion in aggregate purchase commitments and leases for compute and data centers (substantially all tied to AI capacity), with large portions expected before 2030 and the rest stretching into the 2040s. These include multi-year deals with Google, Amazon, Microsoft, and others. Some earlier reports referenced figures in the 500–750 billion range for longer-term compute plans. Net losses remain large (driven in part by non-cash valuation charges on convertibles), and operating margins have fluctuated as compute costs rise.
Context Among Historic IPOs
At the high end of the range, Anthropic’s capital raise would rank among the largest on record—behind SpaceX’s roughly 75–86 billion offering earlier in 2026 but well ahead of Saudi Aramco’s ~29.4 billion. SpaceX itself listed at a multi-trillion valuation; Anthropic is testing a similar scale in a more volatile environment for pure-play AI.
Can It Hold the 1Trillion Mark?
The pricing structure is designed to support it at the IPO. The 70–78 range was set after roadshow feedback and market turbulence. Cornerstone participation from major technology partners provides demand support and a signal of confidence in Anthropic’s compute access. Analysts such as Aswath Damodaran have published a base case near 1.5 trillion (with a wide range from effectively zero to over 4 trillion depending on margins, compute costs, and regulation). Morningstar’s base case has been around 1.7 trillion. At ~17–18x the latest run-rate revenue, the valuation is high but not unprecedented for a company growing at this pace in a secular AI wave.
Risks are material and could pressure the stock after listing. Key concerns include:
The sheer scale and rigidity of infrastructure commitments relative to current cash flow.Slowing sequential growth rates (Q3 sequential growth of ~47% versus much faster prior quarters).Competition from OpenAI, open-source models, and hyperscalers.Governance: Anthropic is a public benefit corporation. A Long-Term Benefit Trust holds Class T shares that elect a majority of the board (four of seven seats). Founders retain substantial voting influence via a separate Class F structure. Public Class A shareholders will have limited control, which some institutional investors view as a governance discount.Broader market conditions: AI-related stocks have been volatile, and a “junk” credit rating possibility has been discussed.
The trillion-dollar threshold is both psychological and practical. Some market participants have indicated that pricing below roughly 1 trillion on a basic-share basis could have led to a delay. With the range now set and cornerstone capital in place, the IPO is expected to proceed. Post-listing performance will depend on whether revenue continues to scale fast enough to absorb the infrastructure spend and whether the broader market re-rates AI favorably.
In short, Anthropic is likely to clear the 1 trillion mark at the IPO itself on a fully diluted basis and come close on basic shares. Sustaining or expanding beyond that level in the public market is a higher bar that will be tested by execution, compute economics, and investor risk appetite in the months after trading begins.
#Anthropic
$ANTHROPIC
The high end of the range produces a fully diluted valuation of roughly 1.404 trillion (including options and restricted stock). On a non-diluted basis of outstanding shares, the figure is closer to 1 trillion. Net proceeds from the IPO alone are expected in 57.75–64.35 billion range, with underwriters’ overallotment potentially adding more. Separately, Anthropic has arranged a 26 billion private placement of non-voting Class N shares at the IPO price to cornerstone investors including Google, Nvidia (10 billion each), AMD, Broadcom, Micron, Microsoft, and TSMC. Total capital raised could approach or exceed 90 billion.
#anthropicipo
This is a clear step down from the 1.5–2 trillion range investors and bankers were discussing in early-to-mid October, and from the 965 billion post-money valuation of the May 2026 Series H round. Market volatility after the U.S. midterms, a sharp AI-related tech sell-off, and closer scrutiny of Anthropic’s infrastructure commitments drove the reset. Some investors had already been talking about 1.2–1.3 trillion ranges even before the formal pricing.
Explosive Growth Meets Massive Commitments
Anthropic’s top-line expansion has been extraordinary. Full-year revenue rose from 41 million in 2023 to 386 million in 2024 and 4.6 billion in 2025. First-half 2026 revenue reached 16.3 billion. Third-quarter revenue hit about 17 billion (up 47% sequentially), and the company reported a run-rate of 81 billion by the end of October. Customer counts have scaled rapidly as well, with more than 11,900 accounts generating at least 100,000 in trailing-twelve-month revenue.
The growth comes with an enormous infrastructure bill. Filings disclose roughly 895 billion in aggregate purchase commitments and leases for compute and data centers (substantially all tied to AI capacity), with large portions expected before 2030 and the rest stretching into the 2040s. These include multi-year deals with Google, Amazon, Microsoft, and others. Some earlier reports referenced figures in the 500–750 billion range for longer-term compute plans. Net losses remain large (driven in part by non-cash valuation charges on convertibles), and operating margins have fluctuated as compute costs rise.
Context Among Historic IPOs
At the high end of the range, Anthropic’s capital raise would rank among the largest on record—behind SpaceX’s roughly 75–86 billion offering earlier in 2026 but well ahead of Saudi Aramco’s ~29.4 billion. SpaceX itself listed at a multi-trillion valuation; Anthropic is testing a similar scale in a more volatile environment for pure-play AI.
Can It Hold the 1Trillion Mark?
The pricing structure is designed to support it at the IPO. The 70–78 range was set after roadshow feedback and market turbulence. Cornerstone participation from major technology partners provides demand support and a signal of confidence in Anthropic’s compute access. Analysts such as Aswath Damodaran have published a base case near 1.5 trillion (with a wide range from effectively zero to over 4 trillion depending on margins, compute costs, and regulation). Morningstar’s base case has been around 1.7 trillion. At ~17–18x the latest run-rate revenue, the valuation is high but not unprecedented for a company growing at this pace in a secular AI wave.
Risks are material and could pressure the stock after listing. Key concerns include:
The sheer scale and rigidity of infrastructure commitments relative to current cash flow.Slowing sequential growth rates (Q3 sequential growth of ~47% versus much faster prior quarters).Competition from OpenAI, open-source models, and hyperscalers.Governance: Anthropic is a public benefit corporation. A Long-Term Benefit Trust holds Class T shares that elect a majority of the board (four of seven seats). Founders retain substantial voting influence via a separate Class F structure. Public Class A shareholders will have limited control, which some institutional investors view as a governance discount.Broader market conditions: AI-related stocks have been volatile, and a “junk” credit rating possibility has been discussed.
The trillion-dollar threshold is both psychological and practical. Some market participants have indicated that pricing below roughly 1 trillion on a basic-share basis could have led to a delay. With the range now set and cornerstone capital in place, the IPO is expected to proceed. Post-listing performance will depend on whether revenue continues to scale fast enough to absorb the infrastructure spend and whether the broader market re-rates AI favorably.
In short, Anthropic is likely to clear the 1 trillion mark at the IPO itself on a fully diluted basis and come close on basic shares. Sustaining or expanding beyond that level in the public market is a higher bar that will be tested by execution, compute economics, and investor risk appetite in the months after trading begins.
#Anthropic
$ANTHROPIC
786 隐狼:
Solid breakdown 👏 One line worth pulling to the front: even the cornerstone investors — Google, Nvidia, Microsoft — took non-voting shares. If the biggest checks don’t get a vote, retail at $70+ definitely won’t. Almost makes the valuation debate secondary — you’re betting on a number you’ll never get to defend. How much does the no-vote structure weigh in your own call?
2
7
1.6k
·
--
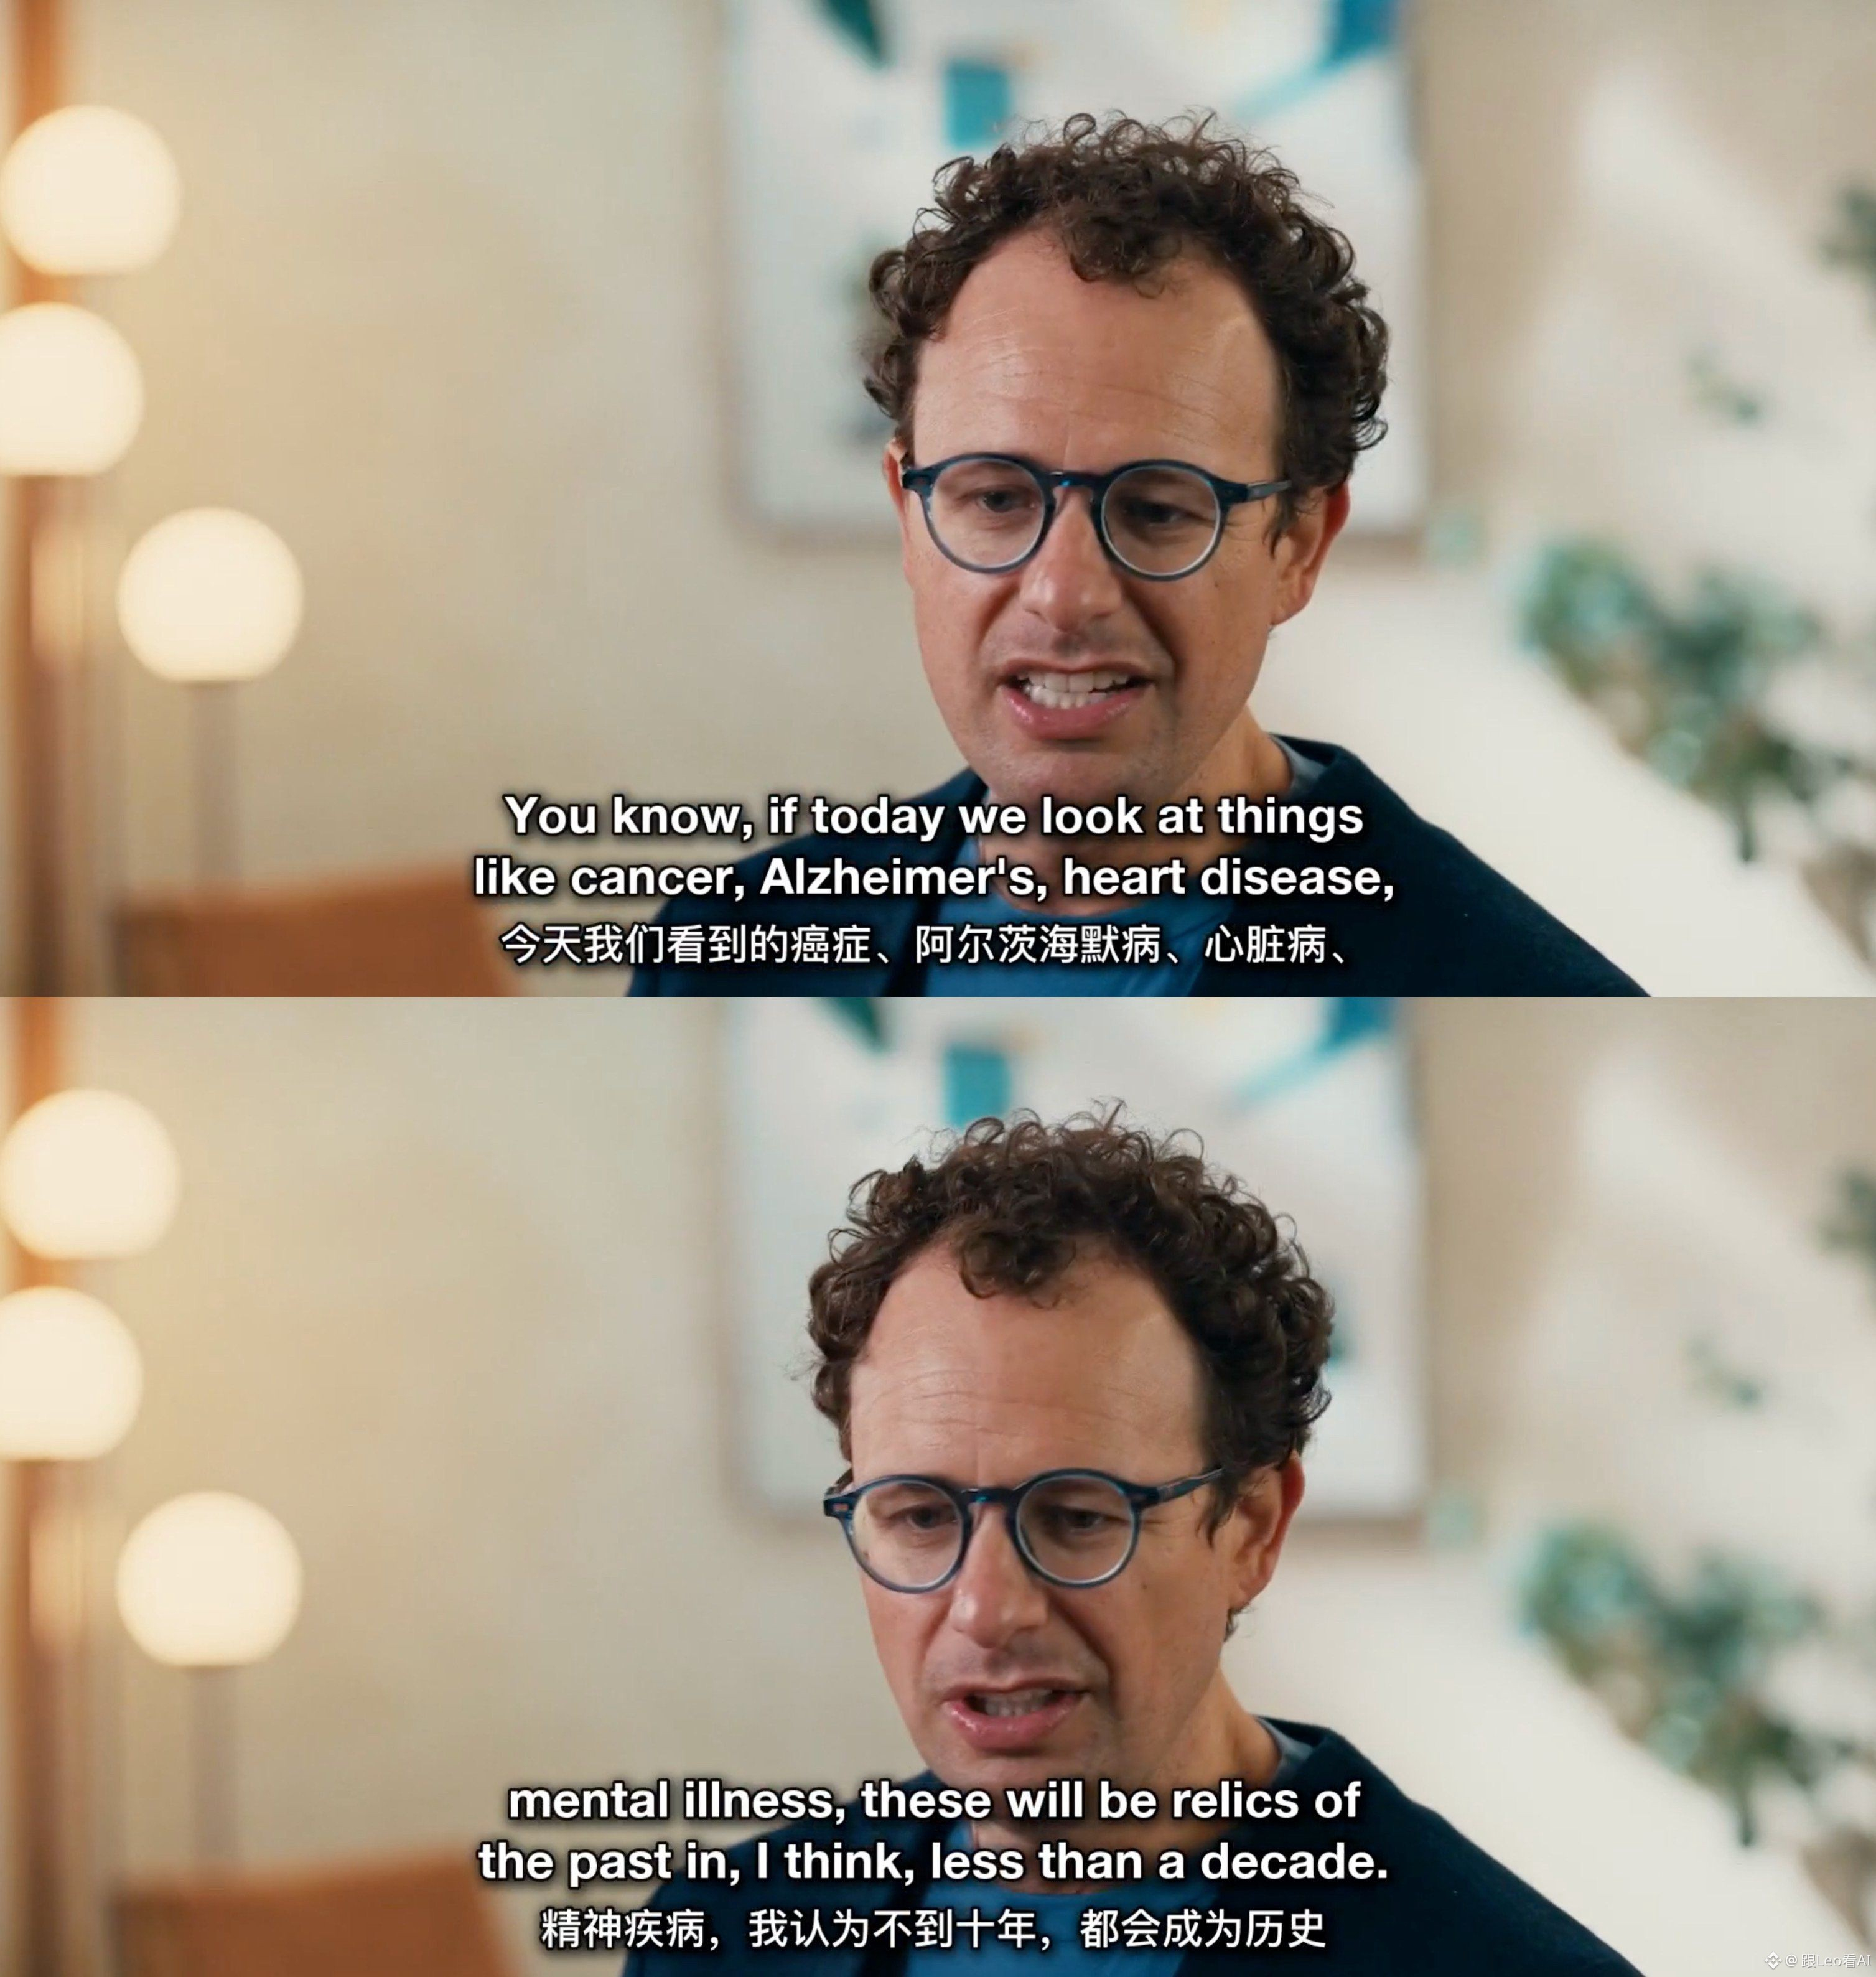
卧槽!!!Dario放话了:不到10年,要让癌症、阿尔茨海默病成为历史!如果是这样,那AI真的是要造福人类了!!!🐮🐮
Anthropic路演视频里,CFO给出的数字:
-Q3营收近170亿美元,同比增长12倍
-今年前三季度毛利率85%,和美光最新一季基本持平
-工程师人均代码量是2024年的45倍
(个人看法:码农真的是夕阳产业,大科技公司还有很大的裁员空间)
-人均营收从140万美元升到660万美元以上
按路演的说法,现在赚的钱只是冰山一角。Dario也很聪明地跳出了AI到底是不是泡沫的证明框架,把赌注推到“终结人类千年疾病、重构物理世界科学”的维度,让这场资本游戏继续运转下去。
只要它真能把哪怕一种绝症的攻克时间缩短几年,这场烧掉人类数千亿资金的豪赌,最终都会被历史原谅。
Dario最好说道"如果我们做对了,就能开创一个奇迹时代" #Anthropic拒绝延期IPO,本周路演估值几何? #Anthropic
卧槽!!!Dario放话了:不到10年,要让癌症、阿尔茨海默病成为历史!如果是这样,那AI真的是要造福人类了!!!🐮🐮
Anthropic路演视频里,CFO给出的数字:
-Q3营收近170亿美元,同比增长12倍
-今年前三季度毛利率85%,和美光最新一季基本持平
-工程师人均代码量是2024年的45倍
(个人看法:码农真的是夕阳产业,大科技公司还有很大的裁员空间)
-人均营收从140万美元升到660万美元以上
按路演的说法,现在赚的钱只是冰山一角。Dario也很聪明地跳出了AI到底是不是泡沫的证明框架,把赌注推到“终结人类千年疾病、重构物理世界科学”的维度,让这场资本游戏继续运转下去。
只要它真能把哪怕一种绝症的攻克时间缩短几年,这场烧掉人类数千亿资金的豪赌,最终都会被历史原谅。
Dario最好说道"如果我们做对了,就能开创一个奇迹时代" #Anthropic拒绝延期IPO,本周路演估值几何? #Anthropic
Anthropic路演视频里,CFO给出的数字:
-Q3营收近170亿美元,同比增长12倍
-今年前三季度毛利率85%,和美光最新一季基本持平
-工程师人均代码量是2024年的45倍
(个人看法:码农真的是夕阳产业,大科技公司还有很大的裁员空间)
-人均营收从140万美元升到660万美元以上
按路演的说法,现在赚的钱只是冰山一角。Dario也很聪明地跳出了AI到底是不是泡沫的证明框架,把赌注推到“终结人类千年疾病、重构物理世界科学”的维度,让这场资本游戏继续运转下去。
只要它真能把哪怕一种绝症的攻克时间缩短几年,这场烧掉人类数千亿资金的豪赌,最终都会被历史原谅。
Dario最好说道"如果我们做对了,就能开创一个奇迹时代" #Anthropic拒绝延期IPO,本周路演估值几何? #Anthropic
Feed-Creator-a023ec0dd:
这不是好事情。权贵阶层会更加努力压榨穷人
2
1
7
5.6k
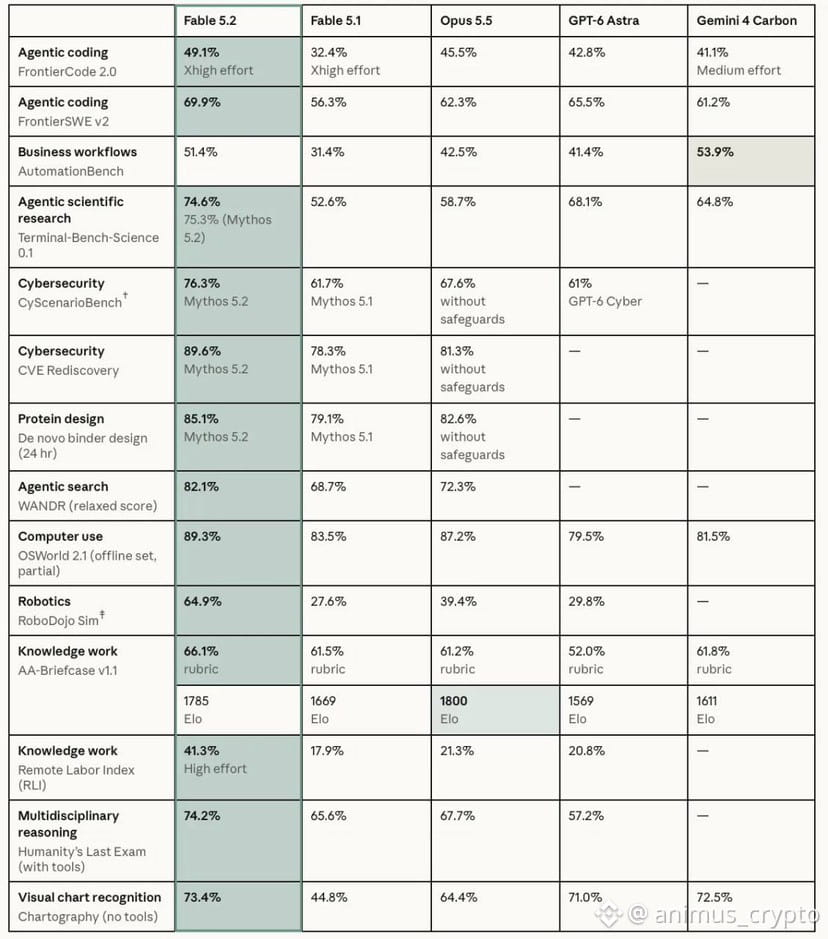
⚠️ Anthropic launched Claude Fable 5.2 and Mythos 5.2.
The new models run up to 30% faster than their predecessors and outperform Opus 5.5 on most of Anthropic’s internal benchmarks.
Fable 5.2 is available to all users, while Mythos 5.2 is limited to vetted organizations.
#Anthropic #AI $BTC
⚠️ Anthropic launched Claude Fable 5.2 and Mythos 5.2.
The new models run up to 30% faster than their predecessors and outperform Opus 5.5 on most of Anthropic’s internal benchmarks.
Fable 5.2 is available to all users, while Mythos 5.2 is limited to vetted organizations.
#Anthropic #AI $BTC
The new models run up to 30% faster than their predecessors and outperform Opus 5.5 on most of Anthropic’s internal benchmarks.
Fable 5.2 is available to all users, while Mythos 5.2 is limited to vetted organizations.
#Anthropic #AI $BTC
122
·
--
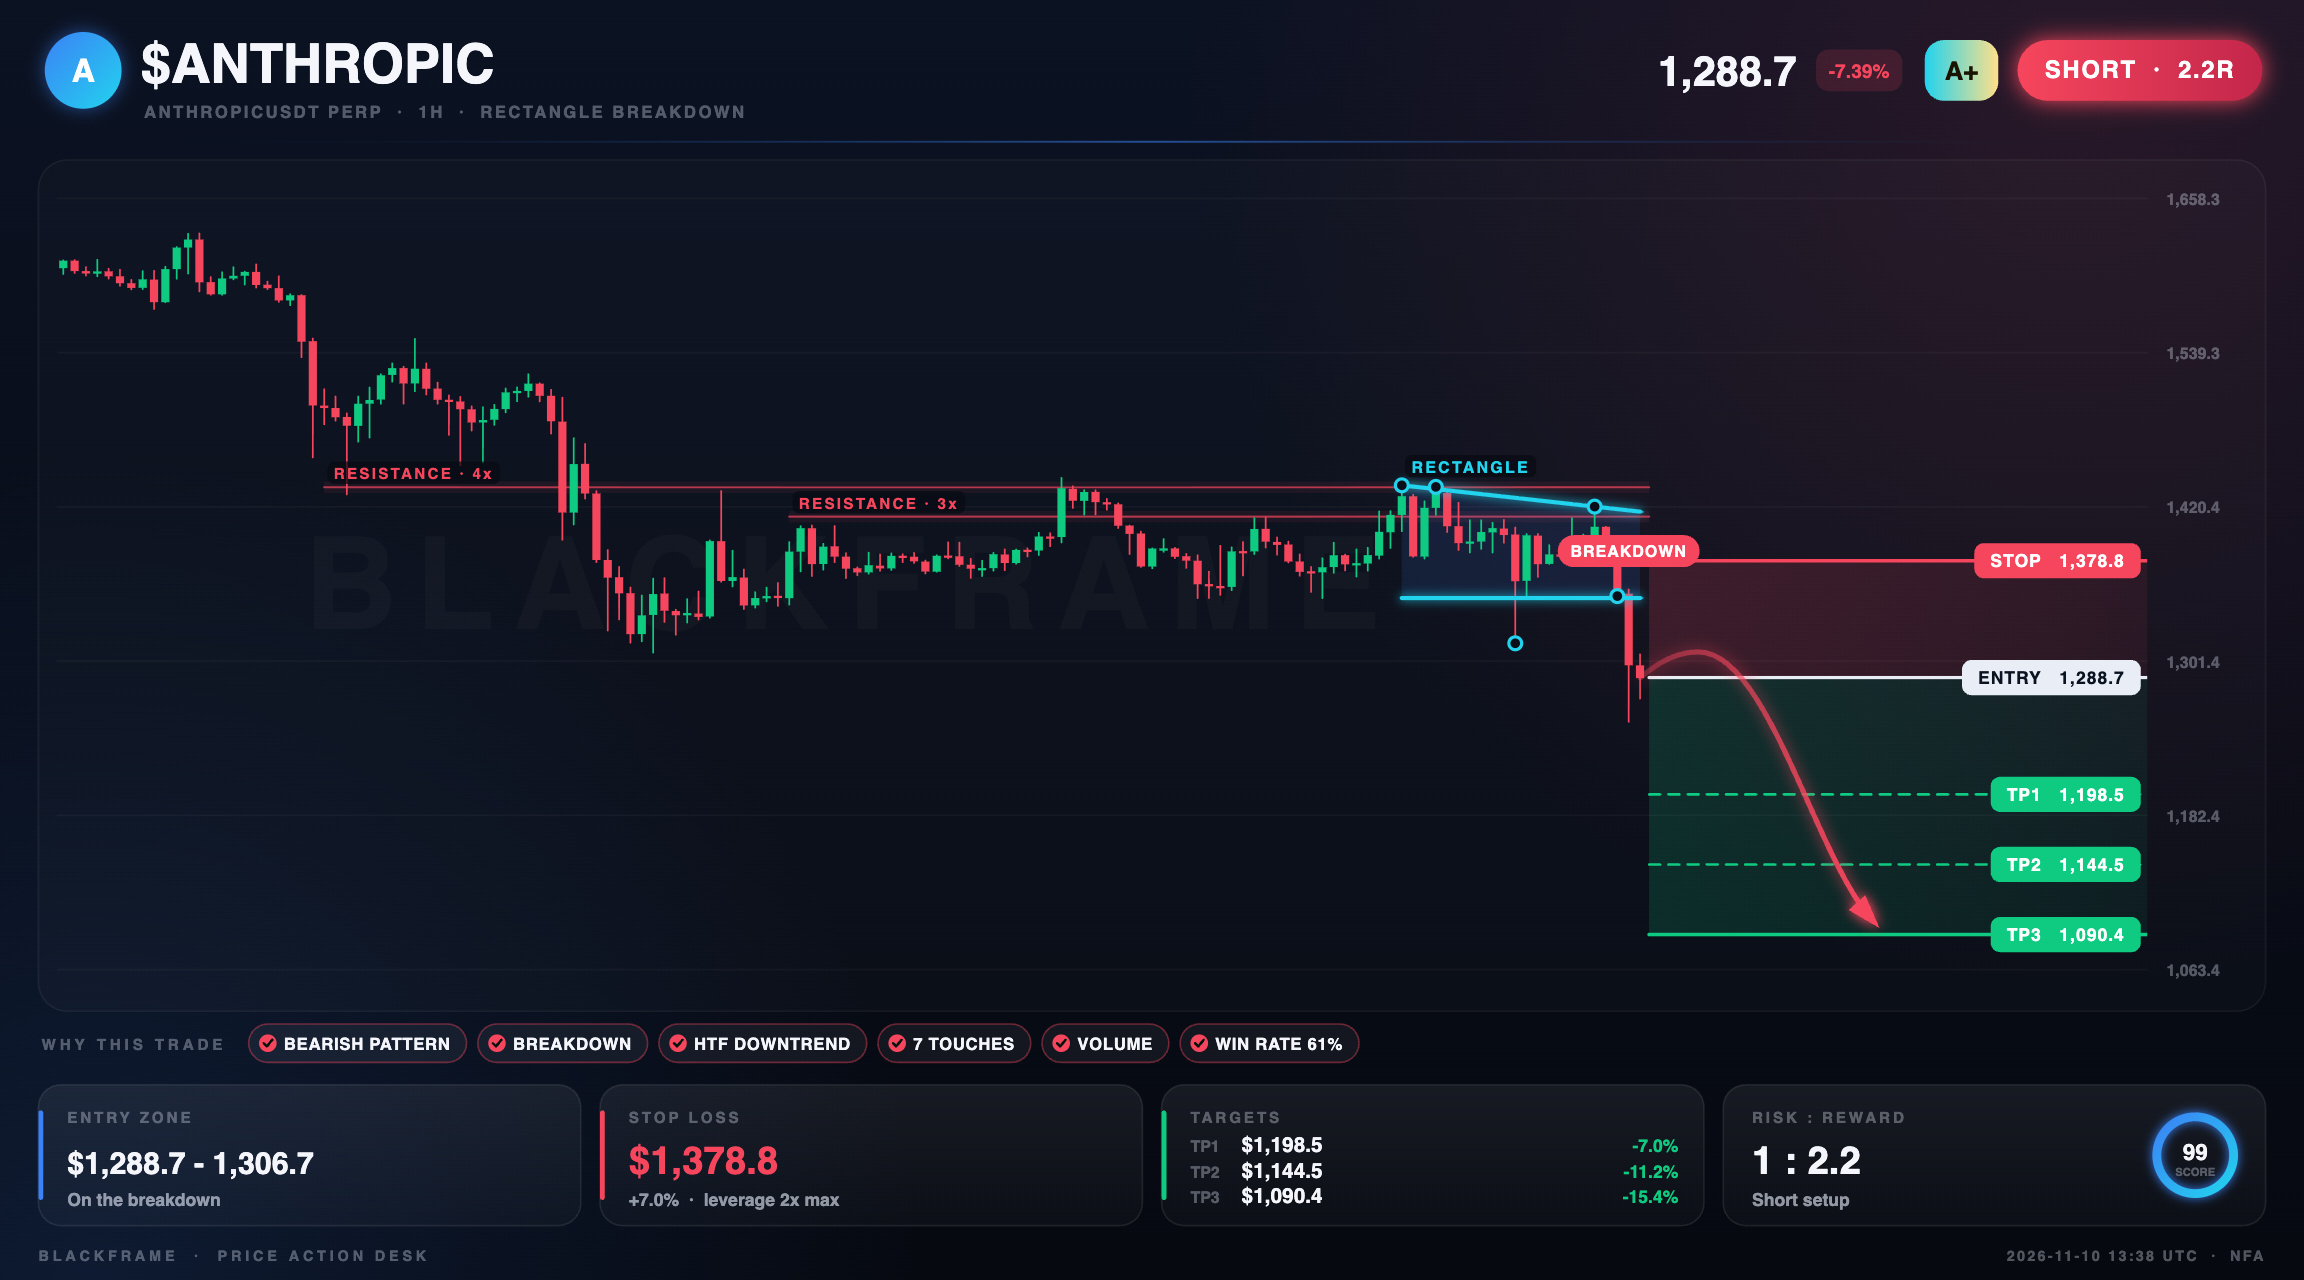
🩸 $ANTHROPIC just lost the floor
SHORT · 1H
Entry: $1,288.7 - $1,311.2
TP1: $1,198.5
TP2: $1,144.5
TP3: $1,090.4
SL: $1,378.8
A rectangle has formed on the 1H, tested 7 times on its lines. Price broke down below the pattern and is holding. The higher timeframe trend agrees, and the target is the measured move of the pattern.
#ANTHROPIC #PriceAction #Binance · NFA
🩸 $ANTHROPIC just lost the floor
SHORT · 1H
Entry: $1,288.7 - $1,311.2
TP1: $1,198.5
TP2: $1,144.5
TP3: $1,090.4
SL: $1,378.8
A rectangle has formed on the 1H, tested 7 times on its lines. Price broke down below the pattern and is holding. The higher timeframe trend agrees, and the target is the measured move of the pattern.
#ANTHROPIC #PriceAction #Binance · NFA
SHORT · 1H
Entry: $1,288.7 - $1,311.2
TP1: $1,198.5
TP2: $1,144.5
TP3: $1,090.4
SL: $1,378.8
A rectangle has formed on the 1H, tested 7 times on its lines. Price broke down below the pattern and is holding. The higher timeframe trend agrees, and the target is the measured move of the pattern.
#ANTHROPIC #PriceAction #Binance · NFA
2
·
--
🚨 AI's Biggest Moment Is Here!
#AnthropicIPO is making headlines as Anthropic takes a major step toward becoming a publicly traded company. This move could attract fresh capital, boost confidence in the AI sector, and increase investor interest across the market.
The IPO is still awaiting regulatory approval, but it's already one of the most closely watched events in the AI industry. Keep this on your radar—this could be a defining moment for the future of artificial intelligence.
What's your take? Bullish on AI? 👇
$ANTHROPIC
{future}(ANTHROPICUSDT)
#Anthropic #IPO #CryptoNews
🚨 AI's Biggest Moment Is Here!
#AnthropicIPO is making headlines as Anthropic takes a major step toward becoming a publicly traded company. This move could attract fresh capital, boost confidence in the AI sector, and increase investor interest across the market.
The IPO is still awaiting regulatory approval, but it's already one of the most closely watched events in the AI industry. Keep this on your radar—this could be a defining moment for the future of artificial intelligence.
What's your take? Bullish on AI? 👇
$ANTHROPIC
#Anthropic #IPO #CryptoNews
#AnthropicIPO is making headlines as Anthropic takes a major step toward becoming a publicly traded company. This move could attract fresh capital, boost confidence in the AI sector, and increase investor interest across the market.
The IPO is still awaiting regulatory approval, but it's already one of the most closely watched events in the AI industry. Keep this on your radar—this could be a defining moment for the future of artificial intelligence.
What's your take? Bullish on AI? 👇
$ANTHROPIC
#Anthropic #IPO #CryptoNews
1
153
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#HotCPIDecemberHikePriced
134,613 views
1,529 Discussing
2
#AnthropicRejectsIPODelayValuationinQuestion
251,190 views
2,126 Discussing
3
#CanNvidiaEarningsEaseMarketConcerns?
48,698 views
699 Discussing
4
#BitcoinFiveWeeklyLosses
591,806 views
3,638 Discussing
5
#TrumpMediaAdds1510BTCInQ3
23,602 views
238 Discussing
6
#TradFiForBeginners
447,323 views
2,942 Discussing
7
#NvidiaInvestigatesAfterHuang’sAffairApology
551,488 views
3,315 Discussing
8
#ADPWeeklyEstimateShowsUSPrivatePayrollsUp19750
21,405 views
323 Discussing
9
#BitcoinSpotETFsPost$201MNetOutflowForThirdStraightDay
3,334 views
39 Discussing
10
#CryptoLiquidationsReach$1.16BIn24Hours
85,442 views
89 Discussing