
美股投资young
77 Posts

美股投资young
Report
Block User
美股科技投资者 ai狂热者 分享每日快讯
all in AI
10 Following
328 Followers
32 Liked
Posts
Portfolio
·
--
I now feel that the Democrats may be trying to destroy Trump's record.
At the moment, Trump's biggest achievement—one he keeps boasting about—is the AI boom and bull market in stocks during his term. $QQQ $SPY $SOXX
I feel they haven't changed their tune yet, and even if they do in the future, it won't happen that quickly. It would be hard to end things well without achieving their goal.
#美股 #AI #Midterm Elections
I now feel that the Democrats may be trying to destroy Trump's record.
At the moment, Trump's biggest achievement—one he keeps boasting about—is the AI boom and bull market in stocks during his term. $QQQ $SPY $SOXX
I feel they haven't changed their tune yet, and even if they do in the future, it won't happen that quickly. It would be hard to end things well without achieving their goal.
#美股 #AI #Midterm Elections
At the moment, Trump's biggest achievement—one he keeps boasting about—is the AI boom and bull market in stocks during his term. $QQQ $SPY $SOXX
I feel they haven't changed their tune yet, and even if they do in the future, it won't happen that quickly. It would be hard to end things well without achieving their goal.
#美股 #AI #Midterm Elections
167
·
--
The last CPI report before the December rate decision is out, and the 10-year yield has touched 4.99%Tonight’s CPI report is the last one before the December FOMC meeting.
The schedule is right there: the Fed announces its decision on December 9, and November’s CPI won’t be released until December 10, a day after the meeting. So tonight’s 0.4% headline figure and 0.3% core figure will basically be the latest inflation data the Fed has in hand when it meets. There’s also a PPI report on Friday, but it carries much less weight.
The market reaction was immediate.
The 10-year Treasury yield touched 4.99% intraday, just one basis point shy of 5%. Around 11 a.m. Eastern, the Nasdaq was down 0.76%, the S&P 500 was down 0.63%, and the VIX had climbed back above 20. To be honest, those losses aren’t that big. The S&P 500 had just posted its best day since April on Monday, so a bit of a pullback is perfectly normal.
The last CPI report before the December rate decision is out, and the 10-year yield has touched 4.99%
Tonight’s CPI report is the last one before the December FOMC meeting.
The schedule is right there: the Fed announces its decision on December 9, and November’s CPI won’t be released until December 10, a day after the meeting. So tonight’s 0.4% headline figure and 0.3% core figure will basically be the latest inflation data the Fed has in hand when it meets. There’s also a PPI report on Friday, but it carries much less weight.
The market reaction was immediate.
The 10-year Treasury yield touched 4.99% intraday, just one basis point shy of 5%. Around 11 a.m. Eastern, the Nasdaq was down 0.76%, the S&P 500 was down 0.63%, and the VIX had climbed back above 20. To be honest, those losses aren’t that big. The S&P 500 had just posted its best day since April on Monday, so a bit of a pullback is perfectly normal.
The schedule is right there: the Fed announces its decision on December 9, and November’s CPI won’t be released until December 10, a day after the meeting. So tonight’s 0.4% headline figure and 0.3% core figure will basically be the latest inflation data the Fed has in hand when it meets. There’s also a PPI report on Friday, but it carries much less weight.
The market reaction was immediate.
The 10-year Treasury yield touched 4.99% intraday, just one basis point shy of 5%. Around 11 a.m. Eastern, the Nasdaq was down 0.76%, the S&P 500 was down 0.63%, and the VIX had climbed back above 20. To be honest, those losses aren’t that big. The S&P 500 had just posted its best day since April on Monday, so a bit of a pullback is perfectly normal.
225
·
--
South Korean retail investors net sold 1.34 trillion won today.
And this was the very day the KOSPI rose 4.39%. The market open immediately triggered a buy-side sidecar, and foreign investors turned net buyers for the first time in eight trading days, while retail investors were dumping shares.
SK Hynix closed at 1.212 million won, up 6.69%. It fell 20.16% last week, then clawed back a little over 7% in two days this week. Samsung was down 16% last week and is up 4.74% today.
Put simply, the people who dumped memory stocks last week have come back over the past two days—and they’re rushing back even faster than they left.
On Wall Street, $MU rose 6.25% last night, and the Philadelphia Semiconductor Index gained 6.85%. The memory-stock sector has bounced back from AI capex worries much faster than I expected. But I’m not convinced this is a reversal. A two-day rebound can’t repair a 20% hole from a single week, and Hynix is still a long way below last week’s high. If tonight’s CPI comes in hot, high-beta stocks like these will be among the first to get sold.
One more thing: BTC was stuck at 74,000 all day. South Korean retail investors used to be among the most aggressive players in crypto, but the money they made selling stocks today doesn’t seem to have flowed into crypto either.
#存储芯片 #美股 #CPI $MU $BTC
South Korean retail investors net sold 1.34 trillion won today.
And this was the very day the KOSPI rose 4.39%. The market open immediately triggered a buy-side sidecar, and foreign investors turned net buyers for the first time in eight trading days, while retail investors were dumping shares.
SK Hynix closed at 1.212 million won, up 6.69%. It fell 20.16% last week, then clawed back a little over 7% in two days this week. Samsung was down 16% last week and is up 4.74% today.
Put simply, the people who dumped memory stocks last week have come back over the past two days—and they’re rushing back even faster than they left.
On Wall Street, $MU rose 6.25% last night, and the Philadelphia Semiconductor Index gained 6.85%. The memory-stock sector has bounced back from AI capex worries much faster than I expected. But I’m not convinced this is a reversal. A two-day rebound can’t repair a 20% hole from a single week, and Hynix is still a long way below last week’s high. If tonight’s CPI comes in hot, high-beta stocks like these will be among the first to get sold.
One more thing: BTC was stuck at 74,000 all day. South Korean retail investors used to be among the most aggressive players in crypto, but the money they made selling stocks today doesn’t seem to have flowed into crypto either.
#存储芯片 #美股 #CPI $MU $BTC
And this was the very day the KOSPI rose 4.39%. The market open immediately triggered a buy-side sidecar, and foreign investors turned net buyers for the first time in eight trading days, while retail investors were dumping shares.
SK Hynix closed at 1.212 million won, up 6.69%. It fell 20.16% last week, then clawed back a little over 7% in two days this week. Samsung was down 16% last week and is up 4.74% today.
Put simply, the people who dumped memory stocks last week have come back over the past two days—and they’re rushing back even faster than they left.
On Wall Street, $MU rose 6.25% last night, and the Philadelphia Semiconductor Index gained 6.85%. The memory-stock sector has bounced back from AI capex worries much faster than I expected. But I’m not convinced this is a reversal. A two-day rebound can’t repair a 20% hole from a single week, and Hynix is still a long way below last week’s high. If tonight’s CPI comes in hot, high-beta stocks like these will be among the first to get sold.
One more thing: BTC was stuck at 74,000 all day. South Korean retail investors used to be among the most aggressive players in crypto, but the money they made selling stocks today doesn’t seem to have flowed into crypto either.
#存储芯片 #美股 #CPI $MU $BTC
2
343
·
--
Holy crap, Waller came right out today and said a December rate hike is likely, and casually mentioned it could even be 50 bps.
A Fed governor said it himself—and before the CPI report is out.
What’s even crazier is the premarket reaction. Dow futures are still up around 0.3%, S&P futures are slightly higher too, and only Nasdaq futures are down 0.2%. It’s as if everyone’s already accepted it: rate futures put the odds of a 25-bp hike in December at 82% to 84%, up from just 74% a week ago. The 2-year Treasury yield is at 4.58%.
So tonight, what I’ll mainly be watching in the CPI report is whether the market takes that 50-bp possibility seriously. The forecast is 0.3% headline and 0.2% core. If core comes in at 0.3% or even 0.4%, I think the S&P’s biggest one-day rally since April yesterday will probably give back half its gains.
BTC is now just above $74,000, barely moved all day, like it’s waiting for the same number. Honestly, lately it seems more focused on the 2-year yield than anything else—it can’t even be bothered to follow the Nasdaq higher.
9:30 p.m. Beijing time, 8:30 a.m. EST. Less than two hours to go.
#美联储 #CPI #美股 $BTC
Holy crap, Waller came right out today and said a December rate hike is likely, and casually mentioned it could even be 50 bps.
A Fed governor said it himself—and before the CPI report is out.
What’s even crazier is the premarket reaction. Dow futures are still up around 0.3%, S&P futures are slightly higher too, and only Nasdaq futures are down 0.2%. It’s as if everyone’s already accepted it: rate futures put the odds of a 25-bp hike in December at 82% to 84%, up from just 74% a week ago. The 2-year Treasury yield is at 4.58%.
So tonight, what I’ll mainly be watching in the CPI report is whether the market takes that 50-bp possibility seriously. The forecast is 0.3% headline and 0.2% core. If core comes in at 0.3% or even 0.4%, I think the S&P’s biggest one-day rally since April yesterday will probably give back half its gains.
BTC is now just above $74,000, barely moved all day, like it’s waiting for the same number. Honestly, lately it seems more focused on the 2-year yield than anything else—it can’t even be bothered to follow the Nasdaq higher.
9:30 p.m. Beijing time, 8:30 a.m. EST. Less than two hours to go.
#美联储 #CPI #美股 $BTC
A Fed governor said it himself—and before the CPI report is out.
What’s even crazier is the premarket reaction. Dow futures are still up around 0.3%, S&P futures are slightly higher too, and only Nasdaq futures are down 0.2%. It’s as if everyone’s already accepted it: rate futures put the odds of a 25-bp hike in December at 82% to 84%, up from just 74% a week ago. The 2-year Treasury yield is at 4.58%.
So tonight, what I’ll mainly be watching in the CPI report is whether the market takes that 50-bp possibility seriously. The forecast is 0.3% headline and 0.2% core. If core comes in at 0.3% or even 0.4%, I think the S&P’s biggest one-day rally since April yesterday will probably give back half its gains.
BTC is now just above $74,000, barely moved all day, like it’s waiting for the same number. Honestly, lately it seems more focused on the 2-year yield than anything else—it can’t even be bothered to follow the Nasdaq higher.
9:30 p.m. Beijing time, 8:30 a.m. EST. Less than two hours to go.
#美联储 #CPI #美股 $BTC
166
·
--
In 2023, they said this car would sell 250,000 units a year. Last year, it sold 20,237 in the U.S.
Cybertruck is being discontinued. Musk posted it himself last Friday: the Texas factory will likely wind down the production line around mid-2027 to make room to expand Cybercab production.
Honestly, there were signs this was coming. Cybertruck sales in the U.S. were down 48% year over year last year. In Tesla’s third-quarter earnings report this year, “other models” beyond the Model 3 and Model Y accounted for just 8,295 deliveries—and that includes the Model S and X.
The market reaction is pretty interesting: almost nobody cares.
That’s because Tesla’s valuation hasn’t been based on car sales for a long time. Stories like Cybercab and Optimus are what prop up that PE, so whether Cybertruck stays in production has little impact on the model. The problem is that Cybercab has its own issues: in September, the NHTSA opened an investigation into how that batch of roughly 1,000 cars with no steering wheels or pedals met federal safety standards.
A product that can’t sell is making way for one that’s still under regulatory scrutiny.
One more thing: of Tesla’s $787 million in net income for the third quarter, $288 million came from BTC’s paper gains. BTC was still around $83,600 at the end of September; now it’s at $74,800. In the fourth quarter, some of those gains will likely be wiped out. Car sales are struggling, and crypto is falling too. I’m not feeling very optimistic about the profit line in the next earnings report.
#特斯拉 #Cybertruck #美股 #BTC
$TSLA $BTC
In 2023, they said this car would sell 250,000 units a year. Last year, it sold 20,237 in the U.S.
Cybertruck is being discontinued. Musk posted it himself last Friday: the Texas factory will likely wind down the production line around mid-2027 to make room to expand Cybercab production.
Honestly, there were signs this was coming. Cybertruck sales in the U.S. were down 48% year over year last year. In Tesla’s third-quarter earnings report this year, “other models” beyond the Model 3 and Model Y accounted for just 8,295 deliveries—and that includes the Model S and X.
The market reaction is pretty interesting: almost nobody cares.
That’s because Tesla’s valuation hasn’t been based on car sales for a long time. Stories like Cybercab and Optimus are what prop up that PE, so whether Cybertruck stays in production has little impact on the model. The problem is that Cybercab has its own issues: in September, the NHTSA opened an investigation into how that batch of roughly 1,000 cars with no steering wheels or pedals met federal safety standards.
A product that can’t sell is making way for one that’s still under regulatory scrutiny.
One more thing: of Tesla’s $787 million in net income for the third quarter, $288 million came from BTC’s paper gains. BTC was still around $83,600 at the end of September; now it’s at $74,800. In the fourth quarter, some of those gains will likely be wiped out. Car sales are struggling, and crypto is falling too. I’m not feeling very optimistic about the profit line in the next earnings report.
#特斯拉 #Cybertruck #美股 #BTC
$TSLA $BTC
Cybertruck is being discontinued. Musk posted it himself last Friday: the Texas factory will likely wind down the production line around mid-2027 to make room to expand Cybercab production.
Honestly, there were signs this was coming. Cybertruck sales in the U.S. were down 48% year over year last year. In Tesla’s third-quarter earnings report this year, “other models” beyond the Model 3 and Model Y accounted for just 8,295 deliveries—and that includes the Model S and X.
The market reaction is pretty interesting: almost nobody cares.
That’s because Tesla’s valuation hasn’t been based on car sales for a long time. Stories like Cybercab and Optimus are what prop up that PE, so whether Cybertruck stays in production has little impact on the model. The problem is that Cybercab has its own issues: in September, the NHTSA opened an investigation into how that batch of roughly 1,000 cars with no steering wheels or pedals met federal safety standards.
A product that can’t sell is making way for one that’s still under regulatory scrutiny.
One more thing: of Tesla’s $787 million in net income for the third quarter, $288 million came from BTC’s paper gains. BTC was still around $83,600 at the end of September; now it’s at $74,800. In the fourth quarter, some of those gains will likely be wiped out. Car sales are struggling, and crypto is falling too. I’m not feeling very optimistic about the profit line in the next earnings report.
#特斯拉 #Cybertruck #美股 #BTC
$TSLA $BTC
142
·
--
The batch of CoreWeave bonds issued this June and maturing in 2032 carries a 9.625% coupon. Yields topped 16% last Friday.
WTF, a company hyped as an AI leader, is being priced by the bond market on a par with junk bonds.
Put a few numbers together. At the end of June, total debt including leases was $51.6 billion, up from just $6.28 billion two years ago. The company’s own Q3 interest expense guidance is $860–940 million, while adjusted operating income is only $200–260 million—not even a third of the interest bill. Analysts estimate interest expense of $5.3 billion in 2027 against EBIT of $4.1 billion. Still underwater.
Five-year CDS briefly hit 1,289 bps last Thursday. The stock has fallen more than 40% in a month.
Revenue will probably come in tonight, with consensus around $3.55 billion, up 160% year over year. What I want to hear about is something else: BofA estimates it still needs about $20 billion in funding. Where will it come from, and at what rate? If it issues another tranche of unsecured debt, the coupon will show just how expensive that route is.
Compare that with IREN, which started out as a miner. Under its newly signed five-year contracts, customers prepay 90% of GPU capex, and IREN owns the land, power, and data centers. Same AI cloud business, but the financing foundations are worlds apart.
Crypto folks shouldn’t think this has nothing to do with them. Over the past two years, a lot of mining companies have earned valuation premiums by pivoting to AI compute. If CoreWeave’s financing gets stuck, that premium will probably be the first thing to disappear. BTC is around 74,800 now, and the coins miners hold aren’t enough to support their valuations.
Earnings are due after the market close on 11/10 ET, around 5 a.m. on 11/11 Beijing time.
#CoreWeave #AI算力 #美股 #BTC
$CRWV $BTC
The batch of CoreWeave bonds issued this June and maturing in 2032 carries a 9.625% coupon. Yields topped 16% last Friday.
WTF, a company hyped as an AI leader, is being priced by the bond market on a par with junk bonds.
Put a few numbers together. At the end of June, total debt including leases was $51.6 billion, up from just $6.28 billion two years ago. The company’s own Q3 interest expense guidance is $860–940 million, while adjusted operating income is only $200–260 million—not even a third of the interest bill. Analysts estimate interest expense of $5.3 billion in 2027 against EBIT of $4.1 billion. Still underwater.
Five-year CDS briefly hit 1,289 bps last Thursday. The stock has fallen more than 40% in a month.
Revenue will probably come in tonight, with consensus around $3.55 billion, up 160% year over year. What I want to hear about is something else: BofA estimates it still needs about $20 billion in funding. Where will it come from, and at what rate? If it issues another tranche of unsecured debt, the coupon will show just how expensive that route is.
Compare that with IREN, which started out as a miner. Under its newly signed five-year contracts, customers prepay 90% of GPU capex, and IREN owns the land, power, and data centers. Same AI cloud business, but the financing foundations are worlds apart.
Crypto folks shouldn’t think this has nothing to do with them. Over the past two years, a lot of mining companies have earned valuation premiums by pivoting to AI compute. If CoreWeave’s financing gets stuck, that premium will probably be the first thing to disappear. BTC is around 74,800 now, and the coins miners hold aren’t enough to support their valuations.
Earnings are due after the market close on 11/10 ET, around 5 a.m. on 11/11 Beijing time.
#CoreWeave #AI算力 #美股 #BTC
$CRWV $BTC
WTF, a company hyped as an AI leader, is being priced by the bond market on a par with junk bonds.
Put a few numbers together. At the end of June, total debt including leases was $51.6 billion, up from just $6.28 billion two years ago. The company’s own Q3 interest expense guidance is $860–940 million, while adjusted operating income is only $200–260 million—not even a third of the interest bill. Analysts estimate interest expense of $5.3 billion in 2027 against EBIT of $4.1 billion. Still underwater.
Five-year CDS briefly hit 1,289 bps last Thursday. The stock has fallen more than 40% in a month.
Revenue will probably come in tonight, with consensus around $3.55 billion, up 160% year over year. What I want to hear about is something else: BofA estimates it still needs about $20 billion in funding. Where will it come from, and at what rate? If it issues another tranche of unsecured debt, the coupon will show just how expensive that route is.
Compare that with IREN, which started out as a miner. Under its newly signed five-year contracts, customers prepay 90% of GPU capex, and IREN owns the land, power, and data centers. Same AI cloud business, but the financing foundations are worlds apart.
Crypto folks shouldn’t think this has nothing to do with them. Over the past two years, a lot of mining companies have earned valuation premiums by pivoting to AI compute. If CoreWeave’s financing gets stuck, that premium will probably be the first thing to disappear. BTC is around 74,800 now, and the coins miners hold aren’t enough to support their valuations.
Earnings are due after the market close on 11/10 ET, around 5 a.m. on 11/11 Beijing time.
#CoreWeave #AI算力 #美股 #BTC
$CRWV $BTC
1
220
·
--
Strategy sold $284 million of common stock last week, but only $81.9 million went toward buying BTC.
The remaining $188 million was used to buy back its own STRC preferred stock. In other words, less than a third of the money raised went into BTC, while two-thirds went to support the price of its preferred stock.
I’ve been thinking about this for a while. The old playbook was simple: if the stock traded at a premium, issue more shares; use the proceeds to buy crypto; and let those purchases push the stock price higher. Now the proceeds are being used to prop up preferred stock instead, and that cycle is clearly slowing down.
Then there’s the cost basis. 850,364 BTC at an average of 75,456. BTC is now at 74,630, just below its cost basis. The 1,036 BTC it bought last week, at an average of 79,012, were already down more than 5% as soon as it got them.
It does still have $4.9 billion in cash reserves, enough to cover more than three years of preferred stock dividends and interest, so no one is forcing it to sell coins in the short term.
Even the biggest single buyer is starting to put its own preferred stock first. If BTC keeps grinding below 75,000 all week, I’m curious how much will be left in the “crypto purchases” line of next Monday’s 8-K.
#BTC #Strategy #MSTR $MSTR $BTC
Strategy sold $284 million of common stock last week, but only $81.9 million went toward buying BTC.
The remaining $188 million was used to buy back its own STRC preferred stock. In other words, less than a third of the money raised went into BTC, while two-thirds went to support the price of its preferred stock.
I’ve been thinking about this for a while. The old playbook was simple: if the stock traded at a premium, issue more shares; use the proceeds to buy crypto; and let those purchases push the stock price higher. Now the proceeds are being used to prop up preferred stock instead, and that cycle is clearly slowing down.
Then there’s the cost basis. 850,364 BTC at an average of 75,456. BTC is now at 74,630, just below its cost basis. The 1,036 BTC it bought last week, at an average of 79,012, were already down more than 5% as soon as it got them.
It does still have $4.9 billion in cash reserves, enough to cover more than three years of preferred stock dividends and interest, so no one is forcing it to sell coins in the short term.
Even the biggest single buyer is starting to put its own preferred stock first. If BTC keeps grinding below 75,000 all week, I’m curious how much will be left in the “crypto purchases” line of next Monday’s 8-K.
#BTC #Strategy #MSTR $MSTR $BTC
The remaining $188 million was used to buy back its own STRC preferred stock. In other words, less than a third of the money raised went into BTC, while two-thirds went to support the price of its preferred stock.
I’ve been thinking about this for a while. The old playbook was simple: if the stock traded at a premium, issue more shares; use the proceeds to buy crypto; and let those purchases push the stock price higher. Now the proceeds are being used to prop up preferred stock instead, and that cycle is clearly slowing down.
Then there’s the cost basis. 850,364 BTC at an average of 75,456. BTC is now at 74,630, just below its cost basis. The 1,036 BTC it bought last week, at an average of 79,012, were already down more than 5% as soon as it got them.
It does still have $4.9 billion in cash reserves, enough to cover more than three years of preferred stock dividends and interest, so no one is forcing it to sell coins in the short term.
Even the biggest single buyer is starting to put its own preferred stock first. If BTC keeps grinding below 75,000 all week, I’m curious how much will be left in the “crypto purchases” line of next Monday’s 8-K.
#BTC #Strategy #MSTR $MSTR $BTC
1
24
·
--
If you sold at a loss last Thursday, don’t look at the market tonight—it’ll only make you feel worse.
On November 5, $SOXX plunged 12.15% in a single day, its worst day of the year—worse than the drop on June 5. Before the market closed, the timeline was full of talk about the AI bubble bursting, data center construction being halted, and how it was exactly like 2000.
#美股 #半导体 #AIBubble
If you sold at a loss last Thursday, don’t look at the market tonight—it’ll only make you feel worse.
On November 5, $SOXX plunged 12.15% in a single day, its worst day of the year—worse than the drop on June 5. Before the market closed, the timeline was full of talk about the AI bubble bursting, data center construction being halted, and how it was exactly like 2000.
#美股 #半导体 #AIBubble
On November 5, $SOXX plunged 12.15% in a single day, its worst day of the year—worse than the drop on June 5. Before the market closed, the timeline was full of talk about the AI bubble bursting, data center construction being halted, and how it was exactly like 2000.
#美股 #半导体 #AIBubble
160
·
--
Take a quick look at Monday’s top ten gainers: three were optical communications stocks. Believe it?
Coherent +16.79%, Lumentum +10.69%, Ciena +10.66%. Add AMD +13.26% and Applied Materials +11.37%, and AI hardware basically dominated the top gainers in the S&P 500.
On the same day, Nvidia fell 4.27% on $81.3 billion in trading volume—the highest of any stock in the entire market.
Honestly, this mix is a little surreal. Money hasn’t left AI; it’s just moved from the big name to the layer that “sells shovels to the shovel sellers.” Optical transceivers, equipment, power supplies—these higher-beta plays, whose beta is even greater than Nvidia’s, have instead become safe havens. I’m baffled.
I generally don’t chase this kind of rotation on day one. These stocks were among last week’s hardest hit, so it’s only natural they’d bounce back the hardest on Monday. No one can say how much of that was short covering. To see if the rally has staying power, we’ll have to wait and see whether they’re still holding up on the second and third days after the CPI comes out.
One more thing: over the past few weeks, BTC has moved a lot like this batch of high-beta tech stocks, falling alongside them. On Monday, they surged, but BTC didn’t follow—it moved sideways around 74,600. Whether this divergence is good or bad, tonight’s CPI report at 8:30 p.m. Eastern (9:30 a.m. Beijing time) will probably give us the answer.
#美股 #光通信 #AI $AMD $BTC
Take a quick look at Monday’s top ten gainers: three were optical communications stocks. Believe it?
Coherent +16.79%, Lumentum +10.69%, Ciena +10.66%. Add AMD +13.26% and Applied Materials +11.37%, and AI hardware basically dominated the top gainers in the S&P 500.
On the same day, Nvidia fell 4.27% on $81.3 billion in trading volume—the highest of any stock in the entire market.
Honestly, this mix is a little surreal. Money hasn’t left AI; it’s just moved from the big name to the layer that “sells shovels to the shovel sellers.” Optical transceivers, equipment, power supplies—these higher-beta plays, whose beta is even greater than Nvidia’s, have instead become safe havens. I’m baffled.
I generally don’t chase this kind of rotation on day one. These stocks were among last week’s hardest hit, so it’s only natural they’d bounce back the hardest on Monday. No one can say how much of that was short covering. To see if the rally has staying power, we’ll have to wait and see whether they’re still holding up on the second and third days after the CPI comes out.
One more thing: over the past few weeks, BTC has moved a lot like this batch of high-beta tech stocks, falling alongside them. On Monday, they surged, but BTC didn’t follow—it moved sideways around 74,600. Whether this divergence is good or bad, tonight’s CPI report at 8:30 p.m. Eastern (9:30 a.m. Beijing time) will probably give us the answer.
#美股 #光通信 #AI $AMD $BTC
Coherent +16.79%, Lumentum +10.69%, Ciena +10.66%. Add AMD +13.26% and Applied Materials +11.37%, and AI hardware basically dominated the top gainers in the S&P 500.
On the same day, Nvidia fell 4.27% on $81.3 billion in trading volume—the highest of any stock in the entire market.
Honestly, this mix is a little surreal. Money hasn’t left AI; it’s just moved from the big name to the layer that “sells shovels to the shovel sellers.” Optical transceivers, equipment, power supplies—these higher-beta plays, whose beta is even greater than Nvidia’s, have instead become safe havens. I’m baffled.
I generally don’t chase this kind of rotation on day one. These stocks were among last week’s hardest hit, so it’s only natural they’d bounce back the hardest on Monday. No one can say how much of that was short covering. To see if the rally has staying power, we’ll have to wait and see whether they’re still holding up on the second and third days after the CPI comes out.
One more thing: over the past few weeks, BTC has moved a lot like this batch of high-beta tech stocks, falling alongside them. On Monday, they surged, but BTC didn’t follow—it moved sideways around 74,600. Whether this divergence is good or bad, tonight’s CPI report at 8:30 p.m. Eastern (9:30 a.m. Beijing time) will probably give us the answer.
#美股 #光通信 #AI $AMD $BTC
237
·
--
In one month, USDT has fallen by nearly $7.9 billion.
On October 10, it was just over $184 billion. Today, it’s $176.2 billion. It’s shrunk by more than $2.3 billion in just the past week. At its peak in May, it was $190.2 billion.
This figure is more honest than the candlestick chart. A few large orders can push prices around, but when stablecoin supply is shrinking, it means people are taking their bullets out of the market and converting them back to dollars, with no plans to come back anytime soon.
So don’t assume the bottom is secure just because BTC is holding around $74,600 without falling much. The water level underneath is dropping, and that has a lot to do with why every rebound seems to run out of steam.
ETFs also saw net outflows of $1.28 billion last week. No money coming in from outside the market, while money inside it is still pulling out.
I’ll feel like this cycle has run its course when USDT starts getting minted again. For now, let’s see what happens after tonight’s CPI report.
#BTC #稳定币 #USDT $BTC $USDT
In one month, USDT has fallen by nearly $7.9 billion.
On October 10, it was just over $184 billion. Today, it’s $176.2 billion. It’s shrunk by more than $2.3 billion in just the past week. At its peak in May, it was $190.2 billion.
This figure is more honest than the candlestick chart. A few large orders can push prices around, but when stablecoin supply is shrinking, it means people are taking their bullets out of the market and converting them back to dollars, with no plans to come back anytime soon.
So don’t assume the bottom is secure just because BTC is holding around $74,600 without falling much. The water level underneath is dropping, and that has a lot to do with why every rebound seems to run out of steam.
ETFs also saw net outflows of $1.28 billion last week. No money coming in from outside the market, while money inside it is still pulling out.
I’ll feel like this cycle has run its course when USDT starts getting minted again. For now, let’s see what happens after tonight’s CPI report.
#BTC #稳定币 #USDT $BTC $USDT
On October 10, it was just over $184 billion. Today, it’s $176.2 billion. It’s shrunk by more than $2.3 billion in just the past week. At its peak in May, it was $190.2 billion.
This figure is more honest than the candlestick chart. A few large orders can push prices around, but when stablecoin supply is shrinking, it means people are taking their bullets out of the market and converting them back to dollars, with no plans to come back anytime soon.
So don’t assume the bottom is secure just because BTC is holding around $74,600 without falling much. The water level underneath is dropping, and that has a lot to do with why every rebound seems to run out of steam.
ETFs also saw net outflows of $1.28 billion last week. No money coming in from outside the market, while money inside it is still pulling out.
I’ll feel like this cycle has run its course when USDT starts getting minted again. For now, let’s see what happens after tonight’s CPI report.
#BTC #稳定币 #USDT $BTC $USDT
2
415
·
--
See translation
昨晚美股涨成这样,头号功臣我觉得是油。
布伦特一天跌了 5.85%,收 92.57,WTI 跌到 86.85。标普跟着 +2.35%,4 月以来最好的一天。
涨最猛的还不是纳指,是 Russell 2000,+3.15%。小盘股最怕的就是利率,油价一砸,通胀预期往下压,大家立刻开始赌利率没那么可怕,小盘先跳。
VIX 一晚上掉了 22%,到 19.92。卧槽,上周还满屏喊崩,一根大阳线就回到 20 以下了。标普 500 里 422 只涨、74 只跌,这么整齐的普涨,空头回补的味道很重。
麻烦在今晚。美东 8:30(北京时间 21:30)出 CPI,昨晚等于先把"通胀降温"的剧本提前买进去了,数字要是偏热,这 2% 吐回去也就一晚上。
BTC 昨晚基本没跟,现在 7.46 万左右。它这阵子看的是美债收益率和 ETF 资金,不太吃股指情绪。10 年期如果真借 CPI 从 4.85% 往下打,那才轮到它动
#美股 #CPI #原油 $BTC
昨晚美股涨成这样,头号功臣我觉得是油。
布伦特一天跌了 5.85%,收 92.57,WTI 跌到 86.85。标普跟着 +2.35%,4 月以来最好的一天。
涨最猛的还不是纳指,是 Russell 2000,+3.15%。小盘股最怕的就是利率,油价一砸,通胀预期往下压,大家立刻开始赌利率没那么可怕,小盘先跳。
VIX 一晚上掉了 22%,到 19.92。卧槽,上周还满屏喊崩,一根大阳线就回到 20 以下了。标普 500 里 422 只涨、74 只跌,这么整齐的普涨,空头回补的味道很重。
麻烦在今晚。美东 8:30(北京时间 21:30)出 CPI,昨晚等于先把"通胀降温"的剧本提前买进去了,数字要是偏热,这 2% 吐回去也就一晚上。
BTC 昨晚基本没跟,现在 7.46 万左右。它这阵子看的是美债收益率和 ETF 资金,不太吃股指情绪。10 年期如果真借 CPI 从 4.85% 往下打,那才轮到它动
#美股 #CPI #原油 $BTC
布伦特一天跌了 5.85%,收 92.57,WTI 跌到 86.85。标普跟着 +2.35%,4 月以来最好的一天。
涨最猛的还不是纳指,是 Russell 2000,+3.15%。小盘股最怕的就是利率,油价一砸,通胀预期往下压,大家立刻开始赌利率没那么可怕,小盘先跳。
VIX 一晚上掉了 22%,到 19.92。卧槽,上周还满屏喊崩,一根大阳线就回到 20 以下了。标普 500 里 422 只涨、74 只跌,这么整齐的普涨,空头回补的味道很重。
麻烦在今晚。美东 8:30(北京时间 21:30)出 CPI,昨晚等于先把"通胀降温"的剧本提前买进去了,数字要是偏热,这 2% 吐回去也就一晚上。
BTC 昨晚基本没跟,现在 7.46 万左右。它这阵子看的是美债收益率和 ETF 资金,不太吃股指情绪。10 年期如果真借 CPI 从 4.85% 往下打,那才轮到它动
#美股 #CPI #原油 $BTC
1
25
·
--
Only one of the 30 Philadelphia Semiconductor Index components closed in the green on Monday.
That was $NVDA.
The index rose 6.9% that day, its biggest one-day gain since late July. AMD rose 13.26%, Broadcom 8.78%, and Micron gained more than 6%. Nvidia itself fell 4.27%, closing at 178.67 on volume of 455 million shares—about 3.7 times its average daily volume over the past three months. WC, that’s some volume.
We all saw the reason: the board launched an independent investigation into Jensen Huang. The company says there’s currently no reason to believe any sensitive information was leaked, but the market doesn’t care about that. Huang himself is part of Nvidia’s valuation, and CEO risk is the kind of thing you can’t put into a model. The easiest thing to do is sell first and ask questions later.
So the money was still in AI that day—it just switched vehicles. It moved out of Nvidia and into AMD, Broadcom, and optical communications. Coherent was up 16.8% in a single day.
There was also one name in crypto that got left out in the cold. The Nasdaq rose 2.74%, BTC barely moved, while MSTR actually fell 2.6%, closing at 125.59.
There’s one week left until the 11/17 earnings report. If the investigation still hasn’t been resolved by then, the first question analysts ask on the call probably won’t have much to do with chips.
#英伟达 #美股 #比特币 $NVDA $BTC
Only one of the 30 Philadelphia Semiconductor Index components closed in the green on Monday.
That was $NVDA .
The index rose 6.9% that day, its biggest one-day gain since late July. AMD rose 13.26%, Broadcom 8.78%, and Micron gained more than 6%. Nvidia itself fell 4.27%, closing at 178.67 on volume of 455 million shares—about 3.7 times its average daily volume over the past three months. WC, that’s some volume.
We all saw the reason: the board launched an independent investigation into Jensen Huang. The company says there’s currently no reason to believe any sensitive information was leaked, but the market doesn’t care about that. Huang himself is part of Nvidia’s valuation, and CEO risk is the kind of thing you can’t put into a model. The easiest thing to do is sell first and ask questions later.
So the money was still in AI that day—it just switched vehicles. It moved out of Nvidia and into AMD, Broadcom, and optical communications. Coherent was up 16.8% in a single day.
There was also one name in crypto that got left out in the cold. The Nasdaq rose 2.74%, BTC barely moved, while MSTR actually fell 2.6%, closing at 125.59.
There’s one week left until the 11/17 earnings report. If the investigation still hasn’t been resolved by then, the first question analysts ask on the call probably won’t have much to do with chips.
#英伟达 #美股 #比特币 $NVDA $BTC
That was $NVDA .
The index rose 6.9% that day, its biggest one-day gain since late July. AMD rose 13.26%, Broadcom 8.78%, and Micron gained more than 6%. Nvidia itself fell 4.27%, closing at 178.67 on volume of 455 million shares—about 3.7 times its average daily volume over the past three months. WC, that’s some volume.
We all saw the reason: the board launched an independent investigation into Jensen Huang. The company says there’s currently no reason to believe any sensitive information was leaked, but the market doesn’t care about that. Huang himself is part of Nvidia’s valuation, and CEO risk is the kind of thing you can’t put into a model. The easiest thing to do is sell first and ask questions later.
So the money was still in AI that day—it just switched vehicles. It moved out of Nvidia and into AMD, Broadcom, and optical communications. Coherent was up 16.8% in a single day.
There was also one name in crypto that got left out in the cold. The Nasdaq rose 2.74%, BTC barely moved, while MSTR actually fell 2.6%, closing at 125.59.
There’s one week left until the 11/17 earnings report. If the investigation still hasn’t been resolved by then, the first question analysts ask on the call probably won’t have much to do with chips.
#英伟达 #美股 #比特币 $NVDA $BTC
336
·
--
The earnings report worth watching most this week isn’t Nvidia’s—it’s Applied Materials’ on 11/12.
The reason is simple. The market is worried that this semiconductor selloff is driven by fears that if Democrats take office, data center construction will slow and chipmakers won’t dare expand production. To answer that question, Nvidia’s numbers tell us “how well it sold last quarter,” while $AMAT ’s orders tell us “whether chipmakers still dare spend money to build capacity.”
One looks at the past; the other looks to the future.
#半导体 #美股财报 #Applied Materials
The earnings report worth watching most this week isn’t Nvidia’s—it’s Applied Materials’ on 11/12.
The reason is simple. The market is worried that this semiconductor selloff is driven by fears that if Democrats take office, data center construction will slow and chipmakers won’t dare expand production. To answer that question, Nvidia’s numbers tell us “how well it sold last quarter,” while $AMAT ’s orders tell us “whether chipmakers still dare spend money to build capacity.”
One looks at the past; the other looks to the future.
#半导体 #美股财报 #Applied Materials
The reason is simple. The market is worried that this semiconductor selloff is driven by fears that if Democrats take office, data center construction will slow and chipmakers won’t dare expand production. To answer that question, Nvidia’s numbers tell us “how well it sold last quarter,” while $AMAT ’s orders tell us “whether chipmakers still dare spend money to build capacity.”
One looks at the past; the other looks to the future.
#半导体 #美股财报 #Applied Materials
1
465
·
--
ETH/BTC dropped nearly 4% in a single day on Sunday, hitting a low around 0.0282—the lowest in 40 days.
This ratio usually has to move even 0.5% in a day to count as a big move.
It’s been less than a week since last Wednesday’s big green candle. ETH peaked at 2450 that day and is now around 2125, giving back 13%. BTC has fallen from 81,196 to 75,000, down 7.5%. In the same market move, ETH didn’t rise much more than BTC, but it sure hasn’t held back on the way down.
Sunday’s move was even more extreme. U.S. stock markets were closed, and there wasn’t any major news. BTC just moved from 75,900 to 74,900 that day, while ETH plunged straight from 2240 to 2060 before buyers stepped in. When prices fall without any news, it’s probably because someone is swapping ETH for BTC—or simply switching to stablecoins to sit out the volatility.
So when looking at ETH now, watching its dollar price alone isn’t enough. Whether it can hold 2100 is one thing; whether the ratio can climb back above 0.029 is another.
Honestly, if the ratio doesn’t recover, then even if BTC leads a rebound, ETH will most likely just get dragged along.
The Fear and Greed Index is at 32 today, still in fear territory.
#以太坊 #比特币 #加密市场 $ETH $BTC
ETH/BTC dropped nearly 4% in a single day on Sunday, hitting a low around 0.0282—the lowest in 40 days.
This ratio usually has to move even 0.5% in a day to count as a big move.
It’s been less than a week since last Wednesday’s big green candle. ETH peaked at 2450 that day and is now around 2125, giving back 13%. BTC has fallen from 81,196 to 75,000, down 7.5%. In the same market move, ETH didn’t rise much more than BTC, but it sure hasn’t held back on the way down.
Sunday’s move was even more extreme. U.S. stock markets were closed, and there wasn’t any major news. BTC just moved from 75,900 to 74,900 that day, while ETH plunged straight from 2240 to 2060 before buyers stepped in. When prices fall without any news, it’s probably because someone is swapping ETH for BTC—or simply switching to stablecoins to sit out the volatility.
So when looking at ETH now, watching its dollar price alone isn’t enough. Whether it can hold 2100 is one thing; whether the ratio can climb back above 0.029 is another.
Honestly, if the ratio doesn’t recover, then even if BTC leads a rebound, ETH will most likely just get dragged along.
The Fear and Greed Index is at 32 today, still in fear territory.
#以太坊 #比特币 #加密市场 $ETH $BTC
This ratio usually has to move even 0.5% in a day to count as a big move.
It’s been less than a week since last Wednesday’s big green candle. ETH peaked at 2450 that day and is now around 2125, giving back 13%. BTC has fallen from 81,196 to 75,000, down 7.5%. In the same market move, ETH didn’t rise much more than BTC, but it sure hasn’t held back on the way down.
Sunday’s move was even more extreme. U.S. stock markets were closed, and there wasn’t any major news. BTC just moved from 75,900 to 74,900 that day, while ETH plunged straight from 2240 to 2060 before buyers stepped in. When prices fall without any news, it’s probably because someone is swapping ETH for BTC—or simply switching to stablecoins to sit out the volatility.
So when looking at ETH now, watching its dollar price alone isn’t enough. Whether it can hold 2100 is one thing; whether the ratio can climb back above 0.029 is another.
Honestly, if the ratio doesn’t recover, then even if BTC leads a rebound, ETH will most likely just get dragged along.
The Fear and Greed Index is at 32 today, still in fear territory.
#以太坊 #比特币 #加密市场 $ETH $BTC
1
305
·
--
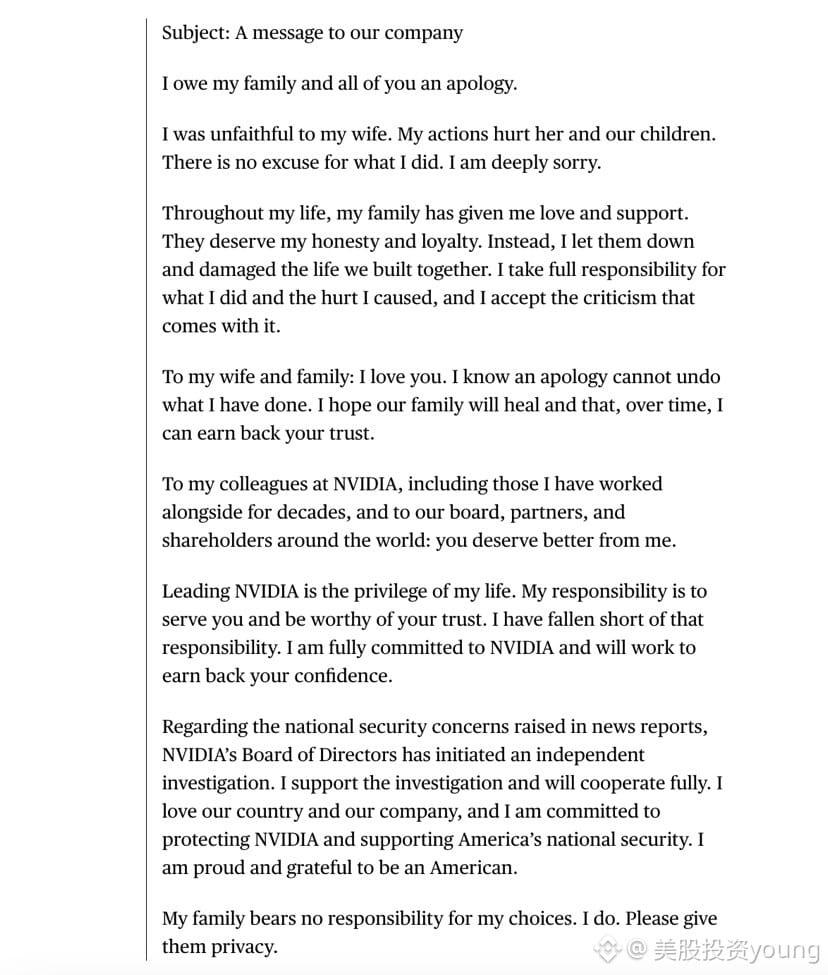
Well, that's just great 😭$NVDAB The first thing I do when I wake up
I take one look and pass out
When the sell-off caused by NVDA's Jensen Huang
triggers $QQQB more selling 😭
I'll definitely cry louder than Jensen Huang's wife
Well, that's just great 😭$NVDAB The first thing I do when I wake up
I take one look and pass out
When the sell-off caused by NVDA's Jensen Huang
triggers $QQQB more selling 😭
I'll definitely cry louder than Jensen Huang's wife
I take one look and pass out
When the sell-off caused by NVDA's Jensen Huang
triggers $QQQB more selling 😭
I'll definitely cry louder than Jensen Huang's wife
2
482
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
HotCPIDecemberHikePriced
26,129 views
629 Discussing
CPI Market Watch | US CPI Rises 0.4% in October, Hotter Than 0.3% Forecast
Binance News
·18 Likes
·31.3k views
AnthropicRejectsIPODelayValuationinQuestion
161,790 views
1,511 Discussing
NvidiaInvestigatesAfterHuang’sAffairApology
423,929 views
2,978 Discussing