
阿Sue的加密日记
297 Posts

阿Sue的加密日记
Report
Block User
链上数据 技术分析
数据解毒师 | 拆穿币圈伪信号
💰 币安返佣20%:108319454
60 Following
173 Followers
1.1K+ Liked
Posts
All
Quotes
·
--
Verified
#anthropic拒绝延期ipo,本周路演估值几何? Anthropic’s valuation has been cut in half, and it still refuses to delay: Here’s the bottom line. Although I’m a cc user, it’s also very strong. At the start of the year, I only used cc, but I wasn’t bullish on companies like this. The reason is simple: its capabilities aren’t that far ahead of the followers, but its price is. Now I use WorkBuddy and Claude together, roughly an 8:2 split.
Hashtag is asking, “What’s the valuation?” After reading the prospectus, I think that’s the wrong question. What we should be watching is the roughly $900.9 billion in compute commitments, against just $131.8 billion in cash and short-term investments.
📊 Key figures
· Roadshow starts 11/10; pricing is planned for 11/18 and listing for 11/19, at $70–78
· Valuation: at the midpoint of $74, about $970 billion; $1.02 trillion at the top end; $1.33–1.41 trillion on a fully diluted basis
· Q3 revenue: $16.956 billion (+1,127%), or about $81 billion annualized; GAAP operating loss: $567 million
· Compute commitments: about $900.9 billion; about $70.7 billion due over the next 12 months (≈87% of annualized revenue)
· Cash + short-term investments: $131.8 billion = 1/6.8 of commitments; nearly all subscribers are upstream suppliers
🔍 Key contradictions
One: A mismatch in timing, spelled out in the prospectus itself. Compute contracts lock in costs for years, while customers pay by usage and can cut back. They’re betting fixed costs on uncertain demand; delaying would cost more, so they’d rather list at a low price than wait.
Two: Nearly all subscribers are upstream suppliers: Google and Nvidia at $10 billion each, AMD at $2.5 billion, Broadcom, Micron, and Microsoft at $1 billion each, and TSMC at $500 million. Suppliers are funding a customer’s subscription, and that customer is using the money to buy chips. That calls the independence of demand into question.
Three: Don’t misread the financial statements. Of the $104 billion net loss in the first three quarters, $94.3 billion came from fair-value changes in convertible bonds and didn’t use cash. Q3 GAAP loss was $567 million; an 85% gross margin ≠ profitability.
🧊 Three reality checks
1. The registration statement is not yet effective, and shares cannot be sold before it becomes effective; a price range ≠ a finalized offering price.
2. There are five different valuation figures: $970 billion / $1.02 trillion / $1.41 trillion / $1.2–1.3 trillion / $2 trillion—a $400 billion spread.
3. Supply-chain subscriptions are a double-edged sword: they show how tightly the parties are linked, but they also concentrate risk in the same chain.
💡 My take
This isn’t a bubble bursting; it’s the public market putting private-market premiums to the test. Add hotter-than-expected CPI and roughly 90% odds of a December rate hike, and discount rates rise while the value of distant cash flows falls—the same chain of events as ZEC breaking $1,000.
What I’d do: Before pricing on 11/18, don’t treat “the largest IPO in history” as a sign of a recovery. Watch the final offering price, first-day buying, and Q4 gross margin.
⚠️ Not investment advice. Refer to the SEC’s effective filings for authoritative figures.
#anthropic拒绝延期ipo,本周路演估值几何? Anthropic’s valuation has been cut in half, and it still refuses to delay: Here’s the bottom line. Although I’m a cc user, it’s also very strong. At the start of the year, I only used cc, but I wasn’t bullish on companies like this. The reason is simple: its capabilities aren’t that far ahead of the followers, but its price is. Now I use WorkBuddy and Claude together, roughly an 8:2 split.
Hashtag is asking, “What’s the valuation?” After reading the prospectus, I think that’s the wrong question. What we should be watching is the roughly $900.9 billion in compute commitments, against just $131.8 billion in cash and short-term investments.
📊 Key figures
· Roadshow starts 11/10; pricing is planned for 11/18 and listing for 11/19, at $70–78
· Valuation: at the midpoint of $74, about $970 billion; $1.02 trillion at the top end; $1.33–1.41 trillion on a fully diluted basis
· Q3 revenue: $16.956 billion (+1,127%), or about $81 billion annualized; GAAP operating loss: $567 million
· Compute commitments: about $900.9 billion; about $70.7 billion due over the next 12 months (≈87% of annualized revenue)
· Cash + short-term investments: $131.8 billion = 1/6.8 of commitments; nearly all subscribers are upstream suppliers
🔍 Key contradictions
One: A mismatch in timing, spelled out in the prospectus itself. Compute contracts lock in costs for years, while customers pay by usage and can cut back. They’re betting fixed costs on uncertain demand; delaying would cost more, so they’d rather list at a low price than wait.
Two: Nearly all subscribers are upstream suppliers: Google and Nvidia at $10 billion each, AMD at $2.5 billion, Broadcom, Micron, and Microsoft at $1 billion each, and TSMC at $500 million. Suppliers are funding a customer’s subscription, and that customer is using the money to buy chips. That calls the independence of demand into question.
Three: Don’t misread the financial statements. Of the $104 billion net loss in the first three quarters, $94.3 billion came from fair-value changes in convertible bonds and didn’t use cash. Q3 GAAP loss was $567 million; an 85% gross margin ≠ profitability.
🧊 Three reality checks
1. The registration statement is not yet effective, and shares cannot be sold before it becomes effective; a price range ≠ a finalized offering price.
2. There are five different valuation figures: $970 billion / $1.02 trillion / $1.41 trillion / $1.2–1.3 trillion / $2 trillion—a $400 billion spread.
3. Supply-chain subscriptions are a double-edged sword: they show how tightly the parties are linked, but they also concentrate risk in the same chain.
💡 My take
This isn’t a bubble bursting; it’s the public market putting private-market premiums to the test. Add hotter-than-expected CPI and roughly 90% odds of a December rate hike, and discount rates rise while the value of distant cash flows falls—the same chain of events as ZEC breaking $1,000.
What I’d do: Before pricing on 11/18, don’t treat “the largest IPO in history” as a sign of a recovery. Watch the final offering price, first-day buying, and Q4 gross margin.
⚠️ Not investment advice. Refer to the SEC’s effective filings for authoritative figures.
Hashtag is asking, “What’s the valuation?” After reading the prospectus, I think that’s the wrong question. What we should be watching is the roughly $900.9 billion in compute commitments, against just $131.8 billion in cash and short-term investments.
📊 Key figures
· Roadshow starts 11/10; pricing is planned for 11/18 and listing for 11/19, at $70–78
· Valuation: at the midpoint of $74, about $970 billion; $1.02 trillion at the top end; $1.33–1.41 trillion on a fully diluted basis
· Q3 revenue: $16.956 billion (+1,127%), or about $81 billion annualized; GAAP operating loss: $567 million
· Compute commitments: about $900.9 billion; about $70.7 billion due over the next 12 months (≈87% of annualized revenue)
· Cash + short-term investments: $131.8 billion = 1/6.8 of commitments; nearly all subscribers are upstream suppliers
🔍 Key contradictions
One: A mismatch in timing, spelled out in the prospectus itself. Compute contracts lock in costs for years, while customers pay by usage and can cut back. They’re betting fixed costs on uncertain demand; delaying would cost more, so they’d rather list at a low price than wait.
Two: Nearly all subscribers are upstream suppliers: Google and Nvidia at $10 billion each, AMD at $2.5 billion, Broadcom, Micron, and Microsoft at $1 billion each, and TSMC at $500 million. Suppliers are funding a customer’s subscription, and that customer is using the money to buy chips. That calls the independence of demand into question.
Three: Don’t misread the financial statements. Of the $104 billion net loss in the first three quarters, $94.3 billion came from fair-value changes in convertible bonds and didn’t use cash. Q3 GAAP loss was $567 million; an 85% gross margin ≠ profitability.
🧊 Three reality checks
1. The registration statement is not yet effective, and shares cannot be sold before it becomes effective; a price range ≠ a finalized offering price.
2. There are five different valuation figures: $970 billion / $1.02 trillion / $1.41 trillion / $1.2–1.3 trillion / $2 trillion—a $400 billion spread.
3. Supply-chain subscriptions are a double-edged sword: they show how tightly the parties are linked, but they also concentrate risk in the same chain.
💡 My take
This isn’t a bubble bursting; it’s the public market putting private-market premiums to the test. Add hotter-than-expected CPI and roughly 90% odds of a December rate hike, and discount rates rise while the value of distant cash flows falls—the same chain of events as ZEC breaking $1,000.
What I’d do: Before pricing on 11/18, don’t treat “the largest IPO in history” as a sign of a recovery. Watch the final offering price, first-day buying, and Q4 gross margin.
⚠️ Not investment advice. Refer to the SEC’s effective filings for authoritative figures.
1.9k
·
--
#circle第三季度营收8.65亿美元 Circle revenue hits a record $865M: $182M came from selling its own token
EPS of $0.84 beat expectations by 127%. The stock rose 3% premarket, then fell 3.35% after the market took the earnings report apart. That rise and fall in a single day says more than the report itself.
📊 Key figures
· Revenue: $865M (+17%), more than 11% above expectations of $778M
· Net income: $226M (+5%); EPS: $0.84 (expected: $0.37)
· Reserve income: $658M (-8%); other income: $207M (+627%)
· Of that, $182M came from the presale of ARC tokens; excluding it, recurring other income was just $25M
· Yield: 3.5% (-61 bps); average USDC in circulation: $73.3B, down 4.2% quarter over quarter
· Market share: 27% (-1.83 percentage points); on-chain transaction volume: $13.9T (+49%)
· $13.9B held on Circle’s own platforms, accounting for 18.1% (+36%)
🔍 The key contradiction
$865M doesn’t mean “the business got better”; it means “the company issued and sold a token.” The $182M from selling ARC tokens to investors was booked as revenue. It’s compliant, but one-off. Excluding it, recurring other income was just $25M, below Q1’s $42M.
Earnings come from the size of the balances held × the yield—not transaction turnover. $13.9T is transaction volume; $73.3B is what stayed on the books. More frequent use didn’t mean much more money stayed, and with yield down to 3.5%, that wasn’t enough to boost reserve income.
🧊 Three reality checks
1. Excluding the $182M leaves about $683M, so year-over-year growth is no longer +17% (my estimate, not the company’s figure). Guidance has already made clear that this revenue won’t recur.
2. Don’t treat the 49% increase in transaction volume as good news. Balances held fell 4.2% quarter over quarter and market share dropped 1.83 percentage points. More usage doesn’t necessarily mean more earnings.
3. The 127% EPS beat was also supported by that same one-off. Net income rose 5% even as reserve income fell 8%—a result of the revenue mix, not wider spreads.
💡 My take
This is an example of old and new growth drivers changing places, not a stablecoin boom. I’m not chasing the new high, but I’m not bearish on USDC either. Both camps are looking at only half the picture.
Three things really matter: whether the share held on Circle’s own platforms can keep rising from 18.1%; whether token revenue can take over after ARC moves to PoS in 2027; and whether reserve yields can stop falling.
What’s underappreciated is Binance’s $100M investment. The distribution landscape has more impact on on-chain liquidity than an extra $180M earned in a single quarter. Don’t attribute BTC at 80,292 to Circle.
⚠️ Not investment advice. Guidance is forward-looking and figures may be updated as disclosures change.
Follow @阿Sue的加密日记 · Using data to expose crypto’s false signals
#Circle #USDC #Stablecoins #Binance #Earnings
#circle第三季度营收8.65亿美元 Circle revenue hits a record $865M: $182M came from selling its own token
EPS of $0.84 beat expectations by 127%. The stock rose 3% premarket, then fell 3.35% after the market took the earnings report apart. That rise and fall in a single day says more than the report itself.
📊 Key figures
· Revenue: $865M (+17%), more than 11% above expectations of $778M
· Net income: $226M (+5%); EPS: $0.84 (expected: $0.37)
· Reserve income: $658M (-8%); other income: $207M (+627%)
· Of that, $182M came from the presale of ARC tokens; excluding it, recurring other income was just $25M
· Yield: 3.5% (-61 bps); average USDC in circulation: $73.3B, down 4.2% quarter over quarter
· Market share: 27% (-1.83 percentage points); on-chain transaction volume: $13.9T (+49%)
· $13.9B held on Circle’s own platforms, accounting for 18.1% (+36%)
🔍 The key contradiction
$865M doesn’t mean “the business got better”; it means “the company issued and sold a token.” The $182M from selling ARC tokens to investors was booked as revenue. It’s compliant, but one-off. Excluding it, recurring other income was just $25M, below Q1’s $42M.
Earnings come from the size of the balances held × the yield—not transaction turnover. $13.9T is transaction volume; $73.3B is what stayed on the books. More frequent use didn’t mean much more money stayed, and with yield down to 3.5%, that wasn’t enough to boost reserve income.
🧊 Three reality checks
1. Excluding the $182M leaves about $683M, so year-over-year growth is no longer +17% (my estimate, not the company’s figure). Guidance has already made clear that this revenue won’t recur.
2. Don’t treat the 49% increase in transaction volume as good news. Balances held fell 4.2% quarter over quarter and market share dropped 1.83 percentage points. More usage doesn’t necessarily mean more earnings.
3. The 127% EPS beat was also supported by that same one-off. Net income rose 5% even as reserve income fell 8%—a result of the revenue mix, not wider spreads.
💡 My take
This is an example of old and new growth drivers changing places, not a stablecoin boom. I’m not chasing the new high, but I’m not bearish on USDC either. Both camps are looking at only half the picture.
Three things really matter: whether the share held on Circle’s own platforms can keep rising from 18.1%; whether token revenue can take over after ARC moves to PoS in 2027; and whether reserve yields can stop falling.
What’s underappreciated is Binance’s $100M investment. The distribution landscape has more impact on on-chain liquidity than an extra $180M earned in a single quarter. Don’t attribute BTC at 80,292 to Circle.
⚠️ Not investment advice. Guidance is forward-looking and figures may be updated as disclosures change.
Follow @阿Sue的加密日记 · Using data to expose crypto’s false signals
#Circle #USDC #Stablecoins #Binance #Earnings
EPS of $0.84 beat expectations by 127%. The stock rose 3% premarket, then fell 3.35% after the market took the earnings report apart. That rise and fall in a single day says more than the report itself.
📊 Key figures
· Revenue: $865M (+17%), more than 11% above expectations of $778M
· Net income: $226M (+5%); EPS: $0.84 (expected: $0.37)
· Reserve income: $658M (-8%); other income: $207M (+627%)
· Of that, $182M came from the presale of ARC tokens; excluding it, recurring other income was just $25M
· Yield: 3.5% (-61 bps); average USDC in circulation: $73.3B, down 4.2% quarter over quarter
· Market share: 27% (-1.83 percentage points); on-chain transaction volume: $13.9T (+49%)
· $13.9B held on Circle’s own platforms, accounting for 18.1% (+36%)
🔍 The key contradiction
$865M doesn’t mean “the business got better”; it means “the company issued and sold a token.” The $182M from selling ARC tokens to investors was booked as revenue. It’s compliant, but one-off. Excluding it, recurring other income was just $25M, below Q1’s $42M.
Earnings come from the size of the balances held × the yield—not transaction turnover. $13.9T is transaction volume; $73.3B is what stayed on the books. More frequent use didn’t mean much more money stayed, and with yield down to 3.5%, that wasn’t enough to boost reserve income.
🧊 Three reality checks
1. Excluding the $182M leaves about $683M, so year-over-year growth is no longer +17% (my estimate, not the company’s figure). Guidance has already made clear that this revenue won’t recur.
2. Don’t treat the 49% increase in transaction volume as good news. Balances held fell 4.2% quarter over quarter and market share dropped 1.83 percentage points. More usage doesn’t necessarily mean more earnings.
3. The 127% EPS beat was also supported by that same one-off. Net income rose 5% even as reserve income fell 8%—a result of the revenue mix, not wider spreads.
💡 My take
This is an example of old and new growth drivers changing places, not a stablecoin boom. I’m not chasing the new high, but I’m not bearish on USDC either. Both camps are looking at only half the picture.
Three things really matter: whether the share held on Circle’s own platforms can keep rising from 18.1%; whether token revenue can take over after ARC moves to PoS in 2027; and whether reserve yields can stop falling.
What’s underappreciated is Binance’s $100M investment. The distribution landscape has more impact on on-chain liquidity than an extra $180M earned in a single quarter. Don’t attribute BTC at 80,292 to Circle.
⚠️ Not investment advice. Guidance is forward-looking and figures may be updated as disclosures change.
Follow @阿Sue的加密日记 · Using data to expose crypto’s false signals
#Circle #USDC #Stablecoins #Binance #Earnings
1
393
·
--
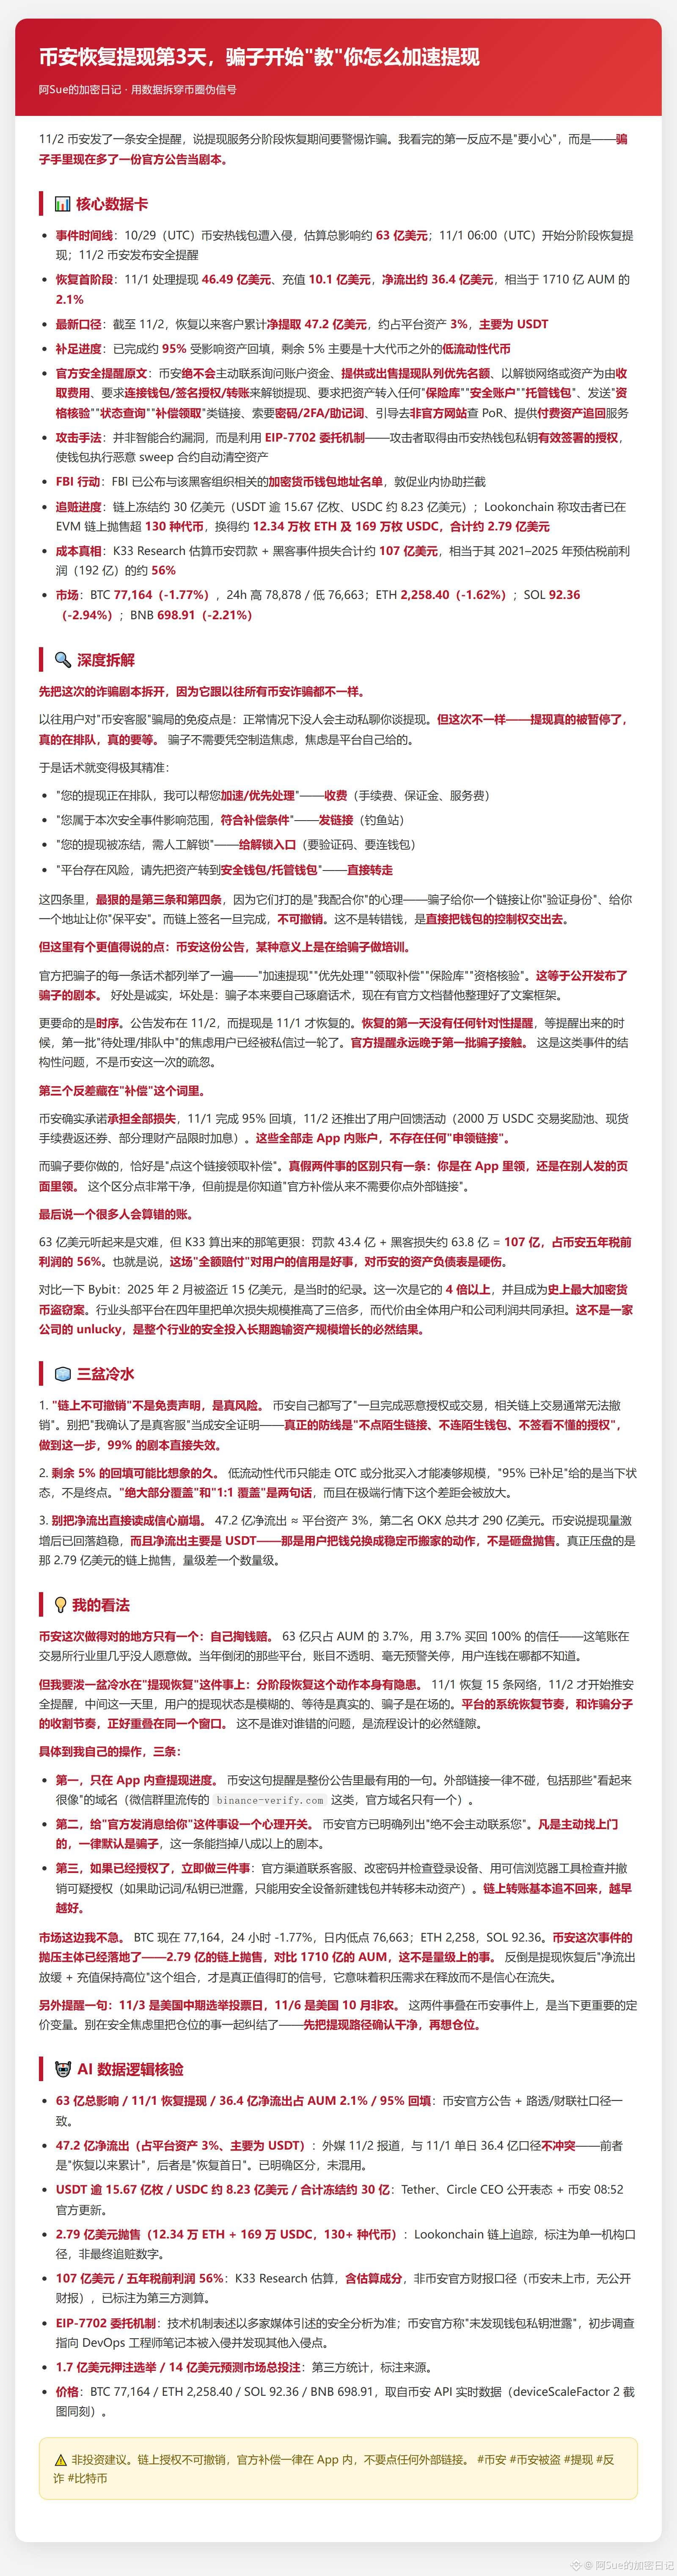
#提现服务恢复期间警惕诈骗 Day 3 of Binance withdrawals resuming, and scammers are starting to “teach” you how to speed up withdrawals
11/2 Binance issued a security reminder warning users to watch out for scams during the withdrawal phase. My first thought wasn’t “be careful”—it was that scammers now have an official announcement to use as a script.
📊 Key figures
· Around 6.3 billion was stolen on 10/29; withdrawals resumed on 11/1
· On 11/1, 4.649 billion was withdrawn and 1.01 billion deposited, for a net outflow of 3.64 billion, or 2.1% of AUM
· As of 11/2, cumulative net withdrawals totaled 4.72 billion, or 3% of platform assets, mainly in USDT
· 95% has been replenished, with the remaining 5% in low-liquidity coins
· The FBI has published a list of the hackers’ wallet addresses
🔍 The key contradiction
Previously, you had a point of protection: no one would proactively DM you about withdrawals. But this time, withdrawals are paused, queued, and delayed—the platform itself is creating the anxiety, so scammers don’t need to. Four common scripts: pay a fee to speed up withdrawals; click a link to qualify for compensation; your withdrawal is frozen, so use this link to unlock it; or transfer funds to a “safe wallet.” The last two are the most dangerous: they exploit the “I’m cooperating with you” mindset, and an on-chain signature cannot be undone.
🧊 Three reality checks
1. This Binance announcement is training scammers—it lays out the talking points one by one, effectively organizing a framework for their scripts.
2. Replenishing the remaining 5% could take a long time; low-liquidity coins can only be handled through OTC. “95% replenished” describes the situation now, not the finish line.
3. Don’t interpret the 4.72 billion in net outflows as a collapse in confidence. OKX has only 29 billion in total, and most of this is USDT being moved, not sold. The real selling pressure is the 279 million on-chain—an order of magnitude smaller.
💡 My take
The most useful line in the official reminder is “check withdrawal progress only in the app.” Don’t touch any external links, even domains that look similar. Set another rule: anyone who contacts you first is a scammer by default.
I’m not in a hurry on the market side. The main wave of selling pressure has already landed, and 279 million is not in the same league as 171 billion in AUM. What’s worth watching instead is “slowing net outflows + deposits staying high.”
One more reminder: U.S. midterm election voting is on 11/3, and the nonfarm payrolls report is on 11/6. First make sure your withdrawal route is secure, then think about your positions.
⚠️ Not investment advice. On-chain approvals cannot be undone. Official compensation is handled only in the app—don’t click external links.
Follow @A-Sue’s Crypto Journal · Using data to expose false signals in crypto
#Binance #BinanceHack #Withdrawals #ScamPrevention #Bitcoin
#提现服务恢复期间警惕诈骗 Day 3 of Binance withdrawals resuming, and scammers are starting to “teach” you how to speed up withdrawals
11/2 Binance issued a security reminder warning users to watch out for scams during the withdrawal phase. My first thought wasn’t “be careful”—it was that scammers now have an official announcement to use as a script.
📊 Key figures
· Around 6.3 billion was stolen on 10/29; withdrawals resumed on 11/1
· On 11/1, 4.649 billion was withdrawn and 1.01 billion deposited, for a net outflow of 3.64 billion, or 2.1% of AUM
· As of 11/2, cumulative net withdrawals totaled 4.72 billion, or 3% of platform assets, mainly in USDT
· 95% has been replenished, with the remaining 5% in low-liquidity coins
· The FBI has published a list of the hackers’ wallet addresses
🔍 The key contradiction
Previously, you had a point of protection: no one would proactively DM you about withdrawals. But this time, withdrawals are paused, queued, and delayed—the platform itself is creating the anxiety, so scammers don’t need to. Four common scripts: pay a fee to speed up withdrawals; click a link to qualify for compensation; your withdrawal is frozen, so use this link to unlock it; or transfer funds to a “safe wallet.” The last two are the most dangerous: they exploit the “I’m cooperating with you” mindset, and an on-chain signature cannot be undone.
🧊 Three reality checks
1. This Binance announcement is training scammers—it lays out the talking points one by one, effectively organizing a framework for their scripts.
2. Replenishing the remaining 5% could take a long time; low-liquidity coins can only be handled through OTC. “95% replenished” describes the situation now, not the finish line.
3. Don’t interpret the 4.72 billion in net outflows as a collapse in confidence. OKX has only 29 billion in total, and most of this is USDT being moved, not sold. The real selling pressure is the 279 million on-chain—an order of magnitude smaller.
💡 My take
The most useful line in the official reminder is “check withdrawal progress only in the app.” Don’t touch any external links, even domains that look similar. Set another rule: anyone who contacts you first is a scammer by default.
I’m not in a hurry on the market side. The main wave of selling pressure has already landed, and 279 million is not in the same league as 171 billion in AUM. What’s worth watching instead is “slowing net outflows + deposits staying high.”
One more reminder: U.S. midterm election voting is on 11/3, and the nonfarm payrolls report is on 11/6. First make sure your withdrawal route is secure, then think about your positions.
⚠️ Not investment advice. On-chain approvals cannot be undone. Official compensation is handled only in the app—don’t click external links.
Follow @A-Sue’s Crypto Journal · Using data to expose false signals in crypto
#Binance #BinanceHack #Withdrawals #ScamPrevention #Bitcoin
11/2 Binance issued a security reminder warning users to watch out for scams during the withdrawal phase. My first thought wasn’t “be careful”—it was that scammers now have an official announcement to use as a script.
📊 Key figures
· Around 6.3 billion was stolen on 10/29; withdrawals resumed on 11/1
· On 11/1, 4.649 billion was withdrawn and 1.01 billion deposited, for a net outflow of 3.64 billion, or 2.1% of AUM
· As of 11/2, cumulative net withdrawals totaled 4.72 billion, or 3% of platform assets, mainly in USDT
· 95% has been replenished, with the remaining 5% in low-liquidity coins
· The FBI has published a list of the hackers’ wallet addresses
🔍 The key contradiction
Previously, you had a point of protection: no one would proactively DM you about withdrawals. But this time, withdrawals are paused, queued, and delayed—the platform itself is creating the anxiety, so scammers don’t need to. Four common scripts: pay a fee to speed up withdrawals; click a link to qualify for compensation; your withdrawal is frozen, so use this link to unlock it; or transfer funds to a “safe wallet.” The last two are the most dangerous: they exploit the “I’m cooperating with you” mindset, and an on-chain signature cannot be undone.
🧊 Three reality checks
1. This Binance announcement is training scammers—it lays out the talking points one by one, effectively organizing a framework for their scripts.
2. Replenishing the remaining 5% could take a long time; low-liquidity coins can only be handled through OTC. “95% replenished” describes the situation now, not the finish line.
3. Don’t interpret the 4.72 billion in net outflows as a collapse in confidence. OKX has only 29 billion in total, and most of this is USDT being moved, not sold. The real selling pressure is the 279 million on-chain—an order of magnitude smaller.
💡 My take
The most useful line in the official reminder is “check withdrawal progress only in the app.” Don’t touch any external links, even domains that look similar. Set another rule: anyone who contacts you first is a scammer by default.
I’m not in a hurry on the market side. The main wave of selling pressure has already landed, and 279 million is not in the same league as 171 billion in AUM. What’s worth watching instead is “slowing net outflows + deposits staying high.”
One more reminder: U.S. midterm election voting is on 11/3, and the nonfarm payrolls report is on 11/6. First make sure your withdrawal route is secure, then think about your positions.
⚠️ Not investment advice. On-chain approvals cannot be undone. Official compensation is handled only in the app—don’t click external links.
Follow @A-Sue’s Crypto Journal · Using data to expose false signals in crypto
#Binance #BinanceHack #Withdrawals #ScamPrevention #Bitcoin
18
·
--
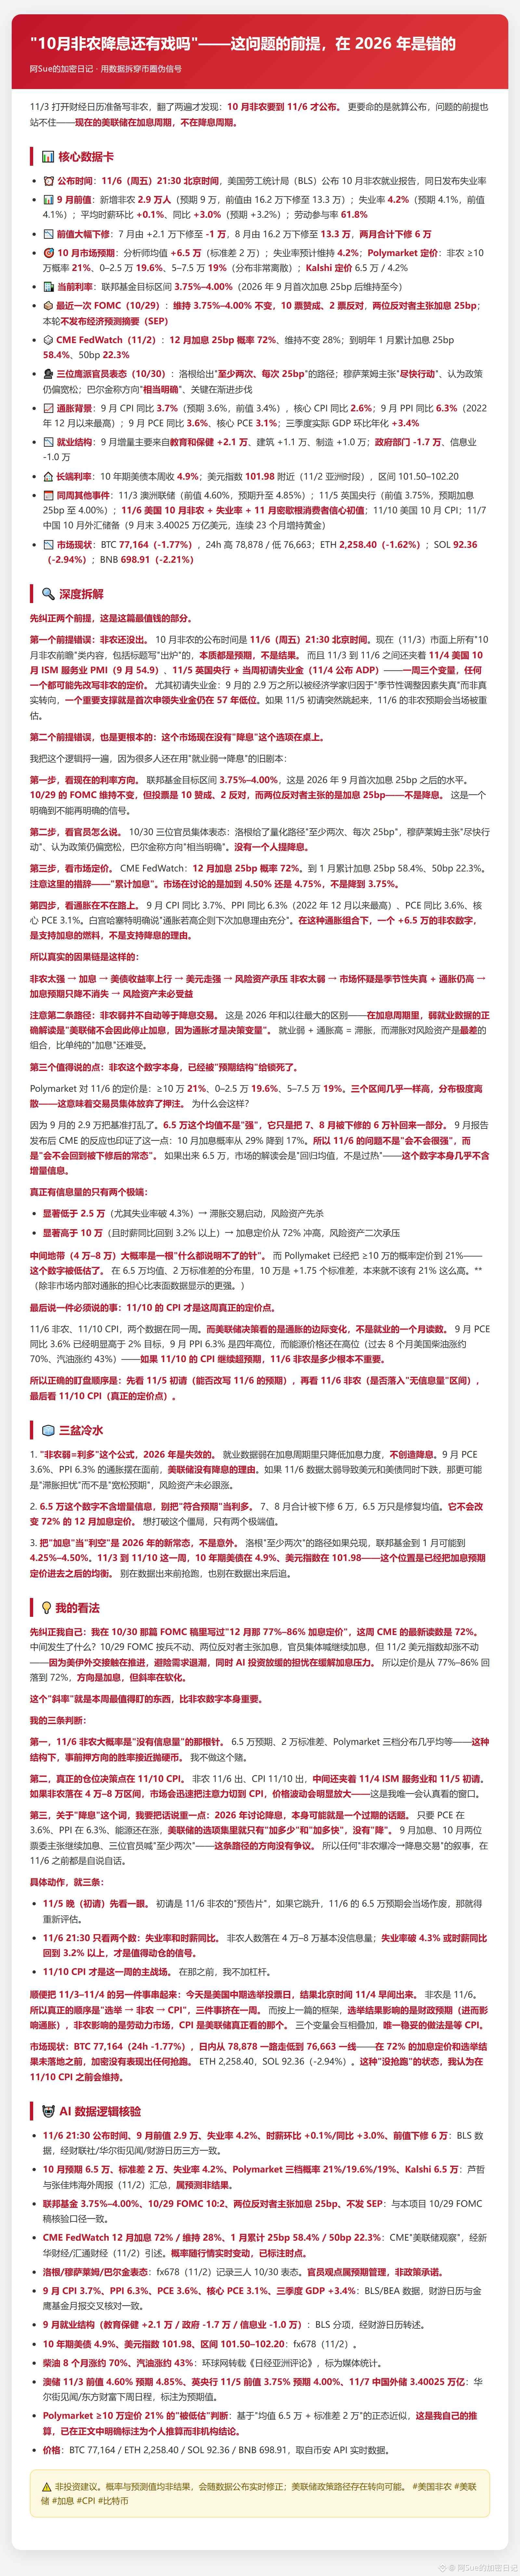
#美国10月非农出炉:降息还有戏吗? "Is an October payrolls rate cut still on the table?" — That premise was already wrong in 2026
I checked the calendar on 11/3 and realized: October payrolls aren’t released until 11/6. The bigger problem is that the premise doesn’t hold up—the Fed is in a rate-hiking cycle, not a rate-cutting cycle.
📊 Key data
· Released Friday, 11/6, at 21:30; September added 29,000 jobs (vs. 90,000 expected), unemployment rate 4.2%
· October forecast: +65,000; July and August were revised down by a combined 60,000
· Federal funds rate: 3.75%–4.00%; rates were raised in September
· FOMC held rates steady on 10/29, with 10 votes in favor and 2 against; both dissenters favored a hike
· CME: 72% probability of a 25bp hike in December
· September CPI: 3.7%; PPI up 6.3% year over year
🔍 The key contradiction
The market isn’t pricing in a “rate cut” scenario. Three hawkish officials spoke on 10/30, and not one mentioned rate cuts. The actual chain of events is: payrolls too strong → rate hike → stronger dollar and pressure on assets; payrolls too weak → doubts about seasonal distortions, while inflation remains high → rate-hike expectations ease but don’t disappear. Weak employment alongside high inflation is stagflation—and harder to deal with than a rate hike.
A 65,000 reading adds no new information—after the 60,000 revisions to July and August, it just brings the numbers back to normal. The only readings that would tell us something are the two extremes: below 25,000 or above 100,000.
🧊 Three reality checks
1. “Weak payrolls = bullish” no longer holds in 2026. Weak employment only reduces the scale of rate hikes; it doesn’t create a case for cuts. PCE is sitting at 3.6%.
2. Don’t treat “in line with expectations” as bullish. The 65,000 forecast adjusts the average; it doesn’t change the 72% pricing.
3. Don’t treat a rate hike as a surprise. If we get two hikes, January puts rates at 4.25%–4.50%.
💡 My take
In my 10/30 FOMC post, I wrote about “December’s 77%–86% rate-hike pricing.” This week, CME’s reading is 72%. The direction is still toward a hike, but the pace is easing—U.S.–Iran diplomacy is reducing safe-haven demand, while a slowdown in AI is easing pressure. The pace matters more.
I’m not betting on 11/6: with a 65,000 forecast, a 20,000 standard deviation, and nearly even odds across three ranges, betting on the direction is close to a coin flip. My plan: check initial jobless claims on 11/5 first; if they jump, the forecast is out the window. On 11/6, I’ll focus only on the unemployment rate and year-over-year hourly earnings; I’ll adjust my position only if unemployment breaks 4.3%. The key pricing event is CPI on 11/10.
BTC is currently at 76994, down 1.81% over 24h. The market isn’t betting on a direction.
⚠️ Not investment advice. Probabilities and forecasts are not outcomes and may change as data is revised.
Follow @阿Sue的加密日记 · Using data to expose crypto market false signals
#USNonfarmPayrolls #FederalReserve #RateHike #CPI #Bitcoin
#美国10月非农出炉:降息还有戏吗? "Is an October payrolls rate cut still on the table?" — That premise was already wrong in 2026
I checked the calendar on 11/3 and realized: October payrolls aren’t released until 11/6. The bigger problem is that the premise doesn’t hold up—the Fed is in a rate-hiking cycle, not a rate-cutting cycle.
📊 Key data
· Released Friday, 11/6, at 21:30; September added 29,000 jobs (vs. 90,000 expected), unemployment rate 4.2%
· October forecast: +65,000; July and August were revised down by a combined 60,000
· Federal funds rate: 3.75%–4.00%; rates were raised in September
· FOMC held rates steady on 10/29, with 10 votes in favor and 2 against; both dissenters favored a hike
· CME: 72% probability of a 25bp hike in December
· September CPI: 3.7%; PPI up 6.3% year over year
🔍 The key contradiction
The market isn’t pricing in a “rate cut” scenario. Three hawkish officials spoke on 10/30, and not one mentioned rate cuts. The actual chain of events is: payrolls too strong → rate hike → stronger dollar and pressure on assets; payrolls too weak → doubts about seasonal distortions, while inflation remains high → rate-hike expectations ease but don’t disappear. Weak employment alongside high inflation is stagflation—and harder to deal with than a rate hike.
A 65,000 reading adds no new information—after the 60,000 revisions to July and August, it just brings the numbers back to normal. The only readings that would tell us something are the two extremes: below 25,000 or above 100,000.
🧊 Three reality checks
1. “Weak payrolls = bullish” no longer holds in 2026. Weak employment only reduces the scale of rate hikes; it doesn’t create a case for cuts. PCE is sitting at 3.6%.
2. Don’t treat “in line with expectations” as bullish. The 65,000 forecast adjusts the average; it doesn’t change the 72% pricing.
3. Don’t treat a rate hike as a surprise. If we get two hikes, January puts rates at 4.25%–4.50%.
💡 My take
In my 10/30 FOMC post, I wrote about “December’s 77%–86% rate-hike pricing.” This week, CME’s reading is 72%. The direction is still toward a hike, but the pace is easing—U.S.–Iran diplomacy is reducing safe-haven demand, while a slowdown in AI is easing pressure. The pace matters more.
I’m not betting on 11/6: with a 65,000 forecast, a 20,000 standard deviation, and nearly even odds across three ranges, betting on the direction is close to a coin flip. My plan: check initial jobless claims on 11/5 first; if they jump, the forecast is out the window. On 11/6, I’ll focus only on the unemployment rate and year-over-year hourly earnings; I’ll adjust my position only if unemployment breaks 4.3%. The key pricing event is CPI on 11/10.
BTC is currently at 76994, down 1.81% over 24h. The market isn’t betting on a direction.
⚠️ Not investment advice. Probabilities and forecasts are not outcomes and may change as data is revised.
Follow @阿Sue的加密日记 · Using data to expose crypto market false signals
#USNonfarmPayrolls #FederalReserve #RateHike #CPI #Bitcoin
I checked the calendar on 11/3 and realized: October payrolls aren’t released until 11/6. The bigger problem is that the premise doesn’t hold up—the Fed is in a rate-hiking cycle, not a rate-cutting cycle.
📊 Key data
· Released Friday, 11/6, at 21:30; September added 29,000 jobs (vs. 90,000 expected), unemployment rate 4.2%
· October forecast: +65,000; July and August were revised down by a combined 60,000
· Federal funds rate: 3.75%–4.00%; rates were raised in September
· FOMC held rates steady on 10/29, with 10 votes in favor and 2 against; both dissenters favored a hike
· CME: 72% probability of a 25bp hike in December
· September CPI: 3.7%; PPI up 6.3% year over year
🔍 The key contradiction
The market isn’t pricing in a “rate cut” scenario. Three hawkish officials spoke on 10/30, and not one mentioned rate cuts. The actual chain of events is: payrolls too strong → rate hike → stronger dollar and pressure on assets; payrolls too weak → doubts about seasonal distortions, while inflation remains high → rate-hike expectations ease but don’t disappear. Weak employment alongside high inflation is stagflation—and harder to deal with than a rate hike.
A 65,000 reading adds no new information—after the 60,000 revisions to July and August, it just brings the numbers back to normal. The only readings that would tell us something are the two extremes: below 25,000 or above 100,000.
🧊 Three reality checks
1. “Weak payrolls = bullish” no longer holds in 2026. Weak employment only reduces the scale of rate hikes; it doesn’t create a case for cuts. PCE is sitting at 3.6%.
2. Don’t treat “in line with expectations” as bullish. The 65,000 forecast adjusts the average; it doesn’t change the 72% pricing.
3. Don’t treat a rate hike as a surprise. If we get two hikes, January puts rates at 4.25%–4.50%.
💡 My take
In my 10/30 FOMC post, I wrote about “December’s 77%–86% rate-hike pricing.” This week, CME’s reading is 72%. The direction is still toward a hike, but the pace is easing—U.S.–Iran diplomacy is reducing safe-haven demand, while a slowdown in AI is easing pressure. The pace matters more.
I’m not betting on 11/6: with a 65,000 forecast, a 20,000 standard deviation, and nearly even odds across three ranges, betting on the direction is close to a coin flip. My plan: check initial jobless claims on 11/5 first; if they jump, the forecast is out the window. On 11/6, I’ll focus only on the unemployment rate and year-over-year hourly earnings; I’ll adjust my position only if unemployment breaks 4.3%. The key pricing event is CPI on 11/10.
BTC is currently at 76994, down 1.81% over 24h. The market isn’t betting on a direction.
⚠️ Not investment advice. Probabilities and forecasts are not outcomes and may change as data is revised.
Follow @阿Sue的加密日记 · Using data to expose crypto market false signals
#USNonfarmPayrolls #FederalReserve #RateHike #CPI #Bitcoin
508
·
--
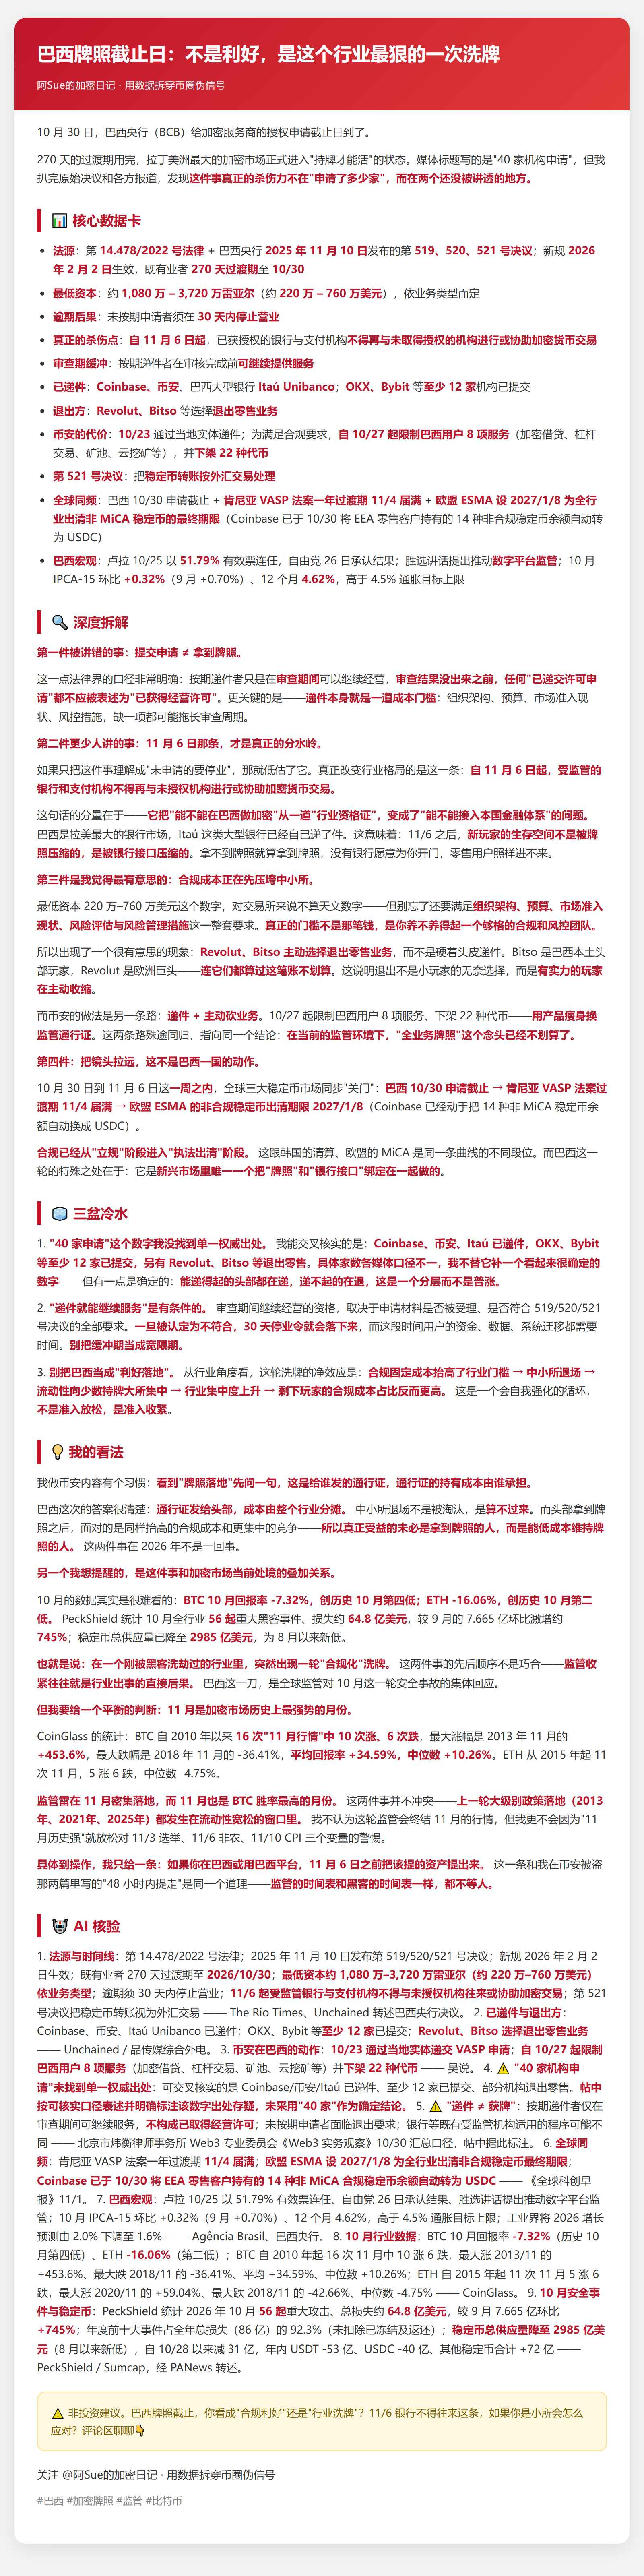
#巴西虚拟资产牌照约40家机构申请 Brazil’s licensing deadline! The real blow comes on November 6
Brazil’s central bank authorization application deadline was October 30, and the 270-day transition period has ended. After digging through the original resolutions, I found that the real impact isn’t “how many firms applied.”
📊 Key figures
· Legal basis: Law No. 14.478/2022 and Central Bank Resolutions 519–521
· Minimum capital: 10.8 million–37.2 million reais
· Overdue firms must cease operations within 30 days
· Starting November 6, banks and payment institutions may not do business with unauthorized firms
· Coinbase, Binance, and Itaú have filed applications, along with at least 12 others, including OKX
🔍 The key contradictions
1. Filing an application doesn’t mean getting a license. Those who apply on time may continue providing services only while their applications are under review. 2. November 6 is the real turning point—regulated banks and payment institutions may no longer do business with unauthorized firms or facilitate crypto transactions. This makes operating in crypto dependent on access to the country’s financial system. 3. Compliance costs are already squeezing out smaller exchanges: the hurdle isn’t the capital itself, but whether you can afford to maintain a compliance team.
🧊 Three reality checks
1. I couldn’t find a single authoritative source for “40 applicants.” What can be verified is that Coinbase, Binance, and Itaú have filed applications.
2. “Filing lets you keep operating” comes with conditions: if a firm is found non-compliant, it will be ordered to cease operations within 30 days.
3. Don’t treat Brazil as a positive development already in the bag. The net effect is higher compliance costs raising the bar → smaller exchanges exiting → liquidity concentrating among a handful of large, licensed exchanges.
💡 My take
I have a habit when creating Binance content: whenever I see “licenses granted,” I first ask who gets the pass and who bears the cost. The answer is clear: the pass goes to the biggest players, while the costs are shared across the industry. Smaller exchanges aren’t being eliminated—they just can’t make the numbers work.
October’s figures look rough—BTC returned -7.32%, its fourth-worst October on record, while ETH was down 16.06%, its second-worst. There were 56 major attacks in October, with losses of about $6.48 billion, up 745% month over month. November is crypto’s strongest month: since 2010, BTC has risen in 10 of 16 Novembers and fallen in 6, with an average return of +34.59%.
🤖 AI verification
Legal basis and timeline, minimum capital, 30-day shutdown for overdue firms, and the November 6 restriction on banks doing business with unauthorized firms—all based on Unchained’s account of the central bank resolutions. Coinbase, Binance, and Itaú have filed applications. “Filing ≠ getting a license” is according to Weiheng Law Firm. October: BTC -7.32%, ETH -16.06%—CoinGlass.
⚠️ Not investment advice. Do you see Brazil’s licensing deadline as a compliance boost or an industry shakeout? Let me know in the comments.
#巴西虚拟资产牌照约40家机构申请 Brazil’s licensing deadline! The real blow comes on November 6
Brazil’s central bank authorization application deadline was October 30, and the 270-day transition period has ended. After digging through the original resolutions, I found that the real impact isn’t “how many firms applied.”
📊 Key figures
· Legal basis: Law No. 14.478/2022 and Central Bank Resolutions 519–521
· Minimum capital: 10.8 million–37.2 million reais
· Overdue firms must cease operations within 30 days
· Starting November 6, banks and payment institutions may not do business with unauthorized firms
· Coinbase, Binance, and Itaú have filed applications, along with at least 12 others, including OKX
🔍 The key contradictions
1. Filing an application doesn’t mean getting a license. Those who apply on time may continue providing services only while their applications are under review. 2. November 6 is the real turning point—regulated banks and payment institutions may no longer do business with unauthorized firms or facilitate crypto transactions. This makes operating in crypto dependent on access to the country’s financial system. 3. Compliance costs are already squeezing out smaller exchanges: the hurdle isn’t the capital itself, but whether you can afford to maintain a compliance team.
🧊 Three reality checks
1. I couldn’t find a single authoritative source for “40 applicants.” What can be verified is that Coinbase, Binance, and Itaú have filed applications.
2. “Filing lets you keep operating” comes with conditions: if a firm is found non-compliant, it will be ordered to cease operations within 30 days.
3. Don’t treat Brazil as a positive development already in the bag. The net effect is higher compliance costs raising the bar → smaller exchanges exiting → liquidity concentrating among a handful of large, licensed exchanges.
💡 My take
I have a habit when creating Binance content: whenever I see “licenses granted,” I first ask who gets the pass and who bears the cost. The answer is clear: the pass goes to the biggest players, while the costs are shared across the industry. Smaller exchanges aren’t being eliminated—they just can’t make the numbers work.
October’s figures look rough—BTC returned -7.32%, its fourth-worst October on record, while ETH was down 16.06%, its second-worst. There were 56 major attacks in October, with losses of about $6.48 billion, up 745% month over month. November is crypto’s strongest month: since 2010, BTC has risen in 10 of 16 Novembers and fallen in 6, with an average return of +34.59%.
🤖 AI verification
Legal basis and timeline, minimum capital, 30-day shutdown for overdue firms, and the November 6 restriction on banks doing business with unauthorized firms—all based on Unchained’s account of the central bank resolutions. Coinbase, Binance, and Itaú have filed applications. “Filing ≠ getting a license” is according to Weiheng Law Firm. October: BTC -7.32%, ETH -16.06%—CoinGlass.
⚠️ Not investment advice. Do you see Brazil’s licensing deadline as a compliance boost or an industry shakeout? Let me know in the comments.
Brazil’s central bank authorization application deadline was October 30, and the 270-day transition period has ended. After digging through the original resolutions, I found that the real impact isn’t “how many firms applied.”
📊 Key figures
· Legal basis: Law No. 14.478/2022 and Central Bank Resolutions 519–521
· Minimum capital: 10.8 million–37.2 million reais
· Overdue firms must cease operations within 30 days
· Starting November 6, banks and payment institutions may not do business with unauthorized firms
· Coinbase, Binance, and Itaú have filed applications, along with at least 12 others, including OKX
🔍 The key contradictions
1. Filing an application doesn’t mean getting a license. Those who apply on time may continue providing services only while their applications are under review. 2. November 6 is the real turning point—regulated banks and payment institutions may no longer do business with unauthorized firms or facilitate crypto transactions. This makes operating in crypto dependent on access to the country’s financial system. 3. Compliance costs are already squeezing out smaller exchanges: the hurdle isn’t the capital itself, but whether you can afford to maintain a compliance team.
🧊 Three reality checks
1. I couldn’t find a single authoritative source for “40 applicants.” What can be verified is that Coinbase, Binance, and Itaú have filed applications.
2. “Filing lets you keep operating” comes with conditions: if a firm is found non-compliant, it will be ordered to cease operations within 30 days.
3. Don’t treat Brazil as a positive development already in the bag. The net effect is higher compliance costs raising the bar → smaller exchanges exiting → liquidity concentrating among a handful of large, licensed exchanges.
💡 My take
I have a habit when creating Binance content: whenever I see “licenses granted,” I first ask who gets the pass and who bears the cost. The answer is clear: the pass goes to the biggest players, while the costs are shared across the industry. Smaller exchanges aren’t being eliminated—they just can’t make the numbers work.
October’s figures look rough—BTC returned -7.32%, its fourth-worst October on record, while ETH was down 16.06%, its second-worst. There were 56 major attacks in October, with losses of about $6.48 billion, up 745% month over month. November is crypto’s strongest month: since 2010, BTC has risen in 10 of 16 Novembers and fallen in 6, with an average return of +34.59%.
🤖 AI verification
Legal basis and timeline, minimum capital, 30-day shutdown for overdue firms, and the November 6 restriction on banks doing business with unauthorized firms—all based on Unchained’s account of the central bank resolutions. Coinbase, Binance, and Itaú have filed applications. “Filing ≠ getting a license” is according to Weiheng Law Firm. October: BTC -7.32%, ETH -16.06%—CoinGlass.
⚠️ Not investment advice. Do you see Brazil’s licensing deadline as a compliance boost or an industry shakeout? Let me know in the comments.
2
3
2.6k
·
--
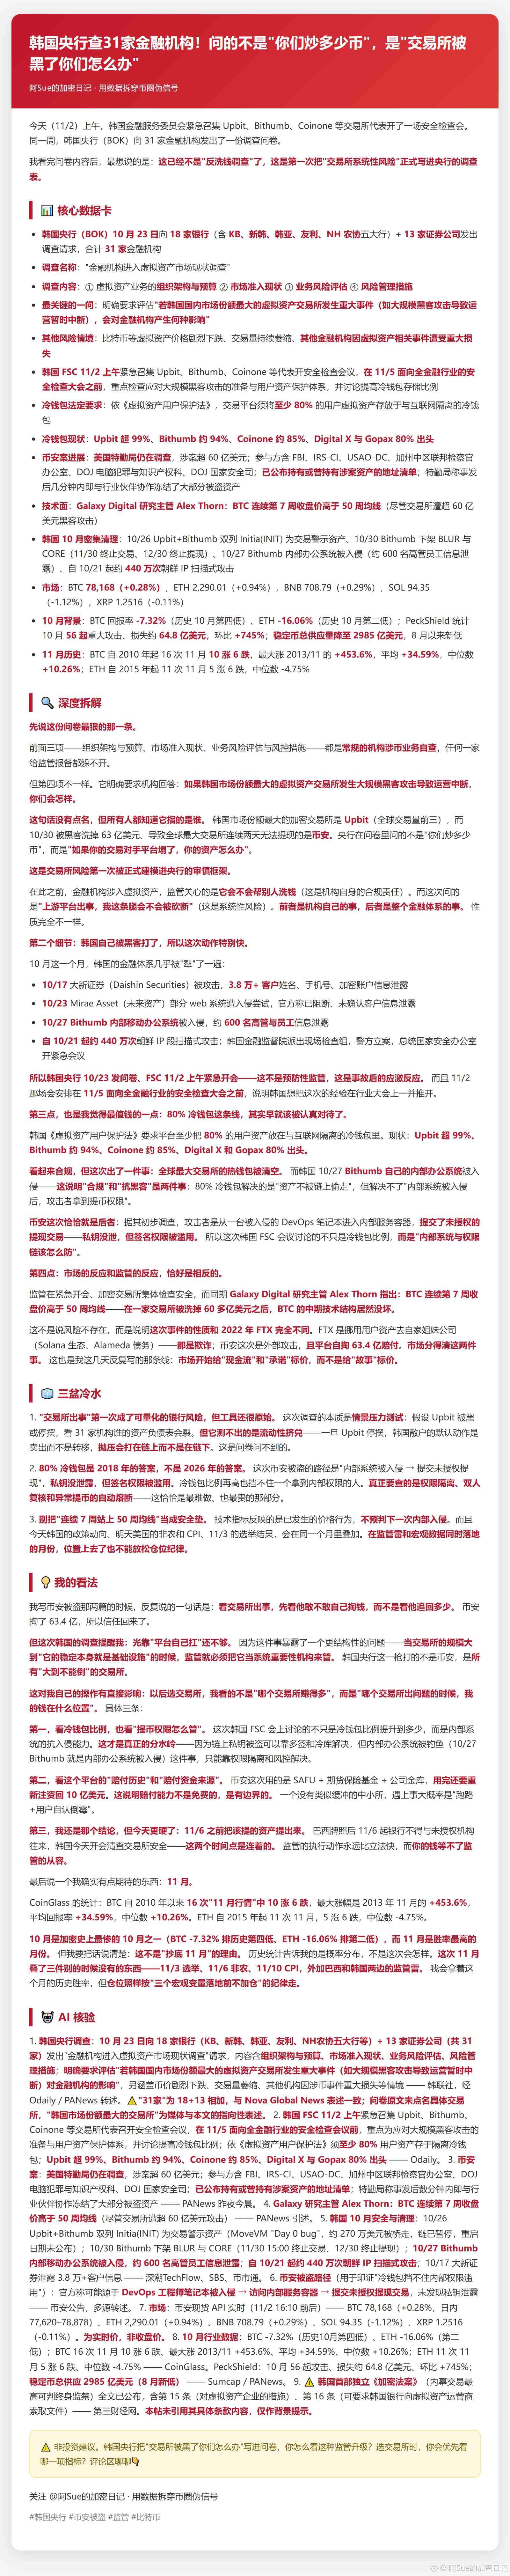
#韩国央行调查虚拟资产业务风险 South Korea’s central bank probes 31 financial institutions! It’s not asking how much crypto you trade
South Korea’s FSC convenes the three major exchanges for a security review; that same week, the central bank sent questionnaires to 31 institutions.
📊 Key figures
· On 10/23, the Bank of Korea sent survey requests to 18 banks + 13 securities firms (31 in total)
· Topics: organizational structure, market access, risk assessment, and risk controls
· The key question: What impact would a hack of the largest exchange have on financial institutions?
· The FSC held a meeting on the morning of 11/2, ahead of an industry conference on 11/5
· At least 80% in cold wallets by law: Upbit >99%, Bithumb 94%
🔍 The key contradiction
The first three items are routine self-assessments. The fourth is different: it explicitly asks institutions to explain what would happen if the virtual asset exchange with the largest market share in South Korea suffered a major hack that disrupted its operations. It doesn’t name names, but everyone knows who it means. This time, they’re asking whether trouble at an upstream platform could cut off one of my lifelines.
🧊 Three reality checks
1. “An exchange going down” has, for the first time, become a quantifiable banking risk. Essentially, it’s a stress test: assume Upbit gets hacked and see who cracks. But it can’t measure a liquidity run, with selling pressure hitting on-chain.
2. The 80% cold-wallet rule is an answer from 2018. The recent Binance theft involved an unauthorized withdrawal submitted after an internal system was compromised. Cold wallets can’t stop abuse of access privileges.
3. Don’t treat seven straight weeks above the 50-week moving average as a safety net. Technical indicators can’t predict the next breach.
💡 My take
When I wrote those two articles about the Binance theft, I kept saying: when trouble hits, first see whether they’re willing to pay out of their own pocket. But this survey reminded me that relying on the platform to bear the burden itself isn’t enough—when an exchange gets so big that its stability becomes infrastructure, regulators have to oversee it as a systemically important institution.
When choosing an exchange, I don’t look at which one makes the most money. Three things: check the cold-wallet ratio and withdrawal permissions; check where compensation funds come from; withdraw before 11/6.
#韩国央行调查虚拟资产业务风险 South Korea’s central bank probes 31 financial institutions! It’s not asking how much crypto you trade
South Korea’s FSC convenes the three major exchanges for a security review; that same week, the central bank sent questionnaires to 31 institutions.
📊 Key figures
· On 10/23, the Bank of Korea sent survey requests to 18 banks + 13 securities firms (31 in total)
· Topics: organizational structure, market access, risk assessment, and risk controls
· The key question: What impact would a hack of the largest exchange have on financial institutions?
· The FSC held a meeting on the morning of 11/2, ahead of an industry conference on 11/5
· At least 80% in cold wallets by law: Upbit >99%, Bithumb 94%
🔍 The key contradiction
The first three items are routine self-assessments. The fourth is different: it explicitly asks institutions to explain what would happen if the virtual asset exchange with the largest market share in South Korea suffered a major hack that disrupted its operations. It doesn’t name names, but everyone knows who it means. This time, they’re asking whether trouble at an upstream platform could cut off one of my lifelines.
🧊 Three reality checks
1. “An exchange going down” has, for the first time, become a quantifiable banking risk. Essentially, it’s a stress test: assume Upbit gets hacked and see who cracks. But it can’t measure a liquidity run, with selling pressure hitting on-chain.
2. The 80% cold-wallet rule is an answer from 2018. The recent Binance theft involved an unauthorized withdrawal submitted after an internal system was compromised. Cold wallets can’t stop abuse of access privileges.
3. Don’t treat seven straight weeks above the 50-week moving average as a safety net. Technical indicators can’t predict the next breach.
💡 My take
When I wrote those two articles about the Binance theft, I kept saying: when trouble hits, first see whether they’re willing to pay out of their own pocket. But this survey reminded me that relying on the platform to bear the burden itself isn’t enough—when an exchange gets so big that its stability becomes infrastructure, regulators have to oversee it as a systemically important institution.
When choosing an exchange, I don’t look at which one makes the most money. Three things: check the cold-wallet ratio and withdrawal permissions; check where compensation funds come from; withdraw before 11/6.
South Korea’s FSC convenes the three major exchanges for a security review; that same week, the central bank sent questionnaires to 31 institutions.
📊 Key figures
· On 10/23, the Bank of Korea sent survey requests to 18 banks + 13 securities firms (31 in total)
· Topics: organizational structure, market access, risk assessment, and risk controls
· The key question: What impact would a hack of the largest exchange have on financial institutions?
· The FSC held a meeting on the morning of 11/2, ahead of an industry conference on 11/5
· At least 80% in cold wallets by law: Upbit >99%, Bithumb 94%
🔍 The key contradiction
The first three items are routine self-assessments. The fourth is different: it explicitly asks institutions to explain what would happen if the virtual asset exchange with the largest market share in South Korea suffered a major hack that disrupted its operations. It doesn’t name names, but everyone knows who it means. This time, they’re asking whether trouble at an upstream platform could cut off one of my lifelines.
🧊 Three reality checks
1. “An exchange going down” has, for the first time, become a quantifiable banking risk. Essentially, it’s a stress test: assume Upbit gets hacked and see who cracks. But it can’t measure a liquidity run, with selling pressure hitting on-chain.
2. The 80% cold-wallet rule is an answer from 2018. The recent Binance theft involved an unauthorized withdrawal submitted after an internal system was compromised. Cold wallets can’t stop abuse of access privileges.
3. Don’t treat seven straight weeks above the 50-week moving average as a safety net. Technical indicators can’t predict the next breach.
💡 My take
When I wrote those two articles about the Binance theft, I kept saying: when trouble hits, first see whether they’re willing to pay out of their own pocket. But this survey reminded me that relying on the platform to bear the burden itself isn’t enough—when an exchange gets so big that its stability becomes infrastructure, regulators have to oversee it as a systemically important institution.
When choosing an exchange, I don’t look at which one makes the most money. Three things: check the cold-wallet ratio and withdrawal permissions; check where compensation funds come from; withdraw before 11/6.
2
715
·
--
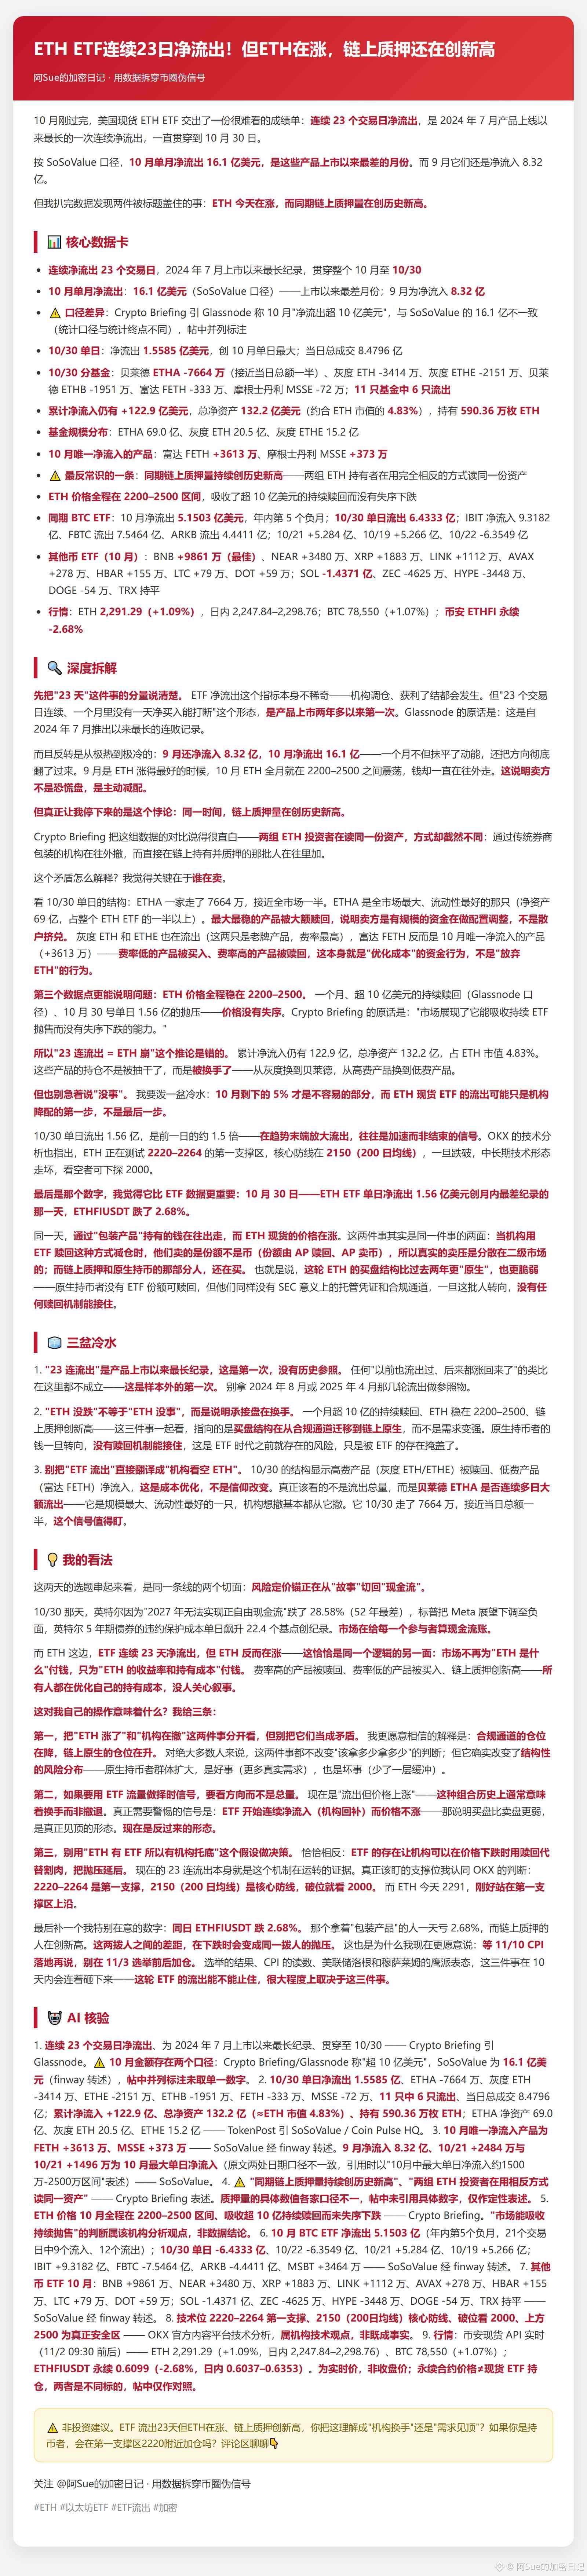
#美国现货ethetf连续23日净流出 ETH ETF outflows for 23 straight days! But ETH is rising, and on-chain staking hits a new high
October is over, and U.S. spot ETH ETFs have seen outflows for 23 consecutive trading days—the longest streak since their launch. But what’s being overlooked is this: ETH is rising, and on-chain staking is still hitting new highs.
📊 Key figures
· 23 consecutive days of outflows, the longest streak since launch in July 2024
· $1.61 billion in outflows in October, the worst month on record
· $832 million in net inflows in September—a reversal in just one month
· $155.85 million in outflows on 10/30, with ETHA accounting for nearly half
· On-chain staking hit a new high over the same period—the two groups are moving in opposite directions
🔍 The key contradiction
What really made me stop and think was the paradox: on-chain staking hit a new high over the same period. Two groups of ETH investors are looking at the same asset but acting in completely different ways: institutions using brokerage-wrapped products are pulling out, while on-chain stakers are adding more. On 10/30, ETHA saw $76.64 million in outflows, suggesting that large investors are actively reducing their positions. The only fund with net inflows in October was Fidelity’s low-fee FETH.
🧊 Three reality checks
1. The 23-day outflow streak is the longest since launch. This is the first time it’s happened, so there’s no historical precedent—comparisons with previous cycles don’t hold up.
2. ETH not falling doesn’t mean everything is fine; it means the holders are changing. Buying is shifting from regulated channels to on-chain-native options. If native holders change course, there’s no redemption mechanism to absorb the selling.
3. Don’t interpret outflows as institutions turning bearish. Redemptions from high-fee funds and buying into low-fee ones point to cost optimization. What you should watch is whether ETHA sees large outflows for several days in a row.
💡 My take
The topics I’ve covered over the past two days connect to the same theme: the valuation anchor is shifting from narratives back to cash flow. On 10/30, Intel fell 28.58% because it couldn’t achieve positive free cash flow by 2027, and S&P downgraded its outlook for Meta. ETH, meanwhile, is rising despite 23 straight days of ETF outflows—the market only pays for yield.
My view: ETH rising despite 23 days of outflows points to a rotation in holders, not an exit. But outflows on 10/30 were 1.5 times the previous day’s, and an end-of-streak surge often signals acceleration. If native holders change course, there’s no redemption mechanism to absorb the selling. I wouldn’t add to my position ahead of the 11/3 election, 11/6 jobs report, and 11/10 CPI release.
⚠️ Not investment advice. With ETF outflows for 23 days but ETH rising, is this a rotation or a market top? Let’s discuss in the comments 👇
Follow @阿Sue的加密日记 · Using data to expose crypto market false signals
#ETH #EthereumETF #ETFOutflows #Crypto
#美国现货ethetf连续23日净流出 ETH ETF outflows for 23 straight days! But ETH is rising, and on-chain staking hits a new high
October is over, and U.S. spot ETH ETFs have seen outflows for 23 consecutive trading days—the longest streak since their launch. But what’s being overlooked is this: ETH is rising, and on-chain staking is still hitting new highs.
📊 Key figures
· 23 consecutive days of outflows, the longest streak since launch in July 2024
· $1.61 billion in outflows in October, the worst month on record
· $832 million in net inflows in September—a reversal in just one month
· $155.85 million in outflows on 10/30, with ETHA accounting for nearly half
· On-chain staking hit a new high over the same period—the two groups are moving in opposite directions
🔍 The key contradiction
What really made me stop and think was the paradox: on-chain staking hit a new high over the same period. Two groups of ETH investors are looking at the same asset but acting in completely different ways: institutions using brokerage-wrapped products are pulling out, while on-chain stakers are adding more. On 10/30, ETHA saw $76.64 million in outflows, suggesting that large investors are actively reducing their positions. The only fund with net inflows in October was Fidelity’s low-fee FETH.
🧊 Three reality checks
1. The 23-day outflow streak is the longest since launch. This is the first time it’s happened, so there’s no historical precedent—comparisons with previous cycles don’t hold up.
2. ETH not falling doesn’t mean everything is fine; it means the holders are changing. Buying is shifting from regulated channels to on-chain-native options. If native holders change course, there’s no redemption mechanism to absorb the selling.
3. Don’t interpret outflows as institutions turning bearish. Redemptions from high-fee funds and buying into low-fee ones point to cost optimization. What you should watch is whether ETHA sees large outflows for several days in a row.
💡 My take
The topics I’ve covered over the past two days connect to the same theme: the valuation anchor is shifting from narratives back to cash flow. On 10/30, Intel fell 28.58% because it couldn’t achieve positive free cash flow by 2027, and S&P downgraded its outlook for Meta. ETH, meanwhile, is rising despite 23 straight days of ETF outflows—the market only pays for yield.
My view: ETH rising despite 23 days of outflows points to a rotation in holders, not an exit. But outflows on 10/30 were 1.5 times the previous day’s, and an end-of-streak surge often signals acceleration. If native holders change course, there’s no redemption mechanism to absorb the selling. I wouldn’t add to my position ahead of the 11/3 election, 11/6 jobs report, and 11/10 CPI release.
⚠️ Not investment advice. With ETF outflows for 23 days but ETH rising, is this a rotation or a market top? Let’s discuss in the comments 👇
Follow @阿Sue的加密日记 · Using data to expose crypto market false signals
#ETH #EthereumETF #ETFOutflows #Crypto
October is over, and U.S. spot ETH ETFs have seen outflows for 23 consecutive trading days—the longest streak since their launch. But what’s being overlooked is this: ETH is rising, and on-chain staking is still hitting new highs.
📊 Key figures
· 23 consecutive days of outflows, the longest streak since launch in July 2024
· $1.61 billion in outflows in October, the worst month on record
· $832 million in net inflows in September—a reversal in just one month
· $155.85 million in outflows on 10/30, with ETHA accounting for nearly half
· On-chain staking hit a new high over the same period—the two groups are moving in opposite directions
🔍 The key contradiction
What really made me stop and think was the paradox: on-chain staking hit a new high over the same period. Two groups of ETH investors are looking at the same asset but acting in completely different ways: institutions using brokerage-wrapped products are pulling out, while on-chain stakers are adding more. On 10/30, ETHA saw $76.64 million in outflows, suggesting that large investors are actively reducing their positions. The only fund with net inflows in October was Fidelity’s low-fee FETH.
🧊 Three reality checks
1. The 23-day outflow streak is the longest since launch. This is the first time it’s happened, so there’s no historical precedent—comparisons with previous cycles don’t hold up.
2. ETH not falling doesn’t mean everything is fine; it means the holders are changing. Buying is shifting from regulated channels to on-chain-native options. If native holders change course, there’s no redemption mechanism to absorb the selling.
3. Don’t interpret outflows as institutions turning bearish. Redemptions from high-fee funds and buying into low-fee ones point to cost optimization. What you should watch is whether ETHA sees large outflows for several days in a row.
💡 My take
The topics I’ve covered over the past two days connect to the same theme: the valuation anchor is shifting from narratives back to cash flow. On 10/30, Intel fell 28.58% because it couldn’t achieve positive free cash flow by 2027, and S&P downgraded its outlook for Meta. ETH, meanwhile, is rising despite 23 straight days of ETF outflows—the market only pays for yield.
My view: ETH rising despite 23 days of outflows points to a rotation in holders, not an exit. But outflows on 10/30 were 1.5 times the previous day’s, and an end-of-streak surge often signals acceleration. If native holders change course, there’s no redemption mechanism to absorb the selling. I wouldn’t add to my position ahead of the 11/3 election, 11/6 jobs report, and 11/10 CPI release.
⚠️ Not investment advice. With ETF outflows for 23 days but ETH rising, is this a rotation or a market top? Let’s discuss in the comments 👇
Follow @阿Sue的加密日记 · Using data to expose crypto market false signals
#ETH #EthereumETF #ETFOutflows #Crypto
209
·
--
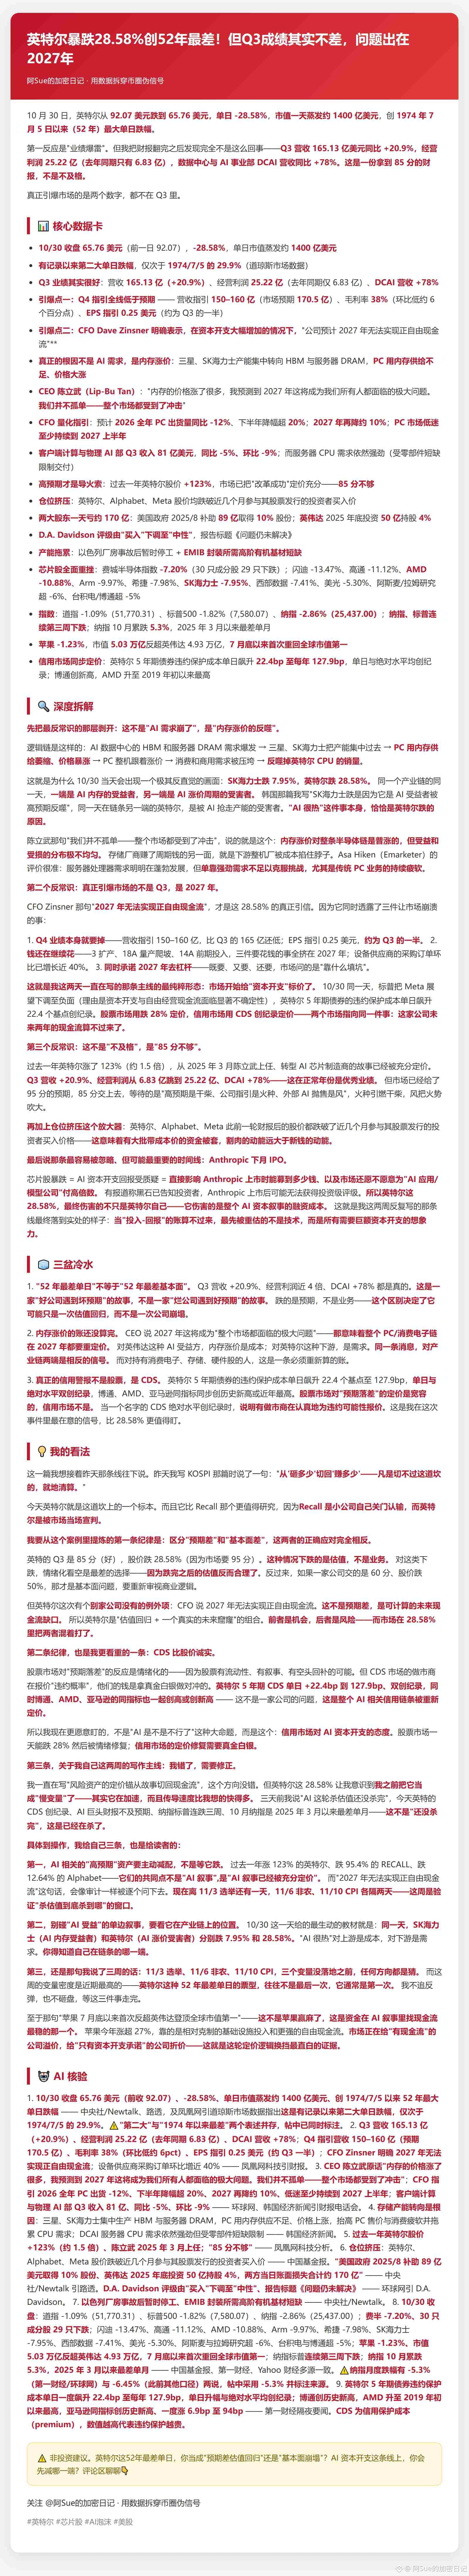
#英特尔创1974年以来最差单日表现 Intel plunges 28.58%, its worst drop in 52 years! But Q3 actually wasn't bad—the problem is 2027
On October 30, Intel fell 28.58% in a single day, wiping out about $140 billion in market value and marking its worst decline in 52 years, since 7/5/1974. But it wasn't an earnings disaster—Q3 revenue was up 20.9%, DCAI was up 78%, and the earnings report scored 85 out of 100.
📊 Key figures
· Closed at $65.76 on 10/30 (previous close: $92.07), down 28.58%
· About $140 billion wiped off its market value in a single day, its worst one-day performance in 52 years
· Second-largest one-day drop on record, behind only the 29.9% fall on 7/5/1974
· Q4 revenue guidance: $15–16 billion; EPS: $0.25
· CFO says the company will be unable to achieve positive free cash flow in 2027
🔍 The key contradiction
The most counterintuitive part: AI demand hasn't collapsed—the backlash is coming from soaring memory prices. AI data centers are snapping up HBM and server DRAM capacity, driving up PC memory prices and the cost of complete systems, while crushing demand. That day, SK hynix fell 7.95% and Intel fell 28.58%—two ends of the same supply chain, one benefiting and the other suffering. But what set off the sell-off was 2027: the CFO explicitly said the company won't achieve positive free cash flow that year.
🧊 Three sobering realities
1. The worst one-day drop in 52 years doesn't mean the worst fundamentals in 52 years. This is a good company facing bad expectations. But being unable to achieve positive free cash flow in 2027 is a serious hole.
2. The full impact of rising memory prices hasn't played out yet. The CEO says 2027 will be a problem for the entire market.
3. The real credit alarm isn't the stock—it's CDS. The cost of five-year protection against an Intel default jumped 22.4 basis points in a single day to 127.9 bp.
💡 My take
This follows the thread from yesterday. Yesterday I said the pricing anchor is shifting from how much a company can build to how much it can earn; companies that can't clear that bar get liquidated on the spot. Intel today is a case study in that shift—Recall closed its doors and admitted defeat; Intel was judged by the market on the spot.
Three rules. First, distinguish an expectations miss from a fundamentals problem: Q3 was good, an 85 out of 100, but the stock fell 28.58% because the market wanted a 95. Second, CDS is more honest than share prices. Third, I’m revising my view: the shift in pricing is accelerating, not playing out as a slow-moving trend.
⚠️ Not investment advice. Intel's worst one-day drop in 52 years: do you see it as a valuation reset or a collapse in fundamentals? Let's discuss in the comments 👇
Follow @阿Sue的加密日记 · Using data to expose crypto market false signals
#Intel #ChipStocks #AIBubble #USStocks
#英特尔创1974年以来最差单日表现 Intel plunges 28.58%, its worst drop in 52 years! But Q3 actually wasn't bad—the problem is 2027
On October 30, Intel fell 28.58% in a single day, wiping out about $140 billion in market value and marking its worst decline in 52 years, since 7/5/1974. But it wasn't an earnings disaster—Q3 revenue was up 20.9%, DCAI was up 78%, and the earnings report scored 85 out of 100.
📊 Key figures
· Closed at $65.76 on 10/30 (previous close: $92.07), down 28.58%
· About $140 billion wiped off its market value in a single day, its worst one-day performance in 52 years
· Second-largest one-day drop on record, behind only the 29.9% fall on 7/5/1974
· Q4 revenue guidance: $15–16 billion; EPS: $0.25
· CFO says the company will be unable to achieve positive free cash flow in 2027
🔍 The key contradiction
The most counterintuitive part: AI demand hasn't collapsed—the backlash is coming from soaring memory prices. AI data centers are snapping up HBM and server DRAM capacity, driving up PC memory prices and the cost of complete systems, while crushing demand. That day, SK hynix fell 7.95% and Intel fell 28.58%—two ends of the same supply chain, one benefiting and the other suffering. But what set off the sell-off was 2027: the CFO explicitly said the company won't achieve positive free cash flow that year.
🧊 Three sobering realities
1. The worst one-day drop in 52 years doesn't mean the worst fundamentals in 52 years. This is a good company facing bad expectations. But being unable to achieve positive free cash flow in 2027 is a serious hole.
2. The full impact of rising memory prices hasn't played out yet. The CEO says 2027 will be a problem for the entire market.
3. The real credit alarm isn't the stock—it's CDS. The cost of five-year protection against an Intel default jumped 22.4 basis points in a single day to 127.9 bp.
💡 My take
This follows the thread from yesterday. Yesterday I said the pricing anchor is shifting from how much a company can build to how much it can earn; companies that can't clear that bar get liquidated on the spot. Intel today is a case study in that shift—Recall closed its doors and admitted defeat; Intel was judged by the market on the spot.
Three rules. First, distinguish an expectations miss from a fundamentals problem: Q3 was good, an 85 out of 100, but the stock fell 28.58% because the market wanted a 95. Second, CDS is more honest than share prices. Third, I’m revising my view: the shift in pricing is accelerating, not playing out as a slow-moving trend.
⚠️ Not investment advice. Intel's worst one-day drop in 52 years: do you see it as a valuation reset or a collapse in fundamentals? Let's discuss in the comments 👇
Follow @阿Sue的加密日记 · Using data to expose crypto market false signals
#Intel #ChipStocks #AIBubble #USStocks
On October 30, Intel fell 28.58% in a single day, wiping out about $140 billion in market value and marking its worst decline in 52 years, since 7/5/1974. But it wasn't an earnings disaster—Q3 revenue was up 20.9%, DCAI was up 78%, and the earnings report scored 85 out of 100.
📊 Key figures
· Closed at $65.76 on 10/30 (previous close: $92.07), down 28.58%
· About $140 billion wiped off its market value in a single day, its worst one-day performance in 52 years
· Second-largest one-day drop on record, behind only the 29.9% fall on 7/5/1974
· Q4 revenue guidance: $15–16 billion; EPS: $0.25
· CFO says the company will be unable to achieve positive free cash flow in 2027
🔍 The key contradiction
The most counterintuitive part: AI demand hasn't collapsed—the backlash is coming from soaring memory prices. AI data centers are snapping up HBM and server DRAM capacity, driving up PC memory prices and the cost of complete systems, while crushing demand. That day, SK hynix fell 7.95% and Intel fell 28.58%—two ends of the same supply chain, one benefiting and the other suffering. But what set off the sell-off was 2027: the CFO explicitly said the company won't achieve positive free cash flow that year.
🧊 Three sobering realities
1. The worst one-day drop in 52 years doesn't mean the worst fundamentals in 52 years. This is a good company facing bad expectations. But being unable to achieve positive free cash flow in 2027 is a serious hole.
2. The full impact of rising memory prices hasn't played out yet. The CEO says 2027 will be a problem for the entire market.
3. The real credit alarm isn't the stock—it's CDS. The cost of five-year protection against an Intel default jumped 22.4 basis points in a single day to 127.9 bp.
💡 My take
This follows the thread from yesterday. Yesterday I said the pricing anchor is shifting from how much a company can build to how much it can earn; companies that can't clear that bar get liquidated on the spot. Intel today is a case study in that shift—Recall closed its doors and admitted defeat; Intel was judged by the market on the spot.
Three rules. First, distinguish an expectations miss from a fundamentals problem: Q3 was good, an 85 out of 100, but the stock fell 28.58% because the market wanted a 95. Second, CDS is more honest than share prices. Third, I’m revising my view: the shift in pricing is accelerating, not playing out as a slow-moving trend.
⚠️ Not investment advice. Intel's worst one-day drop in 52 years: do you see it as a valuation reset or a collapse in fundamentals? Let's discuss in the comments 👇
Follow @阿Sue的加密日记 · Using data to expose crypto market false signals
#Intel #ChipStocks #AIBubble #USStocks
148
·
--
Bearish
#币安已处理46.5亿美元提款 Binance Processed $4.65 Billion in Withdrawals! But Everyone Online Read the Numbers Backwards
When I saw “Binance withdrawals of $4.65 billion,” my first thought was that people were fleeing. But after running the numbers, I realized everyone online had it backwards—the point isn’t the $4.65 billion figure, but these three facts.
📊 Key figures
· Withdrawals resumed on 11/1, and $4.649 billion in withdrawals were processed in 9.5 hours
· $1.01 billion in deposits, for a net outflow of $3.64 billion, or 2.1% of AUM
· Withdrawal volumes have eased and stabilized, while deposits remain high
· 95% coverage overall, with 100% reserves for the top ten tokens
· DefiLlama’s figures show $4.36 billion in outflows, $720 million higher than Binance’s own reported figure
· The PoR report was published on 11/2
🔍 The key discrepancy
Let’s clarify the three figures first: $4.649 billion is gross withdrawals, $1.01 billion is deposits, and $3.64 billion is the net outflow, equivalent to 2.1% of AUM. Second-place OKX had just $29 billion—this isn’t a bank run, it’s traffic clearing through the channel. Binance says withdrawals surged and then eased and stabilized, while deposits remained high. A collapse in confidence would mean rising withdrawals and shrinking deposits; what actually happened was the opposite.
🧊 Three caveats
1. Don’t take “2.1%, so everything’s fine” at face value. The decline in withdrawals is only a one-day observation; we need to see whether it holds for several days.
2. The remaining 5% will be the hardest to handle. Low-liquidity tokens can only be moved through OTC, which could take a long time, turning “1:1 coverage” into “coverage for the vast majority.”
3. Don’t mistake “institutions haven’t left” for “everything’s fine.” Eli Williams is reducing the proportion held on the platform—that’s a portfolio adjustment.
💡 My take
Yesterday I wrote, “Don’t bet everything on the platform’s recovery meaning the market has reversed.” Today confirms the second half: net outflows were only 2.1% of AUM, and BTC rebounded from its 10/29 low of 77,991 to 78,426, up 0.55%, with no withdrawal panic.
But what this really revealed is how a platform handles losses. After the same $6.3 billion theft, Binance regained trust through a balance-sheet event—$6.3 billion was only 3.7% of its AUM. It spent 3.7% to buy back 100% of trust; platforms that didn’t make that trade stand to lose everything. When an exchange runs into trouble, first ask whether it’s willing to pay out of pocket. Tomorrow is the election; I’ll adjust my positions according to the election, nonfarm payrolls, and CPI.
⚠️Not investment advice. Are $4.65 billion in withdrawals a collapse or just the channel clearing? Let’s discuss in the comments 👇
#币安已处理46.5亿美元提款 Binance Processed $4.65 Billion in Withdrawals! But Everyone Online Read the Numbers Backwards
When I saw “Binance withdrawals of $4.65 billion,” my first thought was that people were fleeing. But after running the numbers, I realized everyone online had it backwards—the point isn’t the $4.65 billion figure, but these three facts.
📊 Key figures
· Withdrawals resumed on 11/1, and $4.649 billion in withdrawals were processed in 9.5 hours
· $1.01 billion in deposits, for a net outflow of $3.64 billion, or 2.1% of AUM
· Withdrawal volumes have eased and stabilized, while deposits remain high
· 95% coverage overall, with 100% reserves for the top ten tokens
· DefiLlama’s figures show $4.36 billion in outflows, $720 million higher than Binance’s own reported figure
· The PoR report was published on 11/2
🔍 The key discrepancy
Let’s clarify the three figures first: $4.649 billion is gross withdrawals, $1.01 billion is deposits, and $3.64 billion is the net outflow, equivalent to 2.1% of AUM. Second-place OKX had just $29 billion—this isn’t a bank run, it’s traffic clearing through the channel. Binance says withdrawals surged and then eased and stabilized, while deposits remained high. A collapse in confidence would mean rising withdrawals and shrinking deposits; what actually happened was the opposite.
🧊 Three caveats
1. Don’t take “2.1%, so everything’s fine” at face value. The decline in withdrawals is only a one-day observation; we need to see whether it holds for several days.
2. The remaining 5% will be the hardest to handle. Low-liquidity tokens can only be moved through OTC, which could take a long time, turning “1:1 coverage” into “coverage for the vast majority.”
3. Don’t mistake “institutions haven’t left” for “everything’s fine.” Eli Williams is reducing the proportion held on the platform—that’s a portfolio adjustment.
💡 My take
Yesterday I wrote, “Don’t bet everything on the platform’s recovery meaning the market has reversed.” Today confirms the second half: net outflows were only 2.1% of AUM, and BTC rebounded from its 10/29 low of 77,991 to 78,426, up 0.55%, with no withdrawal panic.
But what this really revealed is how a platform handles losses. After the same $6.3 billion theft, Binance regained trust through a balance-sheet event—$6.3 billion was only 3.7% of its AUM. It spent 3.7% to buy back 100% of trust; platforms that didn’t make that trade stand to lose everything. When an exchange runs into trouble, first ask whether it’s willing to pay out of pocket. Tomorrow is the election; I’ll adjust my positions according to the election, nonfarm payrolls, and CPI.
⚠️Not investment advice. Are $4.65 billion in withdrawals a collapse or just the channel clearing? Let’s discuss in the comments 👇
When I saw “Binance withdrawals of $4.65 billion,” my first thought was that people were fleeing. But after running the numbers, I realized everyone online had it backwards—the point isn’t the $4.65 billion figure, but these three facts.
📊 Key figures
· Withdrawals resumed on 11/1, and $4.649 billion in withdrawals were processed in 9.5 hours
· $1.01 billion in deposits, for a net outflow of $3.64 billion, or 2.1% of AUM
· Withdrawal volumes have eased and stabilized, while deposits remain high
· 95% coverage overall, with 100% reserves for the top ten tokens
· DefiLlama’s figures show $4.36 billion in outflows, $720 million higher than Binance’s own reported figure
· The PoR report was published on 11/2
🔍 The key discrepancy
Let’s clarify the three figures first: $4.649 billion is gross withdrawals, $1.01 billion is deposits, and $3.64 billion is the net outflow, equivalent to 2.1% of AUM. Second-place OKX had just $29 billion—this isn’t a bank run, it’s traffic clearing through the channel. Binance says withdrawals surged and then eased and stabilized, while deposits remained high. A collapse in confidence would mean rising withdrawals and shrinking deposits; what actually happened was the opposite.
🧊 Three caveats
1. Don’t take “2.1%, so everything’s fine” at face value. The decline in withdrawals is only a one-day observation; we need to see whether it holds for several days.
2. The remaining 5% will be the hardest to handle. Low-liquidity tokens can only be moved through OTC, which could take a long time, turning “1:1 coverage” into “coverage for the vast majority.”
3. Don’t mistake “institutions haven’t left” for “everything’s fine.” Eli Williams is reducing the proportion held on the platform—that’s a portfolio adjustment.
💡 My take
Yesterday I wrote, “Don’t bet everything on the platform’s recovery meaning the market has reversed.” Today confirms the second half: net outflows were only 2.1% of AUM, and BTC rebounded from its 10/29 low of 77,991 to 78,426, up 0.55%, with no withdrawal panic.
But what this really revealed is how a platform handles losses. After the same $6.3 billion theft, Binance regained trust through a balance-sheet event—$6.3 billion was only 3.7% of its AUM. It spent 3.7% to buy back 100% of trust; platforms that didn’t make that trade stand to lose everything. When an exchange runs into trouble, first ask whether it’s willing to pay out of pocket. Tomorrow is the election; I’ll adjust my positions according to the election, nonfarm payrolls, and CPI.
⚠️Not investment advice. Are $4.65 billion in withdrawals a collapse or just the channel clearing? Let’s discuss in the comments 👇
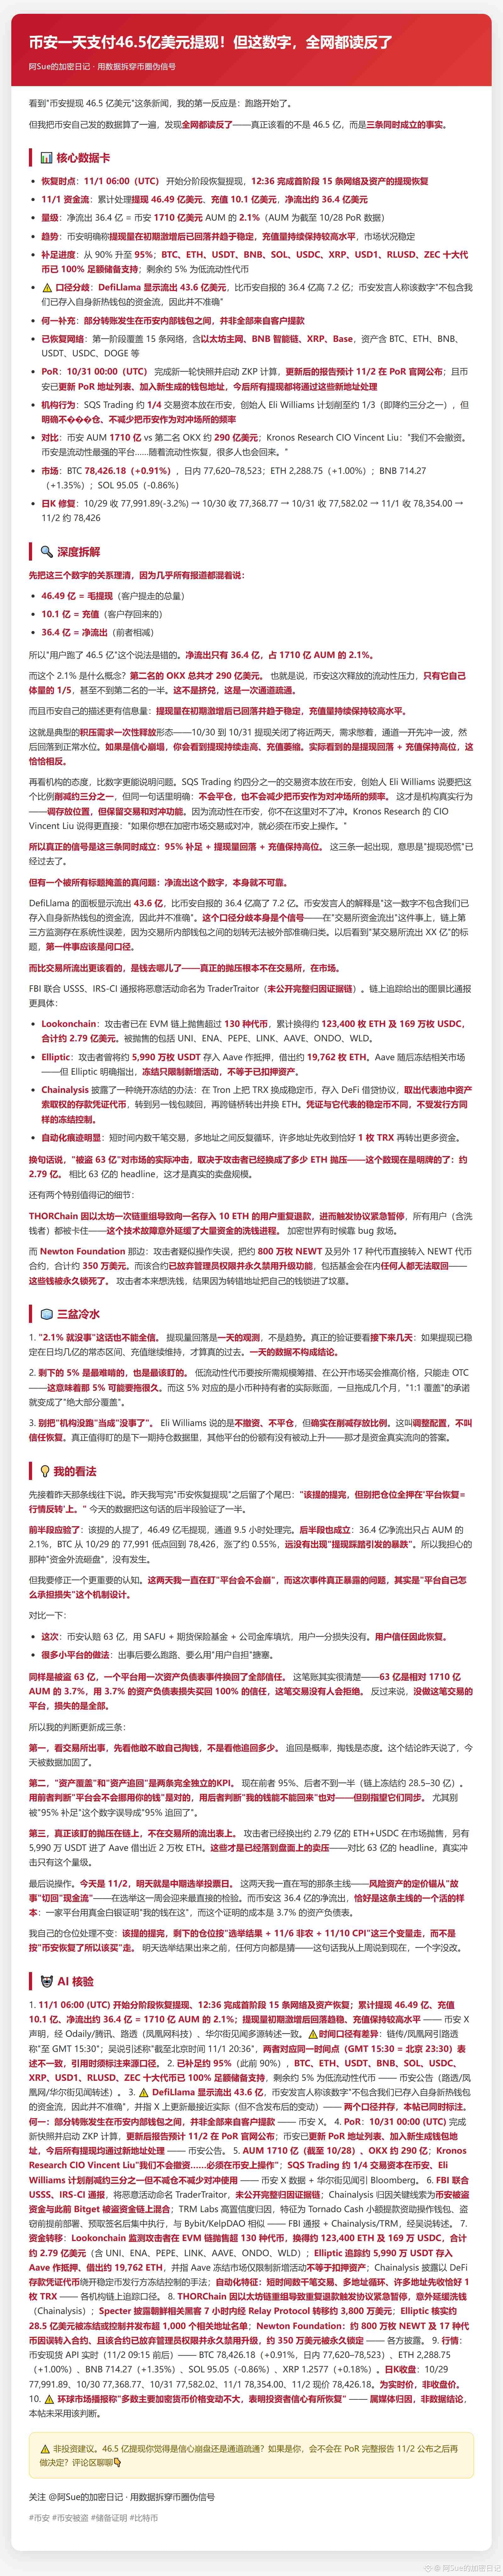
7
·
--
#openai下调融资目标100亿美元 OpenAI cuts fundraising target by $10 billion! The biggest bill is for compute contracts
Yesterday, Alphabet lost $500 billion in market value, its biggest single-day drop in 22 years as a public company. Today’s news is even harsher: OpenAI’s fundraising target was cut from $30 billion to $20 billion, and its valuation fell from $1.4 trillion to $1.25 trillion. Three steps down in one month—that’s the signal.
📊 Key figures
· Originally planned: $30 billion at a $1.4 trillion valuation; now $20 billion at $1.25 trillion
· First closing came in below $20 billion; buyers are dragging their feet
· MGX is leading the round in exchange for UAE compute leasing rights
· Cumulative FCF shortfall of about $278 billion from 2026–30
· More than $1.4 trillion in compute contracts over 15 months, about 35x revenue
· Locking in funding ahead of Anthropic’s IPO next month
🔍 The key contradiction
Three steps down: $30 billion at a $1.4 trillion valuation in mid-October; down to $1.25 trillion around October 22; and this week, the fundraising target was also cut to $20 billion. The two numbers that really set off alarm bells for me: a $278 billion cash-flow shortfall versus $122 billion in fundraising—the money raised in March won’t be enough to last until cash flow turns positive; and $1.4 trillion in compute contracts against $50 billion in revenue, or 35x. The money is going to pay the compute bill, and once those contracts are signed, there’s no easy way to spend less.
🧊 Three reality checks
1. The first closing coming in below $20 billion is bad news in itself. A Friday deadline suggests buyers are dragging their feet, and another cut in the next round can’t be ruled out.
2. Don’t treat $1.25 trillion as a floor. The valuation was still $1.4 trillion last month. When AI valuations are being slashed, a valuation isn’t a floor.
3. Anthropic’s IPO next month will be the real test. If its shares fall below the IPO price, $1.25 trillion won’t hold.
💡 My take
Put yesterday’s events together: Alphabet’s FCF of -$9.07 billion, Intel plunging 28.59%, Amazon’s -$42.4 billion, and OpenAI’s $20 billion fundraising target—the market is starting to put a price on “AI investment.” Before, people looked at who was investing the most. Now they’re looking at whose FCF is positive and whether they have enough cash to last until it turns positive.
So this valuation sell-off isn’t over yet: yesterday was the first muffled thud, today the second. The final signal will be Anthropic’s IPO pricing next month—that will be the market’s ultimate vote on whether AI can pay for itself.
🤖 Fact check
The fundraising target was cut from $30 billion to $20 billion, the valuation is $1.25 trillion, and MGX is leading the round in exchange for compute leasing rights—multiple Bloomberg sources agree. The three-step timeline was compiled by Zhitong Finance; since the pre-money basis wasn’t specified, it is described as “a reduction of about $150 billion.” The $278 billion shortfall and $1.4 trillion in contracts come from internal investor documents.
⚠️ Not investment advice. OpenAI cuts $10 billion—valuation normalizing, or has the AI bubble burst? Let’s discuss in the comments 👇
#openai下调融资目标100亿美元 OpenAI cuts fundraising target by $10 billion! The biggest bill is for compute contracts
Yesterday, Alphabet lost $500 billion in market value, its biggest single-day drop in 22 years as a public company. Today’s news is even harsher: OpenAI’s fundraising target was cut from $30 billion to $20 billion, and its valuation fell from $1.4 trillion to $1.25 trillion. Three steps down in one month—that’s the signal.
📊 Key figures
· Originally planned: $30 billion at a $1.4 trillion valuation; now $20 billion at $1.25 trillion
· First closing came in below $20 billion; buyers are dragging their feet
· MGX is leading the round in exchange for UAE compute leasing rights
· Cumulative FCF shortfall of about $278 billion from 2026–30
· More than $1.4 trillion in compute contracts over 15 months, about 35x revenue
· Locking in funding ahead of Anthropic’s IPO next month
🔍 The key contradiction
Three steps down: $30 billion at a $1.4 trillion valuation in mid-October; down to $1.25 trillion around October 22; and this week, the fundraising target was also cut to $20 billion. The two numbers that really set off alarm bells for me: a $278 billion cash-flow shortfall versus $122 billion in fundraising—the money raised in March won’t be enough to last until cash flow turns positive; and $1.4 trillion in compute contracts against $50 billion in revenue, or 35x. The money is going to pay the compute bill, and once those contracts are signed, there’s no easy way to spend less.
🧊 Three reality checks
1. The first closing coming in below $20 billion is bad news in itself. A Friday deadline suggests buyers are dragging their feet, and another cut in the next round can’t be ruled out.
2. Don’t treat $1.25 trillion as a floor. The valuation was still $1.4 trillion last month. When AI valuations are being slashed, a valuation isn’t a floor.
3. Anthropic’s IPO next month will be the real test. If its shares fall below the IPO price, $1.25 trillion won’t hold.
💡 My take
Put yesterday’s events together: Alphabet’s FCF of -$9.07 billion, Intel plunging 28.59%, Amazon’s -$42.4 billion, and OpenAI’s $20 billion fundraising target—the market is starting to put a price on “AI investment.” Before, people looked at who was investing the most. Now they’re looking at whose FCF is positive and whether they have enough cash to last until it turns positive.
So this valuation sell-off isn’t over yet: yesterday was the first muffled thud, today the second. The final signal will be Anthropic’s IPO pricing next month—that will be the market’s ultimate vote on whether AI can pay for itself.
🤖 Fact check
The fundraising target was cut from $30 billion to $20 billion, the valuation is $1.25 trillion, and MGX is leading the round in exchange for compute leasing rights—multiple Bloomberg sources agree. The three-step timeline was compiled by Zhitong Finance; since the pre-money basis wasn’t specified, it is described as “a reduction of about $150 billion.” The $278 billion shortfall and $1.4 trillion in contracts come from internal investor documents.
⚠️ Not investment advice. OpenAI cuts $10 billion—valuation normalizing, or has the AI bubble burst? Let’s discuss in the comments 👇
Yesterday, Alphabet lost $500 billion in market value, its biggest single-day drop in 22 years as a public company. Today’s news is even harsher: OpenAI’s fundraising target was cut from $30 billion to $20 billion, and its valuation fell from $1.4 trillion to $1.25 trillion. Three steps down in one month—that’s the signal.
📊 Key figures
· Originally planned: $30 billion at a $1.4 trillion valuation; now $20 billion at $1.25 trillion
· First closing came in below $20 billion; buyers are dragging their feet
· MGX is leading the round in exchange for UAE compute leasing rights
· Cumulative FCF shortfall of about $278 billion from 2026–30
· More than $1.4 trillion in compute contracts over 15 months, about 35x revenue
· Locking in funding ahead of Anthropic’s IPO next month
🔍 The key contradiction
Three steps down: $30 billion at a $1.4 trillion valuation in mid-October; down to $1.25 trillion around October 22; and this week, the fundraising target was also cut to $20 billion. The two numbers that really set off alarm bells for me: a $278 billion cash-flow shortfall versus $122 billion in fundraising—the money raised in March won’t be enough to last until cash flow turns positive; and $1.4 trillion in compute contracts against $50 billion in revenue, or 35x. The money is going to pay the compute bill, and once those contracts are signed, there’s no easy way to spend less.
🧊 Three reality checks
1. The first closing coming in below $20 billion is bad news in itself. A Friday deadline suggests buyers are dragging their feet, and another cut in the next round can’t be ruled out.
2. Don’t treat $1.25 trillion as a floor. The valuation was still $1.4 trillion last month. When AI valuations are being slashed, a valuation isn’t a floor.
3. Anthropic’s IPO next month will be the real test. If its shares fall below the IPO price, $1.25 trillion won’t hold.
💡 My take
Put yesterday’s events together: Alphabet’s FCF of -$9.07 billion, Intel plunging 28.59%, Amazon’s -$42.4 billion, and OpenAI’s $20 billion fundraising target—the market is starting to put a price on “AI investment.” Before, people looked at who was investing the most. Now they’re looking at whose FCF is positive and whether they have enough cash to last until it turns positive.
So this valuation sell-off isn’t over yet: yesterday was the first muffled thud, today the second. The final signal will be Anthropic’s IPO pricing next month—that will be the market’s ultimate vote on whether AI can pay for itself.
🤖 Fact check
The fundraising target was cut from $30 billion to $20 billion, the valuation is $1.25 trillion, and MGX is leading the round in exchange for compute leasing rights—multiple Bloomberg sources agree. The three-step timeline was compiled by Zhitong Finance; since the pre-money basis wasn’t specified, it is described as “a reduction of about $150 billion.” The $278 billion shortfall and $1.4 trillion in contracts come from internal investor documents.
⚠️ Not investment advice. OpenAI cuts $10 billion—valuation normalizing, or has the AI bubble burst? Let’s discuss in the comments 👇
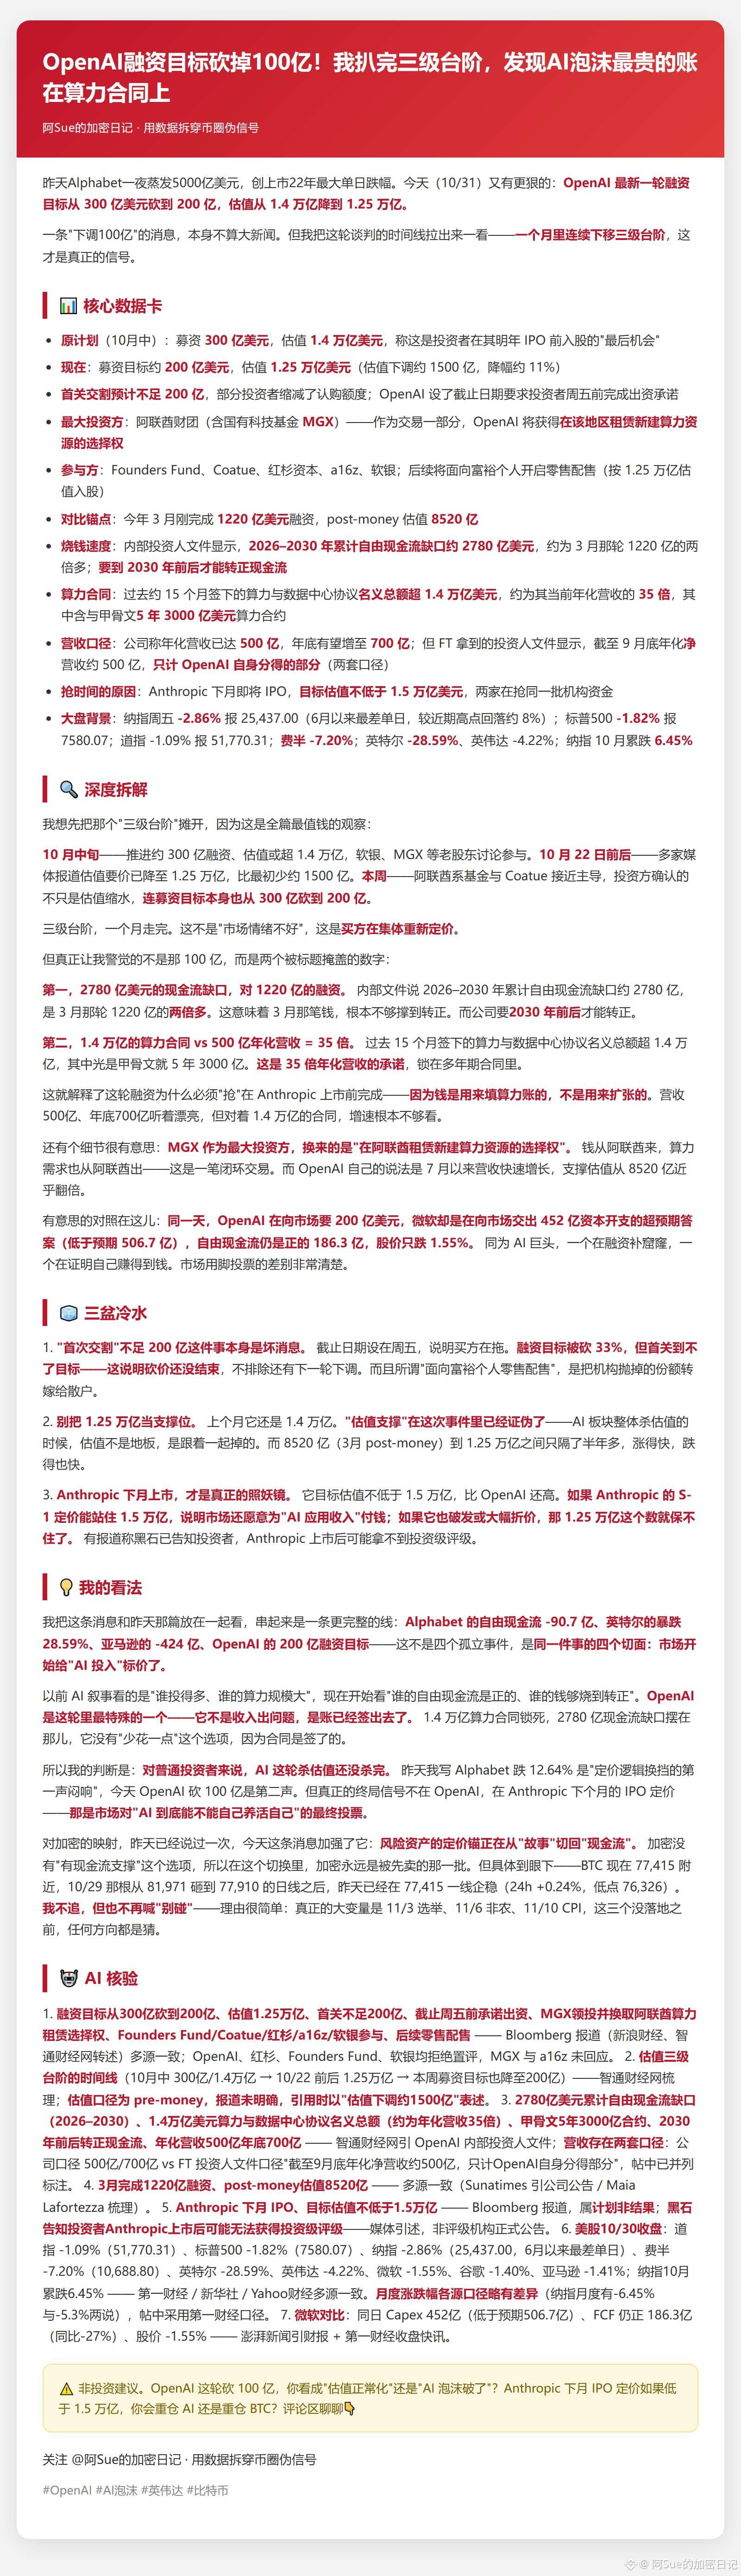
270
·
--
Verified
#recall宣布清算拟销毁35.86%代币 Recall shutdown and destroyed 35.86% of tokens! Holders get nothing back—not a burn, but a liquidation
On the evening of 10/30, the Recall Foundation announced it would shut down: it will destroy about 359 million RECALL tokens, or 35.86% of total supply. The announcement clearly states there will be zero distribution and zero buyback for holders; most of this 35.86% was never in circulation to begin with.
📊 Key figures
· Shutdown on 10/30; 359 million tokens destroyed, accounting for 35.86%
· After the burn, total supply drops to 641 million; holders get zero distribution and zero buyback
· Foundation left with only 3.7 million, of which 3.45 million goes to creditors
· Current price: $0.038; 24h trading volume only $197k
· Down 95.4% from ATH; Bithumb lists it as a warning asset
🔍 The core contradiction
Burning 35.86% sounds bullish, but the announcement makes it clear token holders receive no distribution or buyback. Of the foundation’s 3.7 million, 3.45 million goes to creditors and 200k to liquidation fees, with the remaining balance expected to hit zero. In other words, the so-called burn is really sweeping locked tokens and ecosystem allocations that were already not circulating into a black hole—not removing 35.86% from the circulating market cap. The truly fatal move is that the foundation is also stopping development and liquidity provision.
🧊 Three cold showers
1. Burn ≠ lower circulating supply. CoinScreamer notes that the 35.86% includes already locked allocations, so you can’t treat it as an immediate 35.86% drop in circulating supply.
2. Liquidity is the tombstone. The foundation stops market making, and exchanges decide whether to delist individually; with only $197k in 24h volume, the order book can’t absorb a dump.
3. Don’t use the $42 million fundraising figure as comfort. RootData’s number is the total raised across all historical rounds, not cash sitting on the balance sheet.
💡 My take
This follows the same theme as yesterday’s OpenAI story: yesterday OpenAI cut $10 billion in financing, and today Recall goes straight to shutdown; on the same day, S&P also downgraded Meta’s outlook to negative. The AI narrative is shifting from “how much was spent” back to “how much was earned.”
Recall deserves a separate breakdown because it is a complete AI token case study: it launched on 2025-10-15, hit a high of 0.8317 that same month, then fell to 0.038 a year later, down 95.4%—even worse than BTC. It peaked the month it launched, then drifted down until the foundation itself burned it.
⚠️ Not investment advice. The project burned 35.86% of tokens and returned not a single cent to holders—what do you think of this kind of “dignified liquidation”? Let’s talk in the comments 👇
#recall宣布清算拟销毁35.86%代币 Recall shutdown and destroyed 35.86% of tokens! Holders get nothing back—not a burn, but a liquidation
On the evening of 10/30, the Recall Foundation announced it would shut down: it will destroy about 359 million RECALL tokens, or 35.86% of total supply. The announcement clearly states there will be zero distribution and zero buyback for holders; most of this 35.86% was never in circulation to begin with.
📊 Key figures
· Shutdown on 10/30; 359 million tokens destroyed, accounting for 35.86%
· After the burn, total supply drops to 641 million; holders get zero distribution and zero buyback
· Foundation left with only 3.7 million, of which 3.45 million goes to creditors
· Current price: $0.038; 24h trading volume only $197k
· Down 95.4% from ATH; Bithumb lists it as a warning asset
🔍 The core contradiction
Burning 35.86% sounds bullish, but the announcement makes it clear token holders receive no distribution or buyback. Of the foundation’s 3.7 million, 3.45 million goes to creditors and 200k to liquidation fees, with the remaining balance expected to hit zero. In other words, the so-called burn is really sweeping locked tokens and ecosystem allocations that were already not circulating into a black hole—not removing 35.86% from the circulating market cap. The truly fatal move is that the foundation is also stopping development and liquidity provision.
🧊 Three cold showers
1. Burn ≠ lower circulating supply. CoinScreamer notes that the 35.86% includes already locked allocations, so you can’t treat it as an immediate 35.86% drop in circulating supply.
2. Liquidity is the tombstone. The foundation stops market making, and exchanges decide whether to delist individually; with only $197k in 24h volume, the order book can’t absorb a dump.
3. Don’t use the $42 million fundraising figure as comfort. RootData’s number is the total raised across all historical rounds, not cash sitting on the balance sheet.
💡 My take
This follows the same theme as yesterday’s OpenAI story: yesterday OpenAI cut $10 billion in financing, and today Recall goes straight to shutdown; on the same day, S&P also downgraded Meta’s outlook to negative. The AI narrative is shifting from “how much was spent” back to “how much was earned.”
Recall deserves a separate breakdown because it is a complete AI token case study: it launched on 2025-10-15, hit a high of 0.8317 that same month, then fell to 0.038 a year later, down 95.4%—even worse than BTC. It peaked the month it launched, then drifted down until the foundation itself burned it.
⚠️ Not investment advice. The project burned 35.86% of tokens and returned not a single cent to holders—what do you think of this kind of “dignified liquidation”? Let’s talk in the comments 👇
On the evening of 10/30, the Recall Foundation announced it would shut down: it will destroy about 359 million RECALL tokens, or 35.86% of total supply. The announcement clearly states there will be zero distribution and zero buyback for holders; most of this 35.86% was never in circulation to begin with.
📊 Key figures
· Shutdown on 10/30; 359 million tokens destroyed, accounting for 35.86%
· After the burn, total supply drops to 641 million; holders get zero distribution and zero buyback
· Foundation left with only 3.7 million, of which 3.45 million goes to creditors
· Current price: $0.038; 24h trading volume only $197k
· Down 95.4% from ATH; Bithumb lists it as a warning asset
🔍 The core contradiction
Burning 35.86% sounds bullish, but the announcement makes it clear token holders receive no distribution or buyback. Of the foundation’s 3.7 million, 3.45 million goes to creditors and 200k to liquidation fees, with the remaining balance expected to hit zero. In other words, the so-called burn is really sweeping locked tokens and ecosystem allocations that were already not circulating into a black hole—not removing 35.86% from the circulating market cap. The truly fatal move is that the foundation is also stopping development and liquidity provision.
🧊 Three cold showers
1. Burn ≠ lower circulating supply. CoinScreamer notes that the 35.86% includes already locked allocations, so you can’t treat it as an immediate 35.86% drop in circulating supply.
2. Liquidity is the tombstone. The foundation stops market making, and exchanges decide whether to delist individually; with only $197k in 24h volume, the order book can’t absorb a dump.
3. Don’t use the $42 million fundraising figure as comfort. RootData’s number is the total raised across all historical rounds, not cash sitting on the balance sheet.
💡 My take
This follows the same theme as yesterday’s OpenAI story: yesterday OpenAI cut $10 billion in financing, and today Recall goes straight to shutdown; on the same day, S&P also downgraded Meta’s outlook to negative. The AI narrative is shifting from “how much was spent” back to “how much was earned.”
Recall deserves a separate breakdown because it is a complete AI token case study: it launched on 2025-10-15, hit a high of 0.8317 that same month, then fell to 0.038 a year later, down 95.4%—even worse than BTC. It peaked the month it launched, then drifted down until the foundation itself burned it.
⚠️ Not investment advice. The project burned 35.86% of tokens and returned not a single cent to holders—what do you think of this kind of “dignified liquidation”? Let’s talk in the comments 👇
1
4.3k
·
--
#asic尚未收到预测市场申请 One sentence from the ASIC chair sent prediction markets into a panic! The real signal isn’t in Australia
On Thursday, ASIC Chair Sarah Court told a Senate hearing that no prediction market operators have applied for a license to date. Media headlines called it a “major blow to prediction markets,” but they missed the point.
📊 Key data
· Classification: Mechanisms similar to binary options, with non-financial underlying events
· Australia has banned retail binary options through 2031
· In the 13 months before the ban, 74%–77% of retail clients lost money, totaling A$15.7 million
· In August 2025, ACMA blocked Polymarket, classifying it as illegal gambling
· In Q3, three platforms recorded A$172.4 billion in trading volume, with Kalshi accounting for 83%
🔍 The key contradiction
This isn’t a crackdown; it’s a defensive move. If a platform applies for a license, ASIC will assess it—but the bar is high. With no applications, platforms in Australia are more likely to face gambling regulation. The key comparison is binary options: in the 13 months before the ban, 74%–77% of retail clients lost money, with net losses of A$15.7 million across their accounts; winners made only A$1.7 million. When eight out of ten retail investors lose money, licensing isn’t a good fit.
🧊 Three reality checks
1. No applications doesn’t mean the industry is doomed. The high bar is intended to attract quality applicants, and Kalshi is still doing A$65 billion in monthly trading volume.
2. Being blocked doesn’t mean being banned. Users can still access it via VPN, while ASIC says users aren’t protected.
3. What should really worry us: the 74%–77% retail loss rate for binary options and the 83.8% of crypto liquidations involving long positions tell the same story.
💡 My take
I don’t want to jump on the “prediction markets are finished” bandwagon—the data suggests the opposite. What’s worth noting is that tighter regulation and an industry boom are happening at the same time: ASIC says “it’s like binary options, and seven in ten retail investors lose,” while Q3 trading volume hit A$172.4 billion.
This Australian case has a lesson for the crypto world: separate “the platform says it’s safe” from “users are actually protected.” The message is that you can’t skip investor protection.
⚠️ Not investment advice. Prediction markets are under regulatory scrutiny—do you think this is a shakeout or a step toward legitimacy? Share your thoughts in the comments 👇
#asic尚未收到预测市场申请 One sentence from the ASIC chair sent prediction markets into a panic! The real signal isn’t in Australia
On Thursday, ASIC Chair Sarah Court told a Senate hearing that no prediction market operators have applied for a license to date. Media headlines called it a “major blow to prediction markets,” but they missed the point.
📊 Key data
· Classification: Mechanisms similar to binary options, with non-financial underlying events
· Australia has banned retail binary options through 2031
· In the 13 months before the ban, 74%–77% of retail clients lost money, totaling A$15.7 million
· In August 2025, ACMA blocked Polymarket, classifying it as illegal gambling
· In Q3, three platforms recorded A$172.4 billion in trading volume, with Kalshi accounting for 83%
🔍 The key contradiction
This isn’t a crackdown; it’s a defensive move. If a platform applies for a license, ASIC will assess it—but the bar is high. With no applications, platforms in Australia are more likely to face gambling regulation. The key comparison is binary options: in the 13 months before the ban, 74%–77% of retail clients lost money, with net losses of A$15.7 million across their accounts; winners made only A$1.7 million. When eight out of ten retail investors lose money, licensing isn’t a good fit.
🧊 Three reality checks
1. No applications doesn’t mean the industry is doomed. The high bar is intended to attract quality applicants, and Kalshi is still doing A$65 billion in monthly trading volume.
2. Being blocked doesn’t mean being banned. Users can still access it via VPN, while ASIC says users aren’t protected.
3. What should really worry us: the 74%–77% retail loss rate for binary options and the 83.8% of crypto liquidations involving long positions tell the same story.
💡 My take
I don’t want to jump on the “prediction markets are finished” bandwagon—the data suggests the opposite. What’s worth noting is that tighter regulation and an industry boom are happening at the same time: ASIC says “it’s like binary options, and seven in ten retail investors lose,” while Q3 trading volume hit A$172.4 billion.
This Australian case has a lesson for the crypto world: separate “the platform says it’s safe” from “users are actually protected.” The message is that you can’t skip investor protection.
⚠️ Not investment advice. Prediction markets are under regulatory scrutiny—do you think this is a shakeout or a step toward legitimacy? Share your thoughts in the comments 👇
On Thursday, ASIC Chair Sarah Court told a Senate hearing that no prediction market operators have applied for a license to date. Media headlines called it a “major blow to prediction markets,” but they missed the point.
📊 Key data
· Classification: Mechanisms similar to binary options, with non-financial underlying events
· Australia has banned retail binary options through 2031
· In the 13 months before the ban, 74%–77% of retail clients lost money, totaling A$15.7 million
· In August 2025, ACMA blocked Polymarket, classifying it as illegal gambling
· In Q3, three platforms recorded A$172.4 billion in trading volume, with Kalshi accounting for 83%
🔍 The key contradiction
This isn’t a crackdown; it’s a defensive move. If a platform applies for a license, ASIC will assess it—but the bar is high. With no applications, platforms in Australia are more likely to face gambling regulation. The key comparison is binary options: in the 13 months before the ban, 74%–77% of retail clients lost money, with net losses of A$15.7 million across their accounts; winners made only A$1.7 million. When eight out of ten retail investors lose money, licensing isn’t a good fit.
🧊 Three reality checks
1. No applications doesn’t mean the industry is doomed. The high bar is intended to attract quality applicants, and Kalshi is still doing A$65 billion in monthly trading volume.
2. Being blocked doesn’t mean being banned. Users can still access it via VPN, while ASIC says users aren’t protected.
3. What should really worry us: the 74%–77% retail loss rate for binary options and the 83.8% of crypto liquidations involving long positions tell the same story.
💡 My take
I don’t want to jump on the “prediction markets are finished” bandwagon—the data suggests the opposite. What’s worth noting is that tighter regulation and an industry boom are happening at the same time: ASIC says “it’s like binary options, and seven in ten retail investors lose,” while Q3 trading volume hit A$172.4 billion.
This Australian case has a lesson for the crypto world: separate “the platform says it’s safe” from “users are actually protected.” The message is that you can’t skip investor protection.
⚠️ Not investment advice. Prediction markets are under regulatory scrutiny—do you think this is a shakeout or a step toward legitimacy? Share your thoughts in the comments 👇
2
182
·
--
#kospi下跌3.53%重回6000点下方 KOSPI plunged 3.53%, falling back below 6,000! The trigger lies in three letters: FCF
South Korea’s KOSPI closed today at 5,730.74, down 3.48%, after dipping to 5,599 intraday. Even more striking, the Korea Exchange triggered a sell-side sidecar: futures fell 5.12%, halting program trading for five minutes. The trigger is hidden in three letters: FCF.
📊 Key figures
· KOSPI closed at 5,730.74 (-3.48%), with an intraday low of 5,599
· Sidecar triggered as futures fell 5.12%
· SK Hynix -7.08%, Samsung -3.02%
· Alphabet -12.64%, its biggest drop since listing
· Google FCF: -9.07 billion; Microsoft FCF remained positive at 18.63 billion
🔍 The key contradiction
It’s not that Korea is failing, nor that AI demand has collapsed—Samsung’s Q3 operating profit of 107.4 trillion won and SK Hynix’s 83.33 trillion won are both real. Pepperstone put it accurately: the market isn’t predicting an order collapse; it’s questioning whether shareholders can get returns from the enormous capital being invested. The valuation anchor has shifted: investors used to focus on Capex growth; now they’re watching whether free cash flow is positive. Google’s FCF was -9.07 billion, while Microsoft’s remained positive and its stock fell just 0.16%.
🧊 Three sobering points
1. Record profits at Samsung and SK Hynix can’t rescue their share prices. Profits are backward-looking; share prices are forward-looking. With the focus shifting to cash returns, record profits can only slow the decline.
2. A sidecar isn’t a bottom signal; it shows fragility, not that the market has bottomed. After the circuit breaker on 10/15, the index didn’t reverse course, and it lost 6,000 on 10/29.
3. Don’t assume money flowing out of tech and into defensive assets will flow into crypto. U.S. healthcare and defense stocks are rising today; money is going into Treasuries, not BTC.
💡 My take
I wrote “KOSPI Leads Global Declines With a Drop of Over 2%” on 10/20, and pointed to two things to watch: whether U.S. tech giants’ earnings could prove AI is paying off, and the path of interest rates. Today, we got the worst possible answer to the first question: Alphabet shed 500 billion in a single day, its biggest drop in 22 years as a listed company—a dull thud signaling a shift in valuation logic. The signal to watch is whether Samsung follows through on its buyback: the buyback and cancellation were delayed until next January, IBK cut its target price to 350,000 won, and the stock turned negative late in the session.
⚠️ Not investment advice. Do you think today’s KOSPI drop is an emotional selloff or a shift in valuation logic? Let’s discuss in the comments 👇
#kospi下跌3.53%重回6000点下方 KOSPI plunged 3.53%, falling back below 6,000! The trigger lies in three letters: FCF
South Korea’s KOSPI closed today at 5,730.74, down 3.48%, after dipping to 5,599 intraday. Even more striking, the Korea Exchange triggered a sell-side sidecar: futures fell 5.12%, halting program trading for five minutes. The trigger is hidden in three letters: FCF.
📊 Key figures
· KOSPI closed at 5,730.74 (-3.48%), with an intraday low of 5,599
· Sidecar triggered as futures fell 5.12%
· SK Hynix -7.08%, Samsung -3.02%
· Alphabet -12.64%, its biggest drop since listing
· Google FCF: -9.07 billion; Microsoft FCF remained positive at 18.63 billion
🔍 The key contradiction
It’s not that Korea is failing, nor that AI demand has collapsed—Samsung’s Q3 operating profit of 107.4 trillion won and SK Hynix’s 83.33 trillion won are both real. Pepperstone put it accurately: the market isn’t predicting an order collapse; it’s questioning whether shareholders can get returns from the enormous capital being invested. The valuation anchor has shifted: investors used to focus on Capex growth; now they’re watching whether free cash flow is positive. Google’s FCF was -9.07 billion, while Microsoft’s remained positive and its stock fell just 0.16%.
🧊 Three sobering points
1. Record profits at Samsung and SK Hynix can’t rescue their share prices. Profits are backward-looking; share prices are forward-looking. With the focus shifting to cash returns, record profits can only slow the decline.
2. A sidecar isn’t a bottom signal; it shows fragility, not that the market has bottomed. After the circuit breaker on 10/15, the index didn’t reverse course, and it lost 6,000 on 10/29.
3. Don’t assume money flowing out of tech and into defensive assets will flow into crypto. U.S. healthcare and defense stocks are rising today; money is going into Treasuries, not BTC.
💡 My take
I wrote “KOSPI Leads Global Declines With a Drop of Over 2%” on 10/20, and pointed to two things to watch: whether U.S. tech giants’ earnings could prove AI is paying off, and the path of interest rates. Today, we got the worst possible answer to the first question: Alphabet shed 500 billion in a single day, its biggest drop in 22 years as a listed company—a dull thud signaling a shift in valuation logic. The signal to watch is whether Samsung follows through on its buyback: the buyback and cancellation were delayed until next January, IBK cut its target price to 350,000 won, and the stock turned negative late in the session.
⚠️ Not investment advice. Do you think today’s KOSPI drop is an emotional selloff or a shift in valuation logic? Let’s discuss in the comments 👇
South Korea’s KOSPI closed today at 5,730.74, down 3.48%, after dipping to 5,599 intraday. Even more striking, the Korea Exchange triggered a sell-side sidecar: futures fell 5.12%, halting program trading for five minutes. The trigger is hidden in three letters: FCF.
📊 Key figures
· KOSPI closed at 5,730.74 (-3.48%), with an intraday low of 5,599
· Sidecar triggered as futures fell 5.12%
· SK Hynix -7.08%, Samsung -3.02%
· Alphabet -12.64%, its biggest drop since listing
· Google FCF: -9.07 billion; Microsoft FCF remained positive at 18.63 billion
🔍 The key contradiction
It’s not that Korea is failing, nor that AI demand has collapsed—Samsung’s Q3 operating profit of 107.4 trillion won and SK Hynix’s 83.33 trillion won are both real. Pepperstone put it accurately: the market isn’t predicting an order collapse; it’s questioning whether shareholders can get returns from the enormous capital being invested. The valuation anchor has shifted: investors used to focus on Capex growth; now they’re watching whether free cash flow is positive. Google’s FCF was -9.07 billion, while Microsoft’s remained positive and its stock fell just 0.16%.
🧊 Three sobering points
1. Record profits at Samsung and SK Hynix can’t rescue their share prices. Profits are backward-looking; share prices are forward-looking. With the focus shifting to cash returns, record profits can only slow the decline.
2. A sidecar isn’t a bottom signal; it shows fragility, not that the market has bottomed. After the circuit breaker on 10/15, the index didn’t reverse course, and it lost 6,000 on 10/29.
3. Don’t assume money flowing out of tech and into defensive assets will flow into crypto. U.S. healthcare and defense stocks are rising today; money is going into Treasuries, not BTC.
💡 My take
I wrote “KOSPI Leads Global Declines With a Drop of Over 2%” on 10/20, and pointed to two things to watch: whether U.S. tech giants’ earnings could prove AI is paying off, and the path of interest rates. Today, we got the worst possible answer to the first question: Alphabet shed 500 billion in a single day, its biggest drop in 22 years as a listed company—a dull thud signaling a shift in valuation logic. The signal to watch is whether Samsung follows through on its buyback: the buyback and cancellation were delayed until next January, IBK cut its target price to 350,000 won, and the stock turned negative late in the session.
⚠️ Not investment advice. Do you think today’s KOSPI drop is an emotional selloff or a shift in valuation logic? Let’s discuss in the comments 👇
186
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
CryptoSelloffTriggersMultipleWhaleLiquidations
70 views
33 Discussing
Crypto Liquidations Top $2B in 24 Hours as 329,000 Traders Are Wiped Out
Binance News
·2 Likes
·848 views
USSpotXRPETFsSeeLargestWeeklyOutflowIn8Months
41,875 views
484 Discussing
WillFOMCMinutesReinforceRateHikeExpectations?
0 views
0 Discussing