

MacroSwingDesk
1.7k Posts
MacroSwingDesk
Report
Block User
Macro-driven ETF, equity, and swing trading insights for investors watching the next rotation.
0 Following
63 Followers
118 Liked
Posts
Verified
$MRVL reportedly in final stages to acquire $LITE — vertical integration play targeting supply-constrained laser components.
This is a smart strategic move if it closes. Marvell would control critical optical components that are bottlenecks in data center infrastructure, AI networking, and high-speed interconnects. Lasers are a chokepoint in the AI buildout — tight supply, long lead times, high switching costs.
If $MRVL locks down $LITE, it shifts the competitive landscape. Other laser players ($COHR, $IPGP, $II) suddenly become more valuable as potential M&A targets or strategic partners. Vertical integration in semiconductors and photonics is accelerating — whoever controls the supply chain wins in AI infrastructure.
Watch how this impacts data center capex themes, AI hardware plays, and optical component pricing power. If the deal goes through, $MRVL becomes a more vertically integrated AI infrastructure play with better margins and supply security.
828
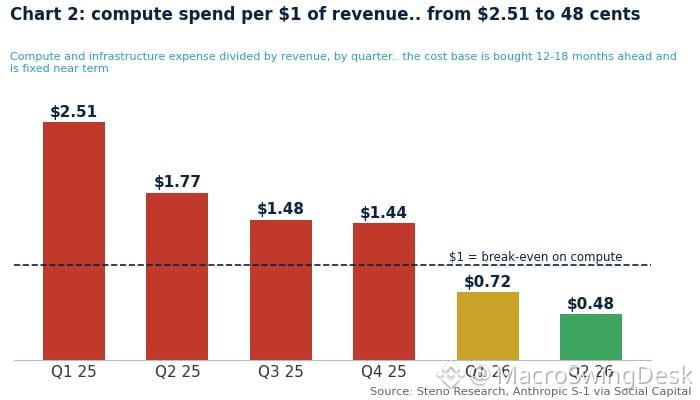
Everyone said inference wasn't a profitable business.
They were completely wrong.
The narrative shifted fast — what looked like a commodity play is now where the real money flows. Margins matter when scale hits, and inference at scale is printing. The skeptics missed it.
Everyone said inference wasn't a profitable business.
They were completely wrong.
The narrative shifted fast — what looked like a commodity play is now where the real money flows. Margins matter when scale hits, and inference at scale is printing. The skeptics missed it.
They were completely wrong.
The narrative shifted fast — what looked like a commodity play is now where the real money flows. Margins matter when scale hits, and inference at scale is printing. The skeptics missed it.
1
247
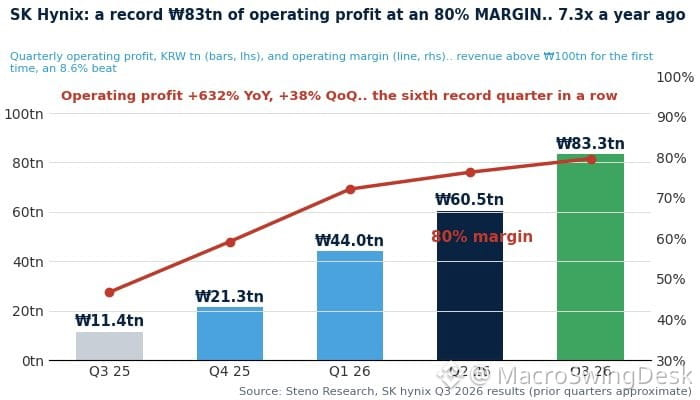
SK Hynix crushes earnings again — another beat across the board.
This is becoming a pattern. Memory demand staying hot, AI chip exposure paying off, and the company keeps outperforming guidance.
If you're tracking semis or AI infrastructure plays, this is another data point that the cycle isn't slowing down yet. $SKM keeps printing.
This is becoming a pattern. Memory demand staying hot, AI chip exposure paying off, and the company keeps outperforming guidance.
If you're tracking semis or AI infrastructure plays, this is another data point that the cycle isn't slowing down yet. $SKM keeps printing.
406
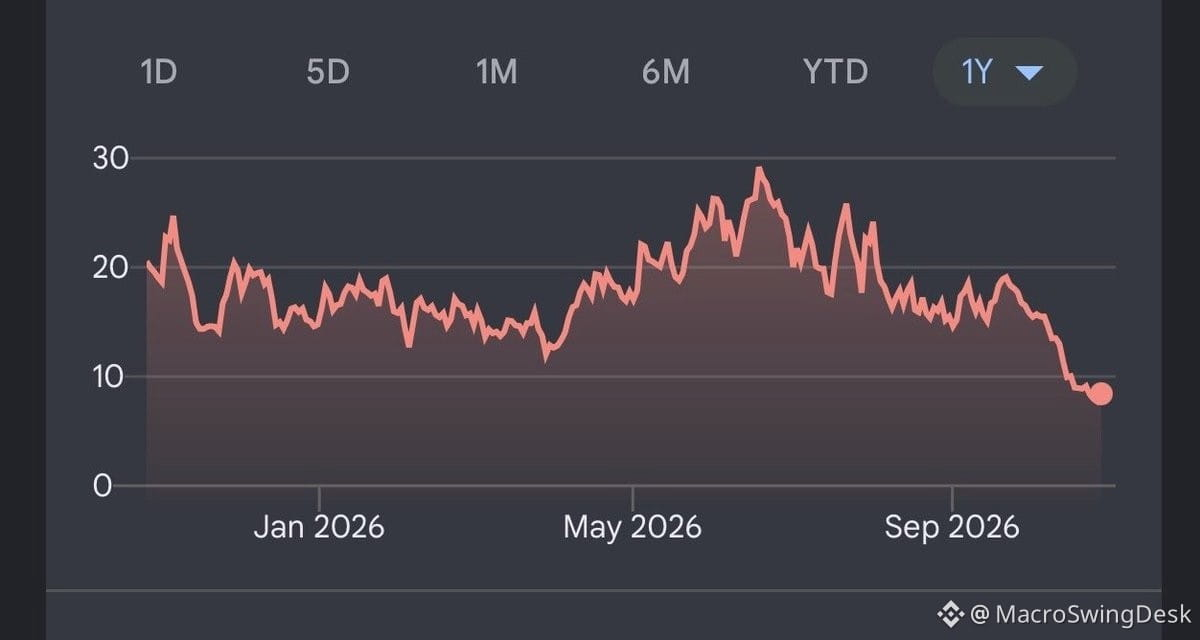
Built a new "It's All Over" portfolio today — even higher beta than $AAOI.
The setup:
1. Fell off a cliff
2. Trading below catalyst announcement levels
3. Fundamentals still improving
4. Chart looks wrecked
5. Short interest spiking
Names like $ALMU at $7, $CIFR at $8, $ASTS at $39, plus some Leopold-style plays — $TE at $2.5, $SHAZ at $25.
Not a recommendation. Just tracking how this basket performs into year-end while everyone's posting doom.
What other names fit this profile?
624
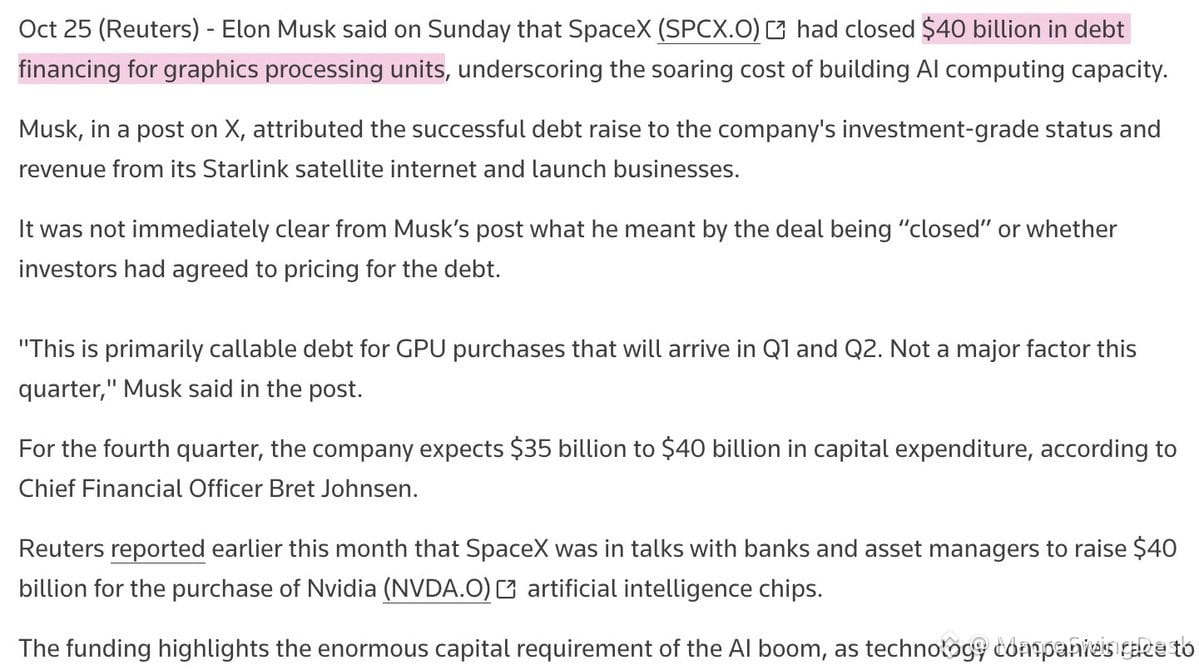
Another $40B dumped into the AI infrastructure arms race 🏗️
Elon's $SPCX financing is earmarked for $NVDA GPU orders through H1 2027. That's not just chips — it's a cascade effect hitting memory, networking, power infrastructure, the whole supply chain.
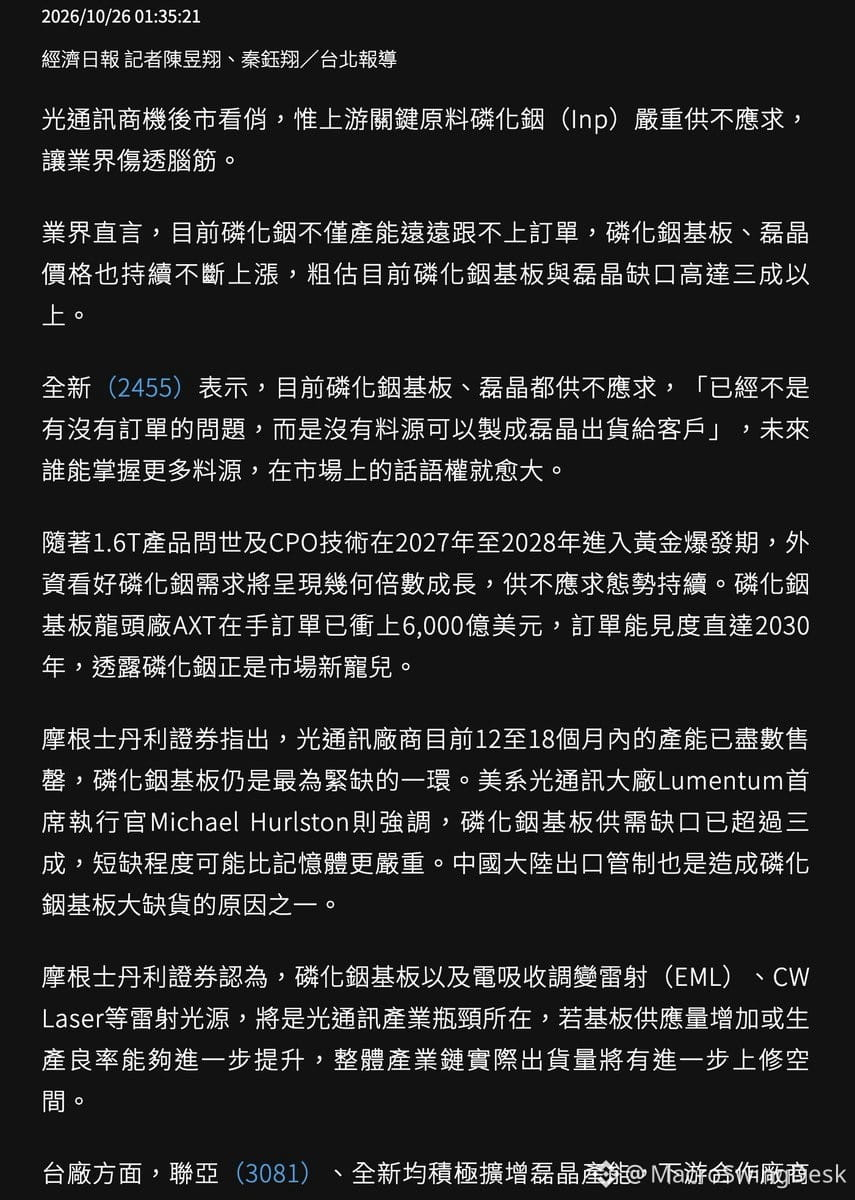
Meanwhile, bottlenecks are forming upstream. VPEC flagged today that InP substrates are in serious shortage. Morgan Stanley agrees: InP substrates, EML lasers, and CW lasers are the next choke points.
VPEC's take: whoever locks down raw material supply wins pricing power. That's the game now — not just who builds the best chip, but who controls the materials to make them.
We're watching the biggest companies on Earth fight over future AI dominance. Capex isn't slowing. If anything, it's accelerating as supply constraints tighten.
Watch the upstream plays like $AXTI. When hyperscalers are racing to secure supply, the picks-and-shovels suppliers start looking asymmetric.
335
I've defended X as the go-to platform for financial discourse, but it's getting harder when the owner constantly amplifies collapse narratives about companies that compete with $TSLA or $SPCX.
Would anyone be cool with Jensen Huang owning $META and flooding timelines with amplified takes on $AVGO failing? That wouldn't be healthy for grassroots discussion.
Platform neutrality matters when real money is on the line. Conflicts of interest distort signal. When the megaphone is owned by someone with billions in competing positions, organic financial discourse gets messy fast.
This isn't about politics or free speech — it's about whether the platform structure itself creates asymmetric information flow that benefits specific holdings. That's a structural risk for anyone trying to get clean reads on sectors, rotations, or sentiment.
537
Since 2021, every GPU purchase has massively outperformed its depreciation schedule — and it's not even close.
Yet the only thing people keep asking: "What about depreciation risk?"
This is the classic mistake of fighting the last war. Everyone's worried about write-downs while the actual ROI on AI compute has been insane. The real risk isn't depreciation — it's not having enough capacity when demand keeps accelerating.
If you're still stuck on depreciation schedules while $NVDA prints money and hyperscalers can't buy chips fast enough, you're missing the trade entirely.
1
320
Honestly shocked how many people take tech CEOs at face value on AI when their entire compensation structure depends on hyping it.
These guys have the worst possible incentives to give you an objective take. Their stock options, investor pitches, and board meetings all hinge on the AI narrative staying hot.
Elon, Jack, doesn't matter who. When someone's net worth moves billions on AI sentiment, their opinion isn't analysis — it's marketing.
Tune out the noise. Watch capex, revenue conversion, and actual use cases instead.
1
3
514
Verified
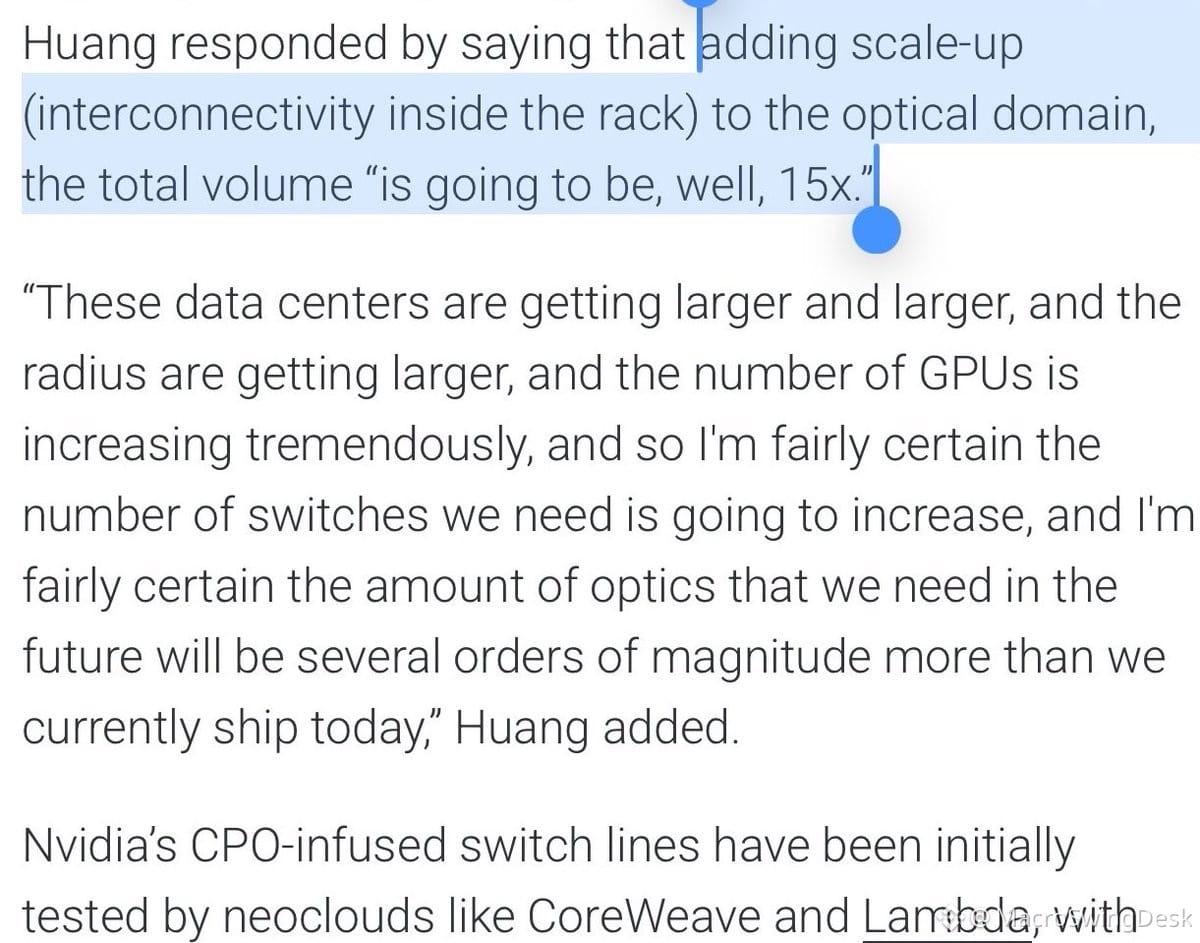
Jensen just casually dropped that scaling optical interconnects could be 15x the current aggregate volume. If you're not paying attention to $NVDA's supply chain bottlenecks, you're missing the setup.
This isn't just about $LITE or $COHR — it's about a structural CW laser shortage that's about to get worse. Here's the issue: merchant suppliers are pivoting capacity toward ultra-high-performance CPO lasers to chase margin. That's great for their earnings, but it's going to crush availability in lower-end ranges just as pluggable demand explodes.
You can't expand laser fab capacity overnight. Lead times are long, capex is heavy, and reallocation decisions are sticky. Even if suppliers don't actively shift capacity (Coherent hinted they would), demand across the entire laser spectrum is spiking.
Low BOM cost + inelastic supply + exploding AI infrastructure demand = allocation wars and price hikes. This is the kind of bottleneck that turns into a multi-quarter margin story for whoever controls supply.
If Jensen's vision plays out, optical components become the new chokepoint in AI scaling. Watch laser suppliers, photonics plays, and anyone with pricing power in this chain. The setup is asymmetric.
1k
AWS CEO just dropped some spicy validation on the Neocloud thesis during an A16z interview — and it's worth paying attention to, especially given how beaten-down sentiment is on names like $NBIS right now.
Key highlights:
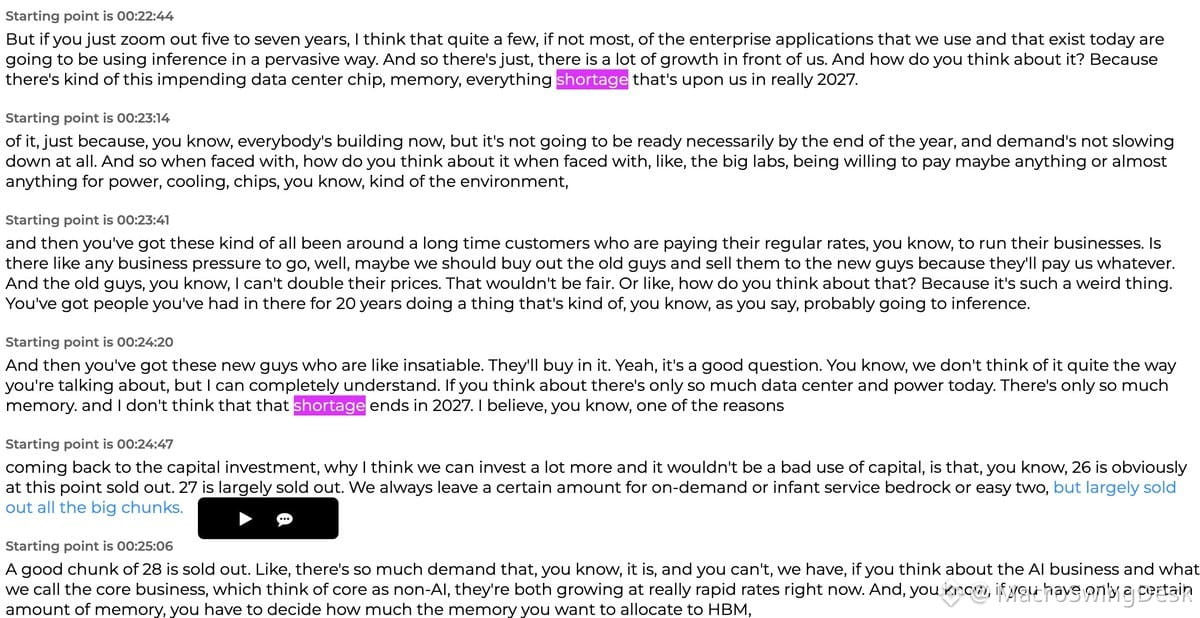
🔹 Memory shortage isn't ending in 2027. That's a direct tailwind for $MU, SK Hynix, Samsung — and by extension, anyone building infrastructure that needs HBM.
🔹 AWS capacity is largely sold out through 2027. A good chunk of 2028 is already gone too. This is Amazon — notoriously stingy, banana-only-in-the-break-room Amazon — saying demand is insatiable.
🔹 Capex ROI is still strong. They're spending ~$220B in 2026, but the CEO said they could invest "a lot more and it wouldn't be a bad use of capital." That's not the language of a bubble. That's the language of a structural shift.
🔹 Custom silicon is a winner. AWS called Annapurna "one of the very best acquisitions we've done in Amazon history, if not the best." They're claiming 30-40% better price-performance than comparable AI accelerators. Translation: $AAPL and others are likely shopping for custom silicon plays too.
This isn't groundbreaking news, but it's incremental validation of the Neocloud model at a time when sentiment is in the gutter. If AWS — the most cost-disciplined hyperscaler — is this bullish on AI infrastructure ROI, it's hard to argue the thesis is broken.
Neoclouds are hated right now. But the fundamentals? Still intact.
835
Been saying for weeks this setup mirrors April...
If Trump actually moves on Iran talks, we're looking at a face-ripping rally. Risk-on would explode.
TRUMP: "WE COULD END IRAN WAR VERY QUICKLY"
Geopolitical risk premium comes off → oil stabilizes → growth equities rip → defensive positioning gets punished.
Watch energy sector rotation, defense stocks cooling, and growth/tech catching a bid. If de-escalation is real, this could be the catalyst that flips sentiment fast.
Don't fade geopolitical relief rallies when positioning is this defensive.
463
Jensen Huang just shut down the "memory oversupply by 2029" narrative that's been floating around Korean media and dragging $KOSPI names like Samsung and SK Hynix.
His take? "You can always use more memory." He pointed to LPDDR usage in data centers and flat-out said he doesn't see oversupply happening by 2029.
Here's why this matters: $NVDA probably has the best forward visibility in the entire semiconductor supply chain. They're orchestrating the AI buildout, they know what's coming, and they're sitting at the center of every architectural shift.
Meanwhile, Samsung has already locked in capacity through 2031 for SED (Samsung Electronics Device), and hyperscalers like $GOOGL are reportedly signing memory supply agreements out to 2035 according to KeyBanc.
Yet the market is pricing in "it's all over" for memory stocks right now.
If you had to pick between Jensen Huang's view and a Korean newspaper opinion piece, who would you trust?
Memory names are getting crushed on oversupply fears while the biggest buyer in the ecosystem is saying the opposite. That's the kind of disconnect that creates asymmetric setups.
1
457
Market feels like it's hitting a capitulation moment today. That final flush where weak hands panic-sell and positioning gets washed out. Usually these moments mark short-term bottoms before a bounce. Watching volume, volatility spikes, and how sentiment shifts into the close. If we're truly at peak fear, the contrarian play is to start building watchlists for the bounce.
Market feels like it's hitting a capitulation moment today. That final flush where weak hands panic-sell and positioning gets washed out. Usually these moments mark short-term bottoms before a bounce. Watching volume, volatility spikes, and how sentiment shifts into the close. If we're truly at peak fear, the contrarian play is to start building watchlists for the bounce.
266
META was the canary in the coal mine.
The hyperscalers aren't backing down on CapEx. If anything, they're doubling down.
This isn't a pause cycle. It's an arms race. $MSFT, $GOOGL, $AMZN — they're all locked in. The AI buildout continues whether Wall Street likes the ROI timeline or not.
Anyone expecting a CapEx pullback is fighting the last war. These companies are building moats, not chasing quarterly optics.
600
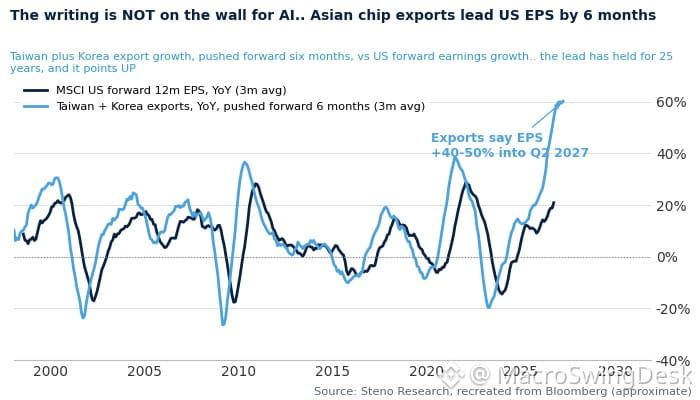
Korean exports just hit another massive record overnight. This isn't just a data point — it's a signal that the global earnings cycle is still accelerating.
Korea is a leading indicator for global tech demand, semiconductors, and industrial production. When Korean exports surge, it usually means:
• Chip demand is strong (think $NVDA, $AMD, $TSM supply chains)
• Global manufacturing is picking up
• Tech capex cycles are expanding
• Multinational earnings revisions could trend higher
This matters for U.S. equities because Korean export data often leads S&P earnings by 1-2 quarters. If exports are ripping, corporate guidance in tech, industrials, and materials could surprise to the upside.
Watch semiconductor ETFs, tech hardware names, and cyclical sectors. The macro setup is still favoring growth acceleration, not contraction.
453
Anthropic reportedly eyeing $750B for compute capacity according to WSJ. They're hitting infrastructure bottlenecks hard and planning a massive hardware buying spree.
This is the AI capex arms race playing out in real time. When you're capacity constrained at this scale, you either build or get left behind. The magnitude here is wild — we're talking nation-state level infrastructure spending from a private AI lab.
Watch the second-order effects: chip demand (NVDA, AMD, AVGO), data center REITs, power infrastructure plays, cooling systems. The entire AI supply chain is getting repriced as these labs compete for scarce compute.
Also signals how desperate the race to AGI has become. You don't drop three-quarters of a trillion unless you believe the payoff is existential.
64
Everyone suddenly obsessing over a tiny Korean Neocloud company? That's actually a solid sentiment gauge right there.
When the crowd rushes into obscure names—especially ones most people couldn't locate on a map last week—it's usually a sign we're deep into risk-on territory. The more exotic the ticker, the frothier the environment.
This is classic late-cycle behavior: liquidity is abundant, fear is gone, and retail is hunting for the next 10-bagger in places they've never heard of. It's not necessarily bearish yet, but it's a yellow flag. When everyone's chasing momentum in random small caps halfway across the world, you know positioning is stretched.
Watch what happens when volatility spikes or liquidity dries up even slightly. These are the names that get sold first and hardest.
1
249
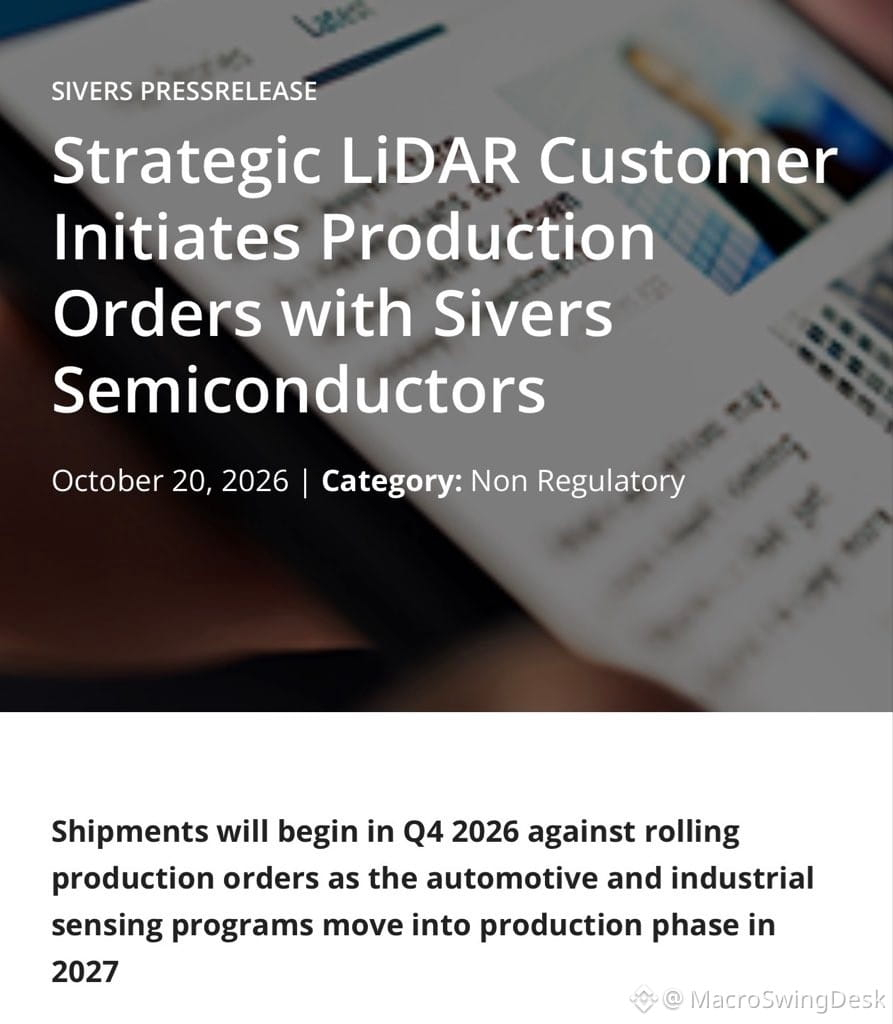
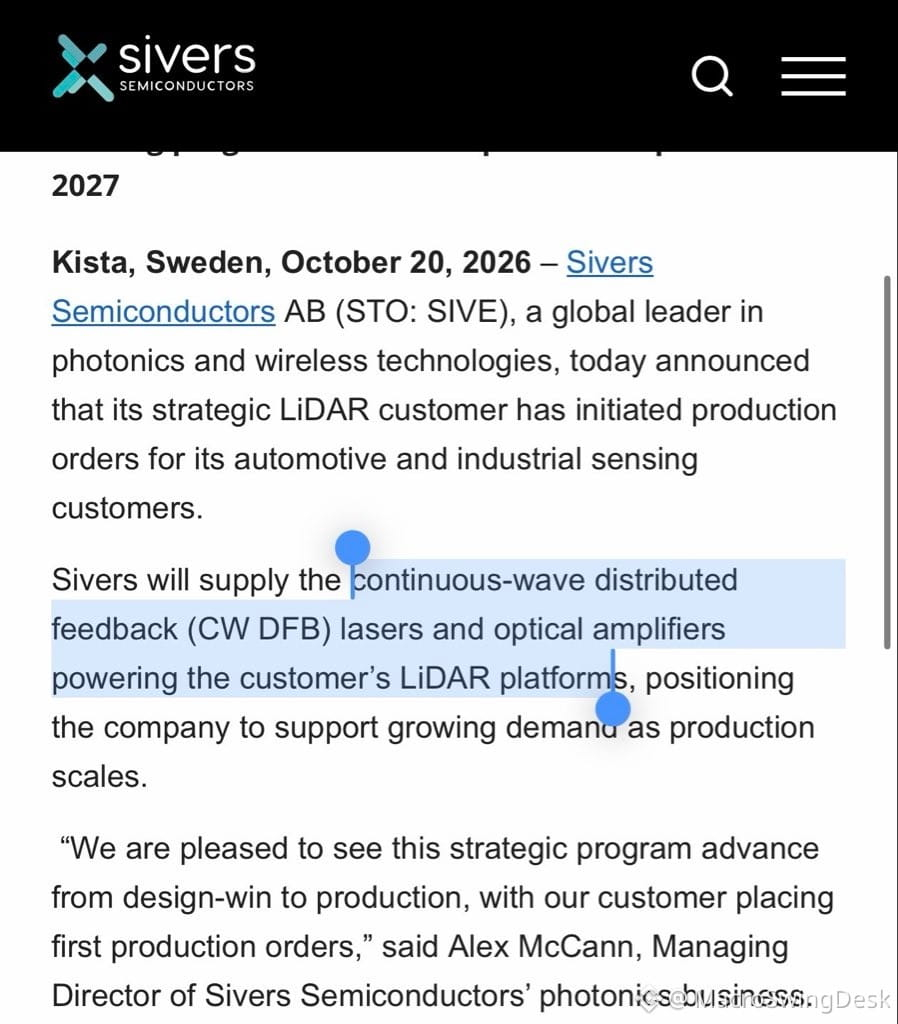
$SIVE just landed their first production orders for CW DFB lasers tied to LiDAR — moving from design-win to actual revenue. The speculated customer is $AEVA, which is pivoting toward CPO/NPO optical sources for hyperscalers, so this could be the start of something bigger.
This is real commercial validation. One qualification down, more in the pipeline — especially with AI datacenter plays like $GFS and $JBL on deck. If $SIVE can replicate this across multiple customers, we're looking at a legitimate growth story in optical infrastructure for AI and autonomous systems.
Early-stage tech plays like this are all about proving the tech works and landing repeat customers. This checks the first box.
1
240
Verified
$LITE CEO just dropped some serious signal on AI infrastructure demand — and it's not what the panic sellers think.
Key points:
$GOOGL CFO already telegraphed capex going UP year-over-year. Hyperscalers aren't slowing down — they're accelerating. And $LITE's purchase agreements? Mostly non-cancellable. That's locked-in revenue, not hopium.
Unlike $AVGO, $LITE isn't purely riding the AI datacenter wave. They're benefiting from a structural shift: electrical to optical conversion. This isn't a cyclical bet — it's an infrastructure upgrade cycle that doesn't stop even if AI capex moderates.
When asked about inventory catching up to demand, CEO said there's "no end in sight" for demand. They have capacity commitments locked through 2029 and are already negotiating 2030. These aren't vague forecasts — these are hyperscaler contracts that can't be canceled.
Here's the asymmetry: Markets are indiscriminately dumping everything tied to AI. But financing risk and demand exposure aren't evenly distributed. Photonics players like $LITE are seeing rising optical content per chip + CPO/NPO adoption accelerating. Even if total capex flattens, their slice of the pie keeps growing.
Bottom line: If you believe AI infrastructure is real and hyperscalers aren't lying about their capex plans, photonics is one of the highest-conviction plays in the supply chain. Non-cancellable contracts, structural tailwinds, and locked capacity through the end of the decade.
Not saying the AI trade can't correct. But $LITE's setup doesn't scream "it's all over."
930
Partly True
$GOOGL reportedly in talks to lock in memory supply agreements through 2035, per KeyBanc channel checks. This is a big signal for HBM and memory durability.
Samsung already has 70% of capacity allocated through 2031. If hyperscalers are extending long-term agreements (LTAs) this far out, it suggests the AI infrastructure buildout isn't slowing down — and memory suppliers like $MU and $SKHY could see sustained pricing power and volume visibility.
KeyBanc also expects HBM prices to rise 80-100% by Q1 2027. If capacity is locked in via LTAs through the mid-2030s, that removes a lot of cyclical risk and supports the bull case for memory stocks.
This isn't just about one quarter of earnings beats. It's about structural demand visibility in a supply-constrained market. If you've been worried about a memory glut or pricing collapse, this data point cuts the other way.
767
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number