
海盗鸭
3.6k Posts
海盗鸭
Report
Block User
69 Following
138 Followers
356 Liked
Posts
All
Quotes
·
--
Ethereum has scheduled its next scaling test for October 26 at 17:42:48 UTC: the Hoodi testnet will activate Glamsterdam, with a single-block gas target of 200 million. The Foundation stressed that 200 million is a planned computational budget, not a hard cap, and that it will be gradually raised under the existing rules.
There are two key changes at the protocol level: EIP-7732 enshrines proposer-builder separation in the protocol, giving validators more time to verify execution results; EIP-7928 records the accounts accessed by each block, paving the way for parallel processing.
The change developers should be most concerned about is the gas pricing adjustment: contracts with hard-coded gas limits or that rely on assumptions about remaining gas could be affected.
My take: the real thing to watch this time is "how block space is priced," not TPS. There’s still no mainnet date as of today, which suggests the client teams aren’t confident it’ll go smoothly on the first try either.
So, $ETH , will you position yourself ahead of the upgrade, or wait until the mainnet date is set?
Ethereum has scheduled its next scaling test for October 26 at 17:42:48 UTC: the Hoodi testnet will activate Glamsterdam, with a single-block gas target of 200 million. The Foundation stressed that 200 million is a planned computational budget, not a hard cap, and that it will be gradually raised under the existing rules.
There are two key changes at the protocol level: EIP-7732 enshrines proposer-builder separation in the protocol, giving validators more time to verify execution results; EIP-7928 records the accounts accessed by each block, paving the way for parallel processing.
The change developers should be most concerned about is the gas pricing adjustment: contracts with hard-coded gas limits or that rely on assumptions about remaining gas could be affected.
My take: the real thing to watch this time is "how block space is priced," not TPS. There’s still no mainnet date as of today, which suggests the client teams aren’t confident it’ll go smoothly on the first try either.
So, $ETH , will you position yourself ahead of the upgrade, or wait until the mainnet date is set?
There are two key changes at the protocol level: EIP-7732 enshrines proposer-builder separation in the protocol, giving validators more time to verify execution results; EIP-7928 records the accounts accessed by each block, paving the way for parallel processing.
The change developers should be most concerned about is the gas pricing adjustment: contracts with hard-coded gas limits or that rely on assumptions about remaining gas could be affected.
My take: the real thing to watch this time is "how block space is priced," not TPS. There’s still no mainnet date as of today, which suggests the client teams aren’t confident it’ll go smoothly on the first try either.
So, $ETH , will you position yourself ahead of the upgrade, or wait until the mainnet date is set?
102
·
--
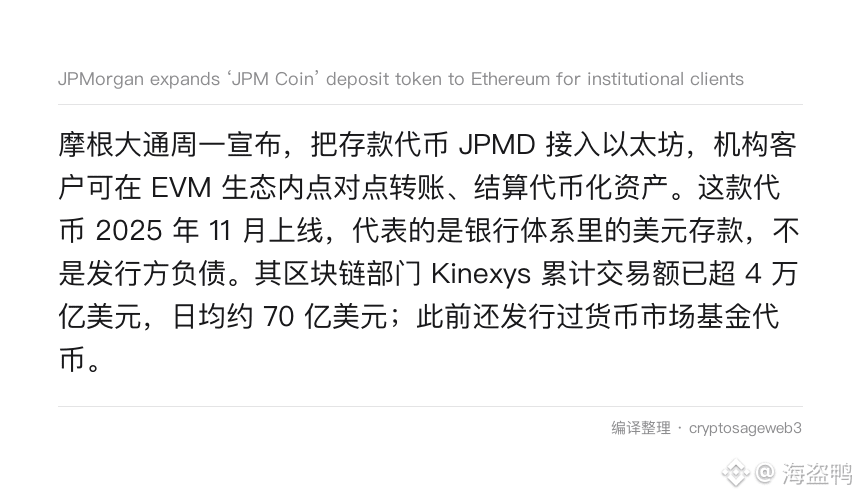
JPMorgan Chase announced on Monday that it would bring its deposit token, JPMD, onto Ethereum, allowing institutional clients to make peer-to-peer transfers and settle tokenized assets within the EVM ecosystem. Launched in November 2025, the token represents dollar deposits in the banking system, rather than liabilities of the issuer. Its blockchain division, Kinexys, has processed more than $4 trillion in cumulative transactions, averaging around $7 billion per day. It has also previously issued money market fund tokens.
I think the significance of this development is being underestimated. The competition among stablecoins has never really been about which one is more decentralized, but about which one has cleaner underlying assets. Deposit tokens are collateralized by the deposits themselves, naturally sidestepping debates over reserve transparency. For Ethereum, this means the settlement layer for institutional dollar flows continues to move on-chain.
The caveat is that these tokens must be transferable across institutions. If each bank operates only within its own closed loop, on-chain liquidity will be fragmented.
One follow-up question: if bank-issued deposit tokens scale up, will $ETH 's settlement demand benefit first, or will the entire public blockchain narrative be revalued?
JPMorgan Chase announced on Monday that it would bring its deposit token, JPMD, onto Ethereum, allowing institutional clients to make peer-to-peer transfers and settle tokenized assets within the EVM ecosystem. Launched in November 2025, the token represents dollar deposits in the banking system, rather than liabilities of the issuer. Its blockchain division, Kinexys, has processed more than $4 trillion in cumulative transactions, averaging around $7 billion per day. It has also previously issued money market fund tokens.
I think the significance of this development is being underestimated. The competition among stablecoins has never really been about which one is more decentralized, but about which one has cleaner underlying assets. Deposit tokens are collateralized by the deposits themselves, naturally sidestepping debates over reserve transparency. For Ethereum, this means the settlement layer for institutional dollar flows continues to move on-chain.
The caveat is that these tokens must be transferable across institutions. If each bank operates only within its own closed loop, on-chain liquidity will be fragmented.
One follow-up question: if bank-issued deposit tokens scale up, will $ETH 's settlement demand benefit first, or will the entire public blockchain narrative be revalued?
I think the significance of this development is being underestimated. The competition among stablecoins has never really been about which one is more decentralized, but about which one has cleaner underlying assets. Deposit tokens are collateralized by the deposits themselves, naturally sidestepping debates over reserve transparency. For Ethereum, this means the settlement layer for institutional dollar flows continues to move on-chain.
The caveat is that these tokens must be transferable across institutions. If each bank operates only within its own closed loop, on-chain liquidity will be fragmented.
One follow-up question: if bank-issued deposit tokens scale up, will $ETH 's settlement demand benefit first, or will the entire public blockchain narrative be revalued?
168
·
--
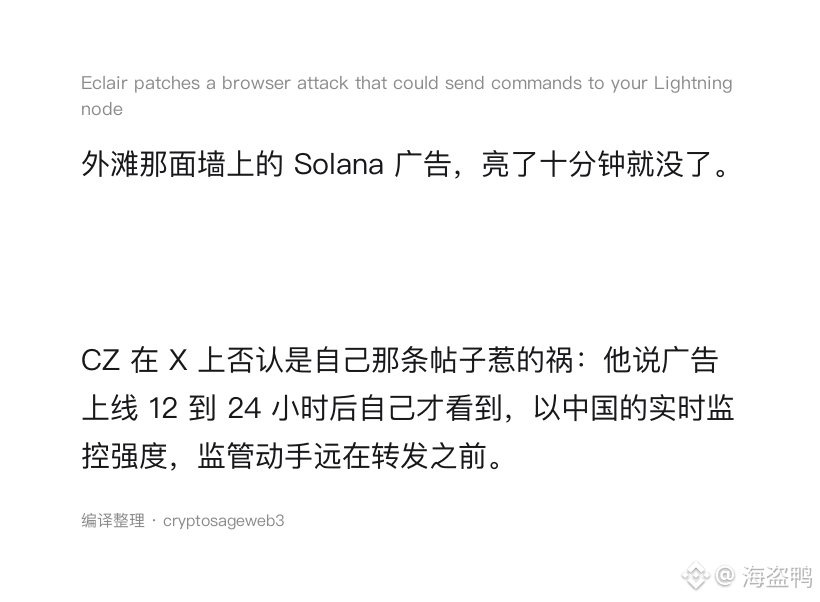
The Solana ad on that wall along the Bund was up for just ten minutes before it disappeared.
CZ denied on X that his post was what caused it: he said he only saw the ad 12 to 24 hours after it went live. Given the intensity of China’s real-time monitoring, regulators would have acted long before any repost. It started when Solana had just opened an office in Shanghai and launched a high-profile ad campaign, which the market interpreted as “China easing up.” Then an event originally scheduled for October 16 at the Shangri-La was postponed. The organizers cited logistical reasons, and Lily Liu said registrations had tripled at the last minute.
What matters more to me isn’t who posted what, but that “opening an office ≠ lifting the ban”: China banned crypto trading in 2021, and in February this year expanded its crackdown to include stablecoin issuance and asset tokenization. CZ himself also acknowledged that the ban hasn’t been lifted.
So how much of $SOL ’s valuation premium is based on “China lifting the ban”? As this wave recedes, will it underperform $BTC , or prove more resilient?
The Solana ad on that wall along the Bund was up for just ten minutes before it disappeared.
CZ denied on X that his post was what caused it: he said he only saw the ad 12 to 24 hours after it went live. Given the intensity of China’s real-time monitoring, regulators would have acted long before any repost. It started when Solana had just opened an office in Shanghai and launched a high-profile ad campaign, which the market interpreted as “China easing up.” Then an event originally scheduled for October 16 at the Shangri-La was postponed. The organizers cited logistical reasons, and Lily Liu said registrations had tripled at the last minute.
What matters more to me isn’t who posted what, but that “opening an office ≠ lifting the ban”: China banned crypto trading in 2021, and in February this year expanded its crackdown to include stablecoin issuance and asset tokenization. CZ himself also acknowledged that the ban hasn’t been lifted.
So how much of $SOL ’s valuation premium is based on “China lifting the ban”? As this wave recedes, will it underperform $BTC , or prove more resilient?
CZ denied on X that his post was what caused it: he said he only saw the ad 12 to 24 hours after it went live. Given the intensity of China’s real-time monitoring, regulators would have acted long before any repost. It started when Solana had just opened an office in Shanghai and launched a high-profile ad campaign, which the market interpreted as “China easing up.” Then an event originally scheduled for October 16 at the Shangri-La was postponed. The organizers cited logistical reasons, and Lily Liu said registrations had tripled at the last minute.
What matters more to me isn’t who posted what, but that “opening an office ≠ lifting the ban”: China banned crypto trading in 2021, and in February this year expanded its crackdown to include stablecoin issuance and asset tokenization. CZ himself also acknowledged that the ban hasn’t been lifted.
So how much of $SOL ’s valuation premium is based on “China lifting the ban”? As this wave recedes, will it underperform $BTC , or prove more resilient?
315
·
--
On-chain monitoring shows that a wallet associated with MARA transferred 1,000 bitcoins to exchanges within five days, worth about $82.8 million. This is already the second time this month: on October 9, 996 coins (about $81.13 million) flowed to an address of Galaxy Digital. In its Q2 disclosure, MARA said it held 35,577 bitcoins as of the end of June, of which 9,270 were staked or lent out — this transfer of 1,000 coins accounts for about 2.8% of its holdings.
The pace is even more worth watching: in Q2, MARA sold 2,213 coins at an average price of $73,078 and explicitly said it would continue selling when the opportunity arose; in March it also sold 15,133 coins to buy back convertible bonds.
My take: when the price fell from $86,000 to $82,000 and ETFs saw net outflows of $910 million over two consecutive weeks, miners adding another round of supply means the supply side gets drained twice, and the second time is passive — not because they are bearish, but because they have electricity bills to pay.
The question is left here: if the third-quarter report confirms this was a sale, would you dare buy above $BTC 810, or wait for that 78,500 support level?
On-chain monitoring shows that a wallet associated with MARA transferred 1,000 bitcoins to exchanges within five days, worth about $82.8 million. This is already the second time this month: on October 9, 996 coins (about $81.13 million) flowed to an address of Galaxy Digital. In its Q2 disclosure, MARA said it held 35,577 bitcoins as of the end of June, of which 9,270 were staked or lent out — this transfer of 1,000 coins accounts for about 2.8% of its holdings.
The pace is even more worth watching: in Q2, MARA sold 2,213 coins at an average price of $73,078 and explicitly said it would continue selling when the opportunity arose; in March it also sold 15,133 coins to buy back convertible bonds.
My take: when the price fell from $86,000 to $82,000 and ETFs saw net outflows of $910 million over two consecutive weeks, miners adding another round of supply means the supply side gets drained twice, and the second time is passive — not because they are bearish, but because they have electricity bills to pay.
The question is left here: if the third-quarter report confirms this was a sale, would you dare buy above $BTC 810, or wait for that 78,500 support level?
The pace is even more worth watching: in Q2, MARA sold 2,213 coins at an average price of $73,078 and explicitly said it would continue selling when the opportunity arose; in March it also sold 15,133 coins to buy back convertible bonds.
My take: when the price fell from $86,000 to $82,000 and ETFs saw net outflows of $910 million over two consecutive weeks, miners adding another round of supply means the supply side gets drained twice, and the second time is passive — not because they are bearish, but because they have electricity bills to pay.
The question is left here: if the third-quarter report confirms this was a sale, would you dare buy above $BTC 810, or wait for that 78,500 support level?
1
200
·
--
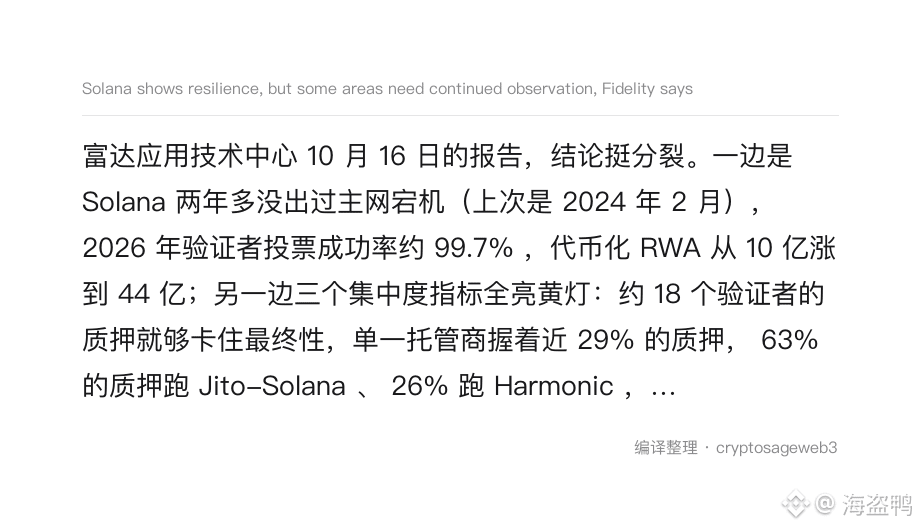
The Fidelity Center for Applied Technology’s October 16 report reached a pretty divided conclusion. On one hand, Solana has had no mainnet outages in more than two years (the last one was in February 2024), validator vote success rates in 2026 are around 99.7%, and tokenized RWA has grown from $1 billion to $4.4 billion. On the other hand, three concentration metrics are all flashing yellow: the stake of about 18 validators is enough to halt finality, a single custodian controls nearly 29% of the stake, 63% of the stake runs Jito-Solana and 26% runs Harmonic—both based on the same Agave codebase—and around 40% of the stake is clustered in Frankfurt and Amsterdam.
My take: the report’s real value isn’t in saying “SOL is stable,” but in shifting the risk question from “could it go down?” to “could everything go down at once?” Shared code means one vulnerability could take out nearly 90% of the stake, which is much harder to hedge against than an outage.
At $SOL , do you think the market is pricing in “two years without an incident,” or has it not even accounted for concentration risk?
The Fidelity Center for Applied Technology’s October 16 report reached a pretty divided conclusion. On one hand, Solana has had no mainnet outages in more than two years (the last one was in February 2024), validator vote success rates in 2026 are around 99.7%, and tokenized RWA has grown from $1 billion to $4.4 billion. On the other hand, three concentration metrics are all flashing yellow: the stake of about 18 validators is enough to halt finality, a single custodian controls nearly 29% of the stake, 63% of the stake runs Jito-Solana and 26% runs Harmonic—both based on the same Agave codebase—and around 40% of the stake is clustered in Frankfurt and Amsterdam.
My take: the report’s real value isn’t in saying “SOL is stable,” but in shifting the risk question from “could it go down?” to “could everything go down at once?” Shared code means one vulnerability could take out nearly 90% of the stake, which is much harder to hedge against than an outage.
At $SOL , do you think the market is pricing in “two years without an incident,” or has it not even accounted for concentration risk?
My take: the report’s real value isn’t in saying “SOL is stable,” but in shifting the risk question from “could it go down?” to “could everything go down at once?” Shared code means one vulnerability could take out nearly 90% of the stake, which is much harder to hedge against than an outage.
At $SOL , do you think the market is pricing in “two years without an incident,” or has it not even accounted for concentration risk?
267
·
--
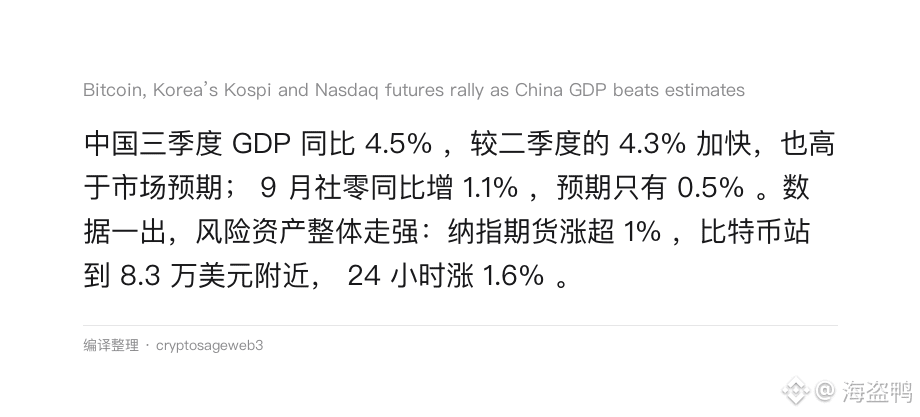
China’s Q3 GDP grew 4.5% year over year, accelerating from 4.3% in Q2 and beating market expectations. September retail sales rose 1.1% year over year, versus expectations of just 0.5%. After the data came out, risk assets broadly strengthened: Nasdaq futures rose more than 1%, Bitcoin climbed to around $83,000, up 1.6% over 24 hours.
One detail is worth considering: gold barely moved that day, remaining around $4,180, while the dollar index stayed below 102. With risk appetite recovering, gold was flat while Bitcoin rose. This looks more like liquidity expectations driving up beta assets than investors buying safe havens.
My view: Bitcoin is now trading as global risk beta, not digital gold. What will really set the direction is the U.S. September CPI, which has risen to 3.7%, and the Federal Reserve meeting on October 27–28. If expectations for rate cuts keep getting pushed back, this rally to $83,000 could well be just a rebound.
Question: Will $BTC first test the resistance at $86,600, or pull back to the 50-day moving average at $80,600? #ChinaQ3EconomicGrowthAcceleratesTo4.5%
China’s Q3 GDP grew 4.5% year over year, accelerating from 4.3% in Q2 and beating market expectations. September retail sales rose 1.1% year over year, versus expectations of just 0.5%. After the data came out, risk assets broadly strengthened: Nasdaq futures rose more than 1%, Bitcoin climbed to around $83,000, up 1.6% over 24 hours.
One detail is worth considering: gold barely moved that day, remaining around $4,180, while the dollar index stayed below 102. With risk appetite recovering, gold was flat while Bitcoin rose. This looks more like liquidity expectations driving up beta assets than investors buying safe havens.
My view: Bitcoin is now trading as global risk beta, not digital gold. What will really set the direction is the U.S. September CPI, which has risen to 3.7%, and the Federal Reserve meeting on October 27–28. If expectations for rate cuts keep getting pushed back, this rally to $83,000 could well be just a rebound.
Question: Will $BTC first test the resistance at $86,600, or pull back to the 50-day moving average at $80,600? #ChinaQ3EconomicGrowthAcceleratesTo4.5%
One detail is worth considering: gold barely moved that day, remaining around $4,180, while the dollar index stayed below 102. With risk appetite recovering, gold was flat while Bitcoin rose. This looks more like liquidity expectations driving up beta assets than investors buying safe havens.
My view: Bitcoin is now trading as global risk beta, not digital gold. What will really set the direction is the U.S. September CPI, which has risen to 3.7%, and the Federal Reserve meeting on October 27–28. If expectations for rate cuts keep getting pushed back, this rally to $83,000 could well be just a rebound.
Question: Will $BTC first test the resistance at $86,600, or pull back to the 50-day moving average at $80,600? #ChinaQ3EconomicGrowthAcceleratesTo4.5%
106
·
--
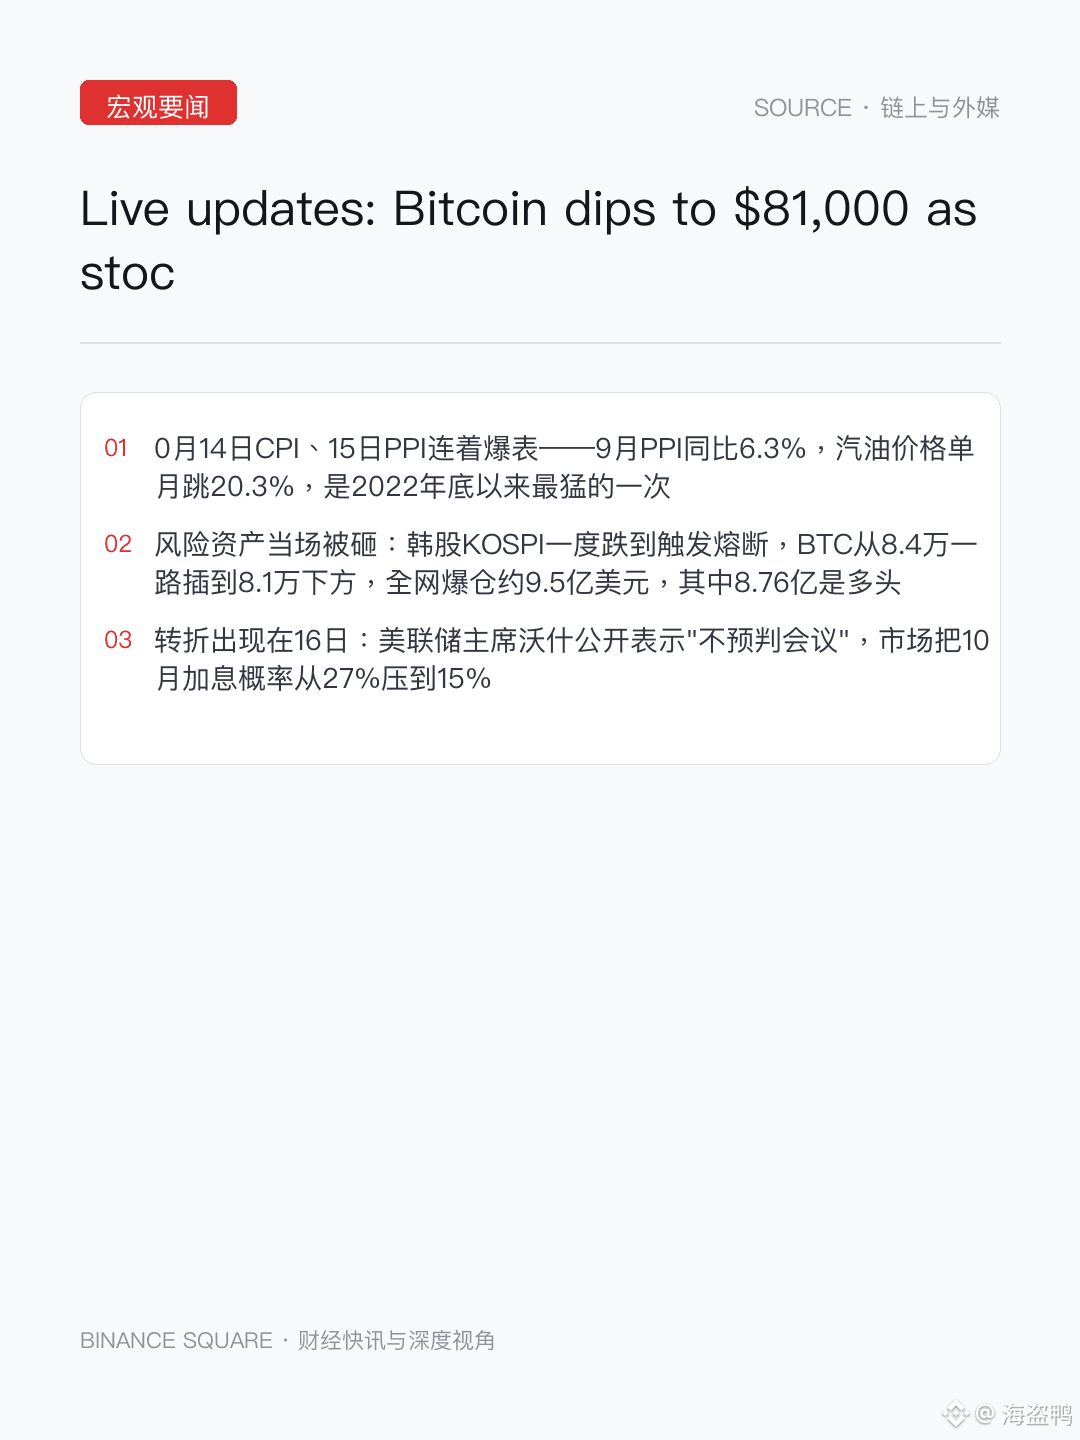
CPI on October 14 and PPI on the 15th both came in scorching hot—September PPI was up 6.3% year over year, while gasoline prices jumped 20.3% in a single month, the biggest surge since late 2022. Risk assets were hit hard on the spot: South Korea’s KOSPI briefly fell far enough to trigger a circuit breaker, BTC plunged from 84,000 to below 81,000, and liquidations across the market totaled about $950 million, including $876 million in long positions.
The turnaround came on the 16th: Fed Chair Warsh publicly said he “wouldn’t prejudge the meeting,” and the market cut the probability of a rate hike in October from 27% to 15%. $BTC promptly recovered to 82,000, giving risk appetite a brief rebound.
My take is that we need to understand what’s driving this rally: it’s coming from “lower rate-hike odds,” not “stronger buying”—ETFs have been seeing net outflows during this period. A rally propped up by shifting expectations can quickly give back its gains if the next inflation report comes in hotter than expected again.
So there’s just one question: at 82,000, is $BTC a spot to trim positions on the rebound, or a chance to get back in?
#BitcoinReboundsTo$82,000
CPI on October 14 and PPI on the 15th both came in scorching hot—September PPI was up 6.3% year over year, while gasoline prices jumped 20.3% in a single month, the biggest surge since late 2022. Risk assets were hit hard on the spot: South Korea’s KOSPI briefly fell far enough to trigger a circuit breaker, BTC plunged from 84,000 to below 81,000, and liquidations across the market totaled about $950 million, including $876 million in long positions.
The turnaround came on the 16th: Fed Chair Warsh publicly said he “wouldn’t prejudge the meeting,” and the market cut the probability of a rate hike in October from 27% to 15%. $BTC promptly recovered to 82,000, giving risk appetite a brief rebound.
My take is that we need to understand what’s driving this rally: it’s coming from “lower rate-hike odds,” not “stronger buying”—ETFs have been seeing net outflows during this period. A rally propped up by shifting expectations can quickly give back its gains if the next inflation report comes in hotter than expected again.
So there’s just one question: at 82,000, is $BTC a spot to trim positions on the rebound, or a chance to get back in?
#BitcoinReboundsTo$82,000
The turnaround came on the 16th: Fed Chair Warsh publicly said he “wouldn’t prejudge the meeting,” and the market cut the probability of a rate hike in October from 27% to 15%. $BTC promptly recovered to 82,000, giving risk appetite a brief rebound.
My take is that we need to understand what’s driving this rally: it’s coming from “lower rate-hike odds,” not “stronger buying”—ETFs have been seeing net outflows during this period. A rally propped up by shifting expectations can quickly give back its gains if the next inflation report comes in hotter than expected again.
So there’s just one question: at 82,000, is $BTC a spot to trim positions on the rebound, or a chance to get back in?
#BitcoinReboundsTo$82,000
153
·
--
Anthropic says Claude solved a mystery in under half an hour: several unexplained elliptic-curve seeds published by NIST about 25 years ago were actually generated by the old C library random number generator lrand48, seeded with Unix timestamps from 1997–1998. The P-256 seed corresponds to August 16, 1997, at 01:52:34. The process is reproducible, and the $36,000 bounty was donated to the Internet Security Research Group. The company emphasizes that this was neither an attack nor a new vulnerability.
My take: What fell apart wasn’t a particular backdoor, but the narrative that “mysterious constants must be a conspiracy”—once the seeds can be reproduced, deliberate planting becomes much harder to argue. Bitcoin uses secp256k1, which wasn’t on the list in the first place, so this neither hit nor exonerated it. The base points for P-224 and P-256 still aren’t fully explained.
The curve choice made by $BTC was criticized as overly conservative at the time. Would you still bet on it today?
Anthropic says Claude solved a mystery in under half an hour: several unexplained elliptic-curve seeds published by NIST about 25 years ago were actually generated by the old C library random number generator lrand48, seeded with Unix timestamps from 1997–1998. The P-256 seed corresponds to August 16, 1997, at 01:52:34. The process is reproducible, and the $36,000 bounty was donated to the Internet Security Research Group. The company emphasizes that this was neither an attack nor a new vulnerability.
My take: What fell apart wasn’t a particular backdoor, but the narrative that “mysterious constants must be a conspiracy”—once the seeds can be reproduced, deliberate planting becomes much harder to argue. Bitcoin uses secp256k1, which wasn’t on the list in the first place, so this neither hit nor exonerated it. The base points for P-224 and P-256 still aren’t fully explained.
The curve choice made by $BTC was criticized as overly conservative at the time. Would you still bet on it today?
My take: What fell apart wasn’t a particular backdoor, but the narrative that “mysterious constants must be a conspiracy”—once the seeds can be reproduced, deliberate planting becomes much harder to argue. Bitcoin uses secp256k1, which wasn’t on the list in the first place, so this neither hit nor exonerated it. The base points for P-224 and P-256 still aren’t fully explained.
The curve choice made by $BTC was criticized as overly conservative at the time. Would you still bet on it today?
155
·
--
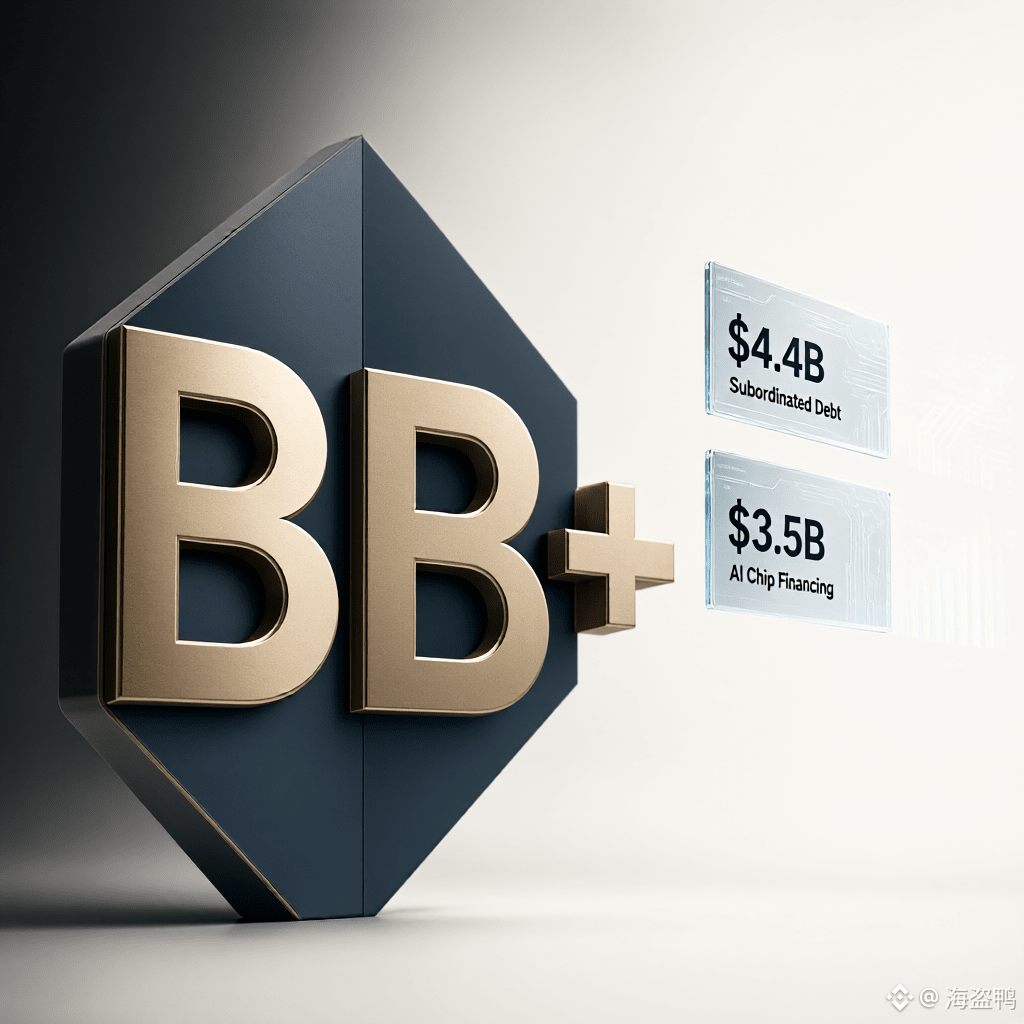
Anthropic received a BB+ rating from KBRA, one notch below investment grade. The rating covers $4.4 billion of subordinated debt in a $3.5 billion AI chip financing deal, with a coupon of around 8.5%; the senior debt backed by Broadcom in the same deal carries a rate of just 5.75%.
Adam Back responded yesterday: Bitcoin is the hurdle rate; every investment should be compared with holding Bitcoin.
I’m inclined to think this is valuation language, not a valuation method—$BTC has no coupon, so you can’t use it as a discount rate to calculate a value. What’s really being repriced is the safe asset: the 10-year Treasury yield topped 5.3% in early October, a 24-year high.
With risk-free rates at this level, AI debt yielding 8.5% is competing with Treasuries for the same pool of money. If AI financing costs rise further, will money flow back to $BTC first, or to Treasuries?
Anthropic received a BB+ rating from KBRA, one notch below investment grade. The rating covers $4.4 billion of subordinated debt in a $3.5 billion AI chip financing deal, with a coupon of around 8.5%; the senior debt backed by Broadcom in the same deal carries a rate of just 5.75%.
Adam Back responded yesterday: Bitcoin is the hurdle rate; every investment should be compared with holding Bitcoin.
I’m inclined to think this is valuation language, not a valuation method—$BTC has no coupon, so you can’t use it as a discount rate to calculate a value. What’s really being repriced is the safe asset: the 10-year Treasury yield topped 5.3% in early October, a 24-year high.
With risk-free rates at this level, AI debt yielding 8.5% is competing with Treasuries for the same pool of money. If AI financing costs rise further, will money flow back to $BTC first, or to Treasuries?
Adam Back responded yesterday: Bitcoin is the hurdle rate; every investment should be compared with holding Bitcoin.
I’m inclined to think this is valuation language, not a valuation method—$BTC has no coupon, so you can’t use it as a discount rate to calculate a value. What’s really being repriced is the safe asset: the 10-year Treasury yield topped 5.3% in early October, a 24-year high.
With risk-free rates at this level, AI debt yielding 8.5% is competing with Treasuries for the same pool of money. If AI financing costs rise further, will money flow back to $BTC first, or to Treasuries?
1
230
·
--
Can it return to $100,000 by year-end? Two firms have different answers: Bitwise research head Ryan Rasmussen says it could go higher and has a chance of topping $100,000; London-based LO:TECH puts its base case at $85,000 to $95,000.
The difference comes down to macro factors: The Fed already raised rates by 25 basis points in September, and markets put the odds of another hike in December at around 75%; CPI on October 14 came in at 0.6% month over month, with core CPI at 0.3%—not exactly supportive. Cumulative net ETF inflows also fell from nearly $57.8 billion on October 2 to $56.88 billion on the 16th.
I lean toward LO:TECH’s range: The prerequisite for $100,000 is a shift in the macro outlook, but right now market pricing is moving in the opposite direction. Bullish sentiment can’t make up for a 75% chance of a rate hike. $BTC If it really crashes back below $80,000, would you buy the dip or wait until the December decision is in before making a move?
Can it return to $100,000 by year-end? Two firms have different answers: Bitwise research head Ryan Rasmussen says it could go higher and has a chance of topping $100,000; London-based LO:TECH puts its base case at $85,000 to $95,000.
The difference comes down to macro factors: The Fed already raised rates by 25 basis points in September, and markets put the odds of another hike in December at around 75%; CPI on October 14 came in at 0.6% month over month, with core CPI at 0.3%—not exactly supportive. Cumulative net ETF inflows also fell from nearly $57.8 billion on October 2 to $56.88 billion on the 16th.
I lean toward LO:TECH’s range: The prerequisite for $100,000 is a shift in the macro outlook, but right now market pricing is moving in the opposite direction. Bullish sentiment can’t make up for a 75% chance of a rate hike. $BTC If it really crashes back below $80,000, would you buy the dip or wait until the December decision is in before making a move?
The difference comes down to macro factors: The Fed already raised rates by 25 basis points in September, and markets put the odds of another hike in December at around 75%; CPI on October 14 came in at 0.6% month over month, with core CPI at 0.3%—not exactly supportive. Cumulative net ETF inflows also fell from nearly $57.8 billion on October 2 to $56.88 billion on the 16th.
I lean toward LO:TECH’s range: The prerequisite for $100,000 is a shift in the macro outlook, but right now market pricing is moving in the opposite direction. Bullish sentiment can’t make up for a 75% chance of a rate hike. $BTC If it really crashes back below $80,000, would you buy the dip or wait until the December decision is in before making a move?
93
·
--
On October 15, MSCI finalized a new rule: “non-operating companies” will be excluded from the GIMI Index, effective after the market close on November 30. The criteria are mechanical: companies with operating assets below 50% of total assets must then pass four out of five financial ratio tests—or be excluded.
The company in the spotlight is Strategy. JPMorgan estimates that if it is removed, passive funds would need to sell about $2.8 billion worth of shares, with other index providers potentially adding another $8.8 billion if they follow suit. Strategy says MSCI-linked funds hold only about 13 million of its shares. Saylor was even more blunt: “Bitcoin doesn’t need MSCI.”
The real impact isn’t the few billion in passive fund flows, but access to financing: Strategy buys bitcoin through a “issue shares—buy bitcoin—issue more shares” cycle, and index eligibility is the gateway. If that gateway is blocked, the premium logic behind $MSTRB needs to be reassessed, and $BTC loses its biggest source of demand.
Would you view this rule as a prelude, or do you think the backlash will be strong enough to water down its implementation?
On October 15, MSCI finalized a new rule: “non-operating companies” will be excluded from the GIMI Index, effective after the market close on November 30. The criteria are mechanical: companies with operating assets below 50% of total assets must then pass four out of five financial ratio tests—or be excluded.
The company in the spotlight is Strategy. JPMorgan estimates that if it is removed, passive funds would need to sell about $2.8 billion worth of shares, with other index providers potentially adding another $8.8 billion if they follow suit. Strategy says MSCI-linked funds hold only about 13 million of its shares. Saylor was even more blunt: “Bitcoin doesn’t need MSCI.”
The real impact isn’t the few billion in passive fund flows, but access to financing: Strategy buys bitcoin through a “issue shares—buy bitcoin—issue more shares” cycle, and index eligibility is the gateway. If that gateway is blocked, the premium logic behind $MSTRB needs to be reassessed, and $BTC loses its biggest source of demand.
Would you view this rule as a prelude, or do you think the backlash will be strong enough to water down its implementation?
The company in the spotlight is Strategy. JPMorgan estimates that if it is removed, passive funds would need to sell about $2.8 billion worth of shares, with other index providers potentially adding another $8.8 billion if they follow suit. Strategy says MSCI-linked funds hold only about 13 million of its shares. Saylor was even more blunt: “Bitcoin doesn’t need MSCI.”
The real impact isn’t the few billion in passive fund flows, but access to financing: Strategy buys bitcoin through a “issue shares—buy bitcoin—issue more shares” cycle, and index eligibility is the gateway. If that gateway is blocked, the premium logic behind $MSTRB needs to be reassessed, and $BTC loses its biggest source of demand.
Would you view this rule as a prelude, or do you think the backlash will be strong enough to water down its implementation?
212
·
--
Verified
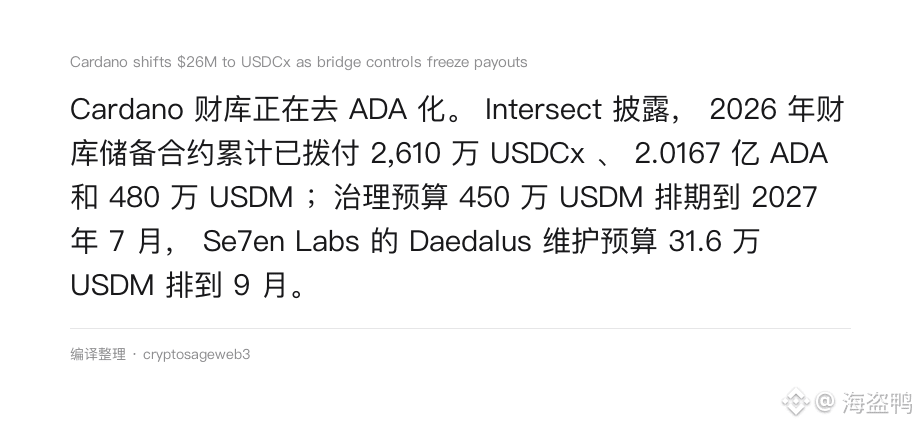
Cardano’s treasury is moving away from ADA. Intersect disclosed that, in 2026, treasury reserve contracts have cumulatively disbursed 26.1 million USDCx, 201.67 million ADA, and 4.8 million USDM. A governance budget of 4.5 million USDM is scheduled through July 2027, while Se7en Labs’ 316,000 USDM budget for maintaining Daedalus runs through September.
The key is the structure: once budgets are denominated in dollars, spending for the next two years is locked in, and ADA’s price movements have no bearing on those funds. An October 16 snapshot showed that three payments from September 29 had been unlocked, but no milestone evidence had been submitted—unlocking funds doesn’t mean they can be spent. What’s more, USDCx must first be converted into USDC before it can be paid out, and Circle, IOG, and Midgard each have the authority to pause the bridge. Redemptions are also subject to identity and sanctions checks.
My view is that governance is buying itself insurance, not that this is bearish—but it does chip away at the “paying with $ADA” narrative. If more treasuries follow suit and shift to dollars, would you still hold $ADA for the long term?
Cardano’s treasury is moving away from ADA. Intersect disclosed that, in 2026, treasury reserve contracts have cumulatively disbursed 26.1 million USDCx, 201.67 million ADA, and 4.8 million USDM. A governance budget of 4.5 million USDM is scheduled through July 2027, while Se7en Labs’ 316,000 USDM budget for maintaining Daedalus runs through September.
The key is the structure: once budgets are denominated in dollars, spending for the next two years is locked in, and ADA’s price movements have no bearing on those funds. An October 16 snapshot showed that three payments from September 29 had been unlocked, but no milestone evidence had been submitted—unlocking funds doesn’t mean they can be spent. What’s more, USDCx must first be converted into USDC before it can be paid out, and Circle, IOG, and Midgard each have the authority to pause the bridge. Redemptions are also subject to identity and sanctions checks.
My view is that governance is buying itself insurance, not that this is bearish—but it does chip away at the “paying with $ADA ” narrative. If more treasuries follow suit and shift to dollars, would you still hold $ADA for the long term?
The key is the structure: once budgets are denominated in dollars, spending for the next two years is locked in, and ADA’s price movements have no bearing on those funds. An October 16 snapshot showed that three payments from September 29 had been unlocked, but no milestone evidence had been submitted—unlocking funds doesn’t mean they can be spent. What’s more, USDCx must first be converted into USDC before it can be paid out, and Circle, IOG, and Midgard each have the authority to pause the bridge. Redemptions are also subject to identity and sanctions checks.
My view is that governance is buying itself insurance, not that this is bearish—but it does chip away at the “paying with $ADA ” narrative. If more treasuries follow suit and shift to dollars, would you still hold $ADA for the long term?
259
·
--
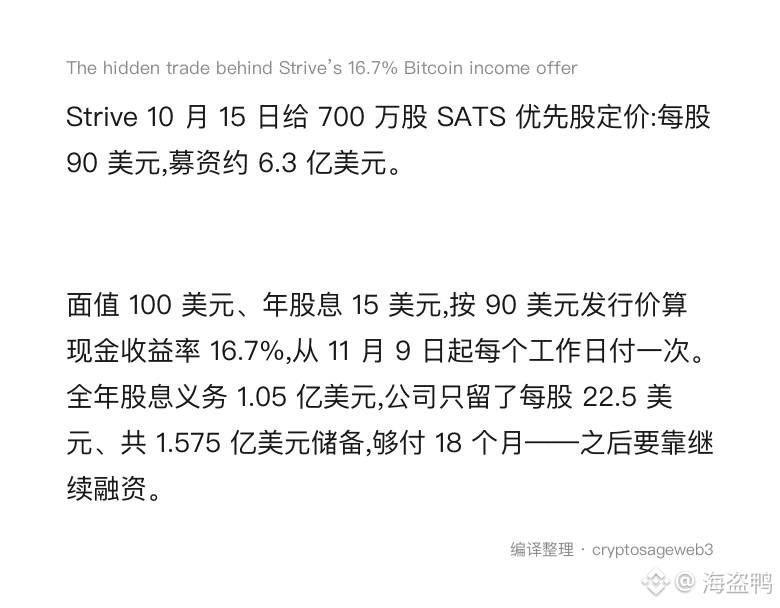
On October 15, Strive priced 7 million shares of SATS preferred stock at $90 per share, raising approximately $630 million.
With a $100 face value and an annual dividend of $15, the cash yield at the $90 offering price is 16.7%. Payments begin on November 9 and are made every business day. The annual dividend obligation is $105 million, but the company has set aside only $22.50 per share, or $157.5 million in total—enough to cover 18 months. After that, it will need to keep raising capital.
What really matters is the order of priority: these shares rank ahead of common stock, but behind existing SATA preferred stock, debt, and certain subsidiary obligations. Nor is there any guarantee that all the proceeds will be used to buy BTC.
My take: 16.7% isn’t a premium handed out for free; it’s the price of a liability. Bitcoin generates no cash flow, so the dividends can only be sustained through liquidity and refinancing. A larger total holding doesn’t mean more BTC backing each share.
So, given the same amount of money, would you choose a BTC treasury preferred stock with a 16.7% coupon, or buy spot $BTC ?
On October 15, Strive priced 7 million shares of SATS preferred stock at $90 per share, raising approximately $630 million.
With a $100 face value and an annual dividend of $15, the cash yield at the $90 offering price is 16.7%. Payments begin on November 9 and are made every business day. The annual dividend obligation is $105 million, but the company has set aside only $22.50 per share, or $157.5 million in total—enough to cover 18 months. After that, it will need to keep raising capital.
What really matters is the order of priority: these shares rank ahead of common stock, but behind existing SATA preferred stock, debt, and certain subsidiary obligations. Nor is there any guarantee that all the proceeds will be used to buy BTC.
My take: 16.7% isn’t a premium handed out for free; it’s the price of a liability. Bitcoin generates no cash flow, so the dividends can only be sustained through liquidity and refinancing. A larger total holding doesn’t mean more BTC backing each share.
So, given the same amount of money, would you choose a BTC treasury preferred stock with a 16.7% coupon, or buy spot $BTC ?
With a $100 face value and an annual dividend of $15, the cash yield at the $90 offering price is 16.7%. Payments begin on November 9 and are made every business day. The annual dividend obligation is $105 million, but the company has set aside only $22.50 per share, or $157.5 million in total—enough to cover 18 months. After that, it will need to keep raising capital.
What really matters is the order of priority: these shares rank ahead of common stock, but behind existing SATA preferred stock, debt, and certain subsidiary obligations. Nor is there any guarantee that all the proceeds will be used to buy BTC.
My take: 16.7% isn’t a premium handed out for free; it’s the price of a liability. Bitcoin generates no cash flow, so the dividends can only be sustained through liquidity and refinancing. A larger total holding doesn’t mean more BTC backing each share.
So, given the same amount of money, would you choose a BTC treasury preferred stock with a 16.7% coupon, or buy spot $BTC ?
140
·
--
TRON settled $2.21 trillion in stablecoins in Q3, up 5.1% quarter over quarter, with on-chain USDT+USDD balances of $93.88 billion.
The other side of the story: from July 1 to October 16, TRX supply increased every day for 108 days. In Q3, 360.2 million tokens were issued and 234.5 million were burned, for a net increase of 125.8 million. In the first 16 days of October, another 22.9 million were added, bringing the total to about 148.6 million.
The key is the mechanism: bandwidth and energy are obtained through staking and replenish on a rolling 24-hour basis, so no matter how many transactions there are, they don’t burn underlying TRX. Issuance, however, is fixed per block. In the first half of October, burns covered just 63.5% of issuance. So I’m inclined to think the narrative that “high settlement volume = deflation” has run its course—stakers get the newly issued TRX, while passive holders bear the dilution.
If you hold $TRX , would you stake to earn rewards, or accept this dilution?
TRON settled $2.21 trillion in stablecoins in Q3, up 5.1% quarter over quarter, with on-chain USDT+USDD balances of $93.88 billion.
The other side of the story: from July 1 to October 16, TRX supply increased every day for 108 days. In Q3, 360.2 million tokens were issued and 234.5 million were burned, for a net increase of 125.8 million. In the first 16 days of October, another 22.9 million were added, bringing the total to about 148.6 million.
The key is the mechanism: bandwidth and energy are obtained through staking and replenish on a rolling 24-hour basis, so no matter how many transactions there are, they don’t burn underlying TRX. Issuance, however, is fixed per block. In the first half of October, burns covered just 63.5% of issuance. So I’m inclined to think the narrative that “high settlement volume = deflation” has run its course—stakers get the newly issued TRX, while passive holders bear the dilution.
If you hold $TRX , would you stake to earn rewards, or accept this dilution?
The other side of the story: from July 1 to October 16, TRX supply increased every day for 108 days. In Q3, 360.2 million tokens were issued and 234.5 million were burned, for a net increase of 125.8 million. In the first 16 days of October, another 22.9 million were added, bringing the total to about 148.6 million.
The key is the mechanism: bandwidth and energy are obtained through staking and replenish on a rolling 24-hour basis, so no matter how many transactions there are, they don’t burn underlying TRX. Issuance, however, is fixed per block. In the first half of October, burns covered just 63.5% of issuance. So I’m inclined to think the narrative that “high settlement volume = deflation” has run its course—stakers get the newly issued TRX, while passive holders bear the dilution.
If you hold $TRX , would you stake to earn rewards, or accept this dilution?
100
·
--
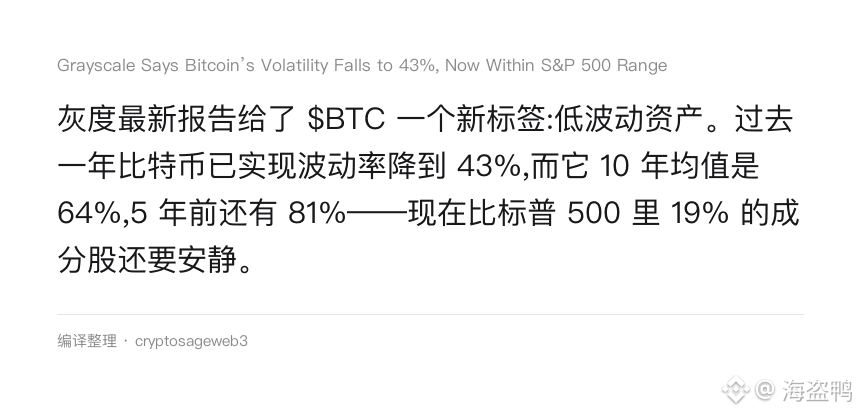
Grayscale’s latest report gave $BTC a new label: low-volatility asset. Bitcoin’s realized volatility fell to 43% over the past year, compared with a 10-year average of 64% and 81% five years ago—making it quieter than 19% of S&P 500 constituents.
The report, authored by Head of Research Zach Pandl, attributes this to deepening liquidity, institutional participation, and regulated channels such as spot ETFs. What it really means isn’t that “Bitcoin has become boring,” but that the question has shifted from “Should I buy a high-volatility asset?” to “How large should my position be?”
I tend to think this narrative is useful, but don’t treat it as a conclusion: Grayscale itself also cautions that one year of data isn’t enough to define risk across market cycles, and a plunge like the one in March 2020 could still happen again.
At 43% volatility, do you think Bitcoin is stable enough to support larger institutional allocations—or does this look more like self-reassurance in the middle of a bull market?
Grayscale’s latest report gave $BTC a new label: low-volatility asset. Bitcoin’s realized volatility fell to 43% over the past year, compared with a 10-year average of 64% and 81% five years ago—making it quieter than 19% of S&P 500 constituents.
The report, authored by Head of Research Zach Pandl, attributes this to deepening liquidity, institutional participation, and regulated channels such as spot ETFs. What it really means isn’t that “Bitcoin has become boring,” but that the question has shifted from “Should I buy a high-volatility asset?” to “How large should my position be?”
I tend to think this narrative is useful, but don’t treat it as a conclusion: Grayscale itself also cautions that one year of data isn’t enough to define risk across market cycles, and a plunge like the one in March 2020 could still happen again.
At 43% volatility, do you think Bitcoin is stable enough to support larger institutional allocations—or does this look more like self-reassurance in the middle of a bull market?
The report, authored by Head of Research Zach Pandl, attributes this to deepening liquidity, institutional participation, and regulated channels such as spot ETFs. What it really means isn’t that “Bitcoin has become boring,” but that the question has shifted from “Should I buy a high-volatility asset?” to “How large should my position be?”
I tend to think this narrative is useful, but don’t treat it as a conclusion: Grayscale itself also cautions that one year of data isn’t enough to define risk across market cycles, and a plunge like the one in March 2020 could still happen again.
At 43% volatility, do you think Bitcoin is stable enough to support larger institutional allocations—or does this look more like self-reassurance in the middle of a bull market?
106
·
--
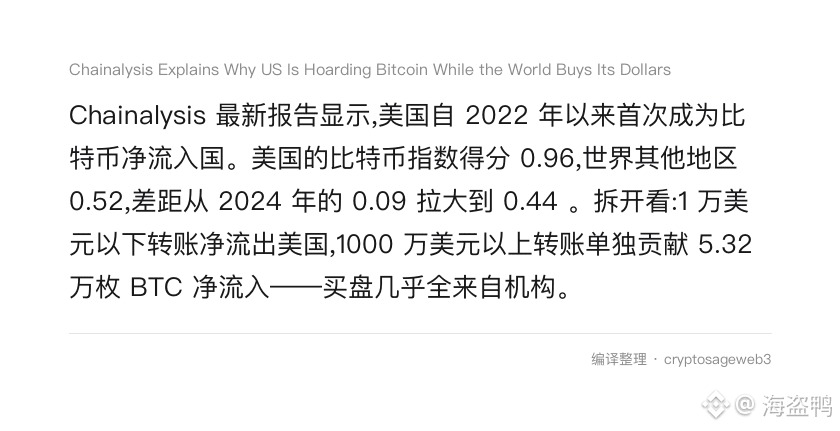
Chainalysis’s latest report shows that the U.S. has become a net recipient of Bitcoin inflows for the first time since 2022. The U.S. Bitcoin index score is 0.96, compared with 0.52 for the rest of the world, widening the gap from 0.09 in 2024 to 0.44. Breaking it down: transfers under $10,000 show net outflows from the U.S., while transfers over $10 million alone account for net inflows of 53,200 BTC—the buying is almost entirely coming from institutions.
The stablecoin index shows the exact opposite: 1.00 for the rest of the world and 0.56 for the U.S. Dollar stablecoins account for 99.1% of stablecoin order-book trading volume, and most of their reserves are in short-term U.S. Treasuries.
My take is that these are two sides of the same coin: foreigners use stablecoins to access dollars, while U.S. institutions use ETFs to scoop up Bitcoin; the latter is far less stable, as institutional allocations follow risk appetite.
The question is: with marginal buying for $BTC increasingly reliant on U.S. institutions, if we see another sell-off in chip stocks like last week’s, will this layer of buyers be the first to pull out?
Chainalysis’s latest report shows that the U.S. has become a net recipient of Bitcoin inflows for the first time since 2022. The U.S. Bitcoin index score is 0.96, compared with 0.52 for the rest of the world, widening the gap from 0.09 in 2024 to 0.44. Breaking it down: transfers under $10,000 show net outflows from the U.S., while transfers over $10 million alone account for net inflows of 53,200 BTC—the buying is almost entirely coming from institutions.
The stablecoin index shows the exact opposite: 1.00 for the rest of the world and 0.56 for the U.S. Dollar stablecoins account for 99.1% of stablecoin order-book trading volume, and most of their reserves are in short-term U.S. Treasuries.
My take is that these are two sides of the same coin: foreigners use stablecoins to access dollars, while U.S. institutions use ETFs to scoop up Bitcoin; the latter is far less stable, as institutional allocations follow risk appetite.
The question is: with marginal buying for $BTC increasingly reliant on U.S. institutions, if we see another sell-off in chip stocks like last week’s, will this layer of buyers be the first to pull out?
The stablecoin index shows the exact opposite: 1.00 for the rest of the world and 0.56 for the U.S. Dollar stablecoins account for 99.1% of stablecoin order-book trading volume, and most of their reserves are in short-term U.S. Treasuries.
My take is that these are two sides of the same coin: foreigners use stablecoins to access dollars, while U.S. institutions use ETFs to scoop up Bitcoin; the latter is far less stable, as institutional allocations follow risk appetite.
The question is: with marginal buying for $BTC increasingly reliant on U.S. institutions, if we see another sell-off in chip stocks like last week’s, will this layer of buyers be the first to pull out?
188
·
--
AI infrastructure stocks were slaughtered this week: NBIS plunged 10.1% to $186 on October 14, then fell about 6% again on Friday, retreating roughly 27% from the previous week’s high.
The trigger wasn’t demand—it was the cost of financing. Yields on a $1.25 billion CoreWeave bond briefly surged to around 15%, CDS spreads topped 1,000 basis points, and a “Yikes” in a repost set off Wednesday’s sell-off. Highly leveraged compute companies took the hit first, with Gartner warning that more than 80% of neoclouds may not be able to operate independently by 2030.
My take: This is a repricing of the “borrow to build compute capacity” model, not a rejection of AI demand. $NBISB returning to its 200-day moving average is the level worth watching.
This sector and crypto share one key variable: rate-hike expectations. Would you choose $BTC and wait for rate cuts, or bet that AI infrastructure rebounds first?
#AI and semiconductor stocks lost over $1 trillion in market value this week
AI infrastructure stocks were slaughtered this week: NBIS plunged 10.1% to $186 on October 14, then fell about 6% again on Friday, retreating roughly 27% from the previous week’s high.
The trigger wasn’t demand—it was the cost of financing. Yields on a $1.25 billion CoreWeave bond briefly surged to around 15%, CDS spreads topped 1,000 basis points, and a “Yikes” in a repost set off Wednesday’s sell-off. Highly leveraged compute companies took the hit first, with Gartner warning that more than 80% of neoclouds may not be able to operate independently by 2030.
My take: This is a repricing of the “borrow to build compute capacity” model, not a rejection of AI demand. $NBISB returning to its 200-day moving average is the level worth watching.
This sector and crypto share one key variable: rate-hike expectations. Would you choose $BTC and wait for rate cuts, or bet that AI infrastructure rebounds first?
#AI and semiconductor stocks lost over $1 trillion in market value this week
The trigger wasn’t demand—it was the cost of financing. Yields on a $1.25 billion CoreWeave bond briefly surged to around 15%, CDS spreads topped 1,000 basis points, and a “Yikes” in a repost set off Wednesday’s sell-off. Highly leveraged compute companies took the hit first, with Gartner warning that more than 80% of neoclouds may not be able to operate independently by 2030.
My take: This is a repricing of the “borrow to build compute capacity” model, not a rejection of AI demand. $NBISB returning to its 200-day moving average is the level worth watching.
This sector and crypto share one key variable: rate-hike expectations. Would you choose $BTC and wait for rate cuts, or bet that AI infrastructure rebounds first?
#AI and semiconductor stocks lost over $1 trillion in market value this week
110
·
--
Charles Hoskinson said on October 18 that he and IOG engineer Lucas Rosa are writing a new language for Cardano: intent-based transactions, proof-carrying data (PCD), and Groth16 zero-knowledge proofs. No name, source code, or timeline has been provided.
The numbers are striking: ADA has a market cap of about $8.3 billion, while total value locked across Cardano DeFi is only $63 million. Weekly trading volume is $8.35 million, down 25% week over week, and the network’s stablecoin supply is about $70 million. By comparison, Solana’s DeFi deposits are more than 90 times higher.
So here’s my take: what ADA lacks isn’t a language—it’s demand. Holders treat it as a store of value, not as on-chain collateral, and the 65-fold increase in throughput promised by Leios won’t change that ratio.
$ADA In this rally, are you adding to your position or trimming it?
Charles Hoskinson said on October 18 that he and IOG engineer Lucas Rosa are writing a new language for Cardano: intent-based transactions, proof-carrying data (PCD), and Groth16 zero-knowledge proofs. No name, source code, or timeline has been provided.
The numbers are striking: ADA has a market cap of about $8.3 billion, while total value locked across Cardano DeFi is only $63 million. Weekly trading volume is $8.35 million, down 25% week over week, and the network’s stablecoin supply is about $70 million. By comparison, Solana’s DeFi deposits are more than 90 times higher.
So here’s my take: what ADA lacks isn’t a language—it’s demand. Holders treat it as a store of value, not as on-chain collateral, and the 65-fold increase in throughput promised by Leios won’t change that ratio.
$ADA In this rally, are you adding to your position or trimming it?
The numbers are striking: ADA has a market cap of about $8.3 billion, while total value locked across Cardano DeFi is only $63 million. Weekly trading volume is $8.35 million, down 25% week over week, and the network’s stablecoin supply is about $70 million. By comparison, Solana’s DeFi deposits are more than 90 times higher.
So here’s my take: what ADA lacks isn’t a language—it’s demand. Holders treat it as a store of value, not as on-chain collateral, and the 65-fold increase in throughput promised by Leios won’t change that ratio.
$ADA In this rally, are you adding to your position or trimming it?
21
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
BinanceWithdrawalScamWarning
1,841 views
159 Discussing
Binance Warns Users of Withdrawal Scams as Services Resume: It Will Never Charge Fees, Sell Queue Spots or Ask You to Move Funds to a “Vault”
Binance News
·1 Likes
·2k views
USMidtermElections
545,263 views
2,719 Discussing
USOctoberNFP-AreRateCutsStillPossible
9,386 views
256 Discussing