

阿曾
371 Posts

阿曾
Report
Block User
币圈韭菜 x: @web3zeng
Open Trade

BTC Holder
Frequent Trader
4.9 Years
84 Following
464 Followers
775 Liked
Posts
Portfolio
All
Quotes
Videos
·
--
Bullish
#币安将恢复第一阶段提现 Binance has opened withdrawals, so why is there so little activity on-chain?
Hahaha, because nobody knows where everyone withdrew to.
#币安将恢复第一阶段提现 Binance has opened withdrawals, so why is there so little activity on-chain?
Hahaha, because nobody knows where everyone withdrew to.
Hahaha, because nobody knows where everyone withdrew to.
94
·
--
Bearish
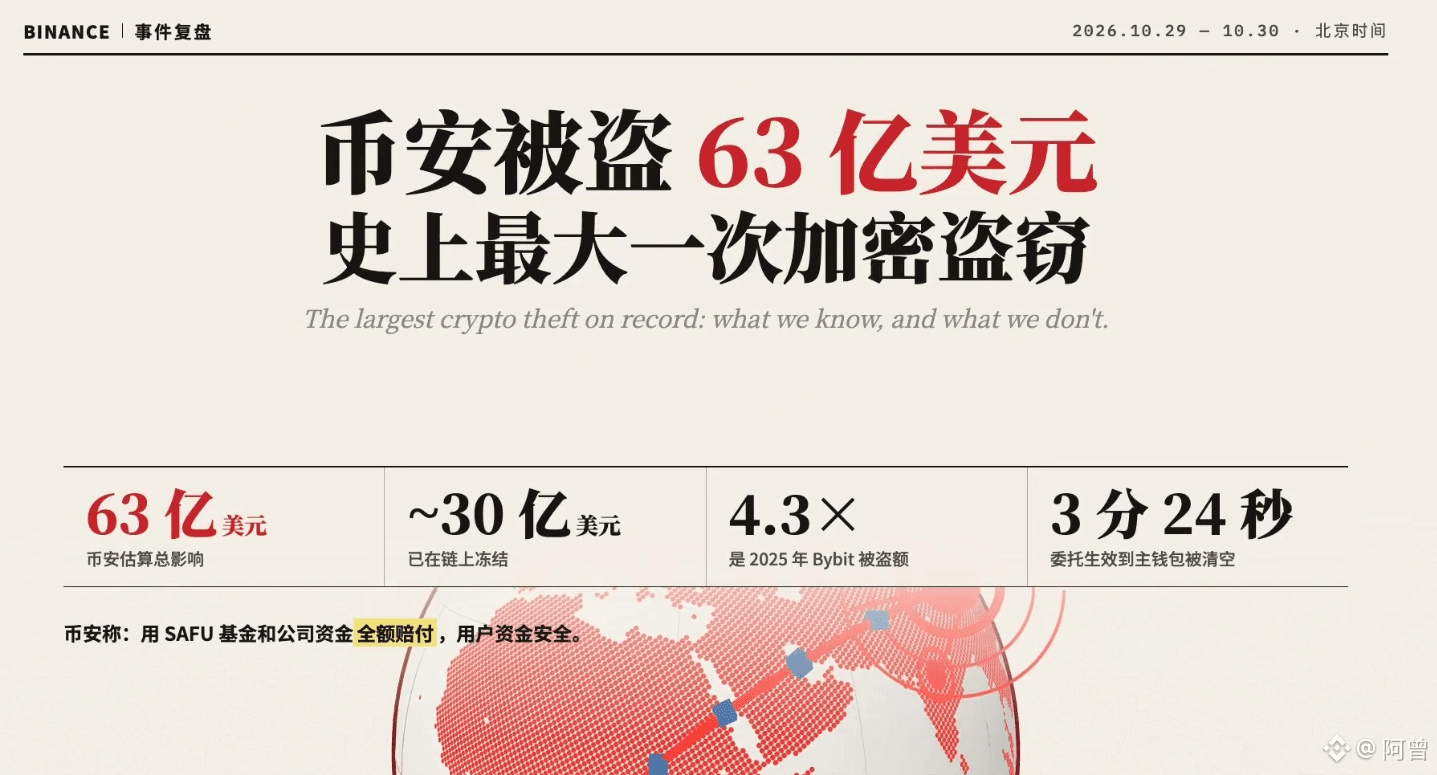
#fbi确认朝鲜应对币安被盗事件负责
The FBI has officially named North Korean hackers as the culprits behind Binance’s loss of more than $6 billion. They operate under the codename TraderTraitor and are often linked to the Lazarus Group.
It happened around October 29. They pulled it off in just a few minutes, in a record-breaking heist.
As for their methods, most of the stolen funds were first converted into Ethereum $ETH , then shuffled through DeFi, cross-chain bridges, and instant swaps to launder them. Some of the stablecoins have already been frozen (reports put the amount at over $2 billion), but most of the funds are still moving around on-chain.
The FBI has also joined forces with the Secret Service and IRS Criminal Investigation to issue a call:
Exchanges, node operators, and analytics firms need to block those addresses immediately and stop the dirty money from moving further.
The takeaway: This wasn’t an ordinary case of hackers showing off. It looks more like a state-sponsored effort to “steal money to prop up the regime”—North Korea often relies on crypto theft to obtain foreign currency.
Now that the perpetrators have been named, international pressure will intensify:
Address blacklists will grow, regulated exchanges will face tighter scrutiny, and DeFi platforms will also be called on to help.
For Binance: Its image shifts from “paying out of pocket” to “willing to compensate users even after a state-sponsored attack.” That could boost trust in the short term, but regulators will keep a closer eye on it.
For ordinary users: The main thing is whether your platform makes you whole. Stay away from airdrops, cross-chain transfers, and obscure exchanges of dubious origin. If your funds touch a tainted address, they could be frozen.
In short: The FBI has confirmed “who did it,” but the money is still being tracked;
Binance being able to pay is one thing. The industry’s next challenge is defending itself against state-level attackers.
18
3
23
45.4k
·
--
Bullish
#cz称币安赔付到位最重要是保护用户 , this is what you should be doing.
#cz称币安赔付到位最重要是保护用户 , this is what you should be doing.
75
·
--
Bullish
Participating in token launches with Agent Wallet is fairly equitable, since each KYC gets one Agent ID. If the project team limits the subscription amount per account, it can ensure a fair launch.
Participating in token launches with Agent Wallet is fairly equitable, since each KYC gets one Agent ID. If the project team limits the subscription amount per account, it can ensure a fair launch.
1
217
·
--
Bullish
I've been in crypto for years, always witnessing history...
$BNB Buy the dip!
I've been in crypto for years, always witnessing history...
$BNB Buy the dip!
$BNB Buy the dip!
1
122
·
--
Bullish
#anthropic预计今日公布s1招股书
Anthropic (the parent company of Claude) publicly filed on October 26 under the ticker ANT, with plans to list on Nasdaq. It had submitted a confidential filing in June; this is the public version. The roadshow could begin as early as the week of November 9, with the listing planned for the week of November 16. The company is aiming to raise up to $100 billion at a valuation of $1.5 trillion to $2 trillion—bigger than SpaceX’s June offering ($86.3 billion raised at a $1.77 trillion valuation).
Revenue is growing incredibly fast: $16.286 billion in the first half, versus $1.163 billion in the same period last year—a 14-fold increase. Second-quarter revenue alone was $11.555 billion. Full-year revenue in 2023 was just $41 million; it has grown more than a hundredfold in three years.
The “$80.7 billion loss” is an accounting figure, not actual cash burn. The company reported a net loss of $80.748 billion in the first half, of which $72.388 billion came from changes in the fair value of convertible notes, derivative liabilities, and SAFEs. The company’s own valuation rose, requiring these financing instruments to be revalued at the new price and recorded as a loss. Excluding these non-cash items, the company was profitable on a non-GAAP basis in the first half, with adjusted net income of $2.671 billion. It also has $112.4 billion in cash and $19.3 billion in short-term investments.
The real good news is on costs: second-quarter operating profit was $974 million, with an 8% margin; a year earlier, the company was still losing money in the same quarter. Compute costs fell from more than twice revenue in the first half of last year to 55%—revenue is growing faster than that fixed bill.
The real risk is the bill still to come: long-term compute purchase commitments total hundreds of billions of dollars—about $161.2 billion for Broadcom TPUs, up to $120.5 billion for SpaceX, at least $114.5 billion for Google, at least $110 billion for Amazon, and at least $44.9 billion for Microsoft, with contracts running as far as 2045. The prospectus itself says future cash flow will remain substantially negative for a long time. The question isn’t “Will it make money?” but “Can it keep raising money?”
The customer base is impressive but concentrated: 11,900 customers pay more than $100,000 a year, including 250 that pay over $10 million, and net revenue retention is 900%. But the top five customers account for about 25% of revenue.
One easily overlooked point: the seven founders control 50.1% of the voting power through Class F shares, and a long-term public-benefit trust can also elect a majority of the board. You buy the stock and take on the risk, but you can’t change the company’s direction. The more than 90 pages of risk disclosures even mention that “AI could pose catastrophic risks.”
In short: this is a prospectus for a company with “explosive growth, improving costs, and a future staked on hundreds of billions of dollars in compute.” A $2 trillion valuation is about 60 times annualized revenue. You’re buying the expectation that “AI will become infrastructure,” not this year’s profits.
1
628
·
--
Bullish
#富兰克林邓普顿申请股息转比特币etf Franklin Templeton filed paperwork with the SEC on October 22 to list two “dividends-to-Bitcoin” ETFs on Nasdaq.
The ETF doesn’t pay its “dividends” to you in cash or use them to buy back shares. Instead, it automatically uses them to buy Bitcoin $BTC .
1. How it works
Franklin Templeton is a long-established asset management giant overseeing about $1.8 trillion. It has filed for two products:
FBEQ: Tracks 500 large U.S. companies, with a 0.09% fee
FIBT: Tracks 100 innovative Nasdaq-listed companies, with a 0.19% fee
Both start with a mix of 95% U.S. stocks and 5% Bitcoin. After that, whenever the stocks pay dividends, the money isn’t distributed as cash or used to buy more shares. Instead, it is automatically used to buy Bitcoin when the market opens on the day after the ex-dividend date. So Bitcoin’s share of the portfolio will gradually grow.
2. Could it turn into a “Bitcoin fund”?
No—there are safeguards. The fund rebalances quarterly, and if Bitcoin exceeds 5% of the portfolio, its allocation is cut back to 4.5%. If it surges past 20% between rebalancings, it is also cut back to 4.5% within two trading days. Put simply, Bitcoin can only ever be a side dish, never the main course.
3. Why it matters
This product isn’t aimed at crypto enthusiasts. It’s designed for conservative investors who “just want to buy U.S. stocks and have no intention of touching crypto” (including retirement account holders). There’s no need to open an exchange account or manage private keys—a little Bitcoin is quietly built into an ordinary ETF. In effect, it wraps Bitcoin in a traditional investment product, marking a step toward mainstream adoption.
4. Keep things in perspective
U.S. stock dividend yields are only around 1% or 2%, so the amount of Bitcoin purchased over a year will be small; the symbolism is more significant than the actual buying pressure. Also, dividends are normally steady cash in hand, but now they’re being converted into highly volatile Bitcoin—turning safe money into risky money. Taxes are more complicated, too: you owe tax on the dividends, but receive Bitcoin rather than cash. And the fund’s Bitcoin exposure may be achieved through futures or other ETFs, so it may not actually hold Bitcoin.
Bottom line: It’s not a new strategy, but a new wrapper—letting Bitcoin slip into ordinary people’s U.S. stock portfolios under the guise of “dividends.”
1
415
·
--
Bullish
$BTC Bulls and bears battle near $80,000:
Galaxy Digital’s Mike Novogratz believes Bitcoin is more likely to rise to $100,000 by year-end than fall to $50,000, but sees $79,000–$80,000 as a key line of defense;
Another analyst warns that a weekly close below $83,000 could signal a false breakout.
Opinions differ widely. These are market predictions, not definitive signals.
$ETH Under pressure near a long-term moving average: Ethereum is around $2,320–$2,350 and, following a recent pullback, is testing support near its 200-day moving average.
Capital flows favor BTC: Reports show Bitcoin’s market share has risen to around 57%, its highest level since November 2022. Spot Bitcoin ETFs saw net inflows of about $305 million last week.
This reflects relatively stronger capital flows into BTC.
Macroeconomic events this week could amplify volatility: Markets are watching the Federal Reserve’s October 27–28 meeting and earnings reports from major tech companies. Interest-rate expectations and risk appetite could affect crypto asset prices.
351
·
--
Bullish
Verified
#市场定价美联储下周加息概率仅10%
Why everyone thinks there won’t be a hike
First, rates were just raised once in September—the first hike since 2023—and now stand at 3.75%–4%. Officials generally want to wait and see more data. Key figures including Vice Chair Williams, Jefferson, and Bowman have all signaled that another hike is still possible, but there’s no rush.
Second, Treasury yields have risen and the dollar has strengthened since September. The market has already tightened financial conditions somewhat on its own, so the Fed doesn’t need to rush in and tighten them further.
Third, this October meeting won’t include economic projections or a dot plot. It’s not the kind of meeting where the Fed makes a major move. The market expects it to be mostly a formality, while setting the tone for December.
The easiest thing to misread
That 10% is not the probability of a rate cut—it’s the probability of a rate hike. The 90% means “no change,” not “a cut is coming.” In fact, the market is still pricing in roughly a 70% chance of a December hike, and all 100 economists surveyed by Reuters expect one hike in December. That’s “holding steady in the near term, but remaining tight further out”—not a policy shift.
And 10% isn’t zero. Just after rates were raised last month, this figure briefly reached 70%; it was still around 17% a week ago, and now it’s down to 10%. That shows how quickly expectations can shift. The Fed under Warsh may be more “hawkish” than the market thinks, and it wouldn’t be surprising if one or two officials dissented in favor of a hike.
What to watch next week
Don’t focus on the interest-rate number—it’s almost certain to stay put. Instead, watch three things: how forceful the statement’s wording is, how many officials dissent, and how Warsh explains this “pause” at the press conference. The real test will be the GDP and PCE inflation data released the day after the decision. Those will be key to determining whether rates go up in December.
7
11
14.8k
·
--
Bullish
#黄金自7月以来首次跌破4000美元 This is a normal pullback in $XAUT gold,
On October 23, spot gold fell below $4,000 per ounce during trading, hitting a low of $3,992.84 for the first time since July 29. New York gold futures were around $4,018, down more than 1%. Silver fell in tandem, dropping below $54.
First, let's be clear: falling below $4,000 does not mean a collapse. The significant drop actually happened on October 22, when gold fell 2.78% in a single day, losing nearly $120. The 0.74% drop on the 23rd was just a continuation. Put in perspective, a 0.7% drop in one day is normal fluctuation for gold. The more noteworthy move was the 2.78% one-day drop on the 22nd.
Why did it fall? Three factors came together.
First, expectations of interest rate hikes heated up again.
Oil prices are rising, and markets are worried that inflation will remain stubborn. The Fed's tightening could extend into the first quarter of next year. Recent comments from FOMC officials have been hawkish, and the dot plot still leaves open the possibility of a rate hike before the end of the year. CME data shows a 92.8% probability that rates will remain unchanged in October and a 74.8% probability of a 25-basis-point hike in December. Gold pays no interest, so when rates rise, the opportunity cost of holding it increases. This is the key factor weighing on gold prices.
Second, liquidity was drained from the market.
Over the past 13 trading days, the Philadelphia Semiconductor Index fell 20% from its peak. Concerns about an AI bubble triggered a broad sell-off in technology stocks. When stocks fall, investors need to meet margin calls. What is the quickest thing to sell? The most liquid assets. Gold was among the first to be sold, and silver also plunged.
Third, this time, safe-haven funds flowed into U.S. Treasuries rather than gold.
The 10-year Treasury yield fell below 5% for the first time in a month, indicating that investors were positioning for a recession rather than buying gold.
The underlying reason for this decline is that bullish positions had become too crowded. With positive news already priced in and the stock market short of cash, some investors chose to exit first.
What should ordinary investors make of this? It depends on the situation. If you're buying jewelry, prices have indeed come down, but gold jewelry includes a markup for craftsmanship, so don't mistake this pullback for a buying opportunity.
For asset allocation, a 0.7% drop in one day isn't enough to base a decision on. Watch whether gold can reclaim the $4,000 level and whether expectations of rate hikes continue to rise.
Keep an eye on three things next: the Fed's policy meeting on October 27–28, whether oil prices continue to rise, and the 10-year Treasury yield.
In a nutshell: in the short term, watch interest rates; in the long term, watch confidence in the financial system.
1
263
·
--
Bullish
This article has racked up 43k views,
Do people all like Bitcoin $BTC , or do they just enjoy looking at beautiful women?
😂
This article has racked up 43k views,
Do people all like Bitcoin $BTC , or do they just enjoy looking at beautiful women?
😂
Do people all like Bitcoin $BTC , or do they just enjoy looking at beautiful women?
😂
阿曾
·
--
Bearish#中国寻求没收61800枚比特币
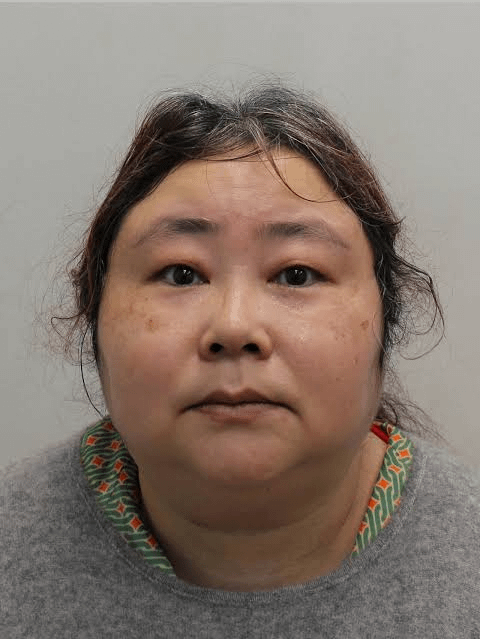
A major illegal fundraising case in Tianjin: the principal offender, Qian Zhimin, fled to the UK with the money and converted it into 61,800 bitcoins $BTC . Prosecutors in China are now applying to confiscate the coins as proceeds of crime. The Tianjin No. 2 Intermediate People’s Court has opened a case and given victims and other relevant parties six months to apply to participate. The coins have been under the control of the British police all along; China’s application for confiscation does not mean it can simply get the coins back.
From April 2014 to August 2017, Qian Zhimin (nicknamed “Huahua”) controlled Tianjin Lantian Gerui Electronic Technology Co., Ltd. and sold wealth-management products nationwide without a financial licence, promising “principal protection and high returns.” In total, she raised 40.378 billion yuan from more than 102,000 investors, causing losses of 19.977 billion yuan. The money was mainly used to repay principal and interest to early investors, keep sham projects running, buy bitcoin, and purchase houses, cars and jewellery.
In July 2017, she fled the country with a computer containing a bitcoin wallet and travelled to the UK under the alias “Yadi Zhang,” using a Saint Kitts passport.
Starting in 2018, London police repeatedly searched her home and safety-deposit boxes, freezing about 61,800 bitcoins under the UK Proceeds of Crime Act 2002—the largest freeze of crypto assets in British history. Wen Jian, who was involved in the same case, was sentenced to six years and eight months in 2024. Qian Zhimin was arrested in April 2024, pleaded guilty in September 2025 and was sentenced to 11 years and eight months in November that year.
On September 28, 2026, the Tianjin No. 2 Intermediate People’s Court accepted an application by the Second Branch of the Tianjin Municipal People’s Procuratorate to “confiscate proceeds of crime.” This is an in-absentia confiscation procedure under Article 298 of the Criminal Procedure Law, specifically designed for cases where “the person has fled and cannot be apprehended after a year on the wanted list.” On October 13, the court issued a public notice, with a six-month notice period.
The list of assets to be confiscated includes more than bitcoin: 61,896.42 BTC, 72,700 BCH, 72,700 BTG, 72,700 BSV, 3.606 million XRP, and 70.08 million DOGE (the Dogecoin has already been liquidated by the British authorities and deposited in an interest-bearing account), as well as £84,366.6 in cash, jewellery and other items.
At current prices, the bitcoin alone is worth about 34.5 billion yuan.
The key question: can these coins actually be returned to the victims?
The coins are in the hands of the UK judicial authorities. At most, the domestic proceedings can determine that “this is criminal proceeds and should be recovered”—but the British may not accept that.
108
·
--
Bearish
Verified
#starknet社区投票支持研究抗量子l1路径
The results of Starknet’s community vote are in: the community supports continuing to explore the option of “leaving Ethereum and becoming an independent, quantum-resistant L1.”
$STRK fell instead of rising, suggesting the market isn’t buying it.
The vote ran for 7 days and received about 3,200 votes. By voting weight, 93.52% were in favor, making it the highest-participation vote in Starknet’s governance history.
StarkWare abstained, leaving the decision up to the community.
But one thing is important to understand: this vote only means “approval to continue researching,” not “approval to actually migrate away from Ethereum $ETH .”
Why consider moving?
Starknet is a Layer 2 network built on Ethereum.
Its own STARK proofs rely on hashes and are quantum-resistant. But two components are controlled by Ethereum: cross-chain bridges use elliptic curves to send messages, and data sent to Ethereum uses KZG commitments. Both could be broken by quantum computers.
Ethereum’s plan is to become fully quantum-resistant only by the end of 2029, while Starknet wants to bring that forward to 2027.
As an L2, Starknet has to follow Ethereum’s pace. If Ethereum doesn’t change, Starknet can’t update the bridge or data components on its own.
So it wants to become an L1 and control the pace of its own upgrades.
The trade-offs are clear, too: right now, Ethereum provides its security, finality, and data availability. After becoming independent, Starknet would need to build its own consensus, maintain its own validators, and solve data availability itself. It would also have to redesign how its bridges connect.
STRK will remain the same token; no new token will be issued.
So this isn’t a sure bet. The upside is speed. The downside is replacing Ethereum’s layer of security with an entire security system of its own. Whether that system can hold up will depend on whether its economic security is strong enough.
Next steps: StarkWare says it will start drafting a white paper this week and publish a public draft in November.
A hard fork and launch as an independent chain would require another binding governance vote. Until then, Starknet remains an L2.
In short: this isn’t a declaration of independence, just permission to begin researching the option.
1
2
689
·
--
Bearish
#中国寻求没收61800枚比特币
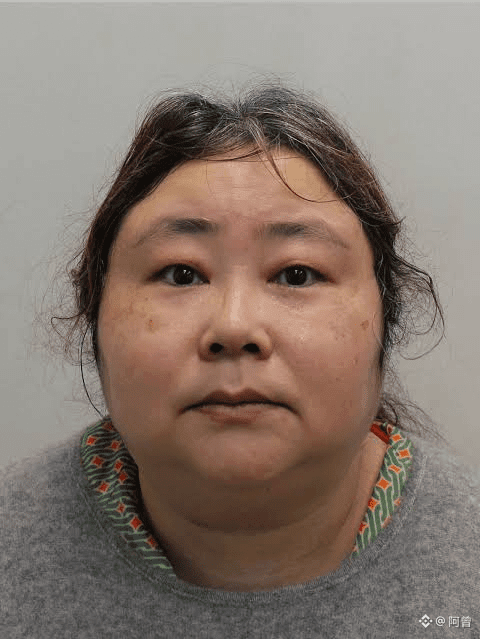
A major illegal fundraising case in Tianjin: the principal offender, Qian Zhimin, fled to the UK with the money and converted it into 61,800 bitcoins $BTC . Prosecutors in China are now applying to confiscate the coins as proceeds of crime. The Tianjin No. 2 Intermediate People’s Court has opened a case and given victims and other relevant parties six months to apply to participate. The coins have been under the control of the British police all along; China’s application for confiscation does not mean it can simply get the coins back.
From April 2014 to August 2017, Qian Zhimin (nicknamed “Huahua”) controlled Tianjin Lantian Gerui Electronic Technology Co., Ltd. and sold wealth-management products nationwide without a financial licence, promising “principal protection and high returns.” In total, she raised 40.378 billion yuan from more than 102,000 investors, causing losses of 19.977 billion yuan. The money was mainly used to repay principal and interest to early investors, keep sham projects running, buy bitcoin, and purchase houses, cars and jewellery.
In July 2017, she fled the country with a computer containing a bitcoin wallet and travelled to the UK under the alias “Yadi Zhang,” using a Saint Kitts passport.
Starting in 2018, London police repeatedly searched her home and safety-deposit boxes, freezing about 61,800 bitcoins under the UK Proceeds of Crime Act 2002—the largest freeze of crypto assets in British history. Wen Jian, who was involved in the same case, was sentenced to six years and eight months in 2024. Qian Zhimin was arrested in April 2024, pleaded guilty in September 2025 and was sentenced to 11 years and eight months in November that year.
On September 28, 2026, the Tianjin No. 2 Intermediate People’s Court accepted an application by the Second Branch of the Tianjin Municipal People’s Procuratorate to “confiscate proceeds of crime.” This is an in-absentia confiscation procedure under Article 298 of the Criminal Procedure Law, specifically designed for cases where “the person has fled and cannot be apprehended after a year on the wanted list.” On October 13, the court issued a public notice, with a six-month notice period.
The list of assets to be confiscated includes more than bitcoin: 61,896.42 BTC, 72,700 BCH, 72,700 BTG, 72,700 BSV, 3.606 million XRP, and 70.08 million DOGE (the Dogecoin has already been liquidated by the British authorities and deposited in an interest-bearing account), as well as £84,366.6 in cash, jewellery and other items.
At current prices, the bitcoin alone is worth about 34.5 billion yuan.
The key question: can these coins actually be returned to the victims?
The coins are in the hands of the UK judicial authorities. At most, the domestic proceedings can determine that “this is criminal proceeds and should be recovered”—but the British may not accept that.
43
2
35
67.6k
·
--
Bullish
Verified
#zcash开发者确认11月nu7升级 What is the main change this time? $ZEC Block times are being reduced from 75 seconds to 25 seconds, doubling the speed. The corresponding ZIP is 218.
For ordinary users, the most noticeable change is this: exchanges typically wait for 3 confirmations before crediting a deposit. Previously, that took nearly 4 minutes; afterward, about 75 seconds will be enough. 60% of transaction fees will be removed from the market (the NSM mechanism).
Of the fees in each block, 60% will be temporarily removed from circulation, and miners will receive the remaining 40%. The removed fees will first be recorded in a publicly verifiable balance ledger, then gradually returned to miners starting in February 2031.
The key point: no extra coins will be minted, the total supply cap will remain unchanged, and the halving schedule will not change. In the September holder vote, 98.9% supported keeping the halving, 96.6% supported starting the returns in February 2031, and 99.9% supported 25-second block times.
Retiring the oldest Sprout privacy pool.
NU7 will disable the v4 transaction format, and spending coins in Sprout requires a v4 transaction. So any ZEC still in Sprout at the moment of the upgrade will become permanently unspendable.
About 22,309 ZEC currently remain there, around 0.13% of the circulating supply.
This is the only time-sensitive risk warning.
Who will be affected?
Ordinary holders and wallet users: basically, no action is needed. The official statement says this upgrade does not introduce a new transaction format, so wallets will not be significantly affected.
There is just one exception: if your coins are in an old Sprout address, you must move them out before November.
Full nodes, block explorers, and indexers: an upgrade is required.
The Zcash Foundation has moved up the end-of-support date for older versions of Zebra to around November 2, specifically to encourage everyone to upgrade promptly.
People running nodes need to complete the update before November. Miners and exchanges need to adapt to the new 25-second cadence.
What does this mean?
Zcash has long been known as “highly private, but somewhat slow to use.”
NU7 primarily addresses two things:
Transfer speeds need to keep up with everyday payments; token economics will incorporate a degree of deflationary design, without changing the halving narrative.
So the market sees it as a signal that “privacy coins are re-entering the competition on usability.”
A positive catalyst: $ZEC is bullish
1
2.8k
·
--
Bullish
#genius法案预计2027年1月18日生效 The United States has passed a law regulating “dollars on-chain” (stablecoins such as $USDT and $USDC ). Starting January 18, 2027, only licensed institutions will be allowed to issue them. They must hold a real dollar in reserve for every coin, and they cannot pay interest.
This isn’t a ban; it’s a formal framework that licenses stablecoin issuers.
In the past, stablecoins were like vouchers anyone on the street could print, with “Redeemable for $1” written on them. But whether there was any money behind the counter—and where it was held—was entirely up to the issuer to say.
Now the United States says: from now on, you need a license to issue these vouchers. You must back them with cash or short-term Treasury securities, publish your books every month, and have the boss sign off. And you can’t say, “Hold my voucher and I’ll pay you interest,” because once you pay interest, it’s no longer a payment instrument—it’s a deposit. And taking deposits is the business of banks.
The path of “earning interest by holding stablecoins” is being squeezed. Note the distinction: the law bans issuers from paying interest; it doesn’t ban you from lending on-chain to earn interest.
But from now on, it will become increasingly difficult to promote “stablecoin yield products,” because the line between them and “taking deposits without a license” is getting thinner.
Stablecoins will increasingly resemble “payment instruments” rather than “investment products.”
This is good for the industry—it separates what stablecoins are best suited for (transfers, settlement, and cross-border payments) from what is most likely to go wrong (using reserves to earn interest-rate spreads).
2
7.3k
·
--
Bullish
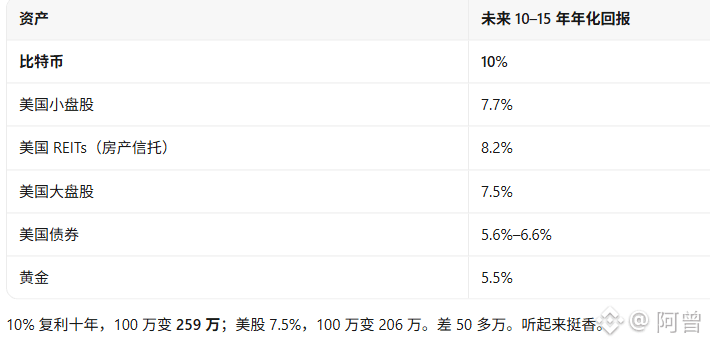
#摩根大通预测比特币十年领跑 JPMorgan says Bitcoin $BTC could earn an average of 10% a year over the next decade, more than U.S. stocks (7.5%) and gold (5.5%).
But it also says: this is only a “forecast,” not “a recommendation to buy.”
There’s a catch behind that 10% that many people miss,
The report also gives two other figures: an arithmetic average return of 20.9% and annualized volatility of 55%.
If you look only at the “average annual price change,” Bitcoin comes in at 20.9%. But what you actually get to keep is only 10%,
If it falls by half, it has to double just to break even. That’s the “volatility tax,” and it’s hidden. Bitcoin’s 55% volatility is three times that of U.S. stocks (18%) and more than three times that of gold (17%). So its “average return” looks the highest, but the “return you actually pocket” is cut in half.
In this report, Bitcoin made it into the “return forecasts” table, but not the “asset allocation model.”
In other words, JPMorgan is willing to tell you “how much this thing might earn,” but not “how much you should buy.”
Why? The report itself gives three reasons:
Its volatility is too high; its correlation with other assets is unstable (0.33 with U.S. stocks and just 0.10 with gold, and it can change at any time); it has no cash flow, and its fundamentals depend on “adoption, regulation, and liquidity,” not technology.
So it characterizes Bitcoin as “a speculative asset, as well as a hedge against monetary easing”—not “digital gold,” and not “a tool for diversifying risk.”
That distinction matters. A forecast is “I think it might go up”; allocation is “I’m using clients’ money to buy it.”
You don’t have to take responsibility for the former; you do for the latter.
JPMorgan only did the former.
124
·
--
Verified
#瑞士批准首只比特币etf : Switzerland’s Financial Market Supervisory Authority (FINMA) has approved the country’s first truly retail-focused Bitcoin $BTC spot ETF
Simply put, an ETF is a fund that can be bought and sold on an exchange just like a stock. When you buy a share, you indirectly own a portion of what the fund holds.
This approval is for a spot Bitcoin ETF: the fund uses its money to buy actual Bitcoin (not futures or derivatives), and its price tracks Bitcoin’s price. Ordinary investors can buy and sell it through a regular brokerage account, without having to manage a wallet or private keys themselves.
Switzerland has had Bitcoin-related products before, but most were:
ETPs (exchange-traded products): more like bonds, with the issuer’s own credit risk. A crypto fund approved in 2021: available only to professional/qualified investors, and invested in a basket of coins rather than Bitcoin alone.
This time is different: it is a retail fund formally approved under Swiss investment fund law (so ordinary people can buy it), with assets held separately and ring-fenced from the issuer, providing more comprehensive regulatory protection. FINMA classifies it as an “Other Alternative Investment Fund” and explicitly labels it as involving “special risks.”
Because the fund holds almost exclusively one asset, Bitcoin, the regulator has exceptionally allowed it not to follow the usual “diversification” rules (which generally require funds to invest in a range of assets to spread risk). The reasoning is that Bitcoin has a long trading history and high trading volumes, and is much more established than other cryptocurrencies.
The issuer is BIT Asset Management (a Swiss subsidiary of the BIT Group). The product is called Bitcoin Fund ETF, has the ticker BBIT, and is expected to list on the SIX Swiss Exchange in November. The issuer says it is currently Europe’s only spot Bitcoin ETF (because the EU has stricter diversification rules, and many markets have not yet fully opened up).
For ordinary investors, this adds a regulated, legitimate way to gain indirect exposure to Bitcoin—convenient and relatively safer (with custody requirements, risk disclosures, suitability checks for sales, and so on).
But FINMA has repeatedly stressed that Bitcoin itself remains high-risk and extremely volatile. Investing through this ETF could also result in the loss of a substantial portion of your principal; it is not a capital-protected investment. Be sure to read the risk disclosures carefully before investing.
6
8
1.8k
·
--
Hahaha, let's not compete for the top spot on the loss leaderboard, shall we?
Hahaha, let's not compete for the top spot on the loss leaderboard, shall we?

Yi He
·
--
I should be at the top of the portfolio loss leaderboard for the past 30 days, so this badge system needs another look 🙃
92
·
--
#strategy增持267枚比特币 #BitMine增持12535枚ETH These two news stories should be read together.
On the surface, it looks like “the two companies bought again.” But lay out the numbers and the real signal is that “they’re buying less and less”—shifting from an offensive stance to a maintenance stance.
What these two companies were doing a couple of years ago was like borrowing money to buy a house: prices kept rising, and the more they borrowed, the more they made—so the more they dared to borrow.
Now prices are flat, and interest rates are still high. What’s the smart move? Pay off the credit card first.
Strategy bought back $193 million worth of preferred shares—that’s like paying off the credit card, since those shares come with fixed annual dividends, a hard expense. It’s making a token purchase of 267 $BTC (for the ritual of saying, “I’m still buying”) while using real money to lower its fixed costs.
BitMine, meanwhile, is a landlord: the house ($ETH ) has fallen in value, but the rent (staking rewards) is still coming in—$300 million a year. Its strategy isn’t to wait for the house price to rise; it’s to collect rent. The problem is that the house itself is losing value too fast for the rent to make up the difference.
267 coins are a “gesture,” not a “decision.”
Adding 267 coins to a holding of 840,000 is like having $1 million in your account and depositing another $300 today. It serves just one purpose: keeping the weekly Monday announcements coming. What these companies fear most isn’t a drop in coin prices—it’s “the story ending.”
BitMine is close to hitting the ceiling.
Its self-imposed goal is to “own 5% of the ETH supply”; it’s now at 4.9%. What happens when it gets there? There’s no new story. In essence, it’s no longer a company but an ETH staking pool with a stock attached: the value of its assets moves entirely with ETH, while its yield is a staking rate of around 2.5%. With ETH down from 4,900 to 2,365, the pool’s net asset value is there for all to see.
Don’t read these two stories as “institutions buying the dip.”
They’re “institutions keeping up appearances.”
In short:
BitMine is collecting rent, Strategy is paying down debt, and both are hanging on—just in different ways.
1
1
575
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
WithdrawalsBack: 15 networks live
413 views
24 Discussing
Binance News Update | Binance Reopens Withdrawals for BTC, ETH, USDT and More Across 15 Networks, Meeting Its Sunday Target
Binance News
·23 Likes
·9.3k views
BinanceUpdatesProofofReservesAddresses
33,478 views
778 Discussing
BinanceToResumePhaseOneOfWithdrawals
65,817 views
1,029 Discussing