

Ether Guru 1
146 Posts
Ether Guru 1
Report
Block User
Where experience meets discipline. Crypto isn’t luck — it’s mindset 💭
0 Following
6 Followers
26 Liked
Posts
·
--
$BTC SHE EARNS $58,000. BUT WOULD QUITTING HER JOB ACTUALLY SAVE MONEY?
Her husband’s promotion changed the conversation at home.
He now earns around $186,000 annually, while she brings in $58,000. With a three-year-old daughter and daycare bills approaching $2,000 a month, he suggested she consider becoming a stay-at-home mom.
The idea sounds reasonable until you look beyond the monthly bills.
Daycare alone costs about $24,000 annually. Add commuting, work lunches, and other job expenses, and a meaningful portion of her paycheck may disappear before it reaches the family budget.
But there’s another side to this calculation.
If she leaves her job, the household loses more than a salary. It may also lose employer retirement contributions, opportunities for raises, and years of career growth.
And there’s a risk families sometimes underestimate: returning to work later might mean starting at a lower salary or spending months searching for the right position.
Meanwhile, relying on one income creates a different kind of financial exposure. If that paycheck disappears, the family has no second salary to fall back on.
Before deciding, they could calculate her actual take-home pay after work-related expenses, compare both household budgets, and explore flexible work or part-time childcare arrangements.
Because the question isn't simply whether daycare is expensive.
It's whether the family's long-term financial position would change after accounting for everything her job provides.
A paycheck has value beyond its monthly deposit.
54
·
--
$BTC 3 BITCOIN COULD COST HIM MORE THAN MONEY.
A friend already owns 3+ BTC bought below $30,000, roughly $2 million in income-producing real estate with equity, and more than $400,000 in cash.
Now his wife wants him to buy another 3 BTC before Bitcoin climbs back above $100,000.
But he has three teenagers approaching college age.
And that changes the calculation.
Buying 3 BTC at $85,000 each would require about $255,000 before fees.
From $400,000 in cash, that leaves just $145,000.
If tuition, property repairs, vacancies or another unexpected expense arrives, he may have to sell assets at an inconvenient time.
His real estate may be valuable, but equity isn't the same as cash. Accessing it can take time, cost money and depend on financing conditions.
And Bitcoin could rise above $100,000—or fall sharply before it gets there.
Nobody knows which happens first.
The decision isn't simply whether 3 more BTC would be a good investment.
It's whether the potential upside justifies reducing the family's readily available financial cushion while major education expenses are approaching.
He could estimate the next several years of college costs, property expenses and household spending first, then determine how much cash is genuinely available for investing.
An opportunity matters less if it weakens your financial flexibility.
64
·
--
$BTC FOUR YEARS CAN CHANGE THE BITCOIN MATH FAST.
On September 27, 2022, Bitcoin was around $18,802.
Four years later, the reference price is about $84,625.
That works out to roughly a 46% annualized growth rate.
Now comes the interesting part.
If Bitcoin somehow repeated that exact 46% CAGR for another four years, the math would put BTC near $381,000 by September 2030.
Rounded up, that's the often-mentioned $385K scenario.
But there’s a huge difference between calculating a return and predicting one.
Bitcoin did not rise 46% every year.
Some periods were dramatically stronger, while others produced deep drawdowns.
So the $385K figure isn't a forecast.
It's simply what happens when you extend the previous four-year annualized growth rate forward for another four years.
That distinction matters whenever historical performance gets turned into future price targets.
Past compounding creates scenarios, not promises.
4
·
--
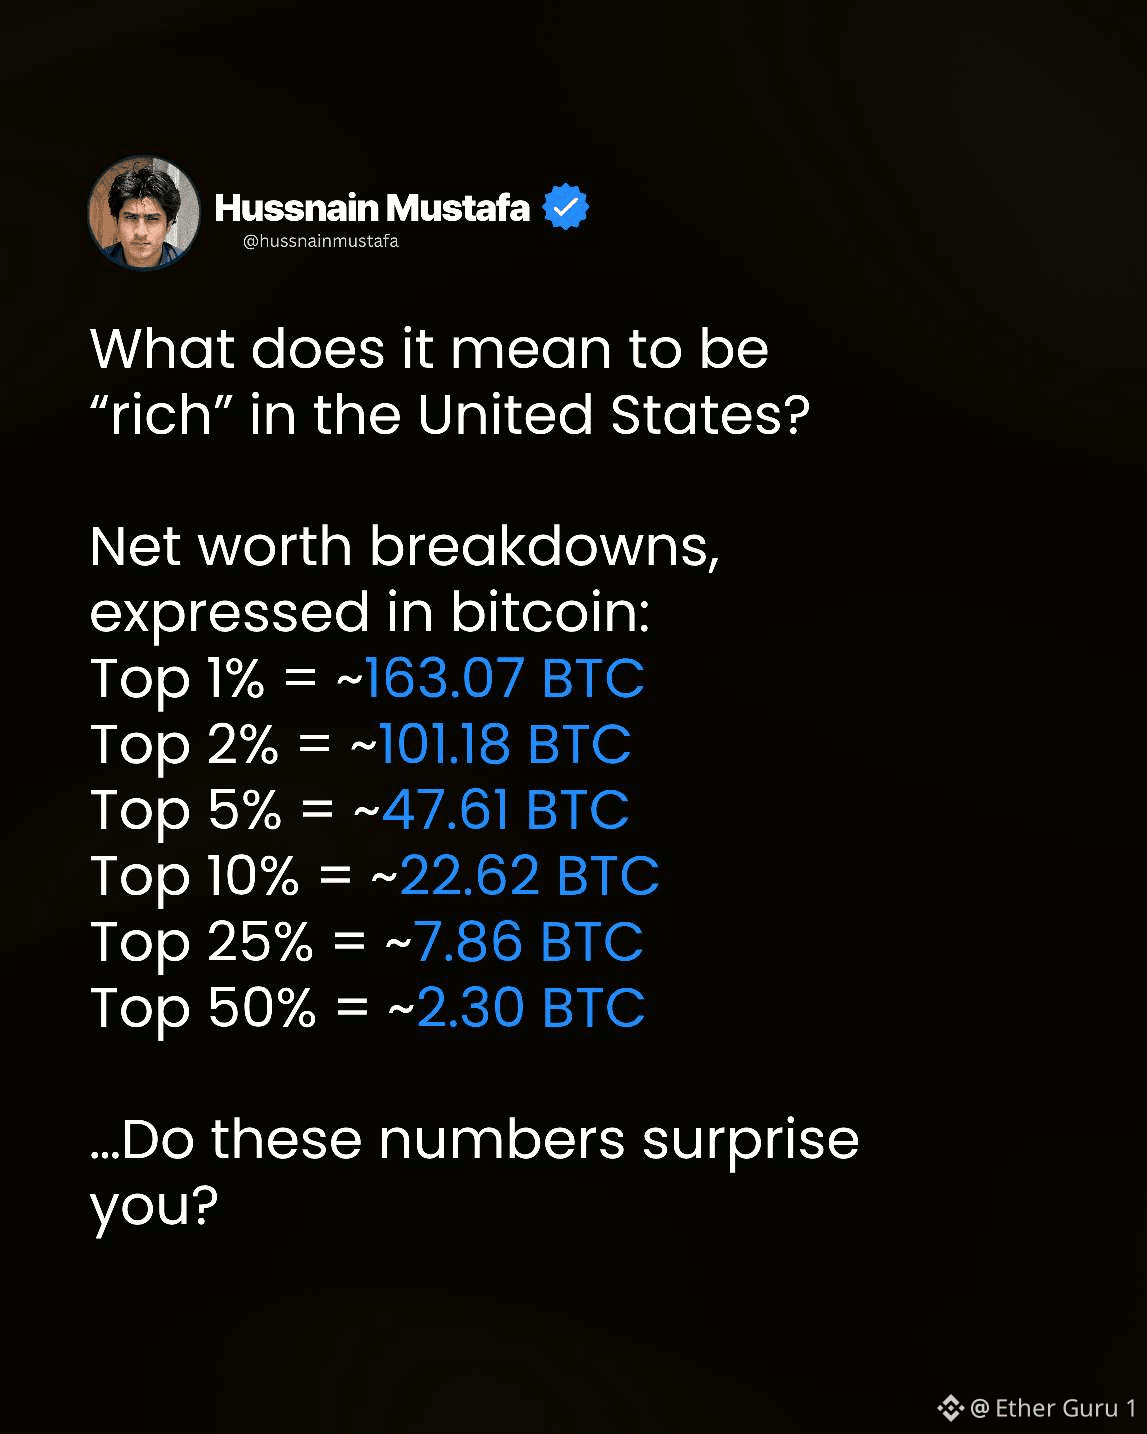
$BTC WHAT IF AMERICAN WEALTH WERE MEASURED IN BTC?
Using a fixed Bitcoin price can make the numbers look surprisingly simple.
But there’s an important catch:
A net-worth threshold measured in BTC changes every time Bitcoin’s dollar price changes.
If a household has $1 million in net worth, that represents about 11.8 BTC at an $85,000 Bitcoin price.
At $170,000, the same $1 million would equal only about 5.9 BTC.
The household didn't become poorer.
The BTC measurement changed.
That’s why converting U.S. wealth percentiles into Bitcoin is more of a thought experiment than a permanent definition of being rich.
It also shows something important about Bitcoin:
As the BTC price rises, the amount of Bitcoin needed to represent the same dollar wealth falls.
Bitcoin can change the measuring stick without changing wealth.
66
·
--
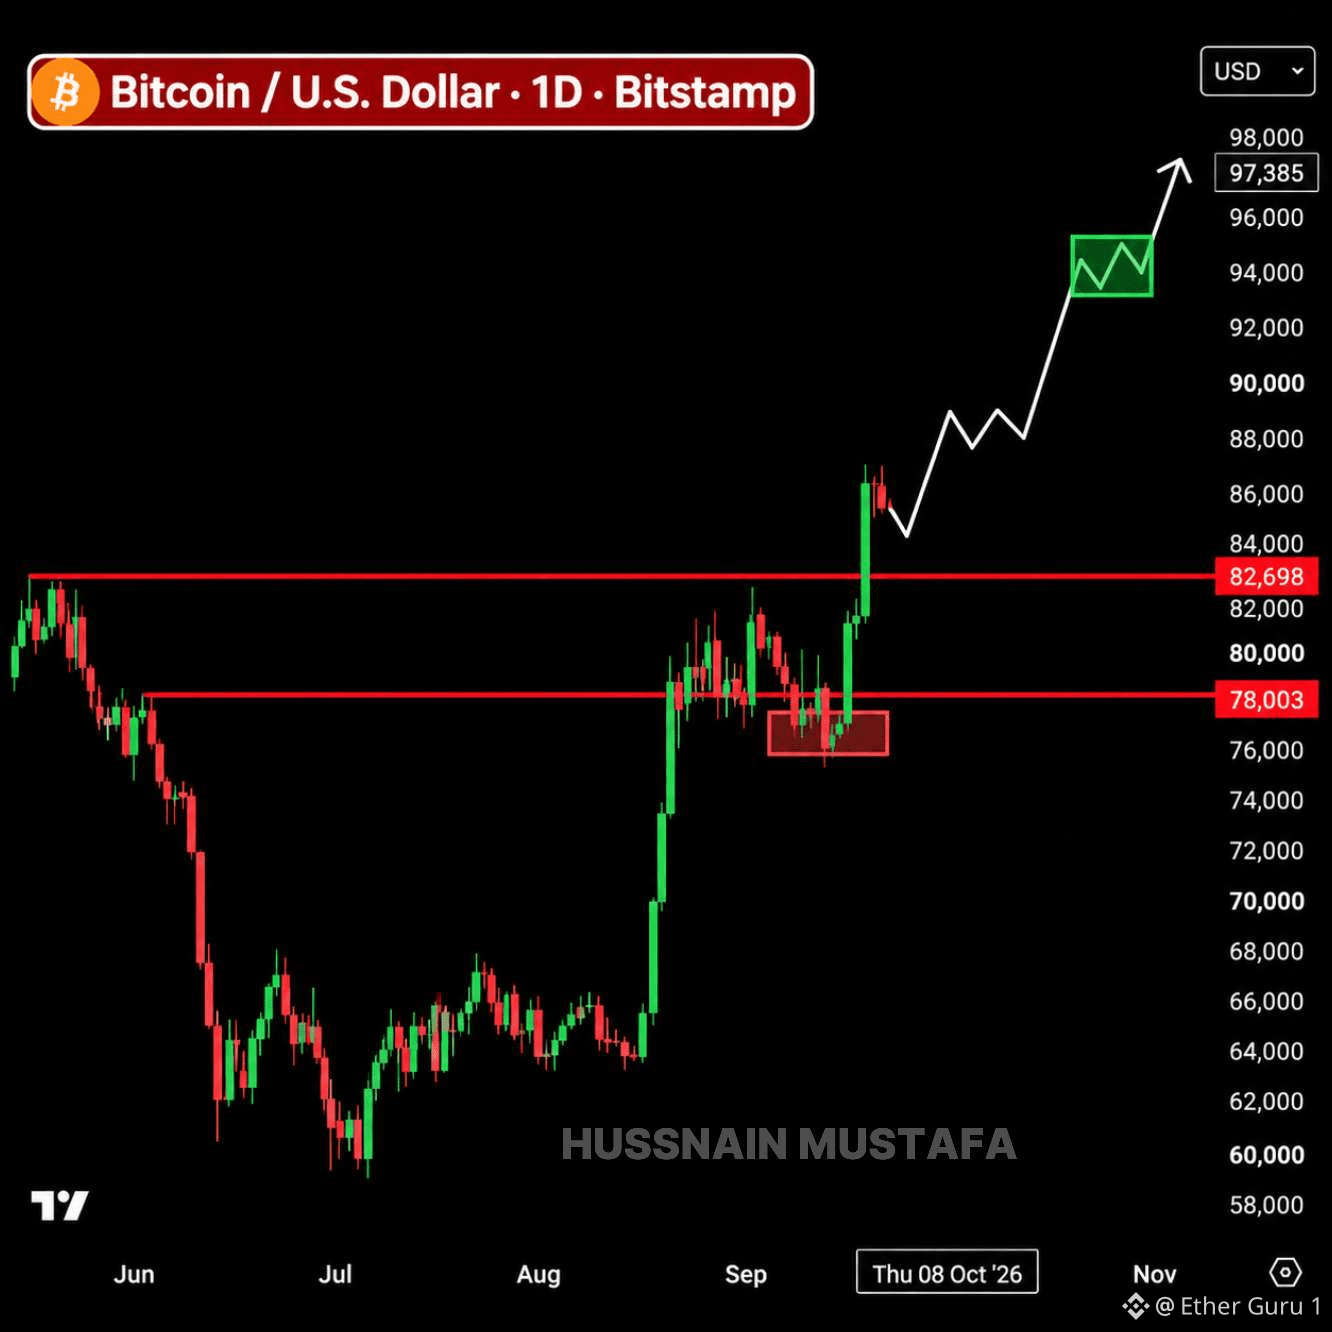
$BTC BITCOIN JUST TURNED TWO OLD RESISTANCE ZONES INTO SUPPORT.
$78K was reclaimed.
Then $82.7K gave way.
Now BTC is trading around $84K, with the market watching whether buyers can keep defending the levels that were previously holding price back.
That distinction matters.
A breakout is one thing.
Holding above it after the excitement fades is another.
If $82.7K continues acting as support, $90K becomes a much more obvious level for traders to watch.
But if that level is lost again, the whole setup starts looking different.
For now, the interesting part isn't the $90K number itself.
It's whether Bitcoin can keep building higher lows underneath it.
The next move depends on what holds.
60
·
--
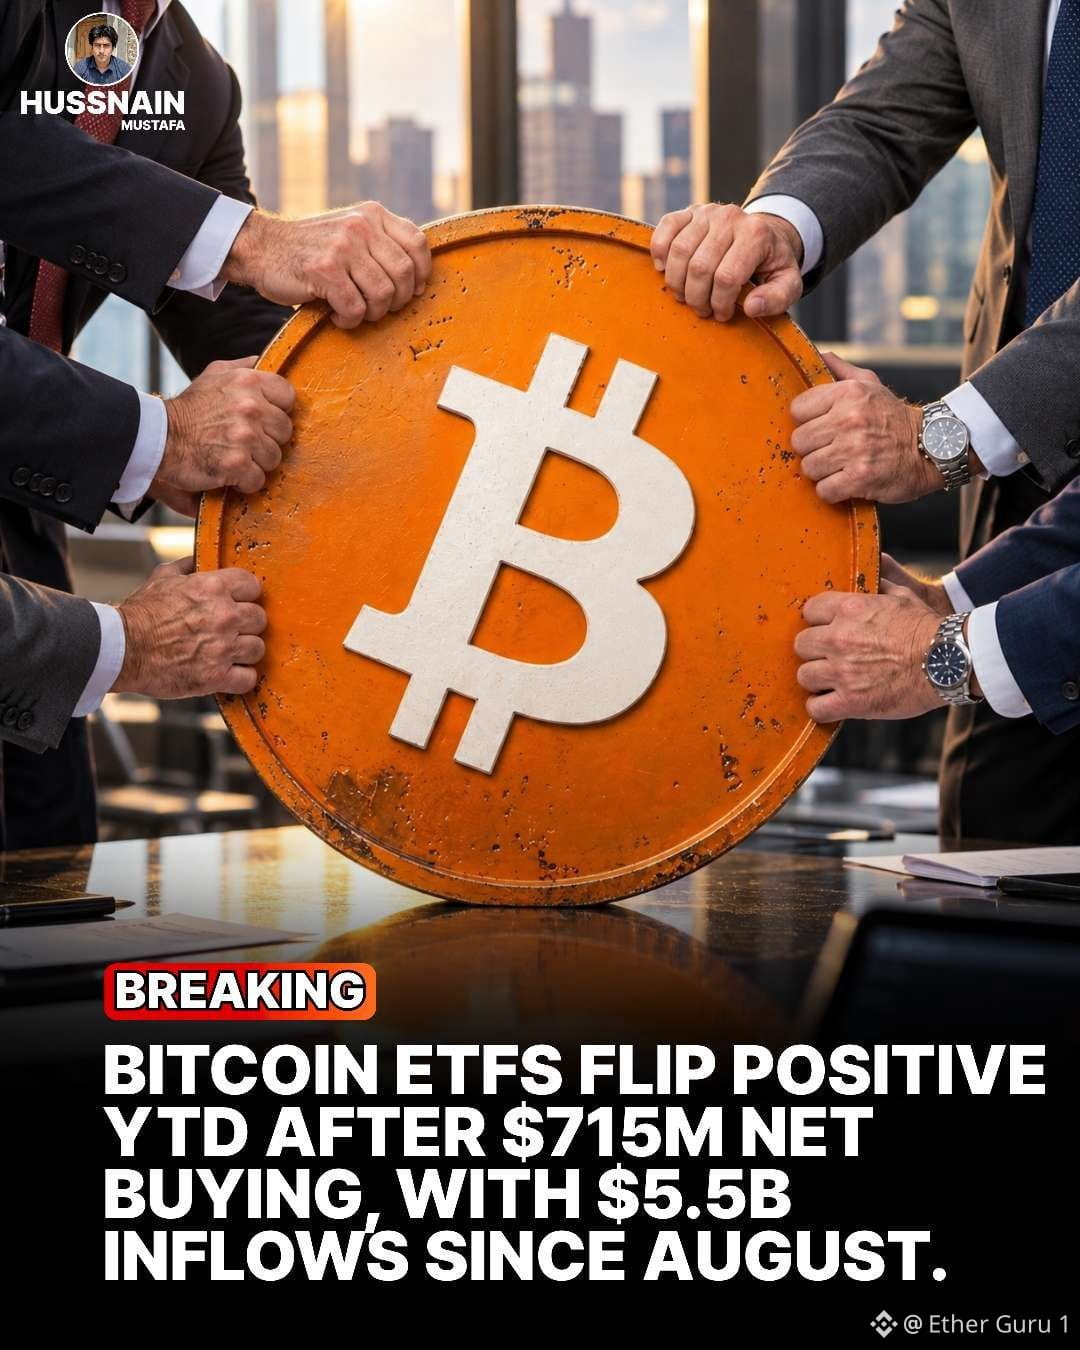
$BTC BITCOIN ETF BUYING JUST GOT SERIOUS AGAIN.
U.S. spot Bitcoin ETFs pulled in roughly $715 million on Tuesday.
That was the fourth straight positive session, bringing the four-day run to about $2.31 billion.
BlackRock's IBIT alone took in roughly $350 million.
Fidelity added another $257 million.
That's important because ETF flows represent actual demand for spot Bitcoin, not just people talking bullish on social media.
After weeks of choppy flows, billions returning in a few sessions is a noticeable change in the tape.
It doesn't guarantee the next move higher.
But if this demand keeps showing up while Bitcoin holds its recent gains, the market is getting a very different signal from the one we saw during the recent selling.
Capital is coming back into Bitcoin.
70
·
--
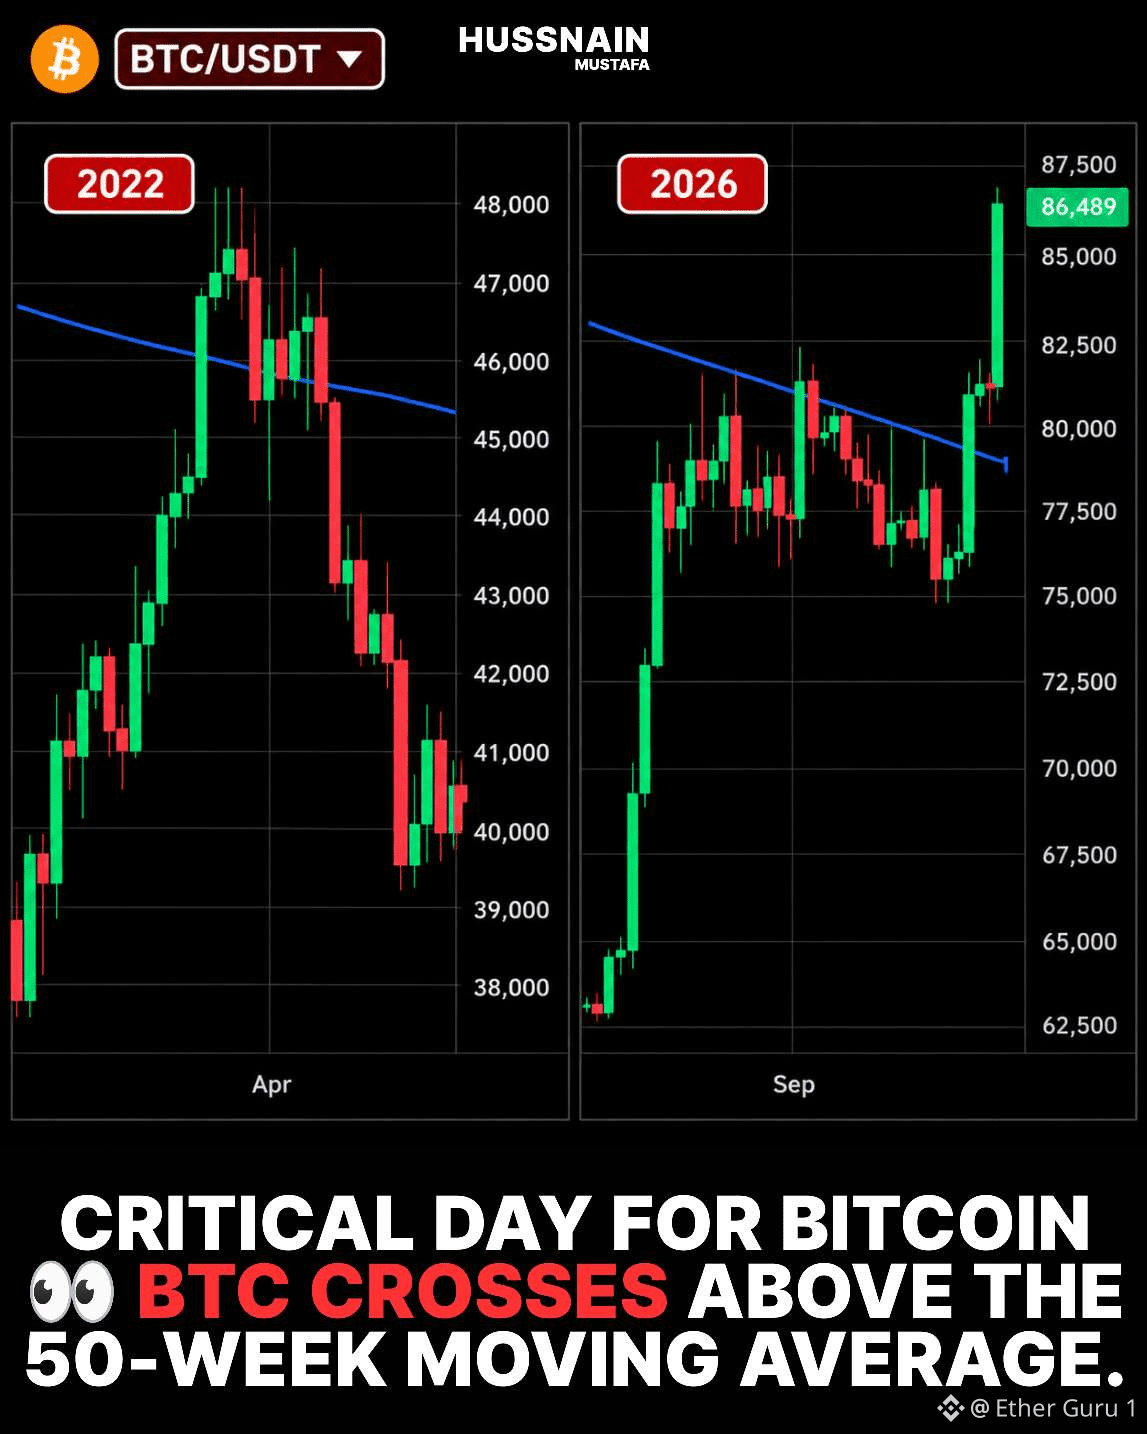
$BTC BITCOIN JUST RECLAIMED A LEVEL THAT MATTERS.
BTC closed around $81,159.
Its 50-week moving average was near $78,788.
That puts Bitcoin roughly 3% above the line.
But history makes this setup interesting.
Galaxy Research found 13 previous weekly reclaims.
Eleven were not followed by a new cycle low.
Two were different.
December 2021 and March 2022 both reclaimed the average before Bitcoin eventually fell much further.
So one successful close is not a guaranteed trend reversal.
The important question now is whether BTC can stay above the moving average.
That is where this signal becomes more useful.
A failed reclaim would turn the same level back into resistance.
A sustained move above it would strengthen the case that the market structure has changed.
Technical indicators work best as evidence, not certainty.
And right now, Bitcoin is sitting directly on one of its most watched long-term trend lines.
The next weekly closes may matter more than today’s breakout.
70
·
--
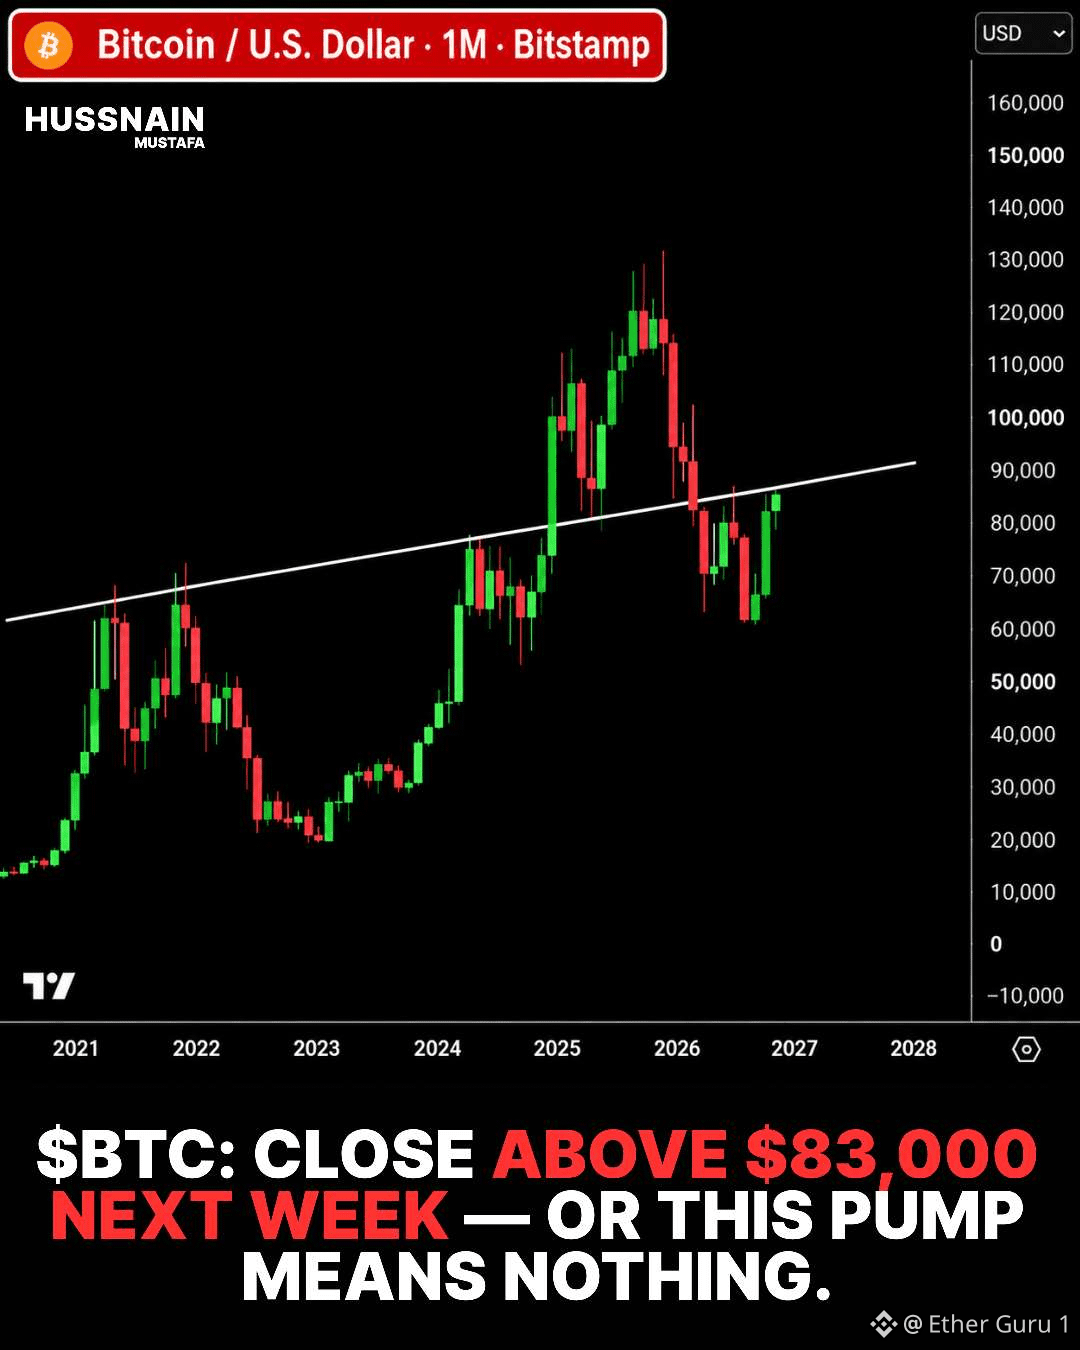
$BTC Bitcoin’s $83K Weekly Test
A weekly close above $83,000 would put Bitcoin at a new short-term milestone.
The level matters because weekly closes show where buyers and sellers finished the period.
An intraday move above $83K tells a different story.
A sustained close would provide stronger evidence of acceptance above that price.
Bitcoin’s recent rebound has already pushed it away from its September lows.
But short-term momentum can disappear quickly in crypto.
Volume, ETF flows, and liquidity can all influence the follow-through.
One closing price cannot confirm an entire market cycle.
The next weekly candle will reveal whether $83K becomes support.
Or whether this rally was simply another temporary move.
63
·
--
$BTC THERE IS NO MAGIC BITCOIN NUMBER FOR RETIREMENT.
One viral chart says 0.05 BTC at 16.
Then 0.25 BTC by your 30s.
And 5 BTC after age 65.
But those targets are not a financial rule.
Bitcoin has a fixed maximum supply of 21 million coins.
At 5 BTC per person, only about 4.2 million people could theoretically hold that amount.
That ignores lost coins, institutions, governments, exchanges, and uneven ownership.
The bigger lesson is actually about accumulation.
Someone holding 0.10 BTC today owns a different share of the network than someone starting ten years from now.
But Bitcoin’s price can also fall dramatically.
A target measured only in BTC ignores income, debt, emergency savings, taxes, retirement accounts, and overall net worth.
For one person, 0.25 BTC could be a small speculative allocation.
For another, it could represent an outsized concentration of their wealth.
So “winning the game” cannot be defined by one Bitcoin number.
The useful question is how much risk an individual can responsibly carry.
Bitcoin ownership matters, but financial context matters more.
71
·
--
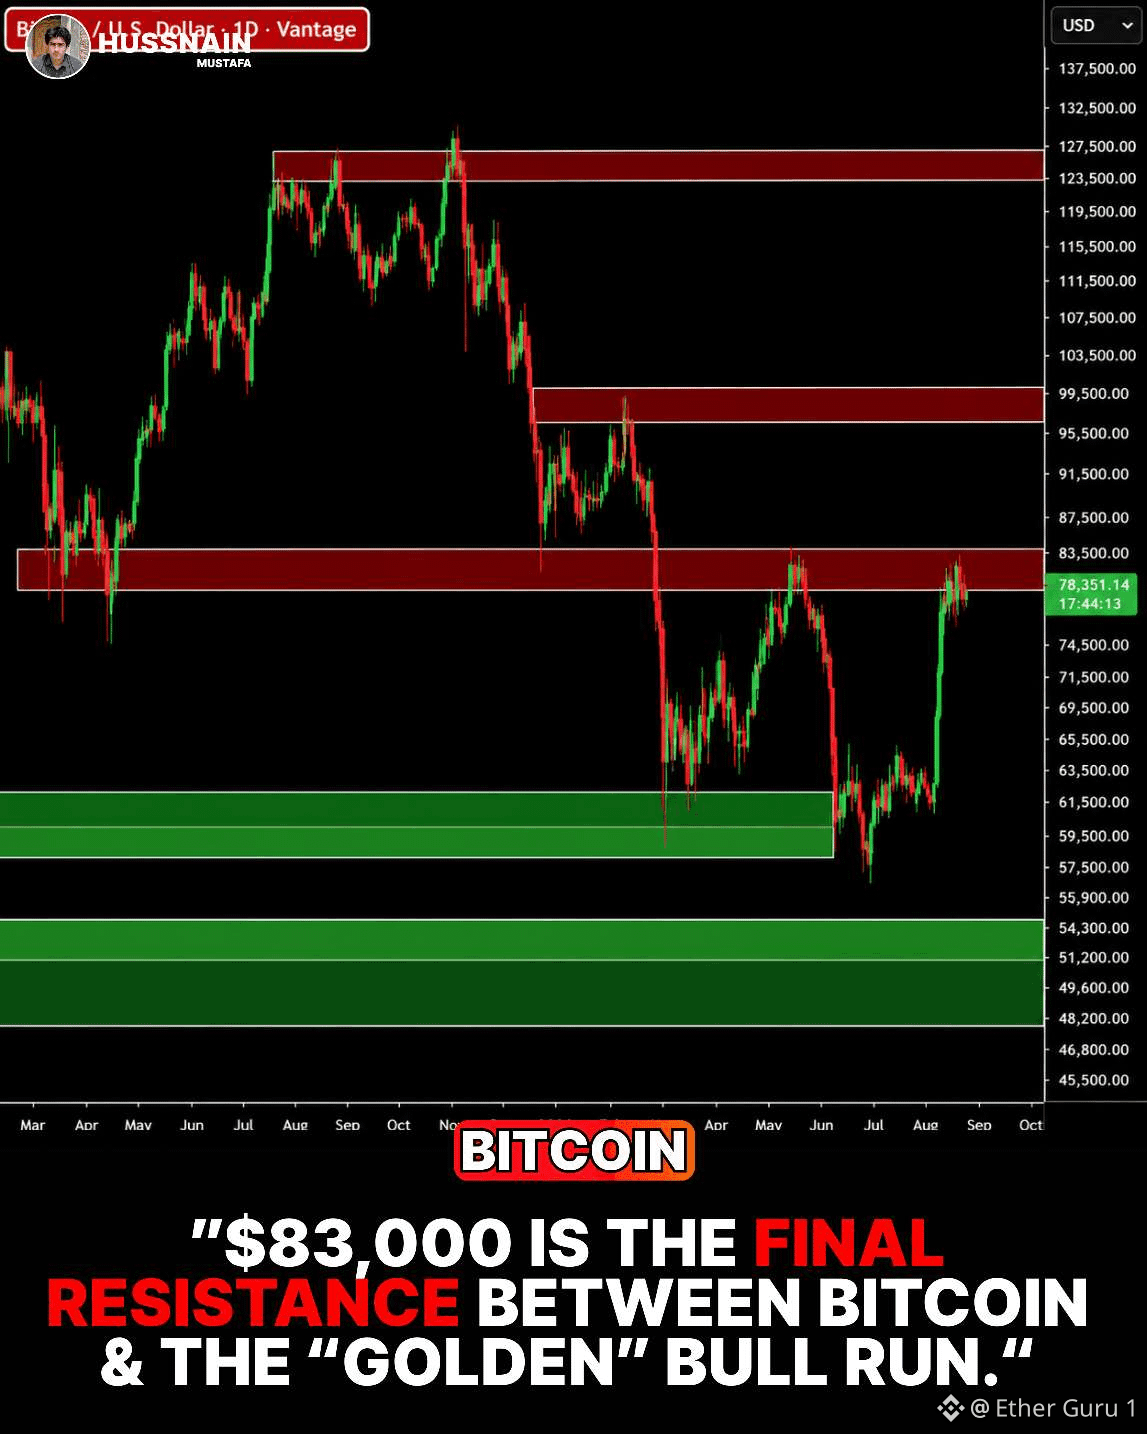
$BTC $83,000 is where the chart gets serious.
That zone lines up with Bitcoin’s May high and sits inside a broader $83K–$86K supply area.
The technical backdrop has improved too.
Bitcoin just printed its first 50-day over 200-day golden cross since May 2025.
But the crossover alone does not confirm a lasting trend reversal.
A decisive break above $83K would remove a major technical barrier.
Until then, sellers still control the most important overhead zone.
$83K remains the gate.
52
·
--
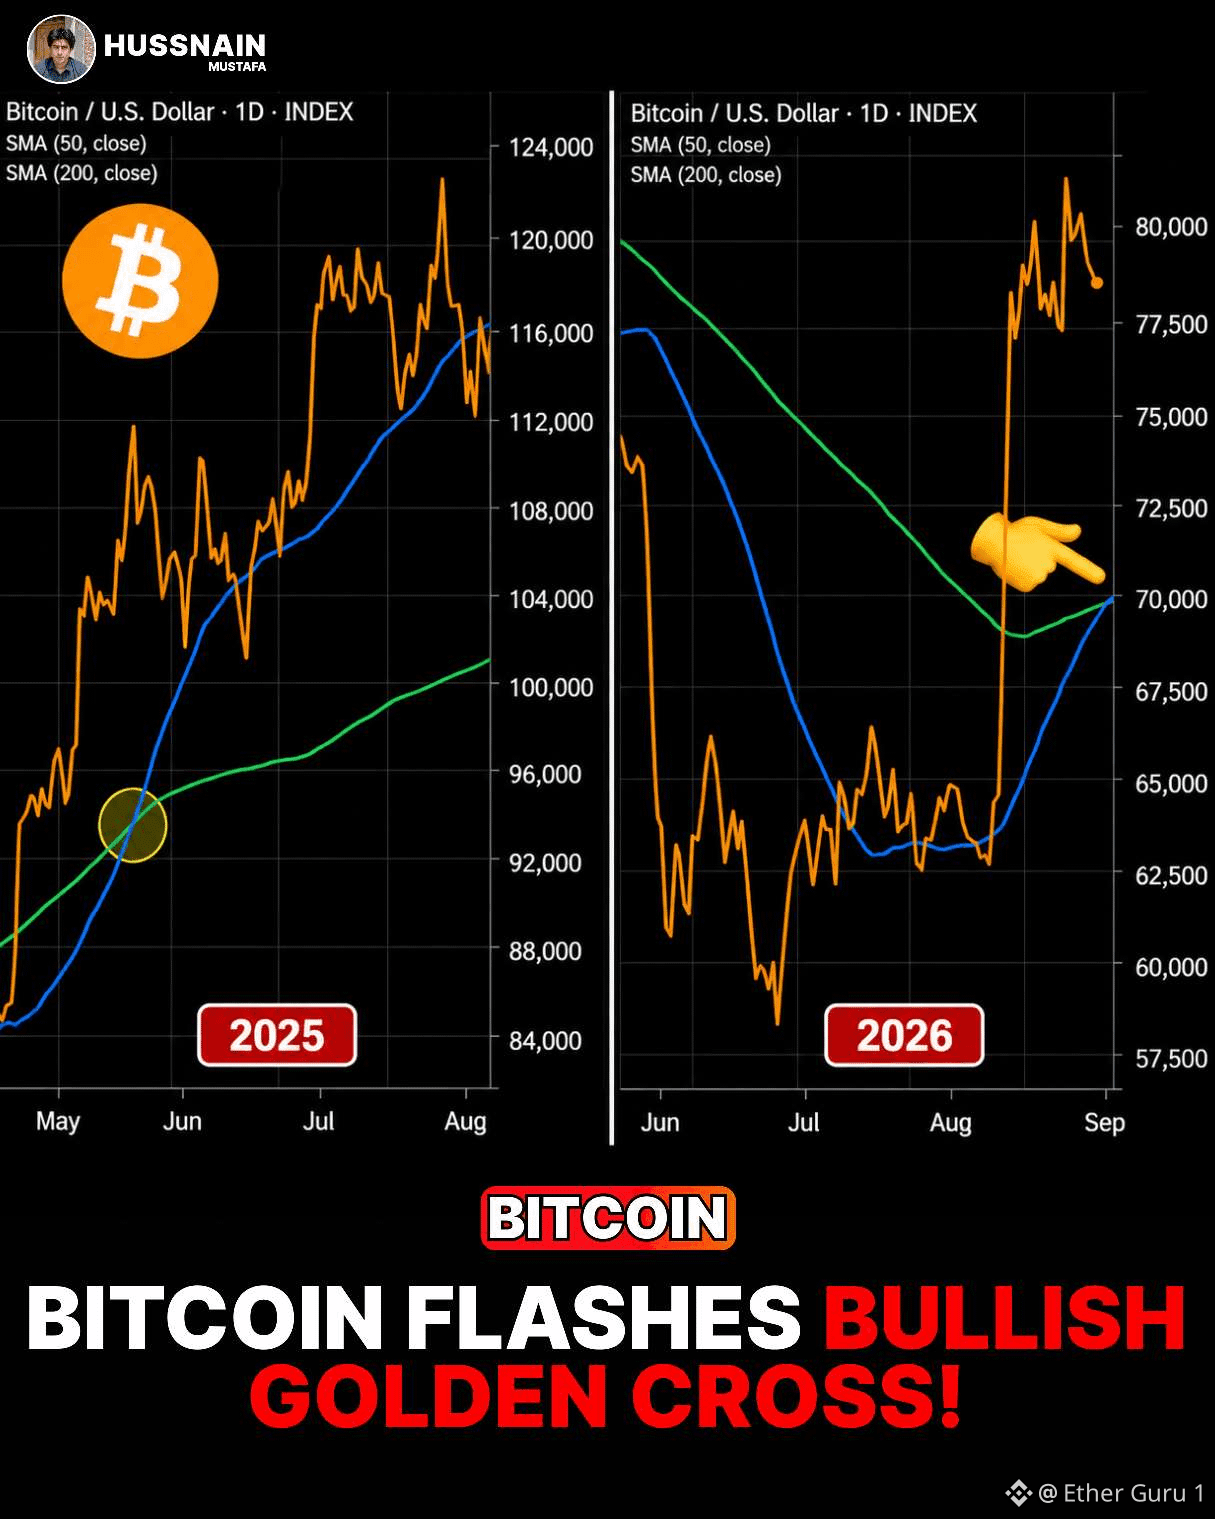
$BTC Bitcoin is flashing a golden-cross setup again.
The same technical pattern appeared in May 2025 before BTC eventually climbed to its $126,200 all-time high.
This time, the chart is again drawing attention to the relationship between Bitcoin’s major moving averages.
But history is a reference, not a promise.
Golden crosses can confirm improving momentum, yet they do not guarantee another straight-line rally. Recent technical analysis still points to major resistance levels that BTC would need to overcome.
The signal is back.
Now price must respond
73
·
--
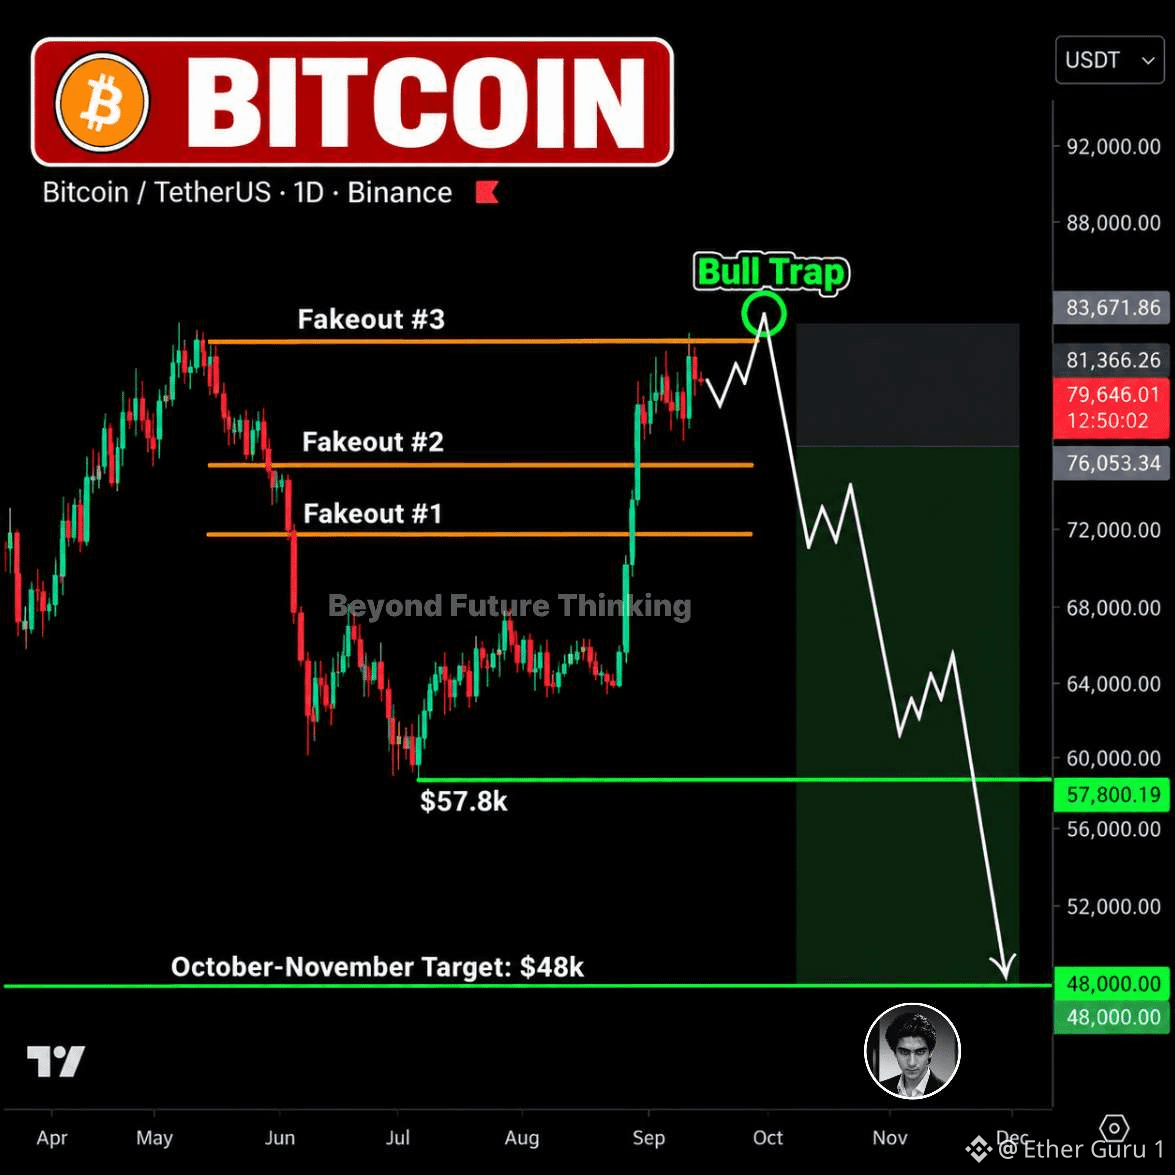
$BTC The $83K Area Could Decide Bitcoin’s Next Major Move
Bitcoin recently pushed back toward $82K, pulling bullish sentiment back into the market.
But there is still a major liquidity zone sitting around $83K.
That means price could potentially make one more move higher before the real direction becomes clear.
My current roadmap remains:
$79K → $83K → $68K
If the market loses momentum after that bounce, the next downside levels I’m watching are:
$57.8K → $49K
The reason I’m not treating the latest bounce as a confirmed recovery is simple.
A sharp move upward can pull new buyers back into the market, especially after weeks of fear and heavy selling.
That liquidity near $83K could become an important area for the next major reaction.
If Bitcoin gets rejected there, the downside structure could quickly come back into focus.
I’ve been watching these major levels closely throughout the cycle, including the moves from $98K → $60K and $83K → $57K.
That doesn’t make every future call guaranteed.
But price action, liquidity and key levels still matter more than emotion.
The next few moves could reveal whether this was a genuine recovery — or simply another trap before a deeper flush.
$83K is the line.
134
·
--
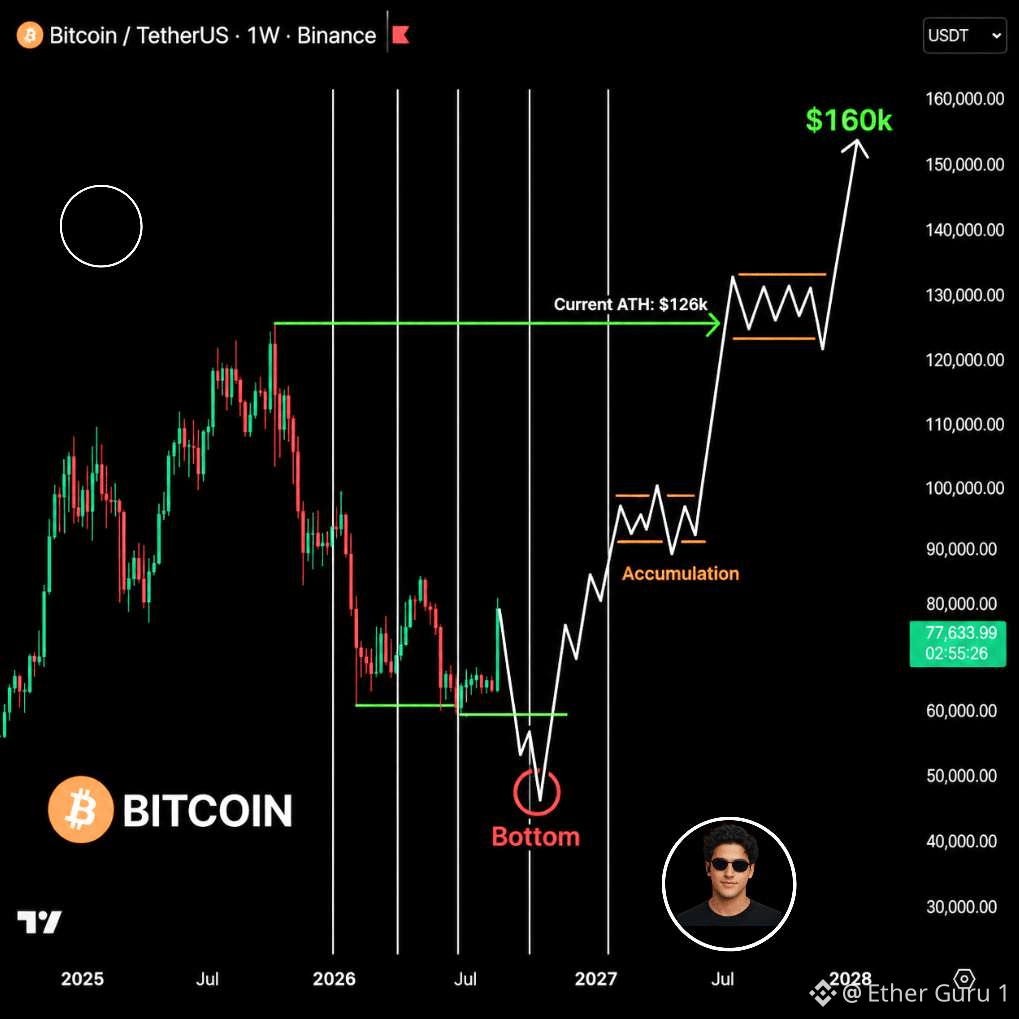
$BTC 🚨 THE 2026–27 MACRO RESET
Q3 2026 could become a major test for risk assets if monetary policy and crypto sentiment weaken together.
BTC: potential bottoming phase
SPX: ~7.3K downside scenario
A new Fed leadership cycle could reshape expectations around rates, liquidity and financial conditions.
The first rate cut would not automatically mean a bull market.
If recession fears intensify, markets could initially interpret easing as a response to economic weakness.
Crypto sentiment: extreme-fear scenario
Q4 could bring a different setup if Bitcoin reclaims important resistance and institutional demand strengthens.
BTC: above $84K
Regulatory clarity could become another catalyst if the CLARITY Act ultimately becomes law.
AI infrastructure and crypto adoption could also create new narratives for capital rotation.
2027 BTC scenario: $160K+
Three Fed cuts would represent a meaningful shift in monetary conditions if economic weakness becomes pronounced.
Bitcoin could increasingly be viewed alongside other scarce assets during periods of monetary uncertainty.
But the path will not be linear.
A 2x return within 12 months would require Bitcoin to reach roughly double the Q3 entry level.
That remains a scenario, not a guaranteed outcome.
The strongest opportunities often appear when sentiment is weakest.
Fear creates the setup.
Liquidity decides the timing.
118
·
--
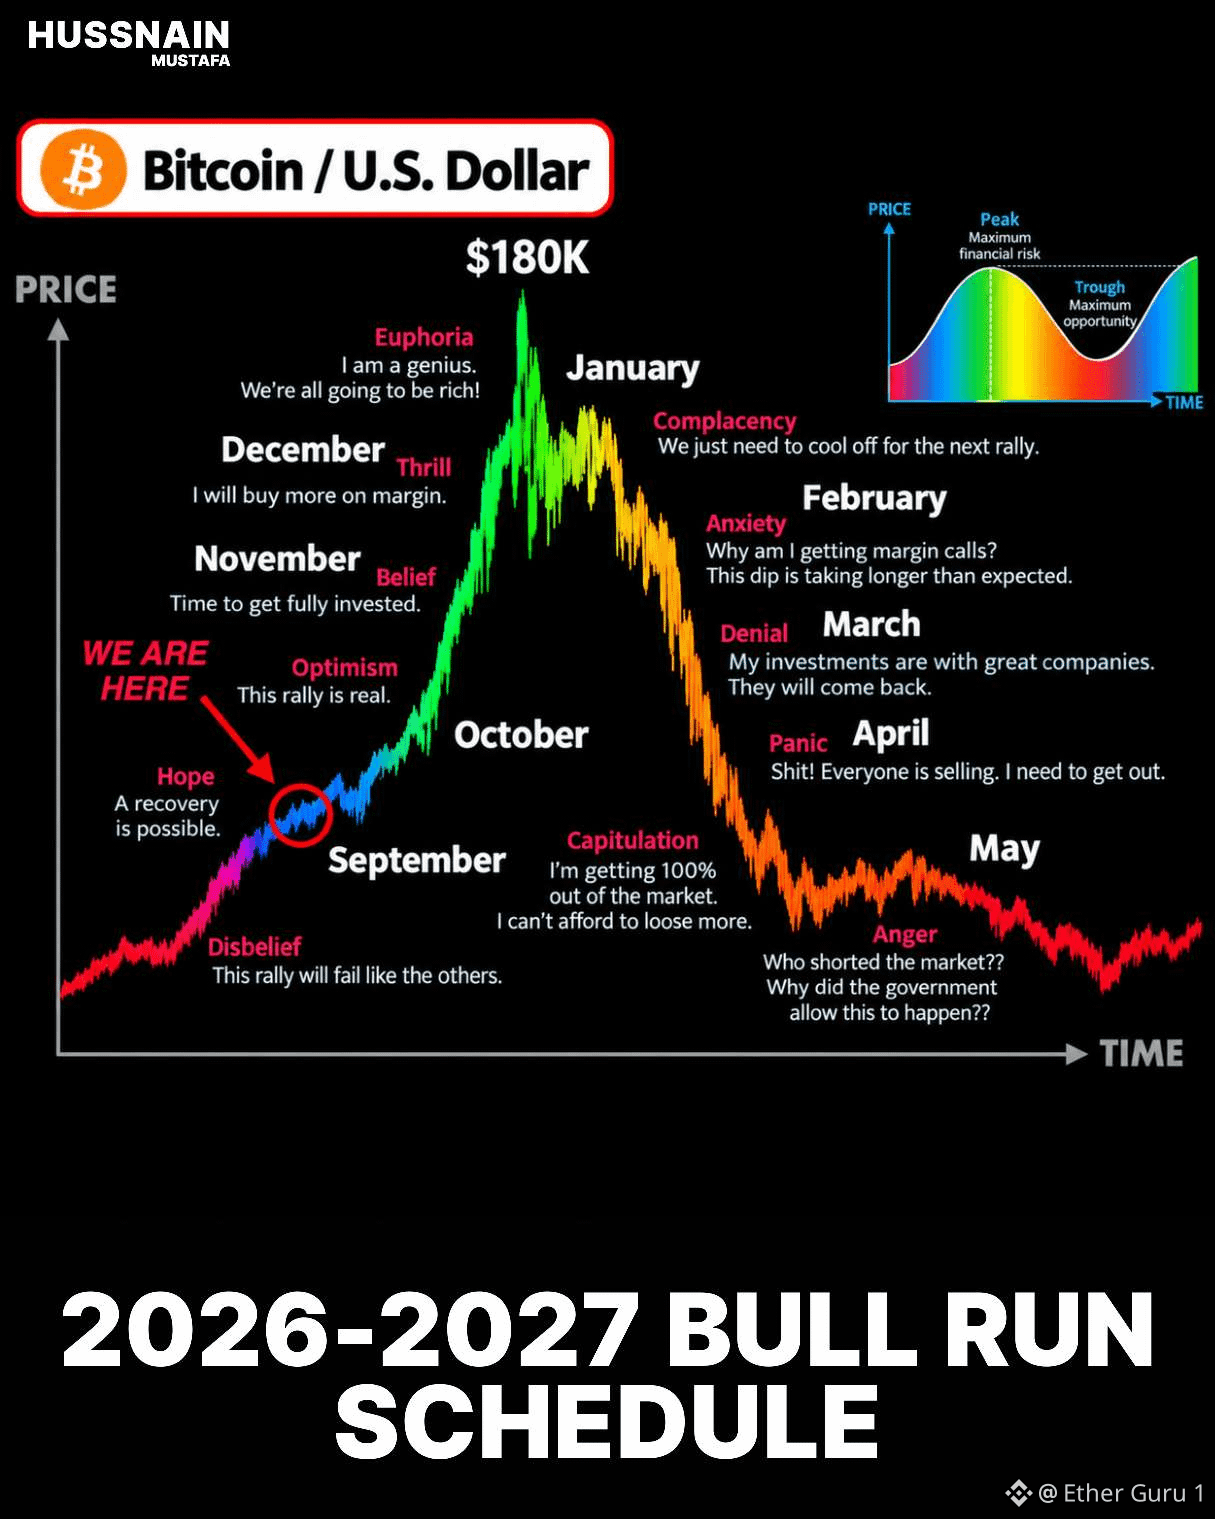
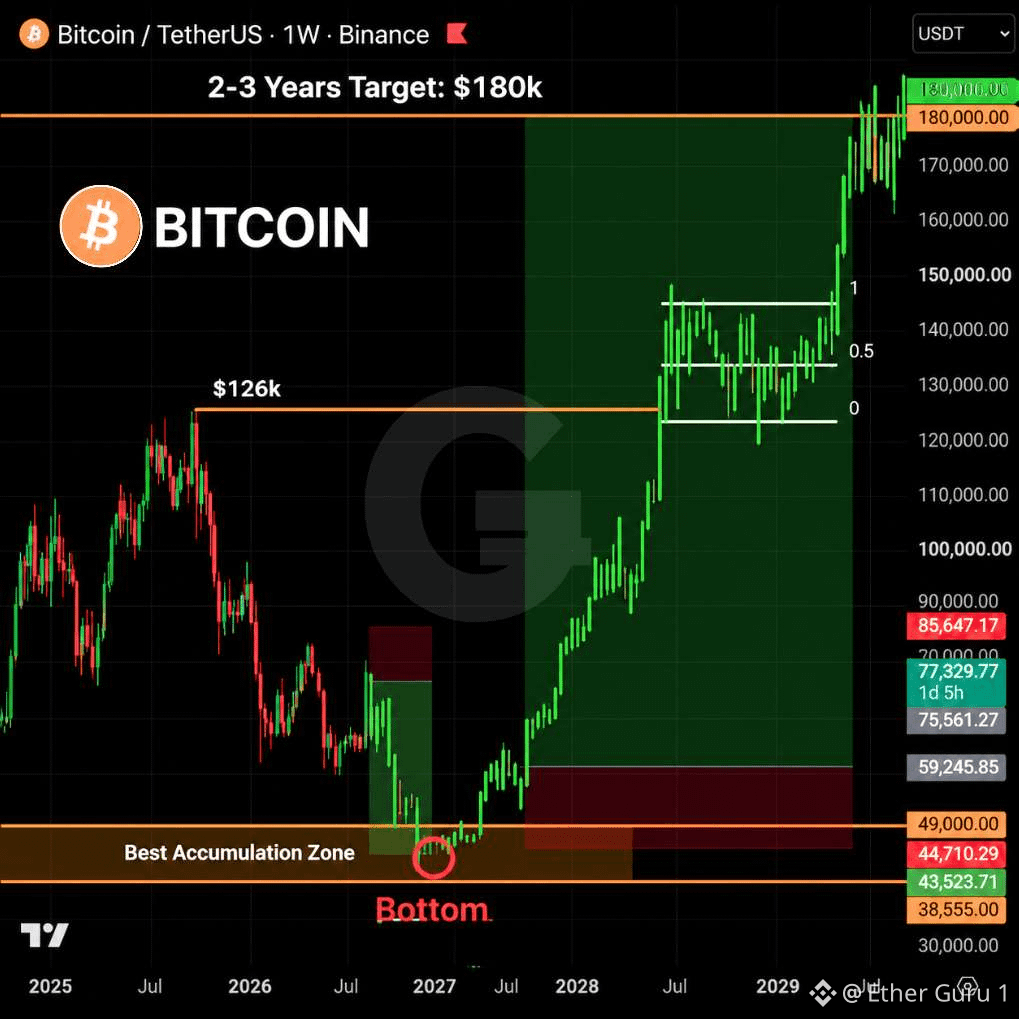
$BTC $BTC ROADMAP 🧭
Bitcoin’s Current Setup Is Being Mapped Around A $77K Starting Point.
The Bear-Case Projection Targets $39K–$49K For A Potential Cycle-Bottom Zone.
That Would Represent A Possible 36%–49% Drawdown From $77K.
The Long-Term Bull Case Then Targets $180K Over The Following 2–3 Years.
From A $45K Midpoint, $180K Would Require Roughly 4× Growth.
This Is A Technical Scenario — The $39K–$49K Zone Is Not A Confirmed Bottom.
The Strategy Is To Watch Fear, Liquidity And Structure Before Treating The Zone As An Accumulation Opportunity.
91
·
--
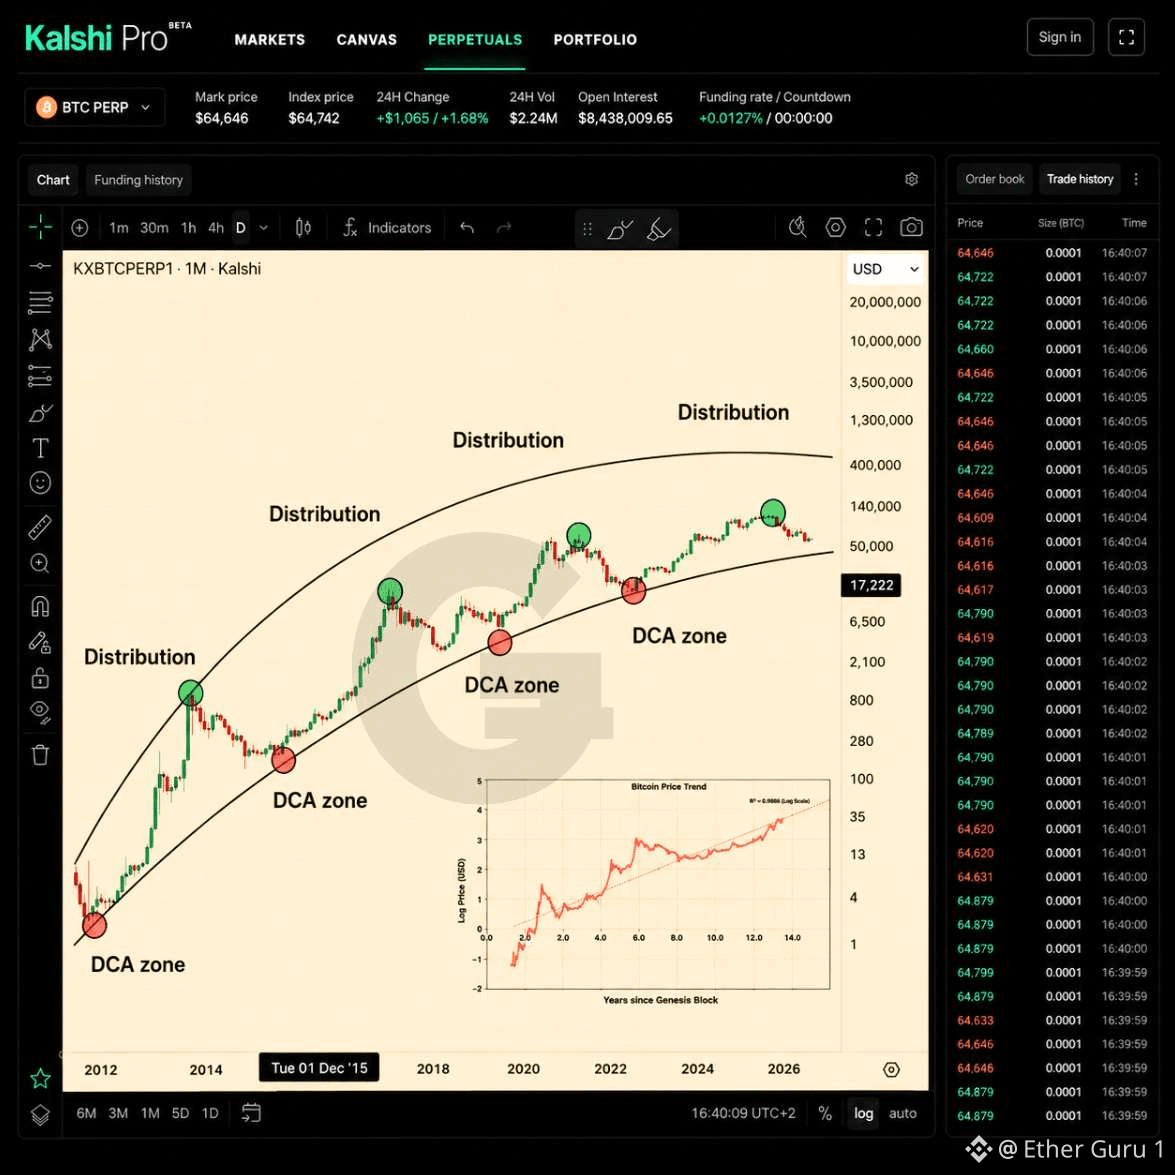
$BTC 🚨 EVERY CRASH HAS LEFT A HIGHER FLOOR
Bitcoin has repeatedly experienced brutal drawdowns, yet later cycles established dramatically higher price floors.
2010 → ~$0.10
2011 → ~$1
2013 → ~$50
2015 → ~$200
2018 → ~$3,000
2022 → ~$15,000
2024 → ~$39,000
2026 → ~$60,000
The progression is striking.
From $0.10 → $60K represents an increase of roughly 600,000×.
Even the move from the 2022 low of ~$15K to $60K represents approximately 4×.
That doesn’t mean every future drawdown must produce a higher floor.
Bitcoin can still experience severe volatility, prolonged bear markets and deeper-than-expected corrections.
But the long-term price history shows a recurring feature:
Yesterday’s “disaster” price has repeatedly become tomorrow’s historical reference point.
The more interesting question is not whether another crash happens.
It’s whether the next major cycle eventually establishes another floor that makes $60K look as distant as $15K does today.
57
·
--
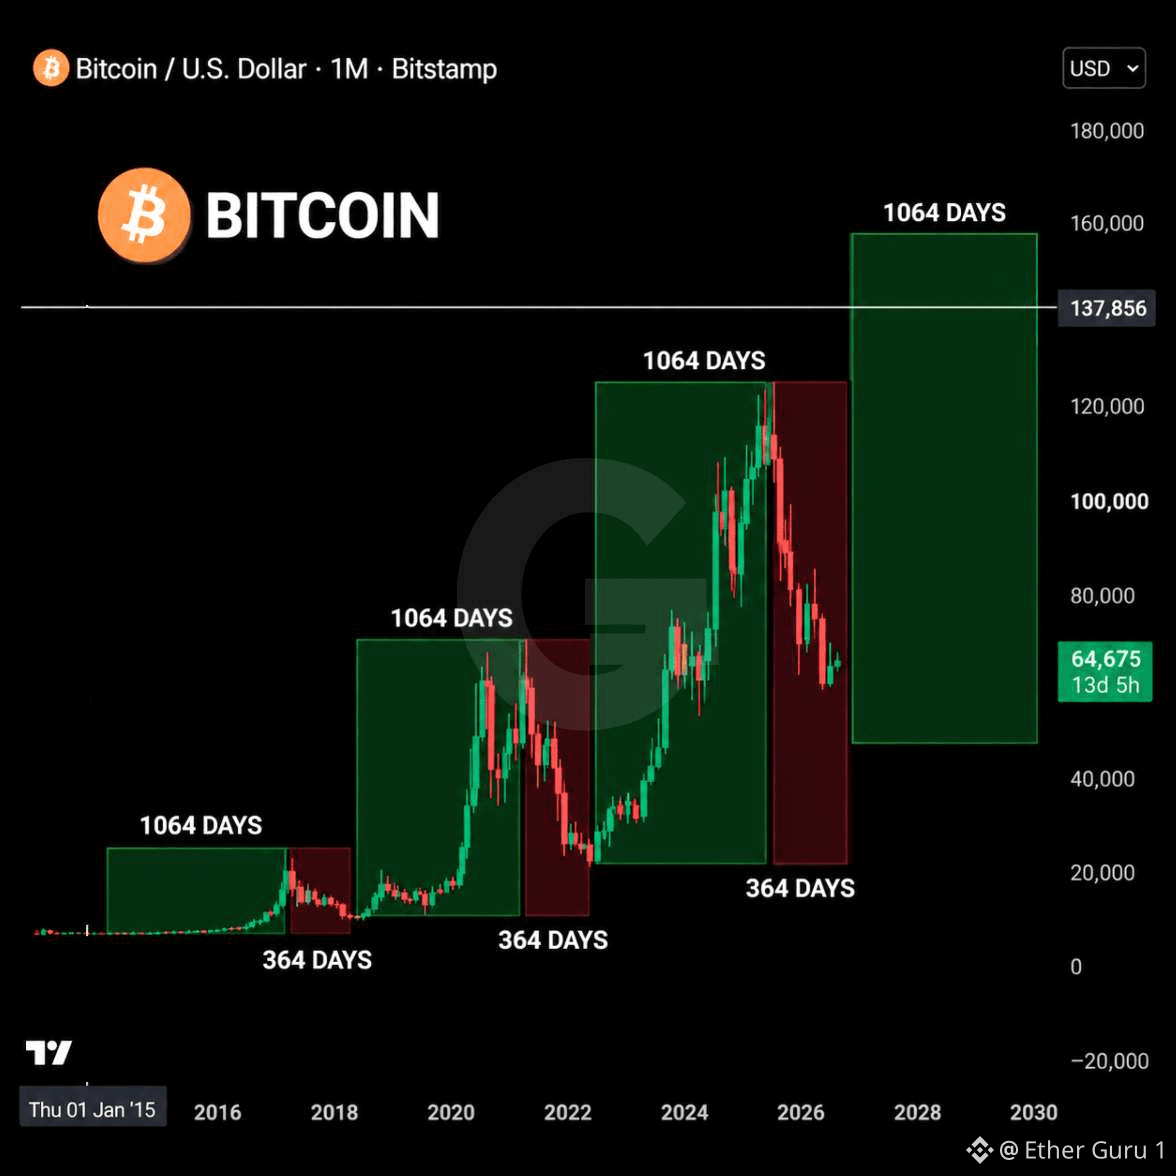
$BTC CYCLE
Bitcoin’s 1,064 / 364-Day Cycle Theory Points Toward Early October 2026.
The Model Uses 1,064 Days For The Expansion Phase And 364 Days For The Bear Phase.
2015–2017: 1,064 Days
2017–2018: 364 Days
2018–2021: 1,064 Days
2021–2022: 364 Days
The 2025 Peak Was Around $126K.
Applying Another 364-Day Phase Places Theoretical Bottom Timing Around October 5–9, 2026.
That Date Is A Historical Pattern Projection — Not A Guaranteed Market Bottom.
76
·
--
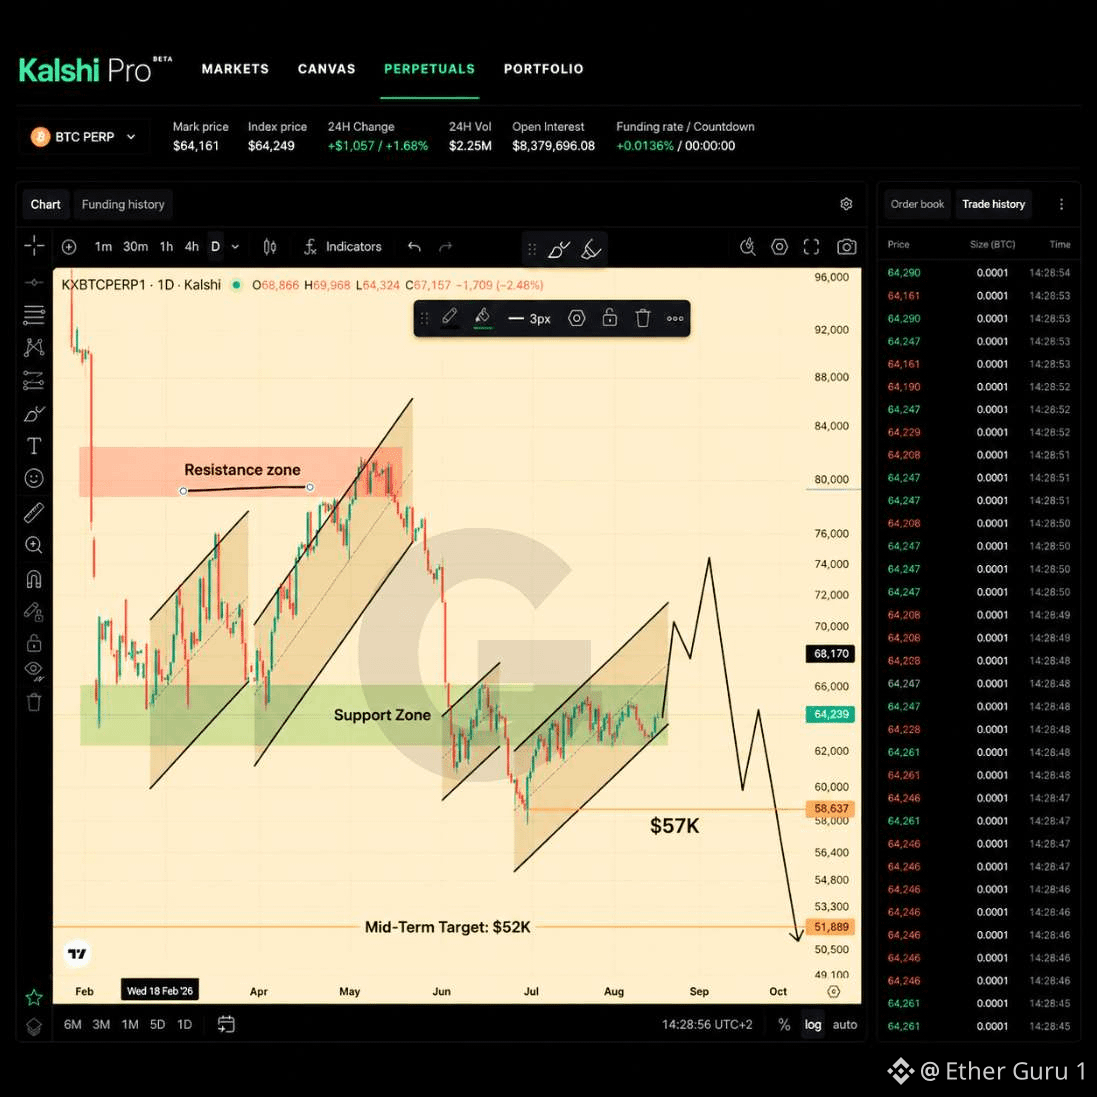
$BTC 🚨 THE NEXT $70K TEST COULD BE THE MARKET’S BIGGEST TRAP
After falling toward $62K, the next major area on the radar is the $70K–$72K FVG.
A recovery into that zone would represent roughly 13–16% upside from $62K.
My current 2–3 month scenario is built around several liquidity tests.
$63K → $70K → $58K
$58K → $64K → $50K
$50K → $55K → $48K
Then potentially 30–45 days of accumulation around the lower range.
If that structure develops, the market could spend weeks moving sideways before establishing a stronger directional trend.
The most important level may therefore be $70K–$72K, not because it guarantees a reversal, but because a rejection there would strengthen the bearish setup.
A move from $72K → $48K would represent roughly 33% downside.
On the other hand, sustained acceptance above the FVG would weaken this roadmap considerably.
That makes the next recovery more important than the prediction itself.
$62K → current reference
$70K–$72K → major upside test
$58K → first downside checkpoint
$50K → deeper support
$48K → potential accumulation zone
This remains a scenario based on liquidity and market structure—not a guaranteed path.
The confirmation will come from how price reacts at each level, not from the roadmap alone.
62
·
--
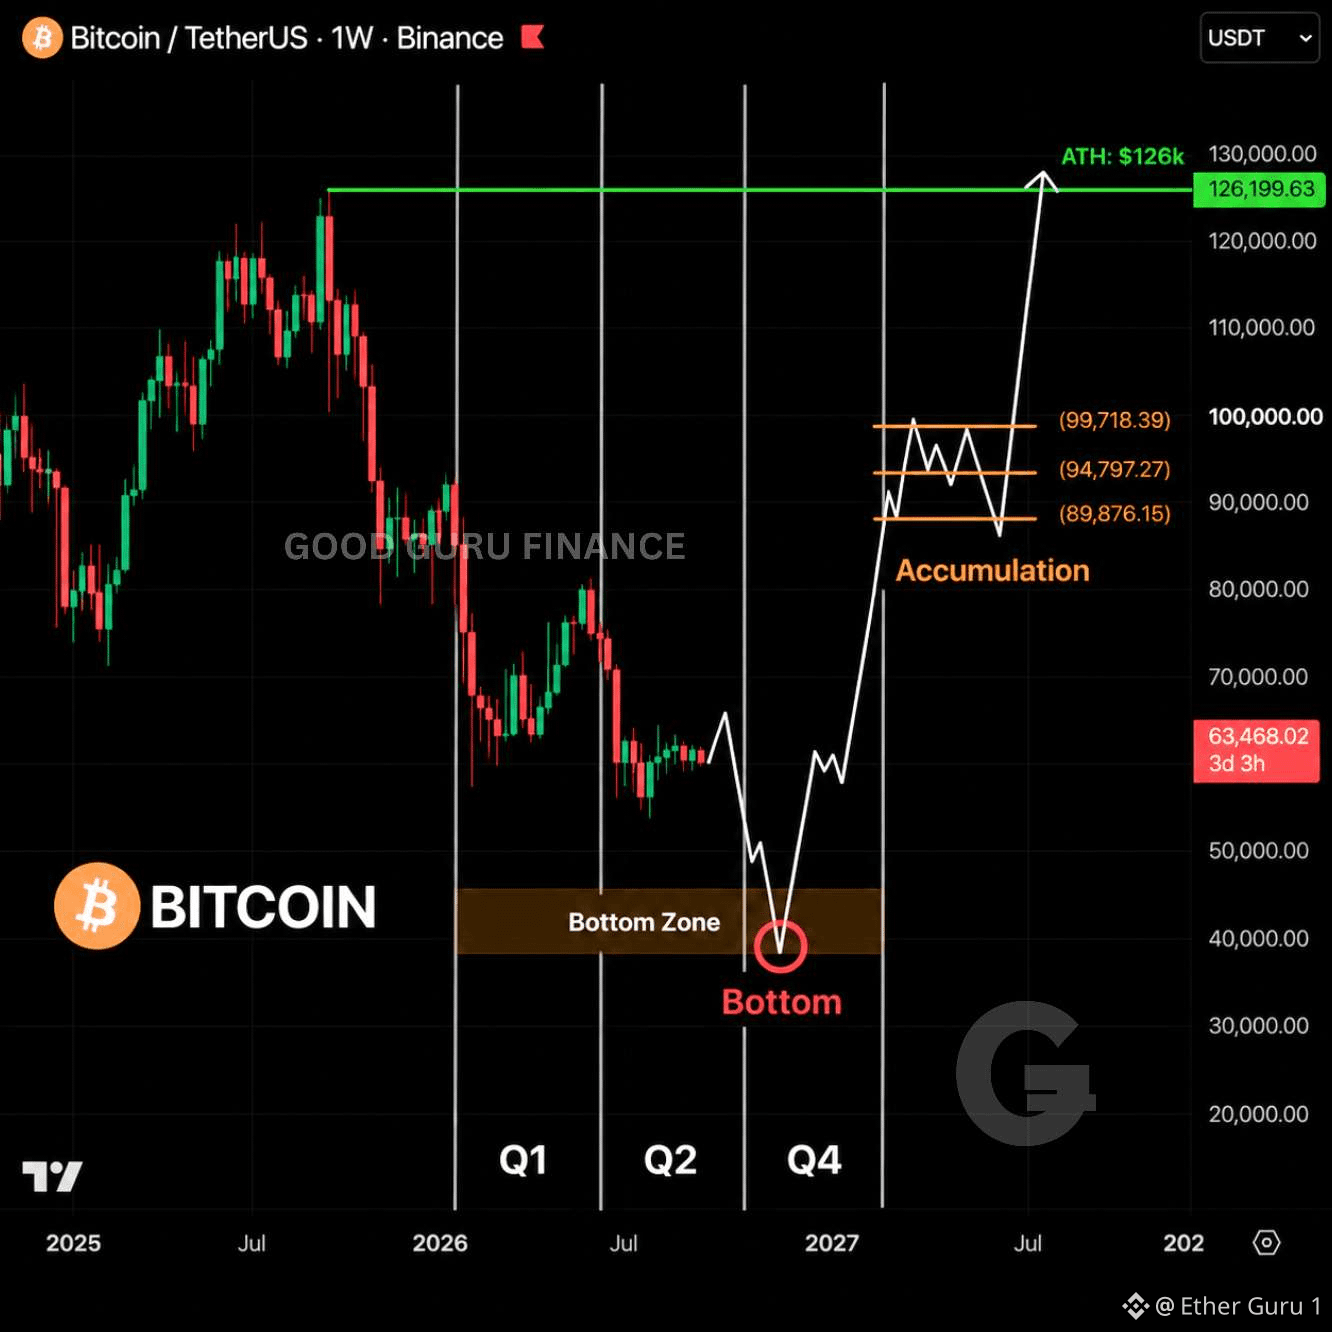
$BTC 🗓️ THE NEXT FOUR MONTHS COULD DEFINE THE ENTIRE SETUP
My current 2026 scenario is built around five distinct phases, rather than one straight-line move.
AUGUST
A push toward $70K could create a strong short-term rally — but the key question would be whether price can actually hold above that zone.
SEPTEMBER
If momentum fades near the highs, distribution could develop and expose the market to a move below $57K.
OCTOBER
The deeper downside scenario sits around $40K–$45K, where a major liquidity test could potentially develop.
NOVEMBER
If selling pressure exhausts, several weeks of consolidation could begin as the market searches for a sustainable higher low.
DECEMBER
A recovery toward $100K would represent a major reversal from the projected October lows.
From $42K → $100K would require roughly 138% upside.
The entire roadmap is a scenario, not a prediction with guaranteed timing.
What matters most is whether each phase confirms or invalidates the next one.
The market doesn’t need to follow the calendar.
Price action will decide.
76
·
--
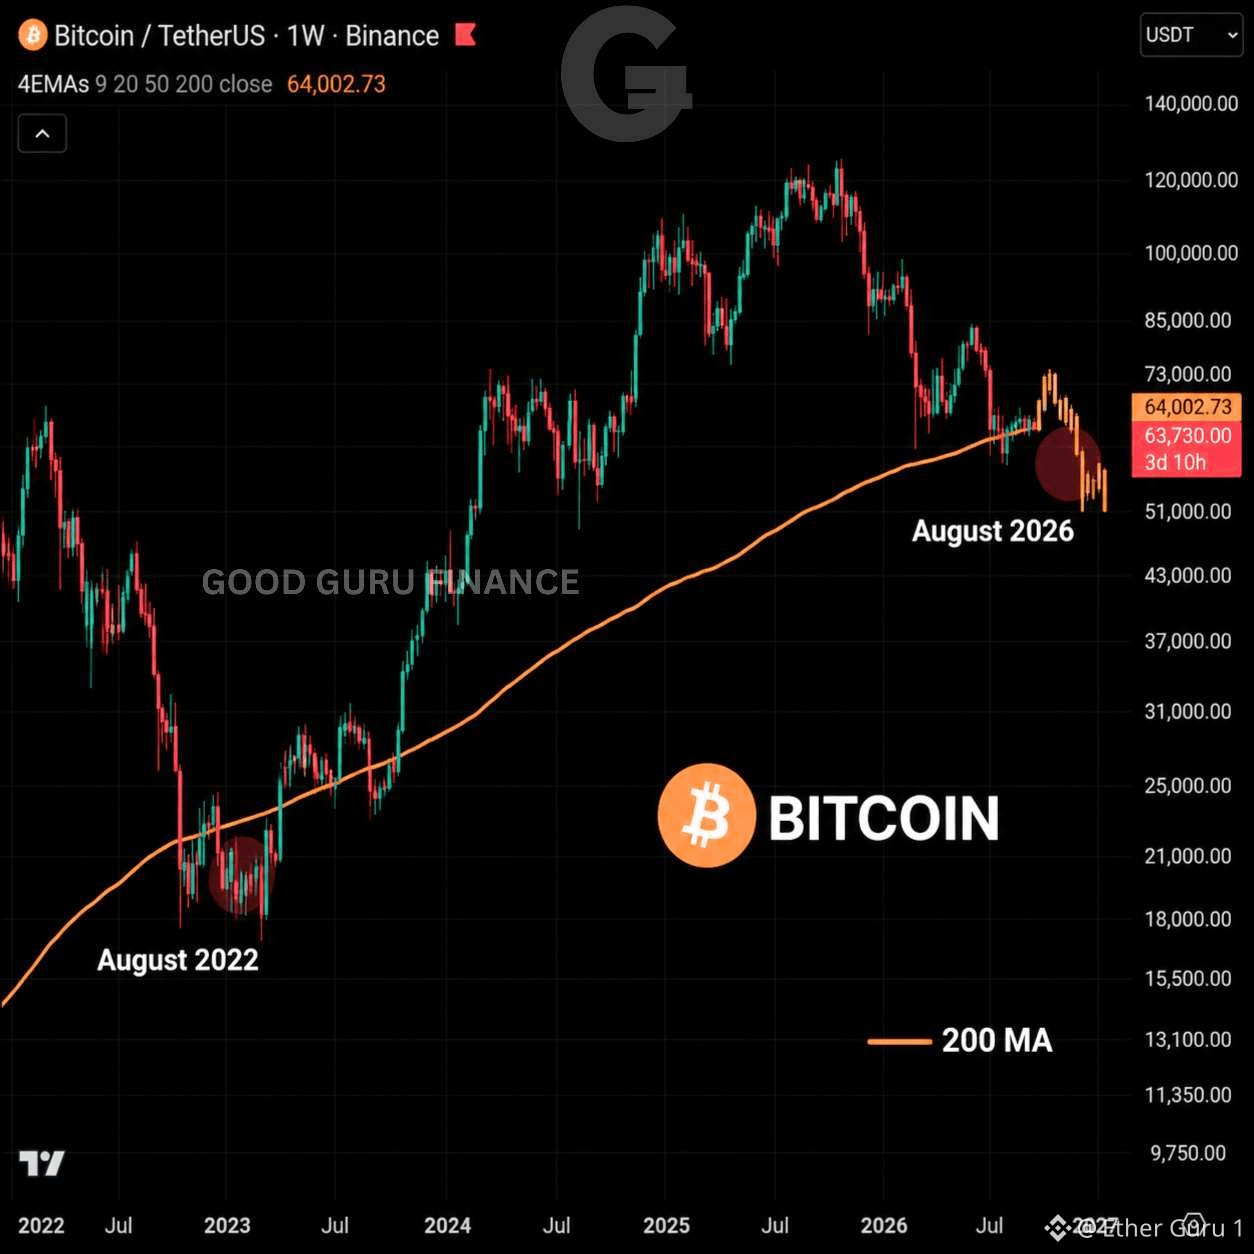
$BTC Bitcoin Has Closed Below A Major Long-Term Trend Indicator Again.
In 2026, BTC Has Already Traded Below Its 200-Week MA, With The Level Around $61.8K In June.
The 2022 Analogy Is Interesting — But The Market Spent Months Below The 200WMA Before The Cycle Bottom Arrived.
One Current Bear-Case Scenario Puts A Potential Cycle Bottom Around $40K–$46K Later In 2026.
A $45K October Bottom Is Therefore A Scenario, Not A Confirmed Roadmap.
The 200WMA Reaction May Matter More Than The Calendar Date.
74
·
--
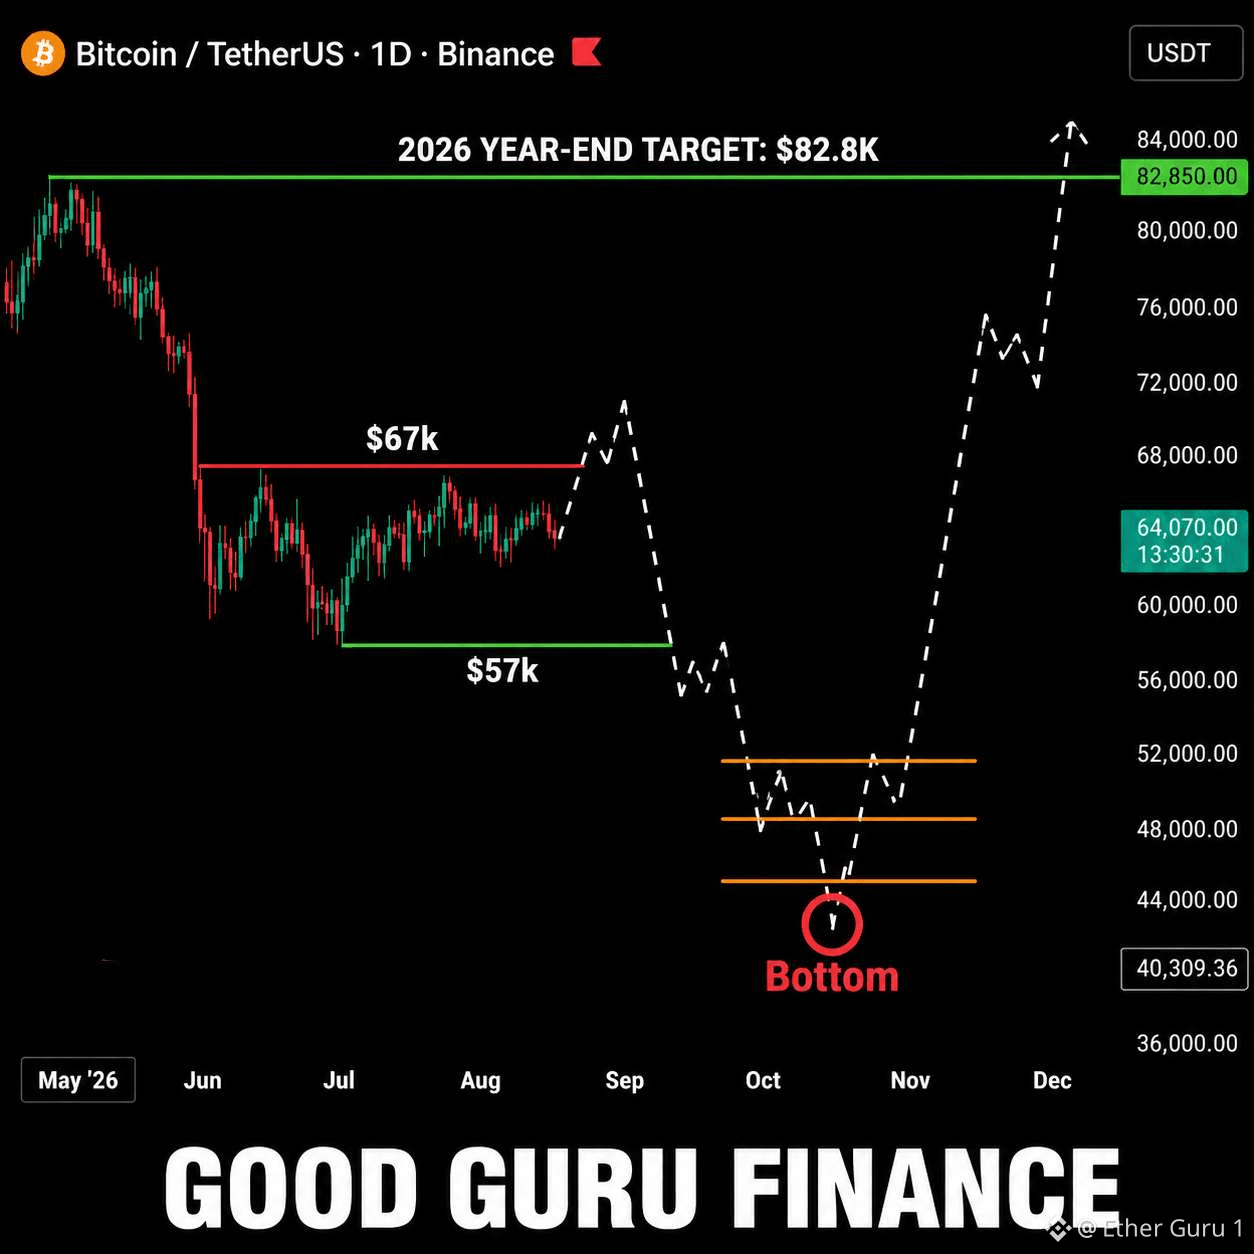
$BTC ⚠️ THE NEXT PHASE COULD BE DECIDED BY A FEW KEY LEVELS
The current recovery may still prove to be a temporary rebound rather than a confirmed trend reversal.
My 2–3 month scenario:
$64K → $70K → $57K → $48K → $42K → $87K
The important levels are separated by very different market conditions.
A move toward $70K would represent roughly 9% upside from $64K.
A decline from $70K to $42K would then represent roughly 40% downside.
From $42K to $87K, the recovery would require roughly 107% upside.
My timeline remains a scenario, not a certainty:
Late August → $57K test
October–November → potential $43K zone
End of 2026 → potential recovery toward $87K
The key confirmation will come from how price behaves around each level.
A sustained breakout changes the bearish structure.
A rejection followed by lower lows keeps the downside scenario alive.
70
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
QNTRises287%
404 views
46 Discussing
#QNTRises287%
🚀 QNT +287% — a move that demands attention.
A rally this sharp can reflect a sudden shift in market sentiment, liquidity, and trading activity. But after a vertical move, volatility can expand quickly.
My takeaway: don’t chase the candle—watch volume, liquidity, and whether QNT can sustain the breakout. 📊
#QNTRises287% #QNT #Crypto #Binance
$QNT
PALASH5
·0 Likes
·190 views
TrumpRejectsAIRulesForVoluntaryAudits
3,736 views
204 Discussing
BitgetHotWalletBreachTiedToThirdPartySecurityFlaw
1,894 views
154 Discussing