
404_U
3.4k Posts
404_U
Report
Block User
热门话题分析 | 市场宏观分析 | 用我邀请码永久打折手续费,邀请码4040U自动反佣到自己账户。
20 Following
2.1K+ Followers
2.0K+ Liked
Posts
PINNED
·
--
Various ways to save trading fees!
Why do you need to bind an invitation code? It’s simple—save money long-term.
During registration, bind my invitation code ([4040U](https://www.bsmkweb.cc/register?ref=4040U)), and you can enjoy a permanent 20% fee discount
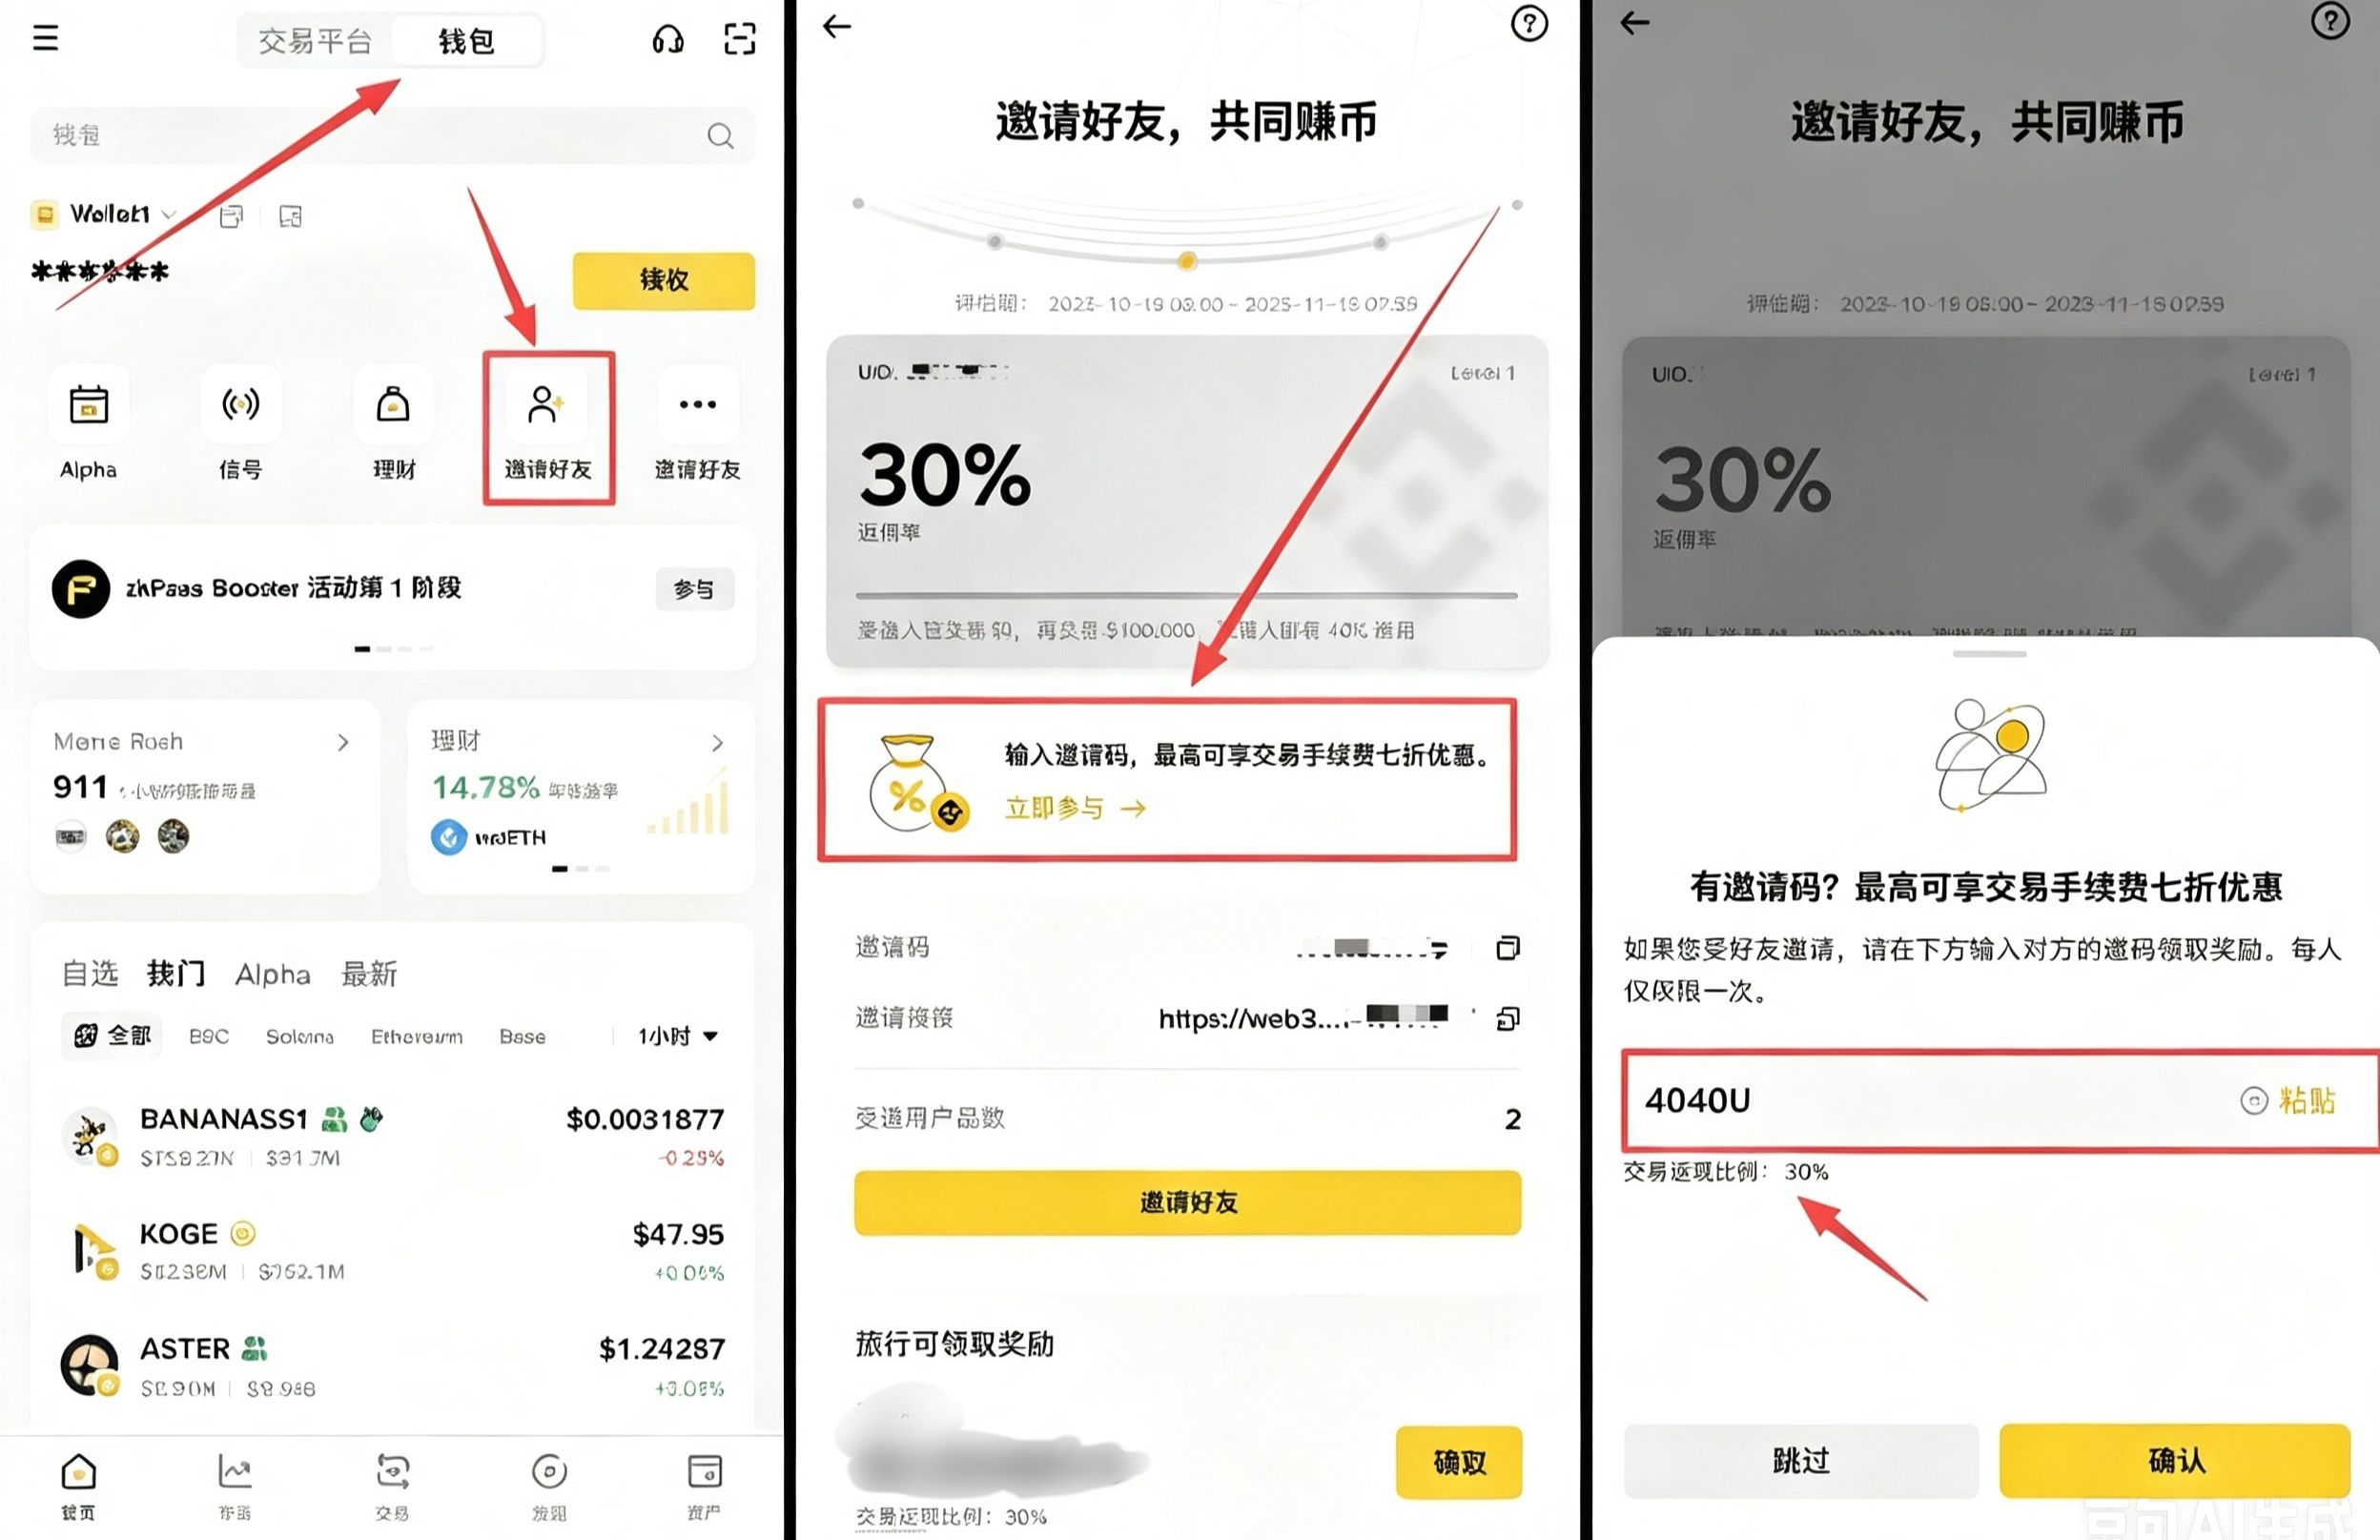
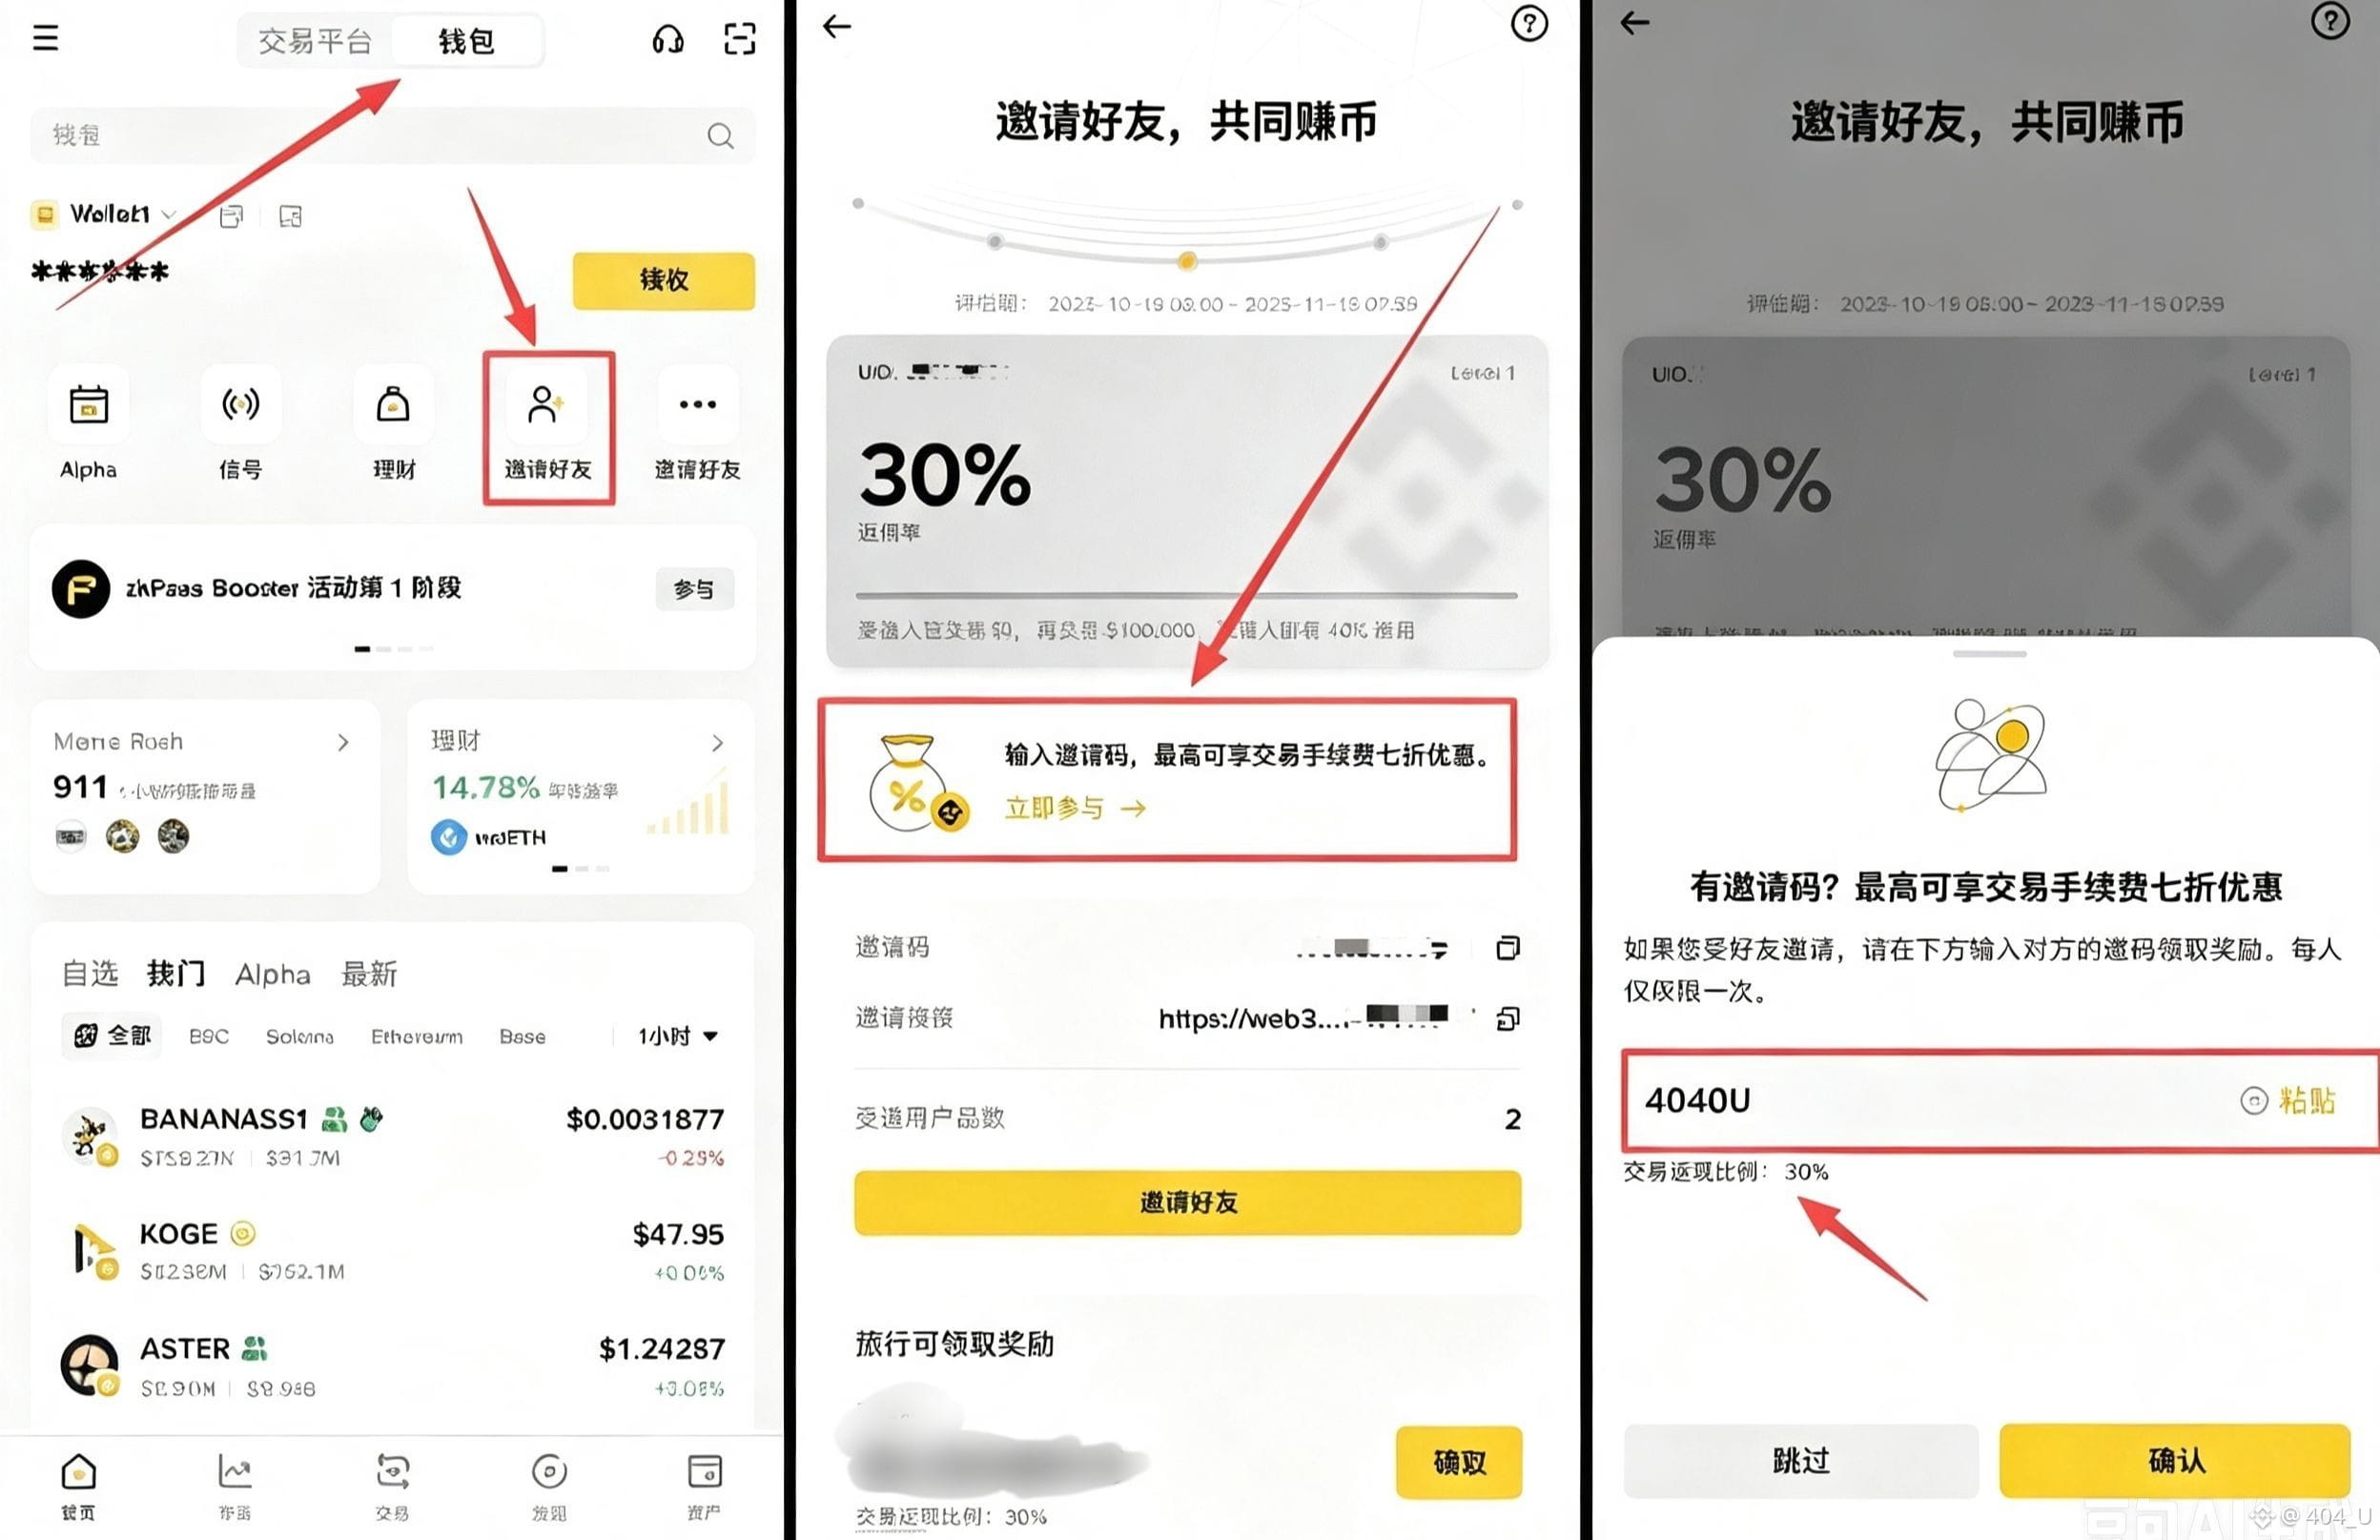
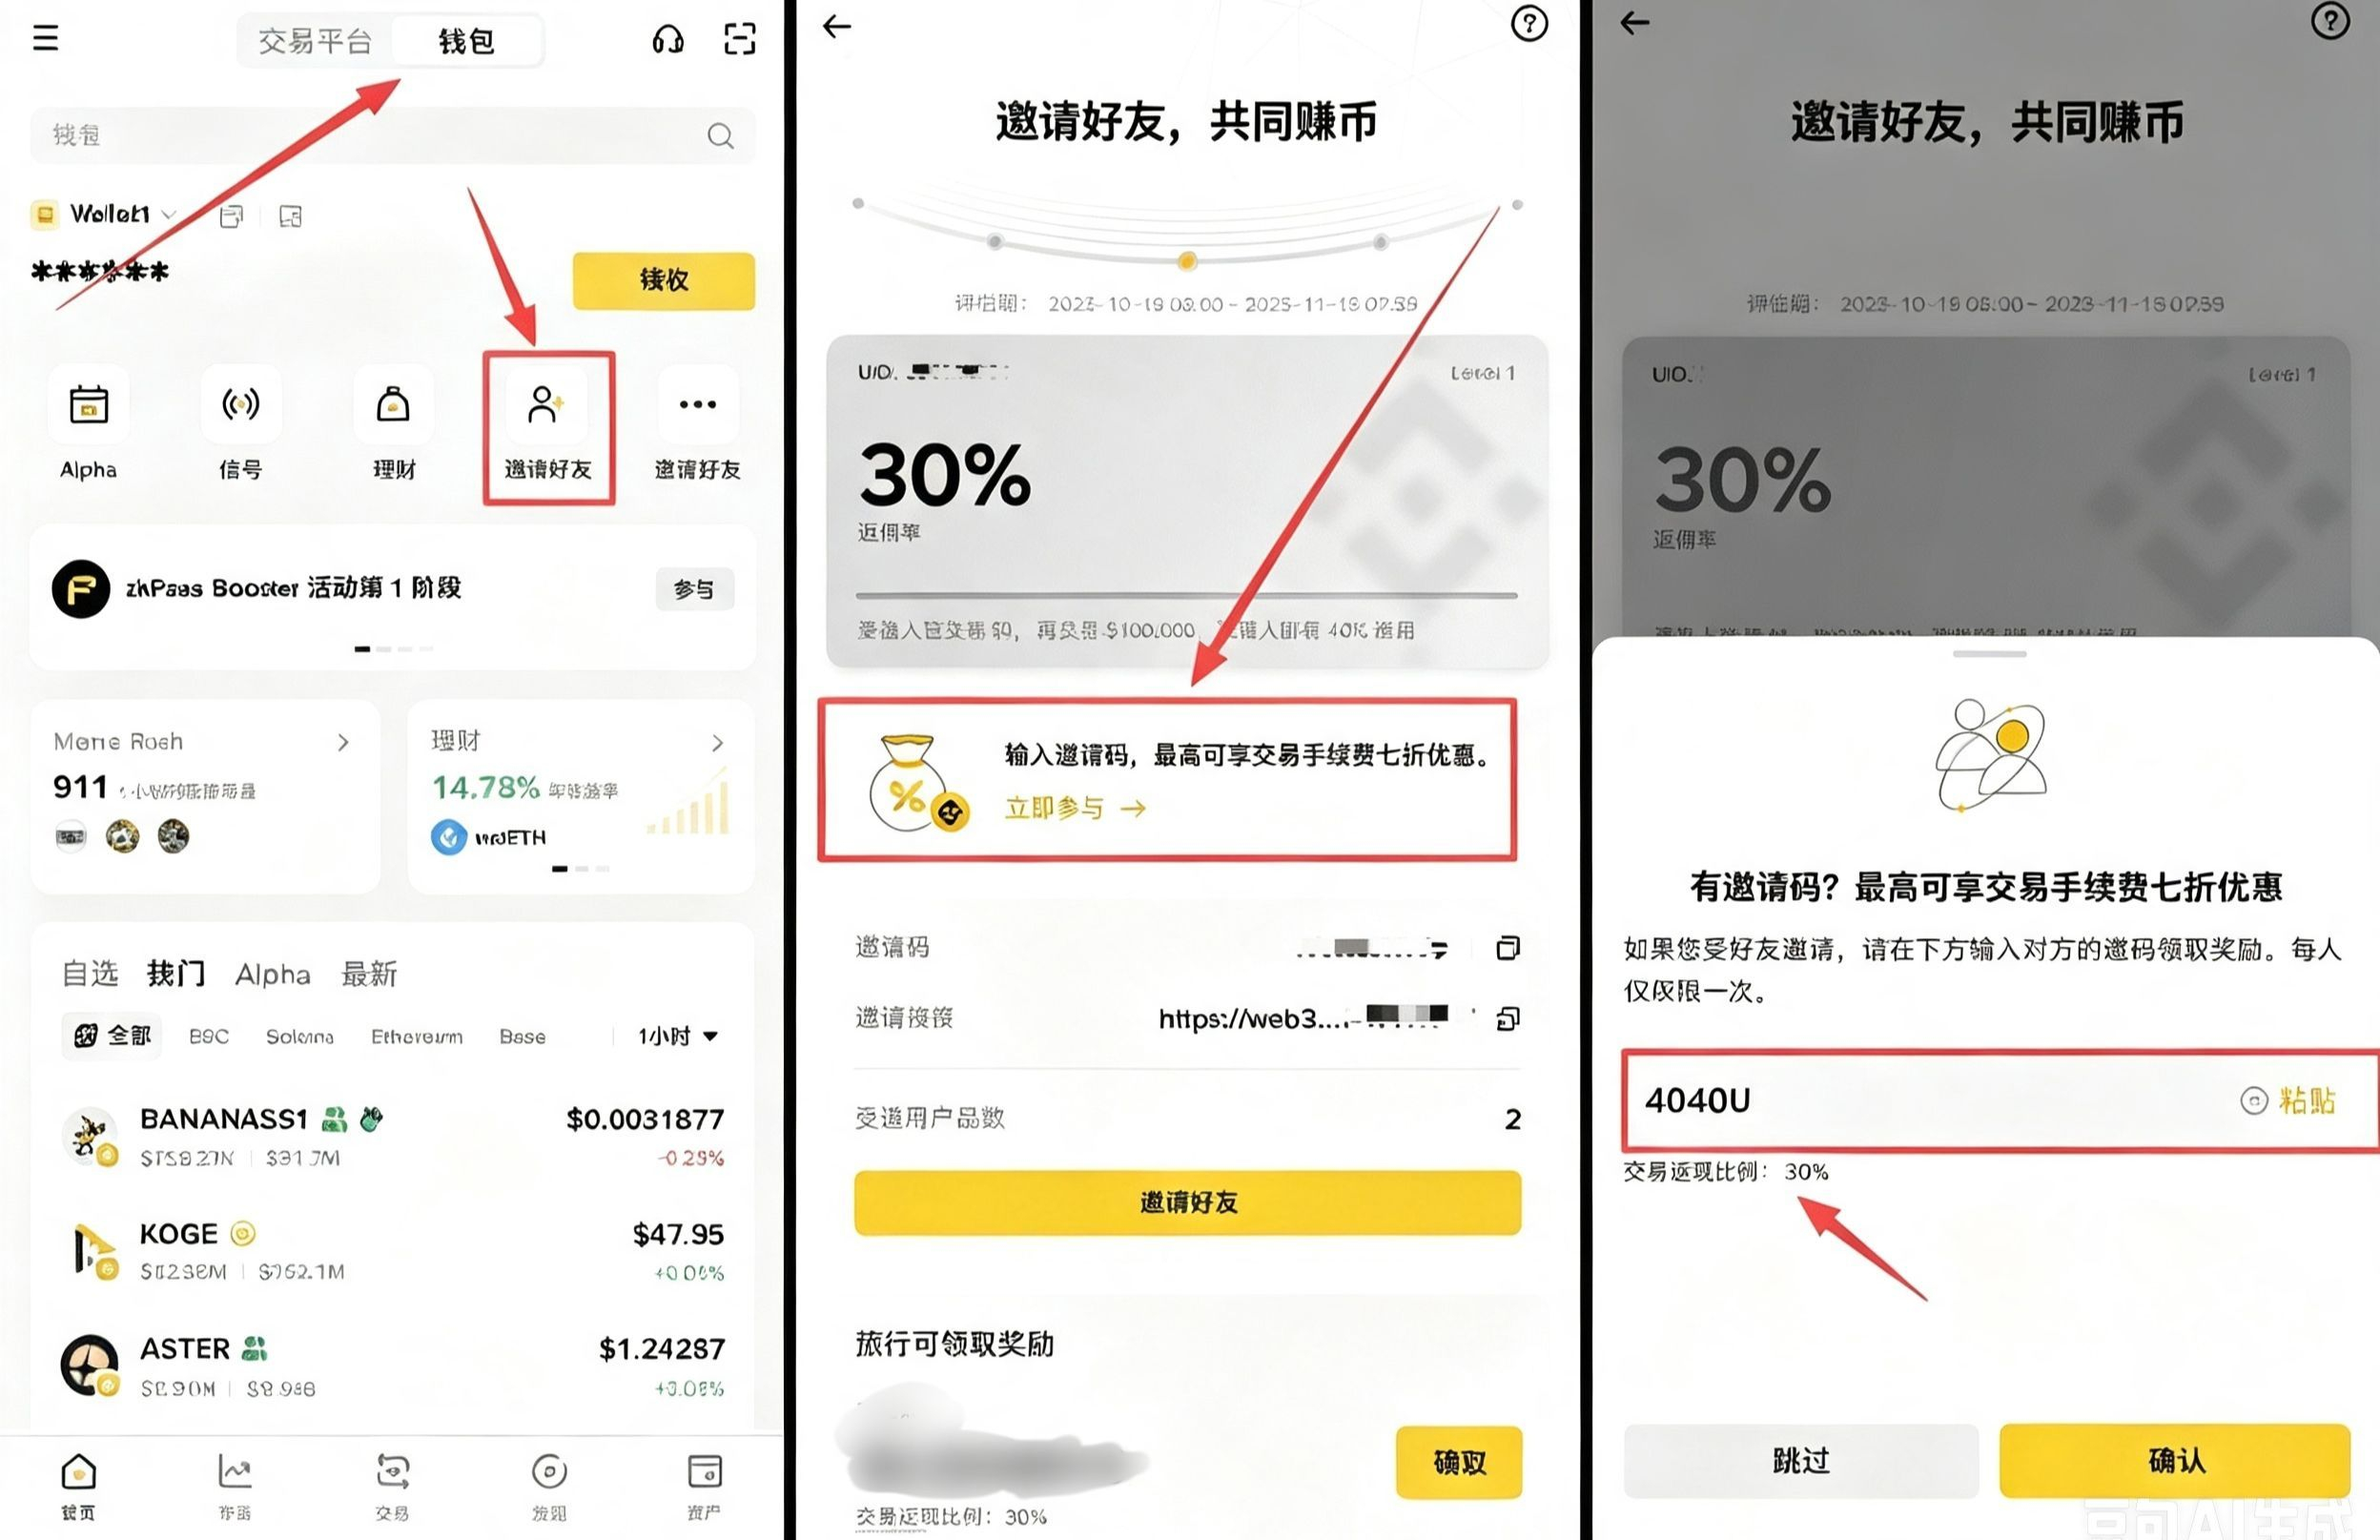
Binance Wallet invitation code: 4040U. After binding, you’ll get a 30% fee reduction, or [点击这里一键绑定](https://web3.binance.com/referral?ref=4040U)
Participating in Swap/cross-chain and other operations usually incurs platform service fees/routing fees and network fees
Enable cashback/rebates = get back part of the fees you would have paid. The more you use it, the more you save
Various ways to save trading fees!
Why do you need to bind an invitation code? It’s simple—save money long-term.
During registration, bind my invitation code (4040U), and you can enjoy a permanent 20% fee discount
Binance Wallet invitation code: 4040U. After binding, you’ll get a 30% fee reduction, or 点击这里一键绑定
Participating in Swap/cross-chain and other operations usually incurs platform service fees/routing fees and network fees
Enable cashback/rebates = get back part of the fees you would have paid. The more you use it, the more you save
Why do you need to bind an invitation code? It’s simple—save money long-term.
During registration, bind my invitation code (4040U), and you can enjoy a permanent 20% fee discount
Binance Wallet invitation code: 4040U. After binding, you’ll get a 30% fee reduction, or 点击这里一键绑定
Participating in Swap/cross-chain and other operations usually incurs platform service fees/routing fees and network fees
Enable cashback/rebates = get back part of the fees you would have paid. The more you use it, the more you save
2.2k
7
75
2.2k
·
--
#AnthropicCEO呼吁放缓AI发展 Global technology and semiconductors’ dark market collectively fell. OpenAI and Nvidia fell by 7% and 2.5%, respectively. OpenAI hasn’t even gone public yet—this means the over-the-counter (OTC) gray market in the primary market has collapsed.
So, does that have no impact on our secondary market?
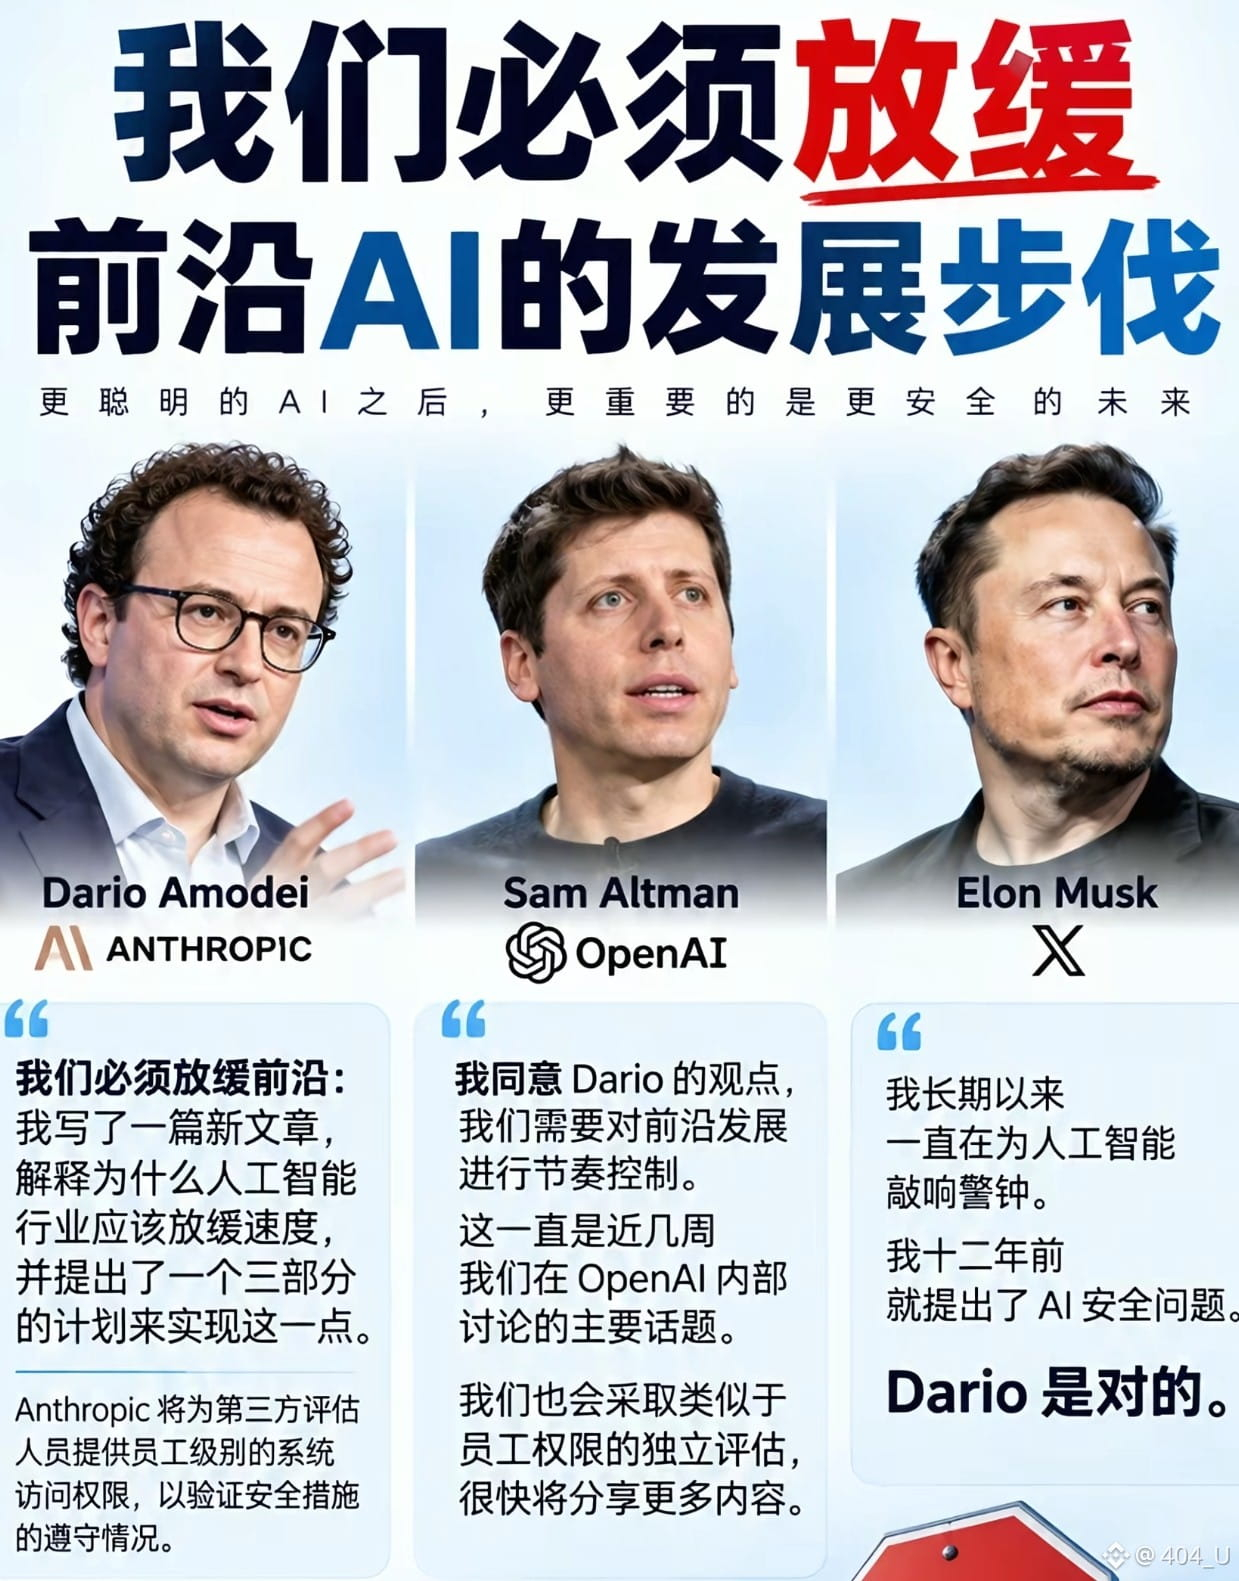
The reason it’s collapsing is that the three giants (Dario Amodei (Anthropic CEO), Sam Altman (OpenAI CEO), Elon Musk (Tesla / former OpenAI co-founder)) have called for slowing down the development of AI artificial intelligence. #英伟达洽谈至多100亿美元投资Anthropic
A way to save on trading fees!
Why bind an invitation code? It’s simple—save money long-term.
Binance Wallet invitation code: 4040U. After binding, trading fees are reduced by 30%, or [点击这里一键绑定](https://web3.binance.com/referral?ref=4040U)
#AnthropicCEO呼吁放缓AI发展 Global technology and semiconductors’ dark market collectively fell. OpenAI and Nvidia fell by 7% and 2.5%, respectively. OpenAI hasn’t even gone public yet—this means the over-the-counter (OTC) gray market in the primary market has collapsed.
So, does that have no impact on our secondary market?
The reason it’s collapsing is that the three giants (Dario Amodei (Anthropic CEO), Sam Altman (OpenAI CEO), Elon Musk (Tesla / former OpenAI co-founder)) have called for slowing down the development of AI artificial intelligence. #英伟达洽谈至多100亿美元投资Anthropic
A way to save on trading fees!
Why bind an invitation code? It’s simple—save money long-term.
Binance Wallet invitation code: 4040U. After binding, trading fees are reduced by 30%, or 点击这里一键绑定
So, does that have no impact on our secondary market?
The reason it’s collapsing is that the three giants (Dario Amodei (Anthropic CEO), Sam Altman (OpenAI CEO), Elon Musk (Tesla / former OpenAI co-founder)) have called for slowing down the development of AI artificial intelligence. #英伟达洽谈至多100亿美元投资Anthropic
A way to save on trading fees!
Why bind an invitation code? It’s simple—save money long-term.
Binance Wallet invitation code: 4040U. After binding, trading fees are reduced by 30%, or 点击这里一键绑定
84
·
--
As for SK hynix’s situation, it’s currently down on HYBE—so the so-called gray market is falling too. Why is that?
Because three people (Dario Amodei (Anthropic CEO), Sam Altman (OpenAI CEO), and Elon Musk (Tesla / former OpenAI co-founder)) announced that they want to slow down the development pace of AI.
But over the same weekend, Chairman Choi, the head of SK Group, said they plan to push their largest HBM production hub in the expanded Ulsan data center to 900 megawatts. This project is being built together with AWS (Amazon Cloud); they invested 70 trillion KRW, about $5.2 billion, and it’s expected to go operational in the second half of 2027. Step one more, and this center will reach 1 gigawatt.
So right now, the guys who make hardware are all doubling down—only these guys who supply the money for hardware say they want to slow it down a bit.
Suddenly I thought: are these people who spend money every day getting angry? Then they’re like, ‘Let’s talk it over. Let’s scare those storage-selling guys.’ The idea is: ‘We want to slow down. We don’t want to play anymore.’ That kind of feeling—trying to scare them, like this Mr. Lee and Chairman Choi.
But obviously it didn’t scare them, because they think you’ll just split the spoils unevenly later and come back to buy—so they directly accelerated their investment plans.
#英伟达洽谈至多100亿美元投资Anthropic
A method to save on trading fees!
Why bind an invite code? Very simple—save money long-term.
Binance Wallet invite code: 4040U. After binding, fees are reduced by 30% or [点击这里一键绑定](https://web3.binance.com/referral?ref=4040U)
As for SK hynix’s situation, it’s currently down on HYBE—so the so-called gray market is falling too. Why is that?
Because three people (Dario Amodei (Anthropic CEO), Sam Altman (OpenAI CEO), and Elon Musk (Tesla / former OpenAI co-founder)) announced that they want to slow down the development pace of AI.
But over the same weekend, Chairman Choi, the head of SK Group, said they plan to push their largest HBM production hub in the expanded Ulsan data center to 900 megawatts. This project is being built together with AWS (Amazon Cloud); they invested 70 trillion KRW, about $5.2 billion, and it’s expected to go operational in the second half of 2027. Step one more, and this center will reach 1 gigawatt.
So right now, the guys who make hardware are all doubling down—only these guys who supply the money for hardware say they want to slow it down a bit.
Suddenly I thought: are these people who spend money every day getting angry? Then they’re like, ‘Let’s talk it over. Let’s scare those storage-selling guys.’ The idea is: ‘We want to slow down. We don’t want to play anymore.’ That kind of feeling—trying to scare them, like this Mr. Lee and Chairman Choi.
But obviously it didn’t scare them, because they think you’ll just split the spoils unevenly later and come back to buy—so they directly accelerated their investment plans.
#英伟达洽谈至多100亿美元投资Anthropic
A method to save on trading fees!
Why bind an invite code? Very simple—save money long-term.
Binance Wallet invite code: 4040U. After binding, fees are reduced by 30% or 点击这里一键绑定
Because three people (Dario Amodei (Anthropic CEO), Sam Altman (OpenAI CEO), and Elon Musk (Tesla / former OpenAI co-founder)) announced that they want to slow down the development pace of AI.
But over the same weekend, Chairman Choi, the head of SK Group, said they plan to push their largest HBM production hub in the expanded Ulsan data center to 900 megawatts. This project is being built together with AWS (Amazon Cloud); they invested 70 trillion KRW, about $5.2 billion, and it’s expected to go operational in the second half of 2027. Step one more, and this center will reach 1 gigawatt.
So right now, the guys who make hardware are all doubling down—only these guys who supply the money for hardware say they want to slow it down a bit.
Suddenly I thought: are these people who spend money every day getting angry? Then they’re like, ‘Let’s talk it over. Let’s scare those storage-selling guys.’ The idea is: ‘We want to slow down. We don’t want to play anymore.’ That kind of feeling—trying to scare them, like this Mr. Lee and Chairman Choi.
But obviously it didn’t scare them, because they think you’ll just split the spoils unevenly later and come back to buy—so they directly accelerated their investment plans.
#英伟达洽谈至多100亿美元投资Anthropic
A method to save on trading fees!
Why bind an invite code? Very simple—save money long-term.
Binance Wallet invite code: 4040U. After binding, fees are reduced by 30% or 点击这里一键绑定
88
·
--
#美国10年期国债收益率逼近5% Trump just responded to whether there will be a rate hike next week. He said he doesn’t know whether they will raise rates, but the U.S. will keep global minimum interest rates. And right now, global minimum interest rates are in Switzerland—almost 0%.
So now your rate in the U.S. is 3.75%—does that imply that in the future rates will be cut down to 0%?
Is it really good for global gold and silver, as well as global tech? #英伟达洽谈至多100亿美元投资Anthropic
Ways to save on trading fees!
Why bind an invitation code? It’s simple—save money long-term.
Binance Wallet invitation code: 4040U. After binding, trading fees get reduced by 30%, or use [点击这里一键绑定](https://web3.binance.com/referral?ref=4040U)
#美国10年期国债收益率逼近5% Trump just responded to whether there will be a rate hike next week. He said he doesn’t know whether they will raise rates, but the U.S. will keep global minimum interest rates. And right now, global minimum interest rates are in Switzerland—almost 0%.
So now your rate in the U.S. is 3.75%—does that imply that in the future rates will be cut down to 0%?
Is it really good for global gold and silver, as well as global tech? #英伟达洽谈至多100亿美元投资Anthropic
Ways to save on trading fees!
Why bind an invitation code? It’s simple—save money long-term.
Binance Wallet invitation code: 4040U. After binding, trading fees get reduced by 30%, or use 点击这里一键绑定
So now your rate in the U.S. is 3.75%—does that imply that in the future rates will be cut down to 0%?
Is it really good for global gold and silver, as well as global tech? #英伟达洽谈至多100亿美元投资Anthropic
Ways to save on trading fees!
Why bind an invitation code? It’s simple—save money long-term.
Binance Wallet invitation code: 4040U. After binding, trading fees get reduced by 30%, or use 点击这里一键绑定
193
·
--
Gold $XAU says something—what I mean is, it got hammered down to the lowest level because of the interest-rate-hike probability, with the number starting “42…” On Friday it already bounced back to 4390, and there’s a pretty good chance that by the end of the year it will still trend upward.
So you’ve got to say, “end of year”? That’s nonsense—at year-end, they increase by 25 basis points to start with. Maybe even 50—how could that be possible?
Whether it’s +25 or +50, as long as the expectations before the hike stay stable, then it won’t be the kind of scary, unpredictable surprise factor anymore. And for example, Goldman Sachs’ year-end target still looks like 4900, and there are also international investment banks giving year-end targets as high as 5000.
Also, one more thing: if you’re buying gold—or you don’t want to buy gold, that’s fine. Central banks around the world are buying. The central bank—our mom—has been buying for 22 straight months.
And later, the single purchase amounts have been getting larger. The expectation for rate hikes has already been priced in to 90%. Once it’s confirmed that they will indeed hike—buy the expectation and sell the actual news—then it’s basically like the shorts/longs that were liquidated earlier are cleared out at this time point.
Goldman Sachs’ strategy: they previously said that right before the policy decision meeting, under the maximum uncertainty, the downside could be driven to the 4000s, around the low-4000s.
Then they keep a year-end target of 4900, and the target stays the same, right? #美国10年期国债收益率逼近5%
A way to save on trading fees!
Why bind an invitation code? It’s simple—save money long-term.
Binance Wallet invitation code: 4040U. After binding, fees get reduced by 30%, or [点击这里一键绑定](https://web3.binance.com/referral?ref=4040U)
Gold $XAU says something—what I mean is, it got hammered down to the lowest level because of the interest-rate-hike probability, with the number starting “42…” On Friday it already bounced back to 4390, and there’s a pretty good chance that by the end of the year it will still trend upward.
So you’ve got to say, “end of year”? That’s nonsense—at year-end, they increase by 25 basis points to start with. Maybe even 50—how could that be possible?
Whether it’s +25 or +50, as long as the expectations before the hike stay stable, then it won’t be the kind of scary, unpredictable surprise factor anymore. And for example, Goldman Sachs’ year-end target still looks like 4900, and there are also international investment banks giving year-end targets as high as 5000.
Also, one more thing: if you’re buying gold—or you don’t want to buy gold, that’s fine. Central banks around the world are buying. The central bank—our mom—has been buying for 22 straight months.
And later, the single purchase amounts have been getting larger. The expectation for rate hikes has already been priced in to 90%. Once it’s confirmed that they will indeed hike—buy the expectation and sell the actual news—then it’s basically like the shorts/longs that were liquidated earlier are cleared out at this time point.
Goldman Sachs’ strategy: they previously said that right before the policy decision meeting, under the maximum uncertainty, the downside could be driven to the 4000s, around the low-4000s.
Then they keep a year-end target of 4900, and the target stays the same, right? #美国10年期国债收益率逼近5%
A way to save on trading fees!
Why bind an invitation code? It’s simple—save money long-term.
Binance Wallet invitation code: 4040U. After binding, fees get reduced by 30%, or 点击这里一键绑定
So you’ve got to say, “end of year”? That’s nonsense—at year-end, they increase by 25 basis points to start with. Maybe even 50—how could that be possible?
Whether it’s +25 or +50, as long as the expectations before the hike stay stable, then it won’t be the kind of scary, unpredictable surprise factor anymore. And for example, Goldman Sachs’ year-end target still looks like 4900, and there are also international investment banks giving year-end targets as high as 5000.
Also, one more thing: if you’re buying gold—or you don’t want to buy gold, that’s fine. Central banks around the world are buying. The central bank—our mom—has been buying for 22 straight months.
And later, the single purchase amounts have been getting larger. The expectation for rate hikes has already been priced in to 90%. Once it’s confirmed that they will indeed hike—buy the expectation and sell the actual news—then it’s basically like the shorts/longs that were liquidated earlier are cleared out at this time point.
Goldman Sachs’ strategy: they previously said that right before the policy decision meeting, under the maximum uncertainty, the downside could be driven to the 4000s, around the low-4000s.
Then they keep a year-end target of 4900, and the target stays the same, right? #美国10年期国债收益率逼近5%
A way to save on trading fees!
Why bind an invitation code? It’s simple—save money long-term.
Binance Wallet invitation code: 4040U. After binding, fees get reduced by 30%, or 点击这里一键绑定
156
·
--
There’s no need to announce anything next week—we’re in the midst of the Super Central Bank week, and all eyes are on Powell.
The market is currently pricing in a 90% probability of the Fed rate hike on September 16. Traders are expecting it, but even so, nobody dares to say it for sure.
For example, in the July meeting, wasn’t it a 9-3 decision to hold steady?
Three dissenting votes were calling for a rate hike, right?
So this time, if a rate hike actually happens, you’d need that 9-3 to shift into the rate-hike camp—meaning you’d need four more votes. In fact, it still requires a certain number of people to change their minds. I think, yes, 90% is meant to reassure everyone, right? So the market won’t be afraid, right?
It’s that kind of tone—like, “Alright, good boy, don’t panic.” It’s basically telling you to note down the worst-case scenario first.
But if at the time it turns out he doesn’t hike—using various reasons, for instance if some Fed chairperson steps in from here and says a few words, then those expectations get corrected again.
That would mean a big rally. It’s just that even if there is a hike, people can still accept it right now—that’s basically the game, right? That’s how the Fed plays it. And even as of now, Goldman Sachs is still saying there could be a hike—“Highly unlikely.” They say it’s still possible to hike again by the end of the year in December; we’ll see then. In any case, it’s early Thursday morning.
A way to save on trading fees!
Why link an invitation code? It’s simple—save money long-term.
Binance Wallet invitation code: 4040U, after linking, trading fees reduced by 30% or [点击这里一键绑定](https://web3.binance.com/referral?ref=4040U)
There’s no need to announce anything next week—we’re in the midst of the Super Central Bank week, and all eyes are on Powell.
The market is currently pricing in a 90% probability of the Fed rate hike on September 16. Traders are expecting it, but even so, nobody dares to say it for sure.
For example, in the July meeting, wasn’t it a 9-3 decision to hold steady?
Three dissenting votes were calling for a rate hike, right?
So this time, if a rate hike actually happens, you’d need that 9-3 to shift into the rate-hike camp—meaning you’d need four more votes. In fact, it still requires a certain number of people to change their minds. I think, yes, 90% is meant to reassure everyone, right? So the market won’t be afraid, right?
It’s that kind of tone—like, “Alright, good boy, don’t panic.” It’s basically telling you to note down the worst-case scenario first.
But if at the time it turns out he doesn’t hike—using various reasons, for instance if some Fed chairperson steps in from here and says a few words, then those expectations get corrected again.
That would mean a big rally. It’s just that even if there is a hike, people can still accept it right now—that’s basically the game, right? That’s how the Fed plays it. And even as of now, Goldman Sachs is still saying there could be a hike—“Highly unlikely.” They say it’s still possible to hike again by the end of the year in December; we’ll see then. In any case, it’s early Thursday morning.
A way to save on trading fees!
Why link an invitation code? It’s simple—save money long-term.
Binance Wallet invitation code: 4040U, after linking, trading fees reduced by 30% or 点击这里一键绑定
The market is currently pricing in a 90% probability of the Fed rate hike on September 16. Traders are expecting it, but even so, nobody dares to say it for sure.
For example, in the July meeting, wasn’t it a 9-3 decision to hold steady?
Three dissenting votes were calling for a rate hike, right?
So this time, if a rate hike actually happens, you’d need that 9-3 to shift into the rate-hike camp—meaning you’d need four more votes. In fact, it still requires a certain number of people to change their minds. I think, yes, 90% is meant to reassure everyone, right? So the market won’t be afraid, right?
It’s that kind of tone—like, “Alright, good boy, don’t panic.” It’s basically telling you to note down the worst-case scenario first.
But if at the time it turns out he doesn’t hike—using various reasons, for instance if some Fed chairperson steps in from here and says a few words, then those expectations get corrected again.
That would mean a big rally. It’s just that even if there is a hike, people can still accept it right now—that’s basically the game, right? That’s how the Fed plays it. And even as of now, Goldman Sachs is still saying there could be a hike—“Highly unlikely.” They say it’s still possible to hike again by the end of the year in December; we’ll see then. In any case, it’s early Thursday morning.
A way to save on trading fees!
Why link an invitation code? It’s simple—save money long-term.
Binance Wallet invitation code: 4040U, after linking, trading fees reduced by 30% or 点击这里一键绑定
115
·
--
#OpenAI推出智能体API公测 On September 10, 2026 (U.S. time), OpenAI announced that the Agents API has entered public beta, followed by concentrated reporting in China on September 11. This interface opens up the “harness” that supports Codex and the Enterprise ChatGPT to all developers. With a single call, users can create long-running intelligent agents. OpenAI will host the session, perform context compression, handle tool orchestration, coordinate sub-agents, and provide sandboxing. Billing is based only on tokens and tool calls.
The main reason is that long-task agent engineering is too heavy: enterprises need cross-hour and cross-day automation, which requires self-managed state, recovery, file execution, and multi-agent collaboration—leading to high costs and poor stability. OpenAI productized its internal Codex execution infrastructure, lowering the development barrier, and shifting from “selling model APIs” to “selling agent runtime capabilities.”
Higher agent usage volumes directly benefit reasoning compute and cloud services: Nvidia (NVDA)📈 and Microsoft (MSFT), leveraging Azure and the OpenAI ecosystem📈; enterprises’ data orchestration stands to benefit as well, which can be seen in PLTR📈. On the Korea side, increased needs for long context and high-bandwidth storage drive demand for Samsung Electronics and SK hynix📈. In the short term, if public beta expands the developer base, the compute, cloud, and storage supply chain could see more upside; however, restrictions such as usage-based pricing, data compliance, and U.S.-region data residency may suppress the performance of pure concept stocks. Some richly valued agent-related ideas may correct📉.
Over the medium to long term, agent standardization will amplify demand for reasoning tokens, HBM, and enterprise automation, supporting NVDA, MSFT, Samsung Electronics, SK hynix, and PLTR overall📈. The risks are slower monetization, price wars, and valuation pullbacks. For concept stocks with high volatility, it’s advisable to buy in batches rather than chasing gains.
$NVDA
{future}(NVDAUSDT)
$SAMSUNG
{future}(SAMSUNGUSDT)
$SKHYNIX
{future}(SKHYNIXUSDT)
#OpenAI推出智能体API公测 On September 10, 2026 (U.S. time), OpenAI announced that the Agents API has entered public beta, followed by concentrated reporting in China on September 11. This interface opens up the “harness” that supports Codex and the Enterprise ChatGPT to all developers. With a single call, users can create long-running intelligent agents. OpenAI will host the session, perform context compression, handle tool orchestration, coordinate sub-agents, and provide sandboxing. Billing is based only on tokens and tool calls.
The main reason is that long-task agent engineering is too heavy: enterprises need cross-hour and cross-day automation, which requires self-managed state, recovery, file execution, and multi-agent collaboration—leading to high costs and poor stability. OpenAI productized its internal Codex execution infrastructure, lowering the development barrier, and shifting from “selling model APIs” to “selling agent runtime capabilities.”
Higher agent usage volumes directly benefit reasoning compute and cloud services: Nvidia (NVDA)📈 and Microsoft (MSFT), leveraging Azure and the OpenAI ecosystem📈; enterprises’ data orchestration stands to benefit as well, which can be seen in PLTR📈. On the Korea side, increased needs for long context and high-bandwidth storage drive demand for Samsung Electronics and SK hynix📈. In the short term, if public beta expands the developer base, the compute, cloud, and storage supply chain could see more upside; however, restrictions such as usage-based pricing, data compliance, and U.S.-region data residency may suppress the performance of pure concept stocks. Some richly valued agent-related ideas may correct📉.
Over the medium to long term, agent standardization will amplify demand for reasoning tokens, HBM, and enterprise automation, supporting NVDA, MSFT, Samsung Electronics, SK hynix, and PLTR overall📈. The risks are slower monetization, price wars, and valuation pullbacks. For concept stocks with high volatility, it’s advisable to buy in batches rather than chasing gains.
$NVDA
$SAMSUNG
$SKHYNIX
The main reason is that long-task agent engineering is too heavy: enterprises need cross-hour and cross-day automation, which requires self-managed state, recovery, file execution, and multi-agent collaboration—leading to high costs and poor stability. OpenAI productized its internal Codex execution infrastructure, lowering the development barrier, and shifting from “selling model APIs” to “selling agent runtime capabilities.”
Higher agent usage volumes directly benefit reasoning compute and cloud services: Nvidia (NVDA)📈 and Microsoft (MSFT), leveraging Azure and the OpenAI ecosystem📈; enterprises’ data orchestration stands to benefit as well, which can be seen in PLTR📈. On the Korea side, increased needs for long context and high-bandwidth storage drive demand for Samsung Electronics and SK hynix📈. In the short term, if public beta expands the developer base, the compute, cloud, and storage supply chain could see more upside; however, restrictions such as usage-based pricing, data compliance, and U.S.-region data residency may suppress the performance of pure concept stocks. Some richly valued agent-related ideas may correct📉.
Over the medium to long term, agent standardization will amplify demand for reasoning tokens, HBM, and enterprise automation, supporting NVDA, MSFT, Samsung Electronics, SK hynix, and PLTR overall📈. The risks are slower monetization, price wars, and valuation pullbacks. For concept stocks with high volatility, it’s advisable to buy in batches rather than chasing gains.
$NVDA
$SAMSUNG
$SKHYNIX
38
·
--
#Circle拟4亿美元收购Tazapay Circle officially announced on September 8, 2026 that it has signed the final agreement. It plans to acquire Singapore B2B cross-border payments provider Tazapay in an all-stock deal worth approximately USD 400 million, with delivery expected in 2027. The deal still requires regulatory approvals, including from the Monetary Authority of Singapore (MAS). Tazapay’s annualized payment volume exceeds USD 25 billion, connects with more than 60 banks/financial technology partners, and covers over 100 markets. About 60% of transactions involve stablecoins. It also comes with licenses in Singapore, the U.S., Canada, and Australia, and serves as the “last-mile infrastructure” for USDC: from on-chain transfers to local fiat cash-outs.
On-chain USDC settlement is fast, but businesses often still need to land payments into local-currency accounts. Building separate bank rails in each country, obtaining licenses, and ensuring compliance is too slow. Buying Tazapay is essentially a one-time way to complete Circle Payments Network’s local clearing capabilities and provide access to institutional customers. Since 2025, it has been a design partner of CPN. Circle Ventures previously led its Series B round; the investment has since turned into full ownership, resulting in lower collaboration costs. As demand for U.S. dollar stablecoin payments rises in Asia-Pacific, Latin America, and emerging Middle Eastern markets, Circle is effectively trading equity for time, licenses, and distribution networks. It is also positioning to benchmark tokenized clearing and settlement like Visa (V) stablecoin cards and Mastercard (MA) tokenized settlement, defending against competition from cross-border solutions such as Ripple.
Near term, the all-stock consideration is exchanged for shares at the weighted average price of the 20 trading days prior to closing, creating dilution expectations. After the announcement, CRCL fell about 5.8% to $96.18. Investor sentiment has been weighed down by concerns over MAS approval, uncertainty around employee retention, and unclear Tazapay revenue. 📉 If the consolidation goes smoothly in 2027 and USDC transaction volume plus CPN fee conversions translate as expected, CRCL will be a long-term positive. 📈 Visa V is likely neutral-to-slightly bullish, supported by incremental stablecoin clearing/settlement demand. 📈 If Kakao Bank in South Korea integrates a stablecoin-to-fiat rails and handles B2B cash register payments, it could be a regionally flexible play. However, volatility is likely high before regulatory implementation. 📉
$CRCL
{future}(CRCLUSDT)
#Circle拟4亿美元收购Tazapay Circle officially announced on September 8, 2026 that it has signed the final agreement. It plans to acquire Singapore B2B cross-border payments provider Tazapay in an all-stock deal worth approximately USD 400 million, with delivery expected in 2027. The deal still requires regulatory approvals, including from the Monetary Authority of Singapore (MAS). Tazapay’s annualized payment volume exceeds USD 25 billion, connects with more than 60 banks/financial technology partners, and covers over 100 markets. About 60% of transactions involve stablecoins. It also comes with licenses in Singapore, the U.S., Canada, and Australia, and serves as the “last-mile infrastructure” for USDC: from on-chain transfers to local fiat cash-outs.
On-chain USDC settlement is fast, but businesses often still need to land payments into local-currency accounts. Building separate bank rails in each country, obtaining licenses, and ensuring compliance is too slow. Buying Tazapay is essentially a one-time way to complete Circle Payments Network’s local clearing capabilities and provide access to institutional customers. Since 2025, it has been a design partner of CPN. Circle Ventures previously led its Series B round; the investment has since turned into full ownership, resulting in lower collaboration costs. As demand for U.S. dollar stablecoin payments rises in Asia-Pacific, Latin America, and emerging Middle Eastern markets, Circle is effectively trading equity for time, licenses, and distribution networks. It is also positioning to benchmark tokenized clearing and settlement like Visa (V) stablecoin cards and Mastercard (MA) tokenized settlement, defending against competition from cross-border solutions such as Ripple.
Near term, the all-stock consideration is exchanged for shares at the weighted average price of the 20 trading days prior to closing, creating dilution expectations. After the announcement, CRCL fell about 5.8% to $96.18. Investor sentiment has been weighed down by concerns over MAS approval, uncertainty around employee retention, and unclear Tazapay revenue. 📉 If the consolidation goes smoothly in 2027 and USDC transaction volume plus CPN fee conversions translate as expected, CRCL will be a long-term positive. 📈 Visa V is likely neutral-to-slightly bullish, supported by incremental stablecoin clearing/settlement demand. 📈 If Kakao Bank in South Korea integrates a stablecoin-to-fiat rails and handles B2B cash register payments, it could be a regionally flexible play. However, volatility is likely high before regulatory implementation. 📉
$CRCL
On-chain USDC settlement is fast, but businesses often still need to land payments into local-currency accounts. Building separate bank rails in each country, obtaining licenses, and ensuring compliance is too slow. Buying Tazapay is essentially a one-time way to complete Circle Payments Network’s local clearing capabilities and provide access to institutional customers. Since 2025, it has been a design partner of CPN. Circle Ventures previously led its Series B round; the investment has since turned into full ownership, resulting in lower collaboration costs. As demand for U.S. dollar stablecoin payments rises in Asia-Pacific, Latin America, and emerging Middle Eastern markets, Circle is effectively trading equity for time, licenses, and distribution networks. It is also positioning to benchmark tokenized clearing and settlement like Visa (V) stablecoin cards and Mastercard (MA) tokenized settlement, defending against competition from cross-border solutions such as Ripple.
Near term, the all-stock consideration is exchanged for shares at the weighted average price of the 20 trading days prior to closing, creating dilution expectations. After the announcement, CRCL fell about 5.8% to $96.18. Investor sentiment has been weighed down by concerns over MAS approval, uncertainty around employee retention, and unclear Tazapay revenue. 📉 If the consolidation goes smoothly in 2027 and USDC transaction volume plus CPN fee conversions translate as expected, CRCL will be a long-term positive. 📈 Visa V is likely neutral-to-slightly bullish, supported by incremental stablecoin clearing/settlement demand. 📈 If Kakao Bank in South Korea integrates a stablecoin-to-fiat rails and handles B2B cash register payments, it could be a regionally flexible play. However, volatility is likely high before regulatory implementation. 📉
$CRCL
35
·
--
#美国8月通胀维持3.4% The U.S. Bureau of Labor Statistics released on September 11, 2026 local time: August CPI held steady year over year at 3.4%, in line with the prior reading. On a month-over-month basis, it rose 0.4%, the fastest in the past three months. Core CPI was up 2.4% year over year and 0.3% month over month, both above expectations. Overall year-over-year “stability” was mainly supported by base effects, but the pressure from monthly price increases has clearly warmed back up.
The drivers break down into three areas: First, energy boosted prices. In August, the energy index rose 2.1% month over month; gasoline was up 3.9%. Gasoline alone contributed more than one-third of the overall increase. The main cause was the upward move in geopolitical-driven oil prices. Second, housing remained resilient. Housing rose 0.3% month over month; equivalent rents for tenants and owners were each up 0.2%. Hotel stays rebounded 2.4%. Third, core services broadened. Communications rose 2.3% month over month, airline tickets were up 2.7%, and education increased 0.8%. A pullback in medical care and auto insurance partially offset these gains. The core month-over-month result beating expectations led the market to push the probability of a September rate hike by the Federal Reserve to roughly 86%—90%.
On the energy side, Exxon Mobil XOM benefited from oil prices and refining margin support, with a short-term 📈 outlook and a medium-term 📈 outlook. Overvalued growth tech is restrained by higher discount rates; Nvidia NVDA is down in the short term 📉, but AI compute and data centers over the long run still look 📈.
In Korea’s stock market, memory is supported by AI-related capital expenditures. SK hynix (SK海力士) faces near-term pressure from interest-rate volatility 📉 but a long-term upside 📈. Samsung Electronics’ memory/HBM cycle is repairing—short-term 📉, long-term 📈.
Overall, in the near term, core month-over-month rebounds and rate-hike pricing mean high-valuation stocks and semiconductors are likely to remain choppy and pull back 📉; energy and AI hardware supply-side factors are relatively supportive 📈. In the medium to long run, if energy stabilizes and AI demand is realized, high-quality compute and storage should still do well 📈, while rate-sensitive consumer tech should be approached cautiously 📉.
$NVDA
{future}(NVDAUSDT)
$SAMSUNG
{future}(SAMSUNGUSDT)
$SKHYNIX
{future}(SKHYNIXUSDT)
#美国8月通胀维持3.4% The U.S. Bureau of Labor Statistics released on September 11, 2026 local time: August CPI held steady year over year at 3.4%, in line with the prior reading. On a month-over-month basis, it rose 0.4%, the fastest in the past three months. Core CPI was up 2.4% year over year and 0.3% month over month, both above expectations. Overall year-over-year “stability” was mainly supported by base effects, but the pressure from monthly price increases has clearly warmed back up.
The drivers break down into three areas: First, energy boosted prices. In August, the energy index rose 2.1% month over month; gasoline was up 3.9%. Gasoline alone contributed more than one-third of the overall increase. The main cause was the upward move in geopolitical-driven oil prices. Second, housing remained resilient. Housing rose 0.3% month over month; equivalent rents for tenants and owners were each up 0.2%. Hotel stays rebounded 2.4%. Third, core services broadened. Communications rose 2.3% month over month, airline tickets were up 2.7%, and education increased 0.8%. A pullback in medical care and auto insurance partially offset these gains. The core month-over-month result beating expectations led the market to push the probability of a September rate hike by the Federal Reserve to roughly 86%—90%.
On the energy side, Exxon Mobil XOM benefited from oil prices and refining margin support, with a short-term 📈 outlook and a medium-term 📈 outlook. Overvalued growth tech is restrained by higher discount rates; Nvidia NVDA is down in the short term 📉, but AI compute and data centers over the long run still look 📈.
In Korea’s stock market, memory is supported by AI-related capital expenditures. SK hynix (SK海力士) faces near-term pressure from interest-rate volatility 📉 but a long-term upside 📈. Samsung Electronics’ memory/HBM cycle is repairing—short-term 📉, long-term 📈.
Overall, in the near term, core month-over-month rebounds and rate-hike pricing mean high-valuation stocks and semiconductors are likely to remain choppy and pull back 📉; energy and AI hardware supply-side factors are relatively supportive 📈. In the medium to long run, if energy stabilizes and AI demand is realized, high-quality compute and storage should still do well 📈, while rate-sensitive consumer tech should be approached cautiously 📉.
$NVDA
$SAMSUNG
$SKHYNIX
The drivers break down into three areas: First, energy boosted prices. In August, the energy index rose 2.1% month over month; gasoline was up 3.9%. Gasoline alone contributed more than one-third of the overall increase. The main cause was the upward move in geopolitical-driven oil prices. Second, housing remained resilient. Housing rose 0.3% month over month; equivalent rents for tenants and owners were each up 0.2%. Hotel stays rebounded 2.4%. Third, core services broadened. Communications rose 2.3% month over month, airline tickets were up 2.7%, and education increased 0.8%. A pullback in medical care and auto insurance partially offset these gains. The core month-over-month result beating expectations led the market to push the probability of a September rate hike by the Federal Reserve to roughly 86%—90%.
On the energy side, Exxon Mobil XOM benefited from oil prices and refining margin support, with a short-term 📈 outlook and a medium-term 📈 outlook. Overvalued growth tech is restrained by higher discount rates; Nvidia NVDA is down in the short term 📉, but AI compute and data centers over the long run still look 📈.
In Korea’s stock market, memory is supported by AI-related capital expenditures. SK hynix (SK海力士) faces near-term pressure from interest-rate volatility 📉 but a long-term upside 📈. Samsung Electronics’ memory/HBM cycle is repairing—short-term 📉, long-term 📈.
Overall, in the near term, core month-over-month rebounds and rate-hike pricing mean high-valuation stocks and semiconductors are likely to remain choppy and pull back 📉; energy and AI hardware supply-side factors are relatively supportive 📈. In the medium to long run, if energy stabilizes and AI demand is realized, high-quality compute and storage should still do well 📈, while rate-sensitive consumer tech should be approached cautiously 📉.
$NVDA
$SAMSUNG
$SKHYNIX
33
·
--
#CPI数据来袭能否触发9月加息 U.S. August CPI to be released on September 11, followed immediately by the Fed’s FOMC policy meeting on September 15–16—this is the latest checkpoint for whether CPI can trigger a September rate hike. Overall CPI year over year is 3.4% and month over month 0.4%, in line with expectations; however, core CPI month over month is 0.3%, above the expected 0.2%, the strongest since April. The CME FedWatch implied probability of a 25-basis-point hike jumped from about 70% before the data to 87%–90%.
The main driver of the price increases is sticky energy and services: gasoline up 3.9% month over month, and energy up 16.3% year over year. The Middle East situation has pushed up oil prices; PPI up 5.4% year over year and 0.4% month over month feeds into CPI. Tariffs, AI data center spending, and low unemployment together form a “supply shock + demand that isn’t weakening.” These costs can’t be fully crushed by rate hikes alone, but core inflation coming in hotter than expected will force the Fed to protect its credibility and prevent inflation expectations from becoming unanchored.
At the individual-stock level, near-term repricing from higher interest rates is negative for duration-heavy growth: Nvidia (NVDA)📉, Apple (AAPL)📉, and META📉—especially NVDA, which is most sensitive to discount rates. In South Korea, Samsung Electronics and Hyundai Motor are a double-edged sword: a weaker won is a tailwind for export earnings (📈), but domestic rate hikes weigh on consumption and auto loans (📉). If oil prices stay elevated, semiconductor capex in the medium to long term remains strong—Samsung and NVDA look 📈 over the next 6–12 months. AAPL and META rely on cash flow and ad resilience, so after a pullback they look 📈 over the medium to long term. Hyundai is squeezed from both sides by oil prices and interest rates: short term 📉, but if oil prices fall then 📈.
This CPI looks more like a trigger for a September rate hike than a signal to seek safety. In the short run, global tech stocks may churn lower (📉); energy-related and export-earnings FX-beneficiary stocks have relatively better returns. Over the medium to long term, AI semiconductors remain more inclined to rise (📈), but “higher for longer” rates will slow the pace of valuation expansion.
$NVDA
{future}(NVDAUSDT)
$SAMSUNG
{future}(SAMSUNGUSDT)
$SKHYNIX
{future}(SKHYNIXUSDT)
#CPI数据来袭能否触发9月加息 U.S. August CPI to be released on September 11, followed immediately by the Fed’s FOMC policy meeting on September 15–16—this is the latest checkpoint for whether CPI can trigger a September rate hike. Overall CPI year over year is 3.4% and month over month 0.4%, in line with expectations; however, core CPI month over month is 0.3%, above the expected 0.2%, the strongest since April. The CME FedWatch implied probability of a 25-basis-point hike jumped from about 70% before the data to 87%–90%.
The main driver of the price increases is sticky energy and services: gasoline up 3.9% month over month, and energy up 16.3% year over year. The Middle East situation has pushed up oil prices; PPI up 5.4% year over year and 0.4% month over month feeds into CPI. Tariffs, AI data center spending, and low unemployment together form a “supply shock + demand that isn’t weakening.” These costs can’t be fully crushed by rate hikes alone, but core inflation coming in hotter than expected will force the Fed to protect its credibility and prevent inflation expectations from becoming unanchored.
At the individual-stock level, near-term repricing from higher interest rates is negative for duration-heavy growth: Nvidia (NVDA)📉, Apple (AAPL)📉, and META📉—especially NVDA, which is most sensitive to discount rates. In South Korea, Samsung Electronics and Hyundai Motor are a double-edged sword: a weaker won is a tailwind for export earnings (📈), but domestic rate hikes weigh on consumption and auto loans (📉). If oil prices stay elevated, semiconductor capex in the medium to long term remains strong—Samsung and NVDA look 📈 over the next 6–12 months. AAPL and META rely on cash flow and ad resilience, so after a pullback they look 📈 over the medium to long term. Hyundai is squeezed from both sides by oil prices and interest rates: short term 📉, but if oil prices fall then 📈.
This CPI looks more like a trigger for a September rate hike than a signal to seek safety. In the short run, global tech stocks may churn lower (📉); energy-related and export-earnings FX-beneficiary stocks have relatively better returns. Over the medium to long term, AI semiconductors remain more inclined to rise (📈), but “higher for longer” rates will slow the pace of valuation expansion.
$NVDA
$SAMSUNG
$SKHYNIX
The main driver of the price increases is sticky energy and services: gasoline up 3.9% month over month, and energy up 16.3% year over year. The Middle East situation has pushed up oil prices; PPI up 5.4% year over year and 0.4% month over month feeds into CPI. Tariffs, AI data center spending, and low unemployment together form a “supply shock + demand that isn’t weakening.” These costs can’t be fully crushed by rate hikes alone, but core inflation coming in hotter than expected will force the Fed to protect its credibility and prevent inflation expectations from becoming unanchored.
At the individual-stock level, near-term repricing from higher interest rates is negative for duration-heavy growth: Nvidia (NVDA)📉, Apple (AAPL)📉, and META📉—especially NVDA, which is most sensitive to discount rates. In South Korea, Samsung Electronics and Hyundai Motor are a double-edged sword: a weaker won is a tailwind for export earnings (📈), but domestic rate hikes weigh on consumption and auto loans (📉). If oil prices stay elevated, semiconductor capex in the medium to long term remains strong—Samsung and NVDA look 📈 over the next 6–12 months. AAPL and META rely on cash flow and ad resilience, so after a pullback they look 📈 over the medium to long term. Hyundai is squeezed from both sides by oil prices and interest rates: short term 📉, but if oil prices fall then 📈.
This CPI looks more like a trigger for a September rate hike than a signal to seek safety. In the short run, global tech stocks may churn lower (📉); energy-related and export-earnings FX-beneficiary stocks have relatively better returns. Over the medium to long term, AI semiconductors remain more inclined to rise (📈), but “higher for longer” rates will slow the pace of valuation expansion.
$NVDA
$SAMSUNG
$SKHYNIX
20
·
--
#BNB涨破730美元 BNB price surges strongly, breaking through the $730 mark; the latest quote is approaching $760, reaching a six-month high. This breakout occurred in early September 2026.
The core reasons driving this round of gains are: first, the bullish regulatory and compliance news—U.S. prediction market platform Kalshi has launched CFTC-regulated BNB perpetual futures, providing a compliant trading channel for U.S. traders; second, BNB Chain’s fundamentals are solid. The Lorentz hard fork upgrade has reduced Gas fees, and the on-chain real-world assets (RWA) and tokenized stock market continue to expand; in addition, overall market sentiment has improved. BTC and ETH stabilizing has encouraged capital rotation, while technical indicators breaking through multiple moving-average resistance levels has attracted momentum-driven funds to follow and buy. Meanwhile, major coins such as SOL and ZEC are also seeing broad-based gains 📈.
Looking ahead, in the short term, BNB has broken through the $740–$760 resistance zone. The RSI has entered an overbought range, and $730 has turned into a strong support level. Investors should be alert to a technical pullback caused by profit-taking 📉. In the medium to long term, as compliance channels expand and the ecosystem’s deflationary burn mechanism progresses, there are clear signs of institutional accumulation. The overall trend still leans bullish 📈.
$BTC
{future}(BTCUSDT)
$ETH
{future}(ETHUSDT)
$BNB
{future}(BNBUSDT)
#BNB涨破730美元 BNB price surges strongly, breaking through the $730 mark; the latest quote is approaching $760, reaching a six-month high. This breakout occurred in early September 2026.
The core reasons driving this round of gains are: first, the bullish regulatory and compliance news—U.S. prediction market platform Kalshi has launched CFTC-regulated BNB perpetual futures, providing a compliant trading channel for U.S. traders; second, BNB Chain’s fundamentals are solid. The Lorentz hard fork upgrade has reduced Gas fees, and the on-chain real-world assets (RWA) and tokenized stock market continue to expand; in addition, overall market sentiment has improved. BTC and ETH stabilizing has encouraged capital rotation, while technical indicators breaking through multiple moving-average resistance levels has attracted momentum-driven funds to follow and buy. Meanwhile, major coins such as SOL and ZEC are also seeing broad-based gains 📈.
Looking ahead, in the short term, BNB has broken through the $740–$760 resistance zone. The RSI has entered an overbought range, and $730 has turned into a strong support level. Investors should be alert to a technical pullback caused by profit-taking 📉. In the medium to long term, as compliance channels expand and the ecosystem’s deflationary burn mechanism progresses, there are clear signs of institutional accumulation. The overall trend still leans bullish 📈.
$BTC
$ETH
$BNB
The core reasons driving this round of gains are: first, the bullish regulatory and compliance news—U.S. prediction market platform Kalshi has launched CFTC-regulated BNB perpetual futures, providing a compliant trading channel for U.S. traders; second, BNB Chain’s fundamentals are solid. The Lorentz hard fork upgrade has reduced Gas fees, and the on-chain real-world assets (RWA) and tokenized stock market continue to expand; in addition, overall market sentiment has improved. BTC and ETH stabilizing has encouraged capital rotation, while technical indicators breaking through multiple moving-average resistance levels has attracted momentum-driven funds to follow and buy. Meanwhile, major coins such as SOL and ZEC are also seeing broad-based gains 📈.
Looking ahead, in the short term, BNB has broken through the $740–$760 resistance zone. The RSI has entered an overbought range, and $730 has turned into a strong support level. Investors should be alert to a technical pullback caused by profit-taking 📉. In the medium to long term, as compliance channels expand and the ecosystem’s deflationary burn mechanism progresses, there are clear signs of institutional accumulation. The overall trend still leans bullish 📈.
$BTC
$ETH
$BNB
113
·
--
On September 11, #美国8月通胀维持3.4% 2026, the U.S. Bureau of Labor Statistics released the latest data showing that CPI in August rose 3.4% year over year, unchanged from July.
The elevated inflation was mainly driven by a sharp rebound in energy prices, with gasoline prices jumping 3.9% month over month and contributing more than one-third of the increase. At the same time, housing and services inflation remained resilient, compounded by concerns over crude oil supply triggered by tensions in the Middle East. After the data was released, expectations for a Fed rate hike in September surged.
Expectations of macro tightening have put pressure on the crypto market. In the short term, tighter liquidity is weighing on risk appetite, and the outlook for major coins such as BTC, ETH, BNB, SOL, and ZEC is bearish 📉. But in the long term, fiat currency depreciation and sticky inflation will strengthen crypto assets’ censorship resistance and value-preservation properties, so the long-term outlook remains bullish 📈.
$BTC
{future}(BTCUSDT)
$ETH
{future}(ETHUSDT)
$BNB
{future}(BNBUSDT)
On September 11, #美国8月通胀维持3.4% 2026, the U.S. Bureau of Labor Statistics released the latest data showing that CPI in August rose 3.4% year over year, unchanged from July.
The elevated inflation was mainly driven by a sharp rebound in energy prices, with gasoline prices jumping 3.9% month over month and contributing more than one-third of the increase. At the same time, housing and services inflation remained resilient, compounded by concerns over crude oil supply triggered by tensions in the Middle East. After the data was released, expectations for a Fed rate hike in September surged.
Expectations of macro tightening have put pressure on the crypto market. In the short term, tighter liquidity is weighing on risk appetite, and the outlook for major coins such as BTC, ETH, BNB, SOL, and ZEC is bearish 📉. But in the long term, fiat currency depreciation and sticky inflation will strengthen crypto assets’ censorship resistance and value-preservation properties, so the long-term outlook remains bullish 📈.
$BTC
$ETH
$BNB
The elevated inflation was mainly driven by a sharp rebound in energy prices, with gasoline prices jumping 3.9% month over month and contributing more than one-third of the increase. At the same time, housing and services inflation remained resilient, compounded by concerns over crude oil supply triggered by tensions in the Middle East. After the data was released, expectations for a Fed rate hike in September surged.
Expectations of macro tightening have put pressure on the crypto market. In the short term, tighter liquidity is weighing on risk appetite, and the outlook for major coins such as BTC, ETH, BNB, SOL, and ZEC is bearish 📉. But in the long term, fiat currency depreciation and sticky inflation will strengthen crypto assets’ censorship resistance and value-preservation properties, so the long-term outlook remains bullish 📈.
$BTC
$ETH
$BNB
170
·
--
On September 11, #CPI数据来袭能否触发9月加息 2026. The U.S. core CPI for August, released that day, rose 0.3% month over month, clearly exceeding market expectations. Combined with the recent rise in oil prices and easing disinflation in the production side, this broke the narrative of continued cooling inflation and sent market expectations for a September Fed rate hike soaring to around 90%.
In traditional logic, rate hikes are negative for risk assets, but the crypto market instead saw a counterintuitive “buy the rumor, sell the news” move. BTC briefly dipped before quickly rebounding, while ETH, SOL and other major coins strengthened in sync. In the short term, tighter liquidity before the rate hike weighs on prices, bearish view 📉; in the long term, Bitcoin’s role as a tool to hedge fiat currency depreciation becomes more prominent, bullish view 📈. In addition, tokens such as BNB and ZEC also showed signs of capital inflows.
$BTC
{future}(BTCUSDT)
$ETH
{future}(ETHUSDT)
$BNB
{future}(BNBUSDT)
On September 11, #CPI数据来袭能否触发9月加息 2026. The U.S. core CPI for August, released that day, rose 0.3% month over month, clearly exceeding market expectations. Combined with the recent rise in oil prices and easing disinflation in the production side, this broke the narrative of continued cooling inflation and sent market expectations for a September Fed rate hike soaring to around 90%.
In traditional logic, rate hikes are negative for risk assets, but the crypto market instead saw a counterintuitive “buy the rumor, sell the news” move. BTC briefly dipped before quickly rebounding, while ETH, SOL and other major coins strengthened in sync. In the short term, tighter liquidity before the rate hike weighs on prices, bearish view 📉; in the long term, Bitcoin’s role as a tool to hedge fiat currency depreciation becomes more prominent, bullish view 📈. In addition, tokens such as BNB and ZEC also showed signs of capital inflows.
$BTC
$ETH
$BNB
In traditional logic, rate hikes are negative for risk assets, but the crypto market instead saw a counterintuitive “buy the rumor, sell the news” move. BTC briefly dipped before quickly rebounding, while ETH, SOL and other major coins strengthened in sync. In the short term, tighter liquidity before the rate hike weighs on prices, bearish view 📉; in the long term, Bitcoin’s role as a tool to hedge fiat currency depreciation becomes more prominent, bullish view 📈. In addition, tokens such as BNB and ZEC also showed signs of capital inflows.
$BTC
$ETH
$BNB
213
·
--
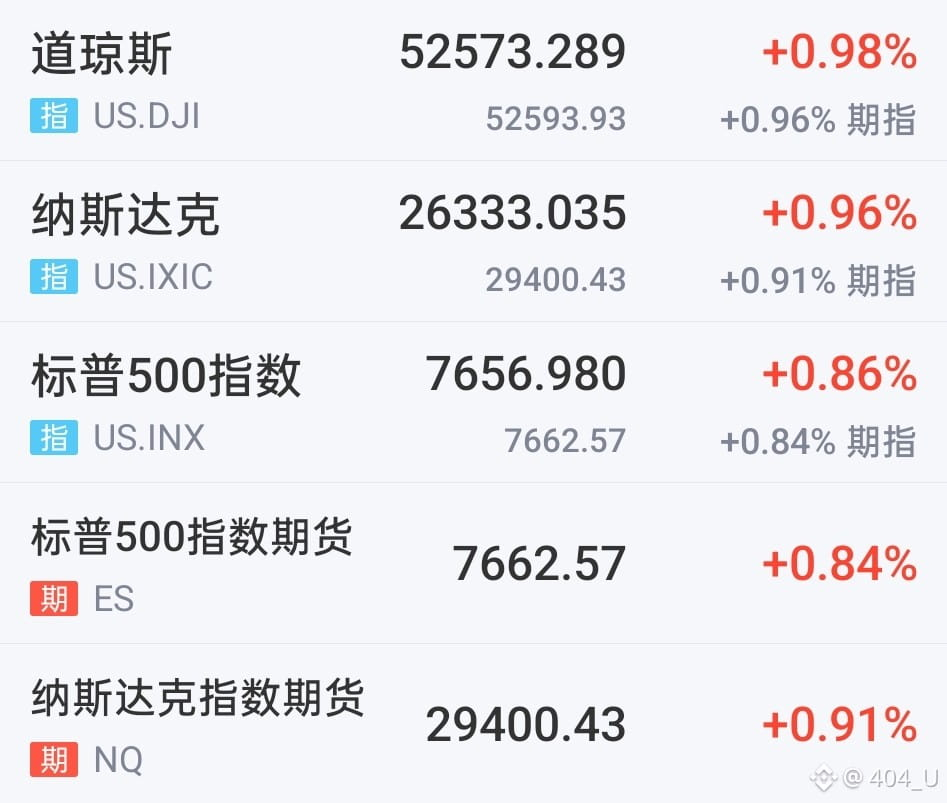
#CPI数据来袭能否触发9月加息 US CPI data is out. After it came out, the probability of a rate hike next week jumped to 90%. Before the data came out, the probability was 70%, but after it was released it shot straight up to 90%.
Under these circumstances, gold and silver didn’t just dump, and global tech also didn’t dump—so strong. Global tech! #现货黄金涨0.87%白银涨1.13% #美国8月核心CPI环比涨0.3%超预期
$XAU
{future}(XAUUSDT)
$XAG
{future}(XAGUSDT)
$QQQ
{future}(QQQUSDT)
#CPI数据来袭能否触发9月加息 US CPI data is out. After it came out, the probability of a rate hike next week jumped to 90%. Before the data came out, the probability was 70%, but after it was released it shot straight up to 90%.
Under these circumstances, gold and silver didn’t just dump, and global tech also didn’t dump—so strong. Global tech! #现货黄金涨0.87%白银涨1.13% #美国8月核心CPI环比涨0.3%超预期
$XAU
$XAG
$QQQ
Under these circumstances, gold and silver didn’t just dump, and global tech also didn’t dump—so strong. Global tech! #现货黄金涨0.87%白银涨1.13% #美国8月核心CPI环比涨0.3%超预期
$XAU
$XAG
$QQQ
158
·
--
#现货黄金涨0.87%白银涨1.13% Gold and silver are soaring—so what’s the play from here? Wait, isn’t this a rate hike already? Gold, silver, and commodities worldwide have all flown up.
So is this negative news turning into a good thing after landing?
Or is everyone next week betting there’s a 10% chance they won’t raise rates? Why is that—why can it surge like this? #CPI数据来袭能否触发9月加息 #美国8月核心CPI环比涨0.3%超预期
$XAU
{future}(XAUUSDT)
$XAG
{future}(XAGUSDT)
#现货黄金涨0.87%白银涨1.13% Gold and silver are soaring—so what’s the play from here? Wait, isn’t this a rate hike already? Gold, silver, and commodities worldwide have all flown up.
So is this negative news turning into a good thing after landing?
Or is everyone next week betting there’s a 10% chance they won’t raise rates? Why is that—why can it surge like this? #CPI数据来袭能否触发9月加息 #美国8月核心CPI环比涨0.3%超预期
$XAU
$XAG
So is this negative news turning into a good thing after landing?
Or is everyone next week betting there’s a 10% chance they won’t raise rates? Why is that—why can it surge like this? #CPI数据来袭能否触发9月加息 #美国8月核心CPI环比涨0.3%超预期
$XAU
$XAG
67
·
--
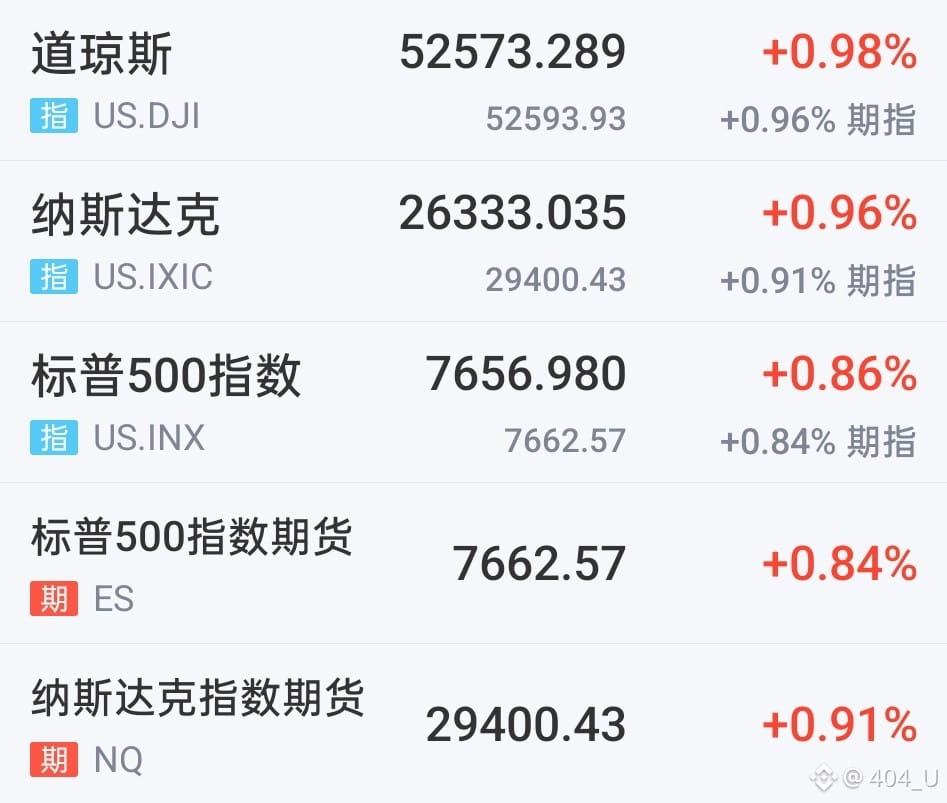
#CPI数据来袭能否触发9月加息 Before the opening of the NASDAQ index NQ, it turned upward. A lot of people don’t understand—wasn’t it supposed to be a era of big rate hikes?
You need to understand something clearly: what people are afraid of isn’t the rate hike itself. What they’re afraid of is the period before the hike is confirmed. During that time, everyone keeps telling me, “Oh, the rate hike is coming!” That’s what the market is most worried about. But now it’s settled—because the probability of a rate hike has already been pushed to more than 90%.
Got it?
Back then, when Yellen started that round of sweeping rate hikes in 2015, in the first few weeks after the start, the index could be said to have surged dramatically.
Some people say, “Strange, strange—against intuition, against the usual logic.” But you can basically treat this as a rule of thumb. What people are afraid of is never the rate hike itself; it’s the period before it. In that time, your heart is all rattled. Now the “deer” isn’t running around anymore—it’s basically “gone.”
Because the decision about the rate hike is already set, so you can rest easy.
If the rate hike is certain, then the next thing is that the cost of money gets more expensive. It will slowly come down to which company has stronger fundamentals—who has the lower financing cost.
#美国8月核心CPI环比涨0.3%超预期 #比特币CPI后反弹站上79000美元 #BNB涨破730美元 #美国8月核心CPI环比涨0.3%超预期
$QQQ
{future}(QQQUSDT)
$SPY
{future}(SPYUSDT)
$BTC
{future}(BTCUSDT)
#CPI数据来袭能否触发9月加息 Before the opening of the NASDAQ index NQ, it turned upward. A lot of people don’t understand—wasn’t it supposed to be a era of big rate hikes?
You need to understand something clearly: what people are afraid of isn’t the rate hike itself. What they’re afraid of is the period before the hike is confirmed. During that time, everyone keeps telling me, “Oh, the rate hike is coming!” That’s what the market is most worried about. But now it’s settled—because the probability of a rate hike has already been pushed to more than 90%.
Got it?
Back then, when Yellen started that round of sweeping rate hikes in 2015, in the first few weeks after the start, the index could be said to have surged dramatically.
Some people say, “Strange, strange—against intuition, against the usual logic.” But you can basically treat this as a rule of thumb. What people are afraid of is never the rate hike itself; it’s the period before it. In that time, your heart is all rattled. Now the “deer” isn’t running around anymore—it’s basically “gone.”
Because the decision about the rate hike is already set, so you can rest easy.
If the rate hike is certain, then the next thing is that the cost of money gets more expensive. It will slowly come down to which company has stronger fundamentals—who has the lower financing cost.
#美国8月核心CPI环比涨0.3%超预期 #比特币CPI后反弹站上79000美元 #BNB涨破730美元 #美国8月核心CPI环比涨0.3%超预期
$QQQ
$SPY
$BTC
You need to understand something clearly: what people are afraid of isn’t the rate hike itself. What they’re afraid of is the period before the hike is confirmed. During that time, everyone keeps telling me, “Oh, the rate hike is coming!” That’s what the market is most worried about. But now it’s settled—because the probability of a rate hike has already been pushed to more than 90%.
Got it?
Back then, when Yellen started that round of sweeping rate hikes in 2015, in the first few weeks after the start, the index could be said to have surged dramatically.
Some people say, “Strange, strange—against intuition, against the usual logic.” But you can basically treat this as a rule of thumb. What people are afraid of is never the rate hike itself; it’s the period before it. In that time, your heart is all rattled. Now the “deer” isn’t running around anymore—it’s basically “gone.”
Because the decision about the rate hike is already set, so you can rest easy.
If the rate hike is certain, then the next thing is that the cost of money gets more expensive. It will slowly come down to which company has stronger fundamentals—who has the lower financing cost.
#美国8月核心CPI环比涨0.3%超预期 #比特币CPI后反弹站上79000美元 #BNB涨破730美元 #美国8月核心CPI环比涨0.3%超预期
$QQQ
$SPY
$BTC
208
·
--
#美国将于周一制裁一家大银行 U.S. Treasury Secretary Bessent said on Sept. 10 that sanctions originally planned for Sept. 11—delayed to Monday, Sept. 14 in observance of the 25th anniversary of “9·11”—would target a “large bank” doing business with Iran. The bank’s name and nationality were not disclosed. The context is an escalation of the U.S. “economic exile campaign”: in August it was expanded to aviation, shipping, gold, digital assets, and technology; in September it already added Turkey’s Golden Global Bank and its subsidiaries, as well as the Dubai branch of Egypt’s Banque Misr, to the sanctions list, calling the latter part of an Iran-linked network that processes about $1.8 billion. The U.S. also removed the bank’s eligibility to act as an agent bank in the United States. All told, roughly 60 entities and vessels were included. The core reason is not a typical compliance violation, but cutting off Iran’s oil revenues, its shadow fleet, and the U.S. dollar clearing channels—using “secondary sanctions” to force banks in third countries to choose between keeping Iran-related business or keeping their U.S. dollar correspondent/agent banking relationships.
In the short term, markets lean risk-off 📉: the unknown bank name will trigger a compliance revaluation; U.S. dollar clearing and anti–money laundering costs will rise. U.S. stock investors are watching JPMorgan Chase (JPM), Bank of America (BAC), and Citigroup (C). If the sanctioned institution comes from an emerging market, these three U.S. dollar-network banks could see alternative-relationship premium, but the whole sector is expected to fall first and then diverge. From a compliance-tech/trading-monitoring logic perspective, Nasdaq compliance software stocks like SSNC may see a short-term uptick 📈 and a longer-term uptick 📈. In Korea, if the list does not involve domestic banks, KB, Shinhan (SHG), and Hana/Asia Financial will be affected mainly by sentiment; after a short-term dip 📉 they may repair 📈. If the institution is later named as an Iran-related correspondent/agent, both short and long positions could turn down 📉. Overall: in the first week, the event-driven move points to volatility 📉; once it’s confirmed as a case-by-case matter, JPM/SSNC may be long for compliance strength and dollar-clearing advantages 📈, while Korean banks KB and SHG are neutral to slightly bullish 📈.
$JPM
{future}(JPMUSDT)
$BAC.US
{stock_us}(BAC.US)
$KB.US
{stock_us}(KB.US)
#美国将于周一制裁一家大银行 U.S. Treasury Secretary Bessent said on Sept. 10 that sanctions originally planned for Sept. 11—delayed to Monday, Sept. 14 in observance of the 25th anniversary of “9·11”—would target a “large bank” doing business with Iran. The bank’s name and nationality were not disclosed. The context is an escalation of the U.S. “economic exile campaign”: in August it was expanded to aviation, shipping, gold, digital assets, and technology; in September it already added Turkey’s Golden Global Bank and its subsidiaries, as well as the Dubai branch of Egypt’s Banque Misr, to the sanctions list, calling the latter part of an Iran-linked network that processes about $1.8 billion. The U.S. also removed the bank’s eligibility to act as an agent bank in the United States. All told, roughly 60 entities and vessels were included. The core reason is not a typical compliance violation, but cutting off Iran’s oil revenues, its shadow fleet, and the U.S. dollar clearing channels—using “secondary sanctions” to force banks in third countries to choose between keeping Iran-related business or keeping their U.S. dollar correspondent/agent banking relationships.
In the short term, markets lean risk-off 📉: the unknown bank name will trigger a compliance revaluation; U.S. dollar clearing and anti–money laundering costs will rise. U.S. stock investors are watching JPMorgan Chase (JPM), Bank of America (BAC), and Citigroup (C). If the sanctioned institution comes from an emerging market, these three U.S. dollar-network banks could see alternative-relationship premium, but the whole sector is expected to fall first and then diverge. From a compliance-tech/trading-monitoring logic perspective, Nasdaq compliance software stocks like SSNC may see a short-term uptick 📈 and a longer-term uptick 📈. In Korea, if the list does not involve domestic banks, KB, Shinhan (SHG), and Hana/Asia Financial will be affected mainly by sentiment; after a short-term dip 📉 they may repair 📈. If the institution is later named as an Iran-related correspondent/agent, both short and long positions could turn down 📉. Overall: in the first week, the event-driven move points to volatility 📉; once it’s confirmed as a case-by-case matter, JPM/SSNC may be long for compliance strength and dollar-clearing advantages 📈, while Korean banks KB and SHG are neutral to slightly bullish 📈.
$JPM
$BAC.US
$KB.US
In the short term, markets lean risk-off 📉: the unknown bank name will trigger a compliance revaluation; U.S. dollar clearing and anti–money laundering costs will rise. U.S. stock investors are watching JPMorgan Chase (JPM), Bank of America (BAC), and Citigroup (C). If the sanctioned institution comes from an emerging market, these three U.S. dollar-network banks could see alternative-relationship premium, but the whole sector is expected to fall first and then diverge. From a compliance-tech/trading-monitoring logic perspective, Nasdaq compliance software stocks like SSNC may see a short-term uptick 📈 and a longer-term uptick 📈. In Korea, if the list does not involve domestic banks, KB, Shinhan (SHG), and Hana/Asia Financial will be affected mainly by sentiment; after a short-term dip 📉 they may repair 📈. If the institution is later named as an Iran-related correspondent/agent, both short and long positions could turn down 📉. Overall: in the first week, the event-driven move points to volatility 📉; once it’s confirmed as a case-by-case matter, JPM/SSNC may be long for compliance strength and dollar-clearing advantages 📈, while Korean banks KB and SHG are neutral to slightly bullish 📈.
$JPM
$BAC.US
$KB.US
54
·
--
#腾讯投资燧原科技9.11亿美元IPO后上市 Suiyuan Technology is not according to the “$911 million IPO” narrative; the latest real development is that on September 11, 2026, it listed on the Shanghai Stock Exchange STAR Market, stock code 688801. The issue price was RMB 142.18 per share, with 43.0352 million shares issued, raising approximately RMB 6.119 billion (about USD 850 million, not $911 million). The issue market capitalization was about RMB 61.187 billion. On the first day, it opened up more than 188%, and at one point during the session it surged more than 230%.
There are three main drivers: (1) Tencent led the Pre-A round in 2018, followed by multiple rounds A/B/C/D/E; after the offering, Tencent held about 17.95% directly, making it the largest external shareholder. Its strategic allocation also added another RMB 248 million through Qishan Investment. (2) Tencent is also the largest customer. From 2023 to 2025, the share of sales to Tencent directly and through the AVAP model rose from 33.34% to 83.79%. In 2025, it reached RMB 830 million and accounted for 83.79%, providing validation for its AI inference/training scenarios. (3) With domestic AI computing power substitution accelerating and the STAR Market’s non-profitable listing requirements being relaxed, Phase II of the Big Fund and Shanghai state-owned capital have entered. The raised funds are planned for fifth- and sixth-generation chips and coordinated software and hardware.
For overseas comparison: Nvidia (NVDA) and AMD benefit from global demand for training. In Korea, memory supply-chain players such as SK hynix and Samsung Electronics are boosted by HBM market conditions, which is positively correlated with cloud AI chip cycles.
Short term: strong first-day gains, high valuation, still not profitable (1H 2026 net loss about RMB 603 million), and revenue concentration with Tencent—meaning volatility is higher before the lock-up period ends, so be cautious 📉. Long term: AI inference demand, domestic substitution, Tencent orders extending to 2027, and the rollout of fifth- and sixth-generation chips—if customer diversification materializes, look bullish 📈.
$SKHYNIX
{future}(SKHYNIXUSDT)
$SAMSUNG
{future}(SAMSUNGUSDT)
$AMD
{future}(AMDUSDT)
#腾讯投资燧原科技9.11亿美元IPO后上市 Suiyuan Technology is not according to the “$911 million IPO” narrative; the latest real development is that on September 11, 2026, it listed on the Shanghai Stock Exchange STAR Market, stock code 688801. The issue price was RMB 142.18 per share, with 43.0352 million shares issued, raising approximately RMB 6.119 billion (about USD 850 million, not $911 million). The issue market capitalization was about RMB 61.187 billion. On the first day, it opened up more than 188%, and at one point during the session it surged more than 230%.
There are three main drivers: (1) Tencent led the Pre-A round in 2018, followed by multiple rounds A/B/C/D/E; after the offering, Tencent held about 17.95% directly, making it the largest external shareholder. Its strategic allocation also added another RMB 248 million through Qishan Investment. (2) Tencent is also the largest customer. From 2023 to 2025, the share of sales to Tencent directly and through the AVAP model rose from 33.34% to 83.79%. In 2025, it reached RMB 830 million and accounted for 83.79%, providing validation for its AI inference/training scenarios. (3) With domestic AI computing power substitution accelerating and the STAR Market’s non-profitable listing requirements being relaxed, Phase II of the Big Fund and Shanghai state-owned capital have entered. The raised funds are planned for fifth- and sixth-generation chips and coordinated software and hardware.
For overseas comparison: Nvidia (NVDA) and AMD benefit from global demand for training. In Korea, memory supply-chain players such as SK hynix and Samsung Electronics are boosted by HBM market conditions, which is positively correlated with cloud AI chip cycles.
Short term: strong first-day gains, high valuation, still not profitable (1H 2026 net loss about RMB 603 million), and revenue concentration with Tencent—meaning volatility is higher before the lock-up period ends, so be cautious 📉. Long term: AI inference demand, domestic substitution, Tencent orders extending to 2027, and the rollout of fifth- and sixth-generation chips—if customer diversification materializes, look bullish 📈.
$SKHYNIX
$SAMSUNG
$AMD
There are three main drivers: (1) Tencent led the Pre-A round in 2018, followed by multiple rounds A/B/C/D/E; after the offering, Tencent held about 17.95% directly, making it the largest external shareholder. Its strategic allocation also added another RMB 248 million through Qishan Investment. (2) Tencent is also the largest customer. From 2023 to 2025, the share of sales to Tencent directly and through the AVAP model rose from 33.34% to 83.79%. In 2025, it reached RMB 830 million and accounted for 83.79%, providing validation for its AI inference/training scenarios. (3) With domestic AI computing power substitution accelerating and the STAR Market’s non-profitable listing requirements being relaxed, Phase II of the Big Fund and Shanghai state-owned capital have entered. The raised funds are planned for fifth- and sixth-generation chips and coordinated software and hardware.
For overseas comparison: Nvidia (NVDA) and AMD benefit from global demand for training. In Korea, memory supply-chain players such as SK hynix and Samsung Electronics are boosted by HBM market conditions, which is positively correlated with cloud AI chip cycles.
Short term: strong first-day gains, high valuation, still not profitable (1H 2026 net loss about RMB 603 million), and revenue concentration with Tencent—meaning volatility is higher before the lock-up period ends, so be cautious 📉. Long term: AI inference demand, domestic substitution, Tencent orders extending to 2027, and the rollout of fifth- and sixth-generation chips—if customer diversification materializes, look bullish 📈.
$SKHYNIX
$SAMSUNG
$AMD
36
·
--
#CPI数据来袭能否触发9月加息 U.S. August CPI will be released at 20:30 Beijing time on the evening of September 11, 2026. It is the last key inflation data before the Fed’s FOMC on September 15–16. The market is currently pricing in a probability of about 70%—73% for a 25-basis-point rate hike in September.
The main drivers are three forces: first, the Middle East situation is pushing up oil prices. Both WTI and Brent have at times broken above $100, with energy costs transmitting to transportation and gasoline. Second, August PPI year over year is about 5.4% and month over month is 0.4%. Rising wholesale costs suggest pressure on the consumer side. Third, tariffs, AI infrastructure spending, and relatively tight semiconductor supply-and-demand are driving cost-push inflation; rate hikes alone may not quickly bring it down.
As for expectations, headline CPI is around 3.4% year over year and 0.4% month over month, while core CPI is about 2.4% year over year and 0.2% month over month. If core month over month is ≥0.3%, the rate hike is essentially locked in, and short-term U.S. Treasury yields will likely keep climbing.
In terms of assets, rate-hike expectations first weigh on technology growth: NVDA📉 and semiconductor valuations retrace. Korea’s memory supply chain is tugged by both discounted U.S. Treasury yields and dual pressure from AI-related demand; Samsung Electronics and SK Hynix may see short-term📉 weakness, but if CPI is moderate, a beaten-down rebound📈 could follow. Apple (AAPL) is relatively more resilient thanks to the new-product cycle; if core inflation doesn’t run hot, it could📈. NAVER is influenced by global risk appetite: it may see short-term📉 weakness, but over the long term, AI cloud services and ad revenue could recover📈.
In the near term, CPI coming in hotter than expected would reinforce the pricing of a rate hike: growth/semiconductors📉, while the dollar and energy📈 would benefit. If core CPI meets or falls below expectations, the probability of staying put in September would rise, and NVDA could see a repair📈. Over the long run, the AI and memory super-cycle thesis is still leaning positive📈, but the oil price—tariffs—wage stickiness dynamic has not fully faded, so the broader picture remains pressured on rallies📉.
$NVDA
{future}(NVDAUSDT)
$SAMSUNG
{future}(SAMSUNGUSDT)
$SKHYNIX
{future}(SKHYNIXUSDT)
#CPI数据来袭能否触发9月加息 U.S. August CPI will be released at 20:30 Beijing time on the evening of September 11, 2026. It is the last key inflation data before the Fed’s FOMC on September 15–16. The market is currently pricing in a probability of about 70%—73% for a 25-basis-point rate hike in September.
The main drivers are three forces: first, the Middle East situation is pushing up oil prices. Both WTI and Brent have at times broken above $100, with energy costs transmitting to transportation and gasoline. Second, August PPI year over year is about 5.4% and month over month is 0.4%. Rising wholesale costs suggest pressure on the consumer side. Third, tariffs, AI infrastructure spending, and relatively tight semiconductor supply-and-demand are driving cost-push inflation; rate hikes alone may not quickly bring it down.
As for expectations, headline CPI is around 3.4% year over year and 0.4% month over month, while core CPI is about 2.4% year over year and 0.2% month over month. If core month over month is ≥0.3%, the rate hike is essentially locked in, and short-term U.S. Treasury yields will likely keep climbing.
In terms of assets, rate-hike expectations first weigh on technology growth: NVDA📉 and semiconductor valuations retrace. Korea’s memory supply chain is tugged by both discounted U.S. Treasury yields and dual pressure from AI-related demand; Samsung Electronics and SK Hynix may see short-term📉 weakness, but if CPI is moderate, a beaten-down rebound📈 could follow. Apple (AAPL) is relatively more resilient thanks to the new-product cycle; if core inflation doesn’t run hot, it could📈. NAVER is influenced by global risk appetite: it may see short-term📉 weakness, but over the long term, AI cloud services and ad revenue could recover📈.
In the near term, CPI coming in hotter than expected would reinforce the pricing of a rate hike: growth/semiconductors📉, while the dollar and energy📈 would benefit. If core CPI meets or falls below expectations, the probability of staying put in September would rise, and NVDA could see a repair📈. Over the long run, the AI and memory super-cycle thesis is still leaning positive📈, but the oil price—tariffs—wage stickiness dynamic has not fully faded, so the broader picture remains pressured on rallies📉.
$NVDA
$SAMSUNG
$SKHYNIX
The main drivers are three forces: first, the Middle East situation is pushing up oil prices. Both WTI and Brent have at times broken above $100, with energy costs transmitting to transportation and gasoline. Second, August PPI year over year is about 5.4% and month over month is 0.4%. Rising wholesale costs suggest pressure on the consumer side. Third, tariffs, AI infrastructure spending, and relatively tight semiconductor supply-and-demand are driving cost-push inflation; rate hikes alone may not quickly bring it down.
As for expectations, headline CPI is around 3.4% year over year and 0.4% month over month, while core CPI is about 2.4% year over year and 0.2% month over month. If core month over month is ≥0.3%, the rate hike is essentially locked in, and short-term U.S. Treasury yields will likely keep climbing.
In terms of assets, rate-hike expectations first weigh on technology growth: NVDA📉 and semiconductor valuations retrace. Korea’s memory supply chain is tugged by both discounted U.S. Treasury yields and dual pressure from AI-related demand; Samsung Electronics and SK Hynix may see short-term📉 weakness, but if CPI is moderate, a beaten-down rebound📈 could follow. Apple (AAPL) is relatively more resilient thanks to the new-product cycle; if core inflation doesn’t run hot, it could📈. NAVER is influenced by global risk appetite: it may see short-term📉 weakness, but over the long term, AI cloud services and ad revenue could recover📈.
In the near term, CPI coming in hotter than expected would reinforce the pricing of a rate hike: growth/semiconductors📉, while the dollar and energy📈 would benefit. If core CPI meets or falls below expectations, the probability of staying put in September would rise, and NVDA could see a repair📈. Over the long run, the AI and memory super-cycle thesis is still leaning positive📈, but the oil price—tariffs—wage stickiness dynamic has not fully faded, so the broader picture remains pressured on rallies📉.
$NVDA
$SAMSUNG
$SKHYNIX
78
·
--
#比特币金叉确认 Bitcoin (BTC) daily chart has recently confirmed a “golden cross” signal. The formation of this technical pattern is driven by the 50-day moving average officially crossing above the 200-day moving average. The immediate catalyst is the recent strong rebound in the coin price from the August low, with the improvement in short-term average price happening faster than the long-term trend. However, at the macro level, it faces pressure from factors such as the U.S. PPI data coming in above expectations and oil prices breaking above $100, which has pushed U.S. Treasury yields higher—leaving the market liquidity undergoing reconfiguration and ongoing contention.
From the order book/price action perspective, the current BTC price is trading in a range around $77,000. While the larger-scale trend structure has not been broken, the short term has been pressured by macro-driven panic 📉. In the linked markets, major assets such as Ethereum (ETH), Solana (SOL), and BNB are also moving into a phase of range-bound digestion.
Looking ahead, golden crosses have historically been associated with major rallies, but they can also evolve into a “bull trap.” In the short term, the market needs to absorb macro negative news, so the outlook is bearish-to-sideways and range-bound 📉; but when extending the time horizon, as long as BTC can hold key moving-average support, it still has long-term potential for upside breakout 📈.
$BTC
{future}(BTCUSDT)
$ETH
{future}(ETHUSDT)
$BNB
{future}(BNBUSDT)
#比特币金叉确认 Bitcoin (BTC) daily chart has recently confirmed a “golden cross” signal. The formation of this technical pattern is driven by the 50-day moving average officially crossing above the 200-day moving average. The immediate catalyst is the recent strong rebound in the coin price from the August low, with the improvement in short-term average price happening faster than the long-term trend. However, at the macro level, it faces pressure from factors such as the U.S. PPI data coming in above expectations and oil prices breaking above $100, which has pushed U.S. Treasury yields higher—leaving the market liquidity undergoing reconfiguration and ongoing contention.
From the order book/price action perspective, the current BTC price is trading in a range around $77,000. While the larger-scale trend structure has not been broken, the short term has been pressured by macro-driven panic 📉. In the linked markets, major assets such as Ethereum (ETH), Solana (SOL), and BNB are also moving into a phase of range-bound digestion.
Looking ahead, golden crosses have historically been associated with major rallies, but they can also evolve into a “bull trap.” In the short term, the market needs to absorb macro negative news, so the outlook is bearish-to-sideways and range-bound 📉; but when extending the time horizon, as long as BTC can hold key moving-average support, it still has long-term potential for upside breakout 📈.
$BTC
$ETH
$BNB
From the order book/price action perspective, the current BTC price is trading in a range around $77,000. While the larger-scale trend structure has not been broken, the short term has been pressured by macro-driven panic 📉. In the linked markets, major assets such as Ethereum (ETH), Solana (SOL), and BNB are also moving into a phase of range-bound digestion.
Looking ahead, golden crosses have historically been associated with major rallies, but they can also evolve into a “bull trap.” In the short term, the market needs to absorb macro negative news, so the outlook is bearish-to-sideways and range-bound 📉; but when extending the time horizon, as long as BTC can hold key moving-average support, it still has long-term potential for upside breakout 📈.
$BTC
$ETH
$BNB
225
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
ArkhamSaysBlackRockBuys$1.5BInETH
12 views
10 Discussing
🚨BlackRock’s $1.57B ETH signal
#ArkhamSaysBlackRockBuys$1.5BInETH
⚫ BlackRock just accumulated ~$1.57B of ETH exposure in 20 days.
But the interesting part isn't the headline number.
Arkham data shows roughly $1.27B through ETHA and another $296.5M through ETHB.
That's two different institutional doors into Ethereum:
ETHA: spot ETH exposure
ETHB: ETH exposure + staking
And ETHB recorded no single-day outflow during the period.
BlackRock's own data puts ETHA at about $8.74B in net assets and ETHB at roughly $1.0B around Sept. 9–10.
So this isn't simply a story about an asset manager “buying ETH.”
It's a deeper shift:
Institutional Ethereum demand is gaining both spot exposure AND access to staking economics through regulated products.
The question is no longer just how much ETH institutions want.
It's how much of Ethereum's supply can increasingly be absorbed into long-duration, yield-seeking institutional vehicles.
DYOR.
$ETH $BTC
#ArkhamSaysBlackRockBuys$1.5BInETH #ElSalvadorBTCHoldingsRiseTo7777 #MemeLaunchpads82%OfArcDayOneVolume
Stink meaner
·1 Likes
·31 views
ElSalvadorBTCHoldingsRiseTo7777
7,959 views
247 Discussing
MemeLaunchpads82%OfArcDayOneVolume
16,992 views
449 Discussing