



On October 7, two things happened on the same day, but they pointed in different directions.
OpenAI rolled out GPT-6 to all ChatGPT users worldwide. Starting that day, paid users (Plus, Pro, Business, and Enterprise) were switched to GPT-6 Sol, while Free and Go users would switch to GPT-6 Luna starting October 8. The rollout also introduced a new capability called Intelligent UI, which can assemble text, charts, and interactive components in real time based on the type of question. According to official OpenAI data, ChatGPT has more than 1.2 billion weekly active users.
That same day, the Federal Reserve released the minutes of its September meeting. All 19 officials who attended supported a September rate hike, and most thought further rate increases might still be needed before year-end. Attendees broadly stressed that inflation remained elevated, the labor market was close to full employment, and inflation risks were tilted to the upside.
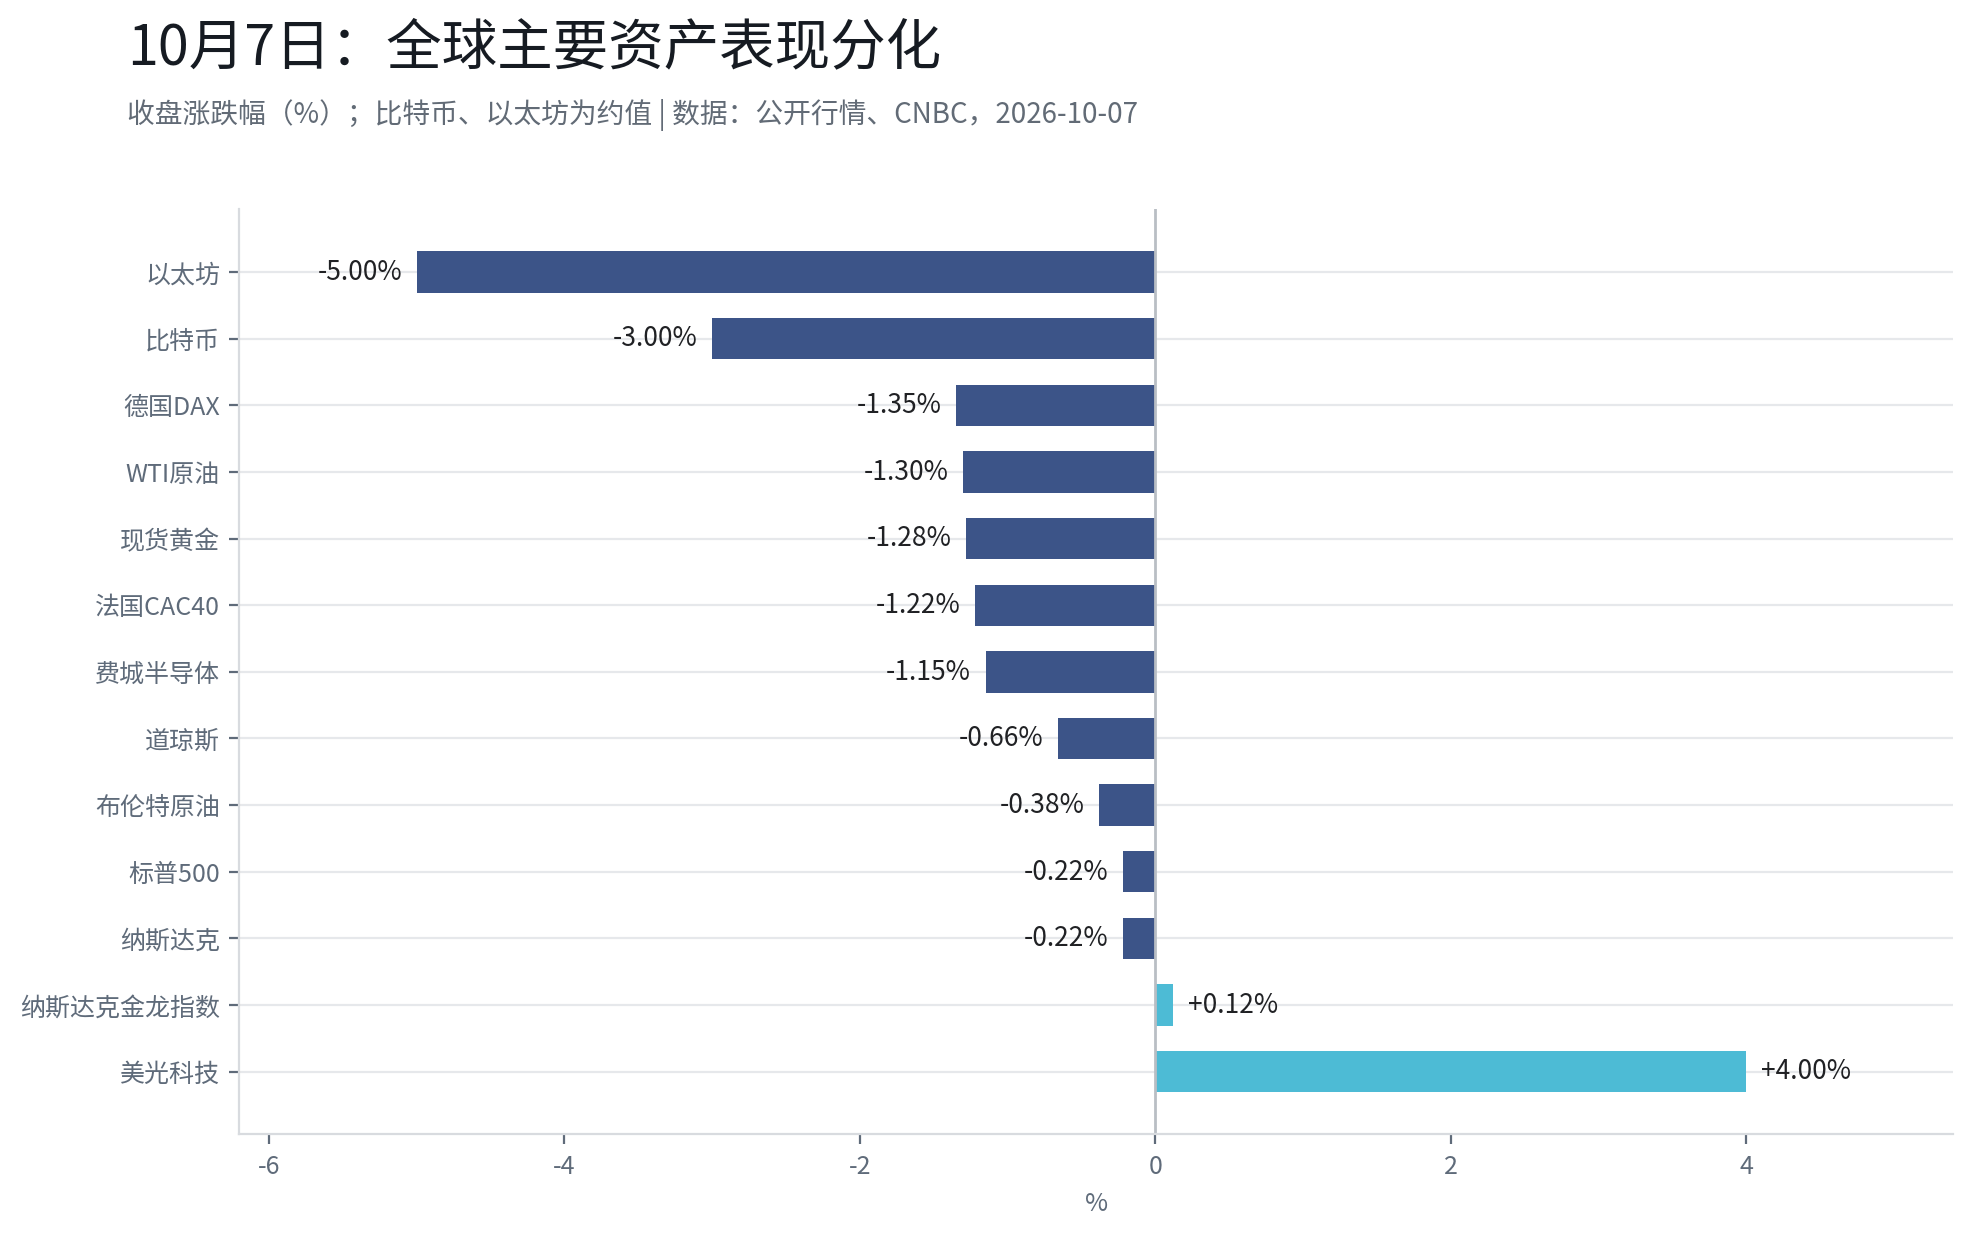
On one side is the market narrative’s “AGI moment,” and on the other is the central bank’s “higher for longer.” That day, the three major U.S. stock indexes pulled back from their record highs from the previous day: the Dow fell 341.41 points to 51,179.87 (-0.66%); the S&P 500 fell 0.22% to 7,801.77; and the Nasdaq fell 0.22% to 27,538.69. Losses were larger in Europe—Germany’s DAX fell 1.35% and France’s CAC40 fell 1.22%. Besides rising Treasury yields, concerns over France’s fiscal situation and high oil prices were also cited as reasons for European stocks weighing on the day.
One, the single sentence in the minutes that’s worth reading more closely
Most coverage focused on “most officials supporting another rate hike this year.” But there is another passage in the minutes that—according to public reports—was mentioned relatively less: some attendees believed that the development of artificial intelligence could cause total demand to exceed supply over the medium term, thereby creating upward pressure on inflation.
The weight of this statement may be no less than “another rate hike later this year.” In the Fed’s inflation discussion, AI capital expenditures themselves are listed as one of the variables that could raise total demand, rather than merely a neutral narrative of “technological progress.” From this, one can infer: if AI commercialization and computing expansion continue to accelerate, it could be one additional reason for a “higher-for-longer” interest-rate path. This is the article’s interpretation based on the minutes’ text; directional judgment still carries uncertainty.
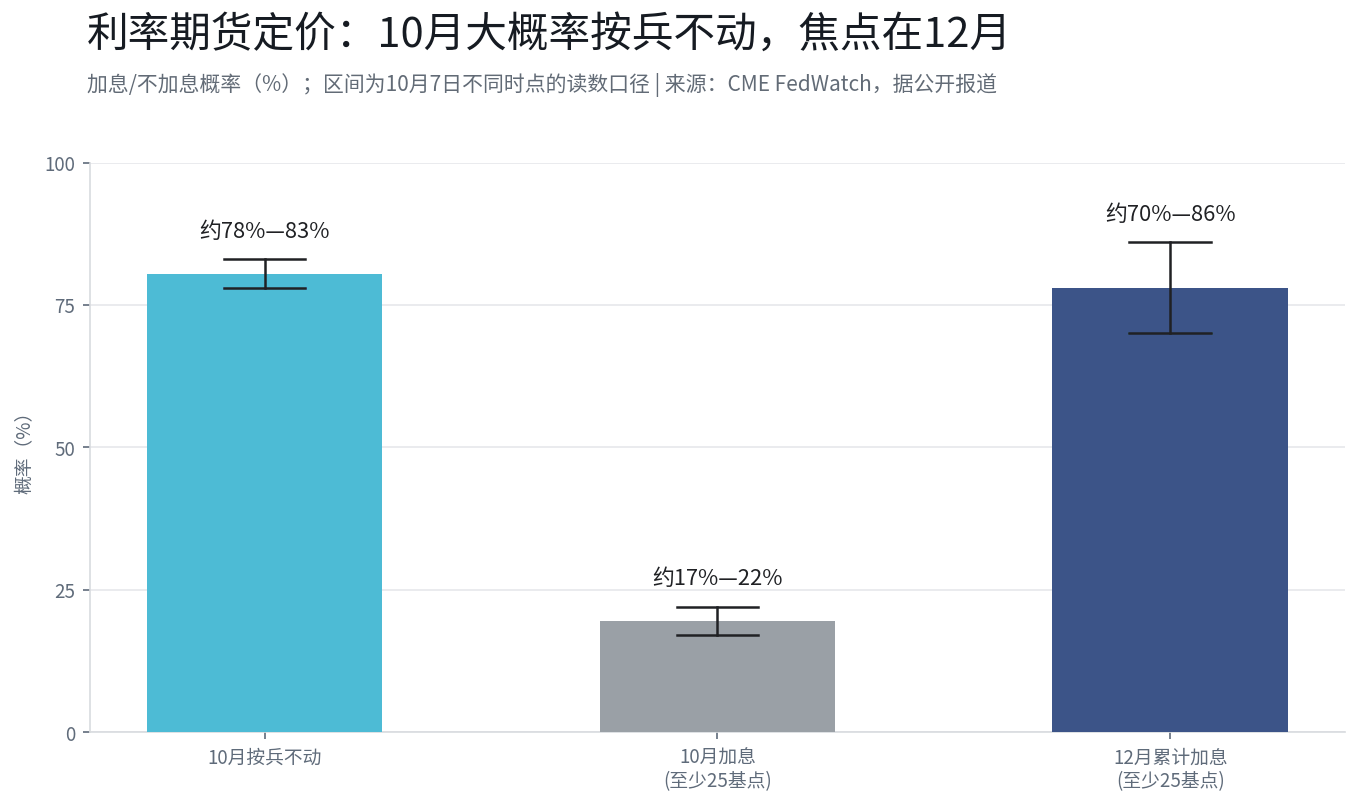
Market pricing is currently between the two scenarios. According to CME FedWatch data (different intraday reference points on Oct 7 have slight differences), the probability of at least 25 bps of hikes in October has fallen to about 17%–22%, while the probability of at least 25 bps of cumulative hikes by December is about 70%–86%. The message the market is sending is: October is likely to hold steady, and the December meeting could be one of the more critical observation points.
II. U.S. Treasuries: 10-year auction demand came in above expectations, but the real issue is the long end
One of the most watched asset-price moves of the day took place in the bond market.
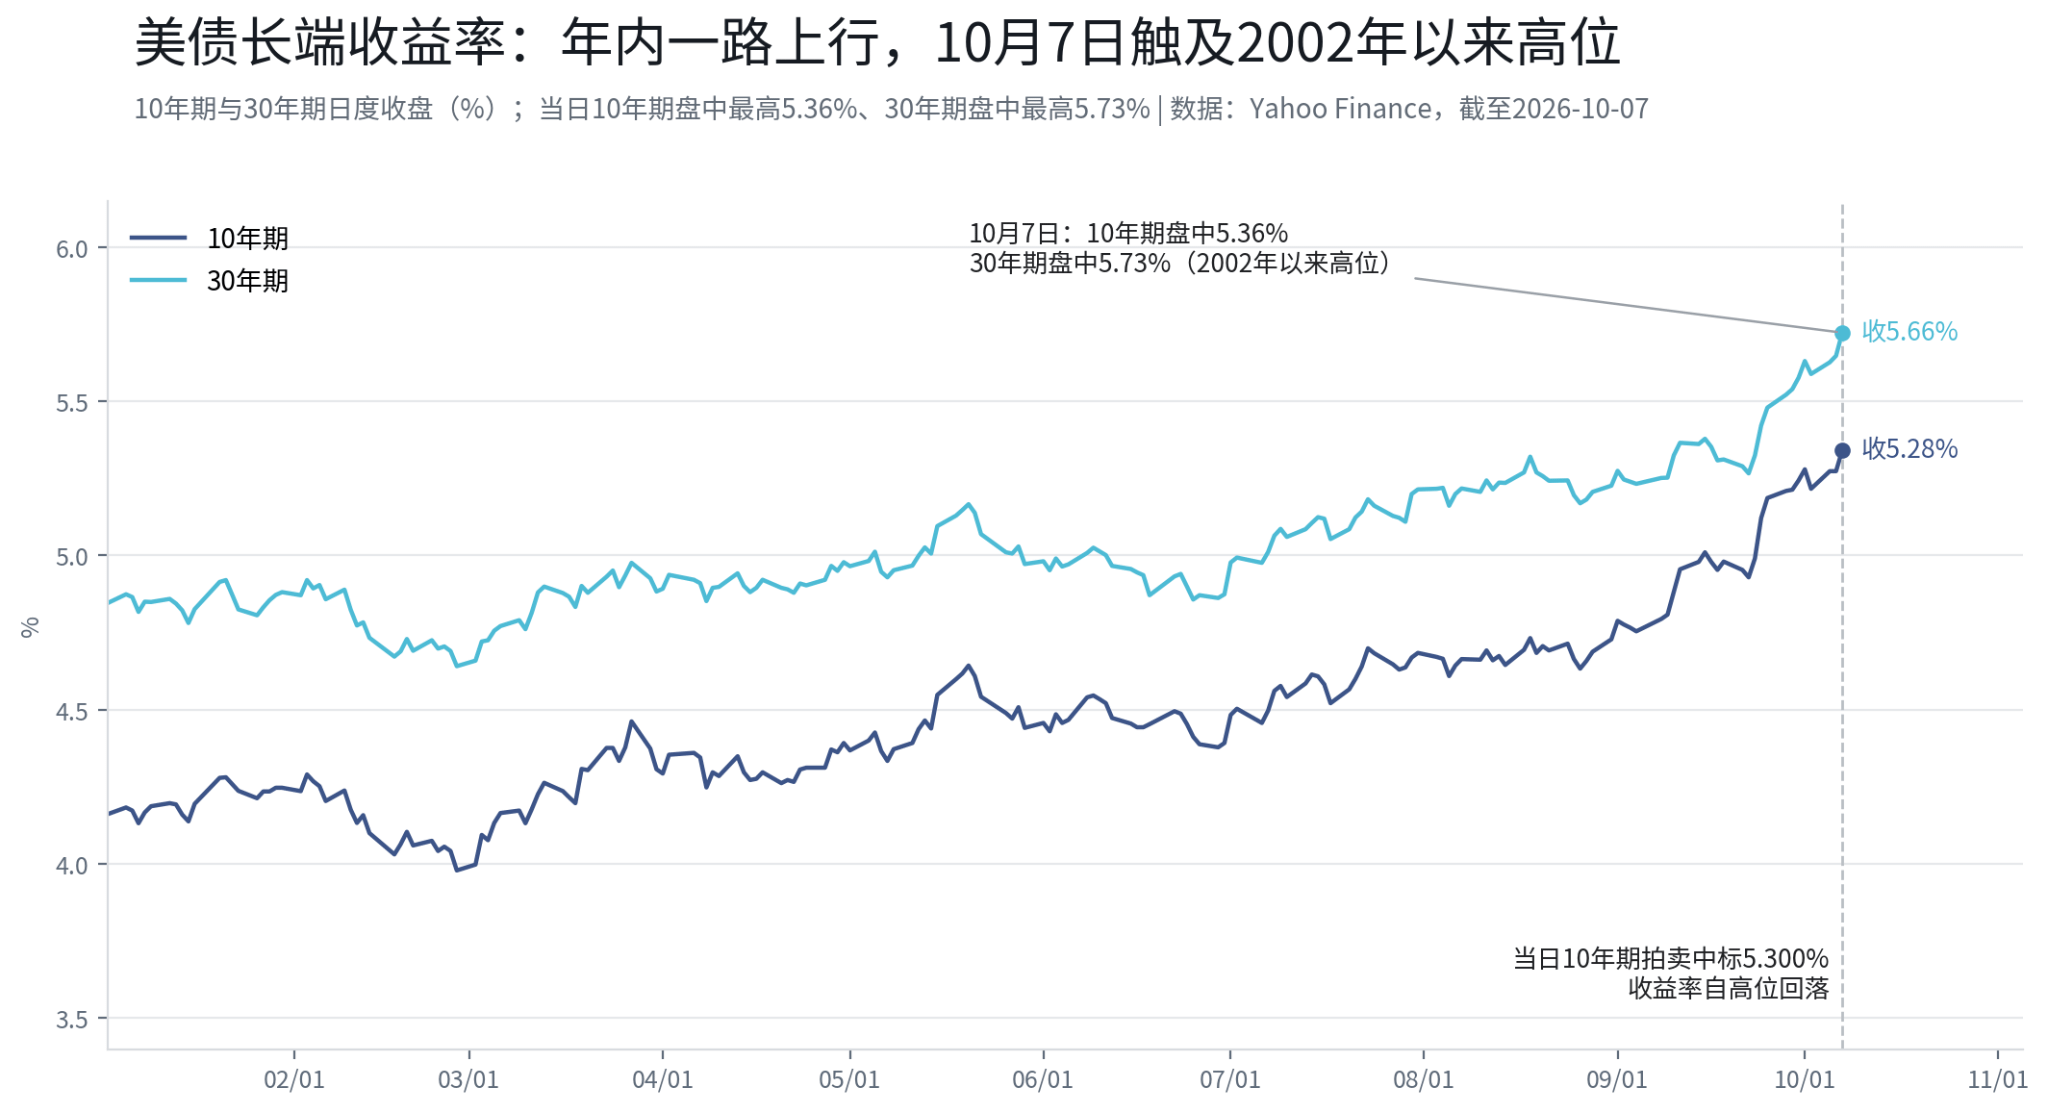
U.S. 10-year Treasury yields briefly rose to 5.364% intraday (according to Reuters, the highest since April 2002), and the 30-year touched 5.70%–5.73% intraday (the highest since May 2002). At the close, both retreated to around 5.28% and 5.66%, respectively. According to public reports, U.S. Treasury officials said in response that the bond selloff was a “global phenomenon”—long-end yields rose in sync across the U.S., Europe, and Japan. Behind this were inflation expectations after oil prices surpassed $100, and the higher compensation investors demanded to absorb large sovereign debt supply.
But there is an important counterexample on Oct 7: that day’s $39 billion 10-year Treasury auction had a bid-to-cover ratio of 2.77, clearly higher than the average of the last six auctions at 2.54. Allocations to primary dealers were only about 2.5%, the lowest since the financial crisis—meaning roughly 97.5% of the issuance was taken directly by non-dealers. Indirect bids (including global central banks and other institutions) were allocated 80.3%, higher than the average of the last 10 auctions at 72.4%.
One interpretation is: when yields are above 5.3%, some long-term allocation capital (pension funds, insurance companies, sovereign-fund-type institutions) may be shifting from “avoiding the long end” to “disciplined allocation of the long end.” This type of funds has internal discipline around yield levels—once yields are high enough, they allocate. But a single auction is not sufficient to confirm a trend. And it needs to be emphasized that it validates demand for the 10-year.
After the auction results were released, the 10-year yield fell back from its intraday high to around 5.28%–5.30%. The yield drop happened after the auction: the most important marginal change in the bond market that day may not have been economic data, but the appearance of buy-side demand.
III. The 30-year: a segment even more worth watching than the 10-year
If the 10-year is the day’s “pricing anchor,” then the 30-year may be the segment where pressure is most concentrated.
In terms of levels, both are actually at extremes: intraday 10-year at 5.364% is the highest since April 2002, and intraday 30-year at 5.70%–5.73% is the highest since May 2002. Based on data from a market interface, both are currently near the 98th percentile of the past 52-week range. Looking only at the rise, the 30-year is not steeper than the 10-year: since early September, the 10-year moved from about 4.79% to 5.28%, while the 30-year moved from about 5.27% to 5.66%.
What makes the 30-year “more astonishing,” however, are three structural reasons.
First, this is the end the central bank can’t directly manage. Policy rates directly determine the short end, while the pricing power for the 30-year yield is in the hands of the market—it is composed of inflation expectations and the term premium. When the Fed says “higher for longer,” the short end follows the policy path; but the rise in the 30-year is more like the market voting for the fiscal path and for long-run inflation itself. According to public reporting, in this round of selling, the pressure borne by the long end has been greater than that on the short end, and the 10-year–30-year spread has remained in a positive steepening shape of roughly 35–40 basis points. The market is not pricing a “recession inversion” pattern; it looks more like it is pricing “inflation and supply premia.”
Second, duration amplified volatility. The duration of a 30-year bond is more than twice that of a 10-year bond. With the same upward move in yields, the price decline is significantly larger. For pension funds and insurance companies holding long-duration bonds, the 30-year is the period with the most concentrated valuation pressure. For issuers (the U.S. Treasury), it is also the most expensive segment of funding.
Third, the answer from the 10-year auction cannot be automatically applied to the 30-year. The Oct 7 auction showed that allocation buyers were willing to take the 10-year at a yield of 5.3%. But pension and life-insurance liabilities’ duration mainly lies in the 20–30 year range—whether there is similarly strong demand for the ultra-long end needs to be answered by the 30-year auction on Oct 8. If the 30-year auction is also strong, the evidence for a “ceilinging” long-end rate would increase by another point; if it is clearly weaker, it would indicate that allocation funds are only willing to extend to the 10-year, and pressure on the 30-year has not yet been lifted.
With oil prices staying above $100, the transmission of inflation expectations to the ultra-long end is even more direct. The results of the 30-year auction and subsequent inflation data may explain how far this rate upcycle can go more than the 10-year’s performance itself.
IV. U.S. stocks on the day GPT-6 was released: hardware diverged, not a broad-based frenzy
The full rollout of GPT-6 did not create an “AI buy-everything” picture on the trading screens; instead, it resulted in internal differentiation.
The Philadelphia Semiconductor Index fell 1.15%. Storage and semiconductors diverged internally: according to publicly available quotes, Micron rose more than 4% against the trend, and Super Micro Computer rose more than 3%. Qualcomm and Arm fell more than 2%, TSMC fell 2.09%, and Western Digital and SK Hynix ADRs weakened.
Micron’s relative strength is related to storage supply and demand. According to reports, on Oct 7 an offshore institutional analyst raised Micron’s target price from $2,100 to $3,000. One of the core logics is demand from AI data centers for HBM high-bandwidth memory (the target price reflects only that institution’s view). One market interpretation is that the greater the inference load of models like GPT-6, the more directly the demand for high-bandwidth memory is reflected, leading to pricing divergence within the storage sector between “AI core storage” and “traditional storage.” Whether this divergence can persist still needs validation from subsequent financial reports and order data.
Big tech stocks saw mixed moves: Amazon rose 1.42%, Apple rose 0.91%, Google rose 0.81%, and Microsoft was slightly up. Meta fell 2.38%, while Nvidia and Tesla ended slightly lower. Divergence itself is a signal: the release of GPT-6 did not drive a broad rally; the market began differentiating “who truly benefits from inference demand.”
V. Gold falls below $4,100: double pressure from holding costs and the U.S. dollar
Gold was one of the assets with the larger intraday decline.
According to publicly available market quotes, spot gold closed at about $4,110 per ounce (different quote sources place it between $4,110.68 and $4,110.75), down 1.28%. Intraday, it hit a low near $4,066, the lowest since Aug 5. Spot silver closed at about $59.75 per ounce. December gold in New York fell $46.40 to $4,140.70 per ounce.
Gold’s weakness that day may be mainly due to two factors: first, the real interest-rate environment—intraday 30-year U.S. Treasury yields were above 5.7%, systematically raising the opportunity cost of holding non-yielding assets. When Treasuries can offer risk-free yields of 5.3% or higher, gold’s “zero-coupon” characteristic shifts from background to a constraint. Second, the U.S. dollar strengthened— the U.S. Dollar Index rose above 102.3, suppressing the dollar-denominated gold price. People from precious-metals analysis institutions told the media that the message the market is sending is that interest rates may remain at a higher level for longer, which supports both yields and the dollar.
It needs to be noted that gold’s intraday dip occurred before the release of the 10-year auction results. After the auction, yields fell back and the gold price rebounded from its low point—simply attributing the decline to a single event is not accurate. Interest rates, the U.S. dollar, and positioning factors may have acted together.
VI. Crude oil: geopolitical tension, but oil prices actually closed lower
WTI crude oil futures fell 1.30% to $88.28 per barrel, while Brent crude oil fell 0.38% to $100.20 per barrel (according to publicly available market data).
Oil prices have not moved in sync with geopolitical news. According to public reports, Iran said that day that the Strait of Hormuz was “closed,” and that Iran’s armed forces had control over it. Conflicts between Saudi Arabia and Yemen’s Houthi forces are also continuing. But oil prices did not rise as a result; hedging power on the supply side may be more important. The G-7 countries agreed to coordinate the release of about 100 million barrels of crude oil and gasoline via the International Energy Agency over the next four months, and on Oct 7 IEA member countries agreed to accelerate the pace of releases of already announced reserves. Maritime data shows that in the Middle East (excluding Iran) crude exports have even recently exceeded pre-conflict levels, with some cargo flows rerouted via detouring routes. Additional reports also mentioned that Saudi Aramco is studying new export channels to handle short-term disruptions.
Geopolitical risk premium was to some extent offset by policy hedges on the supply side, which may be one reason oil prices did not rise in line with the Middle East situation that day. However, if supply disruptions continue to escalate, the buffer capacity of reserve releases has a limit—whether this balance can be maintained remains uncertain.
VII. Crypto pulls back in sync: leveraged longs under pressure
Bitcoin briefly fell below $83,000 for the day, closing at about $83.1k, down more than 3%. Ethereum fell nearly 5%, SOL was down about 3%, HYPE and XRP fell more than 4%, and DOGE fell more than 7% (according to publicly available market data).
According to CoinGlass data, in the past 24 hours the total amount liquidated across the whole market was about $700 million, and more than nine-tenths were long positions. The crypto pullback may relate to multiple factors: rising U.S. Treasury yields and a stronger dollar suppressed the valuation of non-/low-yield assets; leveraged longs were forced liquidations during a rapid drop, amplifying volatility; and early-day geopolitical developments that pushed up oil prices also weighed on risk appetite that day.
VIII. The independent performance of China concept stocks
Against the backdrop of broad declines in U.S. stocks, the Nasdaq China Golden Dragon Index turned positive at the close and ended up slightly (according to publicly available quotes, about +0.1% to +0.3%, with slight differences across data sources); some China concept stocks saw notable gains.
The relatively independent performance of China concept stocks may be related to multiple factors: first, the prior drawdown was larger and valuations are at relatively lower levels; second, according to a statistical analysis by a foreign-invested large bank of nearly 2,800 global funds, the average allocation to Chinese stocks by global active long-only funds has risen since June from “underweight” to “benchmark neutral,” ending a four-year stretch of underweighting. Those funds manage about $562 billion in Chinese equity assets in total (this view represents only the assessment of that institution). Whether changes in historical fund behavior can continue is uncertain, and historical performance does not indicate future outcomes.
Nine, what to watch next
First, the 30-year auction results. This is a direct test of whether allocation buyers extend into the ultra-long end: if the 10-year is strong and the 30-year is also strong, long-end rate pressure may be close to being partially released; if the 10-year is strong and the 30-year is weak, it indicates the ultra-long end remains a weak link, and suppressing factors for high-valued assets and gold have not yet been resolved.
Second, whether the 10-year U.S. Treasury yield can return to and hold below 5.3%. If yields keep trading above 5.3%, the valuation anchor for high-multiple assets will continue to face pressure. If allocation-style buying is sustained, the peak in long-end yields may be closer than what current pricing implies—but this judgment remains uncertain.
Third, industry transmission after the release of GPT-6. Internal divergence within the storage sector (some AI-related storage names rising while traditional storage and parts of semiconductors weaken) is an initial signal. If the pricing gap between “AI core storage” and “traditional storage” continues to widen, the pricing logic across the AI industry chain may shift from “buy AI” to “identify the parts in the AI chain that truly benefit from inference demand.” Ultimately, however, it still needs validation from orders and financial reports.
Fourth, the marginal change in the probability of a December rate hike. The current market pricing implies that the probability of cumulative at least 25 bps of hikes by December is around 70%–80% (depending on the reference time point in the CME FedWatch). If subsequent inflation data show that stickiness remains, this probability could rise further; the “pause” in October might be only a matter of timing. Conversely, any signal of inflation cooling could improve conditions for both growth stocks and long-duration Treasuries at the same time.
Written in conclusion
Reading Oct 7 as “AI narrative setbacks” or “market panic” is incomplete. What actually happened is more like this: the Fed minutes turned AI from an industrial narrative into an inflation framework, causing long-end yields to move higher under pressure. On the same day, a 10-year auction with demand exceeding expectations pulled yields down partially. The full rollout of GPT-6 did not trigger a broad-based rally; instead, it led to a reshuffling of which segments benefited. The pullback in gold and crypto was more a result of holding costs and the dollar environment. And amid all this, the 30-year yield climbed above 5.7%—and has yet to face demand tests of the same caliber. That may be the real litmus test for the next few trading days.
Data source
OpenAI officially releases
Public market data (U.S. stocks, U.S. Treasuries, gold, crude oil, crypto assets, etc.)
U.S. Department of the Treasury auction results
Fed minutes, CME FedWatch
Reuters, CNBC, FXStreet, CoinGlass
G-7/IEA statement
Overseas institutional research reports and public coverage
Disclaimer: The content of this article is for general information and market commentary only. It is compiled based on publicly available materials as of the time mentioned in the text. Relevant market data, expectations, and probabilities may change with market conditions. The views and investment strategies of third-party institutions, analysts, or other individuals cited in this article represent only their views at the specific time, and do not represent BIT’s views or recommendations. This article does not constitute investment advice, investment research, an offer, solicitation, or a recommendation of any securities, investment products, or trading strategies, nor should it be used as the basis for any investment decision. Financial markets carry risks. Security prices and market performance may fluctuate. Past performance and historical market trends do not indicate or guarantee future results. Investors should independently assess relevant risks based on their own circumstances and seek professional advice when needed.