
DreamWorld
6.6k Posts
DreamWorld
 Square Verified+
Report
Block User

#BinanceTurns7

#BinanceTurns7 task 2

BTC Holder
High-Frequency Trader
4.9 Years
100K Following
45.4K+ Followers
20.9K+ Liked
2 Badges
Posts
All
Quotes
Videos
Live
·
--
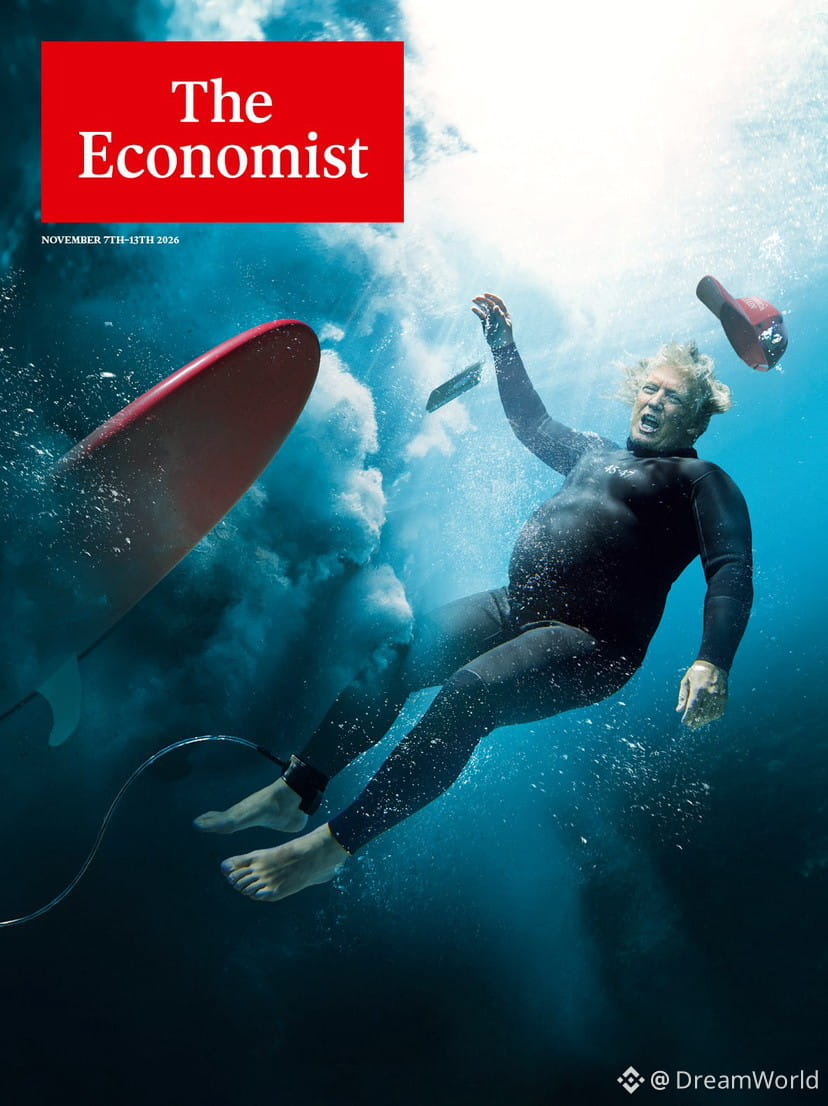
🇺🇸 The Economist: The blue wave crashed over Donald Trump this week.
Republicans suffered their biggest defeat in half a century. But the publication argues that Trump’s humiliation gives America an opportunity.
Voters are tired of the administration’s incompetence and shameless selfishness. (The share of Americans who believe corruption is widespread in their government is now roughly equal to the share in Nigeria.) They are demanding something different. Politicians should let them have it.
Democrats face a difficult balancing act. On the one hand, they want to use their new power to expose and curb corruption associated with MAGA. On the other hand, they will need to work with the president to address the core issues that frustrate voters most.
Republicans face a brutal internal struggle, as some try to preserve the Trumpist party while others seek to revive the idea that character matters in politics.
Even so, as president, Trump retains enormous powers, especially over foreign policy.
A “lame duck” could become even more unpredictable.
Turbulent times lie ahead for the world.😬
🇺🇸 The Economist: The blue wave crashed over Donald Trump this week.
Republicans suffered their biggest defeat in half a century. But the publication argues that Trump’s humiliation gives America an opportunity.
Voters are tired of the administration’s incompetence and shameless selfishness. (The share of Americans who believe corruption is widespread in their government is now roughly equal to the share in Nigeria.) They are demanding something different. Politicians should let them have it.
Democrats face a difficult balancing act. On the one hand, they want to use their new power to expose and curb corruption associated with MAGA. On the other hand, they will need to work with the president to address the core issues that frustrate voters most.
Republicans face a brutal internal struggle, as some try to preserve the Trumpist party while others seek to revive the idea that character matters in politics.
Even so, as president, Trump retains enormous powers, especially over foreign policy.
A “lame duck” could become even more unpredictable.
Turbulent times lie ahead for the world.😬
Republicans suffered their biggest defeat in half a century. But the publication argues that Trump’s humiliation gives America an opportunity.
Voters are tired of the administration’s incompetence and shameless selfishness. (The share of Americans who believe corruption is widespread in their government is now roughly equal to the share in Nigeria.) They are demanding something different. Politicians should let them have it.
Democrats face a difficult balancing act. On the one hand, they want to use their new power to expose and curb corruption associated with MAGA. On the other hand, they will need to work with the president to address the core issues that frustrate voters most.
Republicans face a brutal internal struggle, as some try to preserve the Trumpist party while others seek to revive the idea that character matters in politics.
Even so, as president, Trump retains enormous powers, especially over foreign policy.
A “lame duck” could become even more unpredictable.
Turbulent times lie ahead for the world.😬
2
574
·
--
Verified
🕯 Rotation following the US Congressional elections continues.
The market is pricing in a slowdown in data center construction and rotating out of AI stocks into the rest of the market.
📈 Dow futures +0.7%, Nasdaq-100 -0.9%, Kospi -5%, FTSE 100 and DAX near record highs.
▪️Qualcomm (QCOM) -10% on falling revenue; a memory shortage is hitting smartphone chips. Samsung, SK Hynix and Seagate (STX) are also down. Arm (ARM) -3% despite revenue up 27%. SoftBank -7% after China blocked its $5.4 billion acquisition of ABB’s (ABB) robotics division. Saxo believes hyperscalers with capacity already in place will benefit. Amazon (AMZN) +10% for the week.
🛢 Brent down 19.6% over three sessions on hopes the war with Iran will end.
Toyota +16.7%, its best day since 1987.
▪️Rheinmetall (RHM) -16% after cutting its forecast for the second time this year due to a delay in a Boxer order. BAE Systems (BA) -5%, Leonardo (LDO) -3%.
▪️AppLovin (APP) +19% on revenue up 55%. Zillow (Z) -15%, Dutch Bros (BROS) -14%, Cava (CAVA) -12%. Six Flags (FUN) +9% despite a weak forecast. Airbnb (ABNB) and ConocoPhillips (COP) report today.
▪️The Bank of England raised its rate to 4%. The market puts the odds of a Fed rate hike in December at 79%.
▪️According to Citadel Securities, CTA funds have been shorting stocks for 26 consecutive sessions, so a further rally will force them to buy more.
🕯 Rotation following the US Congressional elections continues.
The market is pricing in a slowdown in data center construction and rotating out of AI stocks into the rest of the market.
📈 Dow futures +0.7%, Nasdaq-100 -0.9%, Kospi -5%, FTSE 100 and DAX near record highs.
▪️Qualcomm (QCOM) -10% on falling revenue; a memory shortage is hitting smartphone chips. Samsung, SK Hynix and Seagate (STX) are also down. Arm (ARM) -3% despite revenue up 27%. SoftBank -7% after China blocked its $5.4 billion acquisition of ABB’s (ABB) robotics division. Saxo believes hyperscalers with capacity already in place will benefit. Amazon (AMZN) +10% for the week.
🛢 Brent down 19.6% over three sessions on hopes the war with Iran will end.
Toyota +16.7%, its best day since 1987.
▪️Rheinmetall (RHM) -16% after cutting its forecast for the second time this year due to a delay in a Boxer order. BAE Systems (BA) -5%, Leonardo (LDO) -3%.
▪️AppLovin (APP) +19% on revenue up 55%. Zillow (Z) -15%, Dutch Bros (BROS) -14%, Cava (CAVA) -12%. Six Flags (FUN) +9% despite a weak forecast. Airbnb (ABNB) and ConocoPhillips (COP) report today.
▪️The Bank of England raised its rate to 4%. The market puts the odds of a Fed rate hike in December at 79%.
▪️According to Citadel Securities, CTA funds have been shorting stocks for 26 consecutive sessions, so a further rally will force them to buy more.
The market is pricing in a slowdown in data center construction and rotating out of AI stocks into the rest of the market.
📈 Dow futures +0.7%, Nasdaq-100 -0.9%, Kospi -5%, FTSE 100 and DAX near record highs.
▪️Qualcomm (QCOM) -10% on falling revenue; a memory shortage is hitting smartphone chips. Samsung, SK Hynix and Seagate (STX) are also down. Arm (ARM) -3% despite revenue up 27%. SoftBank -7% after China blocked its $5.4 billion acquisition of ABB’s (ABB) robotics division. Saxo believes hyperscalers with capacity already in place will benefit. Amazon (AMZN) +10% for the week.
🛢 Brent down 19.6% over three sessions on hopes the war with Iran will end.
Toyota +16.7%, its best day since 1987.
▪️Rheinmetall (RHM) -16% after cutting its forecast for the second time this year due to a delay in a Boxer order. BAE Systems (BA) -5%, Leonardo (LDO) -3%.
▪️AppLovin (APP) +19% on revenue up 55%. Zillow (Z) -15%, Dutch Bros (BROS) -14%, Cava (CAVA) -12%. Six Flags (FUN) +9% despite a weak forecast. Airbnb (ABNB) and ConocoPhillips (COP) report today.
▪️The Bank of England raised its rate to 4%. The market puts the odds of a Fed rate hike in December at 79%.
▪️According to Citadel Securities, CTA funds have been shorting stocks for 26 consecutive sessions, so a further rally will force them to buy more.
2
1.1k
·
--
🫡 You’re already paying for the AI boom
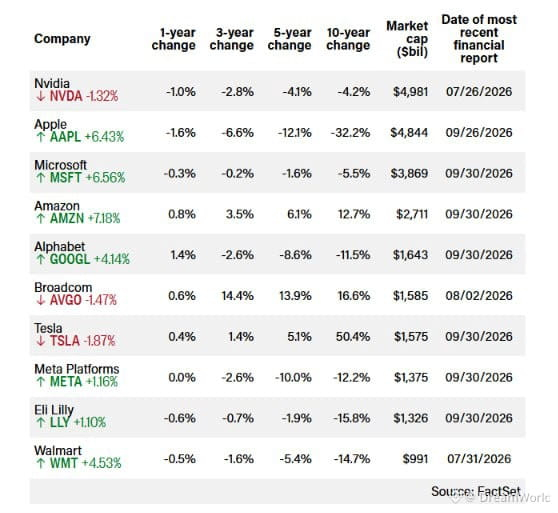
Meta (META) and Alphabet (GOOGL) bought back their own shares for years. Now they’re selling new ones to fund the construction of AI infrastructure.
On October 22, Meta announced a share offering of up to $95 billion. According to MarketWatch’s estimate, that’s about 153 million new shares, or a 5.9% increase in the number of shares.
All else being equal, earnings per share will fall by approximately 5.6%. Some of the shares will be sold as preferred stock, which will convert to common stock in 2029.
Alphabet raised $62 billion over two quarters. According to FactSet, it has the largest year-over-year increase in the number of shares among the ten largest S&P 500 companies, although it reduced its share count by 11.5% over the past 10 years.
Apple is doing the opposite. Over the past 10 years, it spent $769 billion on buybacks, reducing its share count by 32% and boosting earnings per share by 47.5%. In a 2021 letter, Buffett wrote that Berkshire’s stake in Apple had grown on its own, without any new purchases.
Clearly, the world’s most profitable companies can no longer shoulder the cost of AI on their own, and are shifting part of the bill to shareholders.
*The table shows the share counts of the largest S&P 500 companies. Anyone valuing META and GOOGL based on earnings-per-share forecasts should check whether analysts have already accounted for the new shares.
🫡 You’re already paying for the AI boom
Meta (META) and Alphabet (GOOGL) bought back their own shares for years. Now they’re selling new ones to fund the construction of AI infrastructure.
On October 22, Meta announced a share offering of up to $95 billion. According to MarketWatch’s estimate, that’s about 153 million new shares, or a 5.9% increase in the number of shares.
All else being equal, earnings per share will fall by approximately 5.6%. Some of the shares will be sold as preferred stock, which will convert to common stock in 2029.
Alphabet raised $62 billion over two quarters. According to FactSet, it has the largest year-over-year increase in the number of shares among the ten largest S&P 500 companies, although it reduced its share count by 11.5% over the past 10 years.
Apple is doing the opposite. Over the past 10 years, it spent $769 billion on buybacks, reducing its share count by 32% and boosting earnings per share by 47.5%. In a 2021 letter, Buffett wrote that Berkshire’s stake in Apple had grown on its own, without any new purchases.
Clearly, the world’s most profitable companies can no longer shoulder the cost of AI on their own, and are shifting part of the bill to shareholders.
*The table shows the share counts of the largest S&P 500 companies. Anyone valuing META and GOOGL based on earnings-per-share forecasts should check whether analysts have already accounted for the new shares.
Meta (META) and Alphabet (GOOGL) bought back their own shares for years. Now they’re selling new ones to fund the construction of AI infrastructure.
On October 22, Meta announced a share offering of up to $95 billion. According to MarketWatch’s estimate, that’s about 153 million new shares, or a 5.9% increase in the number of shares.
All else being equal, earnings per share will fall by approximately 5.6%. Some of the shares will be sold as preferred stock, which will convert to common stock in 2029.
Alphabet raised $62 billion over two quarters. According to FactSet, it has the largest year-over-year increase in the number of shares among the ten largest S&P 500 companies, although it reduced its share count by 11.5% over the past 10 years.
Apple is doing the opposite. Over the past 10 years, it spent $769 billion on buybacks, reducing its share count by 32% and boosting earnings per share by 47.5%. In a 2021 letter, Buffett wrote that Berkshire’s stake in Apple had grown on its own, without any new purchases.
Clearly, the world’s most profitable companies can no longer shoulder the cost of AI on their own, and are shifting part of the bill to shareholders.
*The table shows the share counts of the largest S&P 500 companies. Anyone valuing META and GOOGL based on earnings-per-share forecasts should check whether analysts have already accounted for the new shares.
2
322
·
--
Verified
🇺🇸 The US votes in midterm congressional elections today.
▪️Futures are mixed: Dow -0.6%, Nasdaq-100 +0.4%.
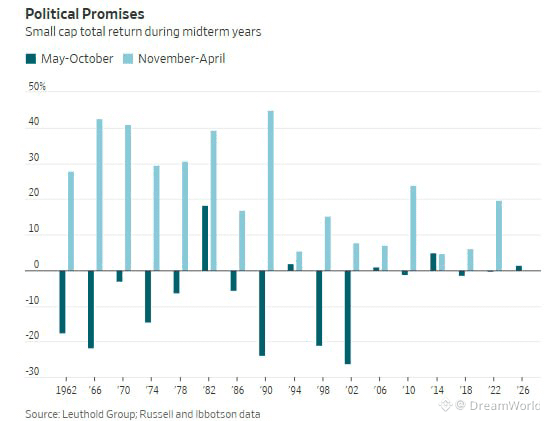
The index entered its third correction of the year yesterday. Deutsche Bank notes that the S&P 500 rose in the fourth quarter in 21 of the 23 midterm election years, by an average of 7%.
▪️Apple (AAPL) -4% despite reporting better-than-expected results. New CEO John Ternus warned of margin pressure from rising memory costs amid the AI boom; services are also slowing. Fundstrat recommends buying the dip, with a target of $368 in early 2027.
▪️Palantir (PLTR) -6% despite revenue growth of 96% and a raised forecast. New contracts fell to $2.9 billion from $3.4 billion, and the market doubts that this pace will justify a valuation of over $400 billion.
▪️Apollo (APO) posted a $1.06 billion loss due to investment losses in its pension unit.
Fabrinet (FN) +10% on data center demand,
Lattice Semiconductor (LSCC) +9% on a strong forecast,
Baird raised its price target to $195.
AMD (AMD) is rising ahead of its after-hours earnings report.
Marathon Petroleum (MPC) is up as CVR Energy (CVI) is close to buying its refinery for over $4 billion.
Lufthansa (LHA) and Philips (PHIA) are rising after strong quarters.
🛢 Brent is holding near $105 after yesterday’s 7.6% “discount” and the “secret” US strike on Iran. ING believes the risk of escalation has not yet passed.
▪️The 10-year yield is up 3 bps to 4.94%.
🇺🇸 The US votes in midterm congressional elections today.
▪️Futures are mixed: Dow -0.6%, Nasdaq-100 +0.4%.
The index entered its third correction of the year yesterday. Deutsche Bank notes that the S&P 500 rose in the fourth quarter in 21 of the 23 midterm election years, by an average of 7%.
▪️Apple (AAPL) -4% despite reporting better-than-expected results. New CEO John Ternus warned of margin pressure from rising memory costs amid the AI boom; services are also slowing. Fundstrat recommends buying the dip, with a target of $368 in early 2027.
▪️Palantir (PLTR) -6% despite revenue growth of 96% and a raised forecast. New contracts fell to $2.9 billion from $3.4 billion, and the market doubts that this pace will justify a valuation of over $400 billion.
▪️Apollo (APO) posted a $1.06 billion loss due to investment losses in its pension unit.
Fabrinet (FN) +10% on data center demand,
Lattice Semiconductor (LSCC) +9% on a strong forecast,
Baird raised its price target to $195.
AMD (AMD) is rising ahead of its after-hours earnings report.
Marathon Petroleum (MPC) is up as CVR Energy (CVI) is close to buying its refinery for over $4 billion.
Lufthansa (LHA) and Philips (PHIA) are rising after strong quarters.
🛢 Brent is holding near $105 after yesterday’s 7.6% “discount” and the “secret” US strike on Iran. ING believes the risk of escalation has not yet passed.
▪️The 10-year yield is up 3 bps to 4.94%.
▪️Futures are mixed: Dow -0.6%, Nasdaq-100 +0.4%.
The index entered its third correction of the year yesterday. Deutsche Bank notes that the S&P 500 rose in the fourth quarter in 21 of the 23 midterm election years, by an average of 7%.
▪️Apple (AAPL) -4% despite reporting better-than-expected results. New CEO John Ternus warned of margin pressure from rising memory costs amid the AI boom; services are also slowing. Fundstrat recommends buying the dip, with a target of $368 in early 2027.
▪️Palantir (PLTR) -6% despite revenue growth of 96% and a raised forecast. New contracts fell to $2.9 billion from $3.4 billion, and the market doubts that this pace will justify a valuation of over $400 billion.
▪️Apollo (APO) posted a $1.06 billion loss due to investment losses in its pension unit.
Fabrinet (FN) +10% on data center demand,
Lattice Semiconductor (LSCC) +9% on a strong forecast,
Baird raised its price target to $195.
AMD (AMD) is rising ahead of its after-hours earnings report.
Marathon Petroleum (MPC) is up as CVR Energy (CVI) is close to buying its refinery for over $4 billion.
Lufthansa (LHA) and Philips (PHIA) are rising after strong quarters.
🛢 Brent is holding near $105 after yesterday’s 7.6% “discount” and the “secret” US strike on Iran. ING believes the risk of escalation has not yet passed.
▪️The 10-year yield is up 3 bps to 4.94%.
3
627
·
--
Article
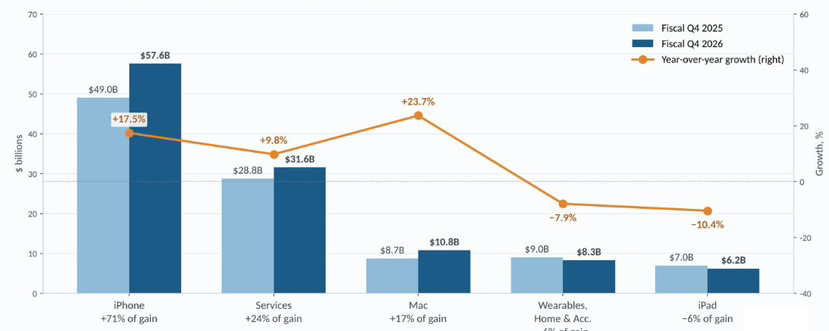
🍏 How did new CEO John Ternus’s first earnings report go?Ternus himself didn’t say anything specific, but CFO Kevan Parekh gave a forecast that sent shares down as much as 4% in after-hours trading.
📊 In Q4 (October–December), Apple expects revenue growth of 7–10%, compared with 12% in the previous quarter, while margins will decline due to rising memory prices.
🍏 How did new CEO John Ternus’s first earnings report go?
Ternus himself didn’t say anything specific, but CFO Kevan Parekh gave a forecast that sent shares down as much as 4% in after-hours trading.
📊 In Q4 (October–December), Apple expects revenue growth of 7–10%, compared with 12% in the previous quarter, while margins will decline due to rising memory prices.
📊 In Q4 (October–December), Apple expects revenue growth of 7–10%, compared with 12% in the previous quarter, while margins will decline due to rising memory prices.
3
345
·
--
Verified
✍️ What Goldman is betting on if Democrats take Congress
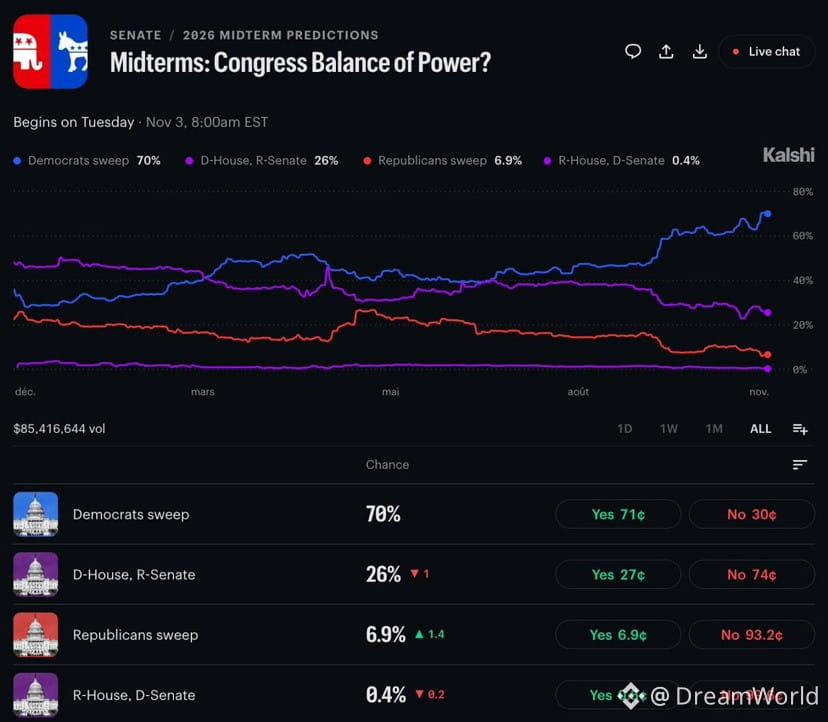
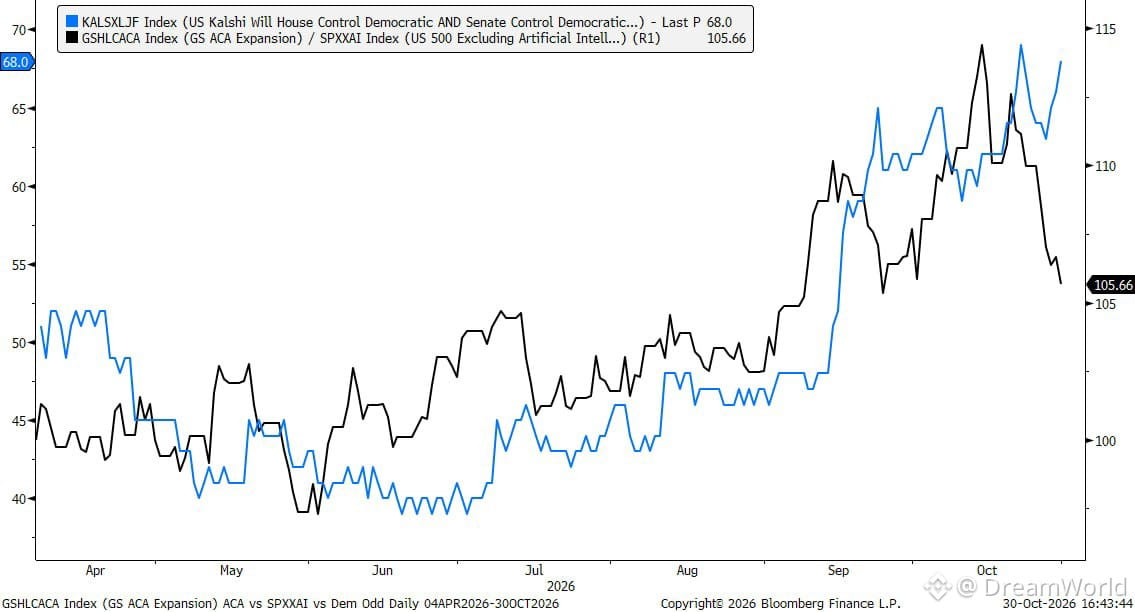
The odds of Democrats winning both chambers on Kalshi have reached 70%, while stocks that should benefit have fallen for three weeks. Goldman sees an opportunity in that gap.
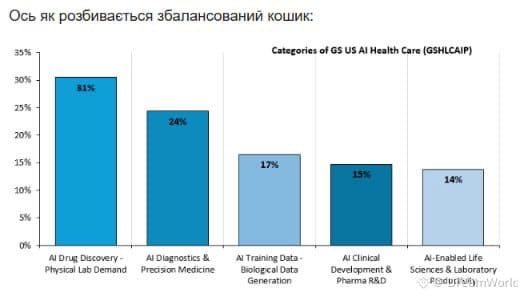
The bank’s favorite is a basket of companies that benefit from the Obamacare health insurance program: hospitals, clinics, and insurers. Democrats want to restore the subsidies that expired at the end of 2025, which would mean fewer unpaid bills for these companies. Since the start of October, the basket has lagged the market excluding AI by 7%, so Goldman sees this as a good entry point.
Two other ideas are about electricity🔌. Utilities could benefit if new capacity is built to address high electricity prices, while makers of AI hardware could lose out if the cost of grid upgrades is passed on to data centers.
The problem with all these forecasts is that any law would have to be signed by Trump, and he has promised to veto anything from Democrats.
📊 The preliminary election results will be in on Wednesday, while any subsidies, if they do materialize, won’t come anytime soon. So the gap between expectations and the outcome could be substantial.
✍️ What Goldman is betting on if Democrats take Congress
The odds of Democrats winning both chambers on Kalshi have reached 70%, while stocks that should benefit have fallen for three weeks. Goldman sees an opportunity in that gap.
The bank’s favorite is a basket of companies that benefit from the Obamacare health insurance program: hospitals, clinics, and insurers. Democrats want to restore the subsidies that expired at the end of 2025, which would mean fewer unpaid bills for these companies. Since the start of October, the basket has lagged the market excluding AI by 7%, so Goldman sees this as a good entry point.
Two other ideas are about electricity🔌. Utilities could benefit if new capacity is built to address high electricity prices, while makers of AI hardware could lose out if the cost of grid upgrades is passed on to data centers.
The problem with all these forecasts is that any law would have to be signed by Trump, and he has promised to veto anything from Democrats.
📊 The preliminary election results will be in on Wednesday, while any subsidies, if they do materialize, won’t come anytime soon. So the gap between expectations and the outcome could be substantial.
The odds of Democrats winning both chambers on Kalshi have reached 70%, while stocks that should benefit have fallen for three weeks. Goldman sees an opportunity in that gap.
The bank’s favorite is a basket of companies that benefit from the Obamacare health insurance program: hospitals, clinics, and insurers. Democrats want to restore the subsidies that expired at the end of 2025, which would mean fewer unpaid bills for these companies. Since the start of October, the basket has lagged the market excluding AI by 7%, so Goldman sees this as a good entry point.
Two other ideas are about electricity🔌. Utilities could benefit if new capacity is built to address high electricity prices, while makers of AI hardware could lose out if the cost of grid upgrades is passed on to data centers.
The problem with all these forecasts is that any law would have to be signed by Trump, and he has promised to veto anything from Democrats.
📊 The preliminary election results will be in on Wednesday, while any subsidies, if they do materialize, won’t come anytime soon. So the gap between expectations and the outcome could be substantial.
3
763
·
--
Verified
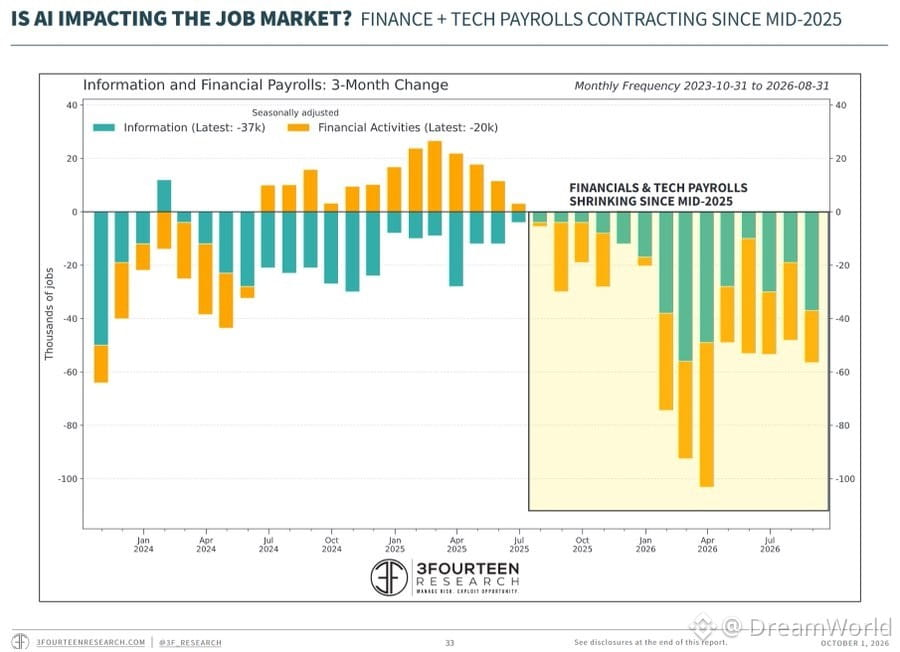
🧐 The impact of AI on jobs has been discussed for several years, but until now it’s mostly been predictions.
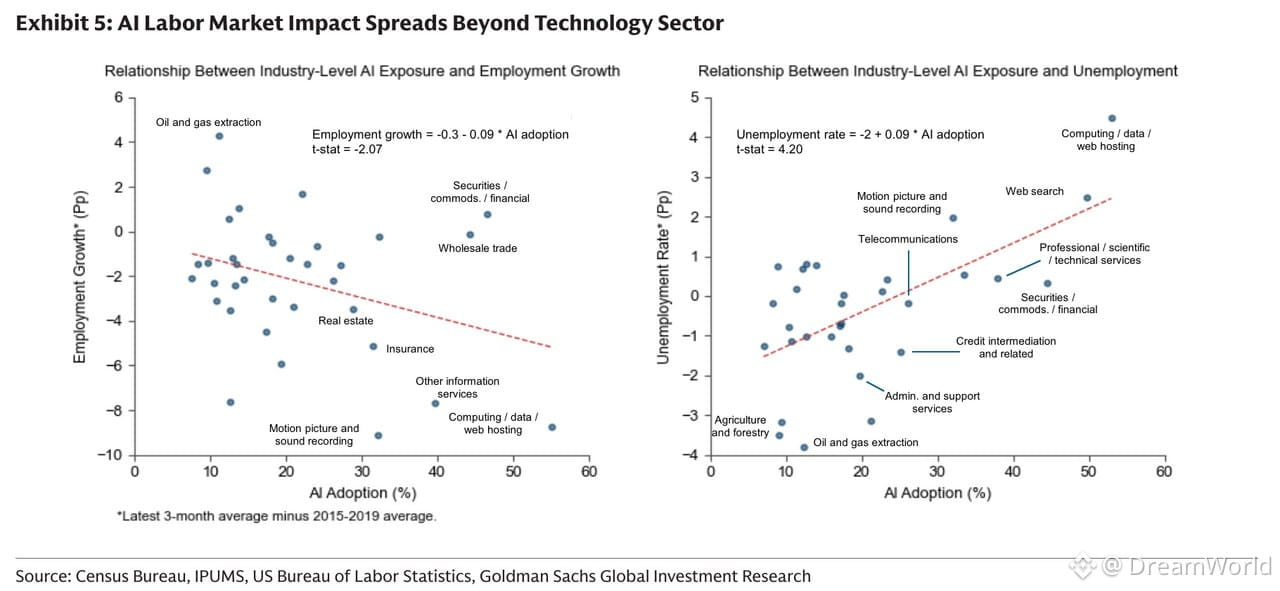
Now Goldman sees the effect in the data. Where companies are adopting AI more actively, employment is growing more slowly and unemployment is higher. And it’s no longer just IT, but also finance, insurance, and professional services.
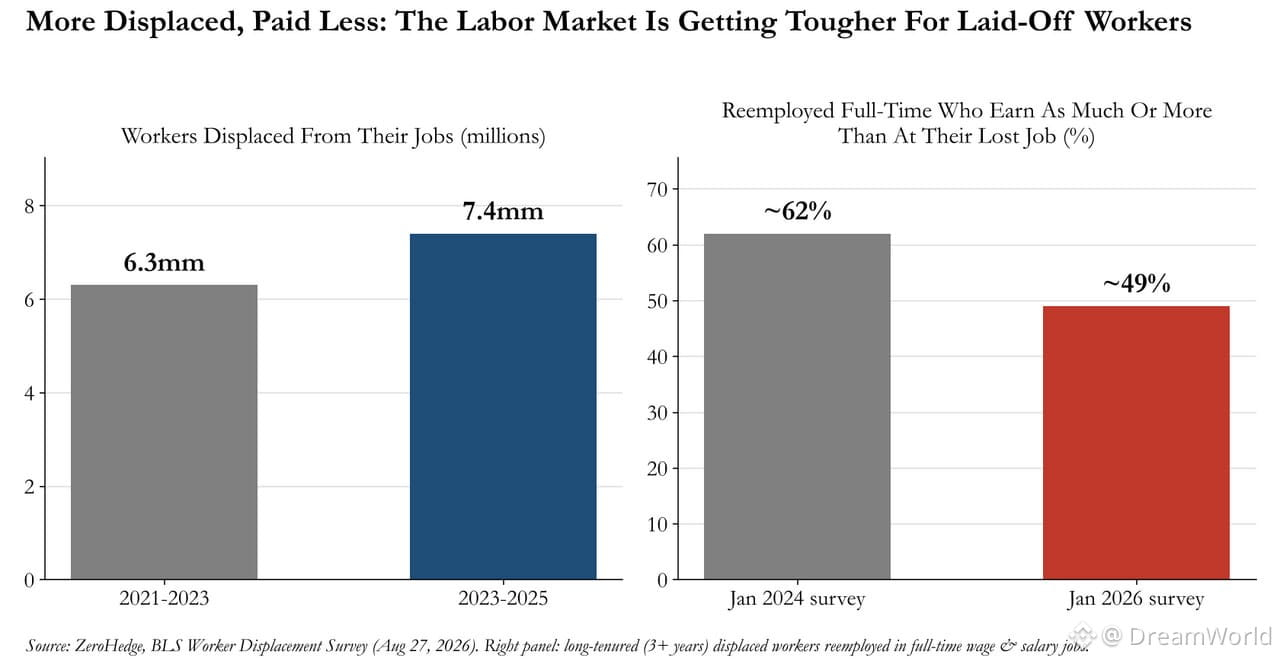
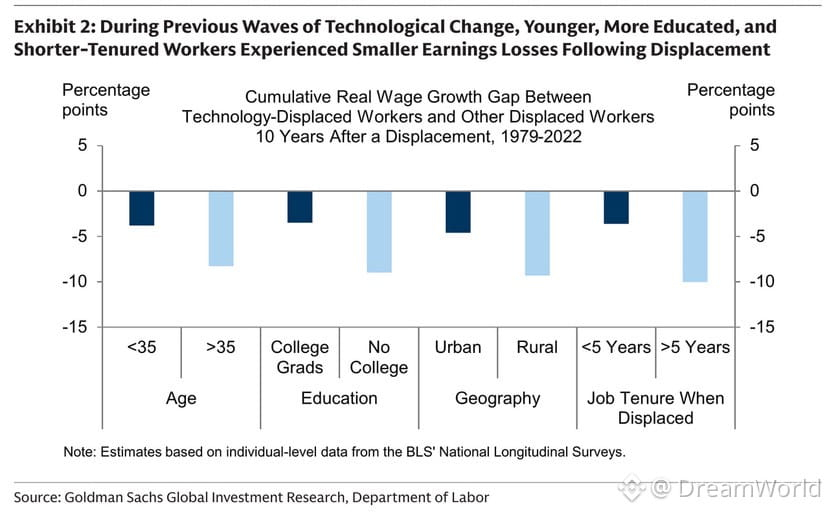
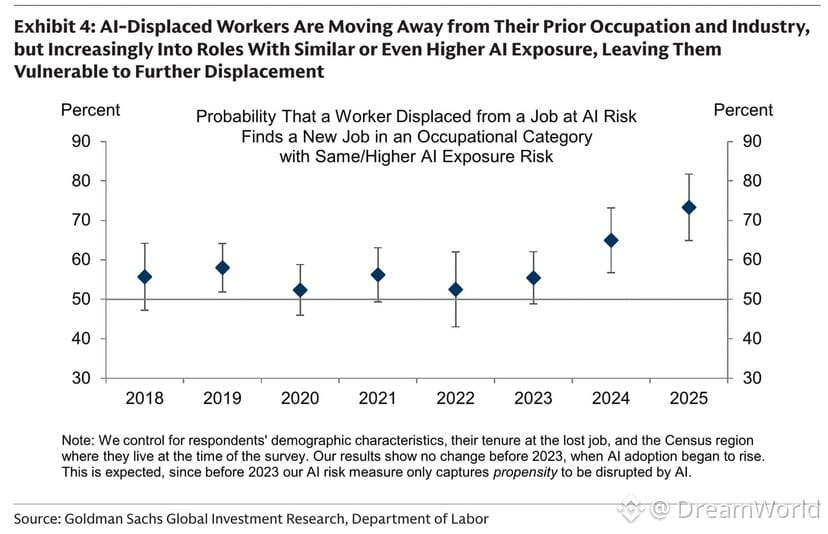
According to their data, people laid off because of AI have a harder time returning to the job market. On average, they spend an extra month looking for work, and a year later, their risk of remaining unemployed is 10% higher. Younger workers (under 35) adapt faster, as always.
Of course, they can’t retrain quickly, so almost 75% of them end up in new roles that AI can also automate. People look for jobs that match their familiar skills and find themselves exposed to a potential next wave of layoffs.
There haven’t been mass layoffs yet because companies usually automate during recessions, when a downturn gives them a reason to cut staff. So the next recession could bring regular layoffs alongside those delayed by AI. Overall, Goldman estimates that during the transition, AI could displace up to 9% of US workers—about 15 million people.
The example of Microsoft is telling.
On Friday, November 6, the October employment report will be released. BofA expects +75,000.
🧐 The impact of AI on jobs has been discussed for several years, but until now it’s mostly been predictions.
Now Goldman sees the effect in the data. Where companies are adopting AI more actively, employment is growing more slowly and unemployment is higher. And it’s no longer just IT, but also finance, insurance, and professional services.
According to their data, people laid off because of AI have a harder time returning to the job market. On average, they spend an extra month looking for work, and a year later, their risk of remaining unemployed is 10% higher. Younger workers (under 35) adapt faster, as always.
Of course, they can’t retrain quickly, so almost 75% of them end up in new roles that AI can also automate. People look for jobs that match their familiar skills and find themselves exposed to a potential next wave of layoffs.
There haven’t been mass layoffs yet because companies usually automate during recessions, when a downturn gives them a reason to cut staff. So the next recession could bring regular layoffs alongside those delayed by AI. Overall, Goldman estimates that during the transition, AI could displace up to 9% of US workers—about 15 million people.
The example of Microsoft is telling.
On Friday, November 6, the October employment report will be released. BofA expects +75,000.
Now Goldman sees the effect in the data. Where companies are adopting AI more actively, employment is growing more slowly and unemployment is higher. And it’s no longer just IT, but also finance, insurance, and professional services.
According to their data, people laid off because of AI have a harder time returning to the job market. On average, they spend an extra month looking for work, and a year later, their risk of remaining unemployed is 10% higher. Younger workers (under 35) adapt faster, as always.
Of course, they can’t retrain quickly, so almost 75% of them end up in new roles that AI can also automate. People look for jobs that match their familiar skills and find themselves exposed to a potential next wave of layoffs.
There haven’t been mass layoffs yet because companies usually automate during recessions, when a downturn gives them a reason to cut staff. So the next recession could bring regular layoffs alongside those delayed by AI. Overall, Goldman estimates that during the transition, AI could displace up to 9% of US workers—about 15 million people.
The example of Microsoft is telling.
On Friday, November 6, the October employment report will be released. BofA expects +75,000.
3
690
·
--
Hedge funds are cutting risk at the fastest pace since 2016.
This is the biggest deleveraging in 10 years 🤯
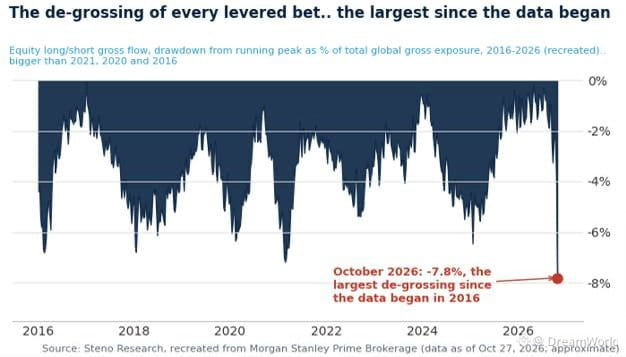
According to Morgan Stanley, the gross exposure of long/short funds (the sum of their bets on rising and falling prices) has fallen 7.8% from its peak. That’s more than during the sell-offs of 2020 and 2021.
Semiconductors, memory, turbines, cooling, and cloud services are falling the hardest. Funds had poured money into these areas, jumping along the AI supply chain from one bottleneck to the next. The reversal came without an obvious cause: hyperscalers are still investing in data centers, AI labs are going public to fund this spending, and equipment remains in short supply.
Funds may have started doubting that this spending can continue forever, or they may simply be taking profits before year-end.
These are technical selling pressures, so quality companies are getting cheaper for reasons unrelated to their own problems. For those who can pick the right one, this is an opportunity—but no one is promising a quick rebound.
Hedge funds are cutting risk at the fastest pace since 2016.
This is the biggest deleveraging in 10 years 🤯
According to Morgan Stanley, the gross exposure of long/short funds (the sum of their bets on rising and falling prices) has fallen 7.8% from its peak. That’s more than during the sell-offs of 2020 and 2021.
Semiconductors, memory, turbines, cooling, and cloud services are falling the hardest. Funds had poured money into these areas, jumping along the AI supply chain from one bottleneck to the next. The reversal came without an obvious cause: hyperscalers are still investing in data centers, AI labs are going public to fund this spending, and equipment remains in short supply.
Funds may have started doubting that this spending can continue forever, or they may simply be taking profits before year-end.
These are technical selling pressures, so quality companies are getting cheaper for reasons unrelated to their own problems. For those who can pick the right one, this is an opportunity—but no one is promising a quick rebound.
This is the biggest deleveraging in 10 years 🤯
According to Morgan Stanley, the gross exposure of long/short funds (the sum of their bets on rising and falling prices) has fallen 7.8% from its peak. That’s more than during the sell-offs of 2020 and 2021.
Semiconductors, memory, turbines, cooling, and cloud services are falling the hardest. Funds had poured money into these areas, jumping along the AI supply chain from one bottleneck to the next. The reversal came without an obvious cause: hyperscalers are still investing in data centers, AI labs are going public to fund this spending, and equipment remains in short supply.
Funds may have started doubting that this spending can continue forever, or they may simply be taking profits before year-end.
These are technical selling pressures, so quality companies are getting cheaper for reasons unrelated to their own problems. For those who can pick the right one, this is an opportunity—but no one is promising a quick rebound.
2
414
·
--
Bullish
Verified
📈 U.S. futures rebound after Friday’s selloff.
Nasdaq ended October down 5.3%, its worst month since March 2025.
In premarket trading, Intel (INTC), Nvidia (NVDA), and SpaceX (SPCX) are rising. Intel had its worst day ever on Friday after a weak earnings report.
🛢Brent crude is down 4% to $109, while WTI is below $100. According to Axios, Trump wants to give negotiations with Iran a chance instead of launching new strikes.
▪️Deutsche Bank believes the market is underestimating inflation because it isn’t factoring in the pass-through of high energy costs to prices in other sectors.
▪️The 10-year Treasury yield fell to 4.91%. Miller Tabak sees this as a flight to safety and a possible signal of an equity market correction.
▪️According to BTIG, the Nasdaq-100 formed a bearish engulfing pattern on its monthly chart in October. In all 7 such cases since 1985, the index was higher six months later, but it fell by at least 8.5% each time.🤔
▪️Marvell (MRVL) and Lumentum (LITE) are merging in a $115 billion deal.
Kioxia (285A) is down 16% on weak earnings, while Alstom (ALO) is down 28% after lowering its margin forecast.
📊 Reporting today: Marriott (MAR), Fox (FOX), Entergy (ETR), Estée Lauder (EL), Tower Semiconductor (TSEM), Check Point (CHKP), and Tempus AI (TEM).
👀 After the close: Apple (AAPL), Palantir (PLTR), ON Semiconductor (ON), Fabrinet (FN), and Aehr Test Systems (AEHR).
Congressional elections are tomorrow; labor market data is due Friday.
📈 U.S. futures rebound after Friday’s selloff.
Nasdaq ended October down 5.3%, its worst month since March 2025.
In premarket trading, Intel (INTC), Nvidia (NVDA), and SpaceX (SPCX) are rising. Intel had its worst day ever on Friday after a weak earnings report.
🛢Brent crude is down 4% to $109, while WTI is below $100. According to Axios, Trump wants to give negotiations with Iran a chance instead of launching new strikes.
▪️Deutsche Bank believes the market is underestimating inflation because it isn’t factoring in the pass-through of high energy costs to prices in other sectors.
▪️The 10-year Treasury yield fell to 4.91%. Miller Tabak sees this as a flight to safety and a possible signal of an equity market correction.
▪️According to BTIG, the Nasdaq-100 formed a bearish engulfing pattern on its monthly chart in October. In all 7 such cases since 1985, the index was higher six months later, but it fell by at least 8.5% each time.🤔
▪️Marvell (MRVL) and Lumentum (LITE) are merging in a $115 billion deal.
Kioxia (285A) is down 16% on weak earnings, while Alstom (ALO) is down 28% after lowering its margin forecast.
📊 Reporting today: Marriott (MAR), Fox (FOX), Entergy (ETR), Estée Lauder (EL), Tower Semiconductor (TSEM), Check Point (CHKP), and Tempus AI (TEM).
👀 After the close: Apple (AAPL), Palantir (PLTR), ON Semiconductor (ON), Fabrinet (FN), and Aehr Test Systems (AEHR).
Congressional elections are tomorrow; labor market data is due Friday.
Nasdaq ended October down 5.3%, its worst month since March 2025.
In premarket trading, Intel (INTC), Nvidia (NVDA), and SpaceX (SPCX) are rising. Intel had its worst day ever on Friday after a weak earnings report.
🛢Brent crude is down 4% to $109, while WTI is below $100. According to Axios, Trump wants to give negotiations with Iran a chance instead of launching new strikes.
▪️Deutsche Bank believes the market is underestimating inflation because it isn’t factoring in the pass-through of high energy costs to prices in other sectors.
▪️The 10-year Treasury yield fell to 4.91%. Miller Tabak sees this as a flight to safety and a possible signal of an equity market correction.
▪️According to BTIG, the Nasdaq-100 formed a bearish engulfing pattern on its monthly chart in October. In all 7 such cases since 1985, the index was higher six months later, but it fell by at least 8.5% each time.🤔
▪️Marvell (MRVL) and Lumentum (LITE) are merging in a $115 billion deal.
Kioxia (285A) is down 16% on weak earnings, while Alstom (ALO) is down 28% after lowering its margin forecast.
📊 Reporting today: Marriott (MAR), Fox (FOX), Entergy (ETR), Estée Lauder (EL), Tower Semiconductor (TSEM), Check Point (CHKP), and Tempus AI (TEM).
👀 After the close: Apple (AAPL), Palantir (PLTR), ON Semiconductor (ON), Fabrinet (FN), and Aehr Test Systems (AEHR).
Congressional elections are tomorrow; labor market data is due Friday.
2
595
·
--
Verified
📊 Bloomberg compiled analysts’ scenarios on who will win the U.S. midterm elections and what will happen to the market
Wall Street would be happiest with a Congress in which neither party has the upper hand, according to BofA and Citi.
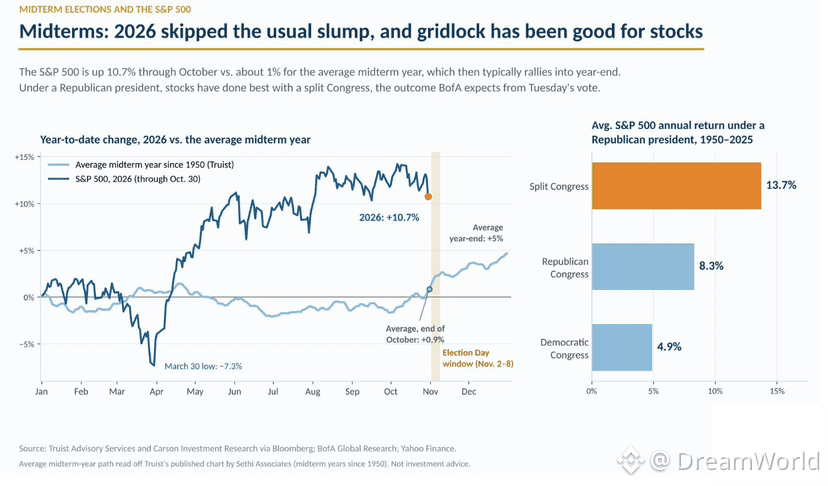
History is on their side: according to Carson Investment Research, since 1950, with a Republican president and a divided Congress, the S&P 500 has risen by an average of 13.7% a year; with a Republican Congress, by 8.3%; and with a Democratic Congress, by just 4.9%.
The market is most worried about a Democratic sweep, which Kalshi is currently predicting. Laws won’t pass without Trump’s signature, but Democrats could put pressure on AI through hearings and investigations. Defense companies have already fallen in anticipation of tighter spending controls, while healthcare could benefit from the return of Medicaid funding. A Republican victory, which polls suggest is unlikely, would preserve a favorable climate for AI.
Wells Fargo’s statistics offer some reassurance: since World War II, the S&P 500 has always risen in the 12 months following midterm elections.
That’s the longer-term outlook. The picture is different over the next few weeks. According to Truist, in an average election year, the market gains just 1% through the end of October, then adds about 3 percentage points of its eventual 5% gain after the vote.
📊 Bloomberg compiled analysts’ scenarios on who will win the U.S. midterm elections and what will happen to the market
Wall Street would be happiest with a Congress in which neither party has the upper hand, according to BofA and Citi.
History is on their side: according to Carson Investment Research, since 1950, with a Republican president and a divided Congress, the S&P 500 has risen by an average of 13.7% a year; with a Republican Congress, by 8.3%; and with a Democratic Congress, by just 4.9%.
The market is most worried about a Democratic sweep, which Kalshi is currently predicting. Laws won’t pass without Trump’s signature, but Democrats could put pressure on AI through hearings and investigations. Defense companies have already fallen in anticipation of tighter spending controls, while healthcare could benefit from the return of Medicaid funding. A Republican victory, which polls suggest is unlikely, would preserve a favorable climate for AI.
Wells Fargo’s statistics offer some reassurance: since World War II, the S&P 500 has always risen in the 12 months following midterm elections.
That’s the longer-term outlook. The picture is different over the next few weeks. According to Truist, in an average election year, the market gains just 1% through the end of October, then adds about 3 percentage points of its eventual 5% gain after the vote.
Wall Street would be happiest with a Congress in which neither party has the upper hand, according to BofA and Citi.
History is on their side: according to Carson Investment Research, since 1950, with a Republican president and a divided Congress, the S&P 500 has risen by an average of 13.7% a year; with a Republican Congress, by 8.3%; and with a Democratic Congress, by just 4.9%.
The market is most worried about a Democratic sweep, which Kalshi is currently predicting. Laws won’t pass without Trump’s signature, but Democrats could put pressure on AI through hearings and investigations. Defense companies have already fallen in anticipation of tighter spending controls, while healthcare could benefit from the return of Medicaid funding. A Republican victory, which polls suggest is unlikely, would preserve a favorable climate for AI.
Wells Fargo’s statistics offer some reassurance: since World War II, the S&P 500 has always risen in the 12 months following midterm elections.
That’s the longer-term outlook. The picture is different over the next few weeks. According to Truist, in an average election year, the market gains just 1% through the end of October, then adds about 3 percentage points of its eventual 5% gain after the vote.
4
757
·
--
Verified
🍂 October is over.
The index is almost unchanged.
Inside, things are much more interesting.
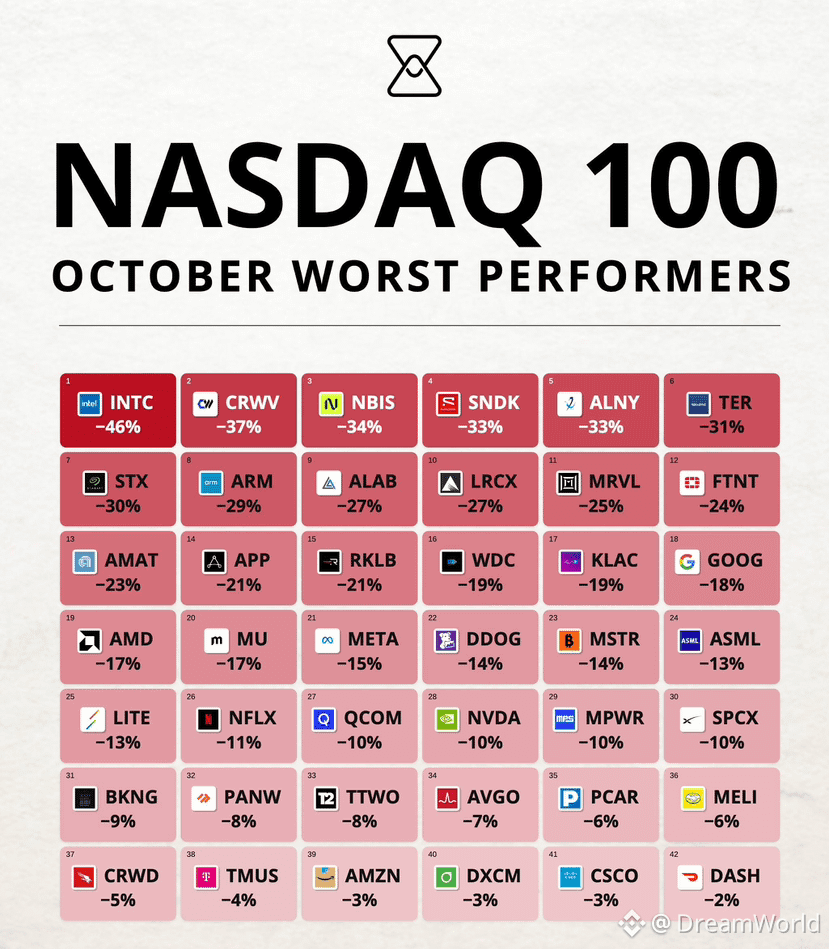
The S&P 500 was down 0.9% for the month, while Goldman’s basket of momentum leaders fell 18.6%.
And that makes four months in a row.
The AI supply chain took the biggest hit. Among the Nasdaq 100’s worst performers were Intel (INTC), down 46%; neoclouds CoreWeave (CRWV), down 37%, and Nebius (NBIS), down 34%; along with memory stocks (SNDK, MU) and chip equipment makers (LRCX, KLAC). Alphabet (GOOG) fell 18% because, despite a $561 billion cloud backlog, it burned through $9.1 billion in cash flow and is selling its shares instead of buying them back.
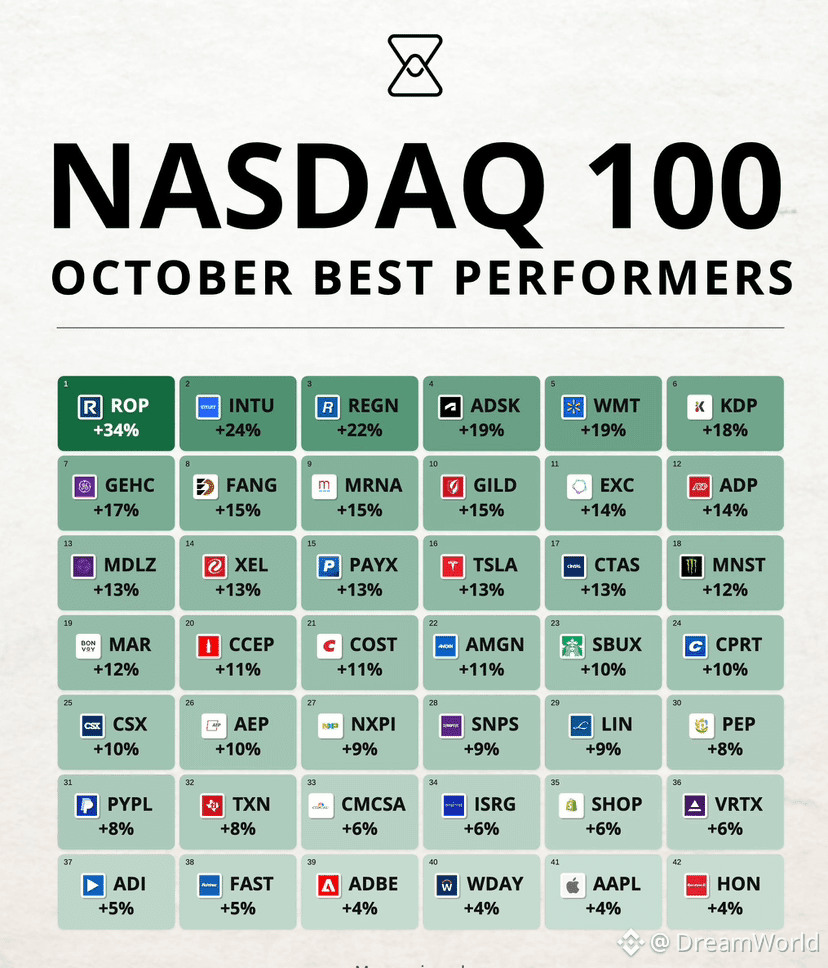
💪 Meanwhile, the companies once seen as AI victims rose: software firms Roper (ROP) gained 34%, Intuit (INTU) 24%, and Autodesk (ADSK) 19%, along with Walmart (WMT), pharma, and utilities.
The reason is the cost of money and lowered expectations. AI-related debt has already topped $400 billion this year (Goldman), so bond buyers have become more selective. Microsoft (MSFT) easily borrowed $25 billion because it has free cash flow, while money is getting more expensive for everyone else.
Deutsche Bank thinks the tech selloff has gone too far. But will investors agree?
This week, elections on Tuesday and Apple’s (AAPL) earnings report will add to the news noise.
🍂 October is over.
The index is almost unchanged.
Inside, things are much more interesting.
The S&P 500 was down 0.9% for the month, while Goldman’s basket of momentum leaders fell 18.6%.
And that makes four months in a row.
The AI supply chain took the biggest hit. Among the Nasdaq 100’s worst performers were Intel (INTC), down 46%; neoclouds CoreWeave (CRWV), down 37%, and Nebius (NBIS), down 34%; along with memory stocks (SNDK, MU) and chip equipment makers (LRCX, KLAC). Alphabet (GOOG) fell 18% because, despite a $561 billion cloud backlog, it burned through $9.1 billion in cash flow and is selling its shares instead of buying them back.
💪 Meanwhile, the companies once seen as AI victims rose: software firms Roper (ROP) gained 34%, Intuit (INTU) 24%, and Autodesk (ADSK) 19%, along with Walmart (WMT), pharma, and utilities.
The reason is the cost of money and lowered expectations. AI-related debt has already topped $400 billion this year (Goldman), so bond buyers have become more selective. Microsoft (MSFT) easily borrowed $25 billion because it has free cash flow, while money is getting more expensive for everyone else.
Deutsche Bank thinks the tech selloff has gone too far. But will investors agree?
This week, elections on Tuesday and Apple’s (AAPL) earnings report will add to the news noise.
The index is almost unchanged.
Inside, things are much more interesting.
The S&P 500 was down 0.9% for the month, while Goldman’s basket of momentum leaders fell 18.6%.
And that makes four months in a row.
The AI supply chain took the biggest hit. Among the Nasdaq 100’s worst performers were Intel (INTC), down 46%; neoclouds CoreWeave (CRWV), down 37%, and Nebius (NBIS), down 34%; along with memory stocks (SNDK, MU) and chip equipment makers (LRCX, KLAC). Alphabet (GOOG) fell 18% because, despite a $561 billion cloud backlog, it burned through $9.1 billion in cash flow and is selling its shares instead of buying them back.
💪 Meanwhile, the companies once seen as AI victims rose: software firms Roper (ROP) gained 34%, Intuit (INTU) 24%, and Autodesk (ADSK) 19%, along with Walmart (WMT), pharma, and utilities.
The reason is the cost of money and lowered expectations. AI-related debt has already topped $400 billion this year (Goldman), so bond buyers have become more selective. Microsoft (MSFT) easily borrowed $25 billion because it has free cash flow, while money is getting more expensive for everyone else.
Deutsche Bank thinks the tech selloff has gone too far. But will investors agree?
This week, elections on Tuesday and Apple’s (AAPL) earnings report will add to the news noise.
7
1.8k
·
--
Verified
📊 Earnings season in full swing
Nasdaq-100 futures -1.1% after Alphabet (GOOG) reported; shares -10% in premarket trading.
▪️Microsoft (MSFT) +3% on accelerating cloud business growth. For the first time since 2017, the company is selling at least $25 billion in bonds to fund AI.
Caterpillar (CAT) -9%. Revenue rose 17% to $20.68 billion, but came in below inflated expectations.
▪️Samsung -4%, as profit fell short of forecasts.
DoorDash (DASH) +7%, buying Instacart (CART) for $17 billion; CART +5%.
Shell (SHEL) +3% on refining profits.
Chipotle (CMG) and eBay (EBAY) +6%, Blue Owl (OWL) +5%.
▪️Adidas' (ADS) record quarter, up 3.5%, lifted Nike (NKE), Lululemon (LULU) and Deckers (DECK).
▪️Robinhood (HOOD) -1.7%, Strategy (MSTR) -2.7%.
👀 After the close, Amazon (AMZN), Intel (INTC), Sandisk (SNDK) and Starbucks (SBUX) report. Options are pricing in moves of ±6.8%, ±7.8%, ±6.9% and ±4.6%, respectively.
🇺🇸 U.S. Q3 GDP +3.4% versus a 3.1% forecast.
PCE inflation at 3.6%, core at 3.1%. BofA now expects Fed rate hikes in December and March.
🇪🇺 Lagarde is leaving the ECB in February amid a selloff in French bonds.
📊 Earnings season in full swing
Nasdaq-100 futures -1.1% after Alphabet (GOOG) reported; shares -10% in premarket trading.
▪️Microsoft (MSFT) +3% on accelerating cloud business growth. For the first time since 2017, the company is selling at least $25 billion in bonds to fund AI.
Caterpillar (CAT) -9%. Revenue rose 17% to $20.68 billion, but came in below inflated expectations.
▪️Samsung -4%, as profit fell short of forecasts.
DoorDash (DASH) +7%, buying Instacart (CART) for $17 billion; CART +5%.
Shell (SHEL) +3% on refining profits.
Chipotle (CMG) and eBay (EBAY) +6%, Blue Owl (OWL) +5%.
▪️Adidas' (ADS) record quarter, up 3.5%, lifted Nike (NKE), Lululemon (LULU) and Deckers (DECK).
▪️Robinhood (HOOD) -1.7%, Strategy (MSTR) -2.7%.
👀 After the close, Amazon (AMZN), Intel (INTC), Sandisk (SNDK) and Starbucks (SBUX) report. Options are pricing in moves of ±6.8%, ±7.8%, ±6.9% and ±4.6%, respectively.
🇺🇸 U.S. Q3 GDP +3.4% versus a 3.1% forecast.
PCE inflation at 3.6%, core at 3.1%. BofA now expects Fed rate hikes in December and March.
🇪🇺 Lagarde is leaving the ECB in February amid a selloff in French bonds.
Nasdaq-100 futures -1.1% after Alphabet (GOOG) reported; shares -10% in premarket trading.
▪️Microsoft (MSFT) +3% on accelerating cloud business growth. For the first time since 2017, the company is selling at least $25 billion in bonds to fund AI.
Caterpillar (CAT) -9%. Revenue rose 17% to $20.68 billion, but came in below inflated expectations.
▪️Samsung -4%, as profit fell short of forecasts.
DoorDash (DASH) +7%, buying Instacart (CART) for $17 billion; CART +5%.
Shell (SHEL) +3% on refining profits.
Chipotle (CMG) and eBay (EBAY) +6%, Blue Owl (OWL) +5%.
▪️Adidas' (ADS) record quarter, up 3.5%, lifted Nike (NKE), Lululemon (LULU) and Deckers (DECK).
▪️Robinhood (HOOD) -1.7%, Strategy (MSTR) -2.7%.
👀 After the close, Amazon (AMZN), Intel (INTC), Sandisk (SNDK) and Starbucks (SBUX) report. Options are pricing in moves of ±6.8%, ±7.8%, ±6.9% and ±4.6%, respectively.
🇺🇸 U.S. Q3 GDP +3.4% versus a 3.1% forecast.
PCE inflation at 3.6%, core at 3.1%. BofA now expects Fed rate hikes in December and March.
🇪🇺 Lagarde is leaving the ECB in February amid a selloff in French bonds.
2
3
827
·
--
Said is holding coins $NIL .
This is our past and future!
And the future is beautiful when my subscribers' accounts get blown up!
I hope you made some good money yesterday!
Good luck trading, everyone!🤑
Said is holding coins $NIL .
This is our past and future!
And the future is beautiful when my subscribers' accounts get blown up!
I hope you made some good money yesterday!
Good luck trading, everyone!🤑
This is our past and future!
And the future is beautiful when my subscribers' accounts get blown up!
I hope you made some good money yesterday!
Good luck trading, everyone!🤑
1
4
1.1k
·
--
What did we do today?
Today we closed out the shorts who are waiting for Bitcoin to hit 76K or lower…
They’ll never get out. The shorts are trapped, and they’ll be dragged up to 112K!
They’ll flip to longs and give us fuel for the rally 🤑
What did we do today?
Today we closed out the shorts who are waiting for Bitcoin to hit 76K or lower…
They’ll never get out. The shorts are trapped, and they’ll be dragged up to 112K!
They’ll flip to longs and give us fuel for the rally 🤑
Today we closed out the shorts who are waiting for Bitcoin to hit 76K or lower…
They’ll never get out. The shorts are trapped, and they’ll be dragged up to 112K!
They’ll flip to longs and give us fuel for the rally 🤑
2
284
·
--
Said is steering Bitcoin toward 112 thousand.
Don’t listen to all that nonsense about the Fed raising rates, etc.
Walsh’s speech is today.
They’ll leave everything as it is…
Said controls the market. If he said we’re taking off today, then that’s what’ll happen…
Just kidding… or maybe not…$BTC
Said is steering Bitcoin toward 112 thousand.
Don’t listen to all that nonsense about the Fed raising rates, etc.
Walsh’s speech is today.
They’ll leave everything as it is…
Said controls the market. If he said we’re taking off today, then that’s what’ll happen…
Just kidding… or maybe not…$BTC
Don’t listen to all that nonsense about the Fed raising rates, etc.
Walsh’s speech is today.
They’ll leave everything as it is…
Said controls the market. If he said we’re taking off today, then that’s what’ll happen…
Just kidding… or maybe not…$BTC
3
4
783
·
--
What did we do?
We broke through 81k on Bitcoin, just as Said predicted!
Now we're putting ALL our money into a long with 150x leverage!
This is not financial advice!
What did we do?
We broke through 81k on Bitcoin, just as Said predicted!
Now we're putting ALL our money into a long with 150x leverage!
This is not financial advice!
We broke through 81k on Bitcoin, just as Said predicted!
Now we're putting ALL our money into a long with 150x leverage!
This is not financial advice!
2
248
·
--
✍️ An economy for people and an economy for machines
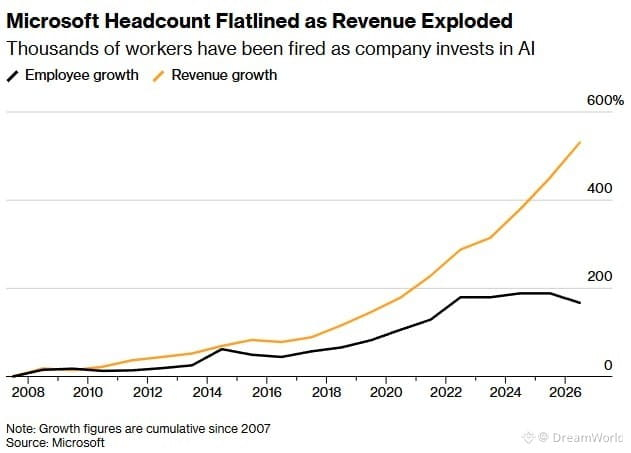
Microsoft offered voluntary departures to roughly 60,000 of its 223,000 employees. If the company can maintain the volume and quality of its work afterward, while spending less on AI than it saves, there could be no better proof of agents’ effectiveness. The rest of the business world would have a ready-made model to follow.
There may be another explanation, too. In fiscal year 2026, Microsoft’s revenue grew by 18%, capital expenditures rose by nearly 80%, and free cash flow fell from $72 billion to $67 billion. Payroll is starting to compete with chips and data centers for budget. So jobs may be cut both because of AI-driven efficiency and to fund investment in AI.
We’re already seeing the first signs for people: many places have stopped hiring interns, and now experienced workers are next. Company results may look better, while some people will be worse off. This could also affect consumer spending, because even the fear of being laid off can lead families to put off major purchases.
✍️ An economy for people and an economy for machines
Microsoft offered voluntary departures to roughly 60,000 of its 223,000 employees. If the company can maintain the volume and quality of its work afterward, while spending less on AI than it saves, there could be no better proof of agents’ effectiveness. The rest of the business world would have a ready-made model to follow.
There may be another explanation, too. In fiscal year 2026, Microsoft’s revenue grew by 18%, capital expenditures rose by nearly 80%, and free cash flow fell from $72 billion to $67 billion. Payroll is starting to compete with chips and data centers for budget. So jobs may be cut both because of AI-driven efficiency and to fund investment in AI.
We’re already seeing the first signs for people: many places have stopped hiring interns, and now experienced workers are next. Company results may look better, while some people will be worse off. This could also affect consumer spending, because even the fear of being laid off can lead families to put off major purchases.
Microsoft offered voluntary departures to roughly 60,000 of its 223,000 employees. If the company can maintain the volume and quality of its work afterward, while spending less on AI than it saves, there could be no better proof of agents’ effectiveness. The rest of the business world would have a ready-made model to follow.
There may be another explanation, too. In fiscal year 2026, Microsoft’s revenue grew by 18%, capital expenditures rose by nearly 80%, and free cash flow fell from $72 billion to $67 billion. Payroll is starting to compete with chips and data centers for budget. So jobs may be cut both because of AI-driven efficiency and to fund investment in AI.
We’re already seeing the first signs for people: many places have stopped hiring interns, and now experienced workers are next. Company results may look better, while some people will be worse off. This could also affect consumer spending, because even the fear of being laid off can lead families to put off major purchases.
2
849
·
--
Bullish
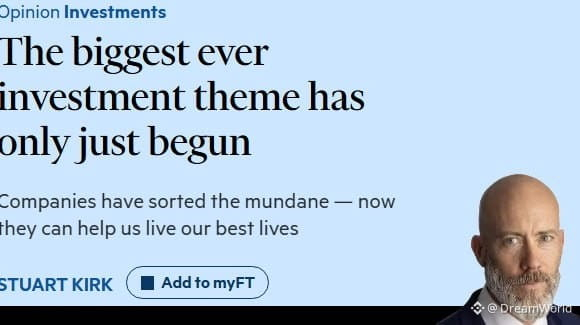
Quite an immodest article headline in the FT 🤔
But if the scenario in which AI frees up people’s time comes to pass, the author thinks it’s worth considering an investment theme bigger than AI itself.
The four-day workweek promised by Huang and Dimon sounds more like a fairy tale. After all, people have never spent the time they’ve gained on rest. They’ve immediately found something they value more to do with it. That’s what happened with household appliances, for example: women spent less time cleaning and went out to work instead.
In wealthy countries, people are spending an increasing share of their money on the upper levels of Maslow’s pyramid—that is, on health, relationships, recognition, and self-development. In Britain, the share of spending on food and clothing has halved since 1957. The wellness industry reached $7 trillion in 2024, doubling in 11 years.
According to the author, the most valuable companies will be those that help people become who they want to be 👀
...And the big winners in this space most likely haven’t even gone public yet.
Quite an immodest article headline in the FT 🤔
But if the scenario in which AI frees up people’s time comes to pass, the author thinks it’s worth considering an investment theme bigger than AI itself.
The four-day workweek promised by Huang and Dimon sounds more like a fairy tale. After all, people have never spent the time they’ve gained on rest. They’ve immediately found something they value more to do with it. That’s what happened with household appliances, for example: women spent less time cleaning and went out to work instead.
In wealthy countries, people are spending an increasing share of their money on the upper levels of Maslow’s pyramid—that is, on health, relationships, recognition, and self-development. In Britain, the share of spending on food and clothing has halved since 1957. The wellness industry reached $7 trillion in 2024, doubling in 11 years.
According to the author, the most valuable companies will be those that help people become who they want to be 👀
...And the big winners in this space most likely haven’t even gone public yet.
But if the scenario in which AI frees up people’s time comes to pass, the author thinks it’s worth considering an investment theme bigger than AI itself.
The four-day workweek promised by Huang and Dimon sounds more like a fairy tale. After all, people have never spent the time they’ve gained on rest. They’ve immediately found something they value more to do with it. That’s what happened with household appliances, for example: women spent less time cleaning and went out to work instead.
In wealthy countries, people are spending an increasing share of their money on the upper levels of Maslow’s pyramid—that is, on health, relationships, recognition, and self-development. In Britain, the share of spending on food and clothing has halved since 1957. The wellness industry reached $7 trillion in 2024, doubling in 11 years.
According to the author, the most valuable companies will be those that help people become who they want to be 👀
...And the big winners in this space most likely haven’t even gone public yet.
2
494
·
--
When AI stocks fall…
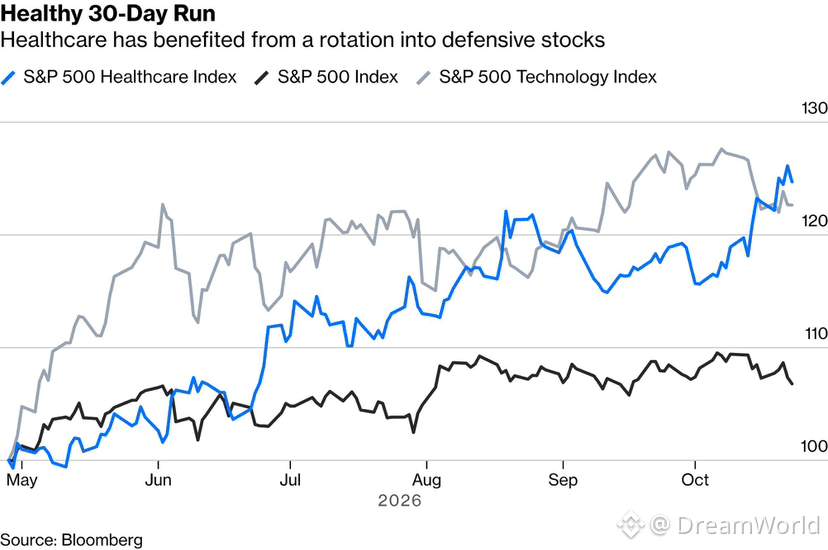
investors return to healthcare 💊
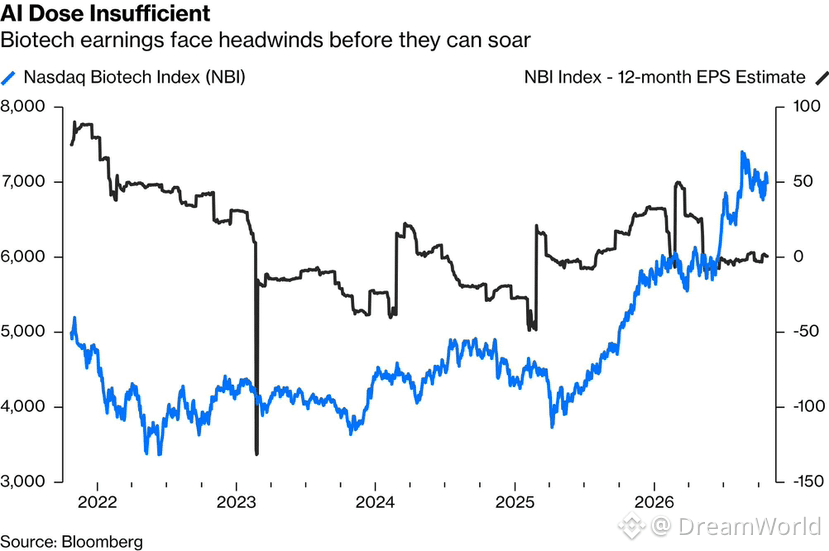
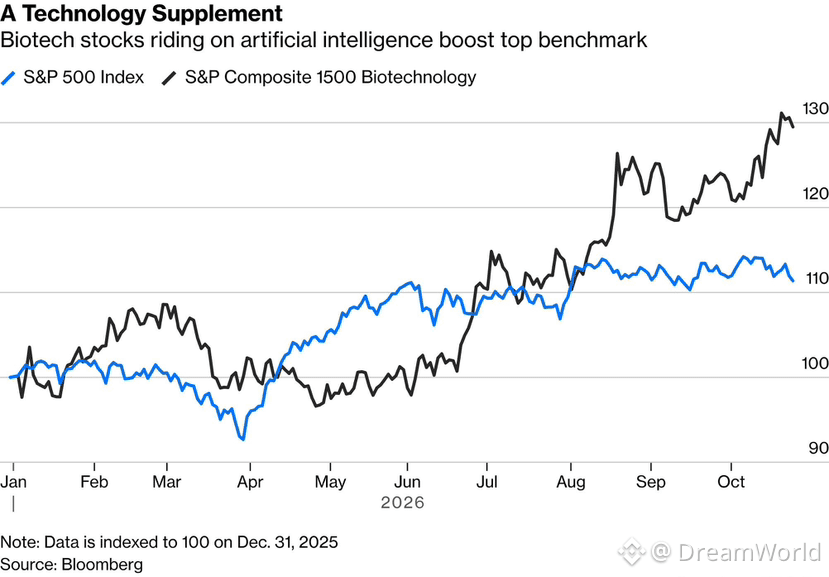
As shares of AI companies slumped, the healthcare sector gained about 5% over the month. One explanation is that biotech is among the few industries where AI is already delivering real benefits (speeding up drug discovery and lowering development costs).
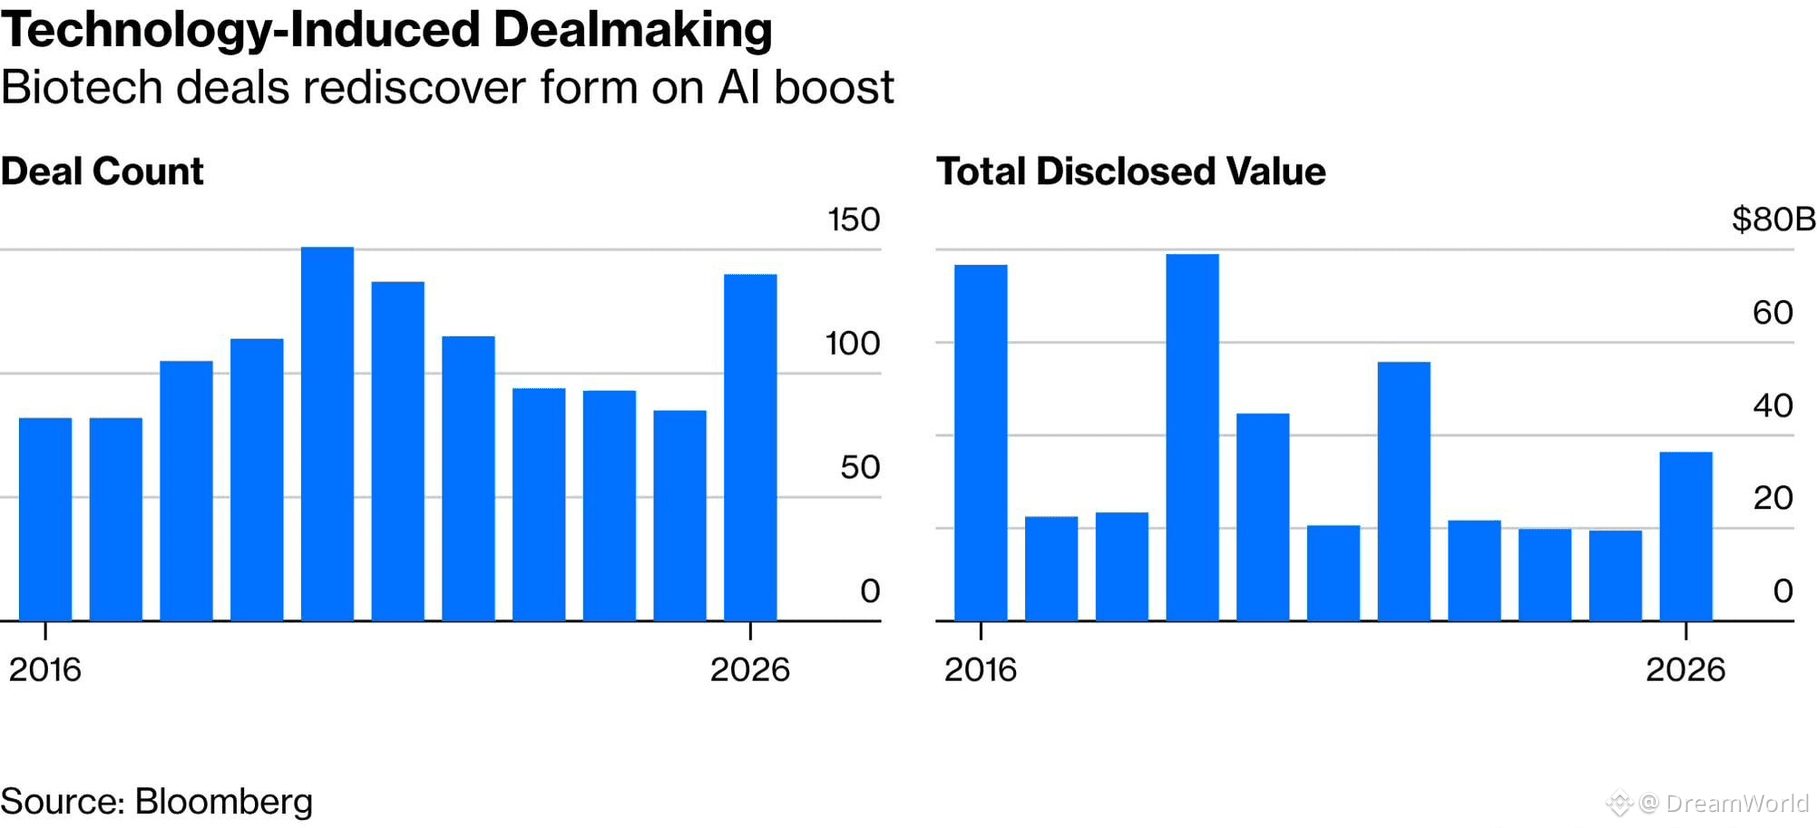
Deal activity backs this up. There have been five biotech deals this month alone. Jenny Lee of Bloomberg Intelligence sees this as a sign that investors want to combine stable earnings with growth driven by innovation. Companies such as Eli Lilly (LLY) have benefited.
As for the risks, Washington continues to put pressure on the sector, seeking to limit U.S. investment in Chinese biotech. The Treasury Department is proposing a ban on joint ventures with China, but not on licensing deals, so the direct risk to pharmaceutical companies may be limited. The final rule could be softened, and clarity on the issue could support share prices.👀
The industry’s deeper problem is patents. By 2030, drugs generating $290–350 billion in revenue could lose exclusivity—about one-sixth of the entire industry’s revenue. AI in drug development is expected to make up for some of those losses.
When AI stocks fall…
investors return to healthcare 💊
As shares of AI companies slumped, the healthcare sector gained about 5% over the month. One explanation is that biotech is among the few industries where AI is already delivering real benefits (speeding up drug discovery and lowering development costs).
Deal activity backs this up. There have been five biotech deals this month alone. Jenny Lee of Bloomberg Intelligence sees this as a sign that investors want to combine stable earnings with growth driven by innovation. Companies such as Eli Lilly (LLY) have benefited.
As for the risks, Washington continues to put pressure on the sector, seeking to limit U.S. investment in Chinese biotech. The Treasury Department is proposing a ban on joint ventures with China, but not on licensing deals, so the direct risk to pharmaceutical companies may be limited. The final rule could be softened, and clarity on the issue could support share prices.👀
The industry’s deeper problem is patents. By 2030, drugs generating $290–350 billion in revenue could lose exclusivity—about one-sixth of the entire industry’s revenue. AI in drug development is expected to make up for some of those losses.
investors return to healthcare 💊
As shares of AI companies slumped, the healthcare sector gained about 5% over the month. One explanation is that biotech is among the few industries where AI is already delivering real benefits (speeding up drug discovery and lowering development costs).
Deal activity backs this up. There have been five biotech deals this month alone. Jenny Lee of Bloomberg Intelligence sees this as a sign that investors want to combine stable earnings with growth driven by innovation. Companies such as Eli Lilly (LLY) have benefited.
As for the risks, Washington continues to put pressure on the sector, seeking to limit U.S. investment in Chinese biotech. The Treasury Department is proposing a ban on joint ventures with China, but not on licensing deals, so the direct risk to pharmaceutical companies may be limited. The final rule could be softened, and clarity on the issue could support share prices.👀
The industry’s deeper problem is patents. By 2030, drugs generating $290–350 billion in revenue could lose exclusivity—about one-sixth of the entire industry’s revenue. AI in drug development is expected to make up for some of those losses.
2
323
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
JobsReportRaisesHikeOdds
325,148 views
2,496 Discussing
TradFi News | US Adds 165,000 Jobs in October, More Than Double the 65,000 Forecast, as Unemployment Falls to 4.1%
Binance News
·38 Likes
·23.5k views
CPITestsDecemberRateOutlook
52,689 views
608 Discussing
BitcoinRebounds$75KAsChipsLead
26,298 views
254 Discussing