

海盗鸭
3.6k Posts

海盗鸭
Report
Block User
69 Following
137 Followers
350 Liked
Posts
All
Quotes
·
--
Charles Hoskinson said on October 18 that he and IOG engineer Lucas Rosa are writing a new language for Cardano: intent-based transactions, proof-carrying data (PCD), and Groth16 zero-knowledge proofs. No name, source code, or timeline has been provided.
The numbers are striking: ADA has a market cap of about $8.3 billion, while total value locked across Cardano DeFi is only $63 million. Weekly trading volume is $8.35 million, down 25% week over week, and the network’s stablecoin supply is about $70 million. By comparison, Solana’s DeFi deposits are more than 90 times higher.
So here’s my take: what ADA lacks isn’t a language—it’s demand. Holders treat it as a store of value, not as on-chain collateral, and the 65-fold increase in throughput promised by Leios won’t change that ratio.
$ADA In this rally, are you adding to your position or trimming it?
15
·
--
CryptoQuant data: since Bitcoin peaked in October, cumulative sell pressure on meme coins on Binance has already exceeded $1.4 billion. $BTC is currently barely fluctuating above $82,000, still about 35% below its peak.
The decline is very clear: $DOGE and SHIB are down about 9% in a week, WIF more than 10%, TRUMP more than 12%, BONK and FLOKI each more than 15%, and MemeCore more than 19%. But the structure is more important — the share of meme coins in total altcoin market cap has fallen below 3%, the lowest on record.
My view is: this time, the altcoin season was not delayed, but skipped entirely. Money did not flow from memes into mainstream altcoins; it left the market instead — the overall risk budget was cut. That 3% figure shows there was simply no buying support.
Do you still have meme positions? After DOGE fell 9%, would you add or cut?
#BitcoinBackAbove82000
31
·
--
BitMine bought another 12,535 ETH, bringing its holdings to 6.04 million as of October 18—about 4.9% of ETH’s total supply. Of that, 5.07 million ETH has been staked.
Tom Lee’s reason for this purchase wasn’t ETH’s own narrative—it was South Korea. From October 1 to 16, the KOSPI fell 17%; Samsung Electronics dropped 19.74%, and SK Hynix fell 28.38%. For four consecutive days leading up to October 16, liquidations exceeded 50 billion won a day. He said concerns over AI financing, US-Iran tensions, the midterm elections, and bond yields were prompting investors to de-risk. And because many investors in the US, South Korea, and Taiwan are heavily positioned in crypto, it got caught in the fallout.
I agree with the direction, but not the timing. A selloff driven by liquidations doesn’t end when fundamentals improve—it ends when leverage has been cleared out.
That’s why the final leg down is the fastest, and the rebound is the strongest. What matters is when liquidations in South Korea hit zero—not the narrative.
$ETH : add now, or wait until the liquidations stop?
#BitMineAdds12535ETH
28
·
--
On Friday, October 16, Strategy fell 9.56% to close at $136.83, its biggest single-day drop in more than eight months. Bitcoin fell only about 1% over the same period, while the Nasdaq dropped 2.14%—the stock crashed before the crypto even moved.
The trigger was a new MSCI rule announced on October 15: “non-operating companies” will be excluded from its global investable market indexes. The final list will be announced on November 11, with the change taking effect after the market closes on November 30. JPMorgan estimates passive outflows of about $2.8 billion.
The risk lies in the premium: Strategy holds 848,250 BTC at an average price of $75,444, and buys bitcoin by issuing common stock when its share price trades above the net value of its holdings. If the stock trades at a discount for a prolonged period, that machine stops running, leaving preferred stock and debt as the only options.
If the November 11 list really names it, will $BTC get swept up in a wave of selling—or will it be completely unaffected? What about $MSTRB ?
#StrategySharesFall9PercentOnFriday
39
·
--
Strategy’s discretionary cash has fallen to $447.3 million, down from $1.61 billion on August 30—a 72% decline in seven weeks.
Where did the money go? Last week, it spent $193.1 million buying back STRC preferred shares and just $100,000 buying Bitcoin. It did buy $22.1 million worth of BTC this week—at an average price of $82,900, bringing its holdings to 848,517 BTC—but the money came from issuing 140,900 shares of common stock.
The board increased the authorization for preferred share buybacks by 50%, from $2 billion to $3 billion, with $1.16 billion remaining. The stock fell 11.35% in a week.
My take is straightforward: cash is going to shareholder returns ahead of Bitcoin accumulation. That’s evidence the premium is disappearing. The final MSCI list on November 11 is the next major test.
Are you betting that $BTC will find a bottom first, or that $MSTRB will catch up and fall back to 120 first?
48
·
--
Dogecoin Labs, established with the support of the Dogecoin Foundation, officially launched today, bringing three businesses under one independent company: the MyDoge wallet (which claims 500,000+ users and has just launched V3); the DogeOS app platform (whose EVM-compatible public testnet goes live on September 30, with no mainnet date announced yet, and whose reported “secure connection” to the Dogecoin mainnet is also not complete); and merchant payments through Such App (whose beta supports invoicing and in-person QR code payments, though integration with DogeOS is still in the planning stage).
The organizational structure is the easiest part to sort out. The real problem for $DOGE has never been a lack of people building apps; it’s that not many people actually need to use it to pay for things. With no mainnet connection on the public testnet and QR code tools not yet integrated into the app layer, the loop hasn’t been closed today.
So my take is: this is a 12-to-24-month story, not a catalyst for this week. The hype will probably fade within a week.
Would you buy $DOGE on an “ecosystem integration” headline, or only pay attention when someone touts it?
70
·
--
Public on-chain transaction data shows the Ethereum Foundation exchanged 2,785 ETH for USDS. The ETH involved was worth about $6.42 million. The swap was executed through CoWSwap. Because the trade appears on public blockchain records, the movement can be verified directly rather than relying on a company statement. The exchange converted a large ETH balance into USDS, a stablecoin. The dollar figure is an approximation based on the ETH value at the time. The foundation's swap is visible to blockchain analysts tracking large flows. $ETH
Public on-chain transaction data shows the Ethereum Foundation exchanged 2,785 ETH for USDS. The ETH involved was worth about $6.42 million. The swap was executed through CoWSwap. Because the trade appears on public blockchain records, the movement can be verified directly rather than relying on a company statement. The exchange converted a large ETH balance into USDS, a stablecoin. The dollar figure is an approximation based on the ETH value at the time. The foundation's swap is visible to blockchain analysts tracking large flows. $ETH
2
·
--
BNB Chain outlined plans for a second, EVM-compatible Layer 1 that will run alongside BNB Smart Chain rather than replace it. The network will connect to BSC through a native bridge and will not introduce a new token; BNB will serve as the asset for gas, staking and governance. A public testnet is planned for the end of 2026, with mainnet targeted for early 2027. Stated targets include roughly 200 millisecond block times, about 20 millisecond transaction pre-confirmations and sub-second transaction ordering. A multi-validator development network is already running. $BNB
BNB Chain outlined plans for a second, EVM-compatible Layer 1 that will run alongside BNB Smart Chain rather than replace it. The network will connect to BSC through a native bridge and will not introduce a new token; BNB will serve as the asset for gas, staking and governance. A public testnet is planned for the end of 2026, with mainnet targeted for early 2027. Stated targets include roughly 200 millisecond block times, about 20 millisecond transaction pre-confirmations and sub-second transaction ordering. A multi-validator development network is already running. $BNB
·
--
Bitquery exposed the “boom” on the XRP Ledger: from September 19 to October 18, 7.79 million of the 7.82 million RLUSD payments—99.6%—came from a bot cluster of 110 addresses, all sent to just 3 recipient addresses, with each payment around a tenth of a cent and only $20 a day spent on fees.
The reality: fewer than 2,000 sending addresses over the entire month. Of the $7.33 billion in settlement volume, $6.98 billion—95%—came from 828 transfers of over $1 million each. The median transfer was just 150 RLUSD.
My take: transaction-count metrics are broken. Using dust transactions to argue that a blockchain is booming is the laziest form of self-deception. If you want to know what’s really happening, look at issuer mints and redemptions, and large settlements—that’s where the real money moves.
When judging $XRP, do you still look at transaction counts, or do you focus only on ETF inflows and the $1.25 level?
Bitquery exposed the “boom” on the XRP Ledger: from September 19 to October 18, 7.79 million of the 7.82 million RLUSD payments—99.6%—came from a bot cluster of 110 addresses, all sent to just 3 recipient addresses, with each payment around a tenth of a cent and only $20 a day spent on fees.
The reality: fewer than 2,000 sending addresses over the entire month. Of the $7.33 billion in settlement volume, $6.98 billion—95%—came from 828 transfers of over $1 million each. The median transfer was just 150 RLUSD.
My take: transaction-count metrics are broken. Using dust transactions to argue that a blockchain is booming is the laziest form of self-deception. If you want to know what’s really happening, look at issuer mints and redemptions, and large settlements—that’s where the real money moves.
When judging $XRP , do you still look at transaction counts, or do you focus only on ETF inflows and the $1.25 level?
26
·
--
This CFTC interpretive statement (issued October 5, published in the Federal Register on October 13, with comments due by December 14) turns a lot of people’s assumptions on their head: paying in full for Bitcoin and declining the credit offered by a platform does not mean the transaction falls outside futures rules. As long as the seller or counterparty has “offered” a financing arrangement that applies—whether it’s in the account-opening documents or the transaction terms—the retail commodity transaction may still fall under CEA Section 2(c)(2)(D), unless an exception such as “actual delivery” applies.
And the bar for actual delivery is meaningful possession and control within 28 days: a balance on an exchange’s ledger generally isn’t enough—you need the private keys. Paying in full also doesn’t, by itself, qualify for an exception.
My take: this isn’t about raising the bar for retail investors; it’s about defining what “BTC on the books” really is. Whether buying coins on a platform counts as spot or leveraged trading depends on whether you actually get the keys—self-custody has become the regulatory-optimal choice for the first time, not just a matter of belief.
Your turn: $BTC —do you keep it in your own wallet or leave it in your platform balance?
24
·
--
On the 19th, BlackRock filed for its third Bitcoin ETF, called Managed Protect. It doesn’t hold Bitcoin; instead, it buys call spreads on IBIT: buying calls with strike prices around 90% and selling calls with higher strike prices to offset the cost, with the remainder allocated to short-term fixed income.
The trade-off is straightforward: upside is capped, while the downside protection is only a buffer, not a guarantee. The prospectus states that the fund does not guarantee a maximum loss of 10%. It also runs three overlapping monthly tranches, so the actual protection is based on a moving average minus fees. The product still needs SEC approval.
My take: this isn’t protection for retail investors. It lets allocation-focused investors price Bitcoin according to their “risk budget”—from holding IBIT outright, to earning premium by selling volatility with BITA, to buying protection. Once institutions enter with a “maximum drawdown of 10%” constraint, the long-term volatility of $BTC could be structurally reduced.
Would you trade capped returns for protection that isn’t guaranteed, or simply hold $BTC outright?
BTC+1.08%
IBITETF+0.02%
43
·
--
JPMorgan’s deposit token, JPMD, officially went live on the Ethereum mainnet on October 19. It’s available only to institutional clients approved by Kinexys (formerly Onyx). It represents U.S. dollar deposits held at JPMorgan—not a stablecoin—and retail investors can’t participate.
Its purpose is clear: 24/7 peer-to-peer settlement, clearing and collateral for on-chain payments and tokenized assets. The official reason for choosing Ethereum was straightforward: liquidity. According to DefiLlama, around $50 billion is locked in Ethereum applications. Kinexys has processed more than $4 trillion in total, with an average of about $7 billion a day.
But set that figure against JPMorgan’s overall payments business, which handles $12 trillion a day, and it’s just a drop in the bucket. So I think the significance of this move is greater than its transaction volume: Wall Street isn’t here to speculate on crypto—it’s moving the wholesale settlement layer for the dollar onto a public blockchain.
The real question is this: Ethereum ETFs are seeing net outflows this week, while on-chain institutional settlement is growing. Which trend do you trust more? Will $ETH reclaim 2,400 first, or test 2,200 again?
64
·
--
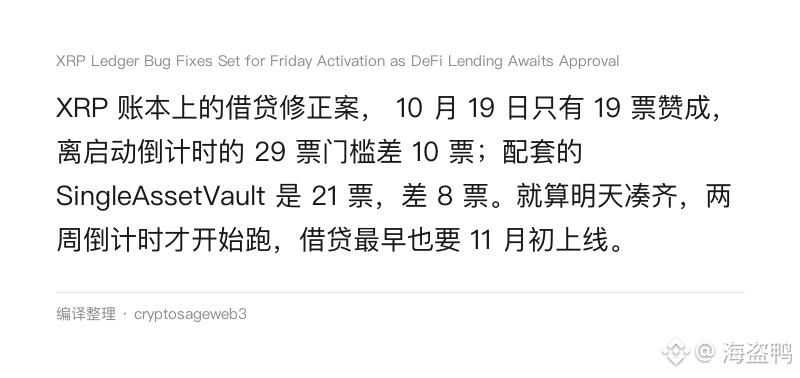
The lending amendment on the XRP Ledger had only 19 votes in favor on October 19, 10 short of the 29-vote threshold needed to start the activation countdown. The accompanying SingleAssetVault amendment had 21 votes, 8 short. Even if they get enough votes tomorrow, the two-week countdown will only just begin, so lending won’t launch until early November at the earliest.
Another proposal is easier to overlook: fixCleanup3_4_0, a bundle of bug fixes, has exactly 29 votes, right on the 80% threshold, and is expected to activate on October 23. It fixes a vulnerability related to PaymentBurn: in certain circumstances, accounts authorized only to destroy tokens could instead create them out of thin air. It also adjusts vault rounding and rules for overdue defaults. Note that this patch does not enable lending.
I’m inclined to think patching first and enabling lending afterward is the right call, but it also exposes a weak spot: the new lending system doesn’t require collateral, creditworthiness is assessed off-chain, and there’s no automatic on-chain liquidation. Risk controls are off-chain; the risk is on-chain.
$XRP Are you waiting until it actually activates in November to get in, or getting in early?
72
·
--
Switzerland’s FINMA approved the country’s first spot Bitcoin ETF aimed at retail investors today.
Two details are worth picking apart: first, it received an exemption from diversification requirements, so the fund holds only Bitcoin, on the grounds that the asset has a sufficiently long trading history. Second, it falls under the framework of the Collective Investment Schemes Act. If the manager goes bankrupt, the fund’s assets are not considered part of the bankruptcy estate—a higher level of legal protection than collateralized ETPs on SIX.
Switzerland approved a fund with crypto exposure in 2021, but it was open only to qualified investors and held a basket of coins. This time, it’s open to the retail public and buys only BTC.
My take: this is a regulatory catch-up, not a new engine for capital inflows. Switzerland’s retail market isn’t big enough to drive marginal buying. The real significance is that it sets a precedent for other European regulators: a single-asset fund can also be exempt from diversification requirements. FINMA also warned that investors could lose a substantial portion of their principal.
Will European capital follow the U.S. and become the next source of marginal buying? Are you trading $BTC directly, or buying this kind of fund wrapper with asset segregation?
#SwitzerlandApprovesFirstBitcoinETF
1
·
--
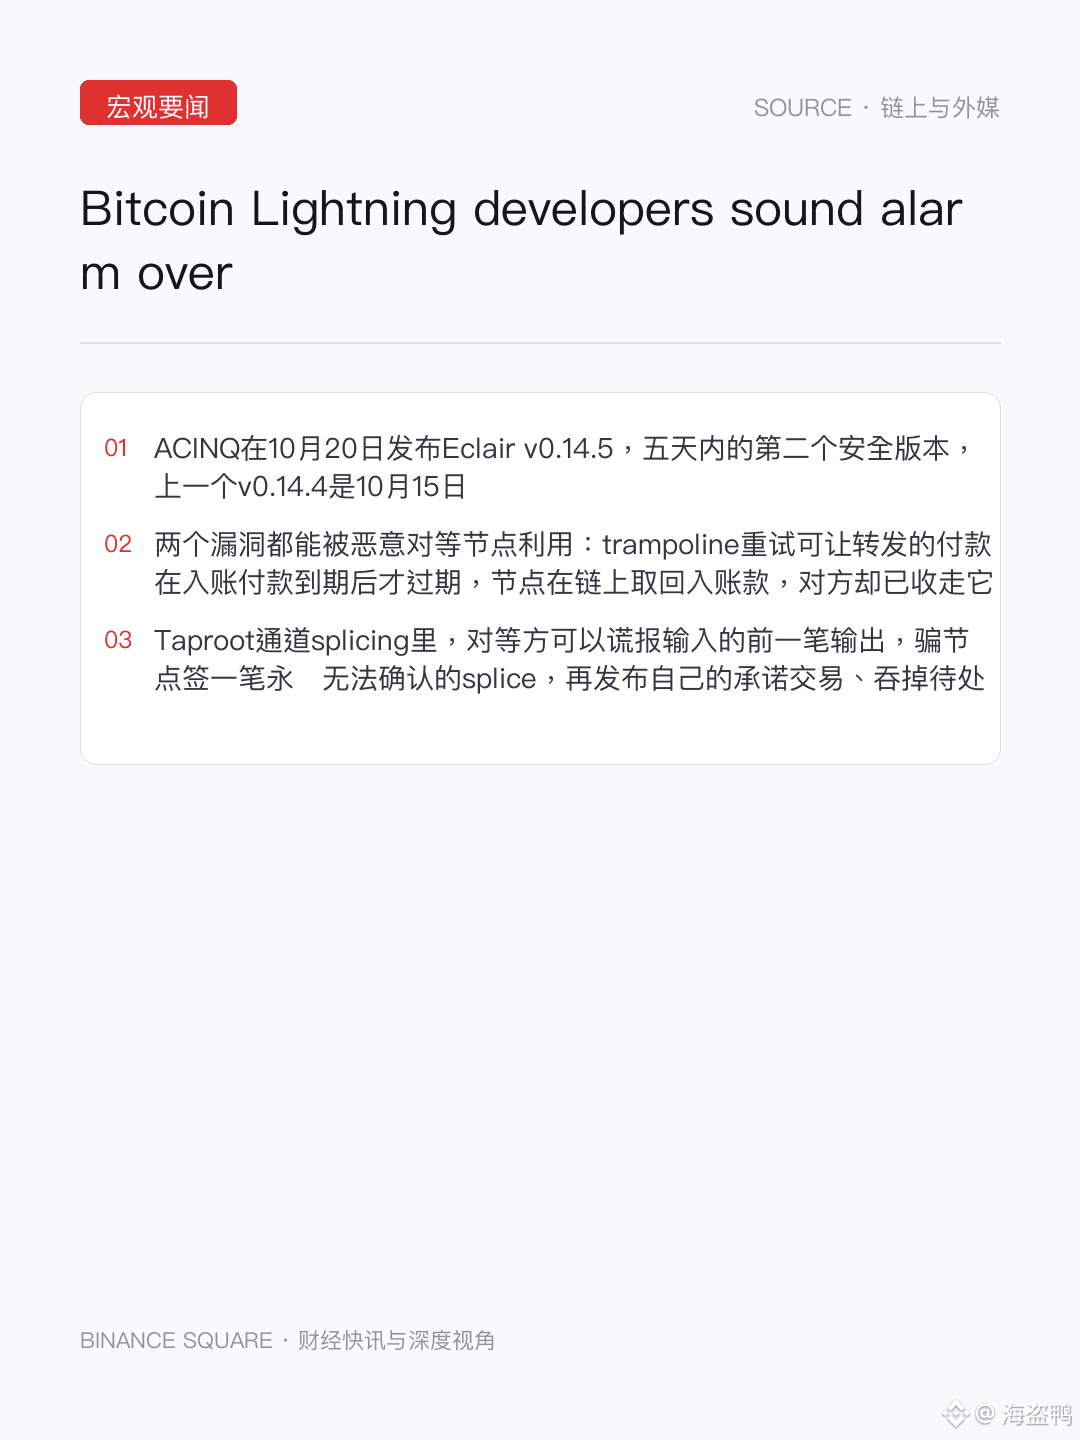
ACINQ released Eclair v0.14.5 on October 20, its second security release in five days; the previous version, v0.14.4, came out on October 15. Both vulnerabilities could be exploited by malicious peers: trampoline retries could cause a forwarded payment to expire only after the incoming payment had expired, letting the node reclaim the incoming funds on-chain while the peer had already claimed the outgoing funds; in Taproot channel splicing, a peer could lie about the previous output of an input, tricking the node into signing a splice that could never confirm, then broadcast its own commitment transaction and steal pending payments.
Upgrading doesn’t require closing existing channels, but the announcement didn’t provide the full range of affected versions or severity ratings, and only said that “no exploitation has been observed.”
My take: the real risk in Lightning is operational—it shifts the responsibility for security onto you. The $BTC main chain is fine, but you have to patch your own node.
When did you last patch your node?
4
·
--
South Korea’s latest regulatory crackdown isn’t about “controlling crypto”—it was prompted by a leak of 100,000 customer records. If you understand what’s going on, there’s one very specific thing you should do tonight.
On October 14, South Korea’s Financial Services Commission (FSC) proposed a cybersecurity reform plan. The incident involved 16 financial companies, including four commercial banks (among them Shinhan and KB Kookmin), four savings banks, and two crypto service providers. The leaked information included names, phone numbers, email addresses, and resident registration numbers. Note that account passwords and card numbers have not been confirmed as leaked. After reviewing a 12-point checklist for 555 financial companies, the FSC found that 130 had deficiencies requiring correction. Common issues included outdated security software, weak monitoring, and a lack of multifactor authentication for critical systems.
There are three key aspects of the reform to remember: assessments of vulnerabilities at large institutions will increase from once a year to at least twice a year; an AI-based threat monitoring framework will be established to counter AI-powered attacks; and executive accountability will be strengthened, with additional inspections permitted in response to urgent threats, beyond the regular assessments. The FSC secretary-general said financial institutions had “repeatedly received warnings but still failed to comply with basic requirements.” The final implementation date has not yet been announced.
My take: The real damage from incidents like this isn’t that “money is stolen on the spot.” It’s that identity data becomes long-term ammunition for phishing. A name, phone number, and resident registration number are enough to create fake messages convincing enough to fool people. So the most effective action for users isn’t switching platforms—it’s replacing SMS verification codes with app-based authenticator codes or a hardware security key. Against SIM hijacking, SMS verification codes offer almost no protection.
A reminder: South Korea is also cracking down on unregistered overseas platforms. Users of these platforms may face restrictions on withdrawals, and moving assets in a panic is itself a risk.
One specific question: Does your account currently use SMS verification codes or a hardware security key? If it’s the former, when do you plan to switch?
#SouthKoreaPlansTighterFinancialCybersecurityRules
1
·
--
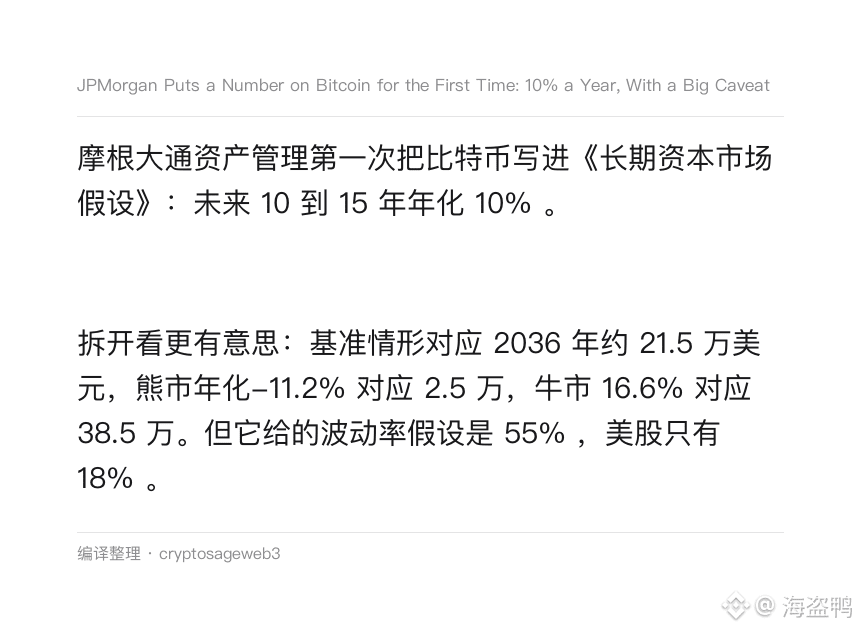
JPMorgan Asset Management has included Bitcoin in its Long-Term Capital Market Assumptions for the first time: 10% annualized returns over the next 10 to 15 years.
The breakdown is even more interesting: the base case puts Bitcoin at around $215,000 by 2036; the bear case, with annualized returns of -11.2%, puts it at $25,000; and the bull case, with returns of 16.6%, puts it at $385,000. But its assumed volatility is 55%, compared with just 18% for US stocks.
For comparison, the figures are 7.5% for US large-cap stocks, 5.5% for gold, and 7% for a 60/40 portfolio. Bitcoin offers the highest returns, at the cost of three times the volatility.
Most importantly, Bitcoin isn’t included in core strategic allocations—the volatility is too high, and its correlation is unstable.
My take: 10% seems conservative. It implies Bitcoin will be just a high-volatility substitute for large-cap stocks over the long term, not digital gold.
$BTC is now around $83,000. Can a 10% annualized return over ten years justify this price? Would you add to your position at the bear-case level, or sit back and watch?
#JPMorganForecastsBitcoinToLeadOverTheNextDecade
6
·
--
South Korea is moving tokenized securities beyond “fractional investing” and into the mainstream securities market. Proposed revisions to subordinate regulations under the Electronic Securities Act and the Capital Markets Act, advanced by the Financial Services Commission, have entered the legislative notice period (from the 2nd of this month to the 11th of next month). Under the current plan, the accompanying laws will take effect on February 4, 2027, and explicitly define stocks, bonds, and funds as eligible for tokenization.
The most notable feature of the framework is its phased approach. Phase 1, which begins when the laws take effect, is limited to institutional investors: private money market funds, private corporate bonds, and trust-based tokenization of unlisted stocks, alongside a small-scale pilot for publicly offered fractional investment securities. Phase 2 will gradually open up publicly offered securities after evaluating operational stability, efficiency, and demand. Only in Phase 3 will regulators explore integration with payment instruments such as stablecoins, paving the way for on-chain settlement infrastructure. The sequence itself is the answer: lawmakers see the bottleneck not in issuance technology, but in payments and settlement.
The regulatory boundaries are also carefully drawn. Ordinary investors will be capped at net annual purchases of KRW 100 million per over-the-counter trading platform. Non-financial institutions may manage investor accounts as “issuer account management institutions” if they meet requirements including KRW 4 billion in equity capital. And there will be no separate license for tokenized securities: securities firms and over-the-counter exchanges that are already licensed can operate under their existing licenses. The market is already moving: 12 brokerages are jointly advancing the issuance platform “KoSTO,” while several others are preparing their own systems, drawing on models such as Hong Kong’s digital bonds, Japan’s tokenized corporate bonds, and U.S. tokenized funds.
My view is that South Korea has chosen a cautious path: “bonds and funds before stocks, institutions before retail investors, and private offerings before public offerings.” Bonds are easier to price and have more predictable cash flows, making them suitable for first testing the reliability of on-chain registration and settlement; purchase limits will help contain risks for retail investors. This also means there is unlikely to be explosive growth in the short term. The real wildcard is whether stablecoin payments can be integrated in Phase 3. For the sector, the issuance and settlement of these RWA assets are still concentrated on Ethereum and its ecosystem, making $ETH an unavoidable asset to watch.
The question for you: Which will scale faster—the South Korean model of gradual, regulated expansion, or the U.S. market-driven issuance approach? When RWA activity really takes off, are you betting on public-chain settlement layers or licensed issuers?
#SouthKoreaProposesExpandingTokenizedSecuritiesToBondsAndFunds
14
·
--
This time, the problem wasn’t with Ledger’s servers. The device had been tampered with before it ever reached the user.
An investigation disclosed on October 9 found that a Ledger user who bought their device through Southeast Asian reseller CryptoBilis reported having their assets stolen. Independent investigators estimate that the amount involved could exceed $93 million. After taking the device apart, they found that at least one unit had been implanted with an unauthorized hardware module. It could read the 24-word recovery phrase as it appeared on the screen during device setup, then send it directly to the attackers through an LTE (eSIM) module. On October 13, Ledger asked resellers in seven markets—Indonesia, Singapore, Thailand, the Philippines, Vietnam, Malaysia, and Hong Kong—to suspend sales and pull their products from shelves. This was a clear expansion from its earlier warning, which named just one reseller.
Why is this worth thinking about carefully? Because the entire trust model of a hardware wallet rests on the assumption that “the private key never leaves the chip.” But this attack didn’t bypass cryptography; it exploited the supply chain: a third-party piece of hardware was inserted between the screen and the secure chip. Firmware signatures and open-source verification can’t stop it—it’s physically there, disguised as part of the factory-fresh device. Ledger stressed that its infrastructure, systems, and direct sales channels were not compromised. The problem was limited to third-party resale in specific regions, and the company has not verified any cases of theft involving devices bought elsewhere.
My take: a hardware wallet’s security boundary has never really been inside the chip. It’s the question of “where did you get it?” A cold wallet moves the attack surface from online to shipping and retail shelves—and that’s precisely the layer that’s hardest to audit. After all, all of someone’s $BTC and mainstream assets often sit inside a piece of metal no bigger than the palm of your hand. Two things remain to be seen: where in the distribution chain the tampering happened, and who carried it out; and whether Ledger Donjon’s analysis of recovered devices will uncover more affected batches.
So the question ultimately comes down to each crypto holder: would you rather save a few dollars and get your device sooner by buying from a local reseller, or wait for direct shipping from the official website and check the tamper-evident packaging yourself?
#Ledger asks resellers in Southeast Asia and Hong Kong to suspend sales
3
·
--
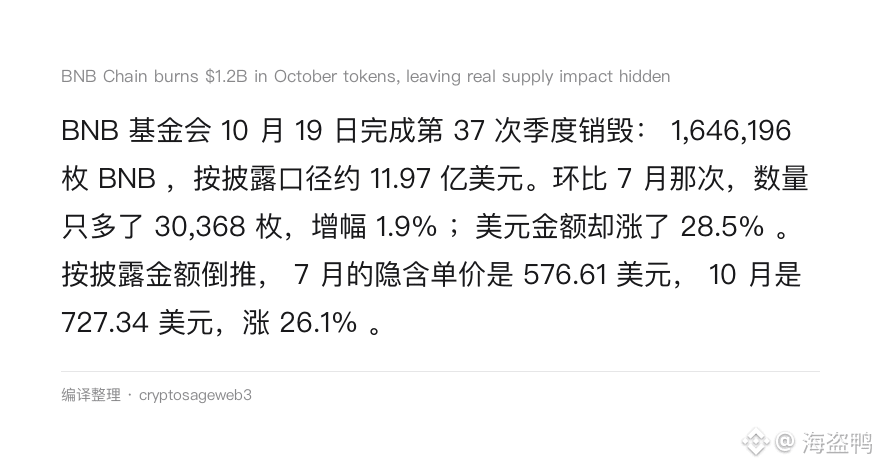
The BNB Foundation completed its 37th quarterly burn on October 19: 1,646,196 BNB, worth approximately $1.197 billion based on the disclosed figure. Compared with the burn in July, the amount was up by just 30,368 BNB, or 1.9%, while its dollar value rose 28.5%. Working backward from the disclosed values, the implied price per BNB was $576.61 in July and $727.34 in October, up 26.1%.
In other words, in this “$1.2 billion burn,” the number of coins burned didn’t increase by much—the valuation per coin did. The remaining total supply is about 131.5 million, with a target of 100 million. Auto-Burn is calculated based on price and blocks produced, so the higher the coin price, the fewer coins are burned for the same dollar amount.
My take: burn announcements are a narrative, not supply and demand. Treating every “another billion-plus burned” headline as bullish news feels more like self-reassurance based on dollar values. If you really want to track deflation, watch the coin-count trend and the remaining 131.5 million.
Question: Would you chase $BNB ’s quarterly burn as bullish news, or do you think it’s already priced in and would rather wait for a pullback?
2
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number