

#007
007
1,101 views
12 Discussing
Hot
Latest
·
--
Article
No Interest on the Coin. A Separate Fund Is HSBC's Next Plan.IKOL Note #007
A coin for paying at more than 100,000 merchants. No interest for holding it. And HSBC's next step is a separate product: a money market fund share class that hasn't launched yet.
On October 23, HSBC launched RedCoin (RCHKD), a Hong Kong dollar stablecoin, on its PayMe app. In the coming days, more than 3.3 million PayMe users will be able to activate a wallet and use it to pay friends and shops. What the coin will never do, under Hong Kong law, is pay its holders interest. The coin, the launch rewards and the planned fund sit close together, but they are not the same thing.
【A coin built for paying】
[Documented] According to HSBC's release (Oct 23):
· RedCoin is "the bank's first stablecoin," denominated in Hong Kong dollars and issued by The Hongkong and Shanghai Banking Corporation under a stablecoin issuer licence granted by the HKMA in April.
· "In the coming days, over 3.3 million PayMe users will be able to activate a stablecoin wallet in-app" for peer-to-peer payments and payments "at more than 100,000 merchants through PayMe."
· "To celebrate the launch, exclusive PayMe transaction discounts, alongside RewardCash, will be offered."
· Later this year, HSBC plans to let customers "subscribe to tokenised investment products via HSBC RedCoin," including "a soon-to-be-launched share class of HSBC's long-running HKD money market fund."
【The rule: no interest at all】
[Documented] The HKMA's Guideline on Supervision of Licensed Stablecoin Issuers (August 2025) puts it under a heading that leaves little doubt: "Non-interest bearing."
「"Section 15 of Schedule 2 to the SO stipulates that a licensee must not pay, or permit to be paid, any interest in relation to the specified stablecoins it issues. A licensee should not pay interest or interest-like incentive in any form to specified stablecoin holders, save that a licensee may offer marketing incentives that do not amount to payment of interest." (para 2.6.1, p. 8)」
Interest is defined by how it arises from holding: any return represented to arise from holding the coins on the basis of "(i) the length of the period during which the holder holds" them, "(ii) the par value," or "(iii) the market value." Income from managing the reserve assets goes to the issuer, not to holders. (paras 2.5.3, 2.6.1, pp. 8–9) In the Guideline, "must" marks a statutory requirement and "should" the HKMA's expectation. (para 1.2)
[Analysis] The US rule in Note #005 bans issuers from paying interest or yield "solely" for holding, using or retaining a stablecoin, and much of the American fight is over that one word. Hong Kong's statute has no "solely." The HKMA then extends the ban to "interest-like" incentives, with one carve-out: marketing incentives that are not interest.
【So what are the launch rewards?】
[Documented] HSBC describes its launch offer in one sentence: "exclusive PayMe transaction discounts, alongside RewardCash." The release gives no further terms.
[Analysis] As described, the offer is tied to transactions and to the launch, not to how long or how much RedCoin someone holds, which are the tests the Guideline uses to define interest. Whether a particular offer stays on the "marketing incentive" side of the line is for the HKMA to judge, and its full terms are not in the release. What the rule does make clear is the direction: rewards for using the coin can exist; returns for holding it cannot.
【Returns live somewhere else】
[Documented] The fund route is a plan, not a product yet: HSBC says customers will be able to use RedCoin to subscribe to tokenized investment products, including the new money market fund share class, later this year.
[Analysis] Note #006 looked at the American version from the other side: SoFi keeps idle money in a tokenized deposit, which can pay interest, and converts it into a stablecoin when it's time to spend. HSBC's plan keeps the stablecoin as the payment tool and points to a fund as a place where money can earn. In both cases the coin itself pays nothing. And a fund is neither a deposit nor interest on the coin: it is an investment with its own terms and risks, and this share class has not launched.
【Before you use it】
· Redemption. The HKMA requires licensees to let holders redeem at par; valid requests must be honored "without charging an unreasonable fee" and, unless otherwise approved, processed "within one (1) business day." Reserves must be worth at least the coins outstanding at all times and kept separate from the issuer's own assets. (Guideline paras 2.2.1, 2.5.1, 3.3.1, 3.3.3) HSBC's release does not describe fees or the redemption path inside PayMe.
· The launch offer. One sentence is all that's public in the release.
· The fund. Timing, minimums, fees and risks are not yet published.
· Which chain. Not named.
· Uptake. 3.3 million is the number of PayMe users who can activate a wallet, not the number who hold RedCoin. We have no usage data.
Would payments alone give you a reason to keep a balance in this wallet? And what would you need to know before using the planned fund alongside it?
—————
Background: the HKMA granted Hong Kong's first two stablecoin issuer licences on April 10, 2026, to Anchorpoint Financial Limited and HSBC, effective that day, and reminded the public to acquire and use stablecoins "only through regulated channels." HSBC's licence number is FRS02; HSBC Digital Assets Custody holds RedCoin's safekeeping; staff pilots with nearly 100 users preceded launch. The Stablecoins Ordinance (Cap. 656) took effect on August 1, 2025.
Evidence: strong for what RedCoin is and how it can be used (HSBC's own release); strong for Hong Kong's no-interest rule and redemption standards (HKMA Guideline, quoting the Stablecoins Ordinance); the statute itself was read through the Guideline's citations, not directly. Nothing on usage, fees or the fund's terms. Not investment or legal advice; no view on the product.
Sources
1. HSBC, "HSBC RedCoin launches today" (Oct 23, 2026) — https://www.about.hsbc.com.hk/news-and-media/hsbc-redcoin-launches-today
2. HKMA, "Granting of stablecoin issuer licences" (Apr 10, 2026) — https://www.hkma.gov.hk/eng/news-and-media/press-releases/2026/04/20260410-4/
3. HKMA, Guideline on Supervision of Licensed Stablecoin Issuers (Aug 2025), paras 1.2, 2.2.1, 2.5.1, 2.5.3, 2.6.1, 3.3.1, 3.3.3 — https://www.hkma.gov.hk/media/eng/doc/key-functions/ifc/stablecoin-issuers/Guideline_on_supervision_of_licensed_stablecoin_issuers_eng.pdf
4. Hong Kong Government, Stablecoins Ordinance (Cap. 656) commencement (press release, Jun 6, 2025) — https://www.info.gov.hk/gia/general/202506/06/P2025060600275.htm
5. IKOL Notes #005 and #006 — https://x.com/2425247/status/2113155622208418105 · https://x.com/2425247/status/2113481960903549169
IKOL · AI-assisted research, human-edited. We label what is documented, reported and analyzed — and publish our corrections.
No Interest on the Coin. A Separate Fund Is HSBC's Next Plan.
IKOL Note #007
A coin for paying at more than 100,000 merchants. No interest for holding it. And HSBC's next step is a separate product: a money market fund share class that hasn't launched yet.
On October 23, HSBC launched RedCoin (RCHKD), a Hong Kong dollar stablecoin, on its PayMe app. In the coming days, more than 3.3 million PayMe users will be able to activate a wallet and use it to pay friends and shops. What the coin will never do, under Hong Kong law, is pay its holders interest. The coin, the launch rewards and the planned fund sit close together, but they are not the same thing.
【A coin built for paying】
[Documented] According to HSBC's release (Oct 23):
· RedCoin is "the bank's first stablecoin," denominated in Hong Kong dollars and issued by The Hongkong and Shanghai Banking Corporation under a stablecoin issuer licence granted by the HKMA in April.
· "In the coming days, over 3.3 million PayMe users will be able to activate a stablecoin wallet in-app" for peer-to-peer payments and payments "at more than 100,000 merchants through PayMe."
· "To celebrate the launch, exclusive PayMe transaction discounts, alongside RewardCash, will be offered."
· Later this year, HSBC plans to let customers "subscribe to tokenised investment products via HSBC RedCoin," including "a soon-to-be-launched share class of HSBC's long-running HKD money market fund."
【The rule: no interest at all】
[Documented] The HKMA's Guideline on Supervision of Licensed Stablecoin Issuers (August 2025) puts it under a heading that leaves little doubt: "Non-interest bearing."
「"Section 15 of Schedule 2 to the SO stipulates that a licensee must not pay, or permit to be paid, any interest in relation to the specified stablecoins it issues. A licensee should not pay interest or interest-like incentive in any form to specified stablecoin holders, save that a licensee may offer marketing incentives that do not amount to payment of interest." (para 2.6.1, p. 8)」
Interest is defined by how it arises from holding: any return represented to arise from holding the coins on the basis of "(i) the length of the period during which the holder holds" them, "(ii) the par value," or "(iii) the market value." Income from managing the reserve assets goes to the issuer, not to holders. (paras 2.5.3, 2.6.1, pp. 8–9) In the Guideline, "must" marks a statutory requirement and "should" the HKMA's expectation. (para 1.2)
[Analysis] The US rule in Note #005 bans issuers from paying interest or yield "solely" for holding, using or retaining a stablecoin, and much of the American fight is over that one word. Hong Kong's statute has no "solely." The HKMA then extends the ban to "interest-like" incentives, with one carve-out: marketing incentives that are not interest.
【So what are the launch rewards?】
[Documented] HSBC describes its launch offer in one sentence: "exclusive PayMe transaction discounts, alongside RewardCash." The release gives no further terms.
[Analysis] As described, the offer is tied to transactions and to the launch, not to how long or how much RedCoin someone holds, which are the tests the Guideline uses to define interest. Whether a particular offer stays on the "marketing incentive" side of the line is for the HKMA to judge, and its full terms are not in the release. What the rule does make clear is the direction: rewards for using the coin can exist; returns for holding it cannot.
【Returns live somewhere else】
[Documented] The fund route is a plan, not a product yet: HSBC says customers will be able to use RedCoin to subscribe to tokenized investment products, including the new money market fund share class, later this year.
[Analysis] Note #006 looked at the American version from the other side: SoFi keeps idle money in a tokenized deposit, which can pay interest, and converts it into a stablecoin when it's time to spend. HSBC's plan keeps the stablecoin as the payment tool and points to a fund as a place where money can earn. In both cases the coin itself pays nothing. And a fund is neither a deposit nor interest on the coin: it is an investment with its own terms and risks, and this share class has not launched.
【Before you use it】
· Redemption. The HKMA requires licensees to let holders redeem at par; valid requests must be honored "without charging an unreasonable fee" and, unless otherwise approved, processed "within one (1) business day." Reserves must be worth at least the coins outstanding at all times and kept separate from the issuer's own assets. (Guideline paras 2.2.1, 2.5.1, 3.3.1, 3.3.3) HSBC's release does not describe fees or the redemption path inside PayMe.
· The launch offer. One sentence is all that's public in the release.
· The fund. Timing, minimums, fees and risks are not yet published.
· Which chain. Not named.
· Uptake. 3.3 million is the number of PayMe users who can activate a wallet, not the number who hold RedCoin. We have no usage data.
Would payments alone give you a reason to keep a balance in this wallet? And what would you need to know before using the planned fund alongside it?
—————
Background: the HKMA granted Hong Kong's first two stablecoin issuer licences on April 10, 2026, to Anchorpoint Financial Limited and HSBC, effective that day, and reminded the public to acquire and use stablecoins "only through regulated channels." HSBC's licence number is FRS02; HSBC Digital Assets Custody holds RedCoin's safekeeping; staff pilots with nearly 100 users preceded launch. The Stablecoins Ordinance (Cap. 656) took effect on August 1, 2025.
Evidence: strong for what RedCoin is and how it can be used (HSBC's own release); strong for Hong Kong's no-interest rule and redemption standards (HKMA Guideline, quoting the Stablecoins Ordinance); the statute itself was read through the Guideline's citations, not directly. Nothing on usage, fees or the fund's terms. Not investment or legal advice; no view on the product.
Sources
1. HSBC, "HSBC RedCoin launches today" (Oct 23, 2026) — https://www.about.hsbc.com.hk/news-and-media/hsbc-redcoin-launches-today
2. HKMA, "Granting of stablecoin issuer licences" (Apr 10, 2026) — https://www.hkma.gov.hk/eng/news-and-media/press-releases/2026/04/20260410-4/
3. HKMA, Guideline on Supervision of Licensed Stablecoin Issuers (Aug 2025), paras 1.2, 2.2.1, 2.5.1, 2.5.3, 2.6.1, 3.3.1, 3.3.3 — https://www.hkma.gov.hk/media/eng/doc/key-functions/ifc/stablecoin-issuers/Guideline_on_supervision_of_licensed_stablecoin_issuers_eng.pdf
4. Hong Kong Government, Stablecoins Ordinance (Cap. 656) commencement (press release, Jun 6, 2025) — https://www.info.gov.hk/gia/general/202506/06/P2025060600275.htm
5. IKOL Notes #005 and #006 — https://x.com/2425247/status/2113155622208418105 · https://x.com/2425247/status/2113481960903549169
IKOL · AI-assisted research, human-edited. We label what is documented, reported and analyzed — and publish our corrections.
A coin for paying at more than 100,000 merchants. No interest for holding it. And HSBC's next step is a separate product: a money market fund share class that hasn't launched yet.
On October 23, HSBC launched RedCoin (RCHKD), a Hong Kong dollar stablecoin, on its PayMe app. In the coming days, more than 3.3 million PayMe users will be able to activate a wallet and use it to pay friends and shops. What the coin will never do, under Hong Kong law, is pay its holders interest. The coin, the launch rewards and the planned fund sit close together, but they are not the same thing.
【A coin built for paying】
[Documented] According to HSBC's release (Oct 23):
· RedCoin is "the bank's first stablecoin," denominated in Hong Kong dollars and issued by The Hongkong and Shanghai Banking Corporation under a stablecoin issuer licence granted by the HKMA in April.
· "In the coming days, over 3.3 million PayMe users will be able to activate a stablecoin wallet in-app" for peer-to-peer payments and payments "at more than 100,000 merchants through PayMe."
· "To celebrate the launch, exclusive PayMe transaction discounts, alongside RewardCash, will be offered."
· Later this year, HSBC plans to let customers "subscribe to tokenised investment products via HSBC RedCoin," including "a soon-to-be-launched share class of HSBC's long-running HKD money market fund."
【The rule: no interest at all】
[Documented] The HKMA's Guideline on Supervision of Licensed Stablecoin Issuers (August 2025) puts it under a heading that leaves little doubt: "Non-interest bearing."
「"Section 15 of Schedule 2 to the SO stipulates that a licensee must not pay, or permit to be paid, any interest in relation to the specified stablecoins it issues. A licensee should not pay interest or interest-like incentive in any form to specified stablecoin holders, save that a licensee may offer marketing incentives that do not amount to payment of interest." (para 2.6.1, p. 8)」
Interest is defined by how it arises from holding: any return represented to arise from holding the coins on the basis of "(i) the length of the period during which the holder holds" them, "(ii) the par value," or "(iii) the market value." Income from managing the reserve assets goes to the issuer, not to holders. (paras 2.5.3, 2.6.1, pp. 8–9) In the Guideline, "must" marks a statutory requirement and "should" the HKMA's expectation. (para 1.2)
[Analysis] The US rule in Note #005 bans issuers from paying interest or yield "solely" for holding, using or retaining a stablecoin, and much of the American fight is over that one word. Hong Kong's statute has no "solely." The HKMA then extends the ban to "interest-like" incentives, with one carve-out: marketing incentives that are not interest.
【So what are the launch rewards?】
[Documented] HSBC describes its launch offer in one sentence: "exclusive PayMe transaction discounts, alongside RewardCash." The release gives no further terms.
[Analysis] As described, the offer is tied to transactions and to the launch, not to how long or how much RedCoin someone holds, which are the tests the Guideline uses to define interest. Whether a particular offer stays on the "marketing incentive" side of the line is for the HKMA to judge, and its full terms are not in the release. What the rule does make clear is the direction: rewards for using the coin can exist; returns for holding it cannot.
【Returns live somewhere else】
[Documented] The fund route is a plan, not a product yet: HSBC says customers will be able to use RedCoin to subscribe to tokenized investment products, including the new money market fund share class, later this year.
[Analysis] Note #006 looked at the American version from the other side: SoFi keeps idle money in a tokenized deposit, which can pay interest, and converts it into a stablecoin when it's time to spend. HSBC's plan keeps the stablecoin as the payment tool and points to a fund as a place where money can earn. In both cases the coin itself pays nothing. And a fund is neither a deposit nor interest on the coin: it is an investment with its own terms and risks, and this share class has not launched.
【Before you use it】
· Redemption. The HKMA requires licensees to let holders redeem at par; valid requests must be honored "without charging an unreasonable fee" and, unless otherwise approved, processed "within one (1) business day." Reserves must be worth at least the coins outstanding at all times and kept separate from the issuer's own assets. (Guideline paras 2.2.1, 2.5.1, 3.3.1, 3.3.3) HSBC's release does not describe fees or the redemption path inside PayMe.
· The launch offer. One sentence is all that's public in the release.
· The fund. Timing, minimums, fees and risks are not yet published.
· Which chain. Not named.
· Uptake. 3.3 million is the number of PayMe users who can activate a wallet, not the number who hold RedCoin. We have no usage data.
Would payments alone give you a reason to keep a balance in this wallet? And what would you need to know before using the planned fund alongside it?
—————
Background: the HKMA granted Hong Kong's first two stablecoin issuer licences on April 10, 2026, to Anchorpoint Financial Limited and HSBC, effective that day, and reminded the public to acquire and use stablecoins "only through regulated channels." HSBC's licence number is FRS02; HSBC Digital Assets Custody holds RedCoin's safekeeping; staff pilots with nearly 100 users preceded launch. The Stablecoins Ordinance (Cap. 656) took effect on August 1, 2025.
Evidence: strong for what RedCoin is and how it can be used (HSBC's own release); strong for Hong Kong's no-interest rule and redemption standards (HKMA Guideline, quoting the Stablecoins Ordinance); the statute itself was read through the Guideline's citations, not directly. Nothing on usage, fees or the fund's terms. Not investment or legal advice; no view on the product.
Sources
1. HSBC, "HSBC RedCoin launches today" (Oct 23, 2026) — https://www.about.hsbc.com.hk/news-and-media/hsbc-redcoin-launches-today
2. HKMA, "Granting of stablecoin issuer licences" (Apr 10, 2026) — https://www.hkma.gov.hk/eng/news-and-media/press-releases/2026/04/20260410-4/
3. HKMA, Guideline on Supervision of Licensed Stablecoin Issuers (Aug 2025), paras 1.2, 2.2.1, 2.5.1, 2.5.3, 2.6.1, 3.3.1, 3.3.3 — https://www.hkma.gov.hk/media/eng/doc/key-functions/ifc/stablecoin-issuers/Guideline_on_supervision_of_licensed_stablecoin_issuers_eng.pdf
4. Hong Kong Government, Stablecoins Ordinance (Cap. 656) commencement (press release, Jun 6, 2025) — https://www.info.gov.hk/gia/general/202506/06/P2025060600275.htm
5. IKOL Notes #005 and #006 — https://x.com/2425247/status/2113155622208418105 · https://x.com/2425247/status/2113481960903549169
IKOL · AI-assisted research, human-edited. We label what is documented, reported and analyzed — and publish our corrections.
22
·
--
【Structure Watch #007 | BTC 4H】Highs and lows are both expanding outward; price is stuck in the lower half of the range
Previous check: BTC was at 81,048–83,390 when I marked it at 20:00 yesterday. The current price of 81,908 is still within that range, and neither boundary has been touched.
At 08:00, the price was 81,908, down 0.21% over 24 hours, with a trading volume of 10.562 billion U. The intraday high/low was 83,158 / 81,701.
① Structure: Over the last 30 bars, the highs have risen while the lows have fallen, forming an expanding triangle. The range is 80,841–83,961, with a width of 3.9%. The current price is at the 34th percentile, in the lower half of the range. MA25 is at 81,810, just below the current price. Its slope over the last 5 bars is +0.03%, essentially flat.
② Volume and price: Volume over the last 10 bars is 0.89 times that of the previous 30, close to the earlier level, with no significant increase. Of the last 10 bars, 5 closed bullish; it’s evenly split between bullish and bearish bars, suggesting back-and-forth price action.
③ Confluence: Above, in the 82,033–82,599 area, Fib 0.618 (82,033) and the previous high (82,599) form a resistance zone. Below, in the 81,320–81,810 area, MA25 (81,810) and the previous low (81,320) overlap. Both sides have two sources of confluence, which is somewhat more reliable than a single level.
④ Positioning: The funding rate is +0.0092%, meaning longs are paying. Open interest is up 1.69% over the last 7 4H bars, indicating positions are building. The long-short account ratio is 1.62. The price hasn’t moved much, but positions are piling in.
Areas to watch: 82,033–83,017 above; 80,829–81,810 below.
1H view: Over the last 12 hours, price has moved between 81,701 and 82,744. The latest close is at the 20th percentile, near the lower end of this move.
Invalidation: If a 4H candle closes above 83,017 or below 80,829, this analysis is invalidated.
My view is that, in an expanding triangle, what matters most isn’t the middle section but how many times the upper and lower boundaries are actually touched. Do the levels you’ve marked for the 82,033 Fib above and the 81,810 MA25 below match mine?
This is a structural analysis based on publicly available data and is not investment advice. Trade at your own risk.
$BTC
#技术分析 #合约交易 #Bitcoin
【Structure Watch #007 | BTC 4H】Highs and lows are both expanding outward; price is stuck in the lower half of the range
Previous check: BTC was at 81,048–83,390 when I marked it at 20:00 yesterday. The current price of 81,908 is still within that range, and neither boundary has been touched.
At 08:00, the price was 81,908, down 0.21% over 24 hours, with a trading volume of 10.562 billion U. The intraday high/low was 83,158 / 81,701.
① Structure: Over the last 30 bars, the highs have risen while the lows have fallen, forming an expanding triangle. The range is 80,841–83,961, with a width of 3.9%. The current price is at the 34th percentile, in the lower half of the range. MA25 is at 81,810, just below the current price. Its slope over the last 5 bars is +0.03%, essentially flat.
② Volume and price: Volume over the last 10 bars is 0.89 times that of the previous 30, close to the earlier level, with no significant increase. Of the last 10 bars, 5 closed bullish; it’s evenly split between bullish and bearish bars, suggesting back-and-forth price action.
③ Confluence: Above, in the 82,033–82,599 area, Fib 0.618 (82,033) and the previous high (82,599) form a resistance zone. Below, in the 81,320–81,810 area, MA25 (81,810) and the previous low (81,320) overlap. Both sides have two sources of confluence, which is somewhat more reliable than a single level.
④ Positioning: The funding rate is +0.0092%, meaning longs are paying. Open interest is up 1.69% over the last 7 4H bars, indicating positions are building. The long-short account ratio is 1.62. The price hasn’t moved much, but positions are piling in.
Areas to watch: 82,033–83,017 above; 80,829–81,810 below.
1H view: Over the last 12 hours, price has moved between 81,701 and 82,744. The latest close is at the 20th percentile, near the lower end of this move.
Invalidation: If a 4H candle closes above 83,017 or below 80,829, this analysis is invalidated.
My view is that, in an expanding triangle, what matters most isn’t the middle section but how many times the upper and lower boundaries are actually touched. Do the levels you’ve marked for the 82,033 Fib above and the 81,810 MA25 below match mine?
This is a structural analysis based on publicly available data and is not investment advice. Trade at your own risk.
$BTC
#技术分析 #合约交易 #Bitcoin
Previous check: BTC was at 81,048–83,390 when I marked it at 20:00 yesterday. The current price of 81,908 is still within that range, and neither boundary has been touched.
At 08:00, the price was 81,908, down 0.21% over 24 hours, with a trading volume of 10.562 billion U. The intraday high/low was 83,158 / 81,701.
① Structure: Over the last 30 bars, the highs have risen while the lows have fallen, forming an expanding triangle. The range is 80,841–83,961, with a width of 3.9%. The current price is at the 34th percentile, in the lower half of the range. MA25 is at 81,810, just below the current price. Its slope over the last 5 bars is +0.03%, essentially flat.
② Volume and price: Volume over the last 10 bars is 0.89 times that of the previous 30, close to the earlier level, with no significant increase. Of the last 10 bars, 5 closed bullish; it’s evenly split between bullish and bearish bars, suggesting back-and-forth price action.
③ Confluence: Above, in the 82,033–82,599 area, Fib 0.618 (82,033) and the previous high (82,599) form a resistance zone. Below, in the 81,320–81,810 area, MA25 (81,810) and the previous low (81,320) overlap. Both sides have two sources of confluence, which is somewhat more reliable than a single level.
④ Positioning: The funding rate is +0.0092%, meaning longs are paying. Open interest is up 1.69% over the last 7 4H bars, indicating positions are building. The long-short account ratio is 1.62. The price hasn’t moved much, but positions are piling in.
Areas to watch: 82,033–83,017 above; 80,829–81,810 below.
1H view: Over the last 12 hours, price has moved between 81,701 and 82,744. The latest close is at the 20th percentile, near the lower end of this move.
Invalidation: If a 4H candle closes above 83,017 or below 80,829, this analysis is invalidated.
My view is that, in an expanding triangle, what matters most isn’t the middle section but how many times the upper and lower boundaries are actually touched. Do the levels you’ve marked for the 82,033 Fib above and the 81,810 MA25 below match mine?
This is a structural analysis based on publicly available data and is not investment advice. Trade at your own risk.
$BTC
#技术分析 #合约交易 #Bitcoin
90
·
--
#广场运营手记 #007: Week One Recap—There’s Only One Pattern That Actually Drove Results
Today is Day 7 of this series, marking a full week of daily posts. I just checked the latest stats on my profile, and after a week, I’ve noticed a few things worth jotting down.
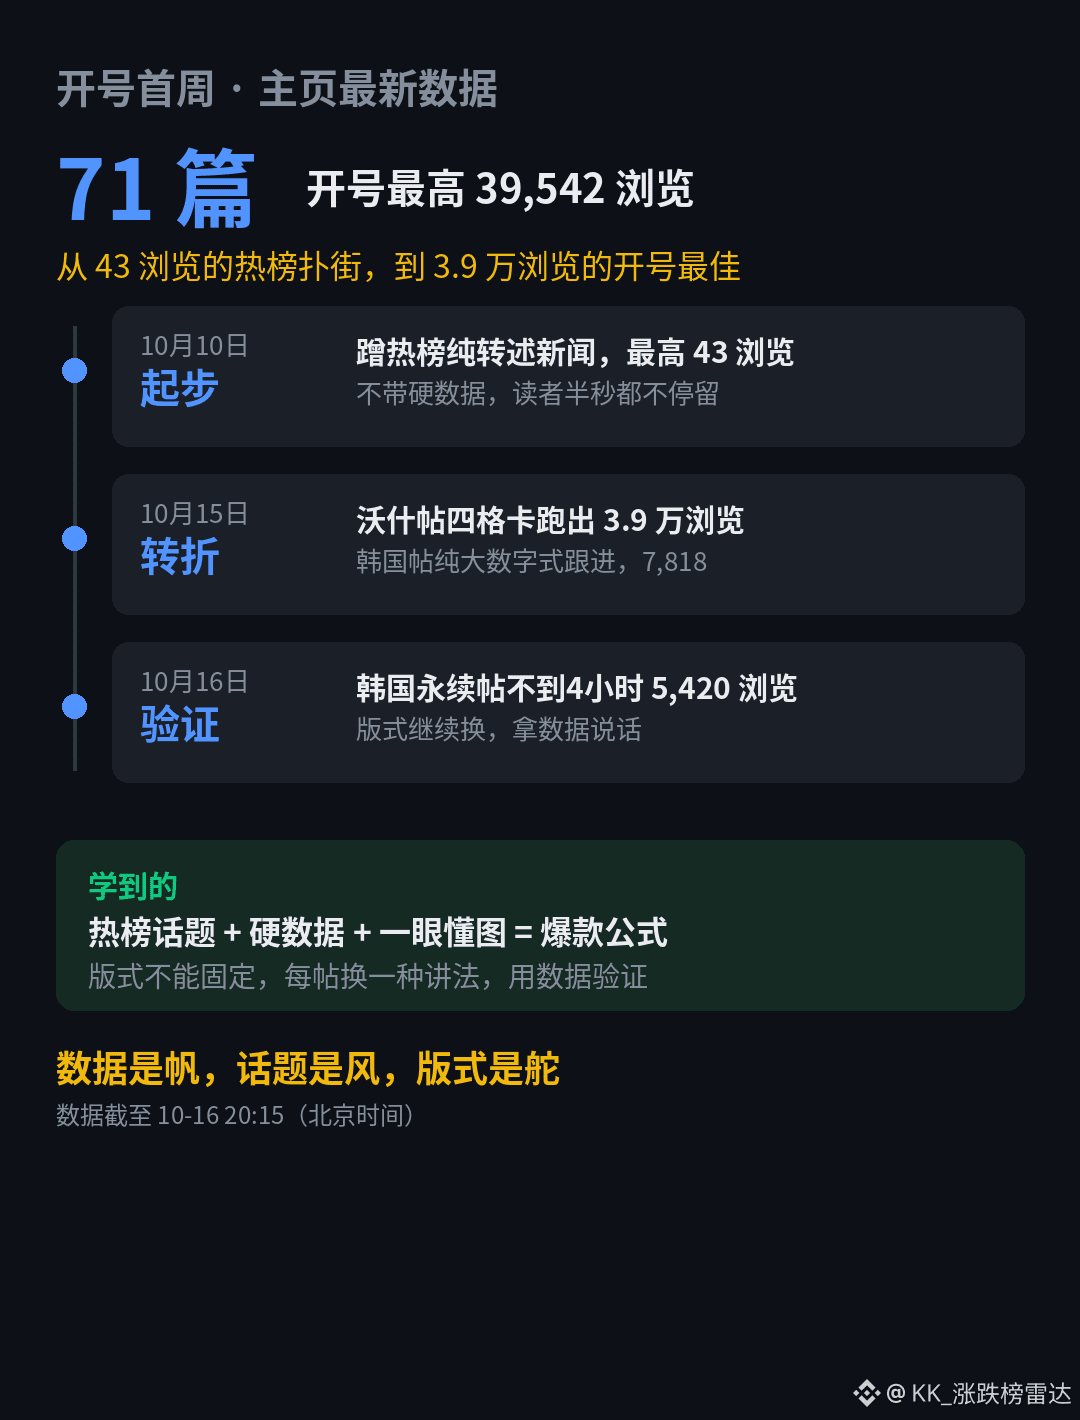
First, the most straightforward takeaway: the post with the most views since I launched this account wasn’t yesterday’s Korea post, which I was pretty proud of. It was one I nearly overlooked—the Wash post from October 15 (“Is the Fed’s ‘playbook’ about to be torn up?”), with 39,542 views, 12 likes, and 5 comments. The post about South Korea blocking 27 exchange websites came in second, with 7,818 views and 3 likes. The post about Korean perpetual futures contracts that I shared this afternoon has already hit 5,420 views in less than 4 hours and is gaining traction. The morning brief remains steady at around 1,000 views a day.
Looking at these posts together, the conclusion actually becomes clearer. The Wash post used a four-panel card: before/now/after/impact, all explained in one image. I was excited when it took off, but today I learned another lesson: don’t turn any one format into a fixed template. The Wash post blew up with a four-panel card; for my next post, I switched to a big-number-only format (the South Korea blocking post, 7,818 views); and today I tried big numbers plus details (the Korea perpetuals post, now gaining traction at 5,420 views). Readers get fatigued. Too many accounts on the platform use the same format until it’s worn out; users can tell at a glance what the next slide will show and just scroll past. My strategy is to change things up with every post and use the data to test what actually works, rather than drawing conclusions from a single hit.
Now, about the trial and error over these 7 days. In the first few days, I also tried to ride trending topics. I posted three times, and the best-performing post got just 43 views—purely repeating the news, with no original data or perspective. It completely flopped. These 7 days have really been a complete trial-and-error cycle: I started out thinking that jumping on trending topics would be enough, but the results showed that without solid data, readers won’t even pause for half a second. After several flops, I nearly started doubting whether this approach could work. Luckily, the morning brief stayed steady and gave me the confidence to keep experimenting. The turning point came on October 15, when the Korea post combined “trending topic + hard data + an image you understand at a glance” and reached 7,818 views. The Wash post went even further, pulling in 39,000.
One more lesson came from a flop: adding hashtags indiscriminately can get your reach penalized. The content and hashtags have to be about the same thing. Better to use too few than too many.
Next week, I’ll focus on three things: continue adding images to trending-topic follow-ups and test a different approach with each post; keep publishing the morning brief every day—it’s my steadiest foundation; and skip trending topics if I don’t have hard data to support them. The cost of a bad post isn’t wasting one posting slot; it’s eroding readers’ trust in this account.
7 days, 71 posts—from flopping with 43 views to my best-ever post with 39,000 views. I’m still a small creator, but the path is getting clearer: data is the sail, topics are the wind, and format is the rudder.
Have you ever tried “using a different format for every post” on the platform? Let’s talk in the comments.
$BTC $ETH
#广场运营手记 #007: Week One Recap—There’s Only One Pattern That Actually Drove Results
Today is Day 7 of this series, marking a full week of daily posts. I just checked the latest stats on my profile, and after a week, I’ve noticed a few things worth jotting down.
First, the most straightforward takeaway: the post with the most views since I launched this account wasn’t yesterday’s Korea post, which I was pretty proud of. It was one I nearly overlooked—the Wash post from October 15 (“Is the Fed’s ‘playbook’ about to be torn up?”), with 39,542 views, 12 likes, and 5 comments. The post about South Korea blocking 27 exchange websites came in second, with 7,818 views and 3 likes. The post about Korean perpetual futures contracts that I shared this afternoon has already hit 5,420 views in less than 4 hours and is gaining traction. The morning brief remains steady at around 1,000 views a day.
Looking at these posts together, the conclusion actually becomes clearer. The Wash post used a four-panel card: before/now/after/impact, all explained in one image. I was excited when it took off, but today I learned another lesson: don’t turn any one format into a fixed template. The Wash post blew up with a four-panel card; for my next post, I switched to a big-number-only format (the South Korea blocking post, 7,818 views); and today I tried big numbers plus details (the Korea perpetuals post, now gaining traction at 5,420 views). Readers get fatigued. Too many accounts on the platform use the same format until it’s worn out; users can tell at a glance what the next slide will show and just scroll past. My strategy is to change things up with every post and use the data to test what actually works, rather than drawing conclusions from a single hit.
Now, about the trial and error over these 7 days. In the first few days, I also tried to ride trending topics. I posted three times, and the best-performing post got just 43 views—purely repeating the news, with no original data or perspective. It completely flopped. These 7 days have really been a complete trial-and-error cycle: I started out thinking that jumping on trending topics would be enough, but the results showed that without solid data, readers won’t even pause for half a second. After several flops, I nearly started doubting whether this approach could work. Luckily, the morning brief stayed steady and gave me the confidence to keep experimenting. The turning point came on October 15, when the Korea post combined “trending topic + hard data + an image you understand at a glance” and reached 7,818 views. The Wash post went even further, pulling in 39,000.
One more lesson came from a flop: adding hashtags indiscriminately can get your reach penalized. The content and hashtags have to be about the same thing. Better to use too few than too many.
Next week, I’ll focus on three things: continue adding images to trending-topic follow-ups and test a different approach with each post; keep publishing the morning brief every day—it’s my steadiest foundation; and skip trending topics if I don’t have hard data to support them. The cost of a bad post isn’t wasting one posting slot; it’s eroding readers’ trust in this account.
7 days, 71 posts—from flopping with 43 views to my best-ever post with 39,000 views. I’m still a small creator, but the path is getting clearer: data is the sail, topics are the wind, and format is the rudder.
Have you ever tried “using a different format for every post” on the platform? Let’s talk in the comments.
$BTC $ETH
Today is Day 7 of this series, marking a full week of daily posts. I just checked the latest stats on my profile, and after a week, I’ve noticed a few things worth jotting down.
First, the most straightforward takeaway: the post with the most views since I launched this account wasn’t yesterday’s Korea post, which I was pretty proud of. It was one I nearly overlooked—the Wash post from October 15 (“Is the Fed’s ‘playbook’ about to be torn up?”), with 39,542 views, 12 likes, and 5 comments. The post about South Korea blocking 27 exchange websites came in second, with 7,818 views and 3 likes. The post about Korean perpetual futures contracts that I shared this afternoon has already hit 5,420 views in less than 4 hours and is gaining traction. The morning brief remains steady at around 1,000 views a day.
Looking at these posts together, the conclusion actually becomes clearer. The Wash post used a four-panel card: before/now/after/impact, all explained in one image. I was excited when it took off, but today I learned another lesson: don’t turn any one format into a fixed template. The Wash post blew up with a four-panel card; for my next post, I switched to a big-number-only format (the South Korea blocking post, 7,818 views); and today I tried big numbers plus details (the Korea perpetuals post, now gaining traction at 5,420 views). Readers get fatigued. Too many accounts on the platform use the same format until it’s worn out; users can tell at a glance what the next slide will show and just scroll past. My strategy is to change things up with every post and use the data to test what actually works, rather than drawing conclusions from a single hit.
Now, about the trial and error over these 7 days. In the first few days, I also tried to ride trending topics. I posted three times, and the best-performing post got just 43 views—purely repeating the news, with no original data or perspective. It completely flopped. These 7 days have really been a complete trial-and-error cycle: I started out thinking that jumping on trending topics would be enough, but the results showed that without solid data, readers won’t even pause for half a second. After several flops, I nearly started doubting whether this approach could work. Luckily, the morning brief stayed steady and gave me the confidence to keep experimenting. The turning point came on October 15, when the Korea post combined “trending topic + hard data + an image you understand at a glance” and reached 7,818 views. The Wash post went even further, pulling in 39,000.
One more lesson came from a flop: adding hashtags indiscriminately can get your reach penalized. The content and hashtags have to be about the same thing. Better to use too few than too many.
Next week, I’ll focus on three things: continue adding images to trending-topic follow-ups and test a different approach with each post; keep publishing the morning brief every day—it’s my steadiest foundation; and skip trending topics if I don’t have hard data to support them. The cost of a bad post isn’t wasting one posting slot; it’s eroding readers’ trust in this account.
7 days, 71 posts—from flopping with 43 views to my best-ever post with 39,000 views. I’m still a small creator, but the path is getting clearer: data is the sail, topics are the wind, and format is the rudder.
Have you ever tried “using a different format for every post” on the platform? Let’s talk in the comments.
$BTC $ETH
175
·
--
#007
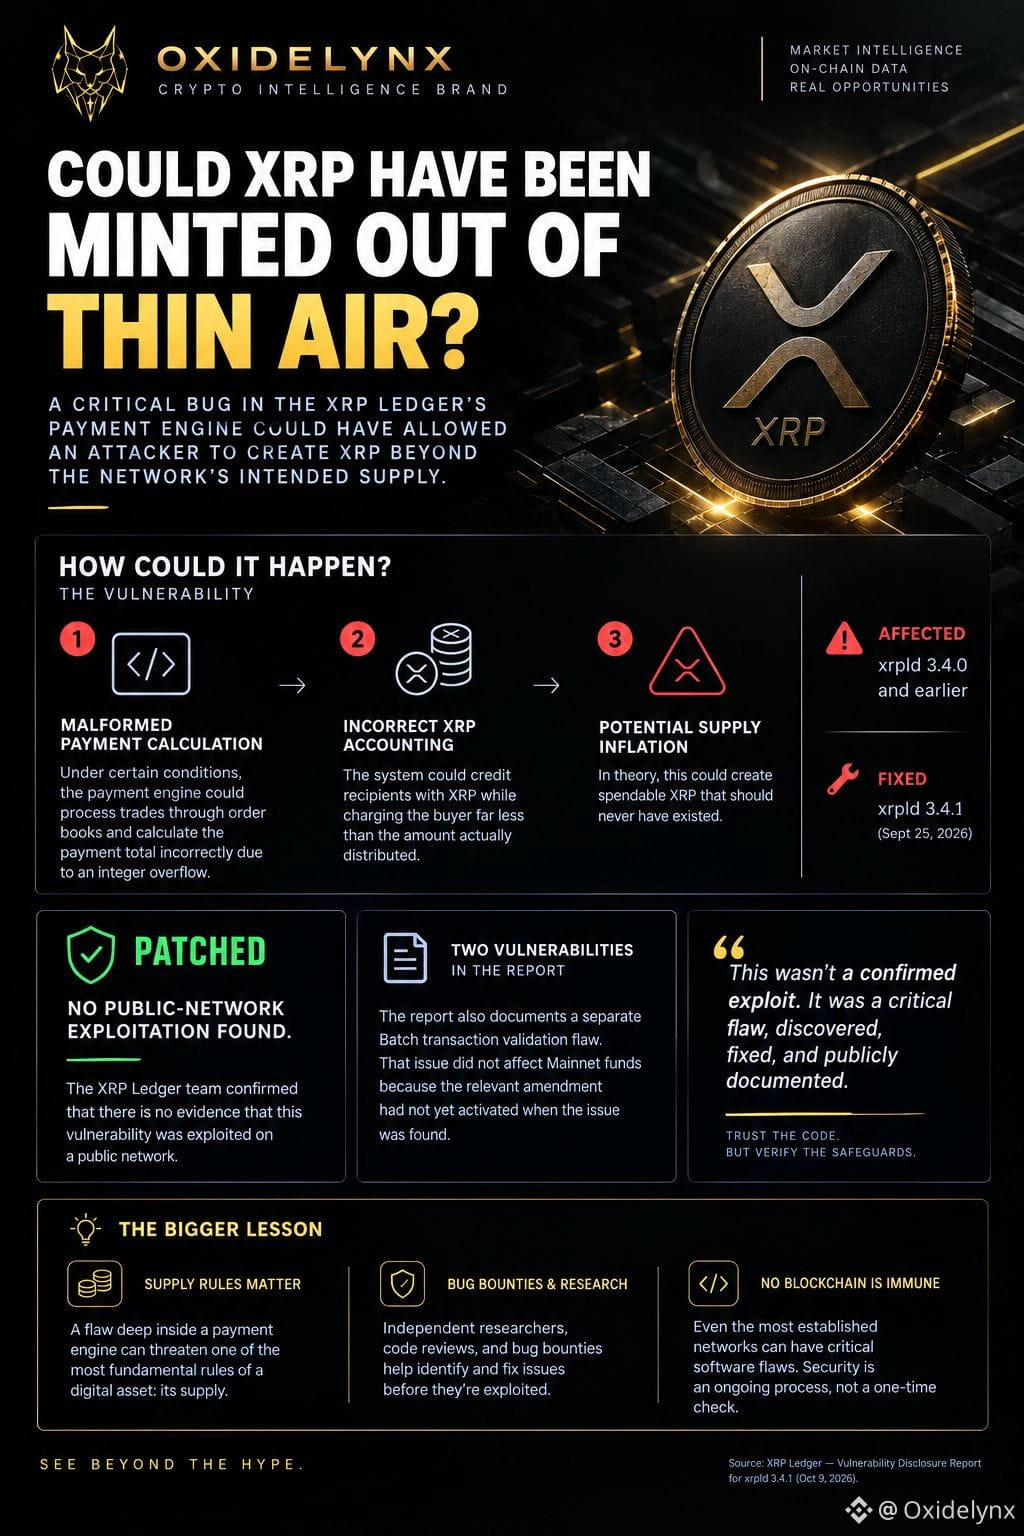
COULD XRP HAVE BEEN MINTED OUT OF THIN AIR?
A critical bug in the XRP Ledger payment engine could theoretically have allowed attackers to create spendable XRP beyond its intended supply.
🔎 What happened?
The flaw may have existed since 2015. A fix was released in xrpld 3.4.1 on September 25, 2026. The team reported no evidence of exploitation on a public network.
⚠️ The key point : A serious vulnerability was discovered, but there is no confirmed exploit.
Even established blockchains need constant security reviews.
Trust the code. Verify the safeguards.
SEE BEYOND THE HYPE.
#XRP #CryptoSecurity #Blockchain #OXIDELYNX
#007
COULD XRP HAVE BEEN MINTED OUT OF THIN AIR?
A critical bug in the XRP Ledger payment engine could theoretically have allowed attackers to create spendable XRP beyond its intended supply.
🔎 What happened?
The flaw may have existed since 2015. A fix was released in xrpld 3.4.1 on September 25, 2026. The team reported no evidence of exploitation on a public network.
⚠️ The key point : A serious vulnerability was discovered, but there is no confirmed exploit.
Even established blockchains need constant security reviews.
Trust the code. Verify the safeguards.
SEE BEYOND THE HYPE.
#XRP #CryptoSecurity #Blockchain #OXIDELYNX
COULD XRP HAVE BEEN MINTED OUT OF THIN AIR?
A critical bug in the XRP Ledger payment engine could theoretically have allowed attackers to create spendable XRP beyond its intended supply.
🔎 What happened?
The flaw may have existed since 2015. A fix was released in xrpld 3.4.1 on September 25, 2026. The team reported no evidence of exploitation on a public network.
⚠️ The key point : A serious vulnerability was discovered, but there is no confirmed exploit.
Even established blockchains need constant security reviews.
Trust the code. Verify the safeguards.
SEE BEYOND THE HYPE.
#XRP #CryptoSecurity #Blockchain #OXIDELYNX
103
·
--
$WLD /USDT | MOMENTUM RADAR #007
{future}(WLDUSDT)
Status: Bullish Continuation Setup
WLD is holding above all major moving averages on the 4H chart, with MA7 and MA25 acting as dynamic support. Buyers are defending the $0.62 area, and a break above $0.66 could trigger another expansion move.
Smart Money Plan Direction: LONG
Entry Zone: $0.638 – $0.648
Leverage: 5x–8x Isolated
Stop Loss: $0.612
Target Map
Target 1: $0.670
Target 2: $0.695
Target 3: $0.725
Market Trigger
A 4H candle close above $0.66 with rising volume can accelerate momentum toward the $0.70+ zone.
Trade Management
Take 30% profits at TP1, move SL to entry, and let the remaining position run.
Edge Score: 8/10
Invalidation: Lose $0.612 support and bullish structure weakens.
The chart is improving, but entries near support always beat chasing green candles.
#FedProposesCIPForStablecoinIssuers #GoldETFInflowsBiggestSinceApril17 #OilHeadsForDeepWeeklyLoss
$WLD /USDT | MOMENTUM RADAR #007
Status: Bullish Continuation Setup
WLD is holding above all major moving averages on the 4H chart, with MA7 and MA25 acting as dynamic support. Buyers are defending the $0.62 area, and a break above $0.66 could trigger another expansion move.
Smart Money Plan Direction: LONG
Entry Zone: $0.638 – $0.648
Leverage: 5x–8x Isolated
Stop Loss: $0.612
Target Map
Target 1: $0.670
Target 2: $0.695
Target 3: $0.725
Market Trigger
A 4H candle close above $0.66 with rising volume can accelerate momentum toward the $0.70+ zone.
Trade Management
Take 30% profits at TP1, move SL to entry, and let the remaining position run.
Edge Score: 8/10
Invalidation: Lose $0.612 support and bullish structure weakens.
The chart is improving, but entries near support always beat chasing green candles.
#FedProposesCIPForStablecoinIssuers #GoldETFInflowsBiggestSinceApril17 #OilHeadsForDeepWeeklyLoss
Status: Bullish Continuation Setup
WLD is holding above all major moving averages on the 4H chart, with MA7 and MA25 acting as dynamic support. Buyers are defending the $0.62 area, and a break above $0.66 could trigger another expansion move.
Smart Money Plan Direction: LONG
Entry Zone: $0.638 – $0.648
Leverage: 5x–8x Isolated
Stop Loss: $0.612
Target Map
Target 1: $0.670
Target 2: $0.695
Target 3: $0.725
Market Trigger
A 4H candle close above $0.66 with rising volume can accelerate momentum toward the $0.70+ zone.
Trade Management
Take 30% profits at TP1, move SL to entry, and let the remaining position run.
Edge Score: 8/10
Invalidation: Lose $0.612 support and bullish structure weakens.
The chart is improving, but entries near support always beat chasing green candles.
#FedProposesCIPForStablecoinIssuers #GoldETFInflowsBiggestSinceApril17 #OilHeadsForDeepWeeklyLoss
1
183
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BinanceProcesses$4.65BWithdrawals
48,664 views
196 Discussing
2
#WithdrawalsBack: 15 networks live
10,737 views
156 Discussing
3
#EthereumSurpasses$2300
15 views
25 Discussing
4
#BitcoinSpotETFsPost$203MWeeklyOutflow
169 views
8 Discussing
5
#SouthKoreanLawmakerProposesReviewOfAllListedDigitalAssets
286 views
12 Discussing
6
#BrazilVirtualAssetLicenseDeadlineDrawsAbout40Firms
9,709 views
190 Discussing
7
#BTCPayServerUrgesOperatorsToShutDownInstances
9,724 views
185 Discussing
8
#BankOfKoreaSurveysFinancialFirmsOnVirtualAssetRisks
435 views
12 Discussing
9
#BinanceUpdatesProofofReservesAddresses
181,467 views
1,874 Discussing
10
#StudyFindsCircleAIAgentWalletLimitsCanBeBypassed
4,158 views
103 Discussing