
ENSIGN TRADING
4.8k Posts

ENSIGN TRADING
Report
Block User
Digital Entrepreneur/P2P BLOCK MERCHANT

Top Voices

Level 1 Creator
Open Trade

BTC Holder
Occasional Trader
5.5 Years
10 Following
27.8K+ Followers
22.1K+ Liked
2 Badges
Posts
Portfolio
All
Quotes
Videos
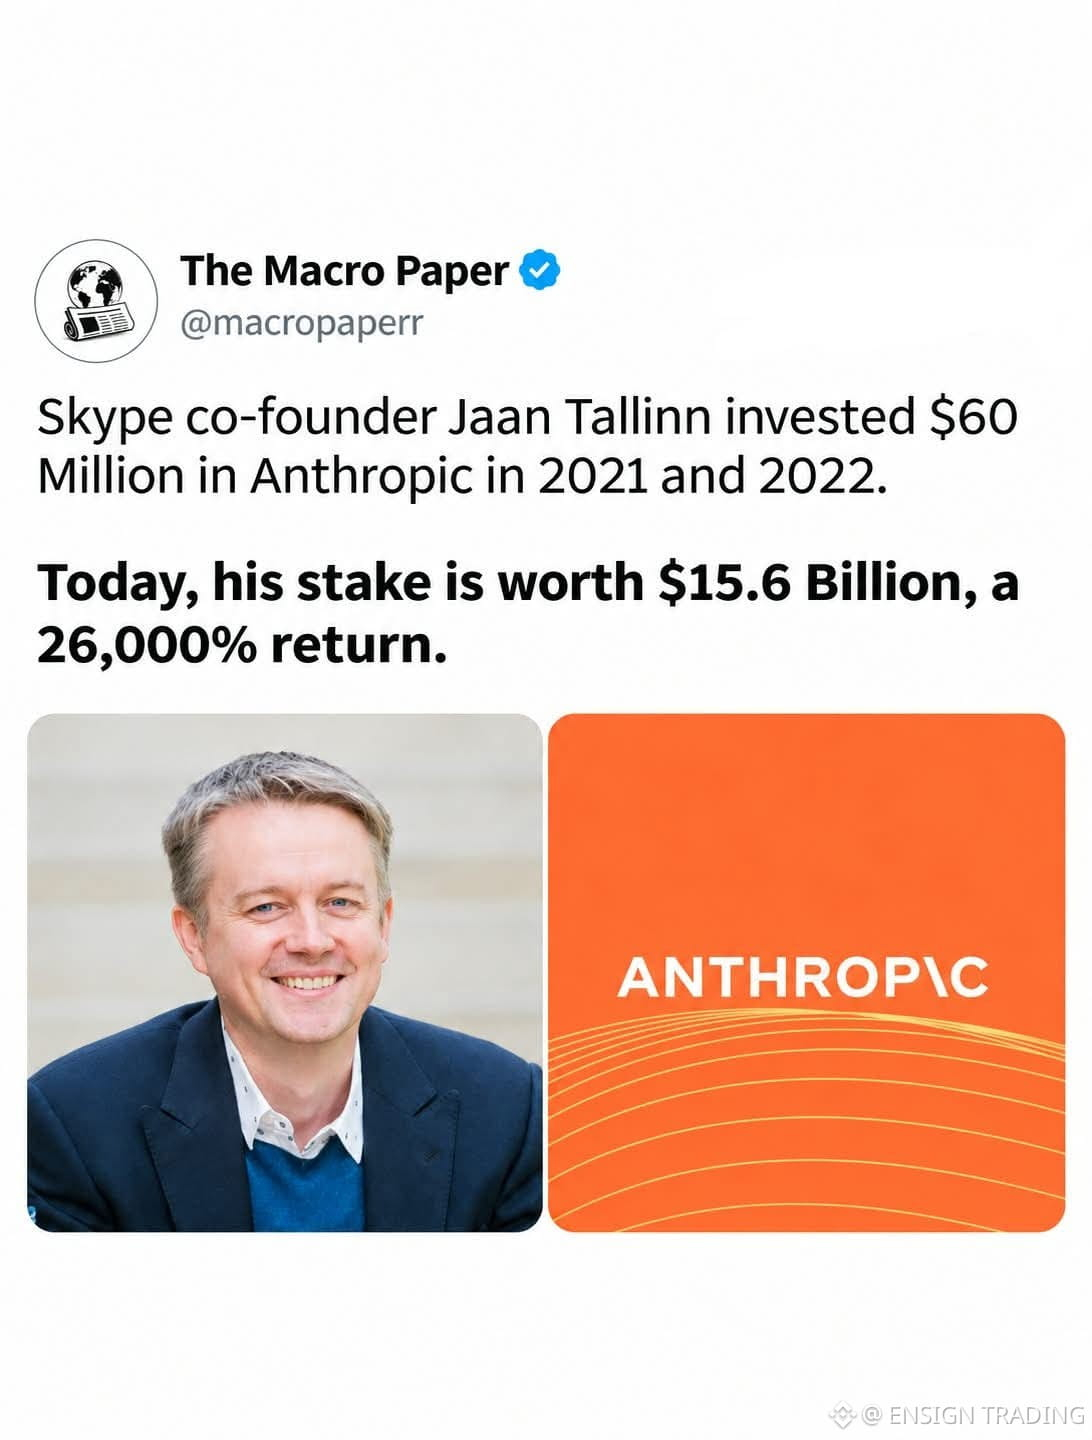
$60 Million Turned Into a $15.6 Billion Fortune — The Power of Investing Early!
In 2021 and 2022, Skype co-founder Jaan Tallinn invested an estimated $60 million in Anthropic, long before AI became one of the biggest investment stories in the world.
Today, Forbes estimates his stake is worth approximately $15.6 billion.
That represents roughly a 260× return, or around 25,900% in gains on the original investment.
An estimated $60 million turned into $15.6 billion.
That's approximately $15.54 billion in value created from one early investment.
What makes this story fascinating isn't just the number.
It's the timing.
He invested when Anthropic was still developing its technology, competing for capital, and carrying the risks that come with backing an early-stage company.
Most investors notice a company when its success is already visible.
But some of the biggest investment returns are created before the market fully recognizes what a business could become.
Of course, finding the next Anthropic is incredibly difficult.
Most early-stage companies never reach this level, and enormous returns come with enormous risk.
But this is exactly why investing is about more than chasing today's popular stocks.
It's about identifying businesses with the potential to change an industry, understanding the risks, and having the patience to let long-term growth work.
Wealth is often built by recognizing potential before it becomes obvious to everyone else.
$60 Million Turned Into a $15.6 Billion Fortune — The Power of Investing Early!
In 2021 and 2022, Skype co-founder Jaan Tallinn invested an estimated $60 million in Anthropic, long before AI became one of the biggest investment stories in the world.
Today, Forbes estimates his stake is worth approximately $15.6 billion.
That represents roughly a 260× return, or around 25,900% in gains on the original investment.
An estimated $60 million turned into $15.6 billion.
That's approximately $15.54 billion in value created from one early investment.
What makes this story fascinating isn't just the number.
It's the timing.
He invested when Anthropic was still developing its technology, competing for capital, and carrying the risks that come with backing an early-stage company.
Most investors notice a company when its success is already visible.
But some of the biggest investment returns are created before the market fully recognizes what a business could become.
Of course, finding the next Anthropic is incredibly difficult.
Most early-stage companies never reach this level, and enormous returns come with enormous risk.
But this is exactly why investing is about more than chasing today's popular stocks.
It's about identifying businesses with the potential to change an industry, understanding the risks, and having the patience to let long-term growth work.
Wealth is often built by recognizing potential before it becomes obvious to everyone else.
In 2021 and 2022, Skype co-founder Jaan Tallinn invested an estimated $60 million in Anthropic, long before AI became one of the biggest investment stories in the world.
Today, Forbes estimates his stake is worth approximately $15.6 billion.
That represents roughly a 260× return, or around 25,900% in gains on the original investment.
An estimated $60 million turned into $15.6 billion.
That's approximately $15.54 billion in value created from one early investment.
What makes this story fascinating isn't just the number.
It's the timing.
He invested when Anthropic was still developing its technology, competing for capital, and carrying the risks that come with backing an early-stage company.
Most investors notice a company when its success is already visible.
But some of the biggest investment returns are created before the market fully recognizes what a business could become.
Of course, finding the next Anthropic is incredibly difficult.
Most early-stage companies never reach this level, and enormous returns come with enormous risk.
But this is exactly why investing is about more than chasing today's popular stocks.
It's about identifying businesses with the potential to change an industry, understanding the risks, and having the patience to let long-term growth work.
Wealth is often built by recognizing potential before it becomes obvious to everyone else.
295
In 2022, a crypto founder called Sam Bankman-Fried, the founder of FTX, a cryptocurrency exchange
invested $500 million in Anthropic, the company behind Claude AI.
At the time, Anthropic was still a relatively young artificial intelligence company.
That investment gave FTX a significant ownership stake in the company, which was reported to be approximately 7.84% by 2024.
However, things took a different turn.
In 2022, FTX collapsed, and Sam Bankman-Fried was subsequently accused of misappropriating billions of dollars belonging to customers and investors.
He was eventually convicted and sentenced to 25 years in prison.
The $500 million investment in Anthropic became one of the assets recovered during the bankruptcy proceedings.
FTX’s bankruptcy estate eventually sold its stake for approximately $884 million to help repay creditors.
But here is the shocker
Anthropic has now priced its IPO at $83 per share, valuing the company at approximately $1.5 trillion.
If that original 7.84% stake had remained intact until today, it would be worth approximately $117.6 billion.
A $500 million investment turned into an asset worth over $117 billion.
Within 4 years.
All He needed was hold on 😬
Sam Bankman-Fried could possibly become one of the richest people in the world through that single investment.
But today, he is in prison.
Imagine being a man who saw the future early enough to invest in one of the most valuable artificial intelligence companies in the world, but whose own actions eventually took away the opportunity to benefit from that investment.
Sometimes, the opportunities we see are not necessarily the problem.
What we do with the opportunities we have, and the decisions we make along the way, can determine whether we eventually benefit from them or lose everything.
The future belongs to people who can see it, but seeing the future is not enough.
You must also have the discipline and judgment to get there.
This is the most upsetting part of the Anthropic going public.
In 2022, a crypto founder called Sam Bankman-Fried, the founder of FTX, a cryptocurrency exchange
invested $500 million in Anthropic, the company behind Claude AI.
At the time, Anthropic was still a relatively young artificial intelligence company.
That investment gave FTX a significant ownership stake in the company, which was reported to be approximately 7.84% by 2024.
However, things took a different turn.
In 2022, FTX collapsed, and Sam Bankman-Fried was subsequently accused of misappropriating billions of dollars belonging to customers and investors.
He was eventually convicted and sentenced to 25 years in prison.
The $500 million investment in Anthropic became one of the assets recovered during the bankruptcy proceedings.
FTX’s bankruptcy estate eventually sold its stake for approximately $884 million to help repay creditors.
But here is the shocker
Anthropic has now priced its IPO at $83 per share, valuing the company at approximately $1.5 trillion.
If that original 7.84% stake had remained intact until today, it would be worth approximately $117.6 billion.
A $500 million investment turned into an asset worth over $117 billion.
Within 4 years.
All He needed was hold on 😬
Sam Bankman-Fried could possibly become one of the richest people in the world through that single investment.
But today, he is in prison.
Imagine being a man who saw the future early enough to invest in one of the most valuable artificial intelligence companies in the world, but whose own actions eventually took away the opportunity to benefit from that investment.
Sometimes, the opportunities we see are not necessarily the problem.
What we do with the opportunities we have, and the decisions we make along the way, can determine whether we eventually benefit from them or lose everything.
The future belongs to people who can see it, but seeing the future is not enough.
You must also have the discipline and judgment to get there.
This is the most upsetting part of the Anthropic going public.
invested $500 million in Anthropic, the company behind Claude AI.
At the time, Anthropic was still a relatively young artificial intelligence company.
That investment gave FTX a significant ownership stake in the company, which was reported to be approximately 7.84% by 2024.
However, things took a different turn.
In 2022, FTX collapsed, and Sam Bankman-Fried was subsequently accused of misappropriating billions of dollars belonging to customers and investors.
He was eventually convicted and sentenced to 25 years in prison.
The $500 million investment in Anthropic became one of the assets recovered during the bankruptcy proceedings.
FTX’s bankruptcy estate eventually sold its stake for approximately $884 million to help repay creditors.
But here is the shocker
Anthropic has now priced its IPO at $83 per share, valuing the company at approximately $1.5 trillion.
If that original 7.84% stake had remained intact until today, it would be worth approximately $117.6 billion.
A $500 million investment turned into an asset worth over $117 billion.
Within 4 years.
All He needed was hold on 😬
Sam Bankman-Fried could possibly become one of the richest people in the world through that single investment.
But today, he is in prison.
Imagine being a man who saw the future early enough to invest in one of the most valuable artificial intelligence companies in the world, but whose own actions eventually took away the opportunity to benefit from that investment.
Sometimes, the opportunities we see are not necessarily the problem.
What we do with the opportunities we have, and the decisions we make along the way, can determine whether we eventually benefit from them or lose everything.
The future belongs to people who can see it, but seeing the future is not enough.
You must also have the discipline and judgment to get there.
This is the most upsetting part of the Anthropic going public.
211
Article
Gold's Biggest Enemy Might Not Be War. It Might Be the Federal Reserve.Gold's Biggest Enemy Might Not Be War. It Might Be the Federal Reserve.
There's something about gold that investors often misunderstand.
When the world becomes unstable, people rush toward safe-haven assets.
Wars escalate.
Oil prices rise.
Inflation fears return.
And suddenly, gold becomes one of the most attractive places to protect wealth.
But here's the part that deserves much more attention:
The same inflation that initially pushes gold higher can eventually create the conditions that push it lower.
History has already demonstrated this.
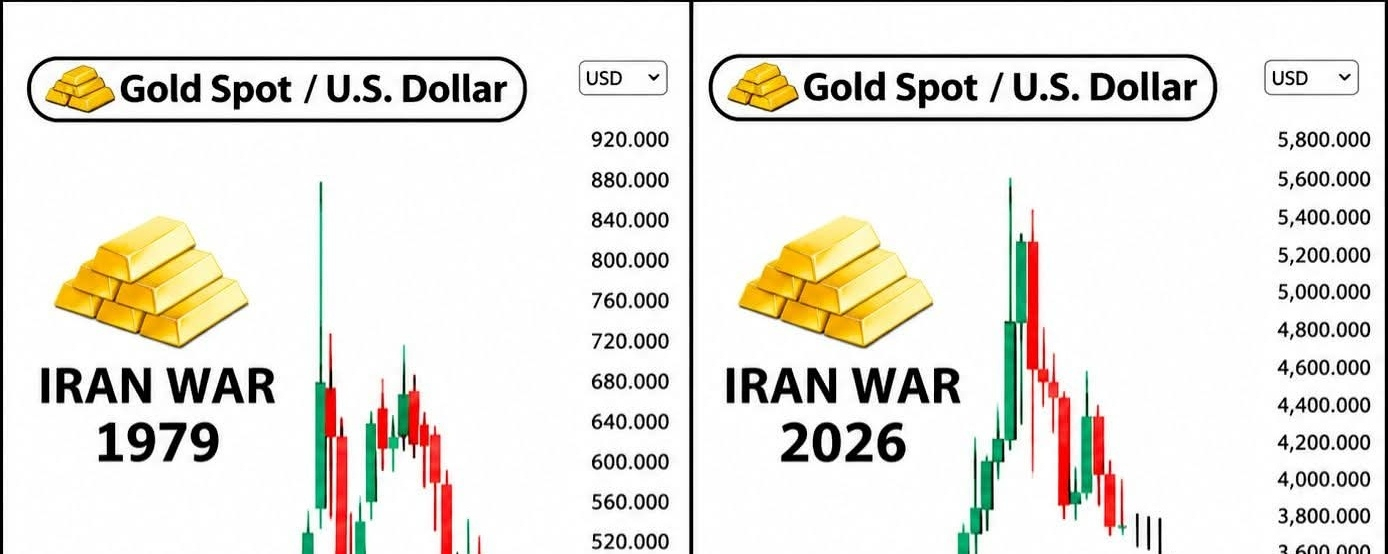
THE 1979–1980 GOLD BOOM: A LESSON WALL STREET HASN'T FORGOTTEN
During the late 1970s, gold experienced an extraordinary rally.
The Iranian Revolution, the hostage crisis, the Soviet invasion of Afghanistan, rising oil prices and accelerating inflation created enormous uncertainty.
Investors wanted protection against declining purchasing power and geopolitical instability.
Gold climbed from approximately $236 per ounce in April 1979 to $850 in January 1980.
That's an increase of more than 250% in roughly nine months.
But the rally didn't last.
Between September 1980 and June 1982, gold fell approximately 52%.
By February 1985, it had reached around $285 per ounce.
What changed?
THE FED CHANGED THE FINANCIAL ENVIRONMENT.
Paul Volcker, then Chairman of the Federal Reserve, was determined to bring inflation under control.
Interest rates climbed dramatically, reaching approximately 20% during parts of 1980 and 1981.
That changed the economics of holding gold.
Unlike Treasury securities or bank deposits, gold doesn't pay interest.
When investors can earn attractive returns on interest-bearing assets, the opportunity cost of holding gold increases.
At the same time, higher real interest rates and a stronger U.S. dollar can reduce demand for bullion.
Gold didn't suddenly become useless.
The financial conditions that had supported its extraordinary valuation were changing.
NOW LOOK AT THE 2026 MARKET.
Gold is facing another difficult combination.
The metal reached a record high of approximately $5,595 per ounce in January.
By November 16, it had fallen to approximately $3,831.
That's a decline of around 31.5%.
And several developments are putting pressure on the market.
1. THE U.S. DOLLAR IS GETTING STRONGER
Gold is priced internationally in U.S. dollars.
When the dollar strengthens, gold becomes more expensive for buyers using other currencies.
That can reduce international demand and put downward pressure on prices.
2. TREASURY YIELDS ARE RISING
The 10-year U.S. Treasury yield recently reached approximately 5.14%.
Higher yields make interest-bearing investments more competitive with gold.
For institutional investors managing enormous portfolios, that opportunity cost matters.
3. INFLATION IS CREATING A POLICY PROBLEM
Geopolitical tensions and higher oil prices can increase inflationary pressure.
But here's the contradiction:
Inflation fears can initially increase demand for gold.
If those same inflation pressures force the Federal Reserve to maintain restrictive policy or raise interest rates, gold can subsequently face selling pressure.
That's the mechanism investors need to understand.
4. THE FED'S NEXT MOVE COULD MATTER MORE THAN THE HEADLINES
Markets are currently anticipating a possible 25-basis-point rate increase in December.
But expectations are not the same as an actual Federal Reserve decision.
If inflation remains persistent and the Fed becomes more aggressive, gold could face additional pressure.
If economic growth weakens or rate expectations reverse, the picture could change again.
HERE'S MY BIGGEST TAKEAWAY FROM THE 1979 COMPARISON.
Gold is not automatically bullish during every war.
And it doesn't automatically collapse when geopolitical tensions ease.
The bigger drivers are often the relationship between inflation, real interest rates, the U.S. dollar, central-bank policy and investor demand.
There is also an important difference between 1980 and 2026.
Today's gold market has substantial central-bank participation, investment funds and different global reserve dynamics.
History can explain the risks, but it cannot guarantee that the same outcome will repeat.
A 50% historical decline is a warning about volatility, not a prediction of the next move.
The real question isn't simply whether gold is expensive or cheap. It's whether the financial conditions supporting its price are getting stronger or weaker.
That's what serious gold investors should be watching.
Gold's Biggest Enemy Might Not Be War. It Might Be the Federal Reserve.
Gold's Biggest Enemy Might Not Be War. It Might Be the Federal Reserve.
There's something about gold that investors often misunderstand.
When the world becomes unstable, people rush toward safe-haven assets.
Wars escalate.
Oil prices rise.
Inflation fears return.
And suddenly, gold becomes one of the most attractive places to protect wealth.
But here's the part that deserves much more attention:
The same inflation that initially pushes gold higher can eventually create the conditions that push it lower.
History has already demonstrated this.
THE 1979–1980 GOLD BOOM: A LESSON WALL STREET HASN'T FORGOTTEN
During the late 1970s, gold experienced an extraordinary rally.
The Iranian Revolution, the hostage crisis, the Soviet invasion of Afghanistan, rising oil prices and accelerating inflation created enormous uncertainty.
Investors wanted protection against declining purchasing power and geopolitical instability.
Gold climbed from approximately $236 per ounce in April 1979 to $850 in January 1980.
That's an increase of more than 250% in roughly nine months.
But the rally didn't last.
Between September 1980 and June 1982, gold fell approximately 52%.
By February 1985, it had reached around $285 per ounce.
What changed?
THE FED CHANGED THE FINANCIAL ENVIRONMENT.
Paul Volcker, then Chairman of the Federal Reserve, was determined to bring inflation under control.
Interest rates climbed dramatically, reaching approximately 20% during parts of 1980 and 1981.
That changed the economics of holding gold.
Unlike Treasury securities or bank deposits, gold doesn't pay interest.
When investors can earn attractive returns on interest-bearing assets, the opportunity cost of holding gold increases.
At the same time, higher real interest rates and a stronger U.S. dollar can reduce demand for bullion.
Gold didn't suddenly become useless.
The financial conditions that had supported its extraordinary valuation were changing.
NOW LOOK AT THE 2026 MARKET.
Gold is facing another difficult combination.
The metal reached a record high of approximately $5,595 per ounce in January.
By November 16, it had fallen to approximately $3,831.
That's a decline of around 31.5%.
And several developments are putting pressure on the market.
1. THE U.S. DOLLAR IS GETTING STRONGER
Gold is priced internationally in U.S. dollars.
When the dollar strengthens, gold becomes more expensive for buyers using other currencies.
That can reduce international demand and put downward pressure on prices.
2. TREASURY YIELDS ARE RISING
The 10-year U.S. Treasury yield recently reached approximately 5.14%.
Higher yields make interest-bearing investments more competitive with gold.
For institutional investors managing enormous portfolios, that opportunity cost matters.
3. INFLATION IS CREATING A POLICY PROBLEM
Geopolitical tensions and higher oil prices can increase inflationary pressure.
But here's the contradiction:
Inflation fears can initially increase demand for gold.
If those same inflation pressures force the Federal Reserve to maintain restrictive policy or raise interest rates, gold can subsequently face selling pressure.
That's the mechanism investors need to understand.
4. THE FED'S NEXT MOVE COULD MATTER MORE THAN THE HEADLINES
Markets are currently anticipating a possible 25-basis-point rate increase in December.
But expectations are not the same as an actual Federal Reserve decision.
If inflation remains persistent and the Fed becomes more aggressive, gold could face additional pressure.
If economic growth weakens or rate expectations reverse, the picture could change again.
HERE'S MY BIGGEST TAKEAWAY FROM THE 1979 COMPARISON.
Gold is not automatically bullish during every war.
And it doesn't automatically collapse when geopolitical tensions ease.
The bigger drivers are often the relationship between inflation, real interest rates, the U.S. dollar, central-bank policy and investor demand.
There is also an important difference between 1980 and 2026.
Today's gold market has substantial central-bank participation, investment funds and different global reserve dynamics.
History can explain the risks, but it cannot guarantee that the same outcome will repeat.
A 50% historical decline is a warning about volatility, not a prediction of the next move.
The real question isn't simply whether gold is expensive or cheap. It's whether the financial conditions supporting its price are getting stronger or weaker.
That's what serious gold investors should be watching.
There's something about gold that investors often misunderstand.
When the world becomes unstable, people rush toward safe-haven assets.
Wars escalate.
Oil prices rise.
Inflation fears return.
And suddenly, gold becomes one of the most attractive places to protect wealth.
But here's the part that deserves much more attention:
The same inflation that initially pushes gold higher can eventually create the conditions that push it lower.
History has already demonstrated this.
THE 1979–1980 GOLD BOOM: A LESSON WALL STREET HASN'T FORGOTTEN
During the late 1970s, gold experienced an extraordinary rally.
The Iranian Revolution, the hostage crisis, the Soviet invasion of Afghanistan, rising oil prices and accelerating inflation created enormous uncertainty.
Investors wanted protection against declining purchasing power and geopolitical instability.
Gold climbed from approximately $236 per ounce in April 1979 to $850 in January 1980.
That's an increase of more than 250% in roughly nine months.
But the rally didn't last.
Between September 1980 and June 1982, gold fell approximately 52%.
By February 1985, it had reached around $285 per ounce.
What changed?
THE FED CHANGED THE FINANCIAL ENVIRONMENT.
Paul Volcker, then Chairman of the Federal Reserve, was determined to bring inflation under control.
Interest rates climbed dramatically, reaching approximately 20% during parts of 1980 and 1981.
That changed the economics of holding gold.
Unlike Treasury securities or bank deposits, gold doesn't pay interest.
When investors can earn attractive returns on interest-bearing assets, the opportunity cost of holding gold increases.
At the same time, higher real interest rates and a stronger U.S. dollar can reduce demand for bullion.
Gold didn't suddenly become useless.
The financial conditions that had supported its extraordinary valuation were changing.
NOW LOOK AT THE 2026 MARKET.
Gold is facing another difficult combination.
The metal reached a record high of approximately $5,595 per ounce in January.
By November 16, it had fallen to approximately $3,831.
That's a decline of around 31.5%.
And several developments are putting pressure on the market.
1. THE U.S. DOLLAR IS GETTING STRONGER
Gold is priced internationally in U.S. dollars.
When the dollar strengthens, gold becomes more expensive for buyers using other currencies.
That can reduce international demand and put downward pressure on prices.
2. TREASURY YIELDS ARE RISING
The 10-year U.S. Treasury yield recently reached approximately 5.14%.
Higher yields make interest-bearing investments more competitive with gold.
For institutional investors managing enormous portfolios, that opportunity cost matters.
3. INFLATION IS CREATING A POLICY PROBLEM
Geopolitical tensions and higher oil prices can increase inflationary pressure.
But here's the contradiction:
Inflation fears can initially increase demand for gold.
If those same inflation pressures force the Federal Reserve to maintain restrictive policy or raise interest rates, gold can subsequently face selling pressure.
That's the mechanism investors need to understand.
4. THE FED'S NEXT MOVE COULD MATTER MORE THAN THE HEADLINES
Markets are currently anticipating a possible 25-basis-point rate increase in December.
But expectations are not the same as an actual Federal Reserve decision.
If inflation remains persistent and the Fed becomes more aggressive, gold could face additional pressure.
If economic growth weakens or rate expectations reverse, the picture could change again.
HERE'S MY BIGGEST TAKEAWAY FROM THE 1979 COMPARISON.
Gold is not automatically bullish during every war.
And it doesn't automatically collapse when geopolitical tensions ease.
The bigger drivers are often the relationship between inflation, real interest rates, the U.S. dollar, central-bank policy and investor demand.
There is also an important difference between 1980 and 2026.
Today's gold market has substantial central-bank participation, investment funds and different global reserve dynamics.
History can explain the risks, but it cannot guarantee that the same outcome will repeat.
A 50% historical decline is a warning about volatility, not a prediction of the next move.
The real question isn't simply whether gold is expensive or cheap. It's whether the financial conditions supporting its price are getting stronger or weaker.
That's what serious gold investors should be watching.
568
Article
BULLSH*t: Nearly $270 Million Exited Bitcoin and Ethereum ETFs. But What Does That Actually Mean?😡BULLSH*t: Nearly $270 Million Exited Bitcoin and Ethereum ETFs. But What Does That Actually Mean?
Most people see ETF outflows and immediately assume that major institutions are dumping crypto.
The reality is more interesting.
On November 17, U.S. spot Bitcoin ETFs recorded $239.94 million in net outflows, while Ethereum ETFs saw another $29.09 million leave.
That's a combined $269.03 million in net withdrawals.
But here's the financial mechanism worth understanding.
An ETF is an investment vehicle, not a permanent buyer of an asset.
When investors purchase shares of a spot Bitcoin ETF, the fund structure allows exposure to Bitcoin without requiring those investors to manage cryptocurrency wallets themselves.
When investors redeem their ETF shares, the fund may need to reduce its underlying holdings to meet those redemptions, depending on how the fund processes them.
This creates an important connection between traditional financial markets and crypto markets.
Here's the part that deserves attention:
BlackRock's IBIT alone recorded approximately $209.54 million in net outflows.
That represented roughly 87% of the total Bitcoin ETF withdrawals that day.
But it doesn't mean BlackRock's management suddenly made a decision to abandon Bitcoin.
Investors in the fund can change their positions, and those transactions show up in the fund's daily flow data.
There is another distinction investors should understand:
Net outflows are not the same as trading volume.
Trading volume measures how much ETF activity took place.
Net flows measure the difference between money entering and leaving the funds.
A fund can trade billions of dollars in a day while experiencing relatively small net inflows or outflows.
Why does this matter?
Because spot ETFs have created a measurable channel through which traditional investors can increase or reduce crypto exposure.
Watching these flows helps investors understand demand through that channel.
But one day's withdrawals cannot tell us whether Bitcoin has reached a market top, whether institutions have permanently changed their outlook, or where prices will go next.
I'd rather watch several consecutive sessions and compare the flows with actual market demand before drawing a bigger conclusion.
In modern crypto markets, understanding where capital moves is just as important as watching where prices move.
BULLSH*t: Nearly $270 Million Exited Bitcoin and Ethereum ETFs. But What Does That Actually Mean?
😡BULLSH*t: Nearly $270 Million Exited Bitcoin and Ethereum ETFs. But What Does That Actually Mean?
Most people see ETF outflows and immediately assume that major institutions are dumping crypto.
The reality is more interesting.
On November 17, U.S. spot Bitcoin ETFs recorded $239.94 million in net outflows, while Ethereum ETFs saw another $29.09 million leave.
That's a combined $269.03 million in net withdrawals.
But here's the financial mechanism worth understanding.
An ETF is an investment vehicle, not a permanent buyer of an asset.
When investors purchase shares of a spot Bitcoin ETF, the fund structure allows exposure to Bitcoin without requiring those investors to manage cryptocurrency wallets themselves.
When investors redeem their ETF shares, the fund may need to reduce its underlying holdings to meet those redemptions, depending on how the fund processes them.
This creates an important connection between traditional financial markets and crypto markets.
Here's the part that deserves attention:
BlackRock's IBIT alone recorded approximately $209.54 million in net outflows.
That represented roughly 87% of the total Bitcoin ETF withdrawals that day.
But it doesn't mean BlackRock's management suddenly made a decision to abandon Bitcoin.
Investors in the fund can change their positions, and those transactions show up in the fund's daily flow data.
There is another distinction investors should understand:
Net outflows are not the same as trading volume.
Trading volume measures how much ETF activity took place.
Net flows measure the difference between money entering and leaving the funds.
A fund can trade billions of dollars in a day while experiencing relatively small net inflows or outflows.
Why does this matter?
Because spot ETFs have created a measurable channel through which traditional investors can increase or reduce crypto exposure.
Watching these flows helps investors understand demand through that channel.
But one day's withdrawals cannot tell us whether Bitcoin has reached a market top, whether institutions have permanently changed their outlook, or where prices will go next.
I'd rather watch several consecutive sessions and compare the flows with actual market demand before drawing a bigger conclusion.
In modern crypto markets, understanding where capital moves is just as important as watching where prices move.
Most people see ETF outflows and immediately assume that major institutions are dumping crypto.
The reality is more interesting.
On November 17, U.S. spot Bitcoin ETFs recorded $239.94 million in net outflows, while Ethereum ETFs saw another $29.09 million leave.
That's a combined $269.03 million in net withdrawals.
But here's the financial mechanism worth understanding.
An ETF is an investment vehicle, not a permanent buyer of an asset.
When investors purchase shares of a spot Bitcoin ETF, the fund structure allows exposure to Bitcoin without requiring those investors to manage cryptocurrency wallets themselves.
When investors redeem their ETF shares, the fund may need to reduce its underlying holdings to meet those redemptions, depending on how the fund processes them.
This creates an important connection between traditional financial markets and crypto markets.
Here's the part that deserves attention:
BlackRock's IBIT alone recorded approximately $209.54 million in net outflows.
That represented roughly 87% of the total Bitcoin ETF withdrawals that day.
But it doesn't mean BlackRock's management suddenly made a decision to abandon Bitcoin.
Investors in the fund can change their positions, and those transactions show up in the fund's daily flow data.
There is another distinction investors should understand:
Net outflows are not the same as trading volume.
Trading volume measures how much ETF activity took place.
Net flows measure the difference between money entering and leaving the funds.
A fund can trade billions of dollars in a day while experiencing relatively small net inflows or outflows.
Why does this matter?
Because spot ETFs have created a measurable channel through which traditional investors can increase or reduce crypto exposure.
Watching these flows helps investors understand demand through that channel.
But one day's withdrawals cannot tell us whether Bitcoin has reached a market top, whether institutions have permanently changed their outlook, or where prices will go next.
I'd rather watch several consecutive sessions and compare the flows with actual market demand before drawing a bigger conclusion.
In modern crypto markets, understanding where capital moves is just as important as watching where prices move.
294
Article
Does Every High-Income Family Actually Need a Financial Advisor?
I think this is a question worth aI think this is a question worth asking, especially for households earning $150,000 or more.
A higher income doesn't automatically mean better financial decisions.
And paying someone to manage your money doesn't automatically mean you're getting more value.
Here's what many families should understand before hiring an advisor:
1. Know exactly what you're paying.
An advisory fee of 1% may not sound significant.
But on a $500,000 portfolio, that's $5,000 every year.
Over 20 years, even before considering investment growth, that's $100,000 in fees if the balance and fee remain unchanged.
The actual lifetime cost can be considerably different as the portfolio grows or shrinks.
2. Understand what you're receiving in return.
Are you getting tax-efficient investment planning?
Retirement projections?
Estate planning coordination?
Help managing risk during market downturns?
Or are you mainly paying someone to select a collection of ETFs?
Those services are not equally valuable, and the difference matters.
3. Know what you can manage yourself.
For someone with a straightforward financial situation, managing a diversified portfolio, monitoring expenses, and maintaining a retirement contribution strategy may be manageable.
But complicated taxes, business ownership, estate issues, and major financial decisions can justify professional advice.
4. Don't confuse saving on fees with making better decisions.
An advisor's value isn't measured only by whether they beat the market.
Sometimes the biggest benefit is preventing costly emotional decisions, keeping a financial plan on track, or identifying tax mistakes.
The important thing is to know whether those benefits justify what you're paying.
My view is simple: people should understand their own financial system even when they hire someone else to manage part of it.
You don't need to become a professional portfolio manager.
But you should know where your money is invested, what you're paying, and why each decision is being made.
One question worth considering:
If your family earns $150,000 a year, would you prefer to manage a simple investment portfolio yourself, or pay a professional for ongoing financial guidance?
The answer may depend more on your financial complexity than your income.
Does Every High-Income Family Actually Need a Financial Advisor? I think this is a question worth a
I think this is a question worth asking, especially for households earning $150,000 or more.
A higher income doesn't automatically mean better financial decisions.
And paying someone to manage your money doesn't automatically mean you're getting more value.
Here's what many families should understand before hiring an advisor:
1. Know exactly what you're paying.
An advisory fee of 1% may not sound significant.
But on a $500,000 portfolio, that's $5,000 every year.
Over 20 years, even before considering investment growth, that's $100,000 in fees if the balance and fee remain unchanged.
The actual lifetime cost can be considerably different as the portfolio grows or shrinks.
2. Understand what you're receiving in return.
Are you getting tax-efficient investment planning?
Retirement projections?
Estate planning coordination?
Help managing risk during market downturns?
Or are you mainly paying someone to select a collection of ETFs?
Those services are not equally valuable, and the difference matters.
3. Know what you can manage yourself.
For someone with a straightforward financial situation, managing a diversified portfolio, monitoring expenses, and maintaining a retirement contribution strategy may be manageable.
But complicated taxes, business ownership, estate issues, and major financial decisions can justify professional advice.
4. Don't confuse saving on fees with making better decisions.
An advisor's value isn't measured only by whether they beat the market.
Sometimes the biggest benefit is preventing costly emotional decisions, keeping a financial plan on track, or identifying tax mistakes.
The important thing is to know whether those benefits justify what you're paying.
My view is simple: people should understand their own financial system even when they hire someone else to manage part of it.
You don't need to become a professional portfolio manager.
But you should know where your money is invested, what you're paying, and why each decision is being made.
One question worth considering:
If your family earns $150,000 a year, would you prefer to manage a simple investment portfolio yourself, or pay a professional for ongoing financial guidance?
The answer may depend more on your financial complexity than your income.
A higher income doesn't automatically mean better financial decisions.
And paying someone to manage your money doesn't automatically mean you're getting more value.
Here's what many families should understand before hiring an advisor:
1. Know exactly what you're paying.
An advisory fee of 1% may not sound significant.
But on a $500,000 portfolio, that's $5,000 every year.
Over 20 years, even before considering investment growth, that's $100,000 in fees if the balance and fee remain unchanged.
The actual lifetime cost can be considerably different as the portfolio grows or shrinks.
2. Understand what you're receiving in return.
Are you getting tax-efficient investment planning?
Retirement projections?
Estate planning coordination?
Help managing risk during market downturns?
Or are you mainly paying someone to select a collection of ETFs?
Those services are not equally valuable, and the difference matters.
3. Know what you can manage yourself.
For someone with a straightforward financial situation, managing a diversified portfolio, monitoring expenses, and maintaining a retirement contribution strategy may be manageable.
But complicated taxes, business ownership, estate issues, and major financial decisions can justify professional advice.
4. Don't confuse saving on fees with making better decisions.
An advisor's value isn't measured only by whether they beat the market.
Sometimes the biggest benefit is preventing costly emotional decisions, keeping a financial plan on track, or identifying tax mistakes.
The important thing is to know whether those benefits justify what you're paying.
My view is simple: people should understand their own financial system even when they hire someone else to manage part of it.
You don't need to become a professional portfolio manager.
But you should know where your money is invested, what you're paying, and why each decision is being made.
One question worth considering:
If your family earns $150,000 a year, would you prefer to manage a simple investment portfolio yourself, or pay a professional for ongoing financial guidance?
The answer may depend more on your financial complexity than your income.
254
Article
MORE THAN $1.16 BILLION IN BITCOIN: EARLY HOLDERS ARE DRAWING MARKET ATTENTION.MORE THAN $1.16 BILLION IN BITCOIN: EARLY HOLDERS ARE DRAWING MARKET ATTENTION.
Bitcoin is facing another development that deserves attention, particularly because it involves coins associated with its earliest years.
A Satoshi-era Bitcoin holder has reportedly moved or sold approximately $601.1 million worth of BTC after holding for around 16 years.
This follows another reported $565 million movement in recent days, bringing the combined reported value to approximately $1.166 billion.
But there is an important distinction that many people misunderstand.
WHAT DOES SATOSHI-ERA ACTUALLY MEAN?
Satoshi-era does not mean Satoshi Nakamoto personally sold Bitcoin.
It is a term used for Bitcoin from the network's earliest years, particularly the period when Satoshi Nakamoto was still involved in the project.
The term is commonly associated with early miners and long-term holders who accumulated Bitcoin when the network was still relatively small.
These holders are sometimes called Satoshi-era whales because of the age and size of their holdings.
Their identities are not necessarily known, and they should not automatically be treated as one individual or a single group.
WHY DOES THIS MATTER FOR BITCOIN?
When coins that have remained untouched for approximately 16 years suddenly become active, the market naturally pays attention.
These are not ordinary short-term trades.
Early holders may have accumulated their Bitcoin when mining rewards were 50 BTC per block and the network had very little mainstream attention.
If large amounts of these holdings eventually reach exchanges and are sold, they can introduce additional supply into the market.
That could increase selling pressure, particularly when demand is already weak.
THE MARKET RISK IS NOT JUST THE AMOUNT
There is another factor worth watching.
When early Bitcoin holders begin moving substantial amounts of their long-dormant supply, investors may start questioning whether other early holders are also considering taking profits.
That uncertainty can affect market sentiment even before any actual selling takes place.
However, an on-chain transfer alone does not confirm that Bitcoin has been sold.
The destination wallets, exchange deposits, and subsequent transactions matter when determining whether a genuine liquidation has occurred.
WHAT I WOULD WATCH NEXT
The important question is whether these coins remain in private wallets or eventually move toward exchanges.
If confirmed selling continues while market demand remains weak, Bitcoin could face additional downside pressure.
If the transactions are simply wallet reorganizations or custody transfers, the actual market impact could be much smaller.
For me, the bigger concern is not simply that old Bitcoin is moving.
It is whether a meaningful amount of previously inactive supply is preparing to return to the market.
Could early Bitcoin holders taking profits become another source of selling pressure during an already weak market?
That is the development worth watching, not just the headline number.
MORE THAN $1.16 BILLION IN BITCOIN: EARLY HOLDERS ARE DRAWING MARKET ATTENTION.
MORE THAN $1.16 BILLION IN BITCOIN: EARLY HOLDERS ARE DRAWING MARKET ATTENTION.
Bitcoin is facing another development that deserves attention, particularly because it involves coins associated with its earliest years.
A Satoshi-era Bitcoin holder has reportedly moved or sold approximately $601.1 million worth of BTC after holding for around 16 years.
This follows another reported $565 million movement in recent days, bringing the combined reported value to approximately $1.166 billion.
But there is an important distinction that many people misunderstand.
WHAT DOES SATOSHI-ERA ACTUALLY MEAN?
Satoshi-era does not mean Satoshi Nakamoto personally sold Bitcoin.
It is a term used for Bitcoin from the network's earliest years, particularly the period when Satoshi Nakamoto was still involved in the project.
The term is commonly associated with early miners and long-term holders who accumulated Bitcoin when the network was still relatively small.
These holders are sometimes called Satoshi-era whales because of the age and size of their holdings.
Their identities are not necessarily known, and they should not automatically be treated as one individual or a single group.
WHY DOES THIS MATTER FOR BITCOIN?
When coins that have remained untouched for approximately 16 years suddenly become active, the market naturally pays attention.
These are not ordinary short-term trades.
Early holders may have accumulated their Bitcoin when mining rewards were 50 BTC per block and the network had very little mainstream attention.
If large amounts of these holdings eventually reach exchanges and are sold, they can introduce additional supply into the market.
That could increase selling pressure, particularly when demand is already weak.
THE MARKET RISK IS NOT JUST THE AMOUNT
There is another factor worth watching.
When early Bitcoin holders begin moving substantial amounts of their long-dormant supply, investors may start questioning whether other early holders are also considering taking profits.
That uncertainty can affect market sentiment even before any actual selling takes place.
However, an on-chain transfer alone does not confirm that Bitcoin has been sold.
The destination wallets, exchange deposits, and subsequent transactions matter when determining whether a genuine liquidation has occurred.
WHAT I WOULD WATCH NEXT
The important question is whether these coins remain in private wallets or eventually move toward exchanges.
If confirmed selling continues while market demand remains weak, Bitcoin could face additional downside pressure.
If the transactions are simply wallet reorganizations or custody transfers, the actual market impact could be much smaller.
For me, the bigger concern is not simply that old Bitcoin is moving.
It is whether a meaningful amount of previously inactive supply is preparing to return to the market.
Could early Bitcoin holders taking profits become another source of selling pressure during an already weak market?
That is the development worth watching, not just the headline number.
Bitcoin is facing another development that deserves attention, particularly because it involves coins associated with its earliest years.
A Satoshi-era Bitcoin holder has reportedly moved or sold approximately $601.1 million worth of BTC after holding for around 16 years.
This follows another reported $565 million movement in recent days, bringing the combined reported value to approximately $1.166 billion.
But there is an important distinction that many people misunderstand.
WHAT DOES SATOSHI-ERA ACTUALLY MEAN?
Satoshi-era does not mean Satoshi Nakamoto personally sold Bitcoin.
It is a term used for Bitcoin from the network's earliest years, particularly the period when Satoshi Nakamoto was still involved in the project.
The term is commonly associated with early miners and long-term holders who accumulated Bitcoin when the network was still relatively small.
These holders are sometimes called Satoshi-era whales because of the age and size of their holdings.
Their identities are not necessarily known, and they should not automatically be treated as one individual or a single group.
WHY DOES THIS MATTER FOR BITCOIN?
When coins that have remained untouched for approximately 16 years suddenly become active, the market naturally pays attention.
These are not ordinary short-term trades.
Early holders may have accumulated their Bitcoin when mining rewards were 50 BTC per block and the network had very little mainstream attention.
If large amounts of these holdings eventually reach exchanges and are sold, they can introduce additional supply into the market.
That could increase selling pressure, particularly when demand is already weak.
THE MARKET RISK IS NOT JUST THE AMOUNT
There is another factor worth watching.
When early Bitcoin holders begin moving substantial amounts of their long-dormant supply, investors may start questioning whether other early holders are also considering taking profits.
That uncertainty can affect market sentiment even before any actual selling takes place.
However, an on-chain transfer alone does not confirm that Bitcoin has been sold.
The destination wallets, exchange deposits, and subsequent transactions matter when determining whether a genuine liquidation has occurred.
WHAT I WOULD WATCH NEXT
The important question is whether these coins remain in private wallets or eventually move toward exchanges.
If confirmed selling continues while market demand remains weak, Bitcoin could face additional downside pressure.
If the transactions are simply wallet reorganizations or custody transfers, the actual market impact could be much smaller.
For me, the bigger concern is not simply that old Bitcoin is moving.
It is whether a meaningful amount of previously inactive supply is preparing to return to the market.
Could early Bitcoin holders taking profits become another source of selling pressure during an already weak market?
That is the development worth watching, not just the headline number.
161
𝗕𝗥𝗘𝗔𝗞𝗜𝗡𝗚🇺🇸SpaceX Starship Makes Historic First Catch After 22-Hour Orbital Flight
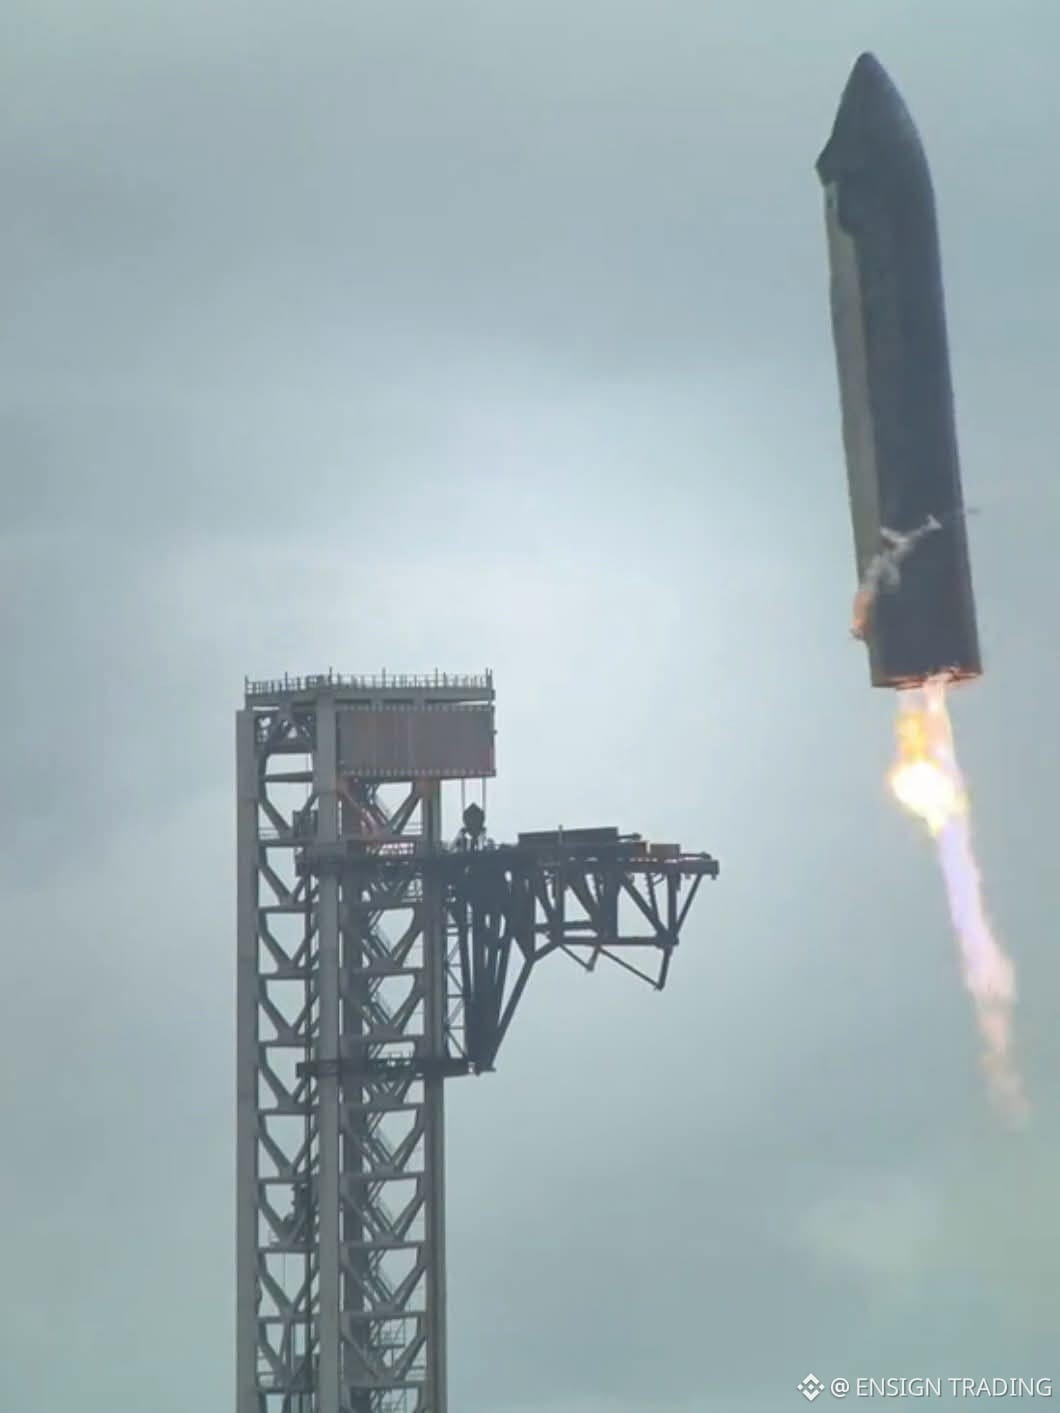
SpaceX has successfully caught a Starship upper stage with the giant mechanical arms of its launch tower for the first time in history, completing a more than 22-hour orbital mission on Flight 15.
The Starship completed 14 orbits around Earth and deployed 26 Starlink satellites before returning to Starbase in Texas. During the final descent, the spacecraft reignited its engines, flipped upright and was guided between the tower’s mechanical “chopstick” arms, which successfully captured the vehicle.
The Super Heavy booster, however, failed to complete its planned return. Its engines shut down earlier than expected during the recovery attempt, forcing the guidance system to divert the booster toward the Gulf of Mexico, where it was destroyed after splashdown.
Despite the booster recovery failure, the successful orbital return and tower catch mark a major step toward SpaceX’s goal of developing a fully reusable launch system.
𝗕𝗥𝗘𝗔𝗞𝗜𝗡𝗚🇺🇸SpaceX Starship Makes Historic First Catch After 22-Hour Orbital Flight
SpaceX has successfully caught a Starship upper stage with the giant mechanical arms of its launch tower for the first time in history, completing a more than 22-hour orbital mission on Flight 15.
The Starship completed 14 orbits around Earth and deployed 26 Starlink satellites before returning to Starbase in Texas. During the final descent, the spacecraft reignited its engines, flipped upright and was guided between the tower’s mechanical “chopstick” arms, which successfully captured the vehicle.
The Super Heavy booster, however, failed to complete its planned return. Its engines shut down earlier than expected during the recovery attempt, forcing the guidance system to divert the booster toward the Gulf of Mexico, where it was destroyed after splashdown.
Despite the booster recovery failure, the successful orbital return and tower catch mark a major step toward SpaceX’s goal of developing a fully reusable launch system.
SpaceX has successfully caught a Starship upper stage with the giant mechanical arms of its launch tower for the first time in history, completing a more than 22-hour orbital mission on Flight 15.
The Starship completed 14 orbits around Earth and deployed 26 Starlink satellites before returning to Starbase in Texas. During the final descent, the spacecraft reignited its engines, flipped upright and was guided between the tower’s mechanical “chopstick” arms, which successfully captured the vehicle.
The Super Heavy booster, however, failed to complete its planned return. Its engines shut down earlier than expected during the recovery attempt, forcing the guidance system to divert the booster toward the Gulf of Mexico, where it was destroyed after splashdown.
Despite the booster recovery failure, the successful orbital return and tower catch mark a major step toward SpaceX’s goal of developing a fully reusable launch system.
1
2
591
A $7 billion paper loss is a serious reminder of what happens when a company builds its balance sheet around one volatile asset.
Michael Saylor’s Strategy holds approximately 850,364 Bitcoin.
The company paid around $64.16 billion for those holdings.
That puts its average purchase price near $75,456 per Bitcoin.
When BTC fell below $67,000, the value of its holdings dropped roughly $7.2 billion below what it paid.
But there is an important distinction here.
Strategy has not necessarily lost that money in cash because it has not sold the entire position at those prices.
If Bitcoin recovers, the unrealized loss can shrink.
If prices fall further, the gap can become even larger.
And this is where the bigger financial question comes in.
How much risk should a publicly traded company take when so much of its financial strategy depends on one asset?
For investors, the lesson isn't simply that Bitcoin can fall.
It's that even a large corporate treasury can experience enormous volatility when it concentrates so heavily in one investment.
Conviction matters, but risk management matters too.
A $7 billion paper loss is a serious reminder of what happens when a company builds its balance sheet around one volatile asset.
Michael Saylor’s Strategy holds approximately 850,364 Bitcoin.
The company paid around $64.16 billion for those holdings.
That puts its average purchase price near $75,456 per Bitcoin.
When BTC fell below $67,000, the value of its holdings dropped roughly $7.2 billion below what it paid.
But there is an important distinction here.
Strategy has not necessarily lost that money in cash because it has not sold the entire position at those prices.
If Bitcoin recovers, the unrealized loss can shrink.
If prices fall further, the gap can become even larger.
And this is where the bigger financial question comes in.
How much risk should a publicly traded company take when so much of its financial strategy depends on one asset?
For investors, the lesson isn't simply that Bitcoin can fall.
It's that even a large corporate treasury can experience enormous volatility when it concentrates so heavily in one investment.
Conviction matters, but risk management matters too.
Michael Saylor’s Strategy holds approximately 850,364 Bitcoin.
The company paid around $64.16 billion for those holdings.
That puts its average purchase price near $75,456 per Bitcoin.
When BTC fell below $67,000, the value of its holdings dropped roughly $7.2 billion below what it paid.
But there is an important distinction here.
Strategy has not necessarily lost that money in cash because it has not sold the entire position at those prices.
If Bitcoin recovers, the unrealized loss can shrink.
If prices fall further, the gap can become even larger.
And this is where the bigger financial question comes in.
How much risk should a publicly traded company take when so much of its financial strategy depends on one asset?
For investors, the lesson isn't simply that Bitcoin can fall.
It's that even a large corporate treasury can experience enormous volatility when it concentrates so heavily in one investment.
Conviction matters, but risk management matters too.
1
1k
Article
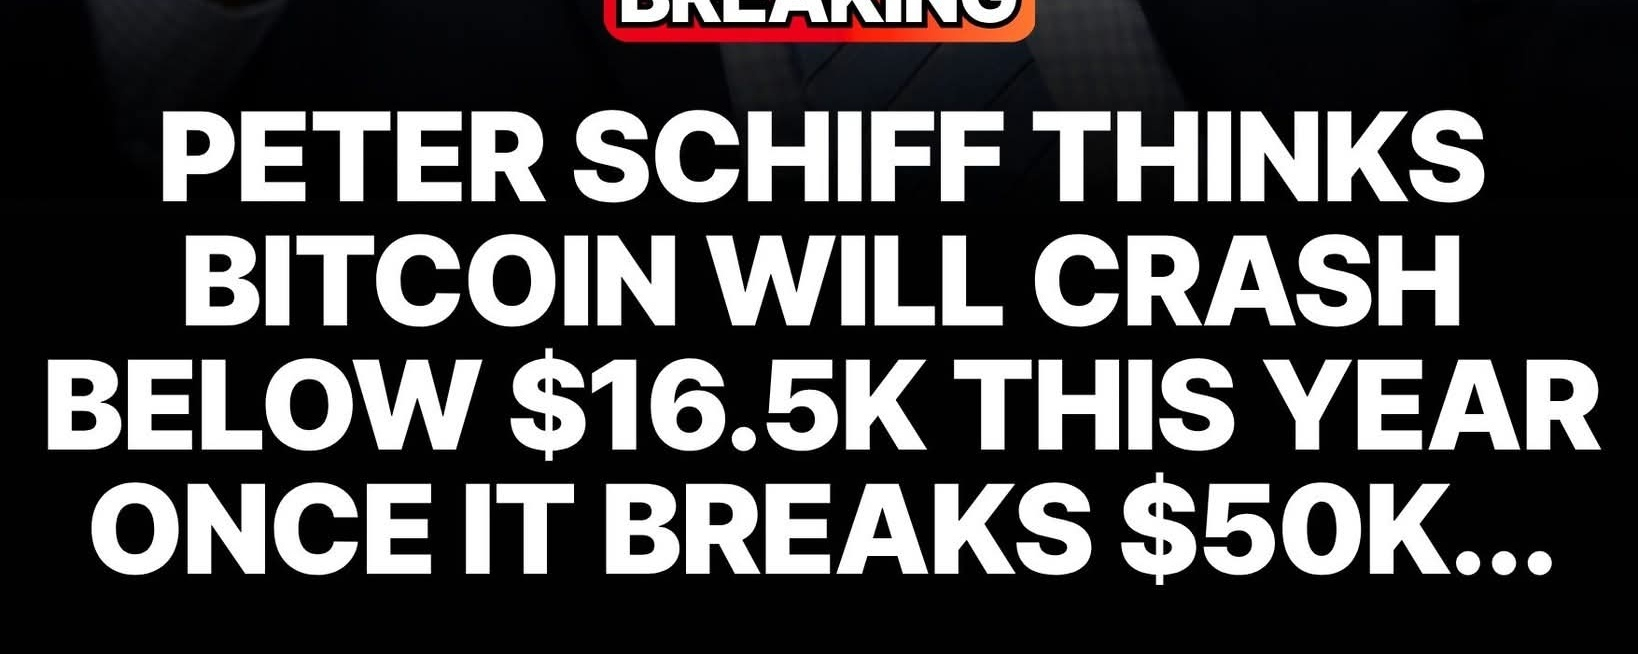
Peter Schiff Sees Bitcoin Below $16,500 If $50K Support Breaks!Peter Schiff Sees Bitcoin Below $16,500 If $50K Support Breaks!
Bitcoin is facing another serious warning from one of its longest-standing critics.
Economist Peter Schiff believes the cryptocurrency could experience a much deeper decline if it loses the $50,000 price level.
His latest prediction is particularly striking because he expects Bitcoin to potentially revisit its 2022 bear-market low of below $16,500 before the end of 2026.
But the bigger concern goes beyond Bitcoin itself.
Why Is $50,000 Such an Important Level?
Schiff argues that a breakdown below $50,000 could accelerate selling pressure.
At the time of reporting on November 14, Bitcoin was trading around $67,200.
That means:
- A decline to $50,000 would represent approximately 25.6% downside.
- A further decline from $50,000 to $16,500 would mean another 67% loss.
- From $67,200 to $16,500, the total decline would be approximately 75.4%.
These are substantial moves, not ordinary daily market fluctuations.
However, this is Schiff's bearish scenario, not a confirmed market forecast.
He has not provided a probability or a detailed valuation model explaining why Bitcoin must reach that target.
The Bigger Risk: Strategy's Massive Bitcoin Holdings
One company particularly exposed to this scenario is Strategy (MSTR).
According to its November 9 disclosure, the company held 850,364 Bitcoin as of November 8.
Its total acquisition cost was approximately $64.16 billion, giving it an average purchase price of $75,456 per Bitcoin.
Consider what happens under Schiff's hypothetical price scenarios.
If Bitcoin reaches $50,000, those holdings would be worth approximately $42.52 billion.
If Bitcoin falls to $16,500, their value would decline to approximately $14.03 billion.
That would put the Bitcoin holdings roughly $50.13 billion below their reported acquisition cost.
These calculations assume the company keeps the same Bitcoin holdings and exclude its other assets, liabilities, and financing arrangements.
A large unrealized loss does not automatically mean a company becomes insolvent.
But a prolonged decline could create serious pressure on investor confidence, financing options, and its ability to raise additional capital.
Why Ordinary Bitcoin Investors Should Pay Attention
There is another side to this story that directly affects individual investors.
Imagine someone purchased Bitcoin at $80,000 using money they might need within the next year.
If the price falls to $50,000, that investment loses 37.5% of its value.
At $16,500, the decline would reach approximately 79.4%.
For someone using borrowed money or leveraged trading, the consequences could be even more severe because exchanges may forcibly liquidate positions before the market reaches its lowest point.
This is why the difference between investing with available savings and investing with borrowed money matters so much during volatile markets.
Not Everyone Agrees With Schiff
Some market analysts have identified the $68,000 region as a potential buying area, while others are watching important long-term technical support levels.
That creates two very different possibilities.
If buyers return and selling pressure weakens, Bitcoin could attempt to recover.
But if major support levels fail alongside continued institutional withdrawals and weak market demand, further downside becomes a risk.
Neither scenario is guaranteed.
The Question Investors Should Be Asking
Is Bitcoin experiencing a temporary correction, or is the market entering a much deeper phase of declining demand?
Schiff has made his position clear.
But the real test will come from actual buying demand, institutional capital flows, market liquidity, and how Bitcoin responds to major support levels.
A price prediction can attract attention.
The financial consequences behind it deserve much closer attention.
Market levels matter, but risk management matters more.
Peter Schiff Sees Bitcoin Below $16,500 If $50K Support Breaks!
Peter Schiff Sees Bitcoin Below $16,500 If $50K Support Breaks!
Bitcoin is facing another serious warning from one of its longest-standing critics.
Economist Peter Schiff believes the cryptocurrency could experience a much deeper decline if it loses the $50,000 price level.
His latest prediction is particularly striking because he expects Bitcoin to potentially revisit its 2022 bear-market low of below $16,500 before the end of 2026.
But the bigger concern goes beyond Bitcoin itself.
Why Is $50,000 Such an Important Level?
Schiff argues that a breakdown below $50,000 could accelerate selling pressure.
At the time of reporting on November 14, Bitcoin was trading around $67,200.
That means:
- A decline to $50,000 would represent approximately 25.6% downside.
- A further decline from $50,000 to $16,500 would mean another 67% loss.
- From $67,200 to $16,500, the total decline would be approximately 75.4%.
These are substantial moves, not ordinary daily market fluctuations.
However, this is Schiff's bearish scenario, not a confirmed market forecast.
He has not provided a probability or a detailed valuation model explaining why Bitcoin must reach that target.
The Bigger Risk: Strategy's Massive Bitcoin Holdings
One company particularly exposed to this scenario is Strategy (MSTR).
According to its November 9 disclosure, the company held 850,364 Bitcoin as of November 8.
Its total acquisition cost was approximately $64.16 billion, giving it an average purchase price of $75,456 per Bitcoin.
Consider what happens under Schiff's hypothetical price scenarios.
If Bitcoin reaches $50,000, those holdings would be worth approximately $42.52 billion.
If Bitcoin falls to $16,500, their value would decline to approximately $14.03 billion.
That would put the Bitcoin holdings roughly $50.13 billion below their reported acquisition cost.
These calculations assume the company keeps the same Bitcoin holdings and exclude its other assets, liabilities, and financing arrangements.
A large unrealized loss does not automatically mean a company becomes insolvent.
But a prolonged decline could create serious pressure on investor confidence, financing options, and its ability to raise additional capital.
Why Ordinary Bitcoin Investors Should Pay Attention
There is another side to this story that directly affects individual investors.
Imagine someone purchased Bitcoin at $80,000 using money they might need within the next year.
If the price falls to $50,000, that investment loses 37.5% of its value.
At $16,500, the decline would reach approximately 79.4%.
For someone using borrowed money or leveraged trading, the consequences could be even more severe because exchanges may forcibly liquidate positions before the market reaches its lowest point.
This is why the difference between investing with available savings and investing with borrowed money matters so much during volatile markets.
Not Everyone Agrees With Schiff
Some market analysts have identified the $68,000 region as a potential buying area, while others are watching important long-term technical support levels.
That creates two very different possibilities.
If buyers return and selling pressure weakens, Bitcoin could attempt to recover.
But if major support levels fail alongside continued institutional withdrawals and weak market demand, further downside becomes a risk.
Neither scenario is guaranteed.
The Question Investors Should Be Asking
Is Bitcoin experiencing a temporary correction, or is the market entering a much deeper phase of declining demand?
Schiff has made his position clear.
But the real test will come from actual buying demand, institutional capital flows, market liquidity, and how Bitcoin responds to major support levels.
A price prediction can attract attention.
The financial consequences behind it deserve much closer attention.
Market levels matter, but risk management matters more.
Bitcoin is facing another serious warning from one of its longest-standing critics.
Economist Peter Schiff believes the cryptocurrency could experience a much deeper decline if it loses the $50,000 price level.
His latest prediction is particularly striking because he expects Bitcoin to potentially revisit its 2022 bear-market low of below $16,500 before the end of 2026.
But the bigger concern goes beyond Bitcoin itself.
Why Is $50,000 Such an Important Level?
Schiff argues that a breakdown below $50,000 could accelerate selling pressure.
At the time of reporting on November 14, Bitcoin was trading around $67,200.
That means:
- A decline to $50,000 would represent approximately 25.6% downside.
- A further decline from $50,000 to $16,500 would mean another 67% loss.
- From $67,200 to $16,500, the total decline would be approximately 75.4%.
These are substantial moves, not ordinary daily market fluctuations.
However, this is Schiff's bearish scenario, not a confirmed market forecast.
He has not provided a probability or a detailed valuation model explaining why Bitcoin must reach that target.
The Bigger Risk: Strategy's Massive Bitcoin Holdings
One company particularly exposed to this scenario is Strategy (MSTR).
According to its November 9 disclosure, the company held 850,364 Bitcoin as of November 8.
Its total acquisition cost was approximately $64.16 billion, giving it an average purchase price of $75,456 per Bitcoin.
Consider what happens under Schiff's hypothetical price scenarios.
If Bitcoin reaches $50,000, those holdings would be worth approximately $42.52 billion.
If Bitcoin falls to $16,500, their value would decline to approximately $14.03 billion.
That would put the Bitcoin holdings roughly $50.13 billion below their reported acquisition cost.
These calculations assume the company keeps the same Bitcoin holdings and exclude its other assets, liabilities, and financing arrangements.
A large unrealized loss does not automatically mean a company becomes insolvent.
But a prolonged decline could create serious pressure on investor confidence, financing options, and its ability to raise additional capital.
Why Ordinary Bitcoin Investors Should Pay Attention
There is another side to this story that directly affects individual investors.
Imagine someone purchased Bitcoin at $80,000 using money they might need within the next year.
If the price falls to $50,000, that investment loses 37.5% of its value.
At $16,500, the decline would reach approximately 79.4%.
For someone using borrowed money or leveraged trading, the consequences could be even more severe because exchanges may forcibly liquidate positions before the market reaches its lowest point.
This is why the difference between investing with available savings and investing with borrowed money matters so much during volatile markets.
Not Everyone Agrees With Schiff
Some market analysts have identified the $68,000 region as a potential buying area, while others are watching important long-term technical support levels.
That creates two very different possibilities.
If buyers return and selling pressure weakens, Bitcoin could attempt to recover.
But if major support levels fail alongside continued institutional withdrawals and weak market demand, further downside becomes a risk.
Neither scenario is guaranteed.
The Question Investors Should Be Asking
Is Bitcoin experiencing a temporary correction, or is the market entering a much deeper phase of declining demand?
Schiff has made his position clear.
But the real test will come from actual buying demand, institutional capital flows, market liquidity, and how Bitcoin responds to major support levels.
A price prediction can attract attention.
The financial consequences behind it deserve much closer attention.
Market levels matter, but risk management matters more.
1
1
1.2k
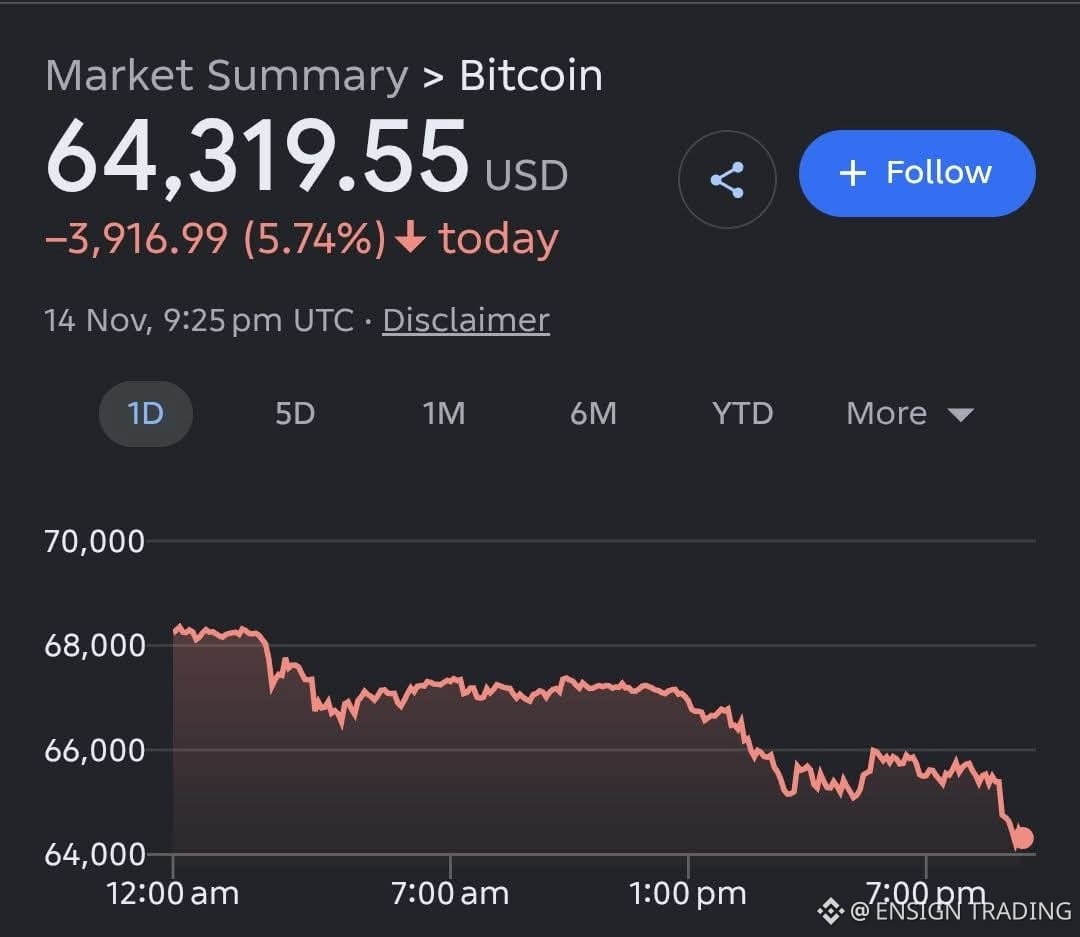
Bitcoin was trading around $96,000 just days ago, but now it's facing a sharp crash.
What do you think is driving this sudden drop?
Is it profit-taking, market uncertainty, liquidations, or something else?
What do you believe is behind Bitcoin's sharp decline?
Bitcoin was trading around $96,000 just days ago, but now it's facing a sharp crash.
What do you think is driving this sudden drop?
Is it profit-taking, market uncertainty, liquidations, or something else?
What do you believe is behind Bitcoin's sharp decline?
What do you think is driving this sudden drop?
Is it profit-taking, market uncertainty, liquidations, or something else?
What do you believe is behind Bitcoin's sharp decline?
1
1
368
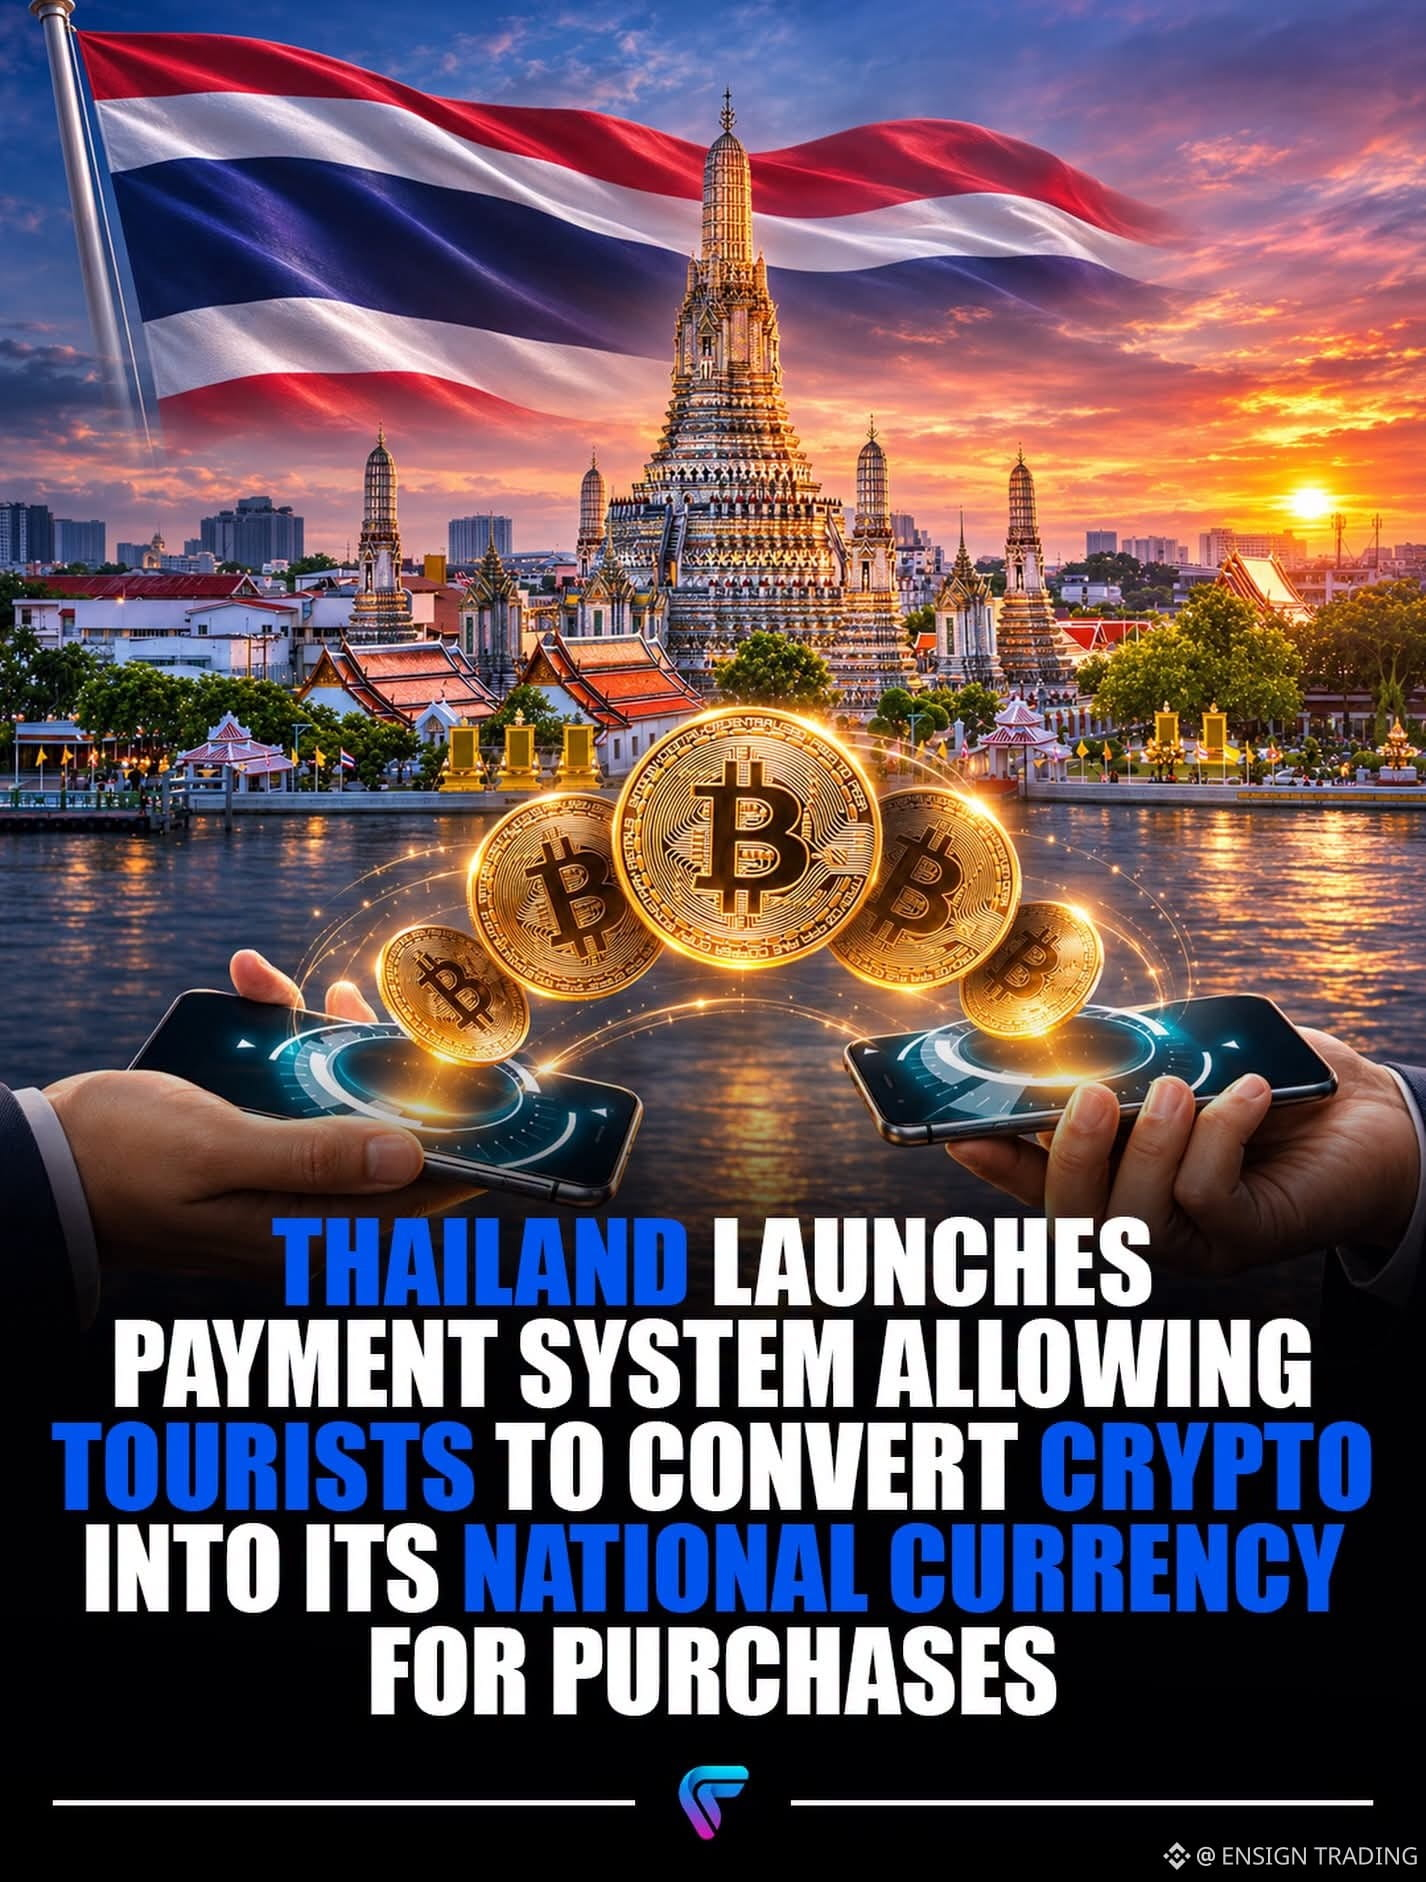
Thailand has officially launched a groundbreaking payment system that allows international tourists to easily convert their cryptocurrency directly into the national currency for everyday purchases.
This innovative initiative aims to boost tourism, modernize the country’s financial infrastructure, and bridge the gap between digital assets and traditional retail spending nationwide.
Thailand has officially launched a groundbreaking payment system that allows international tourists to easily convert their cryptocurrency directly into the national currency for everyday purchases.
This innovative initiative aims to boost tourism, modernize the country’s financial infrastructure, and bridge the gap between digital assets and traditional retail spending nationwide.
This innovative initiative aims to boost tourism, modernize the country’s financial infrastructure, and bridge the gap between digital assets and traditional retail spending nationwide.
81
Elon Musk has 14 children from four different women.
Nobody seems to call it a scandal because he isn't married to any of them.
married and divorced twice.
Jasen had one wife, had two affairs, the whole world is after him
Because Adultery is a Legal sin but Fornication is not 👏
The problem is that once you walk into that registry and sign those court marriage papers, you have locked yourself into a lifelong moral battle.
If you know you're a CEO and you cannot commit to one woman, don't marry.
Or become a Muslim and marry as many wives as your religion permits.
Or embrace my traditional culture, like the Igbo tradition, where I come from, which permits polygamy.
These are your options.
But if you stupidly walk into an American courthouse, sign those marriage papers and make a lifelong commitment you already know you cannot honour, you're on your own.
This advice is coming from...
Elon Musk has 14 children from four different women.
Nobody seems to call it a scandal because he isn't married to any of them.
married and divorced twice.
Jasen had one wife, had two affairs, the whole world is after him
Because Adultery is a Legal sin but Fornication is not 👏
The problem is that once you walk into that registry and sign those court marriage papers, you have locked yourself into a lifelong moral battle.
If you know you're a CEO and you cannot commit to one woman, don't marry.
Or become a Muslim and marry as many wives as your religion permits.
Or embrace my traditional culture, like the Igbo tradition, where I come from, which permits polygamy.
These are your options.
But if you stupidly walk into an American courthouse, sign those marriage papers and make a lifelong commitment you already know you cannot honour, you're on your own.
This advice is coming from...
Nobody seems to call it a scandal because he isn't married to any of them.
married and divorced twice.
Jasen had one wife, had two affairs, the whole world is after him
Because Adultery is a Legal sin but Fornication is not 👏
The problem is that once you walk into that registry and sign those court marriage papers, you have locked yourself into a lifelong moral battle.
If you know you're a CEO and you cannot commit to one woman, don't marry.
Or become a Muslim and marry as many wives as your religion permits.
Or embrace my traditional culture, like the Igbo tradition, where I come from, which permits polygamy.
These are your options.
But if you stupidly walk into an American courthouse, sign those marriage papers and make a lifelong commitment you already know you cannot honour, you're on your own.
This advice is coming from...
2
1
4
1.2k
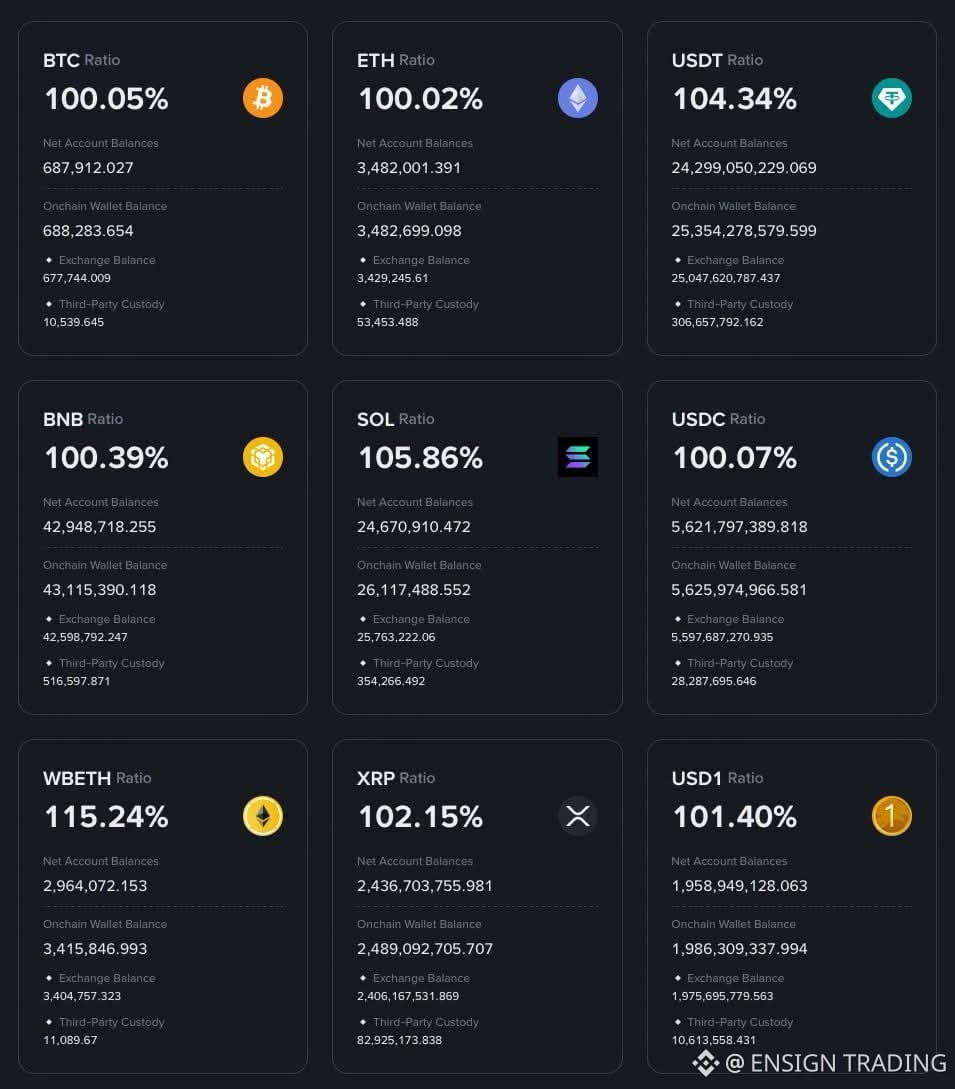
BREAKING: 🚨Binance announces it has now covered 100% of the losses from the $6.3B crypto hack 👏
The exchange says all affected assets have been fully replenished using its own financial resources.
Binance has also published a new Proof of Reserves snapshot, with zero-knowledge verification underway.
BREAKING: 🚨Binance announces it has now covered 100% of the losses from the $6.3B crypto hack 👏
The exchange says all affected assets have been fully replenished using its own financial resources.
Binance has also published a new Proof of Reserves snapshot, with zero-knowledge verification underway.
The exchange says all affected assets have been fully replenished using its own financial resources.
Binance has also published a new Proof of Reserves snapshot, with zero-knowledge verification underway.
58
He Had Only $8 To Pay.
A Young McDonald's Employee
Gave Him Something Money Can't Buy.
Sometimes, the most meaningful acts of kindness happen when nobody is expecting them.
A man stopped at McDonald's for a quick meal.
His total was just $8, but when he tried to pay, his debit card wouldn't work.
It was an uncomfortable moment.
He wasn't asking anyone for free food. He was simply trying to pay for his order, and suddenly his payment wasn't going through.
Then something unexpected happened.
A young employee named Hayden stepped in, pulled out his own debit card, and paid for the man's meal.
The customer offered him the only cash he had, four $1 bills.
But Hayden had already made up his mind to help.
The man left, thinking he had simply received a kind gesture from a stranger.
Then he looked inside his food bag.
His four dollars were sitting there, along with his receipt and a handwritten note:
"Have a Blessed Day."
Hayden had quietly returned the money.
Think about that for a second.
This wasn't a millionaire giving away thousands of dollars.
It wasn't a celebrity making a public donation.
It was a young employee working an ordinary shift, choosing to make someone's difficult moment a little easier.
And that's what makes this story so powerful.
We often measure generosity by how much money someone gives.
But the truth is, generosity isn't always about the size of the gift.
Sometimes it's about noticing that someone needs help and deciding not to look the other way.
Hayden didn't know this customer.
He didn't know whether he would ever see him again.
He simply saw an opportunity to do something good.
And perhaps the most beautiful part is that he didn't even want the money back.
The customer was so touched that he returned to the restaurant to take a picture with Hayden and share his story publicly.
There's a bigger lesson here, too.
A person's job title, paycheck, age, or bank balance doesn't determine the size of their heart.
You don't have to be wealthy to make someone feel valued.
You don't need a platform to inspire people.
He Had Only $8 To Pay.
A Young McDonald's Employee
Gave Him Something Money Can't Buy.
Sometimes, the most meaningful acts of kindness happen when nobody is expecting them.
A man stopped at McDonald's for a quick meal.
His total was just $8, but when he tried to pay, his debit card wouldn't work.
It was an uncomfortable moment.
He wasn't asking anyone for free food. He was simply trying to pay for his order, and suddenly his payment wasn't going through.
Then something unexpected happened.
A young employee named Hayden stepped in, pulled out his own debit card, and paid for the man's meal.
The customer offered him the only cash he had, four $1 bills.
But Hayden had already made up his mind to help.
The man left, thinking he had simply received a kind gesture from a stranger.
Then he looked inside his food bag.
His four dollars were sitting there, along with his receipt and a handwritten note:
"Have a Blessed Day."
Hayden had quietly returned the money.
Think about that for a second.
This wasn't a millionaire giving away thousands of dollars.
It wasn't a celebrity making a public donation.
It was a young employee working an ordinary shift, choosing to make someone's difficult moment a little easier.
And that's what makes this story so powerful.
We often measure generosity by how much money someone gives.
But the truth is, generosity isn't always about the size of the gift.
Sometimes it's about noticing that someone needs help and deciding not to look the other way.
Hayden didn't know this customer.
He didn't know whether he would ever see him again.
He simply saw an opportunity to do something good.
And perhaps the most beautiful part is that he didn't even want the money back.
The customer was so touched that he returned to the restaurant to take a picture with Hayden and share his story publicly.
There's a bigger lesson here, too.
A person's job title, paycheck, age, or bank balance doesn't determine the size of their heart.
You don't have to be wealthy to make someone feel valued.
You don't need a platform to inspire people.
A Young McDonald's Employee
Gave Him Something Money Can't Buy.
Sometimes, the most meaningful acts of kindness happen when nobody is expecting them.
A man stopped at McDonald's for a quick meal.
His total was just $8, but when he tried to pay, his debit card wouldn't work.
It was an uncomfortable moment.
He wasn't asking anyone for free food. He was simply trying to pay for his order, and suddenly his payment wasn't going through.
Then something unexpected happened.
A young employee named Hayden stepped in, pulled out his own debit card, and paid for the man's meal.
The customer offered him the only cash he had, four $1 bills.
But Hayden had already made up his mind to help.
The man left, thinking he had simply received a kind gesture from a stranger.
Then he looked inside his food bag.
His four dollars were sitting there, along with his receipt and a handwritten note:
"Have a Blessed Day."
Hayden had quietly returned the money.
Think about that for a second.
This wasn't a millionaire giving away thousands of dollars.
It wasn't a celebrity making a public donation.
It was a young employee working an ordinary shift, choosing to make someone's difficult moment a little easier.
And that's what makes this story so powerful.
We often measure generosity by how much money someone gives.
But the truth is, generosity isn't always about the size of the gift.
Sometimes it's about noticing that someone needs help and deciding not to look the other way.
Hayden didn't know this customer.
He didn't know whether he would ever see him again.
He simply saw an opportunity to do something good.
And perhaps the most beautiful part is that he didn't even want the money back.
The customer was so touched that he returned to the restaurant to take a picture with Hayden and share his story publicly.
There's a bigger lesson here, too.
A person's job title, paycheck, age, or bank balance doesn't determine the size of their heart.
You don't have to be wealthy to make someone feel valued.
You don't need a platform to inspire people.
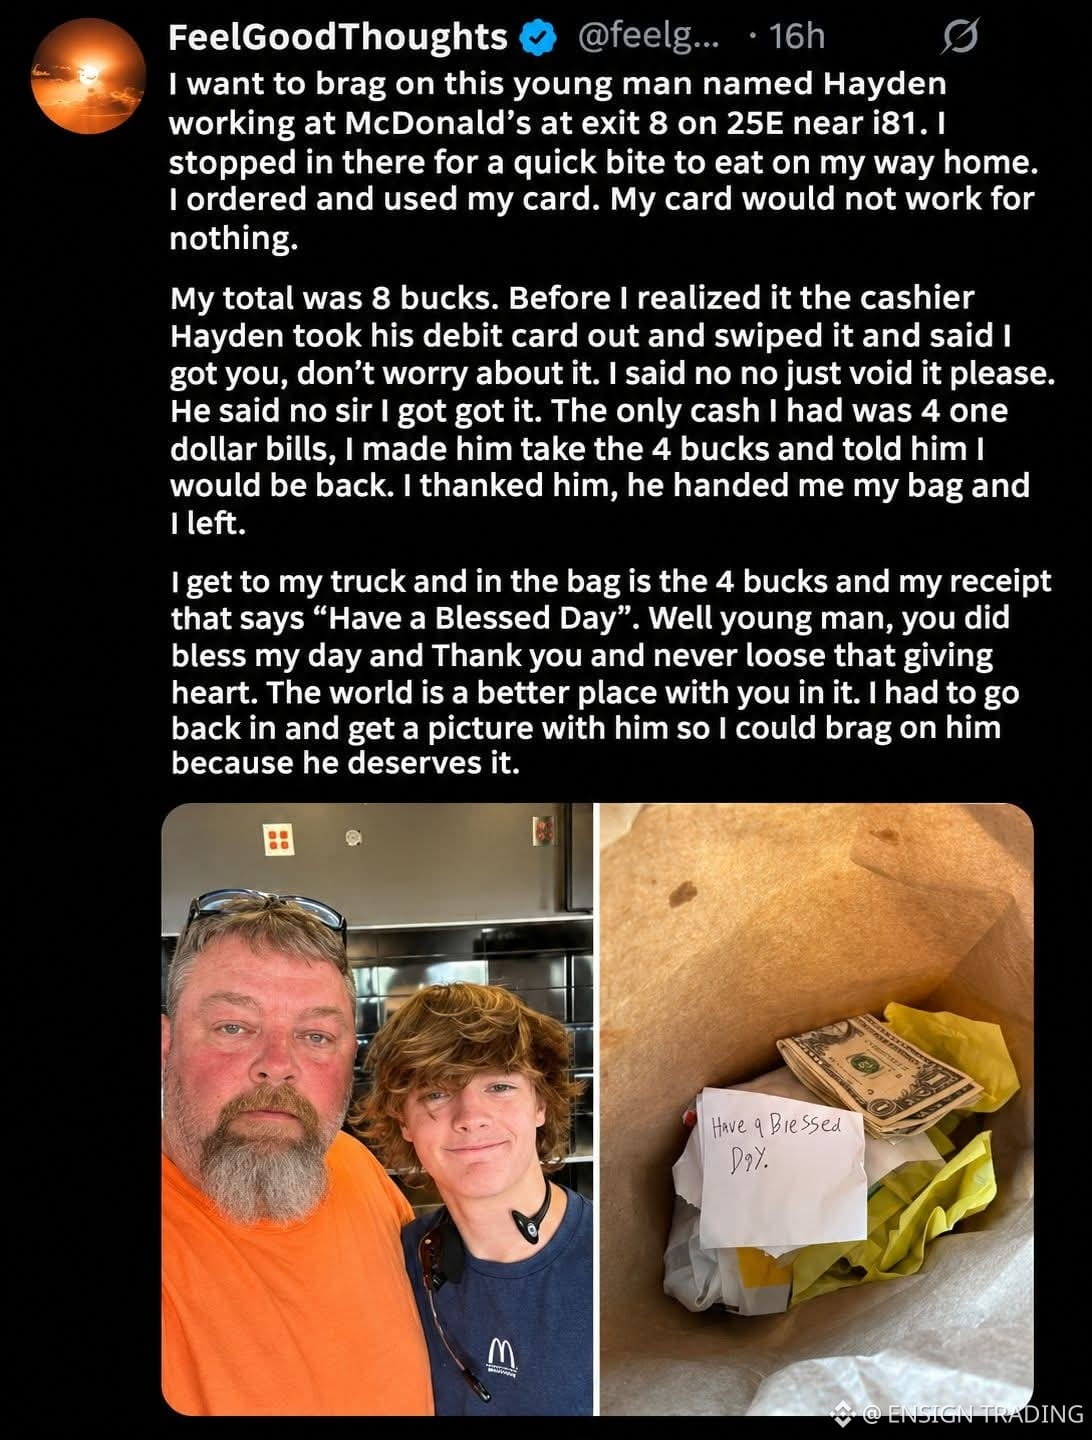
3
498
Strategy’s Trading Activity Is Sending
A Message Wall Street Can’t Ignore
A company built around Bitcoin is now generating the kind of stock-market attention usually associated with America’s biggest corporations.
Strategy’s reported trading turnover reached approximately $2.2 billion in the latest session I could verify, with roughly 19.4 million shares changing hands.
That is an extraordinary level of activity for a company whose market identity is so closely tied to Bitcoin.
But there is an important distinction: trading volume measures how much stock investors are buying and selling—not how much revenue a company earns, or how large its business is.
The MSCI debate adds another layer. Index exclusion can affect institutional demand and passive-fund ownership, but it does not automatically make a stock irrelevant to the market.
Investors are still watching MSTR because it sits at the intersection of public equities, Bitcoin exposure, capital markets, and institutional risk appetite.
Index membership can change. Market attention is harder to erase.
Strategy’s Trading Activity Is Sending
A Message Wall Street Can’t Ignore
A company built around Bitcoin is now generating the kind of stock-market attention usually associated with America’s biggest corporations.
Strategy’s reported trading turnover reached approximately $2.2 billion in the latest session I could verify, with roughly 19.4 million shares changing hands.
That is an extraordinary level of activity for a company whose market identity is so closely tied to Bitcoin.
But there is an important distinction: trading volume measures how much stock investors are buying and selling—not how much revenue a company earns, or how large its business is.
The MSCI debate adds another layer. Index exclusion can affect institutional demand and passive-fund ownership, but it does not automatically make a stock irrelevant to the market.
Investors are still watching MSTR because it sits at the intersection of public equities, Bitcoin exposure, capital markets, and institutional risk appetite.
Index membership can change. Market attention is harder to erase.
A Message Wall Street Can’t Ignore
A company built around Bitcoin is now generating the kind of stock-market attention usually associated with America’s biggest corporations.
Strategy’s reported trading turnover reached approximately $2.2 billion in the latest session I could verify, with roughly 19.4 million shares changing hands.
That is an extraordinary level of activity for a company whose market identity is so closely tied to Bitcoin.
But there is an important distinction: trading volume measures how much stock investors are buying and selling—not how much revenue a company earns, or how large its business is.
The MSCI debate adds another layer. Index exclusion can affect institutional demand and passive-fund ownership, but it does not automatically make a stock irrelevant to the market.
Investors are still watching MSTR because it sits at the intersection of public equities, Bitcoin exposure, capital markets, and institutional risk appetite.
Index membership can change. Market attention is harder to erase.
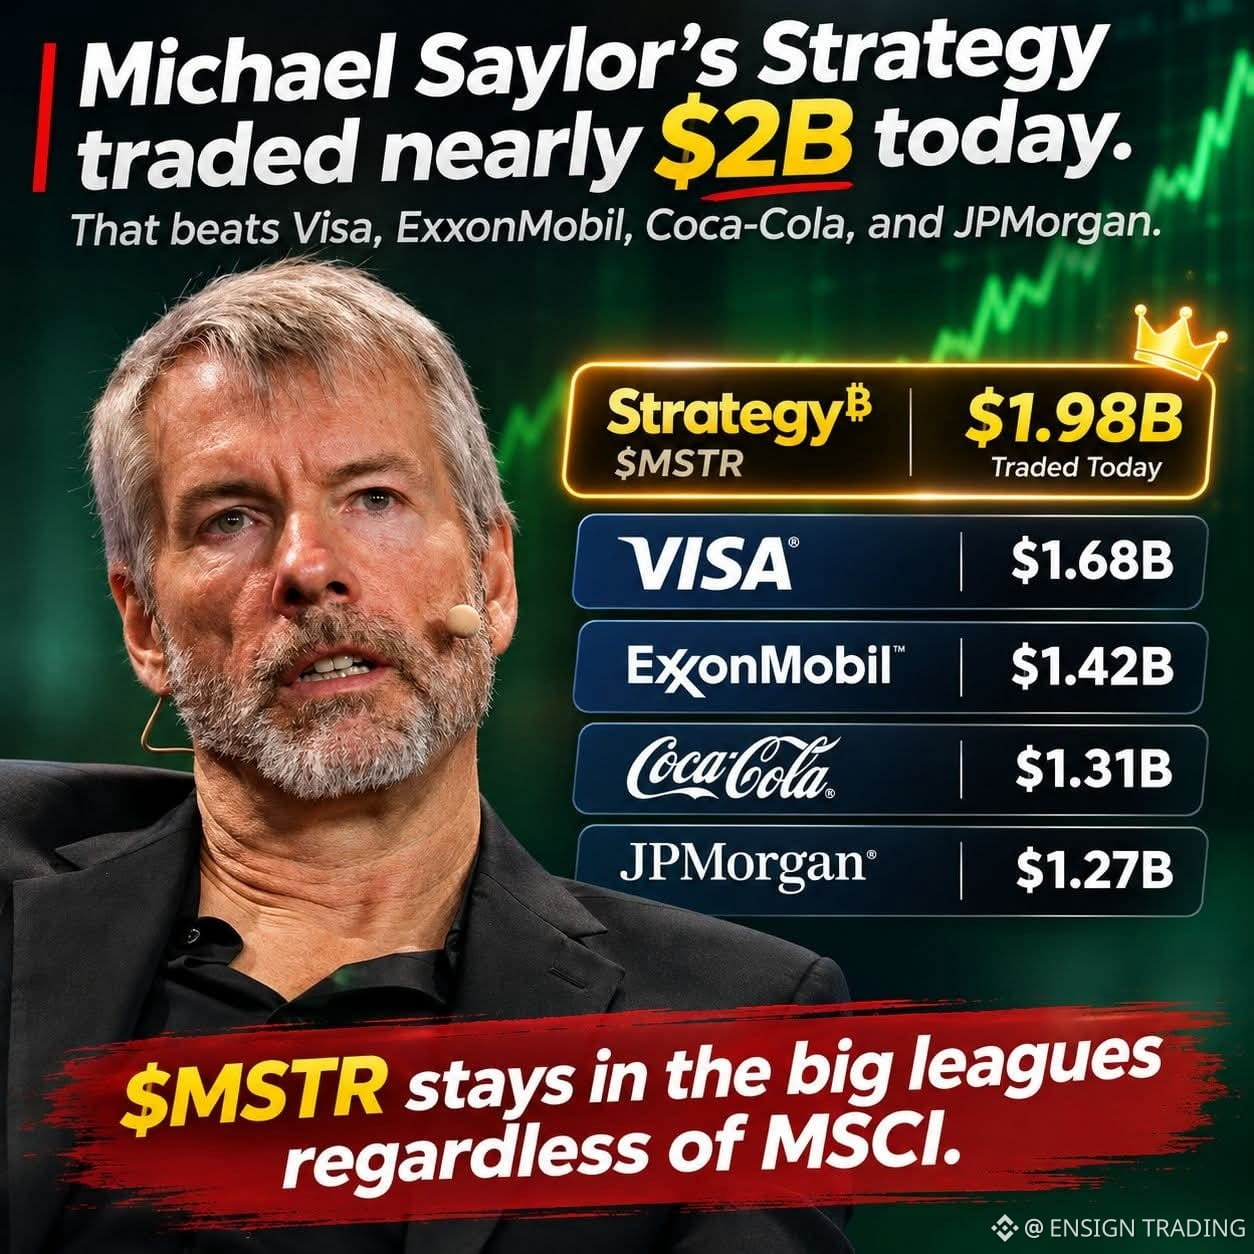
MSTR-7.20%
MSCIUS-1.88%
95
YOUR FUTURE SELF WILL LIVE WITH THE DECISIONS YOU MAKE TODAY.
At 25, it's easy to think you have plenty of time to figure everything out.
You focus on earning more, enjoying life, and getting through the next month.
But somewhere along the way, you realize that your biggest financial problems didn't always come from one bad decision.
Sometimes, they came from small habits repeated for years.
A credit card balance that kept growing.
A lifestyle that became more expensive every time your income increased.
Years passing without building an investment portfolio.
Or spending so much energy on work that your health and personal life kept getting pushed aside.
And here's something worth remembering:
You don't need to completely change your life overnight.
Start by making a few better decisions consistently.
Learn to manage what you earn.
Build skills that increase your future earning potential.
Give your investments time to grow.
Take care of your body before poor health starts limiting your choices.
And don't sacrifice every peaceful moment just to keep up with someone else's lifestyle.
The real advantage isn't having everything figured out at 25.
It's avoiding habits that make life unnecessarily difficult at 40.
BUILD HABITS TODAY THAT YOUR FUTURE SELF WILL THANK YOU FOR.
YOUR FUTURE SELF WILL LIVE WITH THE DECISIONS YOU MAKE TODAY.
At 25, it's easy to think you have plenty of time to figure everything out.
You focus on earning more, enjoying life, and getting through the next month.
But somewhere along the way, you realize that your biggest financial problems didn't always come from one bad decision.
Sometimes, they came from small habits repeated for years.
A credit card balance that kept growing.
A lifestyle that became more expensive every time your income increased.
Years passing without building an investment portfolio.
Or spending so much energy on work that your health and personal life kept getting pushed aside.
And here's something worth remembering:
You don't need to completely change your life overnight.
Start by making a few better decisions consistently.
Learn to manage what you earn.
Build skills that increase your future earning potential.
Give your investments time to grow.
Take care of your body before poor health starts limiting your choices.
And don't sacrifice every peaceful moment just to keep up with someone else's lifestyle.
The real advantage isn't having everything figured out at 25.
It's avoiding habits that make life unnecessarily difficult at 40.
BUILD HABITS TODAY THAT YOUR FUTURE SELF WILL THANK YOU FOR.
At 25, it's easy to think you have plenty of time to figure everything out.
You focus on earning more, enjoying life, and getting through the next month.
But somewhere along the way, you realize that your biggest financial problems didn't always come from one bad decision.
Sometimes, they came from small habits repeated for years.
A credit card balance that kept growing.
A lifestyle that became more expensive every time your income increased.
Years passing without building an investment portfolio.
Or spending so much energy on work that your health and personal life kept getting pushed aside.
And here's something worth remembering:
You don't need to completely change your life overnight.
Start by making a few better decisions consistently.
Learn to manage what you earn.
Build skills that increase your future earning potential.
Give your investments time to grow.
Take care of your body before poor health starts limiting your choices.
And don't sacrifice every peaceful moment just to keep up with someone else's lifestyle.
The real advantage isn't having everything figured out at 25.
It's avoiding habits that make life unnecessarily difficult at 40.
BUILD HABITS TODAY THAT YOUR FUTURE SELF WILL THANK YOU FOR.
69
WHEN DOES PAPER WEALTH BECOME TAXABLE?
There's an interesting difference in how the U.S. tax system treats different kinds of assets.
Imagine a billionaire owns shares worth $5 billion.
If those shares increase in value but are never sold, the increase generally isn't taxed as a capital gain under the traditional federal income tax system.
Now consider a small business owner holding thousands of dollars worth of inventory.
In some states and local jurisdictions, that inventory may be subject to business personal property taxes even before it is sold.
The owner hasn't collected the money.
The products are still sitting in storage.
Yet a tax bill may still be based partly on the value of those goods.
But there's an important distinction here.
Inventory property tax is not the same as income tax on an unrealized stock gain.
One is a tax on holding certain business property.
The other concerns taxing investment appreciation before a sale.
And not every state taxes inventory this way.
Some states have eliminated inventory taxes or provide exemptions.
So the real question isn't whether these two assets should automatically receive identical tax treatment.
It's whether the tax system applies consistent principles when people hold wealth in very different forms.
Because a small business owner may have valuable inventory but very little available cash.
And a billionaire may have billions in stock wealth without selling a single share.
Both situations raise a difficult policy question:
How should governments tax wealth when the value exists on paper, but the cash hasn't necessarily arrived?
THE FORM OF WEALTH CAN CHANGE THE TAX RULES.
WHEN DOES PAPER WEALTH BECOME TAXABLE?
There's an interesting difference in how the U.S. tax system treats different kinds of assets.
Imagine a billionaire owns shares worth $5 billion.
If those shares increase in value but are never sold, the increase generally isn't taxed as a capital gain under the traditional federal income tax system.
Now consider a small business owner holding thousands of dollars worth of inventory.
In some states and local jurisdictions, that inventory may be subject to business personal property taxes even before it is sold.
The owner hasn't collected the money.
The products are still sitting in storage.
Yet a tax bill may still be based partly on the value of those goods.
But there's an important distinction here.
Inventory property tax is not the same as income tax on an unrealized stock gain.
One is a tax on holding certain business property.
The other concerns taxing investment appreciation before a sale.
And not every state taxes inventory this way.
Some states have eliminated inventory taxes or provide exemptions.
So the real question isn't whether these two assets should automatically receive identical tax treatment.
It's whether the tax system applies consistent principles when people hold wealth in very different forms.
Because a small business owner may have valuable inventory but very little available cash.
And a billionaire may have billions in stock wealth without selling a single share.
Both situations raise a difficult policy question:
How should governments tax wealth when the value exists on paper, but the cash hasn't necessarily arrived?
THE FORM OF WEALTH CAN CHANGE THE TAX RULES.
There's an interesting difference in how the U.S. tax system treats different kinds of assets.
Imagine a billionaire owns shares worth $5 billion.
If those shares increase in value but are never sold, the increase generally isn't taxed as a capital gain under the traditional federal income tax system.
Now consider a small business owner holding thousands of dollars worth of inventory.
In some states and local jurisdictions, that inventory may be subject to business personal property taxes even before it is sold.
The owner hasn't collected the money.
The products are still sitting in storage.
Yet a tax bill may still be based partly on the value of those goods.
But there's an important distinction here.
Inventory property tax is not the same as income tax on an unrealized stock gain.
One is a tax on holding certain business property.
The other concerns taxing investment appreciation before a sale.
And not every state taxes inventory this way.
Some states have eliminated inventory taxes or provide exemptions.
So the real question isn't whether these two assets should automatically receive identical tax treatment.
It's whether the tax system applies consistent principles when people hold wealth in very different forms.
Because a small business owner may have valuable inventory but very little available cash.
And a billionaire may have billions in stock wealth without selling a single share.
Both situations raise a difficult policy question:
How should governments tax wealth when the value exists on paper, but the cash hasn't necessarily arrived?
THE FORM OF WEALTH CAN CHANGE THE TAX RULES.
63
WHEN CANCELLING A RIDE STARTS COSTING YOU MONEY.
Imagine waiting nearly 50 minutes for an Uber driver.
The app keeps showing the car nearby, but somehow the pickup never happens.
At that point, you're not just waiting for transportation.
You're losing time, possibly missing an appointment, and wondering whether cancelling will cost you extra money.
That's where the situation gets frustrating.
Ride-hailing apps use cancellation fees to compensate drivers when a rider cancels after certain conditions have been met.
The idea is understandable.
A driver may have already spent time and fuel travelling toward a pickup location.
But there's another side to the equation.
What happens when the delay is unreasonable, the driver isn't actually reaching the passenger, or the rider feels pressured to keep waiting because the cancellation screen warns that rebooking may take even longer?
A cancellation policy should protect drivers from unfair cancellations.
It should also protect passengers from being charged when the service isn't being delivered as expected.
And this is where transparency matters.
Passengers should be able to understand why a fee applies, how long they are expected to wait, and how to challenge a charge when something goes wrong.
If a cancellation fee appears unfair, riders should review the trip details and use Uber's in-app support to request a review.
Because paying for a ride should mean receiving a reasonable service, not feeling trapped by the cancellation button.
FAIR RULES SHOULD WORK FOR BOTH SIDES.
WHEN CANCELLING A RIDE STARTS COSTING YOU MONEY.
Imagine waiting nearly 50 minutes for an Uber driver.
The app keeps showing the car nearby, but somehow the pickup never happens.
At that point, you're not just waiting for transportation.
You're losing time, possibly missing an appointment, and wondering whether cancelling will cost you extra money.
That's where the situation gets frustrating.
Ride-hailing apps use cancellation fees to compensate drivers when a rider cancels after certain conditions have been met.
The idea is understandable.
A driver may have already spent time and fuel travelling toward a pickup location.
But there's another side to the equation.
What happens when the delay is unreasonable, the driver isn't actually reaching the passenger, or the rider feels pressured to keep waiting because the cancellation screen warns that rebooking may take even longer?
A cancellation policy should protect drivers from unfair cancellations.
It should also protect passengers from being charged when the service isn't being delivered as expected.
And this is where transparency matters.
Passengers should be able to understand why a fee applies, how long they are expected to wait, and how to challenge a charge when something goes wrong.
If a cancellation fee appears unfair, riders should review the trip details and use Uber's in-app support to request a review.
Because paying for a ride should mean receiving a reasonable service, not feeling trapped by the cancellation button.
FAIR RULES SHOULD WORK FOR BOTH SIDES.
Imagine waiting nearly 50 minutes for an Uber driver.
The app keeps showing the car nearby, but somehow the pickup never happens.
At that point, you're not just waiting for transportation.
You're losing time, possibly missing an appointment, and wondering whether cancelling will cost you extra money.
That's where the situation gets frustrating.
Ride-hailing apps use cancellation fees to compensate drivers when a rider cancels after certain conditions have been met.
The idea is understandable.
A driver may have already spent time and fuel travelling toward a pickup location.
But there's another side to the equation.
What happens when the delay is unreasonable, the driver isn't actually reaching the passenger, or the rider feels pressured to keep waiting because the cancellation screen warns that rebooking may take even longer?
A cancellation policy should protect drivers from unfair cancellations.
It should also protect passengers from being charged when the service isn't being delivered as expected.
And this is where transparency matters.
Passengers should be able to understand why a fee applies, how long they are expected to wait, and how to challenge a charge when something goes wrong.
If a cancellation fee appears unfair, riders should review the trip details and use Uber's in-app support to request a review.
Because paying for a ride should mean receiving a reasonable service, not feeling trapped by the cancellation button.
FAIR RULES SHOULD WORK FOR BOTH SIDES.
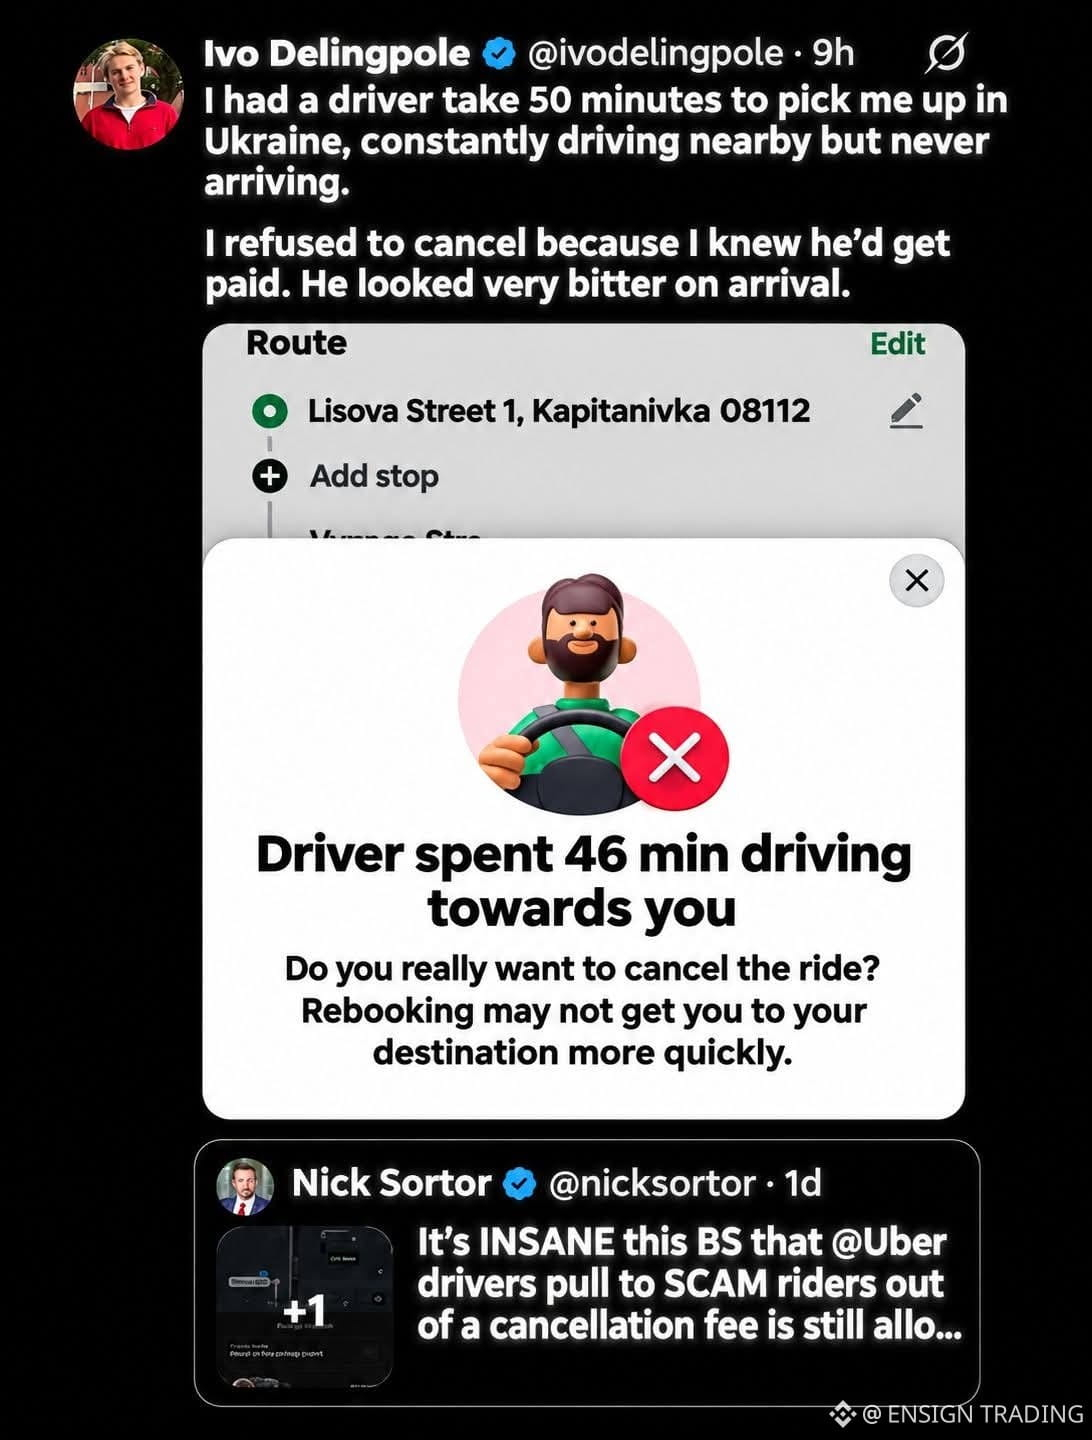
191
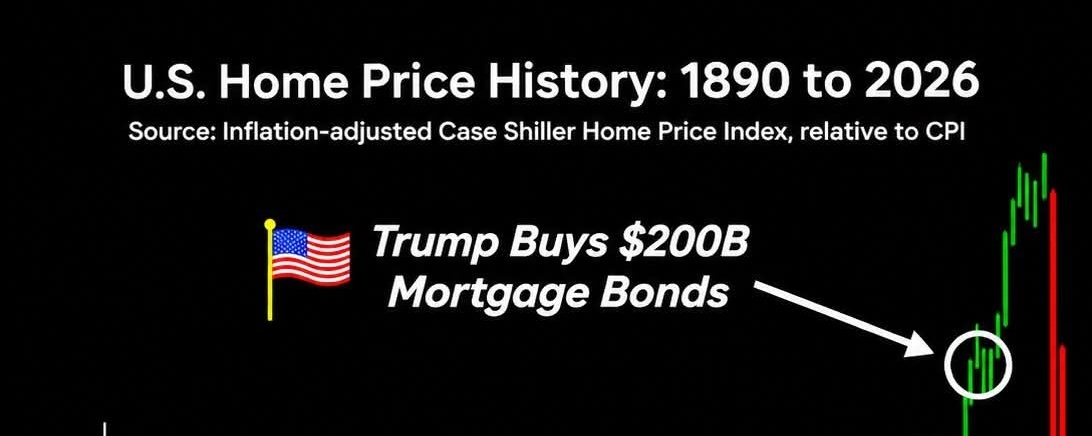
Article
THE $200 BILLION HOUSING MOVE HAS A MUCH BIGGER STORY BEHIND IT.THE $200 BILLION HOUSING MOVE HAS A MUCH BIGGER STORY BEHIND IT.
Let's look at what is actually happening in America's housing market.
Back in January 2026, President Trump directed Fannie Mae and Freddie Mac to purchase $200 billion in mortgage-backed securities.
The objective was straightforward.
Increase demand for mortgage bonds.
Push their prices higher.
Bring mortgage yields lower.
And hopefully reduce the interest rates Americans pay when buying a home.
But here's where things get complicated.
Mortgage rates are not determined by the Federal Reserve alone.
They are influenced by Treasury yields, mortgage-bond prices, investor demand, inflation expectations, and the spread between Treasury securities and mortgage-backed securities.
When large buyers step into the mortgage-bond market, they can influence that equation.
But they cannot control every part of it.
And the latest housing numbers show why this matters.
As of November 12, the average 30-year fixed mortgage rate was still 7.11%.
That's lower than the previous week's 7.18%, but considerably higher than the 6.24% recorded one year earlier.
Meanwhile, existing-home sales in October fell 8.8% compared with the same month last year.
The annual sales pace dropped to approximately 3.75 million homes.
That's the lowest level since August 2010.
Think about what these numbers are telling us.
Millions of potential buyers are dealing with expensive financing.
Many existing homeowners are reluctant to sell because they don't want to give up the much lower mortgage rates they secured years ago.
And buyers are still facing expensive homes.
This creates a difficult situation.
Lower mortgage rates could bring more buyers back into the market.
But if housing supply doesn't increase alongside demand, more purchasing power can also put upward pressure on home prices.
In other words, making mortgages cheaper doesn't automatically make houses affordable.
There's another side of this $200 billion strategy that deserves attention.
Fannie Mae and Freddie Mac are not the Federal Reserve.
They are government-sponsored enterprises with their own balance sheets, investment limits, and financial risks.
Their purchases are not the same as the Fed creating money and launching a new quantitative-easing program.
And the entire $200 billion should not be confused with money already spent.
Implementation has been gradual, rather than an immediate $200 billion injection.
So why should investors pay attention?
Because mortgage-backed securities connect the housing market to the wider financial system.
Their prices and yields influence mortgage financing.
Changes in interest rates can affect banks, mortgage lenders, homebuilders, and housing-related companies.
Treasury markets also matter because mortgage rates are closely linked to longer-term borrowing costs.
But don't assume that one housing policy automatically determines what happens next in stocks, gold, or Bitcoin.
Those markets respond to different forces, even when interest rates and liquidity connect them.
And here's the biggest issue I see in this entire debate.
America doesn't have a housing affordability problem that can be solved by cheaper financing alone.
It also has a problem involving home prices, available housing, construction costs, and the gap between household incomes and the cost of owning a home.
If policymakers reduce borrowing costs without addressing those deeper problems, they could improve monthly payments while leaving the underlying affordability challenge largely untouched.
That's the difference between making mortgages cheaper and making housing genuinely affordable.
LOWER RATES CAN HELP BUYERS. THEY CANNOT BUILD MORE HOMES.
THE $200 BILLION HOUSING MOVE HAS A MUCH BIGGER STORY BEHIND IT.
THE $200 BILLION HOUSING MOVE HAS A MUCH BIGGER STORY BEHIND IT.
Let's look at what is actually happening in America's housing market.
Back in January 2026, President Trump directed Fannie Mae and Freddie Mac to purchase $200 billion in mortgage-backed securities.
The objective was straightforward.
Increase demand for mortgage bonds.
Push their prices higher.
Bring mortgage yields lower.
And hopefully reduce the interest rates Americans pay when buying a home.
But here's where things get complicated.
Mortgage rates are not determined by the Federal Reserve alone.
They are influenced by Treasury yields, mortgage-bond prices, investor demand, inflation expectations, and the spread between Treasury securities and mortgage-backed securities.
When large buyers step into the mortgage-bond market, they can influence that equation.
But they cannot control every part of it.
And the latest housing numbers show why this matters.
As of November 12, the average 30-year fixed mortgage rate was still 7.11%.
That's lower than the previous week's 7.18%, but considerably higher than the 6.24% recorded one year earlier.
Meanwhile, existing-home sales in October fell 8.8% compared with the same month last year.
The annual sales pace dropped to approximately 3.75 million homes.
That's the lowest level since August 2010.
Think about what these numbers are telling us.
Millions of potential buyers are dealing with expensive financing.
Many existing homeowners are reluctant to sell because they don't want to give up the much lower mortgage rates they secured years ago.
And buyers are still facing expensive homes.
This creates a difficult situation.
Lower mortgage rates could bring more buyers back into the market.
But if housing supply doesn't increase alongside demand, more purchasing power can also put upward pressure on home prices.
In other words, making mortgages cheaper doesn't automatically make houses affordable.
There's another side of this $200 billion strategy that deserves attention.
Fannie Mae and Freddie Mac are not the Federal Reserve.
They are government-sponsored enterprises with their own balance sheets, investment limits, and financial risks.
Their purchases are not the same as the Fed creating money and launching a new quantitative-easing program.
And the entire $200 billion should not be confused with money already spent.
Implementation has been gradual, rather than an immediate $200 billion injection.
So why should investors pay attention?
Because mortgage-backed securities connect the housing market to the wider financial system.
Their prices and yields influence mortgage financing.
Changes in interest rates can affect banks, mortgage lenders, homebuilders, and housing-related companies.
Treasury markets also matter because mortgage rates are closely linked to longer-term borrowing costs.
But don't assume that one housing policy automatically determines what happens next in stocks, gold, or Bitcoin.
Those markets respond to different forces, even when interest rates and liquidity connect them.
And here's the biggest issue I see in this entire debate.
America doesn't have a housing affordability problem that can be solved by cheaper financing alone.
It also has a problem involving home prices, available housing, construction costs, and the gap between household incomes and the cost of owning a home.
If policymakers reduce borrowing costs without addressing those deeper problems, they could improve monthly payments while leaving the underlying affordability challenge largely untouched.
That's the difference between making mortgages cheaper and making housing genuinely affordable.
LOWER RATES CAN HELP BUYERS. THEY CANNOT BUILD MORE HOMES.
Let's look at what is actually happening in America's housing market.
Back in January 2026, President Trump directed Fannie Mae and Freddie Mac to purchase $200 billion in mortgage-backed securities.
The objective was straightforward.
Increase demand for mortgage bonds.
Push their prices higher.
Bring mortgage yields lower.
And hopefully reduce the interest rates Americans pay when buying a home.
But here's where things get complicated.
Mortgage rates are not determined by the Federal Reserve alone.
They are influenced by Treasury yields, mortgage-bond prices, investor demand, inflation expectations, and the spread between Treasury securities and mortgage-backed securities.
When large buyers step into the mortgage-bond market, they can influence that equation.
But they cannot control every part of it.
And the latest housing numbers show why this matters.
As of November 12, the average 30-year fixed mortgage rate was still 7.11%.
That's lower than the previous week's 7.18%, but considerably higher than the 6.24% recorded one year earlier.
Meanwhile, existing-home sales in October fell 8.8% compared with the same month last year.
The annual sales pace dropped to approximately 3.75 million homes.
That's the lowest level since August 2010.
Think about what these numbers are telling us.
Millions of potential buyers are dealing with expensive financing.
Many existing homeowners are reluctant to sell because they don't want to give up the much lower mortgage rates they secured years ago.
And buyers are still facing expensive homes.
This creates a difficult situation.
Lower mortgage rates could bring more buyers back into the market.
But if housing supply doesn't increase alongside demand, more purchasing power can also put upward pressure on home prices.
In other words, making mortgages cheaper doesn't automatically make houses affordable.
There's another side of this $200 billion strategy that deserves attention.
Fannie Mae and Freddie Mac are not the Federal Reserve.
They are government-sponsored enterprises with their own balance sheets, investment limits, and financial risks.
Their purchases are not the same as the Fed creating money and launching a new quantitative-easing program.
And the entire $200 billion should not be confused with money already spent.
Implementation has been gradual, rather than an immediate $200 billion injection.
So why should investors pay attention?
Because mortgage-backed securities connect the housing market to the wider financial system.
Their prices and yields influence mortgage financing.
Changes in interest rates can affect banks, mortgage lenders, homebuilders, and housing-related companies.
Treasury markets also matter because mortgage rates are closely linked to longer-term borrowing costs.
But don't assume that one housing policy automatically determines what happens next in stocks, gold, or Bitcoin.
Those markets respond to different forces, even when interest rates and liquidity connect them.
And here's the biggest issue I see in this entire debate.
America doesn't have a housing affordability problem that can be solved by cheaper financing alone.
It also has a problem involving home prices, available housing, construction costs, and the gap between household incomes and the cost of owning a home.
If policymakers reduce borrowing costs without addressing those deeper problems, they could improve monthly payments while leaving the underlying affordability challenge largely untouched.
That's the difference between making mortgages cheaper and making housing genuinely affordable.
LOWER RATES CAN HELP BUYERS. THEY CANNOT BUILD MORE HOMES.
126
I may be misunderstood for this, but I'll say it anyway.
I don't see the need for Jensen Huang to step away from Nvidia completely, board included.
I understand there's no sentiment in corporate governance. But this is a company he built from scratch over 33 years.
Many people bought Nvidia stock because they believed in him, myself included. The people who sit on that board became wealthy because of what he built.
Yes, he made a grave mistake. He should be held accountable, and the investigation should run its full course.
But let's be honest abeg, many American CEOs are guilty of these scandals. Amongst all of them, Jensen always looked to me like one of the most decent. Unfortunately, he has fallen.
#giftmuoneke
I may be misunderstood for this, but I'll say it anyway.
I don't see the need for Jensen Huang to step away from Nvidia completely, board included.
I understand there's no sentiment in corporate governance. But this is a company he built from scratch over 33 years.
Many people bought Nvidia stock because they believed in him, myself included. The people who sit on that board became wealthy because of what he built.
Yes, he made a grave mistake. He should be held accountable, and the investigation should run its full course.
But let's be honest abeg, many American CEOs are guilty of these scandals. Amongst all of them, Jensen always looked to me like one of the most decent. Unfortunately, he has fallen.
#giftmuoneke
I don't see the need for Jensen Huang to step away from Nvidia completely, board included.
I understand there's no sentiment in corporate governance. But this is a company he built from scratch over 33 years.
Many people bought Nvidia stock because they believed in him, myself included. The people who sit on that board became wealthy because of what he built.
Yes, he made a grave mistake. He should be held accountable, and the investigation should run its full course.
But let's be honest abeg, many American CEOs are guilty of these scandals. Amongst all of them, Jensen always looked to me like one of the most decent. Unfortunately, he has fallen.
#giftmuoneke
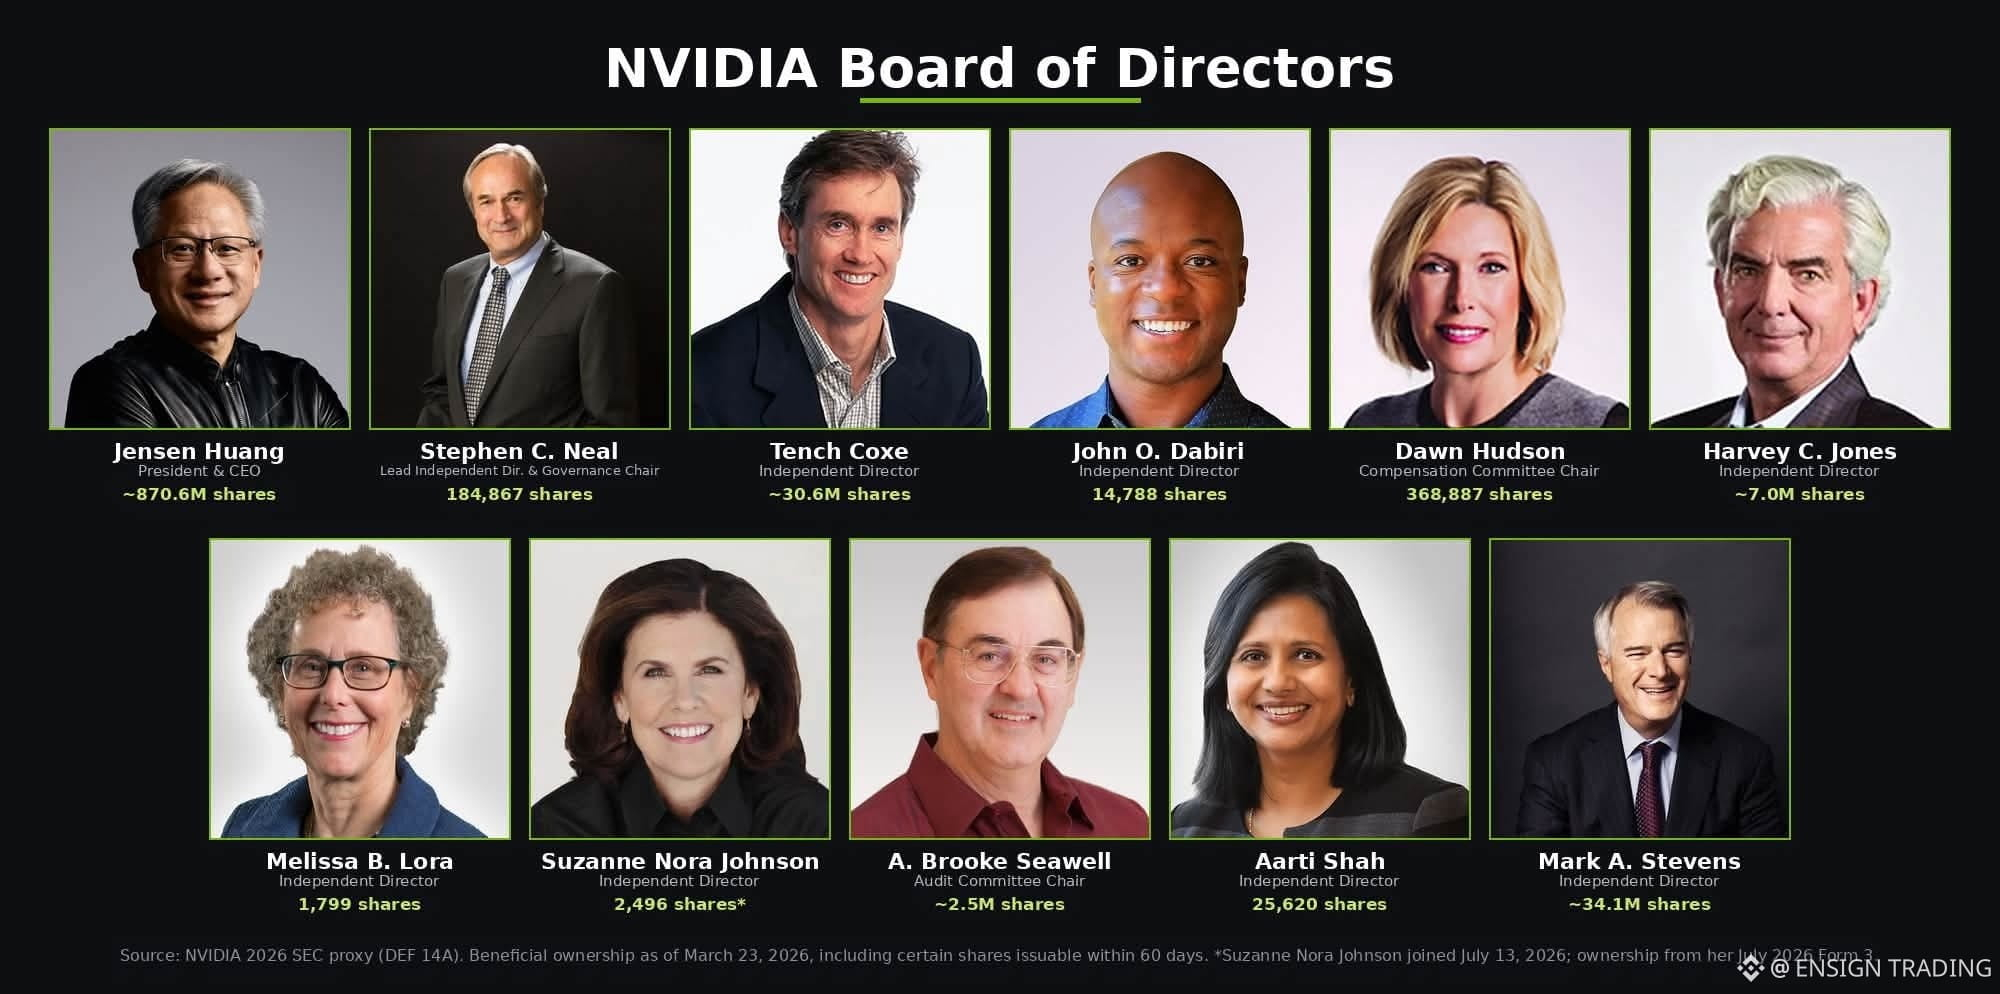
1.1k
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
IsAnthropic’s$1.5TMarketCapJustified?
24,093 views
124 Discussing
Anthropic Set to Open at $105 in Record Nasdaq Debut
Binance News
·12 Likes
·17.1k views
13FInstitutionsBitcoinSpotETPHoldingsHitRecord
829 views
23 Discussing
BTCRemainsUnderPressureAfterHawkishFOMCMinutes
295,467 views
2,225 Discussing