
HYPE broke $97, a new all-time high. Hyperliquid’s monthly active addresses hit 291,900, also an all-time high—up nearly 30% from July.
The data is so good it doesn’t look real.
But when you open Hyperliquid’s on-chain ledger, you’ll find something nobody’s talking about: more people are coming, but no one answers the question of “why are they coming?”
Active addresses are “people who have traded at least once or held a position.” How many of them are here just to farm the airdrop? How many try it once and then leave? How many are genuinely continuing to trade, contribute fees, and drive volume?
BlockBeats even wrote it themselves: the key risk is whether this growth can translate into sustained trading volume and revenue, or whether it will fade as market cycles change.
Translation: bustling with visitors, but you don't know whether they're here to eat or to use the restroom.
The ones truly “quietly eating” are a different group of people.
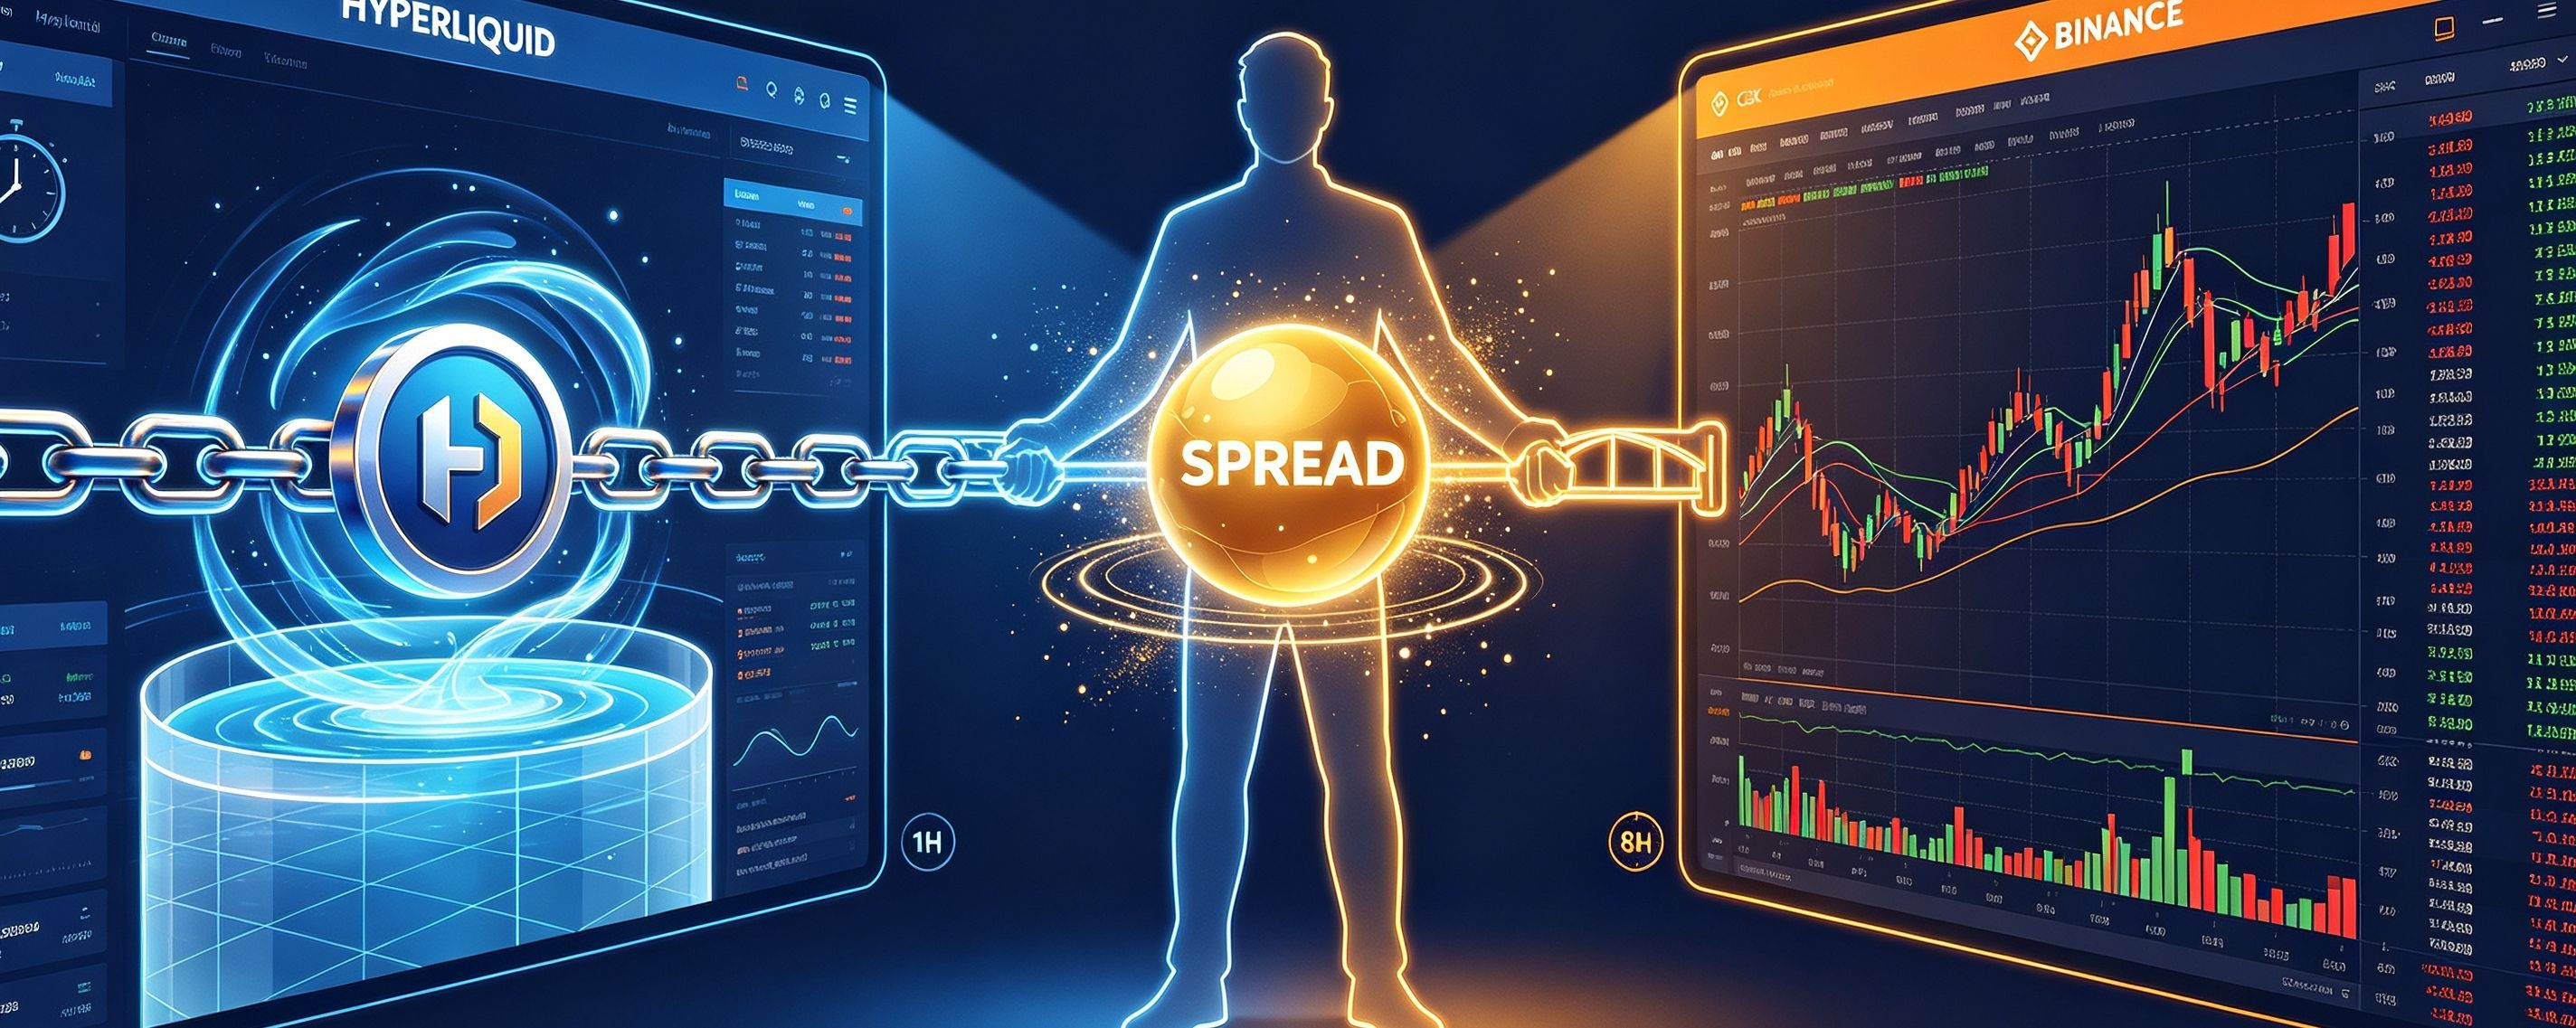
After HYPE broke 97.5, Wintermute started transferring large amounts of HYPE to major centralized exchanges. Market makers don't care whether HYPE goes up or down tomorrow—they care about: what is the current price spread of HYPE between Hyperliquid and Binance?
Same coin, two venues. When the prices are different, that's market makers’ working time.
While you're staring at the candlestick chart thinking, “Can I still chase it?”, they're watching the order book calculating, “How much can this order be filled for?”
Here’s something most people don’t know.
Hyperliquid 的资金费率结算频率是每小时一次。币安是每 8 小时一次。
Right direction, and losses are about 8x? No—gains accumulate by almost 8x. Wrong direction, and losses also ramp up by almost 8x.
You open a position that earns funding rates and feel great—every hour you’re getting paid. But when the funding rate flips, every hour money flows out, and the speed at which it’s being extracted is 8 times faster than what you’re used to.
The funding rate difference sounds great. But the combined cost of opening and closing positions eats 0.2%. Then, if the funding rate flips while you're holding, you're basically working for the exchange.
Bitfinex just gave everyone a lesson.
On September 21, Bitcoin spot was still around 85,000. On Bitfinex, the BTC perpetual contract price briefly surged to $153,960. The order book was too thin, and on top of that, a liquidation cascade of shorts was triggered—within seconds the price completely lost its anchor.
Over the past 24 hours, 117,116 leveraged traders were liquidated.
You think the price you see on one platform is the “market price.” In those few seconds, Bitfinex tells you: every venue is its own separate world.
So what is this piece really trying to say?
Everyone understood HYPE’s story. But Hyperliquid’s ledger—only a few people bother to open it.
290,000 monthly active addresses is a signal, but not the finish line. Wintermute is transferring funds, arbitrageurs are calculating funding rates, and Bitfinex is flashing crashing. These things happen simultaneously, but most people only watch the candlestick chart.
If you're a trader, not an investor, what you should truly care about might not be whether HYPE goes up or down tomorrow. It's the price spread between Hyperliquid and Binance—how much it is today, and when settlement cycles don't line up, which direction your position is bleeding toward.
The funding rate difference is public data. Doing the math is up to each person.
Candlestick charts are for people who watch the market closely. Those who do the math look at a different table.
When you look at funding rates across platforms, how many venues do you usually keep an eye on at the same time? Chat in the comments.