
shahzad 555
218 Posts

shahzad 555
Report
Block User
47 Following
1 Followers
2 Liked
Posts
All
Quotes
·
--
Verified
#CanNvidia’sDataCenterGrowthContinue? Can Nvidia's Data Center Growth Continue?
For the last two years, one name has dominated the entire stock market: Nvidia.
It started as a gaming chip company. Today, more than 93% of its money comes from Data Centers. Those are the massive computers that power AI for ChatGPT, Google, Meta, Microsoft, and almost every AI company in the world.
So the big question is simple: Can this growth continue?
What Just Happened
Nvidia just reported the biggest quarter in its history.
Total revenue: $115.8 billion, up 103% from last year
Data Center revenue: $107.6 billion, up 110% from last year
Next quarter guidance: $130 billion
Next year growth forecast: Around 75%
Its new chip, Vera Rubin, made nearly $20 billion in its very first quarter. That is the fastest product launch in Nvidia's history.
Why Growth Can Continue
1. Demand Is Still Massive
There is a $2.5 trillion backlog of cloud and AI projects waiting to be built. Every one of them needs Nvidia chips.
2. It Is Not Just Big Tech Anymore
Earlier, only Google, Microsoft, and Amazon were buying. Now factories, hospitals, banks, and governments are also building AI centers. That makes demand much wider.
3. New Product Cycle Just Started
Rubin is just beginning. Nvidia expects its CPU business to more than double next year as customers adopt the full Rubin platform.
4. Zero China In The Forecast
Nvidia's guidance assumes zero Data Center revenue from China. So if anything changes there, it would only be upside.
Why Growth Could Slow Down
1. Profit Margins Are Falling
Gross margin fell from 74.8% to a guided 71-72%. Making new chips is getting more expensive, especially memory.
2. Growth Is Slowing On A Weekly Basis
The next quarter includes an extra week. After adjusting for that, growth is closer to 4% quarter-over-quarter, not 12%.
3. Too Dependent On A Few Customers
Most of the demand comes from a handful of hyperscalers and AI labs. If they slow spending or struggle to get financing, Nvidia will feel it immediately.
#CanNvidia’sDataCenterGrowthContinue? Can Nvidia's Data Center Growth Continue?
For the last two years, one name has dominated the entire stock market: Nvidia.
It started as a gaming chip company. Today, more than 93% of its money comes from Data Centers. Those are the massive computers that power AI for ChatGPT, Google, Meta, Microsoft, and almost every AI company in the world.
So the big question is simple: Can this growth continue?
What Just Happened
Nvidia just reported the biggest quarter in its history.
Total revenue: $115.8 billion, up 103% from last year
Data Center revenue: $107.6 billion, up 110% from last year
Next quarter guidance: $130 billion
Next year growth forecast: Around 75%
Its new chip, Vera Rubin, made nearly $20 billion in its very first quarter. That is the fastest product launch in Nvidia's history.
Why Growth Can Continue
1. Demand Is Still Massive
There is a $2.5 trillion backlog of cloud and AI projects waiting to be built. Every one of them needs Nvidia chips.
2. It Is Not Just Big Tech Anymore
Earlier, only Google, Microsoft, and Amazon were buying. Now factories, hospitals, banks, and governments are also building AI centers. That makes demand much wider.
3. New Product Cycle Just Started
Rubin is just beginning. Nvidia expects its CPU business to more than double next year as customers adopt the full Rubin platform.
4. Zero China In The Forecast
Nvidia's guidance assumes zero Data Center revenue from China. So if anything changes there, it would only be upside.
Why Growth Could Slow Down
1. Profit Margins Are Falling
Gross margin fell from 74.8% to a guided 71-72%. Making new chips is getting more expensive, especially memory.
2. Growth Is Slowing On A Weekly Basis
The next quarter includes an extra week. After adjusting for that, growth is closer to 4% quarter-over-quarter, not 12%.
3. Too Dependent On A Few Customers
Most of the demand comes from a handful of hyperscalers and AI labs. If they slow spending or struggle to get financing, Nvidia will feel it immediately.
For the last two years, one name has dominated the entire stock market: Nvidia.
It started as a gaming chip company. Today, more than 93% of its money comes from Data Centers. Those are the massive computers that power AI for ChatGPT, Google, Meta, Microsoft, and almost every AI company in the world.
So the big question is simple: Can this growth continue?
What Just Happened
Nvidia just reported the biggest quarter in its history.
Total revenue: $115.8 billion, up 103% from last year
Data Center revenue: $107.6 billion, up 110% from last year
Next quarter guidance: $130 billion
Next year growth forecast: Around 75%
Its new chip, Vera Rubin, made nearly $20 billion in its very first quarter. That is the fastest product launch in Nvidia's history.
Why Growth Can Continue
1. Demand Is Still Massive
There is a $2.5 trillion backlog of cloud and AI projects waiting to be built. Every one of them needs Nvidia chips.
2. It Is Not Just Big Tech Anymore
Earlier, only Google, Microsoft, and Amazon were buying. Now factories, hospitals, banks, and governments are also building AI centers. That makes demand much wider.
3. New Product Cycle Just Started
Rubin is just beginning. Nvidia expects its CPU business to more than double next year as customers adopt the full Rubin platform.
4. Zero China In The Forecast
Nvidia's guidance assumes zero Data Center revenue from China. So if anything changes there, it would only be upside.
Why Growth Could Slow Down
1. Profit Margins Are Falling
Gross margin fell from 74.8% to a guided 71-72%. Making new chips is getting more expensive, especially memory.
2. Growth Is Slowing On A Weekly Basis
The next quarter includes an extra week. After adjusting for that, growth is closer to 4% quarter-over-quarter, not 12%.
3. Too Dependent On A Few Customers
Most of the demand comes from a handful of hyperscalers and AI labs. If they slow spending or struggle to get financing, Nvidia will feel it immediately.
632
·
--
#Binance #Qafila #JoinMyQafila #Crypto #FreeReward #USDC #EarnTogether@everyone
Join my Qafila: Share $500,000 together!
Binance is giving away $500,000 in USDC. I already joined, now it's your turn. It's totally FREE.
Just click the link below, join and unlock your Lamp.
The more friends join, the more reward we all get.
https://www.binance.com/referral/mystery-box/join-my-qafila/claim?ref=A8GILQPI&utm_medium=app_share_link_whatsapp
Hurry up, only 14 days left!
97,595 people already joined. Don't miss out.
#Binance #Qafila #JoinMyQafila #Crypto #FreeReward #USDC #EarnTogether@everyone
Join my Qafila: Share $500,000 together!
Binance is giving away $500,000 in USDC. I already joined, now it's your turn. It's totally FREE.
Just click the link below, join and unlock your Lamp.
The more friends join, the more reward we all get.
https://www.binance.com/referral/mystery-box/join-my-qafila/claim?ref=A8GILQPI&utm_medium=app_share_link_whatsapp
Hurry up, only 14 days left!
97,595 people already joined. Don't miss out.
Join my Qafila: Share $500,000 together!
Binance is giving away $500,000 in USDC. I already joined, now it's your turn. It's totally FREE.
Just click the link below, join and unlock your Lamp.
The more friends join, the more reward we all get.
https://www.binance.com/referral/mystery-box/join-my-qafila/claim?ref=A8GILQPI&utm_medium=app_share_link_whatsapp
Hurry up, only 14 days left!
97,595 people already joined. Don't miss out.
58
·
--
#Binance #Qafila #JoinMyQafila #Crypto #FreeReward #USDC #EarnTogether@everyone
Join my Qafila: Share $500,000 together!
Binance is giving away $500,000 in USDC. I already joined, now it's your turn. It's totally FREE.
Just click the link below, join and unlock your Lamp.
The more friends join, the more reward we all get.
https://www.binance.com/referral/mystery-box/join-my-qafila/claim?ref=A8GILQPI&utm_medium=app_share_link_whatsapp
Hurry up, only 14 days left!
97,595 people already joined. Don't miss out.
#Binance #Qafila #JoinMyQafila #Crypto #FreeReward #USDC #EarnTogether@everyone
Join my Qafila: Share $500,000 together!
Binance is giving away $500,000 in USDC. I already joined, now it's your turn. It's totally FREE.
Just click the link below, join and unlock your Lamp.
The more friends join, the more reward we all get.
https://www.binance.com/referral/mystery-box/join-my-qafila/claim?ref=A8GILQPI&utm_medium=app_share_link_whatsapp
Hurry up, only 14 days left!
97,595 people already joined. Don't miss out.
Join my Qafila: Share $500,000 together!
Binance is giving away $500,000 in USDC. I already joined, now it's your turn. It's totally FREE.
Just click the link below, join and unlock your Lamp.
The more friends join, the more reward we all get.
https://www.binance.com/referral/mystery-box/join-my-qafila/claim?ref=A8GILQPI&utm_medium=app_share_link_whatsapp
Hurry up, only 14 days left!
97,595 people already joined. Don't miss out.
68
·
--
{future}(BTCUSDT)
BTC Bounce From Morning Low - What Next?
BTC bounced from this morning low of $62,006 to $64,943 ✅
Buyers are back. Sellers are tired.
If BTC holds above $64,500, next target is $66,000 - $67,276.
If it breaks $62,000 again, then it can go down.
What do you think? BTC up or down?
#BTC #Bitcoin
BTC Bounce From Morning Low - What Next?
BTC bounced from this morning low of $62,006 to $64,943 ✅
Buyers are back. Sellers are tired.
If BTC holds above $64,500, next target is $66,000 - $67,276.
If it breaks $62,000 again, then it can go down.
What do you think? BTC up or down?
#BTC #Bitcoin
BTC bounced from this morning low of $62,006 to $64,943 ✅
Buyers are back. Sellers are tired.
If BTC holds above $64,500, next target is $66,000 - $67,276.
If it breaks $62,000 again, then it can go down.
What do you think? BTC up or down?
#BTC #Bitcoin
130
·
--
Article
Get 100 USDC Voucher from BinanceGot 100 USDC Trading Fee Voucher from Binance ✅
Free for everyone. Claim yours before 16 Dec.
Claim here 👇
[https://www.binance.com/activity/community-appreciation?ref=1289302405](https://www.binance.com/activity/community-appreciation?ref=1289302405)
#Binance
Get 100 USDC Voucher from Binance
Got 100 USDC Trading Fee Voucher from Binance ✅
Free for everyone. Claim yours before 16 Dec.
Claim here 👇
https://www.binance.com/activity/community-appreciation?ref=1289302405
#Binance
Free for everyone. Claim yours before 16 Dec.
Claim here 👇
https://www.binance.com/activity/community-appreciation?ref=1289302405
#Binance
3
·
--
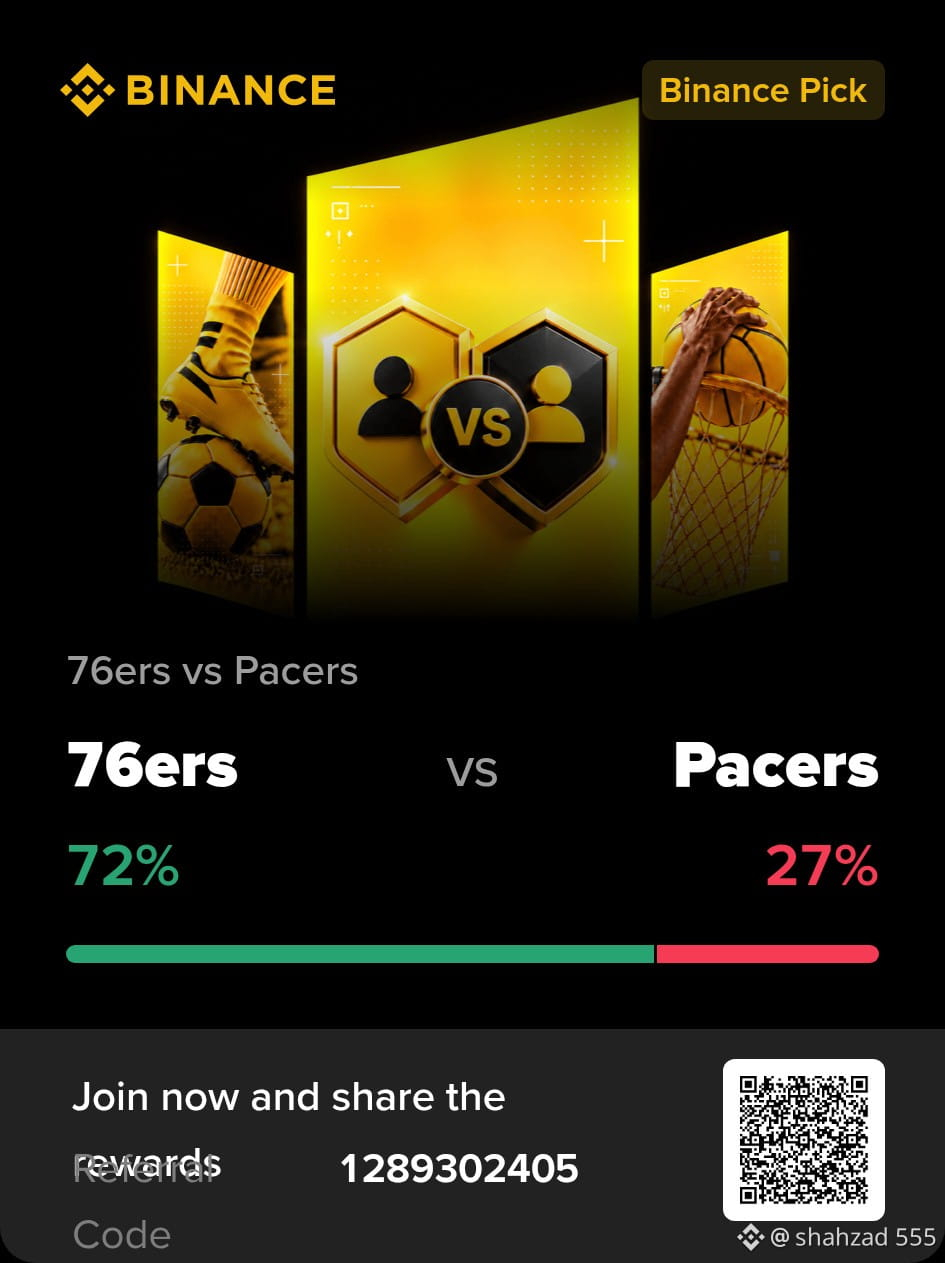
#BinancePick I am loving Binance Pick! Making predictions every day and enjoying the season. #BinancePick
#BinancePick I am loving Binance Pick! Making predictions every day and enjoying the season. #BinancePick

·
--
$
$
S H A N T O_ K H A N
·
--
💫💥 LUCKY GIVEAWAY – WIN 10 USDT! 💥🎁
🎁 Want to Win FREE USDT? 😍
💫 I'm giving away $10 gifts to a few lucky winners! All you have to do is Follow & Repost to get a chance to win! 🎁
🔥 How to Enter:
💬 Comment YES
❤️ Like
🔁 Repost
➕ Follow
🍀 Good Luck, Everyone! 💫❤️
#Crypto #USDT #Giveaway #CryptoGiveaway #GiveawayRedPacket
🎁 Want to Win FREE USDT? 😍
💫 I'm giving away $10 gifts to a few lucky winners! All you have to do is Follow & Repost to get a chance to win! 🎁
🔥 How to Enter:
💬 Comment YES
❤️ Like
🔁 Repost
➕ Follow
🍀 Good Luck, Everyone! 💫❤️
#Crypto #USDT #Giveaway #CryptoGiveaway #GiveawayRedPacket
1
2
·
--
https://www.binance.com/activity/word-of-the-day/Choose-Your-Binance-AI?ref=CPA_00DJ619P8L&utm_medium=web_share_copy
https://www.binance.com/activity/word-of-the-day/Choose-Your-Binance-AI?ref=CPA_00DJ619P8L&utm_medium=web_share_copy
2
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
BTCRemainsUnderPressureAfterHawkishFOMCMinutes
40,497 views
562 Discussing
FOMC Minutes | Fed Minutes Show Almost All Officials Expect More Rate Hikes, With Some Open to a Larger December Move
Binance News
·46 Likes
·55.5k views
AnthropicToDebutAfter$83IPOPricing
10,898 views
63 Discussing
NvidiaBoardReportedlySplitOverHuang’sReturn
13,335 views
224 Discussing