

cryptotradehead
8.8k Posts
cryptotradehead
Report
Block User
backtesting, analyse, how to use AI for trading - can you be a good trader?
Open Trade
High-Frequency Trader
4.8 Years
7 Following
2.6K+ Followers
5.0K+ Liked
Posts
Portfolio
All
Quotes
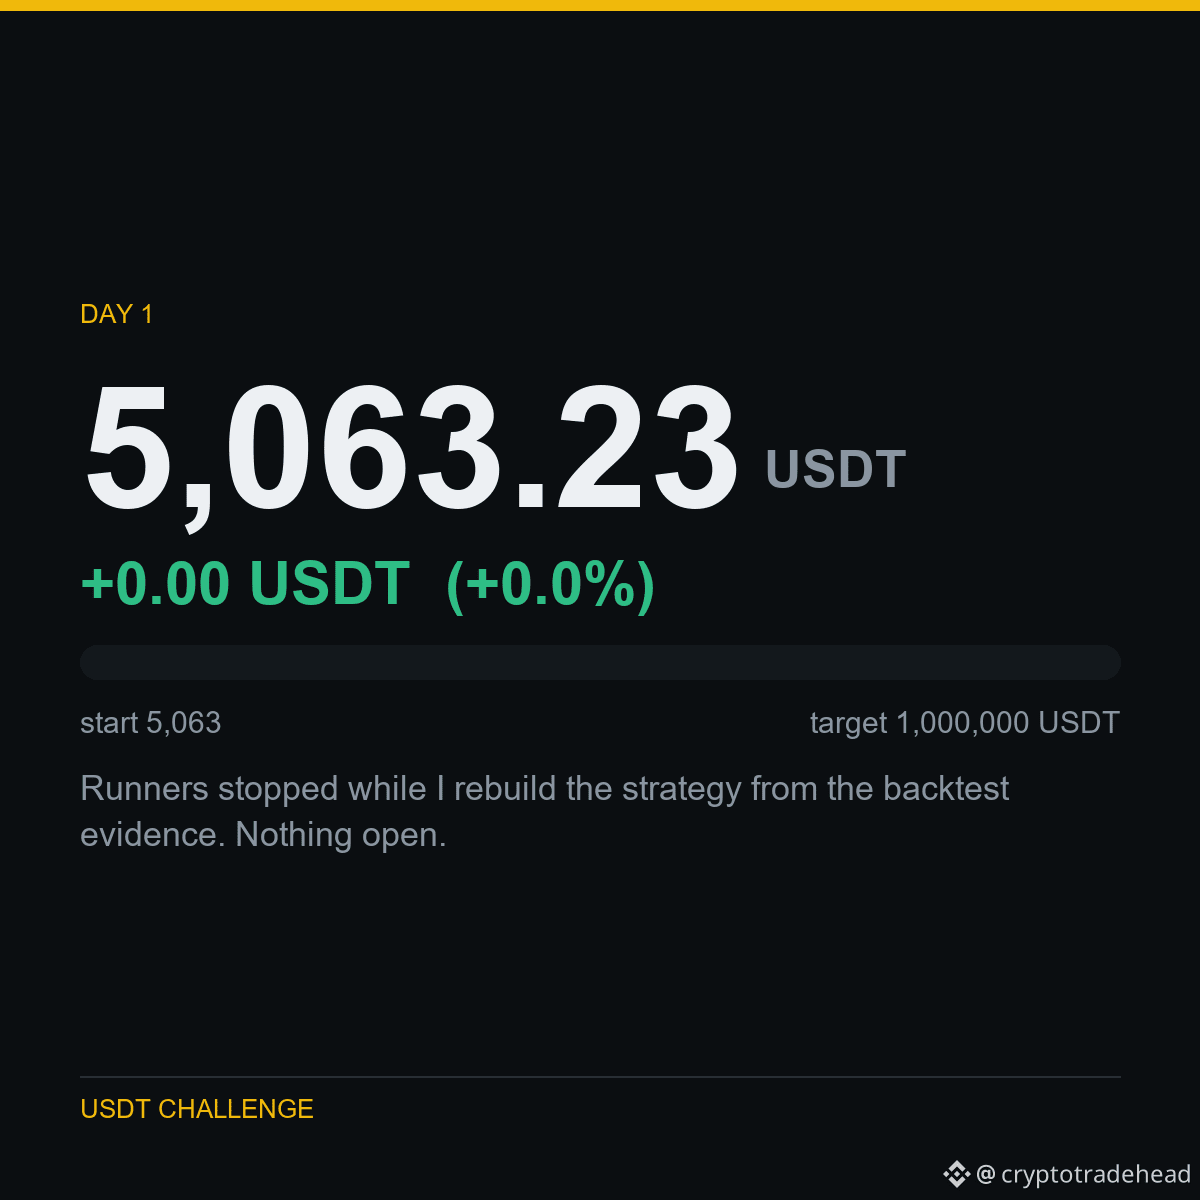
DAY 1 - 5,063 USDT to 1,000,000 USDT
Balance: 5,063.23 USDT
Change: +0.00 USDT (+0.0%)
Runners stopped while I rebuild the strategy from the backtest evidence. Nothing open.
Running on a Binance testnet account, so this is demo capital - I would rather say that than let you assume otherwise. The strategy, the costs and the losses are all real.
No signals for sale, no course, no affiliate link. Just the account and the data behind it.
Traded in this challenge: $BTC $SOL $AVAX
#Binance #USDT #Futures #TradingChallenge #Crypto
Article
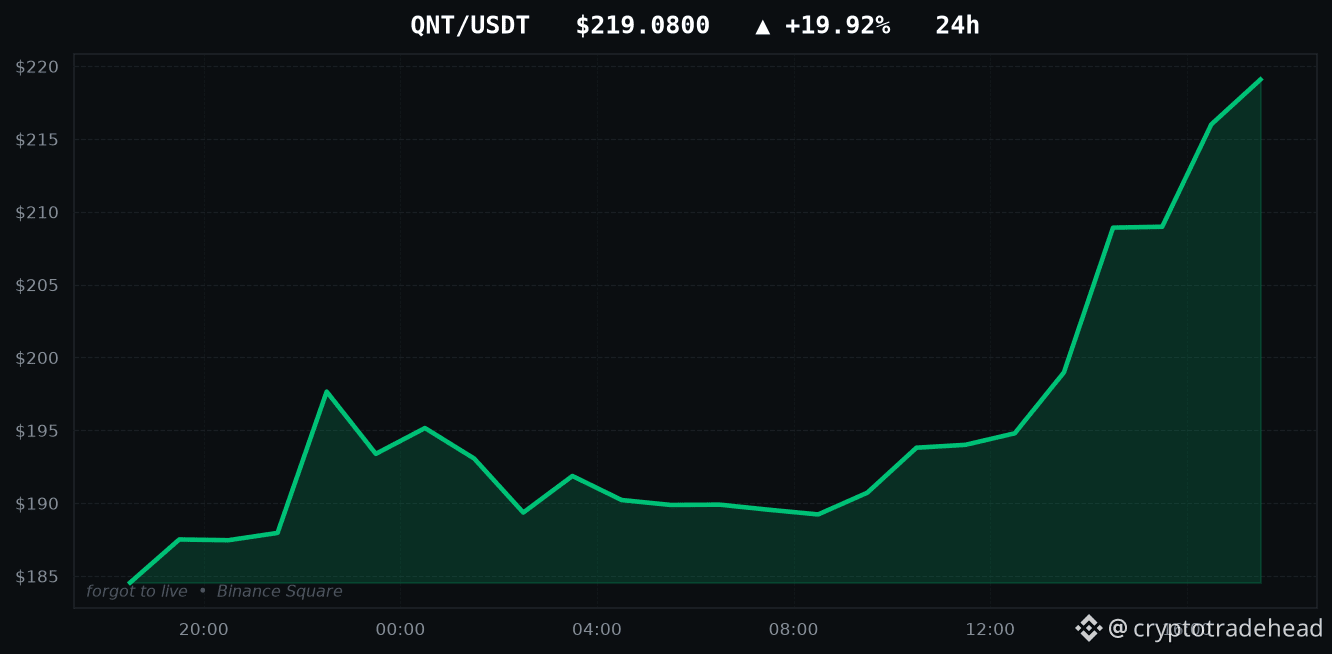
QNT is up +19.92% - I tested both ways to trade itTODAY'S TOP GAINERS
QNT: +19.92%
BANK: +18.22%
ERA: +14.65%
KAT: +13.50%
BEAMX: +12.65%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like QNT's +19.92%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $QNT $BANK $ERA
#Binance #Altcoins #Futures #QNT #CryptoData
QNT is up +19.92% - I tested both ways to trade it
TODAY'S TOP GAINERS
QNT: +19.92%
BANK: +18.22%
ERA: +14.65%
KAT: +13.50%
BEAMX: +12.65%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like QNT's +19.92%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $QNT $BANK $ERA
#Binance #Altcoins #Futures #QNT #CryptoData
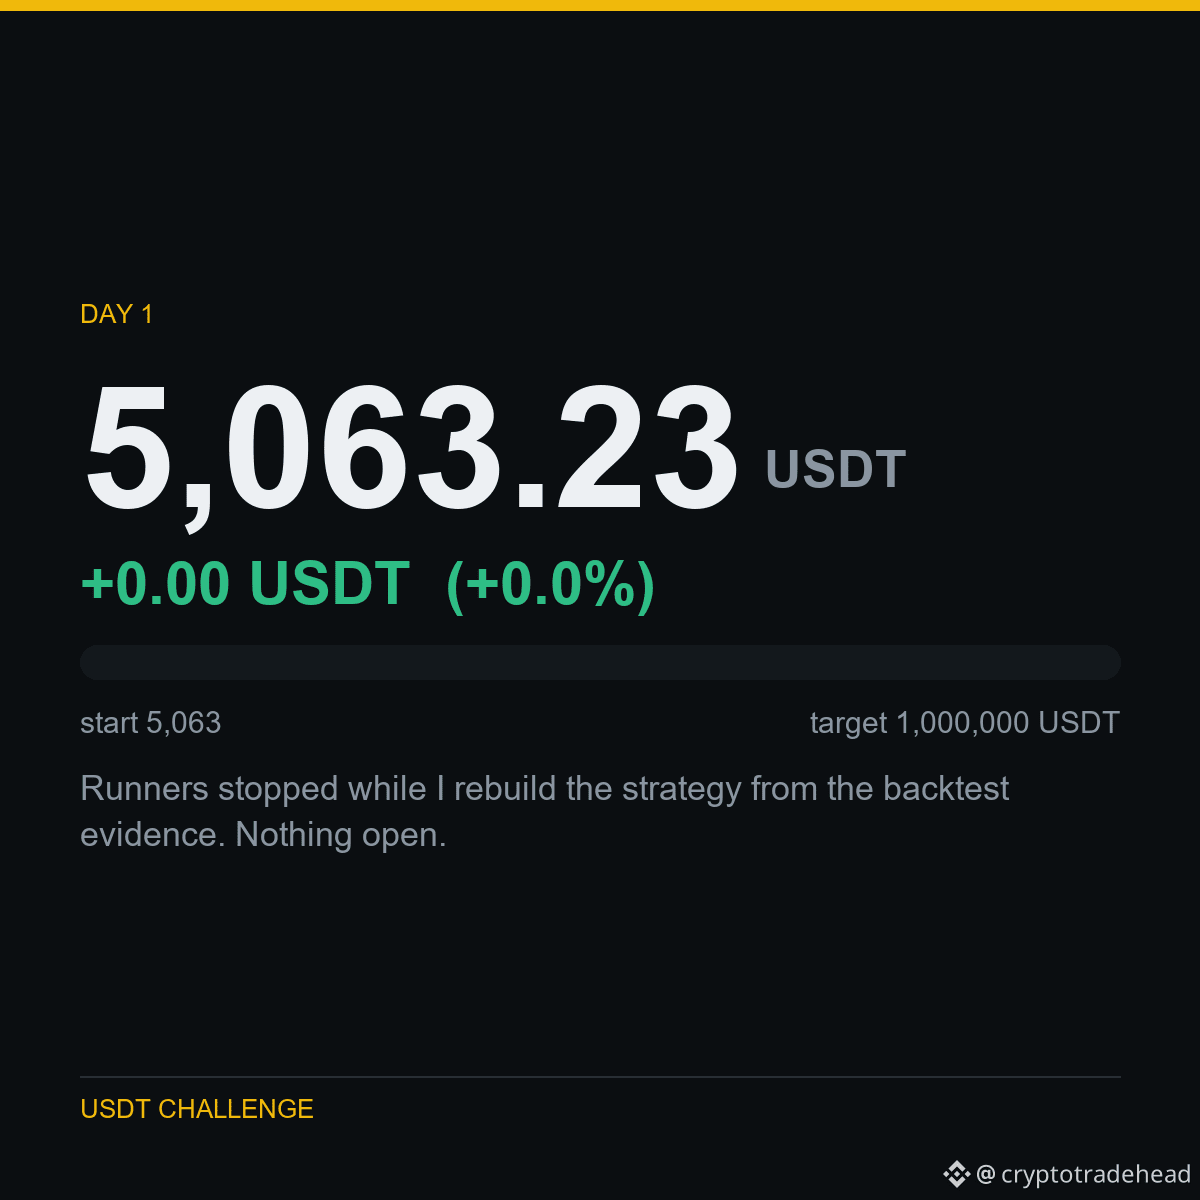
DAY 1 - 5,063 USDT to 1,000,000 USDT
Balance: 5,063.23 USDT
Change: +0.00 USDT (+0.0%)
Runners stopped while I rebuild the strategy from the backtest evidence. Nothing open.
Running on a Binance testnet account, so this is demo capital - I would rather say that than let you assume otherwise. The strategy, the costs and the losses are all real.
No signals for sale, no course, no affiliate link. Just the account and the data behind it.
Traded in this challenge: $BTC $SOL $AVAX
#Binance #USDT #Futures #TradingChallenge #Crypto
3
Article
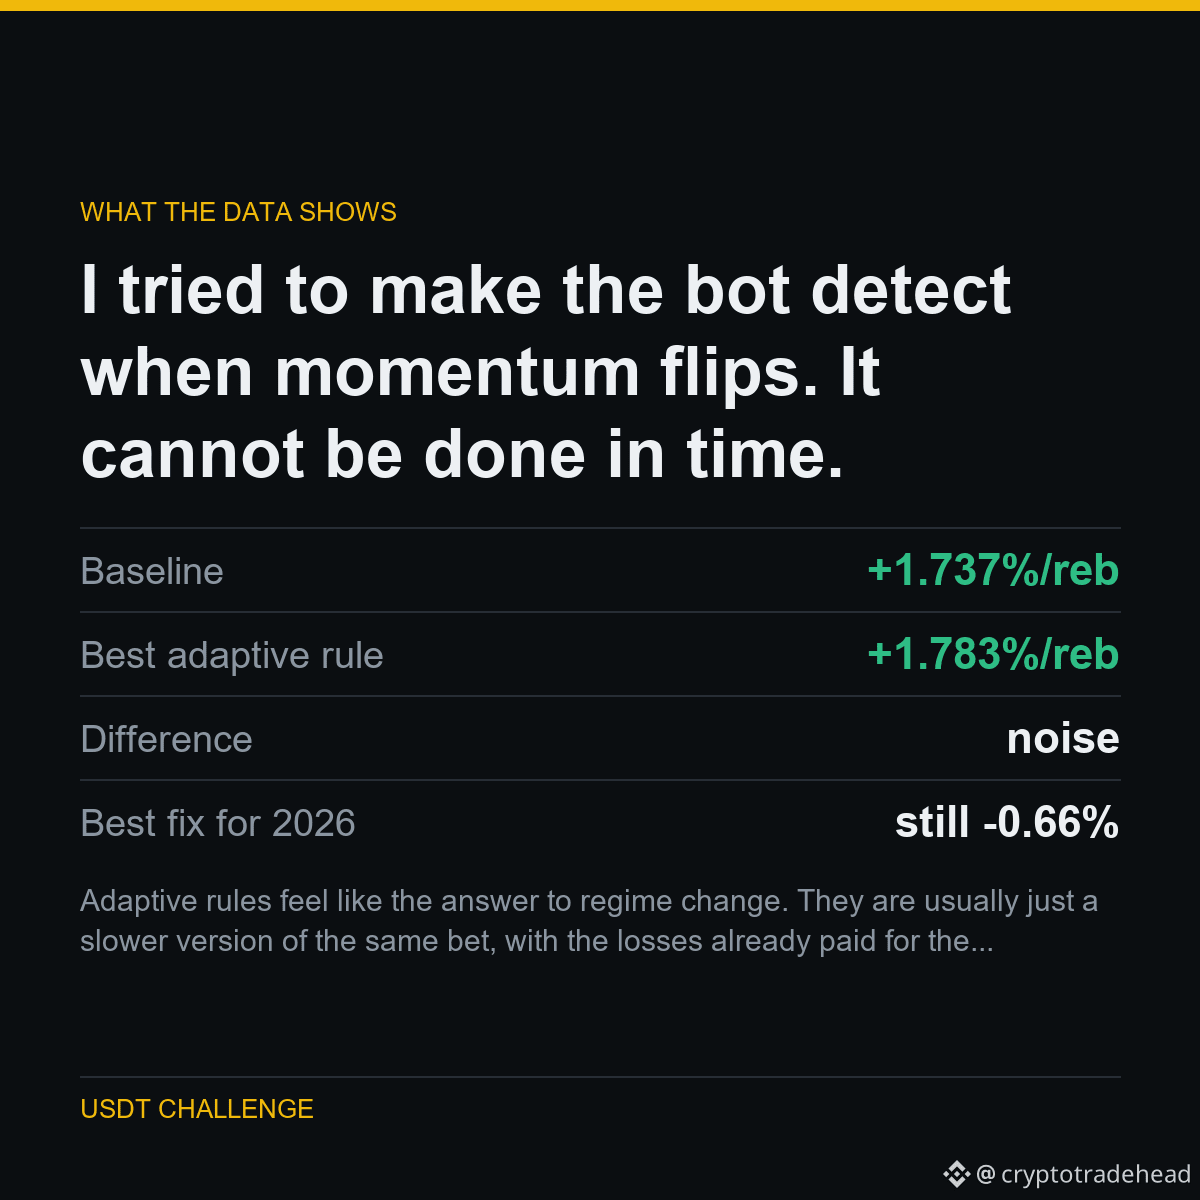
I tried to make the bot detect when momentum flips. It cannot be done in time.I tried to make the bot detect when momentum flips. It cannot be done in time.
Momentum inverted in 2026. The obvious fix: watch recent performance, and flip to the opposite rule when momentum stops paying.
I tested that over six different lookback windows. The best one returned +1.783% per rebalance against a +1.737% baseline - a difference indistinguishable from noise. Every other window was worse. None repaired 2026.
The reason is simple: by the time trailing performance tells you the regime flipped, you have already taken the losses that told you.
WHAT IT MEANS
Adaptive rules feel like the answer to regime change. They are usually just a slower version of the same bet, with the losses already paid for the signal.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $SOL $BTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
I tried to make the bot detect when momentum flips. It cannot be done in time.
I tried to make the bot detect when momentum flips. It cannot be done in time.
Momentum inverted in 2026. The obvious fix: watch recent performance, and flip to the opposite rule when momentum stops paying.
I tested that over six different lookback windows. The best one returned +1.783% per rebalance against a +1.737% baseline - a difference indistinguishable from noise. Every other window was worse. None repaired 2026.
The reason is simple: by the time trailing performance tells you the regime flipped, you have already taken the losses that told you.
WHAT IT MEANS
Adaptive rules feel like the answer to regime change. They are usually just a slower version of the same bet, with the losses already paid for the signal.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $SOL $BTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
1
Article
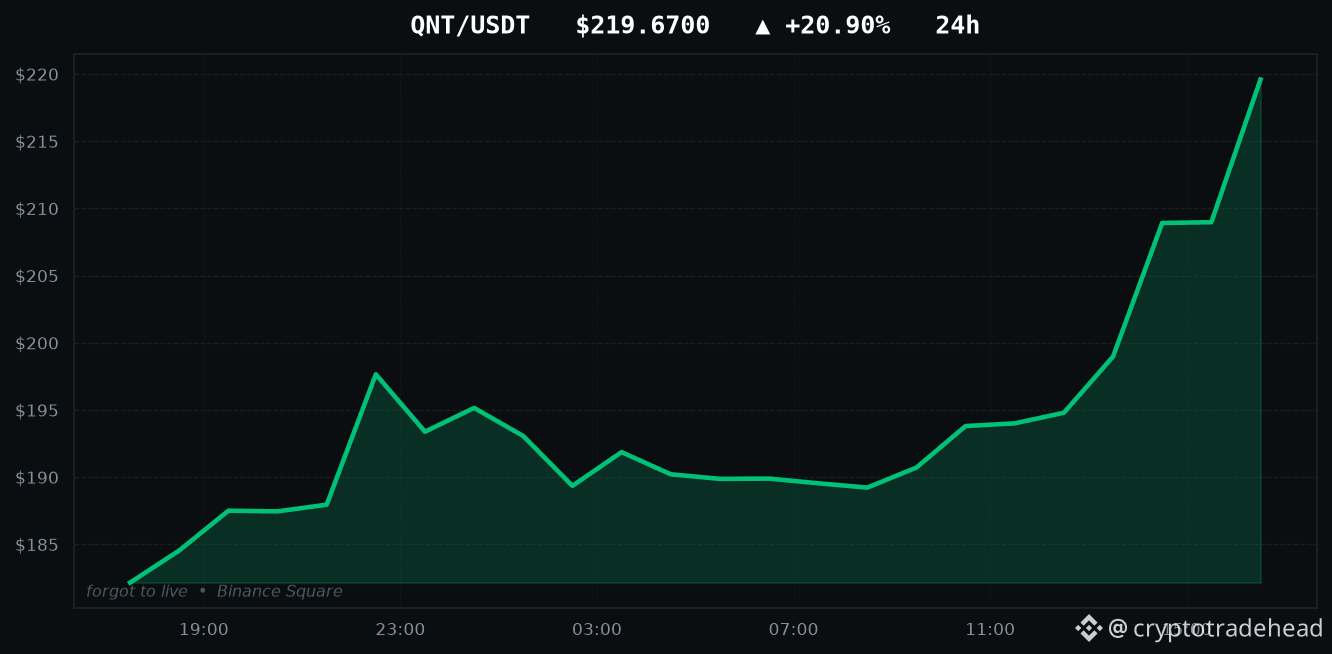
QNT is up +20.90% - I tested both ways to trade itTODAY'S TOP GAINERS
QNT: +20.90%
ERA: +14.61%
OSMO: +13.41%
KAT: +13.35%
NOM: +12.10%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like QNT's +20.90%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $QNT $ERA $OSMO
#Binance #Altcoins #Futures #QNT #CryptoData
QNT is up +20.90% - I tested both ways to trade it
TODAY'S TOP GAINERS
QNT: +20.90%
ERA: +14.61%
OSMO: +13.41%
KAT: +13.35%
NOM: +12.10%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like QNT's +20.90%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $QNT $ERA $OSMO
#Binance #Altcoins #Futures #QNT #CryptoData
5
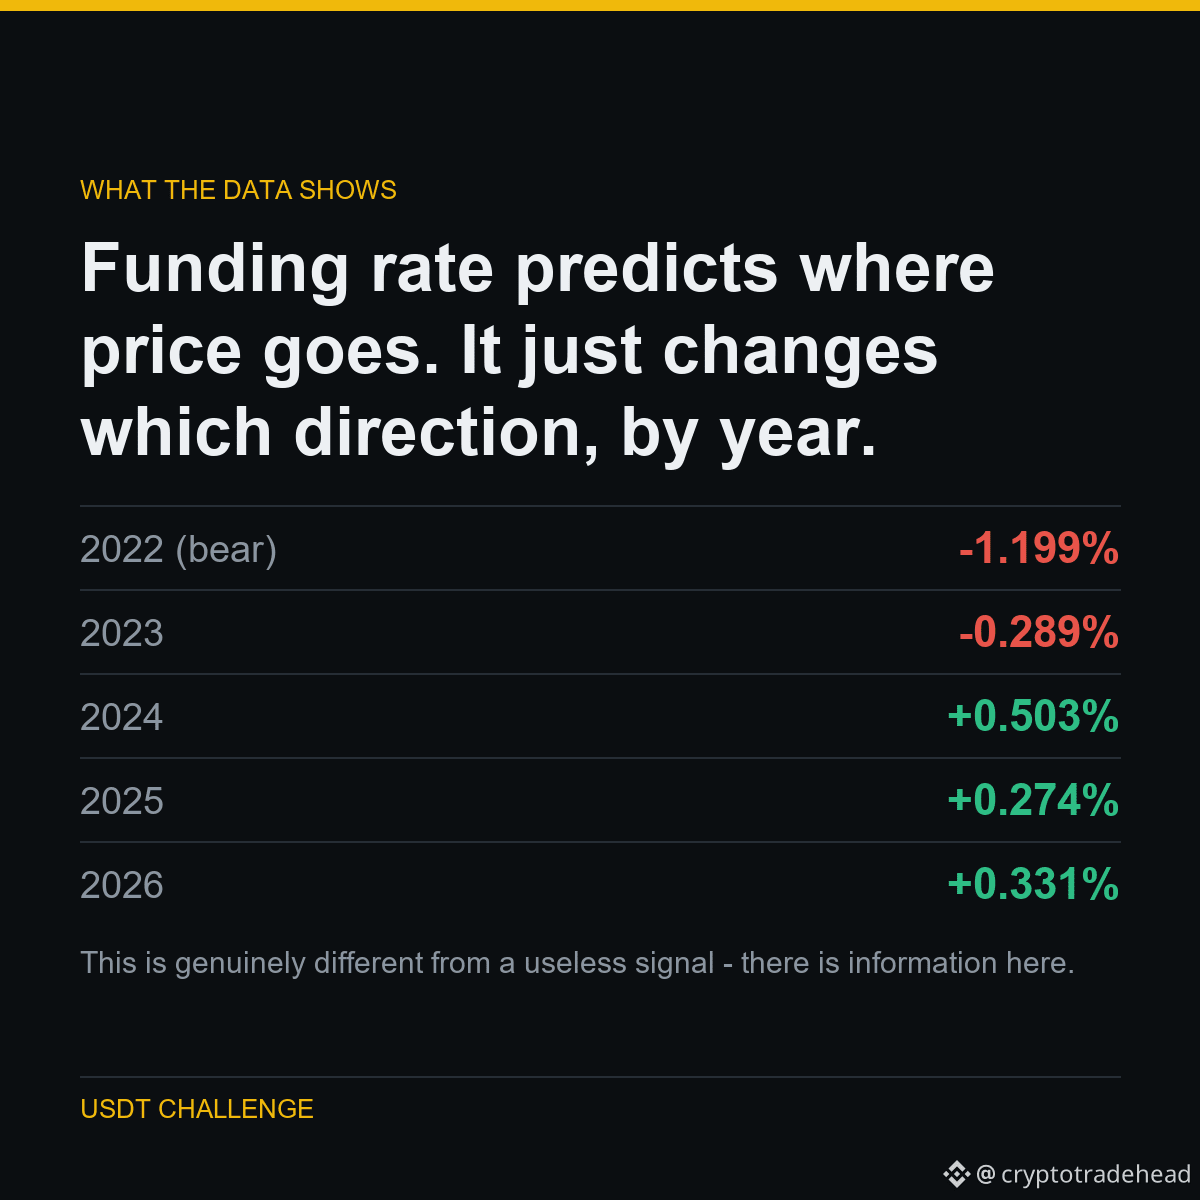
This is genuinely different from a useless signal - there is information here. But to use it you would need to know the regime in advance, which is the same circular problem that kills everything else.
Here is what that came from.
Funding rate predicts where price goes. It just changes which direction, by year.
I sorted every funding print into quintiles and measured the forward 72-hour return of the highest versus the lowest.
In bear markets, high funding preceded WORSE returns - crowded longs getting squeezed. From 2024 onward it preceded BETTER returns - momentum.
The signal is real. The sign is not stable. Average it across all years and you get -0.08%, below the 0.240% it costs to trade.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $ETH $DOGE
#Binance #Futures #Backtesting #TradingBot #CryptoData
3
Crypto falls faster than it rises - liquidation cascades are asymmetric. That is documented market structure, which is why this result is more believable than one that only works when everything goes up.
Here is what that came from.
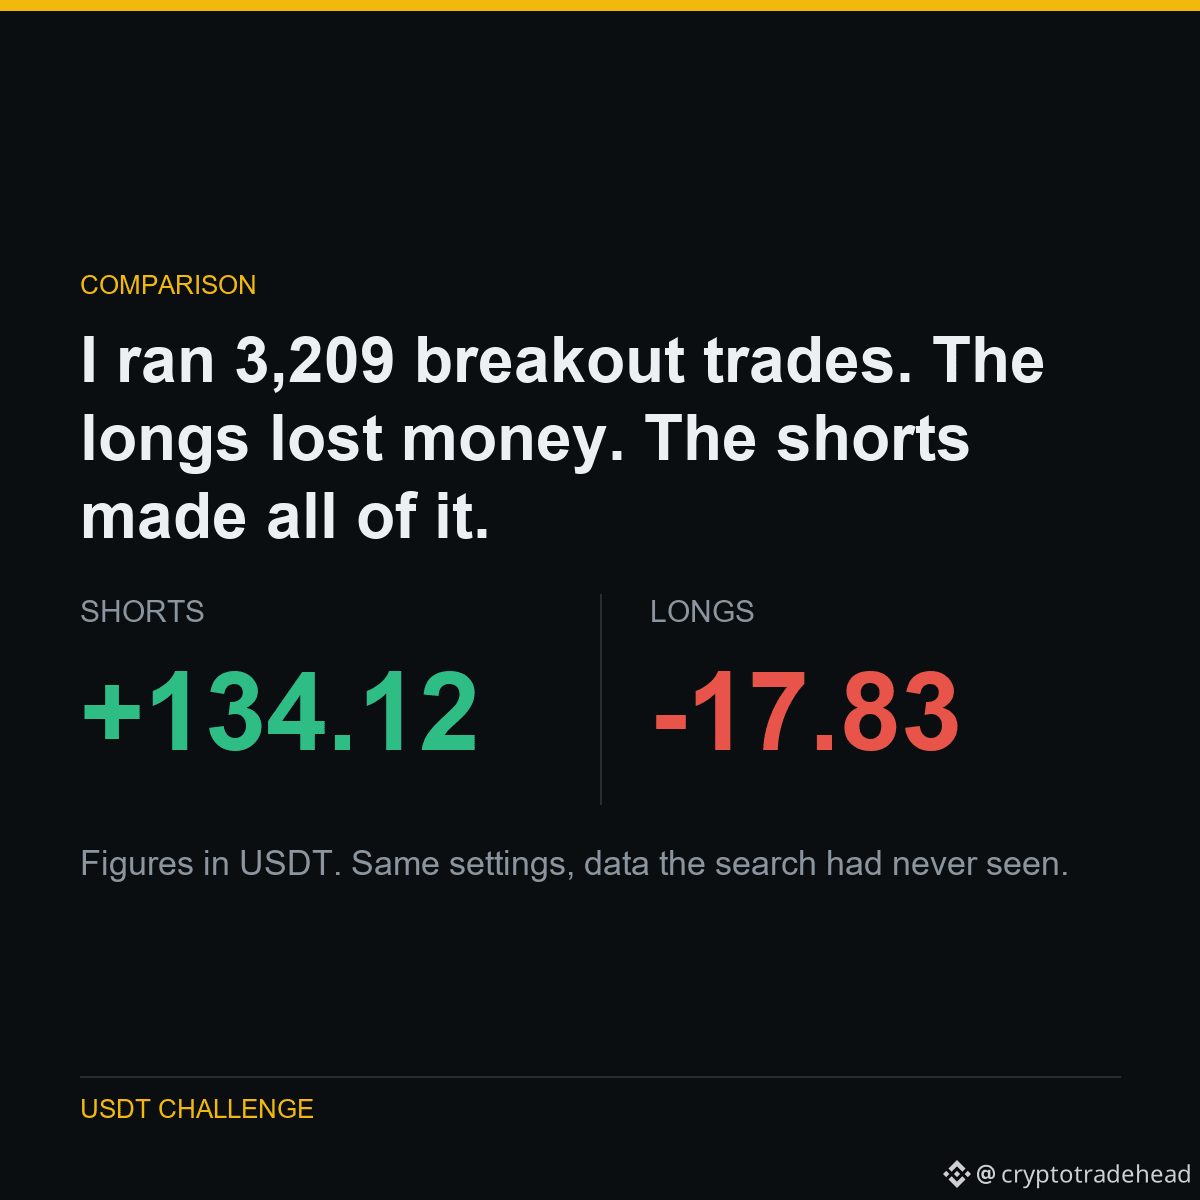
I ran 3,209 breakout trades. The longs lost money. The shorts made all of it.
Donchian 20 channel, ATR stop, 10 symbols, four and a half years.
If this were just riding a bull market, the longs would be the winners. They are not - they are negative.
The shorts even made money on coins that ROSE over the period. BTC gained 94% buy-and-hold, and shorting its breakdowns still returned +22.83 USDT. XRP gained 87%, shorts returned +24.27 USDT.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $XRP $LTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
2
Article
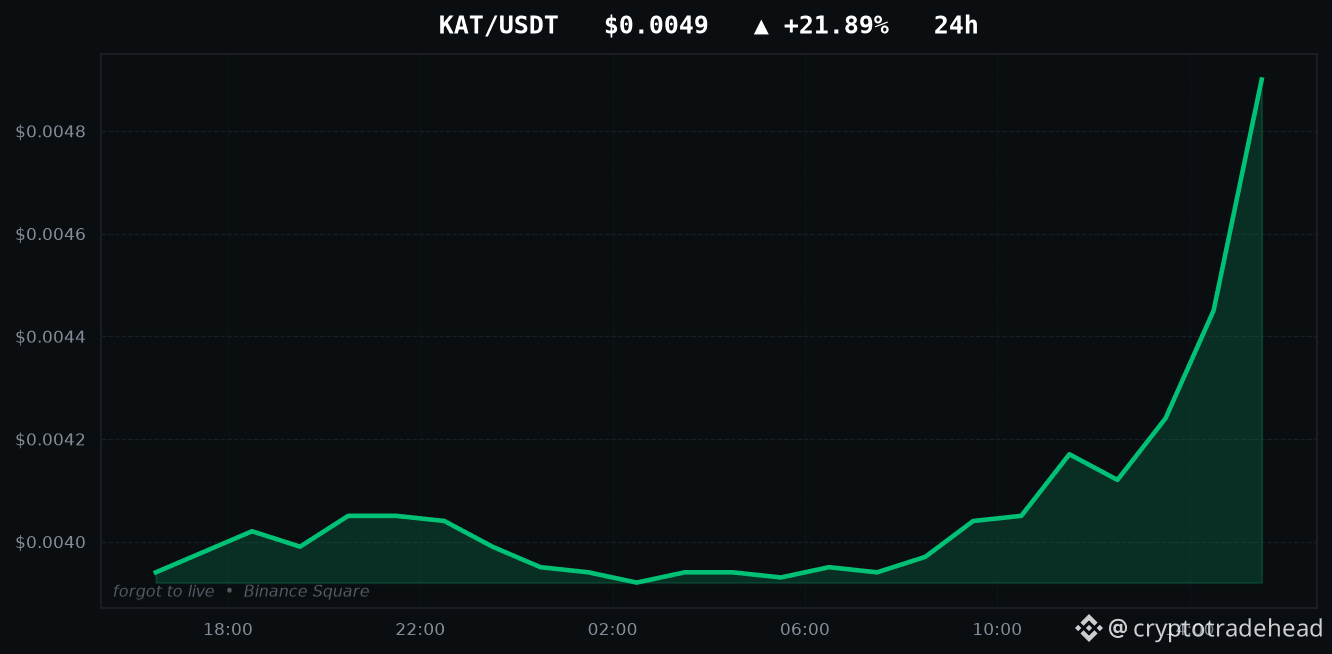
KAT is up +21.89% - I tested both ways to trade itTODAY'S TOP GAINERS
KAT: +21.89%
OSMO: +20.09%
ERA: +19.41%
QNT: +16.44%
NIL: +12.29%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like KAT's +21.89%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $KAT $OSMO $ERA
#Binance #Altcoins #Futures #KAT #CryptoData
KAT is up +21.89% - I tested both ways to trade it
TODAY'S TOP GAINERS
KAT: +21.89%
OSMO: +20.09%
ERA: +19.41%
QNT: +16.44%
NIL: +12.29%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like KAT's +21.89%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $KAT $OSMO $ERA
#Binance #Altcoins #Futures #KAT #CryptoData
2
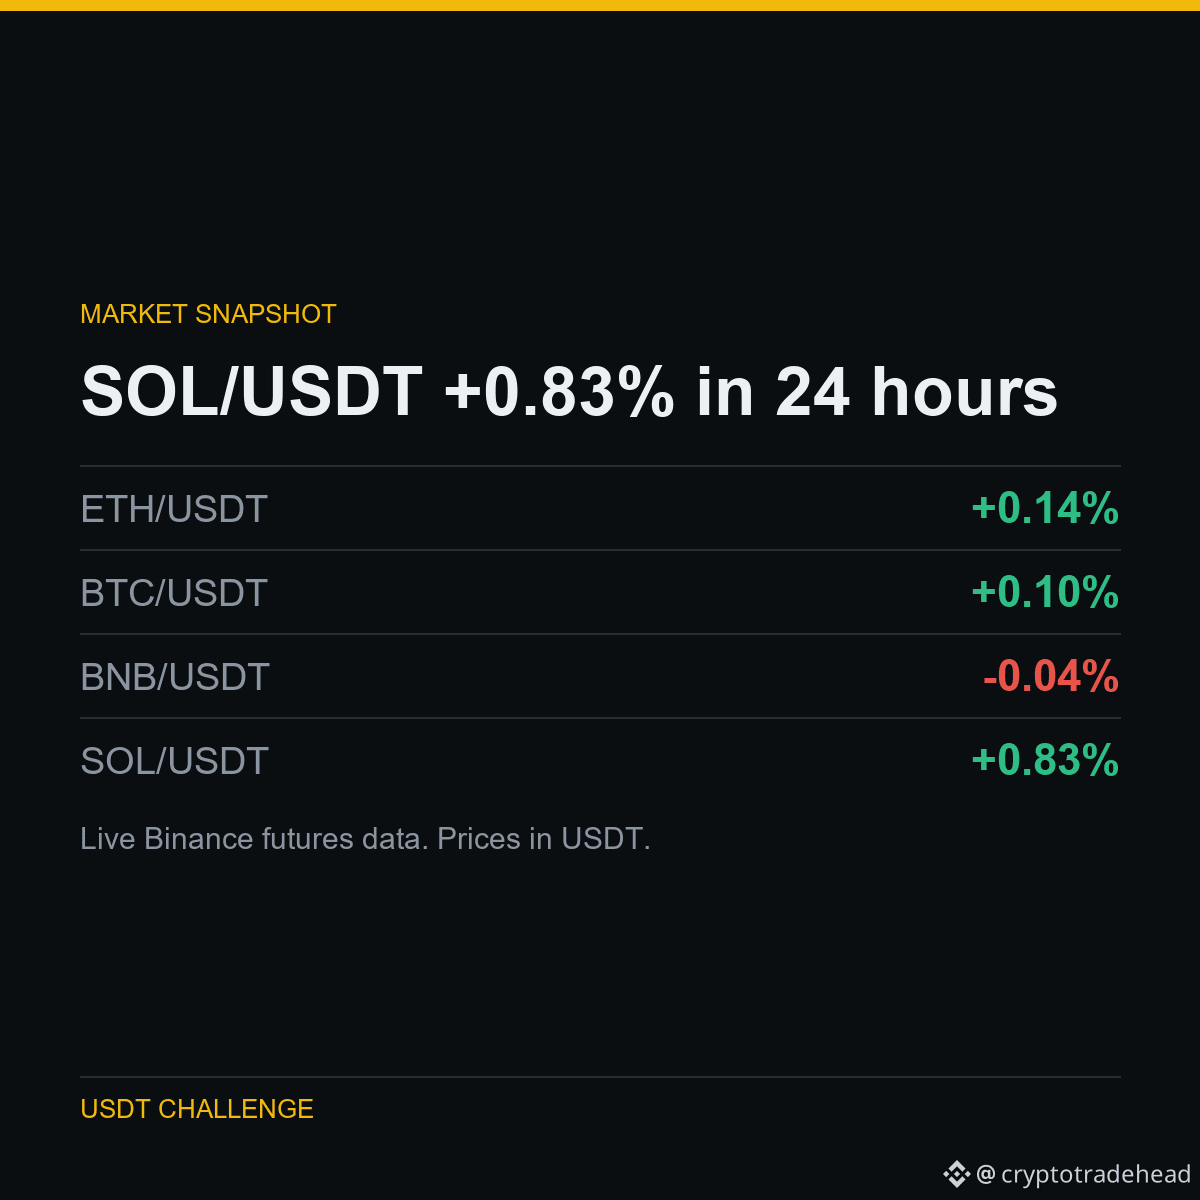
24-HOUR SNAPSHOT
ETH/USDT: 2,330.38 USDT (+0.14%)
BTC/USDT: 80,382.60 USDT (+0.10%)
BNB/USDT: 738.72 USDT (-0.04%)
SOL/USDT: 101.51 USDT (+0.83%)
Funding on SOL/USDT is +0.0100% per 8h.
Context, not a call: I do not post entries or targets. Everything I trade is logged and published after the fact, wins and losses both.
Covered above: $SOL $ETH $BTC
#Binance #Crypto #Futures #BTC #Altcoins
1
Article
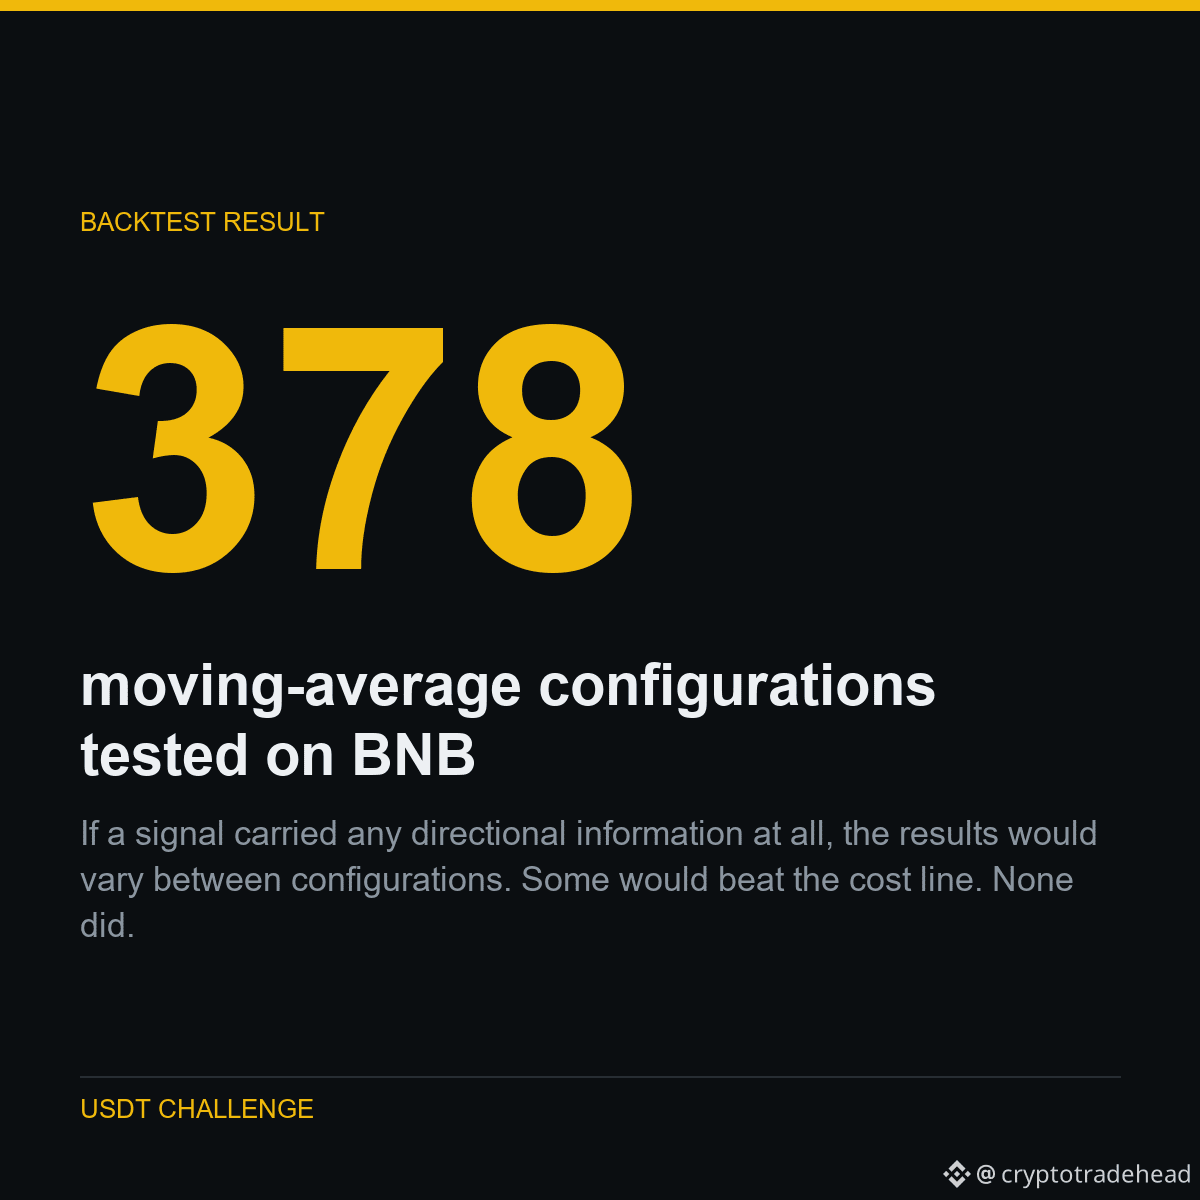
I tested 378 moving-average strategies. Every one lost exactly what it cost to trade.I tested 378 moving-average strategies. Every one lost exactly what it cost to trade.
Two signal families, four timeframes, EMA and SMA, with and without a trend filter, long-only and short-only. 378 combinations in total, all with real fees and real measured slippage applied.
The round-trip cost of a trade is 0.240% of position size. The average result per trade, across every single configuration, landed between -0.361% and -0.401%.
That is the cost, and nothing else.
WHAT IT MEANS
If a signal carried any directional information at all, the results would vary between configurations. Some would beat the cost line. None did. That is not weak edge that needs tuning - it is zero edge being charged an entry fee.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BNB
#Binance #Futures #Backtesting #TradingBot #CryptoData
I tested 378 moving-average strategies. Every one lost exactly what it cost to trade.
I tested 378 moving-average strategies. Every one lost exactly what it cost to trade.
Two signal families, four timeframes, EMA and SMA, with and without a trend filter, long-only and short-only. 378 combinations in total, all with real fees and real measured slippage applied.
The round-trip cost of a trade is 0.240% of position size. The average result per trade, across every single configuration, landed between -0.361% and -0.401%.
That is the cost, and nothing else.
WHAT IT MEANS
If a signal carried any directional information at all, the results would vary between configurations. Some would beat the cost line. None did. That is not weak edge that needs tuning - it is zero edge being charged an entry fee.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BNB
#Binance #Futures #Backtesting #TradingBot #CryptoData
3
Article
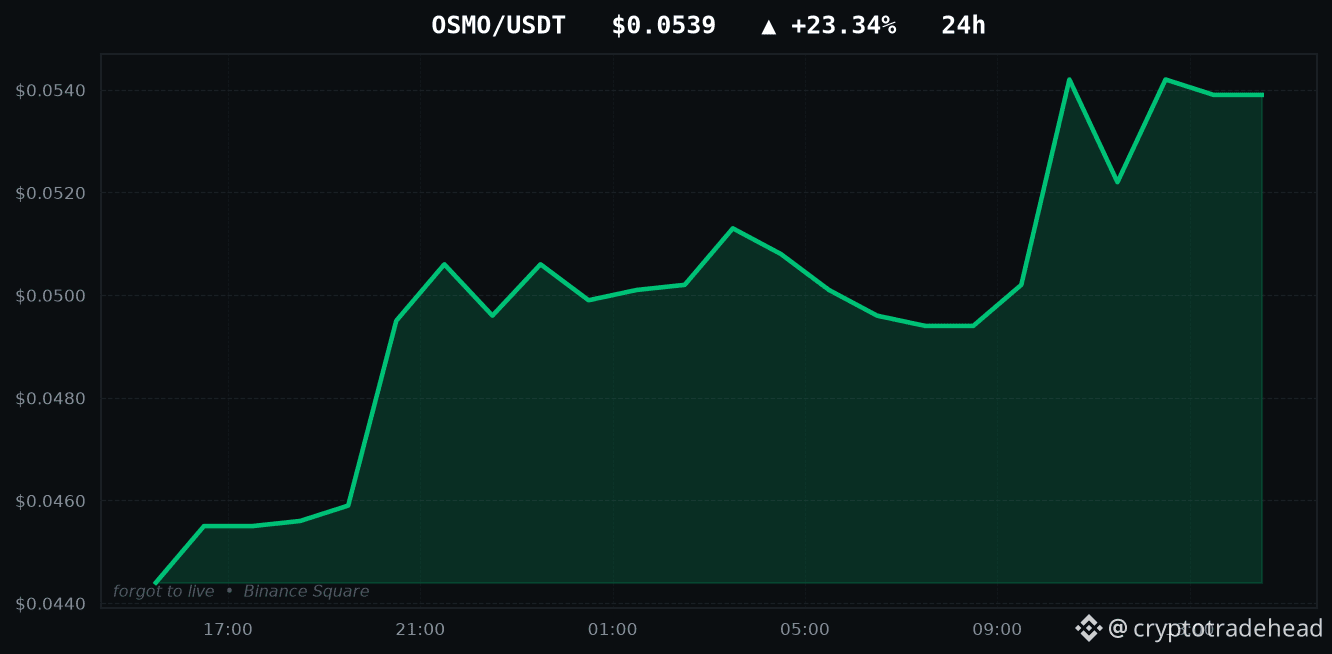
OSMO is up +23.34% - I tested both ways to trade itTODAY'S TOP GAINERS
OSMO: +23.34%
ERA: +19.10%
QNT: +15.85%
KAT: +10.42%
DODO: +10.34%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like OSMO's +23.34%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $OSMO $ERA $QNT
#Binance #Altcoins #Futures #OSMO #CryptoData
OSMO is up +23.34% - I tested both ways to trade it
TODAY'S TOP GAINERS
OSMO: +23.34%
ERA: +19.10%
QNT: +15.85%
KAT: +10.42%
DODO: +10.34%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like OSMO's +23.34%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $OSMO $ERA $QNT
#Binance #Altcoins #Futures #OSMO #CryptoData
10
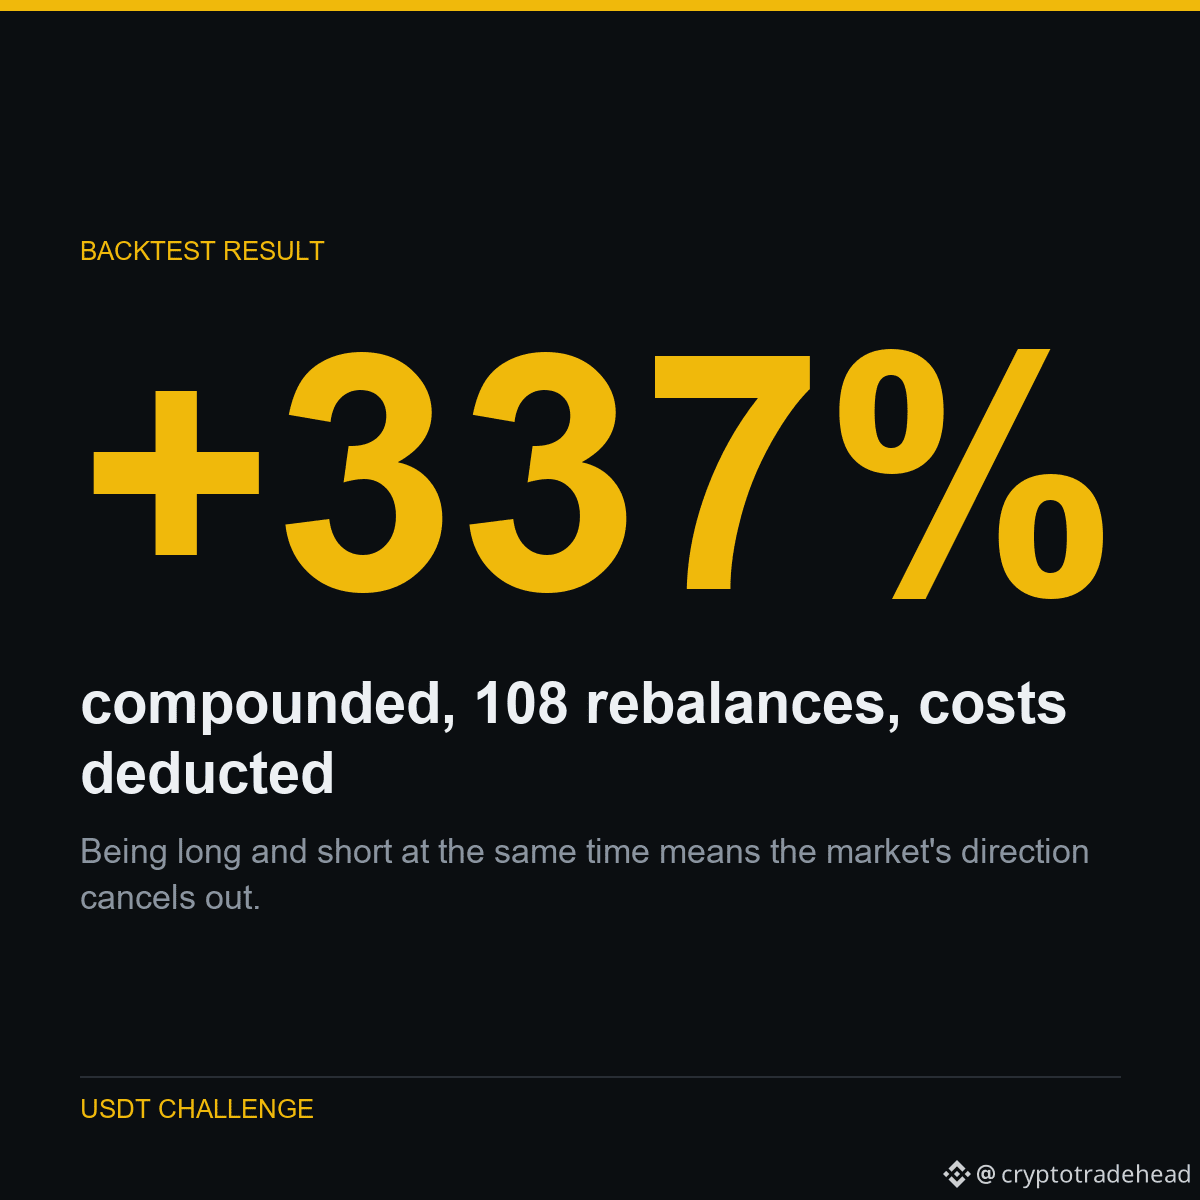
Being long and short at the same time means the market's direction cancels out. What is left is whether the winners keep beating the losers - which is a real question, not a bet on the market going up.
Here is what that came from.
After 378 failures, one strategy finally passed the test that killed all the others.
Rank 45 perpetuals by 5-day return. Long the top 5, short the bottom 5, hold 15 days, rebalance. Equal weight, dollar-neutral.
The out-of-sample control is the one that had destroyed everything before it: fix the settings on old data, then run them on data the search never touched. In-sample +1.711% per rebalance, out-of-sample +1.801%. The mean held.
It also survives costs far worse than real: still +0.48% per rebalance even at a 1.50% round trip, six times what Binance actually charges.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $SOL $BNB $BTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
3
Article
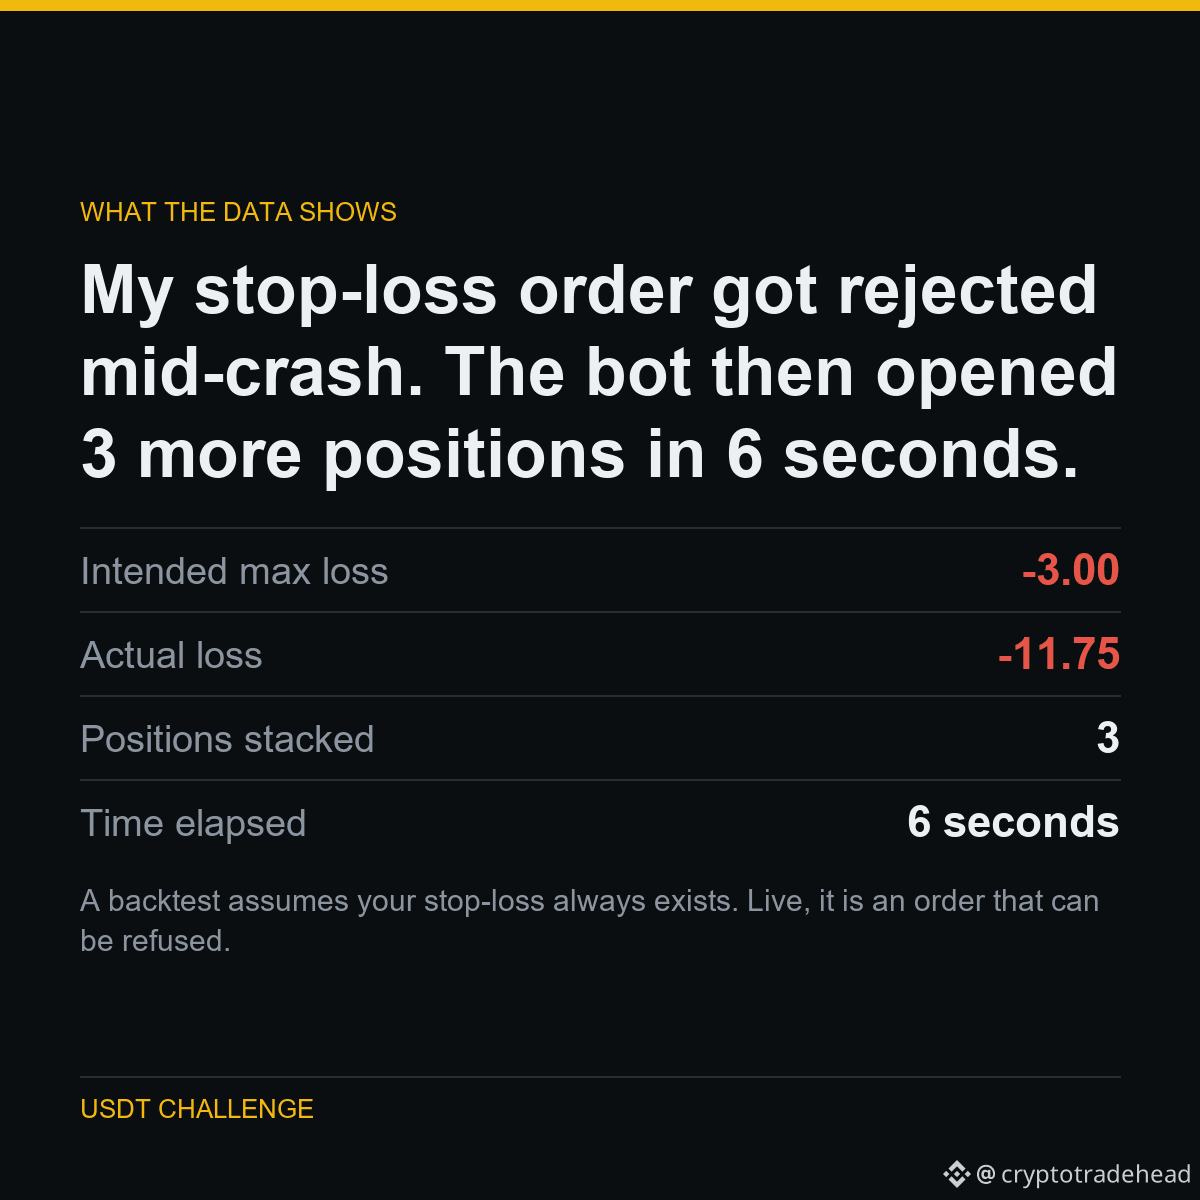
My stop-loss order got rejected mid-crash. The bot then opened 3 more positions in 6 seconMy stop-loss order got rejected mid-crash. The bot then opened 3 more positions in 6 seconds.
During a fast drop, Binance rejected my stop-loss with error -2021: the market had already moved past the trigger price before the order landed.
My code did not handle that rejection. The position stayed open with no stop, and because the bot's own state never recorded it, the next signal opened another position on top. Three times.
Intended risk was 3 USDT. Actual loss was 11.75 USDT.
WHAT IT MEANS
A backtest assumes your stop-loss always exists. Live, it is an order that can be refused. The gap between those two assumptions is where real money goes.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BNB
#Binance #Futures #Backtesting #TradingBot #CryptoData
My stop-loss order got rejected mid-crash. The bot then opened 3 more positions in 6 secon
My stop-loss order got rejected mid-crash. The bot then opened 3 more positions in 6 seconds.
During a fast drop, Binance rejected my stop-loss with error -2021: the market had already moved past the trigger price before the order landed.
My code did not handle that rejection. The position stayed open with no stop, and because the bot's own state never recorded it, the next signal opened another position on top. Three times.
Intended risk was 3 USDT. Actual loss was 11.75 USDT.
WHAT IT MEANS
A backtest assumes your stop-loss always exists. Live, it is an order that can be refused. The gap between those two assumptions is where real money goes.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BNB
#Binance #Futures #Backtesting #TradingBot #CryptoData
10
Article
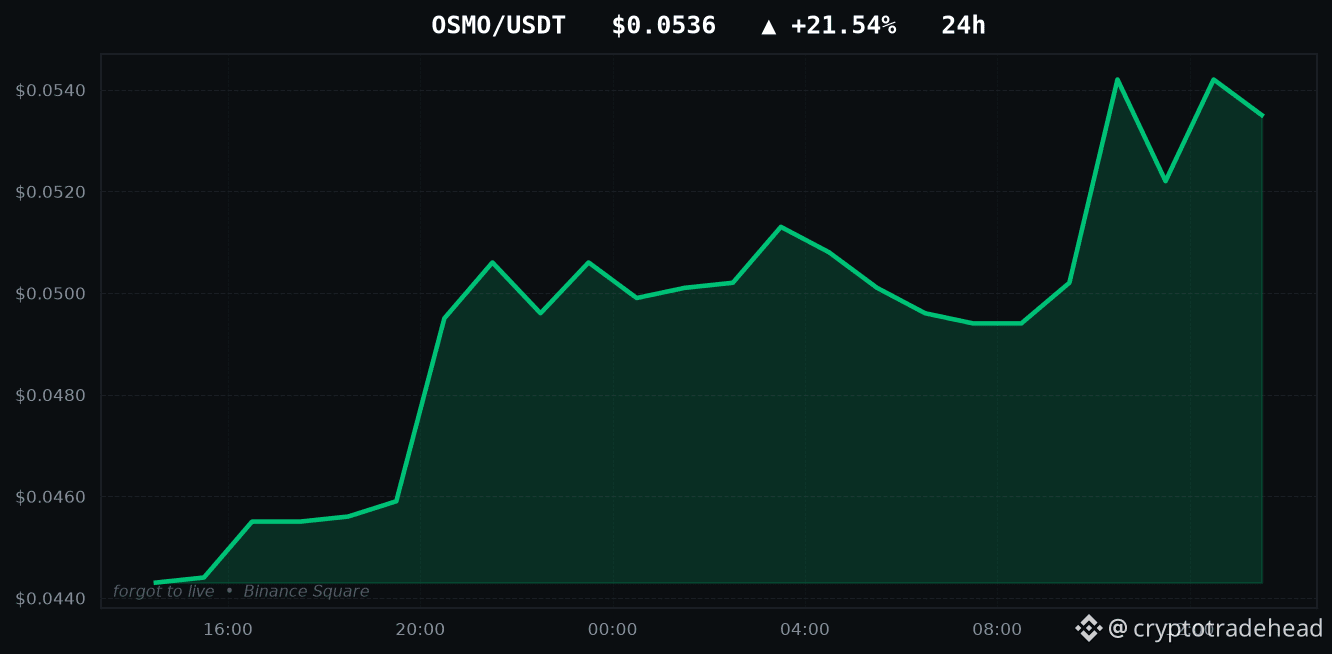
OSMO is up +21.54% - I tested both ways to trade itTODAY'S TOP GAINERS
OSMO: +21.54%
ERA: +17.48%
DODO: +12.41%
WIN: +12.21%
BEAMX: +9.88%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like OSMO's +21.54%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $OSMO $ERA $DODO
#Binance #Altcoins #Futures #OSMO #CryptoData
OSMO is up +21.54% - I tested both ways to trade it
TODAY'S TOP GAINERS
OSMO: +21.54%
ERA: +17.48%
DODO: +12.41%
WIN: +12.21%
BEAMX: +9.88%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like OSMO's +21.54%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $OSMO $ERA $DODO
#Binance #Altcoins #Futures #OSMO #CryptoData
13
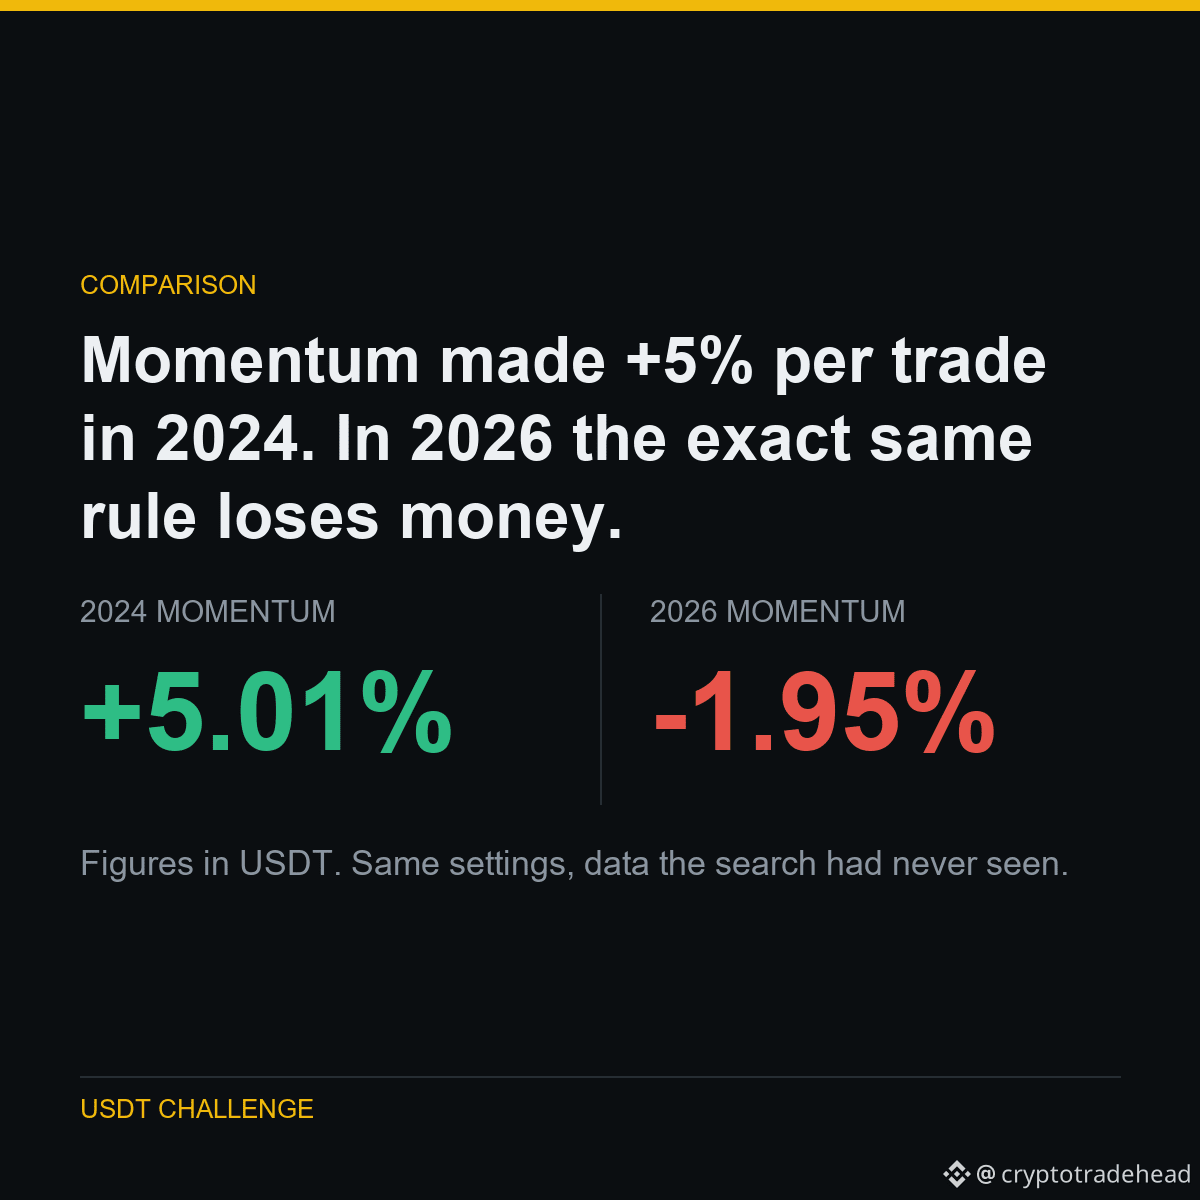
A strategy is not a fact about markets, it is a fact about a period. Anyone showing you a backtest without the year-by-year breakdown is hiding the years that did not work.
Here is what that came from.
Momentum made +5% per trade in 2024. In 2026 the exact same rule loses money.
Same universe, same ranking rule, same holding period, five different years.
2024 and 2025 carried the whole strategy. 2026 is the worst year of the five - a 25% win rate over roughly nine months.
Buying the strongest coins and shorting the weakest has stopped working this year. Doing the opposite would have returned +1.47% per rebalance at a 69% win rate.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $SOL $BTC $ETH
#Binance #Futures #Backtesting #TradingBot #CryptoData
2
Article
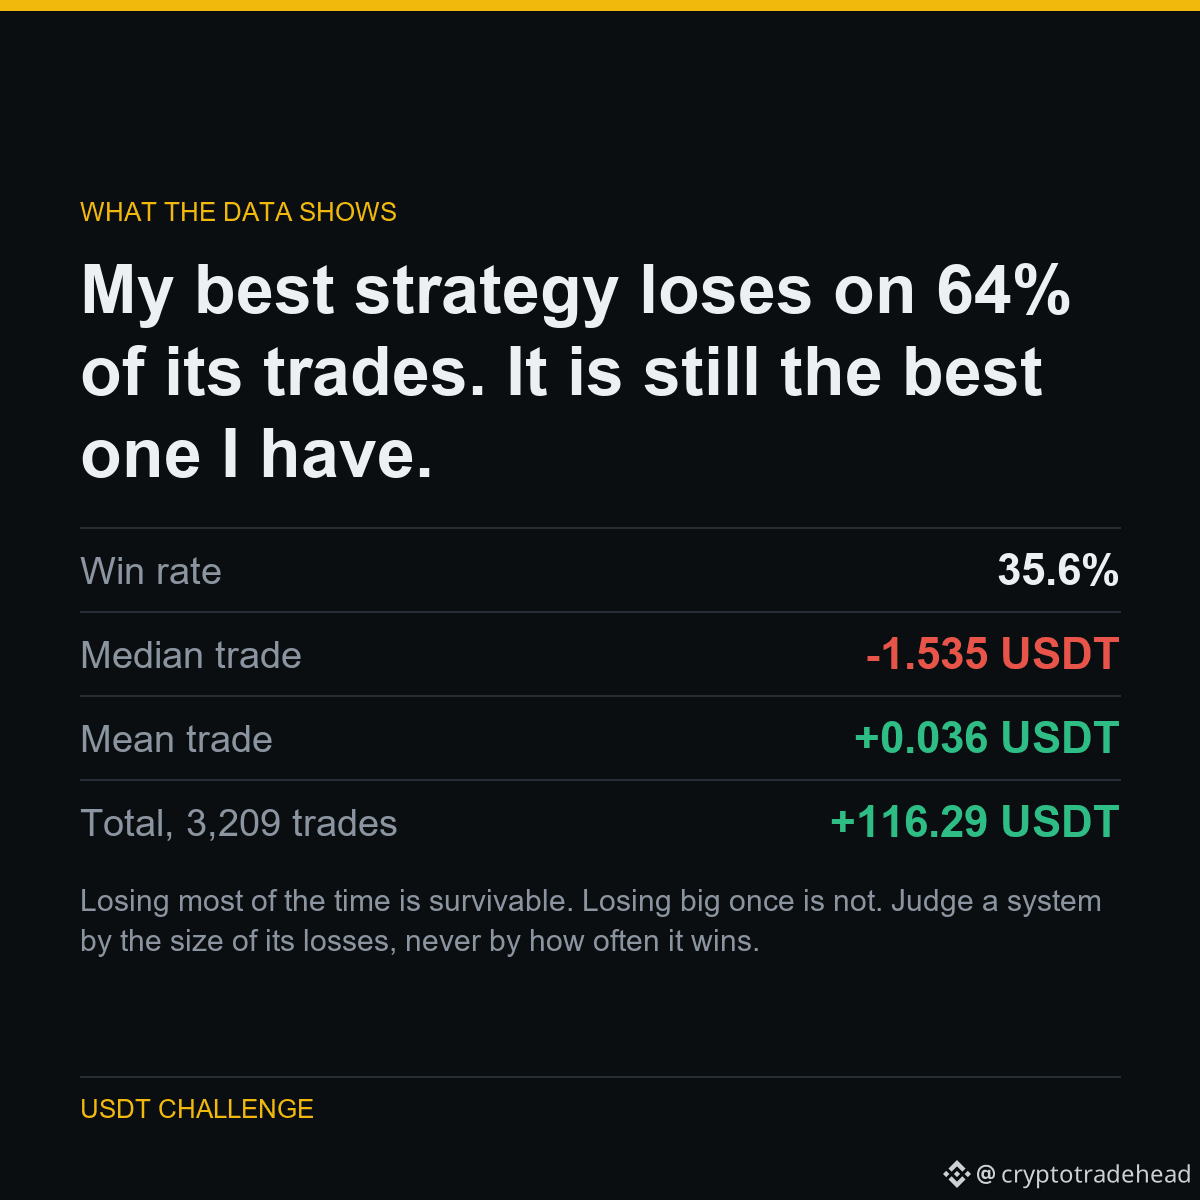
My best strategy loses on 64% of its trades. It is still the best one I have.My best strategy loses on 64% of its trades. It is still the best one I have.
The typical trade in this system loses 1.535 USDT. Nearly two out of three trades are losers.
It is profitable anyway, because the winners are much larger than the losers. The mean trade is positive while the median is clearly negative.
It is also the opposite shape to the martingale I tested, which won 96% of the time and still lost 519.83 USDT.
WHAT IT MEANS
Losing most of the time is survivable. Losing big once is not. Judge a system by the size of its losses, never by how often it wins.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $XRP $LTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
My best strategy loses on 64% of its trades. It is still the best one I have.
My best strategy loses on 64% of its trades. It is still the best one I have.
The typical trade in this system loses 1.535 USDT. Nearly two out of three trades are losers.
It is profitable anyway, because the winners are much larger than the losers. The mean trade is positive while the median is clearly negative.
It is also the opposite shape to the martingale I tested, which won 96% of the time and still lost 519.83 USDT.
WHAT IT MEANS
Losing most of the time is survivable. Losing big once is not. Judge a system by the size of its losses, never by how often it wins.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $XRP $LTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
8
Article
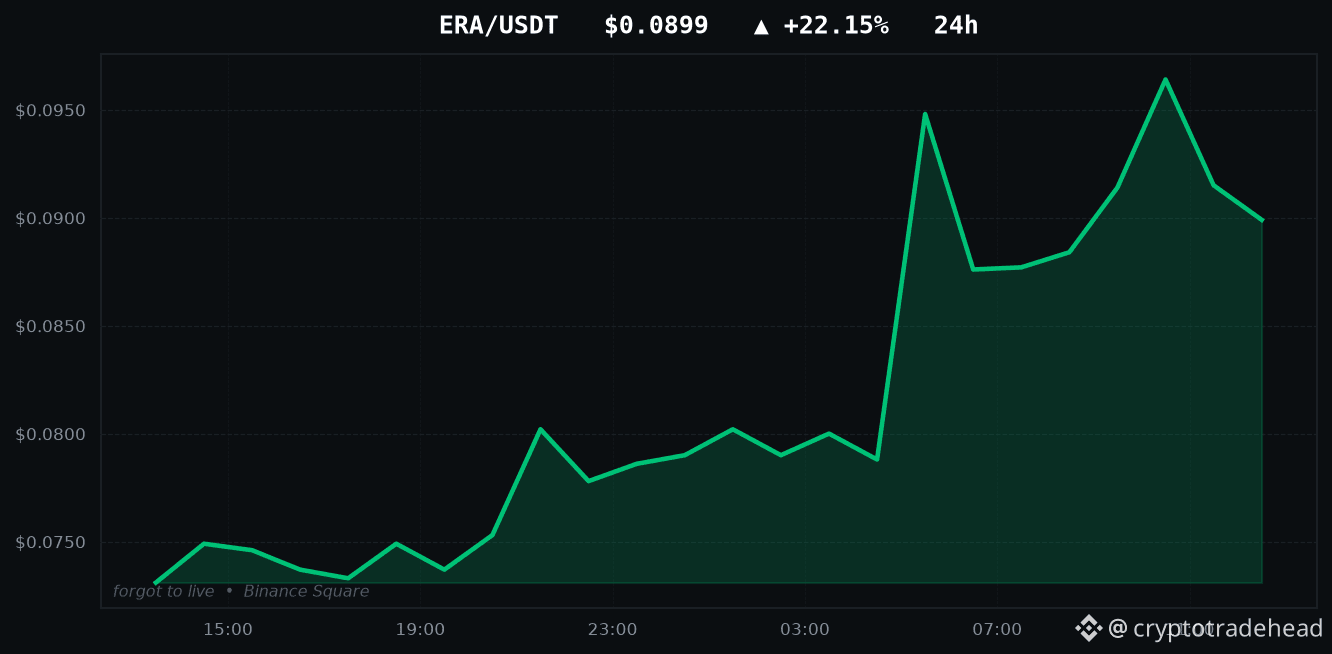
ERA is up +22.15% - I tested both ways to trade itTODAY'S TOP GAINERS
ERA: +22.15%
OSMO: +18.57%
DODO: +10.44%
MITO: +10.20%
REZ: +9.90%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like ERA's +22.15%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $ERA $OSMO $DODO
#Binance #Altcoins #Futures #ERA #CryptoData
ERA is up +22.15% - I tested both ways to trade it
TODAY'S TOP GAINERS
ERA: +22.15%
OSMO: +18.57%
DODO: +10.44%
MITO: +10.20%
REZ: +9.90%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like ERA's +22.15%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $ERA $OSMO $DODO
#Binance #Altcoins #Futures #ERA #CryptoData
3
HOW I TESTED IT
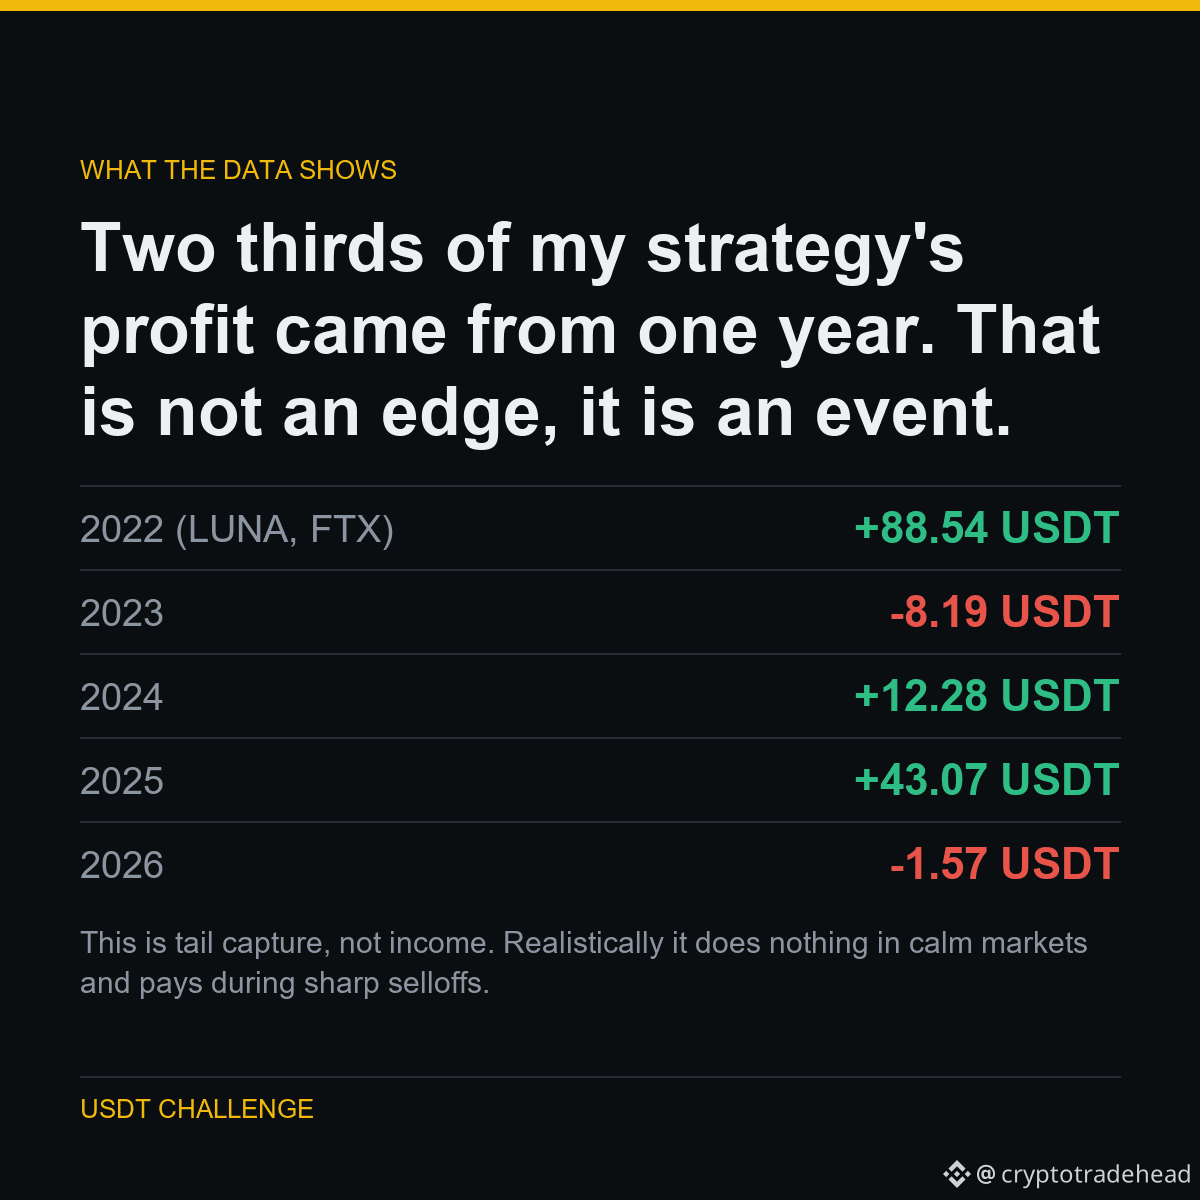
The headline number was +134.12 USDT from short breakouts. Then I split it by year.
2022 - the year of the LUNA collapse and the FTX failure - produced 88.54 of it. Strip that year out and four years of trading returned 45.59 USDT, most of it from 2025.
2026 so far is flat.
THE NUMBERS
2022 (LUNA, FTX): +88.54 USDT
2023: -8.19 USDT
2024: +12.28 USDT
2025: +43.07 USDT
2026: -1.57 USDT
This is tail capture, not income. Realistically it does nothing in calm markets and pays during sharp selloffs. Expecting it to earn every month is how people quit a strategy right before it works.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $LTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
2
Searching hard enough through random data will always produce a winner. The out-of-sample test is the only thing that tells you whether you found an edge or just found noise wearing a costume.
Here is what that came from.
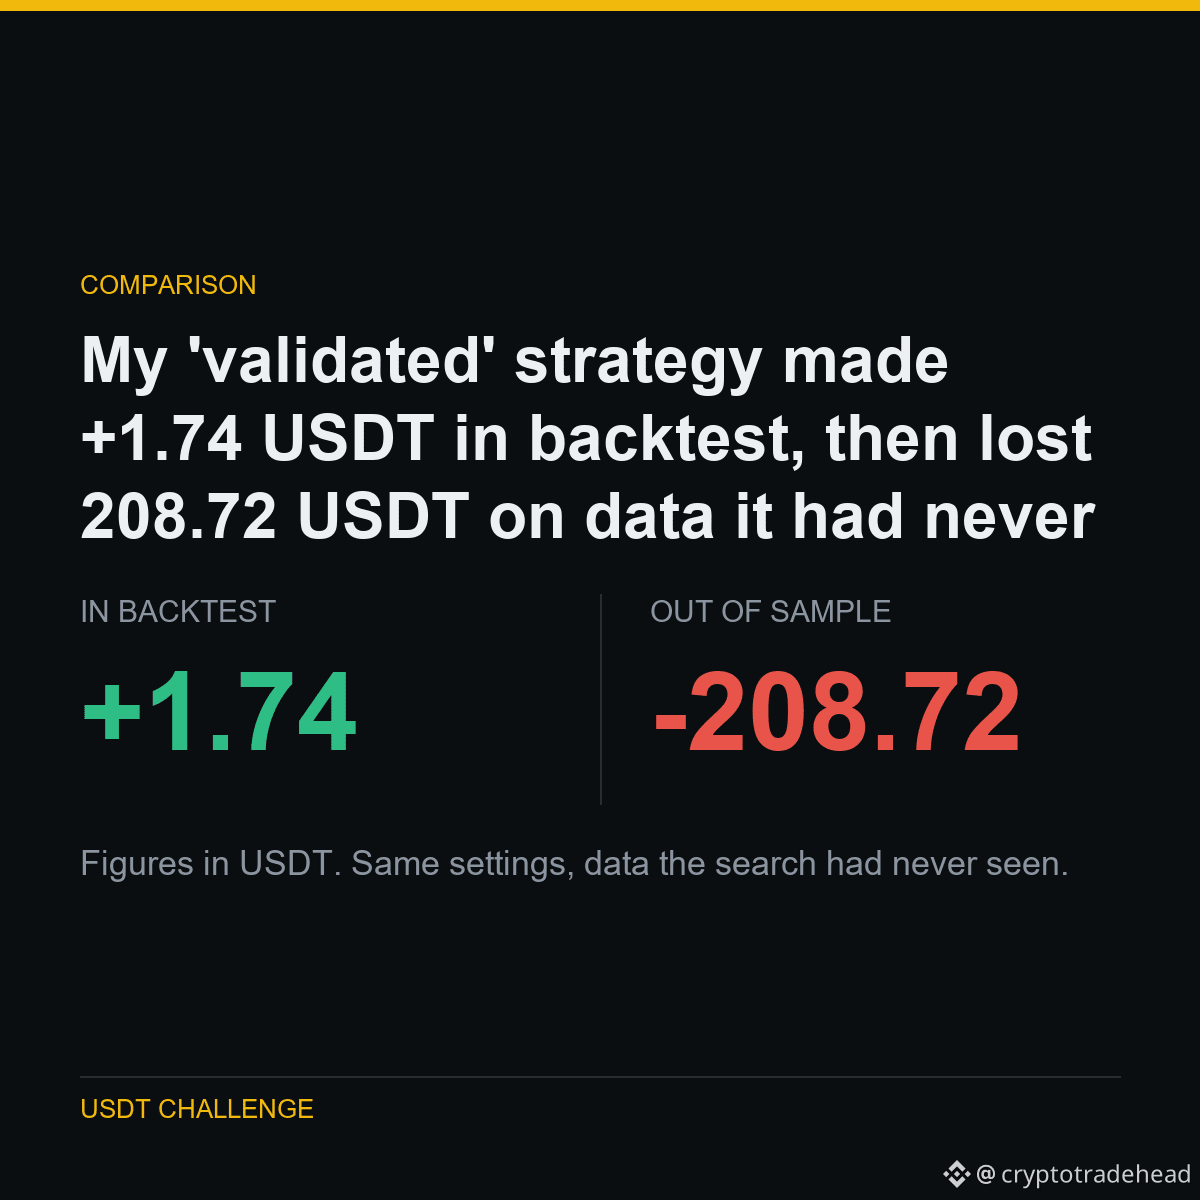
My 'validated' strategy made +1.74 USDT in backtest, then lost 208.72 USDT on data it had never seen.
I swept 40 symbols and found three that looked profitable. I called them validated and put them live.
Then I tested the exact same settings on 751 days of price history the search had never touched. All three reversed. Not marginally - completely.
Three survivors out of 40 is roughly what pure chance produces at that sample size.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $ETH $BNB
#Binance #Futures #Backtesting #TradingBot #CryptoData
1
Article
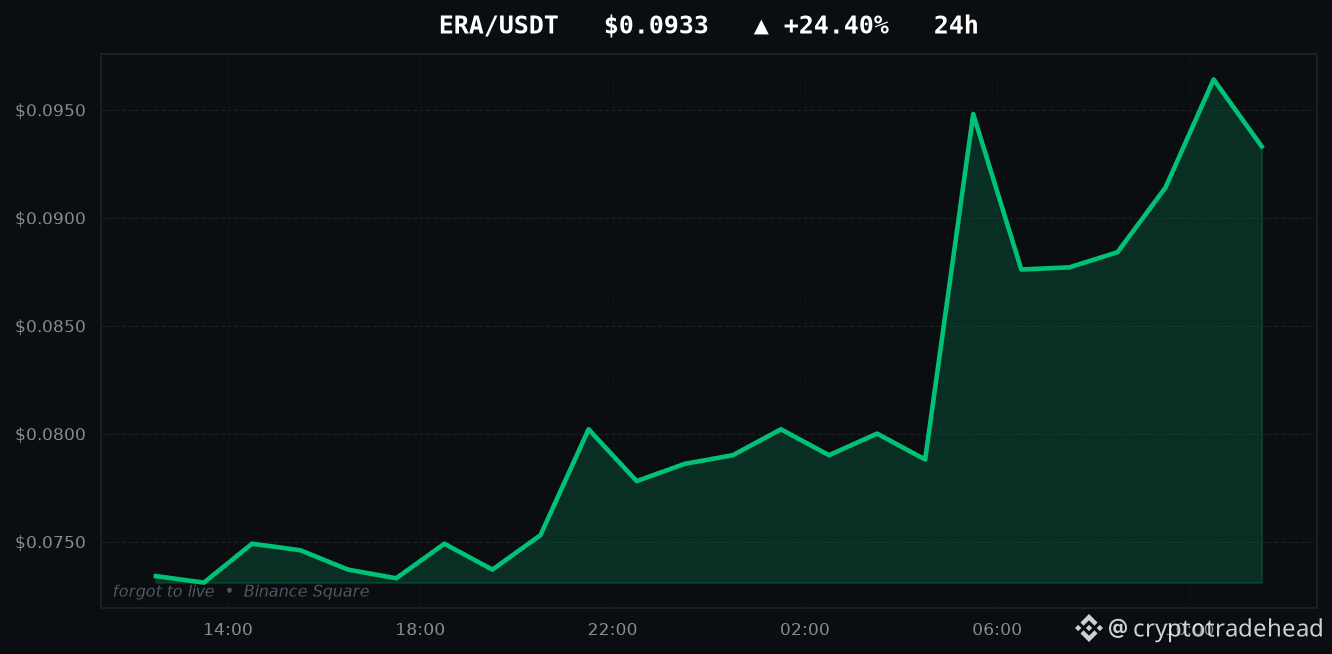
ERA is up +24.40% - I tested both ways to trade itTODAY'S TOP GAINERS
ERA: +24.40%
OSMO: +16.26%
DODO: +10.69%
REZ: +9.96%
BABY: +9.79%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like ERA's +24.40%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $ERA $OSMO $DODO
#Binance #Altcoins #Futures #ERA #CryptoData
ERA is up +24.40% - I tested both ways to trade it
TODAY'S TOP GAINERS
ERA: +24.40%
OSMO: +16.26%
DODO: +10.69%
REZ: +9.96%
BABY: +9.79%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like ERA's +24.40%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $ERA $OSMO $DODO
#Binance #Altcoins #Futures #ERA #CryptoData
8
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
BinancePick
2.7M views
144,553 Discussing
Join #EarningsSeason: Predict Earnings on Binance Pick, Share Your Take on Binance Square!
Binance Square Official
·402 Likes
·339.5k views
EarningsSeason
5M views
24,771 Discussing
SouthKoreaReportedlyWeighsFourthCryptoTaxDelay
4,117 views
164 Discussing