
JAMESCHIU
64 Posts
JAMESCHIU
Report
Block User
117 Following
570 Followers
11 Liked
Posts
All
Quotes
Live
·
--
Top-tier U.S. homebuilder Lennar released its earnings today. Its stock price has plunged from a 52-week high of $140.71 to the brink of being cut in half—hovering near $80. But if you only look at the “down 22% year-to-date” figure, you’re actually underestimating how brutally cold this housing-market downturn has been.
Lennar’s recent earnings reports have laid out clearly how high interest rates have pushed the builders’ profit model into a corner. To make homes affordable for buyers in a roughly 7% mortgage-rate environment, the company has rolled out large-scale “mortgage rate buydowns.” As promotions and incentives have risen, the portion of the home selling price devoted to these deals has surged to 12.9%–14.5%, driving gross margin down from over 18% a year ago to only around 15% now. In the prior quarter, new orders were down 4% year over year, and the company also lowered its home-delivery forecast to 82,000–83,000 units. Full-year EPS consensus was cut from last year’s $8.06 to just $5.52. This isn’t a “there’s a housing shortage and nobody wants it” story. It’s a “homes are being built, but buyers can’t carry the monthly payment”—so builders end up paying the interest themselves to generate sales, and the cost is that profits get chipped away bit by bit.
This earnings report is especially hard to read because it coincides with the Fed’s rate decision on the same day. If, after the meeting, Chair Powell (or the current chair) delivers a dovish signal, mortgage rates could ease, and the market may interpret Lennar’s bad news as “bad news that’s already priced in.” But if the Fed keeps a hawkish tone and the 10-year Treasury yield stays stuck above 5%, then builders’ tactic of using price cuts to drive volume will only become more and more expensive—and gross margin may not be close to its bottom yet.
Price signal: if shares break below the vicinity of the 52-week low near $78–$80, that suggests the market is starting to price in a pessimistic scenario where gross margin stays below 15% for the long term. If the stock climbs back above $90 after the report, that would imply the market believes this round of interest-rate buy-downs is just short-term pain, and that profitability can recover once inventory is worked down.
So will you treat a beaten-down homebuilder stock near the brink of a 50% drop as a contrarian opportunity that benefits first when rates reverse—or do you think gross margin deterioration is only just beginning, and it’s still not time to enter?
$LEN $DHI $PHM #建商股 #房地產 #美債殖利率 #美股財報
Top-tier U.S. homebuilder Lennar released its earnings today. Its stock price has plunged from a 52-week high of $140.71 to the brink of being cut in half—hovering near $80. But if you only look at the “down 22% year-to-date” figure, you’re actually underestimating how brutally cold this housing-market downturn has been.
Lennar’s recent earnings reports have laid out clearly how high interest rates have pushed the builders’ profit model into a corner. To make homes affordable for buyers in a roughly 7% mortgage-rate environment, the company has rolled out large-scale “mortgage rate buydowns.” As promotions and incentives have risen, the portion of the home selling price devoted to these deals has surged to 12.9%–14.5%, driving gross margin down from over 18% a year ago to only around 15% now. In the prior quarter, new orders were down 4% year over year, and the company also lowered its home-delivery forecast to 82,000–83,000 units. Full-year EPS consensus was cut from last year’s $8.06 to just $5.52. This isn’t a “there’s a housing shortage and nobody wants it” story. It’s a “homes are being built, but buyers can’t carry the monthly payment”—so builders end up paying the interest themselves to generate sales, and the cost is that profits get chipped away bit by bit.
This earnings report is especially hard to read because it coincides with the Fed’s rate decision on the same day. If, after the meeting, Chair Powell (or the current chair) delivers a dovish signal, mortgage rates could ease, and the market may interpret Lennar’s bad news as “bad news that’s already priced in.” But if the Fed keeps a hawkish tone and the 10-year Treasury yield stays stuck above 5%, then builders’ tactic of using price cuts to drive volume will only become more and more expensive—and gross margin may not be close to its bottom yet.
Price signal: if shares break below the vicinity of the 52-week low near $78–$80, that suggests the market is starting to price in a pessimistic scenario where gross margin stays below 15% for the long term. If the stock climbs back above $90 after the report, that would imply the market believes this round of interest-rate buy-downs is just short-term pain, and that profitability can recover once inventory is worked down.
So will you treat a beaten-down homebuilder stock near the brink of a 50% drop as a contrarian opportunity that benefits first when rates reverse—or do you think gross margin deterioration is only just beginning, and it’s still not time to enter?
$LEN $DHI $PHM #建商股 #房地產 #美債殖利率 #美股財報
Lennar’s recent earnings reports have laid out clearly how high interest rates have pushed the builders’ profit model into a corner. To make homes affordable for buyers in a roughly 7% mortgage-rate environment, the company has rolled out large-scale “mortgage rate buydowns.” As promotions and incentives have risen, the portion of the home selling price devoted to these deals has surged to 12.9%–14.5%, driving gross margin down from over 18% a year ago to only around 15% now. In the prior quarter, new orders were down 4% year over year, and the company also lowered its home-delivery forecast to 82,000–83,000 units. Full-year EPS consensus was cut from last year’s $8.06 to just $5.52. This isn’t a “there’s a housing shortage and nobody wants it” story. It’s a “homes are being built, but buyers can’t carry the monthly payment”—so builders end up paying the interest themselves to generate sales, and the cost is that profits get chipped away bit by bit.
This earnings report is especially hard to read because it coincides with the Fed’s rate decision on the same day. If, after the meeting, Chair Powell (or the current chair) delivers a dovish signal, mortgage rates could ease, and the market may interpret Lennar’s bad news as “bad news that’s already priced in.” But if the Fed keeps a hawkish tone and the 10-year Treasury yield stays stuck above 5%, then builders’ tactic of using price cuts to drive volume will only become more and more expensive—and gross margin may not be close to its bottom yet.
Price signal: if shares break below the vicinity of the 52-week low near $78–$80, that suggests the market is starting to price in a pessimistic scenario where gross margin stays below 15% for the long term. If the stock climbs back above $90 after the report, that would imply the market believes this round of interest-rate buy-downs is just short-term pain, and that profitability can recover once inventory is worked down.
So will you treat a beaten-down homebuilder stock near the brink of a 50% drop as a contrarian opportunity that benefits first when rates reverse—or do you think gross margin deterioration is only just beginning, and it’s still not time to enter?
$LEN $DHI $PHM #建商股 #房地產 #美債殖利率 #美股財報
74
·
--
backpack This time it’s not about tossing another celebrity stock—it’s about putting 20 of them up at once. Among them are Costco, Alibaba, Boeing, and also “young talent”-friendly picks like Reddit and Roblox.
In the past, on-chain US stocks felt like testing the waters. Now it’s more like unfolding the whole shelf at once. The key is still that old saying, but this time it feels different: being able to 1:1 exchange back to real stocks—not just shadows that only move with the price.
On the weekend, you can pick any stock you want without having to wait for Monday’s market open. No need to chase up or down—just the fact that “your choices have expanded” is already kind of interesting.
Has anyone already started flipping through the list?
Is there a ticker you like?
I’ve first saved the few I usually follow. Slowly, I’ll be moving from traditional brokerages to storing them in 🎒 the red backpack.
https://x.com/solana/status/2097787928558608863
@Backpack_CN
#Backpack #美股 #Solana
backpack This time it’s not about tossing another celebrity stock—it’s about putting 20 of them up at once. Among them are Costco, Alibaba, Boeing, and also “young talent”-friendly picks like Reddit and Roblox.
In the past, on-chain US stocks felt like testing the waters. Now it’s more like unfolding the whole shelf at once. The key is still that old saying, but this time it feels different: being able to 1:1 exchange back to real stocks—not just shadows that only move with the price.
On the weekend, you can pick any stock you want without having to wait for Monday’s market open. No need to chase up or down—just the fact that “your choices have expanded” is already kind of interesting.
Has anyone already started flipping through the list?
Is there a ticker you like?
I’ve first saved the few I usually follow. Slowly, I’ll be moving from traditional brokerages to storing them in 🎒 the red backpack.
https://x.com/solana/status/2097787928558608863
@Backpack_CN
#Backpack #美股 #Solana
In the past, on-chain US stocks felt like testing the waters. Now it’s more like unfolding the whole shelf at once. The key is still that old saying, but this time it feels different: being able to 1:1 exchange back to real stocks—not just shadows that only move with the price.
On the weekend, you can pick any stock you want without having to wait for Monday’s market open. No need to chase up or down—just the fact that “your choices have expanded” is already kind of interesting.
Has anyone already started flipping through the list?
Is there a ticker you like?
I’ve first saved the few I usually follow. Slowly, I’ll be moving from traditional brokerages to storing them in 🎒 the red backpack.
https://x.com/solana/status/2097787928558608863
@Backpack_CN
#Backpack #美股 #Solana
1
159
·
--
#TeslaOwners
@elonmusk
When I was a kid, the TV series "The A-Team" #KnightRider is being realized
Let’s take a look at Cybercab from the past few days
Tesla’s Robotaxi story is finally not a PPT anymore, but the scale is still a far cry from the numbers originally rumored.
On 9/3, Cybercab officially debuted in Austin—no steering wheel, no brake pedal, no safety driver—truly an unmanned taxi. This is Tesla’s most important step along the path from electric vehicles to FSD, and then to autonomous transportation.
But as of 8/31, the Cybercabs registered with the Texas DMV are actually only 7. The total robotaxi fleet in Texas (most of which are Model Y conversions) is about 270 to 276 vehicles. At any given time, the number of cars actually operating in a “no human supervision” mode is roughly only 20 to 30. By comparison, Waymo currently has about 3,500 cars, spread across 11 major metropolitan areas, completing more than 500,000 paid passenger rides per week, and accumulating over 220 million miles of fully autonomous driving. Tesla has only 380,000 miles in total—less than 0.2% of Waymo’s total mileage.
Compared with the existing Model Y converted vehicles, Cybercab’s biggest advantage is efficiency. It’s a two-seat model designed for passenger service: it uses about 165 watt-hours per mile. This makes it Tesla’s most efficient electric vehicle. The car weighs 3,113 pounds and comes with a 48 kWh battery—lighter and more aerodynamically optimized than the Model Y. But this advantage only applies to passenger demand of two people or fewer. The Model Y can seat five, so Tesla is also addressing that market with the Model Y.
The market isn’t suddenly going crazy bidding up prices just because Cybercab debuted. The reason is simple—there’s still a long way between a technical demo and large-scale commercialization. Bulls believe Tesla will ultimately rewrite the entire auto industry using software economics, while bears think that 7 cars are far from enough to prove any commercialization capability.
The key metrics worth watching aren’t what Cybercab looks like—it’s how many additional unmanned vehicles the fleet can add each month going forward, and what kind of review stance the regulators will take toward this new type of vehicle that offers completely no human-driver control options.
Tesla’s Robotaxi has finally started actually carrying people, but the fleet size is only a fraction of Waymo’s. Do you see this as the starting point for rapid replication after a technical breakthrough, or is it another repeat of the “demo is impressive, scaling is hard” story?
$TSLA #美股 #自動駕駛 #财报季
#TeslaOwners
@elonmusk
When I was a kid, the TV series "The A-Team" #KnightRider is being realized
Let’s take a look at Cybercab from the past few days
Tesla’s Robotaxi story is finally not a PPT anymore, but the scale is still a far cry from the numbers originally rumored.
On 9/3, Cybercab officially debuted in Austin—no steering wheel, no brake pedal, no safety driver—truly an unmanned taxi. This is Tesla’s most important step along the path from electric vehicles to FSD, and then to autonomous transportation.
But as of 8/31, the Cybercabs registered with the Texas DMV are actually only 7. The total robotaxi fleet in Texas (most of which are Model Y conversions) is about 270 to 276 vehicles. At any given time, the number of cars actually operating in a “no human supervision” mode is roughly only 20 to 30. By comparison, Waymo currently has about 3,500 cars, spread across 11 major metropolitan areas, completing more than 500,000 paid passenger rides per week, and accumulating over 220 million miles of fully autonomous driving. Tesla has only 380,000 miles in total—less than 0.2% of Waymo’s total mileage.
Compared with the existing Model Y converted vehicles, Cybercab’s biggest advantage is efficiency. It’s a two-seat model designed for passenger service: it uses about 165 watt-hours per mile. This makes it Tesla’s most efficient electric vehicle. The car weighs 3,113 pounds and comes with a 48 kWh battery—lighter and more aerodynamically optimized than the Model Y. But this advantage only applies to passenger demand of two people or fewer. The Model Y can seat five, so Tesla is also addressing that market with the Model Y.
The market isn’t suddenly going crazy bidding up prices just because Cybercab debuted. The reason is simple—there’s still a long way between a technical demo and large-scale commercialization. Bulls believe Tesla will ultimately rewrite the entire auto industry using software economics, while bears think that 7 cars are far from enough to prove any commercialization capability.
The key metrics worth watching aren’t what Cybercab looks like—it’s how many additional unmanned vehicles the fleet can add each month going forward, and what kind of review stance the regulators will take toward this new type of vehicle that offers completely no human-driver control options.
Tesla’s Robotaxi has finally started actually carrying people, but the fleet size is only a fraction of Waymo’s. Do you see this as the starting point for rapid replication after a technical breakthrough, or is it another repeat of the “demo is impressive, scaling is hard” story?
$TSLA #美股 #自動駕駛 #财报季
@elonmusk
When I was a kid, the TV series "The A-Team" #KnightRider is being realized
Let’s take a look at Cybercab from the past few days
Tesla’s Robotaxi story is finally not a PPT anymore, but the scale is still a far cry from the numbers originally rumored.
On 9/3, Cybercab officially debuted in Austin—no steering wheel, no brake pedal, no safety driver—truly an unmanned taxi. This is Tesla’s most important step along the path from electric vehicles to FSD, and then to autonomous transportation.
But as of 8/31, the Cybercabs registered with the Texas DMV are actually only 7. The total robotaxi fleet in Texas (most of which are Model Y conversions) is about 270 to 276 vehicles. At any given time, the number of cars actually operating in a “no human supervision” mode is roughly only 20 to 30. By comparison, Waymo currently has about 3,500 cars, spread across 11 major metropolitan areas, completing more than 500,000 paid passenger rides per week, and accumulating over 220 million miles of fully autonomous driving. Tesla has only 380,000 miles in total—less than 0.2% of Waymo’s total mileage.
Compared with the existing Model Y converted vehicles, Cybercab’s biggest advantage is efficiency. It’s a two-seat model designed for passenger service: it uses about 165 watt-hours per mile. This makes it Tesla’s most efficient electric vehicle. The car weighs 3,113 pounds and comes with a 48 kWh battery—lighter and more aerodynamically optimized than the Model Y. But this advantage only applies to passenger demand of two people or fewer. The Model Y can seat five, so Tesla is also addressing that market with the Model Y.
The market isn’t suddenly going crazy bidding up prices just because Cybercab debuted. The reason is simple—there’s still a long way between a technical demo and large-scale commercialization. Bulls believe Tesla will ultimately rewrite the entire auto industry using software economics, while bears think that 7 cars are far from enough to prove any commercialization capability.
The key metrics worth watching aren’t what Cybercab looks like—it’s how many additional unmanned vehicles the fleet can add each month going forward, and what kind of review stance the regulators will take toward this new type of vehicle that offers completely no human-driver control options.
Tesla’s Robotaxi has finally started actually carrying people, but the fleet size is only a fraction of Waymo’s. Do you see this as the starting point for rapid replication after a technical breakthrough, or is it another repeat of the “demo is impressive, scaling is hard” story?
$TSLA #美股 #自動駕駛 #财报季
105
·
--
21 banks have just announced that they will team up to issue a dollar stablecoin, but Société Générale has already tested the waters for them—more than a year in, with a circulation of just $12.54 million. At the same time, Tether’s circulation is $18.3 billion.
On 9/1, 21 banks and asset management firms, including Goldman Sachs, Citigroup, Bank of America, Wells Fargo, Deutsche Bank, UBS, and Fidelity Investments, jointly announced plans to form a new company to issue a dollar stablecoin, targeting a launch in the first half of 2027. The project grew from the 10-bank research group formed in October 2025 to 21 banks in less than a year, spanning North America, Europe, East Asia, the Middle East, and Africa.
But at this stage, even the company name has not been disclosed. It is expected to be formally established only by the end of this year. The official statement also includes a caveat: “subject to whether the deal conditions are completed”—this is a letter of intent, not a product that is about to be launched.
The real issue is not whether the banks are qualified to issue stablecoins. Bank endorsement has never equaled market buy-in. Société Générale’s USD CoinVertible, launched in June 2025, is a living example: more than a year later, its circulation is still under $13 million, which is an astronomical gap compared with Tether. This shows that the core of stablecoin competition is never solely about compliance—it also depends on distribution channels, on-chain ecosystem integration, and genuine use cases.
This alliance is not the only player either. In Europe, the Qivalis alliance, made up of 37 banks, was formed in September 2025. It is applying for approval from the Dutch central bank to issue a euro stablecoin. Spain’s BBVA even has one foot in two boats. The regulatory framework is not fully in place yet: in the U.S., the OCC’s prudential supervisory rules for stablecoins will only formally take effect in January 2027.
If this plan truly comes to fruition, it could indeed open a path for institutional funds to be converted into on-chain liquidity, reducing the friction costs of cross-border settlement. But to say it could end USDT’s market dominance may be too soon—21 banks’ creditworthiness does not necessarily translate into 21 banks’ product strength.
Tether built a $18.3 billion on-chain empire over a decade. Would you bet that 21 traditional banks can unseat it once they genuinely go live in 2027—or will it just replay the $12.54 million story of Société Générale?
$USDT $USDC
21 banks have just announced that they will team up to issue a dollar stablecoin, but Société Générale has already tested the waters for them—more than a year in, with a circulation of just $12.54 million. At the same time, Tether’s circulation is $18.3 billion.
On 9/1, 21 banks and asset management firms, including Goldman Sachs, Citigroup, Bank of America, Wells Fargo, Deutsche Bank, UBS, and Fidelity Investments, jointly announced plans to form a new company to issue a dollar stablecoin, targeting a launch in the first half of 2027. The project grew from the 10-bank research group formed in October 2025 to 21 banks in less than a year, spanning North America, Europe, East Asia, the Middle East, and Africa.
But at this stage, even the company name has not been disclosed. It is expected to be formally established only by the end of this year. The official statement also includes a caveat: “subject to whether the deal conditions are completed”—this is a letter of intent, not a product that is about to be launched.
The real issue is not whether the banks are qualified to issue stablecoins. Bank endorsement has never equaled market buy-in. Société Générale’s USD CoinVertible, launched in June 2025, is a living example: more than a year later, its circulation is still under $13 million, which is an astronomical gap compared with Tether. This shows that the core of stablecoin competition is never solely about compliance—it also depends on distribution channels, on-chain ecosystem integration, and genuine use cases.
This alliance is not the only player either. In Europe, the Qivalis alliance, made up of 37 banks, was formed in September 2025. It is applying for approval from the Dutch central bank to issue a euro stablecoin. Spain’s BBVA even has one foot in two boats. The regulatory framework is not fully in place yet: in the U.S., the OCC’s prudential supervisory rules for stablecoins will only formally take effect in January 2027.
If this plan truly comes to fruition, it could indeed open a path for institutional funds to be converted into on-chain liquidity, reducing the friction costs of cross-border settlement. But to say it could end USDT’s market dominance may be too soon—21 banks’ creditworthiness does not necessarily translate into 21 banks’ product strength.
Tether built a $18.3 billion on-chain empire over a decade. Would you bet that 21 traditional banks can unseat it once they genuinely go live in 2027—or will it just replay the $12.54 million story of Société Générale?
$USDT $USDC
On 9/1, 21 banks and asset management firms, including Goldman Sachs, Citigroup, Bank of America, Wells Fargo, Deutsche Bank, UBS, and Fidelity Investments, jointly announced plans to form a new company to issue a dollar stablecoin, targeting a launch in the first half of 2027. The project grew from the 10-bank research group formed in October 2025 to 21 banks in less than a year, spanning North America, Europe, East Asia, the Middle East, and Africa.
But at this stage, even the company name has not been disclosed. It is expected to be formally established only by the end of this year. The official statement also includes a caveat: “subject to whether the deal conditions are completed”—this is a letter of intent, not a product that is about to be launched.
The real issue is not whether the banks are qualified to issue stablecoins. Bank endorsement has never equaled market buy-in. Société Générale’s USD CoinVertible, launched in June 2025, is a living example: more than a year later, its circulation is still under $13 million, which is an astronomical gap compared with Tether. This shows that the core of stablecoin competition is never solely about compliance—it also depends on distribution channels, on-chain ecosystem integration, and genuine use cases.
This alliance is not the only player either. In Europe, the Qivalis alliance, made up of 37 banks, was formed in September 2025. It is applying for approval from the Dutch central bank to issue a euro stablecoin. Spain’s BBVA even has one foot in two boats. The regulatory framework is not fully in place yet: in the U.S., the OCC’s prudential supervisory rules for stablecoins will only formally take effect in January 2027.
If this plan truly comes to fruition, it could indeed open a path for institutional funds to be converted into on-chain liquidity, reducing the friction costs of cross-border settlement. But to say it could end USDT’s market dominance may be too soon—21 banks’ creditworthiness does not necessarily translate into 21 banks’ product strength.
Tether built a $18.3 billion on-chain empire over a decade. Would you bet that 21 traditional banks can unseat it once they genuinely go live in 2027—or will it just replay the $12.54 million story of Société Générale?
$USDT $USDC
63
·
--
Broadcom has truly broken the spell of “standing still” from the previous quarter—its guidance has indeed been raised.
Q3 revenue was $29.6 billion, up 86% year over year. AI semiconductor revenue was $16.7 billion, up 221% year over year and up 54% quarter over quarter, beating the company’s own guidance of $16.0 billion. Adjusted EPS was $3.32, also ahead of expectations of $3.24.
The real blockbuster news is in its guidance—Broadcom raised its FY2027 AI semiconductor revenue guidance from the previously maintained “above $100 billion” to $115 billion, and for the first time it also issued an FY2028 outlook of $230 billion. That is four times the $58 billion guidance for this year. In the earnings call, CEO Hock Tan emphasized that the real bottleneck now is not customer demand, but data center infrastructure—whether land, power, and factories can be set up on time.
That’s exactly the answer to the suspense we’ve been tracking. Last quarter (announced on 6/3), Broadcom beat both EPS and AI revenue, yet because guidance stayed unchanged at “above $100 billion,” the market interpreted it as a lack of confidence, and the stock dropped another 12.6% the next day. This time is different—the company has truly raised guidance in measurable terms, which theoretically should be the moment to break the spell.
However, the stock’s reaction is still cautious. Early in the day it fell by more than 1%, and on the next day it officially closed down 0.6%. Currently, it is about 26% below the 52-week high of $495. Year to date, it is up only about 6%, lagging far behind the SOX semiconductor index over the same period. The market’s concerns mainly fall into two areas: first, customer concentration—this growth story is largely supported by its six major custom silicon customers (including Google, Meta, Anthropic, and OpenAI). Second, competitive pressure—Marvell recently won a custom silicon deal with Google, which has led the market to question whether Broadcom’s moat in this segment is as deep as expected.
At the same time, Dell delivered $95 billion in AI server backlog the day before. Now Broadcom has also raised its AI chip revenue guidance to the $115 billion to $230 billion range. Put together, these two figures suggest that order visibility across the AI infrastructure supply chain—from chips to servers to data centers—is rising in tandem.
Guidance has indeed been raised, but the stock has only responded mildly. So do you think this means the market has already priced in the good news ahead of time, or are lingering concerns about customer concentration and competitive pressure more important than the guidance numbers themselves?
$AVGO $NVDA $MRVL
Broadcom has truly broken the spell of “standing still” from the previous quarter—its guidance has indeed been raised.
Q3 revenue was $29.6 billion, up 86% year over year. AI semiconductor revenue was $16.7 billion, up 221% year over year and up 54% quarter over quarter, beating the company’s own guidance of $16.0 billion. Adjusted EPS was $3.32, also ahead of expectations of $3.24.
The real blockbuster news is in its guidance—Broadcom raised its FY2027 AI semiconductor revenue guidance from the previously maintained “above $100 billion” to $115 billion, and for the first time it also issued an FY2028 outlook of $230 billion. That is four times the $58 billion guidance for this year. In the earnings call, CEO Hock Tan emphasized that the real bottleneck now is not customer demand, but data center infrastructure—whether land, power, and factories can be set up on time.
That’s exactly the answer to the suspense we’ve been tracking. Last quarter (announced on 6/3), Broadcom beat both EPS and AI revenue, yet because guidance stayed unchanged at “above $100 billion,” the market interpreted it as a lack of confidence, and the stock dropped another 12.6% the next day. This time is different—the company has truly raised guidance in measurable terms, which theoretically should be the moment to break the spell.
However, the stock’s reaction is still cautious. Early in the day it fell by more than 1%, and on the next day it officially closed down 0.6%. Currently, it is about 26% below the 52-week high of $495. Year to date, it is up only about 6%, lagging far behind the SOX semiconductor index over the same period. The market’s concerns mainly fall into two areas: first, customer concentration—this growth story is largely supported by its six major custom silicon customers (including Google, Meta, Anthropic, and OpenAI). Second, competitive pressure—Marvell recently won a custom silicon deal with Google, which has led the market to question whether Broadcom’s moat in this segment is as deep as expected.
At the same time, Dell delivered $95 billion in AI server backlog the day before. Now Broadcom has also raised its AI chip revenue guidance to the $115 billion to $230 billion range. Put together, these two figures suggest that order visibility across the AI infrastructure supply chain—from chips to servers to data centers—is rising in tandem.
Guidance has indeed been raised, but the stock has only responded mildly. So do you think this means the market has already priced in the good news ahead of time, or are lingering concerns about customer concentration and competitive pressure more important than the guidance numbers themselves?
$AVGO $NVDA $MRVL
Q3 revenue was $29.6 billion, up 86% year over year. AI semiconductor revenue was $16.7 billion, up 221% year over year and up 54% quarter over quarter, beating the company’s own guidance of $16.0 billion. Adjusted EPS was $3.32, also ahead of expectations of $3.24.
The real blockbuster news is in its guidance—Broadcom raised its FY2027 AI semiconductor revenue guidance from the previously maintained “above $100 billion” to $115 billion, and for the first time it also issued an FY2028 outlook of $230 billion. That is four times the $58 billion guidance for this year. In the earnings call, CEO Hock Tan emphasized that the real bottleneck now is not customer demand, but data center infrastructure—whether land, power, and factories can be set up on time.
That’s exactly the answer to the suspense we’ve been tracking. Last quarter (announced on 6/3), Broadcom beat both EPS and AI revenue, yet because guidance stayed unchanged at “above $100 billion,” the market interpreted it as a lack of confidence, and the stock dropped another 12.6% the next day. This time is different—the company has truly raised guidance in measurable terms, which theoretically should be the moment to break the spell.
However, the stock’s reaction is still cautious. Early in the day it fell by more than 1%, and on the next day it officially closed down 0.6%. Currently, it is about 26% below the 52-week high of $495. Year to date, it is up only about 6%, lagging far behind the SOX semiconductor index over the same period. The market’s concerns mainly fall into two areas: first, customer concentration—this growth story is largely supported by its six major custom silicon customers (including Google, Meta, Anthropic, and OpenAI). Second, competitive pressure—Marvell recently won a custom silicon deal with Google, which has led the market to question whether Broadcom’s moat in this segment is as deep as expected.
At the same time, Dell delivered $95 billion in AI server backlog the day before. Now Broadcom has also raised its AI chip revenue guidance to the $115 billion to $230 billion range. Put together, these two figures suggest that order visibility across the AI infrastructure supply chain—from chips to servers to data centers—is rising in tandem.
Guidance has indeed been raised, but the stock has only responded mildly. So do you think this means the market has already priced in the good news ahead of time, or are lingering concerns about customer concentration and competitive pressure more important than the guidance numbers themselves?
$AVGO $NVDA $MRVL
353
·
--
🎙️ Let's talk about the market and invest regularly in BNB spot!
End
03 h 21 m 01 s
16.6k
30
36
·
--
📊September Opening News Flash|Rate-Hike Expectations Reemerge
CPI (July): Headline YoY +3.4% / Core YoY +2.5%. The August data will be released on 9/11—Fed’s last crucial variable before the September meeting.
🔺 US stocks weaken: S&P 7,631 (-0.71%), Nasdaq 26,100 (-1.03%), Dow 52,767 (-0.79%)
🟥 Taiwan stocks surge: TAIEX 46,949 (+1.78%). MediaTek rallies after Nvidia subscribes $3.5B and hits the daily limit
10-year yields rebound to 4.80%, DXY 99.7. Tensions flare again in the Strait of Hormuz between Iran and the “Hezbollah”?—WTI jumps +5.2% in a day and moves above $90
₿ BTC $77,600 (-1%), ETH $2,450 (+0.3%)—consolidating at high levels after a big jump in August
US stocks pull back while Taiwan stocks hit new highs—the narrative is clearly diverging. The market is rapidly flipping from “betting on rate cuts” to “preparing for rate hikes”
📊September Opening News Flash|Rate-Hike Expectations Reemerge
CPI (July): Headline YoY +3.4% / Core YoY +2.5%. The August data will be released on 9/11—Fed’s last crucial variable before the September meeting.
🔺 US stocks weaken: S&P 7,631 (-0.71%), Nasdaq 26,100 (-1.03%), Dow 52,767 (-0.79%)
🟥 Taiwan stocks surge: TAIEX 46,949 (+1.78%). MediaTek rallies after Nvidia subscribes $3.5B and hits the daily limit
10-year yields rebound to 4.80%, DXY 99.7. Tensions flare again in the Strait of Hormuz between Iran and the “Hezbollah”?—WTI jumps +5.2% in a day and moves above $90
₿ BTC $77,600 (-1%), ETH $2,450 (+0.3%)—consolidating at high levels after a big jump in August
US stocks pull back while Taiwan stocks hit new highs—the narrative is clearly diverging. The market is rapidly flipping from “betting on rate cuts” to “preparing for rate hikes”
CPI (July): Headline YoY +3.4% / Core YoY +2.5%. The August data will be released on 9/11—Fed’s last crucial variable before the September meeting.
🔺 US stocks weaken: S&P 7,631 (-0.71%), Nasdaq 26,100 (-1.03%), Dow 52,767 (-0.79%)
🟥 Taiwan stocks surge: TAIEX 46,949 (+1.78%). MediaTek rallies after Nvidia subscribes $3.5B and hits the daily limit
10-year yields rebound to 4.80%, DXY 99.7. Tensions flare again in the Strait of Hormuz between Iran and the “Hezbollah”?—WTI jumps +5.2% in a day and moves above $90
₿ BTC $77,600 (-1%), ETH $2,450 (+0.3%)—consolidating at high levels after a big jump in August
US stocks pull back while Taiwan stocks hit new highs—the narrative is clearly diverging. The market is rapidly flipping from “betting on rate cuts” to “preparing for rate hikes”
358
·
--
A company that has not yet truly brought any data center online is sitting on backlog orders totaling as much as $439 billion—this could be the most outrageous IPO of the year.
SoftBank-backed SB Energy has officially filed to go public in the United States. The stock ticker is SBE, with a target listing sometime before the end of September. It plans to raise between $5 billion and $7 billion, valuing the company at around $50 billion. The company’s backlog is about $439 billion, including $430 billion from data center lease agreements and $10 billion from power projects.
The problem is that this $439 billion backlog is measured against revenue of just $138.7 million in the first half of the year, along with a net loss of as much as $3.21 billion. Of that loss, $2.57 billion comes from a non-cash expense caused by the remeasurement of stock warrants—not actual cash burned—yet the scale is still staggering. More importantly, the company explicitly admits in its filing, in black and white, that none of its data centers are currently officially operational, and that it is “substantially highly dependent on OpenAI.” This is listed by the company as a risk factor, not something speculated by outsiders.
The company’s business model is straightforward—build data centers and power plants, then lease them to customers such as OpenAI and SoftBank. Nvidia has already committed to invest $1.5 billion at the IPO price. OpenAI holds stock warrants worth about $5.5 billion. This aligns directly with the earlier deal in which Nvidia provided a financing guarantee of up to $105 billion for an Ohio data center for OpenAI—SB Energy is the developer responsible for building that data center.
In a sense, this IPO is testing how much the capital markets are willing to pay upfront for “future AI power cash flows.” The backlog is more than 3,100 times six months of revenue; the figure gives investors enormous room for imagination. But it also signals an equally massive execution gap—the theoretical visibility of the orders versus whether the company can actually build the infrastructure, lease it out, and collect rent. There’s still a long road ahead.
After SoftBank goes public, it will still be the controlling shareholder. Under Nasdaq rules, it will be classified as a controlled company. That means the company’s governance structure will leave relatively limited voice for external shareholders.
A company that hasn’t built any data centers yet is charging up a $50 billion valuation based on $439 billion in paper orders—do you see this as the boldest capital-market bet yet in the AI infrastructure boom, or is it another warning sign of the huge gap between “orders” and “cash flows”?
$SBE $NVDA $OPENAI #AI供應鏈 #電力基建 #IPO
A company that has not yet truly brought any data center online is sitting on backlog orders totaling as much as $439 billion—this could be the most outrageous IPO of the year.
SoftBank-backed SB Energy has officially filed to go public in the United States. The stock ticker is SBE, with a target listing sometime before the end of September. It plans to raise between $5 billion and $7 billion, valuing the company at around $50 billion. The company’s backlog is about $439 billion, including $430 billion from data center lease agreements and $10 billion from power projects.
The problem is that this $439 billion backlog is measured against revenue of just $138.7 million in the first half of the year, along with a net loss of as much as $3.21 billion. Of that loss, $2.57 billion comes from a non-cash expense caused by the remeasurement of stock warrants—not actual cash burned—yet the scale is still staggering. More importantly, the company explicitly admits in its filing, in black and white, that none of its data centers are currently officially operational, and that it is “substantially highly dependent on OpenAI.” This is listed by the company as a risk factor, not something speculated by outsiders.
The company’s business model is straightforward—build data centers and power plants, then lease them to customers such as OpenAI and SoftBank. Nvidia has already committed to invest $1.5 billion at the IPO price. OpenAI holds stock warrants worth about $5.5 billion. This aligns directly with the earlier deal in which Nvidia provided a financing guarantee of up to $105 billion for an Ohio data center for OpenAI—SB Energy is the developer responsible for building that data center.
In a sense, this IPO is testing how much the capital markets are willing to pay upfront for “future AI power cash flows.” The backlog is more than 3,100 times six months of revenue; the figure gives investors enormous room for imagination. But it also signals an equally massive execution gap—the theoretical visibility of the orders versus whether the company can actually build the infrastructure, lease it out, and collect rent. There’s still a long road ahead.
After SoftBank goes public, it will still be the controlling shareholder. Under Nasdaq rules, it will be classified as a controlled company. That means the company’s governance structure will leave relatively limited voice for external shareholders.
A company that hasn’t built any data centers yet is charging up a $50 billion valuation based on $439 billion in paper orders—do you see this as the boldest capital-market bet yet in the AI infrastructure boom, or is it another warning sign of the huge gap between “orders” and “cash flows”?
$SBE $NVDA $OPENAI #AI供應鏈 #電力基建 #IPO
SoftBank-backed SB Energy has officially filed to go public in the United States. The stock ticker is SBE, with a target listing sometime before the end of September. It plans to raise between $5 billion and $7 billion, valuing the company at around $50 billion. The company’s backlog is about $439 billion, including $430 billion from data center lease agreements and $10 billion from power projects.
The problem is that this $439 billion backlog is measured against revenue of just $138.7 million in the first half of the year, along with a net loss of as much as $3.21 billion. Of that loss, $2.57 billion comes from a non-cash expense caused by the remeasurement of stock warrants—not actual cash burned—yet the scale is still staggering. More importantly, the company explicitly admits in its filing, in black and white, that none of its data centers are currently officially operational, and that it is “substantially highly dependent on OpenAI.” This is listed by the company as a risk factor, not something speculated by outsiders.
The company’s business model is straightforward—build data centers and power plants, then lease them to customers such as OpenAI and SoftBank. Nvidia has already committed to invest $1.5 billion at the IPO price. OpenAI holds stock warrants worth about $5.5 billion. This aligns directly with the earlier deal in which Nvidia provided a financing guarantee of up to $105 billion for an Ohio data center for OpenAI—SB Energy is the developer responsible for building that data center.
In a sense, this IPO is testing how much the capital markets are willing to pay upfront for “future AI power cash flows.” The backlog is more than 3,100 times six months of revenue; the figure gives investors enormous room for imagination. But it also signals an equally massive execution gap—the theoretical visibility of the orders versus whether the company can actually build the infrastructure, lease it out, and collect rent. There’s still a long road ahead.
After SoftBank goes public, it will still be the controlling shareholder. Under Nasdaq rules, it will be classified as a controlled company. That means the company’s governance structure will leave relatively limited voice for external shareholders.
A company that hasn’t built any data centers yet is charging up a $50 billion valuation based on $439 billion in paper orders—do you see this as the boldest capital-market bet yet in the AI infrastructure boom, or is it another warning sign of the huge gap between “orders” and “cash flows”?
$SBE $NVDA $OPENAI #AI供應鏈 #電力基建 #IPO
84
·
--
NVIDIA has already proven that GPU demand is still accelerating—tonight (after the 9/2 close), it will be Broadcom’s turn to show whether its custom AI chips are also seeing a breakout.
The latest market expectations are EPS of $3.21 and revenue of $29.25 billion, up about 84% to 85% year over year. The Q3 AI chip revenue guidance is $16 billion—this is the number the market most wants to validate tonight. The current share price is $369.34, and the market cap is $1.76 trillion.
This earnings report also has an important historical hint. In the previous quarter (reported on 6/3), Broadcom posted EPS of $2.44, beating expectations of $2.40, but revenue came in at $22.19 billion—below the expected $22.27 billion. Coupled with CEO Hock Tan not further raising the 2027 AI chip revenue target from $100 billion, the stock plunged more than 12% to 15% the next day. Since then, the share price is down more than 25% from its all-time high.
Worth noting: in the last earnings call, Hock Tan said the company landed a $10 billion AI order from a newly added qualified customer, and that the deal would significantly improve its FY2026 AI revenue outlook. The specific details of that order are very likely a key focus of tonight’s earnings call. Analyst Harlan Sur at Morgan Stanley is maintaining a buy/“add” rating with a $400 price target, saying that demand for AI products remains strong.
What institutional investors truly care about now isn’t just whether results “beat” expectations. It’s two things: first, whether increasing the revenue mix from AI chips will dilute the high gross margins of the traditional business; and second, whether the long-term guidance of more than $100 billion for 2027 will finally be raised—or if it will continue to stall. If it’s another stall, it could closely repeat last time’s script. But if guidance is raised—and if the details of that new $10 billion customer order are disclosed—then it could be a crucial step toward answering whether Custom ASICs can carry on the GPU story.
Tech giants don’t want to be held hostage by a single GPU supplier, so they need Broadcom to provide customized chips. In this AI in-house arms race, can tonight’s earnings call break the spell from last quarter—where it beat expectations but still got hammered?
$AVGO $NVDA $MRVL #美股 #AI供應鏈 #Earnings season
NVIDIA has already proven that GPU demand is still accelerating—tonight (after the 9/2 close), it will be Broadcom’s turn to show whether its custom AI chips are also seeing a breakout.
The latest market expectations are EPS of $3.21 and revenue of $29.25 billion, up about 84% to 85% year over year. The Q3 AI chip revenue guidance is $16 billion—this is the number the market most wants to validate tonight. The current share price is $369.34, and the market cap is $1.76 trillion.
This earnings report also has an important historical hint. In the previous quarter (reported on 6/3), Broadcom posted EPS of $2.44, beating expectations of $2.40, but revenue came in at $22.19 billion—below the expected $22.27 billion. Coupled with CEO Hock Tan not further raising the 2027 AI chip revenue target from $100 billion, the stock plunged more than 12% to 15% the next day. Since then, the share price is down more than 25% from its all-time high.
Worth noting: in the last earnings call, Hock Tan said the company landed a $10 billion AI order from a newly added qualified customer, and that the deal would significantly improve its FY2026 AI revenue outlook. The specific details of that order are very likely a key focus of tonight’s earnings call. Analyst Harlan Sur at Morgan Stanley is maintaining a buy/“add” rating with a $400 price target, saying that demand for AI products remains strong.
What institutional investors truly care about now isn’t just whether results “beat” expectations. It’s two things: first, whether increasing the revenue mix from AI chips will dilute the high gross margins of the traditional business; and second, whether the long-term guidance of more than $100 billion for 2027 will finally be raised—or if it will continue to stall. If it’s another stall, it could closely repeat last time’s script. But if guidance is raised—and if the details of that new $10 billion customer order are disclosed—then it could be a crucial step toward answering whether Custom ASICs can carry on the GPU story.
Tech giants don’t want to be held hostage by a single GPU supplier, so they need Broadcom to provide customized chips. In this AI in-house arms race, can tonight’s earnings call break the spell from last quarter—where it beat expectations but still got hammered?
$AVGO $NVDA $MRVL #美股 #AI供應鏈 #Earnings season
The latest market expectations are EPS of $3.21 and revenue of $29.25 billion, up about 84% to 85% year over year. The Q3 AI chip revenue guidance is $16 billion—this is the number the market most wants to validate tonight. The current share price is $369.34, and the market cap is $1.76 trillion.
This earnings report also has an important historical hint. In the previous quarter (reported on 6/3), Broadcom posted EPS of $2.44, beating expectations of $2.40, but revenue came in at $22.19 billion—below the expected $22.27 billion. Coupled with CEO Hock Tan not further raising the 2027 AI chip revenue target from $100 billion, the stock plunged more than 12% to 15% the next day. Since then, the share price is down more than 25% from its all-time high.
Worth noting: in the last earnings call, Hock Tan said the company landed a $10 billion AI order from a newly added qualified customer, and that the deal would significantly improve its FY2026 AI revenue outlook. The specific details of that order are very likely a key focus of tonight’s earnings call. Analyst Harlan Sur at Morgan Stanley is maintaining a buy/“add” rating with a $400 price target, saying that demand for AI products remains strong.
What institutional investors truly care about now isn’t just whether results “beat” expectations. It’s two things: first, whether increasing the revenue mix from AI chips will dilute the high gross margins of the traditional business; and second, whether the long-term guidance of more than $100 billion for 2027 will finally be raised—or if it will continue to stall. If it’s another stall, it could closely repeat last time’s script. But if guidance is raised—and if the details of that new $10 billion customer order are disclosed—then it could be a crucial step toward answering whether Custom ASICs can carry on the GPU story.
Tech giants don’t want to be held hostage by a single GPU supplier, so they need Broadcom to provide customized chips. In this AI in-house arms race, can tonight’s earnings call break the spell from last quarter—where it beat expectations but still got hammered?
$AVGO $NVDA $MRVL #美股 #AI供應鏈 #Earnings season
213
·
--
After the hawkish remarks in Washington, BTC fell back from the $80,000 level to high-level consolidation, and spot gold also dropped by more than 1.1% in tandem. Recently, the correlation between BTC and gold has significantly strengthened under macro interest-rate disturbances, showing highly consistent liquidity-sensitivity characteristics.
Behind the tug-of-war between the two assets at elevated levels, a deeper signal is emerging:
Macroeconomic liquidity drives pricing: When U.S. Treasury yields rise and rate-hike expectations increase, both zero-yield assets like gold and high-beta assets like BTC face pressure from higher risk-free discount rates.
Resonance of reserve-asset attributes: Whether central banks are adding to gold holdings or institutions are allocating to BTC, both essentially serve to hedge against the expansion of fiat-debt; their price movements become highly synchronized as tightening expectations heat up.
Key inflection-point positioning: In the BTC range of $76,000 to $78,000, it demonstrates exceptionally strong absorption capability. Pullbacks and shakeouts may actually help strengthen the next phase’s market positioning structure.
Do you think the strong linkage between BTC and gold confirms the status of digital gold, or is it only short-term liquidity being constrained?
$BTC $XAU #BTC #gold
After the hawkish remarks in Washington, BTC fell back from the $80,000 level to high-level consolidation, and spot gold also dropped by more than 1.1% in tandem. Recently, the correlation between BTC and gold has significantly strengthened under macro interest-rate disturbances, showing highly consistent liquidity-sensitivity characteristics.
Behind the tug-of-war between the two assets at elevated levels, a deeper signal is emerging:
Macroeconomic liquidity drives pricing: When U.S. Treasury yields rise and rate-hike expectations increase, both zero-yield assets like gold and high-beta assets like BTC face pressure from higher risk-free discount rates.
Resonance of reserve-asset attributes: Whether central banks are adding to gold holdings or institutions are allocating to BTC, both essentially serve to hedge against the expansion of fiat-debt; their price movements become highly synchronized as tightening expectations heat up.
Key inflection-point positioning: In the BTC range of $76,000 to $78,000, it demonstrates exceptionally strong absorption capability. Pullbacks and shakeouts may actually help strengthen the next phase’s market positioning structure.
Do you think the strong linkage between BTC and gold confirms the status of digital gold, or is it only short-term liquidity being constrained?
$BTC $XAU #BTC #gold
Behind the tug-of-war between the two assets at elevated levels, a deeper signal is emerging:
Macroeconomic liquidity drives pricing: When U.S. Treasury yields rise and rate-hike expectations increase, both zero-yield assets like gold and high-beta assets like BTC face pressure from higher risk-free discount rates.
Resonance of reserve-asset attributes: Whether central banks are adding to gold holdings or institutions are allocating to BTC, both essentially serve to hedge against the expansion of fiat-debt; their price movements become highly synchronized as tightening expectations heat up.
Key inflection-point positioning: In the BTC range of $76,000 to $78,000, it demonstrates exceptionally strong absorption capability. Pullbacks and shakeouts may actually help strengthen the next phase’s market positioning structure.
Do you think the strong linkage between BTC and gold confirms the status of digital gold, or is it only short-term liquidity being constrained?
$BTC $XAU #BTC #gold
96
·
--
SanDisk’s Kioxia plans to invest $31 billion in expansion
The market’s reaction to the $31 billion expansion plans announced by SanDisk and Kioxia this time has been split in two completely different directions.
On 8/27, the two companies announced at the same time that by 2032 they will add more than $31 billion in investment in Japan to expand two NAND flash memory plants, Yokkaichi and Kitakami. Over the past 25 years, the two sides have already invested more than $50 billion cumulatively in Japan. This latest scale amounts to 60% of what they spent over the previous quarter-century, compressed into completion within the next six years. This money also still requires additional funding support from the Japanese government to be fully covered, so it is not a fully finalized capital expenditure commitment.
On the day the news was released, Kioxia’s stock price surged intraday by nearly 6.9%, but SanDisk’s own stock price fell on the same day. With the same news, the joint-venture partners’ shares headed in completely opposite directions.
This divergence is not hard to understand. The money is not coming entirely out of SanDisk’s own pocket. SanDisk holds 49.9% of the equity in the joint venture Flash Ventures, while Kioxia owns the factories themselves. The two sides split about half the output each, so the true capital expenditure obligation attributed to SanDisk works out to roughly $1.3 billion per year—far below the shock factor suggested by the headline figure of $31 billion. Even more thought-provoking is that this decision directly contradicts what SanDisk management told investors just three weeks ago. At the time, the company emphasized that supply would be increased through “technology upgrades” rather than large-scale capacity expansion, and that the capital expenditure-to-revenue ratio was declining.
The real question is not whether this money is “big enough,” but whether the additional capacity will find buyers in the future. That’s the classic curse of the traditional memory industry: frenzied expansion, capacity oversupply, and then a price crash. This cycle has happened many times in the past.
That said, this time there is one key number that makes the round of expansion look more secure than in the past. SanDisk has already signed long-term supply agreements with eight customers using a lowest guaranteed price calculation. The total value of these agreements is $93.9 billion, covering about half of the unit bit shipment volume estimated for the company’s FY2027. In other words, this expansion is, to some extent, building plants based on orders that have already been signed—not a naked expansion betting purely on future demand.
Also worth noting is that TrendForce data shows that the alliance’s overall capital expenditures have grown at a year-over-year rate of 40% in recent years. One reason is that Samsung and SK hynix have shifted resources toward HBM high-bandwidth memory, leaving NAND as a chance for SanDisk and Kioxia to expand their market share. In that sense, the $31 billion figure is, to some degree, putting the existing expansion trend on the record, rather than a completely new decision conjured out of thin air.
With the same expansion news—Kioxia up, SanDisk down—you could wonder whether the market is rewarding Kioxia for holding the actual production capacity, or punishing SanDisk for a capital expenditure strategy that seems to say one thing and do another?
$SNDK
SanDisk’s Kioxia plans to invest $31 billion in expansion
The market’s reaction to the $31 billion expansion plans announced by SanDisk and Kioxia this time has been split in two completely different directions.
On 8/27, the two companies announced at the same time that by 2032 they will add more than $31 billion in investment in Japan to expand two NAND flash memory plants, Yokkaichi and Kitakami. Over the past 25 years, the two sides have already invested more than $50 billion cumulatively in Japan. This latest scale amounts to 60% of what they spent over the previous quarter-century, compressed into completion within the next six years. This money also still requires additional funding support from the Japanese government to be fully covered, so it is not a fully finalized capital expenditure commitment.
On the day the news was released, Kioxia’s stock price surged intraday by nearly 6.9%, but SanDisk’s own stock price fell on the same day. With the same news, the joint-venture partners’ shares headed in completely opposite directions.
This divergence is not hard to understand. The money is not coming entirely out of SanDisk’s own pocket. SanDisk holds 49.9% of the equity in the joint venture Flash Ventures, while Kioxia owns the factories themselves. The two sides split about half the output each, so the true capital expenditure obligation attributed to SanDisk works out to roughly $1.3 billion per year—far below the shock factor suggested by the headline figure of $31 billion. Even more thought-provoking is that this decision directly contradicts what SanDisk management told investors just three weeks ago. At the time, the company emphasized that supply would be increased through “technology upgrades” rather than large-scale capacity expansion, and that the capital expenditure-to-revenue ratio was declining.
The real question is not whether this money is “big enough,” but whether the additional capacity will find buyers in the future. That’s the classic curse of the traditional memory industry: frenzied expansion, capacity oversupply, and then a price crash. This cycle has happened many times in the past.
That said, this time there is one key number that makes the round of expansion look more secure than in the past. SanDisk has already signed long-term supply agreements with eight customers using a lowest guaranteed price calculation. The total value of these agreements is $93.9 billion, covering about half of the unit bit shipment volume estimated for the company’s FY2027. In other words, this expansion is, to some extent, building plants based on orders that have already been signed—not a naked expansion betting purely on future demand.
Also worth noting is that TrendForce data shows that the alliance’s overall capital expenditures have grown at a year-over-year rate of 40% in recent years. One reason is that Samsung and SK hynix have shifted resources toward HBM high-bandwidth memory, leaving NAND as a chance for SanDisk and Kioxia to expand their market share. In that sense, the $31 billion figure is, to some degree, putting the existing expansion trend on the record, rather than a completely new decision conjured out of thin air.
With the same expansion news—Kioxia up, SanDisk down—you could wonder whether the market is rewarding Kioxia for holding the actual production capacity, or punishing SanDisk for a capital expenditure strategy that seems to say one thing and do another?
$SNDK
The market’s reaction to the $31 billion expansion plans announced by SanDisk and Kioxia this time has been split in two completely different directions.
On 8/27, the two companies announced at the same time that by 2032 they will add more than $31 billion in investment in Japan to expand two NAND flash memory plants, Yokkaichi and Kitakami. Over the past 25 years, the two sides have already invested more than $50 billion cumulatively in Japan. This latest scale amounts to 60% of what they spent over the previous quarter-century, compressed into completion within the next six years. This money also still requires additional funding support from the Japanese government to be fully covered, so it is not a fully finalized capital expenditure commitment.
On the day the news was released, Kioxia’s stock price surged intraday by nearly 6.9%, but SanDisk’s own stock price fell on the same day. With the same news, the joint-venture partners’ shares headed in completely opposite directions.
This divergence is not hard to understand. The money is not coming entirely out of SanDisk’s own pocket. SanDisk holds 49.9% of the equity in the joint venture Flash Ventures, while Kioxia owns the factories themselves. The two sides split about half the output each, so the true capital expenditure obligation attributed to SanDisk works out to roughly $1.3 billion per year—far below the shock factor suggested by the headline figure of $31 billion. Even more thought-provoking is that this decision directly contradicts what SanDisk management told investors just three weeks ago. At the time, the company emphasized that supply would be increased through “technology upgrades” rather than large-scale capacity expansion, and that the capital expenditure-to-revenue ratio was declining.
The real question is not whether this money is “big enough,” but whether the additional capacity will find buyers in the future. That’s the classic curse of the traditional memory industry: frenzied expansion, capacity oversupply, and then a price crash. This cycle has happened many times in the past.
That said, this time there is one key number that makes the round of expansion look more secure than in the past. SanDisk has already signed long-term supply agreements with eight customers using a lowest guaranteed price calculation. The total value of these agreements is $93.9 billion, covering about half of the unit bit shipment volume estimated for the company’s FY2027. In other words, this expansion is, to some extent, building plants based on orders that have already been signed—not a naked expansion betting purely on future demand.
Also worth noting is that TrendForce data shows that the alliance’s overall capital expenditures have grown at a year-over-year rate of 40% in recent years. One reason is that Samsung and SK hynix have shifted resources toward HBM high-bandwidth memory, leaving NAND as a chance for SanDisk and Kioxia to expand their market share. In that sense, the $31 billion figure is, to some degree, putting the existing expansion trend on the record, rather than a completely new decision conjured out of thin air.
With the same expansion news—Kioxia up, SanDisk down—you could wonder whether the market is rewarding Kioxia for holding the actual production capacity, or punishing SanDisk for a capital expenditure strategy that seems to say one thing and do another?
$SNDK
199
·
--
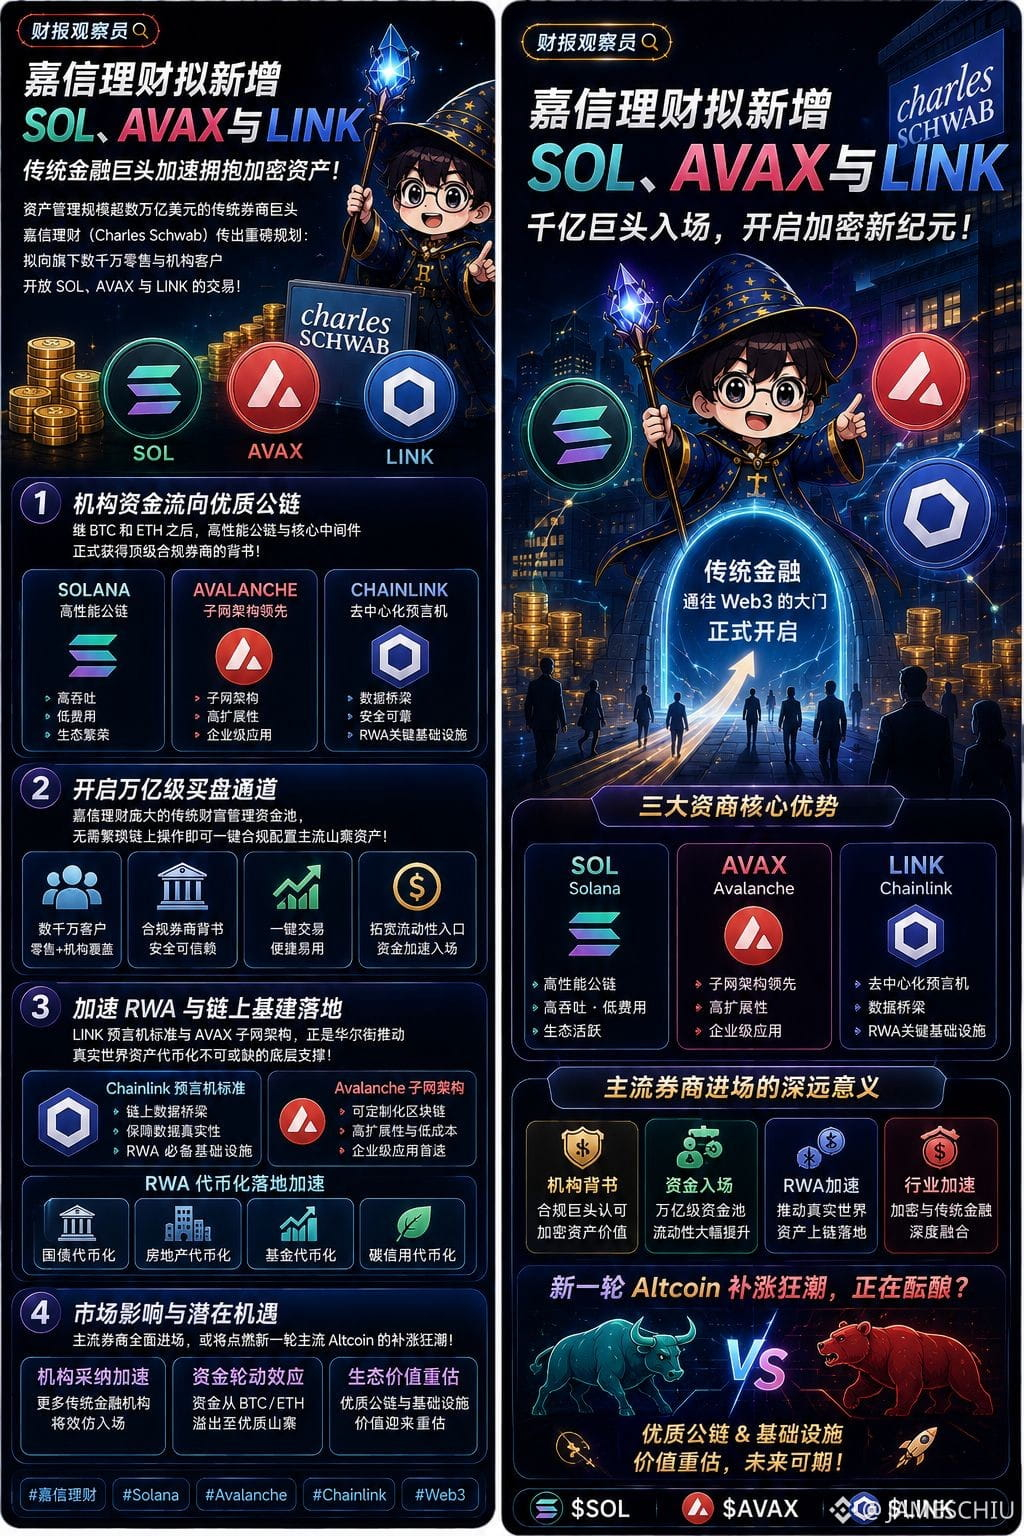
#嘉信理财拟新增SOL與AVAX以及LINK
A major development has emerged from traditional brokerage giant Charles Schwab, which manages assets worth over several tens of trillions of dollars: it is reportedly planning to open trading in SOL, AVAX, and LINK to its tens of millions of retail and institutional clients.
Traditional finance incumbents are accelerating customer acquisition, sending three positive signals at once:
Institutional funds flowing to high-quality public chains: After BTC and ETH, high-performance public chains (Solana, Avalanche) and core middleware (Chainlink) have officially received endorsement from a top-tier compliant broker.
A multi-trillion-dollar buying channel: Schwab’s massive traditional wealth management capital pool enables one-click, compliant allocation of mainstream altcoins without cumbersome on-chain operations—greatly expanding liquidity access.
Accelerating RWA and on-chain infrastructure deployment: LINK oracle standards and Avalanche subnet architecture are exactly the foundational pillars the Wall Street crowd needs to tokenize real-world assets.
With mainstream brokers moving in en masse, do you think this will ignite a new wave of mainstream Altcoin catch-up rallies?
$SOL $AVAX $LINK
#嘉信理财拟新增SOL與AVAX以及LINK
A major development has emerged from traditional brokerage giant Charles Schwab, which manages assets worth over several tens of trillions of dollars: it is reportedly planning to open trading in SOL, AVAX, and LINK to its tens of millions of retail and institutional clients.
Traditional finance incumbents are accelerating customer acquisition, sending three positive signals at once:
Institutional funds flowing to high-quality public chains: After BTC and ETH, high-performance public chains (Solana, Avalanche) and core middleware (Chainlink) have officially received endorsement from a top-tier compliant broker.
A multi-trillion-dollar buying channel: Schwab’s massive traditional wealth management capital pool enables one-click, compliant allocation of mainstream altcoins without cumbersome on-chain operations—greatly expanding liquidity access.
Accelerating RWA and on-chain infrastructure deployment: LINK oracle standards and Avalanche subnet architecture are exactly the foundational pillars the Wall Street crowd needs to tokenize real-world assets.
With mainstream brokers moving in en masse, do you think this will ignite a new wave of mainstream Altcoin catch-up rallies?
$SOL $AVAX $LINK
A major development has emerged from traditional brokerage giant Charles Schwab, which manages assets worth over several tens of trillions of dollars: it is reportedly planning to open trading in SOL, AVAX, and LINK to its tens of millions of retail and institutional clients.
Traditional finance incumbents are accelerating customer acquisition, sending three positive signals at once:
Institutional funds flowing to high-quality public chains: After BTC and ETH, high-performance public chains (Solana, Avalanche) and core middleware (Chainlink) have officially received endorsement from a top-tier compliant broker.
A multi-trillion-dollar buying channel: Schwab’s massive traditional wealth management capital pool enables one-click, compliant allocation of mainstream altcoins without cumbersome on-chain operations—greatly expanding liquidity access.
Accelerating RWA and on-chain infrastructure deployment: LINK oracle standards and Avalanche subnet architecture are exactly the foundational pillars the Wall Street crowd needs to tokenize real-world assets.
With mainstream brokers moving in en masse, do you think this will ignite a new wave of mainstream Altcoin catch-up rallies?
$SOL $AVAX $LINK
181
·
--
After the hawkish remarks in Washington, D.C., BTC fell back from the $80,000 level to a period of high-range consolidation, while spot gold also dropped by more than 1.3% in tandem. Recently, the correlation between BTC and gold amid macro interest-rate disruptions has significantly strengthened, showing a highly consistent liquidity-sensitive pattern.
The tug-of-war at elevated levels between the two assets sends deeper signals:
Macro liquidity leads pricing: When U.S. Treasury yields rise and rate-hike expectations increase, both gold—an asset with no yield—and high-beta BTC are pressured by the rise in risk-free discount rates.
Reserve-asset attribute resonance: Whether central banks add to gold holdings or institutions allocate to BTC, both fundamentally serve to hedge against fiat currency debt expansion; when tightening expectations heat up, their price action moves in near lockstep.
Key support-zone positioning: BTC shows very strong absorption in the $76,000–$78,000 range. Pullbacks and sweeps may actually help solidify the structure of chips for the next phase.
Do you think the strong correlation between BTC and gold confirms the status of “digital gold,” or is it merely a short-term limitation from liquidity?
$BTC $XAU
After the hawkish remarks in Washington, D.C., BTC fell back from the $80,000 level to a period of high-range consolidation, while spot gold also dropped by more than 1.3% in tandem. Recently, the correlation between BTC and gold amid macro interest-rate disruptions has significantly strengthened, showing a highly consistent liquidity-sensitive pattern.
The tug-of-war at elevated levels between the two assets sends deeper signals:
Macro liquidity leads pricing: When U.S. Treasury yields rise and rate-hike expectations increase, both gold—an asset with no yield—and high-beta BTC are pressured by the rise in risk-free discount rates.
Reserve-asset attribute resonance: Whether central banks add to gold holdings or institutions allocate to BTC, both fundamentally serve to hedge against fiat currency debt expansion; when tightening expectations heat up, their price action moves in near lockstep.
Key support-zone positioning: BTC shows very strong absorption in the $76,000–$78,000 range. Pullbacks and sweeps may actually help solidify the structure of chips for the next phase.
Do you think the strong correlation between BTC and gold confirms the status of “digital gold,” or is it merely a short-term limitation from liquidity?
$BTC $XAU
The tug-of-war at elevated levels between the two assets sends deeper signals:
Macro liquidity leads pricing: When U.S. Treasury yields rise and rate-hike expectations increase, both gold—an asset with no yield—and high-beta BTC are pressured by the rise in risk-free discount rates.
Reserve-asset attribute resonance: Whether central banks add to gold holdings or institutions allocate to BTC, both fundamentally serve to hedge against fiat currency debt expansion; when tightening expectations heat up, their price action moves in near lockstep.
Key support-zone positioning: BTC shows very strong absorption in the $76,000–$78,000 range. Pullbacks and sweeps may actually help solidify the structure of chips for the next phase.
Do you think the strong correlation between BTC and gold confirms the status of “digital gold,” or is it merely a short-term limitation from liquidity?
$BTC $XAU
127
·
--
Nvidia surged 8.7% in a single day—but don’t let the market’s headline red make you think everything’s fine.
On 8/27, the S&P 500 rose 0.58% to 0.7%, looking like a picture of prosperity. But when you break it down, among 11 sectors, 10 closed lower—only technology finished up. The equal-weight index (treating the 500 stocks with equal weight, unaffected by the market cap of a few giants) actually fell 0.16% that day. The gap between that and the market-cap-weighted index’s gain—61 to 71 basis points—precisely measures just how concentrated this rally is in a tiny handful of stocks.
The biggest laggards were defensive sectors such as health care, utilities, and consumer staples. Money was clearly pulled out of these areas and flowed back into semiconductors and software. In just that one day, Nvidia added roughly $435 billion in market value out of thin air—an amount larger than the total market cap of the vast majority of publicly listed U.S. companies.
Even more intriguing: this time, Nvidia’s guidance completely did not factor in data-center operating revenue from China. In other words, even after removing the entire China market, Nvidia’s growth momentum from other regions alone was already enough to push it past the guidance number that beat expectations.
This isn’t a broad-based bull market. In an environment of high inflation and expectations of high interest rates, capital has nowhere else to go, forcing it to cluster into the AI core leaders with the highest certainty of profit. At the same time, it is accelerating its retreat from defensive traditional industries and other sectors. On the index’s surface, it looks like business as usual—but in reality, Nvidia is the one shining, while most other sectors are quietly bleeding.
This level of concentration isn’t unusual in historical context either—combined weight of the top five holdings is the highest since the dot-com bubble. The difference this time is that today’s giants are supported by real, sustained earnings, not just imagined upside.
A single company’s one-day increase in market value is more than the market value evaporated by the entire defensive sector that day. Do you see that as a reasonable reflection of the AI dominance era—or a warning sign that risk is becoming over-concentrated?
$NVDA
Nvidia surged 8.7% in a single day—but don’t let the market’s headline red make you think everything’s fine.
On 8/27, the S&P 500 rose 0.58% to 0.7%, looking like a picture of prosperity. But when you break it down, among 11 sectors, 10 closed lower—only technology finished up. The equal-weight index (treating the 500 stocks with equal weight, unaffected by the market cap of a few giants) actually fell 0.16% that day. The gap between that and the market-cap-weighted index’s gain—61 to 71 basis points—precisely measures just how concentrated this rally is in a tiny handful of stocks.
The biggest laggards were defensive sectors such as health care, utilities, and consumer staples. Money was clearly pulled out of these areas and flowed back into semiconductors and software. In just that one day, Nvidia added roughly $435 billion in market value out of thin air—an amount larger than the total market cap of the vast majority of publicly listed U.S. companies.
Even more intriguing: this time, Nvidia’s guidance completely did not factor in data-center operating revenue from China. In other words, even after removing the entire China market, Nvidia’s growth momentum from other regions alone was already enough to push it past the guidance number that beat expectations.
This isn’t a broad-based bull market. In an environment of high inflation and expectations of high interest rates, capital has nowhere else to go, forcing it to cluster into the AI core leaders with the highest certainty of profit. At the same time, it is accelerating its retreat from defensive traditional industries and other sectors. On the index’s surface, it looks like business as usual—but in reality, Nvidia is the one shining, while most other sectors are quietly bleeding.
This level of concentration isn’t unusual in historical context either—combined weight of the top five holdings is the highest since the dot-com bubble. The difference this time is that today’s giants are supported by real, sustained earnings, not just imagined upside.
A single company’s one-day increase in market value is more than the market value evaporated by the entire defensive sector that day. Do you see that as a reasonable reflection of the AI dominance era—or a warning sign that risk is becoming over-concentrated?
$NVDA
On 8/27, the S&P 500 rose 0.58% to 0.7%, looking like a picture of prosperity. But when you break it down, among 11 sectors, 10 closed lower—only technology finished up. The equal-weight index (treating the 500 stocks with equal weight, unaffected by the market cap of a few giants) actually fell 0.16% that day. The gap between that and the market-cap-weighted index’s gain—61 to 71 basis points—precisely measures just how concentrated this rally is in a tiny handful of stocks.
The biggest laggards were defensive sectors such as health care, utilities, and consumer staples. Money was clearly pulled out of these areas and flowed back into semiconductors and software. In just that one day, Nvidia added roughly $435 billion in market value out of thin air—an amount larger than the total market cap of the vast majority of publicly listed U.S. companies.
Even more intriguing: this time, Nvidia’s guidance completely did not factor in data-center operating revenue from China. In other words, even after removing the entire China market, Nvidia’s growth momentum from other regions alone was already enough to push it past the guidance number that beat expectations.
This isn’t a broad-based bull market. In an environment of high inflation and expectations of high interest rates, capital has nowhere else to go, forcing it to cluster into the AI core leaders with the highest certainty of profit. At the same time, it is accelerating its retreat from defensive traditional industries and other sectors. On the index’s surface, it looks like business as usual—but in reality, Nvidia is the one shining, while most other sectors are quietly bleeding.
This level of concentration isn’t unusual in historical context either—combined weight of the top five holdings is the highest since the dot-com bubble. The difference this time is that today’s giants are supported by real, sustained earnings, not just imagined upside.
A single company’s one-day increase in market value is more than the market value evaporated by the entire defensive sector that day. Do you see that as a reasonable reflection of the AI dominance era—or a warning sign that risk is becoming over-concentrated?
$NVDA
100
·
--
Anthropic estimates a $3 trillion market—can the IPO narrative deliver?
As AI super unicorn Anthropic prepares to release its IPO filing, it has put forward a grand vision of a potential $3 trillion enterprise AI market—igniting intense discussion across global capital markets.
With a $3 trillion super-narrative, can it truly be converted into real cash?
A grand narrative supports lofty valuations: As it heads toward the public markets, anchoring on a trillion-level TAM is the key “killer move” to justify expectations of fundraising on par with SpaceX’s massive capital raise, aiming to capture the scarcity premium of a “pure-blood” AI leader.
The real gap in commercialization: Today, even top large-model companies are still stuck in massive compute procurement and extremely high R&D losses. From “tech that dazzles” to “substantively replacing budgets in enterprise software,” the conversion rate still faces rigorous scrutiny.
A shift in the logic of the secondary market: Wall Street’s view of AI has moved from merely telling stories to evaluating customer lifetime value (LTV) and compute-related gross margins.
Is this “vast expanse” of $3 trillion the inevitable future of an AI revolution, or an IPO-driven valuation bubble meant to raise funds?
#Anthropic #Aİ #IPO #科技股 #large-model
Anthropic estimates a $3 trillion market—can the IPO narrative deliver?
As AI super unicorn Anthropic prepares to release its IPO filing, it has put forward a grand vision of a potential $3 trillion enterprise AI market—igniting intense discussion across global capital markets.
With a $3 trillion super-narrative, can it truly be converted into real cash?
A grand narrative supports lofty valuations: As it heads toward the public markets, anchoring on a trillion-level TAM is the key “killer move” to justify expectations of fundraising on par with SpaceX’s massive capital raise, aiming to capture the scarcity premium of a “pure-blood” AI leader.
The real gap in commercialization: Today, even top large-model companies are still stuck in massive compute procurement and extremely high R&D losses. From “tech that dazzles” to “substantively replacing budgets in enterprise software,” the conversion rate still faces rigorous scrutiny.
A shift in the logic of the secondary market: Wall Street’s view of AI has moved from merely telling stories to evaluating customer lifetime value (LTV) and compute-related gross margins.
Is this “vast expanse” of $3 trillion the inevitable future of an AI revolution, or an IPO-driven valuation bubble meant to raise funds?
#Anthropic #Aİ #IPO #科技股 #large-model
As AI super unicorn Anthropic prepares to release its IPO filing, it has put forward a grand vision of a potential $3 trillion enterprise AI market—igniting intense discussion across global capital markets.
With a $3 trillion super-narrative, can it truly be converted into real cash?
A grand narrative supports lofty valuations: As it heads toward the public markets, anchoring on a trillion-level TAM is the key “killer move” to justify expectations of fundraising on par with SpaceX’s massive capital raise, aiming to capture the scarcity premium of a “pure-blood” AI leader.
The real gap in commercialization: Today, even top large-model companies are still stuck in massive compute procurement and extremely high R&D losses. From “tech that dazzles” to “substantively replacing budgets in enterprise software,” the conversion rate still faces rigorous scrutiny.
A shift in the logic of the secondary market: Wall Street’s view of AI has moved from merely telling stories to evaluating customer lifetime value (LTV) and compute-related gross margins.
Is this “vast expanse” of $3 trillion the inevitable future of an AI revolution, or an IPO-driven valuation bubble meant to raise funds?
#Anthropic #Aİ #IPO #科技股 #large-model
415
·
--
Can it bring a greater good news for humanity—will there be more cures for cancer?
This round of gains for Moderna is textbook-level good news followed by high-level consolidation.
On 8/19, Wednesday, Moderna and Merck (MSD) released Phase 3 clinical data for an mRNA melanoma vaccine—this is the world’s first personalized mRNA cancer therapy to pass Phase 3 trials, a groundbreaking milestone. After the news broke, the stock surged directly from around $63 in pre-market trading on Tuesday, topping out at $176.66 during the session and setting a 52-week high. At one point, the intraday gain exceeded 180%.
What’s truly impressive is what happened in the days after the announcement. The stock didn’t crash back to the starting point in a single, typical “sell after the hype” move. Instead, after reaching the $176.66 peak, it spent nearly a week repeatedly trading and consolidating in the $130–$150 range, closing at $139.10 on 8/24. By calculation, it retraced more than 21% from the high, but the cumulative rise over five days was still as high as more than 120%.
This suggests the market’s reaction is more nuanced than simply “hype it up and run.” Early speculative capital did take profits near the peak, but the stock didn’t collapse back to the launch level. That indicates some investors believe this milestone event has real long-term value and are willing to pick up shares on pullbacks.
The harsh reality in biotech is that success in Phase 3 clinical trials is only the beginning. From FDA formal approval to going to hospitals and generating revenue, there’s still a long path of regulatory reviews and commercialization processes to go through. Merck’s Keytruda is the established standard treatment for post-surgery melanoma. This combination therapy has shown it can delay recurrence and reduce the risk of metastasis. These are solid clinical data, not just an imaginative space.
The fact that the stock keeps tugging higher and lower at high levels rather than plunging straight down, to some extent, indicates the market is repricing Moderna’s oncology pipeline. It’s no longer treating it solely as a company whose COVID-vaccine business is in decline. Next, we need to watch the FDA review progress, as well as follow-up trial data for this personalized mRNA platform in other cancer types such as non-small-cell lung cancer—whether it can replicate the success this time.
From a surge of 180% to a pullback and consolidation of more than 21% at the high end, do you think this is the market finding a reasonable valuation after speculative capital retreats—or that the long-term value of this once-in-an-era breakthrough hasn’t been fully reflected yet?
$MRNA $MRK #美股 #生技股 #CancerVaccine
Can it bring a greater good news for humanity—will there be more cures for cancer?
This round of gains for Moderna is textbook-level good news followed by high-level consolidation.
On 8/19, Wednesday, Moderna and Merck (MSD) released Phase 3 clinical data for an mRNA melanoma vaccine—this is the world’s first personalized mRNA cancer therapy to pass Phase 3 trials, a groundbreaking milestone. After the news broke, the stock surged directly from around $63 in pre-market trading on Tuesday, topping out at $176.66 during the session and setting a 52-week high. At one point, the intraday gain exceeded 180%.
What’s truly impressive is what happened in the days after the announcement. The stock didn’t crash back to the starting point in a single, typical “sell after the hype” move. Instead, after reaching the $176.66 peak, it spent nearly a week repeatedly trading and consolidating in the $130–$150 range, closing at $139.10 on 8/24. By calculation, it retraced more than 21% from the high, but the cumulative rise over five days was still as high as more than 120%.
This suggests the market’s reaction is more nuanced than simply “hype it up and run.” Early speculative capital did take profits near the peak, but the stock didn’t collapse back to the launch level. That indicates some investors believe this milestone event has real long-term value and are willing to pick up shares on pullbacks.
The harsh reality in biotech is that success in Phase 3 clinical trials is only the beginning. From FDA formal approval to going to hospitals and generating revenue, there’s still a long path of regulatory reviews and commercialization processes to go through. Merck’s Keytruda is the established standard treatment for post-surgery melanoma. This combination therapy has shown it can delay recurrence and reduce the risk of metastasis. These are solid clinical data, not just an imaginative space.
The fact that the stock keeps tugging higher and lower at high levels rather than plunging straight down, to some extent, indicates the market is repricing Moderna’s oncology pipeline. It’s no longer treating it solely as a company whose COVID-vaccine business is in decline. Next, we need to watch the FDA review progress, as well as follow-up trial data for this personalized mRNA platform in other cancer types such as non-small-cell lung cancer—whether it can replicate the success this time.
From a surge of 180% to a pullback and consolidation of more than 21% at the high end, do you think this is the market finding a reasonable valuation after speculative capital retreats—or that the long-term value of this once-in-an-era breakthrough hasn’t been fully reflected yet?
$MRNA $MRK #美股 #生技股 #CancerVaccine
This round of gains for Moderna is textbook-level good news followed by high-level consolidation.
On 8/19, Wednesday, Moderna and Merck (MSD) released Phase 3 clinical data for an mRNA melanoma vaccine—this is the world’s first personalized mRNA cancer therapy to pass Phase 3 trials, a groundbreaking milestone. After the news broke, the stock surged directly from around $63 in pre-market trading on Tuesday, topping out at $176.66 during the session and setting a 52-week high. At one point, the intraday gain exceeded 180%.
What’s truly impressive is what happened in the days after the announcement. The stock didn’t crash back to the starting point in a single, typical “sell after the hype” move. Instead, after reaching the $176.66 peak, it spent nearly a week repeatedly trading and consolidating in the $130–$150 range, closing at $139.10 on 8/24. By calculation, it retraced more than 21% from the high, but the cumulative rise over five days was still as high as more than 120%.
This suggests the market’s reaction is more nuanced than simply “hype it up and run.” Early speculative capital did take profits near the peak, but the stock didn’t collapse back to the launch level. That indicates some investors believe this milestone event has real long-term value and are willing to pick up shares on pullbacks.
The harsh reality in biotech is that success in Phase 3 clinical trials is only the beginning. From FDA formal approval to going to hospitals and generating revenue, there’s still a long path of regulatory reviews and commercialization processes to go through. Merck’s Keytruda is the established standard treatment for post-surgery melanoma. This combination therapy has shown it can delay recurrence and reduce the risk of metastasis. These are solid clinical data, not just an imaginative space.
The fact that the stock keeps tugging higher and lower at high levels rather than plunging straight down, to some extent, indicates the market is repricing Moderna’s oncology pipeline. It’s no longer treating it solely as a company whose COVID-vaccine business is in decline. Next, we need to watch the FDA review progress, as well as follow-up trial data for this personalized mRNA platform in other cancer types such as non-small-cell lung cancer—whether it can replicate the success this time.
From a surge of 180% to a pullback and consolidation of more than 21% at the high end, do you think this is the market finding a reasonable valuation after speculative capital retreats—or that the long-term value of this once-in-an-era breakthrough hasn’t been fully reflected yet?
$MRNA $MRK #美股 #生技股 #CancerVaccine
332
·
--
#BTC Accelerates the Rally—Can the Capital Keep Passing the Torch?
BTC finally broke months of deadlock and surged straight through $75,000! This massive bullish candle has directly detonated bearish positions across the entire network, with the daily liquidation amount briefly nearing $3 billion. More importantly, the funding situation is showing signs of warming: on August 19, spot ETF inflows in U.S. stocks exceeded $700 million (BTC $517 million, ETH $189 million).
But amid the celebration, how far can this move really go?
Short Squeeze and Liquidation Outweighs Real Accumulation: Earlier short positions were too crowded. The moment prices started to peek higher, it triggered a chain of liquidations, severely amplifying short-term gains through leverage.
Incremental capital is the only true test: ETF returns are a good sign, but whether this can evolve from an “oversold rebound” into a “major uptrend” depends on whether the subsequent stablecoin supply and spot trading volume can keep pace.
Watch for the risk of shakeouts at high levels: Above $75,000, a large amount of historical trapped capital and short-term profit-taking sits clustered there. If volume support doesn’t follow through, leverage can rebuild quickly and trigger violent wick spikes.
Do you think this rally is the start of a new bull-market offensive, or just a temporary top after the shorts have been harvested?
$BTC $ETH #BTC #加密货币 #Market Analysis
#BTC Accelerates the Rally—Can the Capital Keep Passing the Torch?
BTC finally broke months of deadlock and surged straight through $75,000! This massive bullish candle has directly detonated bearish positions across the entire network, with the daily liquidation amount briefly nearing $3 billion. More importantly, the funding situation is showing signs of warming: on August 19, spot ETF inflows in U.S. stocks exceeded $700 million (BTC $517 million, ETH $189 million).
But amid the celebration, how far can this move really go?
Short Squeeze and Liquidation Outweighs Real Accumulation: Earlier short positions were too crowded. The moment prices started to peek higher, it triggered a chain of liquidations, severely amplifying short-term gains through leverage.
Incremental capital is the only true test: ETF returns are a good sign, but whether this can evolve from an “oversold rebound” into a “major uptrend” depends on whether the subsequent stablecoin supply and spot trading volume can keep pace.
Watch for the risk of shakeouts at high levels: Above $75,000, a large amount of historical trapped capital and short-term profit-taking sits clustered there. If volume support doesn’t follow through, leverage can rebuild quickly and trigger violent wick spikes.
Do you think this rally is the start of a new bull-market offensive, or just a temporary top after the shorts have been harvested?
$BTC $ETH #BTC #加密货币 #Market Analysis
BTC finally broke months of deadlock and surged straight through $75,000! This massive bullish candle has directly detonated bearish positions across the entire network, with the daily liquidation amount briefly nearing $3 billion. More importantly, the funding situation is showing signs of warming: on August 19, spot ETF inflows in U.S. stocks exceeded $700 million (BTC $517 million, ETH $189 million).
But amid the celebration, how far can this move really go?
Short Squeeze and Liquidation Outweighs Real Accumulation: Earlier short positions were too crowded. The moment prices started to peek higher, it triggered a chain of liquidations, severely amplifying short-term gains through leverage.
Incremental capital is the only true test: ETF returns are a good sign, but whether this can evolve from an “oversold rebound” into a “major uptrend” depends on whether the subsequent stablecoin supply and spot trading volume can keep pace.
Watch for the risk of shakeouts at high levels: Above $75,000, a large amount of historical trapped capital and short-term profit-taking sits clustered there. If volume support doesn’t follow through, leverage can rebuild quickly and trigger violent wick spikes.
Do you think this rally is the start of a new bull-market offensive, or just a temporary top after the shorts have been harvested?
$BTC $ETH #BTC #加密货币 #Market Analysis
216
·
--
Google granted Marvell a stock option worth up to $12.2 billion. But what’s really noteworthy isn’t that $12.2 billion.
Google obtained rights to buy up to 58.97 million shares of Marvell common stock at an exercise price of $206.58. If fully exercised, the value would be about $12.2 billion—roughly 7% of Marvell’s current outstanding share count. After the news was announced, Marvell surged more than 8% in premarket trading to as high as 14%, while Broadcom—the original main custom-chip partner—reversed and fell more than 5%.
This collaboration is meant to help Google develop a series of custom chips around the TPU ecosystem—AI inference accelerators, storage controllers, network interface controllers, memory interface controllers, and near-memory computing technologies. If Google meets future procurement targets, the potential revenue from this partnership could reach $120 billion by fiscal year 2033.
There’s a detail many media headlines ignore. This $12.2 billion stock option isn’t paid out all at once, and Google hasn’t already wired the money into Marvell’s account. Only about 1.36 million shares would be acquired in the first year, on a quarterly basis, with the remaining shares split into 240 tranches. Each time Google purchases $500 million worth of the custom products from Marvell, another batch gets unlocked. In other words, Google’s equity stake in Marvell would grow in step with the actual procurement amounts—not a sure $12.2 billion being locked in on the signing date.
The market’s initial reaction was that Marvell won and Broadcom lost. But a more grounded interpretation may be that the “pie” for Google’s AI chips is getting bigger—rather than orders being taken away from Broadcom. After all, Google only signed a deal with Broadcom in April to design custom TPUs. Now it has brought Marvell in as a second supplier, which really points to a growing trend: ultra-large cloud operators don’t want to put all their AI-chip supply into a single vendor.
Amazon has its own Trainium and Inferentia, and Microsoft and Meta are also developing their own AI chips. When the backend behind Google’s TPU evolves from relying solely on Broadcom to including Broadcom plus Marvell—and potentially even more suppliers in the future—it suggests the AI-chip market may no longer just be a duopoly battle between Nvidia and the other side. The real next war is whether ultra-large cloud operators want to design chips themselves. If the answer is yes, the beneficiaries won’t be limited to GPU companies—it will also include custom chip design firms, foundries, advanced packaging providers, optical communications, high-bandwidth memory, and the entire supply chain, which could all see their pricing reshaped.
The next validation point is Marvell’s own earnings report on 8/27. The market will want to know whether this Google collaboration can be explained with a clearer revenue timeline. If management can provide more concrete visibility into the long-term outlook, the market may start reassessing the company’s valuation.
That said, this structure isn’t without risk. The collaboration revenue will likely be realized gradually over a long period. Broadcom could still remain one of Google’s partners. Marvell’s current valuation is also not cheap, and custom-chip development costs are high. If AI capital expenditures slow down in the future, these long-term tied orders would be dragged down as well.
Nvidia’s GPUs, Google’s TPU, and now Marvell’s custom chips—do you think the next AI semiconductor supercycle will be bigger than the story of the GPU market alone?
$MRVL $AVGO $GOOGL #美股 #AI供應鏈 #半導體
Google granted Marvell a stock option worth up to $12.2 billion. But what’s really noteworthy isn’t that $12.2 billion.
Google obtained rights to buy up to 58.97 million shares of Marvell common stock at an exercise price of $206.58. If fully exercised, the value would be about $12.2 billion—roughly 7% of Marvell’s current outstanding share count. After the news was announced, Marvell surged more than 8% in premarket trading to as high as 14%, while Broadcom—the original main custom-chip partner—reversed and fell more than 5%.
This collaboration is meant to help Google develop a series of custom chips around the TPU ecosystem—AI inference accelerators, storage controllers, network interface controllers, memory interface controllers, and near-memory computing technologies. If Google meets future procurement targets, the potential revenue from this partnership could reach $120 billion by fiscal year 2033.
There’s a detail many media headlines ignore. This $12.2 billion stock option isn’t paid out all at once, and Google hasn’t already wired the money into Marvell’s account. Only about 1.36 million shares would be acquired in the first year, on a quarterly basis, with the remaining shares split into 240 tranches. Each time Google purchases $500 million worth of the custom products from Marvell, another batch gets unlocked. In other words, Google’s equity stake in Marvell would grow in step with the actual procurement amounts—not a sure $12.2 billion being locked in on the signing date.
The market’s initial reaction was that Marvell won and Broadcom lost. But a more grounded interpretation may be that the “pie” for Google’s AI chips is getting bigger—rather than orders being taken away from Broadcom. After all, Google only signed a deal with Broadcom in April to design custom TPUs. Now it has brought Marvell in as a second supplier, which really points to a growing trend: ultra-large cloud operators don’t want to put all their AI-chip supply into a single vendor.
Amazon has its own Trainium and Inferentia, and Microsoft and Meta are also developing their own AI chips. When the backend behind Google’s TPU evolves from relying solely on Broadcom to including Broadcom plus Marvell—and potentially even more suppliers in the future—it suggests the AI-chip market may no longer just be a duopoly battle between Nvidia and the other side. The real next war is whether ultra-large cloud operators want to design chips themselves. If the answer is yes, the beneficiaries won’t be limited to GPU companies—it will also include custom chip design firms, foundries, advanced packaging providers, optical communications, high-bandwidth memory, and the entire supply chain, which could all see their pricing reshaped.
The next validation point is Marvell’s own earnings report on 8/27. The market will want to know whether this Google collaboration can be explained with a clearer revenue timeline. If management can provide more concrete visibility into the long-term outlook, the market may start reassessing the company’s valuation.
That said, this structure isn’t without risk. The collaboration revenue will likely be realized gradually over a long period. Broadcom could still remain one of Google’s partners. Marvell’s current valuation is also not cheap, and custom-chip development costs are high. If AI capital expenditures slow down in the future, these long-term tied orders would be dragged down as well.
Nvidia’s GPUs, Google’s TPU, and now Marvell’s custom chips—do you think the next AI semiconductor supercycle will be bigger than the story of the GPU market alone?
$MRVL $AVGO $GOOGL #美股 #AI供應鏈 #半導體
Google obtained rights to buy up to 58.97 million shares of Marvell common stock at an exercise price of $206.58. If fully exercised, the value would be about $12.2 billion—roughly 7% of Marvell’s current outstanding share count. After the news was announced, Marvell surged more than 8% in premarket trading to as high as 14%, while Broadcom—the original main custom-chip partner—reversed and fell more than 5%.
This collaboration is meant to help Google develop a series of custom chips around the TPU ecosystem—AI inference accelerators, storage controllers, network interface controllers, memory interface controllers, and near-memory computing technologies. If Google meets future procurement targets, the potential revenue from this partnership could reach $120 billion by fiscal year 2033.
There’s a detail many media headlines ignore. This $12.2 billion stock option isn’t paid out all at once, and Google hasn’t already wired the money into Marvell’s account. Only about 1.36 million shares would be acquired in the first year, on a quarterly basis, with the remaining shares split into 240 tranches. Each time Google purchases $500 million worth of the custom products from Marvell, another batch gets unlocked. In other words, Google’s equity stake in Marvell would grow in step with the actual procurement amounts—not a sure $12.2 billion being locked in on the signing date.
The market’s initial reaction was that Marvell won and Broadcom lost. But a more grounded interpretation may be that the “pie” for Google’s AI chips is getting bigger—rather than orders being taken away from Broadcom. After all, Google only signed a deal with Broadcom in April to design custom TPUs. Now it has brought Marvell in as a second supplier, which really points to a growing trend: ultra-large cloud operators don’t want to put all their AI-chip supply into a single vendor.
Amazon has its own Trainium and Inferentia, and Microsoft and Meta are also developing their own AI chips. When the backend behind Google’s TPU evolves from relying solely on Broadcom to including Broadcom plus Marvell—and potentially even more suppliers in the future—it suggests the AI-chip market may no longer just be a duopoly battle between Nvidia and the other side. The real next war is whether ultra-large cloud operators want to design chips themselves. If the answer is yes, the beneficiaries won’t be limited to GPU companies—it will also include custom chip design firms, foundries, advanced packaging providers, optical communications, high-bandwidth memory, and the entire supply chain, which could all see their pricing reshaped.
The next validation point is Marvell’s own earnings report on 8/27. The market will want to know whether this Google collaboration can be explained with a clearer revenue timeline. If management can provide more concrete visibility into the long-term outlook, the market may start reassessing the company’s valuation.
That said, this structure isn’t without risk. The collaboration revenue will likely be realized gradually over a long period. Broadcom could still remain one of Google’s partners. Marvell’s current valuation is also not cheap, and custom-chip development costs are high. If AI capital expenditures slow down in the future, these long-term tied orders would be dragged down as well.
Nvidia’s GPUs, Google’s TPU, and now Marvell’s custom chips—do you think the next AI semiconductor supercycle will be bigger than the story of the GPU market alone?
$MRVL $AVGO $GOOGL #美股 #AI供應鏈 #半導體
282
·
--
Kaito Katalyst Round 1 project Axis Robotics officially kicks off. The ROI differences across three “fur-pulling” (token-farming) paths are quite clear:
Content creation (0.2% allocation): limited to the first 500 participants (top 100 receive 0.1%, ranks 101–500 receive 0.1%). Pure grind on attention and reach.
$KAITO Staking (0.05% allocation): the threshold is about 5,000 $sKAITO (you need to stake about 5,810 $KAITO on the Base chain). Suitable for “lazy” people—just stake and lie back to share the air drop.
Interactive project tasks: use browser-side remote control to operate the robotic arm and pick up objects to complete data labeling. There are 9 tasks total, with only 1,200 slots available (some are already full).
Doing tasks manually helps the project feed real-world body (embodied) data, while staking is for eating ecosystem Alpha.
So, are you going to grind it out with brute strength in this round—or just stake and lie back?
#Kaito #AxisRobotics #空投 #DePIN #Web3
Kaito Katalyst Round 1 project Axis Robotics officially kicks off. The ROI differences across three “fur-pulling” (token-farming) paths are quite clear:
Content creation (0.2% allocation): limited to the first 500 participants (top 100 receive 0.1%, ranks 101–500 receive 0.1%). Pure grind on attention and reach.
$KAITO Staking (0.05% allocation): the threshold is about 5,000 $sKAITO (you need to stake about 5,810 $KAITO on the Base chain). Suitable for “lazy” people—just stake and lie back to share the air drop.
Interactive project tasks: use browser-side remote control to operate the robotic arm and pick up objects to complete data labeling. There are 9 tasks total, with only 1,200 slots available (some are already full).
Doing tasks manually helps the project feed real-world body (embodied) data, while staking is for eating ecosystem Alpha.
So, are you going to grind it out with brute strength in this round—or just stake and lie back?
#Kaito #AxisRobotics #空投 #DePIN #Web3
Content creation (0.2% allocation): limited to the first 500 participants (top 100 receive 0.1%, ranks 101–500 receive 0.1%). Pure grind on attention and reach.
$KAITO Staking (0.05% allocation): the threshold is about 5,000 $sKAITO (you need to stake about 5,810 $KAITO on the Base chain). Suitable for “lazy” people—just stake and lie back to share the air drop.
Interactive project tasks: use browser-side remote control to operate the robotic arm and pick up objects to complete data labeling. There are 9 tasks total, with only 1,200 slots available (some are already full).
Doing tasks manually helps the project feed real-world body (embodied) data, while staking is for eating ecosystem Alpha.
So, are you going to grind it out with brute strength in this round—or just stake and lie back?
#Kaito #AxisRobotics #空投 #DePIN #Web3
222
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
FedRateWatch
1.6M views
6,931 Discussing
Share & Win Traffic Reward in our Trending Hashtag Campaign
✨Topic: FOMC September, What's The Fed's Next Move?
👉How to Join:
Publish a short post or article with hashtag #FedRateWatch
Create content based on the below angles:
- August core CPI rose 0.3% month-over-month, and the odds of a 25bp hike this week are now close to 90%. Do you anticipate a rate hike this week? Is it a one-off, or the start of a longer hiking cycle?
- If the hike lands, how does it play out for BTC, tech stocks, and gold? Bullish or bearish?
- How are you planning to trade next? Share your BTC, stocks or gold trade/holdings with our trade sharing widget.
⏰Campaign Period:
- 2026-09-15 11:00 - 2026-09-17 3:00 UTC
🎁Reward:
- Qualified posts that comply with the above guidelines and contain more than 100 words will be reviewed and may receive a random traffic boost of 500 to 3,000 views. You will receive a notification from your feed secretary if your post is selected.
- Get a chance to have your article featured on Binance Square Official
Need ideas for your post? Visit the topic page #FedRateWatch or the Square Guide on How to Post for Better Reach.
Binance Square Official
·657 Likes
·1.7M views
ZcashRises6%
69,829 views
735 Discussing
XRPSinks10%
45,218 views
487 Discussing