

SVIATOSLAV GUSEV
816 Posts
SVIATOSLAV GUSEV
Report
Block User
Deeply immersed in the IT world, exploring with passion and gaining insights. Actively investing in blockchain ventures at the very nexus of Web3 innovations.
0 Following
111 Followers
363 Liked
Posts
$SOL A company that called itself a Solana treasury a year ago has sold all its SOL. Every last coin. SkyAI accumulated more than 2 million coins at an average price of around $194. SOL is now trading at around $104, and the money isn’t going toward new purchases, but toward buying back its own shares for 201$ million. Exactly the kind of thing people usually laugh at retail investors for: buying into the hype and getting out when things get scary. But there’s another detail in this story that interests me. The big seller has already sold, its coins have been distributed across the market, and yet the price is still holding above $100. To me, that’s more of a good sign than a bad one. The plan based on levels is simple. As long as SOL stays above $100, I expect an attempt to return to $120, the top of the range from recent months. If 100$ breaks on a daily close, the market could easily move to the lower end of the range; back in June, the coin was trading at $62. And remember the Fed meeting on October 28—it’ll be a nervy ride until then. Would you have held on if you were in SkyAI’s shoes, or would you have cashed out too?
$SOL A company that called itself a Solana treasury a year ago has sold all its SOL. Every last coin. SkyAI accumulated more than 2 million coins at an average price of around $194. SOL is now trading at around $104, and the money isn’t going toward new purchases, but toward buying back its own shares for 201$ million. Exactly the kind of thing people usually laugh at retail investors for: buying into the hype and getting out when things get scary. But there’s another detail in this story that interests me. The big seller has already sold, its coins have been distributed across the market, and yet the price is still holding above $100. To me, that’s more of a good sign than a bad one. The plan based on levels is simple. As long as SOL stays above $100, I expect an attempt to return to $120, the top of the range from recent months. If 100$ breaks on a daily close, the market could easily move to the lower end of the range; back in June, the coin was trading at $62. And remember the Fed meeting on October 28—it’ll be a nervy ride until then. Would you have held on if you were in SkyAI’s shoes, or would you have cashed out too?
91
The most influential person for crypto this week isn’t Fed chief Warsh—it’s the captain of any tanker currently passing through the Strait of Hormuz. Look at the chain reaction. Attacks on vessels have cut oil flows from the Gulf to around 8.5 million barrels a day, down from more than 20 million the week before. Brent closed Friday at its highest level since May and is now around $108. In September’s CPI, gasoline accounted for more than half of the monthly price increase. That’s why inflation is at 3.7% and people are talking about a rate hike in December. And today, Warsh said outright that he wouldn’t make any promises in advance. In other words, the Fed will watch oil and make its decision based on what happens. Which means we should be watching it too. My take: as long as Brent is above $100, any crypto bounce is a breather, not a reversal. This morning, Bitcoin touched 83k and immediately pulled back. The market knows where the real lever is right now. Are you keeping an eye on oil, or just the chart?
The most influential person for crypto this week isn’t Fed chief Warsh—it’s the captain of any tanker currently passing through the Strait of Hormuz. Look at the chain reaction. Attacks on vessels have cut oil flows from the Gulf to around 8.5 million barrels a day, down from more than 20 million the week before. Brent closed Friday at its highest level since May and is now around $108. In September’s CPI, gasoline accounted for more than half of the monthly price increase. That’s why inflation is at 3.7% and people are talking about a rate hike in December. And today, Warsh said outright that he wouldn’t make any promises in advance. In other words, the Fed will watch oil and make its decision based on what happens. Which means we should be watching it too. My take: as long as Brent is above $100, any crypto bounce is a breather, not a reversal. This morning, Bitcoin touched 83k and immediately pulled back. The market knows where the real lever is right now. Are you keeping an eye on oil, or just the chart?
155
The worst thing about the Qubic incident isn’t even the 1,4$ million. It’s that the people did nothing wrong. They didn’t click phishing links, show anyone their seed phrase, or install shady extensions. They simply created a wallet in a browser on an iPhone or in Safari on a Mac. And the randomness turned out not to be so random after all. The result: more than 1,400 drained wallets and a halted network. We’re used to thinking that security is about how you store your seed. Write it down on a piece of paper, hide it, tell no one. But if the phrase was weak to begin with, no safe can protect it. It doesn’t need to be stolen; it can simply be guessed. And this isn’t the first case like this: weak seeds have turned up in browser extensions and even in the firmware of hardware wallets. So my rule is simple: serious money doesn’t belong in a wallet created in a browser tab, and it shouldn’t all be kept on a single seed. Do you remember where you generated yours?
The worst thing about the Qubic incident isn’t even the 1,4$ million. It’s that the people did nothing wrong. They didn’t click phishing links, show anyone their seed phrase, or install shady extensions. They simply created a wallet in a browser on an iPhone or in Safari on a Mac. And the randomness turned out not to be so random after all. The result: more than 1,400 drained wallets and a halted network. We’re used to thinking that security is about how you store your seed. Write it down on a piece of paper, hide it, tell no one. But if the phrase was weak to begin with, no safe can protect it. It doesn’t need to be stolen; it can simply be guessed. And this isn’t the first case like this: weak seeds have turned up in browser extensions and even in the firmware of hardware wallets. So my rule is simple: serious money doesn’t belong in a wallet created in a browser tab, and it shouldn’t all be kept on a single seed. Do you remember where you generated yours?
76
$BTC The most important number for Bitcoin right now isn’t 80 thousand or 100, but $82,300. That’s roughly the average price at which spot ETF buyers entered. On Thursday, the price fell below 80k, and now, at around $81,200, the average fund holder is looking at a loss. And that changes the psychology. While you’re in profit, you hold on. When you’re in the red, every bounce back to your entry price becomes a chance to break even. Hence the picture: about 910$ million flowed out of funds over two weeks, and October is in the red for them. Hot CPI at 3.7% and talk of another rate hike added fuel to the fire. When risk-free investments pay around 5%, holding a volatile asset is psychologically harder. My scenario is simple. If we hold above 82 300$ —sellers will run out of steam, opening the way to 84k. Lose 80k—and the market will go looking for the point where these buyers run out of patience. Until the FOMC meeting on October 28, I expect choppy trading between these levels. Would you buy more now or wait for the Fed?
$BTC The most important number for Bitcoin right now isn’t 80 thousand or 100, but $82,300. That’s roughly the average price at which spot ETF buyers entered. On Thursday, the price fell below 80k, and now, at around $81,200, the average fund holder is looking at a loss. And that changes the psychology. While you’re in profit, you hold on. When you’re in the red, every bounce back to your entry price becomes a chance to break even. Hence the picture: about 910$ million flowed out of funds over two weeks, and October is in the red for them. Hot CPI at 3.7% and talk of another rate hike added fuel to the fire. When risk-free investments pay around 5%, holding a volatile asset is psychologically harder. My scenario is simple. If we hold above 82 300$ —sellers will run out of steam, opening the way to 84k. Lose 80k—and the market will go looking for the point where these buyers run out of patience. Until the FOMC meeting on October 28, I expect choppy trading between these levels. Would you buy more now or wait for the Fed?
99
In just one week, regulators divided the digital dollar into “theirs” and “others.” On October 8, ESMA told European exchanges to stop servicing stablecoins without a MiCA license and close out existing positions within three months, roughly by January 8. That includes $USDT. Then, on October 14, the EBA recognized USDC as the first “significant” stablecoin in the EU, out of 45 registered. Since November 12, its reserves and liquidity have been monitored by the EBA itself. In the US, it’s the same story, just taking a different route. The OCC has promised final rules under the GENIUS Act by the end of October: 1:1 reserves, monthly reporting, and no interest for holders. The law takes effect on January 18. My take: stablecoins are ceasing to be a crypto product and becoming a banking product. For $BTC, that’s probably a plus—the money coming in will be cleaner and larger. But the easy route of using any stablecoin on any exchange is coming to an end. If you’re in Europe, what do you use to hold dollars on an exchange?
In just one week, regulators divided the digital dollar into “theirs” and “others.” On October 8, ESMA told European exchanges to stop servicing stablecoins without a MiCA license and close out existing positions within three months, roughly by January 8. That includes $USDT. Then, on October 14, the EBA recognized USDC as the first “significant” stablecoin in the EU, out of 45 registered. Since November 12, its reserves and liquidity have been monitored by the EBA itself. In the US, it’s the same story, just taking a different route. The OCC has promised final rules under the GENIUS Act by the end of October: 1:1 reserves, monthly reporting, and no interest for holders. The law takes effect on January 18. My take: stablecoins are ceasing to be a crypto product and becoming a banking product. For $BTC, that’s probably a plus—the money coming in will be cleaner and larger. But the easy route of using any stablecoin on any exchange is coming to an end. If you’re in Europe, what do you use to hold dollars on an exchange?
87
$ETH bounced to 2 460$ after hitting a two-month low of 2 313$ on Thursday. But for now, this is a bounce after a long squeeze, not a return of demand. Looking at fund flows: in October, spot Ether ETFs were positive only on the 13th. Another 190$ million or so flowed out on October 14 and 15, while on the 15th, $BTC funds received +5$ million. VanEck also withdrew its application for an ETF with staking through Lido. Institutions are choosing Bitcoin, not Ether. Key levels: below, that same low of 2 313$: if it breaks, the next support, in my view, is around $2,200. Above, $2,550, roughly the 50-day moving average. As long as the price is below it, any rise is a bounce, not a trend. My take: Ether needs more than a green day—it needs at least a week of ETF inflows. Without that, the ETH/BTC pair around 0.030 will keep drifting lower. What would bring money back into Ether: staking within an ETF, or simply a Fed rate reversal?
$ETH bounced to 2 460$ after hitting a two-month low of 2 313$ on Thursday. But for now, this is a bounce after a long squeeze, not a return of demand. Looking at fund flows: in October, spot Ether ETFs were positive only on the 13th. Another 190$ million or so flowed out on October 14 and 15, while on the 15th, $BTC funds received +5$ million. VanEck also withdrew its application for an ETF with staking through Lido. Institutions are choosing Bitcoin, not Ether. Key levels: below, that same low of 2 313$: if it breaks, the next support, in my view, is around $2,200. Above, $2,550, roughly the 50-day moving average. As long as the price is below it, any rise is a bounce, not a trend. My take: Ether needs more than a green day—it needs at least a week of ETF inflows. Without that, the ETH/BTC pair around 0.030 will keep drifting lower. What would bring money back into Ether: staking within an ETF, or simply a Fed rate reversal?
80
U.S. CPI came out yesterday: 3.7% year over year, after 3.4% in August. Core CPI was 2.6%, up from 2.4%. The index rose 0.6% month over month. The market immediately raised the odds of a Fed rate hike in October to nearly 50%, then pulled back to around 26–30%. Over the past 24 hours, about 483$ million positions in $BTC and $ETH were liquidated—around 286$ million of them in ether. Bitcoin spot ETFs saw outflows of 150,5$ million on October 14, after inflows of 175,7$ the day before. $BTC is around 81k. My take: this is a nervous leverage flush triggered by a single data point, not “rates up forever.” Ahead of the October 28 FOMC meeting, markets are once again pricing in a greater than 70% chance of a hold. The question isn’t about one CPI print, but whether $BTC can withstand a couple more days like this without another wave of leveraged longs. How many more hot reports will it take for the market to stop treating every data point like a verdict?
U.S. CPI came out yesterday: 3.7% year over year, after 3.4% in August. Core CPI was 2.6%, up from 2.4%. The index rose 0.6% month over month. The market immediately raised the odds of a Fed rate hike in October to nearly 50%, then pulled back to around 26–30%. Over the past 24 hours, about 483$ million positions in $BTC and $ETH were liquidated—around 286$ million of them in ether. Bitcoin spot ETFs saw outflows of 150,5$ million on October 14, after inflows of 175,7$ the day before. $BTC is around 81k. My take: this is a nervous leverage flush triggered by a single data point, not “rates up forever.” Ahead of the October 28 FOMC meeting, markets are once again pricing in a greater than 70% chance of a hold. The question isn’t about one CPI print, but whether $BTC can withstand a couple more days like this without another wave of leveraged longs. How many more hot reports will it take for the market to stop treating every data point like a verdict?
79
Today at 14:30 Warsaw time, the US CPI report comes out, and everyone is wondering whether the Fed will raise rates on October 28. Hammack of Cleveland is already openly calling for a hike. But let’s look at how much the debt itself costs. The US national debt stood at 40,17$ trillion on September 30. For fiscal year 2026, the Treasury tallied 1,36$ trillion in interest expenses, 11.5% more than a year earlier. Net interest in the budget for 11 months came to 1,02$ trillion. That’s already more than the entire defense budget (876$ billion). My take: every rate hike now hits not just inflation, but also the budget, which pays that interest with new debt. The Fed is caught between prices and debt, and sooner or later it will choose debt. For $BTC around 83k, a hot CPI is a one-day negative, but over a one-year horizon, this is exactly what the story is about. Question: how much longer can the Fed raise rates when interest alone costs 1,36$ trillion a year? #Bitcoin #CPI
Today at 14:30 Warsaw time, the US CPI report comes out, and everyone is wondering whether the Fed will raise rates on October 28. Hammack of Cleveland is already openly calling for a hike. But let’s look at how much the debt itself costs. The US national debt stood at 40,17$ trillion on September 30. For fiscal year 2026, the Treasury tallied 1,36$ trillion in interest expenses, 11.5% more than a year earlier. Net interest in the budget for 11 months came to 1,02$ trillion. That’s already more than the entire defense budget (876$ billion). My take: every rate hike now hits not just inflation, but also the budget, which pays that interest with new debt. The Fed is caught between prices and debt, and sooner or later it will choose debt. For $BTC around 83k, a hot CPI is a one-day negative, but over a one-year horizon, this is exactly what the story is about. Question: how much longer can the Fed raise rates when interest alone costs 1,36$ trillion a year? #Bitcoin #CPI
83
Asia’s AI trade is breaking down today. The KOSPI closed down 5.46% (it was down 7% intraday, triggering a sidecar), SK hynix fell 10%, Samsung 7%, and Japan’s Kioxia 13%. The catalyst: China’s CXMT promised new server DRAM, and the market got spooked that the memory shortage could come to an end.
Meanwhile, $BTC dipped below 81k overnight and climbed back above 83k. Not that it’s getting any help: spot ETFs saw outflows of around 681$ million last week, the biggest outflow since June. 30-year Treasuries touched 5.73% on October 7, their highest level since 2002. Oil is expensive, and CPI is out tomorrow.
My take: Bitcoin holding 81k while chips are down 10% is the first sign that crypto is no longer just a proxy for the Nasdaq. But this is a bounce, not a reversal. A hot CPI print, and 80k will be tested quickly; a soft one, and 84.5k is back in play.
Question: if the AI bubble deflates, where will that money go — into $BTC or into cash earning 5%?
#Bitcoin #CPI
66
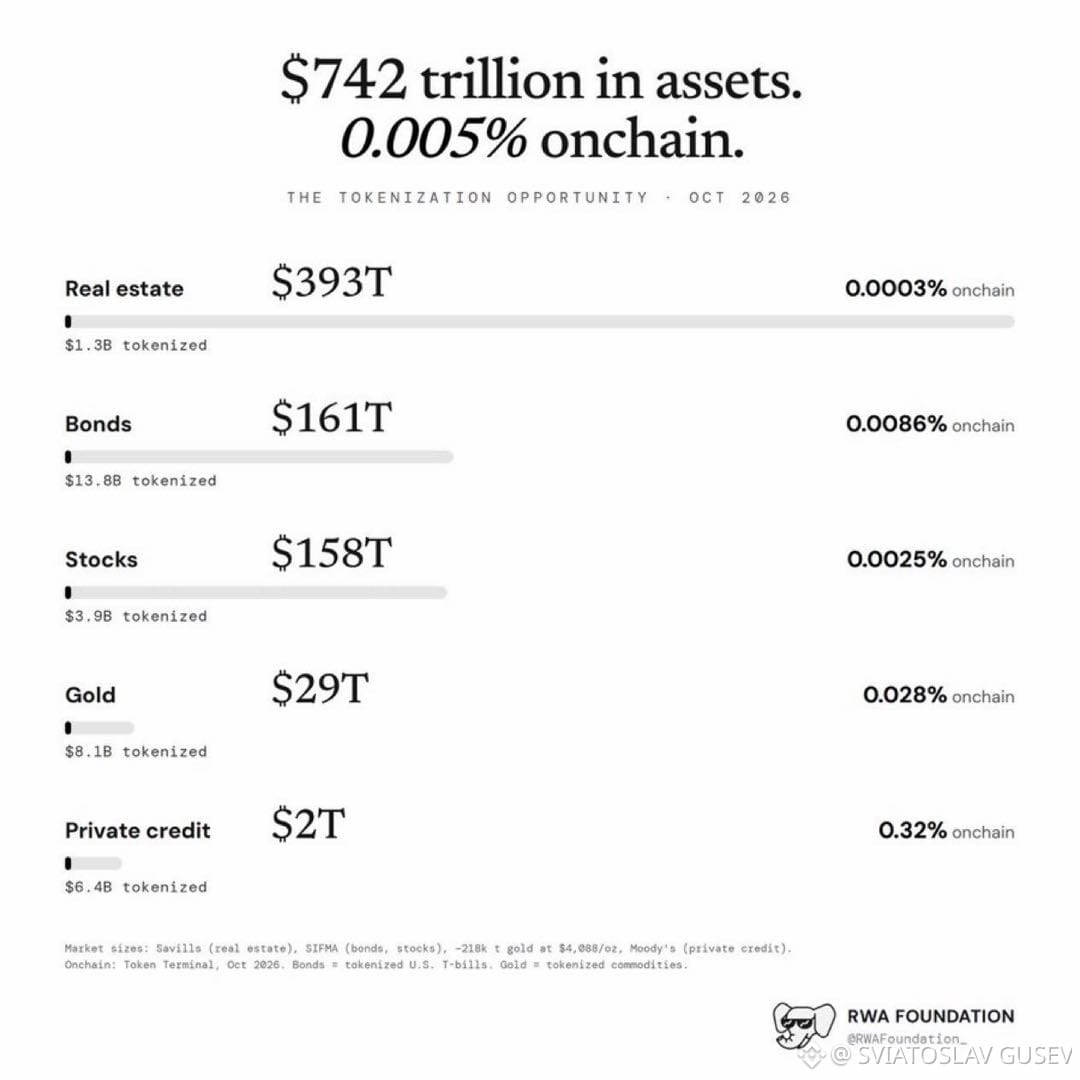
$742 trillion in real-world assets.
Only 0.005% are on the blockchain.
Real estate: $393T, $1.3B tokenized
Bonds: $161T, $13.8B tokenized
Stocks: $158T, $3.9B tokenized
Gold: $29T, $8.1B tokenized
Private credit: $2T, $6.4B tokenized
We haven't even started yet.
$742 trillion in real-world assets.
Only 0.005% are on the blockchain.
Real estate: $393T, $1.3B tokenized
Bonds: $161T, $13.8B tokenized
Stocks: $158T, $3.9B tokenized
Gold: $29T, $8.1B tokenized
Private credit: $2T, $6.4B tokenized
We haven't even started yet.
Only 0.005% are on the blockchain.
Real estate: $393T, $1.3B tokenized
Bonds: $161T, $13.8B tokenized
Stocks: $158T, $3.9B tokenized
Gold: $29T, $8.1B tokenized
Private credit: $2T, $6.4B tokenized
We haven't even started yet.
69
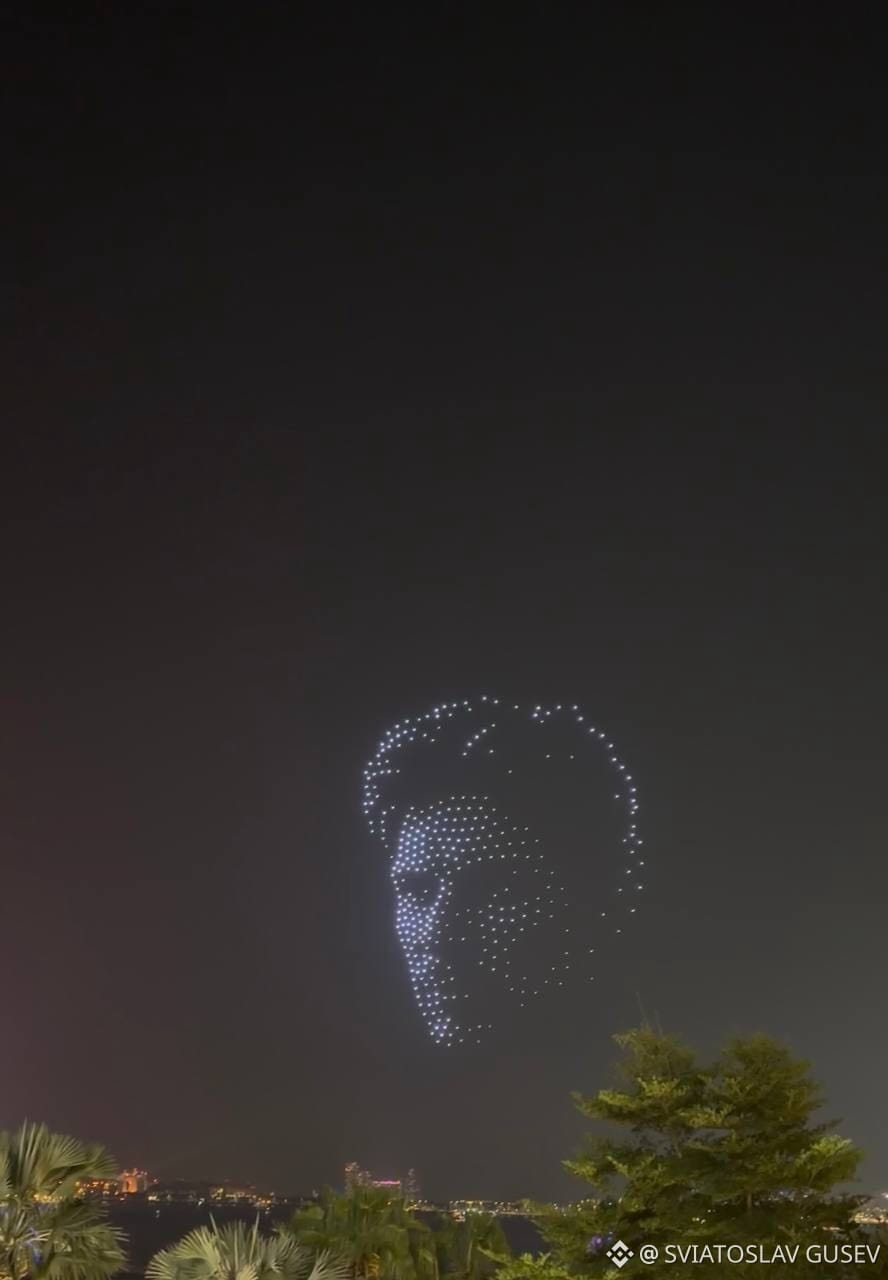
A drone show in Dubai in honor of Pavel Durov’s birthday. Pasha turned 42—such a big boy now. And $Gram has finally been fully integrated into Telegram!
Congratulations to us all!
A drone show in Dubai in honor of Pavel Durov’s birthday. Pasha turned 42—such a big boy now. And $Gram has finally been fully integrated into Telegram!
Congratulations to us all!
Congratulations to us all!
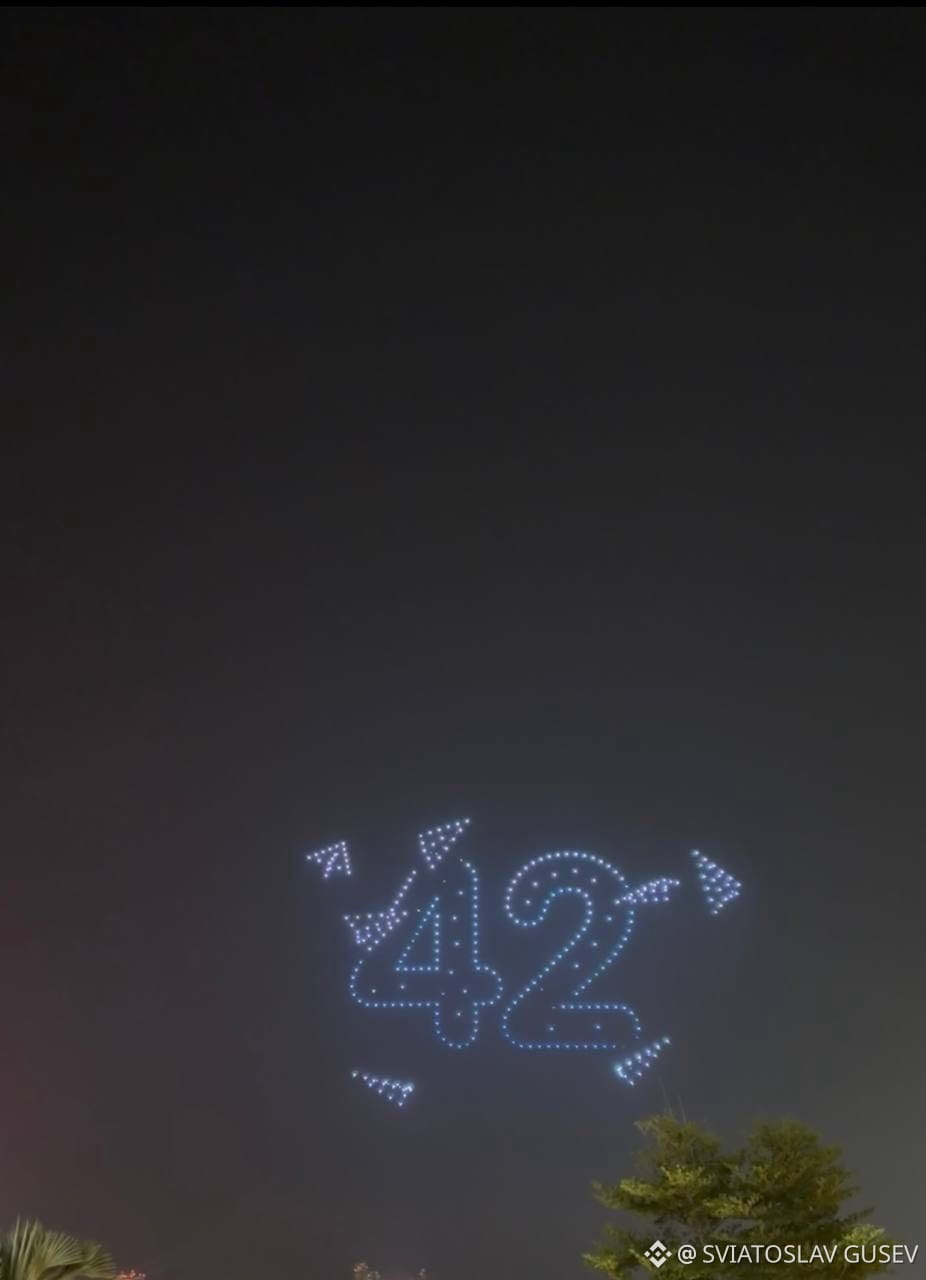
177
I have one fundamental issue with $TON.
Its biggest advantage is also its biggest drawback: Telegram.
$Gram is often marketed as a blockchain with potential access to a billion users. But those billion users don’t belong to TON. They belong to Telegram. And that’s a pretty important distinction.
If a restaurant is the only one past airport security, a large number of customers doesn’t necessarily make it the best restaurant in town.
Decentralization is much the same story. You can have hundreds of validators, open-source code, and a beautiful architecture. But if one private product is also your main source of users, your main distribution channel, and largely determines the rules of the game for developers, the dependency doesn’t go away. It’s just a little further up the stack from the blockchain.
The second problem with TON is that it’s quite complex technologically. Sharding, asynchronous messages, contracts interacting through chains of transactions. On paper, it’s a powerful architecture for scaling. In practice, someone always pays for complexity. Usually the developer, and then the user.
And the third issue is reliability. TON has already run into network problems during sharp spikes in load. That’s normal for a young blockchain. But if your main thesis is that a billion Telegram users will join the blockchain tomorrow, high load stops being a stress test. It becomes a regular Tuesday.
So I’d evaluate TON with a very simple thought experiment.
Take Telegram out of the picture.
Would developers still choose this blockchain over Ethereum, Solana, and other networks purely for its technology, liquidity, tools, and ecosystem?
That’s where the answer is no longer so obvious.
202
The owner of the NYSE is taking stocks onchain itself. OKXICE—a joint venture between OKX and ICE—has notified the SEC that it is launching 24/7 trading in tokenized U.S. stocks.
What we know: 60+ companies (Nvidia, Apple, Tesla, JPMorgan, Coinbase, Circle, SpaceX), permissioned trading on X Layer, and issuers have 30 days to opt out. It’s based on the SEC’s five-year innovation exemption from September: platforms like these can operate without registering as an exchange.
My take: this is no longer crypto knocking on Wall Street’s door—Wall Street is taking the rails for itself. A permissioned network with KYC isn’t DeFi; it’s the same exchange in a new wrapper. There’s no direct inflow into $BTC here: weekend traders’ money could go into Nvidia instead of coins. Meanwhile, $BTC at ~85.8k has failed to break 87k for the second time this week.
Question: Would you trade Apple late on a Sunday night—or will tokenized stocks eat into some of crypto’s trading volume?
$BTC #Tokenization
132
$SOL ~121 and four green days in a row — but inflows into spot ETFs have nearly vanished. Key levels.
The numbers: Solana ETFs saw +2,4$ million from Sept. 28 to Oct. 2, versus 188$ million the week before (SoSoValue), with two sessions in the red. OI ~7,2$ billion, funding neutral. Still ~59% below the ATH of 293.
Upside: A daily close above 123–125 (September high: 124.95) opens the way to 132–133. But we need $BTC above 87k — overnight it once again reached ~86,950 and pulled back.
Downside: Losing 119 (the 50 EMA on the 4-hour chart) points to 116.4, then 112.5–113.5.
My take: A rally on thin volume and with no money flowing into ETFs is a short squeeze, not fresh demand. While $BTC is up against 87k, I’m expecting a retest of 119, not buying the breakout.
Question: Will $SOL hit 125 or 116 first?
$SOL $BTC #Solana
90
Anthropic targets an IPO above 2$ trillion — and $BTC still isn’t holding 87k. Money for risk is flowing into AI obligations, not spot.
Figures (Reuters from the prospectus / CMC). The placement price is being discussed above 2$ trillion — more than twice the May private valuation of ~965$ billion. For 2025 net loss: 42$ billion; for cloud/compute/infra, at least 518$ billion is budgeted for ~a decade, ~80% of which is non-cancelable. Only compute in 2025: 7,33$ billion (three times vs 2024) with opex 12,65$ billion. Confidential S-1 is still in June; marketing — mid-October, listing is being discussed after midterms in November. For comparison: SpaceX previously closed ~1,7$ trillion in 2026. $BTC on Sunday morning is around 84.7–85.4k — after Friday’s failed breakout above 87k.
My take: it’s not “AI ate crypto,” but a test of where long capital is willing to go now. 518$ billion in obligations “even if you don’t use it” is a bet on compute scarcity, not on free liquidity. While the market digests these checks, risk-on in $BTC looks secondary: the hike is priced out by the morning, and spot is still in range. If Anthropic clears the upper band, that’s a signal of appetite for huge equity stories; if they cut the valuation — expect cooling and in alt-bets.
Question: will $BTC break 87k before the Anthropic roadshow — or will the market first show how much it’s really willing to pay for AI equity?
$BTC #Bitcoin #Anthropic #IPO
63
In a week, the market has almost completely unwound the October hike—yet $BTC is still sitting below 87k. They cut the rate, but didn’t buy the price.
Numbers (Glassnode Macro Special 3 Oct / BLS / futures). Probability of a hike at the Oct 28 meeting: from ~66% on Monday down to ~22% by Friday—after Williams (“no urgency”), softer core PCE, and NFP +29k vs. consensus ~84k. Three-month hiring ~51k/month—less than a third of the 2010s average (~183k). The 2s10s curve widened again to ~42 bps (from ~20 bps around the September hike), but the 10y is still around ~5.2%. $BTC over the same week is about +1% and early Sunday is around 84.7–84.8k—after Friday’s fail above 87k. Through December, futures still price in roughly ~24 bps of hikes; the next check is CPI on Oct 14.
My take: the market bought “no urgency,” not risk-on. As long as the long end of the curve doesn’t let go of 5.2%, spot $BTC stays in a range: hike priced out ≠ cheap money. Friday’s squeeze in shorts into NFP and the pullback after the release showed the same thing—movement driven by positioning, not by new demand. The real test isn’t the 22% for October; it’s CPI on Oct 14: a hot print will bring the hike back into play faster than any Fed speech.
Question: Will $BTC break 87k before CPI on Oct 14—or do we first wait for 10y to let go of 5.2%?
$BTC #Bitcoin #Fed #CPI
73
Blast — Paradigm-backed L2 on $ETH — shuts down the network: costs > revenue, «no credible path» to sustainability. Once there was >2,3$ bn in the bridge to mainnet launch. Now they’re asking to move assets to Ethereum by October 26. This isn’t a «pause», it’s a wind-down.
Figures (Decrypt / Cointelegraph / The Block, Oct 2–3). Peak TVL >2,3$ bn by February 2024; Paradigm seed ~20$ m (Nov 2023, Blur team). Now TVL is around tens of millions (~32$ m per The Block). By Oct 26 — a regular withdrawal interface; first a pause of ~a week for unwinding Lido assets, then a 24h delay. After Oct 26 — only direct bridge contracts on Ethereum. This year, alongside Zero Network and Silicon — L2 is also shutting down.
My take: native yield + an airdrop collected deposits, but not the chain’s economics. When DA/sequencer and support cost more than fee revenue — a «major L2» turns into a bridge with a deadline. For $ETH this isn’t a hit to L1; it’s a filter: networks with a real fee base will survive, not those with TVL from points. BLAST has already responded with a sharp sell-off — the market is pricing in the shutdown before the bridge.
Question: by the end of 2026, how many more mid-tier L2 on $ETH will close using the same formula costs > revenue — or has the market already passed the peak of cleanup?
#Ethereum #L2 #Blast
49
Citi has again raised its 12-month $BTC target to $113,000$ —from $82,000 in July. The bank expects roughly +34% from current levels. On Saturday, the market is sitting around 84.6k and for the second time in two weeks it failed to hold 87k. The target is there, but a breakout isn’t.
Figures (CoinDesk / Decrypt / crypto.com weekender / SoSoValue, snapshot 1–3 Oct). Note: Citi: $BTC 82k→113k, $ETH 2,240$→3,028$; base case: about 5$ billion in inflows into crypto products over 12 months—“slower, but stickier” via advisers and broker allocations. Spot-$BTC ETF: from ~5,8$ billion in net outflows by mid-July → roughly +800$ million YTD by the end of September; in September alone: ~2,65$ billion. On Thursday, the 10-year Treasury yield briefly touched 5.34% (highest since 2002); after a softer NFP it pulled back to ~5.2%. On Friday, $BTC briefly traded ~87,100$–87,200$, and by Saturday it was ~84,600$; the ceiling is the same as the one that capped the September move around ~87,400$.
My take: Citi is selling a scenario where yields calm down and advisers calmly add more. While the 10-year is paying >5% with no price risk, “stickier” money in $BTC is a promise, not something confirmed on the chart. 113k is still below ATH >126k— the bank isn’t calling for a new high; it’s simply returning to the mid-case after the summer sell-off. Without a sustained close above 87k, this is a client slide, not a market signal.
Question: which comes first—$BTC closes the week above 87k, or the 10-year yield heads back toward 5.3%+ and eats the bank’s optimism?
$BTC #Bitcoin #Citi
75
The SEC has rolled out a draft of custody rules for advisers and funds — and $BTC already failed to hold 87k and is once again sitting below 85k. The market is taking on structural deleveraging for now; it’s not buying the price yet.
Numbers (SEC.gov / Investing.com / CME FedWatch, morning Oct 3). On Oct 1, the SEC proposed an update to custody rules under the Advisers Act and Investment Company Act: conditional self-custody if there’s no available qualified custodian (checked once per quarter), plus state trust companies as permitted custodians; then there’s 60 days for public comment after the Federal Register — this is not a final rule yet. $BTC briefly moved above 87 219$ (first attempt above 87k since ~Sept 23), but by evening it was already around 84 612$; on Saturday morning, about 84.5–84.6k. FedWatch: October hike ~22% (hold ~78%), December hike still elevated — roughly 75%+.
My take: for institutions, this matters more than any NFP-type blip. While RIAs and funds were living in a gray area of custody, spot demand via regulated wrappers ran into compliance—not just the Fed rate. But the proposal ≠ the rule: the final text of “qualified custodian” will determine whether bitcoin-native trusts win or whether the big banks regain control. Until $BTC holds 87k on the structural headline, this isn’t an “institutional breakout” yet—it’s a bet that the rule will reach the finish line without being watered down.
Question: Will $BTC return to 87k before the end of the comment period—or is the market waiting for the SEC’s final text first?
$BTC #Bitcoin #SEC
69
$BTC after a weak NFP holds near October highs — the market is no longer “waiting for the report,” but deciding whether this is a breakout or a false exit.
Figures (The Block / Crypto Briefing / CoinGlass, Oct 2). September’s NFP — about 29k jobs added versus a consensus around 90k; unemployment 4.2%. FedWatch: probability of a hold in October ~82% (a week ago ~36%). Price after the peak stays above 87 000$ moves around 86,700$–86,900$. The next ask cluster on Glassnode — about 87,000$, roughly twice as thin as the old wall at 85k. QCP: resistance ~87,400$ as the gateway to 90k; nearest support — the 85,000$–85,200$ zone; below that 84k and ~83,500$.
Futures turnover over 24h — about 70$ bn versus ~6.3$ bn spot.
Scenarios. Up: a close and hold above 87 400$ opens the way to 90k with a thin ask. Down: a selloff back to 85k after the squeeze will return 84k / 83,500$ — the same empty order book turns faster.
My take: a weak payroll removes the hike rate, but by itself doesn’t buy above 87k. As long as futures are 10x fatter than spot, that’s leverage and cover, not proven spot demand. Don’t focus on the NFP headline— watch whether 85k holds as the floor after the impulse.
Question: does $BTC close the day above 87k — or pull back to test 85k as the new support?
$BTC #Bitcoin
43
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number