

TradingIsBad
252 Beiträge
TradingIsBad
Hochfrequenz-Trader
4.9 Jahre
37 Following
52 Follower
117 Like gegeben
Beiträge
Alle
Zitierungen
Übersetzung ansehen
Übersetzung ansehen
RIMIBEARS
·
--
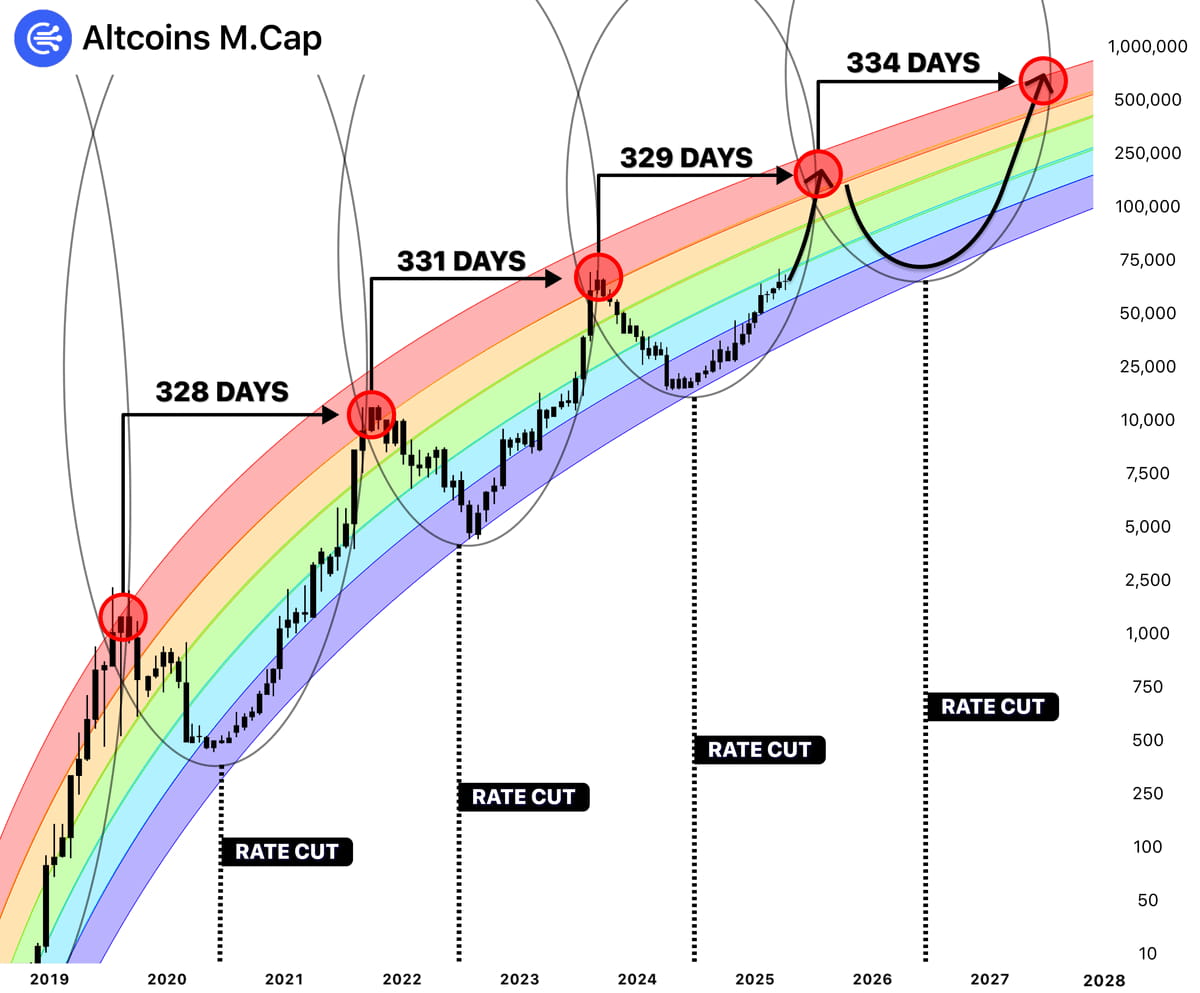
Die größte Altseason wird in 7 Tagen beginnen...
Die FED wird die Zinsen senken und 2 Billionen Dollar in den Markt pumpen
100 Dollar in Alts werden in Tagen zu 100.000 Dollar
Hier sind 6 richtige Lowcaps, die im September um 500x steigen werden 🧵👇
Die FED wird die Zinsen senken und 2 Billionen Dollar in den Markt pumpen
100 Dollar in Alts werden in Tagen zu 100.000 Dollar
Hier sind 6 richtige Lowcaps, die im September um 500x steigen werden 🧵👇
Crypto - Roznama
·
--
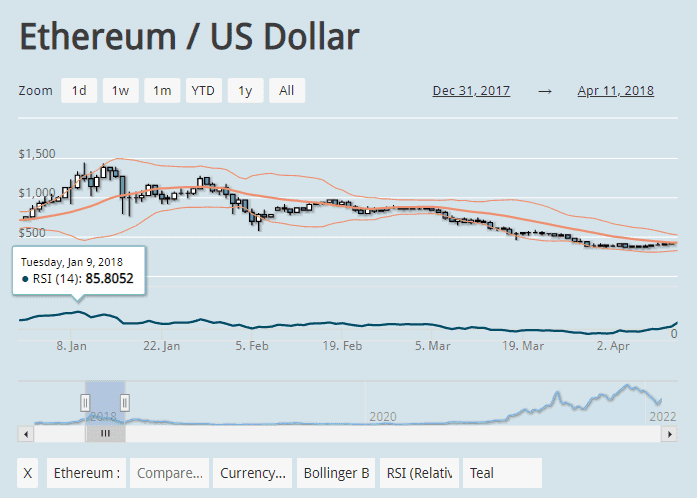
🚨 BREAKING: BLACKROCK VERKAUFT $257 MILLIONEN $ETH STACK 🚨
Das ist richtig — der größte Vermögensverwalter der Welt hat gerade einen Verkauf von $257.000.000 Ethereum entfesselt. Das ist keine Panik bei Kleinanlegern. Das ist institutionelles Schach. 🧠♟️
Die brennende Frage: Warum jetzt?
$ETH
---
👀 Mögliche Motive hinter dem Wal-Splash:
1️⃣ Tasche sichern: ETH war auf einem Höhenflug — vielleicht ziehen sie einfach die Quittungen ein, bevor der nächste Sturm kommt.
2️⃣ ETF-Rauchzeichen: Eine Portfolio-Neuordnung vor der Genehmigung eines ETH ETF? Schließe es nicht aus.
3️⃣ Makro-Jenga: Zinssätze, globale Unsicherheit, regulatorische Flüstereien — alles könnte die Hände zwingen.
4️⃣ Insider-Flüstern: (👀 Würzige Theorie… was wissen sie, das wir nicht wissen?)
---
📉 Markt-Schockwellen:
• Erwarte kurzfristiges Chaos — schwache Hände werden aufgeben 🫨
• ETH könnte einen sharp Rückgang sehen… aber Wale lieben Rabatte 🐋💎
• Wenn dies eine Neuausbalancierung ist, erwarte eine Wiederherstellung mit Lichtgeschwindigkeit ⚡
• Institutionen könnten entweder dem Dump folgen… oder das Blut kaufen.
---
💡 Spielbuch für die schlaue Geld-Crew:
✅ Keine Panikverkäufe. Beobachte die Orderbücher, nicht die Schreie auf Twitter.
✅ Lerne das Spiel. Institutionen bewegen sich nie ohne Strategie.
✅ Bleibe liquide und diversifiziert. Sei kein Pump-Jäger.
✅ Verfolge Wal-Wallets. Ihre Spuren erzählen die Geschichte.
---
🧠 Letzte Alpha:
Dieser Schritt könnte nichts anderes sein als BlackRock, das die Figuren auf dem Brett dreht. Oder es könnte der erste Schuss eines großen Marktwechsels sein. So oder so, denke daran:
👉 Wenn Titanen aufwachen, folgen Wellen. Die echten Spieler ertrinken nicht — sie surfen. 🌊🔥
---
$ETH 4,223.54 ▼ -2.25%
#Ethereum #blackRock #CryptoWhales #ETHSelloff #StaySharp
toaDis
·
--
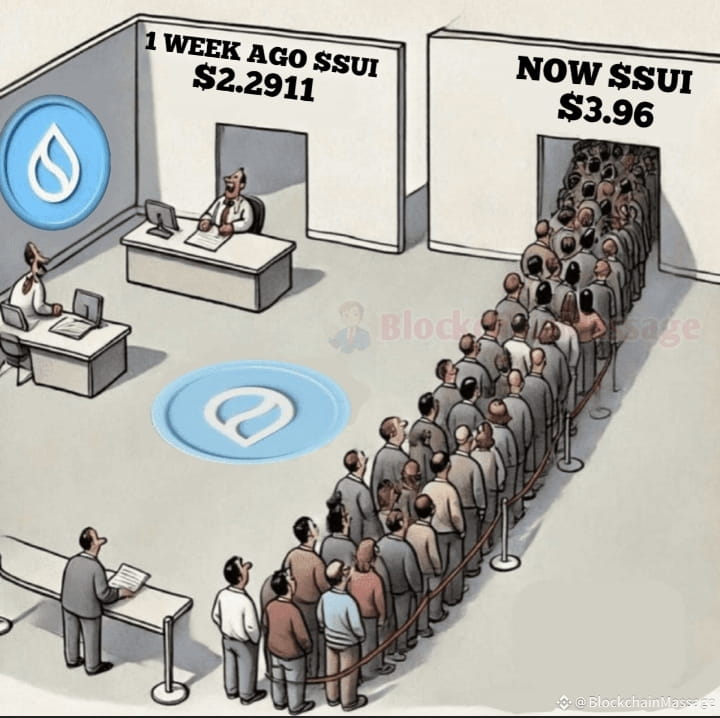
Bullisch*Wird $SUI 400$ erreichen?* 🪙
Ja, aber es wird einige große Initiativen und Zeit erfordern, damit dies wahr wird. Meine Vorhersage wäre, dass SUI bis Ende 2027 400$ erreichen wird🚀. Du solltest wirklich in Betracht ziehen, einen Betrag in Sui zu investieren💯. Es wird dich überhaupt nicht enttäuschen. Viel Glück, Brüder und Schwestern ❤️
Ja, aber es wird einige große Initiativen und Zeit erfordern, damit dies wahr wird. Meine Vorhersage wäre, dass SUI bis Ende 2027 400$ erreichen wird🚀. Du solltest wirklich in Betracht ziehen, einen Betrag in Sui zu investieren💯. Es wird dich überhaupt nicht enttäuschen. Viel Glück, Brüder und Schwestern ❤️
Co_RA
·
--
$ADA 🤣 Wieder gefallen — Keine Überraschung hier!
Ich habe es von Anfang an gesagt — das war eine falsche Rally.
Und jetzt? Es ist gefallen. Und glaub mir, es ist noch nicht vorbei.
Denkst du immer noch, dass dies ein "Kauf in der Delle"-Moment ist? Mach nur — aber sag nicht, ich hätte dich nicht gewarnt.
📉 $ADA rutscht — und es gibt noch mehr Abwärtsbewegung.
📉 Das ist kein Bounce. Es ist eine klassische Falle.
Zeit, aufzuwachen, bevor dein Portfolio einen weiteren Treffer einsteckt.
#ADA #CryptoTrap #MarketReality #ADAFall #ToldYouSo
Rehan shams
·
--
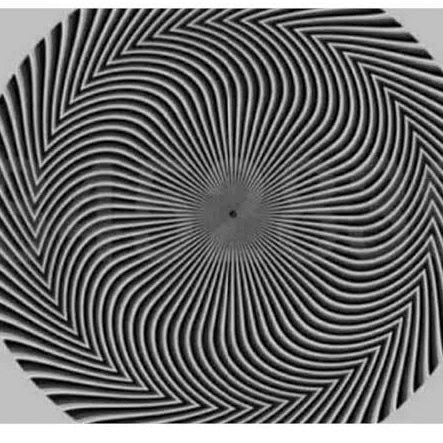
Welche Zahl sehen Sie als unmöglich für die richtige Antwort🙌
Trading_Fever
·
--
Ist es möglich, 61 $ in 5.000 $ in 2 Monaten zu verwandeln???
Big dawg001
·
--
Satoshi Nakamoto ist NICHT verschwunden… Er könnte im GEFÄNGNIS sein?!
Ja, ich weiß, es klingt verrückt – aber hör mir zu.
Einige glauben, Satoshi Nakamoto, der geheimnisvolle Schöpfer von Bitcoin, ist tatsächlich Paul Le Roux – ein in Simbabwe geborener genialer Programmierer… und Drogenboss.
Lass uns diese wilde Theorie aufschlüsseln:
Wer ist Paul Le Roux?
Ein brillanter Programmierer.
Er entwickelte E4M – Verschlüsselungssoftware, die so stark ist, dass sogar die NSA Schwierigkeiten hatte.
Er glaubte, Privatsphäre = Freiheit – und schrieb ein Manifest darüber. Kommt dir das bekannt vor?
Dann wurde es dunkler.
In den 2000er Jahren startete Paul Online-Apotheken, die Regulierungen umgangen.
Er skalierte. Dann baute er ein globales kriminelles Imperium auf.
Gefälschte Pässe. Verschlüsselte Netzwerke. Drogenhandel. Auftragsmord.
Es war organisiert wie eine Militäroperation.
Bis 2008 benötigte er eine Möglichkeit, Geld global und unauffällig zu transferieren.
Das Jahr, in dem Bitcoin geboren wurde.
Warte – hier wird es seltsam:
Einer von Pauls bekannten Aliasnamen?
Paul Solotshi Calder Le Roux.
Solotshi… Satoshi?
Zufall?
Satoshi verschwand 2010.
Le Roux wurde 2012 verhaftet.
Im Prozess Kleiman gegen Wright bezog sich ein geleaktes Dokument auf Paul Le Roux.
Es war das erste Mal, dass ihn jemand mit Bitcoin in Verbindung brachte.
Sogar vor Gericht sagte er dem Richter, dass er eine Bitcoin-Mining-Firma gründen wollte.
Die Verbindungen sind verrückt:
• Genialer Programmierer? Überprüft.
• Brauchte globale, anonyme Geldbewegungen? Überprüft.
• Besessen von Privatsphäre und Freiheit? Überprüft.
Aber es gibt Zweifel:
• Der Programmierstil stimmt nicht überein
• Le Roux war chaotisch, Satoshi war ruhig
• Bitcoin wurde nie in seinen Verbrechen verwendet
• Und Satoshis letzte echte Nachricht war 2014 – Le Roux war bereits im Gefängnis
Also… wer denkst DU, ist Satoshi wirklich?
Ein aufständischer Programmierer? Eine Gruppe von Cypherpunks? Oder… ein Drogenboss in einer Gefängniszelle?
Teile deine Theorie unten.
#BitcoinMystery #SatoshiNakamoto #CryptoConspiracy
Md_Yasir7
·
--
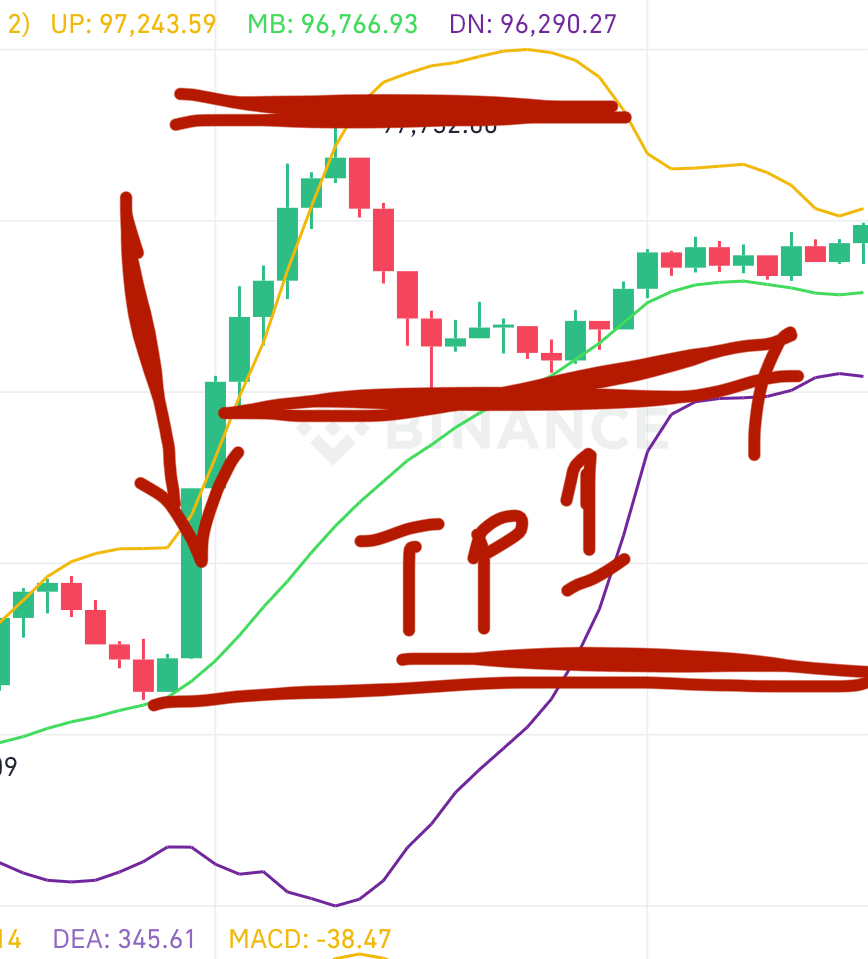
$BTC
Alarm 🚨
Bärisch kommt bald
Alarm 🚨
Bärisch kommt bald

Half_Soul
·
--
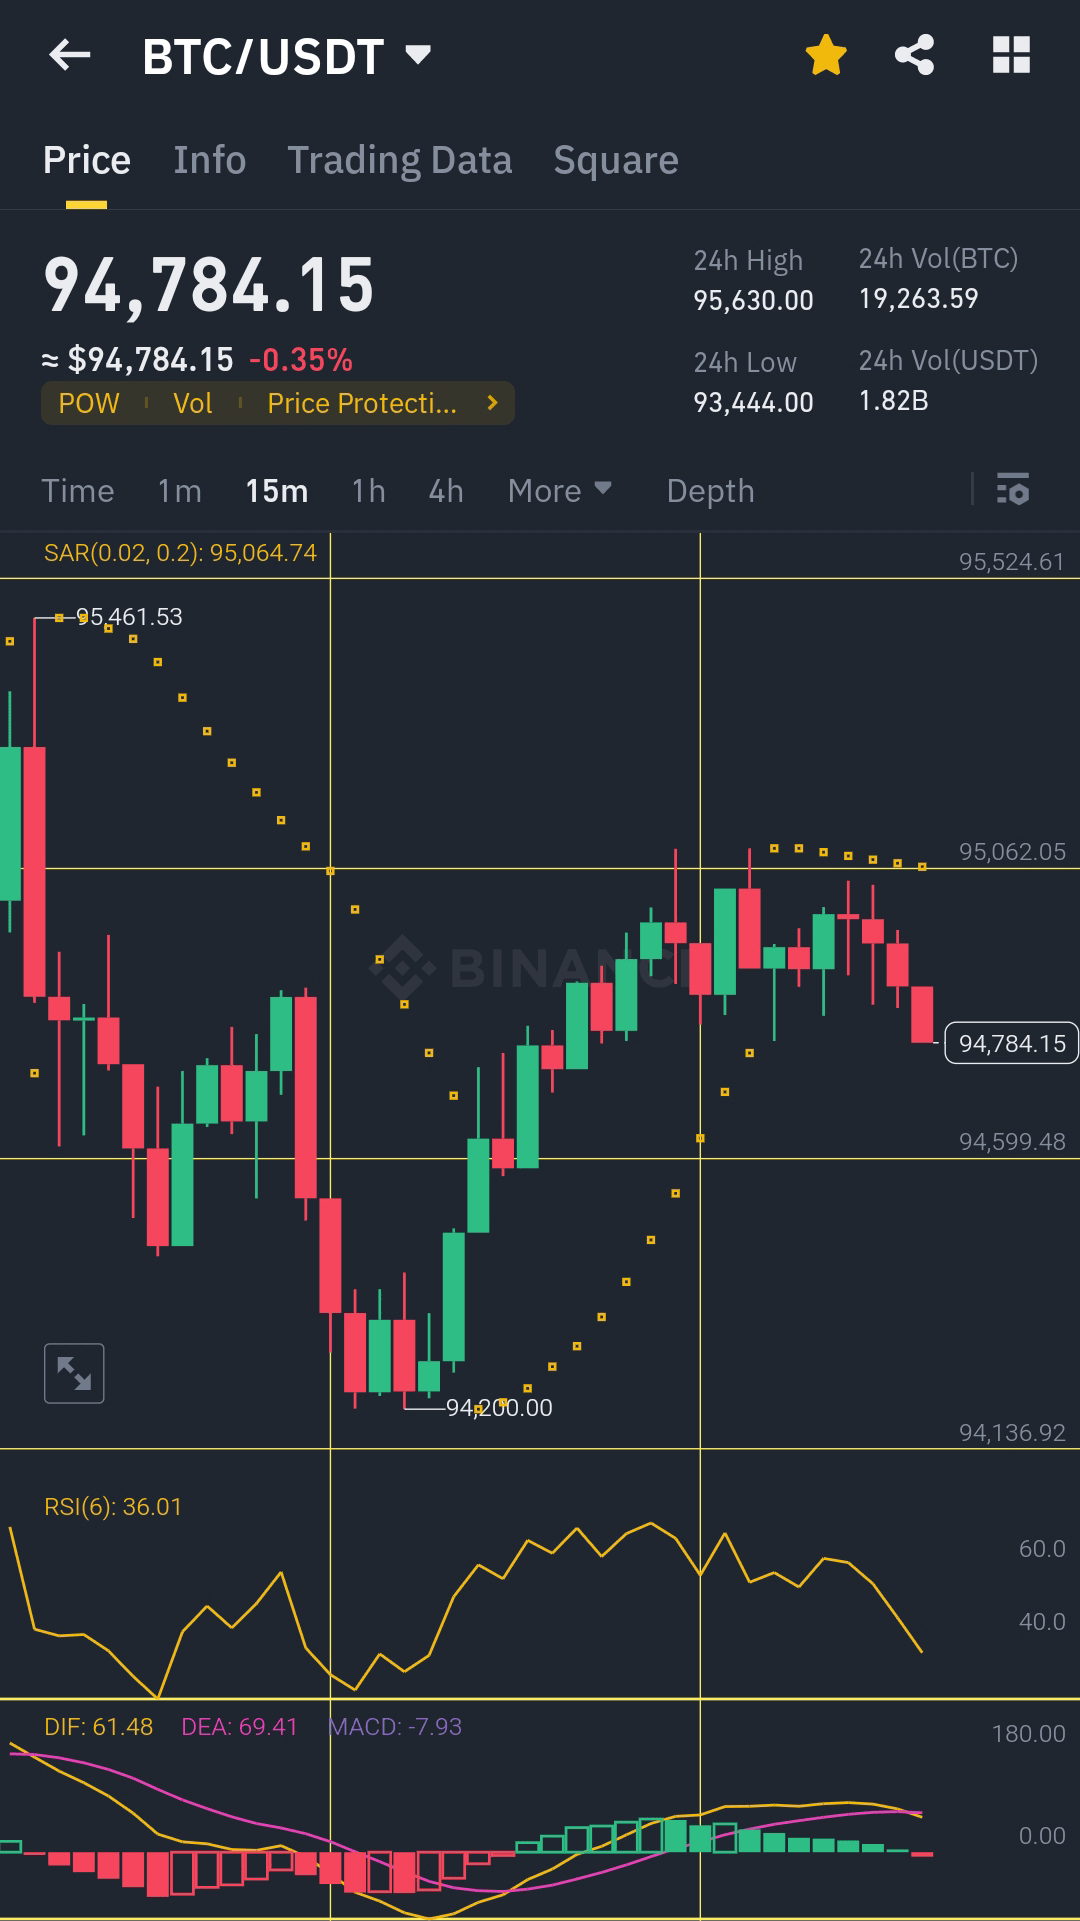
Treffe 70K BTC
Hallo Leute!
Das wird bald 70 K erreichen. $BTC
#BTCRebound
Hallo Leute!
Das wird bald 70 K erreichen. $BTC
#BTCRebound
SK info
·
--
Bullisch$ADA
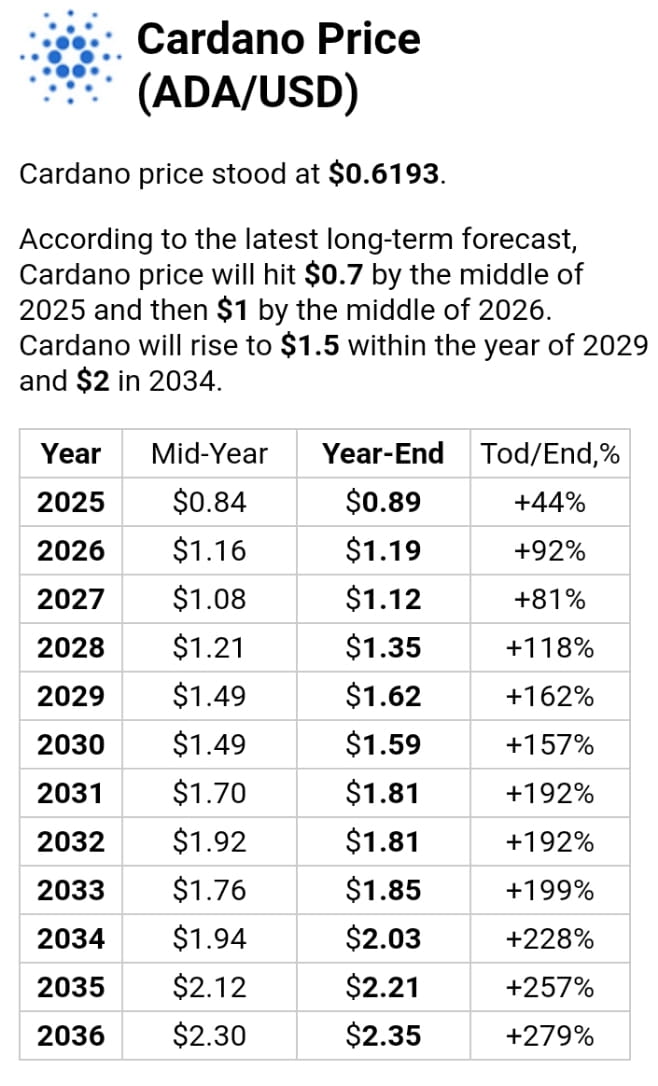
ADA Preisprognose 2025-2036
ADA Preisprognose 2025-2036
Zoila Alberda RNQM
·
--
Ich habe 250 Dollar
wie ich es schaffe, es an einem Tag zu verdoppeln
berate mich
wie ich es schaffe, es an einem Tag zu verdoppeln
berate mich


CryptoMasterMindX
·
--
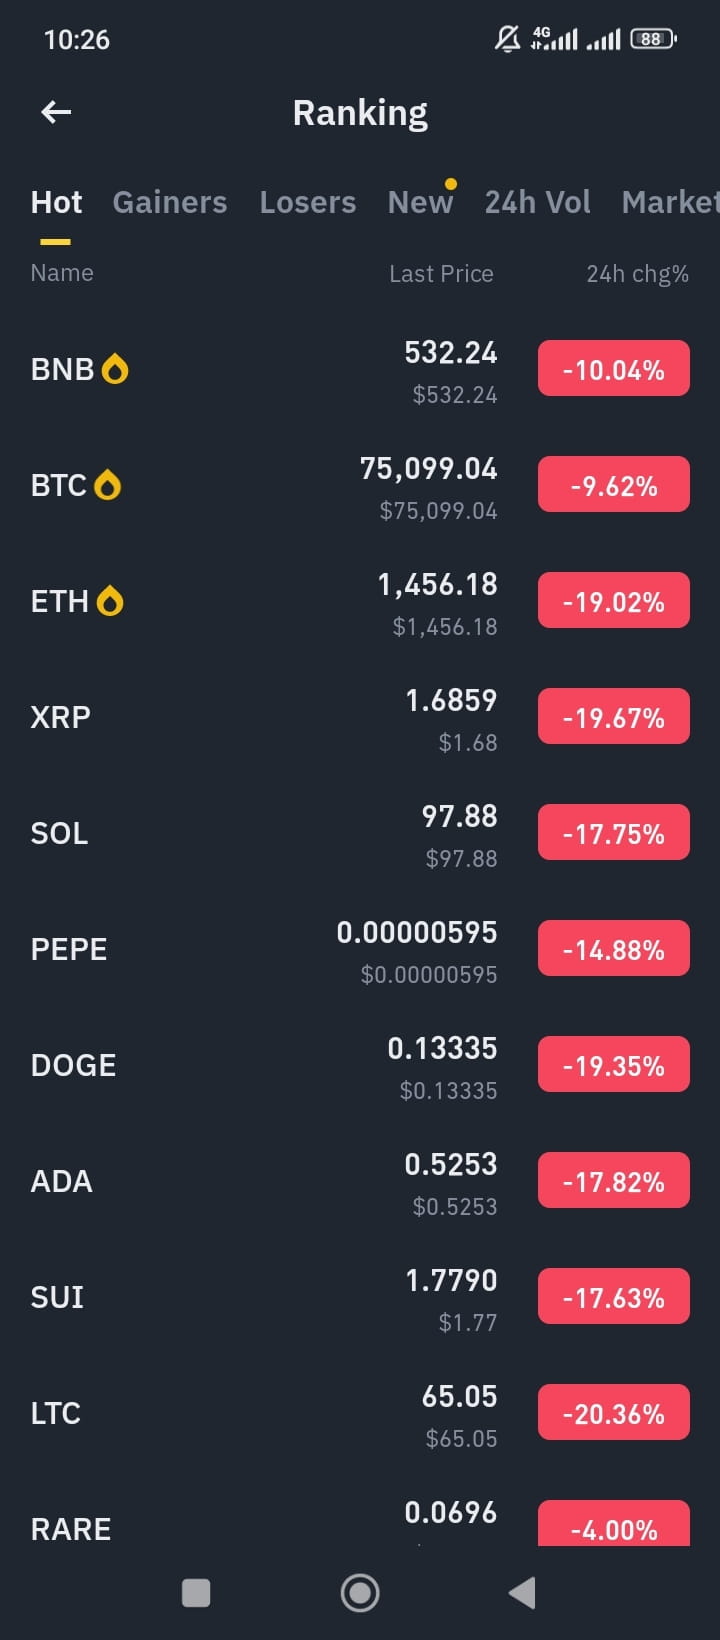
Wie viel Geld haben Sie durch diesen verrückten Crash verloren?
MjayBomb
·
--
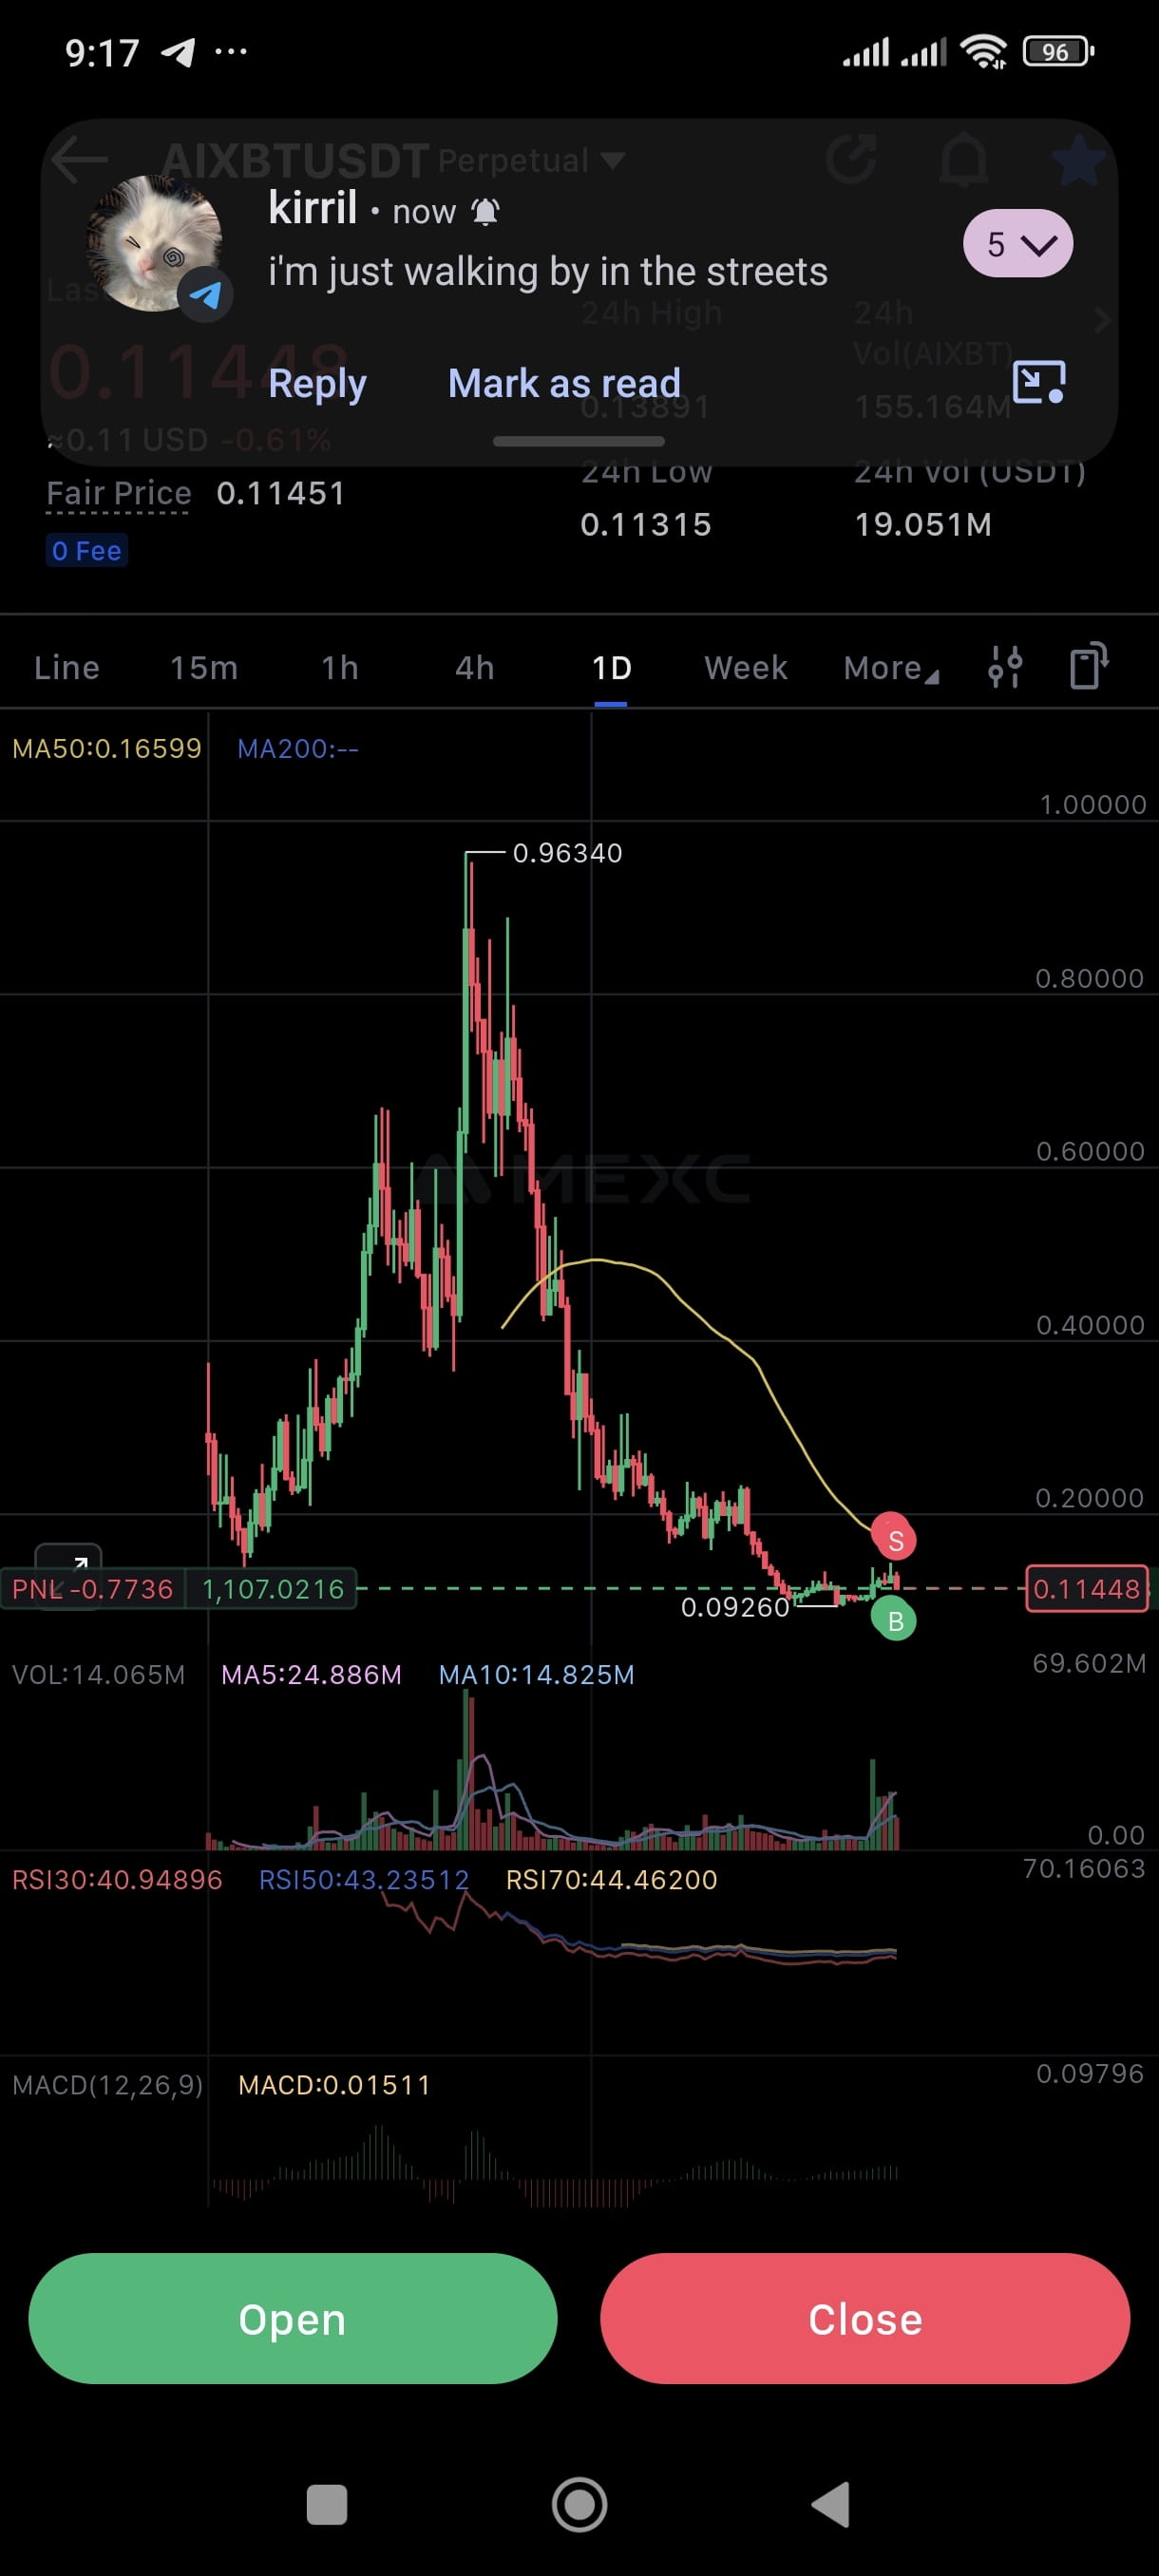
Bullisch#BSCUserExperiences versuchen Sie jetzt zu kaufen, es ist der Tiefpunkt
$AIXBT
$AIXBT
Anmelden und weiter Inhalte entdecken